Tag: Personal Finance

  • Do You Pay Federal Tax on Treasury Bills? 2026 Guide
    Do You Pay Federal Tax on Treasury Bills? 2026 Guide

    Do You Pay Federal Tax on Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: September 23, 2026
    Updated: September 23, 2026
    Reading Time: 10–12 min

    Do You Pay Federal Tax on Treasury Bills?

    Do You Pay Federal Tax on Treasury Bills?Yes, Treasury bills are generally subject to federal income tax. If you are asking, do you pay federal tax on Treasury bills, the key point is simple: T-bill interest is taxable at the federal level. Treasury bills are U.S. government securities, but that does not make their interest exempt from federal income tax. At the same time, Treasury bill interest is generally exempt from state and local income taxes. IRS guidance explains this distinction for Treasury obligations.

    The way T-bill interest is earned can also look different from a bank savings account or CD. Treasury bills are generally issued at a discount and mature at face value. For a standard T-bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes. Applicable Treasury interest is generally reported on Form 1099-INT, Box 3.

    Understanding these rules can make it easier to compare Treasury bills with other short-term investments. For a broader explanation of maturities, pricing, auctions, and tax treatment, see our complete Treasury Bills guide.

    What You’ll Learn

    • How federal income tax applies to Treasury bill interest.
    • When T-bill interest is generally reported for federal tax purposes.
    • How Treasury interest appears on Form 1099-INT.
    • Why T-bills generally receive state and local income-tax treatment that differs from federal tax.
    • How T-bill taxation compares with CDs, savings accounts, and money market accounts.
    • Common federal tax-reporting mistakes to watch for.

    Quick Answer: Do You Pay Federal Tax on Treasury Bills?

    Yes. Interest from Treasury bills is generally subject to federal income tax. Treasury bill interest is also generally exempt from state and local income taxes. For Treasury bills, the applicable interest is generally reported on Form 1099-INT, Box 3.

    Key Takeaways

    • Federal tax applies: Treasury bill interest is generally taxable for federal income-tax purposes.
    • State and local exemption: Treasury bill interest is generally exempt from state and local income taxes.
    • T-bill discount: For a standard T-bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income.
    • 1099-INT Box 3: Treasury bill interest is generally reported in Box 3 of Form 1099-INT rather than Box 1.
    • Not completely tax-free: The state and local tax exemption does not eliminate federal income tax.
    • Tax timing: For a standard T-bill held to maturity, the IRS generally says taxpayers report the interest when the bill is paid at maturity, subject to the applicable tax rules.

    Bottom line: Treasury bills are generally federally taxable, but their interest receives an exemption from state and local income taxes. The exact tax treatment can depend on the type of Treasury transaction and the taxpayer’s circumstances.

    Table of Contents

    Treasury Bills and Federal Tax at a Glance

    Treasury bills are generally subject to federal income tax. They are not federally tax-free investments. However, interest from U.S. Treasury obligations is generally exempt from state and local income taxes. This distinction is important when comparing T-bills with taxable bank deposits and other short-term investments.

    Tax DetailTreasury Bill Treatment
    Federal income taxGenerally taxable
    State income taxGenerally exempt
    Local income taxGenerally exempt
    Form 1099-INTTreasury interest is generally reported in Box 3
    Main tax benefitGenerally exempt from state and local income taxes

    QUICK TAKE: Treasury bills are generally taxable at the federal level, while their interest is generally exempt from state and local income taxes. For example, if a T-bill produces $200 of interest, that interest is generally included in federal taxable income, subject to the applicable federal tax rules.

    Complete Beginner Guide to T-Bill Federal Tax
    Do You Pay Federal Tax on Treasury Bills?Understanding federal tax on Treasury bills starts with one simple rule: interest from Treasury bills is generally subject to federal income tax. A T-bill is issued by the U.S. Treasury, but that does not make its interest federally tax-free. At the same time, Treasury bill interest is generally exempt from state and local income taxes. See the IRS guidance on Treasury interest for the applicable federal tax rules.

    1. How Do Treasury Bills Create Taxable Income?

    Treasury bills are generally issued at a discount instead of paying regular coupon interest. For example, an investor could pay $9,800 for a T-bill with a $10,000 maturity value. If the bill is held to maturity, the $200 difference is generally treated as interest income for federal tax purposes.

    2. Is the Entire T-Bill Amount Taxable?

    No. In a standard purchase held to maturity, the amount originally invested is not itself the interest income. The taxable interest component is generally the difference between the purchase price and the amount received at maturity. The exact treatment can differ for certain transactions, including purchases or sales in the secondary market.

    3. When Is T-Bill Interest Reported?

    For a standard Treasury bill held to maturity, the IRS generally provides that the interest is reported when the bill is paid at maturity. Selling a T-bill before maturity can involve different tax considerations, so investors should retain purchase, sale, and maturity records.

    4. Where Does Treasury Interest Appear?

    Treasury interest is generally reported on Form 1099-INT, Box 3. IRS instructions identify Box 3 for interest on U.S. savings bonds and Treasury obligations. Investors should use the tax documents and records applicable to their specific transaction.

    EASY WAY TO REMEMBER: Treasury bill interest is generally taxable at the federal level, generally exempt from state and local income taxes, and generally reported as Treasury interest in Box 3 of Form 1099-INT.

    How Federal Tax on T-Bills Works

    The federal tax treatment of a Treasury bill is easier to understand when you follow the investment from purchase to maturity. A standard T-bill generally does not make periodic coupon payments. Instead, it is issued at a discount and pays its face value at maturity. The difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes.

    Step 1: You Buy the Treasury Bill

    For example, a T-bill with a $10,000 maturity value might be purchased for $9,800. The $200 difference is generally the interest income associated with the bill when it is held to maturity. Treasury bills are commonly issued with maturities such as 4, 8, 13, 26, and 52 weeks.

    Step 2: The Bill Reaches Maturity

    At maturity, the Treasury generally pays the bill’s face value. For a standard T-bill held to maturity, the difference between the purchase price and the maturity amount is generally treated as interest income rather than a separate capital gain.

    Step 3: Federal Tax Applies

    The interest is generally subject to federal income tax. However, interest from U.S. Treasury obligations is generally exempt from state and local income taxes. This creates an important tax distinction when comparing T-bills with taxable bank deposits.

    Step 4: The Interest Is Reported

    Treasury interest is generally reported on Form 1099-INT, Box 3. For a standard T-bill held to maturity, cash-method taxpayers generally report the interest when the bill is paid at maturity. A purchase or sale in the secondary market can involve different tax rules and reporting considerations.

    THE SIMPLE VERSION: A standard T-bill is generally bought below face value, matures at face value, and the difference is generally treated as federally taxable interest. Treasury interest is generally exempt from state and local income taxes.

    Benefits & Drawbacks of Federal Tax on Treasury Bills

    Treasury bills are generally subject to federal income tax, but their interest is exempt from state and local income taxes. That combination can affect the after-tax comparison between T-bills and other interest-producing investments. The actual impact depends on the investor’s applicable tax situation and the type of transaction.

    Potential Benefits

    • State and local tax exemption: Treasury bill interest is generally exempt from state and local income taxes.
    • Potential after-tax advantage: In a comparison with an otherwise similar taxable investment, avoiding applicable state and local income taxes can increase the amount of interest retained after those taxes.
    • Federal tax treatment is identifiable: Treasury interest is generally reported separately in Box 3 of Form 1099-INT, making it easier to identify the Treasury portion of reported interest income.

    Potential Drawbacks

    • Federal tax still applies: The state and local exemption does not make Treasury bill interest federally tax-free.
    • After-tax results vary: The value of the state and local exemption depends on the applicable tax rules and the investment being compared.
    • Different transactions can have different rules: Buying or selling a T-bill in the secondary market can create additional tax and reporting considerations.

    QUICK TAKE: The main tax benefit of Treasury bills is the general exemption from state and local income taxes. Federal income tax still applies, so comparing the complete after-tax result is more useful than looking only at the stated T-bill yield.

    T-Bills vs. CDs vs. Savings vs. Money Market

    Federal tax treatment can help explain an important difference between Treasury bills and common bank deposit products. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Interest earned from bank CDs, savings accounts, and bank money market accounts is generally subject to federal income tax, while state and local treatment depends on the applicable rules.

    InvestmentFederal TaxState & Local Income TaxCommon Federal Reporting
    Treasury BillsGenerally appliesGenerally exemptForm 1099-INT, generally Box 3
    Bank CDsGenerally appliesDepends on applicable state and local rulesGenerally Form 1099-INT when reportable
    Savings AccountsGenerally appliesDepends on applicable state and local rulesGenerally Form 1099-INT when reportable
    Bank Money Market AccountsGenerally appliesDepends on applicable state and local rulesGenerally Form 1099-INT when reportable

    One Important Distinction

    A bank money market account is different from a money market mutual fund. A bank money market account is a deposit account that generally pays interest. A money market fund is an investment product, and its distributions can have different tax-reporting characteristics. This comparison refers specifically to bank money market accounts.

    QUICK TAKE: Treasury bills have a specific federal, state, and local tax distinction: their interest is generally federally taxable but exempt from state and local income taxes. For bank deposit products, state and local treatment can differ. Compare the applicable tax rules along with yield, maturity, liquidity, and account terms.

    Costs, Tax Risks & Expert Tips

    Treasury bills generally do not pay periodic coupon interest. Instead, they are commonly issued at a discount and pay their face value at maturity. For a standard T-bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes. Other transactions can involve different tax rules.

    Costs to Check

    • Transaction costs: If buying through a brokerage, check the firm’s pricing, bid-ask spread, or other applicable transaction costs.
    • After-tax return: Compare the T-bill’s yield after considering applicable federal tax and its state and local tax exemption.
    • Recordkeeping: Keep purchase confirmations, maturity information, sale records, and tax forms with your investment records.

    Tax Risks to Understand

    • Federal tax still applies: Treasury bill interest is generally subject to federal income tax.
    • Tax forms are not the only consideration: Not receiving a Form 1099-INT does not by itself remove an applicable tax-reporting obligation.
    • Early sale: Selling a T-bill before maturity can involve tax and reporting considerations that differ from a standard held-to-maturity transaction.

    Expert Tips for Cleaner Tax Reporting

    For a standard T-bill held to maturity, keep the original purchase price and maturity amount available when reviewing your tax records. Treasury interest is generally reported on Form 1099-INT, Box 3. If a T-bill is sold before maturity or purchased in the secondary market, review the transaction records and applicable tax rules carefully.

    EXPERT TIP: Keep your Treasury purchase, maturity, sale, and tax records together. For transactions outside a standard held-to-maturity purchase, consult the applicable IRS guidance or a qualified tax professional when needed.

    Common Mistakes + Real-Life Example

    Federal tax on Treasury bills is generally straightforward when a standard bill is purchased and held to maturity. Still, investors can misunderstand the state-tax exemption, overlook their tax records, or assume that an early sale follows exactly the same rules.

    Mistake 1: Assuming T-Bills Are Completely Tax-Free

    Treasury bill interest is generally exempt from state and local income taxes, but it is generally subject to federal income tax. The state and local exemption should not be confused with complete tax-free treatment.

    Mistake 2: Ignoring Form 1099-INT

    Treasury interest is generally reported in Box 3 of Form 1099-INT. Investors should review their tax documents and keep their own purchase, maturity, and transaction records. The absence of a tax form does not by itself determine whether income is reportable.

    Mistake 3: Overlooking an Early Sale

    A standard T-bill held to maturity has relatively straightforward treatment. Selling before maturity or buying a T-bill in the secondary market can involve additional tax and reporting rules, so the transaction records matter.

    Real-Life Example: A $10,000 T-Bill

    Suppose an investor buys a $10,000 face-value T-bill for $9,800 and holds it until maturity. The Treasury pays $10,000 at maturity, creating a $200 difference. For a standard T-bill held to maturity, that difference is generally treated as interest income for federal tax purposes. Treasury interest is generally exempt from state and local income taxes and generally appears in Box 3 of Form 1099-INT.

    KEY LESSON: Treasury bills can receive a state and local income-tax exemption without being federally tax-free. For a standard held-to-maturity T-bill, keep the purchase and maturity records and review the applicable Treasury interest reported for federal tax purposes.

    Who May Consider Treasury Bills?

    Treasury bills may be relevant to investors looking at short-term U.S. government securities and evaluating how federal, state, and local taxes affect their interest income. Their tax treatment can be one factor when comparing T-bills with other short-term investments.

    T-Bills May Be Relevant to Investors Who:

    • Want exposure to a U.S. Treasury security with a short maturity, generally 52 weeks or less.
    • Want to account for the general state and local income-tax exemption on Treasury interest.
    • Are comparing securities that are generally issued at a discount and pay face value at maturity.
    • Understand that Treasury bill interest is generally subject to federal income tax.
    • Want to compare potential after-tax income across different short-term investments.

    KEEP IN MIND: Tax treatment is only one factor in evaluating a Treasury bill. Maturity, yield, liquidity, transaction costs, federal taxes, and the tax treatment of alternative investments can also affect the overall comparison.

    Frequently Asked Questions

    1. Do You Pay Federal Tax on Treasury Bills?

    Yes. Interest from Treasury bills is generally subject to federal income tax. Treasury interest is generally exempt from state and local income taxes.

    2. Are Treasury Bills Tax-Free?

    No. Treasury bills are not completely tax-free. Their interest is generally taxable for federal income-tax purposes, while generally receiving an exemption from state and local income taxes.

    3. How Is T-Bill Interest Taxed?

    For a standard Treasury bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes.

    4. Where Is Treasury Bill Interest Reported?

    Treasury interest is generally reported on Form 1099-INT, Box 3. Investors should also keep their purchase, maturity, and other transaction records.

    5. When Do You Report T-Bill Interest?

    For a standard Treasury bill held to maturity, cash-method taxpayers generally report the interest when the bill is paid at maturity, subject to the applicable federal tax rules.

    6. What If You Do Not Receive Form 1099-INT?

    Not receiving Form 1099-INT does not by itself determine whether income is reportable. Investors should review their Treasury records and the applicable federal tax rules when preparing their return.

    7. Are Treasury Bills Exempt From State and Local Income Taxes?

    Generally, yes. Interest from U.S. Treasury obligations, including Treasury bills, is generally exempt from state and local income taxes.

    8. Does Selling a T-Bill Before Maturity Change the Tax Treatment?

    It can. A sale before maturity or a secondary-market purchase can involve additional tax and reporting considerations. The standard held-to-maturity treatment should not automatically be applied to every transaction.

    QUICK ANSWER: Treasury bills are generally subject to federal income tax, while their interest is generally exempt from state and local income taxes.

    Final Verdict: Do You Pay Federal Tax on Treasury Bills?

    Yes. Treasury bill interest is generally subject to federal income tax. At the same time, interest from U.S. Treasury obligations is generally exempt from state and local income taxes. So, Treasury bills are not completely tax-free, but they do receive a specific state and local income-tax exemption.

    For a standard T-bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes. Treasury interest is generally reported on Form 1099-INT, Box 3. A sale before maturity or a secondary-market purchase can involve additional tax and reporting considerations.

    For a broader explanation of Treasury bill maturities, pricing, auctions, and tax treatment, see our complete Treasury Bills guide.

    BOTTOM LINE: Treasury bills are generally subject to federal income tax, while their interest is generally exempt from state and local income taxes. When comparing T-bills with other investments, consider the applicable tax treatment along with yield, maturity, liquidity, and transaction costs.

    Have a Money Question? Keep Exploring.

    Treasury bill taxes can affect the income you actually keep after taxes. Continue exploring FinanceInvestment to understand T-bill pricing, yields, maturities, and other factors that can help you evaluate short-term investments.

    📩 Get in Touch With FinanceInvestment

    Have a money question or a topic you’d like us to cover? Send us a message.

    Email FinanceInvestment

    Continue Your Research

    Treasury Bills Explained  |  Treasury Bill Price vs. Face Value
  • Are Treasury Bills Exempt From State Taxes? 2026 Guide

    Are Treasury Bills Exempt From State Taxes? 2026 Guide

    Are Treasury Bills Exempt From State Taxes?

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    Published: September 23, 2026
    •
    Updated: September 23, 2026
    •
    Reading Time: 10–12 min

    Are Treasury Bills Exempt From State Taxes?

    Are Treasury Bills Exempt From State Taxes?If you live in a state that charges individual income tax, the tax treatment of your investments can make a noticeable difference. So, are Treasury bills exempt from state taxes? Yes. Interest from U.S. Treasury bills is generally exempt from state and local income taxes. Federal income tax still applies, though, so T-bills should not be described as completely tax-free.

    That state-tax exemption becomes especially relevant when you compare Treasury bills with taxable alternatives such as bank savings accounts, certificates of deposit, or bank money market accounts. The advertised rate is only part of the comparison. The tax treatment can change the amount of income left after taxes.

    If you want the bigger picture first, our
    Treasury Bills Explained
    guide covers how these short-term U.S. government securities work. Here, the focus is narrower: the state and local income-tax exemption and how it affects Treasury bill investors.

    What You’ll Learn

    • Why Treasury bill interest is exempt from state and local income taxes.
    • How federal income tax applies to Treasury bill interest.
    • Why the exemption can matter when comparing after-tax returns.
    • How T-bills compare with CDs, savings accounts, and bank money market accounts.
    • How Form 1099-INT is used for Treasury interest reporting.
    • Common tax-reporting mistakes investors should watch for.

    Quick Answer: Are Treasury Bills Exempt From State Taxes?

    Yes. Interest from U.S. Treasury bills is subject to federal income tax but is exempt from state and local income taxes. Treasury bill interest is generally reported on Form 1099-INT, Box 3. That means the state-tax benefit is real, but Treasury bill income is not completely tax-free.

    Key Takeaways

    • Treasury bill interest is exempt from state and local income taxes.
    • Federal income tax still applies to Treasury bill interest.
    • The exemption can matter when comparing T-bills with taxable bank deposits.
    • Form 1099-INT generally reports Treasury bill interest in Box 3.
    • For a standard T-bill held to maturity, the difference between the discounted purchase price and the face value is generally treated as interest income.
    • State-tax exempt does not mean federal-tax exempt.
    BOTTOM LINE:
    The main tax advantage of Treasury bills is the exemption from state and local income taxes. When comparing a T-bill with another cash investment, look beyond the advertised rate and consider how each investment is taxed.

    Table of Contents

    Treasury Bills and State Taxes at a Glance

    The central tax rule is simple: interest income from U.S. Treasury bills is subject to federal income tax but exempt from all state and local income taxes. That can make the tax treatment different from interest earned on many bank deposits. Treasury interest is generally identified separately on Form 1099-INT.

    Tax DetailTreasury Bill Treatment
    Federal income taxApplies
    State income taxExempt
    Local income taxExempt
    Form 1099-INTTreasury interest generally appears in Box 3
    Key tax benefitExemption from state and local income taxes

    WHO MAY VALUE THIS TAX TREATMENT:
    Investors comparing Treasury bills with taxable cash investments may want to account for the state and local income-tax exemption when comparing after-tax income. The actual benefit depends on the investor’s tax situation and location.

    KEY NUMBERS:
    Treasury bills generally have 4-, 8-, 13-, 26-, or 52-week maturities. They are generally issued at a discount, and for a standard bill held to maturity, the difference between the discounted purchase price and face value is generally treated as interest income.

    Treasury Bill State Tax Exemption: A Complete Beginner Guide

    Are Treasury Bills Exempt From State Taxes?Treasury bills have a tax feature that can be easy to miss when you first compare them with other short-term investments. The IRS says interest from Treasury bills, notes, and bonds is subject to federal income tax but exempt from all state and local income taxes.
    1. What Does the State-Tax Exemption Mean?

    Imagine buying a standard Treasury bill for $9,800 and receiving its $10,000 face value at maturity. The $200 difference is generally treated as interest income. That interest is taxable federally, but it is exempt from state and local income taxes.

    2. Why Doesn’t the Exemption Apply to Federal Tax?

    Treasury bills are obligations of the U.S. government, but their interest is not federally tax-exempt. For a standard Treasury bill held to maturity, the IRS generally treats the difference between the discounted purchase price and the face value received at maturity as interest income.

    3. Does the Exemption Include Local Income Taxes?

    Yes. The exemption covers both state and local income taxes. That means Treasury bill interest is generally not included in state or local income tax based on the interest itself. This treatment can differ from taxable interest earned through many bank deposit products.

    4. Where Does Treasury Interest Appear on Form 1099-INT?

    Treasury bill interest is generally reported on Form 1099-INT, Box 3. IRS instructions specifically say Box 3 is used for interest on U.S. savings bonds, Treasury bills, Treasury notes, and Treasury bonds. The amount is generally included with taxable interest for federal reporting.

    EASY WAY TO REMEMBER:
    Treasury bill interest gets a state and local income-tax exemption, not a complete tax exemption. Federal income tax still applies, and Treasury interest is generally identified in Box 3 of Form 1099-INT.

    That difference matters most when you compare the after-tax income from a Treasury bill with interest from a taxable bank account or another short-term investment.

    How the State-Tax Exemption Works

    The state-tax benefit follows the federal treatment of U.S. Treasury obligations. Treasury bill interest is taxable for federal income tax purposes, while that interest is exempt from state and local income taxes.

    Step 1: You Buy the Treasury Bill

    Treasury bills are generally issued at a discount. For example, a $10,000 face-value bill might be purchased for less than $10,000. The actual purchase price depends on the bill and the transaction terms.

    Step 2: The Bill Reaches Maturity

    For a standard Treasury bill held to maturity, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. Most individual taxpayers using the cash method generally report this interest when the bill is paid at maturity.

    Step 3: The State and Local Exemption Applies

    Once the Treasury interest is recognized for tax purposes, the key distinction is where it is taxed. Federal income tax applies, but the interest from Treasury bills is exempt from state and local income taxes. That is the tax advantage behind the phrase state-tax exempt.

    Step 4: Treasury Interest Is Reported Separately

    Form 1099-INT, when issued for Treasury obligations, reports Treasury bill interest in Box 3. IRS instructions specifically say Treasury bills, Treasury notes, Treasury bonds, and U.S. savings bonds belong in Box 3 rather than Box 1.

    THE SIMPLE VERSION:
    A Treasury bill can create federally taxable interest without creating state or local income tax on that same Treasury interest. The exemption is the tax advantage; it does not make the investment completely tax-free.

    Benefits & Drawbacks of the State-Tax Exemption

    The state-tax exemption can change the after-tax comparison between Treasury bills and taxable cash investments. Still, it is only one factor. Federal income tax continues to apply, while the value of the state and local exemption depends on the investor’s tax situation and where the investor lives.


    ✓ Benefits

    • Treasury bill interest is exempt from state and local income taxes.
    • The exemption can improve the after-tax comparison with taxable bank deposits for investors who would otherwise owe state or local income tax on comparable interest.
    • Treasury obligations are generally reported separately on Form 1099-INT, with applicable Treasury interest reported in Box 3.


    △ Drawbacks

    • Federal income tax still applies to Treasury bill interest.
    • The state-tax exemption does not by itself determine which investment produces the better after-tax result; yield, federal taxes, and the tax treatment of the alternative also matter.
    • Selling a Treasury bill before maturity or dealing with certain secondary-market transactions can introduce additional tax


    QUICK TAKE:

    The tax benefit is specific: state and local income taxes generally do not apply to Treasury bill interest. When comparing investments, look at the yield and federal tax treatment alongside your own state and local tax position.

    Treasury Bills vs. CDs vs. Savings vs. Money Market

    The tax difference becomes clearer when Treasury bills are placed beside familiar cash investments. Treasury interest receives a specific federal benefit: it remains subject to federal income tax but is exempt from state and local income taxes. Interest from ordinary bank deposit products is generally taxable, subject to the rules that apply to the account and the investor.

    InvestmentFederal TaxState & Local Income TaxCommon Federal Reporting
    Treasury BillsAppliesExemptForm 1099-INT, generally Box 3
    Bank CDGenerally appliesGenerally taxable under applicable rulesGenerally Form 1099-INT
    Bank Savings AccountGenerally appliesGenerally taxable under applicable rulesGenerally Form 1099-INT
    Bank Money Market AccountGenerally appliesGenerally taxable under applicable rulesGenerally Form 1099-INT

    Why the Tax Difference Matters

    Imagine two investments producing the same amount of interest. If one is a Treasury bill and the other is a taxable bank deposit, the Treasury interest can avoid state and local income tax while the bank interest generally remains subject to applicable state and local rules. The actual difference depends on the investor’s circumstances and jurisdiction.

    One detail is easy to overlook: a bank money market account is not the same thing as a money market fund. A bank money market account is a deposit account that generally pays interest. A money market fund is an investment product, and its distributions are generally reported as dividends rather than interest.

    QUICK TAKE:
    Treasury bills have a specific tax advantage: their interest is exempt from state and local income taxes. When comparing T-bills with CDs, savings accounts, or bank money market accounts, compare the tax treatment along with the yield.

    Costs, Tax Risks & Expert Tips

    Treasury bills are generally purchased at a discount and do not make regular interest payments during their short term. The main tax issue is straightforward: Treasury bill interest is subject to federal income tax but exempt from state and local income taxes. The purchase price, maturity date, and how the bill was held can also affect how the income is reported.

    Costs to Check Before Buying

    • If you buy through a brokerage account, check the broker’s current pricing and account terms rather than assuming every transaction is free.
    • Compare the Treasury bill’s yield with the yield available on other cash investments after considering the applicable tax treatment.
    • Keep purchase confirmations and maturity records, especially when buying or selling Treasury bills through different accounts.

    Tax Risks to Avoid

    • Do not describe Treasury bills as completely tax-free. Federal income tax still applies to the interest.
    • Do not ignore taxable interest simply because a tax form was not received. The IRS requires taxable interest to be reported even when a Form 1099-INT is not received.
    • Do not automatically enter Treasury bill interest in Form 1099-INT Box 1. Interest from Treasury bills, notes, and bonds is generally shown in Box 3.

    Expert Tips for Cleaner Tax Records

    For a standard Treasury bill held to maturity, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. For cash-method taxpayers, that income is generally reported when the bill is paid at maturity.

    EXPERT TIP:
    Keep your purchase confirmation, maturity statement, and tax forms together. TreasuryDirect reports Treasury bill interest for the year the bill matures or is sold, and a Treasury bill held through a broker can result in additional reporting records if the security moves between accounts.

    Common Mistakes + Real-Life Example

    Treasury bill taxes are usually straightforward, but a few common misunderstandings can create problems. The biggest one is confusing a state-tax exemption with a complete tax exemption. Treasury bill interest remains subject to federal income tax.

    Mistake 1: Assuming T-Bills Are Completely Tax-Free

    The exemption applies to state and local income taxes. It does not remove federal income tax from Treasury bill interest.

    Mistake 2: Ignoring the Tax Form

    For Treasury bills, Treasury notes, and Treasury bonds, Treasury interest is generally shown in Form 1099-INT, Box 3. Taxable interest must still be reported even when a 1099-INT is not received.

    Mistake 3: Overlooking the Sale or Maturity Year

    A Treasury bill does not normally pay periodic interest. For a standard bill held to maturity, the difference between the discounted purchase price and the amount received at maturity is generally interest income, normally reported when the bill matures. If the bill is sold before maturity, keep the transaction records because the reporting can involve additional details.

    Real-Life Example

    Consider this illustrative example: an investor buys a Treasury bill for $9,800 and receives $10,000 at maturity. The $200 difference represents interest income for this simplified example. Federal income tax applies to that interest, while the interest is exempt from state and local income taxes. The investor should use the actual tax documents and transaction records when preparing the tax return.

    KEY LESSON:
    Treasury bills are not completely tax-free. Their specific tax benefit is that Treasury interest is exempt from state and local income taxes while remaining subject to federal income tax.

    Who May Consider Treasury Bills?

    Treasury bills may be worth considering for investors looking for a short-term U.S. Treasury security with a defined maturity date. Their interest is subject to federal income tax but exempt from state and local income taxes, which can matter when comparing T-bills with taxable alternatives.

    T-Bills May Fit Investors Who:

    • Want a short-term U.S. Treasury security with a stated maturity of one year or less.
    • Live in a state or locality with an income tax and want to account for the Treasury interest exemption when comparing taxable investments.
    • Prefer a security that is generally purchased at a discount and redeemed at its face value at maturity.
    • Understand that the interest remains subject to federal income tax.
    KEEP IN MIND:
    The state-tax exemption is only one factor to consider. Maturity period, yield, liquidity needs, federal tax treatment, and the tax treatment of alternative investments can also affect the comparison.

    Frequently Asked Questions

    1. Are Treasury bills exempt from state taxes?

    Yes. Interest income from U.S. Treasury bills is subject to federal income tax but is exempt from state and local income taxes.

    2. Do you pay federal tax on Treasury bills?

    Yes. Treasury bill interest is subject to federal income tax. For a standard Treasury bill held to maturity, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income.

    3. Are Treasury bills exempt from local income taxes?

    Yes. The exemption covers state and local income taxes on Treasury bill interest. Federal income tax still applies, so Treasury bills should not be described as completely tax-free.

    4. Where is Treasury bill interest reported on Form 1099-INT?

    Interest from Treasury bills is generally reported in Box 3 of Form 1099-INT. IRS instructions specifically identify Box 3 for interest on Treasury bills, Treasury notes, Treasury bonds, and U.S. savings bonds.

    5. When do you report Treasury bill interest?

    For a standard Treasury bill held to maturity, the interest is generally reported when the bill is paid at maturity. TreasuryDirect also notes that T-bill interest is reportable in the year the bill matures or is sold.

    6. What if you do not receive a Form 1099-INT?

    Not receiving a Form 1099-INT does not automatically make taxable interest nonreportable. The IRS states that taxable interest must be reported even when the form is not received.

    7. Are Treasury bills tax-free if you live in a state with income tax?

    Treasury bill interest is exempt from state and local income taxes, even when the investor lives in a state that imposes an income tax. Federal income tax still applies to the interest.

    8. Does Treasury bill tax reporting change if you sell before maturity?

    It can. A standard Treasury bill held to maturity has a straightforward discount-to-face-value interest treatment, while a bill sold before maturity can involve different transaction details and reporting. TreasuryDirect states that the difference between the original purchase price and the amount received when a bill is sold or matures is interest.

    Final Verdict: Are Treasury Bills Exempt From State Taxes?

    Yes. Interest from U.S. Treasury bills is exempt from state and local income taxes, while federal income tax still applies. That makes the state and local tax exemption the key tax distinction to understand when evaluating Treasury bills. They are not completely tax-free investments. (IRS Publication 550)

    For a standard Treasury bill held to maturity, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. Treasury bill interest is generally reported in Box 3 of Form 1099-INT. (IRS Form 1099-INT Instructions)

    For a broader explanation of T-bill maturities, pricing, and basic investing concepts, continue with our Treasury Bills Explained guide.

    BOTTOM LINE:
    Treasury bill interest gets a state and local income-tax exemption, but federal income tax still applies. When comparing T-bills with other cash investments, consider the yield together with the applicable federal, state, and local tax treatment.

    Have a Money Question? Keep Exploring.

    Want to understand more about Treasury bills, taxes, or other ways to manage your cash? Keep exploring FinanceInvestment for practical, easy-to-follow personal finance guides.


    📩 Get in Touch With FinanceInvestment


    Have a finance question or a topic you’d like us to cover? Send us a message.


    Email FinanceInvestment

  • How to Buy Treasury Bills in 2026: Beginner’s Guide

    How to Buy Treasury Bills in 2026: Beginner’s Guide

    How to Buy Treasury Bills

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 20, 2026


    Reading Time: ~14 minutes

    How to Buy Treasury Bills: Start With the Right Route

    How to Buy Treasury BillsHow to Buy Treasury Bills is easier when you first understand where the purchase happens and what you are actually ordering. In the U.S., individual investors can buy Treasury bills directly through TreasuryDirect or through a brokerage account. The steps are different, but both routes can give you access to Treasury bill investments.

    Buying a T-bill is more than choosing an amount and clicking purchase. You need to select a maturity, decide how much face value you want, understand whether you are placing a new-issue order, and know when the bill will mature. Treasury bills are issued at a discount and generally pay their face value at maturity when held until then.

    If Treasury bills are new to you, our

    Treasury Bills Explained guide

    covers the fundamentals. This article goes one step further by showing how the buying process fits together, from choosing an account to placing an order and planning for maturity.

    What You’ll Learn

    • What you need before buying your first Treasury bill.
    • How the TreasuryDirect purchase process works.
    • How a brokerage can be used to purchase Treasury bills.
    • How to choose a maturity that fits your cash timeline.
    • What a noncompetitive order means for individual investors.
    • What to check before submitting a Treasury bill order.

    Quick Answer: How Do You Buy Treasury Bills?

    To buy Treasury bills, you can purchase newly issued bills through TreasuryDirect or through a brokerage that offers Treasury securities. Start by choosing a maturity and deciding how much to invest. Then review the available offering, submit the appropriate order and check the settlement and maturity details. TreasuryDirect uses noncompetitive bidding for individual purchases, meaning you accept the yield determined at the auction.

    Key Takeaways

    • Treasury bills can be purchased directly through TreasuryDirect or through a brokerage that offers Treasury securities.
    • Before placing an order, choose a maturity that matches when you expect to need the money.
    • TreasuryDirect individual purchases use noncompetitive bidding, so you do not enter the auction yield yourself.
    • Treasury bills are generally issued at a discount and pay their face value at maturity when held to maturity.
    • A brokerage may also provide access to Treasury bills already trading in the secondary market.
    • Before buying, review the purchase amount, maturity date, settlement information and any applicable brokerage fees or charges.
    BOTTOM LINE

    Buying a T-bill is fairly simple once you know the route you want to use. The important part is matching the maturity to your cash needs and understanding whether you are buying a new issue or a bill in the secondary market.

    Table of Contents

    Treasury Bills Buying at a Glance

    Buying a Treasury bill comes down to a few practical decisions: where you will buy it, which maturity fits your plans, how much you want to invest and whether you are purchasing a new issue or a bill already trading in the secondary market. Once those choices are clear, the order itself becomes easier to follow.

    BUYING ROUTES
    TreasuryDirect or Brokerage
    Common ways to purchase Treasury bills
    MATURITY
    Select an Available Term
    Match the maturity to your cash timeline
    PRICING
    Generally Sold at a Discount
    Face value is generally paid at maturity

    Key Details to Check

    DetailWhat to CheckWhy It Matters
    MaturityAvailable bill term and maturity dateTells you when the bill is scheduled to mature.
    Purchase priceAmount required for the orderHelps determine the difference between what you pay and the face value received at maturity.
    Order typeNew issue or secondary marketPricing and the purchase process can differ between the two markets.
    AccountTreasuryDirect or brokerageDetermines where you place, hold and manage the investment.
    QUICK TAKE

    Before opening the order screen, know how long you can leave the money invested and when you may need it back. Then compare the available bill terms and purchase details that fit that timeline.

    Complete Beginner Guide: What You Need Before Buying Treasury Bills

    How to Buy Treasury BillsBefore you buy Treasury bills, get three things clear: where you will purchase them, how long you can leave the money invested and how much you want to commit. Having those answers ready makes the order process much easier to follow.
    1. Choose Your Buying Account

    You can buy eligible Treasury securities directly through TreasuryDirect or use a brokerage that offers Treasury securities. TreasuryDirect is designed for direct purchases from the Treasury, while a brokerage may also give you access to Treasury securities in the secondary market.

    2. Match the Maturity to Your Cash Needs

    Look at your upcoming expenses before selecting a bill. The maturity date tells you when the security becomes due, so avoid choosing a term that conflicts with a known cash need. If you may need the money earlier, understand the secondary-market selling process before you buy.

    3. Prepare the Purchase Details

    For a new Treasury auction, you specify the par amount you want to purchase. Treasury auction announcements state the applicable minimum bid and purchase multiples. A noncompetitive bid accepts the yield or discount rate determined at the auction instead of entering your own competitive rate.

    BEGINNER CHECK

    Before submitting an order, confirm the account, bill maturity, par amount and order type. If you are using a brokerage, also check its current transaction pricing and any applicable fees or minimums.

    If you want to understand the security before placing an order, read our

    guide to how Treasury bills work
    .
    Then you can move on to the actual purchase process.

    How Buying Treasury Bills Works

    Once you know which account and maturity you want, the buying process follows a simple sequence. The exact screens depend on the platform, but you generally select the bill, review the order details, submit the purchase and then wait for the issue or trade to settle.

    Step 1: Choose the Bill and Maturity

    Start by reviewing the available Treasury bill offerings. For a new auction, check the bill’s term, auction date, issue date, maturity date and the minimum purchase amount or applicable purchase multiples stated in the offering information.

    Step 2: Submit Your Order

    For a new TreasuryDirect purchase, an individual investor generally submits a noncompetitive bid. You enter the par amount you want to purchase rather than specifying your own competitive discount rate. A noncompetitive bid accepts the rate or discount rate awarded through the auction.

    Step 3: Complete the Purchase

    For a new issue, the Treasury conducts the auction and determines the resulting pricing. Your purchase is then completed according to the applicable settlement terms. If you buy an existing T-bill through a brokerage’s secondary market, the transaction uses the market price available when your order is executed instead of waiting for a new Treasury auction.

    Step 4: Track the Maturity Date

    After the purchase, keep the maturity date in your records. A Treasury bill becomes due on that date. If you hold it until maturity, the Treasury pays the bill’s face value. You can then use the proceeds, reinvest them or move the money toward another financial goal.

    PROCESS TIP

    Save your order confirmation, issue date and maturity date after buying. If you plan to reinvest the proceeds, note the maturity date on your calendar so you have time to review the next available Treasury bill options.

    The biggest difference between the two buying routes is what happens after you place the order. TreasuryDirect is built around direct Treasury purchases, while a brokerage can also give you access to securities already trading in the secondary market.

    Benefits and Drawbacks of Buying Treasury Bills

    Treasury bills can be useful for short-term cash that has a defined purpose and timeline. They offer a clear maturity structure, but buying them also means thinking ahead about liquidity, taxes and what you will do when the bill matures.

    Benefits

    • You can choose an available maturity that fits a planned cash need.
    • Treasury bills are obligations of the U.S. government.
    • Treasury bill interest is generally exempt from state and local income taxes.
    • TreasuryDirect provides a direct way to purchase newly issued Treasury securities.

    Drawbacks

    • If you need the money before maturity, you may need to sell the bill through the secondary market.
    • A pre-maturity sale can produce a market price that is different from what you originally paid.
    • The yield available when you reinvest may be higher or lower than the yield on your current bill.
    • Treasury bill interest is generally subject to federal income tax.
    BEFORE YOU BUY

    Look at your cash timeline before focusing on the quoted yield. A bill that matures when you actually need the money may fit your plan more naturally than one selected only because its annualized yield appears higher.

    TreasuryDirect vs. Brokerage: How to Buy Treasury Bills

    TreasuryDirect and brokerage accounts can both provide access to Treasury bills, but they serve different purposes. TreasuryDirect lets investors purchase eligible Treasury securities directly from the U.S. Treasury, while a brokerage can place Treasury orders alongside stocks, bonds and other investments. Some brokers also provide access to Treasury securities in the secondary market.

    FeatureTreasuryDirectBrokerage
    New Treasury issuesDirect access to eligible Treasury auctionsAvailable through brokers that offer Treasury auction orders
    Existing T-billsTreasuryDirect is primarily designed for Treasury holdings and direct purchasesSome brokers offer existing Treasury securities in the secondary market
    Auction orderIndividual investors generally use noncompetitive biddingOrder process depends on the brokerage
    Account experienceFocused on Treasury securitiesTreasury bills can be managed alongside other investments
    Purchase costsTreasuryDirect charges no purchase fee or commissionCosts depend on the brokerage, account and transaction

    When a Brokerage May Be Convenient

    A brokerage can be convenient if you already keep your investments in one account. Depending on the firm, you may be able to purchase new Treasury issues and access existing securities in the secondary market. However, brokerage fees and trading arrangements vary, so review the firm’s current fee schedule and transaction terms before placing an order. Investor.gov notes that brokerage costs can include commissions, markups or markdowns and other account-related charges. 1

    What to Compare Before Choosing

    • Whether you want a newly issued Treasury bill or an existing security in the secondary market.
    • How easily you want to manage Treasury bills alongside your other investments.
    • The brokerage’s current transaction costs, account requirements and trading terms.
    • How you would handle the investment if your cash needs change before maturity.
    COMPARISON TIP

    Compare the complete buying experience rather than looking only at a commission. Check auction access, secondary-market availability, pricing, account features and how you plan to manage the bill after purchase.

    Costs, Taxes, Risks and Expert Tips

    Buying Treasury bills is relatively straightforward, but the purchase price is only one part of the decision. Before placing an order, consider brokerage costs, federal taxes, maturity timing and what could happen if you need to sell the bill before it matures.

    Costs to Know

    TreasuryDirect does not charge a purchase fee or commission for Treasury securities. Brokerage costs can vary by firm and transaction, so check the broker’s current pricing before placing an order. A secondary-market purchase can also have a different price from a newly issued Treasury bill.

    Taxes and Market Risk

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. The discount on a Treasury bill is generally treated as interest income when the bill reaches maturity. If you sell before maturity, the market price can be higher or lower than what you paid because market conditions and interest rates can change.

    PRACTICAL TIP

    Before buying, check the maturity date, purchase amount, expected cash need and tax treatment. If you may need the money early, understand how selling through the secondary market could affect your proceeds.

    For a closer look at Treasury bill pricing, read our

    Treasury Bill Yield vs. Interest Rate guide
    .

    Common Mistakes When Buying Treasury Bills

    Buying Treasury bills is straightforward, but the details still matter. Most problems happen when investors choose a maturity, purchase amount or buying method without first considering when they may need the money.

    1. Choosing a Maturity Without Checking Your Cash Needs

    Before buying, look at when you expect to use the money. If you need the funds before the bill matures, you may need to sell through the secondary market, where the market price can be different from your original purchase price.

    2. Confusing Face Value With Purchase Price

    Treasury bills are generally issued at a discount and mature at face value. That means the amount paid at purchase can be less than the amount due at maturity. Review both figures before submitting an order so you understand the transaction.

    3. Forgetting to Plan for Maturity

    A Treasury bill has a defined maturity date. Before buying, decide what you expect to do with the proceeds when the bill matures. You may need the money for an expense, move it to another account or consider another investment.

    REAL-LIFE EXAMPLE

    Suppose an investor has $10,000 available for a Treasury bill and expects to use that money for a planned expense in about four months. Instead of selecting a maturity without checking the timeline, the investor can review the available Treasury bill terms and consider which maturity date fits the expected cash need. If the money is needed earlier than the selected maturity, the investor should also understand the potential effects of selling in the secondary market.

    A Simple Pre-Purchase Check

    • Confirm the bill’s maturity date.
    • Review the purchase amount and face value.
    • Check whether you are buying a new issue or a secondary-market security.
    • Decide how you expect to use the proceeds when the bill matures.

    Who Should Consider Buying T-Bills?

    Treasury bills may fit investors who have cash available for a defined period and want a U.S. Treasury security with a specific maturity date. Whether they fit your situation depends on your cash needs, investment timeline and overall financial plan.

    May Fit

    • Investors planning for a known short-term cash need.
    • Families setting aside money for an upcoming expense.
    • Investors who want short-term Treasury securities as part of a broader portfolio.
    • Retirees managing a portion of their cash for planned near-term spending.

    Consider the Timing First

    • Investors who may need the money before the selected maturity should understand the secondary market.
    • Investors seeking long-term portfolio growth may need to consider other asset types as well.
    • Money needed for an emergency reserve may require a more accessible cash option.
    PLANNING POINT

    Start with the date you expect to need the money. Then compare that timeline with the available Treasury bill maturities. If your cash needs could change, understand the potential price impact of selling before maturity before committing the funds.

    Frequently Asked Questions About Buying Treasury Bills

    1. Where can I buy Treasury bills?

    You can buy newly issued Treasury bills directly through TreasuryDirect or through a brokerage that offers Treasury securities. Some brokerages also provide access to Treasury bills in the secondary market.

    2. Can beginners buy Treasury bills?

    Yes. Individual investors can buy Treasury bills through TreasuryDirect or an eligible brokerage account. For TreasuryDirect auction purchases, individual investors generally use noncompetitive bids, which accept the yield or discount rate determined at the auction.

    3. Do Treasury bills pay monthly interest?

    No. Treasury bills do not make periodic coupon payments. They are generally issued at a discount and mature at face value. The difference between the purchase price and amount paid at maturity generally represents the bill’s interest income.

    4. What happens when a Treasury bill matures?

    When a Treasury bill reaches its maturity date, the Treasury pays its face value. If you hold the bill through maturity, you do not need to sell it in the secondary market. Eligible TreasuryDirect investors can also arrange for proceeds from maturing securities to be reinvested into new Treasury securities.

    5. Can I sell a Treasury bill before maturity?

    Yes. Treasury bills are marketable securities and can generally be sold in the secondary market before maturity. The selling price may be higher or lower than your original purchase price because market prices can change.

    6. Are Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Your individual tax situation may differ, so review the applicable IRS rules and tax documents when preparing your return.

    7. Can I buy Treasury bills through a brokerage?

    Yes. Many brokerages offer Treasury securities, including newly issued Treasury bills and, depending on the firm, securities available in the secondary market. Check the brokerage’s current trading terms, pricing and order requirements before buying.

    8. Is holding a Treasury bill until maturity an option?

    Yes. An investor can hold a Treasury bill until its maturity date instead of selling it in the secondary market. This can avoid the need to sell at a changing market price, but the appropriate approach depends on when the investor expects to need the money.

    FAQ NOTE

    Treasury auction procedures, account rules and tax requirements can change. Check current TreasuryDirect and IRS information before placing a purchase or making a tax decision.

    Final Takeaway: How to Buy Treasury Bills

    Buying Treasury bills comes down to a few practical decisions. Choose where you want to buy, select a maturity that matches your cash timeline, decide how much you want to invest and review the order details before submitting the purchase.

    TreasuryDirect provides a direct way to purchase newly issued Treasury securities. A brokerage can place Treasury bills alongside other investments and, depending on the firm, may also provide access to the secondary market. Your choice of platform should reflect how you want to purchase and manage the investment.

    Before placing an order, check the maturity date, purchase amount, pricing, tax treatment and the process for selling before maturity. If you are still comparing Treasury bill basics, our

    Treasury Bills Explained guide

    can help you review how these securities work.

    FINAL CHECK

    The key connection is between the Treasury bill’s maturity date and your expected cash need. Once that timeline is clear, you can compare the available buying routes, review the costs and understand what happens if your plans change before maturity.

    Have a Money Question? Keep Exploring.

    Understanding how to buy Treasury bills is one step. You can continue exploring Treasury maturities, pricing and other fixed-income topics to make more informed decisions about your cash.

    📩 Get in Touch With FinanceInvestment

    Have a question, suggestion or Treasury topic you would like us to cover?


    Email FinanceInvestment

  • How Much Can $50,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $50,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $50,000 Earn in Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 20, 2026


    Reading Time: ~14 minutes

    How Much Can $50,000 Earn in Treasury Bills?

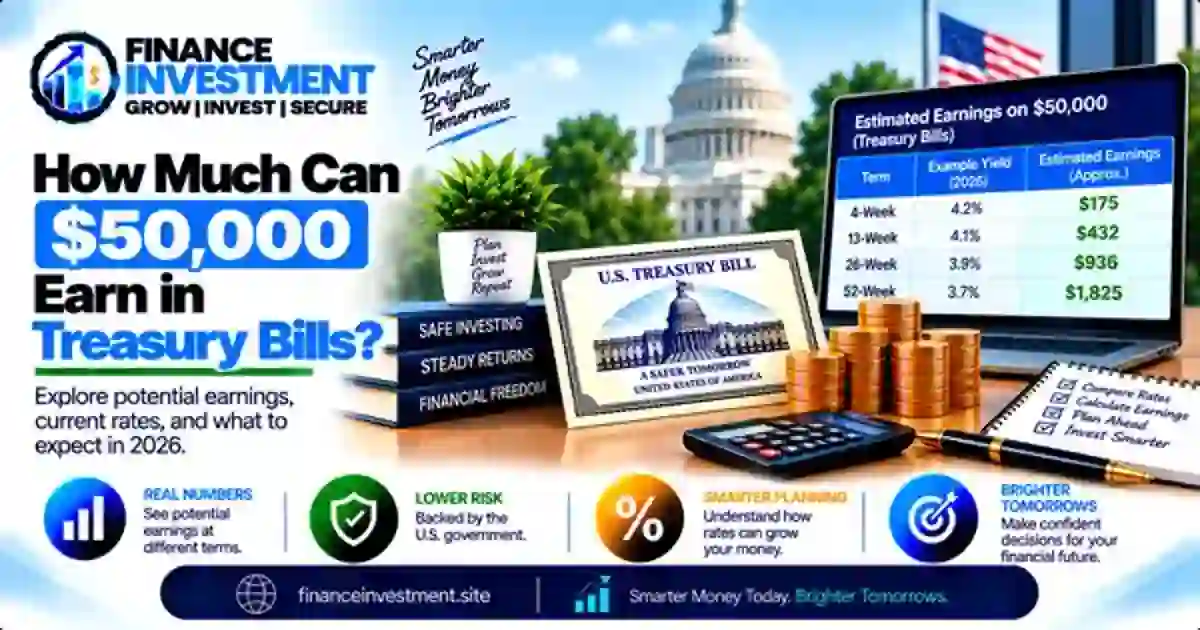
    How Much Can $50,000 Earn in Treasury Bills?How Much Can $50,000 Earn in Treasury Bills? There is no single answer because your potential return depends on the T-bill’s purchase price, maturity and yield available when you invest. With $50,000, the purchase price can make a noticeable difference in the gross amount you receive at maturity.

    Treasury bills also work differently from a savings account that may credit interest periodically. A T-bill is generally purchased at a discount to its face value and pays its face value at maturity when held to maturity. That makes both the price you pay and the date your money comes back important parts of the calculation.

    What You’ll Learn

    • How earnings on a $50,000 Treasury bill are calculated.
    • How 4-, 8-, 13-, 26- and 52-week maturities affect your cash timeline.
    • Why the purchase price matters when estimating your gross return.
    • How federal taxes and early-sale pricing can affect your results.
    • What to consider before placing the full $50,000 into one T-bill maturity.

    If Treasury bills are new to you, start with our

    complete Treasury Bills guide

    for the basic terminology and mechanics before moving into the $50,000 examples and maturity comparisons below.

    Quick Answer: What Could $50,000 Earn?

    The potential earnings on $50,000 in Treasury bills depend on the purchase price, maturity and yield available when you invest. If a $50,000 face-value bill is purchased for less than $50,000 and held to maturity, the difference between those amounts is the gross return before taxes.

    Key Takeaways

    • The face value of the bill and the amount you pay for it can be different.
    • Your gross return is the difference between the purchase price and the amount paid at maturity.
    • T-bill yields are annualized, so the quoted yield should not be treated as the exact dollar return for every term.
    • A shorter maturity returns the principal sooner, while a longer maturity keeps the money invested for more time.
    • Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • If you reinvest after maturity, the next T-bill may have a different yield.
    BOTTOM LINE

    There is no single earnings figure for every $50,000 T-bill purchase. The actual result starts with the price you pay and the face value you receive at maturity, then depends on taxes and what happens if you sell or reinvest.

    $50,000 Treasury Bill Earnings at a Glance

    A $50,000 T-bill investment can produce different gross returns depending on the purchase price, maturity and yield available when you buy. One important detail comes first: $50,000 can be the bill’s face value or the amount of cash you have available to invest. Those are not necessarily the same thing.

    EXAMPLE FACE VALUE
    $50,000
    GROSS RETURN SOURCE
    Face Value − Purchase Price
    MAIN VARIABLES
    Price, Yield & Maturity

    Maturity and Cash-Planning Snapshot

    MaturityApprox. TimelineExample Cash-Planning Role
    4 weeksAbout 1 monthVery short-term cash timeline
    8 weeksAbout 2 monthsNear-term cash planning
    13 weeksAbout 3 monthsRoughly quarterly timing
    26 weeksAbout 6 monthsMedium-term cash planning
    52 weeksAbout 1 yearLonger cash-planning horizon
    QUICK TAKE

    With $50,000, the maturity date can be an important part of the decision because more cash is involved. Start with when you expect to need the money, then compare the available T-bill terms and pricing for that timeline.

    Complete Beginner Guide: How $50,000 in T-Bills Works

    How Much Can $50,000 Earn in Treasury Bills?Treasury bills are short-term U.S. government securities with maturities of one year or less. If you have $50,000 available, you can use that cash to purchase T-bills, but the face value of the bills you receive does not have to equal exactly $50,000 because T-bills are generally purchased at a discount.
    What Happens After You Buy

    Suppose you purchase a hypothetical T-bill with a $50,000 face value for less than $50,000. If you hold that bill until maturity, you receive its $50,000 face value. The difference between the purchase price and the face value is the gross return before taxes.

    You can buy Treasury bills through TreasuryDirect or through a bank or brokerage. The maturity you choose determines when the bill is scheduled to mature, while the auction or market price determines what you pay. That makes the amount committed and the date you need the money important parts of the decision.

    BEGINNER TIP

    Before buying, write down two things: how much cash you want to commit and when you expect to need it again. Then compare that timeline with the T-bill’s maturity. This gives you a practical starting point before you look closely at the available yield.

    If you want to review the basic mechanics first, read our

    guide to how Treasury bills work
    .
    The next section moves from the buying process to the actual earnings calculation.

    How T-Bill Earnings Are Calculated

    The potential return on a $50,000 Treasury bill comes from the difference between what you pay and the bill’s face value at maturity. Treasury bills generally do not make periodic coupon payments. Instead, they are issued or purchased at a discount and pay the face value at maturity when held to maturity.

    Basic T-Bill Return Formula

    Gross Return = Face Value − Purchase Price

    For example, suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400. If you hold it until maturity, you would receive $50,000. The $600 difference represents the gross return before applicable federal income tax.

    Why the Quoted Yield Matters

    Treasury bill rates are annualized, so a quoted rate should not be treated as the exact dollar return for a shorter maturity. Treasury auction pricing commonly uses a discount-rate convention based on face value and a 360-day year, while the investment rate expresses an annualized return based on the purchase price and the applicable day-count convention. The maturity length therefore matters when translating a quoted rate into an actual dollar result.

    CALCULATION TIP

    When estimating earnings, use the actual purchase price, face value and maturity. Avoid simply multiplying $50,000 by an annualized rate and treating that number as the final return.

    For a closer look at Treasury bill pricing terminology, read our

    Treasury Bill Yield vs. Interest Rate guide
    .

    Benefits and Drawbacks of Investing $50,000 in T-Bills

    Investing $50,000 in Treasury bills can give you a defined maturity date and exposure to short-term U.S. government securities. However, the right maturity depends on when you may need the cash and what you plan to do with it afterward.

    Benefits

    • Short maturities can provide a defined timeline for returning the principal.
    • Treasury bills are obligations of the U.S. government.
    • T-bill interest income is generally exempt from state and local income taxes.
    • Different maturities allow you to match the investment with different cash needs.

    Drawbacks

    • Holding a bill to maturity means waiting until its scheduled maturity date for the face-value payment.
    • Reinvestment can produce a different return if future T-bill yields change.
    • Selling before maturity can result in a market price that is different from what you originally paid.
    • T-bills provide a defined short-term return structure rather than the ownership-based growth potential of stocks.
    BEFORE YOU INVEST

    With $50,000 involved, start with your cash timeline before focusing on the quoted yield. A maturity that fits your planned spending can be more useful than choosing a term based only on its annualized rate.

    4-, 8-, 13-, 26- and 52-Week Treasury Bill Comparison

    The maturity you choose determines how long the $50,000 remains invested before the bill reaches its scheduled maturity date. A shorter term can return the principal sooner, while a longer term extends the period before the next maturity or reinvestment decision.

    MaturityApprox. TimelineCash-Planning RoleMain Consideration
    4 weeksAbout 1 monthVery near-term cash timingShort investment period
    8 weeksAbout 2 monthsNear-term cash timingEarlier reinvestment decision
    13 weeksAbout 3 monthsQuarterly cash timingYield depends on purchase timing
    26 weeksAbout 6 monthsMedium-term cash timingCash stays invested longer
    52 weeksAbout 1 yearLonger cash-planning horizonMaturity is farther away

    Does a Longer Maturity Mean More Earnings?

    Not necessarily. Your actual dollar return depends on the purchase price, face value, maturity and yield available when you buy. A 52-week bill does not automatically produce a larger return simply because it has a longer maturity.

    The maturity you select should also fit your cash needs. If you expect to use part of the $50,000 within a few months, putting that entire amount into a longer-term bill may create a timing problem. A ladder can instead spread purchases across different maturity dates so that portions of the money become available at different times.

    MATURITY TIP

    Start with the date you may need the money. Then compare available T-bill maturities, purchase prices and annualized yields. This keeps both liquidity and potential return in view.

    Costs, Taxes, Risks and Expert Tips

    Before putting $50,000 into Treasury bills, look beyond the quoted yield. The purchase method, taxes, liquidity and the possibility of selling before maturity can all affect the practical outcome.

    Costs and Taxes

    TreasuryDirect does not charge a fee to purchase Treasury securities. Banks and brokerages can have their own account, transaction or trading charges, so review the institution’s current fee schedule before investing. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    Risks to Keep in Mind

    • Selling before maturity can produce a market price that is different from your original purchase price.
    • Reinvestment risk matters because future T-bill yields can change when your bill matures.
    • Inflation can reduce the purchasing power of the return over time.
    EXPERT TIP

    Compare the maturity date with your expected cash needs before focusing on the quoted yield. If early access could matter, understand how your bank or broker handles secondary-market sales and what charges may apply.

    The federal tax treatment can also make T-bills different from some other cash investments. Keep the tax effect in mind when comparing your expected after-tax results.

    Common Mistakes and a $50,000 Treasury Bill Example

    When you invest $50,000 in Treasury bills, the biggest mistakes often come from overlooking the details around price, maturity and reinvestment. A clear plan can help you understand what the investment is actually expected to return and when the money may become available again.

    Mistakes to Avoid

    • Treating an annualized yield as the exact dollar return for the entire maturity.
    • Confusing $50,000 of available cash with a $50,000 face-value T-bill.
    • Choosing a maturity without considering when the cash may be needed.
    • Assuming the same yield will be available when the bill matures and you reinvest.
    • Selling before maturity without checking the current market price and any applicable transaction costs.

    Illustrative $50,000 Example

    Suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400.

    $50,000 − $49,400 = $600 gross return

    This is an illustrative purchase-price example, not a current Treasury quote. The actual purchase price depends on the applicable auction or market conditions.

    If the bill is held to maturity, the investor receives its $50,000 face value. The $600 difference represents the gross return before applicable taxes. The actual annualized yield cannot be determined from these two dollar amounts alone because the maturity period also matters.

    CHECK BEFORE BUYING

    Confirm the face value, purchase price, maturity date and applicable tax treatment before committing the full $50,000.

    Who Should Consider $50,000 in T-Bills?

    A $50,000 Treasury bill allocation may be relevant for investors who have cash available for a defined period and want to use short-term U.S. government securities as part of their cash-management strategy. The appropriate maturity depends on when the money may be needed and whether the investor plans to reinvest the proceeds.

    Situations to Consider

    • You have cash that you do not expect to need before a selected maturity date.
    • You want to spread a larger cash balance across different T-bill maturity dates.
    • You are comparing Treasury bills with other short-term cash-management choices.
    • You understand that the yield available for a future reinvestment can change.
    PLANNING CHECK

    Before committing $50,000, separate money needed for near-term expenses or emergencies from money available for a chosen T-bill maturity. A Treasury bill can serve a specific cash-management purpose without being the only part of an overall financial plan.

    Frequently Asked Questions About $50,000 in Treasury Bills

    1. How much can $50,000 earn in Treasury bills?

    It depends on the purchase price, maturity and yield available when you invest. When held to maturity, the gross return is generally the difference between the bill’s face value and purchase price.

    2. Can I use exactly $50,000 to buy Treasury bills?

    Yes. You can commit $50,000 of available cash to a Treasury bill purchase, subject to the applicable purchase rules. Because T-bills are generally bought at a discount, the face value received at maturity can be higher than the amount you paid.

    3. Do Treasury bills pay monthly interest?

    No. Treasury bills generally do not make periodic coupon payments. They are typically purchased at a discount and pay their face value at maturity.

    4. Are Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    5. Can I sell a Treasury bill before maturity?

    Yes. Treasury bills can generally be sold before maturity through a bank or broker in the secondary market. The selling price can be higher or lower than your original purchase price.

    6. Which T-bill maturity should I choose for $50,000?

    There is no single maturity that fits every cash need. Consider when you expect to need the money, then compare the available maturities, purchase prices and annualized yields.

    7. Can I reinvest my $50,000 after a T-bill matures?

    Yes. After maturity, you can use the proceeds or purchase another Treasury bill. The yield available for the new bill may differ from the previous investment.

    8. Are Treasury bills completely risk-free?

    Treasury bills are U.S. government obligations, but “completely risk-free” can be misleading. Holding a bill to maturity avoids the need to sell at a changing market price, while inflation, reinvestment and early-sale considerations can still affect your overall result.

    Final Takeaway: How Much Can $50,000 Earn in Treasury Bills?

    The answer to How Much Can $50,000 Earn in Treasury Bills? depends on the purchase price, maturity and yield available when you invest. That means there is no single earnings figure that applies to every $50,000 T-bill purchase.

    When held to maturity, a Treasury bill generally pays its face value. The difference between the face value and purchase price represents the gross return before applicable taxes. Federal income tax can apply, while Treasury bill interest is generally exempt from state and local income taxes.

    THE BIG PICTURE

    For a $50,000 investment, pay attention to three core details: the purchase price, the face value at maturity and the date the money becomes available. Then account for taxes and your plans for the proceeds after maturity.

    Before You Invest

    Compare the available T-bill maturities, purchase prices and current auction information for the date you plan to invest. If you want to review the fundamentals again, explore our

    Treasury Bills guide

    before comparing specific opportunities.

    Have a Money Question? Keep Exploring.

    Get practical personal finance insights, investing guides and helpful money research from FinanceInvestment.

    📩 Get in Touch With FinanceInvestment


    Email FinanceInvestment

    Continue Your Research