Treasury Bills vs Money Market Accounts
Treasury Bills vs Money Market Accounts: What Should You Know?
 Treasury Bills vs Money Market Accounts is a useful comparison when you have cash you want to keep relatively low-risk while still earning a return. The two products may look similar at first, but they work differently. A Treasury bill is a short-term U.S. government security, while a money market account is a deposit account offered by a bank or credit union.
The difference becomes especially important when you need the money. A money market account generally provides ongoing access according to its account terms, while a T-bill has a maturity date and a marketable bill can generally be sold before maturity. Rates also behave differently: an MMA rate can change, while the return on a T-bill depends on its purchase price and the amount paid at maturity.
What You’ll Learn
- How Treasury bills and money market accounts work.
- How FDIC or NCUA coverage differs from U.S. government backing.
- How maturity, liquidity, and changing rates affect your cash.
- How federal, state, and local taxes can affect your after-tax return.
- Which fees, account restrictions, and early-sale considerations deserve attention.
If you’re new to T-bills, start with our Treasury Bills Explained guide, then use this comparison to see how a Treasury security differs from a money market account.
Quick Answer: Treasury Bills vs Money Market Accounts
These products provide different ways to manage short-term cash. A Treasury bill is a short-term U.S. government security with a defined maturity, while a money market account is a deposit account with access governed by its terms. Eligible deposits at FDIC-insured banks can receive FDIC insurance within applicable limits. Treasury bills are not FDIC-insured; their backing comes from the U.S. government.
Key Takeaways
- They are different products. A T-bill is a Treasury security, while an MMA is a deposit account offered by a bank or credit union.
- Protection works differently. Eligible bank deposits may receive FDIC insurance, while eligible credit-union shares may receive NCUA insurance. T-bills are backed by the U.S. government rather than deposit insurance.
- Maturity matters. A T-bill has a specific maturity date, while an MMA does not have a fixed maturity.
- Rates behave differently. An MMA’s APY can change, while a T-bill’s return is based on its purchase price and maturity value when held to maturity.
- Early access is different. MMA funds can generally be accessed according to account terms. A marketable T-bill can generally be sold before maturity at the market price available at that time.
- Taxes can affect the result. T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. MMA interest is generally taxable income and may also be subject to applicable state and local taxes.
BOTTOM LINE: Compare the product structure, applicable protection, access rules, current yield or APY, taxes, fees, and when you may need the money. Those details can matter more than the headline rate alone.
Table of Contents
Treasury Bills vs Money Market Accounts at a Glance
Both products can be used for short-term cash, but they have different structures. A T-bill is a short-term U.S. Treasury security with a defined maturity. A money market account is a deposit or share account with access and rate terms set by the financial institution.
| Feature | Treasury Bills | Money Market Account |
|---|---|---|
| Product | Short-term U.S. Treasury security | Deposit account at a bank or share account at a credit union |
| Maturity | One year or less, with a specific maturity date | No fixed maturity date |
| Protection | Backed by the full faith and credit of the U.S. government; not FDIC-insured | Eligible deposits at FDIC-insured banks may receive FDIC insurance; eligible shares at federally insured credit unions may receive NCUA insurance |
| Rate behavior | Purchase price and maturity value determine the return when held to maturity | APY can change according to the account’s terms |
| Early access | A marketable bill can generally be sold before maturity at the market price | Access follows the account agreement and applicable rules |
| Tax treatment | Interest generally subject to federal income tax but exempt from state and local income taxes | Interest generally taxable as income and may also be subject to applicable state and local taxes |
A T-bill may fit cash with a defined time frame. An MMA may fit cash that needs ongoing access under its account terms.
At an FDIC-insured bank, the standard FDIC insurance limit is $250,000 per depositor, per insured bank, for each ownership category, subject to applicable rules.
QUICK TAKE: The central difference is structure. A T-bill is a marketable Treasury security with a maturity date, while an MMA is an ongoing deposit or share account. Protection, access, rate changes, taxes, fees, and your expected cash date all deserve a closer look.
Treasury Bills vs Money Market Accounts: A Beginner’s Guide
 If you’re new to this comparison, start with one simple question: what exactly is your money buying? A Treasury bill buys a short-term U.S. government security. A money market account keeps your money in a deposit account at a bank or a share account at a credit union.
What Is a Money Market Account?
A money market account is a deposit product at a bank or a money market share account at a credit union. Depending on the institution, it may offer features such as check-writing or debit-card access. Interest rates, minimum balances, fees, and transaction rules depend on the account.
At an FDIC-insured bank, eligible money market deposit accounts are covered by FDIC insurance within applicable limits. At a federally insured credit union, eligible money market share accounts can receive NCUA share insurance. These protections are different from the government backing of a Treasury security.
What Is a Treasury Bill?
A Treasury bill, or T-bill, is a short-term U.S. Treasury security with a maturity of one year or less. Treasury bills are generally sold at a discount or at face value. When a bill matures, Treasury pays its face value; the difference between the purchase price and maturity value represents the interest when bought at a discount.
You can buy T-bills through TreasuryDirect, a bank, or a broker. Because T-bills are marketable securities, they can generally be sold before maturity. If you sell early, the amount you receive depends on the market price at that time. For a deeper introduction, see our guide to how Treasury bills work.
SIMPLE WAY TO REMEMBER IT: An MMA is an ongoing deposit or share account with institution-specific terms. A T-bill is a short-term Treasury security with a maturity date and a market price if you sell it before maturity.
How Treasury Bills & Money Market Accounts Work
The easiest way to understand the difference is to follow the money. With a T-bill, you purchase a short-term Treasury security with a specific maturity date. With a money market account, you deposit cash with a financial institution and earn interest under the account’s terms.
How Treasury Bills Work
Treasury bills are sold through auctions and are issued at a discount to their par amount. When a bill reaches maturity, the Treasury pays its par amount. For a discounted bill, the difference between what you paid and the amount received at maturity represents the interest earned.
You do not have to wait until maturity if you need to sell a marketable T-bill. It can generally be sold in the secondary market, but its market price can be higher or lower than your purchase price. That means early sale is different from simply withdrawing cash from an account.
How Money Market Accounts Work
With an MMA, you deposit money into an eligible account at a bank or credit union. The institution pays interest according to its current account terms, so the rate can change. Depending on the account, you may also receive features such as check-writing or debit-card access, along with specific withdrawal or transaction rules.
KEY IDEA: A T-bill has a defined maturity and a market price if sold before maturity. An MMA has no fixed maturity, but its interest rate, fees, and access rules depend on the account agreement.
Benefits and Drawbacks of Treasury Bills vs Money Market Accounts
Neither product is designed for every cash-management situation. The practical difference comes down to your time frame, access needs, protection, taxes, and how comfortable you are with either a changing account rate or a security that has a maturity date.
Treasury Bills: Benefits and Drawbacks
- Backed by the full faith and credit of the U.S. government rather than FDIC deposit insurance.
- A defined maturity can help when you have a known future cash date.
- Interest is generally subject to federal income tax but exempt from state and local income taxes.
- Marketable T-bills can generally be sold before maturity.
- The maturity date means you need to consider when the cash will become available without selling.
- Selling before maturity exposes you to the market price at the time of sale.
- Buying and managing securities can require more steps than keeping cash in a bank account.
- T-bills are not FDIC-insured deposits.
Money Market Accounts: Benefits and Drawbacks
- There is no fixed maturity date, so the account can remain open while your cash needs change.
- Eligible deposits at FDIC-insured banks can receive FDIC insurance within applicable limits.
- Some accounts offer convenient features such as checks or debit-card access.
- The interest rate can change according to the account’s terms.
- Minimum balances, fees, or transaction restrictions may apply.
- Interest generally does not receive the same state and local tax treatment as Treasury bill interest.
KEY IDEA: T-bills combine a defined maturity with marketability, while an MMA provides an ongoing account structure with institution-specific rates and access rules. The right comparison depends on when you need the money and how you value access, protection, taxes, and rate stability.
Treasury Bills vs Money Market Accounts: Detailed Comparison
Looking at the products side by side makes the practical differences easier to understand. The right comparison is not just about yield. Your cash timeline, access needs, taxes, fees, and type of protection can all affect the decision.
| Feature | Treasury Bills | Money Market Account |
|---|---|---|
| Product type | Short-term U.S. Treasury marketable security | Deposit account at a bank or share account at a credit union |
| Maturity | One year or less, with a specific maturity date | No fixed maturity date |
| How return is earned | For a bill held to maturity, the return is generally based on the purchase price and amount paid at maturity | Interest is paid according to the account’s current rate and terms |
| Rate behavior | The return for a specific bill is established by its purchase price and maturity value when held to maturity | The APY can change according to the account agreement |
| Protection | Not FDIC-insured; backed by the full faith and credit of the U.S. government | Eligible deposits at FDIC-insured banks may receive FDIC insurance; eligible shares at federally insured credit unions may receive NCUA insurance |
| Access to cash | Paid at maturity, or a marketable bill can generally be sold before maturity | Withdrawals and transfers follow the account agreement and applicable rules |
| Early-access consideration | Selling before maturity means accepting the market price available at the time of sale | Fees, transaction limits, minimum-balance requirements, or other restrictions may apply |
| Federal taxes | Interest is generally subject to federal income tax | Interest is generally taxable income |
| State & local taxes | Interest is generally exempt from state and local income taxes | Interest may be subject to applicable state and local income taxes |
| Common features | Marketable security rather than a transaction account | Some accounts may offer checks, debit cards, or other access features |
| Key question | When will you need the money, and are you comfortable holding until maturity? | What APY, access rules, fees, and insurance coverage does the specific account provide? |
HOW TO USE THIS TABLE: Start with your expected cash date. Then compare the current T-bill yield or MMA APY, applicable protection, tax treatment, access rules, fees, and what could happen if you need the money earlier than planned.
Costs, Risks and Expert Tips
A strong comparison goes beyond the advertised yield. Before moving your cash, look at how you will buy the product, what access may cost, how taxes affect the return, and what happens if your plans change.
Costs and Risks to Check
- T-bills: TreasuryDirect charges no purchase fee or commission, but a brokerage may have its own fees or terms. Selling before maturity also exposes you to the market price at the time of sale.
- Money market accounts: Check the specific account for monthly fees, minimum-balance requirements, transaction restrictions, and other charges. The APY may also change under the account terms.
- Taxes: Compare after-tax returns rather than headline yields alone. T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.
- Protection: Confirm whether the MMA is a deposit account at an FDIC-insured bank or an eligible share account at a federally insured credit union, and review the applicable insurance limits.
Expert Tips Before You Choose
- Start with the date you expect to need the cash.
- Compare the current T-bill yield with the MMA APY after considering taxes and applicable fees.
- Read the MMA’s account disclosures before opening it, including its rate, minimum balance, fees, and transaction rules.
- If considering a T-bill, note the maturity date and understand the possible price impact of selling before maturity.
EXPERT TIP: Don’t compare a T-bill yield with an MMA APY in isolation. First determine how long the money can stay invested, then account for taxes, fees, access requirements, and the protection that applies to the specific product.
Common Mistakes and a Real-Life Example
The details matter when comparing T-bills with an MMA. A few common mistakes can make an otherwise simple cash decision more complicated.
Common Mistakes to Avoid
- Looking only at the headline rate: Taxes, fees, changing APYs, and the timing of your cash need can affect the actual outcome.
- Confusing an MMA with a money market fund: A money market account is a deposit or share account, while a money market fund is an investment product with different risks and protections.
- Ignoring the T-bill maturity date: If you need the money on a specific date, make sure the bill’s maturity fits your timeline.
- Assuming an early T-bill sale returns the original amount: A marketable T-bill sold before maturity is subject to the market price available at the time of sale.
- Assuming every MMA has FDIC coverage: Verify whether the account is an eligible deposit at an FDIC-insured bank. Eligible shares at federally insured credit unions have separate NCUA share insurance.
Real-Life Example
Imagine a family has $25,000 that it expects to use in about six months. If the money can remain untouched until a known date, a T-bill with a maturity that fits the timeline could provide a defined maturity value. If the family may need the cash unexpectedly, an MMA could provide account-based access subject to its terms.
The family could then compare the current T-bill yield with the MMA’s current APY, along with applicable taxes, fees, protection, and access rules. If early access might be necessary, it should also consider the potential market-price impact of selling a T-bill before maturity.
KEY LESSON: Match the product to the job. A defined future cash date can make T-bill maturity important, while uncertain spending needs can make an MMA’s account access more relevant.
Who Should Consider Treasury Bills or Money Market Accounts?
The better fit depends on what you need your cash to do. Consider your expected cash date, access needs, taxes, fees, and the protection that applies to the specific product and institution.
Treasury Bills May Fit You If:
- You have a known cash need that matches a T-bill’s maturity date.
- You want to hold a short-term U.S. Treasury security rather than keep the money in a deposit account.
- State and local tax treatment is relevant to your after-tax return.
- You are comfortable holding the bill to maturity or accepting market-price risk if you sell before maturity.
Money Market Accounts May Fit You If:
- You want an ongoing account without a fixed maturity date.
- You may need access to the cash according to the account’s withdrawal and transaction rules.
- You value features such as check-writing or debit-card access when offered by the account.
- You want eligible deposit or share insurance and have confirmed that the specific institution and account qualify.
QUICK CHECK: If your cash date is predictable, start with maturity, yield, and after-tax return. If your cash needs are less predictable, examine account access, fees, rate changes, and applicable FDIC or NCUA insurance coverage.
Frequently Asked Questions About Treasury Bills vs Money Market Accounts
1. Are Treasury bills safer than money market accounts?
They have different structures and forms of protection. T-bills are U.S. Treasury securities, while eligible money market deposit accounts at FDIC-insured banks can receive FDIC insurance within applicable limits. The comparison depends on which type of risk and protection you are evaluating.
2. Are Treasury bills FDIC-insured?
No. Treasury bills are not FDIC-insured deposits. They are U.S. Treasury securities backed by the full faith and credit of the U.S. government.
3. Is a money market account FDIC-insured?
A money market deposit account at an FDIC-insured bank can receive FDIC insurance within applicable limits. A federally insured credit union has separate NCUA share insurance rules for eligible member accounts.
4. Can you sell a Treasury bill before maturity?
Yes. Marketable T-bills can generally be sold before maturity through the secondary market. The amount you receive depends on the market price at the time of sale and can be different from your original purchase price.
5. Which has easier access to cash?
An MMA may provide account-based access through features offered by the financial institution, subject to its terms and applicable rules. A T-bill has a fixed maturity date, although a marketable bill can generally be sold before maturity.
6. Are T-bill earnings taxed?
T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. Your individual tax circumstances can affect the final after-tax result.
7. Can a money market account rate change?
Yes. Money market accounts commonly have variable rates, so the APY can change according to the account’s terms and prevailing rate environment.
8. Which should you use for short-term cash?
There is no single answer for every situation. Compare your cash timeline, current T-bill yield or MMA APY, taxes, fees, access requirements, and applicable government or deposit insurance protection before choosing.
REMEMBER: A money market account is different from a money market fund. An MMA can be a deposit or share account, while a money market fund is an investment product with different risks and protections.
Treasury Bills vs Money Market Accounts: Final Comparison
Treasury bills and money market accounts can both be used for short-term cash, but they operate differently. A T-bill is a marketable U.S. Treasury security with a defined maturity. An MMA is an ongoing deposit or share account with institution-specific rates, fees, access rules, and applicable insurance coverage.
Start the comparison with your expected cash date. Then review the current T-bill yield or MMA APY, tax treatment, fees, access requirements, and applicable protection. With a T-bill, consider whether you can hold it until maturity or might need to sell before maturity. With an MMA, review the specific account’s rate, minimum balance, transaction rules, and insurance eligibility.
FINAL CHECK: Don’t compare these products by yield alone. Your cash timeline, desired access, tax situation, fees, and applicable protection can all affect how the two options compare.
For a broader introduction, read our Treasury Bills Explained guide. You can also explore our Money Market Accounts guide for more information about account features, rates, and rules.
 If you’re new to this comparison, begin with one practical question: when might you need this money? A high-yield savings account keeps your cash in a bank deposit, while a Treasury bill places it in a short-term U.S. government security. That basic difference explains much of the comparison.
 If you’re new to this comparison, start with one simple question: Where is your money actually going? That answer makes the difference between a Treasury bill and a savings account much easier to understand.
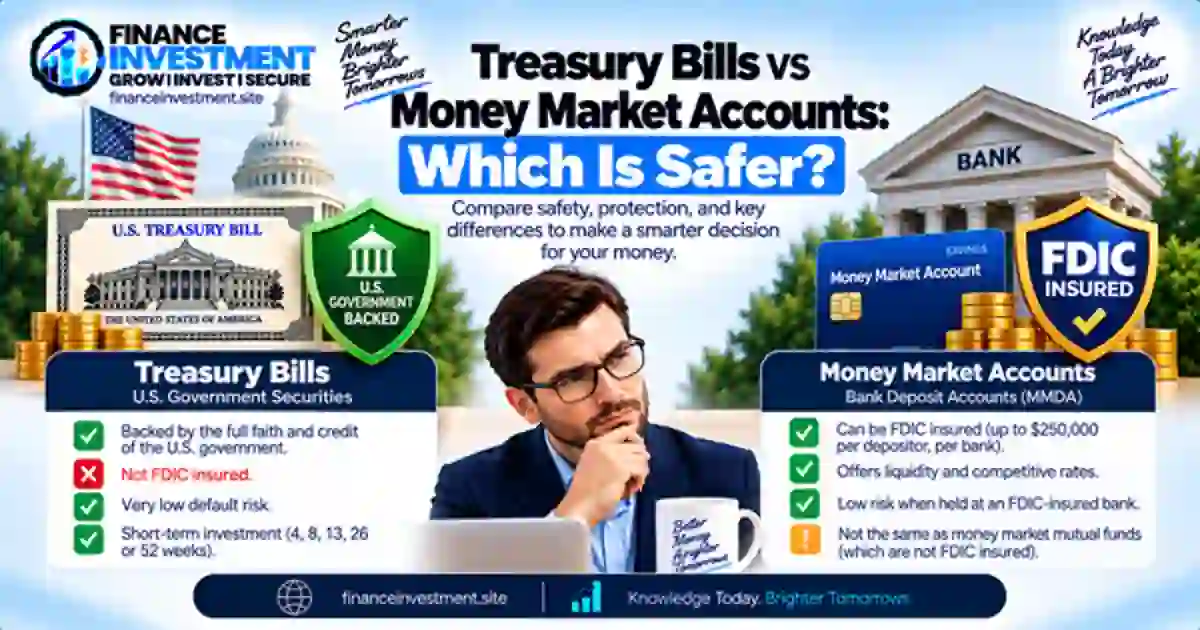
 Before comparing safety, it helps to understand what you actually own. Treasury bills and money market accounts can both be used for short-term cash, but they are different financial products. One is a U.S. government security, while the other is a deposit account.
 If you are new to T-bills, the easiest way to understand their safety is to separate the issuer’s ability to meet its obligation from what can happen to the investment before maturity. Treasury bills are debt obligations issued by the U.S. Department of the Treasury and are considered among the safest investments because they carry the full faith and credit of the U.S. government.
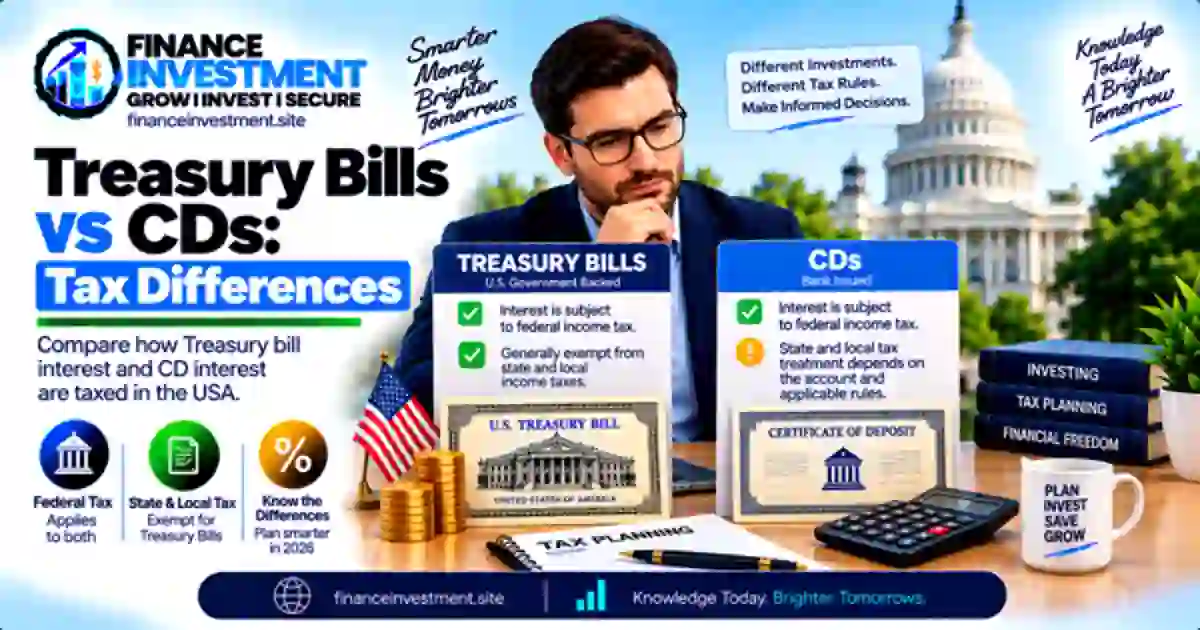
 When comparing Treasury bills and CDs, the advertised yield is only part of the picture. Both can generate taxable income, but the tax treatment is not identical. The biggest difference is what happens at the state and local level.