How Much Can $50,000 Earn in Treasury Bills?
How Much Can $50,000 Earn in Treasury Bills?
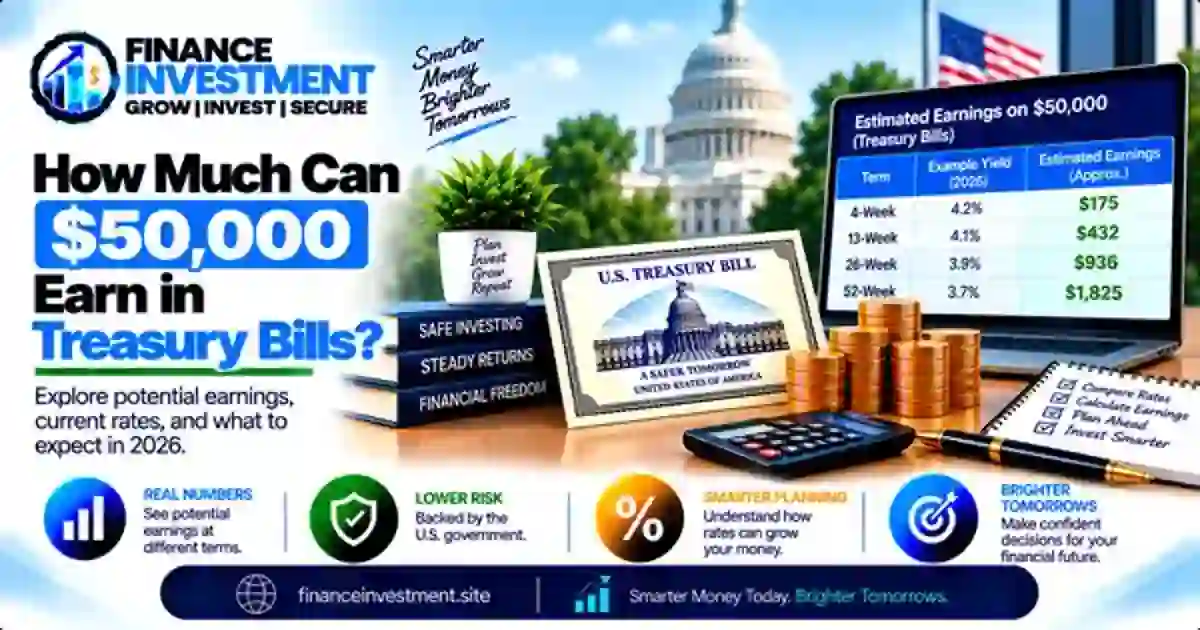 How Much Can $50,000 Earn in Treasury Bills? There is no single answer because your potential return depends on the T-bill’s purchase price, maturity and yield available when you invest. With $50,000, the purchase price can make a noticeable difference in the gross amount you receive at maturity.
Treasury bills also work differently from a savings account that may credit interest periodically. A T-bill is generally purchased at a discount to its face value and pays its face value at maturity when held to maturity. That makes both the price you pay and the date your money comes back important parts of the calculation.
What You’ll Learn
- How earnings on a $50,000 Treasury bill are calculated.
- How 4-, 8-, 13-, 26- and 52-week maturities affect your cash timeline.
- Why the purchase price matters when estimating your gross return.
- How federal taxes and early-sale pricing can affect your results.
- What to consider before placing the full $50,000 into one T-bill maturity.
If Treasury bills are new to you, start with our
complete Treasury Bills guide
for the basic terminology and mechanics before moving into the $50,000 examples and maturity comparisons below.
Quick Answer: What Could $50,000 Earn?
The potential earnings on $50,000 in Treasury bills depend on the purchase price, maturity and yield available when you invest. If a $50,000 face-value bill is purchased for less than $50,000 and held to maturity, the difference between those amounts is the gross return before taxes.
Key Takeaways
- The face value of the bill and the amount you pay for it can be different.
- Your gross return is the difference between the purchase price and the amount paid at maturity.
- T-bill yields are annualized, so the quoted yield should not be treated as the exact dollar return for every term.
- A shorter maturity returns the principal sooner, while a longer maturity keeps the money invested for more time.
- Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
- If you reinvest after maturity, the next T-bill may have a different yield.
There is no single earnings figure for every $50,000 T-bill purchase. The actual result starts with the price you pay and the face value you receive at maturity, then depends on taxes and what happens if you sell or reinvest.
$50,000 Treasury Bill Earnings at a Glance
A $50,000 T-bill investment can produce different gross returns depending on the purchase price, maturity and yield available when you buy. One important detail comes first: $50,000 can be the bill’s face value or the amount of cash you have available to invest. Those are not necessarily the same thing.
Maturity and Cash-Planning Snapshot
| Maturity | Approx. Timeline | Example Cash-Planning Role |
|---|---|---|
| 4 weeks | About 1 month | Very short-term cash timeline |
| 8 weeks | About 2 months | Near-term cash planning |
| 13 weeks | About 3 months | Roughly quarterly timing |
| 26 weeks | About 6 months | Medium-term cash planning |
| 52 weeks | About 1 year | Longer cash-planning horizon |
With $50,000, the maturity date can be an important part of the decision because more cash is involved. Start with when you expect to need the money, then compare the available T-bill terms and pricing for that timeline.
Complete Beginner Guide: How $50,000 in T-Bills Works
 Treasury bills are short-term U.S. government securities with maturities of one year or less. If you have $50,000 available, you can use that cash to purchase T-bills, but the face value of the bills you receive does not have to equal exactly $50,000 because T-bills are generally purchased at a discount.
What Happens After You Buy
Suppose you purchase a hypothetical T-bill with a $50,000 face value for less than $50,000. If you hold that bill until maturity, you receive its $50,000 face value. The difference between the purchase price and the face value is the gross return before taxes.
You can buy Treasury bills through TreasuryDirect or through a bank or brokerage. The maturity you choose determines when the bill is scheduled to mature, while the auction or market price determines what you pay. That makes the amount committed and the date you need the money important parts of the decision.
Before buying, write down two things: how much cash you want to commit and when you expect to need it again. Then compare that timeline with the T-bill’s maturity. This gives you a practical starting point before you look closely at the available yield.
If you want to review the basic mechanics first, read our
guide to how Treasury bills work
.
The next section moves from the buying process to the actual earnings calculation.
How T-Bill Earnings Are Calculated
The potential return on a $50,000 Treasury bill comes from the difference between what you pay and the bill’s face value at maturity. Treasury bills generally do not make periodic coupon payments. Instead, they are issued or purchased at a discount and pay the face value at maturity when held to maturity.
Basic T-Bill Return Formula
For example, suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400. If you hold it until maturity, you would receive $50,000. The $600 difference represents the gross return before applicable federal income tax.
Why the Quoted Yield Matters
Treasury bill rates are annualized, so a quoted rate should not be treated as the exact dollar return for a shorter maturity. Treasury auction pricing commonly uses a discount-rate convention based on face value and a 360-day year, while the investment rate expresses an annualized return based on the purchase price and the applicable day-count convention. The maturity length therefore matters when translating a quoted rate into an actual dollar result.
When estimating earnings, use the actual purchase price, face value and maturity. Avoid simply multiplying $50,000 by an annualized rate and treating that number as the final return.
For a closer look at Treasury bill pricing terminology, read our
Treasury Bill Yield vs. Interest Rate guide
.
Benefits and Drawbacks of Investing $50,000 in T-Bills
Investing $50,000 in Treasury bills can give you a defined maturity date and exposure to short-term U.S. government securities. However, the right maturity depends on when you may need the cash and what you plan to do with it afterward.
Benefits
- Short maturities can provide a defined timeline for returning the principal.
- Treasury bills are obligations of the U.S. government.
- T-bill interest income is generally exempt from state and local income taxes.
- Different maturities allow you to match the investment with different cash needs.
Drawbacks
- Holding a bill to maturity means waiting until its scheduled maturity date for the face-value payment.
- Reinvestment can produce a different return if future T-bill yields change.
- Selling before maturity can result in a market price that is different from what you originally paid.
- T-bills provide a defined short-term return structure rather than the ownership-based growth potential of stocks.
With $50,000 involved, start with your cash timeline before focusing on the quoted yield. A maturity that fits your planned spending can be more useful than choosing a term based only on its annualized rate.
4-, 8-, 13-, 26- and 52-Week Treasury Bill Comparison
The maturity you choose determines how long the $50,000 remains invested before the bill reaches its scheduled maturity date. A shorter term can return the principal sooner, while a longer term extends the period before the next maturity or reinvestment decision.
| Maturity | Approx. Timeline | Cash-Planning Role | Main Consideration |
|---|---|---|---|
| 4 weeks | About 1 month | Very near-term cash timing | Short investment period |
| 8 weeks | About 2 months | Near-term cash timing | Earlier reinvestment decision |
| 13 weeks | About 3 months | Quarterly cash timing | Yield depends on purchase timing |
| 26 weeks | About 6 months | Medium-term cash timing | Cash stays invested longer |
| 52 weeks | About 1 year | Longer cash-planning horizon | Maturity is farther away |
Does a Longer Maturity Mean More Earnings?
Not necessarily. Your actual dollar return depends on the purchase price, face value, maturity and yield available when you buy. A 52-week bill does not automatically produce a larger return simply because it has a longer maturity.
The maturity you select should also fit your cash needs. If you expect to use part of the $50,000 within a few months, putting that entire amount into a longer-term bill may create a timing problem. A ladder can instead spread purchases across different maturity dates so that portions of the money become available at different times.
Start with the date you may need the money. Then compare available T-bill maturities, purchase prices and annualized yields. This keeps both liquidity and potential return in view.
Costs, Taxes, Risks and Expert Tips
Before putting $50,000 into Treasury bills, look beyond the quoted yield. The purchase method, taxes, liquidity and the possibility of selling before maturity can all affect the practical outcome.
Costs and Taxes
TreasuryDirect does not charge a fee to purchase Treasury securities. Banks and brokerages can have their own account, transaction or trading charges, so review the institution’s current fee schedule before investing. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
Risks to Keep in Mind
- Selling before maturity can produce a market price that is different from your original purchase price.
- Reinvestment risk matters because future T-bill yields can change when your bill matures.
- Inflation can reduce the purchasing power of the return over time.
Compare the maturity date with your expected cash needs before focusing on the quoted yield. If early access could matter, understand how your bank or broker handles secondary-market sales and what charges may apply.
The federal tax treatment can also make T-bills different from some other cash investments. Keep the tax effect in mind when comparing your expected after-tax results.
Common Mistakes and a $50,000 Treasury Bill Example
When you invest $50,000 in Treasury bills, the biggest mistakes often come from overlooking the details around price, maturity and reinvestment. A clear plan can help you understand what the investment is actually expected to return and when the money may become available again.
Mistakes to Avoid
- Treating an annualized yield as the exact dollar return for the entire maturity.
- Confusing $50,000 of available cash with a $50,000 face-value T-bill.
- Choosing a maturity without considering when the cash may be needed.
- Assuming the same yield will be available when the bill matures and you reinvest.
- Selling before maturity without checking the current market price and any applicable transaction costs.
Illustrative $50,000 Example
Suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400.
This is an illustrative purchase-price example, not a current Treasury quote. The actual purchase price depends on the applicable auction or market conditions.
If the bill is held to maturity, the investor receives its $50,000 face value. The $600 difference represents the gross return before applicable taxes. The actual annualized yield cannot be determined from these two dollar amounts alone because the maturity period also matters.
Confirm the face value, purchase price, maturity date and applicable tax treatment before committing the full $50,000.
Who Should Consider $50,000 in T-Bills?
A $50,000 Treasury bill allocation may be relevant for investors who have cash available for a defined period and want to use short-term U.S. government securities as part of their cash-management strategy. The appropriate maturity depends on when the money may be needed and whether the investor plans to reinvest the proceeds.
Situations to Consider
- You have cash that you do not expect to need before a selected maturity date.
- You want to spread a larger cash balance across different T-bill maturity dates.
- You are comparing Treasury bills with other short-term cash-management choices.
- You understand that the yield available for a future reinvestment can change.
Before committing $50,000, separate money needed for near-term expenses or emergencies from money available for a chosen T-bill maturity. A Treasury bill can serve a specific cash-management purpose without being the only part of an overall financial plan.
Frequently Asked Questions About $50,000 in Treasury Bills
1. How much can $50,000 earn in Treasury bills?
It depends on the purchase price, maturity and yield available when you invest. When held to maturity, the gross return is generally the difference between the bill’s face value and purchase price.
2. Can I use exactly $50,000 to buy Treasury bills?
Yes. You can commit $50,000 of available cash to a Treasury bill purchase, subject to the applicable purchase rules. Because T-bills are generally bought at a discount, the face value received at maturity can be higher than the amount you paid.
3. Do Treasury bills pay monthly interest?
No. Treasury bills generally do not make periodic coupon payments. They are typically purchased at a discount and pay their face value at maturity.
4. Are Treasury bill earnings taxable?
Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
5. Can I sell a Treasury bill before maturity?
Yes. Treasury bills can generally be sold before maturity through a bank or broker in the secondary market. The selling price can be higher or lower than your original purchase price.
6. Which T-bill maturity should I choose for $50,000?
There is no single maturity that fits every cash need. Consider when you expect to need the money, then compare the available maturities, purchase prices and annualized yields.
7. Can I reinvest my $50,000 after a T-bill matures?
Yes. After maturity, you can use the proceeds or purchase another Treasury bill. The yield available for the new bill may differ from the previous investment.
8. Are Treasury bills completely risk-free?
Treasury bills are U.S. government obligations, but “completely risk-free” can be misleading. Holding a bill to maturity avoids the need to sell at a changing market price, while inflation, reinvestment and early-sale considerations can still affect your overall result.
Final Takeaway: How Much Can $50,000 Earn in Treasury Bills?
The answer to How Much Can $50,000 Earn in Treasury Bills? depends on the purchase price, maturity and yield available when you invest. That means there is no single earnings figure that applies to every $50,000 T-bill purchase.
When held to maturity, a Treasury bill generally pays its face value. The difference between the face value and purchase price represents the gross return before applicable taxes. Federal income tax can apply, while Treasury bill interest is generally exempt from state and local income taxes.
For a $50,000 investment, pay attention to three core details: the purchase price, the face value at maturity and the date the money becomes available. Then account for taxes and your plans for the proceeds after maturity.
Before You Invest
Compare the available T-bill maturities, purchase prices and current auction information for the date you plan to invest. If you want to review the fundamentals again, explore our
Treasury Bills guide
before comparing specific opportunities.
Leave a Reply