Treasury Bill Price vs Face Value Explained
Treasury Bill Price vs Face Value: Why the Difference Matters
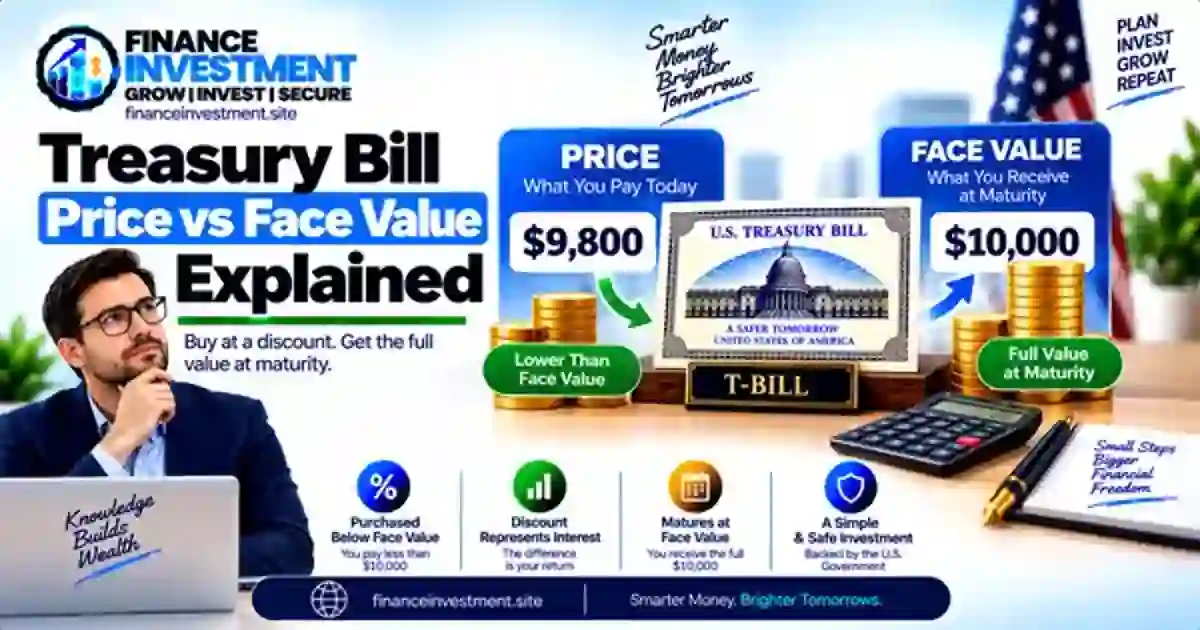 A Treasury bill can have a $1,000 face value but cost less than $1,000 when you buy it. That difference is a key part of how T-bills provide a return. Instead of receiving regular interest payments, you generally buy the bill at a discount and receive its face value when it matures.
For example, suppose a $1,000 Treasury bill has a purchase price of $975. You pay $975 upfront. If you hold the bill until maturity, you receive $1,000. The $25 difference between your purchase price and the face value is the gross return built into that transaction, before considering taxes or any result from selling the bill before maturity.
This is where beginners often get tripped up. Price, face value, discount rate and investment yield are connected, but they measure different things. Once you separate those numbers, a T-bill quote becomes much easier to read.
In this guide, we’ll walk through the numbers step by step. We’ll also connect this topic with our complete Treasury Bills guide so you can see how pricing fits into the bigger picture.
What You’ll Learn
- What Treasury bill price and face value mean.
- Why T-bills can be purchased below face value.
- How the price difference becomes part of your return at maturity.
- How price, discount rate and yield relate to each other.
- How the purchase price affects your actual investment.
- What can happen when you sell a T-bill before maturity.
Quick Answer: How Is Treasury Bill Price Different From Face Value?
A Treasury bill’s face value is the stated amount paid when the bill matures, while its purchase price is the amount you pay to acquire it. T-bills are generally issued at a price below their face value. The difference between those two amounts is the discount, which forms the basic return for an investor who holds the bill until maturity.
Key Takeaways
- The face value is the stated amount the Treasury bill is redeemed for at maturity.
- The purchase price is the amount paid to acquire the bill.
- For a T-bill issued at a discount, the purchase price is lower than its face value.
- The difference between face value and purchase price is the discount amount.
- T-bills do not make periodic coupon payments like Treasury notes and bonds.
- The discount rate is a pricing measure and should not be treated as the same thing as the investor’s annualized return.
BOTTOM LINE: Face value tells you the amount tied to the bill at maturity. Purchase price tells you what you pay upfront. When a T-bill is bought below face value and held to maturity, the difference between those amounts is the basic source of the return.
Table of Contents
Treasury Bill Price vs Face Value at a Glance
The simplest way to read a Treasury bill is to separate its face value from its purchase price. For a newly issued T-bill sold at a discount, you pay less than the bill’s face value. If you hold it until maturity, the bill is redeemed for its stated face value. The difference between those amounts is the discount.
| Quick Fact | What It Means |
|---|---|
| Face value | The stated amount for which the T-bill is redeemed at maturity. |
| Purchase price | The amount an investor pays to acquire the T-bill. |
| Discount | The difference between the face value and the purchase price. |
| Maturity | The date when the T-bill reaches the end of its stated term. |
QUICK TAKE: For example, if a hypothetical T-bill has a $10,000 face value and a $9,800 purchase price, the $200 difference is the discount. If the bill is held to maturity, the stated $10,000 face value is the maturity amount.
Treasury Bill Price vs Face Value: A Complete Beginner Guide
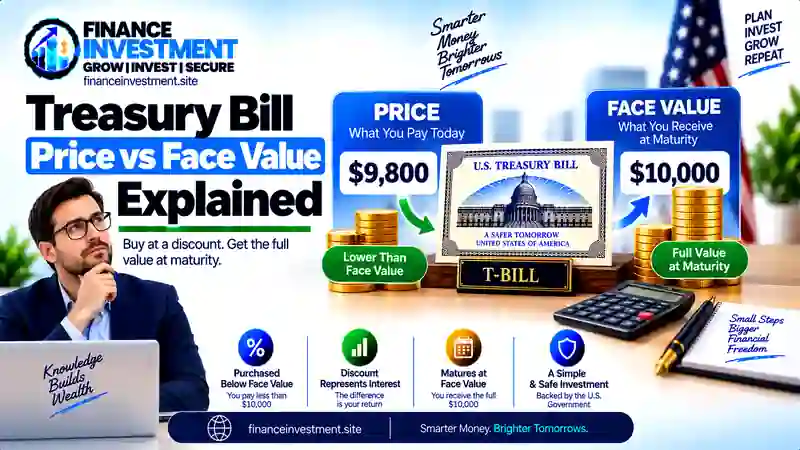 The easiest way to understand a Treasury bill is to separate four numbers: face value, price per $100, purchase price, and discount amount. A newly issued T-bill is generally sold at a price below its face value. If you hold it until maturity, the bill is redeemed at its stated par amount. Treasury bills are short-term securities with maturities of one year or less and do not make periodic coupon payments.
1. Start With Face Value
Face value, also called par value, is the stated dollar amount of the T-bill. Suppose a bill has a $10,000 face value. If you hold that bill until maturity, the Treasury redeems it at its $10,000 par amount. You do not receive separate coupon payments during the bill’s term.
2. Look at the Price Per $100
Treasury bill pricing is expressed on a per-$100-of-face-value basis. For example, a price of $98.00 per $100 means an investor pays $98 for each $100 of face value. For a $10,000 bill, that works out to a $9,800 purchase price. Treasury’s rules use the price per $100 and the par amount to determine the total purchase price.
3. Calculate the Discount Amount
If the $10,000 bill costs $9,800, the discount amount is $200. That is simply the face value minus the purchase price. If you hold the bill until maturity, this difference represents the interest earned through the bill’s discounted purchase structure.
4. Don’t Confuse Price With the Discount Rate
The price tells you how much the bill costs. The discount rate expresses the price difference as an annualized rate using the bill’s face value and a 360-day convention. Treasury uses the discount rate to derive the price per $100. So a quoted discount rate and the resulting purchase price are connected, but they are not the same thing.
BEGINNER TIP: When reading a T-bill quote, ask three questions first: What is the face value? What is the price per $100? How much will I actually pay? Once those numbers are clear, the discount and annualized rates become much easier to understand.
How Treasury Bill Pricing Works
Treasury bill pricing follows a simple chain: the discount rate helps determine the price per $100 of face value, and that price determines how much you actually pay. The face value does not change. What changes is the amount required upfront to buy the bill.
Step 1: Convert the Discount Rate Into a Price
Treasury’s formula for converting a T-bill discount rate into a price per $100 is:
For example, using a hypothetical 5% discount rate and 91 days to maturity, the calculated price is approximately $98.736 per $100 of face value before applying the applicable auction-price rounding convention.
Step 2: Calculate the Purchase Price
Once the price per $100 is known, Treasury calculates the purchase price by dividing the bill’s face value by 100 and multiplying that amount by the price per $100. For a $10,000 face-value T-bill priced at $98.736 per $100, the approximate purchase price would be $9,873.60.
Step 3: Find the Discount
The discount is simply the difference between face value and purchase price. In this example, $10,000 minus $9,873.60 equals approximately $126.40. If the bill is held to maturity, that price-to-face-value difference is the basic return built into the T-bill’s discounted structure.
Treasury Bill Price vs Face Value: Benefits & Drawbacks
The difference between a Treasury bill’s price and face value creates a straightforward way to understand how the bill’s return is built. Still, the price alone does not tell you everything about the investment. Maturity, taxes, market prices and your holding period can all affect the final result.
Benefits of the T-Bill Pricing Structure
- Simple purchase structure: Newly issued Treasury bills are generally bought below face value, with the discount built into the purchase price.
- No periodic coupon payments: T-bills do not make regular interest payments during their term. The difference between the purchase amount and the amount received at maturity represents interest when held to maturity.
- Easy price comparison: The price per $100 makes it easier to compare the upfront cost with the bill’s face value.
- Predictable maturity amount: If you hold the bill until maturity, the Treasury pays the stated face amount, subject to applicable tax withholding or other account-specific considerations.
Drawbacks to Consider
- Price and yield are different: A lower purchase price increases the dollar discount, but it should not be confused with the annualized investment rate.
- Early sale can change the result: If you sell a T-bill before maturity through a brokerage, its market price may be above or below your original purchase price.
- Federal taxes apply: Treasury bill interest is subject to federal income tax, although it is generally exempt from state and local income taxes.
- Inflation still matters: A positive T-bill return does not automatically mean your purchasing power increased after inflation.
Treasury Bill Price vs Face Value vs Yield
Treasury bill price, face value, discount rate and investment rate are connected, but they are not interchangeable. Face value shows the bill’s stated amount at maturity. Price shows the amount paid upfront. The investment rate, also called the coupon-equivalent yield, expresses the annualized return based on the bill’s purchase price.
| Term | What It Means | What It Tells You |
|---|---|---|
| Face Value | The bill’s stated par amount | Amount associated with maturity |
| Purchase Price | The amount paid for the T-bill | Your upfront investment |
| Discount Rate | An annualized rate calculated using par value | The discount quoted on a 360-day basis |
| Investment Rate | An annualized rate based on purchase price | A more useful measure for comparing the bill’s return with other investments |
Why the Discount Rate and Investment Rate Differ
Consider a hypothetical T-bill with a $10,000 face value and a purchase price of $9,800. The $200 difference is the discount. However, that $200 is not automatically a 2% annual return because the bill has a specific time remaining until maturity. The investment rate accounts for the actual purchase price and the holding period. Treasury normally calculates this rate using a 365-day basis, or 366 days when applicable.
Treasury Bill Price vs Face Value: Costs, Risks & Expert Tips
A Treasury bill does not work like a savings account that simply pays a stated interest rate. Your result depends on the price you pay, the amount tied to maturity, the time you hold the bill and the taxes that apply. Looking at these details before buying can prevent common misunderstandings.
Costs to Check Before Buying
- Purchase price: This is the actual amount committed upfront and should be compared with the bill’s face value.
- Brokerage charges: If you buy through a broker, check the firm’s current pricing, spreads or other applicable charges. Costs can vary by provider.
- Taxes: Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes under federal tax rules.
Risks to Understand
- Early-sale price risk: If you sell before maturity, the market price may be different from the amount you originally paid. The result can therefore differ from simply holding the bill to maturity.
- Reinvestment risk: When the bill matures, a new Treasury bill may offer a different rate, so the same return may not be available when you reinvest.
- Inflation risk: A positive nominal return does not guarantee an increase in purchasing power after inflation.
Common Treasury Bill Pricing Mistakes & Real-Life Example
Treasury bill pricing becomes much easier when you keep the key numbers separate. Beginners often make mistakes by treating face value, purchase price, discount rate and investment rate as if they were interchangeable.
Common Mistakes to Avoid
- Confusing face value with purchase price: A $10,000 face-value T-bill can cost less than $10,000 when it is issued at a discount.
- Treating the discount rate as the actual return: Treasury’s discount rate and investment rate use different calculations and day-count conventions.
- Ignoring the holding period: The dollar discount alone does not show the annualized return because the time until maturity also matters.
- Assuming early sale equals maturity: Selling before maturity can produce a different result because the T-bill’s market price may change.
Real-Life Example
Suppose an investor buys a hypothetical Treasury bill with a $10,000 face value for $9,800 and holds it until maturity. The investor pays $9,800 upfront and receives the $10,000 face amount at maturity. The $200 difference is the interest income created by the discounted purchase price. It should not, however, be described as a 2% annual return because the investment rate also depends on the time to maturity and the purchase price.
Who May Consider Treasury Bills?
Treasury bills may fit investors looking for short-term U.S. government debt and a defined maturity date. Because newly issued T-bills are generally sold at a discount, investors can compare the purchase price with the amount received at maturity when evaluating a potential investment.
T-Bills May Fit These Situations
- Short-term goals: You have money that can remain invested until a known maturity date.
- Defined maturity: You prefer a Treasury security with a specific date when the bill matures.
- Price-based investing: You want to evaluate an investment using its purchase price, face value and annualized rate.
- Federal Treasury exposure: You want a direct U.S. government debt security rather than a corporate or municipal obligation.
- Tax considerations: Treasury bill interest is subject to federal income tax but exempt from state and local income taxes under federal tax rules.
When to Compare Other Options
A T-bill may not match every cash need. If you need unrestricted access to your money, want periodic interest payments, or expect to sell before maturity, compare the relevant features, costs and risks of other short-term investments before making a decision.
Frequently Asked Questions About Treasury Bill Price vs Face Value
1. What is the difference between Treasury bill price and face value?
Face value is the stated par amount of a Treasury bill. The purchase price is the amount you pay upfront. Treasury bills are generally issued at a discount, so the purchase price can be lower than the face value paid at maturity.
2. Why are Treasury bills sold below face value?
Treasury bills generally do not make periodic coupon payments. Instead, they are issued at a discount, and the difference between the discounted purchase price and the face value received at maturity represents interest income when the bill is held to maturity.
3. Is the Treasury bill discount rate the same as the investment rate?
No. Treasury calculates the discount rate using the bill’s par value and a 360-day convention. The investment rate, also called the coupon-equivalent yield, is calculated from the purchase price and the applicable annual day count. These rates therefore can differ even for the same T-bill.
4. How do I calculate the discount on a T-bill?
Subtract the purchase price from the face value. For example, a hypothetical $10,000 face-value T-bill purchased for $9,800 has a $200 discount. If held to maturity, that difference represents the bill’s interest income before considering applicable taxes.
5. Can a Treasury bill’s market price change after I buy it?
Yes. If you sell a T-bill before maturity through a brokerage, its market price can change as market conditions change. The amount you receive from an early sale can therefore differ from the amount you would receive by holding the bill until maturity.
6. Are Treasury bill earnings taxable?
Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes under federal tax rules. Your individual tax situation may require additional considerations.
Final Verdict: Understanding Treasury Bill Price vs Face Value
The difference between Treasury bill price and face value comes down to one simple idea: face value is the bill’s stated par amount, while the purchase price is what you pay upfront. When a T-bill is purchased at a discount and held to maturity, the difference between those amounts represents interest income.
For a broader explanation of T-bill maturities, pricing, buying methods and how Treasury bills work, continue with our complete Treasury Bills guide. It provides a useful next step if you want to understand the bigger picture beyond price versus face value.
For this specific topic, check the purchase price, face value, maturity date and applicable investment rate together. The discount rate is a separate measure and should not automatically be treated as the investment’s annualized return. If you sell before maturity, the market price can also affect the amount you receive.
Have a Money Question? Keep Exploring.
Understanding Treasury bills starts with knowing what you pay, what the bill is worth at maturity and how the stated rate is calculated. Keep exploring FinanceInvestment for practical guides that can help you understand different short-term investing topics.
Have a finance question, topic suggestion or feedback?
Email FinanceInvestment
Explore the Complete Treasury Bills Guide
Compare TreasuryDirect vs Brokerage for T-Bills
Leave a Reply