Tag: Bank Transfers

  • How Do Wire Transfers Work? Step-by-Step Guide

    How Do Wire Transfers Work? Step-by-Step Guide

    How Do Wire Transfers Work? A Step-by-Step Guide
    Subhash Rukade
    Founder, FinanceInvestment
    PERSONAL FINANCE · USA
    Published: October 27, 2026
    Updated: October 27, 2026
    Reading time: About 10 minutes


    how do wire transfers work

    How Do Wire Transfers Work? Understanding Each Step

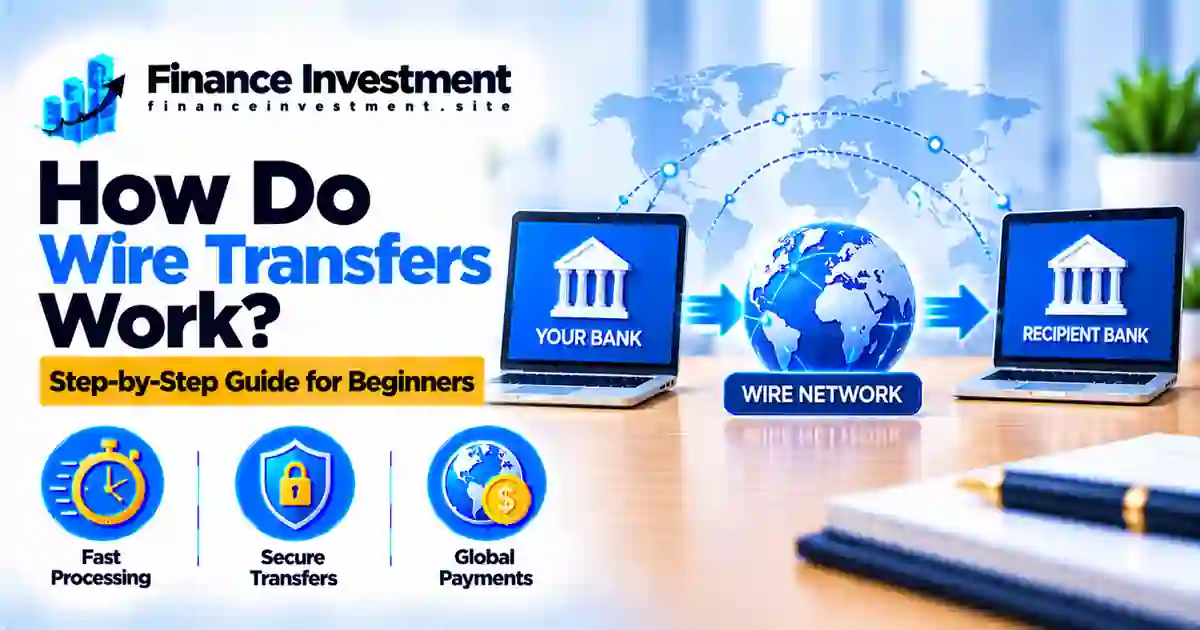
    If you need to pay for a home purchase, send money to family, or move funds between banks, knowing how wire transfers work can help you avoid delays and costly errors. The process typically starts when you provide the recipient’s details and authorize your bank or transfer provider to send the payment.

    The provider then checks the instructions and processes the payment through the relevant payment system. The time it takes depends on factors such as the transfer route, submission cutoff, bank procedures, holidays, and any intermediary institutions involved. International payments may also require currency conversion and additional checks.

    This guide explains what happens from authorization to delivery, how to check a transfer, and how to reduce the risk of sending money to the wrong recipient. For a broader overview, see our complete guide to bank transfers and payments.

    What You’ll Learn

    • How banks and transfer providers process wire instructions.
    • How domestic and international wires can differ.
    • How fees, cutoff times, and intermediary banks affect delivery.
    • How to verify recipient details and respond quickly to a suspected wire-fraud incident.

    Quick Answer: How Do Wire Transfers Work?

    A wire transfer starts when the sender provides the recipient’s banking details and authorizes a payment. The sending bank or provider verifies and processes the instruction through the appropriate payment system. The receiving institution then processes the incoming funds under its procedures. How quickly the money arrives depends on the transfer route, processing cutoffs, business days, security checks, and any intermediary institutions.

    Key Takeaways

    • Verify every detail: Check the recipient’s name, account number, routing information, and any required international bank codes before authorizing the transfer.
    • Allow for processing time: Some domestic wires arrive the same business day, but cutoff times, bank reviews, weekends, and holidays can cause delays.
    • Check the total cost: Sending and receiving fees, intermediary charges, or currency-conversion costs may apply.
    • Respond immediately to problems: If you send money to the wrong recipient or suspect fraud, contact your bank or transfer provider immediately and ask whether a recall is possible. Recovery is not guaranteed.

    Wire Transfers at a Glance

    QUICK TAKE: A wire transfer can be useful when a payment needs to move directly between financial institutions. Before sending, compare the cost and timing with other payment methods, and independently verify the recipient’s instructions.

    Common usesProperty closings, large payments, and domestic or international transfers where the recipient or transaction requires a wire
    Delivery timeSome domestic wires arrive the same business day; international transfers may take several business days. Cutoff times, reviews, holidays, and intermediary banks can affect timing.
    Possible feesOutgoing or incoming wire fees, intermediary charges, and currency-conversion costs, depending on the provider and route
    Details requiredRecipient name and banking details, plus routing numbers or international bank codes as required for the transfer
    Main riskIncorrect details and payment-instruction scams; a completed wire can be difficult to recover, so contact your provider immediately if a problem occurs

    Wire Transfer Basics: How Banks Connect Paymentshow do wire transfers work

    A wire transfer is an electronic payment processed through financial institutions and the payment systems they use. No physical cash travels between banks. Instead, payment instructions are transmitted and the funds are transferred or settled through the relevant financial infrastructure.

    Domestic vs. International Wire Transfers

    A domestic wire moves money between institutions within the same country. In the United States, systems such as Fedwire Funds Service and CHIPS support certain domestic or wholesale payments, depending on the transaction and participating institutions. An international wire crosses national borders and may involve correspondent banks, currency conversion, and additional compliance checks. SWIFT helps financial institutions exchange payment messages internationally; it is not itself a bank or a direct money-transfer service.

    What Information Might You Need?

    Requirements vary by bank, provider, and destination. You may be asked for:

    • The recipient’s full name and account number or other required account details.
    • The recipient bank’s routing number or other domestic bank identifier, when applicable.
    • A SWIFT/BIC code, IBAN, or country-specific bank code if required for an international transfer.
    • The transfer amount, currency, and any additional information requested by the provider.

    Safety tip: Verify the recipient’s banking details before authorizing payment. If wire instructions change unexpectedly, confirm the change through a trusted phone number or another independently verified channel—not by replying to the same email.

    The Wire Transfer Process, Step by Step

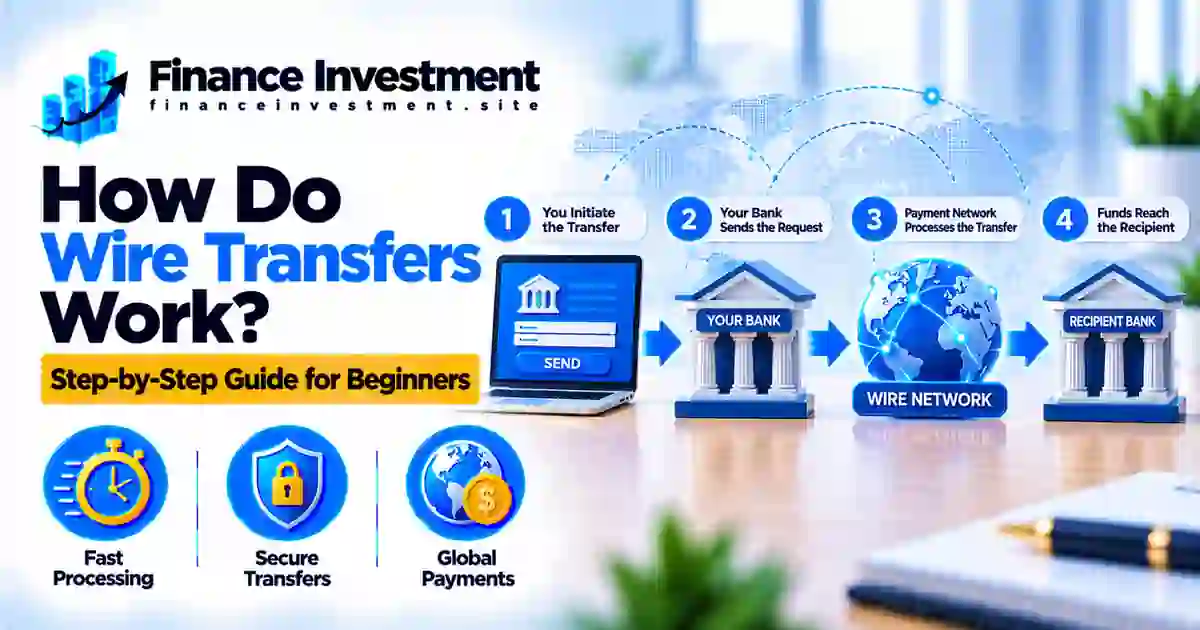
    The exact process depends on the banks, payment system, and destination, but a typical wire transfer follows these stages:

    1. Provide the recipient’s details. Enter the required name, account information, bank identifiers, and payment amount. International transfers may require additional country-specific codes.
    2. Review the payment details. Check the amount, applicable fees, exchange rate if relevant, estimated delivery time, and any transfer limits before submitting the request.
    3. Authorize the transfer. Submit the instruction through your bank or transfer provider and complete any required identity or security verification.
    4. The sending institution processes it. Your bank or provider performs applicable checks and sends the payment instruction through the relevant payment system. Additional review may delay processing.
    5. Intermediaries may be involved. Some international transfers pass through one or more intermediary banks; others do not. Each institution involved may affect processing time or fees.
    6. The receiving institution processes the incoming payment. It applies its own procedures before making the funds available to the recipient. Keep your confirmation or reference number so you can ask your bank to trace the payment if it is delayed.

    Before and after sending: Verify recipient details independently before authorizing the wire. If you discover an error or suspect fraud, contact your bank immediately, provide the transfer reference, and ask whether a recall or other recovery action is possible. Recovery is not guaranteed.

    Benefits and Drawbacks of Wire Transfers

    Wire transfers can be a practical choice when a payment must reach another financial institution, but the right option depends on the transaction, urgency, cost, and risk.

    Advantages

    • Some domestic wires can be processed and delivered on the same business day.
    • Often suitable for transactions such as property closings when a wire is required.
    • Can send funds internationally through providers that support the destination.
    • A confirmation or reference number can help when checking payment status.

    Drawbacks

    • Outgoing, incoming, intermediary, or currency-conversion fees may apply.
    • Cutoff times, holidays, and additional checks can affect delivery.
    • Incorrect recipient details may delay a payment or send it to the wrong account.
    • A completed wire may be difficult to recover, particularly if fraud is involved.

    Expert tip: Before sending a wire, compare the total fees, expected delivery time, and recipient’s requirements. For recurring bills or routine transfers, ACH may be a suitable alternative, depending on the payment deadline and provider. Read our comparison of ACH transfers vs. wire transfers.

    Wire Transfers vs. Other Payment Methods

    The right payment method depends on the deadline, total cost, recipient’s requirements, and available services. Compare these typical characteristics before choosing; actual timing and fees vary by provider and transaction.

    MethodTypical timingCost and common use
    Wire transferSome domestic wires are completed the same business day if submitted before the applicable cutoff; international delivery can take longer.Fees may apply. Often used for property closings and other payments where a wire is required.
    ACH transferStandard ACH timing varies and commonly takes one or more business days; eligible same-day ACH payments may be available.Often low-cost. Common for payroll, bill payments, and routine bank transfers.
    Paper checkMail delivery, deposit processing, and funds availability can each add time.May be convenient when a check is accepted; mailing and other costs depend on the situation.
    P2P payment appTransfers between supported users may be quick, while moving money to a bank account can take additional time.Convenient for eligible person-to-person payments; limits, eligibility, and fees vary by service.

    Which should you choose? Use a wire when the recipient requires it or its payment route suits the transaction. For routine payments, compare ACH and other available methods before paying wire fees. Read our guides to ACH vs. wire transfers and ACH vs. paper checks.

    Wire Transfer Fees, Risks, and Expert Tips

    Wire transfer costs vary by financial institution, account type, destination, and currency. Before approving a payment, check the sending fee, the exchange rate if applicable, and the amount the recipient is expected to receive. Some routes may also involve charges from intermediary or receiving banks.

    Costs and Risks to Consider

    • Sending and receiving fees: Your bank or the recipient’s institution may charge for processing a wire.
    • International transfer costs: Currency-conversion markups and intermediary-bank charges may affect the final amount delivered.
    • Delays: Cutoff times, weekends, holidays, and additional verification may affect when funds arrive.
    • Fraud or incorrect details: A mistaken account number or fraudulent payment instruction can delay a transfer or put funds at risk.

    Expert Tips for Safer Wire Transfers

    • Confirm new or changed payment instructions through a trusted phone number you already know. Do not rely only on a phone number or link in the payment request.
    • Double-check the recipient’s name, account details, amount, currency, and applicable fees before authorizing the transfer.
    • Save the confirmation and reference number so your bank can help trace the payment if needed.
    • If you suspect fraud or an error, contact your bank immediately and ask whether a recall or other recovery action is possible. Recovery is not guaranteed.

    For more ways to protect your finances, use our bank account security checklist and enable transaction alerts if your bank offers them.

    Common Wire Transfer Mistakes—and How to Avoid Them

    • Entering incorrect recipient details: Double-check the account number, recipient name, and required bank identifiers before approving the wire.
    • Overlooking the total cost: Review the sending fee, applicable exchange rate, and estimated amount the recipient will receive.
    • Ignoring processing deadlines: Check your provider’s cutoff time and allow for weekends, holidays, or additional verification.
    • Accepting changed instructions without checking: Verify unexpected account changes through a trusted phone number or contact method you already know.

    Real-Life Scenario: A Last-Minute Wire Change

    Imagine a homebuyer in the United States is preparing to wire a down payment to an escrow company. Just before the deadline, an email appears to come from the company and provides different bank details. The buyer sends the money without independently confirming the change. Later, the buyer discovers the message was fraudulent.

    What could have prevented it? The buyer could have called the escrow company using a previously verified phone number before sending the wire. If the payment has already been sent, the buyer should contact the bank immediately, report suspected fraud, and request a wire recall. A recall may not succeed, so prevention is critical.

    Be cautious with unexpected payment requests, even when they appear to come from a familiar organization. Read our guide to recognizing bank impersonation scams to learn more about common warning signs.

    Who Should Use a Wire Transfer?

    A wire transfer may suit you when the recipient requires a wire, the transaction has specific payment instructions, or the available wire service meets your timing needs. Common situations include:

    • Homebuyers sending closing funds to a verified escrow or title company using independently confirmed instructions.
    • Individuals or businesses making payments when the recipient specifically requests a wire.
    • People sending money internationally through a provider that supports the destination and currency.
    • Customers who have compared the transfer’s total cost, expected delivery time, and payment requirements with other available methods.

    When might another method be better? For routine bills, recurring payments, or everyday bank transfers, ACH or another supported option may be more suitable. Compare the fees, timing, limits, and recipient requirements before deciding. Read our guide to ACH transfers vs. wire transfers.

    Frequently Asked Questions About Wire Transfers

    1. How long does a wire transfer take?

    Some domestic wires can arrive the same business day, depending on the bank, submission time, and processing requirements. International wires may take several business days, depending on the destination and institutions involved.

    2. Are wire transfers instant?

    Not necessarily. A payment may be processed quickly, but bank cutoffs, verification checks, holidays, and the receiving institution’s procedures can affect when funds become available.

    3. How much does a wire transfer cost?

    Fees depend on the bank or provider, account type, destination, and currency. International transfers may also involve intermediary-bank charges or currency-conversion costs. Check the total cost before authorizing payment.

    4. What details are needed to send a wire?

    You generally need the recipient’s name and account details, plus the bank identifiers required for the transfer route. International payments may require a SWIFT/BIC code, IBAN, or another country-specific identifier. Confirm the exact requirements with your provider.

    5. Can I cancel a wire transfer after sending it?

    You may be able to stop a transfer before it is completed, but cancellation is not guaranteed. Once a wire has been processed, recovery can be difficult. Contact your bank immediately to ask about cancellation or recall options.

    6. What happens if I enter the wrong account details?

    The payment may be delayed, rejected, or sent to an unintended recipient. Contact your bank immediately if you discover an error. The available recovery options depend on the payment status and circumstances.

    7. How can I track a wire transfer?

    Check your bank’s transfer status or contact the provider using your confirmation or reference number. If the payment is delayed, ask whether the institution can trace it through the relevant payment system.

    8. Are international wire transfers safe?

    They can be used for legitimate payments, but scams, incorrect details, and unexpected fees remain risks. Verify recipient details independently and confirm any unexpected changes to payment instructions before authorizing a transfer.


    Final Verdict: Is a Wire Transfer the Right Choice?

    A wire transfer can be the right option when a recipient requires one, a property closing has specific payment instructions, or a supported international payment route meets your needs. However, a wire is not automatically the best choice for every large or urgent payment. Fees, processing times, and recipient requirements vary.

    Before authorizing a transfer, compare the total cost and expected delivery time, independently verify the recipient’s banking instructions, and save your confirmation details. If you suspect an error or fraud, contact your bank immediately and ask what action is possible.

    Bottom line: Choose a payment method based on the deadline, total cost, and recipient’s requirements—not speed alone. For help comparing your options, explore our complete guide to bank transfers and payments.
    Questions or Feedback About Wire Transfers?

    Have a question about this guide or a suggestion for a future topic? Send a message to Subhash Rukade at FinanceInvestment.

    Email the Author

    Continue learning with our complete guide to bank transfers and payments.
  • What Is a Wire Transfer? Fees, Time & Safety Guide

    What Is a Wire Transfer? Fees, Time & Safety Guide

    What Is a Wire Transfer? Complete Beginner Guide

    BANKING GUIDE · USA
    Subhash Rukade
    Founder & Personal Finance Writer
    FinanceInvestment
    Published
    October 27, 2026
    Last Updated
    October 27, 2026
    Reading Time
    9 min read

    what is a wire transfer

    What Is a Wire Transfer, and When Would You Use One?

    A wire transfer is an electronic way to send money from one bank or financial institution to another. You might use one when closing on a home, making a large payment, or sending money to someone in another country. Understanding what a wire transfer is can help you decide whether it suits your situation.

    Wire transfers can be useful when money needs to move directly between financial institutions, including across international borders. However, fees, processing cut-off times, and recipient requirements can vary. A transfer sent with incorrect details or to a scammer may be difficult to recover, so verifying the recipient independently before authorizing payment is essential.

    A wire transfer is only one way to move money. Read our guide to bank transfers and payment methods to compare common options and understand how their costs, timing, and convenience differ.

    What You’ll Learn

    • What a wire transfer is and how it works.
    • How domestic and international wire transfers differ.
    • Which fees and processing delays to consider.
    • How wire transfers compare with ACH and other payment methods.
    • How to verify payment details and reduce the risk of wire transfer scams.

    Quick Answer: What Is a Wire Transfer?

    A wire transfer is an electronic payment sent between banks or other financial institutions through a wire payment network. People commonly use wires for real estate closings, large payments, and domestic or international transfers. Fees and delivery times vary, and recovering money sent to the wrong recipient may be difficult.

    Key Takeaways

    • Electronic transfer: A wire sends payment instructions electronically rather than using a paper check.
    • Domestic and international: Domestic wires transfer money within the United States; international wires send it across national borders.
    • Fees can add up: Sending, receiving, intermediary-bank, and currency-conversion fees may apply.
    • Timing varies: Bank cut-off times, holidays, destination, and additional checks can affect delivery.
    • Verify before sending: Confirm the recipient’s name and banking details using a trusted source.
    • Watch for scams: Independently verify unexpected changes to payment instructions before authorizing a transfer.

    Bottom line: A wire transfer can be useful when a direct bank payment fits the transaction. Before sending money, verify the recipient, review all applicable fees, and ask your bank about the expected delivery time.

    Wire Transfers at a Glance

    Quick take: A wire transfer sends money electronically through financial institutions. It can be useful for property closings, large payments, and certain international transactions. Fees, delivery times, and options for recovering a payment depend on the banks and transaction involved.

    Quick FactWhat to Know
    Common usesReal estate closings, large payments, and transfers between people or businesses
    Main typesDomestic wires within the United States and international wires sent across borders
    Possible costsSending or receiving fees, intermediary-bank charges, and currency-conversion costs where applicable
    Delivery timeDepends on bank cut-off times, destination, currency, business days, and required checks
    Key precautionIndependently verify recipient details and any changes to payment instructions before authorizing the transfer

    Before sending: Ask your bank about the total cost, expected delivery time, and available recall procedures. A recall request may not recover money that has already reached the recipient.

    Wire Transfers Explained for Beginnerswhat is a wire transfer

    A wire transfer is an electronic payment used to send money from one bank or financial institution to another. The institutions process the payment through the applicable payment network, rather than relying on a paper check. Wire transfers are commonly used for home purchases, business payments, and other transactions where the recipient requires this payment method.

    Domestic Wire Transfers

    A domestic wire transfer moves money between financial institutions within the United States. Depending on the bank and transaction, you may need the recipient’s legal name, bank account number, and routing information. Your bank will explain which details are required before you authorize the payment.

    International Wire Transfers

    An international wire sends money across national borders. The transfer may involve intermediary banks, foreign currencies, and additional processing requirements. Depending on the destination and receiving institution, you may need a SWIFT/BIC code and other recipient banking details. Exchange rates and intermediary or receiving-bank fees can also affect the final amount delivered.

    Beginner tip: A wire transfer and an ACH transfer use different payment systems and may differ in cost, processing time, and availability. Compare them in our ACH transfer vs. wire transfer guide before choosing a method.

    Before sending money, confirm the recipient’s details and ask your bank about fees, processing times, and any transfer limits. Verify payment instructions through a trusted, independently confirmed channel—especially if someone emails or messages you updated banking details.

    How Wire Transfers Work

    A wire transfer typically involves the sending bank, a payment network, and the receiving bank. The exact route and processing steps depend on the institutions involved and whether the payment is domestic or international.

    1. Enter the Recipient’s Details

    Provide the information your bank requires, which may include the recipient’s name, account number, and routing details. International transfers may require a SWIFT/BIC code or other destination-specific information.

    2. Review and Authorize the Transfer

    Check the recipient details, transfer amount, applicable fees, and currency before approving the payment. Your bank may require identity verification or additional security checks.

    3. The Payment Is Routed and Processed

    The sending institution submits the payment through the applicable wire system. Depending on the route, especially for international transfers, one or more intermediary institutions may help move the funds to the receiving bank.

    4. The Receiving Bank Processes the Payment

    The receiving institution processes the incoming wire before making the funds available, subject to its procedures and any required checks. Processing and availability times can vary.

    Safety tip: Verify wire instructions through a trusted, independently confirmed channel—especially if payment details change unexpectedly. If you notice an error or suspect fraud after authorizing the transfer, contact your bank immediately and ask whether the payment can be stopped or recalled. Recovery is not guaranteed.

    Benefits and Drawbacks of Wire Transfers

    Wire transfers can be useful for moving money between financial institutions, particularly for large or cross-border payments. However, fees, processing requirements, and the difficulty of recovering a completed payment are important considerations.

    Benefits

    • Useful for large payments: Commonly used for real estate closings and certain business transactions.
    • Can be fast: Some domestic wires are processed the same business day when submitted before the applicable cut-off, subject to bank processing and other checks.
    • Supports international payments: Wires can send money across borders through participating financial institutions and payment routes.

    Drawbacks

    • Fees may apply: Sending, receiving, intermediary-bank, and currency-conversion charges can increase the total cost.
    • Errors can cause problems: Incorrect recipient details may delay the transfer or send it to the wrong account.
    • Recovery is uncertain: Once a wire has been processed, stopping or recovering the funds may be difficult, especially in cases of fraud.

    Bottom line: A wire transfer may be a good choice when the recipient requires it or the transaction calls for this payment method. Before proceeding, compare fees and expected delivery times with alternatives, and independently verify the recipient’s payment instructions.

    Wire Transfer vs. Other Payment Methods

    A wire transfer is one of several ways to send money. The right option depends on the payment amount, urgency, fees, recipient requirements, and whether the transaction is domestic or international.

    Payment MethodCommon UsesWhat to Consider
    Wire transferReal estate closings, large payments, and some international transfersFees may apply, and recovery can be difficult after processing
    ACH transferPayroll, recurring bills, and routine bank-to-bank paymentsOften low-cost; standard and same-day processing options may be available
    Paper checkPayments to people or businesses that accept checksMail delivery and bank processing can delay access to funds
    Payment appEveryday payments between eligible usersTransfer limits, fees, timing, and dispute options vary by provider and transaction

    Which should you choose? Consider a wire when the recipient requires it or the transaction calls for that payment method. For routine payments, ACH may be a lower-cost alternative, depending on timing and availability.

    For more detail, read our ACH transfer vs. wire transfer comparison. Before sending money, confirm current fees, processing estimates, transfer limits, and any applicable protections with your bank or payment provider.

    Wire Transfer Costs, Risks, and Expert Tips

    Before sending a wire transfer, check the total cost, confirm the recipient’s instructions, and understand what to do if something goes wrong. Fees and processing requirements vary by bank, account, destination, and currency.

    Understand the Total Cost

    Your bank may charge a sending fee, and the receiving or intermediary bank may deduct additional charges. International wires may also include currency-conversion costs through the exchange rate offered. Ask your bank about the total fees, applicable exchange rate, expected delivery time, and the amount the recipient is likely to receive.

    Recognize Wire Transfer Fraud Risks

    Wire transfers can be difficult to reverse after processing. Scammers may impersonate a real estate agent, business partner, bank employee, or someone you know. Unexpected urgency or last-minute changes to payment instructions should be treated as warning signs—not proof that a request is legitimate.

    Expert Tips Before You Send

    • Verify recipient details using a trusted phone number you obtained independently.
    • Confirm fees, exchange rates, cut-off times, and estimated delivery.
    • If wire instructions change unexpectedly, call the intended recipient using a previously verified number before sending money.
    • If you suspect fraud or notice an error, contact your bank immediately and ask whether the transfer can be stopped or recalled. Recovery is not guaranteed.

    You can also review our bank account security checklist for additional ways to protect your banking information and recognize suspicious activity.

    Common Wire Transfer Mistakes and a Real-Life Example

    Wire transfer mistakes can lead to delays, unexpected costs, or financial losses. Before approving a payment, watch out for these common errors:

    • Entering an incorrect account number, routing number, or recipient name.
    • Trusting new or changed payment instructions without independently verifying them.
    • Overlooking sending fees, intermediary charges, or currency-conversion costs.
    • Assuming a completed wire can always be canceled or recovered.

    Example: A Homebuyer Faces Wire Fraud

    Consider this hypothetical scenario: A homebuyer is preparing to send a $25,000 closing deposit to a title company. Shortly before the deadline, an email arrives with supposedly updated bank details. The buyer trusts the message and sends the money without confirming the change. The instructions were fraudulent, and the funds are sent to an account controlled by a scammer.

    Once the buyer discovers the fraud, they contact their bank immediately and request a wire recall. Quick action may help, but the money is not guaranteed to be recovered. Calling the title company using a previously verified phone number before sending the payment could have helped prevent the loss.

    Remember: Never rely solely on email to confirm changed wire instructions. Independently verify the recipient and payment details before authorizing the transfer.

    Who Should Use a Wire Transfer?

    A wire transfer may be appropriate when the recipient requires this payment method, the transaction involves a substantial amount, or the payment needs to move between financial institutions through a supported wire network. Common situations include:

    • Homebuyers: Sending closing funds when instructed by a verified title or escrow company.
    • Businesses: Paying suppliers or settling transactions when a wire is the agreed payment method.
    • People sending money internationally: Transferring funds abroad when the banks and destination support the transaction.

    For routine payments, an ACH transfer or a suitable payment app may be more convenient or less expensive. The best option depends on the amount, urgency, fees, recipient requirements, and available payment protections.

    Before you decide: Compare total fees and expected delivery times, confirm the recipient accepts wires, and independently verify payment instructions. Never rely solely on an unexpected email or message announcing a change in bank details.

    Frequently Asked Questions About Wire Transfers

    1. What is a wire transfer?

    A wire transfer is an electronic payment sent between financial institutions through an applicable wire payment system. It is commonly used for real estate closings, large payments, and certain international transactions.

    2. How long does a wire transfer take?

    Some domestic wires can arrive the same business day, while international transfers may take longer. Cut-off times, bank procedures, destination, currency, and required checks can affect when funds become available.

    3. How much does a wire transfer cost?

    Costs depend on the financial institution, account, and destination. Sending, receiving, intermediary-bank, and currency-conversion charges may apply. Check the total cost before authorizing the payment.

    4. Is a wire transfer the same as an ACH transfer?

    No. Wire transfers and ACH payments use different payment systems and have different processing rules, costs, and typical uses. Compare your bank’s options in our ACH transfer vs. wire transfer guide.

    5. Can I cancel a wire transfer after sending it?

    It may be possible to stop a transfer before it is processed, depending on the bank and transaction. Once a wire has been processed, cancellation or recovery may be difficult. Contact your bank immediately to ask about available options.

    6. Are wire transfers safe?

    Wire transfers can be processed securely, but incorrect details and scams remain risks. Independently verify the recipient’s identity and payment instructions before sending money, especially for large or unfamiliar transactions.

    7. What information do I need to send a wire transfer?

    Requirements vary by bank and destination. You may need the recipient’s name, account number, and routing details. International wires may require a SWIFT/BIC code and additional information. Confirm the exact requirements with your bank.

    8. What should I do if I sent a wire transfer to a scammer?

    Contact your bank immediately, explain that the transfer may be fraudulent, and request a recall or other available intervention. Preserve transaction records and relevant messages, and report the incident to the appropriate authorities. Recovery is not guaranteed.


    Final Verdict: Is a Wire Transfer Right for You?

    A wire transfer can be useful for real estate closings, certain large payments, and international transactions when the recipient requires this method. However, fees, delivery times, and recovery options vary, so compare alternatives before deciding.

    Before sending money, confirm the total cost with your bank and independently verify the recipient’s payment instructions. If a request feels unusually urgent or the banking details have suddenly changed, pause and confirm the information through a trusted contact.

    Bottom line: Choose a wire transfer because it suits the transaction—not simply because someone demands an urgent payment. For more guidance, explore our complete guide to bank transfers and payments.
    Make Smarter Banking Decisions

    Before sending a wire transfer, compare the fees, confirm the recipient’s details, and understand the risks. Explore more practical banking guides from FinanceInvestment to help you make informed financial decisions.

    Email the Author

    Want to learn more? Read our complete guide to bank transfers and payments.
  • ACH Transfer vs. Paper Check: Cost, Speed & Convenience

    ACH Transfer vs. Paper Check: Cost, Speed & Convenience

    ACH Transfer vs. Paper Check: Cost, Speed & Convenience

    SR
    Subhash Rukade
    Founder & Personal Finance Writer
    FinanceInvestment
    PUBLISHED
    October 26, 2026
    LAST UPDATED
    October 26, 2026
    READING TIME · 9 MIN
    BANKING GUIDE · USA


    ACH Transfer vs. Paper Check: Which Works Better for You? ACH transfer vs paper check

    When you need to pay a bill, send money to a family member, or receive a payment, the method you choose can affect how much effort it takes and when the money becomes available. Comparing an ACH transfer vs. paper check helps you understand the differences before moving money between bank accounts.

    An ACH transfer sends money electronically through the Automated Clearing House network. A paper check gives the recipient a written payment instruction that can be deposited or cashed. Both methods are used across the United States, but they differ in processing, convenience, recordkeeping, and the risks involved.

    Think about a monthly utility bill. An authorized ACH payment may save you from writing and mailing a check every month. On the other hand, a paper check may suit someone who prefers physical records or whose recipient does not accept electronic payments. Fees, processing times, and available options depend on the banks and payment arrangements involved.

    For a broader look at your options, explore our guide to bank transfers and payment methods.

    What You’ll Learn

    • How ACH transfers and paper checks move money.
    • How their costs and processing times compare.
    • What to know about convenience, payment records, and fraud risks.
    • Which method may suit families, retirees, investors, and everyday banking needs.

    Quick Answer: ACH Transfer or Paper Check?

    For many everyday payments, an ACH transfer is convenient because it moves money electronically and can be arranged for recurring bills or direct deposits. A paper check may be useful when the recipient requires one or you prefer a physical payment record. Neither method is always free or instant. The better choice depends on your bank’s fees, processing times, payment requirements, and your comfort with each method.

    Key Takeaways

    • Cost: Many consumer ACH payments have no separate fee, but charges may apply. Paper checks can involve check-ordering, postage, or other costs.
    • Speed: ACH processing depends on the payment type and processing schedule. A check must reach the recipient and be deposited before the collection process begins.
    • Convenience: ACH can simplify recurring payments, while writing and mailing checks usually require more effort.
    • Records: Both methods may appear in your bank statements. A paper check can also provide a physical record.
    • Security: Mailing a check creates risks such as theft or check washing. ACH also requires protecting your account details and authorizing payments carefully.
    • Best choice: Consider the recipient’s requirements, your bank’s fees, and when the money needs to arrive or become available.

    Bottom line: ACH is often a practical choice for routine electronic payments. A paper check remains useful when a physical payment is requested or preferred. Before choosing, check the costs, timing, and precautions that apply to your situation.

    ACH Transfer vs. Paper Check at a Glance

    QUICK TAKE

    ACH is often convenient for recurring bills and other routine electronic payments. Paper checks remain useful when a recipient requires a physical check or you prefer a paper payment record.

    ACH MAY SUIT
    Recurring bills, payroll and direct deposits
    PAPER CHECKS MAY SUIT
    Physical payments or recipients who require checks

    Quick Comparison

    FeatureACH TransferPaper Check
    CostOften low-cost; bank fees may applyCheck-ordering and mailing costs may apply
    TimingDepends on payment type and processing scheduleDepends on delivery, deposit, clearing and funds availability
    ConvenienceMay be scheduled or automatedUsually requires writing and delivering the check
    Security concernProtect account details and payment authorizationGuard against theft, alteration and check washing

    Important: Your bank’s fee schedule, payment setup, processing calendar and funds-availability policy determine the actual cost and timing. Neither method guarantees immediate access to funds.

    ACH Transfers and Paper Checks ExplainedACH transfer vs paper check

    When you pay someone from your bank account, the payment method affects how the transaction is initiated and processed. The basic difference is straightforward: ACH transfers move money electronically through a payment network, while a paper check begins as a written instruction to pay.

    What Is an ACH Transfer?

    ACH stands for Automated Clearing House. It is a U.S. electronic payment network that processes batches of credit and debit transactions between participating financial institutions. An ACH credit sends money to an account, while an ACH debit collects money from an account after the required authorization.

    Common examples include receiving a paycheck through direct deposit, paying a utility bill electronically, and transferring money between eligible bank accounts. Standard ACH payments commonly take one or more business days to process. Eligible transactions may qualify for same-day ACH, subject to network rules, bank participation, and processing cutoffs.

    What Is a Paper Check?

    A paper check is a written payment instruction that tells the account holder’s bank to pay a specified amount to the named recipient. The recipient usually deposits or cashes the check, which then goes through the bank’s collection and processing procedures.

    Checks remain useful for rent, contractor payments, donations, and situations where a recipient prefers or requires a physical payment. A check can take extra time to reach the recipient, and depositing it does not guarantee that all funds will be available immediately.

    One important detail: Banks may process check information electronically during collection. That does not automatically make the original payment an ACH transfer; check-processing systems and ACH payments are distinct, although certain check-related transactions may be converted to electronic debits under applicable rules and authorization.

    How ACH Transfers and Paper Checks Work

    Both methods move money between people or businesses, but the payment process starts differently. Here is what typically happens with each one.

    How an ACH Payment Works

    1. You authorize the transaction. Depending on the payment, you approve a debit, set up a recurring payment, or provide the details needed to receive an ACH credit.
    2. The payment is submitted. The originating bank or payment provider sends the instruction for ACH processing.
    3. The transaction is routed. The ACH system sorts and delivers payment instructions to the relevant financial institutions according to its processing schedule.
    4. The banks process the payment. The accounts are debited or credited as applicable. Processing time and when funds become available depend on the transaction, bank policies, and applicable rules.

    How a Paper Check Works

    1. You complete the check. Enter the payee, amount, date, and signature, then check the details carefully.
    2. You deliver it. Give the check to the recipient or send it to a verified mailing address.
    3. The recipient deposits it. They may use a bank branch, ATM where supported, or mobile deposit if their bank offers it.
    4. The check enters collection. Banks process the payment, and the recipient’s access to the funds depends on applicable funds-availability rules and any permitted holds. A deposit showing in an account does not always mean the payment is final.

    Practical tip: Save ACH confirmations and check details until you have verified the payment. For checks, protect the account and routing numbers printed on the document, and monitor your account for unfamiliar transactions.

    Benefits and Drawbacks of ACH Transfers and Paper Checks

    ACH Transfers: Pros

    • Convenient for recurring bills, payroll, and many routine bank payments.
    • Can reduce the need to write checks, buy postage, or visit a mailbox.
    • Transaction details are generally available through online banking or account statements.

    ACH Transfers: Cons

    • Processing and funds availability are not always immediate.
    • Incorrect account details, insufficient funds, or authorization issues can cause problems.
    • Disputing an unauthorized or mistaken transaction may take time, and the outcome depends on the circumstances and applicable rules.

    Paper Checks: Pros

    • Useful when a landlord, business, or organization requires a physical check.
    • Provides a physical document that can help with personal recordkeeping.
    • Can be used without setting up an electronic payment with the recipient.

    Paper Checks: Cons

    • Writing, delivering, and depositing a check can add extra steps and delays.
    • A check may be lost, stolen, altered, or targeted in a check-washing scam.
    • Depositing a check does not guarantee that all funds are immediately available or that the payment will never be returned.

    Which has the edge? ACH often makes recurring electronic payments easier to manage. Paper checks remain useful when a physical payment is required or preferred. Your bank’s policies, recipient’s requirements, and own payment habits should guide the decision.

    ACH Transfer vs. Paper Check: Side-by-Side Comparison

    ACH and paper checks can both be useful for everyday payments. The difference becomes clearer when you consider the total effort, payment requirements, and how you prefer to keep records.

    FeatureACH TransferPaper Check
    CostOften low-cost; bank or provider fees may apply.Check supplies, postage, or replacement costs may apply.
    ProcessingDepends on payment type, submission cutoff, and bank processing.Requires delivery or handoff, deposit, and check collection.
    ConvenienceCan support recurring or scheduled payments.Requires completing and delivering the check.
    RecordkeepingTransaction details are generally available in bank records.May provide a physical document as well as bank records.
    Common risksUnauthorized transactions, incorrect account details, or payment errors.Theft, alteration, loss, or check-washing fraud.
    May suitDirect deposits, recurring bills, and routine electronic payments.Payments where a recipient requests or prefers a physical check.

    Remember: Processing time is not the same as funds availability. Your bank’s policies and the circumstances of the payment affect when money can be used.

    How to choose: ACH may be more convenient for routine payments when the recipient accepts it. A paper check remains an option when a physical payment is needed. Compare your bank’s charges, the recipient’s requirements, and the time available before deciding.

    ACH Transfer Costs, Check Fraud Risks & Practical Tips

    The cheapest-looking payment method is not always the most convenient. Before sending money, check your bank’s fees, consider how the payment will be processed, and know what to do if something goes wrong.

    Check the Fees Before Paying

    Many routine ACH payments have no separate consumer fee, but charges can vary by bank, account, and payment service. Paper checks may involve check-ordering costs, postage, or fees if a payment is returned. Review your bank’s fee schedule and any applicable service terms instead of assuming either method is free.

    Know the Risks

    ACH transactions can be affected by unauthorized debits, phishing, or compromised account information. Paper checks may be stolen, altered, or targeted by check-washing fraud. If you spot an unfamiliar debit or discover a missing check, contact your bank promptly. Ask whether a stop-payment request, transaction dispute, or additional account safeguards are appropriate; availability and outcomes depend on the circumstances.

    Fraud warning: If someone emails or texts new payment instructions, independently verify them before sending money. Use a trusted phone number or contact method you already know—not the details in the suspicious message.

    Three Habits Worth Keeping

    • Confirm the recipient, amount, and account details before authorizing payment or signing a check.
    • Turn on transaction alerts and review your bank activity regularly.
    • Keep checks secure, avoid leaving outgoing payments in an exposed mailbox, and report suspected fraud quickly.

    For more ways to protect your finances, follow our bank account security checklist.

    Common Payment Mistakes—and How to Avoid Them

    Even a routine payment can cause trouble if you leave it until the last minute or assume the process is complete before checking. A few small habits can help prevent missed due dates and avoidable confusion.

    • Assuming ACH is instant: Check the payment schedule and allow time for processing and funds availability.
    • Mailing a check too late: Allow time for delivery, deposit, and collection rather than sending it on the due date.
    • Skipping the final details check: Verify the payee, amount, and payment authorization before submitting an ACH payment or signing a check.
    • Failing to confirm payment: Review your bank activity and keep the confirmation or check record until the payment is accounted for.

    A Household Example

    Imagine Maya has a utility bill due next week. Her provider accepts both ACH payments and paper checks.

    She chooses an authorized ACH payment because it saves her from writing and mailing a check every month. Before confirming, she checks the scheduled payment date, reviews any applicable fee, and makes sure enough money will be available in her account.

    Her neighbor prefers paper checks. He mails his payment early, records the check number, and checks his bank activity afterward. Both approaches can work when planned carefully.

    The lesson: Choose a method your recipient accepts, allow enough time for processing or delivery, and verify the payment rather than relying on assumptions.

    Who Should Choose ACH—and Who Should Use Paper Checks?

    The best payment method depends on the recipient’s requirements, your preferred way to pay, and how much time the transaction needs. Neither option is right for every situation.

    ACH May Suit You If You…

    • Receive payroll or direct deposits into your bank account.
    • Pay recurring bills through an authorized electronic arrangement.
    • Prefer electronic payment records and fewer paper-based steps.

    A Paper Check May Suit You If You…

    • Pay a landlord, business, or organization that accepts or requires checks.
    • Need to provide a physical payment instrument.
    • Prefer writing and tracking payments manually.

    Before you choose: Confirm the recipient accepts your preferred method, review any applicable fees, and check the expected processing or delivery timeline. If the payment is urgent, ask the bank or provider when the funds are expected to become available.

    For routine payments, ACH may reduce manual work. For recipients who need a physical check, a paper check may be the practical choice. Select the method that fits the transaction—not simply the one that seems faster or cheaper.

    Frequently Asked Questions About ACH Transfers and Paper Checks

    1. Is an ACH transfer faster than a paper check?

    Often, but not always. ACH payments are processed electronically, while mailed checks also require delivery and deposit. Timing depends on processing schedules, bank cutoffs, weekends, holidays, and funds availability.

    2. Is ACH cheaper than paying by paper check?

    ACH payments may have low or no consumer fees, depending on the bank and transaction. Paper checks can involve check-ordering and postage costs. Compare the fees that apply to your specific payment.

    3. How long does an ACH transfer take?

    Many standard ACH payments take one or more business days. Eligible transactions may qualify for same-day ACH, subject to processing deadlines and network rules. The time funds become available can vary.

    4. How long does a paper check take to clear?

    It depends on delivery, deposit, and bank processing. Your bank may make funds available before the check is finally paid by the issuing bank. If the payment is important or time-sensitive, confirm the status rather than relying only on the initial deposit.

    5. Is ACH safer than a paper check?

    Neither method is risk-free. ACH payments can involve unauthorized debits or compromised account details, while checks can be lost, stolen, or altered. Use account alerts, protect banking information, and review transactions regularly.

    6. Can I stop an ACH payment or a paper check?

    Possibly, depending on the payment type, timing, and bank rules. Contact your bank promptly to ask about cancellation, stop-payment, or dispute options. A completed payment may be difficult to recover, and a stop-payment request does not guarantee recovery.

    7. Can I use ACH to pay bills automatically?

    Yes. Many billers accept authorized recurring ACH payments. Before enrolling, confirm the withdrawal amount or calculation method, scheduled date, and cancellation process. Keep sufficient funds in your account and monitor withdrawals.

    8. Should I choose ACH or a paper check?

    ACH may be convenient for eligible electronic and recurring payments. A paper check may be appropriate when the recipient requires one or accepts it as a preferred option. Compare fees, timing, security risks, and recordkeeping needs before choosing.

    Important: Payment processing, funds availability, and final payment are not necessarily the same. If you suspect an unauthorized transaction or a check-related problem, contact your bank promptly.

    Final Verdict: ACH Transfer vs. Paper Check

    For routine bills, direct deposits, and other eligible electronic payments, ACH can be a practical choice because it reduces the need to write, mail, and manually track checks. However, fees, processing times, and account requirements vary.

    A paper check remains useful when the recipient requires or prefers a physical payment. Just allow enough time for delivery and processing, and remember that depositing a check does not always mean the payment is final.

    The bottom line: Choose ACH when electronic payment suits the transaction; choose a paper check when a physical check is needed. Before paying, confirm the recipient’s requirements, review possible fees, and check the expected timeline.

    If you want to compare other ways to send or receive money, explore our guide to bank transfers and payment methods for a broader look at your options.

    Choose Your Payment Method with Confidence

    Whether you use ACH transfers or paper checks, understanding the costs, timing, and risks can help you make informed banking decisions.

    Have a suggestion for a future personal finance guide? Share your topic idea.

  • ACH Transfer vs. Debit Card Payment: Key Differences

    ACH Transfer vs. Debit Card Payment: Key Differences

    ACH Transfer vs. Debit Card Payment: Key Differences

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    BANKING & PAYMENTS
    Published: [October, 26, 10.]
    Updated: October, 26, 10.]
    Reading time: [12 Minites ]

    ACH Transfer vs. Debit Card Payment: What’s the Difference?

    When you pay a bill, shop online, or move money, you may use an ACH transfer or a debit card payment. Both move money electronically, but they follow different payment processes. Understanding the difference can help you choose the right option based on speed, fees, convenience, and the type of transaction.

    In an ACH transfer vs. debit card payment comparison, the main distinction is how the payment is processed. ACH transfers move money between bank accounts through the Automated Clearing House network. Debit card payments generally use a card network and draw money from your linked bank account. ACH is commonly used for recurring bills and bank-to-bank transfers, while debit cards are widely used for everyday purchases and online checkout.

    Neither method is always faster, cheaper, or safer in every situation. Processing times, fees, dispute rights, and transaction limits depend on the payment type, your bank, and the merchant. For a broader overview, explore our complete guide to bank transfers and payments.
    What You’ll Learn

    • How ACH transfers and debit card payments work.
    • How processing speed, fees, and convenience compare.
    • What to know about payment security and disputes.
    • Which method may suit bills, subscriptions, shopping, and bank transfers.
    • How to avoid common payment mistakes and protect your money.

    Quick Answer: ACH Transfer vs. Debit Card Payment

    An ACH transfer moves money electronically between bank accounts and is commonly used for direct deposits, recurring bills, and account-to-account transfers. A debit card payment lets you pay a merchant using funds from your linked bank account, typically through a card network. Debit card authorizations are often quick, while ACH payments may take one or more business days depending on the processing schedule and payment type. Neither method is automatically cheaper or safer in every situation.

    Key Takeaways

    • Processing speed: Debit card authorization is often immediate, but final posting may take longer. ACH timing depends on the payment and processing schedule.
    • Common uses: ACH is useful for eligible recurring payments and bank transfers; debit cards are convenient for everyday purchases.
    • Fees: Costs vary by bank, card issuer, merchant, and transaction type. Check the terms before paying.
    • Protection: Both methods have safeguards, but applicable error-resolution rights and dispute procedures can differ.

    Bottom Line

    Consider ACH for bank-to-bank transfers, direct deposits, and eligible recurring bills. Consider a debit card for convenient merchant payments and everyday shopping. Before choosing, compare the expected processing time, fees, transaction terms, and protections that apply to your specific payment.

    ACH Transfer vs. Debit Card: At a Glance

    QUICK TAKE

    ACH transfers are commonly used for bank-to-bank transfers, direct deposits, and eligible recurring bills. Debit cards are convenient for everyday purchases and merchant checkout. Compare the processing time, fees, and applicable protections before choosing.

    FeatureACH TransferDebit Card Payment
    Common usesBank transfers, direct deposits, recurring billsIn-store and online purchases
    ProcessingOften one or more business days; some payments qualify for same-day processingAuthorization is often quick; final posting may take longer
    Potential feesOften low-cost, but provider fees may applyConsumer purchases are often fee-free; certain transactions or account terms may involve charges
    Best suited forScheduled payments and moving money between accountsConvenient payments to merchants

    Important: Actual processing times, fees, limits, and dispute rights depend on the transaction, financial institution, payment provider, and applicable rules. Card authorization does not necessarily mean final settlement is complete.

    ACH Transfers and Debit Card Payments ExplainedACH transfer vs debit card payment

    What Is an ACH Transfer?

    An ACH transfer is an electronic payment processed through the Automated Clearing House network in the United States. It allows participating financial institutions to process payments between eligible bank accounts. Common uses include payroll direct deposits, utility bills, mortgage payments, and transfers between your own accounts.

    ACH payments can be credits, which send money into an account, such as a paycheck deposit, or debits, which withdraw money with appropriate authorization, such as an automatic bill payment. Processing times depend on submission cutoffs, business days, bank procedures, and eligibility for same-day ACH. Read our guide to how ACH transfers work for more details.

    What Is a Debit Card Payment?

    A debit card payment uses a card linked to your bank account to pay a merchant. When you tap, insert, or enter your card details, the payment network routes an authorization request to the card issuer. If approved, the transaction may appear as pending before it is posted to your account. The final amount can differ from the initial authorization in situations such as restaurant tips or certain merchant holds.

    Debit cards are commonly used for in-store purchases, online shopping, and recurring merchant payments. Protect your card information and check account activity regularly. Learn more in our guide to what a debit card is and how it works.

    Remember: ACH is an electronic bank-payment network, while debit card payments generally use card networks. Both move money electronically, but their processing steps, timing, and applicable consumer protections can differ.

    How Each Payment Method Works

    How an ACH Transfer Works

    1. You provide the required bank details and authorize the payment or transfer.
    2. The originating bank or payment provider submits the payment instructions for ACH processing.
    3. The ACH network sorts and delivers payment instructions between participating financial institutions for processing.
    4. The receiving bank processes the entry. Posting time and when funds are available depend on the transaction, processing schedule, and bank policies.

    How a Debit Card Payment Works

    1. You tap, insert, or enter your debit card details at checkout.
    2. The merchant routes an authorization request through its payment processor and the relevant card network.
    3. Your card issuer evaluates the request and approves or declines it.
    4. For an approved purchase, the transaction can move through clearing and settlement before the final amount is posted to your account.

    Practical tip: A debit card authorization does not necessarily mean the transaction has settled. Likewise, initiating an ACH payment does not guarantee that the recipient already has available funds. If a payment is time-sensitive, confirm its status and expected processing time with your bank or payment provider.

    Benefits and Drawbacks of ACH Transfers vs. Debit Card Payments

    ACH Transfers

    Benefits: ACH can be a cost-effective option for eligible bank-to-bank transfers, direct deposits, and recurring bill payments. Scheduled payments can also reduce the need to handle each payment manually.

    Drawbacks: Processing may take one or more business days, and cutoff times, account limits, or insufficient funds can affect a payment. Errors and unauthorized ACH transactions may require prompt contact with your bank and may be subject to specific return deadlines.

    Debit Card Payments

    Benefits: Debit cards are convenient for in-store purchases, online shopping, and many recurring merchant payments. Authorization is often quick, and you usually do not need to enter bank routing details at checkout.

    Drawbacks: A transaction hold can temporarily reduce your available balance. Lost or compromised card details can lead to unauthorized charges, while merchant disputes and transaction fees depend on the circumstances and applicable terms.

    Expert Tip

    Choose the method that fits the payment and its deadline. Verify account or card details before authorizing a transaction, enable account alerts, and contact your bank promptly if you notice an unfamiliar payment. Reporting deadlines and protections vary by transaction type, so do not delay.

    ACH Transfer vs. Debit Card Payment: Detailed Comparison

    ACH transfers and debit card payments differ in how transactions are initiated, processed, and handled. Use this comparison to identify which method better fits your payment needs.

    FeatureACH TransferDebit Card Payment
    How it worksPayment instructions are processed through the ACH network between participating financial institutions.A card-network transaction is authorized by the card issuer and may proceed through clearing and settlement.
    Processing timeOften one or more business days; eligible transactions may qualify for same-day processing.Authorization is often quick, but final posting and settlement can take longer.
    Common usesDirect deposits, recurring bills, and transfers between eligible bank accounts.In-store purchases, online shopping, and merchant payments.
    Potential feesFees depend on the bank, payment provider, and type of transfer.Ordinary consumer purchases often have no separate card fee, but account or transaction-specific charges may apply.
    Recurring paymentsCommonly used for authorized automatic bill payments.Available when the merchant accepts debit cards for recurring billing.
    Errors and disputesACH rules, applicable consumer protections, and bank procedures determine the process.Issuer procedures, applicable law, and the type of transaction affect the process.
    Best suited forScheduled payments and eligible account-to-account transfers.Convenient payments to merchants.

    Key takeaway: ACH is generally designed for bank-account payments, while debit cards are designed for card-based purchases. Compare the actual fees, timing, and applicable protections rather than assuming one method is always faster, cheaper, or safer.

    Costs, Risks, and Expert Tips

    Compare the Potential Costs

    ACH transfers may be free or low-cost, but fees can apply depending on your bank, provider, and transaction type. Ordinary debit card purchases often carry no separate consumer transaction fee, although ATM withdrawals, foreign transactions, and certain account terms may involve charges. Review your bank’s fee schedule and the merchant’s payment terms before proceeding.

    Understand the Risks

    ACH payments may be delayed or returned because of incorrect account details, insufficient funds, processing cutoffs, or bank holidays. Unauthorized ACH debits may have specific reporting and return deadlines. Debit card risks include stolen card details, unauthorized purchases, and temporary authorization holds that reduce your available balance. The applicable protections and deadlines depend on the transaction and governing rules.

    Expert Tips to Protect Your Money

    • Verify the recipient, account details, and payment amount before authorizing a transaction.
    • Enable transaction alerts and review account activity regularly.
    • Keep sufficient available funds for scheduled ACH debits and check payment dates.
    • Contact your bank promptly if you notice an unfamiliar transaction, and follow its reporting instructions.

    For more practical guidance, review our bank account security checklist and learn how to dispute an unauthorized bank transaction.

    Common Mistakes to Avoid

    • Assuming every payment is instant: Debit card authorization is often quick, but final posting may take longer. ACH timing depends on processing schedules, bank cutoffs, and the type of payment.
    • Overlooking available balances: An ACH debit may be returned if sufficient funds are unavailable. A debit card authorization hold can also temporarily reduce the money available in your checking account.
    • Skipping payment details: Before authorizing an ACH transfer, verify the recipient and account information. For card payments, check the merchant, amount, and any additional charges.
    • Delaying fraud reports: Contact your bank promptly about unfamiliar or unauthorized transactions. Applicable reporting deadlines and protections vary by payment type and circumstances.

    Real-Life Example

    Suppose Maya needs to pay her $120 monthly electricity bill. Her utility company accepts both ACH autopay and debit card payments.

    Maya chooses ACH autopay because she wants a recurring payment. She checks the scheduled withdrawal date, confirms the authorization, and keeps enough money in her account. Later, she uses her debit card for an online purchase, checks the total before paying, and monitors her account for the posted transaction.

    Lesson: ACH can simplify recurring bills, while debit cards offer convenient merchant checkout. Either method requires attention to payment details, available funds, and account activity.

    If you spot an unfamiliar charge, read our guide on how to dispute an unauthorized bank transaction for practical next steps.

    Which Payment Method Should You Choose?

    The right choice depends on the payment’s purpose, the merchant’s options, the expected processing time, and any applicable fees or transaction limits.

    ACH May Be a Better Fit If You Want To

    • Move money between eligible bank accounts.
    • Receive direct deposits or arrange authorized recurring bill payments.
    • Make scheduled payments when the processing timeline suits your needs.

    A Debit Card May Be a Better Fit If You Want To

    • Pay for in-store purchases or online shopping.
    • Use a card-based checkout option accepted by the merchant.
    • Avoid entering bank routing and account details directly at checkout.

    Before deciding: Compare fees, processing times, available funds, and applicable dispute procedures. If a payment has a strict deadline, confirm the expected timing with your bank or provider instead of assuming either method will complete immediately.

    Frequently Asked Questions

    1. Is an ACH transfer the same as a debit card payment?

    No. ACH transfers use the Automated Clearing House network to process payments involving bank accounts. Debit card payments generally use card networks to pay merchants.

    2. Is ACH faster than a debit card?

    Debit card authorization is often quick at checkout, while ACH processing may take one or more business days. Eligible ACH payments can qualify for same-day processing, but authorization and final settlement are different stages.

    3. Which payment method usually costs less?

    It depends on the bank, payment provider, merchant, and transaction. ACH may be cost-effective for certain transfers, while ordinary consumer debit card purchases often have no separate transaction fee. Check the applicable terms.

    4. Can I use ACH to pay monthly bills?

    Yes. Many utility companies, lenders, and service providers accept authorized ACH payments for recurring bills. Check the payment schedule and keep sufficient funds available.

    5. Are ACH transfers safer than debit cards?

    Neither method is automatically safer in every situation. Security depends on how the payment is authorized, fraud controls, account security, and the protections that apply to the specific transaction.

    6. Can an ACH payment be reversed?

    Some ACH entries can be returned or corrected under applicable rules, but a completed payment cannot always be reversed on request. Contact your bank promptly if you identify an error or unauthorized debit.

    7. Do debit card payments come directly from checking?

    A standard debit card is linked to a deposit account, commonly a checking account. An approved purchase may first appear as pending before the final transaction amount is posted.

    8. Should I use ACH or a debit card for recurring payments?

    ACH can be convenient for eligible recurring bills, while debit cards work for subscriptions and services that accept card payments. Compare fees, payment dates, cancellation procedures, and how you can stop future payments.

    Final Verdict: ACH Transfer vs. Debit Card Payment

    ACH transfers and debit card payments both move money electronically, but each is suited to different needs. ACH is commonly used for direct deposits, authorized recurring bills, and transfers between eligible bank accounts. Debit cards are convenient for everyday shopping, online purchases, and payments to merchants that accept cards.

    There is no universal winner. Compare the expected processing time, fees, available balance, and applicable dispute protections before choosing. For time-sensitive payments, confirm the deadline with your bank or payment provider, and always verify the recipient and transaction details.

    Our Takeaway

    Choose ACH when a bank-account payment or scheduled transfer fits your needs. Choose a debit card when you want convenient merchant checkout. The best option is the one that suits your payment purpose, timing, and provider’s terms.

    Want to explore more ways to move money? Read our complete guide to bank transfers and payments for practical information about electronic payments and bank transfers.

    Make Smarter Banking Decisions

    Want to understand your payment options better? Explore our practical guides to bank transfers, electronic payments, and account security.

    Explore Banking Guides

    Have a question or feedback? Email Subhash Rukade.

    Important Disclaimer

    This article is for general educational and informational purposes only and does not constitute personalized financial or legal advice. Payment processing times, fees, error-resolution procedures, and consumer protections depend on the transaction, financial institution, provider, and applicable laws. Confirm the relevant terms with your bank or payment provider before making a decision.

    Written by Subhash Rukade | Founder, FinanceInvestment

  • ACH Transfer vs. Zelle: Differences, Fees & Speed (2026)

    ACH Transfer vs. Zelle: Differences, Fees & Speed (2026)

    ACH Transfer vs. Zelle: Which Is Better?

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    Personal Finance & Banking
    Published: October 26, 2026
    Updated: October 26, 2026
    Reading time: About 10 minutes

    ACH Transfer vs. Zelle: What’s the Difference?

    When you need to move money, the best payment method depends on who is receiving it and how quickly the funds need to arrive. An ACH transfer is commonly used for moving money between bank accounts, receiving direct deposits, and paying recurring bills. Zelle is designed mainly for sending money directly to people you know and trust through participating U.S. banks and credit unions.

    The biggest difference is how you use each service. ACH transfers can be scheduled for eligible payments and may take one or more business days, depending on the transfer type and bank. Zelle payments to enrolled recipients typically arrive within minutes, although timing and availability can vary.

    Speed alone should not decide your choice. You should also consider your bank’s transfer limits, any applicable fees, recipient eligibility, and what options are available if you send money to the wrong person. Zelle is particularly important to use carefully because payments to enrolled recipients generally cannot be canceled once sent.

    For a broader look at electronic payment options, explore our Bank Transfers and Payments Guide.

    What You’ll Learn

    • How ACH transfers and Zelle payments work.
    • How their speed, fees, transfer limits, and common uses compare.
    • When ACH may be more suitable than Zelle, and when Zelle may be more convenient.
    • How to avoid common payment mistakes and protect your money.

    Quick Answer: ACH Transfer vs. Zelle — Which Is Better?

    ACH transfers are generally better for routine bank-to-bank payments, direct deposits, and recurring bills. Zelle is often more convenient when you need to send money quickly to someone you know and trust through a participating U.S. bank or credit union. Before choosing, check your bank’s transfer limits, applicable fees, recipient eligibility, and timing. Zelle payments to enrolled recipients generally cannot be canceled once sent, so verify the recipient before confirming.

    7 Key Takeaways

    • ACH transfers are commonly used for direct deposits, recurring bills, and transfers between bank accounts.
    • Zelle is designed mainly for sending money to people you know and trust through participating U.S. financial institutions.
    • Eligible Zelle payments typically arrive within minutes, while ACH timing depends on the payment type, bank, and processing schedule.
    • ACH transfers are often low-cost, but fees and processing options depend on your bank and the transaction.
    • Zelle limits vary by bank, account, and recipient circumstances; check your financial institution’s current limits.
    • Confirm the recipient and payment details before sending money, especially when using Zelle for the first time.
    • Contact your bank promptly if you notice an unauthorized transaction or send money to the wrong recipient.

    The Bottom Line

    Choose ACH for many planned payments and routine bank transfers; consider Zelle when speed and convenience matter for a payment to someone you trust. Neither option is automatically best for every situation. Check the terms of your bank, verify the recipient, and never use either payment method to respond to pressure from an unexpected caller or stranger.

    ACH Transfer vs. Zelle: At a Glance

    ACH transfers and Zelle both move money electronically, but they serve different needs. ACH is commonly used for scheduled payments and transfers between bank accounts, while Zelle is designed mainly for sending money to people you know and trust.

    Best for ACH

    Recurring bills, direct deposits, and planned transfers between eligible bank accounts.

    Best for Zelle

    Convenient person-to-person payments to enrolled recipients you know and trust.

    Main Difference

    ACH follows bank processing schedules; eligible Zelle payments typically arrive within minutes.

    Quick Comparison Checklist

    FeatureACH TransferZelle
    Typical timingOften one or more business days, depending on the transfer and bank.Typically minutes for enrolled recipients.
    Common usesDirect deposits, bills, and eligible bank-to-bank transfers.Payments to friends, relatives, and other trusted people.
    FeesOften free for consumers, depending on the bank and transfer type.Many participating banks offer it without a consumer fee; check your bank’s terms.
    LimitsDepend on the bank, account, and transfer type.Depend on the participating financial institution and account.
    Payment recoveryOptions depend on the transaction, its status, and bank procedures.Payments to enrolled recipients generally cannot be canceled once sent.

    Quick Take: Choose ACH for many planned bank transfers and recurring payments. Consider Zelle for convenient payments to people you trust. Before sending money, confirm the recipient, review your bank’s limits and fees, and check the expected delivery time.

    ACH Transfers vs. Zelle: A Complete Beginner’s GuideACH transfer vs Zelle

    ACH transfers and Zelle can both move money electronically, but they are designed for different situations. ACH is commonly used for direct deposits, recurring bill payments, and transfers between bank accounts. Zelle is mainly designed to send money to and receive money from people you know through participating U.S. banks and credit unions.

    The biggest difference is not simply speed. It is how each service works, what types of payments it supports, and how much control you may have if something goes wrong. Understanding those differences can help you choose a payment method that fits the transaction.

    1. What Is an ACH Transfer?

    An ACH transfer is an electronic bank payment processed through the Automated Clearing House network in the United States. It allows financial institutions to exchange payment instructions for many everyday transactions without using paper checks.

    ACH transfers are commonly used for:

    • Receiving paychecks or government benefits through direct deposit.
    • Paying utility bills, loan installments, and other recurring expenses.
    • Moving money between your own accounts at different banks.
    • Making eligible payments to businesses and service providers.

    Standard ACH transfers often take one or more business days, although timing depends on the bank, transfer type, processing cutoffs, weekends, and holidays. Some financial institutions offer eligible same-day ACH services. For a closer look at the process, read our guide to how ACH transfers work.

    2. What Is Zelle?

    Zelle is a digital payment service designed primarily for sending money between people with eligible U.S. bank or credit union accounts. Depending on the participating financial institution, you may access Zelle directly through your banking app or online banking service.

    Zelle is commonly used for:

    • Paying a friend back for dinner or shared expenses.
    • Sending money to a family member you know and trust.
    • Splitting household costs with a trusted roommate.
    • Making other eligible person-to-person payments.

    Payments to enrolled recipients typically arrive within minutes, but timing can vary because of bank processing, account eligibility, security reviews, or other restrictions. Zelle should not be treated as a payment method for buying goods from strangers because eligible payments generally do not include standard purchase protection.

    3. How Are ACH Transfers and Zelle Different?

    ACH is a bank payment network used for several kinds of electronic transactions, while Zelle is a service focused mainly on person-to-person payments. This distinction matters when choosing a method.

    • Purpose: ACH works well for scheduled payments, direct deposits, and transfers between bank accounts. Zelle is more suited to sending money to someone you know.
    • Speed: Standard ACH transfers may take one or more business days. Eligible Zelle payments to enrolled recipients typically arrive within minutes.
    • Setup: ACH transfers may require bank account and routing information or a linked-account setup. Zelle typically uses an enrolled recipient’s email address or U.S. mobile number.
    • Limits: ACH transfer limits and Zelle sending limits vary by financial institution, account, and transaction type.
    • Payment problems: Options for stopping, correcting, or disputing a transaction depend on the payment method, transaction status, applicable rules, and your bank.

    4. Which Option Is Better for Everyday Banking?

    Choose ACH when you need to move money between your own bank accounts, receive direct deposits, or arrange recurring payments. It is often the more practical option for transactions that follow a schedule or involve account-to-account transfers.

    Choose Zelle when you need to send money promptly to a person you know and have verified. Before sending, confirm the recipient’s details and amount carefully. A completed payment to an enrolled recipient generally cannot be canceled, so do not rely on being able to recover money sent to the wrong person.

    Practical tip: Match the payment method to the purpose. Use ACH for routine bank transfers and scheduled payments; use Zelle for eligible person-to-person payments when you trust the recipient. Before confirming either transaction, review the amount, destination, fees, and any applicable limits.

    How ACH Transfers and Zelle Payments Work

    Although ACH transfers and Zelle both move money electronically, the steps involved are different. ACH transfers generally follow bank-processing schedules, while Zelle is designed to make eligible person-to-person payments quickly. Knowing what happens before and after you press “Send” can help you avoid delays and costly mistakes.

    1. How an ACH Transfer Works

    An ACH transfer starts when you or an authorized organization submits a payment instruction. Your bank or payment provider processes the instruction and sends it through the Automated Clearing House network. The receiving financial institution then processes the transaction according to its procedures.

    A typical transfer between your own bank accounts may involve these steps:

    1. Link the accounts: Add the receiving account using the information and verification method required by your bank.
    2. Enter the transfer details: Select the sending and receiving accounts, enter the amount, and choose a transfer date if available.
    3. Review and authorize: Check the account details, amount, timing, and any displayed fees before confirming.
    4. Wait for processing: Your bank submits the transfer for processing. Standard ACH transfers often take one or more business days; eligible same-day options may be available.
    5. Confirm completion: Check both accounts or your transaction history to verify that the funds arrived as expected.

    Processing times can depend on bank cutoffs, weekends, holidays, account verification, and the type of ACH service used. A displayed balance or pending transaction does not always mean the transfer is fully settled.

    2. How a Zelle Payment Works

    Zelle payments are generally initiated through a participating bank or credit union’s app or online banking service. You typically select a recipient using an enrolled U.S. mobile number or email address, enter the amount, and authorize the payment.

    A typical Zelle payment follows these steps:

    1. Open your banking app: Find Zelle within your participating financial institution’s payment options.
    2. Choose the recipient: Enter or select the recipient’s enrolled email address or U.S. mobile number.
    3. Enter the amount: Check the amount carefully and confirm that you have selected the correct person.
    4. Authorize the payment: Follow your bank’s instructions to submit the transaction.
    5. Check the status: Review the confirmation and transaction history. Eligible payments to enrolled recipients typically arrive within minutes, but delays or security reviews can occur.

    Before sending money, verify the recipient through a trusted channel, particularly if the payment request came through an unexpected message. If a payment has been sent to an enrolled recipient, it generally cannot be canceled. A payment to an unenrolled recipient may be cancelable while pending, depending on its status and your bank’s rules.

    3. What Happens if Something Goes Wrong?

    The options available after a mistake or suspicious transaction depend on how the payment was made and its current status.

    • Incorrect ACH details: Contact your bank promptly. A transfer may be delayed, rejected, or sent to the wrong account, and recovery is not guaranteed.
    • Unexpected ACH debit: Report unauthorized activity to your financial institution as soon as possible. Applicable dispute procedures and deadlines depend on the transaction and account type.
    • Zelle sent to the wrong person: Contact your bank immediately, but understand that a completed payment to an enrolled recipient generally cannot be canceled or guaranteed to be recovered.
    • Suspected fraud: Use your bank’s official app, website, or the phone number on your card to report the transaction. Do not rely on contact details provided by a suspicious caller or message.

    Practical tip: Save your confirmation details and review the transaction status after sending money. For either method, act quickly if you notice an error or unauthorized payment; contacting your bank promptly may help, but it does not guarantee that funds can be recovered.

    Benefits and Drawbacks of ACH Transfers and Zelle

    ACH transfers and Zelle both offer convenient ways to move money electronically, but each has limitations. ACH is often useful for scheduled payments and transfers between bank accounts, while Zelle can be convenient when you need to pay someone you know quickly. The better option depends on the purpose of the payment, how soon the money is needed, and the risks involved.

    Benefits of ACH Transfers

    • Useful for moving money between your own bank accounts.
    • Supports direct deposits and many recurring bill payments.
    • Can be scheduled in advance for eligible transactions.
    • Often available at low cost or with no consumer fee, depending on the bank and transfer type.
    • Works well for routine payments that do not require immediate delivery.

    Drawbacks of ACH Transfers

    • Standard transfers often take one or more business days.
    • Weekends, holidays, processing cutoffs, and verification can affect timing.
    • Transfer limits and fees vary by financial institution and account.
    • Incorrect account details can delay a payment or send it to the wrong destination.
    • Stopping or recovering a transfer may be difficult after processing begins or completes.

    Benefits of Zelle

    • Eligible payments to enrolled recipients typically arrive within minutes.
    • Convenient for sending money to friends and family you know.
    • Can be accessed through participating banks’ or credit unions’ apps and websites.
    • Many participating institutions offer eligible Zelle payments without a fee, although policies can vary.
    • Usually requires the recipient’s enrolled U.S. mobile number or email address rather than manually entering bank routing details.

    Drawbacks of Zelle

    • It is primarily designed for eligible person-to-person payments, not routine external bank transfers.
    • Sending limits depend on your financial institution and account.
    • Payments to enrolled recipients generally cannot be canceled once sent.
    • Payments to strangers or fraudulent recipients can be difficult to recover.
    • It does not provide standard purchase protection for transactions involving goods or services.

    Practical tip: Use ACH for scheduled payments, direct deposits, and transfers between your own accounts. Consider Zelle for eligible payments to people you know and trust. Before sending money, verify the recipient, check your bank’s limits and fees, and remember that fast payments may be difficult to recover if you make a mistake.

    ACH Transfer vs. Zelle: Detailed Comparison

    ACH transfers and Zelle serve different payment needs. ACH is commonly used for direct deposits, recurring bills, and bank-to-bank transfers, while Zelle is designed mainly for eligible payments between people who know and trust each other. Compare their main features before deciding which method fits your transaction.

    FeatureACH TransferZelle
    Primary purposeBank transfers, direct deposits, recurring payments, and eligible bill paymentsEligible person-to-person payments
    Typical speedStandard transfers often take one or more business days; eligible same-day options may be availablePayments to enrolled recipients typically arrive within minutes, subject to eligibility and bank processing
    Recipient detailsOften requires bank account details, routing information, or a linked accountTypically uses the recipient’s enrolled U.S. mobile number or email address
    Common usesPaychecks, recurring bills, and transfers between your own bank accountsPaying friends or family members you know and trust
    FeesMany consumer transfers are free, but fees may apply depending on the bank and transfer typeMany participating banks offer eligible payments without a fee; check your institution’s terms
    Transfer limitsDepend on the bank, account, transfer method, and transaction typeDepend on the participating financial institution and account
    Recurring paymentsWell suited to eligible scheduled payments and direct depositsPrimarily designed for person-to-person payments rather than routine bill scheduling
    Canceling a paymentOptions depend on the transfer status, type, and bank rulesA completed payment to an enrolled recipient generally cannot be canceled
    Mistakes and disputesContact your bank promptly; correction or recovery is not guaranteedContact your bank promptly; recovery of an incorrectly sent payment is not guaranteed
    Purchase protectionNot a general purchase-protection service; rights depend on the transaction and applicable rulesDoes not provide standard purchase protection for goods or services
    Best suited forRoutine banking, scheduled payments, and account-to-account transfersFast, eligible payments to people you know and trust

    How to choose: Choose ACH for recurring payments, direct deposits, and transfers between your own bank accounts. Consider Zelle when you need to pay someone you know and trust quickly. Before using either method, verify the recipient and review your bank’s current fees, limits, and processing rules.

    Costs, Risks, and Expert Tips for ACH Transfers and Zelle

    ACH transfers and Zelle may be available without a separate fee for many everyday consumer transactions, but the exact costs depend on your financial institution, account, and payment type. Some banks charge for expedited or same-day ACH transfers, and transfer limits can affect how much you can send at once. Zelle fees and sending limits also vary by participating bank or credit union. Review your bank’s fee schedule and payment terms before initiating a transfer.

    Costs to Check Before Sending Money

    • Standard ACH transfers: Many banks offer eligible standard transfers without a fee, but policies vary by institution and account.
    • Same-day or expedited transfers: Some banks charge for faster processing or offer it only for certain accounts and transactions.
    • Zelle payments: Many participating institutions offer eligible payments without a separate fee, but check your bank’s current terms.
    • Transfer limits: Daily, weekly, or per-transaction limits may apply. Limits can differ between ACH and Zelle and may vary by account.
    • Potential loss: A mistaken or fraudulent payment may be difficult to recover. Check the recipient and payment details carefully before confirming.

    Risks Worth Understanding

    Both methods carry risks if you enter incorrect information, fall for a scam, or allow someone else to access your banking account. The type of risk differs depending on the payment.

    With ACH transfers, incorrect account details can delay a payment or send funds to an unintended destination. Unauthorized ACH debits may be subject to dispute procedures and deadlines, which can depend on the account and transaction type. Contact your bank promptly if you notice an unfamiliar debit or transfer.

    With Zelle, the main concern is that eligible payments can arrive quickly and may be difficult to stop after they are sent. A payment to the wrong enrolled recipient generally cannot be canceled. Scammers may also pressure people into authorizing payments themselves. Zelle is best reserved for people you know and trust, not purchases from strangers.

    Practical Ways to Reduce Risk

    • Double-check the recipient’s account details for ACH and the enrolled name and contact information for Zelle before sending money.
    • Use a unique online banking password and enable multifactor authentication when available.
    • Never share your password, PIN, or one-time verification code with someone who contacts you unexpectedly.
    • Ignore urgent requests to move money to a supposed “safe account.” Contact your bank using its official app, website, or the number on your card.
    • Review transaction alerts and account activity regularly so you can report suspicious payments quickly.
    • Keep transaction confirmations and relevant messages if you need to report an error or suspected fraud.

    Warning: Watch for payment and recovery scams. A scammer may pose as a bank employee and pressure you to send money through Zelle, or claim they can recover lost funds for an upfront fee. Do not trust an unexpected caller simply because they know some of your personal details. Verify the request independently, and never share banking credentials to recover money.

    If you suspect someone has accessed your account or an unauthorized transfer has occurred, contact your bank promptly and ask what steps are available to secure the account, restrict further transactions, or dispute the payment. Our bank account security checklist can help you review essential protections.

    Common ACH and Zelle Mistakes—and How to Avoid Them

    Both ACH transfers and Zelle can make everyday payments easier, but a small mistake can create delays or financial losses. The risks often arise when someone rushes through payment details, misunderstands how a transfer works, or trusts a request without verifying it first.

    • Choosing the wrong payment method: Using Zelle for a purchase from a stranger can leave you without standard purchase protection. Choose a payment method suited to the transaction.
    • Entering incorrect recipient details: A wrong bank account number or Zelle contact can send money to an unintended recipient. Check the details carefully before confirming.
    • Assuming every transfer is immediate: Standard ACH transfers often take one or more business days. Even Zelle payments may be delayed by enrollment, eligibility checks, or bank security reviews.
    • Ignoring transfer limits and fees: Your bank may set different limits or charge different fees depending on the payment type. Check the terms before initiating a large transfer.
    • Believing a payment can always be canceled: A completed Zelle payment to an enrolled recipient generally cannot be canceled, while ACH cancellation and recovery options depend on the transaction status and applicable rules.
    • Sending money after an unexpected request: Scammers may impersonate bank employees, relatives, or businesses. Verify the request independently before authorizing a payment.

    A Hypothetical Example

    Imagine Alex needs to move $1,500 from a checking account at one bank to a savings account at another. Alex chooses a standard ACH transfer, checks the linked account details, reviews the estimated arrival date, and confirms the transaction. The transfer takes a couple of business days to complete.

    Later, a person claiming to be from the bank calls and says Alex must immediately send $1,500 through Zelle to protect the savings. Instead of acting on the call, Alex hangs up and contacts the bank through its official app. The bank confirms that the unexpected payment request should not be followed.

    The takeaway: ACH is often a practical choice for moving money between your own bank accounts, while Zelle is intended mainly for eligible payments to people you know and trust. Never send money to a supposed “safe account” because an unexpected caller tells you to.

    If you notice a transfer you did not authorize, contact your bank promptly and ask how to report it. Our bank account security checklist can help you review steps to protect your account.

    Who Should Choose ACH Transfers vs. Zelle?

    The best payment method depends on where the money is going, how quickly it needs to arrive, and whether the recipient is someone you trust. Rather than choosing based on speed alone, match the transfer method to your everyday banking needs.

    • For people transferring money between their own bank accounts: ACH is often the practical choice, especially when moving money between checking and savings accounts at different banks. Check the expected arrival time and any transfer limits before scheduling it.
    • For employees and people receiving regular income: ACH is commonly used for direct deposit of paychecks and eligible government benefits. Your employer or benefits provider typically arranges the deposit using your bank account information.
    • For people paying recurring bills: ACH may be suitable for eligible utility bills, loan payments, and other scheduled expenses. Review the payment amount, due date, and authorization terms to avoid unexpected withdrawals.
    • For friends and family who need money quickly: Zelle can be convenient for eligible payments to people you know and trust. Confirm the recipient’s enrolled details carefully because completed payments generally cannot be canceled.
    • For people paying someone they have never met: Avoid using Zelle for purchases from strangers. Because it does not provide standard purchase protection, consider a payment method that offers appropriate buyer protection for the transaction.
    • For anyone sending a large or time-sensitive payment: Compare your bank’s ACH and Zelle limits, processing times, and fees. If the amount exceeds your limit or the deadline is important, contact your bank before sending the money.

    Choose based on the purpose: ACH is generally better suited to routine bank transfers, direct deposits, and scheduled payments. Zelle is generally better suited to eligible person-to-person payments when speed matters and the recipient is trusted. Neither method guarantees that a mistaken or fraudulent payment can be recovered.

    Frequently Asked Questions About ACH Transfers vs. Zelle

    1. Is ACH or Zelle better for transferring money?

    It depends on the purpose. ACH is generally better suited to transfers between your own bank accounts, direct deposits, and recurring payments. Zelle is designed mainly for eligible person-to-person payments to people you know and trust.

    2. Is Zelle faster than an ACH transfer?

    Usually, for eligible person-to-person payments. Zelle payments to enrolled recipients typically arrive within minutes, while standard ACH transfers often take one or more business days. Delays can occur with either method, and eligible same-day ACH options may be available.

    3. Is ACH cheaper than Zelle?

    Not necessarily. Many banks offer eligible consumer ACH transfers and Zelle payments without a separate fee, but charges depend on the financial institution, account, and transaction type. Check your bank’s current fee schedule before sending money.

    4. Can I use Zelle to transfer money between my own bank accounts?

    Zelle is primarily intended for eligible payments between people, not as a general service for moving money between your own accounts. An ACH transfer is usually the more appropriate option for transferring funds between accounts you own at different banks.

    5. Can I cancel a Zelle payment after sending it?

    A Zelle payment to an enrolled recipient generally cannot be canceled once sent. A payment to someone who has not enrolled may be cancelable while pending, depending on the payment status and your bank’s rules. Always verify the recipient before confirming.

    6. Can an ACH transfer be reversed or recalled?

    Sometimes, but not in every situation. Options depend on whether the transfer is pending or completed, the reason for the request, the transaction type, and applicable rules. Contact your bank promptly if you entered incorrect details or suspect fraud. A recall or recovery is not guaranteed.

    7. Which is safer: ACH or Zelle?

    Neither method is automatically safer in every situation. Both can be used for legitimate payments, but scams and mistakes can lead to losses. ACH is commonly used for routine banking transactions, while Zelle requires particular care because eligible payments can arrive quickly and may be difficult to recover. Verify all payment details and report suspicious activity promptly.

    8. Does Zelle charge a fee to send money?

    Many participating banks and credit unions offer eligible Zelle payments without a separate fee. However, terms can vary, so check your financial institution’s current policies rather than assuming every transaction is free.

    9. What should I do if I accidentally send money to the wrong person?

    Contact your bank or payment provider immediately and explain what happened. For Zelle, a completed payment to an enrolled recipient generally cannot be canceled, and recovery is not guaranteed. For ACH, available correction or recall options depend on the transaction and its status. Keep your confirmation details and any relevant messages.

    10. Should I use Zelle to pay someone I found online?

    Be cautious. Zelle is intended primarily for people you know and trust and does not provide standard purchase protection for goods or services. Avoid using it to pay strangers for online purchases. Consider a payment method that offers appropriate buyer protection.

    Final Verdict: Choose the Transfer Method That Fits Your Needs

    When comparing ACH transfers vs. Zelle, the better choice depends on what you need to accomplish. ACH is generally the more practical option for moving money between your own bank accounts, receiving direct deposits, and arranging eligible recurring payments. Zelle is designed mainly for eligible person-to-person payments and can be convenient when you need to send money quickly to someone you know and trust.

    Before choosing either method, consider the transfer speed, your bank’s fees and limits, and whether you can stop or recover the payment if something goes wrong. Standard ACH transfers often take one or more business days, while eligible Zelle payments to enrolled recipients typically arrive within minutes. However, faster delivery does not necessarily mean a payment is safer or easier to recover.

    Always verify the recipient and amount before confirming a transaction. Avoid using Zelle to pay strangers for online purchases, and never send money because an unexpected caller claims it must be moved to a “safe account.” If you notice an unauthorized transaction or suspect fraud, contact your bank promptly through an official channel. Recovery may be possible in some circumstances, but it is not guaranteed.

    For more guidance on protecting your money, read our Bank Account Security Checklist and our guide to Bank Security and Fraud Prevention. Understanding your payment options and checking details before sending money can help you bank with greater confidence.

    Have a Money Question? Keep Exploring.

    Choosing between ACH transfers and Zelle depends on your payment needs, timing, and comfort with the risks. Have a banking question or a financial topic you would like FinanceInvestment to explain? Get in touch.

    Email FinanceInvestment

    Continue Your Research

    Disclaimer: This article is for educational purposes only and is not financial, legal, or banking advice. Transfer speeds, fees, limits, and recovery options vary by financial institution and transaction. For a specific payment concern or suspected fraud, contact your bank through a verified channel.