Tag: ACH Payments

  • What Happens to Direct Deposit When a Bank Closes? 5 Smart Steps

    What Happens to Direct Deposit When a Bank Closes? 5 Smart Steps

    What Happens to Direct Deposit When a Bank Closes?

    Written by
    Subhash Rukade
    Founder, FinanceInvestment
    Banking Guide
    2026 Edition

    Published:

    Updated:

    Reading Time: Approx. 11 min


     What Happens to Direct Deposit When a Bank Closes Your Bank Closed. Is Your Next Paycheck Still Coming?

    It’s payday tomorrow, but your bank has just failed. Suddenly, one question matters more than anything else: what happens to direct deposit when a bank closes? Will your paycheck arrive on time, or could your Social Security or pension payment get caught in the disruption?

    The answer depends on what happens to your account. If another bank takes over, direct deposits often continue without interruption. If your account closes instead, future payments may need to be redirected or returned to the sender.

    Our guide to FDIC and NCUA deposit insurance explains how eligible balances are protected. Here, we’ll focus on the money you’re still waiting to receive.

    What You’ll Learn

    • Whether payroll, Social Security and pension deposits can continue.
    • What changes when an acquiring bank takes over.
    • What to do if a deposit is delayed or returned.
    • When to give your employer or benefit agency new banking details.

    Quick Answer: Will Your Direct Deposit Still Arrive?

    In many bank failures, direct deposits continue. If another insured bank takes over your account, paychecks and benefit payments can keep arriving. If your account closes without a takeover, incoming deposits may be returned or require new instructions. Some government payments may receive temporary arrangements.

    6 Key Takeaways

    • Acquiring bank: Existing deposit instructions may continue working.
    • Closed account: A future payment could be returned to its sender.
    • Employer payroll: Check with payroll before changing bank details.
    • Federal benefits: Follow official payment and account-update instructions.
    • FDIC protection: Deposit insurance protects eligible balances, not paycheck arrival dates.
    • Backup account: Having another verified account can reduce future disruption.

    Bottom Line: Check the FDIC’s bank-specific announcement and your account activity first. If an expected deposit is missing, contact the employer or agency that sent it and ask whether the payment was completed or returned.

    At a Glance: Direct Deposit After a Bank Closure

    PAYMENT METHOD
    ACH Direct Deposit
    STANDARD FDIC LIMIT
    $250,000*
    WHO SHOULD CHECK
    Employees, retirees and benefit recipients
    SituationLikely Outcome
    Bank acquiredDeposits typically continue if accounts transfer.
    Account closedFuture credits may be returned to the sender.
    Federal benefitsTemporary receiving arrangements may be available.
    Missing paycheckAsk payroll to check payment status and return details.

    *FDIC insurance generally covers eligible deposits up to $250,000 per depositor, per insured bank, per ownership category. It does not guarantee the arrival date of a future deposit.

    Quick Take: Check whether your account transferred to another bank before changing direct deposit instructions. An unnecessary update could create confusion while a scheduled payment is already being processed.

    Complete Beginner Guide: How Direct Deposit Reaches Your Account What Happens to Direct Deposit When a Bank Closes
    Direct deposit lets you receive a paycheck, pension or government benefit electronically. Instead of mailing a paper check, the organization paying you sends instructions to deposit money into your designated bank or credit union account.

    Who Sends the Money?

    Your employer may use a payroll company to send wages, while retirement administrators and government agencies arrange their own payments. Each sender needs valid banking information. If you’re new to the process, our guide to direct deposit explains the basics.

    What Is an ACH Credit?

    Most direct deposits use the Automated Clearing House (ACH) network. An ACH credit pushes money toward your account, unlike an ACH debit that pulls an authorized payment from it. See how ACH transfers work for a fuller explanation.

    One detail matters during a bank failure: payment submitted doesn’t mean payment received. The receiving bank must still process the credit. If the account is no longer available, the deposit may be returned to the sender.

    How Direct Deposit Works After a Bank Failure

    A bank failure doesn’t always mean your account disappears overnight. The FDIC may transfer deposits to another insured bank or arrange a payout when accounts aren’t assumed. What happens next determines how your incoming payments are handled.

    1. Your Account Moves to Another Bank

    When an acquiring bank assumes your deposit account, existing payroll and benefit deposits generally continue. You may receive updated banking information later, but don’t change routing numbers based on rumors. Follow the FDIC’s bank-specific notice and the acquiring bank’s instructions.

    2. No Bank Takes Over Your Account

    If your account closes instead, future ACH credits may be returned. Ask your employer or pension administrator whether a payment was sent, accepted or returned before requesting a replacement. Our guide to changing direct deposit details explains the usual update process.

    3. Social Security and Other Federal Benefits

    For federal benefit payments, temporary receiving arrangements may be made when no bank assumes the accounts. However, those arrangements vary. Check official FDIC instructions and contact the appropriate benefit agency if your payment doesn’t appear as expected.

    Before changing anything: Confirm whether your account is still active, save the official bank notice and ask the payment sender about any deposit already in progress. This helps prevent conflicting instructions or duplicate payments.

    Benefits and Drawbacks of Direct Deposit Transfers

    When another bank takes over your account, the transition may be easier than opening a replacement account yourself. However, some changes can affect how you manage your money.

    Potential Benefits

    • Fewer disruptions: Existing payroll instructions may keep working.
    • Less paperwork: You may not need to submit new bank details immediately.
    • Continued access: The acquiring bank may provide access to transferred deposits.

    Possible Drawbacks

    • Updated details: Routing numbers or account information may eventually change.
    • Payment follow-up: Some deposits may need verification during the transition.
    • Different terms: Account fees, features or service arrangements may change.

    Practical tip: Read the acquiring bank’s account notices and compare any new terms before deciding whether to keep the transferred account.

    Bank Takeover vs. FDIC Payout vs. Closed Account

    The important difference is whether your account stays open to receive new money. An FDIC payout and an account closure can happen together, so these situations aren’t always separate.

    SituationExisting DepositsFuture Direct DepositWhat to Do
    Acquiring bank assumes accountAssumed balances transfer to the new bank.Generally continues through the transferred account.Follow the acquiring bank’s notices.
    FDIC pays insured depositsEligible insured balances are paid under FDIC rules.May require a new account if the original closes.Check payout and account instructions.
    Receiving account closedHandled according to the bank’s resolution.May be returned; special benefit arrangements can apply.Verify status with the payment sender.

    Key distinction: FDIC insurance addresses eligible money already deposited at the failed bank. It does not guarantee that a future paycheck or benefit payment will reach a closed account on schedule.

    Delayed Paychecks, Missing Deposits and Expert Tips

    If payday arrives and your account is still empty, start with the payment trail. A missing deposit could be delayed, redirected or returned—not necessarily lost.

    Four Steps to Take

    1. Read the FDIC notice: Confirm which bank now handles your account, if any.
    2. Check your account: Look for a posted deposit; pending transactions may not always appear.
    3. Contact the sender: Ask payroll or the benefit agency whether the ACH credit was sent or returned.
    4. Confirm the next payment: If new details are required, ask about processing deadlines before updating them.

    Expert Tip: Save the expected payment date, amount and any ACH trace number available from the sender. These details can help investigate a missing credit. See our guide to why direct deposit may arrive late.

    Watch for fees and scams: A delay may affect bill payments. Ask creditors about possible flexibility, and never share banking credentials with someone claiming they can release your paycheck for a fee.

    Common Mistakes to Avoid After a Bank Closes

    A sudden bank closure can make even routine payroll decisions stressful. Avoid these mistakes while your account’s status is being confirmed.

    • Updating payroll immediately: An acquiring bank may still accept deposits using your existing instructions.
    • Assuming a returned payment is lost: The sender may need to trace and reissue it.
    • Requesting payment twice: Ask payroll to verify the original credit before arranging a replacement.
    • Following unofficial instructions: Verify account-change requests through trusted bank or employer channels.

    Example: A $2,400 Paycheck During a Bank Closure

    Hypothetical example: Maria expects a $2,400 paycheck on Friday. Her bank fails on Thursday. If another bank assumes her account, her existing direct deposit instructions may continue working.

    If the receiving account closes instead, the credit may be returned. Maria asks payroll to confirm the payment’s status before providing new banking details or requesting reissuance.

    Key lesson: A bank failure doesn’t automatically erase an incoming paycheck. Confirm the account’s status and trace the payment before taking further action.

    Who Should Act First After a Bank Closure?

    The closer your next payment date, the more important it is to confirm whether your account can still receive deposits. Different payment sources require different contacts.

    Employees

    Contact payroll if payday is approaching and your account status is unclear. Ask about the deadline for changing deposit instructions.

    Retirees

    For private pension payments, contact the plan administrator to confirm the next deposit and any required banking updates.

    Federal Benefit Recipients

    If your receiving account has closed, follow official instructions from Social Security or the agency issuing your benefit.

    Priority rule: Act promptly when an upcoming payment has no working destination. Otherwise, verify the transfer before changing account details.

    Frequently Asked Questions

    1. Will my paycheck arrive if my bank closes?

    Possibly. If an acquiring bank assumes your account, direct deposits generally continue. Check its official transition instructions.

    2. What if payroll sends money to a closed account?

    The ACH credit may be returned. Ask payroll to trace the payment before requesting reissuance.

    3. Does FDIC insurance protect my paycheck?

    Eligible funds already deposited may be insured. A future paycheck not yet deposited isn’t automatically covered.

    4. Must I change direct deposit immediately?

    Not always. Confirm whether your account transferred before updating payroll or benefit instructions.

    5. Will Social Security deposits continue?

    They may continue through an assumed account or temporary arrangements. Follow FDIC and Social Security guidance.

    6. How long does a returned deposit take?

    Timing varies. Your payment sender can check the return status and explain when reissuance may occur.

    7. Will my routing number change?

    It may change later. Follow the acquiring bank’s verified instructions rather than updating details prematurely.

    8. Who can help locate a missing deposit?

    Contact payroll or the paying agency first. The receiving bank may also help investigate.


    Final Verdict: What Happens to Your Direct Deposit?

    A failed bank doesn’t automatically mean a lost paycheck. If another bank assumes your account, direct deposits generally continue. If the account closes, incoming payments may be returned and need to be traced or reissued by the sender.

    Before updating payroll details, confirm your account’s status through official notices. If a payment is missing, contact your employer or benefit agency promptly.

    Remember: Deposit insurance protects eligible bank balances, not the timing of future paychecks. Learn more in our FDIC and NCUA insurance guide.

    Have a Money Question? Keep Exploring.

    Waiting for a paycheck during a bank closure can feel uncertain. FinanceInvestment makes banking topics easier to understand, so you can ask better questions and make informed decisions.

    Start with our guides to verifying FDIC insurance and handling delayed direct deposits.

    📩 Get in Touch With FinanceInvestment

    Disclaimer: This content is educational, not personalized financial or legal advice. Bank-failure procedures and payment timelines vary. Follow official FDIC, bank and payment-agency instructions for your situation.
  • What Happens to Automatic Payments When Your Bank Fails? 7 Smart Tips

    What Happens to Automatic Payments When Your Bank Fails? 7 Smart Tips

    What Happens to Automatic Payments When Your Bank Fails?

    Written by Subhash Rukade
    Founder, FinanceInvestment

    BANKING GUIDE 2026

    Published: Nov 10, 2026

    Updated: Nov 10, 2026

    Reading Time: 11 min


     What Happens to Automatic Payments When Your Bank Fails Your Bank Failed. Are Your Bills Still Getting Paid?

    Your mortgage payment is due Monday. Your electricity bill is on autopay. Then, on Friday, you learn that your bank has failed. Suddenly, a question you never expected to ask becomes urgent: What happens to automatic payments when your bank fails?

    Some payments may continue normally if another bank takes over your accounts. Others may be delayed, returned or require updated payment instructions. The outcome depends on how the failed bank is resolved and how each payment was arranged.

    FDIC insurance protects eligible deposits, but it does not guarantee that every scheduled bill will be paid on time. Our FDIC and NCUA Insurance Explained guide covers the protection basics.

    What You’ll Learn

    • Whether existing automatic payments can continue.
    • How ACH debits, bill pay and recurring card charges differ.
    • Which payments and account details to check first.
    • How to avoid missed bills and possible late fees.

    Quick Answer: Do Automatic Payments Continue After a Bank Failure?

    Sometimes, but not always. When another bank assumes the failed bank’s deposits, many existing automatic payments may continue. If the FDIC instead pays depositors directly and closes their accounts, linked payments may be rejected or require new instructions. Even after a takeover, confirm that important payments are still active.

    6 Key Takeaways

    • Bank takeover: Existing payment arrangements may remain active.
    • FDIC payout: A replacement account may be necessary.
    • ACH withdrawals: Pending does not mean successfully paid.
    • Online bill pay: Review scheduled payments individually.
    • Upcoming due dates: Contact billers before payments become overdue.
    • Payment records: Keep confirmations and check for returned transactions.

    Bottom Line: Check the status of your next essential bill before its due date. If payment instructions have changed, update the biller and use a verified alternative payment method. Avoid sending a duplicate payment until you know whether the original one settled.

    At a Glance: Automatic Payments After a Bank Failure

    FDIC COVERAGE LIMIT
    $250,000
    Per depositor, per insured bank, per ownership category.
    AUTOPAY STATUS
    Must Be Verified
    A bank takeover does not guarantee every payment will settle.

    Best for: Households managing mortgage, rent, utility, insurance, loan or credit card payments through an affected bank.

    SituationWhat You Should Do
    Bank takeoverCheck account details and upcoming autopay.
    FDIC payoutArrange replacement payment instructions.
    Pending paymentConfirm whether the biller received it.

    Quick Take: Start with bills due soonest. Confirm the payment status with each biller, and follow the acquiring bank’s or FDIC’s instructions before changing account details.

    Automatic Payments Explained: What Beginners Should Know What Happens to Automatic Payments When Your Bank Fails

    Automatic payments may look identical on your bank statement, but they can follow different routes. Knowing who initiates each payment helps you decide whom to contact if your bank fails.

    1. ACH Autopay: The Biller Collects the Payment

    A mortgage lender or utility provider can withdraw money from your checking account after you authorize recurring ACH debits. Because the biller initiates the withdrawal, contact it to update your payment account. Our ACH Push vs. ACH Pull guide explains the difference.

    2. Online Bill Pay: Your Bank Arranges the Payment

    When you schedule bills through online banking, your bank or its payment provider sends the money electronically or by check. Check the bank’s bill-pay service for scheduled transactions and follow its instructions before rescheduling. See Online Bill Pay vs. Automatic ACH.

    3. Recurring Debit-Card Charges: The Merchant Uses Your Card

    Subscriptions and memberships often charge a stored debit card. If the card stops working or its details change, the merchant may decline the charge. Check the card’s status before updating your subscription.

    Practical Tip: Check your recent statements and list each recurring payment by type. This makes it easier to find the correct contact and avoid overlooking a bill.

    What Actually Happens to Automatic Payments After a Bank Failure?

    When an FDIC-insured bank closes, the FDIC determines how its deposits will be handled. That decision affects whether existing automatic payment arrangements can continue.

    Scenario 1: Another Bank Takes Over

    The FDIC often arranges for another bank to assume the failed bank’s deposits. In many cases, ACH withdrawals, checks and online bill payments continue with little disruption. Existing routing and account numbers may remain valid during the transition.

    However, the acquiring bank may later change account details or payment services. Review its notices and confirm that essential payments remain active.

    Scenario 2: The FDIC Pays Depositors Directly

    If no bank assumes your deposit account and the FDIC pays insured deposits directly, the failed account is closed. Outstanding checks and payment requests presented after closure are returned unpaid. You will need to arrange payments from another account.

    A returned payment caused by the bank closing does not, by itself, damage your credit standing. Still, contact creditors promptly because an unpaid bill can lead to separate consequences.

    What Happens to Pending ACH Payments?

    A transaction labeled “scheduled” or “pending” is not proof that the biller received the money. Check your account records and ask the biller whether the payment settled before submitting another one.

    What to Do First: Read the FDIC failed-bank notice, confirm your account’s status and review bills due within the next few days. If a payment was returned, contact the biller. Our automatic bill payment troubleshooting guide explains common payment problems.

    Benefits and Drawbacks of FDIC Bank Resolution

    A bank failure does not always mean starting over with every bill. The FDIC’s resolution process can preserve familiar banking services, although some customers may need to make new payment arrangements.

    Benefits: What May Work in Your Favor

    • Deposit protection: Eligible funds remain insured within applicable FDIC limits.
    • Payment continuity: An acquiring bank may maintain existing automatic payment services.
    • Clear instructions: Official FDIC and acquiring-bank notices explain account transitions.

    Drawbacks: Where Problems Can Arise

    • Returned transactions: A direct FDIC deposit payoff can leave outstanding bills unpaid.
    • Payment updates: New account details may require changes with lenders and billers.
    • Possible penalties: Unpaid bills may lead to late fees or other consequences under the biller’s terms.

    Worth remembering: FDIC insurance protects qualifying deposits, not a promise that every automatic payment will arrive on time.

    ACH Autopay vs. Bank Bill Pay vs. Recurring Card Payments

    Each payment method has a different point of contact. This comparison shows where problems may arise and what to verify if your bank fails.

    Payment TypeInitiated ByPossible RiskWhat to Verify
    ACH AutopayBiller or lenderDebit returned if the account closes.Ask the biller whether the payment settled.
    Bank Bill PayBank, on your instructionsScheduled payment may be interrupted.Check bank records and payee receipt.
    Recurring Debit CardMerchant, with your authorizationCharge may fail if the card becomes inactive.Confirm card status and merchant billing details.

    Important: If another bank assumes your account, these payments may continue normally. Check the payment’s final status before paying again to avoid duplicate charges. For related payment arrangements, see Recurring Bank Transfers Explained.

    Costs, Missed Payments, Late Fees and Expert Tips

    A bank failure does not automatically trigger late fees. Problems arise when a scheduled payment fails and the bill remains unpaid. The costs depend on your agreement with the lender, landlord or service provider.

    Three Financial Risks to Watch

    • Late-payment charges: A creditor or biller may assess a fee after the applicable payment deadline or grace period.
    • Returned-payment fees: Some billers charge when an ACH debit or check is returned, depending on their terms and applicable law.
    • Credit-reporting risks: An unresolved late loan or credit-card payment may eventually be reported and affect your credit score.

    How to Reduce Potential Costs

    Contact billers before payments become overdue. Explain the bank closure, confirm whether the original payment cleared and ask about another payment method. If a fee appears, request a waiver and keep the response in writing.

    Expert Tip: Save the FDIC notice, account records and payment confirmations. A returned payment marked as caused by bank closure does not itself damage your credit standing, but the underlying bill still needs payment. If an inaccurate late payment appears on your credit report, dispute it with supporting evidence.

    Common Mistakes After a Bank Failure—and a Mortgage Payment Example

    A bank closure can create confusion, especially when several bills are scheduled. Avoid these mistakes before changing payment instructions.

    Four Mistakes to Avoid

    • Assuming autopay stopped: An acquiring bank may continue existing payments.
    • Paying twice: Check whether the original transaction settled before sending another payment.
    • Ignoring biller notices: Review emails and account alerts for returned payments.
    • Waiting until the deadline: Contact essential billers early if payment status is uncertain.

    Example: A $1,800 Mortgage Payment

    Imagine Sarah has a $1,800 mortgage payment scheduled for Monday. Her bank fails on Friday.

    If another bank assumes her account, the withdrawal may continue. If the FDIC instead pays depositors directly and closes the account, the payment request may be returned.

    Sarah’s next step: Contact her mortgage servicer, verify whether payment was received, and arrange another payment only if needed. She should save confirmation and ask about any deadline or fee concerns.

    Remember: A failed bank does not erase your mortgage obligation. The goal is to prevent both missed and duplicate payments.

    Who Should Act First After a Bank Failure?

    Prioritize bills by their due dates and the consequences of missing them—not simply by payment type. These groups often need attention first.

    Payments to Review First

    1. Mortgage and rent: Check upcoming housing payments and contact the lender or landlord if uncertain.
    2. Insurance and utilities: Confirm payments needed to maintain coverage or essential services.
    3. Loans and credit cards: Verify minimum payments and deadlines to reduce potential fees.
    4. Subscriptions: Review less urgent recurring charges after essential obligations.

    Priority rule: An overdue bill or imminent coverage lapse comes first, regardless of category. Confirm whether the original payment settled before sending another.

    Frequently Asked Questions About Automatic Payments After Bank Failure

    1. Do automatic payments stop when a bank fails?

    Not always. Payments may continue when another bank assumes your account. If the FDIC pays depositors directly and closes the account, new payment arrangements may be necessary.

    2. Will my mortgage autopay still work?

    Possibly. Contact your mortgage servicer to confirm whether the payment was received and whether your account details need updating.

    3. Does FDIC insurance cover missed automatic payments?

    No. FDIC insurance protects eligible deposits within applicable coverage limits. It does not guarantee that scheduled bills will be paid on time or reimburse ordinary late fees.

    4. Can ACH payments be returned after a bank closes?

    Yes. If the FDIC closes an account through a direct deposit payoff, ACH debits presented afterward may be returned unpaid.

    5. Should I immediately update all my autopay details?

    First review official FDIC or acquiring-bank instructions. Update payment details when necessary, prioritizing bills approaching their deadlines.

    6. Will a returned payment damage my credit score?

    A return caused by bank closure does not itself damage your credit standing. However, an unpaid debt that becomes delinquent may affect your credit.

    7. Can I ask for a late-fee waiver?

    Yes. Explain the bank failure, provide supporting records and request a waiver from the biller. Approval is not guaranteed.

    8. How do I avoid paying the same bill twice?

    Review your account records and confirm whether the biller received the original payment before sending a replacement.


    Final Verdict: What to Do If Your Bank Fails

    Your next step depends on how the FDIC resolves the failed bank. An acquiring bank may preserve existing payment arrangements, while a direct deposit payoff can leave you needing a replacement account.

    Check official notices, prioritize bills approaching their deadlines and confirm payment receipt with each biller. If something failed, arrange another payment promptly—but verify the original transaction first to avoid paying twice.

    Bottom Line: Deposit insurance and payment continuity are different protections. Learn how coverage works in our FDIC and NCUA Insurance Explained guide.

    Have a Money Question? Keep Exploring.

    When your bank changes unexpectedly, even a routine bill can become a concern. A little preparation makes the next steps easier: keep your payment records organized, know which bills are approaching and use official instructions before updating accounts.

    Want to understand your protections and payment options? Read our guides to FDIC and NCUA insurance and paying bills through your bank.

    📩 Get in Touch With FinanceInvestment

    Disclaimer: This content is for general educational purposes, not personalized financial or legal advice. Verify account-specific details with the FDIC, your bank and your billers.

  • ACH Push vs. ACH Pull: Key Differences Explained

    ACH Push vs. ACH Pull: Key Differences Explained

    ACH Push vs. ACH Pull: What’s the Difference?

    SR
    Subhash Rukade
    Founder · FinanceInvestment
    BANKING GUIDE
    Published
    November 5, 2026
    Last Updated
    November 5, 2026
    Reading Time
    10–12 minutes

    ACH Push vs. ACH Pull showing the difference between ACH credit and ACH debit payments

    ACH Push vs. ACH Pull: How These Bank Payments Differ

    Imagine paying your rent through your bank’s website or setting up a monthly gym membership. Both payments may use ACH, yet the way money leaves your account can be different. In one case, you instruct your bank to send a payment. In the other, a business you have authorized requests a payment from your account.

    That is the main difference between ACH Push vs. ACH Pull. An ACH push is generally initiated by the person or institution sending the money. An ACH pull is generally initiated by the recipient or its payment processor, which requests a debit from the payer’s account under an authorization. The ACH network can process both types of transactions.

    The distinction matters when you transfer money, pay a bill, or arrange a recurring withdrawal. Knowing who starts the payment can help you understand the setup, review the transaction, and decide which method fits your needs. Neither method should be treated as automatically instant or risk-free.

    If you’re comparing payment options beyond these two, our bank transfers and payments guide covers the broader picture.

    What You’ll Learn

    • What ACH push and ACH pull mean in everyday banking.
    • Who initiates each payment and how authorization works.
    • How the two methods compare for bills, transfers, and recurring payments.
    • What to check before choosing a payment method or approving a withdrawal.

    Quick Answer: ACH Push vs. ACH Pull

    An ACH push starts when you instruct your bank or payment service to send money. An ACH pull starts when a recipient or its payment provider requests a debit from your account under an authorization you have provided. Both use the ACH network, but the payment is initiated from a different side.

    Key Takeaways

    • Push: You initiate a payment through your bank or payment service.
    • Pull: A recipient requests a debit based on your payment authorization.
    • Push payments are common for bank transfers and payments you manually send.
    • Pull payments often handle authorized bill payments and recurring withdrawals.
    • Review the amount, recipient, and authorization before setting up a payment.
    • Timing, fees, and limits depend on the bank and transaction details.

    Bottom Line: ACH push puts you in charge of starting a payment. ACH pull can make authorized bills easier to manage. Either way, check the payment details and keep an eye on your account.

    Table of Contents

    ACH Push vs. ACH Pull at a Glance

    Quick Facts

    Payment network: Automated Clearing House (ACH)

    ACH Push: The sender initiates a payment.

    ACH Pull: A recipient or payment provider requests a debit under an authorization.

    Common uses: Account transfers, payroll, bill payments, and recurring withdrawals.

    Best for: Push payments can suit transfers you initiate yourself. Pull payments can be convenient for bills or recurring payments when you authorize a company to debit your account.

    FeatureACH PushACH Pull
    Who initiates?SenderRecipient or payment provider
    Typical exampleSending money to another accountPaying a bill from your bank account
    What to checkRecipient and payment amountAuthorization, amount, and payment date

    These are practical descriptions based on who initiates the payment. The exact process depends on your bank and the service you use.

    ACH Push vs. ACH Pull: A Beginner’s GuideACH Push vs. ACH Pull

    ACH stands for Automated Clearing House, a U.S. payment network used to move money electronically between bank accounts. When you transfer money or pay a bill from your checking account, ACH may be the network handling that payment.

    The simplest way to tell an ACH push from an ACH pull is to ask: Who starts the payment?

    What Is an ACH Push?

    An ACH push is initiated by the person or business sending money. You use your bank or payment service to instruct a transfer to another account. For example, you might move money from checking to savings or send funds to an account at another bank.

    You typically select the destination and enter the amount before submitting the transfer. Check the recipient’s account details and your bank’s transfer terms before confirming.

    What Is an ACH Pull?

    An ACH pull is initiated by the business or recipient collecting the payment. After you provide the required payment information and authorization, the company or its payment provider submits a debit request through ACH. Paying a utility bill directly from your checking account is a common example.

    Before authorizing a debit, review what you are agreeing to—including the amount or calculation method, payment schedule, and how to cancel or change the arrangement. The details depend on the biller and payment agreement.

    The key difference: With an ACH push, the sender instructs the payment. With an ACH pull, the recipient submits a debit request based on the payer’s authorization. Both use ACH, but the setup and payment experience can vary.

    How ACH Push and Pull Work

    ACH push and ACH pull payments use the same U.S. payment network. The difference is whether the transaction credits an account or collects money from it. In both cases, the Originator sends payment instructions through its bank, and the ACH Operator routes those instructions to the receiving bank.

    How an ACH Push Works

    1. The sender or business initiates an ACH credit, providing the recipient’s account details and payment amount.
    2. The sender’s bank, known as the originating bank, submits the payment instructions to an ACH Operator.
    3. The ACH Operator sorts and routes the instructions to the recipient’s bank.
    4. The recipient’s bank processes the entry: the sender’s account is debited and the recipient’s account is credited through the ACH settlement process.

    How an ACH Pull Works

    1. The payer authorizes a company to collect a payment, such as a utility bill or insurance premium.
    2. The company initiates an ACH debit and sends the payment instructions through its bank.
    3. The ACH Operator routes the debit instructions to the payer’s bank.
    4. The payer’s account is debited, and the collecting company’s account is credited through the ACH process.

    Timing matters: ACH is a batch-oriented network, but eligible payments can use Same Day ACH. Settlement and account posting depend on the payment’s processing schedule, eligibility, and financial institutions. A submitted payment is not necessarily available instantly.

    Benefits and Drawbacks of ACH Push vs. ACH Pull

    ACH push and pull payments can both simplify banking. Their practical differences come down to who initiates the transaction, how you manage it, and what you need to monitor.

    ACH Push: Benefits and Drawbacks

    Benefits

    • You initiate the payment and enter the recipient and amount.
    • Useful for account transfers and payments you prefer to submit yourself.

    Drawbacks

    • You may need to initiate each payment instead of relying on a scheduled debit.
    • Incorrect account details can lead to delays, returned payments, or funds sent to the wrong account.

    ACH Pull: Benefits and Drawbacks

    Benefits

    • Convenient for authorized one-time or recurring payments.
    • Can reduce the need to manually submit each bill payment.

    Drawbacks

    • A scheduled debit may occur when you are not actively reviewing your account.
    • Insufficient funds or an unexpected debit can result in a returned payment or possible bank fees.

    Bottom line: ACH push lets you initiate a payment yourself, while ACH pull can make authorized bill collection more convenient. Neither method removes the need to verify payment details, review account activity, and understand your bank’s processing and fee policies.

    Nacha: How ACH Payments Work and CFPB: ACH Transactions.

    ACH Push vs. ACH Pull: Side-by-Side Comparison

    ACH push and ACH pull describe payment flows based on who initiates the transaction. In common usage, a push generally sends an ACH credit, while a pull generally collects an ACH debit. Here is how they compare in everyday banking.

    FeatureACH PushACH Pull
    Common entryACH creditACH debit
    Who initiates?Sender instructs the paymentCompany or recipient submits a debit request under authorization
    Money movementSender’s account is debited; recipient’s account is creditedPayer’s account is debited; collecting company’s account is credited
    Typical useSending money to another accountPaying a bill from your bank account
    What to reviewRecipient, amount, and transfer termsAuthorization, amount, and debit schedule
    Main considerationYou submit the payment instructionYou monitor authorized debits and account activity

    Important: Push and pull are practical descriptions, not separate ACH networks. Processing time, account availability, transfer limits, and fees depend on the banks and payment service involved.

    ACH Push vs. ACH Pull: Costs, Risks and Expert Tips

    ACH payments can be convenient, but the total cost depends on your bank, payment provider, and account agreement. Many standard transfers may be free, while certain services or account types can involve fees.

    Costs and Risks to Watch

    • Transfer fees: Check whether your bank charges for external transfers, expedited services, or specific account features.
    • Overdraft or returned-payment fees: If funds are insufficient, a payment may be declined or returned. Any fee depends on your bank’s policies and account terms.
    • Incorrect account details: An incorrect routing or account number can cause a delay or payment error.
    • Unauthorized debits: An unfamiliar ACH withdrawal should be reviewed and reported to your bank promptly.

    Expert Tips Before Sending or Authorizing

    • Confirm the recipient’s bank details through a trusted source before sending money.
    • For ACH Pull, review the authorization, payment amount or calculation method, and debit schedule.
    • Keep enough funds available for expected payments and monitor your account activity.
    • Save payment confirmations and review your bank statement after the transaction.

    If you notice a debit you do not recognize, contact your bank or credit union as soon as possible. Ask how to report it, what documentation is needed, and whether any deadlines apply. Do not assume that every disputed payment follows the same process.

    Expert takeaway: Before using ACH, check the fee schedule, verify payment details, understand the authorization, and know how your bank handles returned or disputed transactions.

    CFPB: Overdraft Fees · Nacha: Consumer FAQs on ACH Payments.

    Common ACH Mistakes and a Real-Life Example

    ACH payments can be convenient, but a few common oversights may lead to payment errors, returned transactions, or confusion about when money will move.

    Mistakes to Avoid

    • Entering incorrect bank details when setting up a transfer.
    • Assuming the payment will post immediately after you submit it.
    • Agreeing to a recurring debit without reviewing its amount, schedule, or cancellation process.
    • Overlooking an unfamiliar withdrawal instead of contacting your bank to ask about it.

    Real-Life Example

    Imagine Alex wants to move $300 from checking to savings. Alex starts the transfer through the bank’s app, checks the destination account, and reviews the bank’s transfer details before submitting. Depending on the bank’s service, the transfer may use ACH or another payment method.

    Later, Alex authorizes a utility company to collect a monthly bill through ACH debit. The company submits the debit according to the payment arrangement, so Alex checks the bill amount, expected date, and available balance.

    In this example, Alex initiates the account transfer, while the utility company submits the authorized debit. The key difference is who starts each payment—not whether one is automatically faster or safer.

    Takeaway: Verify the payment details, understand the authorization, and review your account after transactions. If something looks unfamiliar, contact your bank promptly.

    Who Should Choose ACH Push or ACH Pull?

    Your choice depends on who you want to initiate the payment, how often you pay, and which options your bank or payment provider offers.

    ACH Push May Fit You If:

    • You prefer to start a payment or transfer yourself.
    • You want to select the recipient and amount before submitting.
    • You are making a one-time payment or an eligible bank-to-bank transfer.

    ACH Pull May Fit You If:

    • You want a company to collect an authorized bill payment.
    • You prefer scheduled payments instead of submitting each one manually.
    • You can review the authorization, debit date, and account activity.

    How to decide: Compare the payment options your bank or provider actually supports. Check processing time, fees, authorization terms, and how to review or report a transaction. Neither method is automatically faster, safer, or cheaper in every situation.

    Frequently Asked Questions

    1. What is the difference between ACH Push and ACH Pull?

    ACH Push commonly describes a payment initiated by the sender, usually an ACH credit. ACH Pull commonly describes a debit submitted by a company or recipient under the payer’s authorization.

    2. Is ACH Push the same as an ACH credit?

    ACH Push is a common way to describe an ACH credit. The sender initiates the payment, and the receiving account is credited through the ACH network.

    3. Is ACH Pull the same as an ACH debit?

    ACH Pull commonly refers to an ACH debit. The payer authorizes a company or recipient to collect a payment, and the debit is submitted according to the payment arrangement.

    4. Which is faster: ACH Push or ACH Pull?

    Neither is always faster. Timing depends on when the payment is submitted, processing schedules, eligibility, and the banks or providers involved. Some eligible transactions may be processed through Same Day ACH.

    5. Is ACH Push safer than ACH Pull?

    Neither method is automatically safer in every situation. Check recipient details before initiating a push payment, and review authorization terms and account activity when using pull payments.

    6. Can ACH Pull be used for recurring bills?

    Yes. Businesses may collect recurring payments through authorized ACH debits, including utility bills or subscriptions. Review the authorization, payment amount, and expected debit schedule.

    7. Can I stop or report an ACH Pull?

    Depending on the circumstances, you may be able to request a stop payment or report an unauthorized debit. These are different processes and may have specific requirements or deadlines. Contact your bank promptly for instructions.

    8. Do ACH Push and ACH Pull have different fees?

    Fees depend on the bank, account, and payment provider. Review the applicable fee schedule and transfer terms before sending or authorizing a payment.

    For consumer payment guidance, visit Nacha’s ACH Consumer FAQs. For a specific transaction, contact your bank.

    Final Verdict: ACH Push vs. ACH Pull

    The key difference between ACH Push vs. ACH Pull is who starts the payment. With a push payment, you initiate the transfer. With a pull payment, a company or recipient submits a debit under your authorization.

    For a payment you want to initiate yourself, push may be a practical fit. For an authorized bill or scheduled collection, pull may be more convenient. Processing time, fees, and available controls depend on your bank and payment provider, so neither method is automatically faster, cheaper, or safer.

    Bottom line: Choose based on your payment needs, verify the details, review any authorization, and monitor your account. For more payment basics, explore our Bank Transfers and Payments Guide.

    Keep Building Your Banking Knowledge

    Now that you understand ACH Push vs. ACH Pull, keep learning how bank transfers and payment methods work. FinanceInvestment shares practical personal finance guides to help you make informed banking decisions.

    Have a question or article suggestion? Contact FinanceInvestment.

    Explore the Bank Transfers Guide

  • Why Did My Automatic Bill Payment Fail? 9 Reasons

    Why Did My Automatic Bill Payment Fail? 9 Reasons

    Why Did My Automatic Bill Payment Fail? 9 Common Reasons and How to Fix Them

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    PUBLISHED
    November 01, 2026
    LAST UPDATED
    November 01, 2026
    READING TIME
    11 minutes

    why did my automatic bill payment fail

    Why Did My Automatic Bill Payment Fail?

    You scheduled your electricity, insurance, or credit card bill to be paid automatically. The due date arrives, but instead of a payment confirmation, you receive a failed-payment alert. If you’re asking, why did my automatic bill payment fail when everything seemed to be set up correctly, the problem could be with your bank account, payment details, debit card, or the billing company’s payment system.

    Insufficient funds are one possible explanation, but they are not the only one. An expired card, incorrect account information, a bank security block, or a processing delay can also interrupt a scheduled payment. The cause often depends on whether you authorized an ACH withdrawal, scheduled bill pay through your bank, or used a recurring card payment.

    We’ll help you identify where the payment went wrong, understand what to check first, and avoid unnecessary fees or duplicate payments. For more background, explore our complete guide to bank transfers and payments.

    What You’ll Learn

    • Nine common reasons automatic bill payments fail.
    • How ACH, bank bill pay, and recurring card payments differ.
    • What to check when a payment is declined, pending, or returned.
    • How to resolve a failed payment and reduce the risk of late fees.

    Quick Answer: Why Did Your Automatic Bill Payment Fail?

    Your automatic bill payment may have failed because of insufficient available funds, outdated bank details, an expired card, a bank security block, an account restriction, or a problem with the billing company’s payment system. Check your bank transaction history and the biller’s payment status to identify what happened. Before paying again, confirm that the original transaction is not still processing.

    Key Takeaways

    • A low available balance can cause an automatic withdrawal to be rejected, even when your account shows money.
    • An expired debit card or incorrect account information can interrupt scheduled payments.
    • ACH debits, bank bill pay, and recurring card charges have different failure points.
    • A pending transaction does not automatically mean the payment has failed.
    • Depending on the bank and biller’s policies, a failed payment may result in additional fees.
    • Checking the transaction status before retrying can help prevent duplicate payments.

    Bottom Line: A scheduled payment is not proof that your bill was paid. Confirm the transaction, identify the reason for the failure, and arrange payment before the due date or contact the biller if the deadline has passed.

    Automatic Bill Payment: Key Facts at a Glance

    Quick overview: An automatic payment can be interrupted by a problem with your bank account, payment method, payment network, or biller’s system. Identifying where the transaction stopped is the first step toward fixing it.

    What to CheckWhy It Matters
    Available balancePending transactions or account holds may leave less money available than your displayed balance suggests.
    Bank account detailsIncorrect or outdated account information can prevent an ACH withdrawal from reaching the right account.
    Debit or credit cardAn expired, replaced, or blocked card may cause a recurring card charge to be declined.
    Transaction statusA pending transaction may still be processing, while a returned or declined payment needs further attention.
    Bank and biller alertsNotifications may identify a security block, payment rejection, or other issue requiring action.

    Best for: Families managing household bills, retirees paying recurring expenses from a fixed income, and anyone handling insurance, loan, utility, or credit card payments automatically.

    Remember: A delayed payment is not always a failed payment. Check the bank’s transaction details and the biller’s records before attempting another payment.

    A Beginner’s Guide to Failed Automatic Bill Paymentswhy did my automatic bill payment fail

    When an automatic payment fails, start by identifying who was supposed to send the money. A payment arranged through your bank works differently from a withdrawal initiated by a billing company. Knowing the difference helps you find the right place to investigate.

    1. Automatic ACH Debit

    An ACH debit allows a company, such as an insurance provider or utility company, to request money directly from your checking account. The transaction may be returned because of insufficient funds, a closed account, incorrect account information, or an authorization issue. Learn more in our guide to how ACH transfers work.

    2. Bank-Scheduled Bill Pay

    With this option, you ask your bank or credit union to pay a company on your behalf. Depending on the bank and recipient, it may send an electronic payment or mail a paper check. Incorrect payee details, an unsuitable delivery date, insufficient funds, or a delayed check can prevent the bill from being paid on time.

    3. Recurring Debit or Credit Card Payment

    Here, the billing company charges the card saved to your account. A charge may be declined if the card expires, is replaced and its details are not updated, has insufficient available credit, or is blocked by the card issuer’s security checks.

    Practical tip: Check the payment method and transaction description before contacting support. If your bank initiated the payment, start with the bank. If the company charged your stored card or requested an ACH debit, contact the biller as well.

    How Automatic Bill Payment Processing Works

    An automatic bill payment passes through several steps before the biller receives the money. The exact process depends on whether the payment is initiated by the billing company, your bank, or your card issuer.

    Step 1: You Authorize or Schedule the Payment

    You provide your bank account details for an ACH debit, schedule a payment through your bank’s bill-pay service, or save a debit or credit card with the billing company for recurring charges.

    Step 2: The Payment Request Is Sent

    For an ACH debit, the biller submits a withdrawal request through its financial institution. With bank bill pay, your bank arranges delivery to the payee, electronically or by paper check. For a recurring card charge, the merchant sends a transaction request through the card network to the card issuer.

    Step 3: The Financial Institution Processes It

    The bank or card issuer checks the relevant account or card details and applies its available-funds, authorization, and security controls. An ACH request may be rejected or later returned. A card transaction may be declined during authorization. A bank bill-pay instruction may also be delayed or rejected before delivery.

    Step 4: Confirm the Payment Result

    Check your bank activity and the biller’s records to confirm whether the payment was completed. ACH transactions follow processing schedules, so weekends and federal holidays can affect timing. A card authorization may appear before the final transaction is posted.

    Remember: Scheduling a payment, receiving an authorization, and completing a payment are not necessarily the same event. Always verify the final status before assuming your bill has been paid.

    Benefits and Drawbacks of Automatic Bill Payments

    Automatic bill payments can simplify monthly finances, especially when you have several recurring expenses. However, convenience does not guarantee successful payment. Your account balance, payment details, and billing activity still need occasional attention.

    Benefits of Automatic Payments

    • Fewer manual reminders: Scheduled payments reduce the need to remember every monthly due date.
    • More consistent bill handling: Payments can arrive on time when the account is funded and the payment details are valid.
    • Simpler budgeting: Knowing recurring payment dates helps you plan upcoming household expenses.

    Drawbacks to Watch For

    • Payment interruptions: Insufficient available funds, expired cards, or incorrect details can cause a scheduled payment to fail.
    • Unexpected withdrawals: You may overlook a changed bill amount or a recurring charge you did not expect.
    • Extra costs: A failed payment may lead to returned-payment charges, late fees, or service interruption, depending on the account and provider policies.

    A sensible balance: Use automation to handle routine bills, but review upcoming withdrawals, maintain enough available funds, and pay attention to bank and biller notifications. A quick account check can help you catch a problem before it affects your next payment.

    ACH vs. Bank Bill Pay vs. Recurring Card Payment Failures

    The same bill can fail for different reasons depending on how you pay it. The key difference is who initiates the transaction and which financial institution processes it.

    Payment MethodWhy It May FailFirst Check
    ACH DebitInsufficient funds, closed account, invalid account details, or an ACH authorization problem.Available balance, bank transaction history, and the return or rejection notice.
    Bank Bill PayIncorrect payee details, scheduling problems, insufficient funds, or delayed paper-check delivery.Bank payment history, payee information, and delivery confirmation.
    Recurring Card PaymentExpired or replaced card, insufficient available credit, spending restrictions, or a security decline.Card status, issuer notification, and billing account details.

    Where should you start? For an ACH debit, check with your bank and the company requesting the withdrawal. For bank bill pay, ask your bank whether the payment was sent and how it was delivered. For a recurring card charge, contact the card issuer about the decline and ask the billing company to verify its payment details.

    Automatic Payment Failure: Fees, Risks and Expert Tips

    A failed automatic payment can create costs beyond the original bill. What you may owe depends on your bank’s account terms, the billing company’s policy, and whether the unpaid bill is for a utility, credit card, loan, or another service.

    Possible Fees and Financial Risks

    • NSF or returned-payment fee: Your bank may charge a fee if it returns a payment because your account does not have enough available funds.
    • Overdraft fee: If your bank pays a transaction that exceeds your available balance, an overdraft fee may apply under your account agreement.
    • Late-payment fee: The biller may charge a fee if the payment remains unpaid after the due date.
    • Service or credit consequences: An unpaid bill could lead to service restrictions. A late credit card or loan payment may also affect your credit if it is reported to the credit bureaus.

    Some banks and billers may charge separate fees, but this is not automatic. Review your account agreement and billing terms. The CFPB’s guide to automatic bank payments explains how these withdrawals work and what to watch for.

    Important: Before paying manually, confirm whether the original transaction was declined, returned, or is still pending. Retrying too soon could result in duplicate payments if the first transaction later completes.

    Expert Tips to Prevent Repeat Failures

    • Keep enough available money for scheduled bills and pending transactions.
    • Update expired cards and changed bank account details.
    • Enable bank transaction alerts and review unusual activity.
    • Contact the biller promptly if a payment fails near its due date.

    Common Automatic Payment Mistakes and a Real-Life Example

    A scheduled payment can still go wrong when account activity is overlooked. These common mistakes can turn a simple payment issue into an overdue bill:

    • Assuming a scheduled payment has cleared without checking its status.
    • Looking only at the displayed balance instead of accounting for pending transactions and available funds.
    • Forgetting to update an expired or replaced payment card.
    • Ignoring a bank alert or a returned-payment notification.
    • Making another payment before confirming whether the original transaction is still processing.

    Illustrative Example: A Family’s Electricity Bill

    Imagine a family in Ohio schedules its $180 electricity bill through ACH debit. Several card purchases are pending, so the available balance is lower than the family expected. When the utility company’s withdrawal is processed, the bank returns it because sufficient funds are unavailable.

    The family overlooks the bank notification and assumes the bill was paid. A few days later, the utility company sends an overdue notice. The family must now confirm the returned payment, check for applicable charges, and arrange payment directly with the provider.

    What this example teaches: Check available funds before scheduled withdrawals and respond promptly to failed-payment alerts. Always verify the original transaction’s status before trying again.

    Who Should Pay Extra Attention to Automatic Payment Failures?

    Anyone using autopay can experience a failed transaction. However, a missed withdrawal can create greater pressure for households with tight budgets, multiple recurring bills, or income that does not arrive on a predictable schedule.

    Families Managing Multiple Household Bills

    Several utility, insurance, loan, and subscription payments may fall within the same week. Track their due dates and make sure enough money is available for the combined withdrawals.

    Retirees Living on a Fixed Income

    When retirement income arrives on a set schedule, an unexpected expense or delayed deposit can affect money reserved for essential bills. Keep a reasonable cash buffer where possible and monitor important payment dates.

    Beginners and New Bank Account Holders

    Entering an incorrect routing number or account number can disrupt an ACH payment. Verify both details with your bank before giving them to a billing company.

    Freelancers and People With Irregular Income

    Income may arrive on different dates each month, while bills follow fixed schedules. Where the provider allows it, choose payment dates that better match your expected cash flow.

    A useful habit: Review upcoming withdrawals, available funds, and payment alerts before major bill dates. This small routine can help you catch problems while there is still time to contact the bank or biller.

    Frequently Asked Questions About Failed Automatic Bill Payments

    1. Why did my automatic bill payment fail even though I had money?

    Your available balance may have been lower than your displayed balance because of pending transactions, account holds, or other withdrawals. A bank security block or incorrect payment details could also cause the transaction to fail.

    2. Will a failed automatic payment retry automatically?

    Not necessarily. Retry policies depend on the billing company, payment method, and reason for failure. Contact the biller to find out whether another attempt is scheduled.

    3. Can a bank reject an ACH payment?

    Yes. An ACH debit may be returned because of insufficient funds, a closed account, invalid account information, or certain authorization problems.

    4. Will I pay a fee if autopay fails?

    Possibly. Your bank or biller may charge an NSF, returned-payment, or late fee, depending on the account agreement and billing policy. Some failed payments do not result in a fee.

    5. Can a failed automatic payment affect my credit score?

    A failed transaction does not automatically lower your credit score. However, if an unpaid credit card or loan payment becomes seriously overdue and the creditor reports it to the credit bureaus, your credit history may be affected.

    6. How long does a failed ACH payment take to return?

    There is no single timeline for every ACH return. Timing depends on the return reason and processing schedule. Ask your bank or biller for the specific transaction status and expected update.

    7. Should I pay the bill manually after autopay fails?

    First confirm that the original transaction was declined or returned rather than still pending. Then ask the biller for the outstanding balance and arrange another payment if needed.

    8. What should I do if my bank blocks an automatic payment?

    Contact your bank through its official phone number or secure banking app. Ask why the transaction was blocked, complete any required verification, and confirm with the biller how to pay the outstanding bill.

    Final Verdict: What to Do When an Automatic Bill Payment Fails

    An automatic payment failure is a problem worth checking promptly, but it does not always mean your bank account has an issue. The cause could be insufficient available funds, outdated payment details, a card decline, or a processing problem.

    Start by checking your bank transaction history and the biller’s records. Confirm whether the payment was declined, returned, or is still pending. Once you know what happened, correct the issue, arrange payment for any outstanding balance, and get confirmation from the biller.

    Explore more banking guidance: Visit our Bank Transfers and Payments Guide to understand ACH transfers, payment delays, and common banking problems in greater detail.

    Stay Informed. Make Smarter Financial Decisions.

    Explore FinanceInvestment for practical banking guides, personal finance insights, and helpful updates to manage your money with greater confidence.

  • How to Stop an Automatic Bank Payment: Step-by-Step Guide

    How to Stop an Automatic Bank Payment: Step-by-Step Guide

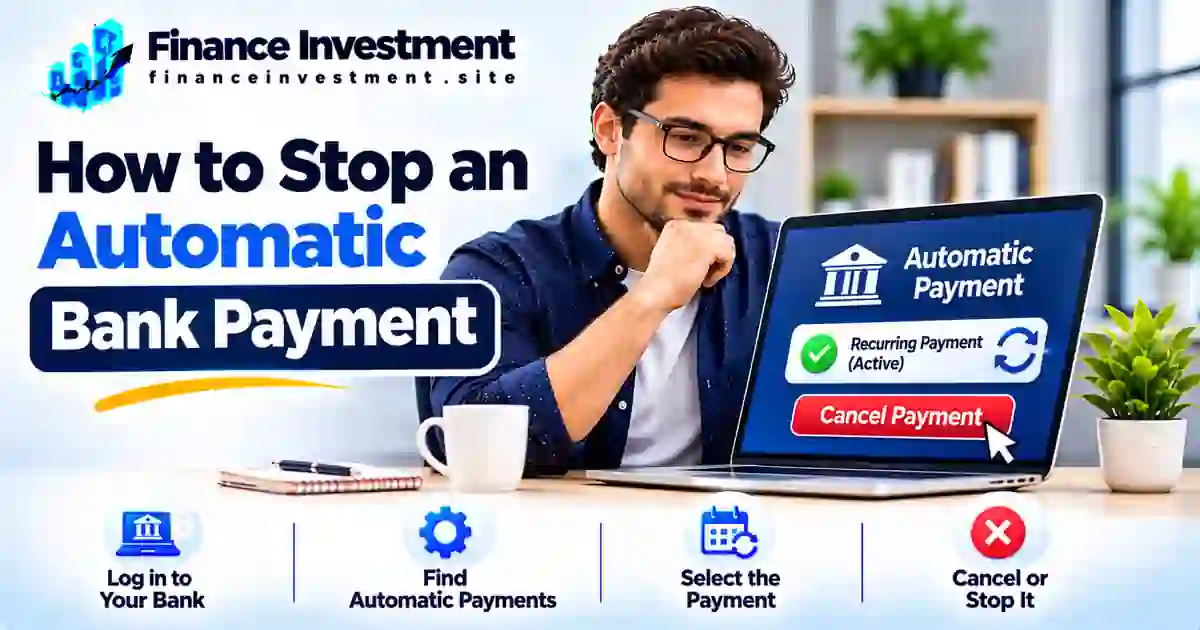
    How to Stop an Automatic Bank Payment: A Step-by-Step Guide

    SR
    Subhash Rukade
    Founder, FinanceInvestment

    Published: November 01, 2026

    Updated: November 01, 2026

    Reading Time: 10 minutes


    how to stop an automatic bank payment

    How to Stop an Automatic Bank Payment Without Creating Another Problem

    A subscription you no longer use, a gym membership you cancelled, or a bill you want to pay manually can keep triggering withdrawals from your bank account. If you’re wondering how to stop an automatic bank payment, start by finding out how the payment was authorized and who is collecting it.

    The right cancellation method depends on the payment type. A payment scheduled through your bank may need to be cancelled with the bank. An automatic ACH debit may require you to revoke the company’s authorization and notify your bank. A recurring debit-card charge follows a different process.

    Act promptly, keep written proof of your request, and check whether another payment is already being processed. Most importantly, stopping a withdrawal does not automatically cancel the subscription, loan, or service agreement behind it. Our complete guide to bank transfers and payments explains the wider payment landscape.

    What You’ll Learn

    • How to identify the type of recurring payment.
    • How to cancel a payment with the company or your bank.
    • When to request a stop-payment order.
    • What to do if a withdrawal continues after authorization is revoked.
    • How to protect your account without overlooking an unpaid bill.

    Quick Answer: How Do You Stop an Automatic Bank Payment?

    Quick answer: First, identify how the payment is being collected. Cancel a bank-scheduled payment through your bank, contact the company to revoke authorization for recurring ACH debits, or follow the card issuer’s process for recurring card charges. If needed, ask your bank about a stop-payment order and applicable deadlines. Keep written proof and monitor your account for further withdrawals.

    Key Takeaways

    • Identify whether the payment is bank-scheduled, an ACH debit, or a recurring card charge.
    • Contact the company to cancel or revoke recurring payment authorization.
    • Ask your bank about stop-payment options, notice requirements, and deadlines.
    • Save confirmation numbers, emails, and cancellation records.
    • Report unauthorized withdrawals to your financial institution promptly.
    • Remember that stopping a withdrawal does not automatically cancel the underlying bill, loan, or service agreement.

    Bottom Line: Use the cancellation process that matches your payment type. Contact the responsible company or bank in time, keep proof of your request, and verify that future withdrawals have stopped.

    Automatic Bank Payments: Quick Facts at a Glance

    The right cancellation method depends on how the payment is set up. Identify the payment type before contacting your bank or the company.

    Start Here

    Identify the payment method

    ACH Payments

    Revoke authorization with the biller

    Bank Bill Pay

    Cancel through your bank

    Important Reminder

    Stopping payment does not cancel the underlying bill

    Which Payment Are You Trying to Stop?

    Payment TypeWhere to StartKey Action
    Bank-scheduled bill payYour bank or credit unionCancel the scheduled payment before its cutoff.
    Automatic ACH debitCompany or biller, then your bank if neededRevoke authorization and ask your bank about stopping future withdrawals.
    Recurring card paymentMerchant and card issuerCancel the recurring billing arrangement and ask your issuer about available protections.

    Important: A payment already processing may not be cancellable. Contact your bank promptly, keep written confirmation, and continue checking your account. You may still owe the bill even after automatic withdrawals stop.

    A Beginner’s Guide to Stopping Automatic Bank Paymentshow to stop an automatic bank payment

    Before you stop an automatic bank payment, identify how the money is being withdrawn. A payment scheduled through your bank works differently from a company-initiated ACH debit or a recurring debit-card charge. Choosing the correct cancellation method can help prevent another unwanted withdrawal.

    1. Bank-Scheduled Bill Payments

    With online bill pay, you ask your bank or credit union to send money to a company or individual on a specific date. You usually manage these payments through your banking app or website. To cancel one, find the scheduled transaction and check whether it is still eligible for cancellation. Once processing begins, your bank may not be able to stop it.

    2. Automatic ACH Debits

    An ACH debit occurs when a company initiates an electronic withdrawal from your bank account under an authorization you provided. Utility bills, insurance premiums, and loan payments commonly use this method. To stop future withdrawals, contact the company to revoke your authorization. Also notify your bank and ask about a stop-payment order if another withdrawal is scheduled. Read our guide on how ACH transfers work to understand the process.

    3. Recurring Debit-Card Payments

    Streaming services, memberships, and other subscriptions may charge your debit card automatically. Start by cancelling the recurring billing arrangement with the merchant and keeping its confirmation. If charges continue or you cannot resolve the issue, contact your card issuer about available options for blocking or disputing future charges.

    Beginner Tip: Check your bank statement for the payee name, transaction description, amount, and date. These details can help you identify the payment type and explain exactly which withdrawal you want to stop.

    How to Stop an Automatic Bank Payment: Step by Step

    After identifying the payment method, follow these steps to request cancellation, protect your account, and avoid confusion about upcoming withdrawals.

    1

    Identify the Automatic Payment

    Open your bank statement and note the payee name, transaction amount, date, and description. Determine whether the withdrawal is bank-scheduled bill pay, an ACH debit, or a recurring debit-card charge.

    2

    Check the Next Withdrawal Date

    Review the next scheduled payment and contact the responsible provider promptly. Ask whether the transaction is still scheduled, pending, or already being processed. Cancellation options may depend on its status and the provider’s cutoff time.

    3

    Cancel the Recurring Authorization

    For an ACH debit, contact the company and clearly revoke permission for future withdrawals. For a recurring debit-card charge, cancel the merchant’s recurring billing arrangement. Keep written confirmation, an email, or a cancellation reference number.

    4

    Request the Appropriate Action From Your Bank

    For an ACH withdrawal, tell your bank about the revoked authorization and ask whether a stop-payment order is appropriate. For bank-scheduled bill pay, request cancellation through your bank’s app, website, or customer service before its cutoff. Provide the payee, amount, and expected payment date.

    5

    Get Confirmation and Monitor Your Account

    Confirm which future payments have been stopped and whether any pending transaction can still be processed. Save the bank’s confirmation and review your account around the expected withdrawal date. If an unauthorized or incorrect payment occurs, contact your bank promptly.

    Important: Cancelling an automatic payment does not cancel the underlying subscription, loan, insurance policy, or utility agreement. Arrange another payment method for any amount you still owe to avoid late fees or service interruptions.

    Benefits and Drawbacks of Stopping Automatic Payments

    Stopping an automatic payment can give you greater control over your money, especially when you no longer need a service or want to prevent an unwanted withdrawal. However, cancelling autopay without arranging another payment method can create avoidable financial problems.

    Benefits

    • Helps prevent future unwanted withdrawals after cancellation is properly completed.
    • Gives you more control over when money leaves your account.
    • Can reduce repeated charges for services you have cancelled.
    • Allows closer monitoring of payments after identifying suspicious or unauthorized activity.

    Drawbacks

    • You may forget to make a payment manually after cancelling autopay.
    • Missed due dates can lead to late fees or service interruptions.
    • Missed loan or credit-card payments may be reported to credit bureaus and affect your credit history.
    • Your bank may charge a stop-payment fee depending on its account terms and policies.

    Expert Tip: Before stopping autopay for a loan, insurance premium, utility bill, or credit card, arrange another payment method and confirm the next due date. Remember, cancelling the automatic withdrawal does not cancel the bill, debt, or contractual obligation.

    Bank Bill Pay vs. ACH Debit vs. Recurring Card Payments

    Automatic payments may look similar on your bank statement, but the payment process and cancellation method can be different. The key is identifying who initiates the transaction and which account or card is charged.

    FeatureBank Bill PayACH DebitRecurring Card Payment
    Who initiates it?Your bank or credit unionCompany or billerMerchant through card network
    Payment sourceBank accountBank accountDebit or credit card
    Where to start?Your bankBiller, then your bank when appropriateMerchant, then card issuer if needed
    How to stop itCancel the scheduled payment before the bank’s cutoff.Revoke the company’s ACH authorization and ask your bank about stop-payment options.Cancel recurring billing and contact the card issuer if charges continue.
    Important cautionA payment already sent or processed may not be cancellable.Stopping a withdrawal does not automatically cancel the bill or contract.Replacing a card may not always stop recurring billing arrangements.

    Which method should you use? For bank-scheduled bill pay, contact your bank. For ACH withdrawals, revoke authorization with the company and notify your bank when appropriate. For recurring card charges, cancel with the merchant and contact your card issuer if the problem continues.

    Cancellation Costs, Risks and Expert Tips

    Before stopping an automatic payment, understand the applicable cancellation rules, possible bank fees, and timing requirements. Your rights can depend on whether the withdrawal is a qualifying ACH payment, bank-scheduled bill pay, or recurring card charge.

    Understand the Three-Business-Day Rule

    Under Regulation E, you can stop a qualifying preauthorized electronic fund transfer by notifying your bank orally or in writing at least three business days before its scheduled date. If you make an oral request, your bank may require written confirmation within 14 days. It must explain this requirement and provide submission instructions when you make the request.

    Know Your ACH Authorization Rights

    You can revoke authorization for future ACH withdrawals. Notify your bank that the authorization is no longer valid and provide written evidence if requested. Under Regulation E, the bank must block future payments covered by that revoked authorization; it cannot simply wait for the company to complete its own cancellation process.

    Check Fees and Avoid Payment Problems

    Stop-payment fees, renewal periods, and procedures vary by financial institution and account agreement. Before cancelling autopay for a loan, insurance premium, or utility bill, arrange another payment method so you do not miss the due date.

    Expert Tips

    • Contact your bank as early as possible.
    • Give the bank the payee name and scheduled withdrawal details.
    • Keep written proof of authorization revocation and stop-payment requests.
    • Monitor your account and report unauthorized transactions promptly.

    Official guidance: Read the CFPB’s Regulation E, Section 1005.10 for the federal rules on preauthorized transfers and stop-payment rights.

    Common Mistakes When Stopping Automatic Bank Payments

    Stopping an automatic payment involves more than clicking a cancellation button. Overlooking the following details can lead to another withdrawal, an unpaid bill, or unnecessary fees.

    • Deleting autopay instead of revoking authorization: Removing a scheduled payment from your banking app may not cancel a company’s ACH authorization.
    • Contacting only one party: Some situations require notifying both the biller and your bank.
    • Waiting until payment day: Late requests may arrive after the transaction has entered processing.
    • Ignoring confirmation: Without written proof, it can be harder to establish when you requested cancellation.
    • Forgetting the outstanding bill: Stopping autopay does not remove a remaining balance or contractual payment obligation.

    Real-Life Example: A Cancelled Gym Membership

    Consider a customer who cancels a gym membership but does not revoke the ACH authorization used for monthly withdrawals. Depending on the payment schedule and processing status, another debit may still be initiated. The customer should check the membership agreement, request written confirmation of cancellation, revoke the payment authorization, and notify the bank if another withdrawal needs to be stopped.

    Key Lesson: Cancelling a membership, revoking payment authorization, and settling any remaining contractual balance are three separate matters. Complete each one to avoid future billing disputes.

    When Should You Contact Your Bank or the Biller?

    The right contact depends on how the payment is set up and why you want to stop it. Use these situations to decide where to begin.

    Bank-scheduled bill payment: Contact your bank or credit union to cancel the scheduled payment. Ask whether it has already entered processing and whether cancellation is still possible.

    Automatic ACH withdrawal: Contact the company to revoke its authorization. Separately notify your bank if you need to stop a future debit or place a stop-payment order.

    Recurring debit or credit card charge: Contact the merchant to cancel recurring billing. If charges continue or a transaction is unauthorized, contact your card issuer about blocking or disputing options.

    Unknown or unauthorized withdrawal: Contact your bank immediately to report the transaction, ask about securing your account, and understand the applicable error-resolution process. Do not wait for the merchant to respond first.

    Important: A pending or completed transaction may not be cancellable through an ordinary stop-payment request. Ask your bank what options remain. A completed unauthorized or incorrect transaction may need to be reported and disputed rather than cancelled.

    Frequently Asked Questions About Stopping Automatic Bank Payments

    1. Can I stop an automatic bank payment online?

    Often, yes. Many banks allow eligible scheduled bill payments to be cancelled through online banking or a mobile app. For ACH debits or recurring card charges, you may also need to contact the company or card issuer.

    2. How do I stop an automatic ACH payment?

    Revoke authorization with the company and notify your bank that future withdrawals are no longer authorized. Ask the bank about a stop-payment order if another debit is scheduled.

    3. Do I need to contact my bank or the company?

    It depends on the payment method. Cancel bank-scheduled bill pay through your bank. For ACH debits, contact the company to revoke authorization and notify your bank. For recurring card charges, contact the merchant and your card issuer when necessary.

    4. How much notice does a bank need to stop an automatic payment?

    For a qualifying preauthorized electronic fund transfer, Regulation E generally requires notice at least three business days before the scheduled transfer. Other payment methods may have different cancellation deadlines.

    5. Can my bank stop a payment that has already been processed?

    A completed payment generally cannot be cancelled through a standard stop-payment request. Contact your bank promptly to ask about recovery or dispute options, particularly if the transaction was unauthorized or incorrect.

    6. Does cancelling autopay cancel my subscription or loan?

    No. Stopping an automatic withdrawal does not automatically end a subscription, loan, or service agreement. Follow the provider’s cancellation terms and arrange payment of any remaining balance.

    7. What if a company keeps charging after I cancel?

    Keep your cancellation confirmation and contact the company in writing. Notify your bank or card issuer promptly, explain the continued charges, and ask how to stop future payments and dispute any eligible transactions.

    8. Can I stop recurring debit-card payments through my bank?

    Contact the merchant to cancel recurring billing. If an unauthorized charge occurs or billing continues after cancellation, contact your card issuer promptly about available blocking and dispute options.

    Official guidance: Read the CFPB’s Regulation E, Section 1005.10 for federal rules on preauthorized electronic fund transfers and stop-payment rights.


    Final Verdict: Stop Automatic Payments Without Missing Important Bills

    Stopping an automatic bank payment starts with identifying how the money is being withdrawn. Cancel bank-scheduled payments through your bank, revoke ACH authorization with the company and notify your bank when necessary, or cancel recurring card billing with the merchant.

    Keep written confirmation, check your account for further withdrawals, and arrange another payment method for any outstanding balance. Remember, stopping autopay does not cancel a subscription, loan, or other financial obligation.

    Explore the Complete Guide

    Learn how ACH transfers, bank payments, and other money-transfer methods work in the United States.

    Read the Bank Transfers & Payments Guide →

    FinanceInvestment

    Take Control of Your Banking Decisions

    Explore practical banking guides, understand payment options, and make more confident financial decisions with clear, helpful information.

    FinanceInvestment — Practical financial education for everyday decisions.