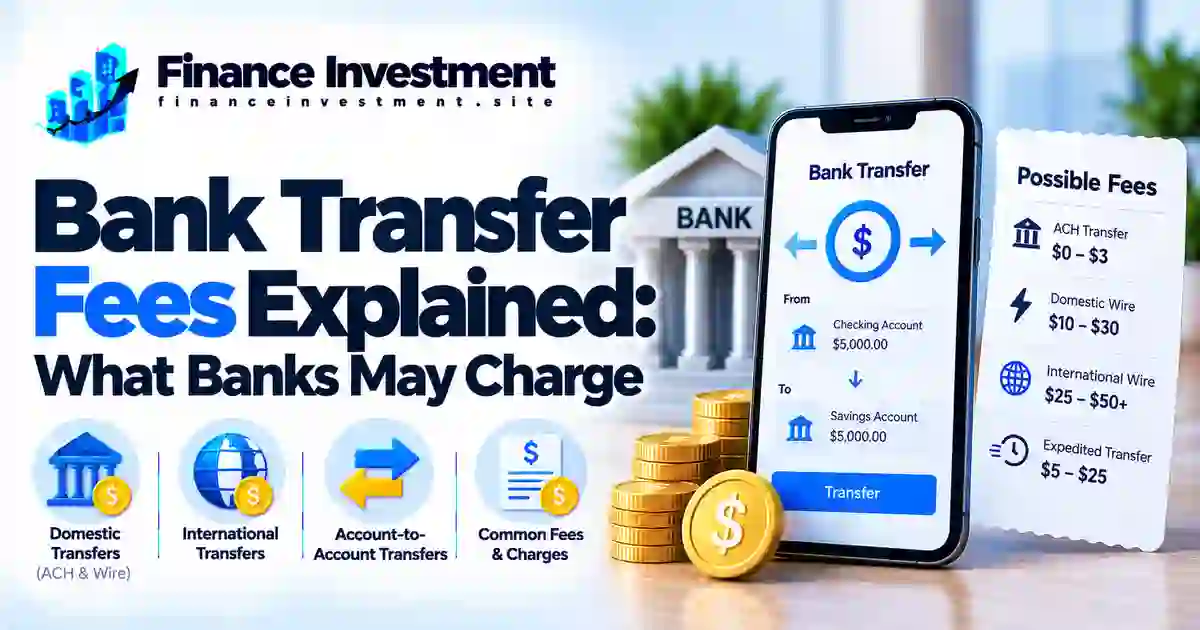
Bank Transfer Fees Explained: What Banks May Charge
Bank Transfer Fees: Know What You Could Pay Before Sending Money 
Moving money between bank accounts should be straightforward, but the cost can depend on how you send it. A standard ACH transfer between linked accounts may be free, while a domestic wire can carry a sending or receiving fee. International transfers may cost more if your bank, an intermediary bank, or the recipient’s bank deducts a charge. Some institutions also offer expedited options for an additional fee.
That doesn’t mean you need to pay every time you move money. Choosing the right transfer method—and checking your bank’s current fee schedule before confirming a payment—can help you avoid unnecessary charges. This guide explains bank transfer fees in the United States in 2026, what different fees mean, and how to compare your options. For a wider overview of payment methods, see our complete guide to bank transfers and payments.
What You’ll Learn
- When ACH transfers are typically free and when charges may apply.
- How incoming, outgoing, domestic, and international wire fees differ.
- How expedited services and intermediary banks can affect the total cost.
- How to compare transfer methods and avoid fees where possible.
Quick Answer: What Do Banks Charge for Transfers?
Bank transfer fees depend on your bank, account, transfer method, and destination. Many standard ACH transfers between linked accounts cost nothing, while others may carry a fee. Domestic wires can involve separate sending and receiving charges. International wires may also include intermediary-bank fees and currency-conversion costs. There is no single price that applies to every bank, so check your account’s current fee schedule and review any charges shown before confirming the transfer.
Key Takeaways
- ACH transfers: Often free for routine linked-account transfers, although some banks charge for certain transfer types or expedited service.
- Wire transfers: May involve outgoing, incoming, or separate international transfer fees.
- International payments: Intermediary-bank deductions and exchange-rate markups can raise the total cost.
- Speed matters: Faster delivery options may cost more than standard transfers.
- Check before sending: Review your bank’s fee schedule, delivery estimate, and any displayed charges.
The Bottom Line
For everyday transfers, compare a standard ACH transfer with other available options before paying for a wire. If a wire is necessary, confirm the sending fee and ask whether the recipient or an intermediary bank may deduct additional charges. The best choice balances total cost, delivery time, and your payment needs.
Table of Contents
Bank Transfer Fees at a Glance
QUICK TAKE: Many standard ACH transfers between linked accounts are free, but certain transfer services may carry charges. Wire transfers can involve sending and receiving fees, while international payments may include intermediary-bank deductions and currency-conversion costs.
Best for: Consider ACH for routine transfers when its delivery time works for you. Consider a wire when the recipient requires it or the payment’s timing and circumstances justify the potential cost.
| Transfer method | Possible fees | Common use |
|---|---|---|
| Standard ACH | Often free; some banks charge for certain services | Routine transfers between bank accounts |
| Domestic wire | Outgoing and/or incoming wire fees may apply | Payments where wire delivery is required |
| International wire | Wire fees, intermediary deductions, and possible exchange-rate markup | Cross-border payments |
| Expedited transfer | An additional fee may apply, depending on the provider | When a faster delivery option is available and needed |
These are general fee patterns, not guaranteed prices. Charges depend on your financial institution, account terms, transfer method, and destination. Check the current fee schedule and the final payment details before confirming a transfer.
Understanding Bank Transfer Fees 
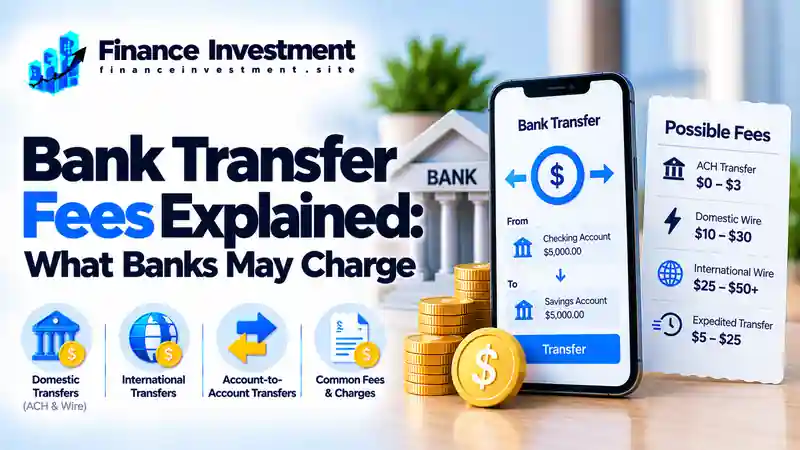
A bank transfer fee is a charge a bank, credit union, or payment provider may apply when money moves between accounts. The cost depends on the transfer method, your account agreement, the destination, and any optional services you select. Some transfers cost nothing, while others may involve one or more fees.
Why Do Banks Charge Transfer Fees?
Financial institutions set fees for certain services, including sending or receiving wire transfers, handling some international payments, and offering expedited processing. Many standard ACH transfers between linked accounts are free, but charges can apply to particular account types or transfer services. A bank’s fee schedule explains which charges apply to your account.
Who May Deduct a Fee?
For a domestic transfer, the sending or receiving institution may charge a fee, depending on the service and account terms. International wires can be more complicated: the sending bank, intermediary bank, or recipient’s bank may deduct charges. If currency conversion is involved, the exchange rate may also include a markup, affecting how much the recipient receives.
Beginner tip: Before confirming a transfer, check the applicable fees, estimated delivery time, exchange rate when relevant, and the expected amount the recipient will receive. For wires, ask whether additional bank charges may be deducted along the way.
How Bank Transfer Fees Work
The cost of sending money depends on the transfer method, your account terms, and whether other financial institutions handle the payment. Follow these four steps to understand the potential charges before you send.
1. Choose the Transfer Method
Standard ACH transfers between linked accounts are often free, although some banks charge for particular services. Domestic and international wires may carry sending fees, and expedited options may cost extra.
2. Identify Who May Charge You
Your sending bank may charge a transfer fee, and the receiving bank may apply its own fee under its account terms. International wires can also pass through intermediary banks that may deduct charges.
3. Calculate the Overall Cost
Do not look only at the advertised transfer fee. For international payments, compare the exchange rate and any conversion markup, along with disclosed charges and the estimated amount the recipient will receive. Some intermediary deductions may not be known in advance.
4. Review Before Authorizing
Check the fee disclosure, delivery estimate, recipient details, and applicable account terms before confirming the payment. Save the confirmation for your records.
Expert tip: If the payment is not urgent, compare a standard ACH transfer with a wire. Choose the lower-cost option that meets the recipient’s requirements and your delivery deadline.
Benefits and Drawbacks of Bank Transfer Methods
Bank transfers can make moving money convenient, but the best option depends on your budget, deadline, and the recipient’s requirements. Compare both the potential cost and the practical trade-offs before sending money.
Benefits
- Potentially lower costs: Many routine ACH transfers between linked accounts have no separate transfer fee.
- Easy access: Eligible transfers can often be arranged through online or mobile banking.
- Flexible options: You can compare standard transfers with faster services based on your needs.
- Suitable for larger payments: Wires may be appropriate when a recipient specifically requires a wire transfer.
Drawbacks
- Possible extra charges: Fees may apply depending on your account, transfer method, and receiving institution.
- Timing differences: Standard transfers may not arrive as quickly as urgent payments require.
- International costs: Intermediary-bank deductions and exchange-rate markups may reduce the amount received.
- Correction challenges: A completed wire sent to the wrong recipient can be difficult to recover; contact your bank immediately if an error occurs.
Practical takeaway: Choose the least expensive method that meets the recipient’s requirements and your deadline. Verify the recipient’s details and review any disclosed fees before authorizing the transfer.
Bank Transfer Fees Compared: ACH vs. Wire Transfers
The cost and delivery time of a bank transfer depend on your financial institution, account terms, destination, and the service you choose. This table provides general guidance, not guaranteed prices or delivery times.
| Transfer method | Potential fees | Delivery timing | Common use |
|---|---|---|---|
| Standard ACH | Often free; certain services may carry a fee | Often takes one or more business days; timing varies | Routine domestic account transfers |
| Domestic wire | Outgoing and/or incoming fees may apply | Often processed the same business day when eligible and submitted before the cutoff | Payments requiring wire delivery |
| International wire | Wire fees, possible intermediary deductions, and currency-conversion costs | Varies by destination, currency, and banks involved | Cross-border payments |
| Expedited transfer | An extra service fee may apply | Depends on provider, eligibility, and cutoff time | When an eligible faster option is needed |
Expert tip: Compare the total expected cost, not just the advertised transfer fee. For international payments, check the exchange rate and expected amount received. For domestic wires, confirm the processing cutoff and whether the receiving bank may charge a fee.
Actual charges and arrival times depend on the institution and transaction. Check the current fee schedule and transfer confirmation before sending money.
Bank Transfer Costs, Risks, and Expert Tips
The transfer fee shown by your bank may not represent the full cost of moving money. Before authorizing a payment, review possible additional charges, delivery conditions, and the risks of sending funds to incorrect or fraudulent recipients.
Costs and Risks to Watch
- Outgoing and incoming wire fees: The sending bank and receiving bank may charge separate fees under their account terms.
- Currency-conversion markup: The exchange rate offered for an international payment may include a markup that increases the effective cost.
- Intermediary-bank deductions: Banks routing an international wire may deduct charges, potentially reducing the amount received.
- Delays and errors: Incorrect account details, processing cutoffs, or bank holidays can affect delivery. Recovering a completed transfer may be difficult, especially if the money reaches an unintended recipient.
Expert Tips to Reduce Costs
- Compare standard ACH transfers with wire options when both meet the recipient’s requirements.
- Check your bank’s current fee schedule and review the charges displayed before confirming payment.
- For international transfers, compare the exchange rate and estimated amount the recipient will receive.
- Verify recipient details independently, especially when payment instructions arrive by email or text.
- Ask your bank whether your account qualifies for a wire-fee waiver or discounted service.
- If you suspect fraud or send money to the wrong recipient, contact your bank immediately and request assistance.
Expert reminder: The lowest advertised fee is not always the lowest overall cost. Compare fees, exchange rates, delivery timing, security, and the recipient’s requirements before choosing a transfer method.
Common Bank Transfer Fee Mistakes to Avoid
- Assuming every ACH transfer is free: Many standard transfers have no separate fee, but charges may apply to specific services or account types.
- Checking only the sending fee: A receiving bank may charge its own fee for an incoming wire.
- Ignoring currency conversion: International transfers may include exchange-rate markups and intermediary-bank deductions.
- Paying for speed unnecessarily: A wire may not be worth the extra cost if a standard ACH transfer meets the deadline.
- Skipping recipient verification: Incorrect details can delay a transfer or make recovering the funds difficult.
Illustrative Example: Sending $1,000
Suppose Alex needs to move $1,000 between eligible U.S. bank accounts. Alex’s bank offers a standard ACH transfer with no transfer fee, while its hypothetical domestic wire fee is $25. If the payment is not urgent and ACH meets the recipient’s requirements, choosing ACH would avoid that $25 sending charge.
If the recipient requires a wire for a time-sensitive payment, Alex should compare the fee with the delivery requirements and confirm the bank’s cutoff time. Alex should also check whether the receiving institution charges an additional fee. The $25 figure is illustrative only and is not a quote from a specific bank.
Key lesson: Compare the total potential cost, delivery time, and recipient requirements before choosing a transfer method. Saving on fees matters only when the chosen method suits the payment.
Who Should Choose Each Bank Transfer Method?
The best transfer method depends on your deadline, the recipient’s requirements, the available services, and the total cost—not just the advertised fee.
- Choose standard ACH for eligible routine transfers between U.S. bank accounts when the expected processing time works for you. Check whether your bank charges for the specific transfer service.
- Choose a domestic wire when needed if the recipient requires a wire or the payment arrangement calls for one. Confirm the sending fee, any receiving fee, and the bank’s cutoff time.
- Consider an international wire when the recipient or payment route requires it. Compare the transfer fee, exchange rate, potential intermediary deductions, and estimated amount the recipient will receive.
- Consider an expedited option if your bank or payment provider offers an eligible faster service and the delivery benefit justifies the extra cost.
Decision tip: Compare the total expected cost, delivery estimate, and recipient requirements before authorizing payment. If the payment instructions are unexpected, verify them independently before sending money.
Frequently Asked Questions About Bank Transfer Fees
1. Do banks charge fees for every bank transfer?
No. Many standard ACH transfers are free, but fees may apply to wire transfers, expedited services, or certain account types. Check your bank’s current fee schedule.
2. Are ACH transfers usually free?
Many routine ACH transfers between linked U.S. bank accounts have no separate transfer fee. However, pricing depends on the bank, account, and service selected.
3. Why do wire transfers cost more than some other transfers?
Wire transfers use payment systems designed for direct bank-to-bank payments and may involve processing and service costs. Banks set their own applicable fees.
4. Can a bank charge for receiving a wire transfer?
Yes. Some banks charge an incoming wire fee, while others may waive it for certain accounts. Check the receiving bank’s fee schedule.
5. Why can international bank transfers cost more?
International transfers may involve sending-bank fees, intermediary-bank deductions, receiving-bank charges, and currency-conversion markups. The total depends on the payment route and institutions involved.
6. How can I avoid unnecessary bank transfer fees?
Compare eligible transfer methods, review your account’s fee schedule, and avoid paying for expedited delivery when it is not needed. Confirm that the recipient accepts your chosen method.
7. Are bank transfer fees tax-deductible?
It depends on the purpose of the transfer and your tax situation. Personal transfer fees are generally not deductible as personal expenses, while certain business-related fees may qualify. Consult current IRS guidance or a qualified tax professional.
8. Where can I find my bank’s transfer fees?
Check your bank’s current fee schedule, account agreement, online transfer screen, or customer-service team. For international transfers, also ask about exchange rates and possible intermediary deductions.
Final Verdict: How to Avoid Unnecessary Bank Transfer Fees
Bank transfer fees depend on your financial institution, account terms, transfer method, and destination. Many routine ACH transfers are free, while domestic and international wires may involve sending fees, receiving fees, or additional costs.
Before sending money, compare the available methods, check your bank’s current fee schedule, and confirm the expected delivery time. For international payments, review the exchange rate and ask whether intermediary or receiving banks may deduct charges. Never choose a transfer method on price alone if the recipient requires a specific payment type.
Our recommendation: Use a suitable low-cost option for routine payments, and pay for a wire or expedited service only when its features meet your needs.
Want to understand your options in more detail? Read our complete guide to bank transfers and payments for more information on transfer methods and payment choices.
Make Smarter Bank Transfer Decisions
Before sending money, compare transfer fees, check delivery times, and confirm how much the recipient is expected to receive.
Have a question or suggestion about this guide? Send your feedback to the FinanceInvestment author.
Leave a Reply