Tag: Treasury Securities

  • What Happens to T-Bills If a Brokerage Fails? | SIPC Guide

    What Happens to T-Bills If a Brokerage Fails? | SIPC Guide

    What Happens to T-Bills If a Brokerage Fails?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 24, 2026
    Updated: Sep 24, 2026
    Reading Time: 11–13 min
    What happens to your Treasury bills when the brokerage holding them fails—and what SIPC protection can and cannot do.


    What Happens to T-Bills If a Brokerage Fails?

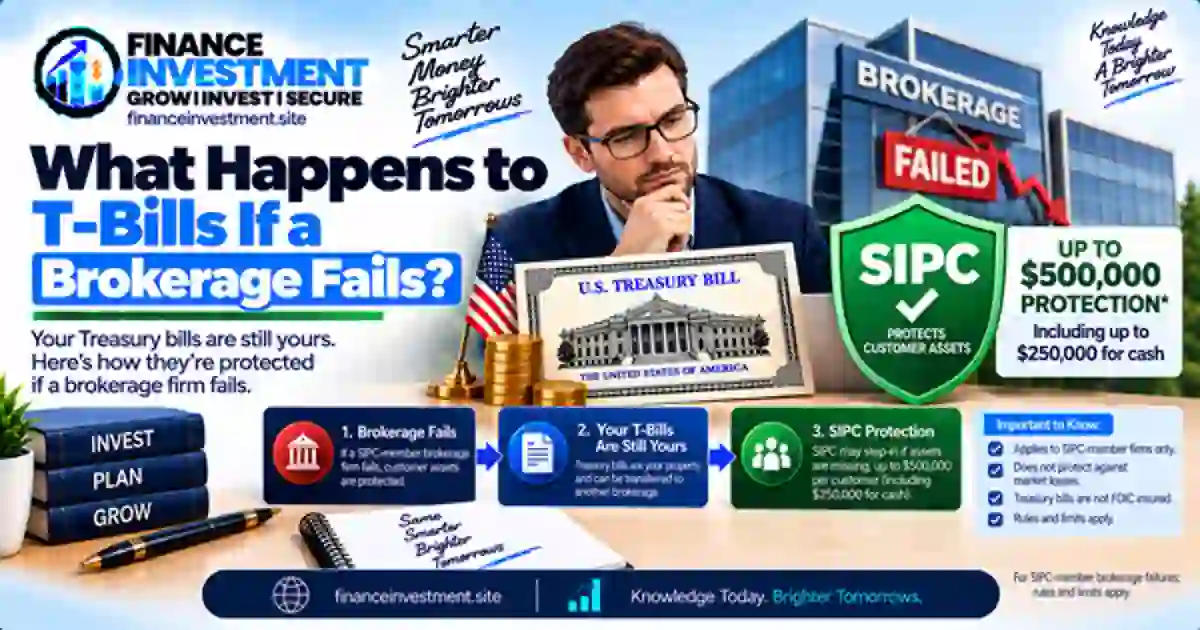
    What Happens to T-Bills If a Brokerage FailsWhat happens to T-bills if a brokerage fails? Your Treasury bills do not simply become worthless because the brokerage holding them fails. T-bills are securities held in a brokerage account, and when a SIPC-member brokerage fails, SIPC may help protect eligible customer securities and cash if customer property is missing, subject to applicable rules and limits.

    There is an important distinction, though. SIPC protection does not cover a drop in the market value of your T-bills. If interest rates change and the market price of a Treasury bill moves, that investment risk remains yours. SIPC protection is designed for situations involving a failed member brokerage and missing customer property, not ordinary investment losses.

    During a brokerage liquidation, customer accounts may sometimes be transferred to another brokerage, while a trustee works through customer claims and the firm’s records. The exact process depends on the circumstances of the failure.

    That makes one question especially useful for T-bill investors: what protection applies to the Treasury security itself, and what protection applies to the brokerage account holding it? Keeping those two issues separate makes the whole process much easier to understand.

    What You’ll Learn

    • What can happen to your T-bills when a brokerage fails.
    • How SIPC protection can apply to eligible Treasury securities.
    • Why brokerage failure is different from a decline in a T-bill’s market price.
    • What the standard $500,000 SIPC protection limit means, including the $250,000 cash limit.
    • How a trustee may handle customer accounts and missing property during a liquidation.
    • What investors should check before keeping T-bills at a brokerage.

    If you want to review the basics first, see our Treasury Bills Explained guide. It provides the foundation for understanding what you actually own before we look at brokerage failure.

    Quick Answer: What Happens to T-Bills If a Brokerage Fails?

    Your T-bills do not automatically become worthless if your brokerage fails. If the brokerage is a SIPC member and customer securities or cash are missing, SIPC may provide protection for eligible customer property, subject to applicable rules and limits. Treasury securities are among the securities that SIPC protection can cover.

    Key Takeaways

    • A brokerage failure is different from an investment loss. SIPC protection addresses certain missing customer securities and cash when a qualifying brokerage fails.
    • The brokerage must be a SIPC member. SIPC protection is available only under the conditions established by the Securities Investor Protection Act.
    • Treasury securities can qualify for SIPC protection. Investor.gov specifically lists Treasuries among the protected securities.
    • The standard SIPC limit is $500,000 per customer. This includes a maximum of $250,000 for claims involving cash. The limit does not mean every investor automatically receives $500,000.
    • SIPC does not cover market losses. If a T-bill’s market value falls because interest rates or other market conditions change, SIPC does not reimburse that decline.
    • A failed brokerage may not always require a full SIPC liquidation. In some cases, customer accounts can be transferred to another SIPC-member brokerage without a SIPC protection proceeding.

    BOTTOM LINE: SIPC protection is designed to address missing eligible customer securities and cash when a SIPC-member brokerage fails. It is not protection against changes in the market value of your T-bills.

    Table of Contents

    T-Bills and Brokerage Failure at a Glance

    When you hold Treasury bills through a brokerage, two things should be kept separate: the Treasury security you own and the brokerage relationship through which it is held. If the brokerage fails, the issue is generally whether customer property can be returned and, when eligible property is missing, whether SIPC protection applies.

    Quick FactWhat It Means
    What you holdA Treasury security recorded in your brokerage account
    If the brokerage failsCustomer accounts may be transferred, or a SIPC liquidation may occur if required
    SIPC limitUp to $500,000 per customer, including up to $250,000 for cash claims
    Market lossNot protected by SIPC
    Membership checkConfirm that the relevant brokerage and, where applicable, clearing firm are SIPC members

    Best For Investors Who Want to Understand the Protection Layers

    The simplest way to look at brokerage-held T-bills is to separate the investment from the account provider. The Treasury bill remains a Treasury security, while SIPC focuses on certain customer cash and securities held by a failed SIPC-member brokerage. Those are different layers of protection.

    QUICK TAKE: A brokerage failure does not by itself mean your T-bills have lost their value or Treasury status. The practical concern is whether the brokerage can account for and return customer property and, if eligible property is missing, whether SIPC protection applies.

    T-Bills at a Brokerage: Complete Beginner Guide

    What Happens to T-Bills If a Brokerage FailsBuying Treasury bills through a brokerage can look similar to buying a stock, but the investment itself is different. A T-bill is a short-term debt security issued by the U.S. Treasury. The brokerage provides the account and services used to purchase and hold that security.
    What You Actually Hold

    When you buy a T-bill through a brokerage, the Treasury—not the brokerage—is the issuer of the security. The brokerage account records your position and provides the custody and trading relationship. Securities can be held in different registration arrangements, including customer-name or street-name form, depending on the account structure.

    If you are new to T-bills, our guide to how Treasury bills work explains how the purchase price, maturity value, and return fit together.

    Why the Brokerage Still Matters

    Even though the Treasury issues the T-bill, the brokerage handles the account through which you hold it. If that brokerage fails, the key question is whether customer property can be accounted for and returned. If a SIPC-member brokerage fails and eligible customer securities or cash are missing, SIPC may provide protection for the resulting shortfall, subject to the applicable rules and limits.

    What SIPC Does—and Does Not—Cover

    SIPC can provide advances of up to $500,000 per customer, including up to $250,000 for cash claims, when the statutory requirements are met. The limit is designed to address a shortfall in eligible customer property; it does not mean every investor automatically receives $500,000.

    Just as important, SIPC does not protect against a decline in the market value of your T-bill. If you sell before maturity and the price is lower because interest rates or other market conditions have changed, that investment loss is not covered by SIPC.

    BEGINNER TIP: Think about the arrangement in two layers: the T-bill is the Treasury security, while the brokerage provides the account and custody relationship. A brokerage failure and a change in the T-bill’s market price are separate risks.

    How T-Bills Are Protected When a Brokerage Fails

    A brokerage failure does not automatically mean that investors must wait for a SIPC payout. U.S. rules require broker-dealers to segregate customer securities and cash from the firm’s own assets, with the goal of making customer property available for return if the firm fails. If a SIPC-member brokerage cannot meet its obligations, a customer-account transfer or SIPC liquidation may follow, depending on the circumstances.

    Step 1: Customer Property Is Identified

    The trustee reviews the brokerage’s books and records to determine what each customer is entitled to receive. Your account statements, trade confirmations, and other records can help establish the securities and cash connected with your account. This is why keeping accurate records and reviewing statements matters.

    Step 2: Accounts May Be Transferred

    When practical, a trustee may arrange for some or all customer accounts to be transferred to another SIPC-member brokerage. If your account is transferred, you may continue to hold your securities through the new firm rather than going through a lengthy liquidation process for the account itself. Even after a transfer, customers may still need to file a claim if the transfer does not make the account whole.

    Step 3: A Trustee Handles a Liquidation When Necessary

    If liquidation is required, a court-appointed trustee works to return customer property and process valid claims. Customer-name securities can be delivered to the customer in whose name they are registered, while other customer property may be pooled and distributed under the SIPA process.

    Step 4: SIPC Can Address a Shortfall

    If eligible customer property is missing, SIPC may provide an advance of up to $500,000 per customer, including up to $250,000 for cash claims, subject to the applicable rules. Treasury securities are among the securities SIPC protects. This protection addresses a shortfall caused by a qualifying brokerage failure; it does not protect against a decline in the market value of a T-bill.

    IMPORTANT DISTINCTION: There are two separate questions: Can the brokerage return your customer property? And, if eligible property is missing, does SIPC protection apply? Neither question changes the market value of the T-bills themselves.

    Benefits and Drawbacks of Brokerage T-Bills

    Holding Treasury bills through a brokerage can make them easier to manage alongside other investments. At the same time, the brokerage account introduces a separate layer of custody and account-related considerations. Knowing both sides can help you understand what you are actually relying on.

    ✓ Potential Benefits

    • One investment account: T-bills can be managed alongside stocks, bonds, ETFs, and other securities in the same brokerage account.
    • Convenient account records: Purchases, holdings, sales, and maturity information can appear within your regular brokerage records.
    • Access to the secondary market: A brokerage can provide a way to sell a T-bill before maturity, although the price you receive can change with market conditions.
    • SIPC protection may apply: If a SIPC-member brokerage fails and eligible customer securities or cash are missing, SIPC may provide protection for the resulting shortfall, subject to statutory limits and other requirements.

    △ Potential Drawbacks

    • SIPC does not cover market losses: If your T-bill declines in market value, SIPC does not reimburse that investment loss.
    • A brokerage failure can cause disruption: Accounts may need to be transferred, or a liquidation and claims process may be required when customer property is missing.
    • Trading costs can matter: Brokerage commissions, spreads, markups, markdowns, or other transaction costs may affect what you receive when buying or selling in the secondary market.
    • SIPC protection has conditions: The brokerage must be a SIPC member, and the protection applies to qualifying customer securities and cash under the rules of SIPA.

    PRACTICAL TAKE: A brokerage can make T-bills convenient to manage, but convenience is not the same as investment protection. Before buying, check the firm’s SIPC membership, understand its trading costs, and know whether you may need to sell the T-bill before maturity.

    SIPC vs. FDIC vs. Treasury Protection

    SIPC, FDIC insurance, and Treasury backing are not three versions of the same protection. They apply to different financial products and different situations. SIPC addresses certain missing customer securities and cash when a qualifying brokerage fails. FDIC insurance protects eligible deposits at FDIC-insured banks. Treasury backing refers to the U.S. government’s obligation on Treasury securities such as T-bills.

    Protection or BackingApplies ToWhat It Addresses
    SIPCEligible securities and qualifying cash held at a SIPC-member brokerageMissing customer property after a qualifying brokerage failure
    FDIC insuranceEligible deposits at an FDIC-insured bankCovered deposit losses when an insured bank fails
    Treasury backingU.S. Treasury securities such as T-billsThe U.S. government’s obligation to honor the security according to its terms

    What This Means for Brokerage-Held T-Bills

    Suppose you hold T-bills in a brokerage account and the brokerage later fails. The T-bills remain Treasury securities. If the brokerage is a SIPC member and eligible customer securities or cash are missing, SIPC may provide protection for the resulting customer-property shortfall. Treasury securities are specifically included among the securities SIPC protects. The standard SIPC limit is up to $500,000 per customer, including up to $250,000 for cash claims, subject to the applicable rules.

    FDIC insurance works differently. If a brokerage uses a bank sweep program, unused cash may be moved into a bank deposit that can receive FDIC insurance under applicable rules. That does not make your separately held T-bills FDIC insured.

    There is another important boundary: SIPC does not protect against a decline in the market value of a security. So if your T-bill’s market price falls because interest rates or other market conditions change, that investment loss is not a SIPC claim.

    EASY WAY TO REMEMBER: SIPC = certain brokerage-failure losses involving missing customer property. FDIC = eligible bank deposits. Treasury backing = the U.S. government’s obligation on Treasury securities.

    Limits, Risks and Practical Tips

    SIPC protection can be valuable when a brokerage fails, but it is not unlimited insurance. The standard protection is up to $500,000 per customer, including a maximum of $250,000 for cash claims. The amount actually available depends on the customer’s eligible claim, the customer-property shortfall, and the applicable SIPC rules.

    Know the Main Limits

    • SIPC is not market-loss insurance. If your T-bill falls in market value, SIPC does not reimburse that investment loss.
    • The brokerage must qualify for SIPC protection. SIPC protection applies when the relevant brokerage is a SIPC member and the other legal requirements are met.
    • Different account capacities can matter. Accounts held in separate capacities can receive separate SIPC limits, while accounts held in the same capacity at the same firm are generally combined for the protection limits.

    Practical Tips for T-Bill Investors

    1. Verify SIPC membership before keeping a large T-bill position at a brokerage.
    2. Save account statements and trade confirmations so you can document your holdings if a problem occurs.
    3. Understand your cash position. Uninvested cash, money market funds, and bank sweep deposits can receive different types of protection.
    4. Know your broker and clearing firm. Review which firms actually hold or clear your account and understand the account structure.
    5. Do not confuse SIPC protection with a guarantee of value. The purpose is to address certain missing customer securities and cash after a qualifying brokerage failure.

    PRACTICAL TAKE: Before buying T-bills through a brokerage, check three things: SIPC membership, account structure, and what happens to your uninvested cash. Those details help you understand the protection that may apply if the brokerage later fails.

    Common Mistakes and Real-Life Example

    Many T-bill investors focus on the Treasury security itself and overlook the brokerage relationship. That can create confusion if the brokerage later fails. Understanding the difference between returning customer property and covering a shortfall makes the process easier to follow.

    Common Mistakes to Avoid

    • Assuming SIPC works like FDIC insurance: SIPC addresses certain missing customer securities and cash after a qualifying brokerage failure. It does not protect against investment losses.
    • Assuming every brokerage account is automatically protected: The brokerage must be a SIPC member, and the customer and property must meet the applicable requirements.
    • Confusing T-bills with cash: A T-bill is a Treasury security. Uninvested brokerage cash can have different protection depending on how it is held.
    • Ignoring account records: Statements, trade confirmations, and other records can help establish what securities and cash are connected with your account.

    Real-Life Example: A $300,000 T-Bill Position

    Imagine an investor holds $300,000 of Treasury bills through a SIPC-member brokerage. The brokerage later fails, but its records and custody systems show that the investor owns those T-bills. If the securities can be located and returned, the investor generally receives the securities rather than a SIPC payment for their market value. Treasury securities are among the securities covered by SIPC protection.

    Now assume some eligible customer property is missing. SIPC may provide an advance toward the qualifying shortfall, subject to the applicable protection limits. The standard limit is up to $500,000 per customer, including up to $250,000 for cash claims. This does not mean an investor automatically receives $500,000.

    Finally, suppose the T-bills are worth less in the secondary market because interest rates changed. That is a separate investment risk. SIPC does not cover a decline in market value. The example shows why brokerage failure, missing customer property, and ordinary market-price changes should not be treated as the same event.

    KEY LESSON: If a brokerage fails, first determine whether your T-bills and other customer property can be returned. If eligible property is missing, then SIPC protection may address the qualifying shortfall, subject to its rules and limits.

    Who Should Consider Brokerage T-Bills?

    Brokerage-held T-bills may be relevant for investors who want to manage Treasury securities alongside stocks, bonds, ETFs, or other investments in one account. A brokerage can also provide access to Treasury purchases and, depending on the firm, a secondary market for selling before maturity.

    This Setup May Fit Investors Who Value

    • Account convenience: Keep T-bills and other investments together in one brokerage account.
    • Trading access: Use brokerage tools to buy or sell Treasury bills, including before maturity when secondary-market access is available.
    • Portfolio management: View Treasury holdings alongside the rest of the investment portfolio.
    • Brokerage-based custody: Hold eligible Treasury securities through a SIPC-member brokerage, where SIPC protection may apply if the firm fails and eligible customer property is missing.

    What to Check Before Buying

    Compare the brokerage’s SIPC membership, clearing arrangement, trading costs, account structure, and treatment of uninvested cash. Investor.gov recommends checking whether the brokerage and clearing firm are SIPC members.  If you prefer to hold Treasury securities directly rather than through a brokerage, compare that approach with your other Treasury bill options before making a decision.

    KEY POINT: Brokerage-held T-bills can offer account convenience, but SIPC protection is a separate issue. It addresses certain missing customer securities and cash after a qualifying brokerage failure; it does not protect against normal investment losses.

    Frequently Asked Questions

    1. What happens to T-bills if a brokerage fails?

    Your T-bills do not automatically become worthless if a brokerage fails. Customer accounts may be transferred to another SIPC-member brokerage, or a SIPC liquidation may occur if necessary. If eligible customer property is missing, SIPC may provide protection for a qualifying shortfall, subject to applicable rules and limits.

    2. Are Treasury bills protected by SIPC?

    Treasury securities are among the securities SIPC can protect when held through a qualifying SIPC-member brokerage. The protection is designed for certain missing customer securities and cash after a qualifying brokerage failure. It does not protect against a decline in the market value of the investment.

    3. What is the SIPC protection limit for T-bills?

    SIPC may provide protection of up to $500,000 per customer, including a maximum of $250,000 for cash claims. The limit is not an automatic payment. The amount available depends on the customer’s eligible claim, missing customer property, and the applicable SIPC rules.

    4. Does SIPC protect T-bills from losing value?

    No. SIPC does not protect against a decline in the market value of securities. If interest rates change and the secondary-market price of your T-bill falls, that investment loss is not covered by SIPC.

    5. Are T-bills FDIC insured when bought through a brokerage?

    No. T-bills are Treasury securities, not bank deposits, so FDIC deposit insurance does not apply to the T-bills themselves. A brokerage may separately offer a bank sweep program for uninvested cash. Eligible swept deposits may receive FDIC protection under applicable banking rules, but that protection is separate from the T-bills.

    6. Can my T-bill account be transferred if my broker fails?

    It may be. A closed SIPC-member brokerage may be able to transfer customer accounts to another SIPC-member brokerage without a SIPC protection proceeding. If SIPC initiates a liquidation, a trustee may also work to transfer customer accounts when possible. The exact process depends on the circumstances.

    7. What should I check before holding T-bills at a brokerage?

    Check whether the brokerage is a SIPC member, understand its clearing arrangement, review how uninvested cash is held, and keep your account statements and trade confirmations. Investor.gov recommends checking the brokerage firm and its clearing firm for SIPC membership.

    8. Is TreasuryDirect different from holding T-bills at a brokerage?

    Yes. TreasuryDirect and brokerage accounts are different ways to hold Treasury securities. A brokerage account involves a brokerage and custody relationship and may involve SIPC protection if the firm qualifies. TreasuryDirect is a separate Treasury account. Investors should compare the account structure, access, and features that matter to them before choosing where to hold T-bills.

    FAQ TAKEAWAY: Treasury backing, SIPC protection, and FDIC insurance are different concepts. Treasury backing relates to the Treasury security itself. SIPC addresses certain missing customer securities and cash when a qualifying brokerage fails. FDIC insurance applies to eligible bank deposits.


    Final Verdict: What Happens to T-Bills If a Brokerage Fails?

    What happens to T-bills if a brokerage fails? A brokerage failure does not automatically make your Treasury bills worthless. If the brokerage is a SIPC member, customer accounts may be transferred to another brokerage, or a SIPC liquidation may occur when necessary. If eligible customer property is missing, SIPC may provide an advance toward the qualifying shortfall, subject to applicable rules and limits.

    The key distinction is between brokerage-failure risk and investment risk. SIPC protection can address certain missing customer securities and cash when a qualifying brokerage fails, but it does not protect against a decline in the market value of your T-bills. The standard SIPC protection limit is up to $500,000 per customer, including up to $250,000 for cash claims.

    Before holding a large T-bill position at a brokerage, review the firm’s SIPC membership, clearing arrangement, account structure, and treatment of uninvested cash. Investor.gov recommends checking both the brokerage firm and its clearing firm for SIPC membership.

    BOTTOM LINE: A brokerage failure is mainly a custody and customer-property issue. If eligible T-bills are properly accounted for, they may be returned or transferred. If eligible customer property is missing, SIPC may address the qualifying shortfall. SIPC does not guarantee the market value of the investment.

    Have a Money Question? Keep Exploring.

    Knowing how your T-bills are held can help you understand the protection that may apply if a brokerage fails. Keep exploring practical Treasury bill and personal finance guides from FinanceInvestment.

    📩 Get in Touch With FinanceInvestment
    Have a question, suggestion, or topic you’d like us to cover?

    Email FinanceInvestment

    Continue Your Research
  • Do You Pay Federal Tax on Treasury Bills? 2026 Guide

    Do You Pay Federal Tax on Treasury Bills? 2026 Guide

    Do You Pay Federal Tax on Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: September 23, 2026
    Updated: September 23, 2026
    Reading Time: 10–12 min

    Do You Pay Federal Tax on Treasury Bills?

    Do You Pay Federal Tax on Treasury Bills?Yes, Treasury bills are generally subject to federal income tax. If you are asking, do you pay federal tax on Treasury bills, the key point is simple: T-bill interest is taxable at the federal level. Treasury bills are U.S. government securities, but that does not make their interest exempt from federal income tax. At the same time, Treasury bill interest is generally exempt from state and local income taxes. IRS guidance explains this distinction for Treasury obligations.

    The way T-bill interest is earned can also look different from a bank savings account or CD. Treasury bills are generally issued at a discount and mature at face value. For a standard T-bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes. Applicable Treasury interest is generally reported on Form 1099-INT, Box 3.

    Understanding these rules can make it easier to compare Treasury bills with other short-term investments. For a broader explanation of maturities, pricing, auctions, and tax treatment, see our complete Treasury Bills guide.

    What You’ll Learn

    • How federal income tax applies to Treasury bill interest.
    • When T-bill interest is generally reported for federal tax purposes.
    • How Treasury interest appears on Form 1099-INT.
    • Why T-bills generally receive state and local income-tax treatment that differs from federal tax.
    • How T-bill taxation compares with CDs, savings accounts, and money market accounts.
    • Common federal tax-reporting mistakes to watch for.

    Quick Answer: Do You Pay Federal Tax on Treasury Bills?

    Yes. Interest from Treasury bills is generally subject to federal income tax. Treasury bill interest is also generally exempt from state and local income taxes. For Treasury bills, the applicable interest is generally reported on Form 1099-INT, Box 3.

    Key Takeaways

    • Federal tax applies: Treasury bill interest is generally taxable for federal income-tax purposes.
    • State and local exemption: Treasury bill interest is generally exempt from state and local income taxes.
    • T-bill discount: For a standard T-bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income.
    • 1099-INT Box 3: Treasury bill interest is generally reported in Box 3 of Form 1099-INT rather than Box 1.
    • Not completely tax-free: The state and local tax exemption does not eliminate federal income tax.
    • Tax timing: For a standard T-bill held to maturity, the IRS generally says taxpayers report the interest when the bill is paid at maturity, subject to the applicable tax rules.

    Bottom line: Treasury bills are generally federally taxable, but their interest receives an exemption from state and local income taxes. The exact tax treatment can depend on the type of Treasury transaction and the taxpayer’s circumstances.

    Table of Contents

    Treasury Bills and Federal Tax at a Glance

    Treasury bills are generally subject to federal income tax. They are not federally tax-free investments. However, interest from U.S. Treasury obligations is generally exempt from state and local income taxes. This distinction is important when comparing T-bills with taxable bank deposits and other short-term investments.

    Tax DetailTreasury Bill Treatment
    Federal income taxGenerally taxable
    State income taxGenerally exempt
    Local income taxGenerally exempt
    Form 1099-INTTreasury interest is generally reported in Box 3
    Main tax benefitGenerally exempt from state and local income taxes

    QUICK TAKE: Treasury bills are generally taxable at the federal level, while their interest is generally exempt from state and local income taxes. For example, if a T-bill produces $200 of interest, that interest is generally included in federal taxable income, subject to the applicable federal tax rules.

    Complete Beginner Guide to T-Bill Federal Tax

    Do You Pay Federal Tax on Treasury Bills?Understanding federal tax on Treasury bills starts with one simple rule: interest from Treasury bills is generally subject to federal income tax. A T-bill is issued by the U.S. Treasury, but that does not make its interest federally tax-free. At the same time, Treasury bill interest is generally exempt from state and local income taxes. See the IRS guidance on Treasury interest for the applicable federal tax rules.
    1. How Do Treasury Bills Create Taxable Income?

    Treasury bills are generally issued at a discount instead of paying regular coupon interest. For example, an investor could pay $9,800 for a T-bill with a $10,000 maturity value. If the bill is held to maturity, the $200 difference is generally treated as interest income for federal tax purposes.

    2. Is the Entire T-Bill Amount Taxable?

    No. In a standard purchase held to maturity, the amount originally invested is not itself the interest income. The taxable interest component is generally the difference between the purchase price and the amount received at maturity. The exact treatment can differ for certain transactions, including purchases or sales in the secondary market.

    3. When Is T-Bill Interest Reported?

    For a standard Treasury bill held to maturity, the IRS generally provides that the interest is reported when the bill is paid at maturity. Selling a T-bill before maturity can involve different tax considerations, so investors should retain purchase, sale, and maturity records.

    4. Where Does Treasury Interest Appear?

    Treasury interest is generally reported on Form 1099-INT, Box 3. IRS instructions identify Box 3 for interest on U.S. savings bonds and Treasury obligations. Investors should use the tax documents and records applicable to their specific transaction.

    EASY WAY TO REMEMBER: Treasury bill interest is generally taxable at the federal level, generally exempt from state and local income taxes, and generally reported as Treasury interest in Box 3 of Form 1099-INT.

    How Federal Tax on T-Bills Works

    The federal tax treatment of a Treasury bill is easier to understand when you follow the investment from purchase to maturity. A standard T-bill generally does not make periodic coupon payments. Instead, it is issued at a discount and pays its face value at maturity. The difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes.

    Step 1: You Buy the Treasury Bill

    For example, a T-bill with a $10,000 maturity value might be purchased for $9,800. The $200 difference is generally the interest income associated with the bill when it is held to maturity. Treasury bills are commonly issued with maturities such as 4, 8, 13, 26, and 52 weeks.

    Step 2: The Bill Reaches Maturity

    At maturity, the Treasury generally pays the bill’s face value. For a standard T-bill held to maturity, the difference between the purchase price and the maturity amount is generally treated as interest income rather than a separate capital gain.

    Step 3: Federal Tax Applies

    The interest is generally subject to federal income tax. However, interest from U.S. Treasury obligations is generally exempt from state and local income taxes. This creates an important tax distinction when comparing T-bills with taxable bank deposits.

    Step 4: The Interest Is Reported

    Treasury interest is generally reported on Form 1099-INT, Box 3. For a standard T-bill held to maturity, cash-method taxpayers generally report the interest when the bill is paid at maturity. A purchase or sale in the secondary market can involve different tax rules and reporting considerations.

    THE SIMPLE VERSION: A standard T-bill is generally bought below face value, matures at face value, and the difference is generally treated as federally taxable interest. Treasury interest is generally exempt from state and local income taxes.

    Benefits & Drawbacks of Federal Tax on Treasury Bills

    Treasury bills are generally subject to federal income tax, but their interest is exempt from state and local income taxes. That combination can affect the after-tax comparison between T-bills and other interest-producing investments. The actual impact depends on the investor’s applicable tax situation and the type of transaction.

    Potential Benefits

    • State and local tax exemption: Treasury bill interest is generally exempt from state and local income taxes.
    • Potential after-tax advantage: In a comparison with an otherwise similar taxable investment, avoiding applicable state and local income taxes can increase the amount of interest retained after those taxes.
    • Federal tax treatment is identifiable: Treasury interest is generally reported separately in Box 3 of Form 1099-INT, making it easier to identify the Treasury portion of reported interest income.

    Potential Drawbacks

    • Federal tax still applies: The state and local exemption does not make Treasury bill interest federally tax-free.
    • After-tax results vary: The value of the state and local exemption depends on the applicable tax rules and the investment being compared.
    • Different transactions can have different rules: Buying or selling a T-bill in the secondary market can create additional tax and reporting considerations.

    QUICK TAKE: The main tax benefit of Treasury bills is the general exemption from state and local income taxes. Federal income tax still applies, so comparing the complete after-tax result is more useful than looking only at the stated T-bill yield.

    T-Bills vs. CDs vs. Savings vs. Money Market

    Federal tax treatment can help explain an important difference between Treasury bills and common bank deposit products. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Interest earned from bank CDs, savings accounts, and bank money market accounts is generally subject to federal income tax, while state and local treatment depends on the applicable rules.

    InvestmentFederal TaxState & Local Income TaxCommon Federal Reporting
    Treasury BillsGenerally appliesGenerally exemptForm 1099-INT, generally Box 3
    Bank CDsGenerally appliesDepends on applicable state and local rulesGenerally Form 1099-INT when reportable
    Savings AccountsGenerally appliesDepends on applicable state and local rulesGenerally Form 1099-INT when reportable
    Bank Money Market AccountsGenerally appliesDepends on applicable state and local rulesGenerally Form 1099-INT when reportable

    One Important Distinction

    A bank money market account is different from a money market mutual fund. A bank money market account is a deposit account that generally pays interest. A money market fund is an investment product, and its distributions can have different tax-reporting characteristics. This comparison refers specifically to bank money market accounts.

    QUICK TAKE: Treasury bills have a specific federal, state, and local tax distinction: their interest is generally federally taxable but exempt from state and local income taxes. For bank deposit products, state and local treatment can differ. Compare the applicable tax rules along with yield, maturity, liquidity, and account terms.

    Costs, Tax Risks & Expert Tips

    Treasury bills generally do not pay periodic coupon interest. Instead, they are commonly issued at a discount and pay their face value at maturity. For a standard T-bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes. Other transactions can involve different tax rules.

    Costs to Check

    • Transaction costs: If buying through a brokerage, check the firm’s pricing, bid-ask spread, or other applicable transaction costs.
    • After-tax return: Compare the T-bill’s yield after considering applicable federal tax and its state and local tax exemption.
    • Recordkeeping: Keep purchase confirmations, maturity information, sale records, and tax forms with your investment records.

    Tax Risks to Understand

    • Federal tax still applies: Treasury bill interest is generally subject to federal income tax.
    • Tax forms are not the only consideration: Not receiving a Form 1099-INT does not by itself remove an applicable tax-reporting obligation.
    • Early sale: Selling a T-bill before maturity can involve tax and reporting considerations that differ from a standard held-to-maturity transaction.

    Expert Tips for Cleaner Tax Reporting

    For a standard T-bill held to maturity, keep the original purchase price and maturity amount available when reviewing your tax records. Treasury interest is generally reported on Form 1099-INT, Box 3. If a T-bill is sold before maturity or purchased in the secondary market, review the transaction records and applicable tax rules carefully.

    EXPERT TIP: Keep your Treasury purchase, maturity, sale, and tax records together. For transactions outside a standard held-to-maturity purchase, consult the applicable IRS guidance or a qualified tax professional when needed.

    Common Mistakes + Real-Life Example

    Federal tax on Treasury bills is generally straightforward when a standard bill is purchased and held to maturity. Still, investors can misunderstand the state-tax exemption, overlook their tax records, or assume that an early sale follows exactly the same rules.

    Mistake 1: Assuming T-Bills Are Completely Tax-Free

    Treasury bill interest is generally exempt from state and local income taxes, but it is generally subject to federal income tax. The state and local exemption should not be confused with complete tax-free treatment.

    Mistake 2: Ignoring Form 1099-INT

    Treasury interest is generally reported in Box 3 of Form 1099-INT. Investors should review their tax documents and keep their own purchase, maturity, and transaction records. The absence of a tax form does not by itself determine whether income is reportable.

    Mistake 3: Overlooking an Early Sale

    A standard T-bill held to maturity has relatively straightforward treatment. Selling before maturity or buying a T-bill in the secondary market can involve additional tax and reporting rules, so the transaction records matter.

    Real-Life Example: A $10,000 T-Bill

    Suppose an investor buys a $10,000 face-value T-bill for $9,800 and holds it until maturity. The Treasury pays $10,000 at maturity, creating a $200 difference. For a standard T-bill held to maturity, that difference is generally treated as interest income for federal tax purposes. Treasury interest is generally exempt from state and local income taxes and generally appears in Box 3 of Form 1099-INT.

    KEY LESSON: Treasury bills can receive a state and local income-tax exemption without being federally tax-free. For a standard held-to-maturity T-bill, keep the purchase and maturity records and review the applicable Treasury interest reported for federal tax purposes.

    Who May Consider Treasury Bills?

    Treasury bills may be relevant to investors looking at short-term U.S. government securities and evaluating how federal, state, and local taxes affect their interest income. Their tax treatment can be one factor when comparing T-bills with other short-term investments.

    T-Bills May Be Relevant to Investors Who:

    • Want exposure to a U.S. Treasury security with a short maturity, generally 52 weeks or less.
    • Want to account for the general state and local income-tax exemption on Treasury interest.
    • Are comparing securities that are generally issued at a discount and pay face value at maturity.
    • Understand that Treasury bill interest is generally subject to federal income tax.
    • Want to compare potential after-tax income across different short-term investments.

    KEEP IN MIND: Tax treatment is only one factor in evaluating a Treasury bill. Maturity, yield, liquidity, transaction costs, federal taxes, and the tax treatment of alternative investments can also affect the overall comparison.

    Frequently Asked Questions

    1. Do You Pay Federal Tax on Treasury Bills?

    Yes. Interest from Treasury bills is generally subject to federal income tax. Treasury interest is generally exempt from state and local income taxes.

    2. Are Treasury Bills Tax-Free?

    No. Treasury bills are not completely tax-free. Their interest is generally taxable for federal income-tax purposes, while generally receiving an exemption from state and local income taxes.

    3. How Is T-Bill Interest Taxed?

    For a standard Treasury bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes.

    4. Where Is Treasury Bill Interest Reported?

    Treasury interest is generally reported on Form 1099-INT, Box 3. Investors should also keep their purchase, maturity, and other transaction records.

    5. When Do You Report T-Bill Interest?

    For a standard Treasury bill held to maturity, cash-method taxpayers generally report the interest when the bill is paid at maturity, subject to the applicable federal tax rules.

    6. What If You Do Not Receive Form 1099-INT?

    Not receiving Form 1099-INT does not by itself determine whether income is reportable. Investors should review their Treasury records and the applicable federal tax rules when preparing their return.

    7. Are Treasury Bills Exempt From State and Local Income Taxes?

    Generally, yes. Interest from U.S. Treasury obligations, including Treasury bills, is generally exempt from state and local income taxes.

    8. Does Selling a T-Bill Before Maturity Change the Tax Treatment?

    It can. A sale before maturity or a secondary-market purchase can involve additional tax and reporting considerations. The standard held-to-maturity treatment should not automatically be applied to every transaction.

    QUICK ANSWER: Treasury bills are generally subject to federal income tax, while their interest is generally exempt from state and local income taxes.

    Final Verdict: Do You Pay Federal Tax on Treasury Bills?

    Yes. Treasury bill interest is generally subject to federal income tax. At the same time, interest from U.S. Treasury obligations is generally exempt from state and local income taxes. So, Treasury bills are not completely tax-free, but they do receive a specific state and local income-tax exemption.

    For a standard T-bill held to maturity, the difference between the purchase price and the amount received at maturity is generally treated as interest income for federal tax purposes. Treasury interest is generally reported on Form 1099-INT, Box 3. A sale before maturity or a secondary-market purchase can involve additional tax and reporting considerations.

    For a broader explanation of Treasury bill maturities, pricing, auctions, and tax treatment, see our complete Treasury Bills guide.

    BOTTOM LINE: Treasury bills are generally subject to federal income tax, while their interest is generally exempt from state and local income taxes. When comparing T-bills with other investments, consider the applicable tax treatment along with yield, maturity, liquidity, and transaction costs.

    Have a Money Question? Keep Exploring.

    Treasury bill taxes can affect the income you actually keep after taxes. Continue exploring FinanceInvestment to understand T-bill pricing, yields, maturities, and other factors that can help you evaluate short-term investments.

    📩 Get in Touch With FinanceInvestment

    Have a money question or a topic you’d like us to cover? Send us a message.

    Email FinanceInvestment

    Continue Your Research

    Treasury Bills Explained  |  Treasury Bill Price vs. Face Value