What Happens to T-Bills If a Brokerage Fails?
What Happens to T-Bills If a Brokerage Fails?
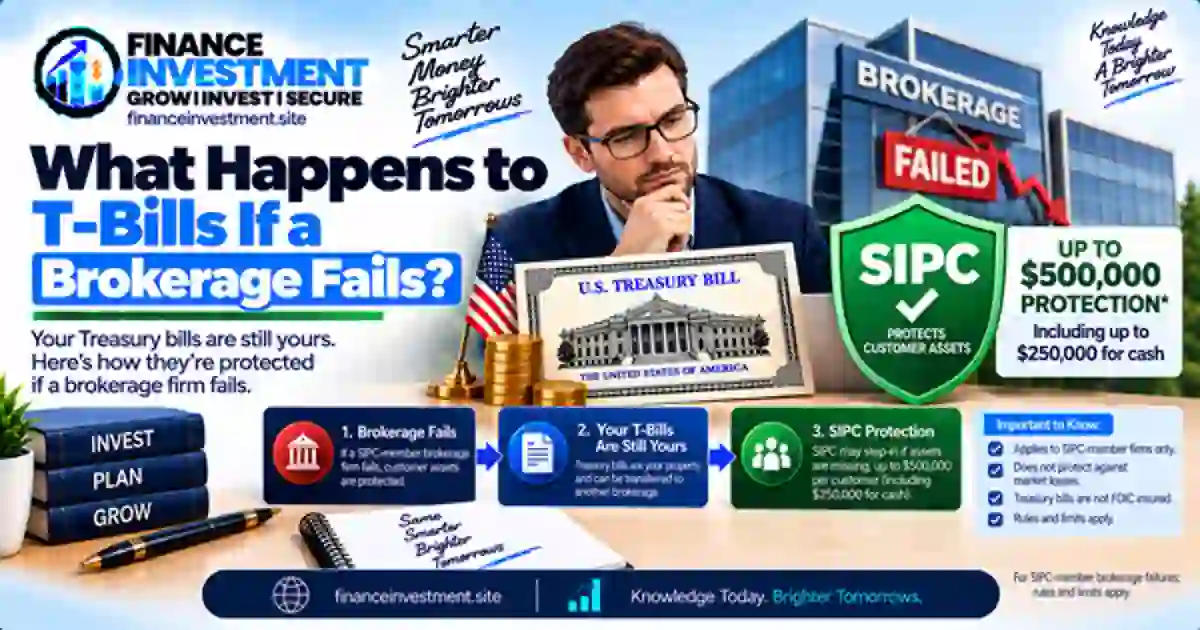 What happens to T-bills if a brokerage fails? Your Treasury bills do not simply become worthless because the brokerage holding them fails. T-bills are securities held in a brokerage account, and when a SIPC-member brokerage fails, SIPC may help protect eligible customer securities and cash if customer property is missing, subject to applicable rules and limits.
There is an important distinction, though. SIPC protection does not cover a drop in the market value of your T-bills. If interest rates change and the market price of a Treasury bill moves, that investment risk remains yours. SIPC protection is designed for situations involving a failed member brokerage and missing customer property, not ordinary investment losses.
During a brokerage liquidation, customer accounts may sometimes be transferred to another brokerage, while a trustee works through customer claims and the firm’s records. The exact process depends on the circumstances of the failure.
That makes one question especially useful for T-bill investors: what protection applies to the Treasury security itself, and what protection applies to the brokerage account holding it? Keeping those two issues separate makes the whole process much easier to understand.
What You’ll Learn
- What can happen to your T-bills when a brokerage fails.
- How SIPC protection can apply to eligible Treasury securities.
- Why brokerage failure is different from a decline in a T-bill’s market price.
- What the standard $500,000 SIPC protection limit means, including the $250,000 cash limit.
- How a trustee may handle customer accounts and missing property during a liquidation.
- What investors should check before keeping T-bills at a brokerage.
If you want to review the basics first, see our Treasury Bills Explained guide. It provides the foundation for understanding what you actually own before we look at brokerage failure.
Quick Answer: What Happens to T-Bills If a Brokerage Fails?
Your T-bills do not automatically become worthless if your brokerage fails. If the brokerage is a SIPC member and customer securities or cash are missing, SIPC may provide protection for eligible customer property, subject to applicable rules and limits. Treasury securities are among the securities that SIPC protection can cover.
Key Takeaways
- A brokerage failure is different from an investment loss. SIPC protection addresses certain missing customer securities and cash when a qualifying brokerage fails.
- The brokerage must be a SIPC member. SIPC protection is available only under the conditions established by the Securities Investor Protection Act.
- Treasury securities can qualify for SIPC protection. Investor.gov specifically lists Treasuries among the protected securities.
- The standard SIPC limit is $500,000 per customer. This includes a maximum of $250,000 for claims involving cash. The limit does not mean every investor automatically receives $500,000.
- SIPC does not cover market losses. If a T-bill’s market value falls because interest rates or other market conditions change, SIPC does not reimburse that decline.
- A failed brokerage may not always require a full SIPC liquidation. In some cases, customer accounts can be transferred to another SIPC-member brokerage without a SIPC protection proceeding.
BOTTOM LINE: SIPC protection is designed to address missing eligible customer securities and cash when a SIPC-member brokerage fails. It is not protection against changes in the market value of your T-bills.
Table of Contents
T-Bills and Brokerage Failure at a Glance
When you hold Treasury bills through a brokerage, two things should be kept separate: the Treasury security you own and the brokerage relationship through which it is held. If the brokerage fails, the issue is generally whether customer property can be returned and, when eligible property is missing, whether SIPC protection applies.
| Quick Fact | What It Means |
|---|---|
| What you hold | A Treasury security recorded in your brokerage account |
| If the brokerage fails | Customer accounts may be transferred, or a SIPC liquidation may occur if required |
| SIPC limit | Up to $500,000 per customer, including up to $250,000 for cash claims |
| Market loss | Not protected by SIPC |
| Membership check | Confirm that the relevant brokerage and, where applicable, clearing firm are SIPC members |
Best For Investors Who Want to Understand the Protection Layers
The simplest way to look at brokerage-held T-bills is to separate the investment from the account provider. The Treasury bill remains a Treasury security, while SIPC focuses on certain customer cash and securities held by a failed SIPC-member brokerage. Those are different layers of protection.
QUICK TAKE: A brokerage failure does not by itself mean your T-bills have lost their value or Treasury status. The practical concern is whether the brokerage can account for and return customer property and, if eligible property is missing, whether SIPC protection applies.
T-Bills at a Brokerage: Complete Beginner Guide
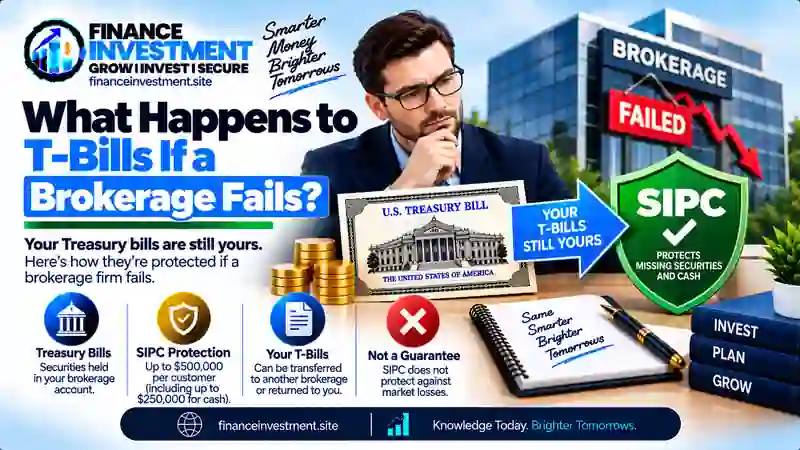 Buying Treasury bills through a brokerage can look similar to buying a stock, but the investment itself is different. A T-bill is a short-term debt security issued by the U.S. Treasury. The brokerage provides the account and services used to purchase and hold that security.
What You Actually Hold
When you buy a T-bill through a brokerage, the Treasury—not the brokerage—is the issuer of the security. The brokerage account records your position and provides the custody and trading relationship. Securities can be held in different registration arrangements, including customer-name or street-name form, depending on the account structure.
If you are new to T-bills, our guide to how Treasury bills work explains how the purchase price, maturity value, and return fit together.
Why the Brokerage Still Matters
Even though the Treasury issues the T-bill, the brokerage handles the account through which you hold it. If that brokerage fails, the key question is whether customer property can be accounted for and returned. If a SIPC-member brokerage fails and eligible customer securities or cash are missing, SIPC may provide protection for the resulting shortfall, subject to the applicable rules and limits.
What SIPC Does—and Does Not—Cover
SIPC can provide advances of up to $500,000 per customer, including up to $250,000 for cash claims, when the statutory requirements are met. The limit is designed to address a shortfall in eligible customer property; it does not mean every investor automatically receives $500,000.
Just as important, SIPC does not protect against a decline in the market value of your T-bill. If you sell before maturity and the price is lower because interest rates or other market conditions have changed, that investment loss is not covered by SIPC.
BEGINNER TIP: Think about the arrangement in two layers: the T-bill is the Treasury security, while the brokerage provides the account and custody relationship. A brokerage failure and a change in the T-bill’s market price are separate risks.
How T-Bills Are Protected When a Brokerage Fails
A brokerage failure does not automatically mean that investors must wait for a SIPC payout. U.S. rules require broker-dealers to segregate customer securities and cash from the firm’s own assets, with the goal of making customer property available for return if the firm fails. If a SIPC-member brokerage cannot meet its obligations, a customer-account transfer or SIPC liquidation may follow, depending on the circumstances.
Step 1: Customer Property Is Identified
The trustee reviews the brokerage’s books and records to determine what each customer is entitled to receive. Your account statements, trade confirmations, and other records can help establish the securities and cash connected with your account. This is why keeping accurate records and reviewing statements matters.
Step 2: Accounts May Be Transferred
When practical, a trustee may arrange for some or all customer accounts to be transferred to another SIPC-member brokerage. If your account is transferred, you may continue to hold your securities through the new firm rather than going through a lengthy liquidation process for the account itself. Even after a transfer, customers may still need to file a claim if the transfer does not make the account whole.
Step 3: A Trustee Handles a Liquidation When Necessary
If liquidation is required, a court-appointed trustee works to return customer property and process valid claims. Customer-name securities can be delivered to the customer in whose name they are registered, while other customer property may be pooled and distributed under the SIPA process.
Step 4: SIPC Can Address a Shortfall
If eligible customer property is missing, SIPC may provide an advance of up to $500,000 per customer, including up to $250,000 for cash claims, subject to the applicable rules. Treasury securities are among the securities SIPC protects. This protection addresses a shortfall caused by a qualifying brokerage failure; it does not protect against a decline in the market value of a T-bill.
IMPORTANT DISTINCTION: There are two separate questions: Can the brokerage return your customer property? And, if eligible property is missing, does SIPC protection apply? Neither question changes the market value of the T-bills themselves.
Benefits and Drawbacks of Brokerage T-Bills
Holding Treasury bills through a brokerage can make them easier to manage alongside other investments. At the same time, the brokerage account introduces a separate layer of custody and account-related considerations. Knowing both sides can help you understand what you are actually relying on.
✓ Potential Benefits
- One investment account: T-bills can be managed alongside stocks, bonds, ETFs, and other securities in the same brokerage account.
- Convenient account records: Purchases, holdings, sales, and maturity information can appear within your regular brokerage records.
- Access to the secondary market: A brokerage can provide a way to sell a T-bill before maturity, although the price you receive can change with market conditions.
- SIPC protection may apply: If a SIPC-member brokerage fails and eligible customer securities or cash are missing, SIPC may provide protection for the resulting shortfall, subject to statutory limits and other requirements.
△ Potential Drawbacks
- SIPC does not cover market losses: If your T-bill declines in market value, SIPC does not reimburse that investment loss.
- A brokerage failure can cause disruption: Accounts may need to be transferred, or a liquidation and claims process may be required when customer property is missing.
- Trading costs can matter: Brokerage commissions, spreads, markups, markdowns, or other transaction costs may affect what you receive when buying or selling in the secondary market.
- SIPC protection has conditions: The brokerage must be a SIPC member, and the protection applies to qualifying customer securities and cash under the rules of SIPA.
PRACTICAL TAKE: A brokerage can make T-bills convenient to manage, but convenience is not the same as investment protection. Before buying, check the firm’s SIPC membership, understand its trading costs, and know whether you may need to sell the T-bill before maturity.
SIPC vs. FDIC vs. Treasury Protection
SIPC, FDIC insurance, and Treasury backing are not three versions of the same protection. They apply to different financial products and different situations. SIPC addresses certain missing customer securities and cash when a qualifying brokerage fails. FDIC insurance protects eligible deposits at FDIC-insured banks. Treasury backing refers to the U.S. government’s obligation on Treasury securities such as T-bills.
| Protection or Backing | Applies To | What It Addresses |
|---|---|---|
| SIPC | Eligible securities and qualifying cash held at a SIPC-member brokerage | Missing customer property after a qualifying brokerage failure |
| FDIC insurance | Eligible deposits at an FDIC-insured bank | Covered deposit losses when an insured bank fails |
| Treasury backing | U.S. Treasury securities such as T-bills | The U.S. government’s obligation to honor the security according to its terms |
What This Means for Brokerage-Held T-Bills
Suppose you hold T-bills in a brokerage account and the brokerage later fails. The T-bills remain Treasury securities. If the brokerage is a SIPC member and eligible customer securities or cash are missing, SIPC may provide protection for the resulting customer-property shortfall. Treasury securities are specifically included among the securities SIPC protects. The standard SIPC limit is up to $500,000 per customer, including up to $250,000 for cash claims, subject to the applicable rules.
FDIC insurance works differently. If a brokerage uses a bank sweep program, unused cash may be moved into a bank deposit that can receive FDIC insurance under applicable rules. That does not make your separately held T-bills FDIC insured.
There is another important boundary: SIPC does not protect against a decline in the market value of a security. So if your T-bill’s market price falls because interest rates or other market conditions change, that investment loss is not a SIPC claim.
EASY WAY TO REMEMBER: SIPC = certain brokerage-failure losses involving missing customer property. FDIC = eligible bank deposits. Treasury backing = the U.S. government’s obligation on Treasury securities.
Limits, Risks and Practical Tips
SIPC protection can be valuable when a brokerage fails, but it is not unlimited insurance. The standard protection is up to $500,000 per customer, including a maximum of $250,000 for cash claims. The amount actually available depends on the customer’s eligible claim, the customer-property shortfall, and the applicable SIPC rules.
Know the Main Limits
- SIPC is not market-loss insurance. If your T-bill falls in market value, SIPC does not reimburse that investment loss.
- The brokerage must qualify for SIPC protection. SIPC protection applies when the relevant brokerage is a SIPC member and the other legal requirements are met.
- Different account capacities can matter. Accounts held in separate capacities can receive separate SIPC limits, while accounts held in the same capacity at the same firm are generally combined for the protection limits.
Practical Tips for T-Bill Investors
- Verify SIPC membership before keeping a large T-bill position at a brokerage.
- Save account statements and trade confirmations so you can document your holdings if a problem occurs.
- Understand your cash position. Uninvested cash, money market funds, and bank sweep deposits can receive different types of protection.
- Know your broker and clearing firm. Review which firms actually hold or clear your account and understand the account structure.
- Do not confuse SIPC protection with a guarantee of value. The purpose is to address certain missing customer securities and cash after a qualifying brokerage failure.
PRACTICAL TAKE: Before buying T-bills through a brokerage, check three things: SIPC membership, account structure, and what happens to your uninvested cash. Those details help you understand the protection that may apply if the brokerage later fails.
Common Mistakes and Real-Life Example
Many T-bill investors focus on the Treasury security itself and overlook the brokerage relationship. That can create confusion if the brokerage later fails. Understanding the difference between returning customer property and covering a shortfall makes the process easier to follow.
Common Mistakes to Avoid
- Assuming SIPC works like FDIC insurance: SIPC addresses certain missing customer securities and cash after a qualifying brokerage failure. It does not protect against investment losses.
- Assuming every brokerage account is automatically protected: The brokerage must be a SIPC member, and the customer and property must meet the applicable requirements.
- Confusing T-bills with cash: A T-bill is a Treasury security. Uninvested brokerage cash can have different protection depending on how it is held.
- Ignoring account records: Statements, trade confirmations, and other records can help establish what securities and cash are connected with your account.
Real-Life Example: A $300,000 T-Bill Position
Imagine an investor holds $300,000 of Treasury bills through a SIPC-member brokerage. The brokerage later fails, but its records and custody systems show that the investor owns those T-bills. If the securities can be located and returned, the investor generally receives the securities rather than a SIPC payment for their market value. Treasury securities are among the securities covered by SIPC protection.
Now assume some eligible customer property is missing. SIPC may provide an advance toward the qualifying shortfall, subject to the applicable protection limits. The standard limit is up to $500,000 per customer, including up to $250,000 for cash claims. This does not mean an investor automatically receives $500,000.
Finally, suppose the T-bills are worth less in the secondary market because interest rates changed. That is a separate investment risk. SIPC does not cover a decline in market value. The example shows why brokerage failure, missing customer property, and ordinary market-price changes should not be treated as the same event.
KEY LESSON: If a brokerage fails, first determine whether your T-bills and other customer property can be returned. If eligible property is missing, then SIPC protection may address the qualifying shortfall, subject to its rules and limits.
Who Should Consider Brokerage T-Bills?
Brokerage-held T-bills may be relevant for investors who want to manage Treasury securities alongside stocks, bonds, ETFs, or other investments in one account. A brokerage can also provide access to Treasury purchases and, depending on the firm, a secondary market for selling before maturity.
This Setup May Fit Investors Who Value
- Account convenience: Keep T-bills and other investments together in one brokerage account.
- Trading access: Use brokerage tools to buy or sell Treasury bills, including before maturity when secondary-market access is available.
- Portfolio management: View Treasury holdings alongside the rest of the investment portfolio.
- Brokerage-based custody: Hold eligible Treasury securities through a SIPC-member brokerage, where SIPC protection may apply if the firm fails and eligible customer property is missing.
What to Check Before Buying
Compare the brokerage’s SIPC membership, clearing arrangement, trading costs, account structure, and treatment of uninvested cash. Investor.gov recommends checking whether the brokerage and clearing firm are SIPC members. If you prefer to hold Treasury securities directly rather than through a brokerage, compare that approach with your other Treasury bill options before making a decision.
KEY POINT: Brokerage-held T-bills can offer account convenience, but SIPC protection is a separate issue. It addresses certain missing customer securities and cash after a qualifying brokerage failure; it does not protect against normal investment losses.
Frequently Asked Questions
1. What happens to T-bills if a brokerage fails?
Your T-bills do not automatically become worthless if a brokerage fails. Customer accounts may be transferred to another SIPC-member brokerage, or a SIPC liquidation may occur if necessary. If eligible customer property is missing, SIPC may provide protection for a qualifying shortfall, subject to applicable rules and limits.
2. Are Treasury bills protected by SIPC?
Treasury securities are among the securities SIPC can protect when held through a qualifying SIPC-member brokerage. The protection is designed for certain missing customer securities and cash after a qualifying brokerage failure. It does not protect against a decline in the market value of the investment.
3. What is the SIPC protection limit for T-bills?
SIPC may provide protection of up to $500,000 per customer, including a maximum of $250,000 for cash claims. The limit is not an automatic payment. The amount available depends on the customer’s eligible claim, missing customer property, and the applicable SIPC rules.
4. Does SIPC protect T-bills from losing value?
No. SIPC does not protect against a decline in the market value of securities. If interest rates change and the secondary-market price of your T-bill falls, that investment loss is not covered by SIPC.
5. Are T-bills FDIC insured when bought through a brokerage?
No. T-bills are Treasury securities, not bank deposits, so FDIC deposit insurance does not apply to the T-bills themselves. A brokerage may separately offer a bank sweep program for uninvested cash. Eligible swept deposits may receive FDIC protection under applicable banking rules, but that protection is separate from the T-bills.
6. Can my T-bill account be transferred if my broker fails?
It may be. A closed SIPC-member brokerage may be able to transfer customer accounts to another SIPC-member brokerage without a SIPC protection proceeding. If SIPC initiates a liquidation, a trustee may also work to transfer customer accounts when possible. The exact process depends on the circumstances.
7. What should I check before holding T-bills at a brokerage?
Check whether the brokerage is a SIPC member, understand its clearing arrangement, review how uninvested cash is held, and keep your account statements and trade confirmations. Investor.gov recommends checking the brokerage firm and its clearing firm for SIPC membership.
8. Is TreasuryDirect different from holding T-bills at a brokerage?
Yes. TreasuryDirect and brokerage accounts are different ways to hold Treasury securities. A brokerage account involves a brokerage and custody relationship and may involve SIPC protection if the firm qualifies. TreasuryDirect is a separate Treasury account. Investors should compare the account structure, access, and features that matter to them before choosing where to hold T-bills.
FAQ TAKEAWAY: Treasury backing, SIPC protection, and FDIC insurance are different concepts. Treasury backing relates to the Treasury security itself. SIPC addresses certain missing customer securities and cash when a qualifying brokerage fails. FDIC insurance applies to eligible bank deposits.
Final Verdict: What Happens to T-Bills If a Brokerage Fails?
What happens to T-bills if a brokerage fails? A brokerage failure does not automatically make your Treasury bills worthless. If the brokerage is a SIPC member, customer accounts may be transferred to another brokerage, or a SIPC liquidation may occur when necessary. If eligible customer property is missing, SIPC may provide an advance toward the qualifying shortfall, subject to applicable rules and limits.
The key distinction is between brokerage-failure risk and investment risk. SIPC protection can address certain missing customer securities and cash when a qualifying brokerage fails, but it does not protect against a decline in the market value of your T-bills. The standard SIPC protection limit is up to $500,000 per customer, including up to $250,000 for cash claims.
Before holding a large T-bill position at a brokerage, review the firm’s SIPC membership, clearing arrangement, account structure, and treatment of uninvested cash. Investor.gov recommends checking both the brokerage firm and its clearing firm for SIPC membership.
BOTTOM LINE: A brokerage failure is mainly a custody and customer-property issue. If eligible T-bills are properly accounted for, they may be returned or transferred. If eligible customer property is missing, SIPC may address the qualifying shortfall. SIPC does not guarantee the market value of the investment.
Have a Money Question? Keep Exploring.
Knowing how your T-bills are held can help you understand the protection that may apply if a brokerage fails. Keep exploring practical Treasury bill and personal finance guides from FinanceInvestment.
Leave a Reply