Are Treasury Bills FDIC Insured?
Are Treasury Bills FDIC Insured? Here’s What Investors Need to Know
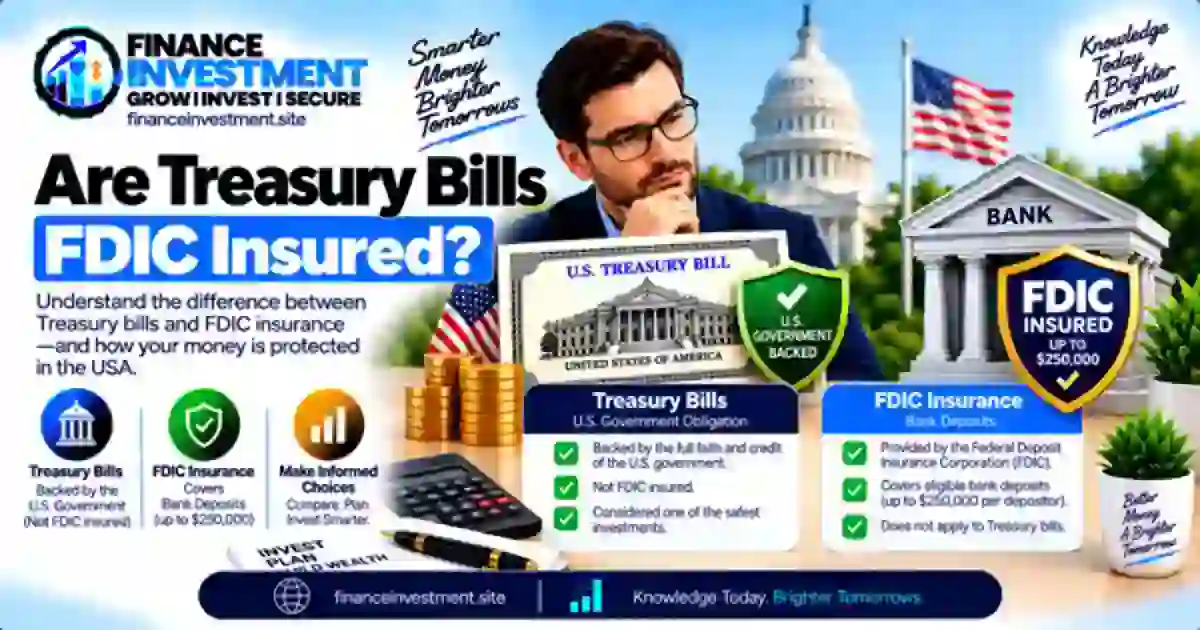 Are Treasury Bills FDIC Insured? No. Treasury bills are not covered by FDIC deposit insurance because they are securities, not bank deposits. A T-bill is a short-term debt security issued by the U.S. Department of the Treasury and backed by the full faith and credit of the U.S. government.
That distinction is important when comparing T-bills with products such as savings accounts, money market deposit accounts, and CDs. FDIC insurance applies to eligible deposits held at FDIC-insured banks. It does not automatically cover an investment simply because you purchased it through a bank.
So, if you are considering Treasury bills for cash you may need in the near future, the right question is not simply whether they are “insured.” You also need to understand who issued the security, what backs it, how maturity works, and what risks remain before you invest.
What You’ll Learn
- Why Treasury bills are not covered by FDIC deposit insurance.
- How Treasury backing differs from FDIC deposit protection.
- What T-bills are and how their maturity structure works.
- How early sale, inflation, and market prices can affect your investment.
- How T-bills compare with FDIC-insured savings accounts, money market deposit accounts, and CDs.
- What you should know when buying Treasury bills through TreasuryDirect or a brokerage.
If you want to start with the basics, read our Treasury Bills Explained guide before going deeper into FDIC coverage.
Quick Answer: Are Treasury Bills FDIC Insured?
No. Treasury bills are not FDIC insured. They are U.S. Treasury securities, not bank deposit accounts, so they fall outside the FDIC deposit insurance system.
That does not mean Treasury bills have no government backing. T-bills are short-term debt obligations of the U.S. Treasury and are backed by the full faith and credit of the U.S. government. This is different from FDIC insurance, which protects qualifying deposits held at FDIC-insured banks.
Key Takeaways
- T-bills are not FDIC insured: FDIC deposit insurance does not cover U.S. Treasury bills.
- Treasury backing is different: T-bills are obligations of the U.S. government and are backed by its full faith and credit.
- Buying location does not change the security: A T-bill purchased through a bank or brokerage does not become an FDIC-insured deposit.
- Investment risks still exist: Selling before maturity, changing market prices, inflation, and reinvestment conditions can affect your results.
- SIPC is separate from FDIC: When applicable, SIPC protection addresses certain losses connected with a failed SIPC-member brokerage and missing customer assets. It does not protect against normal market losses.
The important distinction: FDIC insurance protects qualifying bank deposits, while Treasury bills are securities backed by the U.S. government’s credit. Understanding that difference makes it easier to compare T-bills with savings accounts, CDs, and other cash options.
Table of Contents
Treasury Bills at a Glance
Before comparing Treasury bills with FDIC-insured bank accounts, it helps to separate two different forms of protection. FDIC insurance applies to eligible bank deposits, while Treasury bills are U.S. government securities backed by the full faith and credit of the federal government.
| Feature | Treasury Bills | FDIC-Insured Deposit |
|---|---|---|
| FDIC insured? | No | Yes, when eligible |
| What is it? | U.S. Treasury security | Bank deposit |
| What backs it? | Full faith and credit of the U.S. government | FDIC deposit insurance, subject to applicable limits |
| Standard FDIC limit | Not applicable | $250,000 per depositor, ownership category, per insured bank |
| Maturity | Short-term; Treasury bills mature in one year or less | Depends on the deposit product |
QUICK TAKE: Treasury bills are not FDIC-insured deposits. Their backing comes from the U.S. government’s obligation on the security. An eligible savings account or CD at an FDIC-insured bank has a different protection structure because it is a bank deposit. The two should be compared based on their structure, liquidity, maturity, taxes, and investment risks—not simply by asking whether one is “insured.”
Treasury Bills: A Complete Beginner Guide
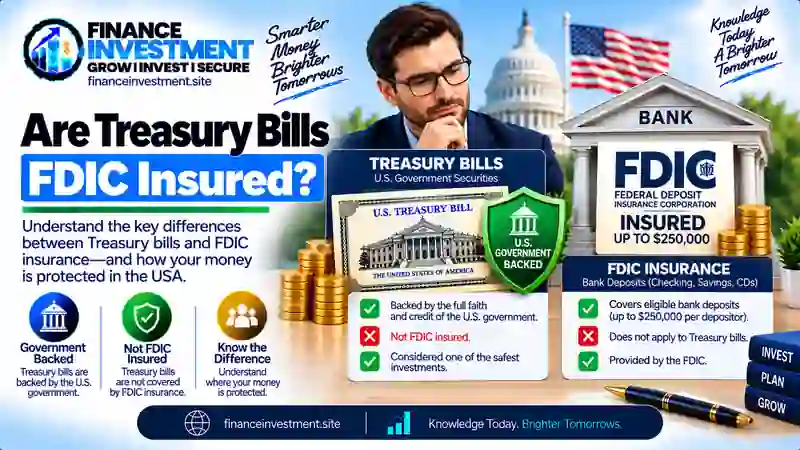 If you are new to Treasury bills, start with one simple idea: a T-bill is a short-term debt security issued by the U.S. Department of the Treasury. When you buy one, you are lending money to the U.S. government for a defined period. Treasury bills are short-term securities that can mature in a few days to 52 weeks.
How a T-Bill Works
Unlike a savings account or CD, a Treasury bill is a security rather than a bank deposit. T-bills are generally issued at a discount from their face value and do not make periodic coupon payments. For example, you could pay $9,800 for a $10,000 face-value bill and receive the $10,000 face value at maturity, with the difference representing the return before taxes and other considerations.
Because the U.S. Treasury issues these securities, Treasury bills carry the full faith and credit of the U.S. government. This is why U.S. Treasury securities are generally considered to have very low credit risk. However, that government backing is not the same thing as FDIC insurance.
Where Can You Buy Treasury Bills?
Individual investors can buy Treasury securities through TreasuryDirect or through a bank or brokerage. The purchase channel does not turn the T-bill into a bank deposit. It remains a Treasury security even when held through a brokerage account.
What Happens at Maturity?
If you hold a T-bill until maturity, the Treasury pays the security’s face value according to its terms. If you sell before maturity, the market price can be higher or lower than the face value. Changes in interest rates can affect that price, so a T-bill intended for a specific cash need may be easier to manage when its maturity date matches the date you expect to need the money.
BEGINNER TIP: Keep two ideas separate: FDIC insurance applies to qualifying bank deposits, while Treasury bills are securities backed by the full faith and credit of the U.S. government. Knowing that difference prevents one of the most common T-bill misconceptions.
How FDIC and Treasury Protection Works
The easiest way to understand the difference is to start with what you own. FDIC insurance applies to qualifying deposits at FDIC-insured banks. Treasury bills are securities issued by the U.S. Department of the Treasury, so the T-bill itself is not covered by FDIC deposit insurance.
How FDIC Insurance Protects Bank Deposits
Eligible checking accounts, savings accounts, money market deposit accounts, and CDs at FDIC-insured banks can receive FDIC protection if the insured bank fails, subject to applicable rules and limits. The standard coverage amount is $250,000 per depositor, per ownership category, per insured bank.
How Treasury Backing Works
Treasury bills are backed by the full faith and credit of the U.S. government. This is government credit backing, not FDIC insurance. Treasury securities are generally considered to have very low credit risk, although investors can still face market-price, interest-rate, inflation, and early-sale risks.
What If You Hold T-Bills at a Brokerage?
Holding a T-bill through a brokerage introduces a separate layer of investor protection. If a SIPC-member brokerage fails and customer assets are missing, SIPC may protect eligible securities and cash, generally up to $500,000 per customer, including a $250,000 limit for cash, subject to the applicable rules. SIPC does not protect against market losses or a decline in the value of a T-bill.
SMART CHECK: FDIC insurance, Treasury backing, and SIPC protection address different situations. First identify whether you own a bank deposit, a Treasury security, or a security held through a brokerage. Then look at the specific protection and risks that apply.
Benefits and Drawbacks of Treasury Bills
Treasury bills can be useful for investors looking for short-term exposure to U.S. government debt. But their benefits should not be confused with FDIC insurance. T-bills have their own maturity, liquidity, tax, and market considerations.
Potential Benefits
- U.S. government backing: Treasury bills are backed by the full faith and credit of the U.S. government.
- Short maturities: T-bills mature in a few days to 52 weeks, giving investors several short-term time frames to consider.
- Known maturity value: When held to maturity, a T-bill pays its face value according to its terms. The return comes from the difference between the purchase price and face value.
- State and local tax benefit: Interest income from U.S. Treasury securities is generally exempt from state and local income taxes, although federal income tax generally applies.
Potential Drawbacks
- No FDIC insurance: A T-bill is a security, not a bank deposit, so FDIC deposit insurance does not cover it.
- Early-sale risk: If you sell before maturity, the market price can be higher or lower than your purchase price or the bill’s face value.
- Inflation risk: Inflation can reduce the purchasing power of the return you earn.
- Reinvestment risk: When a T-bill matures, available rates on a new T-bill may be higher or lower than the rate you previously received.
WHAT TO REMEMBER: Treasury bills combine short maturities with U.S. government backing, but they are not FDIC-insured deposits. Before buying one, consider when you need the money, whether you may sell early, and how taxes, inflation, and future reinvestment rates could affect the result.
FDIC Insurance vs. Treasury Safety
FDIC insurance and Treasury backing are sometimes discussed together when investors compare places to keep money, but they protect against different situations. FDIC insurance applies to eligible bank deposits, while Treasury bills are securities backed by the full faith and credit of the U.S. government. Treasury bills themselves are not FDIC insured.
| Factor | Treasury Bills | FDIC-Insured Deposits |
|---|---|---|
| What you own | U.S. Treasury security | Bank deposit |
| FDIC coverage | No | Yes, when eligible and within applicable limits |
| What provides protection or backing? | Full faith and credit of the U.S. government | FDIC deposit insurance |
| Standard FDIC limit | Not applicable | $250,000 per depositor, ownership category, per insured bank |
| Price risk before maturity | Yes, if sold before maturity | A bank deposit does not trade like a Treasury security |
Why the Difference Matters
Suppose you buy a T-bill through a bank. The bank’s FDIC-insured status does not turn that T-bill into an FDIC-insured deposit. The investment remains a Treasury security. The same principle applies when you purchase a T-bill through a brokerage.
A brokerage account can involve SIPC protection when the brokerage is a SIPC member and the requirements for coverage are met. SIPC may protect eligible customer securities and cash when a member brokerage fails and assets are missing, subject to legal limits. It does not protect against a decline in the market value of a Treasury bill.
THE SIMPLE VERSION: FDIC insurance covers qualifying bank deposits when an insured bank fails. Treasury bills are U.S. government securities backed by the government’s full faith and credit. SIPC, when applicable, addresses certain brokerage-firm failures. These are separate protection systems.
Costs, Risks and Practical Tips
Treasury bills can be relatively simple to buy, but investors should look beyond the quoted yield. Your costs and results can depend on how you purchase the security, whether you hold it until maturity, and what happens to interest rates and taxes during the investment period.
Costs to Watch
- TreasuryDirect purchase cost: TreasuryDirect states that it charges no purchase fee or commission when you buy Treasury securities directly through the platform.
- Brokerage transaction costs: Depending on the broker and transaction, you may encounter commissions, markups, markdowns, or other account-related charges.
- Taxes: Income from Treasury securities is generally subject to federal income tax but may be exempt from state and local income taxes.
Risks to Understand
If you sell a T-bill before maturity, its market price can be different from what you originally paid. Changes in interest rates can move that price, and a broker may apply a commission or markdown to the transaction. Inflation can also reduce the purchasing power of your return.
PRACTICAL TIP: If you already know when you will need the money, consider a T-bill maturity that fits that time frame. If you may need the money earlier, check the possible selling costs and understand that the market price can differ from the amount you would receive at maturity.
Common Treasury Bill Mistakes and a Real-Life Example
Many T-bill mistakes happen because investors treat a Treasury security like a bank deposit. Understanding the difference between FDIC insurance, Treasury backing, and market pricing can help you avoid common surprises.
Common Mistakes to Avoid
- Assuming T-bills are FDIC insured: Treasury bills are securities, not FDIC-insured bank deposits.
- Confusing government backing with insurance: The U.S. government’s full faith and credit is different from FDIC deposit coverage.
- Ignoring the maturity date: Selling before maturity can expose you to changes in market price and possible transaction costs.
- Thinking the purchase channel changes the protection: Buying a T-bill through a bank or brokerage does not turn it into an FDIC-insured deposit.
- Forgetting reinvestment risk: When a T-bill matures, the rate available on a new T-bill may be different from the previous rate.
Real-Life Example
Imagine Maria has $10,000 that she expects to need in about six months. She buys a Treasury bill with a maturity that fits that time frame and plans to hold it until maturity. The T-bill is not FDIC insured, but it is a U.S. government security backed by the government’s full faith and credit. If Maria sells before maturity, its market price could be higher or lower than what she paid and could also differ from its face value.
For example, if market interest rates rise after Maria buys the T-bill, its market price could fall. If rates decline, the market price could rise. Her result from an early sale would therefore depend on the market price at that time, along with any applicable transaction costs.
SMART CHECK: Before buying, confirm three things: what you are buying, when you need the money, and what could happen if you sell before maturity. This helps you avoid treating a Treasury bill like a bank deposit.
Who Should Consider Treasury Bills?
Treasury bills can be relevant for investors looking for short-term U.S. government securities and who have a reasonably clear idea of when they may need the money. Their short maturities allow investors to match a security with a planned cash need, while their government backing distinguishes them from bank deposits and corporate debt.
T-Bills May Be Relevant When You:
- Want exposure to a short-term U.S. government security.
- Have a planned or estimated cash need that matches a T-bill’s maturity.
- Want Treasury income that is generally exempt from state and local income taxes.
- Understand that a T-bill is a security rather than an FDIC-insured bank deposit.
- Want to spread cash across different Treasury maturity dates.
When a Bank Deposit May Better Match the Need
If immediate access to cash or FDIC deposit insurance is an important requirement, an eligible bank deposit may offer a different structure. A savings account, money market deposit account, or qualifying CD does not have the same market-price mechanics as a Treasury security sold before maturity. The appropriate choice depends on your time horizon, liquidity needs, taxes, and risk considerations.
A USEFUL CHECK: Before buying a T-bill, compare its maturity with the date you expect to need the money. If your plans change, remember that selling before maturity can expose you to market-price changes and transaction costs.
Frequently Asked Questions About Treasury Bills and FDIC Insurance
1. Are Treasury bills FDIC insured?
No. Treasury bills are U.S. government securities, not bank deposits, so they are not covered by FDIC deposit insurance.
2. If T-bills are not FDIC insured, are they government backed?
Yes. Treasury bills are debt obligations of the U.S. Treasury and carry the full faith and credit of the U.S. government. This is different from FDIC insurance.
3. How does Treasury backing differ from FDIC insurance?
FDIC insurance protects qualifying bank deposits at insured institutions, subject to applicable coverage rules and limits. Treasury backing refers to the U.S. government’s obligation on Treasury securities. The two are separate protection systems.
4. Does buying a T-bill through a bank make it FDIC insured?
No. The purchase channel does not change the underlying security. A T-bill remains a Treasury security even when purchased through an insured bank.
5. Are Treasury bills protected by SIPC?
SIPC does not protect a T-bill against market losses. If a SIPC-member brokerage fails and customer securities or cash are missing, SIPC may provide protection subject to its rules and limits.
6. Can I lose money on a Treasury bill?
If you hold a T-bill until maturity, the Treasury pays its face value according to the security’s terms. Selling before maturity can produce a gain or loss because market prices can change.
7. Are Treasury bill earnings subject to taxes?
Income from Treasury securities is generally subject to federal income tax but may be exempt from state and local income taxes. Individual tax situations can vary.
8. What is the difference between FDIC insurance and Treasury backing?
FDIC insurance protects qualifying deposits at insured banks, subject to coverage rules and limits. Treasury backing refers to the U.S. government’s obligation on Treasury securities. They are separate protection systems.
FAQ QUICK CHECK: The key distinction is simple: FDIC insurance covers qualifying bank deposits, while Treasury bills are U.S. government securities backed by the government’s full faith and credit.
Final Takeaway: Are Treasury Bills FDIC Insured?
No, Treasury bills are not FDIC insured. FDIC insurance applies to qualifying deposits at FDIC-insured banks. Treasury bills are non-deposit investment products issued by the U.S. Department of the Treasury and are backed by the full faith and credit of the U.S. government. These are two different systems and should not be treated as interchangeable.
This distinction still matters when a T-bill is purchased through a bank. The bank’s FDIC-insured status does not make the Treasury security an FDIC-insured deposit. The same underlying security remains a Treasury bill when purchased through a brokerage.
T-bills have short maturities and can be sold before maturity, but an early sale can expose you to changing market prices. Income from Treasury securities is generally subject to federal income tax and may be exempt from state and local taxes.
THE BOTTOM LINE: When evaluating a Treasury bill, separate two questions: Is it FDIC insured? No. What backs the security? The full faith and credit of the U.S. government. Understanding that distinction helps you compare T-bills with bank deposits without confusing insurance with government credit backing.
For a broader explanation of how T-bills work, see our Treasury Bills Explained guide.
Have a Money Question? Keep Exploring.
Questions about Treasury bills, FDIC insurance, or other ways to manage your cash? FinanceInvestment provides practical guides designed to make financial topics easier to understand.
📩 Get in Touch With FinanceInvestment
Have a question or a topic you’d like us to cover?
Leave a Reply