Tag: Recurring Payments

  • Why Did My Automatic Bill Payment Fail? 9 Reasons

    Why Did My Automatic Bill Payment Fail? 9 Reasons

    Why Did My Automatic Bill Payment Fail? 9 Common Reasons and How to Fix Them
    SR
    Subhash Rukade
    Founder, FinanceInvestment
    PUBLISHED
    November 01, 2026
    LAST UPDATED
    November 01, 2026
    READING TIME
    11 minutes

    why did my automatic bill payment fail

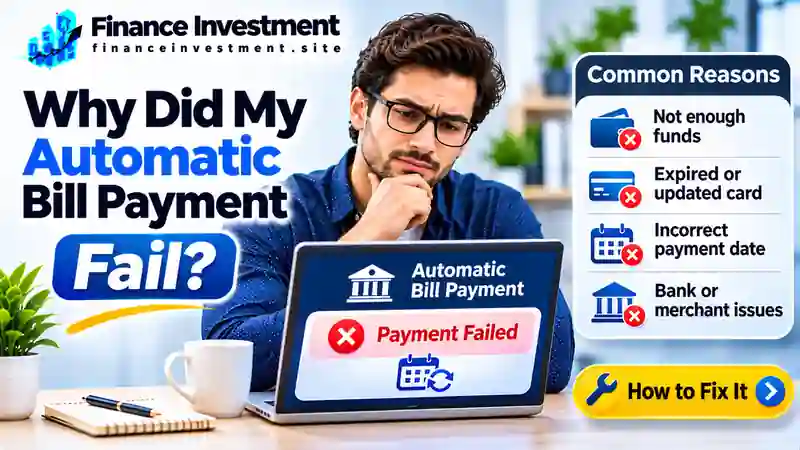
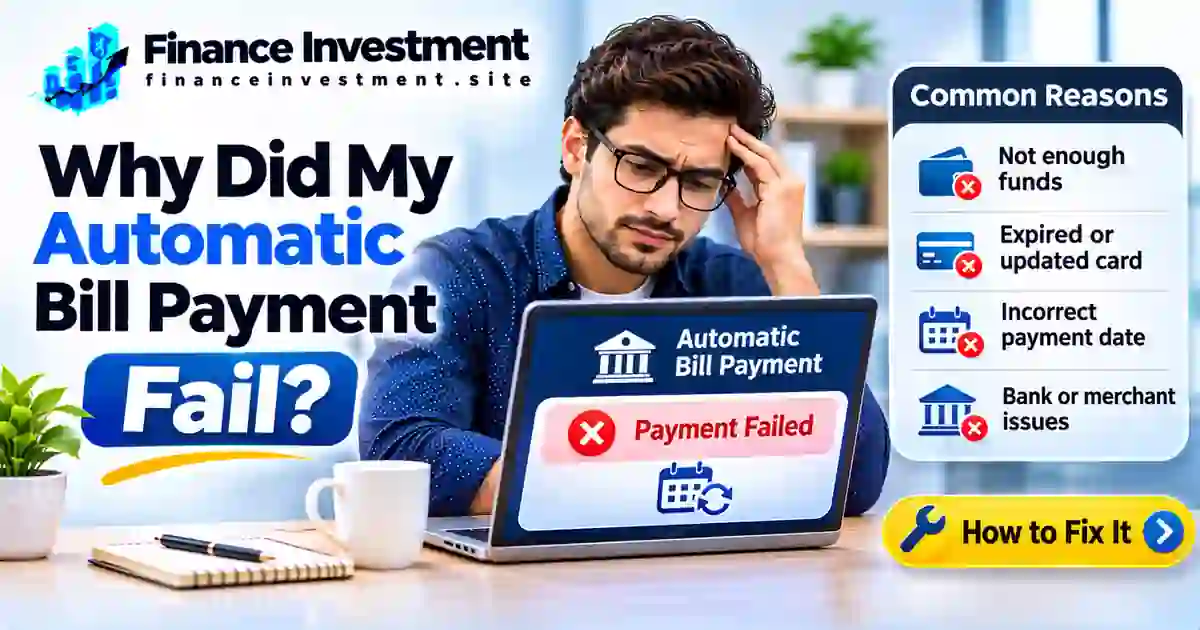
    Why Did My Automatic Bill Payment Fail?

    You scheduled your electricity, insurance, or credit card bill to be paid automatically. The due date arrives, but instead of a payment confirmation, you receive a failed-payment alert. If you’re asking, why did my automatic bill payment fail when everything seemed to be set up correctly, the problem could be with your bank account, payment details, debit card, or the billing company’s payment system.

    Insufficient funds are one possible explanation, but they are not the only one. An expired card, incorrect account information, a bank security block, or a processing delay can also interrupt a scheduled payment. The cause often depends on whether you authorized an ACH withdrawal, scheduled bill pay through your bank, or used a recurring card payment.

    We’ll help you identify where the payment went wrong, understand what to check first, and avoid unnecessary fees or duplicate payments. For more background, explore our complete guide to bank transfers and payments.

    What You’ll Learn

    • Nine common reasons automatic bill payments fail.
    • How ACH, bank bill pay, and recurring card payments differ.
    • What to check when a payment is declined, pending, or returned.
    • How to resolve a failed payment and reduce the risk of late fees.

    Quick Answer: Why Did Your Automatic Bill Payment Fail?

    Your automatic bill payment may have failed because of insufficient available funds, outdated bank details, an expired card, a bank security block, an account restriction, or a problem with the billing company’s payment system. Check your bank transaction history and the biller’s payment status to identify what happened. Before paying again, confirm that the original transaction is not still processing.

    Key Takeaways

    • A low available balance can cause an automatic withdrawal to be rejected, even when your account shows money.
    • An expired debit card or incorrect account information can interrupt scheduled payments.
    • ACH debits, bank bill pay, and recurring card charges have different failure points.
    • A pending transaction does not automatically mean the payment has failed.
    • Depending on the bank and biller’s policies, a failed payment may result in additional fees.
    • Checking the transaction status before retrying can help prevent duplicate payments.

    Bottom Line: A scheduled payment is not proof that your bill was paid. Confirm the transaction, identify the reason for the failure, and arrange payment before the due date or contact the biller if the deadline has passed.

    Automatic Bill Payment: Key Facts at a Glance

    Quick overview: An automatic payment can be interrupted by a problem with your bank account, payment method, payment network, or biller’s system. Identifying where the transaction stopped is the first step toward fixing it.

    What to CheckWhy It Matters
    Available balancePending transactions or account holds may leave less money available than your displayed balance suggests.
    Bank account detailsIncorrect or outdated account information can prevent an ACH withdrawal from reaching the right account.
    Debit or credit cardAn expired, replaced, or blocked card may cause a recurring card charge to be declined.
    Transaction statusA pending transaction may still be processing, while a returned or declined payment needs further attention.
    Bank and biller alertsNotifications may identify a security block, payment rejection, or other issue requiring action.

    Best for: Families managing household bills, retirees paying recurring expenses from a fixed income, and anyone handling insurance, loan, utility, or credit card payments automatically.

    Remember: A delayed payment is not always a failed payment. Check the bank’s transaction details and the biller’s records before attempting another payment.

    A Beginner’s Guide to Failed Automatic Bill Paymentswhy did my automatic bill payment fail

    When an automatic payment fails, start by identifying who was supposed to send the money. A payment arranged through your bank works differently from a withdrawal initiated by a billing company. Knowing the difference helps you find the right place to investigate.

    1. Automatic ACH Debit

    An ACH debit allows a company, such as an insurance provider or utility company, to request money directly from your checking account. The transaction may be returned because of insufficient funds, a closed account, incorrect account information, or an authorization issue. Learn more in our guide to how ACH transfers work.

    2. Bank-Scheduled Bill Pay

    With this option, you ask your bank or credit union to pay a company on your behalf. Depending on the bank and recipient, it may send an electronic payment or mail a paper check. Incorrect payee details, an unsuitable delivery date, insufficient funds, or a delayed check can prevent the bill from being paid on time.

    3. Recurring Debit or Credit Card Payment

    Here, the billing company charges the card saved to your account. A charge may be declined if the card expires, is replaced and its details are not updated, has insufficient available credit, or is blocked by the card issuer’s security checks.

    Practical tip: Check the payment method and transaction description before contacting support. If your bank initiated the payment, start with the bank. If the company charged your stored card or requested an ACH debit, contact the biller as well.

    How Automatic Bill Payment Processing Works

    An automatic bill payment passes through several steps before the biller receives the money. The exact process depends on whether the payment is initiated by the billing company, your bank, or your card issuer.

    Step 1: You Authorize or Schedule the Payment

    You provide your bank account details for an ACH debit, schedule a payment through your bank’s bill-pay service, or save a debit or credit card with the billing company for recurring charges.

    Step 2: The Payment Request Is Sent

    For an ACH debit, the biller submits a withdrawal request through its financial institution. With bank bill pay, your bank arranges delivery to the payee, electronically or by paper check. For a recurring card charge, the merchant sends a transaction request through the card network to the card issuer.

    Step 3: The Financial Institution Processes It

    The bank or card issuer checks the relevant account or card details and applies its available-funds, authorization, and security controls. An ACH request may be rejected or later returned. A card transaction may be declined during authorization. A bank bill-pay instruction may also be delayed or rejected before delivery.

    Step 4: Confirm the Payment Result

    Check your bank activity and the biller’s records to confirm whether the payment was completed. ACH transactions follow processing schedules, so weekends and federal holidays can affect timing. A card authorization may appear before the final transaction is posted.

    Remember: Scheduling a payment, receiving an authorization, and completing a payment are not necessarily the same event. Always verify the final status before assuming your bill has been paid.

    Benefits and Drawbacks of Automatic Bill Payments

    Automatic bill payments can simplify monthly finances, especially when you have several recurring expenses. However, convenience does not guarantee successful payment. Your account balance, payment details, and billing activity still need occasional attention.

    Benefits of Automatic Payments

    • Fewer manual reminders: Scheduled payments reduce the need to remember every monthly due date.
    • More consistent bill handling: Payments can arrive on time when the account is funded and the payment details are valid.
    • Simpler budgeting: Knowing recurring payment dates helps you plan upcoming household expenses.

    Drawbacks to Watch For

    • Payment interruptions: Insufficient available funds, expired cards, or incorrect details can cause a scheduled payment to fail.
    • Unexpected withdrawals: You may overlook a changed bill amount or a recurring charge you did not expect.
    • Extra costs: A failed payment may lead to returned-payment charges, late fees, or service interruption, depending on the account and provider policies.

    A sensible balance: Use automation to handle routine bills, but review upcoming withdrawals, maintain enough available funds, and pay attention to bank and biller notifications. A quick account check can help you catch a problem before it affects your next payment.

    ACH vs. Bank Bill Pay vs. Recurring Card Payment Failures

    The same bill can fail for different reasons depending on how you pay it. The key difference is who initiates the transaction and which financial institution processes it.

    Payment MethodWhy It May FailFirst Check
    ACH DebitInsufficient funds, closed account, invalid account details, or an ACH authorization problem.Available balance, bank transaction history, and the return or rejection notice.
    Bank Bill PayIncorrect payee details, scheduling problems, insufficient funds, or delayed paper-check delivery.Bank payment history, payee information, and delivery confirmation.
    Recurring Card PaymentExpired or replaced card, insufficient available credit, spending restrictions, or a security decline.Card status, issuer notification, and billing account details.

    Where should you start? For an ACH debit, check with your bank and the company requesting the withdrawal. For bank bill pay, ask your bank whether the payment was sent and how it was delivered. For a recurring card charge, contact the card issuer about the decline and ask the billing company to verify its payment details.

    Automatic Payment Failure: Fees, Risks and Expert Tips

    A failed automatic payment can create costs beyond the original bill. What you may owe depends on your bank’s account terms, the billing company’s policy, and whether the unpaid bill is for a utility, credit card, loan, or another service.

    Possible Fees and Financial Risks

    • NSF or returned-payment fee: Your bank may charge a fee if it returns a payment because your account does not have enough available funds.
    • Overdraft fee: If your bank pays a transaction that exceeds your available balance, an overdraft fee may apply under your account agreement.
    • Late-payment fee: The biller may charge a fee if the payment remains unpaid after the due date.
    • Service or credit consequences: An unpaid bill could lead to service restrictions. A late credit card or loan payment may also affect your credit if it is reported to the credit bureaus.

    Some banks and billers may charge separate fees, but this is not automatic. Review your account agreement and billing terms. The CFPB’s guide to automatic bank payments explains how these withdrawals work and what to watch for.

    Important: Before paying manually, confirm whether the original transaction was declined, returned, or is still pending. Retrying too soon could result in duplicate payments if the first transaction later completes.

    Expert Tips to Prevent Repeat Failures

    • Keep enough available money for scheduled bills and pending transactions.
    • Update expired cards and changed bank account details.
    • Enable bank transaction alerts and review unusual activity.
    • Contact the biller promptly if a payment fails near its due date.

    Common Automatic Payment Mistakes and a Real-Life Example

    A scheduled payment can still go wrong when account activity is overlooked. These common mistakes can turn a simple payment issue into an overdue bill:

    • Assuming a scheduled payment has cleared without checking its status.
    • Looking only at the displayed balance instead of accounting for pending transactions and available funds.
    • Forgetting to update an expired or replaced payment card.
    • Ignoring a bank alert or a returned-payment notification.
    • Making another payment before confirming whether the original transaction is still processing.

    Illustrative Example: A Family’s Electricity Bill

    Imagine a family in Ohio schedules its $180 electricity bill through ACH debit. Several card purchases are pending, so the available balance is lower than the family expected. When the utility company’s withdrawal is processed, the bank returns it because sufficient funds are unavailable.

    The family overlooks the bank notification and assumes the bill was paid. A few days later, the utility company sends an overdue notice. The family must now confirm the returned payment, check for applicable charges, and arrange payment directly with the provider.

    What this example teaches: Check available funds before scheduled withdrawals and respond promptly to failed-payment alerts. Always verify the original transaction’s status before trying again.

    Who Should Pay Extra Attention to Automatic Payment Failures?

    Anyone using autopay can experience a failed transaction. However, a missed withdrawal can create greater pressure for households with tight budgets, multiple recurring bills, or income that does not arrive on a predictable schedule.

    Families Managing Multiple Household Bills

    Several utility, insurance, loan, and subscription payments may fall within the same week. Track their due dates and make sure enough money is available for the combined withdrawals.

    Retirees Living on a Fixed Income

    When retirement income arrives on a set schedule, an unexpected expense or delayed deposit can affect money reserved for essential bills. Keep a reasonable cash buffer where possible and monitor important payment dates.

    Beginners and New Bank Account Holders

    Entering an incorrect routing number or account number can disrupt an ACH payment. Verify both details with your bank before giving them to a billing company.

    Freelancers and People With Irregular Income

    Income may arrive on different dates each month, while bills follow fixed schedules. Where the provider allows it, choose payment dates that better match your expected cash flow.

    A useful habit: Review upcoming withdrawals, available funds, and payment alerts before major bill dates. This small routine can help you catch problems while there is still time to contact the bank or biller.

    Frequently Asked Questions About Failed Automatic Bill Payments

    1. Why did my automatic bill payment fail even though I had money?

    Your available balance may have been lower than your displayed balance because of pending transactions, account holds, or other withdrawals. A bank security block or incorrect payment details could also cause the transaction to fail.

    2. Will a failed automatic payment retry automatically?

    Not necessarily. Retry policies depend on the billing company, payment method, and reason for failure. Contact the biller to find out whether another attempt is scheduled.

    3. Can a bank reject an ACH payment?

    Yes. An ACH debit may be returned because of insufficient funds, a closed account, invalid account information, or certain authorization problems.

    4. Will I pay a fee if autopay fails?

    Possibly. Your bank or biller may charge an NSF, returned-payment, or late fee, depending on the account agreement and billing policy. Some failed payments do not result in a fee.

    5. Can a failed automatic payment affect my credit score?

    A failed transaction does not automatically lower your credit score. However, if an unpaid credit card or loan payment becomes seriously overdue and the creditor reports it to the credit bureaus, your credit history may be affected.

    6. How long does a failed ACH payment take to return?

    There is no single timeline for every ACH return. Timing depends on the return reason and processing schedule. Ask your bank or biller for the specific transaction status and expected update.

    7. Should I pay the bill manually after autopay fails?

    First confirm that the original transaction was declined or returned rather than still pending. Then ask the biller for the outstanding balance and arrange another payment if needed.

    8. What should I do if my bank blocks an automatic payment?

    Contact your bank through its official phone number or secure banking app. Ask why the transaction was blocked, complete any required verification, and confirm with the biller how to pay the outstanding bill.

    Final Verdict: What to Do When an Automatic Bill Payment Fails

    An automatic payment failure is a problem worth checking promptly, but it does not always mean your bank account has an issue. The cause could be insufficient available funds, outdated payment details, a card decline, or a processing problem.

    Start by checking your bank transaction history and the biller’s records. Confirm whether the payment was declined, returned, or is still pending. Once you know what happened, correct the issue, arrange payment for any outstanding balance, and get confirmation from the biller.

    Explore more banking guidance: Visit our Bank Transfers and Payments Guide to understand ACH transfers, payment delays, and common banking problems in greater detail.

    Stay Informed. Make Smarter Financial Decisions.

    Explore FinanceInvestment for practical banking guides, personal finance insights, and helpful updates to manage your money with greater confidence.
  • How to Stop an Automatic Bank Payment: Step-by-Step Guide

    How to Stop an Automatic Bank Payment: Step-by-Step Guide

    How to Stop an Automatic Bank Payment: A Step-by-Step Guide

    SR
    Subhash Rukade
    Founder, FinanceInvestment

    Published: November 01, 2026

    Updated: November 01, 2026

    Reading Time: 10 minutes


    how to stop an automatic bank payment

    How to Stop an Automatic Bank Payment Without Creating Another Problem

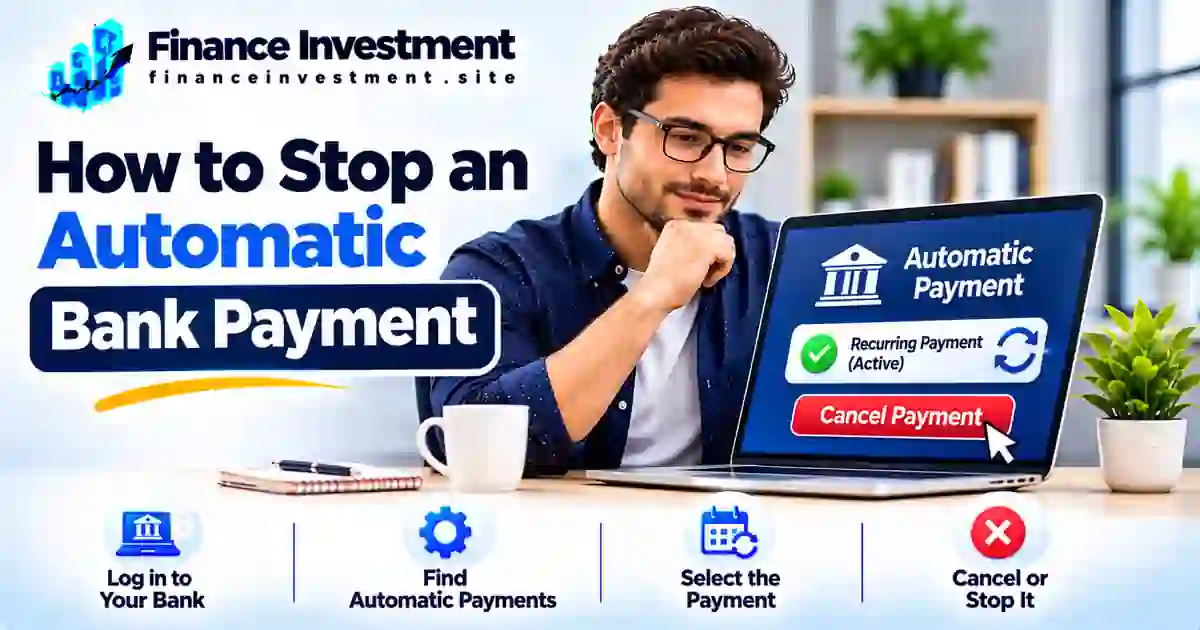
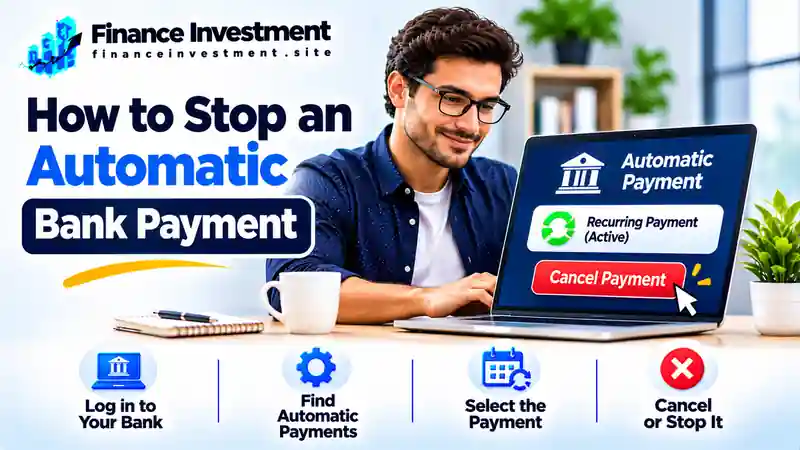
    A subscription you no longer use, a gym membership you cancelled, or a bill you want to pay manually can keep triggering withdrawals from your bank account. If you’re wondering how to stop an automatic bank payment, start by finding out how the payment was authorized and who is collecting it.

    The right cancellation method depends on the payment type. A payment scheduled through your bank may need to be cancelled with the bank. An automatic ACH debit may require you to revoke the company’s authorization and notify your bank. A recurring debit-card charge follows a different process.

    Act promptly, keep written proof of your request, and check whether another payment is already being processed. Most importantly, stopping a withdrawal does not automatically cancel the subscription, loan, or service agreement behind it. Our complete guide to bank transfers and payments explains the wider payment landscape.

    What You’ll Learn

    • How to identify the type of recurring payment.
    • How to cancel a payment with the company or your bank.
    • When to request a stop-payment order.
    • What to do if a withdrawal continues after authorization is revoked.
    • How to protect your account without overlooking an unpaid bill.

    Quick Answer: How Do You Stop an Automatic Bank Payment?

    Quick answer: First, identify how the payment is being collected. Cancel a bank-scheduled payment through your bank, contact the company to revoke authorization for recurring ACH debits, or follow the card issuer’s process for recurring card charges. If needed, ask your bank about a stop-payment order and applicable deadlines. Keep written proof and monitor your account for further withdrawals.

    Key Takeaways

    • Identify whether the payment is bank-scheduled, an ACH debit, or a recurring card charge.
    • Contact the company to cancel or revoke recurring payment authorization.
    • Ask your bank about stop-payment options, notice requirements, and deadlines.
    • Save confirmation numbers, emails, and cancellation records.
    • Report unauthorized withdrawals to your financial institution promptly.
    • Remember that stopping a withdrawal does not automatically cancel the underlying bill, loan, or service agreement.

    Bottom Line: Use the cancellation process that matches your payment type. Contact the responsible company or bank in time, keep proof of your request, and verify that future withdrawals have stopped.

    Automatic Bank Payments: Quick Facts at a Glance

    The right cancellation method depends on how the payment is set up. Identify the payment type before contacting your bank or the company.

    Start Here

    Identify the payment method

    ACH Payments

    Revoke authorization with the biller

    Bank Bill Pay

    Cancel through your bank

    Important Reminder

    Stopping payment does not cancel the underlying bill

    Which Payment Are You Trying to Stop?

    Payment TypeWhere to StartKey Action
    Bank-scheduled bill payYour bank or credit unionCancel the scheduled payment before its cutoff.
    Automatic ACH debitCompany or biller, then your bank if neededRevoke authorization and ask your bank about stopping future withdrawals.
    Recurring card paymentMerchant and card issuerCancel the recurring billing arrangement and ask your issuer about available protections.

    Important: A payment already processing may not be cancellable. Contact your bank promptly, keep written confirmation, and continue checking your account. You may still owe the bill even after automatic withdrawals stop.

    A Beginner’s Guide to Stopping Automatic Bank Paymentshow to stop an automatic bank payment

    Before you stop an automatic bank payment, identify how the money is being withdrawn. A payment scheduled through your bank works differently from a company-initiated ACH debit or a recurring debit-card charge. Choosing the correct cancellation method can help prevent another unwanted withdrawal.

    1. Bank-Scheduled Bill Payments

    With online bill pay, you ask your bank or credit union to send money to a company or individual on a specific date. You usually manage these payments through your banking app or website. To cancel one, find the scheduled transaction and check whether it is still eligible for cancellation. Once processing begins, your bank may not be able to stop it.

    2. Automatic ACH Debits

    An ACH debit occurs when a company initiates an electronic withdrawal from your bank account under an authorization you provided. Utility bills, insurance premiums, and loan payments commonly use this method. To stop future withdrawals, contact the company to revoke your authorization. Also notify your bank and ask about a stop-payment order if another withdrawal is scheduled. Read our guide on how ACH transfers work to understand the process.

    3. Recurring Debit-Card Payments

    Streaming services, memberships, and other subscriptions may charge your debit card automatically. Start by cancelling the recurring billing arrangement with the merchant and keeping its confirmation. If charges continue or you cannot resolve the issue, contact your card issuer about available options for blocking or disputing future charges.

    Beginner Tip: Check your bank statement for the payee name, transaction description, amount, and date. These details can help you identify the payment type and explain exactly which withdrawal you want to stop.

    How to Stop an Automatic Bank Payment: Step by Step

    After identifying the payment method, follow these steps to request cancellation, protect your account, and avoid confusion about upcoming withdrawals.

    1

    Identify the Automatic Payment

    Open your bank statement and note the payee name, transaction amount, date, and description. Determine whether the withdrawal is bank-scheduled bill pay, an ACH debit, or a recurring debit-card charge.

    2

    Check the Next Withdrawal Date

    Review the next scheduled payment and contact the responsible provider promptly. Ask whether the transaction is still scheduled, pending, or already being processed. Cancellation options may depend on its status and the provider’s cutoff time.

    3

    Cancel the Recurring Authorization

    For an ACH debit, contact the company and clearly revoke permission for future withdrawals. For a recurring debit-card charge, cancel the merchant’s recurring billing arrangement. Keep written confirmation, an email, or a cancellation reference number.

    4

    Request the Appropriate Action From Your Bank

    For an ACH withdrawal, tell your bank about the revoked authorization and ask whether a stop-payment order is appropriate. For bank-scheduled bill pay, request cancellation through your bank’s app, website, or customer service before its cutoff. Provide the payee, amount, and expected payment date.

    5

    Get Confirmation and Monitor Your Account

    Confirm which future payments have been stopped and whether any pending transaction can still be processed. Save the bank’s confirmation and review your account around the expected withdrawal date. If an unauthorized or incorrect payment occurs, contact your bank promptly.

    Important: Cancelling an automatic payment does not cancel the underlying subscription, loan, insurance policy, or utility agreement. Arrange another payment method for any amount you still owe to avoid late fees or service interruptions.

    Benefits and Drawbacks of Stopping Automatic Payments

    Stopping an automatic payment can give you greater control over your money, especially when you no longer need a service or want to prevent an unwanted withdrawal. However, cancelling autopay without arranging another payment method can create avoidable financial problems.

    Benefits

    • Helps prevent future unwanted withdrawals after cancellation is properly completed.
    • Gives you more control over when money leaves your account.
    • Can reduce repeated charges for services you have cancelled.
    • Allows closer monitoring of payments after identifying suspicious or unauthorized activity.

    Drawbacks

    • You may forget to make a payment manually after cancelling autopay.
    • Missed due dates can lead to late fees or service interruptions.
    • Missed loan or credit-card payments may be reported to credit bureaus and affect your credit history.
    • Your bank may charge a stop-payment fee depending on its account terms and policies.

    Expert Tip: Before stopping autopay for a loan, insurance premium, utility bill, or credit card, arrange another payment method and confirm the next due date. Remember, cancelling the automatic withdrawal does not cancel the bill, debt, or contractual obligation.

    Bank Bill Pay vs. ACH Debit vs. Recurring Card Payments

    Automatic payments may look similar on your bank statement, but the payment process and cancellation method can be different. The key is identifying who initiates the transaction and which account or card is charged.

    FeatureBank Bill PayACH DebitRecurring Card Payment
    Who initiates it?Your bank or credit unionCompany or billerMerchant through card network
    Payment sourceBank accountBank accountDebit or credit card
    Where to start?Your bankBiller, then your bank when appropriateMerchant, then card issuer if needed
    How to stop itCancel the scheduled payment before the bank’s cutoff.Revoke the company’s ACH authorization and ask your bank about stop-payment options.Cancel recurring billing and contact the card issuer if charges continue.
    Important cautionA payment already sent or processed may not be cancellable.Stopping a withdrawal does not automatically cancel the bill or contract.Replacing a card may not always stop recurring billing arrangements.

    Which method should you use? For bank-scheduled bill pay, contact your bank. For ACH withdrawals, revoke authorization with the company and notify your bank when appropriate. For recurring card charges, cancel with the merchant and contact your card issuer if the problem continues.

    Cancellation Costs, Risks and Expert Tips

    Before stopping an automatic payment, understand the applicable cancellation rules, possible bank fees, and timing requirements. Your rights can depend on whether the withdrawal is a qualifying ACH payment, bank-scheduled bill pay, or recurring card charge.

    Understand the Three-Business-Day Rule

    Under Regulation E, you can stop a qualifying preauthorized electronic fund transfer by notifying your bank orally or in writing at least three business days before its scheduled date. If you make an oral request, your bank may require written confirmation within 14 days. It must explain this requirement and provide submission instructions when you make the request.

    Know Your ACH Authorization Rights

    You can revoke authorization for future ACH withdrawals. Notify your bank that the authorization is no longer valid and provide written evidence if requested. Under Regulation E, the bank must block future payments covered by that revoked authorization; it cannot simply wait for the company to complete its own cancellation process.

    Check Fees and Avoid Payment Problems

    Stop-payment fees, renewal periods, and procedures vary by financial institution and account agreement. Before cancelling autopay for a loan, insurance premium, or utility bill, arrange another payment method so you do not miss the due date.

    Expert Tips

    • Contact your bank as early as possible.
    • Give the bank the payee name and scheduled withdrawal details.
    • Keep written proof of authorization revocation and stop-payment requests.
    • Monitor your account and report unauthorized transactions promptly.

    Official guidance: Read the CFPB’s Regulation E, Section 1005.10 for the federal rules on preauthorized transfers and stop-payment rights.

    Common Mistakes When Stopping Automatic Bank Payments

    Stopping an automatic payment involves more than clicking a cancellation button. Overlooking the following details can lead to another withdrawal, an unpaid bill, or unnecessary fees.

    • Deleting autopay instead of revoking authorization: Removing a scheduled payment from your banking app may not cancel a company’s ACH authorization.
    • Contacting only one party: Some situations require notifying both the biller and your bank.
    • Waiting until payment day: Late requests may arrive after the transaction has entered processing.
    • Ignoring confirmation: Without written proof, it can be harder to establish when you requested cancellation.
    • Forgetting the outstanding bill: Stopping autopay does not remove a remaining balance or contractual payment obligation.

    Real-Life Example: A Cancelled Gym Membership

    Consider a customer who cancels a gym membership but does not revoke the ACH authorization used for monthly withdrawals. Depending on the payment schedule and processing status, another debit may still be initiated. The customer should check the membership agreement, request written confirmation of cancellation, revoke the payment authorization, and notify the bank if another withdrawal needs to be stopped.

    Key Lesson: Cancelling a membership, revoking payment authorization, and settling any remaining contractual balance are three separate matters. Complete each one to avoid future billing disputes.

    When Should You Contact Your Bank or the Biller?

    The right contact depends on how the payment is set up and why you want to stop it. Use these situations to decide where to begin.

    Bank-scheduled bill payment: Contact your bank or credit union to cancel the scheduled payment. Ask whether it has already entered processing and whether cancellation is still possible.

    Automatic ACH withdrawal: Contact the company to revoke its authorization. Separately notify your bank if you need to stop a future debit or place a stop-payment order.

    Recurring debit or credit card charge: Contact the merchant to cancel recurring billing. If charges continue or a transaction is unauthorized, contact your card issuer about blocking or disputing options.

    Unknown or unauthorized withdrawal: Contact your bank immediately to report the transaction, ask about securing your account, and understand the applicable error-resolution process. Do not wait for the merchant to respond first.

    Important: A pending or completed transaction may not be cancellable through an ordinary stop-payment request. Ask your bank what options remain. A completed unauthorized or incorrect transaction may need to be reported and disputed rather than cancelled.

    Frequently Asked Questions About Stopping Automatic Bank Payments

    1. Can I stop an automatic bank payment online?

    Often, yes. Many banks allow eligible scheduled bill payments to be cancelled through online banking or a mobile app. For ACH debits or recurring card charges, you may also need to contact the company or card issuer.

    2. How do I stop an automatic ACH payment?

    Revoke authorization with the company and notify your bank that future withdrawals are no longer authorized. Ask the bank about a stop-payment order if another debit is scheduled.

    3. Do I need to contact my bank or the company?

    It depends on the payment method. Cancel bank-scheduled bill pay through your bank. For ACH debits, contact the company to revoke authorization and notify your bank. For recurring card charges, contact the merchant and your card issuer when necessary.

    4. How much notice does a bank need to stop an automatic payment?

    For a qualifying preauthorized electronic fund transfer, Regulation E generally requires notice at least three business days before the scheduled transfer. Other payment methods may have different cancellation deadlines.

    5. Can my bank stop a payment that has already been processed?

    A completed payment generally cannot be cancelled through a standard stop-payment request. Contact your bank promptly to ask about recovery or dispute options, particularly if the transaction was unauthorized or incorrect.

    6. Does cancelling autopay cancel my subscription or loan?

    No. Stopping an automatic withdrawal does not automatically end a subscription, loan, or service agreement. Follow the provider’s cancellation terms and arrange payment of any remaining balance.

    7. What if a company keeps charging after I cancel?

    Keep your cancellation confirmation and contact the company in writing. Notify your bank or card issuer promptly, explain the continued charges, and ask how to stop future payments and dispute any eligible transactions.

    8. Can I stop recurring debit-card payments through my bank?

    Contact the merchant to cancel recurring billing. If an unauthorized charge occurs or billing continues after cancellation, contact your card issuer promptly about available blocking and dispute options.

    Official guidance: Read the CFPB’s Regulation E, Section 1005.10 for federal rules on preauthorized electronic fund transfers and stop-payment rights.


    Final Verdict: Stop Automatic Payments Without Missing Important Bills

    Stopping an automatic bank payment starts with identifying how the money is being withdrawn. Cancel bank-scheduled payments through your bank, revoke ACH authorization with the company and notify your bank when necessary, or cancel recurring card billing with the merchant.

    Keep written confirmation, check your account for further withdrawals, and arrange another payment method for any outstanding balance. Remember, stopping autopay does not cancel a subscription, loan, or other financial obligation.

    Explore the Complete Guide

    Learn how ACH transfers, bank payments, and other money-transfer methods work in the United States.

    Read the Bank Transfers & Payments Guide →

    FinanceInvestment

    Take Control of Your Banking Decisions

    Explore practical banking guides, understand payment options, and make more confident financial decisions with clear, helpful information.

    FinanceInvestment — Practical financial education for everyday decisions.