Money Market Accounts: Complete Guide to Rates, Rules & Benefits (USA 2026)
FINANCE INVESTMENT
Practical Money Guides for Smarter Decisions
Written by ,
Subhash Rukade.
Finance Investment Editorial Team
•
Updated Sept ,01, 2026
•
25 min read
Fact Checked
USA 2026 Guide
 A money market account can give your cash a useful middle ground between everyday access and earning interest. It may work well for an emergency fund, a large upcoming purchase, or savings you expect to use within the next few months or years. Instead of leaving extra cash in a basic checking account, you may be able to earn interest while keeping reasonable access to the money.What Is a Money Market Account?
The tricky part is that money market accounts can differ quite a bit from one bank to another. One may offer a competitive APY but require a higher balance. Another may provide checks or a debit card but offer a lower rate. Fees, minimum-balance requirements, and account-access rules can also change the value of an offer. So, the highest advertised APY is not always the most useful choice.
This guide looks at the details that matter after the headline rate catches your attention. You’ll learn how these accounts work in everyday situations, how balances and fees can affect your earnings, and where they stand next to savings accounts, CDs, and checking accounts. The goal is to help you understand the trade-offs before moving your cash.
If you’re still getting familiar with everyday banking, our
Checking Accounts USA 2026 guide
explains the role of checking accounts and can give you useful context before comparing places to keep your cash.
What You’ll Learn
- What a money market account is and how it works.
- How APY, balance requirements, deposits, and withdrawals can affect your money.
- When a money market account may be useful for short- or medium-term cash.
- Which fees and minimum-balance rules deserve attention.
- How money market accounts compare with savings accounts, CDs, and checking accounts.
- How to compare an account beyond its advertised interest rate.
Quick Answer: Are Money Market Accounts Worth Considering?
The short answer
A money market account can make sense when you want your cash to earn interest without giving up as much access as you would with a CD. It can be useful for emergency savings, a large purchase, or cash you expect to need within the next few months or years. The catch is that account terms vary. Minimum balances, monthly fees, transaction features, and APYs can all affect the real value of an offer.
Key Takeaways
1. Access varies
Depending on the bank, you may have access through transfers, checks, a debit card, or other withdrawal methods.
2. The APY may move
Unlike a fixed-rate CD, a money market account generally does not lock your interest rate for a set term.
3. Read the balance rules
Some accounts require a minimum balance to earn the advertised rate or avoid a monthly maintenance fee.
4. Check deposit insurance
If safety is a priority, confirm that the bank is FDIC-insured and understand the applicable coverage rules.
5. It differs from a CD
A money market account usually offers more day-to-day flexibility, while a CD typically trades access for a fixed term and rate.
6. Compare the full package
Look beyond the advertised APY. Fees, minimums, access options, and account restrictions can change the outcome.Money Market Account Pros & Cons
Bottom Line
A money market account can be a practical middle ground for cash that needs to stay reasonably accessible while still earning interest. The best fit is not necessarily the account with the biggest advertised APY. A lower-rate account with fewer fees, a manageable minimum balance, and better access could leave you with a more useful setup.
Money Market Accounts at a Glance
A money market account can give your cash two useful qualities at once: interest earnings and relatively easy access. It may be a practical fit for an emergency fund, a larger cash reserve, or money you’re setting aside for a purchase without wanting to lock it away in a CD.
Quick Facts
- Money market accounts are deposit accounts offered by banks and credit unions.
- They generally earn interest, and their rates can change as market conditions and account policies change.
- Depending on the institution, you may get checks, a debit card, ATM access, or electronic transfers.
- Minimum balances, monthly fees, and account requirements vary from one institution to another.
- Deposits at FDIC-insured banks may qualify for FDIC insurance within applicable limits. Deposits at federally insured credit unions may qualify for NCUA share insurance within applicable limits.
Who Is a Money Market Account Best For?
It can work well for savers who have cash beyond their day-to-day spending needs but don’t want to give up convenient access. For example, someone building a six-month emergency reserve may prefer a money market account over a CD because the money remains easier to reach. The account can also suit a larger short-term savings balance when earning interest matters.
Key Features to Check
APY
Compare the annual percentage yield, not just the interest rate. Also check whether the advertised APY requires a particular balance.
Minimum Balance
Find out whether you need to maintain a certain balance to earn the advertised rate or avoid a monthly maintenance fee.
Access
Check how you can move money, including transfers, ATMs, checks, debit cards, and any transaction restrictions that apply.
Quick Summary
| Feature | What to Expect |
|---|
| Purpose | Hold cash while earning interest |
| Interest | Usually variable, so the APY can change over time |
| Access | May include transfers, ATMs, checks, or debit-card access |
| Main trade-off | Better access can come with balance requirements, fees, or a lower APY |
Best Money Market Accounts in 2026
Money Market Accounts: A Complete Beginner Guide
 A money market account is a deposit account offered by a bank or credit union that lets your cash earn interest while keeping it relatively accessible. It can be useful when you want more earning potential than a basic spending account without committing the money to a fixed-term CD.
One important distinction comes first: a money market account is not the same as a money market mutual fund. A bank or credit union money market account is a deposit product. A money market mutual fund is an investment that holds short-term securities and follows different rules, protections, and risks.
Money Market Account vs. Savings Account
Why Would Someone Use a Money Market Account?
Picture someone with $20,000 set aside for a car purchase next year. Keeping the money in a checking account makes it easy to reach, but that balance may not be earning much interest. A money market account could give the saver a way to earn interest while keeping the funds available for the planned purchase.
It can also be useful for a larger emergency reserve. You may want the money separate from everyday spending but still available if an unexpected repair, medical bill, or other major expense comes up.
How Does the Interest Work?
Money market accounts generally pay interest, and the return is commonly shown as an annual percentage yield (APY). APY helps you compare deposit accounts by showing the annualized return while taking the effect of compounding into account under the account’s stated terms.
The rate is often variable, which means the APY can move up or down after you open the account. A rate that looks attractive today may not remain the same months later. When comparing offers, check whether the advertised APY applies to your entire balance, whether a minimum balance is required, and whether fees could reduce your actual earnings.
How Can You Access the Money?
Access depends on the institution and the specific account. Some money market accounts may offer electronic transfers, ATM access, checks, or a debit card. Others may provide fewer ways to move money.
That difference can matter more than it first appears. For example, if you keep $15,000 for a future home repair but frequently move money out for everyday purchases, an account with balance requirements or transaction conditions may become inconvenient. Keeping routine spending in a checking account can help preserve the purpose of the money market balance.
Minimum Balances and Account Fees
Minimum-balance rules can have a direct effect on your return. Some accounts require a certain balance to earn a promotional or advertised APY, while others may charge a monthly maintenance fee when your balance falls below a specified threshold.
Consider the balance you can realistically maintain rather than the largest rate displayed in an advertisement. For example, a slightly lower APY with no monthly fee could be more useful than a higher APY that requires a balance you cannot comfortably keep in the account.
💡 Expert Tip
Before depositing a large amount, write down the advertised APY, required balance, monthly fee, and available access methods. Then check how those terms fit the amount you actually plan to keep there. That simple comparison can reveal whether the headline rate is genuinely useful for you.
Money Market Account or Savings Account?
A savings account may be the simpler choice when you mainly want to build savings and do not need extra access features. A money market account may be worth considering when you have a larger cash balance and want a combination of interest earnings and convenient access.
The difference is not simply about which account advertises the higher APY. Look at the full package: rate, balance requirements, fees, withdrawal and transfer options, and how easily you can access the money when you actually need it.
How Money Market Accounts Work
A money market account follows a simple cycle: you deposit cash, the institution credits interest according to its current terms, and you access the balance through the methods available with the account. The important details are the ones that can affect your day-to-day experience—such as how the rate is set, how often interest is credited, what access features are included, and whether fees or balance requirements apply.
The Basic Money Flow
1. Deposit
Fund the account by transfer, direct deposit, check deposit, or another method supported by the institution.
2. Earn Interest
Your balance earns interest based on the account’s current rate and stated terms.
3. Access Cash
Use the transfer, ATM, check, debit-card, or other options the account provides.
4. Review
Keep an eye on the APY, balance requirements, fees, and account activity.
1. Funding the Account
Most people fund a money market account by transferring money from another bank account. Depending on the institution, you may also be able to use direct deposit, an electronic transfer, or mobile check deposit. Large transfers can take time to settle, so check the institution’s processing rules when moving money for an upcoming expense.
For instance, suppose you have $25,000 sitting in checking for a home renovation planned several months from now. Moving an appropriate portion into a money market account could separate that money from everyday spending while allowing it to earn interest.
2. How the Interest Rate Works
Money market accounts generally pay interest based on the rate in effect under the account’s terms. The return is commonly displayed as an APY, which makes it easier to compare deposit accounts. Unlike a fixed-rate CD, however, the rate on many money market accounts can change after the account is opened.
Some institutions use balancMoney Market Account vs. CDe tiers, meaning different portions or levels of your balance may receive different rates. Others may offer one rate to qualifying balances. Check the rate schedule carefully, particularly if you are depositing a substantial amount.
3. How You Access Your Cash
Access features vary. Depending on the account, you might be able to transfer funds online, withdraw through an ATM, write checks, or use a debit card. These features can make a money market account more convenient than some other savings products.
Still, convenient access does not necessarily make it a replacement for checking. If the money is meant for a future expense or emergency reserve, using a separate checking account for everyday purchases can help keep the balance intact and make your savings easier to track.
4. What Happens to Fees and Balance Requirements?
The advertised APY is only one part of the deal. A monthly maintenance fee can reduce your earnings, while a minimum-balance requirement may determine whether you receive a particular rate or avoid a charge.
Consider a simple example: if an account requires $10,000 to avoid a monthly fee, but you expect to withdraw enough money to fall below that amount regularly, the account may not be as attractive as its advertised rate suggests. The practical terms matter more than the headline number.
5. Keeping the Account Secure
Protect the account just as you would any other bank account. Use a strong password, enable available account alerts, and keep verification codes private. If someone unexpectedly asks for your login details or a security code, contact the institution through a trusted official channel instead of responding to the request.
Once you understand how the account operates, the next step is weighing what you gain against the possible drawbacks.
Money Market Account Benefits and Drawbacks
A money market account can offer a useful combination of interest and access, especially when you’re holding cash for a specific goal. But the account still has trade-offs. A changing rate, balance requirement, or monthly fee can make one offer much less appealing than another.Can You Write Checks From a Money Market Account?
✓ Potential Benefits
- Earn interest: Your cash can generate interest while it remains in the account.
- Keep convenient access: Depending on the institution, you may have transfers, ATM access, checks, or a debit card. Can You Use a Debit Card With a Money Market Account?
- Useful for larger cash reserves: A money market account may be practical when you want your savings to earn interest without locking the balance into a fixed term.
- Create a separate savings bucket: Keeping money for a major goal away from everyday spending can make it easier to protect that balance.
⚠ Potential Drawbacks
- The rate can change: Many money market accounts have variable rates, so today’s APY may not be tomorrow’s APY.
- Balance requirements may apply: Some accounts require a minimum balance to earn a particular rate or avoid a fee.
- Fees can reduce the return: A monthly maintenance charge can make a seemingly attractive account less valuable.
- Access features vary: A money market account may offer more ways to reach your cash than some savings accounts, but it is not necessarily designed for heavy everyday spending.
When the Benefits Can Be Useful
Suppose you’ve built a six-month emergency reserve and want that money available without keeping it in your everyday checking account. A suitable money market account could give the reserve a chance to earn interest while keeping it relatively accessible. The same setup can work for cash earmarked for a vehicle, home improvement, tuition, or another expense that is still months away.
When Another Account May Fit Better
A different account may make more sense if you need to use the money frequently, cannot maintain a required balance, or find that the account’s fees outweigh its interest earnings. Checking can be more convenient for regular bills and purchases, while a savings account may provide a simpler home for cash you rarely touch. If you can leave the money alone for a defined period, a CD may also deserve a comparison.
Keep the purpose in view:
the best account is the one whose access, rate, fees, and rules match how you expect to use the money. A high APY is useful only when the rest of the account works for you.
Money Market Account Comparison: How Does It Stack Up?
A money market account can sit in the middle of the cash-management spectrum: it may offer more access than a CD while providing interest that a basic checking account may not. Still, a savings account, checking account, or CD can be a better fit depending on when you need the money and how often you plan to use it.
A practical comparison of common places to keep cash.| Account | Main Purpose | Access | Rate Type | May Suit |
|---|
| Money Market Account | Interest-bearing cash | Usually convenient | Often variable | Larger reserves and near-term goals |
|---|
| Savings Account | Building a cash reserve | Generally easy | Often variable | Emergency funds and regular saving |
|---|
| Checking Account | Everyday spending | Very convenient | Often low or none | Bills, purchases, and direct deposits |
|---|
| Certificate of Deposit (CD) | Time-based saving | More restricted | Often fixed | Money you can leave untouched |
|---|
Money Market vs. Savings Account
These accounts have a lot in common: both can hold savings and generally earn interest. A money market account may stand out when you value additional access features, such as checks or a debit card, if the institution offers them. A savings account may be the cleaner choice when your main goal is simply to build a reserve and leave it alone.
For instance, someone keeping $30,000 for a planned home project might value convenient access. Someone building an emergency fund may prefer a simpler savings account with fewer requirements. Compare the actual APY, fees, minimum balance, and access rules rather than relying on the account label.
Money Market Account Fees Explained
Money Market vs. Checking Account
Checking accounts are built for frequent movement: paychecks arrive, bills are paid, and purchases happen throughout the month. A money market account is generally better suited to cash you want available but do not expect to spend every day. Keeping spending money separate can also make a savings goal easier to protect.Money Market Account vs. Money Market Fund
Money Market vs. CD
A CD typically trades flexibility for a defined term and, in many cases, a fixed interest rate. Taking money out before maturity can trigger an early-withdrawal penalty. A money market account generally offers easier access, but its rate may change. If you know you will not need the money for a set period, compare the potential return and restrictions of both options.Money Market Account vs. Treasury Bills. Money Market Account vs Treasury Bills: Which Is Better for Cash?
A Simple Way to Decide
Start with the purpose of the money. If you need it for everyday spending, checking is usually the natural home. If you are building a reserve, savings may be enough. If you can leave the money untouched for a defined period, a CD may be worth considering. A money market account can make sense when you want interest plus relatively convenient access.
Money Market Account Costs, Risks & Expert Tips
A strong APY can catch your attention, but it does not tell the whole story. The account’s fees, balance requirements, access rules, and rate changes can have a bigger effect on your results than a small difference in the advertised rate.
Common Costs to Watch
Depending on the institution, a money market account may have a monthly maintenance fee, minimum-balance requirement, ATM fee, returned-payment fee, or other account-specific charges. Some banks waive a monthly fee when you maintain a specified balance or meet another condition.
This is why comparing APYs alone can be misleading. Suppose one account offers a slightly higher rate but charges a monthly fee when your balance falls below its threshold. Another account may offer a lower APY with no monthly fee. For a smaller balance, the second option could leave you with more money overall.Money Market Account vs Money Market Fund: Which Is Safer?
Risks Worth Understanding
The most important rate-related risk is that many money market deposit accounts have variable interest rates. The APY available when you open the account can change later, so today’s return should not be treated as a permanent promise.
There is also a behavioral risk. When savings are easy to access, it can be tempting to use money that was meant for an emergency fund or a planned purchase. Keeping everyday spending money in a separate checking account can create a useful boundary. Are Money Market Accounts FDIC Insured?
Expert Tip
Compare what you are likely to keep after fees, not just the highest advertised APY. Check the rate, minimum balance, monthly charge, access features, and conditions attached to the offer. Then judge the account using the balance you realistically expect to maintain.
Simple Ways to Protect Your Interest Earnings
- Pick a balance requirement you can comfortably maintain.
- Keep routine spending money in checking instead of repeatedly dipping into savings.
- Review the APY from time to time because variable rates can move.
- Check ATM and transaction costs before making frequent withdrawals.
- Read the fee schedule and account disclosures before depositing a large balance.
Protect Your Account From Fraud
Be cautious with unexpected calls, texts, and emails about your account. A legitimate financial institution should not require you to reveal a one-time security code to an unsolicited caller. If something seems unusual, contact the bank or credit union through its official app, website, or a trusted phone number. Do You Pay Taxes on Money Market Account Interest?
Important Distinction
Do not confuse a money market deposit account with a money market mutual fund. A deposit account is a bank or credit union product, while a money market mutual fund is an investment product. Their features and protections are not the same.
If you are deciding how to organize cash across different accounts, our
guide to protecting and growing your cash
can help you think through access, safety, and potential returns together.
Common Money Market Account Mistakes to Avoid
Choosing a money market account is not just about finding an attractive APY. The details behind the rate can affect your earnings, access, and overall experience. A few simple checks can help you avoid choosing an account that looks better on paper than it works in real life.
1. Chasing the Highest APY
The highest advertised rate is not automatically the best deal. Check whether the APY requires a minimum balance, applies to your entire balance, or is subject to change. A slightly lower rate with fewer fees may produce a better result for your actual balance. Best Money Market Accounts for Large Balances
2. Ignoring the Minimum Balance
Some accounts require you to maintain a certain balance to avoid a monthly fee or qualify for a particular rate. If you expect to withdraw money regularly, make sure you can still meet the account’s requirements afterward. Best Money Market Accounts for Retirees
3. Using It Like a Checking Account
Some money market accounts may offer checks or debit-card access, but that does not necessarily make them ideal for everyday spending. Using the account for constant purchases can make it harder to protect money meant for an emergency or a specific goal.
4. Forgetting That the Rate Can Change
Many money market accounts have variable rates. The APY available when you open the account may not be the same months later. Keep an eye on account notices and statements so a rate change does not catch you by surprise.
5. Overlooking Fees and Insurance
Before moving a large cash balance, review the monthly fee, minimum-balance rules, ATM charges, and other account costs. Also confirm whether the bank or credit union is federally insured and understand the applicable deposit-insurance limits. Insurance protects eligible deposits within the coverage rules; it does not guarantee a particular interest rate. Money Market Account vs Savings for Emergency Funds . Are Money Market Accounts Good for Emergency Funds?
A Real-Life Example: Managing a $25,000 Cash Reserve
Consider a hypothetical saver named Maria. She has $25,000 set aside for a future home renovation. The money is currently sitting in her checking account because she wants to be able to reach it when the project begins.
Maria compares several accounts and finds a money market account offering a competitive APY. Instead of focusing only on that number, she checks the minimum balance, monthly fee, access features, and whether the advertised rate can change. She also keeps enough money in checking for regular bills and near-term spending.
A few months later, the account’s APY falls. Maria notices the change because she reviews her statements periodically. She can then compare the new rate and account terms with other suitable options rather than leaving the money there simply because the original rate looked attractive.
The Takeaway
Maria’s decision was not based on the highest rate alone. She matched the account to the purpose of the money, checked the rules before depositing it, kept spending cash separate, and paid attention when the rate changed. That approach can be more useful than simply chasing whichever APY looks best today.
Who Should Choose a Money Market Account?
A money market account may be a good fit when you want your cash to earn interest while keeping reasonably convenient access to it. It can be particularly useful for money that is not part of your everyday spending but may be needed for an emergency, a planned purchase, or another near-term financial goal.
The key is matching the account with how you actually use your money. A competitive APY is helpful, but minimum-balance requirements, monthly fees, access features, and a variable rate can matter just as much.
Good Fits for a Money Market Account
- Emergency fund holders:
You want your backup cash to earn interest while remaining available when an unexpected expense comes up. - People saving for a major purchase:
A car, home improvement project, wedding, education expense, or other planned purchase may benefit from a separate interest-bearing cash reserve. - Savers with larger balances:
If you can comfortably maintain the required balance, a money market account may offer useful interest earnings without requiring you to lock the money into a CD. - People who want more access than a typical savings setup:
Depending on the institution, you may have features such as checks, ATM access, debit-card access, or convenient transfers. - People separating savings from everyday spending:
Keeping reserve money in a separate account can make it easier to avoid spending funds intended for a specific goal.
Who May Want Something Else?
A checking account may be more practical for money you use constantly for groceries, bills, subscriptions, and everyday purchases. Checking accounts are generally built around frequent transactions and payment activity.
A savings account may be simpler if your main goal is building an accessible cash reserve and you do not need additional features such as checks or a debit card. The account’s APY, fees, and balance requirements should still be compared.
A CD may be worth considering when you know you can leave the money untouched for a specified term and want to consider a fixed interest rate. The trade-off is usually less flexibility, and withdrawing funds before maturity may result in an early-withdrawal penalty under the CD’s terms.
A Simple Way to Decide
Ask Yourself Three Questions
- How often will I need this money?
If you expect frequent spending, a checking account may be easier. - Can I comfortably maintain the account requirements?
Make sure the minimum balance and fee rules fit your normal cash balance. - Do I want interest while keeping reasonably convenient access?
If yes, a money market account may be worth comparing with savings accounts and CDs.
If your answers point toward occasional access, a meaningful cash balance, and interest earnings, a money market account may be a practical option. If daily spending flexibility or maximum simplicity matters more, another account type may be a better fit.
You Do Not Have to Choose Just One Account
Your cash does not necessarily need to live in a single account. You might keep money for routine bills in checking, maintain an emergency reserve in a savings account, and use a money market account for a separate pool of cash tied to a larger or near-term goal.
This approach can make your cash easier to organize because each account has a clear purpose. The important part is understanding the terms of each account and keeping enough liquidity for expenses that cannot wait.How to Open a Money Market Account Online
Frequently Asked Questions About Money Market Accounts
Money market accounts can vary in their interest rates, fees, balance requirements, and access features. The questions below cover the key points to understand before choosing one for your cash savings.
1. Is a money market account the same as a savings account?
No. Both are deposit accounts that can earn interest, but their features may differ. A money market account may offer checks, a debit card, or other access options, depending on the institution. A savings account may have a simpler structure and fewer transaction features.
2. Are money market accounts safe?
A money market deposit account at an FDIC-insured bank is generally covered by FDIC deposit insurance up to applicable limits. At a federally insured credit union, eligible deposits are generally insured by the NCUA within applicable limits. Deposit insurance does not protect you from changes in the account’s interest rate or from fees and withdrawals.
3. Money market deposit account ≠ money market mutual fund.
A money market deposit account is a bank or credit union deposit account, not a stock-market investment. Your balance can decrease because of withdrawals, fees, or other account charges. Do not confuse a money market deposit account with a money market mutual fund, which is a different investment product with different risks and protections.
4. Do money market accounts have minimum balance requirements?
Some do and some do not. An institution may require a minimum balance to avoid a monthly fee or to qualify for a particular APY. Check the current account disclosure for the minimum opening deposit, ongoing balance requirements, and any consequences of falling below the required balance.
5. How easily can I withdraw money from a money market account?
Access depends on the specific account and institution. Available methods may include online transfers, ATM withdrawals, checks, or debit-card transactions. However, fees, transaction restrictions, withdrawal conditions, or other account-specific rules may apply. Always review the account agreement for the exact terms.
6. Can I use a money market account for everyday spending?
You may be able to make certain purchases if the account provides a debit card or checks, but a checking account is generally more suitable for frequent everyday spending. Using a separate checking account for regular bills and purchases can also help keep money reserved for savings goals.
7. Are money market account interest rates fixed?
Usually, no. Many money market accounts have variable interest rates, which means the APY can increase or decrease after you open the account. When comparing accounts, consider the current APY along with the balance requirements, fees, and other conditions that affect your actual return.
8. Is a money market account better than a CD?
Neither is automatically better. A money market account generally offers more convenient access to your money, but its interest rate may change. A CD typically requires you to keep money deposited for a specified term and may impose an early-withdrawal penalty if you take funds out before maturity. Your need for liquidity should be an important part of the comparison.
9. How much money should I keep in a money market account?
There is no universal amount. Consider what the money is for, how quickly you may need it, and the account’s minimum-balance requirements. A money market account may be used for an emergency reserve, a planned major purchase, or another near-term cash goal. Keep enough money in checking to cover routine expenses without repeatedly dipping into your reserve.
10. What should I compare before opening a money market account?
Compare the APY, minimum opening deposit, minimum balance, monthly maintenance fee, withdrawal and transfer options, ATM access, and other applicable charges. Also verify that the bank or credit union has the appropriate federal deposit insurance. Looking at the complete account can help you avoid choosing based on the advertised APY alone.
Quick Reminder
Money market accounts can offer a useful combination of interest and access, but the exact terms vary by institution. Check the current disclosure for the account you are considering, especially its APY, fees, balance requirements, access features, and applicable deposit insurance.
Final Verdict: Is a Money Market Account Worth It?
A money market account can be a useful home for cash that you do not need for everyday spending but still want to keep reasonably accessible. It may work well for an emergency reserve, a planned major purchase, or another short- to medium-term cash goal where earning interest matters.
The advertised APY should not be the only factor you consider. Look at the complete account, including the minimum opening deposit, balance requirements, monthly fees, access options, transaction rules, and whether the interest rate can change. A slightly higher APY may not be valuable if you cannot meet the account’s conditions or regularly incur fees.
A money market account also does not have to replace your other bank accounts. Checking can handle everyday purchases and bills, while savings or a money market account can hold money reserved for emergencies or larger goals. Separating these purposes can make your cash easier to manage while keeping funds available when needed.
If you’re still deciding how checking fits into your overall cash-management strategy, our
Checking Accounts USA 2026 guide
provides a broader look at everyday banking and account features.
Final Takeaway
A money market account is worth considering when you want a combination of interest earnings, convenient access, and a separate place for meaningful cash savings. Before choosing one, compare the current APY with the fees, balance requirements, access features, and rate terms. The best account is the one whose rules work comfortably with how you actually use your money.
FINANCE INVESTMENT
Make Your Cash Work Smarter
Understanding how money market accounts work is only the first step. Keep exploring Finance Investment for practical guides on banking, saving, investing, and making informed decisions with your money.
Before You Choose an Account
Compare the APY, minimum balance, monthly fees, access options, rate changes, and deposit-insurance status. The account with the highest advertised rate is not necessarily the best fit for your cash needs.
Have a question?
Share your question or experience in the comments. Your insight could help another reader compare their options.
Found this guide useful? Share it with someone who is deciding where to keep their savings.
Smart Money Starts With Better Information
 Credit Union Certificates Explained starts with a simple idea: a share certificate is a credit union savings product that works in a way similar to a bank certificate of deposit, or CD. You deposit money for a stated term, and the certificate can earn dividends according to its account terms.
 If you are new to share certificates, the easiest way to understand them is to think about the timing of your money. You place a specified amount into a certificate under agreed account terms and choose a defined term. In exchange, the account may provide dividends based on its applicable rate and conditions.
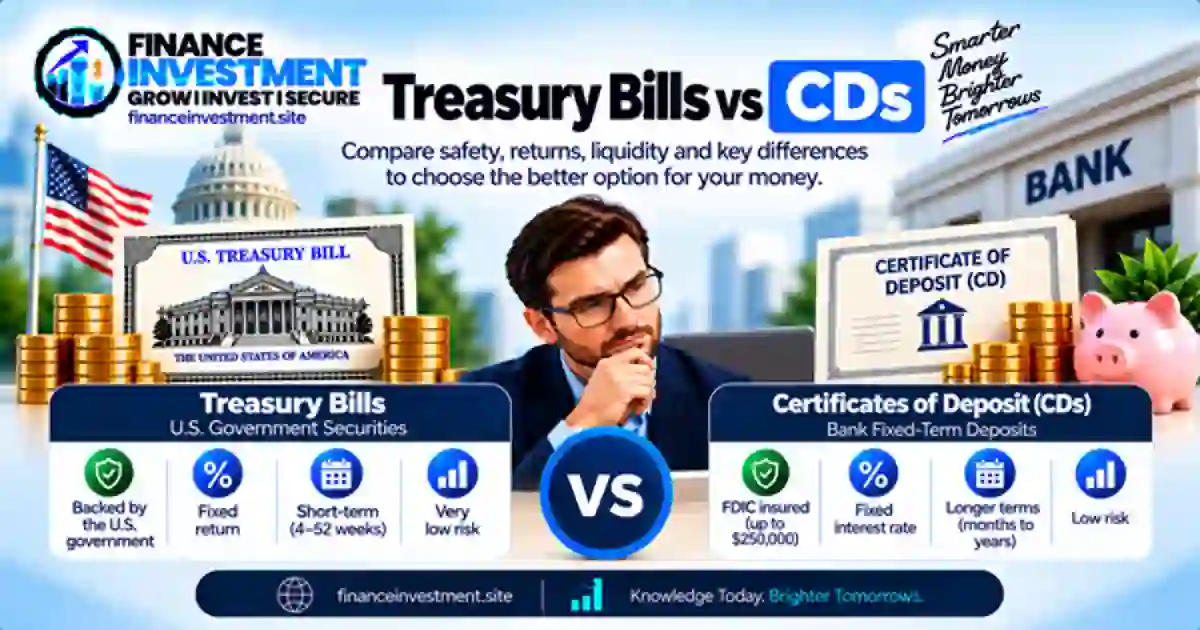
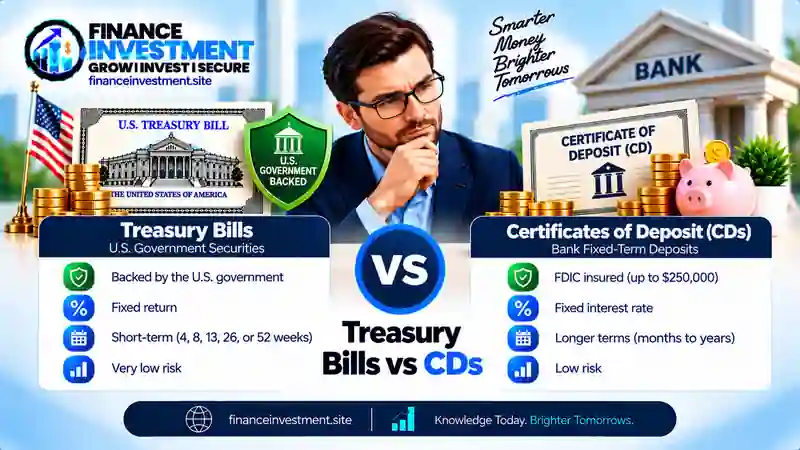 If you’re new to Treasury Bills vs CDs, start with the basic difference. A Treasury bill is a short-term U.S. government security. A CD is a time deposit offered by a bank or credit union. Both can be used for money you expect to keep relatively stable, but the way you earn and access that money is different.
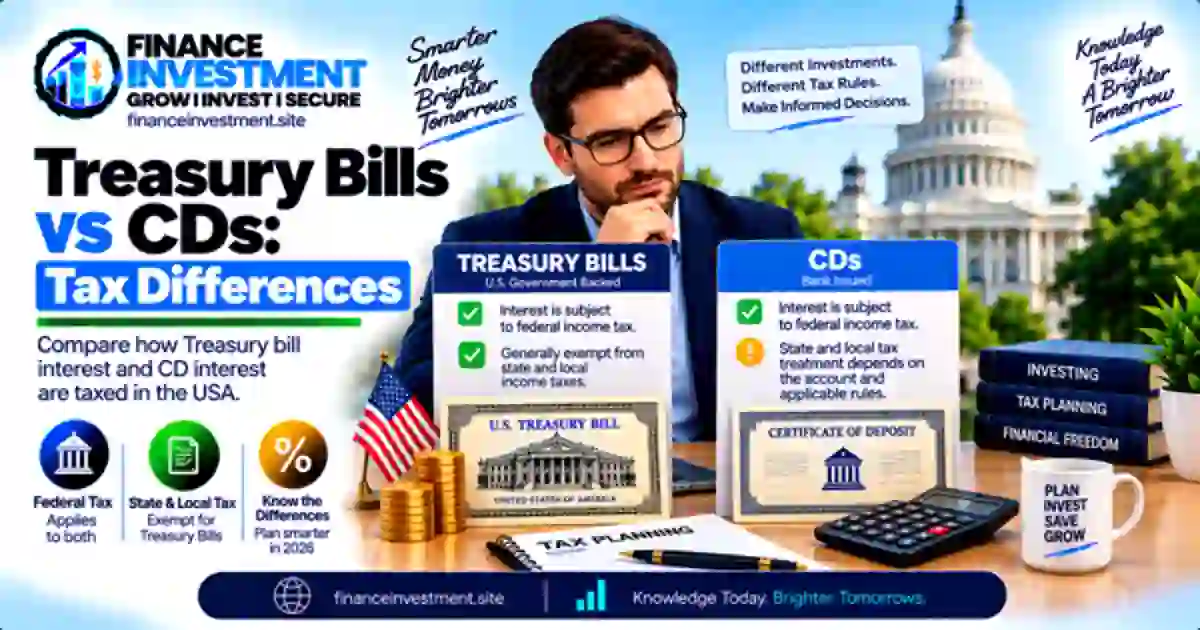
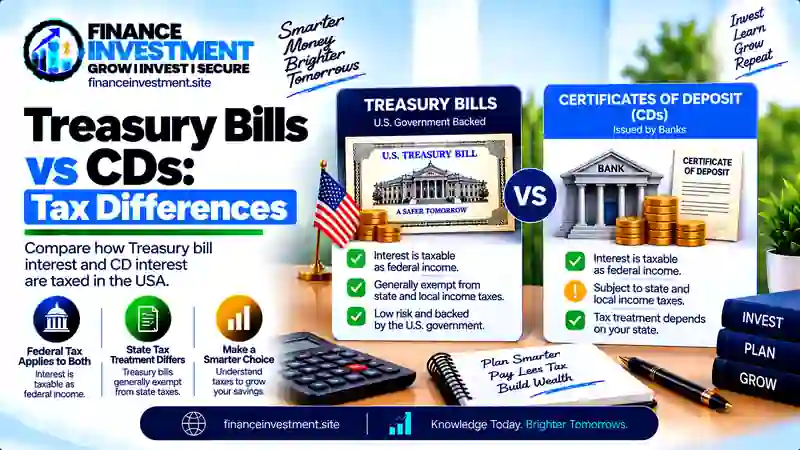 When comparing Treasury bills and CDs, the advertised yield is only part of the picture. Both can generate taxable income, but the tax treatment is not identical. The biggest difference is what happens at the state and local level.
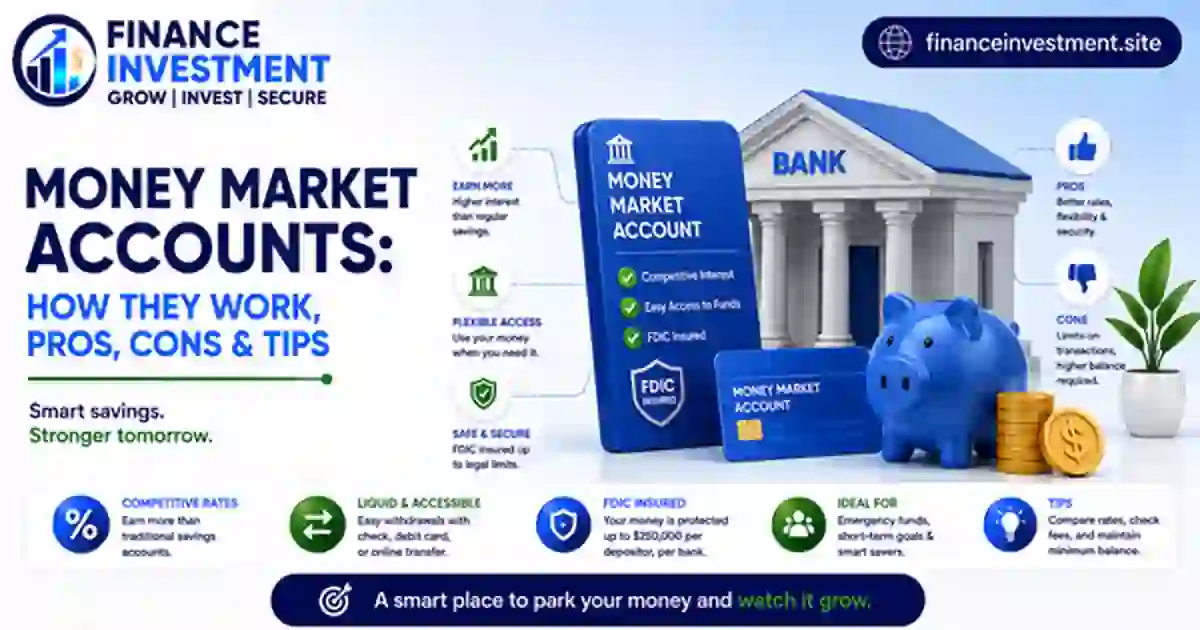
 A money market account is a deposit account offered by a bank or credit union that lets your cash earn interest while keeping it relatively accessible. It can be useful when you want more earning potential than a basic spending account without committing the money to a fixed-term CD.
 If you’ve used a regular certificate of deposit before, the main difference here is the interest rate. With a traditional fixed-rate CD, the rate is generally set when you open the account and remains unchanged through the term. A variable-rate CD can adjust during that period based on the terms of the account.
 When you have cash to put to work, a certificate of deposit isn’t the only place it can go. A CD may offer a predictable return, but a high-yield savings account can keep your money easier to reach, while Treasury bills and bonds may play a different role in a broader investment plan. The real question isn’t simply which option pays more.
 Choosing where to keep your money starts with one simple question: When will you need it? A CD, savings account, money market account, Treasury bill and bond can all hold or grow money, but they do not work the same way.