How Do Credit Unions Work? Complete Beginner Guide
How Do Credit Unions Work?
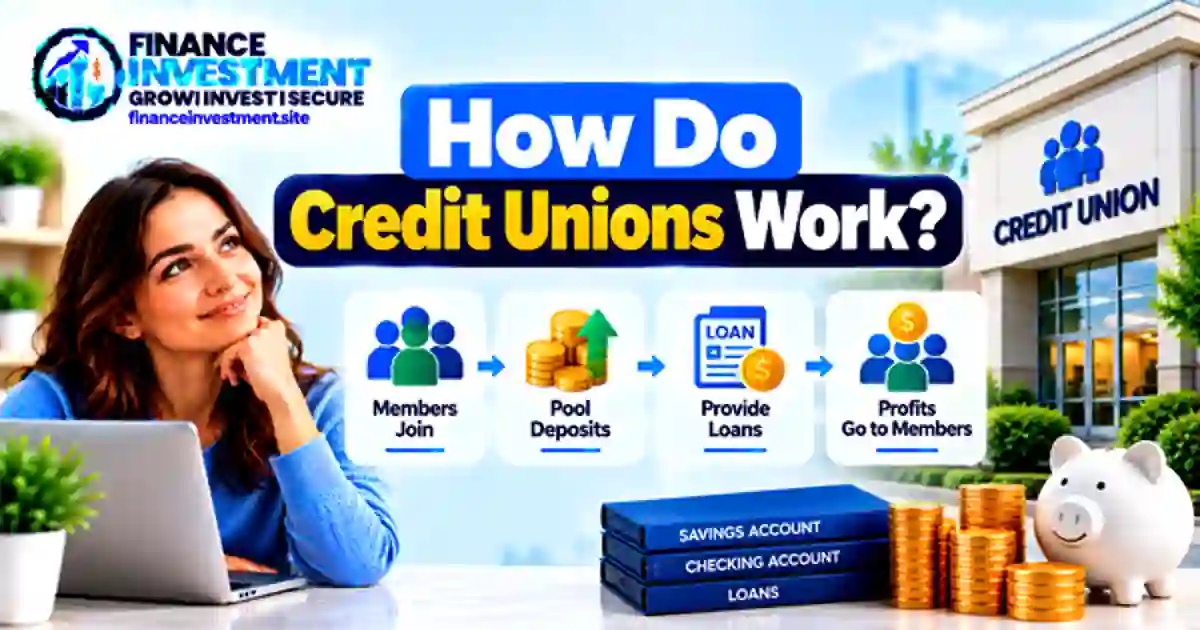 If you’ve ever wondered how do credit unions work, the simplest answer is this: members save, borrow and use financial services through a cooperative institution they collectively own. Credit unions can accept member savings, make loans and provide services much like banks, but their ownership structure is different. The NCUA describes credit unions as member-owned, member-controlled cooperatives.
The money flow is at the heart of the model. Members put money into savings and other share accounts. The credit union uses its available funds to support lending and day-to-day operations. When members borrow, their loan payments bring money back into the institution. Revenue from loans, fees and other activities helps cover operating costs and maintain the credit union’s financial strength.
Membership is another important piece. A credit union usually has a defined field of membership, which can be based on factors such as employment, location, family or association membership. So before opening an account, you need to determine whether you qualify.
THE SIMPLE IDEA
A credit union creates a cooperative financial cycle: members save → the credit union lends → borrowers repay → the institution serves its members and covers its costs.
For the bigger picture, see our complete Credit Unions Explained guide, which covers accounts, membership, fees, NCUA insurance and other important details.
What You’ll Learn
- How credit union membership and ownership work.
- How member savings and loans connect inside the cooperative model.
- How checking, savings and other share accounts fit into the system.
- How revenue, fees and operating costs affect the credit union.
- How credit unions differ from traditional banks.
- What to consider before joining or opening an account.
Quick Answer: How Do Credit Unions Work?
How do credit unions work? They operate as member-owned financial cooperatives. People who qualify for membership can place money into share accounts, use checking and savings services, and apply for loans. The credit union earns revenue, pays its operating expenses, manages financial reserves and provides services for its members.
The biggest difference from a traditional bank is the ownership structure. Eligible members become part of the cooperative and may have voting rights under the credit union’s rules. Credit unions also use different terminology: a savings account may be called a share account, while a checking account may be called a share draft account.
KEY TAKEAWAYS
- You generally need to meet the credit union’s membership eligibility rules.
- Members can use share accounts, checking services, loans and other financial products.
- Membership gives eligible individuals an ownership interest in the cooperative.
- Credit unions generate revenue to cover expenses, maintain financial strength and serve members.
- Accounts at federally insured credit unions can receive NCUA share insurance, subject to applicable coverage limits and rules.
Credit Unions at a Glance
| Feature | What It Means |
|---|---|
| Ownership | Eligible members have an ownership interest in the cooperative. |
| Membership | You generally must qualify under the credit union’s field-of-membership rules. |
| Accounts | Products may include share savings, share draft checking and share certificates. |
| Loans | Credit unions can provide financing for needs such as vehicles, personal expenses and homes. |
| Share Insurance | Accounts at federally insured credit unions may receive NCUA share insurance, subject to coverage limits and applicable rules. |
QUICK TAKE
A credit union brings membership, saving, borrowing and financial services together under a cooperative structure. The exact products, fees, eligibility rules and insurance arrangements vary, so compare the specific credit union before opening an account.
How Credit Unions Work: Complete Beginner Guide
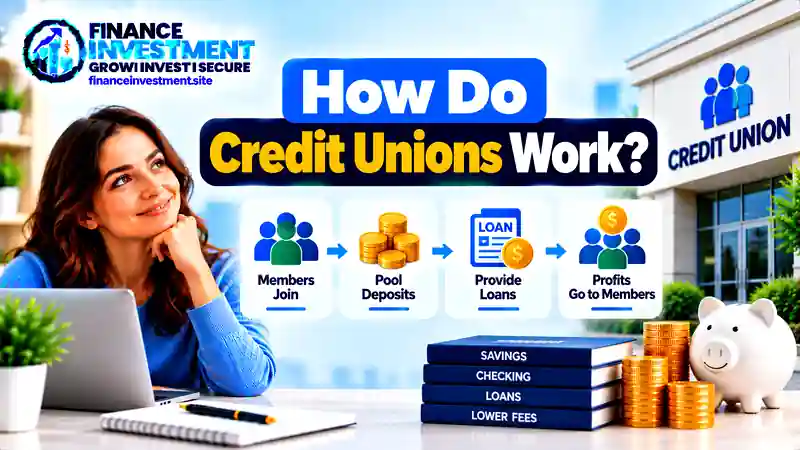 To understand how credit unions work, it helps to follow the process from eligibility to everyday financial services. The experience can look familiar if you’ve used a bank before: you may save money, make payments, use a debit card, manage your account online and apply for a loan. The main difference is the cooperative ownership structure.
1. You Qualify for Membership
A credit union generally serves a defined field of membership. Depending on its charter, eligibility may be connected to your community, employer, family relationship, association or another qualifying group. Once you qualify, the credit union explains the steps and minimum share requirements for becoming a member.
2. You Open Accounts and Use Services
Credit unions can offer many of the same everyday services available at banks. A share savings account can hold savings, while a share draft account can provide checking features. Depending on the institution, members may also have access to share certificates, debit cards, digital banking, credit cards and other products.
3. The Credit Union Manages Its Resources
The credit union manages member shares along with other funding sources, investments, liquidity and financial reserves. It can use available resources to make loans to qualified borrowers and provide other services. Interest from loans, fees and other revenue help the institution pay operating expenses and maintain financial strength.
4. Members Have an Ownership Role
The members are the owners of the cooperative. Eligible members generally have voting rights under the credit union’s governing rules and elect a board of directors to oversee the institution. This member-owner structure is one of the clearest differences between a credit union and an investor-owned bank.
BEGINNER TIP
Before joining, check the credit union’s eligibility rules, minimum share requirement, account fees, digital access, ATM options and applicable insurance coverage. If you’re comparing digital institutions with cooperative options, our guide to digital banks vs. credit unions can help you compare the basic models.
How Credit Union Money Flow Works
To understand how money moves through a credit union, think beyond a simple “savings account funds a loan” model. A credit union manages member shares together with its other funding sources, investments, liquidity and capital. Its goal is to provide financial services while meeting withdrawals, loan demand, operating expenses and other obligations.
Step 1: Members Keep Money in Share Accounts
Members may keep money in share savings, share draft and other eligible accounts. These balances become part of the credit union’s overall funding base. The institution manages that money rather than treating each member’s balance as a separate pool reserved for a particular purpose.
Step 2: The Credit Union Provides Financing
Credit unions evaluate loan applications and may provide financing to qualified borrowers. Depending on the institution, loans can include auto loans, personal loans, mortgages and credit cards. Borrowers then make principal and interest payments according to their agreements.
Step 3: Revenue Covers Costs and Supports Financial Strength
Interest from loans and revenue from other activities help the credit union pay employee, technology, facility, insurance and regulatory expenses. The institution also manages capital, liquidity and reserves to remain financially sound and ready to meet member needs.
Step 4: The Cycle Continues
Members continue saving, borrowing, making payments and using financial services. Because the institution is member-owned, its financial activities are organized around serving its membership rather than outside stockholders. The exact rates, fees and financial products vary by credit union.
MONEY-FLOW SNAPSHOT
Members provide funding → the credit union manages its resources → qualified borrowers receive financing → borrowers make payments → revenue supports operations, liquidity and financial strength. This is a simplified view of a much more detailed balance sheet.
Credit Union Benefits & Drawbacks
Credit unions can offer a different banking experience because members own the cooperative and eligible members can participate in its governance. At the same time, a credit union is not automatically the right fit for everyone. Products, rates, fees, technology and access can vary considerably between institutions.
Potential Benefits
- Eligible members have an ownership role in the cooperative.
- Members can access checking, savings, loans and other financial services.
- Some credit unions may offer competitive rates or fees on particular products.
- Members may have voting rights under the credit union’s governing rules.
Potential Drawbacks
- Eligibility rules can limit who is able to join.
- Branch and ATM access may vary by location and network.
- Digital banking tools and product selection can differ between institutions.
- Rates and fees are not automatically better than those offered by banks.
WHAT TO CHECK
Before joining, compare the specific credit union’s APYs, loan rates, account fees, minimum balances, ATM access, digital banking features, membership rules and applicable share insurance. The cooperative structure is only one part of the decision.
Credit Union vs. Bank Comparison
Credit unions and banks can both provide checking, savings, payment services and loans. The clearest structural difference is ownership: a credit union is a member-owned cooperative, while a bank may be shareholder-owned or privately owned. That distinction can affect governance and membership rules, but it does not by itself determine the rates, fees or services available to customers.
| Feature | Credit Union | Bank |
|---|---|---|
| Ownership | Member-owned cooperative | May be shareholder-owned or privately owned |
| Eligibility | Generally requires meeting the credit union’s membership rules | Must meet the bank’s account-opening and customer requirements |
| Governance | Eligible members may vote under applicable rules | Governed according to the bank’s ownership and corporate structure |
| Deposit/Share Insurance | Federally insured credit unions can have NCUA share insurance, subject to applicable limits and rules | FDIC-insured banks provide FDIC deposit insurance, subject to applicable limits and rules |
COMPARE THE ACTUAL ACCOUNT
When comparing a credit union with a bank, look beyond the label. Check the APY, interest rate, fees, minimum balance, ATM access, digital tools, branch availability and applicable insurance coverage for the specific account.
Credit Union Costs, Risks & Expert Tips
A credit union can offer useful financial services, but joining does not automatically mean lower costs or better terms. Depending on the institution and account, you may encounter monthly maintenance fees, overdraft charges, ATM fees, minimum-balance requirements, loan interest and other service charges. Always review the specific account terms before joining.
Risks and Limitations to Consider
Access can vary significantly between credit unions. One institution may have convenient branches and shared-branch access, while another may rely more heavily on digital banking. Product selection, ATM availability and mobile features can also differ. You should also verify the institution’s share-insurance status and understand which accounts are covered and what limits apply.
Expert Tips Before You Join
- Read the account agreement and current fee schedule.
- Check minimum opening deposits and balance requirements.
- Compare loan APRs, fees and total borrowing costs.
- Review branch, ATM, shared-branch and digital access.
- Verify the credit union’s applicable share-insurance coverage before depositing significant funds.
SMART CHECK
Don’t judge an account by its headline rate alone. Compare the rate, fees, requirements, access and applicable insurance coverage together before making a decision.
Common Credit Union Mistakes + Illustrative Example
Knowing how credit unions work is useful, but the account details matter just as much. Many mistakes happen when people focus on the cooperative label and skip the practical terms that affect their everyday banking.
Mistakes to Avoid
- Not checking eligibility: Confirm that you qualify before spending time comparing accounts.
- Ignoring account requirements: Review monthly fees, minimum balances, opening deposits and transaction rules.
- Assuming all credit unions are alike: Products, rates, technology, branches and ATM access can differ.
- Comparing only the advertised rate: Consider fees and other account conditions alongside the rate.
A Simple Example
Imagine Maria qualifies for a credit union and needs a checking account. She expects to use ATMs several times a month and deposits her paycheck electronically. Before opening the account, she compares the monthly fee, minimum balance, ATM access, mobile deposit features and overdraft terms with another financial institution. The credit union may meet her needs, but if ATM availability or another account feature is less convenient for her routine, she has a practical factor to weigh before joining.
THE LESSON
Don’t choose an account based only on the institution’s label. Compare the specific fees, requirements, access, services and applicable insurance coverage against how you actually plan to use the account.
Who May Benefit From a Credit Union?
A credit union may fit your needs when its membership rules, account terms, services and access align with how you manage money. The cooperative structure gives eligible members an ownership role, but that feature is only one part of the decision. Your everyday costs, account features and access should also match your priorities.
A Credit Union May Fit If You:
- Meet the institution’s membership eligibility requirements.
- Want checking, savings, lending or other financial services from the same institution.
- Value having an ownership and voting role under the cooperative’s governing rules.
- Can conveniently use the credit union’s branches, ATMs, shared-branch network or digital services.
- Find its fees, rates, minimum requirements and account features suitable for your needs.
The same comparison process applies whether you’re managing everyday spending, saving for a goal or looking for borrowing options. If you’re comparing online banking with cooperative banking, see our guide to digital banks vs. credit unions.
A PRACTICAL RULE
Eligibility determines whether you can join. After that, compare the account terms, costs, access, services and applicable insurance coverage before opening an account.
Frequently Asked Questions About How Credit Unions Work
1. How do credit unions work?
Credit unions operate as member-owned financial cooperatives. Eligible members can use savings, checking, lending and other financial services. The institution manages its resources, earns revenue and uses that revenue to cover operating expenses and maintain financial strength.
2. Are credit unions banks?
No. Credit unions and banks can offer many similar financial products, but their organizational structures differ. Credit unions are member-owned cooperatives, while banks may be shareholder-owned or privately owned.
3. How does a credit union generate revenue?
Credit unions can generate revenue from loan interest, fees and other financial activities. That revenue helps pay operating expenses, support financial operations and maintain the institution’s financial condition.
4. Do credit unions have checking and savings accounts?
Yes. Many credit unions offer both. They may use different terminology, such as share accounts for savings and share draft accounts for checking.
5. Are credit union accounts insured?
Accounts at federally insured credit unions may receive NCUA share insurance, subject to applicable coverage limits and rules. Check the institution’s insurance status and account coverage before depositing money.
6. Can anyone join a credit union?
Not necessarily. Credit unions generally have a defined field of membership. Eligibility can depend on factors such as location, employment, family relationships or membership in a qualifying organization.
7. Can credit unions offer loans?
Yes. Depending on the institution, credit unions may offer auto loans, personal loans, mortgages, credit cards and other financing. Approval, rates and terms depend on the specific product and borrower.
8. What should I check before joining a credit union?
Check eligibility, fees, minimum balances, APYs, loan rates, ATM and branch access, digital banking features, account terms and applicable share insurance. Compare those details with your actual banking needs.
Final Verdict: How Do Credit Unions Work?
So, how do credit unions work? The model is built around eligible members who use and collectively own a cooperative financial institution. The credit union manages member shares and other resources, provides financial services, makes loans to qualified borrowers and uses revenue to cover operating expenses and maintain financial strength.
For someone considering membership, the ownership structure is only the starting point. The practical details can differ by institution, including membership eligibility, account fees, rates, minimum balances, ATM access, digital banking features, loan terms and applicable share insurance.
BOTTOM LINE
A credit union combines cooperative ownership with everyday financial services. Before joining, review the specific institution’s terms and compare them with the way you actually plan to save, spend or borrow.
Related Resources & Authority Sources
If you want to continue researching credit unions, start with our complete Credit Unions Explained guide. You can also compare different banking models with our guide to digital banks vs. credit unions.
Official Authority Sources
- NCUA Share Insurance Coverage — explains federal share insurance, coverage limits and how to verify whether a credit union is federally insured.
- NCUA Field of Membership Resources — explains how a credit union’s field of membership determines who may join.
- FDIC Deposit Insurance — provides official information about deposit insurance at FDIC-insured banks.
RESEARCH TIP
Before opening an account, use the institution’s current disclosures and official regulator information to verify membership eligibility, fees, rates, account terms and applicable insurance coverage.
Have a Money Question? Keep Exploring.
Credit unions are just one part of the banking landscape. As you compare your options, keep looking at the details that affect your everyday money decisions, including fees, account features, access, rates and applicable protections.
📩 Get in Touch With FinanceInvestment
Have a personal-finance question or a topic you’d like FinanceInvestment to explain?
Leave a Reply