Tag: Cash Management

  • How Much Can $100,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $100,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $100,000 Earn in Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 20, 2026


    Reading Time: ~14 minutes

    How Much Can $100,000 Earn in Treasury Bills?

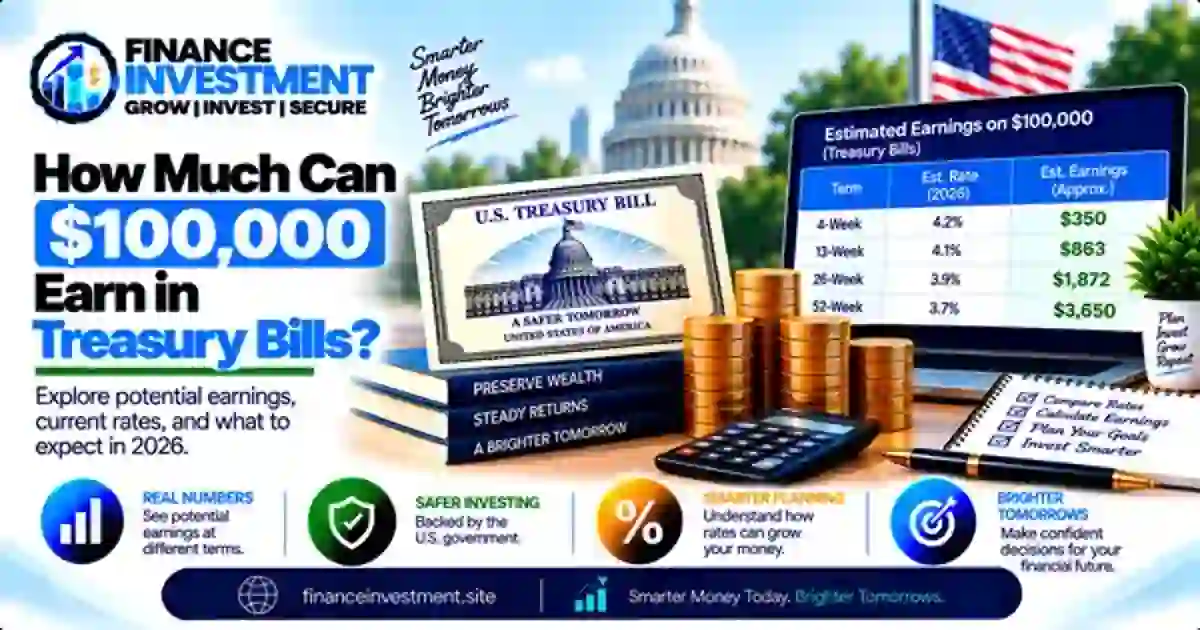
    How Much Can $100,000 Earn in Treasury Bills?How Much Can $100,000 Earn in Treasury Bills? The answer depends on the purchase price, maturity and yield available when you invest. With $100,000 involved, even a relatively small change in the purchase price can affect the dollar amount of your gross return.

    Treasury bills also work differently from a savings account or a certificate of deposit. They generally do not make periodic coupon payments. Instead, a T-bill is typically purchased for less than its face value and pays its face value at maturity when held to maturity. That makes both the amount you pay and the date your money becomes available important parts of the decision.

    What You’ll Learn

    • How a $100,000 T-bill investment can generate a gross return.
    • How 4-, 8-, 13-, 26- and 52-week maturities affect your cash timeline.
    • Why the purchase price matters when estimating dollar earnings.
    • How federal taxes, early sales and reinvestment can affect the outcome.
    • What to consider before committing a large cash balance to Treasury bills.

    If Treasury bills are new to you, start with our

    complete Treasury Bills guide

    for the basic terminology and mechanics before moving into the $100,000 examples and maturity comparisons below.

    Quick Answer: What Could $100,000 Earn?

    A $100,000 Treasury bill investment can produce different gross returns depending on its purchase price, maturity and yield at the time you buy. If a bill has a $100,000 face value and you purchase it below that amount, the difference between your purchase price and the face value is the gross return when the bill reaches maturity.

    Key Takeaways

    • A $100,000 face-value T-bill may cost less than $100,000 when purchased at a discount.
    • The difference between the purchase price and face value represents the gross return at maturity.
    • T-bill yields are annualized, so a quoted annual rate is not the same as the exact dollar return for every maturity.
    • Shorter maturities return the money sooner, while longer maturities keep the funds committed for a longer period.
    • Treasury bill income is generally subject to federal income tax but exempt from state and local income taxes.
    • Reinvesting after maturity can produce a different return because future T-bill yields may change.
    BOTTOM LINE

    There is no single earnings figure for every $100,000 T-bill investment. The actual result starts with the purchase price and face value, then depends on the maturity, taxes and what you do with the money afterward.

    $100,000 Treasury Bill Earnings at a Glance

    A $100,000 Treasury bill position can generate a meaningful dollar return, but the exact amount depends on the price you pay and the bill’s maturity. The quoted yield is annualized, so it should not be treated as the exact cash earnings for every T-bill term.

    QUICK FACT
    $100,000 Face Value
    Example amount received at maturity
    RETURN SOURCE
    Face Value − Purchase Price
    Gross return when held to maturity
    BEST FOR
    Defined Cash Timelines
    Investors planning around a maturity date

    Key Numbers to Watch

    Number or TermWhat It Tells YouWhy It Matters
    $100,000Example face valueEstablishes the maturity value used in the example.
    Purchase priceAmount paid for the billDetermines the gross dollar difference at maturity.
    4–52 weeksAvailable maturity rangeDetermines when the money is scheduled to mature.
    Annualized yieldRate used for comparisonHelps compare different Treasury bill opportunities.
    QUICK TAKE

    With $100,000, the maturity date deserves close attention. First decide when the cash may be needed. Then compare the available purchase prices and annualized yields for maturities that fit that timeline.

    Complete Beginner Guide: How $100,000 in T-Bills Works

    How Much Can $100,000 Earn in Treasury Bills?If you have $100,000 available, Treasury bills can put that cash into short-term U.S. government securities for a defined period. T-bills have maturities of one year or less. They are issued at a discount and redeemed at their face, or par, amount at maturity.
    What Happens When You Buy

    Suppose you buy a hypothetical $100,000 face-value T-bill for less than $100,000. You pay the purchase price when the security is purchased. If you hold the bill until maturity, the Treasury pays the $100,000 face value. The difference between what you paid and what you receive at maturity is the gross interest earned on the bill.

    You can buy Treasury bills directly through TreasuryDirect or through a bank or brokerage. With TreasuryDirect, you select the bill’s term and par amount when scheduling a purchase. The maturity date then tells you when the bill is scheduled to be redeemed.

    BEGINNER TIP

    Before committing the full $100,000, mark the date when you may need the cash. Then compare that date with the T-bill’s maturity. For a larger balance, matching the maturity to your cash plan can help you avoid an unnecessary liquidity problem.

    For the basic mechanics behind Treasury bills, read our

    guide to how Treasury bills work
    .
    Next, we will look at how the purchase price turns into an actual dollar return.

    How T-Bill Earnings Are Calculated

    The basic calculation for a $100,000 Treasury bill starts with two numbers: the face value and the purchase price. Treasury bills are generally sold at a discount, and the Treasury pays the face value when the bill matures. The difference between those amounts is the interest earned when the bill is held to maturity.

    The Basic Dollar Calculation

    Gross Return = Face Value − Purchase Price

    For example, imagine a hypothetical $100,000 face-value T-bill with a purchase price of $98,500. If you hold it until maturity, the difference is $1,500. That $1,500 is the gross interest earned before applicable taxes. This example is for illustration only and is not a current Treasury auction quote.

    Why the Quoted Rate Can Look Different

    Treasury bill pricing uses an annualized discount-rate convention based on a 360-day year. TreasuryDirect also reports an investment rate or yield, which is an annualized simple-interest measure based on the purchase price and a 365-day year, or 366 days when applicable during a leap year. Because these measures use different bases, the quoted discount rate and investment rate are not interchangeable.

    CALCULATION TIP

    For a $100,000 investment, start with the actual purchase price, face value and maturity date. Do not simply multiply $100,000 by an annualized rate and treat that figure as the exact T-bill earnings.

    For a closer explanation of the terminology, read our

    Treasury Bill Yield vs. Interest Rate guide
    .

    Benefits and Drawbacks of Investing $100,000 in T-Bills

    A $100,000 Treasury bill position can offer a defined maturity date and a relatively straightforward return structure. However, putting a large amount into one short-term security also means paying attention to access to cash, taxes and what happens when the bill matures.

    Benefits

    • A known maturity date can make short-term cash planning easier.
    • Treasury bills are obligations of the U.S. government.
    • T-bill interest is generally exempt from state and local income taxes.
    • Different maturities can help spread a larger cash balance across several dates.

    Drawbacks

    • Holding the bill to maturity means waiting for its scheduled maturity date to receive the face value.
    • Future T-bill yields may be higher or lower when you reinvest the proceeds.
    • Selling before maturity exposes you to the current secondary-market price, which can differ from your purchase price.
    • T-bills are designed for short-term cash management rather than long-term growth from ownership of businesses or other assets.
    BEFORE YOU INVEST

    With $100,000, start with your cash timeline rather than the headline yield. Decide when the money may be needed, then compare T-bill maturities and pricing that fit that timeline.

    4-, 8-, 13-, 26- and 52-Week Treasury Bill Comparison

    If you are considering $100,000 in Treasury bills, the maturity date can be just as important as the quoted yield. This comparison focuses on five common T-bill terms: 4, 8, 13, 26 and 52 weeks. Treasury also offers other bill maturities, so these terms should be viewed as a practical comparison rather than a complete list of every available bill.

    MaturityApprox. TimelineCash-Planning RoleMain Consideration
    4 weeksAbout 1 monthVery near-term cashThe money reaches maturity relatively soon, creating an earlier reinvestment decision.
    8 weeksAbout 2 monthsNear-term cashGives you a little more time before the next maturity and reinvestment decision.
    13 weeksAbout 3 monthsShort-term cash planningCan fit a cash need that falls roughly three months ahead.
    26 weeksAbout 6 monthsMedium-term cash planningThe funds remain committed longer before the scheduled maturity.
    52 weeksAbout 1 yearLonger cash horizonThe money stays committed much longer before the next maturity decision.

    Does a Longer T-Bill Always Mean More Earnings?

    Not necessarily. Your actual dollar return depends on the purchase price, face value, maturity and yield available when you buy. A 52-week bill does not automatically produce a larger return simply because it has a longer term. Yields can differ across maturities and can change from one auction to another.

    Your cash needs matter too. If you expect to use part of the $100,000 within a few months, putting the entire amount into a longer-term bill could create a liquidity problem. A T-bill ladder can spread purchases across different maturity dates instead of concentrating the entire balance around one maturity.

    MATURITY TIP

    Start with the date when you may need the money. Then compare the available T-bill terms, purchase prices and current auction yields. That keeps the maturity decision connected to your cash plan rather than focusing only on the headline rate.

    Costs, Taxes, Risks and Expert Tips

    When $100,000 is involved, the quoted T-bill yield is only one part of the picture. Taxes, liquidity, reinvestment and the way you purchase or sell the bill can all affect the practical result.

    Taxes and Purchase Costs

    Interest from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes. For T-bills, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. TreasuryDirect does not charge a purchase fee or commission, although a bank or brokerage may have its own fees.

    Risks to Keep in Mind

    • Selling before maturity can expose you to a secondary-market price that differs from what you originally paid.
    • Reinvestment risk matters because the yield available when your bill matures may be different from today’s yield.
    • Inflation can reduce the purchasing power of your return even when the investment produces a positive nominal return.
    EXPERT TIP

    Before committing the full $100,000, check the maturity date against your expected cash needs. If you might need the money early, understand how your bank or broker handles secondary-market sales and review any applicable charges before buying.

    When comparing T-bills with other short-term choices, look beyond the headline yield. The tax treatment, maturity date and access to your money can change how useful the investment is for your particular cash plan.

    Common Mistakes and a $100,000 Treasury Bill Example

    A $100,000 Treasury bill purchase deserves more than a quick look at the quoted yield. The purchase price, maturity date and plan for the proceeds can all affect how the investment fits into your finances.

    Common Mistakes to Avoid

    • Treating an annualized T-bill yield as the exact dollar return for the entire maturity.
    • Assuming that having $100,000 in cash means the bill’s face value must also be exactly $100,000.
    • Choosing a maturity without checking when the money may actually be needed.
    • Assuming the same yield will be available when the bill matures and the proceeds are reinvested.
    • Selling before maturity without checking the current market price and any applicable transaction costs.

    A $100,000 Example

    Suppose an investor buys a hypothetical $100,000 face-value Treasury bill for $98,500.

    $100,000 − $98,500 = $1,500 gross return

    This is an illustrative example, not a current Treasury auction or market quote. The actual purchase price depends on the applicable Treasury pricing.

    If the investor holds the bill until maturity, the Treasury pays the $100,000 face value. The $1,500 difference is the gross return before applicable taxes. The example does not by itself establish an annualized yield because the maturity period is also needed for that calculation.

    CHECK BEFORE BUYING

    Before committing the full $100,000, confirm the face value, purchase price and maturity date. Then consider the federal tax treatment and when you expect to need the proceeds.

    Who Should Consider $100,000 in T-Bills?

    A $100,000 Treasury bill position may make sense for someone who has a substantial amount of cash available for a defined period and wants a scheduled maturity date. The key question is not simply how much the investment can earn. It is whether the maturity, liquidity and tax treatment fit the purpose of the money.

    Situations Where T-Bills May Fit

    • You have cash that is not expected to be needed before a selected maturity date.
    • You want to divide a large cash balance across several Treasury bill maturity dates.
    • You are comparing short-term Treasury securities with other cash-management choices.
    • You are comfortable with the possibility that reinvestment yields may be different when a bill matures.
    PLANNING CHECK

    Keep emergency reserves and money needed for near-term expenses separate from funds committed to a T-bill maturity. With $100,000, dividing the money across suitable maturities can also give you more than one point at which cash becomes available.

    Frequently Asked Questions About $100,000 in Treasury Bills

    1. How much can $100,000 earn in Treasury bills?

    The amount depends on the purchase price, maturity and yield available when you invest. When held to maturity, the gross return is generally the difference between the bill’s face value and purchase price.

    2. Can I invest exactly $100,000 in Treasury bills?

    Yes. You can use $100,000 of available cash to purchase Treasury bills, subject to the applicable purchase rules and available offerings. Because T-bills are generally purchased at a discount, the face value at maturity can be greater than the amount paid.

    3. Do Treasury bills pay monthly interest?

    No. Treasury bills generally do not make periodic coupon payments. They are typically purchased at a discount and pay their face value at maturity.

    4. Are Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Your individual tax situation can affect the amount you ultimately keep.

    5. Can I sell a Treasury bill before maturity?

    Yes. Treasury bills can generally be sold before maturity through a bank or broker in the secondary market. The market price at the time of sale can be higher or lower than your original purchase price.

    6. Which T-bill maturity should I choose for $100,000?

    There is no single maturity that fits every cash plan. Consider when you may need the money, then compare the available terms, purchase prices and annualized yields that fit that timeline.

    7. Can I reinvest $100,000 after a T-bill matures?

    You can use the maturity proceeds to purchase another Treasury bill. The next bill may have a different purchase price and yield, so its potential return may differ from the previous investment.

    8. Are Treasury bills completely risk-free?

    Treasury bills are U.S. government obligations, but investors can still face risks and limitations. Inflation can reduce purchasing power, future yields can change, and selling before maturity can expose you to changing market prices.

    Final Takeaway: How Much Can $100,000 Earn in Treasury Bills?

    The answer to How Much Can $100,000 Earn in Treasury Bills? depends on the purchase price, maturity and yield available when you invest. Because those factors can change, there is no single earnings figure that applies to every $100,000 T-bill purchase.

    When held to maturity, a Treasury bill generally pays its face value. The difference between the face value and purchase price represents the gross return before applicable taxes. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    THE BIG PICTURE

    For a $100,000 investment, pay attention to what you pay, when the bill matures and how you plan to use the proceeds. Taxes, liquidity needs and future reinvestment rates can also affect the overall result.

    Before You Invest

    Check the latest Treasury bill offerings and pricing before investing because yields and auction results can change. For the broader fundamentals, explore our

    Treasury Bills guide

    before making a purchase decision.

    Have a Money Question? Keep Exploring.

    Keep researching Treasury bills, cash management and investing with practical guides from FinanceInvestment.

    📧 Get in Touch With FinanceInvestment


    Email FinanceInvestment

    Continue Your Research
  • How Much Can $50,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $50,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $50,000 Earn in Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 20, 2026


    Reading Time: ~14 minutes

    How Much Can $50,000 Earn in Treasury Bills?

    How Much Can $50,000 Earn in Treasury Bills?How Much Can $50,000 Earn in Treasury Bills? There is no single answer because your potential return depends on the T-bill’s purchase price, maturity and yield available when you invest. With $50,000, the purchase price can make a noticeable difference in the gross amount you receive at maturity.

    Treasury bills also work differently from a savings account that may credit interest periodically. A T-bill is generally purchased at a discount to its face value and pays its face value at maturity when held to maturity. That makes both the price you pay and the date your money comes back important parts of the calculation.

    What You’ll Learn

    • How earnings on a $50,000 Treasury bill are calculated.
    • How 4-, 8-, 13-, 26- and 52-week maturities affect your cash timeline.
    • Why the purchase price matters when estimating your gross return.
    • How federal taxes and early-sale pricing can affect your results.
    • What to consider before placing the full $50,000 into one T-bill maturity.

    If Treasury bills are new to you, start with our

    complete Treasury Bills guide

    for the basic terminology and mechanics before moving into the $50,000 examples and maturity comparisons below.

    Quick Answer: What Could $50,000 Earn?

    The potential earnings on $50,000 in Treasury bills depend on the purchase price, maturity and yield available when you invest. If a $50,000 face-value bill is purchased for less than $50,000 and held to maturity, the difference between those amounts is the gross return before taxes.

    Key Takeaways

    • The face value of the bill and the amount you pay for it can be different.
    • Your gross return is the difference between the purchase price and the amount paid at maturity.
    • T-bill yields are annualized, so the quoted yield should not be treated as the exact dollar return for every term.
    • A shorter maturity returns the principal sooner, while a longer maturity keeps the money invested for more time.
    • Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • If you reinvest after maturity, the next T-bill may have a different yield.
    BOTTOM LINE

    There is no single earnings figure for every $50,000 T-bill purchase. The actual result starts with the price you pay and the face value you receive at maturity, then depends on taxes and what happens if you sell or reinvest.

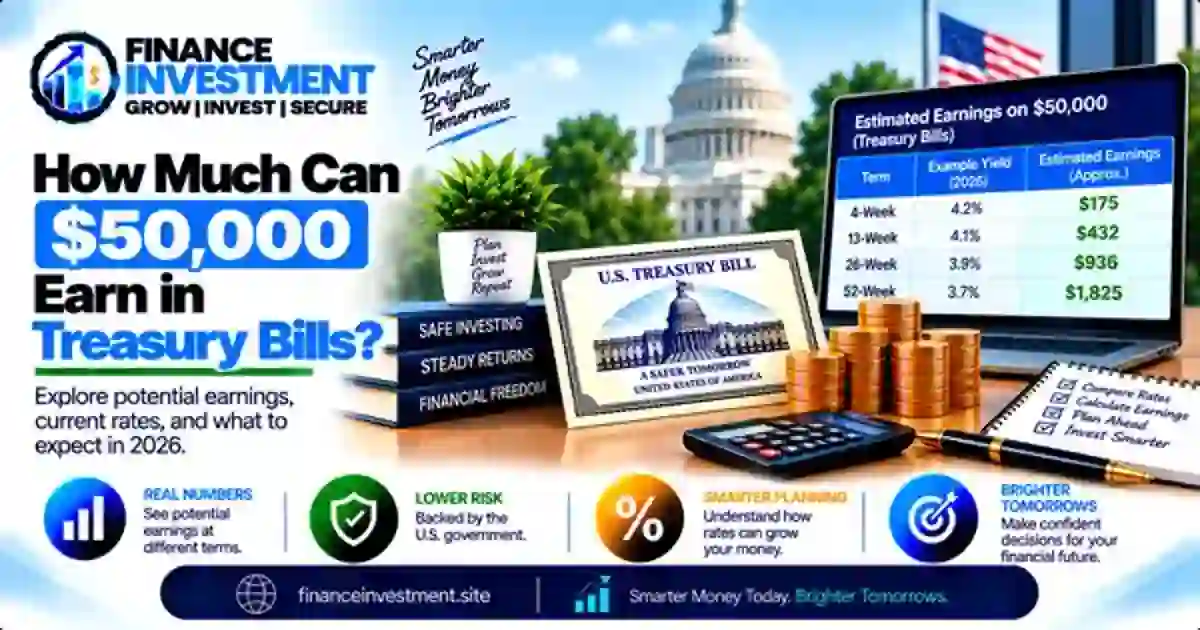
    $50,000 Treasury Bill Earnings at a Glance

    A $50,000 T-bill investment can produce different gross returns depending on the purchase price, maturity and yield available when you buy. One important detail comes first: $50,000 can be the bill’s face value or the amount of cash you have available to invest. Those are not necessarily the same thing.

    EXAMPLE FACE VALUE
    $50,000
    GROSS RETURN SOURCE
    Face Value − Purchase Price
    MAIN VARIABLES
    Price, Yield & Maturity

    Maturity and Cash-Planning Snapshot

    MaturityApprox. TimelineExample Cash-Planning Role
    4 weeksAbout 1 monthVery short-term cash timeline
    8 weeksAbout 2 monthsNear-term cash planning
    13 weeksAbout 3 monthsRoughly quarterly timing
    26 weeksAbout 6 monthsMedium-term cash planning
    52 weeksAbout 1 yearLonger cash-planning horizon
    QUICK TAKE

    With $50,000, the maturity date can be an important part of the decision because more cash is involved. Start with when you expect to need the money, then compare the available T-bill terms and pricing for that timeline.

    Complete Beginner Guide: How $50,000 in T-Bills Works

    How Much Can $50,000 Earn in Treasury Bills?Treasury bills are short-term U.S. government securities with maturities of one year or less. If you have $50,000 available, you can use that cash to purchase T-bills, but the face value of the bills you receive does not have to equal exactly $50,000 because T-bills are generally purchased at a discount.
    What Happens After You Buy

    Suppose you purchase a hypothetical T-bill with a $50,000 face value for less than $50,000. If you hold that bill until maturity, you receive its $50,000 face value. The difference between the purchase price and the face value is the gross return before taxes.

    You can buy Treasury bills through TreasuryDirect or through a bank or brokerage. The maturity you choose determines when the bill is scheduled to mature, while the auction or market price determines what you pay. That makes the amount committed and the date you need the money important parts of the decision.

    BEGINNER TIP

    Before buying, write down two things: how much cash you want to commit and when you expect to need it again. Then compare that timeline with the T-bill’s maturity. This gives you a practical starting point before you look closely at the available yield.

    If you want to review the basic mechanics first, read our

    guide to how Treasury bills work
    .
    The next section moves from the buying process to the actual earnings calculation.

    How T-Bill Earnings Are Calculated

    The potential return on a $50,000 Treasury bill comes from the difference between what you pay and the bill’s face value at maturity. Treasury bills generally do not make periodic coupon payments. Instead, they are issued or purchased at a discount and pay the face value at maturity when held to maturity.

    Basic T-Bill Return Formula

    Gross Return = Face Value − Purchase Price

    For example, suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400. If you hold it until maturity, you would receive $50,000. The $600 difference represents the gross return before applicable federal income tax.

    Why the Quoted Yield Matters

    Treasury bill rates are annualized, so a quoted rate should not be treated as the exact dollar return for a shorter maturity. Treasury auction pricing commonly uses a discount-rate convention based on face value and a 360-day year, while the investment rate expresses an annualized return based on the purchase price and the applicable day-count convention. The maturity length therefore matters when translating a quoted rate into an actual dollar result.

    CALCULATION TIP

    When estimating earnings, use the actual purchase price, face value and maturity. Avoid simply multiplying $50,000 by an annualized rate and treating that number as the final return.

    For a closer look at Treasury bill pricing terminology, read our

    Treasury Bill Yield vs. Interest Rate guide
    .

    Benefits and Drawbacks of Investing $50,000 in T-Bills

    Investing $50,000 in Treasury bills can give you a defined maturity date and exposure to short-term U.S. government securities. However, the right maturity depends on when you may need the cash and what you plan to do with it afterward.

    Benefits

    • Short maturities can provide a defined timeline for returning the principal.
    • Treasury bills are obligations of the U.S. government.
    • T-bill interest income is generally exempt from state and local income taxes.
    • Different maturities allow you to match the investment with different cash needs.

    Drawbacks

    • Holding a bill to maturity means waiting until its scheduled maturity date for the face-value payment.
    • Reinvestment can produce a different return if future T-bill yields change.
    • Selling before maturity can result in a market price that is different from what you originally paid.
    • T-bills provide a defined short-term return structure rather than the ownership-based growth potential of stocks.
    BEFORE YOU INVEST

    With $50,000 involved, start with your cash timeline before focusing on the quoted yield. A maturity that fits your planned spending can be more useful than choosing a term based only on its annualized rate.

    4-, 8-, 13-, 26- and 52-Week Treasury Bill Comparison

    The maturity you choose determines how long the $50,000 remains invested before the bill reaches its scheduled maturity date. A shorter term can return the principal sooner, while a longer term extends the period before the next maturity or reinvestment decision.

    MaturityApprox. TimelineCash-Planning RoleMain Consideration
    4 weeksAbout 1 monthVery near-term cash timingShort investment period
    8 weeksAbout 2 monthsNear-term cash timingEarlier reinvestment decision
    13 weeksAbout 3 monthsQuarterly cash timingYield depends on purchase timing
    26 weeksAbout 6 monthsMedium-term cash timingCash stays invested longer
    52 weeksAbout 1 yearLonger cash-planning horizonMaturity is farther away

    Does a Longer Maturity Mean More Earnings?

    Not necessarily. Your actual dollar return depends on the purchase price, face value, maturity and yield available when you buy. A 52-week bill does not automatically produce a larger return simply because it has a longer maturity.

    The maturity you select should also fit your cash needs. If you expect to use part of the $50,000 within a few months, putting that entire amount into a longer-term bill may create a timing problem. A ladder can instead spread purchases across different maturity dates so that portions of the money become available at different times.

    MATURITY TIP

    Start with the date you may need the money. Then compare available T-bill maturities, purchase prices and annualized yields. This keeps both liquidity and potential return in view.

    Costs, Taxes, Risks and Expert Tips

    Before putting $50,000 into Treasury bills, look beyond the quoted yield. The purchase method, taxes, liquidity and the possibility of selling before maturity can all affect the practical outcome.

    Costs and Taxes

    TreasuryDirect does not charge a fee to purchase Treasury securities. Banks and brokerages can have their own account, transaction or trading charges, so review the institution’s current fee schedule before investing. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    Risks to Keep in Mind

    • Selling before maturity can produce a market price that is different from your original purchase price.
    • Reinvestment risk matters because future T-bill yields can change when your bill matures.
    • Inflation can reduce the purchasing power of the return over time.
    EXPERT TIP

    Compare the maturity date with your expected cash needs before focusing on the quoted yield. If early access could matter, understand how your bank or broker handles secondary-market sales and what charges may apply.

    The federal tax treatment can also make T-bills different from some other cash investments. Keep the tax effect in mind when comparing your expected after-tax results.

    Common Mistakes and a $50,000 Treasury Bill Example

    When you invest $50,000 in Treasury bills, the biggest mistakes often come from overlooking the details around price, maturity and reinvestment. A clear plan can help you understand what the investment is actually expected to return and when the money may become available again.

    Mistakes to Avoid

    • Treating an annualized yield as the exact dollar return for the entire maturity.
    • Confusing $50,000 of available cash with a $50,000 face-value T-bill.
    • Choosing a maturity without considering when the cash may be needed.
    • Assuming the same yield will be available when the bill matures and you reinvest.
    • Selling before maturity without checking the current market price and any applicable transaction costs.

    Illustrative $50,000 Example

    Suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400.

    $50,000 − $49,400 = $600 gross return

    This is an illustrative purchase-price example, not a current Treasury quote. The actual purchase price depends on the applicable auction or market conditions.

    If the bill is held to maturity, the investor receives its $50,000 face value. The $600 difference represents the gross return before applicable taxes. The actual annualized yield cannot be determined from these two dollar amounts alone because the maturity period also matters.

    CHECK BEFORE BUYING

    Confirm the face value, purchase price, maturity date and applicable tax treatment before committing the full $50,000.

    Who Should Consider $50,000 in T-Bills?

    A $50,000 Treasury bill allocation may be relevant for investors who have cash available for a defined period and want to use short-term U.S. government securities as part of their cash-management strategy. The appropriate maturity depends on when the money may be needed and whether the investor plans to reinvest the proceeds.

    Situations to Consider

    • You have cash that you do not expect to need before a selected maturity date.
    • You want to spread a larger cash balance across different T-bill maturity dates.
    • You are comparing Treasury bills with other short-term cash-management choices.
    • You understand that the yield available for a future reinvestment can change.
    PLANNING CHECK

    Before committing $50,000, separate money needed for near-term expenses or emergencies from money available for a chosen T-bill maturity. A Treasury bill can serve a specific cash-management purpose without being the only part of an overall financial plan.

    Frequently Asked Questions About $50,000 in Treasury Bills

    1. How much can $50,000 earn in Treasury bills?

    It depends on the purchase price, maturity and yield available when you invest. When held to maturity, the gross return is generally the difference between the bill’s face value and purchase price.

    2. Can I use exactly $50,000 to buy Treasury bills?

    Yes. You can commit $50,000 of available cash to a Treasury bill purchase, subject to the applicable purchase rules. Because T-bills are generally bought at a discount, the face value received at maturity can be higher than the amount you paid.

    3. Do Treasury bills pay monthly interest?

    No. Treasury bills generally do not make periodic coupon payments. They are typically purchased at a discount and pay their face value at maturity.

    4. Are Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    5. Can I sell a Treasury bill before maturity?

    Yes. Treasury bills can generally be sold before maturity through a bank or broker in the secondary market. The selling price can be higher or lower than your original purchase price.

    6. Which T-bill maturity should I choose for $50,000?

    There is no single maturity that fits every cash need. Consider when you expect to need the money, then compare the available maturities, purchase prices and annualized yields.

    7. Can I reinvest my $50,000 after a T-bill matures?

    Yes. After maturity, you can use the proceeds or purchase another Treasury bill. The yield available for the new bill may differ from the previous investment.

    8. Are Treasury bills completely risk-free?

    Treasury bills are U.S. government obligations, but “completely risk-free” can be misleading. Holding a bill to maturity avoids the need to sell at a changing market price, while inflation, reinvestment and early-sale considerations can still affect your overall result.

    Final Takeaway: How Much Can $50,000 Earn in Treasury Bills?

    The answer to How Much Can $50,000 Earn in Treasury Bills? depends on the purchase price, maturity and yield available when you invest. That means there is no single earnings figure that applies to every $50,000 T-bill purchase.

    When held to maturity, a Treasury bill generally pays its face value. The difference between the face value and purchase price represents the gross return before applicable taxes. Federal income tax can apply, while Treasury bill interest is generally exempt from state and local income taxes.

    THE BIG PICTURE

    For a $50,000 investment, pay attention to three core details: the purchase price, the face value at maturity and the date the money becomes available. Then account for taxes and your plans for the proceeds after maturity.

    Before You Invest

    Compare the available T-bill maturities, purchase prices and current auction information for the date you plan to invest. If you want to review the fundamentals again, explore our

    Treasury Bills guide

    before comparing specific opportunities.

    Have a Money Question? Keep Exploring.

    Get practical personal finance insights, investing guides and helpful money research from FinanceInvestment.

    📩 Get in Touch With FinanceInvestment


    Email FinanceInvestment

    Continue Your Research
  • What Happens When a Treasury Bill Matures? A 2026 Guide

    What Happens When a Treasury Bill Matures? A 2026 Guide

    What Happens When a Treasury Bill Matures?

    SR
    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 17, 2026


    Reading Time: ~11 minutes

    When a Treasury Bill Reaches Maturity

    What Happens When a Treasury Bill Matures?What happens when a Treasury bill matures? For most investors, the process is straightforward. The bill reaches its maturity date, and the U.S. Treasury pays its face value according to the security’s terms. If you purchased the bill for less than its face value, the difference represents your return.

    The bigger question comes next. Once the money becomes available, you can use the proceeds, move the cash to another account, or reinvest in another Treasury bill. The right choice depends on when you need the money, what yields are available, and how long you want to keep your cash invested.

    So, the maturity date is not simply the finish line. It is also a natural point to review your next move. Our Treasury Bills Explained guide covers the broader topic, while this article focuses on the practical steps that follow maturity.

    What You’ll Learn

    • What happens on the Treasury bill maturity date
    • How the maturity payment works
    • What happens when you reinvest the proceeds
    • What to know about taxes and timing
    • How to think about your next use of the money

    Quick Answer: What Happens at T-Bill Maturity?

    When a Treasury bill reaches its maturity date, the bill’s term ends and the Treasury pays its face value according to the security’s terms. Because T-bills are generally bought at a discount, the difference between the purchase price and the face value represents the investor’s return. Once the proceeds are received, you can use the cash or consider another investment.

    Key Takeaways

    • The maturity date marks the end of the T-bill’s stated term.
    • The Treasury pays the bill’s face value at maturity.
    • The return generally comes from purchasing the bill below face value.
    • After maturity, you can use, transfer, or reinvest the proceeds.
    • TreasuryDirect offers reinvestment options for eligible Treasury bills.
    • Federal income tax generally applies to Treasury interest, while state and local income taxes generally do not.
    Bottom Line:

    Treasury bill maturity gives you a clear decision point. You can take the proceeds, put the money toward a goal, or reinvest it based on your current cash needs.

    Treasury Bill Maturity at a Glance

    When a Treasury bill matures, its scheduled term ends and the Treasury makes the maturity payment according to the bill’s terms. If you purchased the bill at a discount, the difference between your purchase price and its face value generally represents your return.

    Quick FactWhat It Means
    Maturity dateThe date when the Treasury bill reaches the end of its stated term
    Maturity paymentThe bill’s face value is paid according to its terms
    Investor returnGenerally the difference between the purchase price and face value
    After maturityUse the proceeds, move the cash, or consider another investment
    Best forInvestors planning for a future cash need or deciding what to do with the proceeds
    QUICK TAKE:

    Maturity is a natural checkpoint for your cash plan. Once the bill reaches its end date, the next decision is what you want to do with the proceeds.

    Complete Beginner Guide to Treasury Bill Maturity

    What Happens When a Treasury Bill Matures?If you are new to Treasury bills, maturity is simply the point when the bill’s stated term ends. You purchase the bill, hold it during the term, and receive its face value at maturity according to its terms. Because T-bills are generally issued at a discount, the amount you paid can be lower than the amount you receive.

    What Happens While You Hold the Bill?

    Treasury bills do not make regular coupon payments. Instead, the return is generally built into the purchase price. For example, if a bill has a $1,000 face value and you pay $970, the $30 difference represents the return before applicable taxes.

    You can hold the bill until its maturity date. If you need the money sooner, you may be able to sell the security through a bank or brokerage that supports Treasury securities. However, the market price can change before maturity, so the amount you receive from an early sale may be different from what you originally paid.

    What Happens When the Bill Matures?

    On the maturity date, the Treasury bill reaches the end of its term and the Treasury makes the scheduled payment. After the proceeds become available, you can use the money for a financial goal, move it to another cash account, or put it into another investment.

    Can You Reinvest the Proceeds?

    Yes. TreasuryDirect allows eligible Treasury bill investments to be scheduled for reinvestment. This can make it easier to continue a short-term Treasury strategy without manually starting from scratch each time.

    Beginner Tip:

    Check your maturity date before buying and decide in advance what you want the proceeds to do. That simple step can prevent a last-minute cash decision.

    What Happens When a Treasury Bill Matures?

    When a Treasury bill matures, its stated term ends. If you have held the bill until maturity, you generally do not need to sell it. Instead, the Treasury makes the scheduled maturity payment based on the bill’s face value and terms. Your original purchase price determines how much you invested, while the difference generally represents your return.

    1. The Bill Reaches Its Maturity Date

    Every Treasury bill has a specific maturity date established when it is issued. On that date, the bill reaches the end of its term. For example, if you purchased a $1,000 face-value T-bill for $970 and held it to maturity, the scheduled payment is based on the $1,000 face value. The $30 difference is the return before applicable taxes.

    2. The Maturity Proceeds Are Credited

    Where the money goes depends on how you purchased and hold the bill. With TreasuryDirect, maturity proceeds are handled through your TreasuryDirect account according to the applicable instructions. With a brokerage, the proceeds are generally reflected in the brokerage account under that firm’s procedures.

    3. You Choose What to Do Next

    Once the proceeds are available, you can use the money for a planned expense, move it to an appropriate cash account, or consider another investment. If your goal has changed since you bought the T-bill, maturity gives you a natural opportunity to reassess your cash needs.

    4. Reinvestment Starts a New Investment

    Eligible TreasuryDirect Treasury bills can be scheduled for reinvestment. A reinvestment means the proceeds are used to purchase another Treasury bill when the new bill is issued. The new bill has its own maturity date and auction-determined terms, so its yield may differ from the original investment.

    Key Point:

    Maturity does not automatically mean you must invest again. Your original T-bill ends, the maturity proceeds are handled through your account, and you then decide whether to spend, save, or reinvest the money.

    Benefits and Drawbacks of Treasury Bill Maturity

    A maturing Treasury bill gives you a defined point at which the investment ends and the proceeds can be redirected. That can make planning easier, but there are still a few trade-offs to consider before deciding what to do next.

    Pros

    • Defined maturity date: You know when the bill is scheduled to reach the end of its term.
    • Predictable maturity value: When held to maturity, the Treasury pays the bill’s face value according to its terms.
    • Useful for planning: The maturity date can be matched with a known future cash need.
    • Reinvestment available: Eligible TreasuryDirect bills can be scheduled for reinvestment.
    • State tax treatment: Treasury interest is generally exempt from state and local income taxes.

    Cons

    • Limited access before maturity: If you need the money early, you generally must sell the bill through the secondary market.
    • Early-sale price risk: The market value can be above or below your purchase price when you sell.
    • Changing reinvestment yields: A new T-bill may have a different yield from your original bill.
    • Federal taxation: Treasury interest is generally subject to federal income tax.
    Key Point:

    The maturity date gives you a clear point to reassess your money. Before reinvesting, consider your cash needs, the new available yield, and how long you are comfortable keeping the money invested.

    Maturity, Reinvestment and Cash Options

    Once a Treasury bill matures, the proceeds give you a new choice. You can reinvest the money in another Treasury bill, move it to a suitable cash account, or use it for a planned expense. The right path depends on when you expect to need the money and what you want your cash to accomplish next.

    ChoiceAccess to MoneyWhat Happens Next?May Make Sense When
    ReinvestMoney is placed into another Treasury billA new T-bill begins with its own purchase price, yield, and maturity dateYou want to keep the money invested
    Move to a cash accountGenerally more accessible than a maturing investmentThe proceeds can be transferred to an appropriate savings or money market accountYou may need the cash soon
    Use the proceedsDepends on how the funds are held and accessedThe money can be directed toward a planned expense or financial goalThe original purpose for the money has arrived
    QUICK COMPARISON:

    Reinvesting keeps the proceeds in another Treasury bill, while moving the money to a cash account can provide easier access. A new T-bill can have different terms and yield, so review the new opportunity before reinvesting.

    Taxes, Risks and Expert Tips for Treasury Bill Maturity

    Treasury bill maturity is straightforward, but taxes, early sales, and reinvestment decisions can affect how you use the money afterward. Understanding these points before maturity can make the next step easier to plan.

    How Are Treasury Bill Returns Taxed?

    Treasury bill interest is generally subject to federal income tax but is generally exempt from state and local income taxes. For a bill purchased at a discount and held to maturity, the difference between the purchase price and the amount received is generally treated as interest income for federal tax purposes.

    What Risks Should You Consider?

    Holding a T-bill until maturity is different from selling it early. If you sell before maturity, its market price can change as interest rates and market conditions move. Reinvestment also involves uncertainty because a new Treasury bill may have a different yield from the bill that just matured.

    Warning:

    Do not assume that reinvesting will preserve your previous yield. A new Treasury bill has its own auction price, yield, and maturity date.

    Expert Tips Before Maturity

    • Check the maturity date and review your plans before it arrives.
    • Decide whether you need the proceeds for an upcoming expense.
    • Compare the available yield before choosing to reinvest.
    • Keep your Treasury records for your federal tax reporting.

    Common Treasury Bill Maturity Mistakes

    A Treasury bill can be easy to hold, but the maturity date deserves some attention. The investment may be ending, yet you still need to decide what should happen to the money next.

    Mistakes to Avoid

    • Forgetting the maturity date: You may not have enough time to plan how the proceeds will be used.
    • Reinvesting automatically without reviewing the new yield: A new T-bill has its own auction price and yield.
    • Overlooking upcoming expenses: Money you expect to need soon may deserve a more accessible home.
    • Confusing early sale with maturity: Selling before maturity means accepting the market price available at that time.
    • Ignoring tax treatment: Federal taxes can affect the amount of your return that you ultimately keep.

    A Simple Real-Life Example

    Suppose Sarah buys a Treasury bill with a $10,000 face value for $9,700. She plans to hold it until maturity. If she holds the bill through maturity, the Treasury pays the $10,000 face value according to its terms. The $300 difference between her purchase price and the face value represents her return before applicable taxes.

    Sarah now needs to decide what happens next. If she has a planned home repair, she could use the proceeds for that expense. If she does not need the money, she could consider another Treasury bill, a money market account, or another suitable option. The new decision should reflect her current financial timeline.

    SMART MOVE:

    Treat the maturity date as a financial checkpoint. Review your upcoming needs first, then decide where the proceeds belong.

    Who Should Consider a Treasury Bill?

    A Treasury bill may be worth considering when you have cash that can remain invested for its full term and you have a clear idea of when you may need the money. A defined maturity date can make it easier to connect the investment with a future expense or savings goal.

    It May Fit If You

    • Have cash you do not expect to need before maturity.
    • Want to hold a U.S. Treasury security.
    • Can match the bill’s maturity date with a future cash need.
    • Value the generally favorable state and local tax treatment of Treasury interest.
    • Prefer a maturity-based return rather than periodic coupon payments.

    When Another Option May Be Worth Comparing

    If you expect to need the money before maturity, consider how easily you can access the funds. A savings or money market account may provide different access features, while a shorter-term Treasury bill may better match a nearer cash need.

    SIMPLE CHECK:

    Look at the date first. If the maturity timeline matches your financial goal, you can then compare the available yield, taxes, access, and other terms.

    Frequently Asked Questions About Treasury Bill Maturity

    1. What happens when a Treasury bill matures?

    When a Treasury bill reaches its maturity date, its term ends and the Treasury makes the scheduled payment according to the bill’s terms. The proceeds are then handled through the account where you hold the security.

    2. Do I receive a separate interest payment when a T-bill matures?

    Generally, no. T-bills do not make periodic coupon payments. They are typically purchased at a discount, and the difference between the purchase price and face value generally represents the return.

    3. What happens to my money after a Treasury bill matures?

    You can use the maturity proceeds for a planned expense, move the money to an appropriate cash account, or consider another investment. The exact process depends on where you hold the T-bill.

    4. Can I reinvest a matured Treasury bill?

    Yes. Eligible TreasuryDirect Treasury bills can be scheduled for reinvestment. The new purchase has its own price, yield, and maturity date.

    5. Is a Treasury bill automatically reinvested at maturity?

    Not necessarily. Reinvestment depends on your instructions and the platform or account you use. Check your settings before the maturity date if you want to continue investing the proceeds.

    6. Are Treasury bill returns taxable when the bill matures?

    Treasury bill interest is generally subject to federal income tax but is generally exempt from state and local income taxes. Keep your Treasury tax records for your federal tax reporting.

    7. Can I sell a Treasury bill before maturity?

    Generally, yes, if your bank or brokerage supports secondary-market Treasury transactions. The market price can change before maturity, so you may receive more or less than your original purchase price.

    8. What should I do before my T-bill matures?

    Check the maturity date, review upcoming expenses, compare current Treasury yields, and decide whether you want to use, move, or reinvest the proceeds.

    Final Thoughts on Treasury Bill Maturity

    When a Treasury bill matures, its stated term ends and the Treasury makes the scheduled maturity payment according to the bill’s terms. For a bill purchased at a discount, the difference between the purchase price and face value generally represents the investor’s return.

    What happens next depends on your financial plans. You may need the proceeds for an upcoming expense, want to keep the money accessible, or decide to reinvest in another Treasury bill. If you reinvest, remember that the new bill has its own purchase price, yield, and maturity date.

    For a broader look at how Treasury bills work, visit our Treasury Bills Explained guide. It can help you understand where T-bills fit alongside other Treasury securities and short-term cash options.

    BOTTOM LINE:

    Treat maturity as a planning checkpoint. Before deciding what to do with the proceeds, consider your cash needs, available yields, tax treatment, and how soon you may need the money.

    Have a Money Question? Keep Exploring.

    Your T-bill may have reached maturity, but your cash plan can keep moving. Explore FinanceInvestment for practical guides on Treasury bills, savings accounts, CDs, and money market accounts.

    📩 Get in Touch With FinanceInvestment


    Email Us