How Do Treasury Bills Make Money? A Complete Beginner Guide
Treasury bills can look confusing at first. You buy a security, but you do not receive a monthly or quarterly interest payment. So, how do Treasury bills make money?
How Do Treasury Bills Make Money?
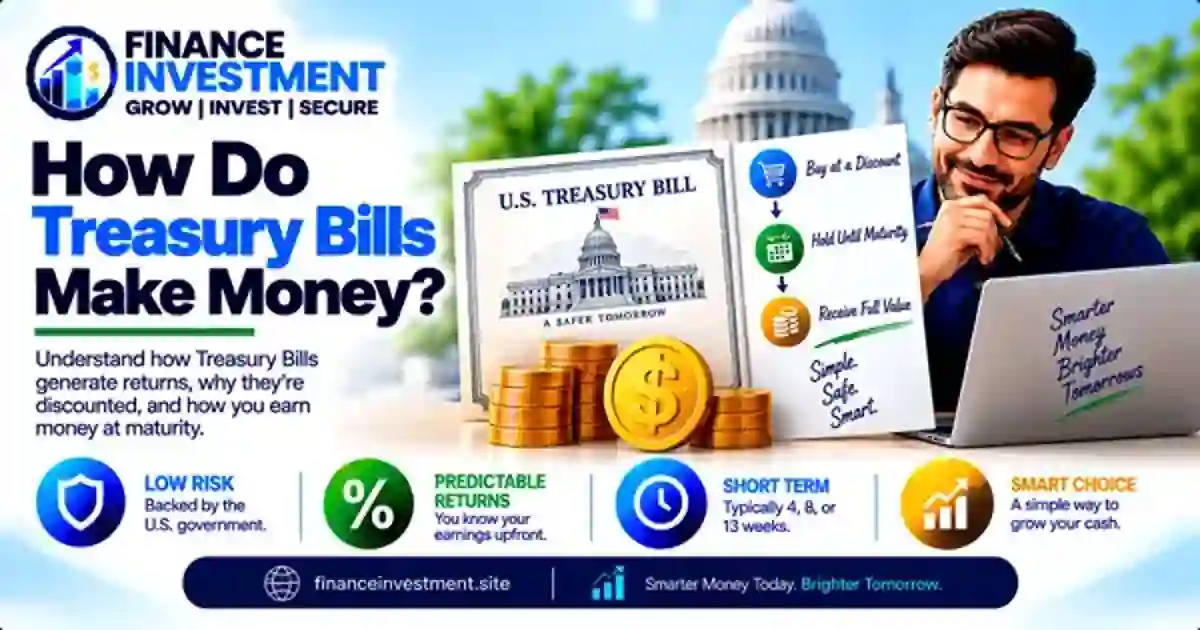 The basic idea is simple: a Treasury bill can be purchased for less than its face value and then redeemed for the full face value when it matures. That difference is your return. For example, if you pay $9,800 for a bill that pays $10,000 at maturity, the $200 difference is the gross return before taxes.
Your actual result depends on the bill’s purchase price, maturity period and annualized yield. The quoted discount rate is not always the same as the investment rate, so comparing T-bills with savings accounts or CDs requires looking at the right number.
This guide focuses on the money side of T-bills: where the return comes from, how the profit is calculated, how taxes affect it, and what happens when you reinvest the proceeds.
What You’ll Learn
How the T-bill discount creates your dollar profit.
How purchase price, maturity and yield work together.
How T-bill returns compare with savings accounts, CDs and money market accounts.
How federal taxes can change your after-tax return.
How reinvestment and T-bill ladders can turn short-term returns into an ongoing strategy.
How Do Treasury Bills Make Money? Quick Answer
Treasury bills make money for investors through the difference between the bill’s purchase price and its face value at maturity. For a bill bought below face value and held to maturity, that difference is the investor’s gross interest income.
For example, suppose a $10,000 face-value T-bill has a purchase price of $9,850. If you hold it until maturity, you receive $10,000. The $150 difference is your gross return before taxes and other applicable costs.
The return should not be judged only by the dollar difference. The bill’s maturity period matters, and Treasury reports both a discount rate and an investment rate. The investment rate is based on the purchase price and is the more useful figure for comparing a T-bill with other investments.
Key Takeaways
- The basic return is the difference between what you pay and what you receive at maturity.
- T-bills generally do not make periodic coupon payments; the return is paid at maturity.
- A T-bill’s discount rate and investment rate are calculated differently.
- Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
- Reinvesting maturity proceeds can create a repeating T-bill investment strategy.
Table of Contents
At a Glance: How T-Bills Make Money
Treasury bills generally make money for investors through the difference between the price paid and the amount received at maturity. The return is built into the purchase price rather than paid through regular coupon payments.
| Return Factor | What Happens | Effect on Your Return |
|---|---|---|
| Purchase price | You pay the price determined at the auction. | Sets your initial investment. |
| Face value | The Treasury pays the bill’s face value at maturity. | The difference from your purchase price is the gross return. |
| Maturity | The bill reaches its scheduled maturity date. | Determines how long your money was invested. |
| Investment rate | The return is expressed on an annualized basis. | Makes T-bill returns easier to compare. |
| Reinvestment | Maturity proceeds can be used to purchase another T-bill. | Can extend the strategy beyond one maturity. |
QUICK TAKE
Think of a T-bill return as the gap between the purchase price and the amount received at maturity. The investment rate then puts that return into an annualized format for easier comparison.
Where Does the Treasury Bill Return Come From?
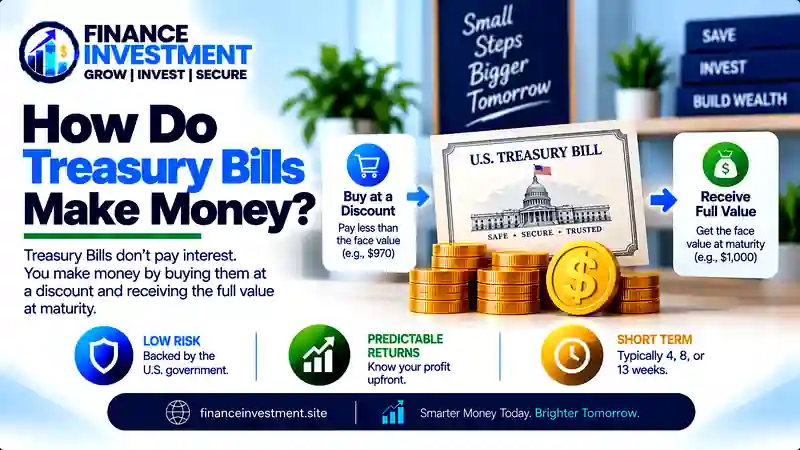 The easiest way to understand how Treasury bills make money is to stop thinking of them like a savings account. You usually do not receive a separate interest deposit every month. Instead, the return is built into the price you pay for the bill.
1. You Pay a Price for a Larger Face Value
Treasury bills have a stated face value, such as $1,000. At auction, a bill may be issued below that amount. Suppose your purchase price is $985 for a $1,000 face-value bill. If you hold it until maturity, the Treasury pays $1,000. The $15 difference is your gross return.
Simple T-Bill Return Formula
Gross return = Amount received at maturity − Purchase price
Example: $1,000 − $985 = $15 gross return.
2. The Time Period Changes the Meaning of the Return
A $15 gain does not tell you much by itself. A $15 return earned over a few weeks is different from $15 earned over a full year. That is why Treasury bills also have an annualized investment rate. It gives investors a more useful way to compare bills with other short-term investments.
3. Discount Rate and Investment Rate Are Not the Same
This is one of the easiest T-bill details to miss. The discount rate is calculated using the bill’s face value and a 360-day basis. The investment rate uses the purchase price and a 365- or 366-day basis. Because the calculations use different inputs and conventions, the two percentages can differ.
For a beginner, the practical takeaway is simple: first find the actual purchase price and maturity value. Then use the investment rate when comparing the T-bill’s annualized return with other investments.
How T-Bill Profit Works Step by Step
Once you know that the return comes from the purchase price and maturity value, the calculation becomes much easier. Here is the process an investor can follow.
Step 1: Choose the T-Bill Maturity
Treasury bills are short-term securities with maturities of one year or less. Common terms include 4, 8, 13, 17, 26 and 52 weeks. The maturity you choose determines how long your money is committed to the bill if you hold it until maturity.
Step 2: Check the Auction Price
At auction, Treasury bills are generally sold at a discount to face value, although they can also be issued at par. Your purchase price is the amount used to calculate your actual dollar investment.
Step 3: Calculate the Dollar Return
Illustrative example
Face value: $10,000
Purchase price: $9,900
Gross return at maturity: $100
Calculation: $10,000 − $9,900 = $100
Step 4: Look at the Annualized Investment Rate
The $100 profit above is a dollar amount, not an annual yield. Treasury’s investment rate annualizes the return using the purchase price and the actual term. This makes the T-bill easier to compare with other short-term investments.
Step 5: Account for Taxes and Reinvestment
Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. After maturity, you can take the proceeds as cash or use them to purchase another T-bill. Reinvesting can extend the strategy, but future returns will depend on the rates available at each new purchase.
Benefits and Drawbacks of T-Bill Returns
Treasury bills can be useful for investors who want a relatively conservative place for short-term cash. But the return comes with trade-offs. The right choice depends on what you need the money to do and when you may need it.
Benefits
- Backed by the U.S. government, so credit risk is generally low.
- Short maturities can make T-bills useful for managing near-term cash.
- Interest is generally exempt from state and local income taxes.
- TreasuryDirect allows individuals to buy T-bills without a purchase fee.
Drawbacks
- Your return is tied to the price and rate available when you buy.
- Selling before maturity can produce a gain or loss because market prices change.
- T-bills do not provide periodic coupon payments.
- Reinvestment carries rate risk because future T-bill yields may be different.
Bottom line: T-bills can offer a predictable maturity value when held to maturity, but that does not make them the best option for every cash goal. Compare the yield, maturity date, taxes and access to your money before investing.
T-Bill Return vs. Savings, CDs and Money Market Accounts
A T-bill can look similar to other short-term cash options because all four can be used for relatively conservative goals. The way you earn money, however, is different. The best choice depends on the return available, access to your cash, taxes and how long you can leave the money invested.
| Option | How You Earn | Access | Key Tax Point |
|---|---|---|---|
| T-Bills | Usually through the difference between purchase price and maturity value. | Limited until maturity unless sold. | Federal tax generally applies; state/local exemption. |
| Savings account | Interest paid by the bank. | Generally easy access. | Interest generally taxable federally and by applicable state/local rules. |
| CD | Interest paid according to the CD’s terms. | Early withdrawal may involve a penalty. | Interest generally taxable as income. |
| Money market account | Interest paid by the bank or credit union. | Generally more accessible than a T-bill held to maturity. | Interest generally taxable as income. |
QUICK TAKE: T-bills stand out when federal Treasury credit quality and state/local tax treatment matter. Savings and money market accounts generally offer easier access, while CDs can provide a fixed rate for a chosen term. Compare the actual annualized yield, liquidity and tax impact rather than choosing based on the headline rate alone.
T-Bill Costs, Taxes, Risks and Expert Tips
A T-bill’s quoted rate does not tell the whole story. Your actual result depends on the purchase price, holding period, taxes and what happens if you sell before maturity.
Costs
TreasuryDirect does not charge a fee to buy marketable Treasury securities through the platform. A bank or brokerage may have its own fees, commissions or pricing differences, so check the firm’s terms before purchasing.
Taxes
Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Treasury interest is generally reported in Box 3 of Form 1099-INT. Tax reporting can become more complicated if you sell a T-bill before maturity.
Risks and Practical Tips
- Selling before maturity can expose you to changes in the market price.
- Inflation can reduce the purchasing power of your return.
- Reinvestment rates can change when your T-bill matures.
- Compare the investment rate, maturity date and after-tax return before investing.
Expert tip: If you have a known future cash need, choose a maturity that fits that date. A slightly different yield may be worth accepting if it better matches when you need the money.
Common T-Bill Mistakes and a Real-Life Profit Example
Most T-bill mistakes are not about the security itself. They happen when investors misunderstand the quoted rate, maturity date or amount they will actually earn.
Mistakes to Avoid
- Confusing the discount rate with your investment return. They use different calculation methods.
- Ignoring the maturity date. A T-bill may have an attractive annualized rate but still may not fit your cash timeline.
- Assuming the quoted rate is guaranteed forever. A new T-bill can have a different rate when you reinvest.
- Forgetting taxes. Federal income tax generally applies even though state and local income taxes generally do not.
Illustrative Profit Example
Suppose you buy a $10,000 face-value T-bill for $9,900.
If you hold it until maturity, you receive $10,000. Your gross dollar return is therefore $100.
$10,000 maturity value − $9,900 purchase price = $100 gross return.
That $100 is not automatically the annual yield. The actual annualized return depends on the bill’s term and purchase price. After federal taxes, your net result may be lower. If you reinvest the $10,000, the next T-bill’s rate will depend on market conditions at that time.
Who Should Choose T-Bills for Income?
T-bills can make sense for investors who have money they can leave invested until a known maturity date. They may also suit people looking for short-term Treasury exposure rather than relying on a single bank deposit or corporate issuer.
T-Bills May Fit
- Investors with a defined short-term cash goal
- Retirees planning for upcoming expenses
- Investors who value U.S. Treasury credit quality
Consider Other Options
- You need immediate, unrestricted cash access
- You want long-term growth from your investment
- You are choosing only by the highest advertised rate
Bottom line: A T-bill is most useful when its maturity date, expected return and tax treatment line up with your cash needs.
Frequently Asked Questions About T-Bill Returns
1. How do Treasury bills make money?
For a T-bill purchased below face value and held to maturity, the gross return generally comes from the difference between the purchase price and the face value paid at maturity.
2. Do T-bills pay monthly interest?
No. T-bills generally do not make periodic coupon payments. For a bill issued at a discount, the return is built into the purchase price and realized when the bill matures.
3. Is the T-bill discount rate the same as the investment rate?
No. They use different calculation methods and day-count conventions. The investment rate is based on the purchase price and is useful for comparing annualized T-bill returns.
4. What happens when a T-bill matures?
If you hold the bill until maturity, the Treasury pays its face value. You can keep the proceeds or use them to purchase another T-bill.
5. Are T-bill returns taxable?
Generally, yes. Interest from Treasury bills is subject to federal income tax but exempt from state and local income taxes. Specific tax reporting can vary if you sell before maturity.
6. Can I sell a T-bill before maturity?
Yes. T-bills are marketable securities and can be sold before maturity through the secondary market. The selling price can be above or below your purchase price.
7. Can I reinvest T-bill proceeds?
Yes. After maturity, you can use the proceeds to buy another T-bill. The new bill will have the rate available when you make the new investment.
8. Are T-bills a good way to earn money?
They can be useful for short-term goals when the maturity, expected return, tax treatment and liquidity fit your situation. They are not a substitute for a diversified long-term investment portfolio.
Final Verdict: How Do Treasury Bills Make Money?
How do Treasury bills make money? For a T-bill issued below face value and held to maturity, the basic return is the difference between what you paid and the face value you receive. The investment rate puts that return into an annualized form, making it easier to compare with other short-term investments.
T-bills can be a useful option for money with a defined short-term purpose. They offer exposure to U.S. Treasury obligations, and Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.
Before buying, look beyond the headline rate.
Check the purchase price, investment rate, maturity date, after-tax return and access to your money. Those details tell you much more than a quoted percentage alone.
If your goal is short-term cash management and the maturity fits your timeline, a T-bill may deserve a place in your strategy. If you need unrestricted access to cash or are seeking long-term growth, compare other options before deciding.
Related Resources and Authority Sources
Ready to go deeper? These resources can help you understand T-bills, compare them with other short-term choices, and verify important pricing and tax details before investing.
Continue Your Research
Treasury Bills Explained
— a broader beginner guide covering T-bill rates, buying, taxes and risks.
CDs vs. Treasury Bills
— compare how CDs and T-bills generate returns and differ in access and taxes.
Money Market Account vs. Treasury
— compare T-bills with a more accessible cash-management option.
Official Sources
For current T-bill terms and purchase information, visit
TreasuryDirect
.
For federal tax guidance, see
IRS Publication 550
.
These official sources are useful for checking details that can change over time.
Leave a Reply