Why CD Rates Can Look So Different From One Bank to Another
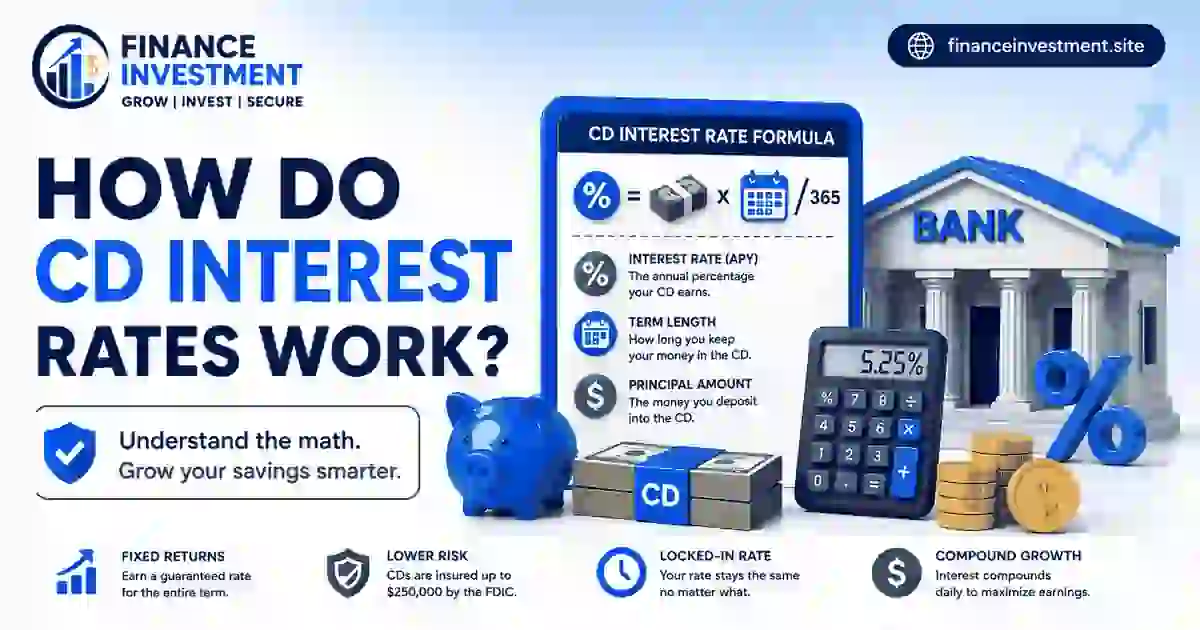 How Do CD Interest Rates Work becomes easier to understand when you stop looking at the rate alone. Picture a saver with $25,000 who finds one bank offering 3.00% APY and another offering 4.10%. The difference is not just a bigger number on a comparison page—it can change the interest earned over the same term. In 2026, CD yields vary widely by institution and maturity, while broader market rates also influence the environment banks operate in. 0
This guide breaks down what determines a CD rate, why APY matters, how term length affects offers, and what happens after you lock in a rate.
For the bigger picture, start with our
complete CD guide for 2026
.
What You’ll Learn
- What determines a CD’s rate
- How APY and compounding affect returns
- Why banks offer different rates
- How to compare CD offers without chasing the headline number
Quick Answer: What Really Drives a CD Rate?
How Do CD Interest Rates Work? Banks set offers based on factors such as market conditions, funding needs, competition, and the CD’s term. The APY then tells you the annualized yield you can compare across accounts.
- Longer terms do not always have the highest APYs.
- APY accounts for the effect of compounding.
- A fixed CD rate generally stays in place through its term.
- Two banks can price the same term very differently.
- Rate shopping matters more when your deposit is large.
- Early withdrawal rules can reduce the return you expected.
Bottom line: Compare APY, term, access rules, and insurance—not just the biggest rate on the screen.
Table of Contents
CD Interest Rates at a Glance
How Do CD Interest Rates Work depends on more than the advertised percentage. The term, APY, bank pricing, market conditions, and competition can all affect the offer you see.
A CD rate is usually fixed for the agreed term.
Savers who can leave money untouched until maturity.
APY, term, minimum deposit, penalty and maturity.
| Illustrative APY | Term | Rate Type | Main Use |
|---|---|---|---|
| 3.75 % | 6 month | Fixed | Short-term cash |
| 4.25% | 1 year | Fixed | Planned expense |
| 4.50% | 2 year | Fixed | Medium-term savings |
*Illustrative estimates using the stated APY. Actual CD earnings depend on the institution’s terms and interest-crediting method.
A Beginner’s Guide to Understanding CD Rates
 How Do CD Interest Rates Work becomes much clearer when you compare actual offers instead of staring at the percentage alone. Imagine Sarah has $20,000 she will not need for 18 months. One bank offers a 12-month CD at 4.00% APY, while another offers 18 months at 4.25%. The second rate looks better, but Sarah also has to keep her money locked up for six additional months.
Start With APY, Then Check the Term
APY gives you a standardized way to compare annual yields. For a simple one-year illustration, $20,000 at 4.00% APY could produce about $800 in interest. At 4.25%, the same deposit could produce about $850. The extra $50 may not justify choosing a longer term if Sarah expects to need the money sooner.
Look Beyond the Headline Rate
Check the minimum deposit, early-withdrawal penalty, interest-crediting schedule, maturity instructions, and whether the rate is fixed. Our
guide to how CDs work
explains what happens from opening the account through maturity.
If you’re focused on the return itself, our
CD earnings guide
shows how deposit size and APY can change your potential interest.
Beginner rule:
Choose the rate and term together. A slightly higher APY is not necessarily a better deal if the maturity date does not fit your plans.
How CD Interest Rates Actually Work
How Do CD Interest Rates Work from the bank’s side? A bank generally considers market conditions, its need for deposits, competition, and the length of the CD when setting an offer. The rate you lock in is typically fixed for the agreed term, so later market changes do not normally change that CD’s rate.
Rate vs. APY
The stated interest rate tells you the rate used to calculate interest, while APY shows the annualized yield after taking compounding into account. That makes APY especially useful when comparing CDs with different compounding schedules.
| Item | What It Tells You | Example |
|---|---|---|
| Interest rate | Stated rate used to calculate interest | 4.50% |
| APY | Annualized yield including compounding | 4.60% APY |
Why the Term Matters
A bank might offer different rates for six months, one year, and five years. However, longer does not automatically mean higher. Banks price each maturity according to their funding needs and market expectations. Before choosing, compare the complete offer rather than assuming the longest term wins.
For a deeper explanation, see our
APY vs. interest rate guide
.
Benefits & Drawbacks of CD Rates
How Do CD Interest Rates Work can be a useful question when rates are moving in different directions. A fixed CD can protect the rate you locked in, but that same lock can become a disadvantage if better offers appear later.
✓ Pros
- Rate certainty: A fixed-rate CD can keep your agreed rate through maturity.
- Easy comparisons: APY makes different offers easier to evaluate.
- Predictable planning: You can estimate interest before committing.
- Less market exposure: Your CD rate is not tied to daily stock prices.
− Cons
- Rate lock: You could miss higher rates that appear later.
- Limited access: Early withdrawals may trigger penalties.
- Inflation risk: Your return may lose purchasing power over time.
- Opportunity cost: Cash locked in a low-rate CD cannot easily move to a better offer.
Rate-shopping tip:
Compare today’s APY with the term and withdrawal rules. A slightly lower rate can make sense if the maturity date fits your plans better.
CD Rate Comparison: Term, APY and Rate Certainty
How Do CD Interest Rates Work becomes easier to judge when you put different terms side by side. The figures below are illustrative, not current bank offers. A higher APY can look attractive, but the right choice also depends on how long you can leave the money untouched.
| CD Term | Illustrative APY | Rate Certainty | Practical Use |
|---|---|---|---|
| 6 months | 3.75% | Fixed through maturity | Near-term goals |
| 1 year | 4.25% | Fixed through maturity | Planned expenses |
| 2 years | 4.50% | Fixed through maturity | Medium-term cash |
| 5 years | 4.00% | Fixed through maturity | Long-term rate lock |
The takeaway:
Don’t assume the longest CD has the best rate. Compare the APY with your timeline and the flexibility you’ll give up.
Costs, Taxes, Risks & Expert Tips
How Do CD Interest Rates Work also means understanding what can reduce your actual return. Suppose you place $20,000 in a one-year CD at 4.50% APY. The simple annual estimate is about $900 in interest. If $900 were taxed at a hypothetical 22% federal rate, about $198 would go to federal taxes, leaving roughly $702 before any state tax.
💡 Expert Tip
Compare the APY after considering the CD’s term, early-withdrawal penalty, and maturity rules. A rate that looks excellent may not be useful if you need the money before the CD ends.
⚠️ Early-Withdrawal Warning
If you close a CD before maturity, the institution may charge an early-withdrawal penalty based on its agreement. For example, a penalty equal to several months of interest could reduce the benefit of choosing a higher rate in the first place. Check the disclosure before opening the account.
Common CD Rate Mistakes + Real-Life Example
How Do CD Interest Rates Work is worth understanding before you chase the highest number on a comparison page. Common mistakes include comparing the advertised rate instead of APY, ignoring the term, overlooking the early-withdrawal penalty, and assuming every bank offers the same maturity options.
Real-Life Example: Mark Finds a Better Rate
Mark has $40,000 ready for a CD. He finds a 12-month offer at 4.10% APY and another at 4.35%. He immediately chooses the higher rate without checking the withdrawal terms. Three months later, he needs part of the money for a home repair. The penalty makes the supposedly better deal less attractive than he expected.
Practical Lesson
- Compare APY, not just the stated rate.
- Check the maturity date before opening the account.
- Read the early-withdrawal penalty.
- Keep money needed for emergencies outside the CD.
- Check whether the quoted rate has a minimum-deposit requirement.
The best rate is only useful when the account’s rules fit your plans.
Who Should Pay Attention to CD Rates?
How Do CD Interest Rates Work matters most when you have cash that can stay untouched for a specific period. The right rate can improve the return, but the term still needs to match your plans.
✓ Premium Best Fit
- Goal-based savers: You have a known future expense and date.
- Retirees: You want a predictable return on part of your cash.
- Families: You are saving for tuition, a home, or another planned purchase.
- Rate-sensitive savers: You are willing to compare banks and terms carefully.
- Surplus-cash holders: Your emergency fund and near-term needs are already covered.
Frequently Asked Questions About CD Interest Rates
How Do CD Interest Rates Work depends on several moving parts, including APY, term length, market conditions, and the bank’s pricing. These nine questions cover the details most savers should understand before choosing a CD.
1. What determines a CD interest rate?
Banks consider market conditions, funding needs, competition, and the CD’s maturity when pricing an offer.
2. Is CD APY the same as the interest rate?
Not exactly. The stated rate is used to calculate interest, while APY reflects the annualized yield with compounding included.
3. Can a CD rate change after I open the account?
A typical fixed-rate CD keeps its agreed rate until maturity. Market rates can change, but they normally do not change that existing CD’s rate.
4. Do longer CDs always have higher rates?
No. Banks can price different maturities differently, so a one-year CD may sometimes offer more than a longer-term option.
5. Does compounding affect CD earnings?
Yes. Interest that is credited and then earns additional interest can increase the effective annual yield. APY accounts for this effect.
6. Is CD interest taxable?
Interest from a regular taxable CD is generally taxable income. Your actual tax liability depends on your circumstances and applicable federal and state rules.
7. Can an early-withdrawal penalty erase the benefit of a higher rate?
It can reduce your return substantially. Check the institution’s penalty before choosing a CD solely because its APY is higher.
8. Are CDs protected by FDIC insurance?
Eligible CDs at FDIC-insured banks are generally covered up to the applicable insurance limit, subject to ownership-category rules and your other deposits at that bank.
9. How should I compare CD rates?
Compare APY, term, minimum deposit, withdrawal penalty, maturity rules, and insurance coverage rather than choosing by rate alone.
Once you understand How Do CD Interest Rates Work, comparing offers becomes much easier because you can judge the full account instead of one headline number.
Final Verdict: Choose the Rate That Fits Your Timeline
How Do CD Interest Rates Work is ultimately a question about more than finding the biggest percentage. A strong CD choice balances APY, term length, access to your money, early-withdrawal rules, and the reason you’re saving.
The Smart Rate-Checking Approach
First decide when you’ll need the money. Then compare APYs for CDs that mature around that date. Finally, check the withdrawal penalty, minimum deposit, maturity instructions, and insurance coverage.
If you want to take the next step, explore our
complete 2026 CD guide
for a broader look at CD strategies, terms, and choosing an account.
Related Resources
Keep learning with these practical FinanceInvestment guides and trusted U.S. sources before choosing a CD.
What Is a Certificate of Deposit?
How Much Can You Earn From a CD?
How Much Can You Earn From a $10,000 CD?
Trusted U.S. Sources
Keep Making Smarter Money Decisions
Get practical banking, saving, and investing guides from FinanceInvestment without the jargon or unnecessary noise.
Questions or suggestions?
subhashr325@gmail.com
Leave a Reply