Tag: CD Interest Rates

  • When Is the Best Time to Open a CD? Smart 2026 Guide

    When Is the Best Time to Open a CD? Smart 2026 Guide

    FINANCEINVESTMENT • CD TIMING GUIDE • 2026

    When Is the Best Time to Open a CD? Smart Timing Guide for 2026

    SR
    Written by Subhash Rukade
    FinanceInvestment

    Updated August 27, 2026

    About 10–12 min read

    The best time to open a CD is not always the day you see the highest advertised rate. Your cash needs, the term you can comfortably lock in, current rates, and what you expect to do with the money at maturity all matter.

    When Is the Best Time to Open a CD? Smart Timing Guide for 2026
    Find out when the best time to open a CD may be in 2026. Learn how rates, timing, CD terms, cash needs, rate locks, and CD ladders can shape your decision.
    when-is-the-best-time-to-open-a-cd
    best time to open a CD
    best time to open a CD in 2026,
    when to open a CD,
    when should I open a CD,
    CD timing,
    best time to lock in a CD rate,
    CD rates 2026,
    when to buy a CD,
    CD rate timing,
    should I open a CD now,
    CD ladder timing
    https://financeinvestment.site/when-is-the-best-time-to-open-a-cd/
    Subhash Rukade
    August 26, 2026
    About 10–12 minutes

    When Is the Best Time to Open a CD?

    When Is the Best Time to Open a CD? Smart Timing Guide for 2026The best time to open a CD is rarely determined by one perfect interest-rate moment. A better decision comes from looking at two things together: what CD rates are doing and when you expect to need your money. If you have cash you will not need for a defined period and you find a rate that fits your goals, opening a CD now can make sense rather than waiting indefinitely for something better.

    Waiting can be reasonable when you have an important expense approaching, need easy access to the money, or are not comfortable with the available terms. But waiting for the exact top of the rate cycle is difficult because nobody knows future rates with certainty.

    That is where a CD ladder can help. Instead of putting everything into one maturity date, you can spread deposits across different terms. As each CD matures, you get another opportunity to reassess rates and your cash needs. Our

    CD Guide 2026

    provides a broader look at how CDs can fit into a savings strategy.

    What You’ll Learn

    • When opening a CD now may make sense
    • When waiting may be the better choice
    • How your personal cash timeline affects CD timing
    • Why chasing the highest possible rate can backfire
    • How CD ladders can reduce the pressure to predict future rates

    Quick Answer: When Should You Open a CD?

    There is no single calendar date that guarantees the best CD rate. A practical decision starts with your own timeline, then weighs the rates and terms currently available.

    6-Step CD Timing Test

    1. Check your cash timeline: Make sure the money can remain untouched for the period you are considering.
    2. Review current rates: Look at several comparable CD offers instead of relying on one advertised rate.
    3. Choose your lock-in period: Decide whether a short, medium or longer term fits your plans.
    4. Compare the APYs: Once the terms are comparable, see whether the available return justifies locking up the funds.
    5. Consider staggered maturities: A CD ladder can give you multiple opportunities to reassess rates rather than making one large timing decision.
    6. Decide without chasing a perfect peak: If the rate and term already work for you, waiting solely for a higher future rate can leave the money earning less in the meantime.

    Bottom line: The best time to open a CD is often when the rate is reasonable and the term fits your financial timeline—not when you can somehow predict the exact market peak.

    CD Timing at a Glance

    Good CD timing starts with the relationship between the rate available today and the job your money needs to perform. This quick snapshot helps you judge the timing without trying to forecast every move in interest rates.

    Timing FactorWhat to Look AtTiming Signal
    Rate environmentAvailable CD APYsA competitive rate may support opening now
    Cash timelineWhen you may need the moneyNear-term needs favor flexibility
    CD termLength of commitmentChoose a term you can comfortably hold
    Rate lockFixed rate for the selected termUseful when today’s rate fits your expectations
    Maturity dateWhen the CD endsBest when it lines up with a future goal
    LiquidityHow much cash must stay accessibleHigher liquidity needs may argue against a long CD
    Ladder potentialMultiple maturity datesUseful when you want several future decision points
    Goal fitPurpose of the moneyA clear goal can make the timing decision easier

    Quick perspective: A CD can be well-timed even when rates are not at their absolute peak if the term, rate lock and maturity date fit your plan.

    Complete Beginner Guide: Should You Open a CD Now?
    best time to open a CDYou do not need to predict the next move in interest rates to make a sensible CD decision. A better approach is to work from your own financial timeline and then see how today’s available offers fit it.

    1. Start With Your Cash Needs

    First, separate money you may need soon from money that can stay untouched. Emergency savings and cash for upcoming bills generally need easier access. Only consider a CD for funds you can reasonably leave committed for the selected term.

    2. Check the Rates Available Today

    Look at current offers for the terms you could actually use. You can review our
    CD rates in 2026
    resource as one starting point. The goal is not to find a mythical perfect rate; it is to understand what is realistically available when you are making the decision.

    3. Choose a Term You Can Live With

    A higher APY may come with a longer commitment. If you know you will need the money in a year, locking it away for several years simply because the rate looks attractive may create a bigger problem later. Our guide to
    choosing the right CD
    can help you think through the term.

    4. Decide Whether the Rate Lock Is Worth Taking

    A fixed CD rate gives you certainty for the agreed term. That can be valuable if the current offer already meets your expectations. On the other hand, keeping all your cash uncommitted because rates might rise can mean giving up today’s known return.

    5. Plan the Maturity Date Before Opening

    Picture the date when the CD will mature. If it lands near a known expense, another investment decision, or a period when you expect to need cash, that timing deserves attention.

    6. Consider Staggering the Money

    You do not have to make one all-or-nothing timing call. A
    CD ladder
    can spread money across different maturity dates, giving you recurring opportunities to access funds and reconsider available rates.

    Beginner Tip

    If today’s CD fits your timeline and you are comfortable with the return, you do not need to wait for a perfect market moment. If it does not fit, waiting—or splitting the money—can be the smarter move.

    How CD Timing Works After You Open the Account

    When you open a fixed-rate CD, the institution generally locks in the stated rate for the selected term. Your deposit then remains in the certificate until maturity, subject to the account’s withdrawal rules. The important point is that the rate you receive is tied to the CD you open—not to whatever rates become available later.

    If market rates rise after you open the CD, your existing certificate normally keeps its agreed rate. You gain certainty, but you also give up the chance to move that money immediately into a newly available higher-rate CD. If rates fall, the same rate lock can work in your favor because your existing CD continues earning under its original terms.

    The term determines how long this trade-off lasts. A shorter CD gives you an earlier maturity date and another opportunity to reassess. A longer CD can provide a longer period of rate certainty, but your money remains committed for more time.

    Illustrative Example: Open Now vs. Wait

    Illustrative only: Imagine you have $20,000 available. A hypothetical one-year CD offers 4.25% APY today. If you open it, the account would earn roughly $850 over a year if the stated APY applies and the money remains under the CD’s terms.

    Now suppose you wait three months hoping for a better rate. A hypothetical offer later reaches 4.50%, but your money earned no CD interest during those three months. The higher future APY does not automatically mean waiting produced a better overall result. The outcome depends on how long the money remained uninvested and the rates actually available.

    Lesson: Waiting can work when rates improve enough to compensate for the return you gave up, but that result cannot be known in advance.

    This is why CD timing is partly about accepting a known return versus making a bet on future rates. A CD ladder can reduce the size of that bet by creating several maturity dates instead of requiring one large timing decision.

    Benefits and Drawbacks of Opening a CD at the Right Time

    Opening a CD when the rate and your timeline line up can turn idle cash into a predictable return. The trade-off is that the decision also fixes your rate and limits access for the selected term.

    Pros

    • Rate certainty: A fixed-rate CD can lock in the agreed return for its term.
    • Predictable earnings: You can estimate the interest under the CD’s stated terms.
    • Disciplined saving: Limited access can make it easier to leave designated savings untouched.
    • Protection from falling rates: A later decline in available rates does not normally change the locked rate.

    Cons

    • Missed upside: Rates could rise after you open the CD.
    • Reduced liquidity: Getting money out early may involve restrictions or penalties.
    • Inflation risk: The purchasing power of the return can change while your money is locked.
    • Opportunity cost: The money may have earned more elsewhere or served another financial goal.

    A Practical Perspective

    You do not need perfect timing for a CD to be useful. If the rate provides reasonable value, the term fits your plans, and you can accept the reduced access, locking in a known return can be more practical than waiting indefinitely for a better offer.

    Best CD Timing Scenarios Compared

    The right timing strategy can look different depending on how certain you are about your future cash needs and how much rate uncertainty you are comfortable accepting. These approaches offer different ways to balance today’s return with tomorrow’s flexibility.

    StrategyBest FitMain AdvantageMain Trade-Off
    Open nowYou like today’s rate and can commitLocks in a known returnFuture rates could be higher
    WaitYou have flexibility and expect conditions to improveKeeps the option to choose laterFuture rates may fall instead
    Short-term CDYou want an earlier decision pointMoney reaches maturity soonerRates may differ from longer terms
    Longer-term CDYou value longer rate certaintyLocks the rate for a longer periodLess flexibility if plans change
    CD ladderYou want several maturity datesReduces reliance on one timing decisionRequires more planning and tracking
    Keep cash flexibleYou may need the money soonEasy access to fundsPotentially lower return

    If you want several opportunities to reassess your money, explore
    how to build a CD ladder.
    For money with a shorter timeline, our guide to
    using CDs for short-term savings
    can help you evaluate the commitment.

    If your priority is deciding whether today’s rate is worth locking in, you can also review
    whether to lock in a CD rate now.

    Simple rule: The more flexibility you need, the less attractive a long lock-in may be. The more certain you are about the timeline, the easier it can be to use a fixed CD strategically.

    Costs, Risks & Expert Tips Before Opening a CD

    CD timing becomes harder when the decision is treated like a bet on where interest rates are heading. Forecasts can provide context, but they cannot tell you exactly what rates will do next. The bigger question is what you give up by waiting, locking in now, or choosing a term that later proves inconvenient.

    Watch the Cost of Waiting

    If your money sits in a lower-yield account while you wait for a better CD rate, the extra interest from a future offer must first make up for what you missed. A higher APY later is not automatically a better outcome.

    Understand Rate and Liquidity Risk

    If rates rise after you open a fixed-rate CD, your existing rate normally stays unchanged. If rates fall, that lock can become valuable. Either way, withdrawing early may trigger a penalty or other restrictions, so check the account terms before committing.

    Remember Taxes and Inflation

    CD interest is generally taxable income for federal tax purposes, which means the amount you keep can be lower than the headline earnings. Inflation also matters because a fixed return does not guarantee that your purchasing power will rise.

    Check Deposit Insurance and Account Limits

    Confirm that the institution is properly insured and consider how your total deposits are distributed across accounts and ownership categories. The standard FDIC coverage limit is generally $250,000 per depositor, per insured bank, per ownership category. Credit-union deposits use NCUA share insurance instead.

    Expert Tip

    Before locking in a CD, write down three numbers: the amount you are depositing, the maturity date, and the amount of accessible cash you will still have afterward. If those three numbers work together, the timing decision becomes much easier.

    Common CD Timing Mistakes to Avoid

    Trying to choose the perfect day to open a CD can create more uncertainty than it solves. A few common mistakes can turn an otherwise useful savings decision into an awkward one later.

    • Waiting for the perfect rate: Rates can move in either direction, so holding cash indefinitely for a higher offer may mean giving up interest today.
    • Following forecasts blindly: Rate predictions are estimates, not guarantees. Your financial timeline should carry more weight than a confident-sounding forecast.
    • Locking up money needed soon: A CD may be a poor fit for an upcoming tuition payment, home expense, emergency reserve, or other known need.
    • Ignoring early-withdrawal terms: Check the penalty and account rules before assuming you can access the money cheaply if plans change.
    • Overlooking taxes or insurance: Consider the after-tax return and verify applicable deposit insurance, especially when holding larger balances.
    • Choosing the wrong maturity date: A CD that matures at an inconvenient time can make a simple savings plan harder to manage.

    Illustrative Example: Maria’s Timing Decision

    Illustrative only: Maria has $15,000 that she expects to use for a home renovation in about 14 months. She considers a longer CD because its advertised APY is attractive, but the maturity date would fall well after her planned expense. Instead of chasing the higher rate, she chooses a shorter term that better matches her timeline and keeps other savings accessible.

    Her choice does not guarantee the highest possible return. It simply avoids making a rate decision that conflicts with a known financial goal.

    Who Should Open a CD?

    A CD can make sense for people who have money with a defined purpose and do not need immediate access to it. The timing becomes especially useful when a predictable return matters more than keeping every dollar fully flexible.

    People Who May Benefit

    • Beginners: A fixed rate and defined maturity date can make the savings plan easy to understand.
    • Retirees: CDs can provide predictable interest for money that is not needed immediately, although liquidity needs should come first.
    • Families: A CD may work for a known future expense, such as a planned education or large purchase.
    • Conservative savers: Those who prefer predictable returns may appreciate knowing the agreed rate for the CD term.
    • Goal-focused savers: A CD can fit well when the maturity date lines up with a future financial milestone.

    When Another Choice May Be Better

    A CD may not be appropriate if you expect to need the money soon, have not built an accessible emergency reserve, or are uncomfortable with early-withdrawal restrictions. In those situations, keeping more money in a flexible savings account can be more practical. Waiting can also make sense if the available CD terms do not fit your timeline and you have a reasonable alternative for holding the cash in the meantime.

    Key idea: A CD works best when its rate, term and maturity date fit the job you have assigned to the money.

    Frequently Asked Questions About the Best Time to Open a CD

    What is the best time to open a CD?

    The best time is usually when the available rate and term fit your financial timeline. You do not need to predict the exact market peak.

    Should I wait for CD rates to rise?

    Waiting can make sense when you have flexibility, but rates can also fall. Consider the interest you may give up while waiting.

    What happens when I lock in a CD rate?

    A fixed-rate CD generally keeps its stated rate for the agreed term, even if market rates later move higher or lower.

    Should I choose a short-term or long-term CD?

    Choose a term based on when you can comfortably use the money again. A longer term can provide extended rate certainty, while a shorter term gives you an earlier maturity date.

    Can CD rates rise after I open a CD?

    Yes. If market rates rise, your existing fixed-rate CD generally remains at its original rate until maturity.

    Can a CD ladder help with timing?

    Yes. A ladder spreads money across different maturity dates, giving you recurring opportunities to reassess rates and cash needs.

    Can I withdraw money from a CD before maturity?

    Some CDs permit early withdrawal subject to the account’s rules and a possible penalty. Check the terms before opening the account.

    Is CD interest taxable?

    CD interest is generally taxable income for federal tax purposes, although your specific tax situation can differ.

    Are CDs covered by deposit insurance?

    CDs at FDIC-insured banks generally receive FDIC deposit insurance within applicable limits. Qualifying federally insured credit-union accounts receive NCUA share insurance.

    Is opening a CD now always better than waiting?”

    Illustrative only: Suppose $10,000 can earn 4.25% APY today. Waiting for a higher rate could help if rates rise enough, but the money may earn less while you wait. The better choice depends on the eventual rate, waiting period and your cash needs.


    Final Verdict: Should You Open a CD Now or Wait?

    There is no reliable way to know the exact day when CD rates will reach their highest point. That makes waiting for a perfect rate a risky strategy on its own. A better decision is to ask whether today’s available rate is attractive enough for your goals and whether you can comfortably leave the money committed for the selected term.

    Opening a CD now can make sense when you have cash you will not need soon, the rate is competitive, and the maturity date fits your plans. Locking in can also provide useful certainty if you are concerned that rates could move lower.

    Waiting may be reasonable when you have an upcoming expense, need greater flexibility, or have a strong reason to keep the money available. A CD ladder can offer another path by spreading maturity dates instead of forcing one large timing decision.

    For a broader look at CD terms, strategies and safety considerations, explore our

    CD Guide 2026
    .

    Bottom line: You do not need perfect market timing. You need a CD rate, term and maturity date that make sense for your money today.

    FINANCEINVESTMENT • SMART CD GUIDANCE

    Make Your Next CD Decision With Confidence

    CD rates will change, but your savings goals do not have to wait for a perfect market moment. Get practical FinanceInvestment guidance on CDs, rates, savings strategies and smarter ways to plan your cash.

    📧 subhashr325@gmail.com
  • How to Compare CD Rates Before Opening a CD in 2026: Smart Guide

    How to Compare CD Rates Before Opening a CD in 2026: Smart Guide

    FINANCEINVESTMENT • CD RATE GUIDE • 2026

    How to Compare CD Rates Before Opening a CD in 2026

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August 27, 2026
    About 10–12 min read

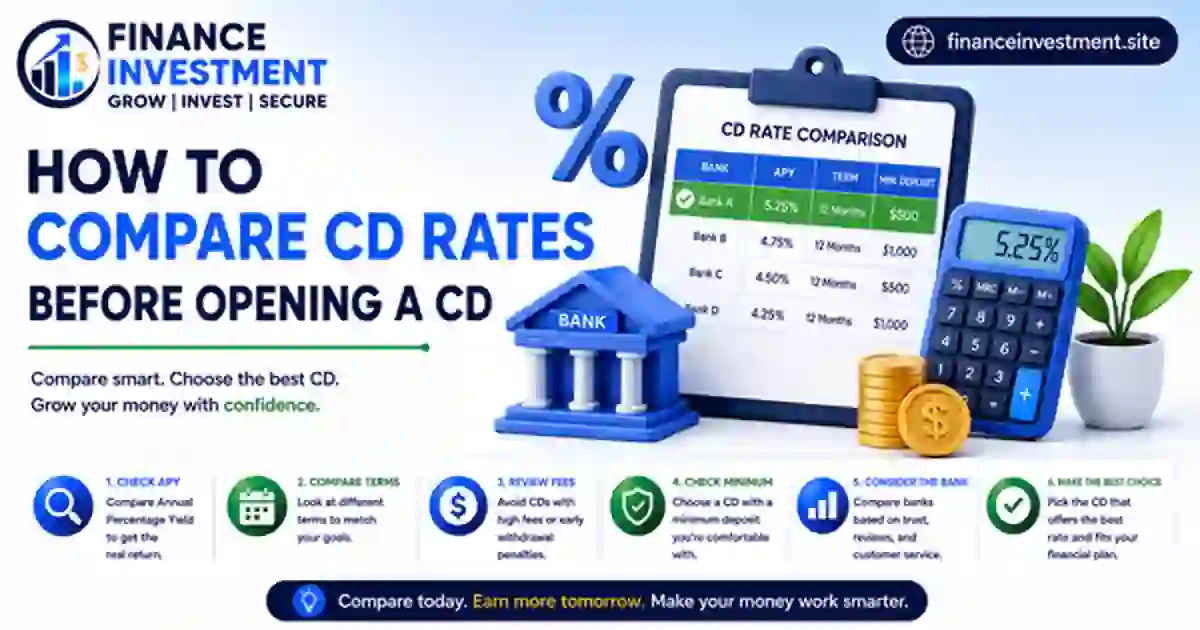
    A CD can advertise an attractive APY, but the rate alone does not tell you whether the certificate is a good fit. Comparing the term, deposit requirements, withdrawal rules, interest payments, and maturity date can help you see the full picture before you commit your money.

    How to Compare CD Rates Before Opening a CD in 2026: Smart Rate-Shopping Guide
    Learn how to compare CD rates before opening a CD, including APY, terms, minimum deposits, withdrawal penalties, interest payments, and account safety.
    how-to-compare-cd-rates-before
    how to compare CD rates before opening a CD
    compare CD rates,
    CD rate comparison,
    best CD rates,
    compare CD APYs,
    CD rates before opening,
    how to compare CDs,
    CD term comparison,
    CD interest rates,
    CD minimum deposit,
    CD early withdrawal penalty,
    CD rate shopping
    Informational / Commercial / Transactional
    USA
    Beginners, Investors, Families & Retirees
    https://financeinvestment.site/how-to-compare-cd-rates-before/
    Subhash Rukade
    August 26, 2026
    About 10–12 minutes

    Comparing CD Rates Is About More Than the Biggest APY

    How to Compare CD Rates Before Opening a CD in 2026When you compare CD rates before opening a CD, the highest APY can grab your attention first. But a rate is only one piece of the deal. Two certificates can advertise different APYs while having very different terms, minimum deposits, withdrawal rules, and maturity dates.

    The term matters because it determines how long your money may remain committed. A slightly higher APY may not be useful if the CD matures after you expect to need the funds. Likewise, a low minimum deposit can make one certificate easier to use, while another may require a larger balance to qualify for its advertised offer.

    Interest-payment details deserve a closer look, too. Find out whether interest is compounded, credited to the CD, or paid elsewhere. Then check the early-withdrawal rules so you understand the potential cost of accessing your money ahead of schedule.

    For a broader foundation on certificates of deposit, visit our

    CD Guide 2026
    .
    This article builds on those basics by showing you how to compare competing CD offers before putting your money into one.

    What You’ll Learn

    • How to compare APYs without ignoring the fine print
    • Why CD terms and maturity dates matter
    • How minimum deposits can affect your choices
    • What to check in interest-payment and withdrawal rules
    • How to compare the overall value of competing CD offers

    Quick Answer: How to Compare CD Rates

    A useful CD comparison comes down to six checks. Start with the advertised APY, then make sure the term, deposit requirement, interest rules, withdrawal conditions, and maturity date fit the way you plan to use the money.

    6 Checks Before Opening a CD

    1. Check the APY: Compare the annual percentage yield across similar CD terms rather than comparing unrelated maturities.
    2. Match the term: Choose a length that works with when you expect to need the money again.
    3. Verify the minimum deposit: Make sure the balance required for the advertised offer fits your available funds.
    4. Read the interest-payment rules: Find out when interest is credited and whether it stays in the CD or is paid to another account.
    5. Examine early-withdrawal terms: Understand the potential penalty before assuming the money will be easy to access.
    6. Confirm the maturity date: Know exactly when the CD ends and what instructions or renewal choices apply afterward.

    Bottom line: Compare CDs on the complete package, not just the number printed beside the APY.

    CD Rate Comparison at a Glance

    Before choosing between CD offers, put the important terms side by side. This makes it easier to spot a deal that looks attractive at first but has a requirement or restriction that does not suit your plans.

    FactorWhat to CompareQuestion to Ask
    APYAnnual percentage yieldIs the rate competitive for this term?
    TermLength of the CDCan I leave the money untouched that long?
    Minimum depositAmount required to open or earn the advertised rateDoes my deposit qualify?
    Interest payoutHow and when interest is credited or paidWhere will my interest go?
    Early withdrawalPenalty and access rulesWhat could access cost me?
    Maturity dateDate the fixed term endsWill the date fit my financial calendar?
    Deposit insuranceApplicable FDIC or NCUA coverageIs the institution federally insured?

    Quick check: A CD offer is easier to judge when its rate, restrictions, requirements, and timeline are viewed together.

    Complete Beginner Guide to Comparing CD Rates

    how to compare CD rates before opening a CDComparing CDs becomes much easier when you treat it like shopping for a financial product rather than chasing one impressive number. The process below gives you a consistent way to evaluate offers without getting distracted by headline rates.
    1. Set the Amount You Plan to Deposit

    Start with the actual amount you can comfortably place in a CD. Your deposit determines which offers you qualify for and whether minimum-balance requirements are relevant. Keep money needed for emergencies or near-term expenses outside the certificate.

    2. Choose Your Target Term

    Decide roughly how long you can leave the money untouched before comparing rates. Looking at a six-month CD beside a five-year CD simply because one has a higher APY can give you a misleading result. If you are unsure about the timeline, our guide on
    how long to keep money in a CD
    can help.

    3. Collect Comparable Offers

    Gather several CDs with similar terms and deposit requirements. Include banks and credit unions that meet your needs rather than limiting your search to the institution you already use. Our
    CD rates in 2026
    resource can provide another starting point for rate research.

    4. Check the APY and Requirements

    Record the APY alongside the minimum deposit, account eligibility, promotional conditions, and any restrictions attached to the offer. Make sure the advertised rate actually applies to your deposit amount and chosen term.

    5. Read the Account Terms

    Look for early-withdrawal penalties, interest-payment arrangements, automatic-renewal provisions, and maturity instructions. These details can matter long after the initial rate comparison is finished. For more on withdrawal costs, see our guide to
    CD early withdrawal.

    6. Make a Side-by-Side Choice

    Put your final candidates next to each other and ask which offer gives you the best overall fit for the money, timeline, and access you want. Then save the product terms before opening the account so you have a record of what you agreed to.

    Beginner Tip

    Compare like with like. Once the term and deposit amount are similar, APY differences become much more meaningful.

    How CD Rate Comparison Affects Your Potential Earnings

    Once you compare CDs with similar terms, the next step is understanding what the quoted APY could mean for your actual deposit. The amount you invest, the APY, the length of the CD, and the way the account compounds all influence the result. The maturity date then tells you when the agreed term ends and when you can review your next move.

    For example, a $10,000 deposit earning 4.00% APY for one year would produce about $400 in interest if the stated APY applies for the full year. A comparable $10,000 CD at 4.25% APY would produce about $425 over the same one-year period, before taxes and assuming the advertised APY applies.

    Illustrative Example: Same Deposit, Different APY

    Hypothetical CDDepositAPY1-Year Interest*
    Offer A$10,0004.00%About $400
    Offer B$10,0004.25%About $425

    *Illustrative figures only. Actual earnings depend on the CD’s stated APY, term, compounding and account terms. Taxes are not included.

    The difference becomes more noticeable as the deposit grows, but the rate should still be viewed alongside the term. A higher APY attached to a much longer CD may not be the better fit if you expect to use the money sooner. Likewise, a shorter CD may mature earlier, giving you another opportunity to compare available offers.

    This is why the maturity date belongs in the comparison. It connects today’s rate decision with tomorrow’s cash needs. Your goal is not simply to predict the biggest interest number; it is to understand what the CD can reasonably earn while fitting the period you are prepared to leave the money invested.

    Benefits and Drawbacks of Comparing CD Rates

    A careful CD comparison can do more than help you find a competitive return. It can also reveal whether the account fits your timeline and how easily you can live with its restrictions. Still, comparing offers takes a little extra attention, and a higher rate can sometimes come with a trade-off.

    Pros

    • Can help you identify a more competitive APY.
    • Makes differences in terms and account conditions easier to spot.
    • Can improve the expected return on money you do not need immediately.
    • Encourages a more deliberate choice instead of opening the first CD you see.
    • Can help match maturity dates with future financial goals.

    Cons

    • Rates can change, so today’s comparison may not remain current.
    • A higher APY may require a longer commitment.
    • Early access can reduce the interest you keep.
    • Promotional offers may have eligibility or balance requirements.
    • Comparing several institutions takes more time than choosing a familiar account.

    A Useful Way to Think About It

    The goal is not to spend hours hunting for a tiny rate difference. It is to find an offer where the return, commitment and account rules make sense together. That makes the comparison useful rather than simply competitive.

    CD Rate Comparison Methods Compared

    There is no single way to shop for a CD. Your starting point can change depending on whether your priority is return, timing, access, or how you want to spread your savings. The table below shows how each approach works and when it can be useful.

    ApproachMain FocusWorks Well WhenWatch For
    APY-firstHighest competitive returnYou can comfortably commit the money for the required termLonger terms or special requirements
    Term-firstWhen you need the moneyYour future cash date is already knownA shorter term may have a different rate
    Institution comparisonBank or credit union offersYou are willing to shop beyond your current providerEligibility and account requirements
    Goal-basedSpecific financial objectiveThe money has a known purpose and timelineA tempting rate that does not match the goal
    CD ladderMultiple maturity datesYou want recurring access pointsMore accounts to track
    Flexible-cash approachAccess and liquidityYou may need the money sooner than expectedPotentially lower return than a locked CD

    If several maturity dates appeal to you, learn
    how to build a CD ladder.
    If you are deciding between a fixed certificate and more accessible savings, our guide to
    using CDs for short-term savings
    can help you think through the trade-off.

    Practical takeaway: Start with the factor that matters most to your situation, then use the other criteria to narrow the field.

    Costs, Risks and Expert Tips Before Opening a CD

    A CD can look straightforward on the surface, yet the details behind an advertised rate can change the value of the offer. Before moving money, take a few minutes to look for conditions that may matter after the account is opened.

    Watch for Promotional Rates

    Some offers may be designed to attract new deposits or may have eligibility requirements. Confirm who qualifies, what balance is needed, how long the stated offer applies, and what happens when the CD reaches maturity. Do not assume a promotional rate automatically applies to every deposit.

    Consider the Cost of Locking In

    Market rates can change after you open a CD. If rates rise, a longer certificate may leave you committed to the earlier rate. If rates fall, however, locking in a competitive fixed rate may look more useful. There is no way to know the future path with certainty, so the term should fit your timeline rather than depend entirely on a rate prediction.

    Read the Fine Print Around Access

    Early withdrawal can result in a penalty or reduced interest. Check the exact rules before opening the account, especially if the money might be needed unexpectedly. Also verify whether the advertised APY requires a particular minimum balance.

    Do Not Ignore Taxes or Insurance

    CD interest held in a taxable account can create taxable income. A large deposit also deserves an insurance check. Confirm whether the bank is FDIC-insured or the credit union is federally insured by the NCUA, and consider your total balances under the applicable ownership category.

    Expert Tip: Save the Terms

    Before clicking “Open,” save or print the offer details. Keep the APY, term, minimum deposit, early-withdrawal policy, maturity instructions, and renewal terms with your financial records. A screenshot of the headline rate is not enough.

    Common Mistakes When Comparing CD Rates

    A rate comparison can go wrong even when the math looks simple. Most problems happen when savers compare offers that are not truly equivalent or focus on the headline number while overlooking the conditions attached to it.

    • Comparing different terms as if they were equal: A five-year CD and a six-month CD serve different timelines, even if one advertises a higher APY.
    • Ignoring deposit requirements: Check whether your balance qualifies for the advertised rate and whether a minimum deposit applies.
    • Overlooking promotional conditions: A special offer may have eligibility, funding, or other account requirements that affect who can receive it.
    • Forgetting maturity timing: A good rate can become inconvenient if the CD ends when you are likely to need the money elsewhere.
    • Looking only at the rate: Compare the expected interest on your actual deposit and term rather than assuming a small APY difference will create a major gain.
    • Opening too many CDs without checking coverage: Multiple certificates at the same institution can count toward applicable deposit-insurance limits.

    Illustrative Example: Elena Compares Two Offers

    Elena has $25,000 to place in a CD. One offer advertises a hypothetical 4.25% APY for one year, while another advertises 4.50% for five years. The second rate looks better, but Elena expects to use the money for a home-related expense in about 18 months. She chooses to compare one-year and shorter-term options instead of treating the five-year rate as the obvious winner.

    Illustrative lesson: The most attractive rate on the screen is not necessarily the most useful rate for the money.

    Who Should Compare CD Rates This Way?

    A detailed CD comparison is especially useful when the amount of money or length of the commitment makes small differences meaningful. It can also help people who want a predictable return without taking on the price swings associated with many market investments.

    Savers Who May Benefit Most

    Beginners can use a structured comparison to learn what they are actually agreeing to before locking away savings. Larger-balance savers may benefit because even a modest rate difference can affect the interest earned over time, while deposit-insurance limits deserve closer attention.

    Retirees may want to coordinate CD maturities with future cash needs. Families saving for a known expense can compare terms around the date they expect to use the money. Conservative investors and rate-sensitive savers may also appreciate the ability to compare fixed-return choices across institutions.

    When a Detailed Comparison May Not Be Worth It

    Spending hours chasing a tiny rate difference may not add much value if the deposit is small or the difference in expected interest is minimal. More importantly, money needed for an emergency or near-term bill should not be locked away simply to earn a higher rate. In those situations, liquidity can matter more than squeezing out the last few dollars of interest.

    Frequently Asked Questions About Comparing CD Rates

    How should I compare CD rates before opening an account?

    Compare CDs with similar terms first, then look at APY, minimum deposit, interest rules, early-withdrawal provisions, maturity date, and insurance coverage. This gives you a more useful comparison than looking at the advertised rate alone.

    Is APY the same as the interest rate on a CD?

    No. The interest rate is the stated rate paid on the deposit, while APY reflects the effect of compounding over a year. When comparing deposit products, APY is generally the more useful figure for comparing potential annual earnings.

    Does the CD term affect the rate I receive?

    Yes. Financial institutions can offer different rates for different terms. Compare CDs within the same or similar maturity period before deciding that one offer is better.

    Why does the minimum deposit matter when comparing CDs?

    Some CDs require a minimum opening deposit, and certain offers may require a particular balance to receive the advertised rate. Make sure your available funds qualify for the offer you are evaluating.

    Should I trust a promotional CD rate?

    A promotional rate can be attractive, but check eligibility, deposit requirements, term, availability and renewal conditions. The headline APY should be considered alongside the complete account terms.

    How do early-withdrawal penalties affect a CD comparison?

    An early-withdrawal penalty can reduce the interest you keep if you access the money before maturity. If there is a reasonable chance you will need the funds early, examine this rule before choosing a higher-rate CD.

    Why should I compare CD maturity dates?

    The maturity date determines when the fixed term ends and when the money becomes available under the account’s terms. A CD with an attractive APY may be inconvenient if its maturity date does not fit your financial plans.

    Are CDs covered by deposit insurance?

    CDs at FDIC-insured banks are generally covered as deposits within applicable limits. The standard FDIC insurance amount is $250,000 per depositor, per insured bank, for each ownership category. 0

    Is CD interest taxable?

    Generally, interest from CDs held in taxable accounts is taxable under federal income-tax rules. The IRS explains that CD interest generally must be included in income when received or when you are entitled to receive it, subject to applicable rules. 1

    Illustrative: Which CD could earn more on a $25,000 deposit?

    Illustrative example only: Suppose one hypothetical one-year CD offers 4.00% APY and another offers 4.25% APY for the same one-year term and deposit. Ignoring taxes and assuming the stated APYs apply, the second offer would produce roughly $62.50 more over one year on $25,000. Actual earnings depend on the institution’s terms and compounding.

    Final Verdict: Compare the Whole CD Offer

    The best way to compare CD rates before opening a CD is to look beyond the headline APY. A strong offer should make sense for the amount you are depositing, the time you can leave the money untouched, and the date when you expect to need it again.

    Start with comparable terms, then consider the minimum deposit, interest-payment rules, early-withdrawal provisions, maturity date and applicable deposit-insurance coverage. These details can make two seemingly similar CDs quite different once your money is committed.

    The highest APY can be worthwhile when the term and conditions fit your plans. But if it requires a longer commitment than you can comfortably handle, a slightly lower rate with a better timeline may be the more practical choice.

    If you want to strengthen your understanding before making a decision, explore our

    CD Guide 2026
    .
    It brings together CD basics, strategies, safety considerations and related guidance in one place.

    Bottom line: Choose the CD that gives your money a useful return without creating a term, access or account condition you will regret later.

    FINANCEINVESTMENT • SMART CD GUIDANCE

    Compare Smarter Before You Lock In Your Money

    CD rates change, and the details behind an offer matter. Get practical FinanceInvestment updates on CD rates, savings strategies, and smarter ways to make your cash work harder.

    📧 subhashr325@gmail.com

  • Best 18-Month CD Rates in 2026: Compare Top CD Offers

    Best 18-Month CD Rates in 2026: Compare Top CD Offers

    Best 18-Month CD Rates in 2026


    By Subhash Rukade


    Updated August, 22, 2026


    12 min read

    A practical guide to comparing 18-month CD yields, deposits, penalties, maturity terms and real earning potential.

    Why an 18-Month CD Deserves a Closer Look in 2026

    Best 18-Month CD Rates in 2026The Best 18-Month CD Rates in 2026 are worth comparing carefully because this term sits between short-term flexibility and a longer rate lock. In August 2026, market observation + reader problem + why 18 months is different  although rates, deposits and account terms vary by institution. Bankrate’s current listings, for example, show Bread Savings at 4.50% APY with a $1,500 minimum, while other banks offer different combinations.

    That makes the decision more interesting than simply chasing the highest number. A slightly lower APY may offer a smaller opening deposit or more suitable terms, while a higher rate may require more money upfront. Our

    Complete CD Guide for 2026

    provides the broader picture.

    What You’ll Learn

    You’ll see how to compare 18-month APYs, minimum deposits, compounding, penalties and maturity rules, plus how this term stacks up against shorter and longer CDs.

    Quick Take: 18-Month CD Shopping in August 2026
    • Competitive 18-month CD offers are available above 4% APY, although rates and terms vary by institution.

    As of August 20, 2026, NerdWallet lists Bread Savings at 4.35% APY for an 18-month CD.

    Some offers require $1,000 or more to open, so check the minimum deposit before applying.

    Review the early-withdrawal penalty before committing your money.

    On larger balances, even a modest APY difference can affect total interest earned.

    Compare 12-, 18-, and 24-month CDs before deciding how long to lock up your money.

    Bottom line:

    The Best 18-Month CD Rates in 2026 can be attractive for money you won’t need for a year and a half, but the highest APY is only one part of the decision.

    18-Month CD Rates at a Glance

     The best 18-month CD rates in 2026 are currently around 4.50% APY. As of August 20, 2026, NerdWallet lists Bread Savings at 4.35% APY, while other rate trackers show offers reaching about 4.50%.

    Best for: Savers who can leave money untouched for 18 months.

    Key numbers: APY, minimum deposit, penalty and maturity date.

    August 2026 SnapshotWhat to Check
    Up to about 4.50% APYVerify the live offer
    Term: 18 monthsPlan around maturity
    Example minimum: $1,500Minimums vary by institution

    How to Shop for an 18-Month CD

    When comparing the Best 18-Month CD Rates in 2026, start with APY, but don’t stop there. Current August 2026 listings show competitive offers around 4% or higher, with Bread Savings listed at 4.25% APY and a $1,500 minimum deposit in Yahoo Finance’s recent comparison. Rates can change, so verify the bank’s current disclosure before applying.

    Look Beyond the APY

    APY makes different accounts easier to compare because it reflects the effect of compounding. Then check the minimum opening deposit and how interest is credited. For example, a $1,500 minimum may be comfortable for one saver but too restrictive for someone building an emergency fund.

    Calculate the Real Dollar Return

    Suppose you deposit $25,000 into an 18-month CD at a hypothetical 4.25% APY. If that APY remains applicable for the full term, the approximate interest would be about $1,602 before taxes, assuming the stated APY and normal compounding. Your actual result depends on the institution’s terms.

    Don’t overlook the exit cost:

    Early withdrawal penalties vary widely. Recent listings show penalties ranging from 60 days of interest to 180 days or more, depending on the institution. Read the penalty formula before committing money you may need.

    For a broader comparison, read our

    1-year CD rates guide

    and then see

    6-month CD rates

    before deciding how long you want your cash locked up.

    How an 18-Month CD Works

    Best 18-Month CD Rates in 2026An 18-month CD gives you a fixed term in exchange for a stated yield. The Best 18-Month CD Rates in 2026 can look appealing because the rate is generally locked for the entire term, but your money is also less accessible until maturity. Current August 2026 listings show a wide spread among offers, from accounts around 3.8% to 4.25% APY.
    APY & Compounding

    APY reflects the annualized return after compounding. Current 18-month listings include daily and monthly compounding, depending on the bank.

    Maturity & Renewal

    At maturity, you can usually withdraw the funds or renew under the bank’s then-current terms. Check the grace period before the CD automatically renews.

    For an August 2026 illustration, a $10,000 deposit earning 4.25% APY for 18 months would produce roughly $643 in interest if the stated APY applies throughout and the account compounds as assumed. Actual earnings depend on the bank’s disclosed calculation and crediting schedule.

    Early withdrawal matters:

    Current listings show penalties ranging from about 60 days to 180 days of interest, depending on the institution. That cost can materially reduce your return if you need the money early. 2

    For a broader explanation, read our

    guide to how CDs work
    .

    Benefits and Drawbacks of an 18-Month CD

    An 18-month CD can be a useful middle ground when you want a fixed return but don’t want to commit for several years. In August 2026, Bankrate lists several 18-month offers above 4% APY, including Bread Savings at 4.50%, although minimum deposits differ widely.

    ✓ Pros

    • Locks a fixed APY for 18 months.
    • Can provide a stronger return than many traditional savings accounts.
    • Useful for a planned expense more than a year away.
    • Long enough to avoid frequent rate-shopping.

    ✕ Cons

    • Your cash is less accessible before maturity.
    • Early withdrawal can reduce your interest earnings.
    • Rates on new CDs could become more attractive while your money is locked.
    • An 18-month term may be unnecessary for a goal due within a year.
    When it makes sense:

    An 18-month lock can work well when the money has a clear future purpose and you already have accessible cash elsewhere. If you may need the funds sooner, a 6- or 12-month CD—or a high-yield savings account—can preserve more flexibility. Current savings rates can also remain competitive, so compare the return you gain against the freedom you give up.

    18-Month CD Rate Comparison: August 2026

    The Best 18-Month CD Rates in 2026 are not always the highest CD rates overall. Recent August 2026 comparisons show Bread Savings at 4.25% APY with a $1,500 minimum, while Limelight Bank lists 4.10% with a $1,000 minimum and TAB Bank lists 4.05% with a $1,000 minimum.

    InstitutionAPYMinimumCompoundingPractical Use
    Bread Savings4.25%$1,500DailyCompetitive yield for a larger planned balance
    Limelight Bank4.10%$1,000Check current disclosureLower entry point
    TAB Bank4.05%$1,000Check current disclosureCompetitive alternative

    Rates shown are an August 2026 market snapshot and can change. Verify the institution’s current APY, compounding method, insurance status and withdrawal penalty before opening an account. Yahoo Finance’s August comparison evaluated more than 400 data points across CD terms using factors including APY, minimum deposit and customer service.

    Costs, Taxes, Risks & Expert Tips

    The Best 18-Month CD Rates in 2026 can produce a solid fixed return, but the headline APY isn’t your only consideration. Early access, taxes and insurance limits can change the value of an offer.

    Expert Tip

    Suppose you deposit $25,000 at a hypothetical 4.25% APY for 18 months. The estimated interest is about $1,602 before taxes, assuming the stated APY applies for the full term. Compare that gross figure with the return you could earn while keeping the money accessible.

    ⚠️ Watch the Exit Cost

    FDIC guidance notes that fixed-rate CDs generally allow early redemption only under the account’s stated terms, often with a penalty. ([fdic.gov](https://www.fdic.gov/consumer-resource-center/2023-11/shopping-certificate-deposit?utm_source=chatgpt.com)) CD interest is generally taxable as ordinary income; the IRS says interest income is generally taxable and reportable. ([irs.gov](https://www.irs.gov/faqs/interest-dividends-other-types-of-income/1099-int-interest-income?

    Common 18-Month CD Mistakes and a Real-Life Example

    The Best 18-Month CD Rates in 2026 can look tempting, but chasing the biggest APY can lead to a poor decision. Common mistakes include ignoring the minimum deposit, overlooking the early-withdrawal penalty, and assuming every advertised rate is available nationwide. August 2026 comparisons show meaningful differences between institutions and terms.

    A $40,000 Shopping Decision

    Imagine Maria has $40,000 available for 18 months. She finds one offer at 4.25% APY and another at 4.50%, but the higher-rate account has stricter terms. The extra 0.25 percentage point looks attractive, yet the difference is only about $150 in simple annual-interest terms on $40,000. If the higher-rate CD has a less suitable penalty or access rule, the small gain may not justify the trade-off.

    Practical lesson:

    Compare the complete offer—not just the headline APY. Check the deposit requirement, withdrawal rules, insurance coverage and maturity instructions before moving your money.

    Who Should Choose an 18-Month CD?

    Best Fit: Money With a Clear 18-Month Job

    The Best 18-Month CD Rates in 2026 may suit savers who know they can leave their money untouched until maturity. It can work well for:

    • Goal-based savers: money earmarked for a future purchase.
    • Retirees: surplus cash that isn’t needed for near-term expenses.
    • Families: funds being held for a known expense more than a year away.
    • Rate-sensitive savers: people seeking a fixed yield while rates remain competitive.
    • Surplus-cash holders: money already separated from emergency savings.

    If your timeline is uncertain, a shorter CD or high-yield savings account may offer a better balance of return and access. Current August 2026 coverage shows CD yields remain competitive, while term-by-term rates vary considerably.

    Frequently Asked Questions About 18-Month CDs

    1. What are the best 18-month CD rates in August 2026?

    Current listings show 18-month APYs reaching about 4.40%, while NerdWallet lists Bread Savings at 4.35%. Rates can change, so verify the live offer before opening an account.

    2. Is an 18-month CD a good choice right now?

    It can make sense if you can leave the money untouched for 18 months and want a fixed return. Compare the rate with shorter CDs and savings accounts first.

    3. What APY should I look for?

    As a current benchmark, 4% or more is considered a strong 18-month rate, with top offers around 4.40% in August 2026.

    4. How much money do I need to open one?

    Minimums vary. Some current offers require $1,000 or $1,500, while other CD products may have different requirements. Always check the bank’s disclosure.

    5. Are CD earnings taxable?

    Generally, yes. The IRS says most interest that becomes available to you is taxable income.

    6. What happens if I withdraw early?

    You may owe an early-withdrawal penalty under the CD’s terms. The amount varies by institution.

    7. Are 18-month CDs FDIC insured?

    CDs at FDIC-insured banks are generally covered within applicable deposit-insurance limits and ownership categories.

    8. Can CD rates change after I open one?

    A standard fixed-rate CD generally keeps its stated rate through the term. New CD offers can change as banks respond to market and Federal Reserve conditions.

    9. Should I choose an 18-month CD over a shorter term?

    Choose the longer term when the yield and your timeline make sense. If you may need the cash sooner, a shorter CD or accessible savings account may be a better fit.

    Final Verdict: Is an 18-Month CD Worth It in August 2026?

    The market still gives savers a reasonable opportunity to lock in competitive yields. As of August 20, 2026, NerdWallet lists an 18-month Bread Savings CD at 4.35% APY, while some CD terms elsewhere reach 4.50%.

    So, should you choose the Best 18-Month CD Rates in 2026? Choose an 18-month term if your money has a clear purpose beyond the next year and you value a fixed return. Compare first if a 12-month or 2-year CD offers a better combination of yield and flexibility. Wait only if you have a strong reason to keep your cash liquid or believe another term better matches your timeline.

    Simple rule:

    Don’t chase the highest APY blindly. Match the term, penalty and maturity date to your actual cash needs.

    For the bigger picture, visit our

    complete CD guide for 2026
    .

    Related Resources

    Keep exploring before you lock up your cash. These guides cover nearby CD terms, rate trends and practical earnings questions.

    Keep Building Smarter Savings Habits

    Get practical money guides in your inbox, then explore more CD resources when you’re ready to compare terms, yields and strategies.

    Questions or feedback?

    subhashr325@gmail.com

  • Best 1-Year CD Rates in 2026: Compare Top 12-Month CDs

    Best 1-Year CD Rates in 2026: Compare Top 12-Month CDs

    Best 1-Year CD Rates in 2026


    Written by Subhash Rukade

    FinanceInvestment • Updated August 21, 2026 • About 13 min read
    SEO Title: Best 1-Year CD Rates in 2026: Compare Top 12-Month CDs
    Meta Description: Compare the best 1-year CD rates in 2026, including APY, minimum deposits, maturity dates, early-withdrawal penalties and practical savings strategies.
    Focus Keyword: Best 1-Year CD Rates in 2026
    Slug: best-1-year-cd-rates-in-2026
    Canonical: https://financeinvestment.site/best-1-year-cd-rates-in-2026/
    Featured Image ALT: Best 1-Year CD Rates in 2026

    Why a 1-Year CD Deserves a Closer Look in August 2026

    Best 1-Year CD Rates in 2026The Best 1-Year CD Rates in 2026 are worth comparing carefully this August. Competitive offers are still well above the national average, with Bankrate listing a leading 1-year CD at 4.30% APY on August 20, while other published lists show similarly strong offers.

    The bigger question isn’t simply which bank posts the highest number. A 12-month commitment affects when you can access your money, what happens at maturity, and how much flexibility you have if rates change.

    Our
    Complete CD Guide for 2026

    covers the broader picture. This guide narrows the focus to one-year CDs and the decisions that matter most.

    What You’ll Learn

    You’ll learn how to compare 1-year CD APYs, minimum deposits, penalties, maturity rules and real-dollar earnings before deciding where your cash belongs.

    Quick answer: The Best 1-Year CD Rates in 2026 can work well when you want a fixed return and know you won’t need the money for about 12 months. As of August 20, competitive one-year offers are around 4.30% APY, although rates and eligibility vary. 0

    • Compare APY with the actual deposit requirement.
    • Check the early-withdrawal penalty before opening.
    • A lower APY can sometimes produce more total interest over a longer term.
    • Check whether the CD automatically renews at maturity.
    • Keep emergency money outside the CD.
    • Confirm FDIC or NCUA coverage before depositing.
    Bottom line: Don’t chase the biggest APY alone. Match the term, rate and access rules to your actual one-year goal.

    1-Year CD Rates at a Glance

    The Best 1-Year CD Rates in 2026 can offer a useful balance between a fixed return and a manageable one-year commitment. As of August 20, 2026, Bankrate reported a 2.03% national average for one-year CDs, while top offers were considerably higher.

    Best for: Money you can leave untouched for about 12 months.

    Key numbers: APY, minimum deposit, maturity date and withdrawal penalty.

    August 2026 SnapshotWhat It Means
    1-year national average: 2.03% APYTop offers can be much higher
    Term: 12 monthsLonger lock than a 6-month CD
    Compare APY + deposit + penaltyThe headline rate isn’t the whole deal

    How to Shop for a 1-Year CD as a Beginner

    Best 1-Year CD Rates in 2026When comparing the Best 1-Year CD Rates in 2026, start with the APY, then look beyond the headline number. On August 20, 2026, leading CD offers were still above 4%, while one-year rates varied by institution, deposit size and eligibility.
    APY Is Only the Starting Point

    APY lets you compare yields on the same annual basis. For example, $10,000 earning a hypothetical 4.30% APY for one year would produce about $430 before taxes, assuming the stated APY applies throughout the term. A higher rate is useful only if the account’s other conditions work for you.

    Check the Deposit and Maturity Rules

    A $500 minimum and a $5,000 minimum can make two seemingly similar offers very different for smaller savers. Also check the exact maturity date, interest payout method and renewal policy. FDIC guidance says banks must disclose early-withdrawal penalties and whether a time account renews automatically.

    A simple shopping test:

    Write down the APY, minimum deposit, estimated interest, maturity date and early-withdrawal penalty for each finalist. Then compare the complete package rather than choosing from the biggest rate alone.

    For the rate mechanics, see our

    guide to CD interest rates
    .
    You can also review

    how much a CD can earn

    before deciding how much cash to commit.

    How 1-Year CDs Work

    A one-year CD is a time deposit with a fixed maturity period. When you open one, you agree to leave the money deposited for the stated term in exchange for the disclosed APY. In August 2026, the highest reported one-year CD rate was about 4.33%, while the average was much lower, showing why shopping around matters.

    APY & Compounding

    APY expresses the annualized yield and accounts for compounding. The actual interest credited depends on the bank’s terms.

    12-Month Term

    Your deposit generally stays in the account until the maturity date unless the bank permits an early withdrawal under its stated rules.

    Maturity & Renewal

    At maturity, you can usually take the money out or renew the CD according to the institution’s disclosure and grace-period rules.

    For a simple August 2026 example, suppose you place $10,000 into a one-year CD at a hypothetical 4.30% APY. If the stated APY applies for the full term, the account would earn roughly $430 before taxes. That is an illustration, not a guaranteed payout; the bank’s actual compounding and interest-crediting terms control the result.

    The Best 1-Year CD Rates in 2026 can therefore look similar on a comparison page while producing different experiences because of minimum deposits, renewal policies and withdrawal penalties. Before opening an account, review the maturity and early-withdrawal terms carefully. You can also read our

    guide to how CDs work

    and

    CD interest-rate guide
    .

    Benefits and Drawbacks of a 1-Year CD

    A one-year CD sits in an interesting spot in August 2026. Competitive 1-year offers are around 4.30% APY, while shorter CDs can sometimes offer different yields. That makes the extra six months of commitment worth considering rather than assuming a longer term is automatically better.

    ✓ Pros

    • Locks a fixed yield for about 12 months.
    • Can provide more total interest than a shorter term.
    • Useful for money tied to a known future goal.
    • Creates a clear date for your next savings decision.

    ✕ Cons

    • Your money is less accessible before maturity.
    • Early withdrawal may reduce your earnings.
    • Rates could be more attractive elsewhere before maturity.
    • A high APY may come with a larger minimum deposit.
    The practical test:

    If you have a known 12-month goal and enough separate cash for emergencies, locking part of your savings can make sense. If you may need the money sooner, a high-yield savings account can offer more flexibility. Current top savings offers can also be competitive, so compare both before committing.

    1-Year CD Rate Comparison for August 2026

    The Best 1-Year CD Rates in 2026 are easier to judge when you compare the entire offer. On August 20, Bankrate reported a 2.03% national average for one-year CDs, while individual banks and credit unions were offering considerably more. ([bankrate.com](https://www.bankrate.com/banking/cds/current-cd-interest-rates/))

    TermIllustrative APY*Minimum DepositRate TypePractical Use
    12 monthsUp to about 4%+ on competitive offersVariesUsually fixedPlanned 1-year goals
    6 monthsCompare current offersVariesUsually fixedEarlier access
    18 monthsCompare separatelyVariesUsually fixedLonger-term cash

    *APYs are illustrative market ranges, not guaranteed offers. Rates and minimum deposits can change by institution and eligibility.

    For a broader list, see our

    Best CD Rates in 2026

    guide before choosing a specific account.

    Costs, Taxes, Risks & Expert Tips

    A strong APY doesn’t tell the whole story. With a one-year CD, consider the tax on interest, the cost of accessing your money early and what you might give up if better opportunities appear during the term. The FDIC notes that CD withdrawals before maturity can be subject to an early-withdrawal penalty.

    Expert Tip

    Suppose you put $25,000 into a CD at a hypothetical 4.30% APY. If that APY applies for the full year, the interest would be about $1,075 before taxes. Compare that after-tax result with what you could earn while keeping the money accessible.

    ⚠️ Warning Before You Lock In

    Bank CD interest is generally taxable interest income. Keep your year-end tax documents and account statements. If you withdraw early, check the bank’s exact penalty before acting; the penalty can reduce the return you expected. IRS guidance covers interest income reporting, while the account agreement controls the CD’s withdrawal terms.

    Common 1-Year CD Mistakes + A Real-Life Example

    One mistake is choosing a CD because its APY looks impressive without checking the minimum deposit, maturity date or withdrawal penalty. Another is putting all available cash into one term. In August 2026, competitive CD yields remain well above many national averages, making careful comparison especially important.

    Real-Life Example: David Has $30,000

    David has $30,000 that he expects to leave untouched for a year. He finds a 1-year CD advertising 4.30% APY, but the account requires a larger deposit than another option offering 4.15%. Instead of chasing the extra rate, he checks the penalty and maturity terms first. At 4.30% APY, $30,000 could earn about $1,290 before taxes over one year if the stated APY applies throughout.

    Practical Lesson

    The Best 1-Year CD Rates in 2026 should be judged as complete offers. Compare APY, minimum deposit, penalty and maturity date together. FDIC guidance also requires institutions to disclose applicable early-withdrawal penalties and renewal terms.

    Who Should Choose a 1-Year CD?

    Premium Best Fit

    The Best 1-Year CD Rates in 2026 may suit savers who have a clear 12-month timeline and don’t expect to touch the money before maturity. Current August offers remain competitive, with some one-year CDs around 4.30%–4.35% APY.

    • Goal-based savers: money earmarked for a known expense.
    • Retirees: surplus cash that doesn’t need immediate access.
    • Families: planned expenses roughly a year away.
    • Rate-sensitive savers: people willing to shop for a better fixed yield.
    • Surplus-cash holders: funds sitting idle in lower-yield accounts.

    Keep emergency savings separate. If liquidity is uncertain, a high-yield savings account may be a better fit because you retain easier access to the cash.

    Frequently Asked Questions About 1-Year CDs

    1. What are the best 1-year CD rates in August 2026?

    Competitive CD offers remain above 4% in August 2026, although the highest rate depends on the exact term, institution, deposit and eligibility. Current published comparisons show meaningful differences between banks.

    2. What APY should I look for?

    Compare the APY with the minimum deposit, penalty and maturity terms. A slightly lower yield can be worthwhile if the account has better conditions for your situation.

    3. How much money is needed to open a 1-year CD?

    Minimums vary by institution. Some accounts require only a few hundred dollars, while others require substantially more. Always check the current account disclosure.

    4. Can CD rates change after I open the account?

    A typical fixed-rate CD keeps its agreed rate through maturity. Rates offered on new CDs can change as market conditions and bank funding needs change.

    5. What happens when a 1-year CD matures?

    You generally receive the principal and interest according to the account terms. Some CDs automatically renew, so check the maturity notice and grace period before the deadline.

    6. Is interest from a CD taxable?

    Generally, yes. The IRS treats interest from certificates of deposit as taxable interest income, subject to the applicable tax rules.

    7. What happens if I withdraw money early?

    The institution may charge an early-withdrawal penalty. The amount depends on the account agreement, so review it before committing money you may need soon.

    8. Are 1-year CDs FDIC insured?

    A CD at an FDIC-insured bank is generally covered as an insured deposit, subject to applicable coverage limits and ownership rules. Confirm the institution’s insurance status before depositing.

    9. Are the best 1-year CD rates likely to change?

    Yes. Banks can change rates for new accounts. Current August data shows top CD yields still vary considerably by term and institution, so today’s leading offer may not remain available later.

    Bottom line:
    The Best 1-Year CD Rates in 2026 should be compared using APY, deposit requirements, maturity rules, penalties and insurance—not the headline rate alone.

    Final Verdict: Is a 1-Year CD Right for You?

    In August 2026, the Best 1-Year CD Rates in 2026 remain attractive for savers who value a predictable return and can leave their money untouched for 12 months. But a strong APY should never be the only reason to open an account.

    Choose, Compare, or Wait

    • Choose if your 12-month goal is clear and liquidity is not a concern.
    • Compare if another bank offers a better combination of APY, minimum deposit and penalty.
    • Wait if you may need the cash or want to keep flexibility for changing rates.

    For a broader look at CD strategies, visit our

    Complete CD Guide for 2026
    .
    The right account is the one that fits your timeline, cash needs and comfort with locking up money—not simply the highest number on a rate table.

    Related Resources

    Before opening a CD, these guides can help you compare rates, understand earnings and review the rules that matter.

    Official sources:
    Check the

    FDIC

    for deposit-insurance rules, the

    Federal Reserve

    for monetary-policy information, and the

    IRS

    for interest-income tax guidance.

    Make Your Next CD Decision With Confidence

    Get practical money guides by email, then explore our CD resources whenever you’re ready to compare rates, terms and savings strategies.

    Email:

    subhashr325@gmail.com

  • Best 6-Month CD Rates in 2026: Compare Top Short-Term CDs

    Best 6-Month CD Rates in 2026: Compare Top Short-Term CDs

    Best 6-Month CD Rates in 2026


    Written by Subhash Rukade

    FinanceInvestment • Updated August 21, 2026 • About 12 min read

    SEO Title: Best 6-Month CD Rates in 2026: Compare Top Short-Term CDs
    Meta Description: Compare the best 6-month CD rates in 2026, including APY, minimum deposits, early-withdrawal penalties, maturity rules and short-term savings alternatives.
    Focus Keyword: Best 6-Month CD Rates in 2026
    Slug: best-6-month-cd-rates-in-2026
    Canonical: https://financeinvestment.site/best-6-month-cd-rates-in-2026/
    Featured Image ALT: Best 6-Month CD Rates in 2026

    Why a 6-Month CD Can Be a Useful Middle Ground

    Best 6-Month CD Rates in 2026If you’re comparing the Best 6-Month CD Rates in 2026, August 2026 is an interesting point for short-term savers. Competitive CD offers remain attractive, but the headline APY is only one part of the decision. Your cash timeline, minimum deposit, withdrawal penalty, and what happens when the CD matures can matter just as much.

    A six-month term can suit someone who wants a fixed return without committing cash for a full year. It can also create a useful checkpoint if you expect your savings needs or available rates to change.

    What You’ll Learn

    You’ll learn how six-month CDs work, how to compare APYs, where penalties matter, when a shorter term may fit, and how to think about the money you will need when the CD matures.

    For the broader picture, see our

    Complete CD Guide for 2026
    .

    Quick answer: The Best 6-Month CD Rates in 2026 can be useful when you want a fixed return but don’t want to commit your cash for a full year. Compare the APY with your actual six-month goal before opening an account.

    • Compare APY, not just the advertised rate.
    • Check the minimum opening deposit.
    • Read the early-withdrawal penalty first.
    • Check whether the CD automatically renews.
    • Keep emergency cash outside the CD.
    • Compare six months with shorter and longer terms.
    Bottom line: A strong six-month APY matters, but the best choice is the one that matches when you need the money.

    6-Month CD Rates at a Glance

    The Best 6-Month CD Rates in 2026 can be attractive for savers who want a fixed return without a long commitment. As of August 2026, published market data showed a leading 6-month offer around 4.50% APY, although rates, terms and eligibility can change.

    Best for: Short-term goals, planned expenses and money you can leave untouched for six months.

    Key numbers: APY, deposit minimum, maturity date and early-withdrawal penalty.

    August 2026 SnapshotPractical Meaning
    6-month leader: about 4.50% APYCompetitive short-term yield
    Term: 6 monthsEarlier access than a 12-month CD
    Compare: APY + minimum + penaltyHeadline rate isn’t the whole deal

    How to Compare a 6-Month CD as a Beginner

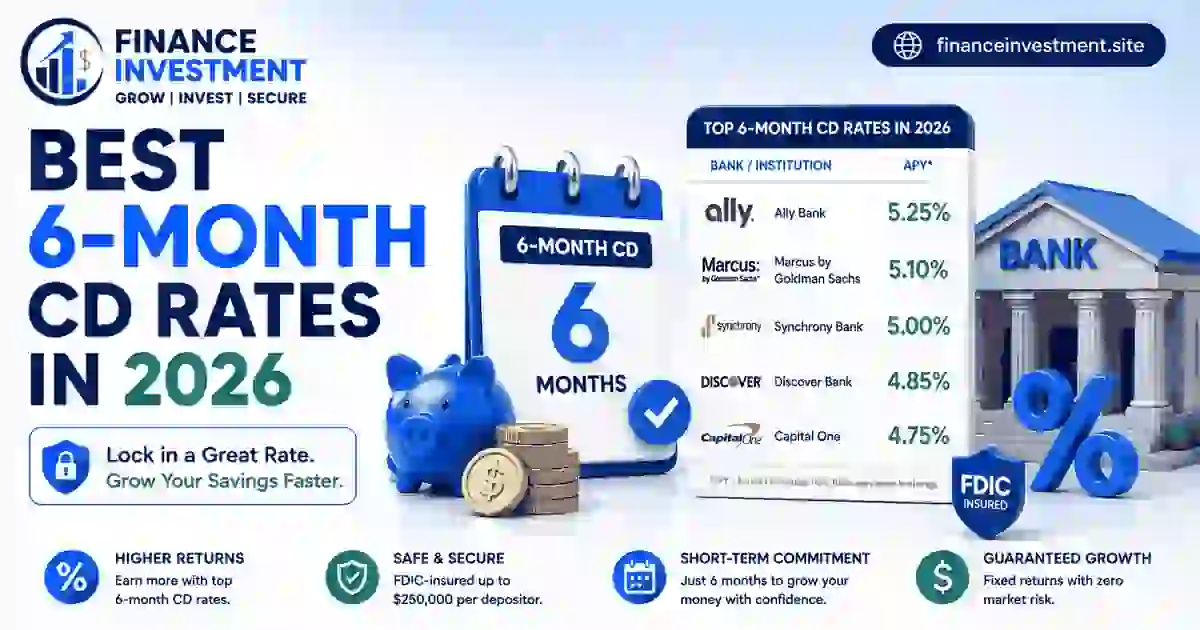
    Best 6-Month CD Rates in 2026When shopping for the Best 6-Month CD Rates in 2026, don’t stop at the biggest APY on the screen. As of August 20, 2026, some published six-month offers were near 4.9%, while many competitive CDs were around 4% or higher. The exact offer can depend on the institution, membership rules, deposit size and eligibility.
    Start With the APY

    APY makes it easier to compare deposits because it reflects the annualized yield and compounding. But a six-month CD does not pay a full year’s worth of interest simply because its APY is quoted annually. For example, $10,000 at a hypothetical 4.50% APY would earn roughly $222 over six months before taxes, assuming the stated APY and compounding structure remain applicable.

    Then Check the Fine Print

    Look at the minimum deposit, maturity date, interest payout method and early-withdrawal penalty. FDIC guidance says account disclosures should explain the maturity date, penalty terms, compounding details and whether the CD renews automatically.

    A useful comparison:

    Put the APY, minimum deposit, estimated six-month earnings and penalty side by side. A slightly lower APY can be more useful if it has a smaller deposit requirement or better withdrawal terms.

    For the rate mechanics, read our

    guide to CD interest rates
    .
    For the broader product basics, see

    what a certificate of deposit is
    .

    How 6-Month CDs Work

    A six-month CD gives your deposit a fixed term and, with a fixed-rate CD, locks the agreed APY until maturity. In August 2026, six-month yields remain competitive: one current market snapshot lists a top six-month APY of 4.94%, although offers vary by bank, deposit size and eligibility.

    APY

    Shows the annualized yield, including compounding.

    Six-Month Term

    Your money generally stays in the CD until the maturity date.

    Maturity

    You can usually withdraw, renew or move the money during the bank’s stated grace period.

    For example, imagine opening a six-month CD in August 2026 at a hypothetical 4.50% APY. The APY is an annualized figure, so six months of earnings won’t equal 4.50% of your deposit. Your actual interest depends on the bank’s compounding and payout method. At maturity, check the renewal terms rather than letting the account roll over by accident. FDIC guidance recommends reviewing the CD’s disclosures, including maturity and withdrawal provisions.

    Learn more in our

    guide to how CDs work

    and our

    explanation of CD interest rates
    .

    Benefits and Drawbacks of 6-Month CDs

    The appeal of a six-month CD is simple: you can secure a fixed yield without tying up your money for years. In August 2026, short-term CDs remain among the more competitive terms, with some six-month offers around 4% or higher.

    ✓ Pros

    • Locks a fixed rate for the term.
    • Shorter commitment than a one-year CD.
    • Useful for money with a known near-term goal.
    • Can provide a clear maturity date for the next decision.

    ✕ Cons

    • Money is less accessible before maturity.
    • Early withdrawal can trigger a penalty.
    • Rates may be higher when the CD matures—or lower.
    • A higher APY elsewhere may require a larger deposit.
    Best use:

    A six-month CD can fit planned cash you won’t need immediately, but it shouldn’t replace an emergency fund or money you may need tomorrow.

    6-Month CD Rate Comparison for August 2026

    When comparing the Best 6-Month CD Rates in 2026, look at more than the APY. Current August data shows six-month offers reaching roughly 4.94% APY, while other competitive offers sit lower depending on the institution and eligibility.

    TermIllustrative APY*Minimum DepositRate TypePractical Use
    6 monthsUp to ~4.94%Varies by bankUsually fixedShort-term goals
    3 monthsOften lowerVariesUsually fixedVery near-term cash
    12 monthsCompare separatelyVariesUsually fixedLonger commitment

    *APYs are illustrative market figures, not guaranteed offers. Verify the current rate, minimum deposit and account terms directly before opening.

    Costs, Taxes, Risks & Expert Tips

    A six-month CD can look attractive at first glance, but the real return depends on taxes, withdrawal rules and the amount you actually deposit. In August 2026, leading CD yields remained competitive, with some published rates above 4%.

    Expert Tip

    Imagine depositing $20,000 at a hypothetical 4.50% APY. Six-month interest would be roughly $445 before taxes, depending on the bank’s compounding method. Compare that after-tax result with the return and access offered by a savings account.

    ⚠️ Warning Before Opening

    CD interest is generally taxable income under federal rules. If you withdraw early, the bank may impose a penalty, and the IRS has specific reporting rules for the interest and penalty. Check the account disclosure before committing your cash.

    Common 6-Month CD Mistakes + A Real-Life Example

    One common mistake is chasing the highest APY without checking the deposit requirement or early-withdrawal rules. Another is assuming every six-month offer is equally competitive. On August 20, 2026, published CD data showed rates as high as 4.94% across available terms, while recent six-month offers have varied by institution.

    Real-Life Example: Maria Has $18,000

    Maria expects to use $18,000 for a vehicle purchase in about eight months. She finds a six-month CD advertising 4.50% APY, but another account offers 4.25% with easier access. She chooses the six-month CD only for the portion she knows she won’t need before maturity and keeps the rest liquid for the purchase.

    Practical Lesson

    • Don’t compare APY alone.
    • Match the maturity date to your cash goal.
    • Check the penalty before depositing.
    • Don’t lock money needed for emergencies.

    Who Should Choose a 6-Month CD?

    A six-month CD can suit savers who have a clear reason for keeping their money untouched for half a year. Current August 2026 data shows six-month yields remain competitive, with some offers reaching 4.94% APY.

    Premium Best Fit

    • Goal-based savers: You have a known expense in roughly six months.
    • Retirees: You want predictable interest on part of your cash.
    • Families: You are setting aside money for a planned expense.
    • Rate-sensitive savers: You value today’s fixed yield.
    • Surplus-cash holders: You can leave the deposit untouched.

    Frequently Asked Questions About 6-Month CDs

    1. What are the best 6-month CD rates in August 2026?

    Published rates vary by bank, credit union, deposit size and eligibility. Recent August data shows six-month offers around 4% to 5%, with some special offers reaching 5%. Always verify the rate before opening.

    2. What APY should I look for on a six-month CD?

    There is no single target APY that fits everyone. Compare the advertised yield with the minimum deposit, penalty, maturity terms and available savings alternatives.

    3. Is a six-month CD better than a savings account?

    A CD can provide a fixed rate, while a savings account usually offers easier access but a variable APY. The better choice depends on whether certainty or liquidity matters more.

    4. How much money do I need to open a six-month CD?

    Minimums vary widely. Some accounts require only a small opening deposit, while promotional or specialty CDs may require thousands of dollars. Check the bank’s current terms.

    5. What happens when a six-month CD matures?

    Depending on the bank, the CD may renew automatically unless you withdraw or change instructions during the stated grace period. Check the maturity notice before the deadline.

    6. Is CD interest taxable?

    Generally, yes. The IRS says most taxable interest is reported as income when it becomes available to you.

    7. What happens if I withdraw a CD early?

    The bank may charge an early-withdrawal penalty or reduce the interest you receive. The exact rule depends on the account agreement.

    8. Are six-month CDs FDIC insured?

    A CD at an FDIC-insured bank is generally an insured deposit, subject to applicable coverage limits and ownership rules. Confirm the institution’s insurance status before depositing money.

    9. Are the best 6-month CD rates likely to change?

    Yes. Banks and credit unions can change the rates offered on new CDs as market conditions and their funding needs change. Once you open a typical fixed-rate CD, its agreed rate generally remains fixed through the term.

    Bottom line:
    The best 6-month CD rates in 2026 should be judged by the complete deal—not APY alone. Check the deposit requirement, maturity date, withdrawal penalty and insurance before opening.

    Final Verdict: Is a 6-Month CD Worth It?

    In August 2026, the Best 6-Month CD Rates in 2026 can make sense for money you expect to leave untouched for roughly half a year. Some published offers are near 5% APY, but the highest headline rate isn’t automatically the best choice for every saver.

    Choose, Compare, or Wait

    • Choose: when the APY fits your goal and you won’t need the cash early.
    • Compare: when another bank may offer a better combination of APY, minimum deposit and penalty.
    • Wait: when your cash needs are uncertain or liquidity matters more than a fixed return.

    Before opening an account, use our

    Complete CD Guide for 2026

    to review CD terms, safety and strategies. The strongest choice is the one that fits your timeline—not simply the number printed beside the APY.

    Related Resources

    Want to compare your options more carefully? These guides cover CD rates, earnings, APY and the rules that can affect your choice.

    Official resources:
    Review the

    FDIC

    for deposit-insurance information,

    Federal Reserve

    materials for monetary-policy information, and

    IRS Topic 403

    for taxable-interest guidance.

    Ready to Compare Your Options?

    Keep your rate shopping simple. Get practical finance guides by email, then explore our CD resources when you’re ready to compare terms, APYs and account details.

    Email:

    subhashr325@gmail.com

  • Should You Lock in a CD Rate Now? 2026 Guide

    Should You Lock in a CD Rate Now? 2026 Guide

    Should You Lock in a CD Rate Now?


    Written by Subhash Rukade

    FinanceInvestment • Updated August 21, 2026 • About 12 min read

    SEO Title: Should You Lock in a CD Rate Now? 2026 Guide
    Meta Description: Should you lock in a CD rate now? Compare today’s fixed APY with waiting, rate risk, CD terms, penalties, and your cash needs before deciding.
    Focus Keyword: Should You Lock in a CD Rate Now
    Slug: should-you-lock-in-a-cd-rate-now
    Canonical: https://financeinvestment.site/should-you-lock-in-a-cd-rate-now/
    Featured Image ALT: Should You Lock in a CD Rate Now

    Is This a Good Time to Lock a CD?

    Should You Lock in a CD Rate Now? 2026 CD rate guideIf you’re asking, Should You Lock in a CD Rate Now, August 2026 offers a genuinely interesting choice. The Fed has kept its target range at 3.50%–3.75%, while some competitive CDs are offering around 4.5% APY.

    The right move depends less on guessing the next Fed decision and more on when you’ll need the money. A fixed CD can protect an attractive rate, but locking everything away can become frustrating if rates rise or your plans change.

    What You’ll Learn

    You’ll see when locking a rate may make sense, when waiting could be reasonable, how term length changes the decision, and how splitting your cash can reduce timing risk.

    For the bigger picture, start with our

    Complete CD Guide for 2026
    .

    Quick answer: There is no universal “right now” answer. With competitive August 2026 CDs reaching roughly 4%–4.5% APY, locking can make sense when the rate fits your goal and you can leave the money untouched. 0

    • Locking fixes your APY for the CD term.
    • Waiting preserves access and future shopping power.
    • Shorter CDs can reduce timing risk.
    • Longer CDs can protect today’s yield for longer.
    • A CD ladder can spread maturity dates.
    • Never lock emergency cash just for a higher APY.
    Bottom line: Lock when the current rate works for your timeline—not simply because you fear rates will change.

    Locking a CD Rate: At a Glance

    Should You Lock in a CD Rate Now? In August 2026, the answer depends on your timeline, liquidity needs and the APY you can actually secure. The Fed’s target range is 3.50%–3.75%, while some competitive CDs are offering roughly 4%–4.5% APY.

    Best for: Money you can leave untouched until maturity.

    Key numbers: APY, term, minimum deposit and early-withdrawal penalty.

    August 2026 SnapshotWhat It Means
    Fed range: 3.50%–3.75%Rates remain sensitive to Fed decisions
    Top offers: about 4%–4.5%+Competitive yields are available
    Short terms remain attractiveFlexibility may matter when timing is uncertain

    When Does Locking a CD Rate Make Sense?

    <!-- FOCUS KEYWORD -->
Should You Lock in a CD Rate NowIf you’re wondering Should You Lock in a CD Rate Now, start with one question: When will I need this money? That matters more than trying to predict the next rate move. In August 2026, competitive CD offers are reaching roughly 4.5% APY, while the Federal Reserve’s target range remains 3.50%–3.75%.

    When Locking Can Work

    Locking may fit when you have cash you won’t need before maturity and the APY is strong enough for your goal. A fixed rate removes one uncertainty: your bank generally won’t lower that agreed rate during the CD term. Recent market data also shows unusually strong yields on several shorter-term CDs, making term selection especially important.

    When Waiting Can Be Better

    Waiting can make sense if you may need the cash soon or if you expect better offers and can accept the risk that today’s rate disappears. Don’t sacrifice liquidity simply to chase a slightly higher APY.

    Simple test:

    Compare the guaranteed APY with your expected holding period, minimum deposit, penalty and access needs.

    Before choosing a term, read our

    guide to CD interest rates

    and see the practical math in

    how much you can earn from a CD
    .

    How Locking a CD Rate Actually Works

    When you open a fixed-rate CD, you agree to leave your deposit with the bank for a specific term in exchange for the stated yield. The Should You Lock in a CD Rate Now decision is really about trading flexibility for rate certainty. The FDIC defines a CD as a deposit instrument that pays interest for a specific period and may carry either a fixed or variable rate.

    APY

    Shows the annualized yield, including the effect of compounding.

    Term

    Sets how long your money is committed before maturity.

    Maturity

    At maturity, you can generally take the funds or follow the bank’s renewal rules.

    For example, suppose you open a 12-month CD in August 2026 at 4.25% APY. If rates later move higher, your existing fixed-rate CD normally keeps its agreed rate through maturity. If you withdraw early, however, the bank may apply the disclosed penalty. Renewal terms also matter because some CDs automatically renew unless you act during a stated grace period.

    Before choosing, compare the

    best CD rates available

    and review

    how CDs work

    from deposit to maturity.

    Benefits & Drawbacks of Locking a CD Rate

    Locking a competitive rate can be attractive in August 2026 because some top CDs are offering yields around 4% or more. A fixed rate gives you certainty for the agreed term, even if banks later reduce rates.

    ✓ Pros

    • Locks in a predictable APY.
    • Protects the rate if new CD yields fall.
    • Makes future interest easier to estimate.
    • Works well for money with a known future use.

    − Cons

    • Your money is less flexible during the term.
    • Higher future rates could leave you with a lower yield.
    • Early withdrawal may trigger a penalty.
    • Long terms can create opportunity-cost risk.

    The trade-off:
    you’re exchanging some flexibility for rate certainty. That can be worthwhile when the APY fits your goal, but keeping part of your cash liquid can make sense when your plans or rates may change.

    Lock Now vs. Wait: Which Strategy Fits?

    The best choice depends on what your money needs to do next. In August 2026, top CD offers were reaching about 4.50% APY, while the Federal Reserve’s target range remained 3.50%–3.75%.

    StrategyAPY CertaintyFlexibilityRate RiskBest Use
    Lock nowHighLowerMisses higher future ratesKnown future goal
    WaitNoneHigherToday’s offer may disappearNear-term flexibility
    Split moneyMixedMedium–HighReduced timing riskUncertain plans

    A practical middle ground:
    If you’re unsure, you don’t have to make an all-or-nothing decision. Lock the portion you know you won’t need while keeping the rest accessible or using shorter maturities.

    Costs, Taxes, Risks & Expert Tips

    Before you decide Should You Lock in a CD Rate Now, look beyond the advertised APY. CD interest is generally taxable when it becomes available to you. The IRS also provides for reporting certain early-withdrawal penalties on Form 1099-INT.

    💡 Expert Tip

    Suppose you lock $25,000 at a hypothetical 4.25% APY for one year. The simple interest estimate is about $1,062.50 before taxes. Compare that after-tax result with keeping some money flexible.

    ⚠️ Warning Before You Lock

    If an unexpected expense forces you to break the CD, your bank may charge an early-withdrawal penalty or reduce the interest you keep. FDIC guidance recommends checking the bank’s specific fees before opening the CD.

    Common Lock-In Mistakes + A $60,000 Example

    One mistake is locking every dollar simply because today’s APY looks attractive. Another is waiting forever for a better rate. In August 2026, competitive CDs were reaching about 4.55% APY, while shorter terms remained particularly competitive.

    Real-Life Example: Jennifer Has $60,000

    Jennifer has $60,000 in cash. She knows $20,000 may be needed within a year, while $25,000 can remain untouched for two years. The remaining $15,000 is her emergency reserve. Instead of putting the entire balance into one CD, she could keep the emergency money liquid, use a shorter CD for the near-term portion, and consider a longer maturity for the money she won’t need soon.

    Practical Lesson

    • Don’t lock money you’ll need soon.
    • Compare the APY with the full term, not just the headline rate.
    • Use multiple maturities when timing is uncertain.
    • Check the early-withdrawal penalty before opening.

    Who Should Lock in a CD Rate?

    Should You Lock in a CD Rate Now is easier to answer when your cash has a clear job. In August 2026, some competitive CDs were offering around 4.5% APY, but the right choice still depends on your timeline and access needs.

    Premium Best Fit

    • Goal-based savers: You know when the money will be needed.
    • Retirees: You want predictable interest from part of your cash.
    • Families: A future expense has a defined timeline.
    • Rate-sensitive savers: Today’s APY looks attractive enough to accept less flexibility.
    • Surplus-cash holders: You can comfortably leave the deposit untouched.

    Frequently Asked Questions About Locking a CD

    1. Should You Lock in a CD Rate Now?

    It can make sense if the current APY fits your goal and you can leave the money untouched until maturity. In August 2026, some leading CDs were offering up to about 4.55% APY, particularly on shorter terms.

    2. What is a good CD rate right now?

    There isn’t one universal “good” rate. Compare the APY with the term, minimum deposit, withdrawal rules and your alternatives. Current top offers are well above the national average for many terms.

    3. Can CD rates change after I lock one?

    A fixed-rate CD generally keeps its agreed rate through the term. New CDs opened later can have different rates, however, so locking protects your current yield but also limits your ability to benefit from higher future offers.

    4. Is it better to choose a short-term or long-term CD?

    Choose based on when you’ll need the money. Shorter terms can preserve flexibility, while longer terms can lock a fixed yield for more time. Current August 2026 data shows unusually competitive short-term CD yields.

    5. What if CD rates rise after I lock my money?

    Your existing fixed-rate CD generally keeps its original APY, but new CDs may offer more. That’s the main opportunity cost of locking early.

    6. Is CD interest taxable?

    Generally, yes. The IRS says interest from certificates of deposit is taxable interest income, subject to applicable tax rules.

    7. What happens if I withdraw a CD early?

    Your bank may charge an early-withdrawal penalty or reduce the interest you receive. Check the CD agreement before opening it. The IRS also provides specific reporting and deduction rules for qualifying early-withdrawal penalties.

    8. Are CDs covered by FDIC insurance?

    CDs are covered deposit products when held at an FDIC-insured bank, subject to applicable insurance limits and ownership rules. Always confirm the institution is FDIC-insured.

    9. Should I lock all my savings into one CD?

    Usually, there is no reason to make it all-or-nothing. Keeping emergency cash accessible and splitting longer-term money across different maturities can reduce the risk of choosing the wrong timing.

    Bottom line:
    the right CD decision depends on your cash timeline, the APY available today, and how comfortable you are giving up flexibility.

    Final Verdict: Lock, Wait, or Split?

    In August 2026, the decision is less about finding a perfect moment and more about matching the CD to your cash timeline. With competitive offers around 4%–4.5% APY, a fixed rate can be worth locking when you have a clear goal and won’t need the money before maturity.

    A Simple Decision

    • Lock: when today’s APY fits your goal and timeline.
    • Wait: when you need flexibility or may need the cash soon.
    • Split: when you want some rate certainty without committing everything.

    For the bigger picture on CD terms, safety and strategies, see our

    Complete CD Guide for 2026
    .
    The best choice is the one that protects both your yield and your access to cash.

    Related Resources

    Before opening a CD, these guides can help you compare rates, understand the fine print, estimate potential earnings, and check official banking rules.

    Official sources:
    Check the
    Federal Reserve
    for monetary-policy information,
    FDIC
    for deposit-insurance guidance, and the
    IRS
    for interest-income tax information.

    Make Your Next CD Decision With Confidence

    Rates can change, but your money goals don’t have to. Get practical banking and investing guides delivered by email, then use our related CD resources when you’re ready to compare your options.

    Email:
    subhashr325@gmail.com