What Could $100,000 in a CD Earn in 2026?
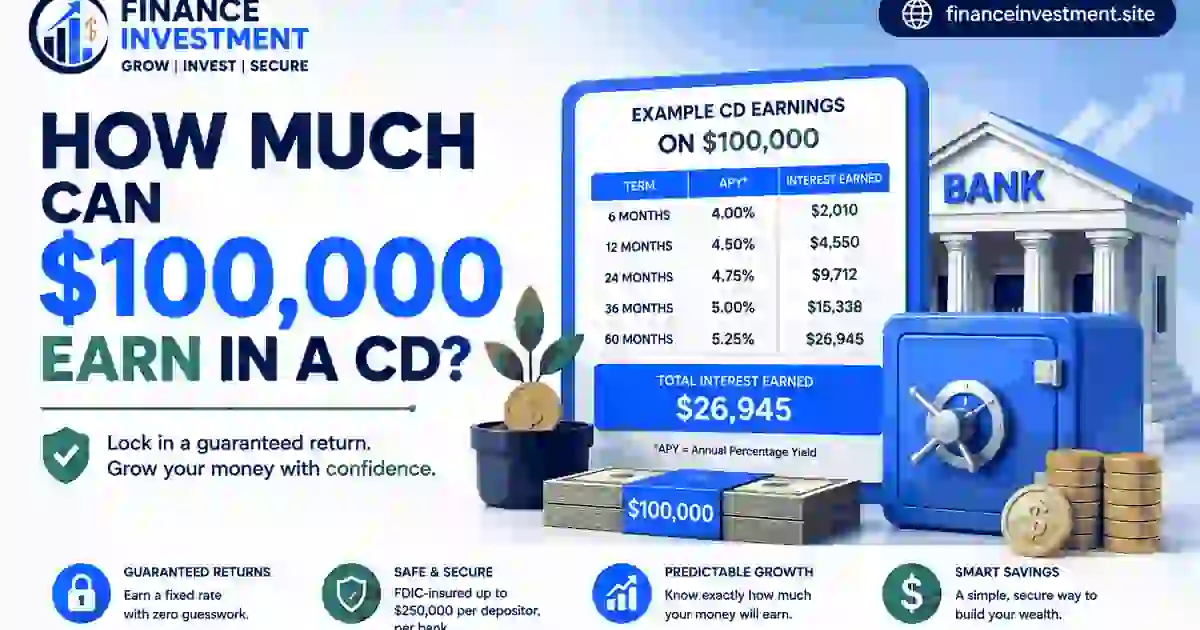 How Much Can $100,000 Earn in a CD depends on the APY, term, and CD agreement. Imagine Sarah has $100,000 from the sale of a home and does not expect to use most of it for the next year. Rather than choosing a CD based only on the headline rate, she compares the potential interest, maturity date, withdrawal rules, and deposit insurance before committing the money.
At this balance, even a small rate difference can become significant. A 1-percentage-point difference represents roughly $1,000 of interest over one year before taxes, using a simple illustration. That makes rate shopping worthwhile, but access to the money matters just as much.
For the bigger picture, explore our
complete CD guide for 2026
.
What You’ll Learn
You’ll see how APYs affect $100,000, how terms and compounding change the numbers, what taxes and early withdrawal penalties can cost, and why insurance coverage and CD laddering deserve attention with a large deposit.
Quick Answer: What Could $100,000 Earn?
How Much Can $100,000 Earn in a CD depends on the APY and term. At a 4.00% APY for one year, a $100,000 deposit could earn about $4,000 before taxes, assuming the stated APY applies for the full year.
- A 0.50% APY difference can represent about $500 over one year.
- A 1% rate difference can mean roughly $1,000 more or less in annual interest.
- A longer CD can increase total earnings but reduces access to your cash.
- Compounding can make the actual return differ from a simple interest estimate.
- CD interest is generally taxable in a regular taxable account.
- With $100,000, deposit-insurance rules deserve careful attention.
Bottom line:
With a six-figure deposit, comparing APYs carefully can make a meaningful difference, but liquidity and account safety should stay part of the decision.
Table of Contents
At a Glance: $100,000 CD Earnings
How Much Can $100,000 Earn in a CD varies with the APY and term. With six figures invested, even a modest rate difference can noticeably change the interest earned.
4% APY for one year could produce about $4,000.
Surplus cash with a known timeline.
Deposit, APY, term, taxes, penalty and coverage.
| APY | Term | Deposit | Estimated Interest* | Approx. Balance* |
|---|---|---|---|---|
| 3.00% | 1 year | $100,000 | ~$3,000 | ~$103,000 |
| 4.00% | 1 year | $100,000 | ~$4,000 | ~$104,000 |
| 5.00% | 1 year | $100,000 | ~$5,000 | ~$105,000 |
*Illustrative one-year estimates using the stated APY. Actual maturity values depend on the CD agreement and compounding method.
A Beginner’s Guide to Putting $100,000 in a CD
 How Much Can $100,000 Earn in a CD becomes easier to judge when you separate the decision into three parts: the APY, the term, and your need for access. Imagine James receives $100,000 after selling a rental property. He expects to use about $30,000 for a renovation next year, while the remaining $70,000 can stay untouched longer. Instead of treating the entire balance the same way, he compares terms that match each goal.
Start With the APY
Suppose a one-year CD offers 4.25% APY. A simple estimate is $100,000 × 0.0425 = $4,250 in interest before taxes. At 4.75%, the same calculation gives about $4,750. That 0.50-percentage-point difference is roughly $500 over one year, assuming the stated APYs apply for the full term.
Match the Term to Your Goal
A six-month CD may work for money needed relatively soon. A longer CD can suit cash with a later purpose, but locking everything away can create problems if plans change. Before opening the account, review
how CD terms and maturity work
.
It is also worth comparing the potential return with a savings account. Our
CD earnings guide
explains how deposit size and rates can change the numbers.
A useful starting point:
Keep money needed soon accessible, and consider CDs for the portion that truly fits the maturity schedule.
How $100,000 CD Interest Is Calculated
How Much Can $100,000 Earn in a CD depends on the APY, term, and how interest compounds. A quick multiplication can help you estimate the return, but APY is the better number to use when comparing CD offers because it reflects the annual yield after compounding.
A Fresh $100,000 Example
Suppose a one-year CD advertises a 4.60% APY. A simple estimate would be:
That suggests about $104,600 after one year before taxes. The actual maturity amount can differ slightly depending on the bank’s compounding and interest-crediting rules.
| Method | Purpose | $100K Example |
|---|---|---|
| Simple estimate | Deposit × APY | ~$4,600 |
| APY-based result | Annual yield including compounding | Use the stated APY |
For more detail, read our
APY vs. interest rate guide
.
You can also see how compounding affects savings in our
compound interest guide
.
Benefits & Drawbacks of a $100,000 CD
A six-figure deposit changes the math. How Much Can $100,000 Earn in a CD can become a meaningful question when a small APY difference translates into hundreds or thousands of dollars. At the same time, putting this much cash into one account requires more attention to access, insurance, and taxes.
✓ Pros
- Meaningful interest: At 4.50% APY, $100,000 could generate about $4,500 over one year before taxes.
- Predictable planning: A fixed-rate CD can make future cash planning easier.
- Less market exposure: Your return is not tied to daily stock-market swings.
- Goal matching: A maturity date can fit a planned expense.
− Cons
- Access can be limited: Early withdrawals may trigger penalties.
- Rate lock: You may miss a better rate after opening the CD.
- Tax exposure: Interest can increase taxable income.
- Insurance planning: A large deposit requires checking coverage across your accounts and ownership categories.
The key trade-off:
A strong rate can make $100,000 work harder, but flexibility and proper deposit-insurance planning become more important as the balance grows.
$100,000 CD Earnings Comparison
With How Much Can $100,000 Earn in a CD, the rate difference becomes much easier to see in dollars. The figures below are illustrative APY-based estimates using annual compounding. They are not current bank offers.
| Deposit | APY | Term | Estimated Interest* | Ending Balance* |
|---|---|---|---|---|
| $100,000 | 3.50% | 1 year | $3,500 | $103,500 |
| $100,000 | 4.00% | 1 year | $4,000 | $104,000 |
| $100,000 | 4.50% | 2 years | $9,202.50 | $109,202.50 |
| $100,000 | 5.00% | 3 years | $15,762.50 | $115,762.50 |
*Calculated as $100,000 × (1 + APY)years. Actual CD maturity values depend on the institution’s terms and interest-crediting rules.
What stands out:
A higher APY can add thousands of dollars over several years, but locking up $100,000 longer also reduces flexibility.
Costs, Taxes, Risks & Expert Tips
How Much Can $100,000 Earn in a CD should be judged after considering taxes, access, and possible penalties—not just the advertised APY. For example, if a CD earns $4,500 in interest and you face a hypothetical 22% federal tax rate, about $990 could go toward federal taxes, leaving roughly $3,510 before any state tax.
💡 Expert Tip
Before depositing $100,000, compare the APY with the early-withdrawal penalty, maturity rules, and insurance coverage. A slightly lower rate may be worthwhile if it gives you better flexibility.
⚠️ Early-Withdrawal Warning
Suppose you open a CD with $100,000 and later need the cash before maturity. The institution may charge an early-withdrawal penalty based on its agreement. That cost can reduce the interest you expected and, depending on the terms, may affect your principal.
Common $100,000 CD Mistakes + Real-Life Example
How Much Can $100,000 Earn in a CD can look impressive when you see the interest figure, but the wrong account can create unnecessary problems. Common mistakes include locking up every dollar, ignoring the early-withdrawal penalty, overlooking deposit-insurance limits, and choosing a rate without checking the maturity date.
Real-Life Example: Linda’s Inheritance
Linda receives a $100,000 inheritance. She finds a two-year CD offering a strong APY and deposits the entire amount. Six months later, her daughter needs help with a home purchase, and Linda wants to provide $20,000. The CD’s early-withdrawal rules make accessing the money more expensive than she expected.
The Practical Lesson
- Don’t lock up money you may need soon.
- Compare insurance coverage before concentrating a large balance.
- Check the penalty before opening the CD.
- Consider splitting the money across different maturity dates.
With a six-figure deposit, planning the timing can matter just as much as chasing the highest rate.
Who Should Consider a $100,000 CD?
How Much Can $100,000 Earn in a CD matters most when the money has a clear purpose and you can leave it untouched for the selected term. A large balance can generate meaningful interest, but flexibility still matters.
✓ Premium Best Fit
- Goal-based savers: You have a known expense with a future date.
- Retirees: Part of your cash needs a predictable return without stock-market exposure.
- Families: You are setting aside money for tuition, a home purchase, or another planned cost.
- Inheritance recipients: You want time to decide what to do with newly received cash.
- Surplus-cash holders: Your emergency reserve and near-term needs are already covered.
Frequently Asked Questions About a $100,000 CD
How Much Can $100,000 Earn in a CD depends on the APY, term, compounding method, and account rules. These questions cover the details worth checking before placing a large cash balance into a CD.
1. How much can $100,000 earn in a CD?
At a 4% APY for one year, $100,000 could earn about $4,000 before taxes, assuming the stated APY applies for the full year.
2. How much would $100,000 earn at 5% APY?
A one-year illustration at 5% APY produces about $5,000 in interest before taxes. The actual maturity value follows the CD’s stated terms.
3. Does APY include CD compounding?
Yes. APY is intended to reflect the annual yield while accounting for compounding. Always review the institution’s disclosure for the exact interest-crediting rules.
4. Is interest from a $100,000 CD taxable?
Interest from a regular taxable CD is generally included in taxable income. Your actual tax bill depends on your federal, state, and personal tax situation.
5. What if I need the $100,000 before maturity?
You may be able to withdraw the funds early, but the bank or credit union can apply an early-withdrawal penalty according to the account agreement.
6. What happens when a $100,000 CD matures?
At maturity, you generally receive the principal plus earned interest, or the CD may renew if you do not provide different instructions during the institution’s grace period.
7. Is a $100,000 CD fully covered by FDIC insurance?
Generally, yes, if it is held at an FDIC-insured bank in an eligible ownership category and your total deposits in that category remain within the applicable insurance limit. Other accounts at the same bank can affect your coverage.
8. Should I put the entire $100,000 into one CD?
Not always. A CD ladder or multiple maturity dates can provide more flexibility, while spreading deposits across institutions may help with insurance planning when appropriate.
9. Is a higher APY always better for $100,000?
No. Compare the APY with the term, penalty, maturity rules, liquidity needs, and deposit-insurance coverage before choosing an account.
Once you understand How Much Can $100,000 Earn in a CD, look beyond the headline rate and compare the complete account terms.
Final Verdict: Is a $100,000 CD Worth It?
How Much Can $100,000 Earn in a CD can be a meaningful question when a large cash balance is sitting on the sidelines. At 4% APY, a one-year CD could generate about $4,000 before taxes. At 5%, that rises to about $5,000. The difference is large enough to make rate shopping worthwhile.
Still, the highest rate should not be the only deciding factor. If the money has a known future purpose, choose a term that fits the date you expect to need it. If you may need access sooner, keeping some cash outside the CD can prevent an unnecessary early-withdrawal penalty.
For a six-figure deposit: compare APY, term, taxes, withdrawal rules, maturity instructions, and deposit-insurance coverage before committing the full amount.
For a broader look at CD strategies, rates, terms, and account choices, read our
complete CD guide for 2026
.
Related Resources
If you’re deciding what to do with a large cash balance, these guides can help you compare CD options, understand interest, and weigh alternatives.
For official guidance, see the
FDIC deposit-insurance information
,
CFPB bank-account resources
,
and
IRS guidance on interest income
.
Make Your Next Money Move With Confidence
Get practical CD insights, savings ideas, and easy-to-follow money guides from FinanceInvestment delivered straight to your inbox.
Questions or suggestions?
subhashr325@gmail.com
Leave a Reply