FDIC Insurance for Couples With Multiple Bank Accounts: 2026 Guide
11 min read
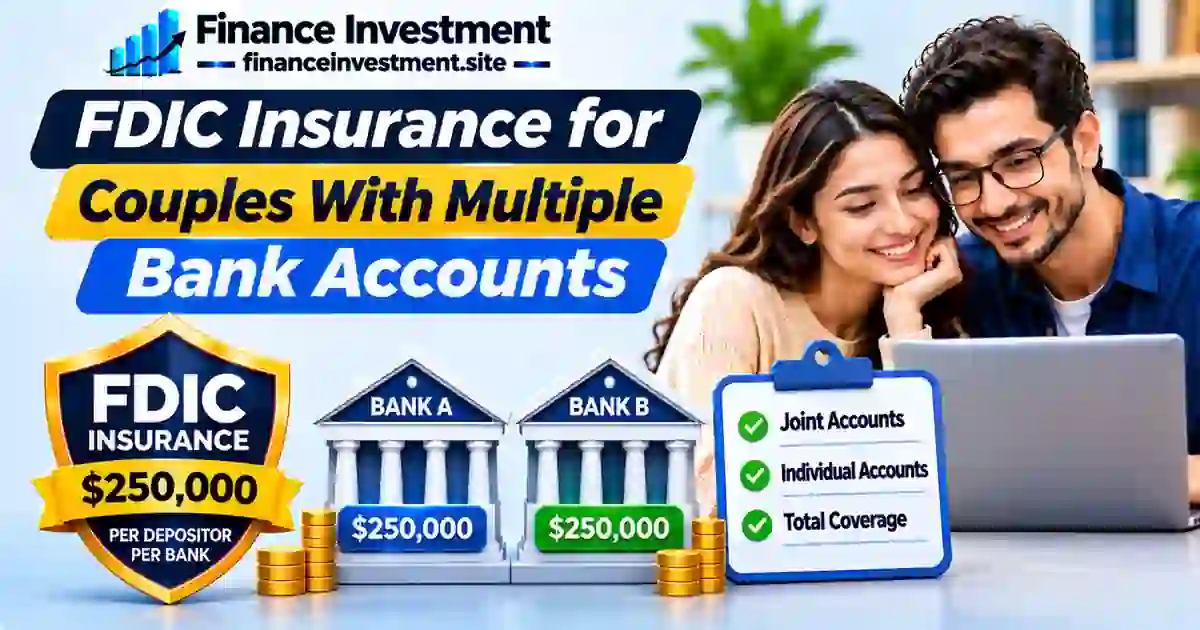
FDIC Insurance for Couples: Why Account Ownership Matters
FDIC insurance for couples with multiple bank accounts raises an important question: how much of your shared savings is actually protected? Picture a married couple with $700,000 divided among checking, savings and joint accounts at the same bank. Would every dollar be insured if that bank failed?
The answer depends on account ownership, FDIC insurance categories and the total eligible deposits held at that insured bank. Having several account numbers does not automatically create additional coverage.
This guide walks through the rules with practical examples, helping couples identify possible coverage gaps before moving money. For the fundamentals, read our FDIC and NCUA insurance guide.
What You’ll Learn
- How FDIC coverage differs for individual and joint accounts.
- When using more than one insured bank increases protection.
- How to estimate coverage and spot common mistakes.
Quick Answer: How Much FDIC Insurance Can a Couple Have?
Quick Answer: At one FDIC-insured bank, each spouse can receive up to $250,000 in single-account coverage. Qualifying joint accounts can provide another $500,000 combined for two equal co-owners. That means a couple may have up to $1 million in combined coverage across these two ownership categories, provided all requirements are met.
6 Key Takeaways for Couples
- Individual accounts: Each spouse has a separate $250,000 single-ownership limit per insured bank.
- Joint accounts: Each qualifying co-owner generally receives up to $250,000 in joint-category coverage.
- Multiple accounts: Deposits in the same ownership category at one bank are added together.
- Different banks: Separately FDIC-insured institutions provide separate coverage limits.
- Trust accounts: Eligible trust deposits follow additional beneficiary-based rules.
- Interest matters: Accrued interest counts toward applicable insurance limits.
Bottom Line: Check who owns each account, group deposits by insured bank and ownership category, and calculate coverage before adding more money.
Table of Contents
At a Glance: FDIC Coverage for Couples
For couples, the biggest distinction is between individual and jointly owned deposits. The figures below assume eligible accounts at one FDIC-insured bank, with no other deposits affecting these coverage limits.
Quick Facts and Coverage Summary
| Account Ownership | Potential FDIC Coverage |
|---|---|
| Spouse A: single accounts | Up to $250,000 |
| Spouse B: single accounts | Up to $250,000 |
| Both spouses: qualifying joint accounts | Up to $500,000 combined |
| Combined potential at one bank | Up to $1,000,000* |
*Illustrative maximum for these two ownership categories. Actual coverage depends on FDIC eligibility, account ownership, total deposits and accrued interest.
Best For: Married couples managing personal savings alongside shared household funds, especially when balances are approaching standard insurance limits.
Complete Beginner Guide: FDIC Insurance Rules for Couples
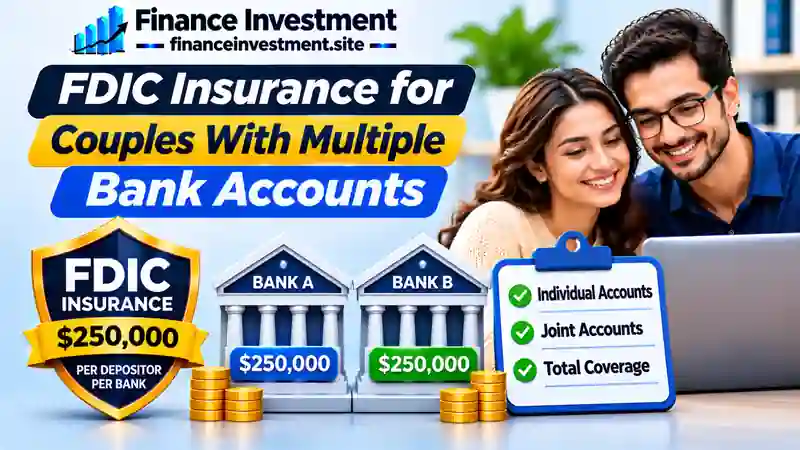
When couples open several bank accounts, the most important detail is whose name appears on each account. FDIC insurance follows legal ownership—not simply whether the money belongs to the same household.
1. Individual Accounts Belong to One Spouse
A checking account owned only by one spouse falls under the single ownership category. That spouse’s other single accounts at the same insured bank are combined for coverage. Learn more in our single vs. joint FDIC insurance guide.
2. Joint Accounts Have Separate Requirements
When both spouses are qualifying co-owners, their joint deposits are generally insured separately from their individual accounts. Each co-owner must satisfy FDIC joint-account requirements, including equal withdrawal rights.
3. Different Accounts May Still Share One Limit
Opening multiple savings accounts or CDs at the same bank does not create new insurance limits within the same ownership category. What matters is the combined balance, including applicable interest.
4. Trust Accounts Follow Different Rules
Eligible trust accounts may receive additional coverage based on account owners and eligible beneficiaries. However, naming a spouse as a beneficiary does not automatically guarantee extra protection.
Quick Take: Before calculating coverage, list every account by its owner, ownership category and insured bank. This simple inventory makes potential gaps easier to identify.
How FDIC Coverage Works Across Multiple Bank Accounts
Imagine a couple keeping their personal savings, household checking and certificates of deposit (CDs) at one FDIC-insured bank. Their protection depends on how those deposits are owned, not how many accounts they opened.
Step 1: Add Each Spouse’s Single Accounts
Spouse A has $180,000 in individual savings and $90,000 in an individual CD. The combined $270,000 exceeds the $250,000 single-ownership limit by $20,000. Spouse B has $200,000 across individual accounts, all within the limit.
Step 2: Calculate Joint Coverage Separately
Together, they hold $300,000 in joint savings and $150,000 in joint checking. Assuming both accounts qualify for joint coverage and each spouse owns an equal share, the entire $450,000 is insured. Each spouse’s $225,000 share remains below the $250,000 joint-category limit.
Step 3: Review the Combined Result
| Ownership | Deposits | Insured |
|---|---|---|
| Spouse A: single | $270,000 | $250,000 |
| Spouse B: single | $200,000 | $200,000 |
| Both: joint | $450,000 | $450,000 |
| Total | $920,000 | $900,000 |
In this example, $20,000 is uninsured. Moving that excess to a separately insured bank could provide coverage under that bank’s applicable limits. See our FDIC insurance at different banks guide.
Step 4: Include Interest and Check Ownership Records
Accrued interest counts toward insurance limits. Also verify joint-owner withdrawal rights and beneficiary designations, since qualifying trust accounts follow different rules.
Expert Tip: Use the official FDIC EDIE calculator to estimate coverage using your actual account details.
Benefits and Drawbacks of Multiple Bank Accounts for Couples
Separate and shared accounts can help couples organize their finances, but more accounts do not always mean more FDIC protection. The benefits depend on ownership, bank identity and how carefully balances are monitored.
Benefits: What Works Well
- Clearer budgeting: Separate personal spending from shared household expenses.
- Flexible ownership: Eligible single and joint deposits receive coverage under separate categories.
- Bank diversification: Deposits at separately insured banks have independent FDIC limits.
- Better organization: Dedicated accounts can simplify savings goals and bill payments.
Drawbacks: What to Watch
- Coverage confusion: Same-category deposits at one insured bank are combined.
- More account maintenance: Couples must track balances, statements and access details.
- Possible fees: Some accounts charge monthly maintenance or minimum-balance fees.
- Interest exposure: Accrued interest can push deposits beyond an insurance limit.
Bottom Line: Multiple accounts are useful for organization, but couples should calculate FDIC coverage by depositor, insured bank and ownership category—not account count.
FDIC Coverage Comparison: Single, Joint, Trust and Multiple Banks
Couples can qualify for different insurance limits depending on account ownership. The table compares the main arrangements and explains when deposits share coverage.
| Ownership Type | Coverage Limit | Important Rule |
|---|---|---|
| Single Accounts | $250,000 per owner | Each spouse’s individually owned deposits at the same insured bank are combined. |
| Joint Accounts | $250,000 per qualifying co-owner | Two eligible co-owners generally receive up to $500,000 combined at one insured bank. |
| Eligible Trust Accounts | $250,000 per owner per unique eligible beneficiary, up to $1.25 million per owner | Qualifying POD, revocable and most irrevocable trust deposits share the trust category. |
| Different Insured Banks | Separate applicable limits at each bank | Each legally distinct FDIC-insured bank is evaluated independently. |
Coverage is calculated per depositor, per insured bank and per ownership category. Trust limits require eligible beneficiaries and qualifying ownership records. Five or more unique eligible beneficiaries provide a maximum of $1.25 million per trust owner at one insured bank.
Quick Take: Account ownership matters more than account count. Before relying on beneficiary-based coverage, read our revocable trust FDIC insurance guide.
Costs, Risks and Expert Tips for Couples
FDIC insurance is automatic and free for eligible deposits at insured banks. However, managing several accounts can create fees, coverage gaps and extra paperwork.
Banking Costs to Consider
- Account fees: Compare monthly charges and minimum-balance requirements.
- Transfer expenses: Check wire fees and CD early-withdrawal penalties.
- Interest trade-offs: Compare annual percentage yields (APYs) before dividing savings between banks.
Coverage Gaps and Hidden Risks
Checking, savings and CDs owned in the same category at one insured bank are aggregated. Accrued interest also counts toward the limit. Different branches of one bank do not provide separate insurance.
FDIC insurance covers eligible deposits if an insured bank fails. It does not cover fraud losses, which are handled under separate consumer protection rules.
Expert Tip: Build a Coverage Checklist
Record each bank’s legal identity, account owners, beneficiaries and balances. Leave room for interest, then review coverage after major deposits or ownership changes. Use our multiple-account FDIC calculation guide and the official FDIC EDIE estimator to check your arrangement.
Common FDIC Insurance Mistakes Couples Should Avoid
A couple may have several accounts and still leave part of their savings uninsured. These four mistakes are especially easy to overlook:
- Counting accounts separately: One spouse’s single checking, savings and CDs at the same insured bank share a coverage limit.
- Confusing branches with banks: Different branches of the same insured bank do not create separate limits.
- Assuming marriage means joint ownership: Legal ownership and FDIC eligibility requirements determine the category.
- Ignoring accrued interest: Interest can push balances above the applicable limit.
Hypothetical Example: A Couple With $800,000
Maya and James hold the following deposits at one FDIC-insured bank, with no other accounts there:
| Ownership | Deposits | Insured |
|---|---|---|
| Maya: single | $300,000 | $250,000 |
| James: single | $100,000 | $100,000 |
| Both: joint | $400,000 | $400,000 |
| Total | $800,000 | $750,000 |
What Went Wrong? Maya’s single deposits exceed her $250,000 limit by $50,000. Unused coverage in another category cannot automatically protect that excess. Moving it to a separately FDIC-insured bank could address the gap if sufficient coverage is available there.
Illustrative balances include accrued interest. The joint account assumes two eligible equal co-owners, no beneficiaries and no other deposits affecting coverage at this bank.
Who Should Choose Which Bank Account Setup?
Couples have different banking needs. The most practical arrangement should support household expenses, personal savings and clear account ownership while keeping FDIC limits in view.
Newly Married Couples
A joint checking account can simplify shared bills. Individual accounts may help each spouse retain flexibility over personal spending.
Dual-Income Couples
Separate income accounts and shared household savings can simplify budgeting, provided both spouses understand the ownership records.
Families Planning for Beneficiaries
Payable-on-death (POD) designations or qualifying trust accounts may support estate planning. Review beneficiary records and applicable FDIC trust rules.
Couples With Large Cash Balances
Separately FDIC-insured banks may offer additional coverage. Confirm each institution’s identity rather than assuming different branches provide separate limits.
Quick Recommendation: Choose ownership arrangements that reflect genuine financial needs, then verify insurance using actual account records.
Frequently Asked Questions About FDIC Insurance for Couples
1. How much FDIC insurance can a married couple have?
At one insured bank, a couple may qualify for up to $1 million across two separately owned single-account categories and qualifying joint accounts, assuming all applicable requirements are met.
2. Are separate bank accounts insured individually?
Each spouse’s single deposits are evaluated separately. However, all single accounts owned by the same spouse at one insured bank share a $250,000 coverage limit.
3. Is a joint bank account insured up to $500,000?
Generally, two qualifying joint owners can receive up to $500,000 combined at one insured bank. Each owner must meet FDIC joint-account requirements, including equal withdrawal rights.
4. Does opening multiple accounts increase FDIC coverage?
Not automatically. Deposits held in the same ownership category at one insured bank are combined, regardless of how many checking, savings or CD accounts exist.
5. Do different banks provide separate FDIC insurance?
Yes. Legally distinct FDIC-insured banks have separate applicable insurance limits. Different branches of the same insured bank do not create additional coverage.
6. Can trust accounts increase FDIC coverage for couples?
Qualifying trust deposits may receive $250,000 per owner for each unique eligible beneficiary, up to five beneficiaries per owner at one insured bank. Applicable trust deposits are combined.
7. Does FDIC insurance cover interest earned?
Yes. Accrued interest is included with eligible deposits when calculating insurance coverage and counts toward the applicable limit.
8. What should couples do if their deposits exceed FDIC limits?
Review account ownership, calculate uninsured balances and consider moving excess deposits to separately FDIC-insured banks where sufficient coverage is available.
Helpful Reminder: Use the official FDIC Electronic Deposit Insurance Estimator (EDIE) to review your actual account arrangement.
Final Verdict: Smart FDIC Coverage Planning for Couples
Multiple bank accounts can make managing household finances easier, but the number of accounts does not determine FDIC protection. What matters is who owns the deposits, which insured bank holds them and which ownership category applies.
Couples may qualify for separate coverage through eligible individual and joint accounts. Before balances approach insurance limits, check ownership records, include accrued interest and confirm whether accounts belong to the same insured institution.
Our Recommendation: Review deposit coverage annually and after major financial changes. For a broader explanation of protection at banks and credit unions, explore our FDIC and NCUA insurance guide.
Have a Money Question? Keep Exploring.
Protecting household savings starts with understanding how your accounts are owned and insured. Review your balances, confirm your bank’s FDIC status and check coverage before making major transfers.
Explore our FDIC and NCUA insurance guide or learn about FDIC coverage at different banks.
📩 Get in Touch With FinanceInvestment
Disclaimer: This content is for educational purposes, not personalized financial or legal advice. Actual FDIC coverage depends on account ownership, insured-bank identity, deposit balances and applicable rules. Verify your situation with the FDIC or your bank.
Leave a Reply