Tag: FDIC Insurance

  • NCUA vs FDIC Insurance: What’s the Difference in 2026?

    NCUA vs FDIC Insurance: What’s the Difference in 2026?

    NCUA vs FDIC Insurance: What’s the Difference?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: October 4, 2026
    Updated: October 4, 2026
    Reading Time: 10–12 min

    NCUA vs FDIC Insurance is easier to understand once you know which agency protects your money. The NCUA provides federal share insurance for eligible accounts at federally insured credit unions, while the FDIC provides deposit insurance for eligible accounts at FDIC-insured banks. Both programs generally provide up to $250,000 of standard coverage per depositor or member-owner, per insured institution, per ownership category.
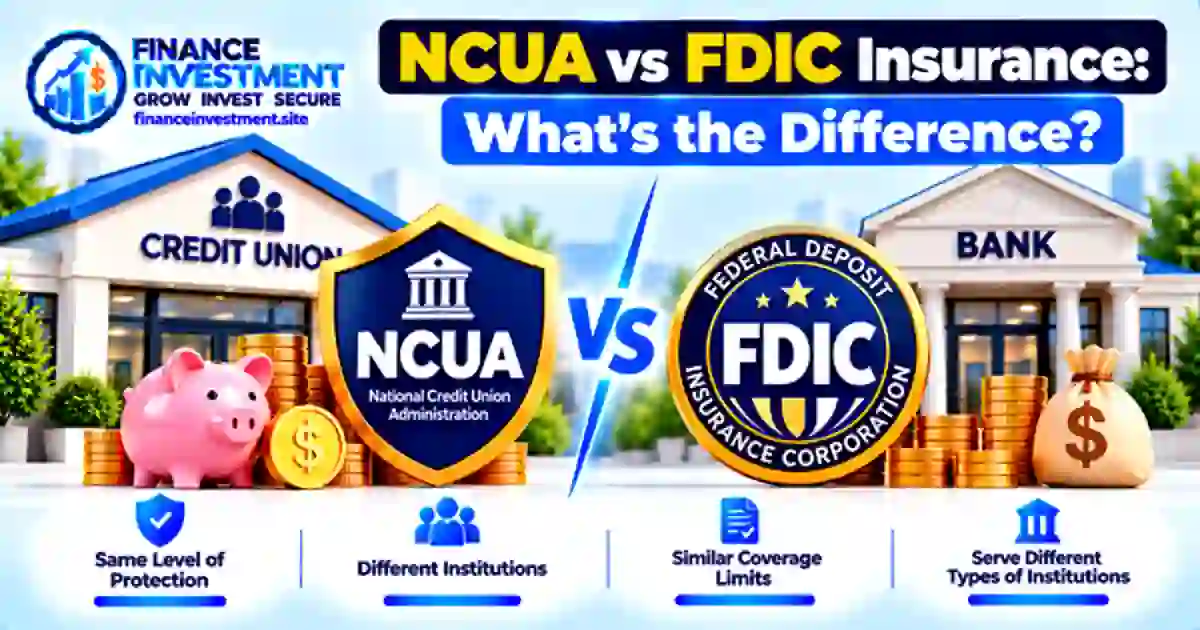
    NCUA vs FDIC InsuranceThe basic purpose is similar: protect qualifying funds if an insured bank or credit union fails. But the terminology, covered institutions, ownership categories, and account structures can differ. Those details matter if you have multiple accounts, share an account with another person, or keep a large cash balance at one institution.

    This guide explains the differences in plain English and uses practical examples to show how NCUA coverage and FDIC coverage work in everyday banking situations.

    What You’ll Learn

    • How NCUA insurance and FDIC insurance protect eligible funds.
    • How the standard $250,000 insurance limit works.
    • How ownership categories can affect your total coverage.
    • Which institutions and accounts may qualify for protection.
    • How NCUA and FDIC coverage compare for consumers.
    • Common mistakes that can leave balances uninsured.

    NCUA vs FDIC Insurance: Quick Answer

    The main difference between NCUA vs FDIC Insurance is the type of institution each program protects. NCUA insurance covers eligible share accounts at federally insured credit unions, while FDIC insurance covers eligible deposit accounts at FDIC-insured banks. The standard coverage limit is generally $250,000 per member-owner or depositor, per insured institution, per ownership category.

    6 Key Takeaways

    1. NCUA protects eligible credit union shares. Federal share insurance is provided through the National Credit Union Share Insurance Fund (NCUSIF), administered by the NCUA.
    2. FDIC protects eligible bank deposits. FDIC insurance applies to qualifying deposits held at FDIC-insured banks.
    3. $250,000 is the standard coverage limit. For FDIC insurance, the limit generally applies per depositor, per insured bank, per ownership category. For NCUA insurance, it generally applies per member-owner, per insured credit union, per ownership category.
    4. Ownership matters. Single, joint, and certain other ownership categories have different coverage rules, so account structure can affect the amount insured.
    5. Investment products are not covered. Stocks, bonds, mutual funds, and similar investment products are not protected by FDIC or NCUA deposit/share insurance.
    6. Check the institution’s insurance status. Before keeping a large cash balance, verify that the bank is FDIC-insured or the credit union has federal share insurance through the NCUSIF.

    NCUA vs FDIC at a Glance: Key Numbers

    NCUA and FDIC insurance serve a similar purpose: protecting eligible customer funds when an insured financial institution fails. The key difference is the institution covered. NCUA share insurance applies to eligible shares at federally insured credit unions, while FDIC insurance applies to eligible deposits at FDIC-insured banks.

    FeatureNCUA InsuranceFDIC Insurance
    ProtectsEligible shares at federally insured credit unionsEligible deposits at FDIC-insured banks
    Standard coverage limit$250,000 per member-owner, per insured credit union, per ownership category$250,000 per depositor, per insured bank, per ownership category
    Insurance fundNational Credit Union Share Insurance Fund (NCUSIF)Deposit Insurance Fund (DIF)
    Federal agencyNational Credit Union Administration (NCUA)Federal Deposit Insurance Corporation (FDIC)

    QUICK TAKE: The standard coverage limit is $250,000 under both systems, but the terminology and institution differ. NCUA insurance protects eligible credit union shares through the NCUSIF, while FDIC insurance protects eligible bank deposits through the FDIC’s Deposit Insurance Fund.

    NCUA vs FDIC: A Complete Beginner GuideNCUA vs FDIC Insurance

    If you keep money at a bank or credit union, federal insurance can protect eligible funds if the insured institution fails. The program depends on where the account is held. Banks use FDIC deposit insurance, while federally insured credit unions use NCUA share insurance through the National Credit Union Share Insurance Fund (NCUSIF).

    What NCUA Insurance Covers

    NCUA insurance protects eligible share accounts at federally insured credit unions. Common examples include share savings, share draft accounts, and certain share certificates. The standard limit is generally $250,000 per member-owner, per federally insured credit union, per ownership category, subject to applicable rules.

    What FDIC Insurance Covers

    FDIC insurance protects eligible deposit accounts at FDIC-insured banks. Covered deposit products can include checking accounts, savings accounts, money market deposit accounts, and CDs. The standard limit is generally $250,000 per depositor, per insured bank, per ownership category.

    The Simple Rule to Remember

    Credit union → NCUA/NCUSIF. Bank → FDIC. The $250,000 standard limit is similar, but your actual coverage depends on the insured institution, ownership category, account structure, and eligible balances.

    How NCUA and FDIC Insurance Works

    NCUA and FDIC insurance generally works in the background. You do not normally purchase a separate policy for an eligible account. Instead, coverage is tied to the financial institution and the type of account you hold. FDIC insurance applies at FDIC-insured banks, while NCUA federal share insurance applies at federally insured credit unions.

    1. The Institution Must Have Federal Insurance

    For bank deposits to receive FDIC protection, the bank must be FDIC-insured. For credit union shares to receive federal NCUA protection, the credit union must have federal share insurance through the NCUSIF. This includes all federal credit unions and the overwhelming majority of state-chartered credit unions.

    2. Coverage Depends on Ownership and Balances

    The standard limit is generally $250,000 per depositor at an FDIC-insured bank or per member-owner at a federally insured credit union, based on the applicable ownership category. At an FDIC-insured bank, deposits in the same ownership category are generally added together when calculating coverage. NCUA coverage also depends on how accounts are structured under its share-insurance rules.

    3. What Happens If the Institution Fails?

    If an insured bank or credit union fails, the applicable federal insurance system protects eligible funds according to its coverage rules. FDIC insurance can provide prompt access to insured deposits after a bank failure, while NCUA administers the NCUSIF to protect insured shares at federally insured credit unions. Amounts above applicable limits and products outside the insurance rules are not automatically protected.

    Benefits & Drawbacks of NCUA and FDIC Insurance

    NCUA and FDIC insurance provide an important layer of protection for eligible funds if a federally insured financial institution fails. The protection is valuable, but it follows specific rules and does not cover every account or financial product.

    Benefits

    • Federal insurance protection: Eligible deposits or shares are protected according to the applicable federal insurance rules if an insured institution fails.
    • Substantial standard coverage: The standard limit is generally $250,000 per depositor or member-owner, per insured institution, per ownership category.
    • No separate policy purchase: Consumers generally do not need to purchase a separate insurance policy for eligible accounts at an insured institution.
    • Useful for cash holdings: The coverage can protect eligible checking, savings, and other qualifying deposits or shares within the applicable limits.

    Drawbacks & Limits

    • Coverage is limited: Funds above the applicable insurance limit may not be fully protected under the standard coverage rules.
    • Some products are excluded: Stocks, bonds, mutual funds, and other investment products are not protected by FDIC or NCUA deposit/share insurance.
    • Account structure matters: Ownership category, account title, institution, and eligible balance can affect how much of your money is insured.

    NCUA vs FDIC Insurance: Side-by-Side Comparison

    NCUA and FDIC insurance serve a similar purpose, but they apply to different types of insured financial institutions and use different terminology. This comparison highlights the core rules consumers should understand when evaluating a bank account or credit union account.

    ComparisonNCUA InsuranceFDIC Insurance
    InstitutionFederally insured credit unionFDIC-insured bank
    What is insured?Eligible share accountsEligible deposit accounts
    Standard coverage limit$250,000 per member-owner, per insured credit union, per ownership category$250,000 per depositor, per insured bank, per ownership category
    Insurance fundNational Credit Union Share Insurance Fund (NCUSIF)FDIC Deposit Insurance Fund
    Federal agencyNational Credit Union Administration (NCUA)Federal Deposit Insurance Corporation (FDIC)
    Common covered accountsShare savings, share draft accounts, and qualifying share certificatesChecking, savings, money market deposit accounts, and CDs
    Investment securitiesNot covered by NCUA share insuranceNot covered by FDIC deposit insurance

    KEY POINT: NCUA and FDIC insurance are separate federal programs with a similar core purpose. The institution, eligible account type, ownership category, and balance all matter when determining how much money is protected.

    NCUA vs FDIC Coverage Limits, Risks & Practical Tips

    The standard $250,000 limit does not mean every account automatically receives a separate $250,000 of protection. Coverage depends on the insured institution, ownership category, account structure, and the amount of eligible funds held under those rules.

    How the $250,000 Limit Works

    For FDIC insurance, eligible deposits in the same ownership category at the same insured bank are generally combined when determining coverage. For NCUA insurance, eligible shares are evaluated under the applicable ownership-category rules at the same federally insured credit union. Opening multiple accounts at one institution does not automatically create a separate $250,000 limit for every account.

    Three Practical Ways to Avoid Coverage Mistakes

    • Verify insurance status: Confirm that your bank is FDIC-insured or that your credit union has federal share insurance through the NCUSIF.
    • Review ownership categories: Check whether your accounts are individually owned, jointly owned, or held under another ownership category with its own coverage rules.
    • Review large cash balances: If eligible funds approach or exceed $250,000, calculate your coverage instead of assuming the entire balance is insured.

    PRACTICAL TIP: Start with the institution, identify the ownership category, confirm which balances are eligible for insurance, and then apply the relevant coverage limit. That is more reliable than simply counting the number of accounts you have.

    Common NCUA vs FDIC Insurance Mistakes

    Insurance mistakes often happen when people focus only on an account balance and overlook the institution, ownership category, or financial product involved. A few simple examples show why those details matter.

    Mistake 1: Assuming Every Financial Product Is Insured

    Stocks, bonds, mutual funds, and other investment securities are not protected by FDIC or NCUA deposit/share insurance. A brokerage account may hold different types of assets, so the underlying product—not simply the account’s connection to a financial institution—determines whether federal deposit or share insurance applies.

    Mistake 2: Assuming Every Account Gets a Separate $250,000 Limit

    Imagine one person has $150,000 in savings and $150,000 in checking at the same FDIC-insured bank, with both accounts in the same ownership category. The eligible deposits are generally combined for coverage purposes. That creates $300,000 in deposits against a $250,000 standard limit for that category, leaving $50,000 above the standard insured amount.

    Mistake 3: Forgetting to Verify Insurance Status

    Before moving a large amount of cash, verify that the bank is FDIC-insured or that the credit union has federal share insurance through the NCUSIF. Do not assume insurance simply because an institution uses the words “bank” or “credit union.”

    REAL-LIFE CHECK: If you have a large cash balance, identify the institution, ownership category, eligible account type, and total balance before assuming how much is insured.

    Who Should Pay Attention to NCUA vs FDIC?

    Understanding NCUA vs FDIC Insurance matters to anyone keeping eligible funds at a bank or credit union. It becomes especially relevant when balances are large, multiple accounts are involved, or ownership is shared.

    People With Large Cash Balances

    If eligible deposits or shares are approaching $250,000, review the applicable insurance rules carefully. The institution, ownership category, and eligible balance can affect how much protection applies.

    Families With Multiple or Joint Accounts

    Families may hold individual and joint accounts at the same institution. These balances are evaluated under applicable ownership-category rules, so having several account numbers does not automatically create a separate $250,000 insurance limit for each account.

    Bank and Credit Union Customers

    Anyone opening or maintaining an account should verify the institution’s federal insurance status. Bank customers should confirm FDIC insurance, while credit union members should confirm federal share insurance through the NCUSIF.

    QUICK CHECK: Before keeping a large eligible balance at one institution, verify the insurance program, ownership category, account type, and applicable coverage limit.

    NCUA vs FDIC Insurance: Frequently Asked Questions

    1. Is NCUA insurance the same as FDIC insurance?

    No. They are separate federal insurance programs with a similar purpose. NCUA insurance protects eligible shares at federally insured credit unions, while FDIC insurance protects eligible deposits at FDIC-insured banks.

    2. How much does NCUA insurance cover?

    The standard NCUA share-insurance limit is generally $250,000 per member-owner, per federally insured credit union, per ownership category, subject to applicable rules.

    3. How much does FDIC insurance cover?

    The standard FDIC insurance limit is generally $250,000 per depositor, per insured bank, per ownership category.

    4. Does NCUA insurance cover stocks and mutual funds?

    No. NCUA share insurance protects eligible shares at federally insured credit unions. It does not protect stocks, bonds, mutual funds, or other investment securities.

    5. Does FDIC insurance cover stocks and mutual funds?

    No. FDIC insurance protects eligible bank deposits. It does not protect stocks, bonds, mutual funds, or other investment securities.

    6. Does having multiple accounts increase my insurance coverage?

    Not automatically. Coverage is based on the insured institution, ownership category, and eligible balances. At an FDIC-insured bank, deposits in the same ownership category are generally combined when determining coverage. NCUA coverage also follows applicable ownership-category rules.

    7. Are credit unions insured by the FDIC?

    No. Federally insured credit unions receive federal share insurance through the National Credit Union Share Insurance Fund (NCUSIF), which is administered by the NCUA. FDIC insurance applies to FDIC-insured banks.

    8. How can I check whether my money is insured?

    Confirm that your bank is FDIC-insured or that your credit union has federal share insurance through the NCUSIF. Then review your account type, ownership category, and balance against the applicable coverage rules.

    NCUA vs FDIC Insurance: Final Takeaway

    The main difference in NCUA vs FDIC Insurance is the institution covered. NCUA federal share insurance protects eligible shares at federally insured credit unions, while FDIC insurance protects eligible deposits at FDIC-insured banks.

    Both programs generally provide a standard limit of $250,000 per member-owner or depositor, per insured institution, per ownership category. The amount actually protected can depend on the account type, ownership category, institution, and eligible balance.

    KEY TAKEAWAY: NCUA and FDIC coverage use different insurance systems, but both provide federal protection for qualifying funds when the applicable requirements are met. The $250,000 standard limit should always be considered together with the relevant ownership and account rules.

    If you hold a large cash balance, verify the institution’s federal insurance status and review how your accounts are categorized. This gives you a clearer picture of which funds fall within the applicable insurance limits.
    Have a Money Question? Keep Exploring.

    Have a question about bank accounts, credit unions, or deposit insurance? Send your question to FinanceInvestment and continue exploring practical personal-finance guides.

    Email FinanceInvestment

  • Credit Union vs Bank: What’s the Difference? (2026 Guide)

    Credit Union vs Bank: What’s the Difference? (2026 Guide)

    Credit Union vs Bank: What’s the Difference?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 29, 2026Updated: Sep 29, 2026Reading Time: 10–12 min


    Credit Union vs Bank: What’s the Difference?

    Credit Union vs Bank What's the Difference 2026If you’re comparing a credit union vs bank, the difference goes deeper than the name on your debit card. Both can provide checking accounts, savings accounts, loans and other everyday financial services. The bigger distinction is how each institution is structured and who owns it. Credit unions are member-owned cooperatives, while banks generally operate as for-profit businesses.
    That ownership difference can shape the way you experience an account, but it does not tell the whole story. Membership eligibility, interest rates, fees, branch networks, ATM access, digital tools and loan terms can vary widely from one institution to another. A national bank may offer broad access across the country, while a credit union may have a more limited footprint but serve a specific community, employer group or association.

    The right comparison starts with your own banking habits. Do you need frequent branch visits? Is a large ATM network important? Are you mainly looking for a checking account, a savings account or a loan? Once you know what matters, comparing the actual account terms becomes much easier. For the broader picture, see our complete Credit Unions Explained guide.

    THE BIG IDEA

    A bank and a credit union can look similar from a customer’s perspective. The meaningful differences usually appear in ownership, membership, rates, fees, access and account protections.

    What You’ll Learn

    • How credit unions and banks are structured and owned.
    • Why credit union membership can have eligibility requirements.
    • How rates, fees, branches and digital banking may differ.
    • How NCUA share insurance compares with FDIC deposit insurance.
    • Which account features deserve attention before you open an account.
    • Common mistakes to avoid when comparing the two.

    Quick Answer: Credit Union vs Bank

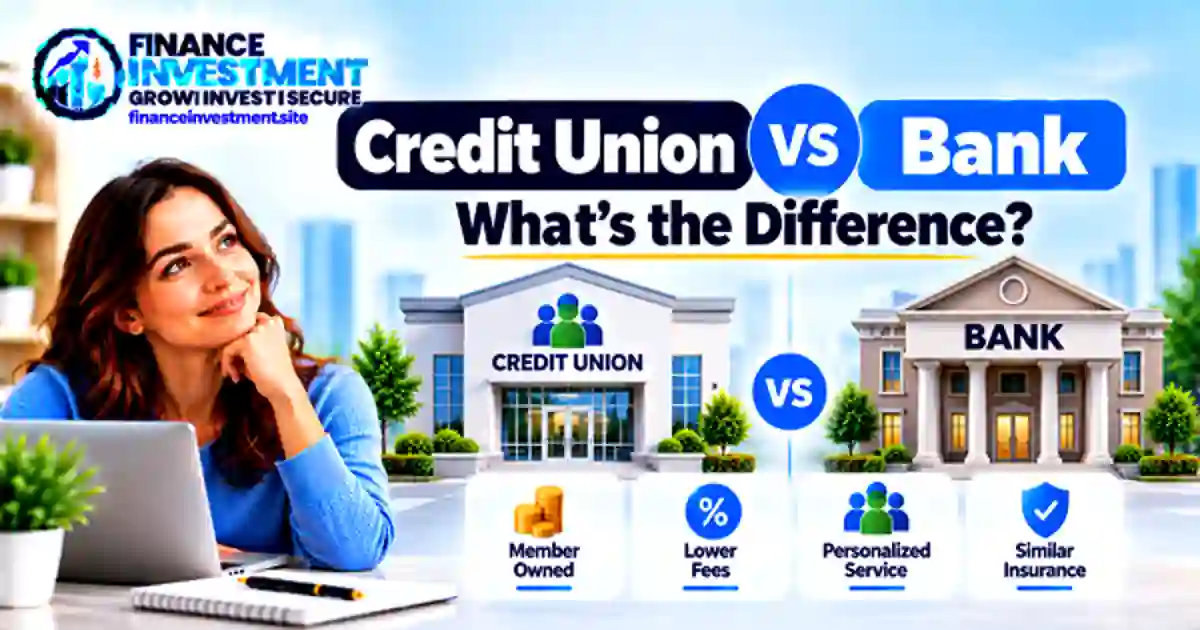
    The simplest credit union vs bank difference is ownership. A credit union is a member-owned cooperative, while a bank generally operates as a for-profit financial institution. Yet both can handle everyday needs such as checking, savings, payments and borrowing. What matters is how the specific institution’s terms fit your needs.

    KEY TAKEAWAYS

    • Credit unions are member-owned financial cooperatives.
    • Banks and credit unions can offer many similar financial products.
    • Credit union membership usually depends on eligibility rules.
    • Interest rates, fees and account requirements vary by institution.
    • Branch, ATM and online banking access can differ significantly.
    • Qualifying accounts at federally insured credit unions can receive NCUA share insurance, subject to coverage rules and limits.

    BOTTOM LINE

    There isn’t one universal answer for every household. Compare the actual rates, fees, account features, access and applicable insurance before deciding where to keep your money.

    Credit Union vs Bank at a Glance

    A credit union and a bank can look similar when you use them day to day. Both may offer checking, savings, debit cards, online banking and loans. The bigger differences involve ownership, eligibility, governance and insurance.

    FeatureCredit UnionBank
    OwnershipMember-owned cooperativeOwnership structure varies by bank
    EligibilityUsually requires meeting the credit union’s field-of-membership rulesUsually based on the bank’s account-opening requirements
    GovernanceMembers elect the board under applicable rulesGoverned according to the bank’s corporate or ownership structure
    Account TermsRates, fees and requirements vary by credit unionRates, fees and requirements vary by bank
    Federal InsuranceNCUA share insurance may apply at federally insured credit unionsFDIC deposit insurance may apply at FDIC-insured banks

    QUICK TAKE

    The institution’s label is only the starting point. Before opening an account, compare the APY, interest rate, fees, minimums, ATM access, digital features and applicable federal insurance for the specific product.

    Credit Union vs Bank: Complete Beginner Guide

    Credit Union vs BankFor a beginner, the easiest way to understand a credit union vs bank comparison is to follow the customer journey. You start by finding an institution that fits your needs, open an account, use its services and then compare how well the account works for you over time.
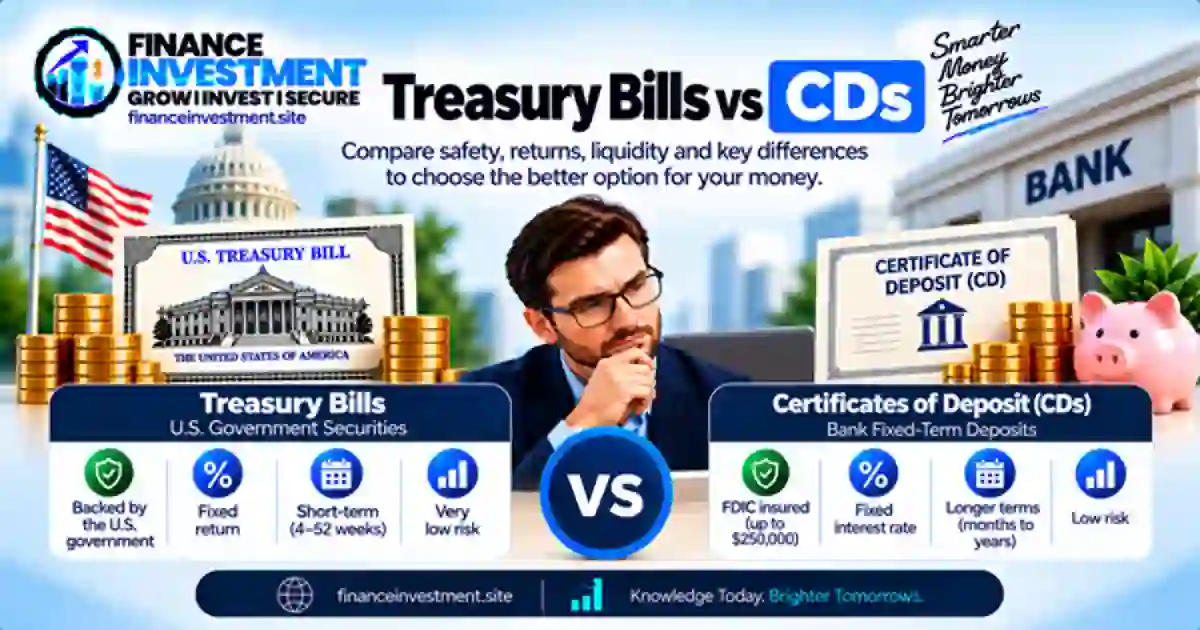
    1. Check Whether You Can Join

    With a credit union, eligibility comes first. A credit union generally has a defined field of membership. Depending on its charter, eligibility may be connected to where you live, where you work, a family relationship or membership in a qualifying organization. Once you qualify, the institution will explain its membership and account-opening requirements.

    2. Compare the Account Before Opening It

    Whether you choose a bank or credit union, look at the actual account rather than relying on the institution’s name. Check the monthly fee, minimum balance, opening deposit, transaction rules, ATM access and digital banking features. For checking accounts, our guide to how checking accounts work covers the basics beginners should understand.

    3. Use the Account for Everyday Money

    After opening an account, your daily routine may look similar at either type of institution. You might receive a debit card, set up direct deposit, pay bills, transfer money, deposit checks and manage your balance through online or mobile banking. The available features depend on the specific institution and account.

    4. Apply for Loans When Needed

    Banks and credit unions can both provide loans to qualified borrowers. The application process can involve reviewing income, credit history, existing obligations and other information. Rates, fees, approval standards and repayment terms vary by lender, so compare the complete cost rather than focusing only on the advertised rate.

    5. Recheck the Fit Over Time

    Your banking needs can change. A convenient account today may become less useful if fees increase, your location changes or you need different services. Review your account periodically and compare the rates, fees, access, features and applicable federal insurance with other available options.

    BEGINNER TIP

    Don’t start with “Which institution is better?” Start with “Which account meets my needs?” That shift makes the comparison more practical and easier to evaluate.

    How Credit Unions and Banks Work

    A useful way to understand the difference is to look at how each institution is organized and manages money. Both banks and credit unions can hold customer funds, provide payment services and make loans. However, their ownership structures and governing rules are different.

    How a Credit Union Works

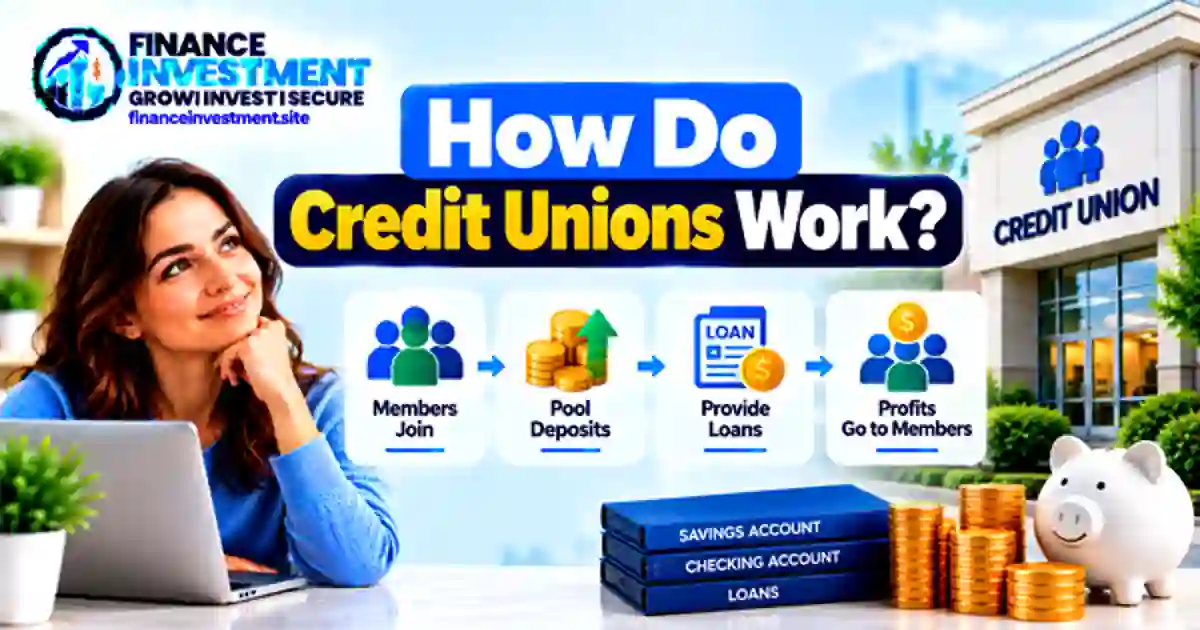
    A credit union operates as a member-owned cooperative. Eligible individuals join under the institution’s field-of-membership rules and may need to maintain a required share account. The credit union manages member shares along with its other funding, investments, liquidity and capital. It can use its financial resources to make loans and provide services, while interest income, fees and other revenue help cover operating costs and support financial strength. Members also have a governance role under applicable rules.

    How a Bank Works

    A bank also manages deposits, lending, payments and other financial services. Deposits are part of the bank’s broader funding structure, while loans and investments are managed as part of its overall balance sheet. Interest income, fees and other revenue help the bank pay operating expenses and run its business. Banks can range from small community institutions to large national organizations, so the products and services available can vary widely.

    Where the Difference Becomes Visible

    For customers, the structural difference can show up in practical areas such as eligibility, account terminology, governance, rates, fees and access. Credit unions may also use shared-branch or cooperative ATM networks, while individual banks may operate their own branch and ATM networks or participate in other networks. The actual experience depends on the institution.

    THE PRACTICAL DIFFERENCE

    Both models manage money through funding, lending, payments and financial services. The key distinction is the structure behind those activities: a credit union is organized as a member-owned cooperative, while a bank follows its own ownership and corporate structure.

    Credit Union vs Bank: Benefits & Drawbacks

    Both credit unions and banks can be useful for everyday banking. The important point is that the experience can vary significantly between individual institutions. A feature that matters to one household may be less important to another.

    Potential Credit Union Benefits

    • Member ownership: Eligible members have an ownership interest in the cooperative.
    • Member participation: Eligible members may have voting rights under the institution’s governing rules.
    • Everyday services: Many credit unions offer checking, savings, cards and lending products.
    • Cooperative structure: The institution is organized around its membership rather than outside stockholders.

    Potential Credit Union Drawbacks

    • Eligibility limits: You may need to meet specific membership requirements.
    • Access differences: Branch and ATM availability depends on the institution and its networks.
    • Technology differences: Mobile and online banking features can vary.
    • Product selection: Some institutions may offer a narrower range of products than larger financial institutions.

    AND WHAT ABOUT BANKS?

    Banks can offer broad product selections, branch networks and digital services, but those features differ by institution too. Fees, minimum requirements, rates and account features also vary. That is why the most useful comparison is between the actual accounts and services you would use.

    Credit Union vs Bank: Side-by-Side Comparison

    The basic difference is easy to remember: credit unions are member-owned cooperatives, while banks follow their own ownership and corporate structures. The more useful comparison, however, is what those structures mean for the accounts and services you actually use.

    FeatureCredit UnionBank
    OwnershipMember-owned cooperativeOwnership structure varies by institution
    EligibilityGenerally requires meeting the credit union’s field-of-membership rulesGenerally requires meeting the bank’s account-opening requirements
    GovernanceEligible members may vote under applicable governing rulesGoverned according to the institution’s ownership and corporate structure
    AccountsChecking, savings and other products may use share terminologyChecking, savings and other deposit products are commonly available
    Rates & FeesVary by institution, account and productVary by institution, account and product
    Branch & ATM AccessDepends on the credit union and available networksDepends on the bank and its branch or ATM networks
    Digital BankingFeatures and tools vary by institutionFeatures and tools vary by institution
    Federal InsuranceQualifying shares at federally insured credit unions may receive NCUA share insurance, subject to coverage rulesQualifying deposits at FDIC-insured banks may receive FDIC deposit insurance, subject to coverage rules

    What This Means for Your Decision

    The ownership difference matters, but it should not be the only thing you compare. If you rarely visit branches, digital features may matter more. If you use ATMs frequently, network access can become important. For borrowing, compare the full APR, fees and repayment terms. For savings, look at the APY and account requirements.

    COMPARE THE ACTUAL PRODUCT

    Before opening an account, compare the APY, APR, fees, minimum balance, ATM access, branch availability, digital features and applicable federal insurance. Those details tell you more about the account than the words “bank” or “credit union” alone.

    Credit Union vs Bank: Costs, Risks & Expert Tips

    The words “credit union” or “bank” don’t tell you what an account will cost. Both types of institutions can have fees, minimum requirements and different rates. Before opening an account, review the current fee schedule, account disclosures and terms for the specific product.

    Costs to Check

    • Monthly maintenance or service fees.
    • Minimum balance and opening deposit requirements.
    • Out-of-network ATM fees and other transaction charges.
    • Overdraft, returned-payment or other account fees.
    • Loan origination, late-payment and other borrowing costs.

    Risks and Practical Limitations

    Access can vary significantly. A credit union may have fewer physical branches than a large bank, although shared-branch arrangements or ATM networks may provide additional access. Banks also differ in branch coverage, ATM availability and digital features. You should also verify the institution’s federal insurance status and understand which accounts qualify for coverage.

    Expert Tips Before You Open an Account

    • Compare the APY or loan APR with the related fees.
    • Check minimum balances and recurring requirements.
    • Review ATM, branch and digital access based on your routine.
    • Read overdraft and transaction rules before relying on the account.
    • Confirm the applicable federal insurance program and coverage terms.

    EXPERT TIP

    Put the numbers side by side before deciding. A useful comparison includes the rate, recurring fees, one-time charges, access and account requirements for the exact products you are considering.

    Common Credit Union vs Bank Mistakes + Illustrative Example

    Choosing between a credit union and a bank can become confusing when the institution’s reputation gets more attention than the account itself. A few practical checks can make the comparison much clearer.

    Mistakes to Avoid

    • Assuming one type always costs less: Rates and fees vary by institution and product.
    • Skipping eligibility checks: A credit union may have membership requirements you must satisfy before opening an account.
    • Looking only at the headline rate: Check fees, minimum balances and other account conditions too.
    • Ignoring everyday access: Consider ATM availability, branches and digital features based on your normal routine.

    An Illustrative Example

    Suppose Daniel needs a new checking account. He qualifies for a nearby credit union, while a national bank is also available to him. Instead of choosing based on the institution’s name, he compares the monthly fee, minimum balance, ATM access, mobile banking features, overdraft terms and direct-deposit options offered by each account.

    That comparison gives Daniel a clearer picture of how each account would fit his routine. The example does not make one institution type the automatic winner. It shows why looking at the actual account terms can be more useful than relying on general assumptions about banks or credit unions.

    THE LESSON

    Start with your real banking habits. List the features you need, compare the specific accounts and then review their costs, access and applicable protections.

    Who Should Choose a Credit Union or Bank?

    There is no single option that fits every household. Your priorities may point toward one institution, while someone with different banking habits may choose another. Start by identifying what you need most from the account.

    A Credit Union May Fit Your Needs If:

    • You meet the institution’s membership eligibility requirements.
    • You value having an ownership role in a cooperative institution.
    • Its rates, fees and account features match your needs.
    • Its branches, ATMs, shared networks or digital services are convenient for you.

    A Bank May Fit Your Needs If:

    • You need access to a particular bank’s branch or ATM network.
    • You prefer the digital tools or account features offered by a specific bank.
    • You need a product or service available through that institution.
    • Its rates, fees and account requirements work for your situation.

    A SIMPLE WAY TO COMPARE

    Write down your top three priorities—such as low fees, convenient ATM access, digital banking or competitive loan terms. Then compare actual accounts against those priorities instead of choosing based only on the institution’s name.

    Frequently Asked Questions About Credit Unions vs Banks

    1. What is the main difference between a credit union and a bank?

    The main structural difference is ownership. A credit union is a member-owned cooperative, while a bank operates according to its own ownership and corporate structure. Both can offer many similar financial services.

    2. Are credit unions and banks insured in the same way?

    No. Qualifying shares at federally insured credit unions may receive NCUA share insurance, while qualifying deposits at FDIC-insured banks may receive FDIC deposit insurance. Coverage depends on the institution, account ownership category, account type and applicable limits.

    3. Do credit unions usually have lower fees than banks?

    Fees vary by institution and account. Some credit unions may offer competitive fees, but you should compare the actual fee schedule rather than assume one type of institution will always cost less.

    4. Can anyone join a credit union?

    Not necessarily. Credit unions generally have a defined field of membership. Eligibility may depend on factors such as location, employment, family relationships or membership in a qualifying organization.

    5. Are credit union accounts FDIC insured?

    No. Federally insured credit unions use NCUA share insurance through the National Credit Union Share Insurance Fund. FDIC insurance applies to qualifying deposits at FDIC-insured banks. These are separate federal insurance programs with their own coverage rules.

    6. Can a credit union offer checking and savings accounts?

    Yes. Many credit unions offer both. They may use terms such as share savings and share draft accounts for products that function similarly to savings and checking accounts.

    7. Which usually has more branches, a credit union or bank?

    There is no universal answer. A particular bank may have a large branch network, while a credit union may provide access through its own locations, shared branches or ATM networks. Compare the access available where you live and travel.

    8. What should I compare before choosing between a credit union and bank?

    Compare eligibility, APY or APR, fees, minimum balances, ATM and branch access, digital banking features, account terms and applicable federal insurance. Then match those details with the way you plan to use the account.


    Final Verdict: Credit Union vs Bank

    The credit union vs bank comparison is ultimately about how each institution fits your financial needs. A credit union is a member-owned cooperative for eligible members, while a bank operates under its own ownership and corporate structure. Both can provide checking, savings, payments, lending and digital banking services.

    The practical differences can appear in membership eligibility, rates, fees, branch and ATM access, digital tools and available products. Insurance also depends on the institution’s federal insurance status, the account involved and the applicable coverage rules.

    Before opening an account, compare the specific products you would actually use. Look at the APY or APR, fees, minimum requirements, access, digital features and applicable federal insurance. Those details give you a clearer basis for comparing institutions than the label alone.

    BOTTOM LINE

    Banks and credit unions can both serve everyday banking needs. Compare the actual institution, account terms and available services against the way you plan to manage your money.

    For a broader explanation of membership, accounts, fees and NCUA insurance, continue with our complete Credit Unions Explained guide.

    Related Resources & Authority Sources

    If you’re comparing banks, credit unions and other account options, these FinanceInvestment guides can help you explore the details that matter beyond the basic ownership difference. Start with the complete Credit Unions Explained guide for a broader look at membership, accounts, fees and NCUA insurance.

    FINANCEINVESTMENT GUIDES

    Official Authority Sources

    RESEARCH TIP

    Banking terms and account features can change. Before opening an account, check the institution’s current disclosures and official regulator information for rates, fees, eligibility and applicable insurance coverage.

    Have a Money Question? Keep Exploring.

    Your banking choice is only one part of a larger money plan. Keep exploring the account features, costs, access and protections that can shape your everyday financial decisions.

    📩 Get in Touch With FinanceInvestment

    Have a personal-finance question or a topic you’d like FinanceInvestment to explain?

    Email FinanceInvestment

  • Treasury Bills vs CDs: Safety, Taxes, Rates & Liquidity

    Treasury Bills vs CDs: Safety, Taxes, Rates & Liquidity

    Treasury Bills vs CDs

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 25, 2026
    Updated: Sep 25, 2026
    Reading Time: 10–12 min


    Treasury Bills vs CDs: What Should You Know?

    Treasury Bills vs CDsTreasury Bills vs CDs is a useful comparison when you have cash to put aside and want to earn a return without taking on the volatility of stocks. Both can serve short-term savings goals, but they work differently. A T-bill is a short-term U.S. Treasury security, while a CD is a time deposit offered by a bank or credit union.

    The real difference shows up when you look past the advertised rate. The maturity date, access to your money, taxes, insurance, and what happens if your plans change can all affect the outcome. T-bills have maturities of one year or less, while CDs can come with a much wider range of terms.

    What You’ll Learn

    • How Treasury bills and CDs work from purchase to maturity.
    • How U.S. government backing differs from FDIC or NCUA insurance.
    • What can happen when you need your money before maturity.
    • How federal and state taxes can affect your actual return.
    • Which rates, fees, terms, and access rules deserve attention.
    • How to match each option with a short-term financial goal.

    If T-bills are new to you, start with our Treasury Bills Explained guide. It covers the basics before we get into the practical differences between T-bills and CDs.

    Quick Answer: Treasury Bills vs CDs

    Treasury bills and CDs can both fit short-term savings goals, but they are built differently. A T-bill is a short-term U.S. Treasury security with a maturity of one year or less. A CD is a time deposit from a bank or credit union with a specific term and account rules.

    Key Takeaways

    • Different products: T-bills are Treasury securities; CDs are deposit products.
    • Protection differs: T-bills are backed by the U.S. government, while eligible CDs at FDIC-insured banks can receive FDIC insurance within applicable limits.
    • Maturity differs: T-bills mature within one year, while CDs can have terms ranging from short periods to several years.
    • Early access differs: A CD may impose an early-withdrawal penalty. A marketable T-bill can generally be sold before maturity, but its market price may be higher or lower than the purchase price.
    • Taxes matter: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally taxable income.
    • Yield is only one factor: Compare the return with taxes, maturity, insurance, fees, access rules, and your cash timeline.

    BOTTOM LINE: Start with when you expect to need the money. Then compare the current T-bill yield or CD APY, applicable protection, tax treatment, fees, and the consequences of accessing the money early.

    Table of Contents

    Treasury Bills vs CDs at a Glance

    T-bills and CDs can both be used for money you expect to keep relatively stable, but they are structured differently. A T-bill is a marketable U.S. Treasury security with a maturity of one year or less. A CD is a time deposit with a specific term and institution-specific rules.

    BEST FOR

    T-bills may fit a defined cash timeline. CDs may fit savers who are comfortable committing money for a selected term.

    KEY NUMBERS

    T-bills mature in 1 year or less. Standard FDIC coverage is $250,000 per depositor, per insured bank, for each ownership category.

    FeatureTreasury BillsCDs
    ProductU.S. Treasury securityTime deposit at a bank or credit union
    MaturityOne year or lessSpecific term selected when opened
    ProtectionBacked by the U.S. government; not FDIC-insuredEligible bank CDs may receive FDIC insurance; eligible credit-union CDs may receive NCUA share insurance
    Early accessA marketable bill can generally be sold before maturity at the available market priceEarly withdrawal may involve a penalty or other product-specific restrictions
    ReturnFor a bill held to maturity, generally based on purchase price and maturity valueInterest is earned according to the CD’s stated terms

    QUICK TAKE: Don’t stop at the advertised return. Check the maturity, applicable insurance or government backing, taxes, access rules, and what happens if you need the money earlier than planned.

    Treasury Bills vs CDs: A Complete Beginner Guide

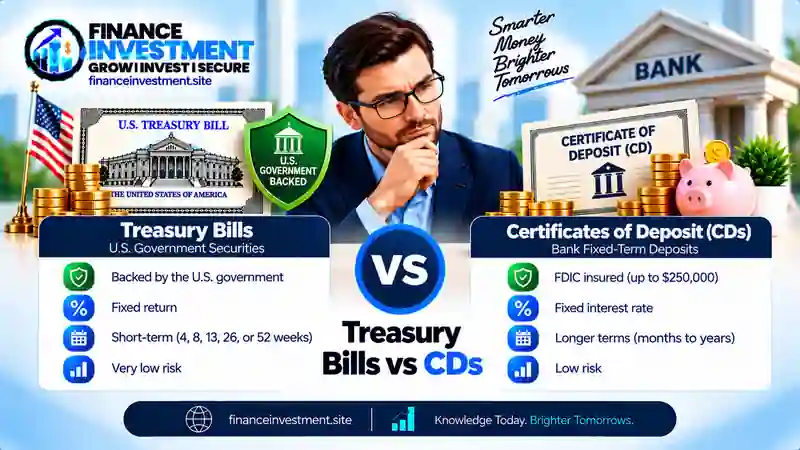
    Treasury Bills vs CDsIf you’re new to Treasury Bills vs CDs, start with the basic difference. A Treasury bill is a short-term U.S. government security. A CD is a time deposit offered by a bank or credit union. Both can be used for money you expect to keep relatively stable, but the way you earn and access that money is different.
    Treasury Bills in Simple Terms

    T-bills have maturities of one year or less. They are generally issued at a discount to face value, although an auction can result in a price at par. When a discounted bill reaches maturity, you receive its face value, with the difference between your purchase price and the amount received representing the interest earned.

    CDs in Simple Terms

    A certificate of deposit is a time deposit with a selected term. Traditional CDs commonly offer a fixed rate for that term, although the exact terms depend on the institution and CD type. Taking money out before maturity may trigger an early-withdrawal penalty, so the account’s disclosure matters before you open one.

    A SIMPLE WAY TO THINK ABOUT IT: A T-bill is a short-term Treasury security with a maturity date. A CD is a time deposit with a selected term. Once you understand that difference, compare the return, taxes, protection, and access rules.

    How Treasury Bills and CDs Work

    The practical difference becomes clearer when you follow the money from purchase to maturity. A T-bill is issued through a Treasury auction and has a defined maturity. A CD is opened with a bank or credit union for a selected term, with the institution’s terms controlling interest, maturity, and early access.

    How a Treasury Bill Works

    The Treasury sells bills through auctions. T-bills are issued at a discount and redeemed at their face value when they mature. For a discounted bill, the difference between the purchase price and the amount received at maturity is the interest earned. A marketable T-bill can generally be sold before maturity, but the sale price is determined by the market at that time.

    How a CD Works

    With a CD, you deposit money for a stated term and earn interest according to the CD’s terms. When the term ends, the deposit becomes available according to the institution’s maturity rules. If you need the money earlier, the CD agreement determines whether early withdrawal is permitted and what penalty or other restriction may apply.

    THE PRACTICAL DIFFERENCE: With a T-bill, getting out before maturity generally means selling a security at its current market price. With a CD, early access is governed by the deposit agreement and may involve a penalty.

    Treasury Bills vs CDs: Benefits and Drawbacks

    Neither product is automatically the right fit for every cash goal. The useful question is what you value most: a Treasury security with a defined maturity, or a time deposit with institution-specific terms.

    Treasury Bills: Pros and Cons

    PROS
    • Backed by the full faith and credit of the U.S. government.
    • Maturities of one year or less can fit short-term cash planning.
    • Interest is generally exempt from state and local income taxes.
    • Marketable T-bills can generally be sold before maturity.
    CONS
    • An early sale exposes you to the market price at that time.
    • Buying and managing Treasury securities may require more steps than opening a bank CD.
    • T-bills are securities, not FDIC-insured deposits.

    CDs: Pros and Cons

    PROS
    • Traditional CDs commonly provide a fixed rate for a defined term.
    • Different terms can accommodate different savings timelines.
    • Eligible bank CDs can receive FDIC insurance within applicable limits.
    • Eligible CDs at federally insured credit unions can receive NCUA share insurance.
    CONS
    • Early withdrawal may result in a penalty under the CD’s terms.
    • Your money may be less accessible during the selected term.
    • CD interest is generally subject to federal income tax and may also be subject to applicable state or local taxes.

    WHAT MATTERS MOST: A T-bill can be sold before maturity, but its market price can change. A traditional CD can keep its stated rate through the term, but early access may cost you through an early-withdrawal penalty. Your cash timeline should come first.

    Treasury Bills vs CDs: Detailed Comparison

    The headline return is only one piece of the puzzle. When comparing Treasury bills and CDs, look at how each product handles maturity, access, taxes, protection and what happens if your plans change.

    FeatureTreasury BillsCDs
    What you ownA short-term U.S. Treasury securityA time deposit with a bank or credit union
    MaturityOne year or lessThe term selected when the CD is opened
    ReturnFor a discounted bill held to maturity, the purchase price and maturity value determine the returnInterest is earned according to the CD’s stated terms
    ProtectionBacked by the U.S. government; not FDIC-insuredEligible bank CDs may receive FDIC insurance; eligible share certificates at federally insured credit unions may receive NCUA share insurance
    Early accessA marketable bill can generally be sold before maturity at the market price available thenEarly withdrawal depends on the CD agreement and may involve a penalty
    Federal taxInterest is generally subject to federal income taxInterest is generally taxable income
    State & local taxGenerally exempt from state and local income taxesMay be subject to applicable state and local income taxes
    Main trade-offDefined maturity with the ability to sell before maturity at the prevailing market priceDefined deposit term with early-access rules set by the CD

    HOW TO USE THIS TABLE: Start with your expected cash date. Then compare the current return, applicable protection, tax treatment and early-access rules. That gives you a more useful comparison than looking at the advertised rate alone.

    Costs, Risks and Expert Tips

    A good comparison goes beyond the advertised return. Before choosing a T-bill or CD, look at the cost of buying or exiting, the tax treatment, and what could happen if you need the money sooner than expected.

    Costs and Risks to Watch

    • T-bills: TreasuryDirect charges no purchase fee or commission. A broker may have its own charges or terms. Selling before maturity also means accepting the market price available at that time.
    • CDs: Check the specific CD agreement for early-withdrawal provisions, minimum deposit requirements, renewal terms, and any other conditions.
    • Taxes: Compare after-tax returns. T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally taxable income.
    • Protection: Confirm whether a CD is held at an FDIC-insured bank or through a federally insured credit union, and check the applicable insurance rules and limits.

    Expert Tips Before You Buy

    1. Start with the date you expect to need the money.
    2. Compare the current T-bill yield with the CD’s APY after considering taxes and applicable costs.
    3. Read the CD disclosure, especially the early-withdrawal and maturity sections.
    4. If buying a T-bill, decide whether you can hold it to maturity or accept the possibility of a different market price if you sell early.

    EXPERT TIP: Don’t compare the rate alone. A slightly higher return may not matter if the product’s maturity, taxes, fees, or early-access rules don’t fit your plans.

    Common Mistakes and a Real-Life Example

    The rate may grab your attention first, but the details can matter more. A few common mistakes can make a T-bill or CD less convenient than expected.

    Common Mistakes to Avoid

    • Looking only at the highest rate: Taxes, fees, maturity and access rules can change the practical value of a return.
    • Ignoring the maturity date: Make sure the T-bill maturity or CD term fits your expected cash date.
    • Confusing selling with withdrawing: A marketable T-bill can generally be sold before maturity at its market price, while a CD follows the withdrawal terms in its agreement.
    • Forgetting tax differences: T-bill interest is generally exempt from state and local income taxes, while CD interest may be subject to applicable state and local taxes.
    • Assuming every CD has identical protection: Check whether the deposit is at an FDIC-insured bank or whether the share certificate is at a federally insured credit union.

    Real-Life Example

    Suppose a couple has $25,000 set aside for a home improvement project they expect to fund in about six months. They could compare a T-bill with a maturity close to that date against a CD whose term fits their timeline.

    They would then compare the current return, taxes, applicable insurance, and early-access rules. If the project date moves, the consequences also matter: selling a T-bill before maturity means accepting its market price, while accessing a CD early depends on the CD’s terms and any applicable penalty.

    KEY LESSON: Choose the time frame first, then compare the return. Matching the product to your cash date can prevent an avoidable early-access problem.

    Who Should Choose Treasury Bills or CDs?

    Your plans for the money can help narrow the choice. Consider how long you can leave it untouched, whether you prefer a Treasury security or a deposit account, and how each product’s terms affect your return.

    Treasury Bills May Fit If:

    • Your spending date matches an available short-term T-bill maturity.
    • You want to hold a security backed by the U.S. government.
    • The state and local income tax treatment matters to you.
    • You can hold until maturity or accept market-price risk if you sell early.

    CDs May Fit If:

    • You want a deposit product with a term suited to your savings goal.
    • You prefer the predictable rate offered by a traditional fixed-rate CD.
    • You can meet the minimum deposit and early-withdrawal conditions.
    • You have confirmed applicable FDIC coverage for an eligible bank CD or NCUA coverage for an eligible credit-union share certificate.

    ONE MORE THING: If you might need this money without warning, neither product should be treated like an everyday spending account. Keep your immediate cash needs in mind before committing to a maturity date or deposit term.

    Frequently Asked Questions About Treasury Bills vs CDs

    1. How do Treasury bills and CDs differ?

    A T-bill is a short-term U.S. Treasury security, while a CD is a time deposit offered by a bank or credit union. Their maturity, access, tax treatment and protection work differently.

    2. Are Treasury bills FDIC-insured?

    No. Treasury bills are not FDIC-insured deposits. They are U.S. Treasury securities backed by the full faith and credit of the U.S. government.

    3. Are CDs FDIC-insured?

    An eligible CD at an FDIC-insured bank can receive FDIC coverage within applicable limits. A share certificate at a federally insured credit union may receive NCUA share insurance instead.

    4. Can you sell a Treasury bill before maturity?

    Yes. A marketable T-bill can generally be sold before maturity, but the amount received depends on its market price at the time of sale.

    5. Can you withdraw money from a CD early?

    That depends on the CD’s terms. A traditional CD may allow early withdrawal with a penalty, while certain CD types can have different access rules.

    6. Are Treasury bill earnings exempt from state taxes?

    Generally, yes. Interest from U.S. Treasury securities is generally exempt from state and local income taxes, while federal income tax generally applies.

    7. Do CDs and Treasury bills have the same tax treatment?

    No. T-bill interest generally receives state and local tax exemption. CD interest is generally taxable income and may also be subject to applicable state and local taxes.

    8. Which should you compare for short-term cash?

    Compare the specific T-bill and CD based on your cash date, current return, taxes, fees, access rules and applicable protection. There is no single comparison that fits every situation.

    REMEMBER: A T-bill is a Treasury security, while a CD is a deposit product. Their insurance, tax and early-access rules should be evaluated separately.


    Treasury Bills vs CDs: Final Comparison

    Treasury bills and CDs can both be used for short-term cash planning, but they work in different ways. A T-bill is a short-term U.S. Treasury security with a defined maturity. A CD is a time deposit with a term and conditions set by the financial institution.

    Before comparing them, look at when you need the money, the current return, applicable taxes, protection, and early-access rules. With a T-bill, consider the maturity date and the market price if you sell before maturity. With a CD, review the term, rate, maturity instructions, and early-withdrawal provisions.

    FINAL CHECK: A useful comparison goes beyond the headline rate. Review the cash timeline, access rules, tax treatment, applicable insurance or government backing, and any costs before making a decision.

    For a broader introduction to Treasury securities, read our Treasury Bills Explained guide. You can also compare another short-term cash option in our CD vs Money Market Account guide.

    Have a Money Question? Keep Exploring.

    Understanding the details can make short-term money decisions easier to compare. Keep exploring FinanceInvestment for practical guides on Treasury bills, CDs, and other personal finance topics.

    📩 Get in Touch With FinanceInvestment

    Have a money question or a topic you’d like us to cover?

    Email FinanceInvestment

    Continue Your Research