FDIC Insurance for Single Accounts vs. Joint Accounts
2026 Edition
Last Updated: November 7, 2026
Reading Time: About 11 minutes
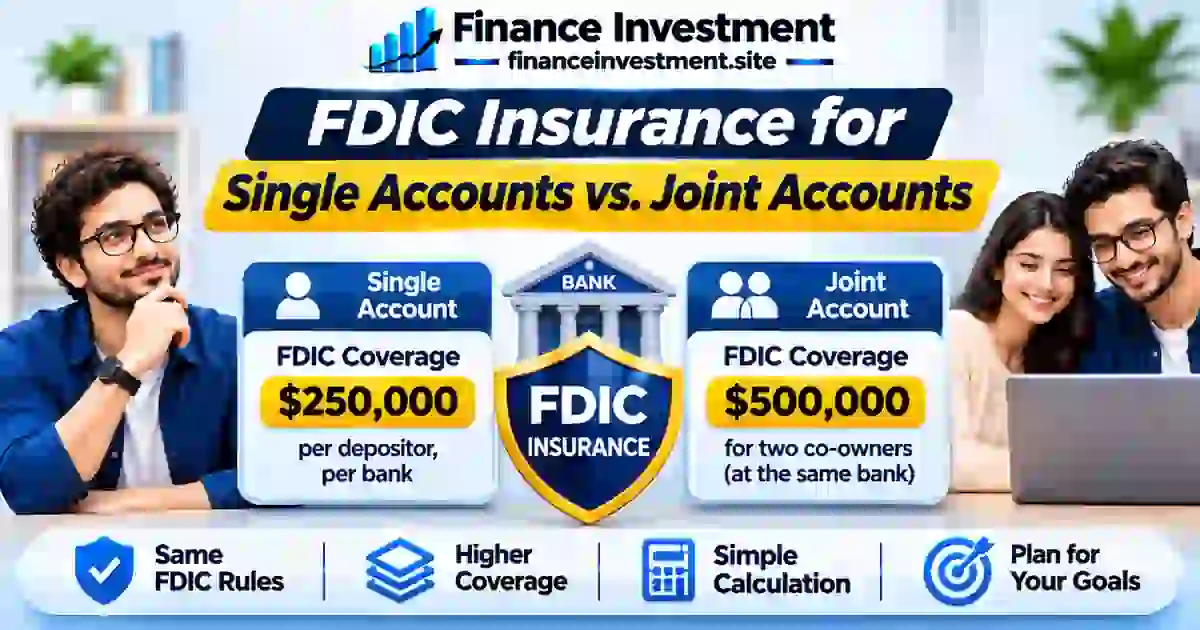
FDIC Insurance for Single Accounts vs. Joint Accounts: What Changes?
FDIC insurance for single accounts vs. joint accounts matters when your family keeps money under different names at the same bank. Two accounts with similar balances may receive different protection because the FDIC considers who legally owns the deposits.
Imagine you have $240,000 in a personal savings account and another $420,000 in a joint savings account with your spouse. If both of you qualify as equal joint owners, could the entire $660,000 be insured? Potentially, yes—but only if the applicable ownership requirements are met and other deposits do not reduce your available coverage.
Knowing these rules can help you organize savings without accidentally exceeding insurance limits. For the bigger picture, read our FDIC and NCUA insurance guide.
What You’ll Learn
- How FDIC limits differ for single and joint accounts.
- When married couples may qualify for additional coverage.
- Why multiple checking, savings, and CD balances matter.
- Which ownership mistakes can leave deposits uninsured.
- How to estimate coverage before moving large savings balances.
Quick Answer: Single vs. Joint FDIC Coverage
At an FDIC-insured bank, single accounts generally receive up to $250,000 per owner in the single ownership category. Qualifying joint accounts receive up to $250,000 per co-owner for their combined joint-account interests. That means two eligible equal co-owners can have up to $500,000 in joint coverage at the same bank.
6 Key Takeaways
- Single and joint deposits are insured in separate ownership categories.
- Being married does not automatically make an account jointly owned.
- Joint owners must satisfy FDIC ownership and withdrawal-right requirements.
- An owner’s deposits within the same category at one bank are combined.
- Checking, savings, and CDs count toward their applicable ownership-category limits.
- Deposits at separately chartered FDIC-insured banks are insured independently.
Bottom Line: FDIC coverage depends on who owns the money, the ownership category, and the insured bank—not simply how many accounts you open.
Single vs. Joint FDIC Insurance at a Glance
Account ownership determines which FDIC insurance limit applies. Here’s how personal and shared deposits compare at the same FDIC-insured bank.
| Quick Fact | Single Account | Joint Account |
|---|---|---|
| Owners | One person | Two or more people |
| Best For | Individually owned savings | Genuinely shared funds |
| Insurance Basis | Owner’s combined single deposits | Each co-owner’s combined joint interests |
| FDIC Category | Single ownership | Joint ownership |
What Is a Single Account Under FDIC Rules?
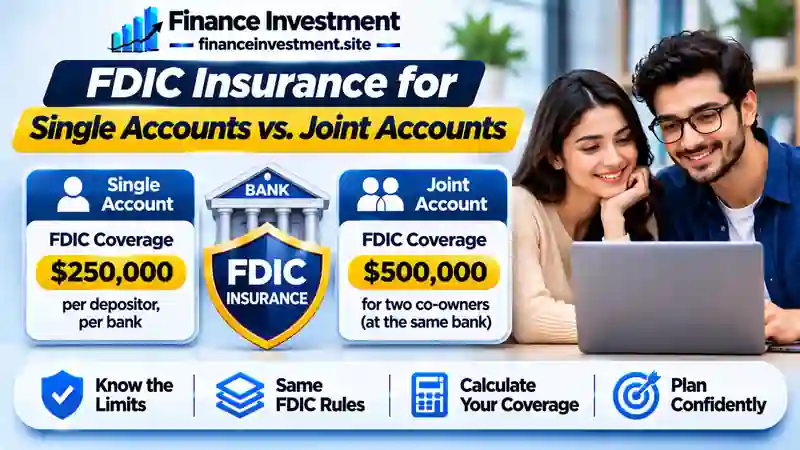
Under FDIC rules, a single account generally belongs to one person and has no named beneficiaries. It can be an everyday checking account, a personal savings account, or a certificate of deposit (CD). An account held in one person’s name with eligible payable-on-death beneficiaries may instead qualify for the trust ownership category.
The FDIC combines your eligible single-ownership deposits at the same insured bank and generally protects up to $250,000 per owner, including accrued interest. Different account numbers do not create additional coverage.
Example: Three Accounts at One Bank
Suppose your deposits at one FDIC-insured bank are:
- Checking: $45,000
- Savings: $135,000
- CD: $95,000
Total: $275,000 | Insured: $250,000 | Uninsured: $25,000
This assumes all three accounts qualify as single-ownership deposits, no other deposits affect the category, and the stated balances include accrued interest.
What About an Authorized Signer?
Giving someone permission to make transactions does not automatically make that person a co-owner. The bank’s ownership records and applicable FDIC rules determine coverage.
Learn more in our FDIC insurance guide for checking accounts.
How Does FDIC Insurance Work for Joint Accounts?
A joint account is owned by two or more people. At an FDIC-insured bank, each eligible co-owner generally receives up to $250,000 in joint ownership coverage. The FDIC combines each person’s interests across qualifying joint accounts at that same bank before applying the limit.
What Makes a Joint Account Eligible?
- Every co-owner must be a living individual.
- Each co-owner must have equal rights to withdraw funds.
- The bank’s deposit records must identify joint ownership.
- Required signatures or qualifying electronic account records must be maintained, subject to FDIC exceptions.
Example: A Couple With $480,000
Emma and James have $480,000 in a qualifying joint savings account. Assuming equal ownership interests:
- Emma’s insured interest: $240,000
- James’s insured interest: $240,000
- Total insured: $480,000
This assumes neither person has additional joint-account interests at the same bank and the balances include accrued interest.
Can Three Owners Receive More Coverage?
Yes. Three qualifying equal co-owners may receive up to $750,000 combined in joint coverage. However, adding another owner gives that person legal rights to the account, so insurance should not be the only consideration.
Compare ownership choices in our joint vs. individual checking account guide.
Benefits and Drawbacks of Single and Joint Accounts
Choosing an account isn’t just about insurance limits. Think about who needs access to the money and how comfortably you can share financial decisions.
Benefits
- Single: You maintain individual ownership and control.
- Single: Personal savings stay separate from shared household funds.
- Joint: Co-owners can manage shared expenses together.
- Joint: Qualifying ownership may provide additional FDIC coverage.
Drawbacks
- Single: Other people generally cannot access funds without authorization.
- Single: Additional single accounts at one bank don’t increase the category limit.
- Joint: A co-owner may withdraw shared funds without asking you.
- Joint: Ownership disputes or legal claims can complicate access.
Practical Tip: Use joint ownership when you genuinely intend to share control—not simply to increase deposit insurance.
Single vs. Joint Accounts: FDIC Coverage Comparison
The biggest difference isn’t the account type—it’s how ownership affects insurance, access, and the way deposits are combined at one bank.
| Feature | Single Account | Joint Account |
|---|---|---|
| Ownership | One individual | Two or more individuals |
| FDIC Limit | $250,000 per owner | $250,000 per eligible co-owner |
| Two-Owner Example | Separate single accounts: $250,000 each | Up to $500,000 combined |
| Multiple Accounts | Same owner’s single deposits combined | Each owner’s joint interests combined |
| Account Access | Individual owner controls funds | Co-owners generally have withdrawal rights |
| Named Beneficiaries | May change FDIC category to trust | May change FDIC category to trust |
| Best Suited For | Personal funds | Genuinely shared funds |
Important: The limits apply per ownership category at each FDIC-insured bank, assuming all eligibility requirements are met. A qualifying beneficiary designation can change which category applies.
FDIC Coverage Limits, Hidden Risks and Expert Tips
A large bank balance deserves more than a quick glance at the account name. Before moving family savings, check the bank’s identity, ownership records and interest earnings.
Three Details That Can Affect Coverage
- Bank identity: Different branches or banking brands may operate under one insured bank charter. Their deposits are combined within the same ownership category.
- Accrued interest: FDIC insurance includes eligible principal and accrued interest through the bank’s failure date. Leave room for interest when planning balances.
- Ownership records: Joint coverage depends on qualifying co-ownership, equal withdrawal rights and applicable documentation requirements.
Expert Tip: Check Your Actual Coverage
Use the official FDIC EDIE calculator to estimate insurance for all deposits at one bank. Our FDIC insurance calculator guide explains what information to gather.
Warning: Opening another account at a different branch of the same bank won’t increase coverage within the same ownership category. Separately chartered insured banks provide separate limits. Read our FDIC coverage at different banks guide before spreading large balances.
5 Common FDIC Insurance Mistakes to Avoid
FDIC coverage depends on ownership, not simply the number of accounts. Avoid these five mistakes when organizing family savings.
- Counting accounts separately: Deposits within the same ownership category at one bank are generally combined for each owner.
- Assuming marriage means joint ownership: Marriage alone does not establish joint-account coverage.
- Ignoring additional joint deposits: Each co-owner’s qualifying joint interests at the same bank are aggregated.
- Confusing signers with owners: An authorized signer is not automatically a joint owner.
- Misunderstanding beneficiaries: Qualifying beneficiary designations may place deposits in the trust category, subject to its rules.
Hypothetical Family Example: $700,000 at One Bank
Maya and Daniel hold these deposits at one FDIC-insured bank:
- Maya’s single savings: $150,000 insured
- Daniel’s single CD: $150,000 insured
- Joint savings: $400,000 insured ($200,000 per co-owner)
Total: $700,000 insured; $0 uninsured.
Important: This assumes qualifying account ownership, no other deposits at that bank, and balances that include accrued interest.
Who Should Choose a Single or Joint Account?
Your choice should reflect how you manage money, who needs access and whether you genuinely want shared ownership.
A Single Account May Suit You If:
- You prefer independent control over savings.
- You want personal finances kept separate.
- You don’t need another legal account owner.
A Joint Account May Suit You If:
- You share household bills or savings goals.
- You trust your co-owner with access to funds.
- You both need ongoing account control.
A Practical Middle Ground: Keep personal savings separate and use a joint account for shared expenses. Confirm ownership terms and FDIC coverage before depositing large amounts.
Frequently Asked Questions About Single and Joint FDIC Insurance
Final Verdict: Single vs. Joint FDIC Insurance
The better choice depends on how you want to own and manage your money. Single accounts offer independent control, with up to $250,000 insured per depositor, per insured bank, in the single ownership category. Qualifying joint accounts provide up to $250,000 per co-owner in the joint category.
Many households benefit from keeping personal savings separate while sharing an account for common expenses. Remember that co-owners generally have withdrawal rights, and deposits in the same ownership category at one bank are combined for coverage purposes.
Bottom Line: Choose genuine ownership arrangements, check your total balances, and read our FDIC and NCUA insurance guide for more deposit protection guidance.
Have a Money Question? Keep Exploring.
Wondering whether your single or joint deposits are fully protected? Explore our banking guides or send us your question.
Disclaimer: This content is educational, not personalized financial or legal advice. Actual FDIC coverage depends on the insured bank, account ownership, balances and applicable rules. Confirm your coverage using official FDIC resources.
Leave a Reply