Do Checking and Savings Accounts Share the Same FDIC Insurance Limit?
Updated: November 6, 2026
Reading time: 10 minutes
Do Checking and Savings Accounts Share the Same FDIC Insurance Limit?
Your checking account handles everyday expenses, while your savings account may hold money for emergencies or future plans. Keeping these accounts separate can make budgeting easier—but it does not automatically give you separate FDIC insurance limits.
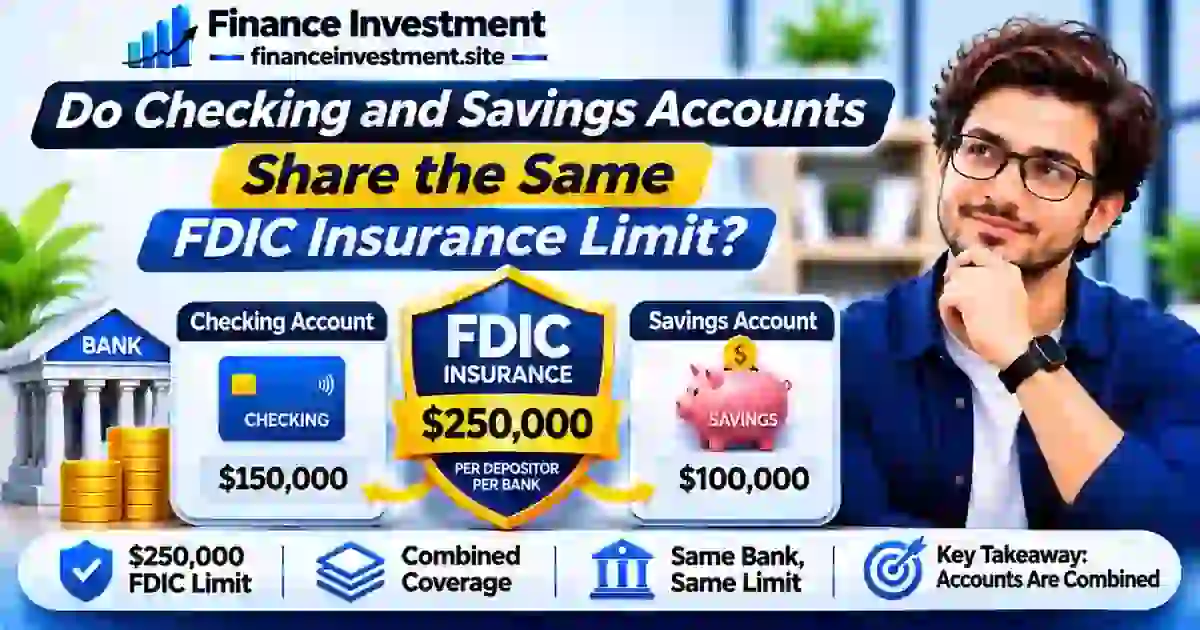
At the same FDIC-insured bank, deposits you own in the same ownership category are generally combined when coverage is calculated. checking and savings accounts FDIC insurance That means your checking and savings balances may count toward one standard $250,000 insurance limit, rather than receiving $250,000 of protection each.
The important details are where your money is held, who owns it, and how the accounts are legally categorized. Understanding those factors can help you avoid assuming that opening another account increases your protection.
This guide explains the rule in practical terms, including how account ownership can affect coverage and what to review before moving money. For a broader explanation of bank and credit union protection, visit our FDIC and NCUA insurance guide.
What You’ll Learn
- Why checking and savings accounts generally share the same FDIC limit at one bank
- How the standard $250,000 coverage rule applies to your deposits
- How account ownership categories can affect total protection
- What to check before deciding whether your deposits need a different arrangement
Quick Answer: Do Checking and Savings Accounts Share FDIC Insurance?
Yes, generally. If you own checking and savings deposits at the same FDIC-insured bank in the same ownership category, those balances are combined toward the standard $250,000 FDIC insurance limit. Having separate accounts does not automatically give you a separate $250,000 limit for each one.
Key Takeaways
- Same bank and ownership category: Your eligible checking and savings deposits generally count together.
- Standard coverage: The limit is generally $250,000 per depositor, per insured bank, per ownership category.
- More accounts do not automatically mean more coverage: Account count alone does not increase your insurance limit.
- Ownership can make a difference: Qualifying ownership categories may receive separate coverage under FDIC rules.
- Check your situation: Use the official FDIC EDIE calculator to estimate coverage based on your deposits and ownership details.
FDIC Coverage at a Glance
Checking and savings accounts may have different everyday uses, but FDIC insurance is based on how deposits are owned and where they are held—not simply how many accounts you open. This quick table highlights the standard coverage rules.
| Coverage Detail | What It Means |
|---|---|
| Standard limit | $250,000 per depositor, per FDIC-insured bank, per ownership category |
| Checking + savings | Generally combined when owned by the same depositor in the same ownership category at one insured bank |
| Different insured banks | Coverage is generally calculated separately at each FDIC-insured bank |
| Ownership categories | Qualifying categories may receive separate coverage under FDIC rules |
| Coverage estimate | Use the FDIC EDIE calculator to estimate coverage based on your account details |
This is a general overview. Actual coverage depends on deposit eligibility, bank status, account ownership, and applicable FDIC rules.
FDIC Insurance Basics: What Every Bank Customer Should Know
The Federal Deposit Insurance Corporation (FDIC) is an independent U.S. government agency that protects depositors if an FDIC-insured bank fails. Its insurance helps protect eligible deposits from losses caused by a bank failure, subject to the applicable coverage limits and rules.
What Does FDIC Insurance Cover?
FDIC insurance covers eligible deposit products held at FDIC-insured banks. Common examples include checking accounts, savings accounts, money market deposit accounts, and certificates of deposit (CDs). Coverage is automatic when eligible deposits are held at an insured bank, so customers do not need to purchase a separate insurance policy.
What Is Not FDIC-Insured?
Some financial products offered through banks are investments rather than deposits. Stocks, bonds, mutual funds, annuities, and cryptocurrency are not protected by FDIC deposit insurance. A product does not become insured simply because a bank offers or sells it.
Why Does Account Ownership Matter?
The FDIC determines coverage based on who owns the deposits and the applicable ownership category. Eligible deposits in the same category at the same insured bank are generally combined. Certain qualifying categories, such as individual and joint accounts, may receive separate coverage when FDIC requirements are met.
For a broader explanation of deposit protection at banks and credit unions, read our FDIC and NCUA insurance guide.
How Checking and Savings Accounts Share FDIC Coverage
FDIC insurance is calculated using three key factors: who owns the deposits, which FDIC-insured bank holds them, and the ownership category they belong to. Eligible deposits in the same category are combined, even when they are spread across checking, savings, and other deposit accounts.
Checking and Savings at the Same Bank
If you own an individual checking account and an individual savings account at the same FDIC-insured bank, their eligible balances generally count together under the single-account ownership category. Opening another account or moving money between those accounts does not create an additional insurance limit.
Accounts at Different Banks
Deposits at separately chartered FDIC-insured banks are generally calculated separately. However, different branches, websites, or brand names may belong to the same insured bank. Before relying on separate coverage, confirm that each institution is independently FDIC-insured.
When Ownership Categories Can Differ
FDIC rules recognize different legal ownership categories. For example, qualifying individual deposits and qualifying joint deposits may receive separate coverage. The accounts must meet the requirements for their respective categories; simply opening checking and savings accounts does not create separate ownership.
Remember: The FDIC looks at eligible deposits and their legal ownership—not just the account names, number of accounts, or bank branding.
To estimate your coverage, enter your account ownership and balances in the official FDIC EDIE calculator. You can also review our FDIC and NCUA insurance guide for a broader explanation of deposit protection.
Benefits and Drawbacks of Shared FDIC Coverage
Knowing how checking and savings deposits are insured can make it easier to organize your money and understand where your coverage may fall short. The main benefit is clarity; the limitation is that separate accounts do not automatically create separate insurance limits.
Benefits
- Clearer deposit planning: Reviewing checking and savings balances together helps you understand how eligible deposits are counted.
- Flexible account organization: You can keep spending money in checking and reserves in savings without assuming that the account setup changes your insurance limit.
- More coverage options: Qualifying ownership categories or deposits at separately insured banks may receive separate coverage when FDIC requirements are met.
Drawbacks
- Easy to miscalculate: Multiple accounts can make combined eligible balances harder to track.
- Possible uninsured amounts: Deposits exceeding the applicable limit may not be fully insured.
- Ownership rules can be complex: Joint, trust, and other account categories have specific eligibility requirements.
Important: FDIC insurance protects eligible deposits if an insured bank fails. It does not protect against fraud, theft, or unauthorized transactions. For official coverage details, review the FDIC deposit insurance guidance.
Checking vs. Savings Accounts: Do They Get Separate FDIC Coverage?
Checking and savings accounts are both eligible deposit products, but their names do not create separate insurance limits. The FDIC generally combines eligible deposits owned by the same depositor in the same ownership category at the same insured bank. See the FDIC coverage overview.
| Account Situation | How FDIC Coverage Generally Works |
|---|---|
| Individual checking + individual savings at one bank | Eligible balances are generally combined under the single-account ownership category. |
| Two individual checking accounts at one bank | Balances generally count together; opening another account does not create another limit. |
| Checking and savings at separately chartered insured banks | Coverage is generally calculated separately at each FDIC-insured bank. |
| Individual account + qualifying joint account | These may receive separate coverage because they fall under different ownership categories, if FDIC requirements are met. |
Bottom line: The account type alone does not create another FDIC limit. Coverage depends on the insured bank, depositor, and qualifying ownership category.
FDIC Coverage Risks and Expert Tips
The biggest FDIC coverage risk is assuming that every dollar across your checking and savings accounts is protected without reviewing the combined balance. Eligible deposits are insured within the applicable limit, including principal and accrued interest through the date an insured bank fails.
Risks to Watch
- Accrued interest: Interest earned before a bank failure counts toward your applicable insurance limit.
- Uninsured deposits: Eligible balances above your available coverage may not be fully insured.
- Bank identity confusion: Different branches or brand names may belong to the same FDIC-insured bank.
- Deposit eligibility: Confirm that your institution is FDIC-insured and your financial product qualifies as an insured deposit.
Practical Expert Tips
- Verify your institution through the official FDIC BankFind Suite.
- Review combined eligible balances across checking, savings, and other deposits in the same ownership category.
- Include accrued interest when estimating your total deposits.
- Use the official FDIC EDIE calculator to estimate coverage based on your account details.
If you have complex trust, business, or joint-account arrangements, confirm the applicable requirements with the FDIC before relying on a coverage estimate.
Common FDIC Insurance Mistakes and Real-Life Examples
Checking and savings accounts may look like separate financial products, but FDIC insurance depends on more than the account name. These common mistakes can lead to an incorrect estimate of how much money is protected.
Mistake 1: Assuming Every Account Gets Its Own Limit
Jordan keeps $140,000 in checking and $125,000 in savings at the same FDIC-insured bank. If both accounts are owned individually and fall within the same ownership category, the $265,000 combined balance exceeds the standard $250,000 limit by $15,000, before considering accrued interest or other eligible deposits.
Mistake 2: Confusing Bank Brands With Separate Banks
A bank may operate under multiple brand names or offer online accounts through a separate website. If those accounts belong to the same insured bank, eligible deposits in the same ownership category generally count together. Different names alone do not establish separate insurance coverage.
Mistake 3: Assuming Joint Accounts Automatically Add Coverage
Adding a spouse or another person to an account does not automatically create separate coverage. Joint accounts must meet FDIC ownership and recordkeeping requirements, and each co-owner’s share is considered under the joint-account rules.
Mistake 4: Forgetting Accrued Interest
Riley checks only the original deposit amount. However, accrued interest through the date of an insured bank’s failure also counts toward the applicable coverage limit.
Bottom line: Review the insured bank, account ownership, combined eligible balances, and accrued interest. Use the official FDIC EDIE calculator to estimate your coverage.
Who Should Review Their FDIC Coverage?
Reviewing FDIC insurance is especially important when your deposits, account ownership, or banking arrangements change. Checking and savings accounts at the same insured bank may share one coverage limit when they belong to the same ownership category.
Consider Reviewing Your Coverage If You:
- Hold substantial combined checking, savings, or CD balances at one insured bank.
- Receive a large deposit from a home sale, inheritance, bonus, or maturing CD.
- Have accounts under different bank brands and are unsure whether they belong to the same insured institution.
- Maintain individual, joint, trust, or business accounts and need to understand their ownership categories.
- Are uncertain whether your institution or financial product qualifies for FDIC insurance.
Start by confirming your institution through FDIC BankFind. Then review eligible deposits, account ownership, and accrued interest. Use the official FDIC EDIE calculator to estimate coverage. Complex trust or business arrangements may require additional review.
Frequently Asked Questions About Checking and Savings FDIC Insurance
1. Do checking and savings accounts share the same FDIC limit?
Yes. If both accounts belong to the same depositor, insured bank, and ownership category, eligible balances generally combine toward the $250,000 standard limit, along with other eligible deposits in that category.
2. Is checking account money automatically FDIC-insured?
Eligible checking deposits are automatically insured when held at an FDIC-insured bank, subject to the applicable coverage limit.
3. Does opening two savings accounts increase FDIC coverage?
No. Multiple accounts in the same ownership category at the same insured bank generally share the same limit.
4. Are checking and savings accounts insured separately at different banks?
Generally, deposits at separately chartered FDIC-insured banks are insured separately, subject to the applicable ownership category limit.
5. Does FDIC insurance cover accrued interest?
Yes. Principal and accrued interest through the date of an insured bank’s failure count toward applicable coverage.
6. Are joint checking accounts covered separately?
Joint accounts may qualify for separate coverage under the joint-account category, including up to $250,000 per co-owner, if FDIC ownership and recordkeeping requirements are met.
7. Are money market accounts FDIC-insured?
Money market deposit accounts at insured banks are eligible deposits. Money market mutual funds are investment products and are not FDIC-insured.
8. Does FDIC insurance protect against bank fraud?
No. FDIC insurance protects eligible deposits against an insured bank’s failure, not fraud, theft, or unauthorized transactions.
9. How can I calculate my FDIC coverage?
Use the official FDIC EDIE calculator and enter your bank, account balances, and ownership details.
10. Can I have more than $250,000 insured at one bank?
Yes. You may qualify for more than $250,000 in total coverage through different ownership categories at the same insured bank when all FDIC requirements are satisfied.
Final Verdict: Checking and Savings Accounts Share One FDIC Limit
Checking and savings accounts generally share the same $250,000 FDIC insurance limit when they belong to the same depositor, the same insured bank, and the same ownership category. Opening another account at that bank does not automatically increase your protection.
Additional coverage may be available through separately chartered FDIC-insured banks or qualifying ownership categories, provided all applicable FDIC requirements are met. To understand your coverage, consider your combined eligible deposits, account ownership, and accrued interest.
For a broader explanation of deposit insurance and ownership categories, read our FDIC and NCUA Insurance Explained guide.
Bottom line: Your FDIC coverage depends on where your money is held and how the deposits are owned—not simply how many checking or savings accounts you have.
Have Questions About Your FDIC Insurance?
Checking and savings accounts can share an FDIC insurance limit, but your coverage depends on the insured bank, account ownership, and eligible deposits. Review your balances and use official FDIC resources if you need to estimate your protection.
Need help understanding a banking topic?
Send FinanceInvestment your question or suggestion for a future guide.
Continue learning with our FDIC and NCUA Insurance Explained guide.
Leave a Reply