Category: Investing

  • What Happens to T-Bills If a Brokerage Fails? | SIPC Guide

    What Happens to T-Bills If a Brokerage Fails? | SIPC Guide

    What Happens to T-Bills If a Brokerage Fails?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 24, 2026
    Updated: Sep 24, 2026
    Reading Time: 11–13 min
    What happens to your Treasury bills when the brokerage holding them fails—and what SIPC protection can and cannot do.


    What Happens to T-Bills If a Brokerage Fails?

    What Happens to T-Bills If a Brokerage FailsWhat happens to T-bills if a brokerage fails? Your Treasury bills do not simply become worthless because the brokerage holding them fails. T-bills are securities held in a brokerage account, and when a SIPC-member brokerage fails, SIPC may help protect eligible customer securities and cash if customer property is missing, subject to applicable rules and limits.

    There is an important distinction, though. SIPC protection does not cover a drop in the market value of your T-bills. If interest rates change and the market price of a Treasury bill moves, that investment risk remains yours. SIPC protection is designed for situations involving a failed member brokerage and missing customer property, not ordinary investment losses.

    During a brokerage liquidation, customer accounts may sometimes be transferred to another brokerage, while a trustee works through customer claims and the firm’s records. The exact process depends on the circumstances of the failure.

    That makes one question especially useful for T-bill investors: what protection applies to the Treasury security itself, and what protection applies to the brokerage account holding it? Keeping those two issues separate makes the whole process much easier to understand.

    What You’ll Learn

    • What can happen to your T-bills when a brokerage fails.
    • How SIPC protection can apply to eligible Treasury securities.
    • Why brokerage failure is different from a decline in a T-bill’s market price.
    • What the standard $500,000 SIPC protection limit means, including the $250,000 cash limit.
    • How a trustee may handle customer accounts and missing property during a liquidation.
    • What investors should check before keeping T-bills at a brokerage.

    If you want to review the basics first, see our Treasury Bills Explained guide. It provides the foundation for understanding what you actually own before we look at brokerage failure.

    Quick Answer: What Happens to T-Bills If a Brokerage Fails?

    Your T-bills do not automatically become worthless if your brokerage fails. If the brokerage is a SIPC member and customer securities or cash are missing, SIPC may provide protection for eligible customer property, subject to applicable rules and limits. Treasury securities are among the securities that SIPC protection can cover.

    Key Takeaways

    • A brokerage failure is different from an investment loss. SIPC protection addresses certain missing customer securities and cash when a qualifying brokerage fails.
    • The brokerage must be a SIPC member. SIPC protection is available only under the conditions established by the Securities Investor Protection Act.
    • Treasury securities can qualify for SIPC protection. Investor.gov specifically lists Treasuries among the protected securities.
    • The standard SIPC limit is $500,000 per customer. This includes a maximum of $250,000 for claims involving cash. The limit does not mean every investor automatically receives $500,000.
    • SIPC does not cover market losses. If a T-bill’s market value falls because interest rates or other market conditions change, SIPC does not reimburse that decline.
    • A failed brokerage may not always require a full SIPC liquidation. In some cases, customer accounts can be transferred to another SIPC-member brokerage without a SIPC protection proceeding.

    BOTTOM LINE: SIPC protection is designed to address missing eligible customer securities and cash when a SIPC-member brokerage fails. It is not protection against changes in the market value of your T-bills.

    Table of Contents

    T-Bills and Brokerage Failure at a Glance

    When you hold Treasury bills through a brokerage, two things should be kept separate: the Treasury security you own and the brokerage relationship through which it is held. If the brokerage fails, the issue is generally whether customer property can be returned and, when eligible property is missing, whether SIPC protection applies.

    Quick FactWhat It Means
    What you holdA Treasury security recorded in your brokerage account
    If the brokerage failsCustomer accounts may be transferred, or a SIPC liquidation may occur if required
    SIPC limitUp to $500,000 per customer, including up to $250,000 for cash claims
    Market lossNot protected by SIPC
    Membership checkConfirm that the relevant brokerage and, where applicable, clearing firm are SIPC members

    Best For Investors Who Want to Understand the Protection Layers

    The simplest way to look at brokerage-held T-bills is to separate the investment from the account provider. The Treasury bill remains a Treasury security, while SIPC focuses on certain customer cash and securities held by a failed SIPC-member brokerage. Those are different layers of protection.

    QUICK TAKE: A brokerage failure does not by itself mean your T-bills have lost their value or Treasury status. The practical concern is whether the brokerage can account for and return customer property and, if eligible property is missing, whether SIPC protection applies.

    T-Bills at a Brokerage: Complete Beginner Guide

    What Happens to T-Bills If a Brokerage FailsBuying Treasury bills through a brokerage can look similar to buying a stock, but the investment itself is different. A T-bill is a short-term debt security issued by the U.S. Treasury. The brokerage provides the account and services used to purchase and hold that security.
    What You Actually Hold

    When you buy a T-bill through a brokerage, the Treasury—not the brokerage—is the issuer of the security. The brokerage account records your position and provides the custody and trading relationship. Securities can be held in different registration arrangements, including customer-name or street-name form, depending on the account structure.

    If you are new to T-bills, our guide to how Treasury bills work explains how the purchase price, maturity value, and return fit together.

    Why the Brokerage Still Matters

    Even though the Treasury issues the T-bill, the brokerage handles the account through which you hold it. If that brokerage fails, the key question is whether customer property can be accounted for and returned. If a SIPC-member brokerage fails and eligible customer securities or cash are missing, SIPC may provide protection for the resulting shortfall, subject to the applicable rules and limits.

    What SIPC Does—and Does Not—Cover

    SIPC can provide advances of up to $500,000 per customer, including up to $250,000 for cash claims, when the statutory requirements are met. The limit is designed to address a shortfall in eligible customer property; it does not mean every investor automatically receives $500,000.

    Just as important, SIPC does not protect against a decline in the market value of your T-bill. If you sell before maturity and the price is lower because interest rates or other market conditions have changed, that investment loss is not covered by SIPC.

    BEGINNER TIP: Think about the arrangement in two layers: the T-bill is the Treasury security, while the brokerage provides the account and custody relationship. A brokerage failure and a change in the T-bill’s market price are separate risks.

    How T-Bills Are Protected When a Brokerage Fails

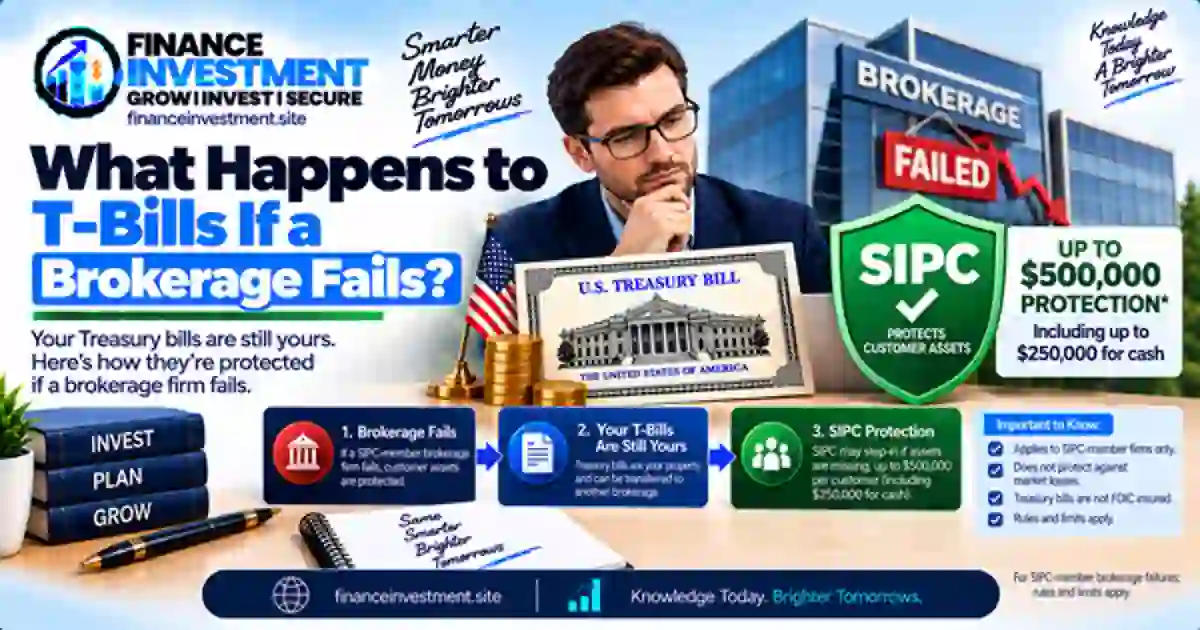
    A brokerage failure does not automatically mean that investors must wait for a SIPC payout. U.S. rules require broker-dealers to segregate customer securities and cash from the firm’s own assets, with the goal of making customer property available for return if the firm fails. If a SIPC-member brokerage cannot meet its obligations, a customer-account transfer or SIPC liquidation may follow, depending on the circumstances.

    Step 1: Customer Property Is Identified

    The trustee reviews the brokerage’s books and records to determine what each customer is entitled to receive. Your account statements, trade confirmations, and other records can help establish the securities and cash connected with your account. This is why keeping accurate records and reviewing statements matters.

    Step 2: Accounts May Be Transferred

    When practical, a trustee may arrange for some or all customer accounts to be transferred to another SIPC-member brokerage. If your account is transferred, you may continue to hold your securities through the new firm rather than going through a lengthy liquidation process for the account itself. Even after a transfer, customers may still need to file a claim if the transfer does not make the account whole.

    Step 3: A Trustee Handles a Liquidation When Necessary

    If liquidation is required, a court-appointed trustee works to return customer property and process valid claims. Customer-name securities can be delivered to the customer in whose name they are registered, while other customer property may be pooled and distributed under the SIPA process.

    Step 4: SIPC Can Address a Shortfall

    If eligible customer property is missing, SIPC may provide an advance of up to $500,000 per customer, including up to $250,000 for cash claims, subject to the applicable rules. Treasury securities are among the securities SIPC protects. This protection addresses a shortfall caused by a qualifying brokerage failure; it does not protect against a decline in the market value of a T-bill.

    IMPORTANT DISTINCTION: There are two separate questions: Can the brokerage return your customer property? And, if eligible property is missing, does SIPC protection apply? Neither question changes the market value of the T-bills themselves.

    Benefits and Drawbacks of Brokerage T-Bills

    Holding Treasury bills through a brokerage can make them easier to manage alongside other investments. At the same time, the brokerage account introduces a separate layer of custody and account-related considerations. Knowing both sides can help you understand what you are actually relying on.

    ✓ Potential Benefits

    • One investment account: T-bills can be managed alongside stocks, bonds, ETFs, and other securities in the same brokerage account.
    • Convenient account records: Purchases, holdings, sales, and maturity information can appear within your regular brokerage records.
    • Access to the secondary market: A brokerage can provide a way to sell a T-bill before maturity, although the price you receive can change with market conditions.
    • SIPC protection may apply: If a SIPC-member brokerage fails and eligible customer securities or cash are missing, SIPC may provide protection for the resulting shortfall, subject to statutory limits and other requirements.

    △ Potential Drawbacks

    • SIPC does not cover market losses: If your T-bill declines in market value, SIPC does not reimburse that investment loss.
    • A brokerage failure can cause disruption: Accounts may need to be transferred, or a liquidation and claims process may be required when customer property is missing.
    • Trading costs can matter: Brokerage commissions, spreads, markups, markdowns, or other transaction costs may affect what you receive when buying or selling in the secondary market.
    • SIPC protection has conditions: The brokerage must be a SIPC member, and the protection applies to qualifying customer securities and cash under the rules of SIPA.

    PRACTICAL TAKE: A brokerage can make T-bills convenient to manage, but convenience is not the same as investment protection. Before buying, check the firm’s SIPC membership, understand its trading costs, and know whether you may need to sell the T-bill before maturity.

    SIPC vs. FDIC vs. Treasury Protection

    SIPC, FDIC insurance, and Treasury backing are not three versions of the same protection. They apply to different financial products and different situations. SIPC addresses certain missing customer securities and cash when a qualifying brokerage fails. FDIC insurance protects eligible deposits at FDIC-insured banks. Treasury backing refers to the U.S. government’s obligation on Treasury securities such as T-bills.

    Protection or BackingApplies ToWhat It Addresses
    SIPCEligible securities and qualifying cash held at a SIPC-member brokerageMissing customer property after a qualifying brokerage failure
    FDIC insuranceEligible deposits at an FDIC-insured bankCovered deposit losses when an insured bank fails
    Treasury backingU.S. Treasury securities such as T-billsThe U.S. government’s obligation to honor the security according to its terms

    What This Means for Brokerage-Held T-Bills

    Suppose you hold T-bills in a brokerage account and the brokerage later fails. The T-bills remain Treasury securities. If the brokerage is a SIPC member and eligible customer securities or cash are missing, SIPC may provide protection for the resulting customer-property shortfall. Treasury securities are specifically included among the securities SIPC protects. The standard SIPC limit is up to $500,000 per customer, including up to $250,000 for cash claims, subject to the applicable rules.

    FDIC insurance works differently. If a brokerage uses a bank sweep program, unused cash may be moved into a bank deposit that can receive FDIC insurance under applicable rules. That does not make your separately held T-bills FDIC insured.

    There is another important boundary: SIPC does not protect against a decline in the market value of a security. So if your T-bill’s market price falls because interest rates or other market conditions change, that investment loss is not a SIPC claim.

    EASY WAY TO REMEMBER: SIPC = certain brokerage-failure losses involving missing customer property. FDIC = eligible bank deposits. Treasury backing = the U.S. government’s obligation on Treasury securities.

    Limits, Risks and Practical Tips

    SIPC protection can be valuable when a brokerage fails, but it is not unlimited insurance. The standard protection is up to $500,000 per customer, including a maximum of $250,000 for cash claims. The amount actually available depends on the customer’s eligible claim, the customer-property shortfall, and the applicable SIPC rules.

    Know the Main Limits

    • SIPC is not market-loss insurance. If your T-bill falls in market value, SIPC does not reimburse that investment loss.
    • The brokerage must qualify for SIPC protection. SIPC protection applies when the relevant brokerage is a SIPC member and the other legal requirements are met.
    • Different account capacities can matter. Accounts held in separate capacities can receive separate SIPC limits, while accounts held in the same capacity at the same firm are generally combined for the protection limits.

    Practical Tips for T-Bill Investors

    1. Verify SIPC membership before keeping a large T-bill position at a brokerage.
    2. Save account statements and trade confirmations so you can document your holdings if a problem occurs.
    3. Understand your cash position. Uninvested cash, money market funds, and bank sweep deposits can receive different types of protection.
    4. Know your broker and clearing firm. Review which firms actually hold or clear your account and understand the account structure.
    5. Do not confuse SIPC protection with a guarantee of value. The purpose is to address certain missing customer securities and cash after a qualifying brokerage failure.

    PRACTICAL TAKE: Before buying T-bills through a brokerage, check three things: SIPC membership, account structure, and what happens to your uninvested cash. Those details help you understand the protection that may apply if the brokerage later fails.

    Common Mistakes and Real-Life Example

    Many T-bill investors focus on the Treasury security itself and overlook the brokerage relationship. That can create confusion if the brokerage later fails. Understanding the difference between returning customer property and covering a shortfall makes the process easier to follow.

    Common Mistakes to Avoid

    • Assuming SIPC works like FDIC insurance: SIPC addresses certain missing customer securities and cash after a qualifying brokerage failure. It does not protect against investment losses.
    • Assuming every brokerage account is automatically protected: The brokerage must be a SIPC member, and the customer and property must meet the applicable requirements.
    • Confusing T-bills with cash: A T-bill is a Treasury security. Uninvested brokerage cash can have different protection depending on how it is held.
    • Ignoring account records: Statements, trade confirmations, and other records can help establish what securities and cash are connected with your account.

    Real-Life Example: A $300,000 T-Bill Position

    Imagine an investor holds $300,000 of Treasury bills through a SIPC-member brokerage. The brokerage later fails, but its records and custody systems show that the investor owns those T-bills. If the securities can be located and returned, the investor generally receives the securities rather than a SIPC payment for their market value. Treasury securities are among the securities covered by SIPC protection.

    Now assume some eligible customer property is missing. SIPC may provide an advance toward the qualifying shortfall, subject to the applicable protection limits. The standard limit is up to $500,000 per customer, including up to $250,000 for cash claims. This does not mean an investor automatically receives $500,000.

    Finally, suppose the T-bills are worth less in the secondary market because interest rates changed. That is a separate investment risk. SIPC does not cover a decline in market value. The example shows why brokerage failure, missing customer property, and ordinary market-price changes should not be treated as the same event.

    KEY LESSON: If a brokerage fails, first determine whether your T-bills and other customer property can be returned. If eligible property is missing, then SIPC protection may address the qualifying shortfall, subject to its rules and limits.

    Who Should Consider Brokerage T-Bills?

    Brokerage-held T-bills may be relevant for investors who want to manage Treasury securities alongside stocks, bonds, ETFs, or other investments in one account. A brokerage can also provide access to Treasury purchases and, depending on the firm, a secondary market for selling before maturity.

    This Setup May Fit Investors Who Value

    • Account convenience: Keep T-bills and other investments together in one brokerage account.
    • Trading access: Use brokerage tools to buy or sell Treasury bills, including before maturity when secondary-market access is available.
    • Portfolio management: View Treasury holdings alongside the rest of the investment portfolio.
    • Brokerage-based custody: Hold eligible Treasury securities through a SIPC-member brokerage, where SIPC protection may apply if the firm fails and eligible customer property is missing.

    What to Check Before Buying

    Compare the brokerage’s SIPC membership, clearing arrangement, trading costs, account structure, and treatment of uninvested cash. Investor.gov recommends checking whether the brokerage and clearing firm are SIPC members.  If you prefer to hold Treasury securities directly rather than through a brokerage, compare that approach with your other Treasury bill options before making a decision.

    KEY POINT: Brokerage-held T-bills can offer account convenience, but SIPC protection is a separate issue. It addresses certain missing customer securities and cash after a qualifying brokerage failure; it does not protect against normal investment losses.

    Frequently Asked Questions

    1. What happens to T-bills if a brokerage fails?

    Your T-bills do not automatically become worthless if a brokerage fails. Customer accounts may be transferred to another SIPC-member brokerage, or a SIPC liquidation may occur if necessary. If eligible customer property is missing, SIPC may provide protection for a qualifying shortfall, subject to applicable rules and limits.

    2. Are Treasury bills protected by SIPC?

    Treasury securities are among the securities SIPC can protect when held through a qualifying SIPC-member brokerage. The protection is designed for certain missing customer securities and cash after a qualifying brokerage failure. It does not protect against a decline in the market value of the investment.

    3. What is the SIPC protection limit for T-bills?

    SIPC may provide protection of up to $500,000 per customer, including a maximum of $250,000 for cash claims. The limit is not an automatic payment. The amount available depends on the customer’s eligible claim, missing customer property, and the applicable SIPC rules.

    4. Does SIPC protect T-bills from losing value?

    No. SIPC does not protect against a decline in the market value of securities. If interest rates change and the secondary-market price of your T-bill falls, that investment loss is not covered by SIPC.

    5. Are T-bills FDIC insured when bought through a brokerage?

    No. T-bills are Treasury securities, not bank deposits, so FDIC deposit insurance does not apply to the T-bills themselves. A brokerage may separately offer a bank sweep program for uninvested cash. Eligible swept deposits may receive FDIC protection under applicable banking rules, but that protection is separate from the T-bills.

    6. Can my T-bill account be transferred if my broker fails?

    It may be. A closed SIPC-member brokerage may be able to transfer customer accounts to another SIPC-member brokerage without a SIPC protection proceeding. If SIPC initiates a liquidation, a trustee may also work to transfer customer accounts when possible. The exact process depends on the circumstances.

    7. What should I check before holding T-bills at a brokerage?

    Check whether the brokerage is a SIPC member, understand its clearing arrangement, review how uninvested cash is held, and keep your account statements and trade confirmations. Investor.gov recommends checking the brokerage firm and its clearing firm for SIPC membership.

    8. Is TreasuryDirect different from holding T-bills at a brokerage?

    Yes. TreasuryDirect and brokerage accounts are different ways to hold Treasury securities. A brokerage account involves a brokerage and custody relationship and may involve SIPC protection if the firm qualifies. TreasuryDirect is a separate Treasury account. Investors should compare the account structure, access, and features that matter to them before choosing where to hold T-bills.

    FAQ TAKEAWAY: Treasury backing, SIPC protection, and FDIC insurance are different concepts. Treasury backing relates to the Treasury security itself. SIPC addresses certain missing customer securities and cash when a qualifying brokerage fails. FDIC insurance applies to eligible bank deposits.


    Final Verdict: What Happens to T-Bills If a Brokerage Fails?

    What happens to T-bills if a brokerage fails? A brokerage failure does not automatically make your Treasury bills worthless. If the brokerage is a SIPC member, customer accounts may be transferred to another brokerage, or a SIPC liquidation may occur when necessary. If eligible customer property is missing, SIPC may provide an advance toward the qualifying shortfall, subject to applicable rules and limits.

    The key distinction is between brokerage-failure risk and investment risk. SIPC protection can address certain missing customer securities and cash when a qualifying brokerage fails, but it does not protect against a decline in the market value of your T-bills. The standard SIPC protection limit is up to $500,000 per customer, including up to $250,000 for cash claims.

    Before holding a large T-bill position at a brokerage, review the firm’s SIPC membership, clearing arrangement, account structure, and treatment of uninvested cash. Investor.gov recommends checking both the brokerage firm and its clearing firm for SIPC membership.

    BOTTOM LINE: A brokerage failure is mainly a custody and customer-property issue. If eligible T-bills are properly accounted for, they may be returned or transferred. If eligible customer property is missing, SIPC may address the qualifying shortfall. SIPC does not guarantee the market value of the investment.

    Have a Money Question? Keep Exploring.

    Knowing how your T-bills are held can help you understand the protection that may apply if a brokerage fails. Keep exploring practical Treasury bill and personal finance guides from FinanceInvestment.

    📩 Get in Touch With FinanceInvestment
    Have a question, suggestion, or topic you’d like us to cover?

    Email FinanceInvestment

    Continue Your Research
  • Are Treasury Bills FDIC Insured? What Investors Should Know

    Are Treasury Bills FDIC Insured? What Investors Should Know

    Are Treasury Bills FDIC Insured?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 23, 2026
    Updated: Sep 23, 2026
    Reading Time: 11–13 min
    A practical explanation of FDIC insurance, Treasury backing, and what protects investors who buy T-bills.


    Are Treasury Bills FDIC Insured? Here’s What Investors Need to Know

    
Are Treasury Bills FDIC InsuredAre Treasury Bills FDIC Insured? No. Treasury bills are not covered by FDIC deposit insurance because they are securities, not bank deposits. A T-bill is a short-term debt security issued by the U.S. Department of the Treasury and backed by the full faith and credit of the U.S. government.

    That distinction is important when comparing T-bills with products such as savings accounts, money market deposit accounts, and CDs. FDIC insurance applies to eligible deposits held at FDIC-insured banks. It does not automatically cover an investment simply because you purchased it through a bank.

    So, if you are considering Treasury bills for cash you may need in the near future, the right question is not simply whether they are “insured.” You also need to understand who issued the security, what backs it, how maturity works, and what risks remain before you invest.

    What You’ll Learn

    • Why Treasury bills are not covered by FDIC deposit insurance.
    • How Treasury backing differs from FDIC deposit protection.
    • What T-bills are and how their maturity structure works.
    • How early sale, inflation, and market prices can affect your investment.
    • How T-bills compare with FDIC-insured savings accounts, money market deposit accounts, and CDs.
    • What you should know when buying Treasury bills through TreasuryDirect or a brokerage.

    If you want to start with the basics, read our Treasury Bills Explained guide before going deeper into FDIC coverage.

    Quick Answer: Are Treasury Bills FDIC Insured?

    No. Treasury bills are not FDIC insured. They are U.S. Treasury securities, not bank deposit accounts, so they fall outside the FDIC deposit insurance system.

    That does not mean Treasury bills have no government backing. T-bills are short-term debt obligations of the U.S. Treasury and are backed by the full faith and credit of the U.S. government. This is different from FDIC insurance, which protects qualifying deposits held at FDIC-insured banks.

    Key Takeaways

    • T-bills are not FDIC insured: FDIC deposit insurance does not cover U.S. Treasury bills.
    • Treasury backing is different: T-bills are obligations of the U.S. government and are backed by its full faith and credit.
    • Buying location does not change the security: A T-bill purchased through a bank or brokerage does not become an FDIC-insured deposit.
    • Investment risks still exist: Selling before maturity, changing market prices, inflation, and reinvestment conditions can affect your results.
    • SIPC is separate from FDIC: When applicable, SIPC protection addresses certain losses connected with a failed SIPC-member brokerage and missing customer assets. It does not protect against normal market losses.

    The important distinction: FDIC insurance protects qualifying bank deposits, while Treasury bills are securities backed by the U.S. government’s credit. Understanding that difference makes it easier to compare T-bills with savings accounts, CDs, and other cash options.

    Table of Contents

    Treasury Bills at a Glance

    Before comparing Treasury bills with FDIC-insured bank accounts, it helps to separate two different forms of protection. FDIC insurance applies to eligible bank deposits, while Treasury bills are U.S. government securities backed by the full faith and credit of the federal government.

    FeatureTreasury BillsFDIC-Insured Deposit
    FDIC insured?NoYes, when eligible
    What is it?U.S. Treasury securityBank deposit
    What backs it?Full faith and credit of the U.S. governmentFDIC deposit insurance, subject to applicable limits
    Standard FDIC limitNot applicable$250,000 per depositor, ownership category, per insured bank
    MaturityShort-term; Treasury bills mature in one year or lessDepends on the deposit product

    QUICK TAKE: Treasury bills are not FDIC-insured deposits. Their backing comes from the U.S. government’s obligation on the security. An eligible savings account or CD at an FDIC-insured bank has a different protection structure because it is a bank deposit. The two should be compared based on their structure, liquidity, maturity, taxes, and investment risks—not simply by asking whether one is “insured.”

    Treasury Bills: A Complete Beginner Guide

    
Are Treasury Bills FDIC InsuredIf you are new to Treasury bills, start with one simple idea: a T-bill is a short-term debt security issued by the U.S. Department of the Treasury. When you buy one, you are lending money to the U.S. government for a defined period. Treasury bills are short-term securities that can mature in a few days to 52 weeks.
    How a T-Bill Works

    Unlike a savings account or CD, a Treasury bill is a security rather than a bank deposit. T-bills are generally issued at a discount from their face value and do not make periodic coupon payments. For example, you could pay $9,800 for a $10,000 face-value bill and receive the $10,000 face value at maturity, with the difference representing the return before taxes and other considerations.

    Because the U.S. Treasury issues these securities, Treasury bills carry the full faith and credit of the U.S. government. This is why U.S. Treasury securities are generally considered to have very low credit risk. However, that government backing is not the same thing as FDIC insurance.

    Where Can You Buy Treasury Bills?

    Individual investors can buy Treasury securities through TreasuryDirect or through a bank or brokerage. The purchase channel does not turn the T-bill into a bank deposit. It remains a Treasury security even when held through a brokerage account.

    What Happens at Maturity?

    If you hold a T-bill until maturity, the Treasury pays the security’s face value according to its terms. If you sell before maturity, the market price can be higher or lower than the face value. Changes in interest rates can affect that price, so a T-bill intended for a specific cash need may be easier to manage when its maturity date matches the date you expect to need the money.

    BEGINNER TIP: Keep two ideas separate: FDIC insurance applies to qualifying bank deposits, while Treasury bills are securities backed by the full faith and credit of the U.S. government. Knowing that difference prevents one of the most common T-bill misconceptions.

    How FDIC and Treasury Protection Works

    The easiest way to understand the difference is to start with what you own. FDIC insurance applies to qualifying deposits at FDIC-insured banks. Treasury bills are securities issued by the U.S. Department of the Treasury, so the T-bill itself is not covered by FDIC deposit insurance.

    How FDIC Insurance Protects Bank Deposits

    Eligible checking accounts, savings accounts, money market deposit accounts, and CDs at FDIC-insured banks can receive FDIC protection if the insured bank fails, subject to applicable rules and limits. The standard coverage amount is $250,000 per depositor, per ownership category, per insured bank.

    How Treasury Backing Works

    Treasury bills are backed by the full faith and credit of the U.S. government. This is government credit backing, not FDIC insurance. Treasury securities are generally considered to have very low credit risk, although investors can still face market-price, interest-rate, inflation, and early-sale risks.

    What If You Hold T-Bills at a Brokerage?

    Holding a T-bill through a brokerage introduces a separate layer of investor protection. If a SIPC-member brokerage fails and customer assets are missing, SIPC may protect eligible securities and cash, generally up to $500,000 per customer, including a $250,000 limit for cash, subject to the applicable rules. SIPC does not protect against market losses or a decline in the value of a T-bill.

    SMART CHECK: FDIC insurance, Treasury backing, and SIPC protection address different situations. First identify whether you own a bank deposit, a Treasury security, or a security held through a brokerage. Then look at the specific protection and risks that apply.

    Benefits and Drawbacks of Treasury Bills

    Treasury bills can be useful for investors looking for short-term exposure to U.S. government debt. But their benefits should not be confused with FDIC insurance. T-bills have their own maturity, liquidity, tax, and market considerations.

    Potential Benefits

    • U.S. government backing: Treasury bills are backed by the full faith and credit of the U.S. government.
    • Short maturities: T-bills mature in a few days to 52 weeks, giving investors several short-term time frames to consider.
    • Known maturity value: When held to maturity, a T-bill pays its face value according to its terms. The return comes from the difference between the purchase price and face value.
    • State and local tax benefit: Interest income from U.S. Treasury securities is generally exempt from state and local income taxes, although federal income tax generally applies.

    Potential Drawbacks

    • No FDIC insurance: A T-bill is a security, not a bank deposit, so FDIC deposit insurance does not cover it.
    • Early-sale risk: If you sell before maturity, the market price can be higher or lower than your purchase price or the bill’s face value.
    • Inflation risk: Inflation can reduce the purchasing power of the return you earn.
    • Reinvestment risk: When a T-bill matures, available rates on a new T-bill may be higher or lower than the rate you previously received.

    WHAT TO REMEMBER: Treasury bills combine short maturities with U.S. government backing, but they are not FDIC-insured deposits. Before buying one, consider when you need the money, whether you may sell early, and how taxes, inflation, and future reinvestment rates could affect the result.

    FDIC Insurance vs. Treasury Safety

    FDIC insurance and Treasury backing are sometimes discussed together when investors compare places to keep money, but they protect against different situations. FDIC insurance applies to eligible bank deposits, while Treasury bills are securities backed by the full faith and credit of the U.S. government. Treasury bills themselves are not FDIC insured.

    FactorTreasury BillsFDIC-Insured Deposits
    What you ownU.S. Treasury securityBank deposit
    FDIC coverageNoYes, when eligible and within applicable limits
    What provides protection or backing?Full faith and credit of the U.S. governmentFDIC deposit insurance
    Standard FDIC limitNot applicable$250,000 per depositor, ownership category, per insured bank
    Price risk before maturityYes, if sold before maturityA bank deposit does not trade like a Treasury security

    Why the Difference Matters

    Suppose you buy a T-bill through a bank. The bank’s FDIC-insured status does not turn that T-bill into an FDIC-insured deposit. The investment remains a Treasury security. The same principle applies when you purchase a T-bill through a brokerage.

    A brokerage account can involve SIPC protection when the brokerage is a SIPC member and the requirements for coverage are met. SIPC may protect eligible customer securities and cash when a member brokerage fails and assets are missing, subject to legal limits. It does not protect against a decline in the market value of a Treasury bill.

    THE SIMPLE VERSION: FDIC insurance covers qualifying bank deposits when an insured bank fails. Treasury bills are U.S. government securities backed by the government’s full faith and credit. SIPC, when applicable, addresses certain brokerage-firm failures. These are separate protection systems.

    Costs, Risks and Practical Tips

    Treasury bills can be relatively simple to buy, but investors should look beyond the quoted yield. Your costs and results can depend on how you purchase the security, whether you hold it until maturity, and what happens to interest rates and taxes during the investment period.

    Costs to Watch

    • TreasuryDirect purchase cost: TreasuryDirect states that it charges no purchase fee or commission when you buy Treasury securities directly through the platform.
    • Brokerage transaction costs: Depending on the broker and transaction, you may encounter commissions, markups, markdowns, or other account-related charges.
    • Taxes: Income from Treasury securities is generally subject to federal income tax but may be exempt from state and local income taxes.

    Risks to Understand

    If you sell a T-bill before maturity, its market price can be different from what you originally paid. Changes in interest rates can move that price, and a broker may apply a commission or markdown to the transaction. Inflation can also reduce the purchasing power of your return.

    PRACTICAL TIP: If you already know when you will need the money, consider a T-bill maturity that fits that time frame. If you may need the money earlier, check the possible selling costs and understand that the market price can differ from the amount you would receive at maturity.

    Common Treasury Bill Mistakes and a Real-Life Example

    Many T-bill mistakes happen because investors treat a Treasury security like a bank deposit. Understanding the difference between FDIC insurance, Treasury backing, and market pricing can help you avoid common surprises.

    Common Mistakes to Avoid

    • Assuming T-bills are FDIC insured: Treasury bills are securities, not FDIC-insured bank deposits.
    • Confusing government backing with insurance: The U.S. government’s full faith and credit is different from FDIC deposit coverage.
    • Ignoring the maturity date: Selling before maturity can expose you to changes in market price and possible transaction costs.
    • Thinking the purchase channel changes the protection: Buying a T-bill through a bank or brokerage does not turn it into an FDIC-insured deposit.
    • Forgetting reinvestment risk: When a T-bill matures, the rate available on a new T-bill may be different from the previous rate.

    Real-Life Example

    Imagine Maria has $10,000 that she expects to need in about six months. She buys a Treasury bill with a maturity that fits that time frame and plans to hold it until maturity. The T-bill is not FDIC insured, but it is a U.S. government security backed by the government’s full faith and credit. If Maria sells before maturity, its market price could be higher or lower than what she paid and could also differ from its face value.

    For example, if market interest rates rise after Maria buys the T-bill, its market price could fall. If rates decline, the market price could rise. Her result from an early sale would therefore depend on the market price at that time, along with any applicable transaction costs.

    SMART CHECK: Before buying, confirm three things: what you are buying, when you need the money, and what could happen if you sell before maturity. This helps you avoid treating a Treasury bill like a bank deposit.

    Who Should Consider Treasury Bills?

    Treasury bills can be relevant for investors looking for short-term U.S. government securities and who have a reasonably clear idea of when they may need the money. Their short maturities allow investors to match a security with a planned cash need, while their government backing distinguishes them from bank deposits and corporate debt.

    T-Bills May Be Relevant When You:

    • Want exposure to a short-term U.S. government security.
    • Have a planned or estimated cash need that matches a T-bill’s maturity.
    • Want Treasury income that is generally exempt from state and local income taxes.
    • Understand that a T-bill is a security rather than an FDIC-insured bank deposit.
    • Want to spread cash across different Treasury maturity dates.

    When a Bank Deposit May Better Match the Need

    If immediate access to cash or FDIC deposit insurance is an important requirement, an eligible bank deposit may offer a different structure. A savings account, money market deposit account, or qualifying CD does not have the same market-price mechanics as a Treasury security sold before maturity. The appropriate choice depends on your time horizon, liquidity needs, taxes, and risk considerations.

    A USEFUL CHECK: Before buying a T-bill, compare its maturity with the date you expect to need the money. If your plans change, remember that selling before maturity can expose you to market-price changes and transaction costs.

    Frequently Asked Questions About Treasury Bills and FDIC Insurance

    1. Are Treasury bills FDIC insured?

    No. Treasury bills are U.S. government securities, not bank deposits, so they are not covered by FDIC deposit insurance.

    2. If T-bills are not FDIC insured, are they government backed?

    Yes. Treasury bills are debt obligations of the U.S. Treasury and carry the full faith and credit of the U.S. government. This is different from FDIC insurance.

    3. How does Treasury backing differ from FDIC insurance?

    FDIC insurance protects qualifying bank deposits at insured institutions, subject to applicable coverage rules and limits. Treasury backing refers to the U.S. government’s obligation on Treasury securities. The two are separate protection systems.

    4. Does buying a T-bill through a bank make it FDIC insured?

    No. The purchase channel does not change the underlying security. A T-bill remains a Treasury security even when purchased through an insured bank.

    5. Are Treasury bills protected by SIPC?

    SIPC does not protect a T-bill against market losses. If a SIPC-member brokerage fails and customer securities or cash are missing, SIPC may provide protection subject to its rules and limits.

    6. Can I lose money on a Treasury bill?

    If you hold a T-bill until maturity, the Treasury pays its face value according to the security’s terms. Selling before maturity can produce a gain or loss because market prices can change.

    7. Are Treasury bill earnings subject to taxes?

    Income from Treasury securities is generally subject to federal income tax but may be exempt from state and local income taxes. Individual tax situations can vary.

    8. What is the difference between FDIC insurance and Treasury backing?

    FDIC insurance protects qualifying deposits at insured banks, subject to coverage rules and limits. Treasury backing refers to the U.S. government’s obligation on Treasury securities. They are separate protection systems.

    FAQ QUICK CHECK: The key distinction is simple: FDIC insurance covers qualifying bank deposits, while Treasury bills are U.S. government securities backed by the government’s full faith and credit.


    Final Takeaway: Are Treasury Bills FDIC Insured?

    No, Treasury bills are not FDIC insured. FDIC insurance applies to qualifying deposits at FDIC-insured banks. Treasury bills are non-deposit investment products issued by the U.S. Department of the Treasury and are backed by the full faith and credit of the U.S. government. These are two different systems and should not be treated as interchangeable.

    This distinction still matters when a T-bill is purchased through a bank. The bank’s FDIC-insured status does not make the Treasury security an FDIC-insured deposit. The same underlying security remains a Treasury bill when purchased through a brokerage.

    T-bills have short maturities and can be sold before maturity, but an early sale can expose you to changing market prices. Income from Treasury securities is generally subject to federal income tax and may be exempt from state and local taxes.

    THE BOTTOM LINE: When evaluating a Treasury bill, separate two questions: Is it FDIC insured? No. What backs the security? The full faith and credit of the U.S. government. Understanding that distinction helps you compare T-bills with bank deposits without confusing insurance with government credit backing.

    For a broader explanation of how T-bills work, see our Treasury Bills Explained guide.

    Have a Money Question? Keep Exploring.

    Questions about Treasury bills, FDIC insurance, or other ways to manage your cash? FinanceInvestment provides practical guides designed to make financial topics easier to understand.

    📩 Get in Touch With FinanceInvestment

    Have a question or a topic you’d like us to cover?

    Email FinanceInvestment

  • Are Treasury Bills Safe? Risks, Safety & 2026 Guide

    Are Treasury Bills Safe? Risks, Safety & 2026 Guide

    Are Treasury Bills Safe?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 24, 2026
    Updated: Sep 24, 2026
    Reading Time: 11–13 min
    A practical guide to Treasury bill safety, government backing, risks, and what investors should know before buying.


    Are Treasury Bills Safe? A Beginner’s Guide

    Are Treasury Bills Safe?Are Treasury Bills Safe? For many investors, the answer is that T-bills are considered among the safest investments available. They are short-term debt securities issued by the U.S. Department of the Treasury and backed by the full faith and credit of the U.S. government.

    Still, safe does not mean risk-free in every sense. Your experience can change depending on whether you hold the bill until maturity or sell it earlier. Inflation can also reduce the purchasing power of your return, while changing interest rates can affect a T-bill’s market value before maturity. 2

    This guide looks beyond the simple “safe or unsafe” question. You’ll see what protects T-bill investors, what risks remain, how buying through a brokerage differs from buying directly, and how Treasury bills compare with other short-term cash options.

    What You’ll Learn

    • Why Treasury bills are considered very low-credit-risk investments.
    • What the U.S. government’s backing means for T-bill investors.
    • What generally happens when you hold a Treasury bill until maturity.
    • How inflation, interest rates, and an early sale can affect your investment.
    • Why Treasury bills are securities rather than FDIC-insured bank deposits.
    • How T-bills compare with money market accounts and other short-term options.

    For a broader introduction before going deeper, read our Treasury Bills Explained guide.

    Quick Answer: Are Treasury Bills Safe?

    The short answer: Treasury bills are considered among the safest investments because they are short-term U.S. government securities backed by the full faith and credit of the U.S. government. However, that does not mean they are completely free of investment risk. Inflation can reduce purchasing power, and selling before maturity can expose you to changes in market value.

    Key Takeaways

    • Very low credit risk: T-bills are direct obligations of the U.S. Department of the Treasury.
    • Maturity matters: If you hold a T-bill to maturity, the Treasury generally pays its face value according to the security’s terms.
    • Early sale can change the outcome: A T-bill sold before maturity can be worth more or less than its face value.
    • Inflation still matters: Rising prices can reduce the purchasing power of the money you receive.
    • Not FDIC insured: T-bills are government securities, not bank deposits covered by FDIC deposit insurance.
    • Brokerage and Treasury protection are different: Buying a T-bill through a brokerage does not make the security an FDIC-insured deposit.
    • Taxes still apply: Treasury interest is generally subject to federal income tax, while qualifying Treasury interest is generally exempt from state and local income taxes.

    BOTTOM LINE: T-bills have very low credit risk, but “safe” does not mean “no risk.” Your result can depend on your holding period, need for liquidity, market conditions, and inflation.

    Table of Contents

    Are Treasury Bills Safe? At a Glance

    Treasury bills are short-term U.S. government securities. They are considered among the safest investments because they are backed by the full faith and credit of the U.S. government. Still, “safe” does not mean every possible risk disappears. Inflation can reduce purchasing power, and selling before maturity can expose you to changes in market value.

    Quick Facts

    • Issuer: U.S. Department of the Treasury
    • Maturity: Short-term bills with maturities ranging from a few days to 52 weeks
    • Minimum purchase: $100 for TreasuryDirect purchases and current Treasury bill offerings
    • At maturity: A T-bill held to maturity generally pays its face value according to its terms
    • Interest structure: T-bills are generally sold at a discount, with the difference between the purchase price and face value representing the return
    • Federal taxes: Treasury interest is generally subject to federal income tax
    • State and local taxes: Treasury interest is generally exempt from state and local income taxes

    Best For

    T-bills may be relevant for investors seeking a short-term government security with a defined maturity and very low credit risk. They can also be useful when an investor wants to hold a Treasury security until maturity rather than depend on stock-market performance for short-term cash needs.

    Safety FactorWhat It Means
    Credit riskVery low because T-bills are obligations of the U.S. government
    Early-sale riskThe market value can be above or below face value before maturity
    Inflation riskInflation can reduce the purchasing power of the return
    FDIC insuranceNot applicable; T-bills are Treasury securities, not bank deposits

    QUICK TAKE: T-bills have very low credit risk, but it helps to separate credit risk from market-value and inflation risks. The distinction becomes especially important if you may need to sell before maturity.

    Complete Beginner Guide to Treasury Bill Safety

    Are Treasury Bills Safe?If you are new to T-bills, the easiest way to understand their safety is to separate the issuer’s ability to meet its obligation from what can happen to the investment before maturity. Treasury bills are debt obligations issued by the U.S. Department of the Treasury and are considered among the safest investments because they carry the full faith and credit of the U.S. government.

    1. What Makes Treasury Bills Safe?

    A Treasury bill is a short-term U.S. government security. Because it is a Treasury obligation, its credit risk is generally considered very low. That is different from investments whose repayment depends on the financial condition of a private company or other issuer.

    2. What Happens If You Hold a T-Bill to Maturity?

    Treasury bills are generally sold at a discount or, in some cases, at face value. When a bill reaches maturity, Treasury pays its face value according to the security’s terms. For a discounted bill, the difference between what you paid and the face value is the interest earned.

    3. Can You Lose Money on a T-Bill?

    It depends on when you sell. If you sell a T-bill before maturity, its market price can be above or below face value. Changes in market interest rates can affect that price, so an early sale may produce a gain or a loss compared with your purchase price.

    4. What About Inflation?

    Even if a T-bill pays according to its terms, inflation can reduce the purchasing power of the money you receive. This is different from credit risk: the Treasury may meet its obligation while your dollars still buy less than they did when you invested.

    5. Are T-Bills the Same as a Bank Deposit?

    No. A T-bill is a Treasury security, not a bank deposit. It is therefore not covered by FDIC deposit insurance. Buying the security through a bank or brokerage does not change what the investment is; the T-bill remains a Treasury obligation.

    EASY WAY TO THINK ABOUT IT: T-bill safety starts with the strength of the issuer. The main risks to understand separately are market-value changes before maturity and the loss of purchasing power caused by inflation.

    How Treasury Bill Safety Works

    A T-bill’s safety is easier to understand when you follow what happens from purchase through maturity. The important distinction is between the U.S. government’s obligation and the market risks an investor can face before the bill matures.

    Step 1: You Buy a U.S. Government Security

    When you buy a Treasury bill, you are purchasing a short-term debt obligation issued by the U.S. Department of the Treasury. Treasury securities carry the full faith and credit of the U.S. government, which is why they are considered among the safest

    Step 2: The Bill Has a Defined Maturity

    Treasury bills are short-term securities with maturities ranging from a few days to 52 weeks. They are generally issued at a discount, although Treasury bills can also be issued at par depending on auction results. Unlike Treasury notes and bonds, T-bills do not make regular coupon payments.

    Step 3: Maturity Changes the Risk Picture

    If you hold the T-bill until maturity, Treasury pays the bill’s face value according to its terms. This means temporary changes in the market price do not determine the maturity payment. The situation is different if you sell before maturity because the market price can be higher or lower than the amount you originally paid.

    Step 4: Interest Rates Can Affect an Early Sale

    Market interest rates can influence the price of a Treasury security before maturity. If rates rise, existing securities can become less attractive relative to newly issued securities, which can push their market prices lower. The opposite can happen when rates fall.

    Step 5: Inflation Is a Separate Risk

    A T-bill can pay according to its terms while inflation still reduces the purchasing power of the money you receive. So, government credit safety and purchasing-power protection are two different questions.

    THE SIMPLE VERSION: Treasury backing addresses the security’s credit risk. Holding to maturity avoids relying on the market price at the time of sale, but it does not eliminate inflation risk or other investment considerations.

    Benefits & Drawbacks of Treasury Bills

    Treasury bills offer several features that can appeal to investors who want a short-term U.S. government security. But low credit risk does not remove every trade-off. The right way to evaluate a T-bill is to look at both its safety characteristics and the risks that remain.

    Benefits

    • Very low credit risk: T-bills are obligations of the U.S. government and carry its full faith and credit.
    • Short, defined maturities: Treasury bills mature from a few days to 52 weeks, giving investors a specific date for repayment.
    • Face-value repayment at maturity: When held to maturity, Treasury pays the bill’s face value according to its terms.
    • State and local tax treatment: Income from Treasury securities is generally exempt from state and local income taxes, although federal income tax generally applies.

    Drawbacks

    • Inflation risk: Inflation can reduce the purchasing power of the money you receive at maturity.
    • Early-sale risk: If you sell before maturity, the T-bill’s market value can be higher or lower than your purchase price.
    • Reinvestment risk: When a T-bill matures, the yield available on a new bill may be higher or lower than the yield you previously received.
    • No FDIC deposit insurance: T-bills are Treasury securities, not bank deposits, so FDIC deposit insurance does not apply.

    WHAT TO REMEMBER: Treasury bills combine very low credit risk with a defined maturity, but investors still need to consider inflation, market pricing before maturity, and the yield available when the money is reinvested.

    Treasury Bills Safety Comparison Table

    Treasury bills are often compared with other short-term places to keep money, but “safe” can mean different things. Government backing, deposit insurance, access to funds, and market-value changes are separate factors. This comparison focuses on those differences rather than labeling one option as universally safer.

    Safety FactorTreasury BillsMoney Market AccountCDMoney Market Fund
    What it isShort-term U.S. government debt securityBank deposit accountBank time depositMutual fund investing in short-term securities
    FDIC insuranceNoGenerally yes, if held at an FDIC-insured bank and within applicable limitsGenerally yes, if held at an FDIC-insured bank and within applicable limitsNo
    Value before maturityMarket price can change if sold before maturityAccount balance is not marked to a daily market priceUsually accessed through withdrawal or maturity terms rather than daily market tradingShare value depends on the fund’s holdings and applicable valuation rules
    Access to moneyCan generally be sold before maturity, subject to market conditionsGenerally accessible under the account’s termsEarly withdrawal may involve penalties or restrictionsShares are generally redeemable under the fund’s rules
    Main risksInflation, early-sale price changes, and reinvestment riskBank exposure beyond applicable insurance coverage and changing interest ratesEarly-withdrawal restrictions, changing rates, and inflationMarket, interest-rate, liquidity, and inflation-related risks

    One distinction deserves special attention: a money market account, also called a money market deposit account, is a bank deposit that may qualify for FDIC insurance. A money market fund is a mutual fund and is not FDIC-insured. Treasury bills are also not FDIC-insured because they are securities rather than bank deposits.

    COMPARE THE RIGHT FACTORS: Look beyond the word “safe.” Consider who owes you the money, whether government deposit insurance applies, how easily you can access the funds, whether the value can change before you need the money, and how inflation may affect your purchasing power.

    Costs, Risks & Expert Tips for Treasury Bills

    Treasury bills have very low credit risk, but the advertised yield is not the only factor to consider. How you buy the bill, whether you sell before maturity, taxes, inflation, and your reinvestment plan can all affect the overall result.

    Costs to Watch

    • TreasuryDirect purchase costs: TreasuryDirect states that it charges no purchase fee or commission when you buy marketable Treasury securities directly through the platform.
    • Brokerage transaction costs: If you sell a T-bill before maturity through a broker, the transaction may involve a commission or a markdown in the sale price. Check the broker’s pricing before placing the order.
    • Taxes: Treasury income is generally subject to federal income tax but is generally exempt from state and local income taxes.

    Risks That Still Matter

    The main risks include inflation, changes in market value before maturity, and reinvestment risk. If market interest rates change after you buy a bill, its price can move before maturity. Selling at that point can produce a different result from simply holding the bill until maturity.

    Practical Tips

    • Match maturity to your cash need: Choose a maturity that fits when you expect to use the money.
    • Plan for early access: If you may need the cash before maturity, understand how market pricing could affect the amount you receive.
    • Look at the after-tax result: Compare the return after considering applicable federal taxes and your state’s tax treatment of other investments.
    • Consider a T-bill ladder: Multiple maturity dates can spread out when your money becomes available instead of concentrating everything in one maturity.

    SMART CHECK: Before buying, ask three questions: When will I need the money? Can I reasonably hold the bill until maturity? And what costs, taxes, and reinvestment choices will apply afterward?

    Common Treasury Bill Mistakes + Real-Life Example

    Treasury bills are relatively simple once you understand how they work, but a few mistakes can lead to unexpected results. The biggest issue is assuming that low credit risk means there are no other risks to consider.

    Common Mistakes to Avoid

    • Assuming T-bills have no risk: They have very low credit risk, but inflation and market-value risk before maturity still matter.
    • Confusing T-bills with FDIC-insured deposits: Treasury bills are securities, not bank deposits, so FDIC deposit insurance does not apply.
    • Ignoring the maturity date: If you need the money before maturity, you may have to sell the bill at its current market price.
    • Expecting the market value to stay unchanged: A T-bill’s price can move before maturity as market conditions and interest rates change.
    • Forgetting reinvestment risk: The yield available when the bill matures may be different from the yield on your original purchase.

    Real-Life Example: A Hypothetical $10,000 T-Bill

    Suppose an investor buys a hypothetical T-bill with a $10,000 face value for $9,800. The $200 difference represents the gross discount, or return, if the bill is held to maturity. This is only an illustration; actual Treasury bill prices depend on the applicable auction or market price.

    If the investor holds the bill until maturity, Treasury pays the $10,000 face value according to the security’s terms. But suppose the investor needs the money early and sells when the market price is $9,850. The investor would receive $9,850 before any applicable transaction costs, rather than waiting for the $10,000 maturity payment. A sale before maturity can produce a higher or lower amount depending on market conditions.

    THE LESSON: A T-bill can have very low credit risk while still carrying inflation and early-sale market risks. Knowing your maturity date and having a plan for the money can help you avoid selling simply because you need cash unexpectedly.

    Who Should Consider Treasury Bills?

    Treasury bills may be relevant for investors who have a short-term financial need, want a defined maturity date, or prefer a U.S. government security with very low credit risk. T-bills mature in periods ranging from a few days to 52 weeks, so the maturity can be matched with a specific short-term cash need.

    T-Bills May Be Relevant If You:

    • Want exposure to a short-term U.S. government security.
    • Know approximately when you expect to use the money.
    • Prefer a defined maturity rather than an investment with an uncertain end date.
    • Want Treasury income that is generally exempt from state and local income taxes.
    • Can reasonably hold the bill until maturity and avoid relying on an early sale.

    When Another Option May Fit the Goal

    T-bills are not designed for every financial objective. Money needed immediately may call for an option with different access features, while long-term growth goals may require a broader investment approach. Investors specifically focused on inflation protection can also research Treasury Inflation-Protected Securities (TIPS). TIPS are Treasury notes and bonds whose principal is adjusted based on changes in the Consumer Price Index, making them different from short-term T-bills.

    KEY POINT: Instead of asking only whether T-bills are safe, consider whether the bill’s maturity, access requirements, return, and inflation characteristics fit the specific purpose of your money.

    Frequently Asked Questions About Treasury Bill Safety

    1. Are Treasury bills safe?

    Treasury bills are considered among the safest investments because they are short-term U.S. government securities backed by the full faith and credit of the U.S. government. However, inflation and market-value risks before maturity still apply.

    2. Can you lose money on Treasury bills?

    If you sell a T-bill before maturity, its market price can be higher or lower than what you paid. If you hold it until maturity, Treasury pays the bill’s face value according to its terms.

    3. Are Treasury bills guaranteed?

    Treasury bills are obligations of the U.S. government and carry its full faith and credit. This supports their very low credit risk, but it does not protect an investor from inflation or a potential market-price loss on an early sale.

    4. Are Treasury bills FDIC insured?

    No. Treasury bills are securities rather than bank deposits, so FDIC deposit insurance does not apply to the T-bill itself.

    5. What happens if I sell a Treasury bill before maturity?

    You sell it at its current market price, which can be above or below your purchase price. Interest-rate and market conditions can affect that price, and a brokerage transaction may also involve applicable costs.

    6. What happens to Treasury bills if a brokerage fails?

    If a Treasury bill is held at a SIPC-member brokerage, Treasury securities are among the securities that SIPC can protect when the brokerage fails and customer assets are missing, subject to applicable rules and limits. SIPC protection is generally up to $500,000 per customer, including a $250,000 limit for cash. SIPC does not protect against a decline in the market value of an investment.

    7. Are Treasury bills safe during a recession?

    Treasury bills remain U.S. government debt securities during a recession. Their government backing does not disappear because economic conditions weaken. However, market yields and prices can still change as interest rates and investor demand change.

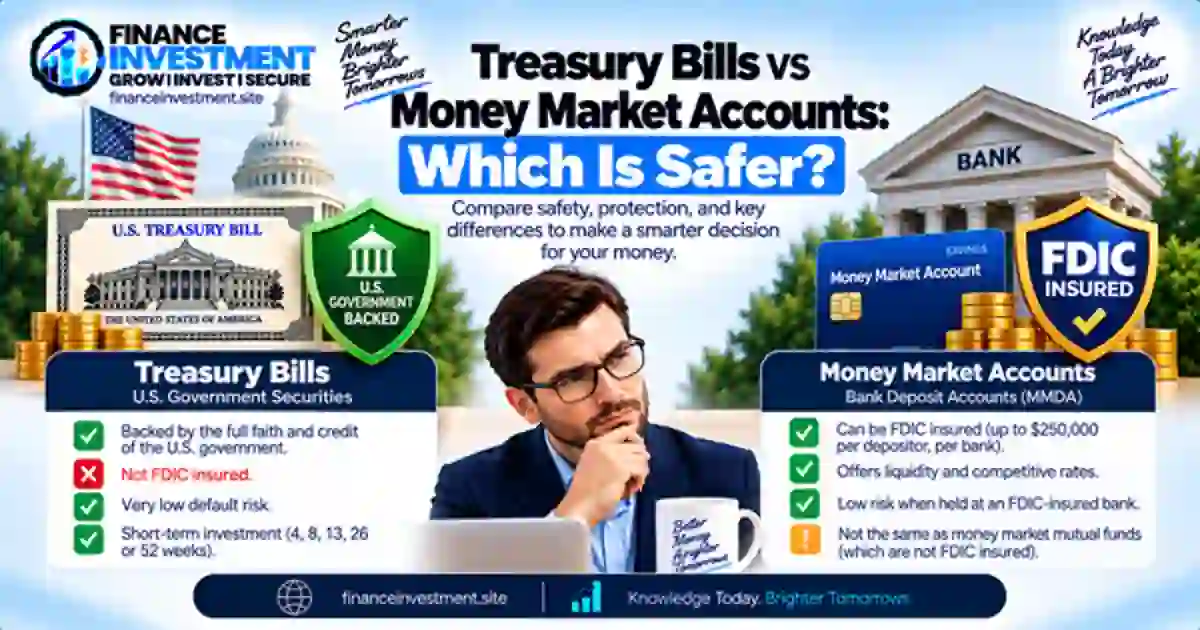
    8. Are Treasury bills safer than money market accounts?

    They have different forms of protection. T-bills are U.S. government securities backed by the government’s full faith and credit. A money market account is a bank deposit that may qualify for FDIC insurance when held at an insured bank and within applicable limits. The two should therefore be compared by issuer, insurance, maturity, access, and market risks rather than by one overall safety label.

    FAQ SUMMARY: Treasury bills have very low credit risk, but investors should still understand early-sale pricing, inflation, taxes, reinvestment, and the protections that apply when securities are held through a brokerage.


    Final Verdict: Are Treasury Bills Safe?

    Are Treasury Bills Safe? Treasury bills are considered among the safest investments because they are short-term U.S. government debt securities backed by the full faith and credit of the U.S. government. Their short maturities also generally limit the period during which an investor may be exposed to market-price changes before maturity.

    Still, safe does not mean completely free of investment risk. If you sell before maturity, the T-bill’s market value can be higher or lower than the amount you paid. Inflation can also reduce the purchasing power of the money you receive.

    For a broader explanation of how these securities work, see our Treasury Bills Explained guide.

    BOTTOM LINE: T-bills offer very low credit risk, but investors should still consider maturity, early-sale pricing, inflation, taxes, and their specific cash needs before investing.

    Have a Money Question? Keep Exploring.

    Understanding Treasury bill safety is one part of making informed short-term investing decisions. Keep exploring Treasury bill maturities, buying methods, yields, and other cash-management topics to better understand your options.

    📩 Get in Touch With FinanceInvestment

    Have a finance topic you’d like us to explain? Send your question or feedback by email.

    Email FinanceInvestment

    Continue Your Research