Category: Investing

  • Treasury Bills for Short-Term Savings Goals: 2026 Guide

    Treasury Bills for Short-Term Savings Goals: 2026 Guide

    Treasury Bills for Short-Term Savings Goals

    Subhash Rukade
    Founder, FinanceInvestment


    Published: Sep 26, 2026


    Updated: Sep 26, 2026


    Reading Time: 12–14 min


    Treasury Bills for Short-Term Savings Goals: Matching Your Money to the Date You Need It
    Treasury Bills for Short-Term Savings Goals Treasury Bills for Short-Term Savings Goals can make sense when you are setting money aside for something you expect to pay for within the next several months or year. Maybe you are building a down payment, planning a family vacation, replacing a vehicle, paying a large insurance bill, or preparing for a tuition payment. Unlike a general savings balance, this money already has a purpose.

    That makes the timing especially important. Treasury bills are short-term U.S. government securities with specific maturity dates. So instead of looking at the yield first, it can be more useful to start with the date you expect to need the money. The closer the investment timeline matches the goal, the easier it becomes to plan around the maturity.

    If Treasury bills are new to you, our Treasury Bills Explained guide covers the basics, including what T-bills are and how they work.

    What You’ll Learn

    • How Treasury bills can fit different short-term savings goals.
    • How to think about maturity dates when a future expense has a known deadline.
    • Why access to your money still matters even when you have a planned goal.
    • How T-bills compare with savings accounts, money market accounts and CDs.
    • How taxes, early sales and changing rates can affect the amount available for your goal.
    • Which common mistakes can make a short-term savings strategy harder to manage.

    The idea is straightforward: give your short-term savings a clear purpose and choose an option that fits the date and access you need. A T-bill can be part of that plan, but the maturity should work with your goal rather than the other way around.

    Quick Answer: Can Treasury Bills Work for Short-Term Savings Goals?

    Yes, Treasury bills can fit certain short-term savings goals when the maturity date works with the date you expect to need the money. They can provide a defined timeline for money set aside for a planned expense. But a T-bill is a security, not a bank-account balance. If you need the funds before maturity, a marketable T-bill can generally be sold, but its market price may differ from what you originally paid.

    Key Takeaways

    • Begin with the goal date: Know roughly when the money will be needed before choosing a T-bill term.
    • Match the maturity: The bill’s maturity should fit comfortably within your planned savings timeline.
    • Leave room for changes: A planned expense can move earlier, later, or change in size.
    • Know what you are buying: T-bills are Treasury securities, not FDIC-insured bank deposits.
    • Understand early-sale risk: Selling before maturity can expose you to changes in the T-bill’s market price.
    • Watch the next rate: Reinvesting after maturity does not guarantee the same yield as the original bill.
    • Remember the tax difference: Treasury interest is generally subject to federal income tax and generally exempt from state and local income taxes.

    BOTTOM LINE: Treasury bills can be one option for money with a defined short-term purpose. The important part is to make the maturity work around your savings goal, while keeping enough accessible money for expenses that may arrive sooner than expected.

    Table of Contents

    Treasury Bills for Short-Term Savings Goals at a Glance

    Treasury bills can fit a short-term savings plan when you have a defined goal and a reasonably clear spending timeline. Because a T-bill has a set maturity date, the calendar matters almost as much as the return. A useful starting point is to decide when the money will be needed and how much flexibility you have around that date.

    Quick FactWhat It Means for Your Savings Goal
    Best ForPlanned expenses where the money can remain invested for a defined short period.
    Key NumberTreasury bills have maturities of one year or less.
    Planning WindowChoose a maturity that gives you enough time to reach the goal without creating an awkward cash gap.
    Before MaturityA marketable T-bill can generally be sold before maturity, but its market price can change.
    Tax TreatmentTreasury interest is generally subject to federal income tax and exempt from state and local income taxes.
    Main Planning CheckAsk whether you can leave the money invested until the selected maturity date.

    Examples of Short-Term Savings Goals

    A planned vehicle purchase, vacation, home repair, insurance premium, tuition payment, or estimated tax bill could have a defined spending date. For these goals, the important comparison is not simply which option offers a higher return. You also need to consider access, timing, taxes, and what happens if the expense moves earlier than expected.

    Complete Beginner Guide to Using Treasury Bills for Short-Term Savings Goals
    Treasury Bills for Short-Term Savings GoalsIf Treasury bills are new to you, begin with the goal rather than the security. Write down what you are saving for, the amount you expect to need, and roughly when you expect to spend it. Once those three pieces are clear, you can decide whether a T-bill fits the timeline.

    1. Define the Goal and Target Amount

    Start with a realistic estimate. For example, if you are building a $12,000 fund for a vehicle purchase, consider whether the final cost could change before you buy. Also decide whether the entire amount needs to be available on one date or whether you may spend it in stages.

    2. Mark the Expected Spending Date

    Put the expected payment date on your calendar. If the deadline is firm, leave some room between the T-bill maturity and the actual payment date. That cushion can help if the purchase date changes or the funds take time to become available through your chosen account.

    3. Choose a Term That Fits the Timeline

    Treasury bills are short-term securities with defined maturities. Compare the available term with your goal date and ask how long you can comfortably leave the money invested. A maturity that looks convenient on paper may be less useful if your spending date is uncertain.

    4. Decide Where to Buy and Hold the T-Bill

    Treasury bills can be purchased through TreasuryDirect or through a brokerage that offers Treasury securities. Before buying, check how the account handles maturity proceeds and what you would need to do if your plans change. Our How to Buy Treasury Bills guide covers the basic purchase process.

    5. Recheck the Goal Before Maturity

    As maturity approaches, look at the original goal again. If the expense is coming up, the proceeds may need to remain accessible. If the goal has been delayed, you can reassess the money instead of automatically rolling it into another T-bill.

    BEGINNER TIP: Put the goal date on your calendar before you buy the T-bill. The investment should fit your timeline, including a reasonable cushion, rather than making the timeline fit the investment.

    How Treasury Bills Work for Short-Term Savings Goals

    A Treasury bill is a short-term debt security issued by the U.S. Department of the Treasury. T-bills mature in one year or less, so the maturity date becomes an important part of any plan built around a future expense.

    1. You Buy the Bill at a Discount

    T-bills are generally issued at a price below their face value. You pay the purchase price when you buy the bill. If you hold it until maturity, the Treasury pays the face value according to the security’s terms. The difference between the purchase price and face value represents the bill’s discount.

    2. The Auction Establishes the Price

    Treasury bills are sold through auctions. A noncompetitive bidder does not choose a specific discount rate. Instead, the investor agrees to accept the rate determined by the auction and receives the requested amount, subject to the Treasury’s auction rules.

    That auction process is why the amount paid for a T-bill can be below its face value. Treasury bills do not send regular interest payments during the term like many coupon-paying bonds. The return is reflected in the difference between the purchase price and the amount paid at maturity.

    3. Maturity Creates a Planned Cash Point

    When the T-bill reaches maturity, it becomes due and the face value is paid according to its terms. For a short-term savings goal, this creates a specific point when the invested money can be directed toward the planned expense.

    4. Selling Before Maturity Changes the Calculation

    A marketable T-bill can generally be sold before maturity through the secondary market. However, the price at that time can be different from what you originally paid. Changes in market interest rates can affect the security’s market value, so an early sale may produce a different result from simply holding the bill to maturity.

    5. The Goal Date Still Comes First

    For goal-based saving, the mechanics are useful only when they fit the plan. If you expect to spend the money around a particular date, consider the maturity date, the time needed to access the proceeds, and what you would do if the expense arrives earlier than expected.

    PRACTICAL POINT: A T-bill has a purchase date, a maturity date and a market value between those dates. For a short-term savings goal, keeping track of all three helps you understand what your money is doing before the planned expense arrives.

    Benefits and Drawbacks of Using Treasury Bills for Short-Term Savings Goals

    Treasury bills can work well with some planned savings goals, but they come with a different set of trade-offs than an ordinary savings account. Their defined maturity can help organize money for a future expense, while the security’s market value and access process matter if your plans change.

    Potential Benefits

    • Defined maturity: A known maturity date can help you organize savings around a planned expense.
    • Short-term terms: T-bills have maturities of one year or less, which can fit certain near-term goals.
    • U.S. Treasury security: T-bills are securities issued by the U.S. Department of the Treasury.
    • State and local tax treatment: Treasury interest is generally exempt from state and local income taxes.

    Potential Drawbacks

    • Less convenient than cash: A T-bill follows a security and maturity process rather than working like an ordinary bank-account balance.
    • Early-sale market risk: If you sell before maturity, the market price may differ from your original purchase price.
    • Changing goal dates: An expense may arise earlier than expected, creating a need for funds before maturity.
    • Reinvestment uncertainty: A new T-bill purchased after maturity may have a different yield.

    WATCH THE TIMING: Even a carefully planned savings goal can move. Before buying a T-bill, consider whether you have another accessible source of money if the expense arrives sooner than expected.

    Treasury Bills vs. Other Short-Term Savings Options

    When you are saving for a near-term expense, the product should match the way you expect to use the money. Treasury bills have a defined maturity, while savings accounts and money market deposit accounts generally do not. CDs also have a set term, but their withdrawal rules are different from those of Treasury securities.

    OptionAccessTime StructureFDIC InsurancePotential Use
    Treasury BillsHold to maturity or sell a marketable bill before maturityDefined maturity of one year or lessNoA planned goal that can accommodate a defined maturity
    Savings AccountGenerally convenient access, subject to account termsNo fixed maturityGenerally yes, when held as an eligible deposit at an FDIC-insured bank and within applicable limitsGoals where flexibility and access matter
    Money Market Deposit AccountGenerally convenient access, subject to account termsNo fixed maturityGenerally yes, when held as an eligible deposit at an FDIC-insured bank and within applicable limitsSavings that may need accessible cash features
    Certificate of DepositAccess before maturity depends on the CD’s terms and may involve an early-withdrawal penaltyFixed termGenerally yes, when held as an eligible deposit at an FDIC-insured bank and within applicable limitsMoney that can remain committed for a specified period

    QUICK COMPARISON: Treasury bills and CDs both have defined terms, while savings accounts and money market deposit accounts generally do not. T-bills are Treasury securities rather than FDIC-insured deposits. The useful choice depends on your goal date, access needs, and the rules attached to the account or security.

    Costs, Risks and Expert Tips for Short-Term Savings Goals

    Before putting money into a Treasury bill, look beyond the advertised yield. Your decision can involve account costs, tax treatment, access rules, market prices and the timing of the expense you are saving for.

    Costs and Financial Considerations

    • TreasuryDirect purchases: The U.S. Treasury states that it does not charge a purchase fee or commission when you buy Treasury securities through TreasuryDirect.
    • Brokerage charges: Costs and trading policies can vary by brokerage, so check the firm’s current terms before placing an order.
    • Taxes: Treasury interest is generally subject to federal income tax but generally exempt from state and local income taxes.

    Risks to Keep in Mind

    • Timing risk: The savings goal could arrive before the T-bill reaches maturity.
    • Market-price risk: If you sell a marketable T-bill before maturity, the amount received can differ from the original purchase price.
    • Reinvestment risk: If you use the proceeds to buy another T-bill, the new security may have a different yield.
    • Access risk: The steps for getting money before maturity can depend on whether the T-bill is held through TreasuryDirect or a brokerage.

    EXPERT TIP: If a savings goal has a firm payment date, give yourself a cushion. A T-bill that matures shortly before the expense can provide more breathing room than one scheduled to mature on the exact day you need the money.

    Common Mistakes and a Real-Life Short-Term Savings Example

    A short-term savings plan can become complicated when the investment gets more attention than the goal itself. With Treasury bills, the most common mistakes involve timing, access and what happens after the bill matures.

    Common Mistakes to Avoid

    • Choosing the maturity first: Picking a T-bill term before identifying the date you expect to spend the money can put the investment schedule ahead of the actual goal.
    • Putting the entire goal amount into one bill: If the spending date changes, having no other accessible funds can make the plan less flexible.
    • Using the exact payment date as the maturity date: A little time between maturity and the planned expense can give you more breathing room.
    • Assuming early sale works like a withdrawal: Selling a marketable T-bill before maturity is a market transaction, and the price can differ from the original purchase price.
    • Reinvesting without checking the goal: Once a T-bill matures, first ask whether the money is still needed for the original purpose before buying another one.

    Illustrative Example: A $15,000 Home Project

    Imagine a family expects to spend $15,000 on a home renovation several months from now. Instead of starting with a T-bill maturity, they first estimate when the contractor will need the money. They can then compare that date with available T-bill terms and decide whether the timing gives them enough room.

    If the renovation is delayed, the family can reassess the money when the T-bill matures rather than automatically reinvesting it. If the project moves forward earlier, an accessible cash reserve can reduce the need to sell the T-bill before maturity.

    IMPORTANT: The $15,000 figure is only an illustration. It is not a recommended amount or allocation. A short-term savings plan should reflect the actual goal, payment date, available cash and personal circumstances.

    Who Should Consider Treasury Bills for Short-Term Savings Goals?

    Treasury bills may fit savers who have a defined goal, a reasonably clear timeline and enough flexibility to leave the money invested until maturity. The main question is not simply how much a T-bill may earn. It is whether its maturity and access characteristics fit the way the money will be used.

    This Approach May Fit

    • People saving for a planned expense within one year who can work with a defined maturity date.
    • Families setting aside money for expenses such as tuition, insurance payments, travel or a planned purchase.
    • Savers who want to keep money for a specific goal separate from their everyday spending funds.
    • Investors who understand that selling a marketable T-bill before maturity can result in a market price different from the original purchase price.

    When Another Option May Fit Better

    A savings account or money market deposit account may fit better when the spending date is uncertain and convenient access to cash is a priority. A CD may also be worth comparing when you are comfortable with a fixed term and want to consider bank-deposit features. The useful comparison depends on the goal, timeline, access needs and account or security terms.

    QUICK CHECK: Before choosing a T-bill, ask three questions: When will I need the money? Can I leave it invested until maturity? What other accessible funds would I have if the goal arrives earlier?

    Frequently Asked Questions About Treasury Bills for Short-Term Savings Goals

    Are Treasury bills suitable for short-term savings goals?

    Treasury bills can fit a short-term savings goal when the maturity date lines up with the expected spending timeline. They may be less convenient when the money could be needed unexpectedly before maturity.

    What is the shortest Treasury bill term?

    Treasury bills are available in several short-term maturities, including 4-week, 6-week, 8-week, 13-week, 17-week, 26-week and 52-week bills. Availability can depend on the Treasury’s current offerings.

    Can I sell a Treasury bill before maturity?

    Yes, a marketable Treasury bill can generally be sold before maturity. If the bill is held in TreasuryDirect, however, it must first be transferred to a bank, broker or dealer because TreasuryDirect does not directly sell marketable securities for you. A TreasuryDirect purchase also has a 45-day holding period before a newly issued marketable security can generally be transferred or sold.

    Are Treasury bills taxable?

    Interest income from Treasury bills is subject to federal income tax but is exempt from state and local income taxes. Treasury bill interest is reported as Treasury interest on Form 1099-INT.

    Are Treasury bills FDIC insured?

    No. Treasury bills are securities issued by the U.S. Treasury, not deposits at an FDIC-insured bank. They therefore do not receive FDIC deposit insurance.

    What happens when a Treasury bill matures?

    At maturity, the Treasury pays the bill’s face value according to its terms. If you hold the bill through TreasuryDirect, you can generally receive the proceeds or arrange for the money to be reinvested in another Treasury security. The appropriate choice depends on whether the original savings goal still requires the money.

    FAQ TIP: For a short-term savings goal, check the maturity date, access rules, tax treatment and planned spending date together. Looking at only the quoted yield can leave out details that matter to the goal.


    Final Verdict: Evaluating Treasury Bills for a Short-Term Savings Goal

    Treasury bills can be considered for a short-term savings goal when the amount has a defined purpose and the selected maturity fits the expected spending timeline. The fixed maturity provides a specific date for planning, while the security’s access and market-price characteristics need to be considered if plans change.

    They are different from an ordinary savings balance. If the goal date is uncertain or the money may be needed before maturity, a savings account or money market deposit account offers a different access structure. A CD can also be compared when a fixed bank-deposit term fits the planned use of the money.

    THE KEY IDEA: Start with the purpose and expected date for the money. Then consider the T-bill’s maturity, access options, tax treatment and potential risks before deciding how it fits into the savings plan.

    The goal is to keep the investment timeline aligned with the planned use of the money. If the timeline, access needs or purpose changes, reassess the savings arrangement rather than assuming the original plan still fits.

    Have a Money Question? Keep Exploring.

    A short-term savings goal becomes easier to plan when you know when the money is needed, how much access you may require and when your investment matures. Keep those details in view as you compare your options.

    📩 Get in Touch With FinanceInvestment

    Email FinanceInvestment

    Continue Your Research

    Treasury Bills Explained
    •
    How to Buy Treasury Bills

  • Treasury Bills for Emergency Funds in 2026: What to Know

    Treasury Bills for Emergency Funds in 2026: What to Know

    Treasury Bills for Emergency Funds

    Subhash Rukade
    Founder, FinanceInvestment

    Published: Sep 26, 2026

    Updated: Sep 26,   2026

    Reading Time: 12–14 min


    Treasury Bills for Emergency Funds: A Practical Starting Point

    Treasury Bills for Emergency FundsTreasury Bills for Emergency Funds can be worth considering if you want part of your short-term reserves invested in U.S. government securities. But an emergency fund has a different priority from a regular investment account: you need to be able to reach the money when an unexpected bill arrives.

    That is why liquidity matters before yield. A T-bill has a stated maturity date, while cash in a checking or savings account can generally be accessed without waiting for a security to mature. Some people may therefore keep their most immediate emergency cash in an accessible account and use shorter-term T-bills for money they may not need right away.

    If Treasury bills are new to you, our Treasury Bills Explained guide is a useful starting point. It covers what T-bills are and how they work before you decide whether they fit your emergency-fund plan.

    What You’ll Learn

    • Where T-bills can fit within an emergency-fund strategy.
    • Why immediate access can matter more than yield for emergency cash.
    • How T-bill maturities affect when invested money becomes available.
    • The potential benefits and drawbacks of using T-bills.
    • How T-bills compare with savings and money market accounts.
    • What to consider before using T-bills for unexpected expenses.

    The central question is not simply whether T-bills are safe or offer a competitive return. It is whether the maturity, access, and structure of the investment match the kind of emergency you are preparing for.

    Quick Answer: Can Treasury Bills Be Used for Emergency Funds?

    Yes, Treasury bills can be part of an emergency-fund strategy, but they may not be suitable for every portion of your reserve. Emergency money needs dependable access. Because a T-bill has a maturity date, it can require more planning than cash held in an accessible bank account. Keeping some emergency savings readily available can reduce the chance of needing to sell a T-bill at an inconvenient time.

    Key Takeaways

    • Liquidity matters: The money you may need immediately should be easy to access without relying on a security sale.
    • Maturity dates matter: A T-bill follows a defined maturity schedule, so the timing should fit your expected cash needs.
    • Shorter maturities offer more frequent planning points: They can give you more opportunities to reassess the money as bills mature.
    • You can split your emergency reserves: Some money can remain in an accessible account while another portion is allocated to short-term T-bills.
    • Early sales carry market-price risk: If you sell a marketable T-bill before maturity, the amount you receive may be different from your purchase price.
    • Future yields can change: Reinvesting after maturity does not guarantee the same yield as the original T-bill.
    • Tax treatment is different from bank interest: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    BOTTOM LINE: T-bills can be one component of an emergency-fund plan. The key is to match the amount and maturity of the T-bills with how quickly you may need the money, while keeping sufficient cash accessible for immediate surprises.

    Table of Contents

    Treasury Bills for Emergency Funds at a Glance

    Treasury bills can be useful for part of an emergency-fund plan, but they should be viewed differently from cash in a checking or savings account. The main issue is timing: a T-bill has a defined maturity, while an unexpected expense may arrive at any time.

    FeatureWhat It Means for an Emergency Fund
    MaturityT-bills have short-term maturities, so the maturity date should fit when you expect the money could be needed.
    AccessAccess is different from withdrawing cash from an ordinary bank account, particularly if the T-bill has not yet matured.
    FDIC insuranceT-bills are not FDIC-insured deposits. They are marketable securities issued by the U.S. Department of the Treasury.
    Before maturityA marketable T-bill can generally be sold before maturity through a broker, but its market price can change.
    Tax treatmentT-bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    Potential roleT-bills may fit a portion of emergency reserves that does not need to remain immediately accessible.

    QUICK TAKE: An emergency fund is about more than earning a return. If you use T-bills, match their maturity and access requirements with your expected cash needs. Money needed for an immediate emergency can remain in an easily accessible account, while a separate portion may be considered for short-term T-bills.

    Complete Beginner Guide to Using Treasury Bills for an Emergency Fund

    Treasury Bills for Emergency FundsA simple way to think about Treasury Bills for Emergency Funds is to divide your reserves according to when you might need the money. Cash needed for an expense tomorrow should be handled differently from money that may remain untouched for several months.

    1. Build an Accessible Cash Reserve First

    Start with money that can be accessed easily through a checking or savings account. This portion can help cover an urgent car repair, insurance deductible, unexpected household expense, or temporary gap in income without requiring you to sell an investment.

    2. Identify Money You May Not Need Immediately

    After setting aside readily accessible cash, look at the remaining emergency reserve. If some of that money is unlikely to be needed immediately, short-term Treasury bills may be one option to consider. The important point is to avoid treating the entire reserve as though it has the same access requirements.

    3. Choose a Maturity That Fits Your Timeline

    Each T-bill has a stated maturity. Before buying one, consider when the money may be needed and whether you are comfortable waiting until maturity. A shorter maturity can bring the maturity date closer, while a longer one may require a longer planning horizon.

    4. Decide What Happens When the Bill Matures

    At maturity, you can reassess the money based on your current circumstances. You might keep it available as cash, use it for an upcoming need, or consider another short-term investment. This review point can help keep your emergency reserves aligned with your changing financial situation.

    BEGINNER TIP: Build the emergency-fund structure around access rather than chasing the highest available yield. The right setup is one where you know which money is immediately available and which portion follows a T-bill maturity schedule.

    How Treasury Bills Work for Emergency Funds

    Using Treasury bills for an emergency fund involves more than buying a government security. You need to plan around the purchase amount, maturity date, account you use, and what you would do if an unexpected expense occurs before the bill matures.

    1. Decide How Much to Put Into T-Bills

    First, identify the portion of your emergency reserve that can follow a maturity schedule. Money needed for an immediate expense may be better kept in an easily accessible account. The T-bill portion should be money you are comfortable keeping invested for its selected term.

    2. Select the Maturity

    Treasury bills are short-term Treasury securities with maturities of one year or less. Different bill terms are offered through Treasury auctions. When choosing a term, consider how long you can leave that portion of your emergency reserve invested without needing it.

    3. Choose Where to Buy

    Individuals can buy Treasury bills through TreasuryDirect or through a brokerage that offers Treasury securities. The two routes differ in how securities are purchased, held, transferred, and sold, so the account you choose matters when planning for emergency access.

    For the purchase process, see our How to Buy Treasury Bills guide. You can also compare the two account options in TreasuryDirect vs. Brokerage T-Bills.

    4. Hold Until Maturity or Plan for an Early Sale

    Holding the T-bill until maturity follows the scheduled maturity process. If you need the money earlier, a marketable T-bill may be sold before maturity, but the process depends on where the security is held. With TreasuryDirect, a marketable security generally needs to be transferred to the commercial book-entry system for sale, and the amount received can be affected by market conditions.

    5. Review the Money at Maturity

    When the T-bill matures, reassess your emergency-fund needs. You may keep the proceeds accessible, use them for an upcoming expense, or consider another short-term investment. If you choose to reinvest, remember that the yield available on a new T-bill may be different from the original one.

    PRACTICAL POINT: For emergency savings, the purchase decision and the access plan should be considered together. A T-bill can provide a scheduled source of funds, but it should not be treated as identical to cash that is immediately available in a bank account.

    Benefits and Drawbacks of Using Treasury Bills for Emergency Funds

    Treasury bills can serve a purpose within a broader emergency-fund plan, particularly for reserves that do not need to remain immediately accessible. However, their advantages come with trade-offs that are important to understand before using them for unexpected expenses.

    Potential Benefits

    • U.S. government obligation: T-bills are securities issued by the U.S. Treasury and backed by the federal government’s obligation to pay according to their terms.
    • Short-term maturities: Their relatively short terms can suit money that has a defined short-term purpose.
    • State and local tax treatment: Interest from Treasury securities is generally exempt from state and local income taxes.
    • Known maturity date: The maturity date is established when the bill is issued, which can make future cash planning easier.

    Potential Drawbacks

    • Not immediate cash: A T-bill follows a security and maturity process rather than functioning like a bank-account balance.
    • Early-sale risk: If you sell before maturity, the market price may be different from the price you paid.
    • Changing future yields: If you reinvest after maturity, the new T-bill may have a different yield.
    • More administration: You need to keep track of maturities, account access, and how the proceeds will be handled.

    KEY POINT: T-bills can add a short-term government-security layer to an emergency-fund plan, but they do not eliminate the need for accessible cash. The important question is whether the maturity and access arrangements fit the type of emergency you are preparing for.

    Treasury Bills vs. Other Emergency-Fund Options

    Different emergency-fund options solve different cash-management needs. The key differences are how quickly you can access the money, whether there is a maturity date, whether the product is a bank deposit, and what happens if you need the funds earlier than planned.

    OptionAccessMaturity / WithdrawalFDIC InsurancePotential Role
    Treasury BillsDepends on maturity or an early-sale processFixed maturity; marketable bills may generally be sold before maturityNoA portion of reserves that can follow a Treasury maturity schedule
    High-Yield Savings AccountGenerally convenient accessNo fixed maturityGenerally yes, if it is a deposit at an FDIC-insured bank and within applicable limitsReadily accessible emergency cash
    Money Market Deposit AccountGenerally convenient accessNo fixed maturityGenerally yes, if it is an FDIC-insured bank deposit and within applicable limitsAccessible cash with bank-account features
    Certificate of Deposit (CD)Usually less flexible before maturityFixed term; early withdrawal may involve a penaltyGenerally yes, if it is an FDIC-insured bank CD and within applicable limitsMoney that can remain committed for a defined period

    QUICK COMPARISON: Bank savings and money market deposit accounts generally provide simpler access to emergency cash. T-bills and CDs add a defined investment term, so they require more planning when the money may be needed unexpectedly. FDIC insurance applies to eligible bank deposits, not Treasury bills.

    Costs, Risks and Expert Tips for Using T-Bills in an Emergency Fund

    Treasury bills generally have a straightforward cost structure when purchased directly through TreasuryDirect. The bigger issue for an emergency fund is often the trade-off between earning a return and keeping money readily available. Your purchase method and the timing of a potential withdrawal both matter.

    Potential Costs and Trade-Offs

    • TreasuryDirect purchase cost: The U.S. Treasury states that it does not charge a purchase fee or commission when you buy Treasury securities through TreasuryDirect.
    • Brokerage pricing: If you use a brokerage, review that firm’s current pricing and trading terms because costs and transaction policies can vary.
    • Liquidity trade-off: Money invested in a T-bill follows a maturity schedule, so it may not be as convenient for an emergency as cash held in an accessible bank account.

    Key Risks

    • Timing risk: An emergency may occur before your T-bill reaches maturity.
    • Market-price risk: If you sell a marketable T-bill before maturity, the price you receive can differ from the amount you originally paid.
    • Reinvestment risk: When a T-bill matures, a new bill may have a different yield.
    • Access considerations: The steps for accessing funds before maturity depend partly on where the T-bill is held and how it is sold or transferred.

    EXPERT TIP: For emergency savings, think about liquidity before yield. Keep an accessible cash layer for expenses that cannot wait, and consider T-bills only for the portion of your reserve that fits comfortably within a maturity schedule.

    Common Mistakes and an Illustrative Real-Life Example

    Treasury bills can be useful for part of an emergency-fund plan, but mistakes often happen when investors focus on the investment itself and overlook how quickly the money may be needed.

    Common Mistakes to Avoid

    • Putting the entire emergency fund into T-bills: This can create an access problem if an urgent expense occurs before a bill matures.
    • Choosing a maturity without considering cash needs: The maturity date should fit how long you can reasonably leave that portion of your reserve invested.
    • Assuming early access works like a bank withdrawal: Selling or transferring a marketable T-bill before maturity involves a different process.
    • Assuming future yields will remain unchanged: A new T-bill may have a different yield when the original bill matures.
    • Overlooking tax treatment: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • Never reviewing the emergency-fund structure: Changes in income, expenses, family circumstances, or other liquid assets can affect how much accessible cash you need.

    Illustrative Example: A $24,000 Emergency Reserve

    Consider a hypothetical household with a $24,000 emergency reserve. The household decides to keep $8,000 in an accessible savings account and considers using the remaining $16,000 for short-term Treasury bills. The purpose is to separate money needed for immediate expenses from money that can follow a maturity schedule.

    Suppose an unexpected $3,000 expense occurs. The household could use part of its accessible cash instead of immediately trying to sell a T-bill. Later, when a T-bill matures, the household can reassess its cash needs and decide whether to keep the proceeds available or consider another short-term option.

    IMPORTANT: The $8,000 and $16,000 amounts are only illustrative. They are not a recommended emergency-fund allocation. The appropriate structure depends on factors such as monthly expenses, income stability, household obligations, other liquid assets, and how quickly the money may be needed.

    Who Should Consider Using Treasury Bills for an Emergency Fund?

    Treasury bills may be considered by people who want to keep part of their short-term reserves in U.S. government securities while maintaining separate funds that are readily accessible. Whether this approach fits depends on how quickly the money may be needed and how comfortable you are with a security that has a defined maturity.

    This Approach May Fit People Who:

    • Already keep some emergency money in an easily accessible account.
    • Can identify a portion of their reserves that is unlikely to be needed immediately.
    • Are comfortable tracking T-bill maturity dates and managing Treasury securities.
    • Understand that selling a marketable T-bill before maturity can involve changes in its market price.
    • Want to consider Treasury interest and its federal, state, and local tax treatment when comparing short-term options.

    It May Be Less Suitable When:

    You have very little readily accessible cash, expect frequent or unpredictable withdrawals, or do not want to manage maturity dates and potential early-sale considerations. In those circumstances, an emergency-fund structure with greater immediate access may better match your cash-flow needs.

    KEY QUESTION: Before using a T-bill for emergency savings, ask: “If I needed this money unexpectedly, would the maturity timing and access process work for me?”

    Frequently Asked Questions About Treasury Bills for Emergency Funds

    1. Can Treasury bills be used for an emergency fund?

    Yes. Treasury bills can be used for a portion of an emergency fund, particularly money that does not need to remain immediately accessible. Keeping some cash readily available can help cover expenses that cannot wait for a T-bill to mature.

    2. Are T-bills good for emergency savings?

    They can be useful for part of an emergency reserve, but they are not the same as immediately accessible cash. The appropriate choice depends on when you may need the money and whether the T-bill’s maturity and access arrangements fit your circumstances.

    3. How much of an emergency fund should be in T-bills?

    There is no universal percentage. The amount depends on your expenses, income, other liquid assets, and how quickly you might need the money. A useful framework is to separate immediately accessible cash from reserves that can follow a T-bill maturity schedule.

    4. Can you access T-bill money before maturity?

    Marketable T-bills can generally be sold before maturity, but the process depends on where the security is held. A TreasuryDirect-held marketable security may need to be transferred or sold through the applicable TreasuryDirect process, and an early sale can produce a price different from the amount originally paid.

    5. Are Treasury bills FDIC insured?

    No. Treasury bills are securities issued by the U.S. Treasury, not FDIC-insured bank deposits. FDIC insurance applies to eligible deposits held at FDIC-insured banks, subject to applicable coverage limits.

    6. Do T-bills have state and local tax benefits?

    Generally, yes. Interest from U.S. Treasury securities is generally exempt from state and local income taxes, while federal income tax generally applies.

    7. What T-bill maturity is best for an emergency fund?

    There is no single maturity that is best for everyone. The appropriate term depends on how long you can leave the money invested, how much accessible cash you already have, and how soon you may need the reserve.

    8. Should you keep some emergency money in a savings account?

    Keeping some emergency money in an accessible savings account can make sense when immediate access is important. The appropriate amount depends on your expected expenses, cash-flow needs, and overall financial situation.

    FAQ NOTE: These answers explain the general framework. Your emergency-fund structure should reflect your own cash needs, access requirements, and financial circumstances.


    Final Verdict: Where Treasury Bills Can Fit in an Emergency Fund

    Treasury Bills for Emergency Funds can be considered for a portion of short-term reserves when that money does not need to remain immediately accessible. Their defined maturities can help with planned cash management, while their status as U.S. Treasury securities gives them a different role from ordinary bank deposits.

    The main consideration is liquidity. An unexpected expense can arise before a T-bill reaches maturity. If you need to access the money earlier, the process depends on where the security is held, and selling before maturity can expose you to changes in market price. This is why emergency-fund planning should account for readily accessible cash as well as investments with defined terms.

    THE BIG IDEA: Think of an emergency fund as a liquidity structure rather than a single investment. Accessible cash can cover immediate needs, while T-bills may be considered for reserves that can comfortably follow a maturity schedule.

    There is no universal T-bill allocation or maturity for every household. The appropriate structure depends on expenses, income, other liquid assets, expected cash needs, and your comfort with managing Treasury securities.

    Have a Money Question? Keep Exploring.

    Emergency savings work best when the access plan matches your real-life needs. If you are considering Treasury bills, explore the guides below to understand the basics and compare them with other short-term options.

    📩 Get in Touch With FinanceInvestment
    Email FinanceInvestment

    Continue Your Research
  • How to Build a Treasury Bill Ladder in 2026: Beginner Guide

    How to Build a Treasury Bill Ladder in 2026: Beginner Guide

    How to Build a Treasury Bill Ladder

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 26, 2026Updated: Sep 26, 2026

    Reading Time: 12–14 min


    How to Build a Treasury Bill Ladder: A Simple Starting Point

    how to build a treasury bill ladderHow to Build a Treasury Bill Ladder is easier to understand when you look at the timing of your cash. Instead of putting all your money into one Treasury bill with a single maturity date, a ladder spreads purchases across several maturity dates. As one bill matures, that cash becomes available while the other bills continue toward their own maturity dates.

    This approach can give you a more organized way to manage short-term money. For instance, you may want part of your savings to become available every few months instead of having everything mature at once. The right setup depends on your starting amount, expected cash needs, and the Treasury bill maturities available when you invest.

    If Treasury bills are still new to you, begin with our Treasury Bills Explained guide. It covers the basics of T-bills, including how they work and mature. Here, we’ll focus on turning individual Treasury bills into a simple ladder you can manage over time.

    What You’ll Learn

    • What a Treasury bill ladder is and how the strategy is structured.
    • How to choose maturity dates around your expected cash needs.
    • How to divide money among different T-bill maturities.
    • What happens when one bill reaches maturity.
    • How reinvesting can keep a ladder going over time.
    • What to consider before selling a T-bill before maturity.
    • Common mistakes that can make a ladder difficult to manage.

    The idea is straightforward: give different portions of your cash different maturity dates. Once the schedule is set up, you can decide whether each maturity should be spent, held in cash, or reinvested.

    Quick Answer: How to Build a Treasury Bill Ladder

    A Treasury bill ladder uses multiple T-bills with different maturity dates. You start by identifying when you may need your money, choose maturities that fit that timeline, divide your cash among the purchases, and keep track of each maturity. When a bill matures, you can use the proceeds or reinvest them, depending on your next cash need.

    Key Takeaways

    • Spread maturity dates: Instead of having all your money mature at once, you create several maturity points.
    • Plan around your cash needs: Your expected spending dates should guide the ladder more than a particular maturity schedule.
    • Divide the investment: You can allocate different amounts to different T-bills rather than committing everything to one purchase.
    • Decide what happens at maturity: Each maturity can provide cash for spending or become the starting point for another T-bill purchase.
    • Understand early sales: A marketable T-bill can generally be sold before maturity, but its market price may be different from what you paid.
    • Expect changing yields: Reinvesting later may produce a different return because Treasury market rates can change.
    • Track the schedule: Recording purchase amounts and maturity dates can make the ladder much easier to manage.

    BOTTOM LINE: A T-bill ladder is a way to organize short-term Treasury investments around future cash needs. The important part is not simply buying several bills. It is choosing maturity dates and amounts that make sense for your own timeline.

    Table of Contents

    Treasury Bill Ladder at a Glance

    A Treasury bill ladder is a group of T-bills arranged with different maturity dates. Instead of having all your money tied to one maturity, you spread purchases across a schedule. When each bill matures, its proceeds become available for spending or another investment.

    BEST FOR

    Investors who want to spread short-term cash availability across several planned maturity dates.

    KEY NUMBERS

    Treasury bills have maturities of one year or less. The number of rungs in your ladder depends on your cash needs and investment amount.

    FeatureWhat It Means
    StructureMultiple T-bills with maturity dates spread across a chosen schedule
    Starting pointIdentify your expected cash needs and decide how much money to allocate
    MaturityEach T-bill reaches maturity on its own scheduled date
    When a bill maturesYou can use the proceeds for a planned expense or consider reinvesting them
    Early saleA marketable T-bill can generally be sold before maturity, but its market price may differ from the purchase price
    Tax treatmentT-bill interest is generally subject to federal income tax but exempt from state and local income taxes

    QUICK TAKE: Think about the dates first. A useful ladder starts with when you expect to need your cash, then works backward to the T-bill maturities and amounts that fit those needs.

    Treasury Bill Ladder: A Complete Beginner Guide

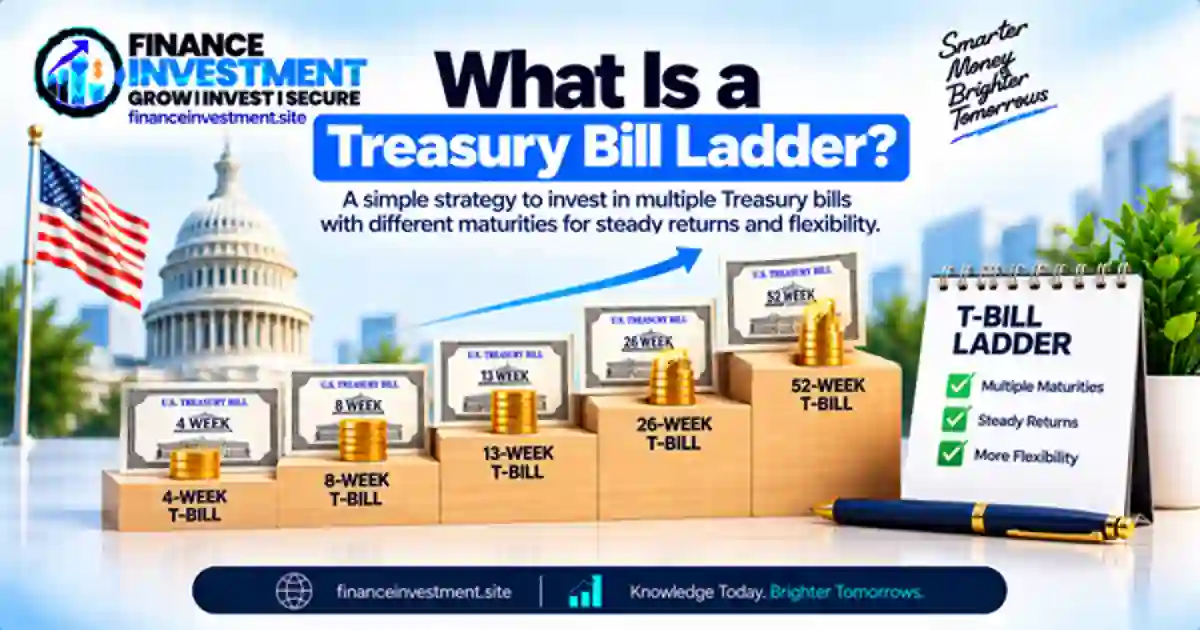
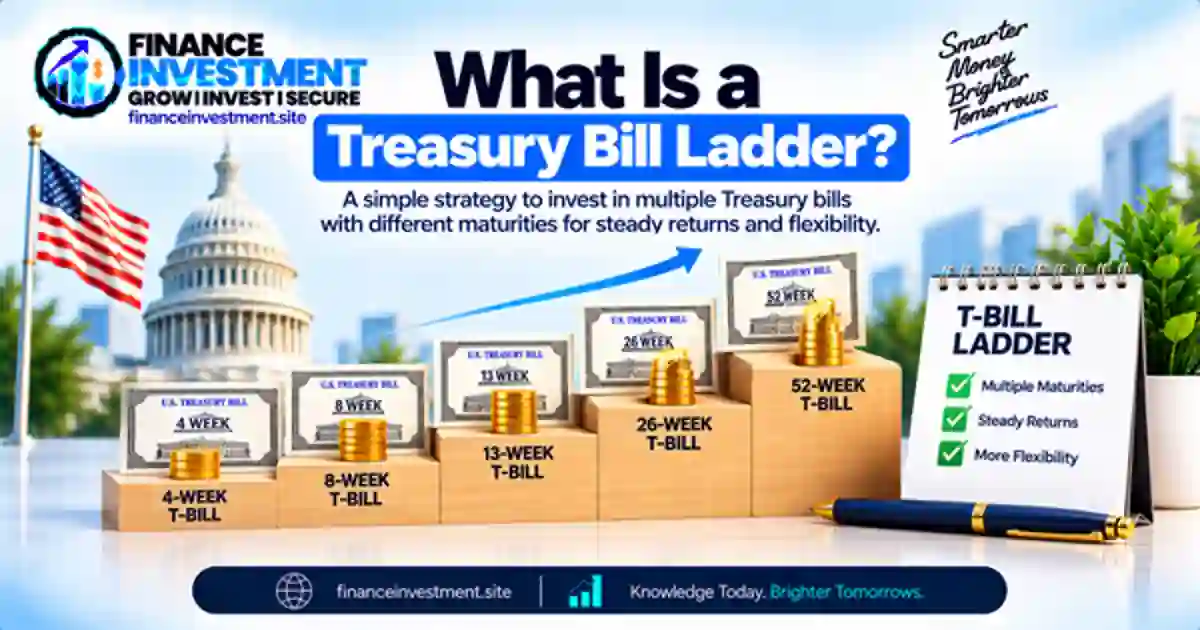
    how to build a treasury bill ladderFor a first-time investor, a Treasury bill ladder may sound more complicated than it really is. At its core, you are combining several T-bill purchases so that they reach maturity on different dates. That gives you a planned sequence of future cash availability.
    What Is a Treasury Bill Ladder?

    Suppose you have $20,000 that you do not expect to use immediately. You could put the entire amount into one T-bill. Another approach is to divide the money among several T-bills with different maturity dates. The result is a series of dates when portions of the investment can become available.

    Start With Your Cash Timeline

    The first question is not, “Which T-bill has the highest yield?” It is, “When might I need this money?” A planned tax payment, tuition bill, home repair, travel expense, or other short-term goal can help you decide when individual rungs should mature.

    What Is a Ladder Rung?

    Each T-bill in the arrangement can be thought of as one rung. The rungs do not have to contain equal amounts. You can allocate more money to a maturity that matches a larger upcoming expense and less to another. When a bill matures, you can use the proceeds or decide whether to replace that rung with a new T-bill.

    BEGINNER TIP: Your first ladder does not need to be elaborate. A small number of clearly planned rungs can make it easier to track maturity dates, cash needs, and reinvestment decisions.

    How to Build a Treasury Bill Ladder

    A workable ladder starts with your cash calendar. Once you know how much money you can set aside and when you may need it, you can choose T-bill maturities and assign an amount to each one.

    1. Set Aside the Right Amount

    Use money intended for short-term investing rather than cash needed for everyday bills. Keep your immediate spending needs and emergency reserves separate. This helps prevent an unexpected expense from forcing you to sell a T-bill before maturity.

    2. List Your Expected Cash Dates

    Write down upcoming expenses and the approximate dates when you may need the money. A home project, tuition payment, tax bill, or planned purchase can give you a useful target for one or more maturities.

    3. Match T-Bill Maturities to Your Timeline

    Treasury bills come in several short-term maturities. Select the available maturities that fit your schedule rather than copying someone else’s ladder. If you need a refresher on the purchase process, see our guide to buying Treasury bills.

    4. Assign an Amount to Each Rung

    You can divide the money evenly or use different amounts. For example, a larger upcoming expense may justify a larger allocation to the T-bill maturing around that time. The important point is to make the amounts fit your actual cash plan.

    5. Decide What Happens at Maturity

    Each maturity creates a decision point. If you need the money, use the proceeds for the planned expense. If you do not, you can consider reinvesting them into another T-bill. Reinvestment can keep the ladder running, but the new T-bill’s yield may differ from the rate available when you made the original purchase.

    SIMPLE EXAMPLE: Suppose you have $20,000 for short-term goals. You could split it across several T-bills with different maturity dates. When the first bill matures, you decide whether to spend that cash or buy a replacement T-bill. That decision can then be repeated as the next rungs mature.

    Treasury Bill Ladder: Benefits and Drawbacks

    A Treasury bill ladder can bring structure to short-term cash management, but it is not a set-it-and-forget-it strategy. Its usefulness depends on how well the maturity schedule fits your goals. Before building one, consider both the advantages and the trade-offs.

    BENEFITS
    • Staggered access: Different maturity dates can provide several planned opportunities to access cash.
    • Goal-based planning: You can align individual T-bills with known or expected short-term expenses.
    • Reinvestment flexibility: At maturity, you can use the proceeds or evaluate another Treasury investment.
    • Government obligation: T-bills are direct obligations of the U.S. government, subject to the government’s ability to meet its obligations.
    DRAWBACKS
    • More recordkeeping: Multiple T-bills mean more purchase details and maturity dates to monitor.
    • Changing reinvestment rates: The yield available when a bill matures may be higher or lower than your original yield.
    • Market-price risk before maturity: If you sell a marketable T-bill before maturity, its price can be different from what you paid.
    • Planning risk: A poorly timed ladder may not provide cash exactly when an expense is due.

    KEY POINT: The goal of a ladder is not to create as many maturity dates as possible. A practical ladder uses a manageable number of rungs that fit your expected cash needs and your willingness to reinvest.

    Treasury Bill Ladder Comparison

    A Treasury bill ladder can be structured in different ways. The main difference is how you divide the money and what you plan to do when each bill matures. The table below compares four common approaches without assuming that one structure works for every investor.

    StructureHow It WorksMain Planning Focus
    Single T-billMost or all of the money is placed into one T-bill maturity.One primary maturity date.
    Equal-rung ladderSimilar amounts are divided among T-bills with staggered maturity dates.Keeping the schedule simple and consistent.
    Goal-based ladderAmounts and maturity dates are selected around specific expected cash needs.Matching proceeds with planned expenses.
    Rolling ladderWhen a T-bill matures, its proceeds may be used to purchase another T-bill and extend the schedule.Maintaining an ongoing short-term investment cycle.

    QUICK TAKE: The structure should follow your purpose. A simple equal-rung schedule may be easier to track, while a goal-based ladder gives you more flexibility when future expenses vary in size or timing.

    Treasury Bill Ladder: Costs, Risks and Expert Tips

    A Treasury bill ladder does not require complicated maintenance, but you still need to consider purchase costs, market prices, reinvestment rates, and the timing of your cash needs. Understanding these details can help you avoid building a ladder that looks organized but does not fit your actual financial schedule.

    Potential Costs

    • TreasuryDirect purchases: TreasuryDirect does not charge a fee or commission for purchasing Treasury securities directly through the platform.
    • Brokerage costs: A broker may have its own commissions, spreads, markups, markdowns, or other transaction-related costs. Review the broker’s current pricing before placing an order.
    • Management effort: A ladder with several rungs requires you to keep track of purchase amounts, maturity dates, and what you want to do with each maturity.

    Key Risks

    • Early-sale price risk: If you sell a marketable T-bill before maturity, its market price may be above or below the amount you paid.
    • Reinvestment risk: When a T-bill matures, the yield available on a replacement bill may be different from the yield on your original investment.
    • Cash-flow risk: If a maturity date does not line up with an upcoming expense, you may need another source of cash or may have to consider selling a bill early.
    • Opportunity cost: Money committed to a ladder may not be available for another investment or financial goal during the selected maturity period.

    EXPERT TIP: Build the ladder around your expected cash-flow dates first. Then compare available maturities, yields, and purchase costs. If you use a brokerage account, check its current fee schedule and understand how the broker handles Treasury purchases and secondary-market sales.

    Common Treasury Bill Ladder Mistakes and an Illustrative Example

    A Treasury bill ladder can be easy to understand but still easy to mismanage. The most common problems usually come from building the schedule without considering when the money will actually be needed.

    Common Mistakes to Avoid

    • Choosing maturities by yield alone: A higher yield may not be useful if the maturity date does not fit your cash needs.
    • Investing money you may need soon: Keep money for immediate expenses and emergencies accessible rather than automatically adding it to the ladder.
    • Making every rung the same size: Equal allocations are simple, but your future expenses may not be equal.
    • Skipping the maturity plan: Decide in advance whether each maturity is likely to be spent, held as cash, or considered for reinvestment.
    • Assuming the same yield will continue: Future T-bill yields can change, so a replacement bill may have a different return.

    Illustrative Example: A $30,000 Ladder

    Consider a hypothetical investor with $30,000 available for several short-term goals. Instead of placing the entire amount into one T-bill, the investor could divide the money among several T-bills with staggered maturity dates. The actual amounts and maturities would depend on the investor’s expected cash needs.

    If one maturity is scheduled around a planned expense, those proceeds could be used for that expense. The remaining T-bills could continue until their own maturity dates. At each maturity, the investor can reassess the next step rather than automatically reinvesting every dollar.

    KEY LESSON: A useful ladder connects three things: how much money you have available, when you expect to need it, and what you plan to do when each T-bill matures. The schedule should serve your cash needs rather than exist simply for the sake of having multiple rungs.

    Who Should Consider a Treasury Bill Ladder?

    A Treasury bill ladder is generally designed for short-term money that has a planned timeline. It can be useful when you want several T-bills to mature at different points instead of having one maturity date for the entire amount.

    A Ladder May Fit Your Situation If You:

    • Have money available for goals that are months away rather than immediate expenses.
    • Expect to need portions of your savings at different times.
    • Want to organize several T-bill maturities around a cash-flow schedule.
    • Are comfortable keeping track of multiple purchase and maturity dates.
    • Want to make a fresh decision whenever a T-bill matures.

    A Ladder May Be Less Suitable If You:

    Need the money available at any time, do not want to monitor multiple securities, or are investing for a goal that requires a longer time horizon. A ladder also should not replace an appropriate emergency cash reserve or money needed for near-term bills.

    Frequently Asked Questions About Treasury Bill Ladders

    1. What is a Treasury bill ladder?

    A Treasury bill ladder is a strategy that uses multiple T-bills with different maturity dates. Instead of having the entire investment mature at one time, portions of the money become available according to a planned schedule.

    2. How do I build a Treasury bill ladder?

    Start by deciding how much money you can allocate and when you may need it. Then select available T-bill maturities, divide the money among the purchases, record the maturity dates, and decide whether to use or reinvest each maturity.

    3. How many T-bills should be in a ladder?

    There is no standard number of rungs. The appropriate number depends on your investment amount, expected cash needs, preferred maturity spacing, and how much activity you want to manage.

    4. What happens when a T-bill in the ladder matures?

    At maturity, the Treasury pays the bill according to its terms. For a typical discount T-bill, you receive its face value at maturity. You can then use the proceeds for a planned expense or consider reinvesting them.

    5. Can I sell a T-bill before it matures?

    Marketable T-bills can generally be sold before maturity through a brokerage or other appropriate secondary-market channel. The market price at the time of sale can be higher or lower than your purchase price, so the amount you receive may differ from the amount originally invested.

    6. Are Treasury bills FDIC insured?

    No. Treasury bills are not FDIC-insured bank deposits. They are direct debt obligations of the U.S. government, subject to the government’s ability to meet its obligations.

    7. Are Treasury bill earnings exempt from state income tax?

    Generally, interest income from U.S. Treasury bills is subject to federal income tax but exempt from state and local income taxes. Individual tax situations can vary, so review your circumstances with a qualified tax professional when appropriate.

    8. Should I reinvest every maturing T-bill?

    Not necessarily. You can use the proceeds for a planned expense, keep the money available for another goal, or consider buying another Treasury security. The decision depends on your cash needs, the available yields, and your overall financial plan.


    Final Comparison: How to Build a Treasury Bill Ladder

    A Treasury bill ladder is ultimately a way to organize short-term money around future dates. The structure you use should reflect how often you expect to need cash, how much you want to invest, and whether you plan to spend or reinvest the proceeds when each T-bill matures.

    Planning QuestionWhat to Consider
    When will I need the money?Use expected cash-flow dates to help determine when individual T-bills should mature.
    How much should each rung contain?Equal amounts can simplify tracking, while different amounts may better match expenses of different sizes.
    What happens at maturity?Decide whether to use the proceeds, hold the cash for another goal, or consider reinvesting.
    Could my plans change?Leave enough flexibility so an unexpected cash need does not force an unnecessary early sale.

    FINAL TAKEAWAY: A well-planned T-bill ladder starts with your cash-flow needs, not with the number of rungs. Choose maturities and investment amounts that you can comfortably track, then reassess the plan whenever a bill matures or your financial needs change.

    Have a Money Question? Keep Exploring.

    A Treasury bill ladder works best when the maturity schedule reflects your actual cash needs. Before adding a new rung, consider when you may need the money, how much you want to allocate, and what you will do when each T-bill matures.

    📩 Get in Touch With FinanceInvestment

    Have a Treasury bill question or a topic you’d like us to explain?

    Email FinanceInvestment

  • What Is a Treasury Bill Ladder? How It Works in 2026

    What Is a Treasury Bill Ladder? How It Works in 2026

    What Is a Treasury Bill Ladder?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 25, 2026
    Updated: Sep 25, 2026
    Reading Time: 10–12 min


    What Is a Treasury Bill Ladder?

    What Is a Treasury Bill Ladder?What Is a Treasury Bill Ladder? It is a strategy that spreads money across Treasury bills with different maturity dates instead of putting everything into one bill. As each T-bill matures, you can use the cash or reinvest it into another bill.
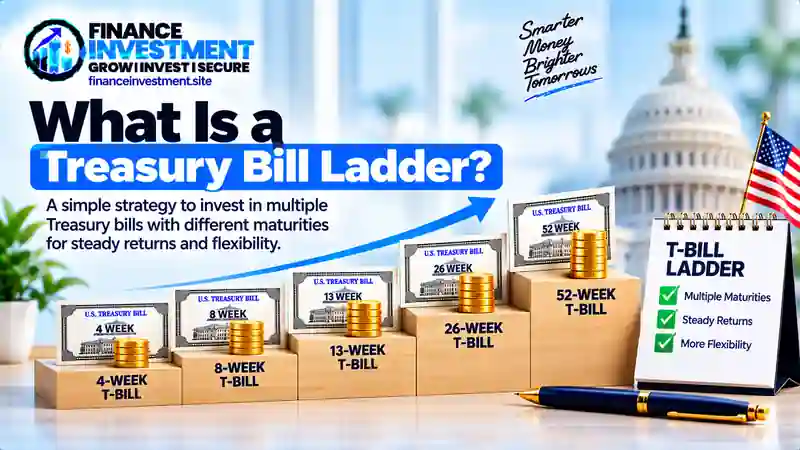
    The goal is to create a planned schedule for when money becomes available. Because Treasury bills mature in one year or less, investors can arrange maturities around upcoming expenses, savings targets, or other short-term cash needs.

    What You’ll Learn

    • How a Treasury bill ladder is structured.
    • How staggered maturities create a planned cash schedule.
    • How reinvestment can keep a ladder going.
    • How to match maturities with your cash needs.
    • What costs and risks to consider.
    • How a ladder differs from buying one T-bill maturity.

    If Treasury bills are new to you, start with our Treasury Bills Explained guide. Then use this article to understand how multiple T-bills can work together as a ladder.

    Quick Answer: What Is a Treasury Bill Ladder?

    A Treasury bill ladder is a group of T-bills with different maturity dates. Instead of having all the bills mature at once, you spread them across a schedule. When one matures, you can use the cash or reinvest it into another T-bill.

    Key Takeaways

    • Staggered maturities: Bills mature on different dates instead of all at once.
    • Planned cash flow: Maturities can be arranged around expected expenses.
    • Reinvestment: A matured bill can be replaced with another T-bill if you still want the money invested.
    • Short-term structure: Treasury bills have maturities of one year or less.
    • Adjustable schedule: You can change future purchases as your cash needs change.
    • Early-sale risk: Selling a T-bill before maturity means accepting the market price available at that time.

    BOTTOM LINE: A T-bill ladder is a way to organize short-term Treasury maturities around your cash needs. The key decisions are when each bill matures, whether to reinvest, and what to do if you need the money early.

    Table of Contents

    Treasury Bill Ladder at a Glance

    A Treasury bill ladder spreads T-bill purchases across different maturity dates. Instead of having the entire amount mature at one time, the investor creates several maturity points that can provide a more organized schedule for accessing or reinvesting cash.

    QUICK FACTS

    Treasury bills have maturities of one year or less. A ladder combines multiple bills with different maturity dates.

    SUITS THIS APPROACH

    Investors who want to organize short-term Treasury maturities around expected cash needs.

    KEY IDEA

    At maturity, you can use the proceeds or reinvest them into another marketable Treasury security.

    FeatureTreasury Bill Ladder
    StructureMultiple T-bills with different maturity dates
    Time frameShort term; each bill matures in one year or less
    At maturityUse the proceeds or reinvest them into another marketable Treasury security
    Main purposeCreate a planned schedule of Treasury maturities
    Early saleA marketable T-bill can generally be sold before maturity, with the amount received determined by its market price at that time

    QUICK TAKE: A Treasury bill ladder is not a separate investment product. It is a way to organize multiple T-bills and their maturity dates around your cash schedule.

    Treasury Bill Ladder: A Complete Beginner Guide

    What Is a Treasury Bill Ladder?A Treasury bill ladder is not one investment. It is a group of T-bills arranged around different maturity dates. Instead of having all your money tied to one maturity, you spread purchases across several dates so portions of the money can become available at different times.
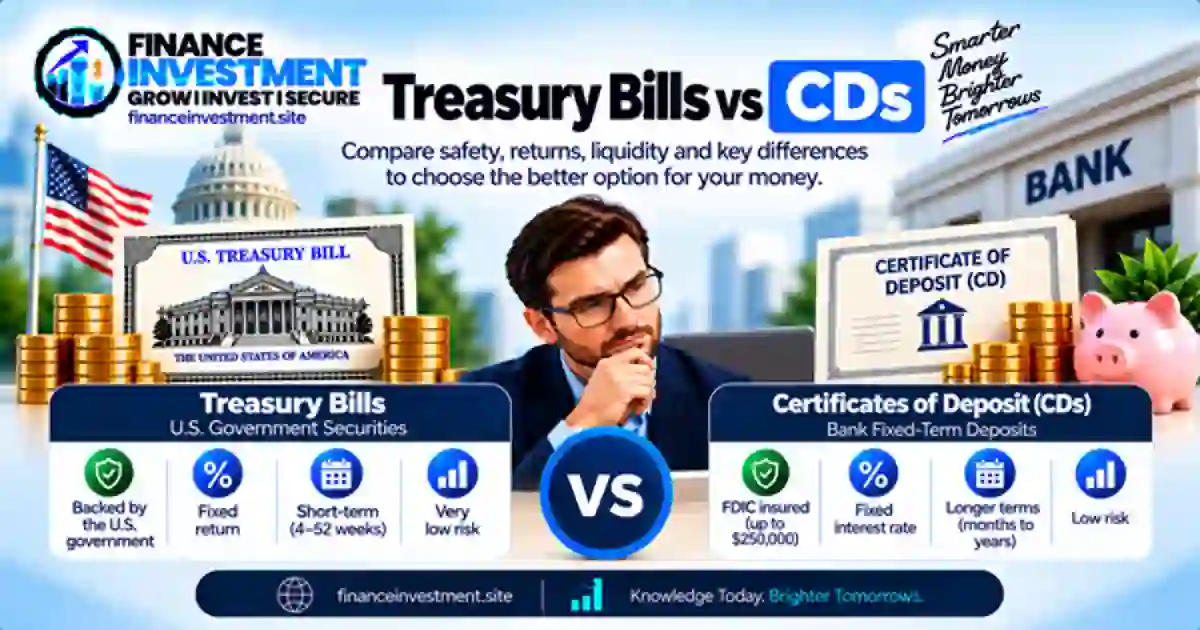
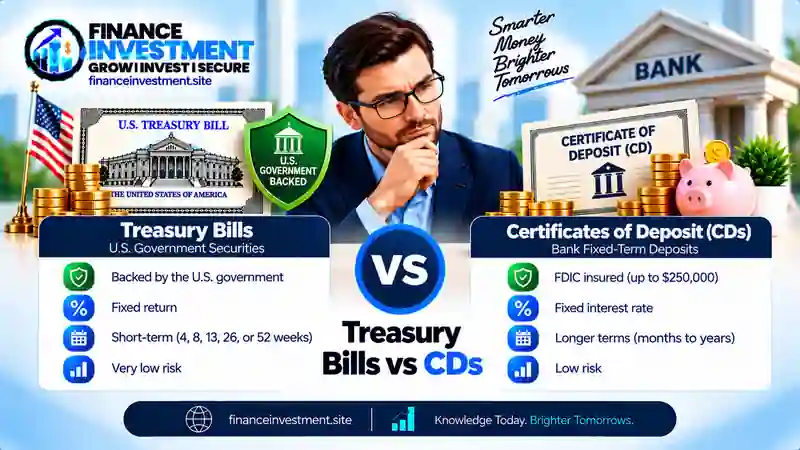
    What Makes It a Ladder?

    Suppose you have $20,000 that you may need at different points over the coming year. Rather than choosing one maturity for the entire amount, you could divide the money among several T-bills with different maturity dates. The amounts and timing would depend on your actual cash needs.

    What Happens When a Bill Matures?

    At maturity, you receive the proceeds and can use the money for its intended purpose or reinvest it. TreasuryDirect allows eligible marketable securities to be scheduled for reinvestment. Its automatic reinvestment uses the proceeds to purchase another security of the same type and term.

    Why the Timing Matters

    The maturity dates should have a reason behind them. You might plan around a tuition payment, a home project, a tax bill, or another short-term expense. The goal is to make the maturity schedule fit your cash needs rather than choosing dates at random.

    BEGINNER TIP: Start with the dates when you expect to need cash. Then consider the T-bill maturities and purchase amounts that could line up with those dates.

    How a Treasury Bill Ladder Works

    A T-bill ladder works by spreading purchases across several maturity dates. You decide when you want portions of your money to become available, then choose T-bills that fit those dates. The result is a planned sequence of maturities rather than one large maturity date.

    1. Start With Your Cash Needs

    List the expenses or cash needs you expect during the period. For example, you may want part of your money available in a few months and another portion later in the year. These dates become the starting point for your ladder.

    2. Match T-Bills to Those Dates

    Next, divide the amount you want to invest among T-bills with maturity dates that fit your schedule. Treasury bills are available in several short-term maturities, so the exact mix depends on the bills available when you buy and the timing of your goals.

    3. Handle Each Maturity

    When a bill matures, you can use the proceeds or reinvest the money. If you use TreasuryDirect’s reinvestment feature for an eligible security, the proceeds can be used to purchase another security of the same type and term. Other purchasing platforms may have different reinvestment procedures.

    SIMPLE EXAMPLE: Suppose three T-bills mature at different points during the year. When the first one matures, you can use that cash while the other bills remain invested. If you do not need the proceeds, you can reinvest them according to your plan.

    Treasury Bill Ladder: Benefits and Drawbacks

    A T-bill ladder can make short-term cash planning more organized, but it also requires some planning and ongoing decisions. The main question is whether the maturity schedule fits the way you expect to use your money.

    Benefits

    • Staggered maturities: Different maturity dates can spread out when portions of your money become available.
    • Planned reinvestment: Matured proceeds can be used or reinvested according to your cash plan.
    • Short-term structure: Treasury bills have maturities of one year or less.
    • Tax treatment: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    Drawbacks

    • More planning: You need to track maturity dates, purchase amounts and reinvestment choices.
    • Reinvestment risk: A new T-bill may offer a different yield when the previous bill matures.
    • Early-sale risk: Selling before maturity means accepting the market price available at that time.
    • Less convenient for everyday cash: A ladder is designed around Treasury maturities rather than routine spending and bill payments.

    WATCH THE TIMING: A ladder does not lock in today’s yield for every future purchase. When a bill matures, the rate available for a replacement bill may be different.

    Treasury Bill Ladder Comparison

    A T-bill ladder can be built in different ways. The main choices involve how many bills you buy, when they mature, how much money goes into each maturity, and what you plan to do when a bill reaches maturity.

    Ladder FeatureWhat It MeansWhat to Consider
    Number of billsThe ladder uses multiple T-bills with different maturity dates.More maturity points can create a more detailed cash schedule but require more tracking.
    Maturity spacingMaturities are distributed across selected dates.Set the timing around expected cash needs rather than using an arbitrary schedule.
    Amount per maturityYour available money is divided among the selected T-bill purchases.Larger amounts can be assigned to maturities tied to larger expected expenses.
    At maturityYou can use the proceeds or reinvest them.A replacement T-bill may have a different yield from the maturing bill.
    Early saleMarketable T-bills can generally be sold before maturity.The amount received depends on the market price when you sell.
    Tax treatmentT-bill interest is subject to federal income tax.Interest is generally exempt from state and local income taxes.

    QUICK TAKE: There is no universal number of T-bills or maturity spacing for a ladder. Start with your expected cash dates, divide the money accordingly, and decide in advance whether each maturity will be spent or reinvested.

    Treasury Bill Ladder: Costs, Risks and Practical Tips

    The cost of a Treasury bill ladder depends partly on where you buy and sell the bills. TreasuryDirect says it charges no purchase fee or commission for buying marketable Treasury securities. A brokerage may have different transaction costs or pricing arrangements, so check its fee schedule before trading.

    Costs and Risks to Watch

    • Purchase costs: TreasuryDirect charges no purchase fee or commission, while brokerage costs can vary by firm and transaction.
    • Early-sale costs: Selling before maturity may expose you to a lower market price, a commission, a markdown, or other transaction costs.
    • Reinvestment risk: When a T-bill matures, a replacement bill may offer a different yield.
    • Timing risk: If a maturity date does not match your cash needs, you may need to adjust your plan or sell before maturity.

    Practical Tips

    • Keep a simple calendar showing each maturity date and expected proceeds.
    • Keep enough cash outside the ladder for expenses that cannot wait for a T-bill maturity.
    • Review the available yield before automatically reinvesting matured proceeds.
    • Check your brokerage’s current fee and pricing disclosures before buying or selling T-bills.

    RISK CHECK: A ladder can spread maturity dates, but it does not remove reinvestment risk or the possibility of receiving a different market price if you sell a T-bill before maturity.

    Common Treasury Bill Ladder Mistakes and Real-Life Example

    A Treasury bill ladder is simple in concept, but poor planning can make the schedule less useful. Most mistakes come from choosing maturity dates without first considering when the money will actually be needed.

    Common Mistakes

    • Choosing random maturity dates: Each maturity should have a clear purpose in your cash plan.
    • Investing all available cash: Keep enough money outside the ladder for expenses that may arise before a bill matures.
    • Assuming future yields will be the same: The yield available when you reinvest can be higher or lower than the yield on the maturing bill.
    • Ignoring early-sale risk: If you sell before maturity, the market price may be different from your original purchase price.

    Illustrative Example

    Suppose a family has $20,000 set aside for short-term goals and expects to need portions of the money at different times during the year. Instead of placing the entire amount into one T-bill maturity, they could divide the money among several T-bills with different maturity dates.

    When the first bill matures, the family could use the proceeds for the planned expense. If the money is not needed, they could reinvest it. TreasuryDirect also allows investors to schedule eligible marketable securities for reinvestment.

    KEY LESSON: The purpose of a ladder is not to predict future rates. It is to organize maturity dates around your cash needs and give you a clear choice at each maturity: use the proceeds or reinvest them.

    Who Should Consider a T-Bill Ladder?

    A T-bill ladder may be useful for investors who have short-term money to manage and want to spread maturity dates across a planned schedule. It can be particularly relevant when expected expenses or savings goals have different dates.

    A Ladder May Fit If You:

    • Have money earmarked for expenses or goals within the next year.
    • Want to spread T-bill maturity dates instead of having all your bills mature at once.
    • Are comfortable tracking maturity dates and deciding whether to use or reinvest proceeds.
    • Want to hold some short-term savings in marketable U.S. Treasury securities.

    It May Be Less Convenient If You:

    Need most of your money available for frequent everyday spending or do not want to track multiple maturity dates. Although marketable T-bills can generally be sold before maturity, the amount received depends on the market price at the time of sale.

    Frequently Asked Questions About Treasury Bill Ladders

    1. What is a Treasury bill ladder?

    A Treasury bill ladder is a group of T-bills arranged with different maturity dates. Instead of having all the bills mature at the same time, the schedule spreads maturities across multiple dates.

    2. How does a T-bill ladder work?

    You divide your investment among T-bills with different maturity dates. When each bill matures, you can use the proceeds or reinvest them into another Treasury security.

    3. How long can a Treasury bill ladder last?

    There is no fixed maximum length for a ladder. Individual Treasury bills have maturities of one year or less, while a ladder can continue for longer if you keep reinvesting maturing bills into new Treasury securities.

    4. Can I sell a T-bill before maturity?

    Yes. Marketable Treasury bills can generally be sold before maturity through a brokerage or applicable market channel. The amount you receive depends on the market price when you sell.

    5. Do Treasury bill ladders earn the same rate on every bill?

    Not necessarily. Each T-bill purchase is made under the yield and market conditions available at that time. A replacement bill may therefore have a higher or lower yield than the bill that just matured.

    6. Are Treasury bill ladder earnings taxable?

    Interest income from Treasury bills is subject to federal income tax but is exempt from all state and local income taxes under federal tax rules. Your individual tax reporting requirements may depend on your circumstances.

    7. Can beginners build a Treasury bill ladder?

    Yes. A beginner can start with a simple schedule using a few maturity dates. The key is to understand when the money may be needed and keep track of each maturity and reinvestment decision.

    8. Is a Treasury bill ladder suitable for emergency savings?

    It may be considered for a portion of short-term reserves, but it should not automatically replace readily accessible emergency cash. Consider how quickly you may need the money and the possibility of selling a T-bill before maturity.

    QUICK FAQ TAKEAWAY: A T-bill ladder is mainly a maturity-planning strategy. Its usefulness depends on your cash needs, maturity schedule, reinvestment choices and ability to manage money that may be needed before maturity.


    Final Verdict: Is a Treasury Bill Ladder Worth Considering?

    A Treasury bill ladder is mainly a cash-planning strategy. It lets you spread T-bill maturities across different dates instead of having the entire investment mature at once. That structure can be useful when your short-term financial goals have different timing needs.

    The strategy also requires some management. You need to track maturity dates, decide whether to use or reinvest each maturity, and understand that future T-bill yields can change. If you sell a bill before maturity, the market price at that time determines the amount you receive.

    BOTTOM LINE: A T-bill ladder may be worth considering if you want to organize short-term Treasury investments around specific cash dates. Start with your expected cash needs, choose maturity dates accordingly, and review each maturity before deciding whether to spend or reinvest the proceeds.

    For a broader overview of Treasury bills, see our Treasury Bills Explained guide.

    Related Treasury Bill Resources

    If you want to go deeper, these FinanceInvestment guides cover Treasury bill purchases, maturities, taxes and comparisons with other short-term savings choices.

    Official Sources

    U.S. TreasuryDirect for Treasury security information and reinvestment guidance.
    IRS Publication 550 for Treasury interest and federal tax information.
    Investor.gov for information about selling bonds before maturity.

    Use the resources that match your next question rather than trying to build a ladder around a fixed formula. Your maturity dates, cash needs and reinvestment plans should drive the structure.

    Have a Money Question? Keep Exploring.

    Understanding how Treasury bills fit into your short-term cash plan is easier when you compare the strategy with related Treasury topics. Keep learning and build your approach around your own goals, timing and cash needs.

    📩 Get in Touch With FinanceInvestment

    Have a question about Treasury bills, saving or investing? Send us your question.

    Email FinanceInvestment

  • Treasury Bills vs CDs: Safety, Taxes, Rates & Liquidity

    Treasury Bills vs CDs: Safety, Taxes, Rates & Liquidity

    Treasury Bills vs CDs

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 25, 2026
    Updated: Sep 25, 2026
    Reading Time: 10–12 min


    Treasury Bills vs CDs: What Should You Know?

    Treasury Bills vs CDsTreasury Bills vs CDs is a useful comparison when you have cash to put aside and want to earn a return without taking on the volatility of stocks. Both can serve short-term savings goals, but they work differently. A T-bill is a short-term U.S. Treasury security, while a CD is a time deposit offered by a bank or credit union.

    The real difference shows up when you look past the advertised rate. The maturity date, access to your money, taxes, insurance, and what happens if your plans change can all affect the outcome. T-bills have maturities of one year or less, while CDs can come with a much wider range of terms.

    What You’ll Learn

    • How Treasury bills and CDs work from purchase to maturity.
    • How U.S. government backing differs from FDIC or NCUA insurance.
    • What can happen when you need your money before maturity.
    • How federal and state taxes can affect your actual return.
    • Which rates, fees, terms, and access rules deserve attention.
    • How to match each option with a short-term financial goal.

    If T-bills are new to you, start with our Treasury Bills Explained guide. It covers the basics before we get into the practical differences between T-bills and CDs.

    Quick Answer: Treasury Bills vs CDs

    Treasury bills and CDs can both fit short-term savings goals, but they are built differently. A T-bill is a short-term U.S. Treasury security with a maturity of one year or less. A CD is a time deposit from a bank or credit union with a specific term and account rules.

    Key Takeaways

    • Different products: T-bills are Treasury securities; CDs are deposit products.
    • Protection differs: T-bills are backed by the U.S. government, while eligible CDs at FDIC-insured banks can receive FDIC insurance within applicable limits.
    • Maturity differs: T-bills mature within one year, while CDs can have terms ranging from short periods to several years.
    • Early access differs: A CD may impose an early-withdrawal penalty. A marketable T-bill can generally be sold before maturity, but its market price may be higher or lower than the purchase price.
    • Taxes matter: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally taxable income.
    • Yield is only one factor: Compare the return with taxes, maturity, insurance, fees, access rules, and your cash timeline.

    BOTTOM LINE: Start with when you expect to need the money. Then compare the current T-bill yield or CD APY, applicable protection, tax treatment, fees, and the consequences of accessing the money early.

    Table of Contents

    Treasury Bills vs CDs at a Glance

    T-bills and CDs can both be used for money you expect to keep relatively stable, but they are structured differently. A T-bill is a marketable U.S. Treasury security with a maturity of one year or less. A CD is a time deposit with a specific term and institution-specific rules.

    BEST FOR

    T-bills may fit a defined cash timeline. CDs may fit savers who are comfortable committing money for a selected term.

    KEY NUMBERS

    T-bills mature in 1 year or less. Standard FDIC coverage is $250,000 per depositor, per insured bank, for each ownership category.

    FeatureTreasury BillsCDs
    ProductU.S. Treasury securityTime deposit at a bank or credit union
    MaturityOne year or lessSpecific term selected when opened
    ProtectionBacked by the U.S. government; not FDIC-insuredEligible bank CDs may receive FDIC insurance; eligible credit-union CDs may receive NCUA share insurance
    Early accessA marketable bill can generally be sold before maturity at the available market priceEarly withdrawal may involve a penalty or other product-specific restrictions
    ReturnFor a bill held to maturity, generally based on purchase price and maturity valueInterest is earned according to the CD’s stated terms

    QUICK TAKE: Don’t stop at the advertised return. Check the maturity, applicable insurance or government backing, taxes, access rules, and what happens if you need the money earlier than planned.

    Treasury Bills vs CDs: A Complete Beginner Guide

    Treasury Bills vs CDsIf you’re new to Treasury Bills vs CDs, start with the basic difference. A Treasury bill is a short-term U.S. government security. A CD is a time deposit offered by a bank or credit union. Both can be used for money you expect to keep relatively stable, but the way you earn and access that money is different.
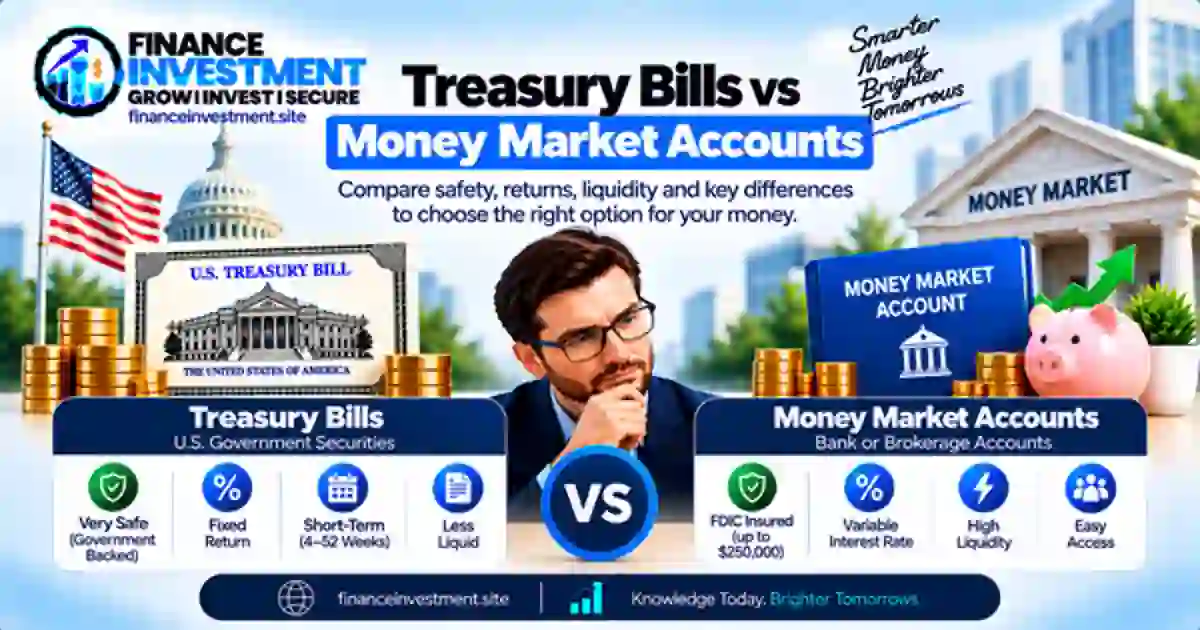
    Treasury Bills in Simple Terms

    T-bills have maturities of one year or less. They are generally issued at a discount to face value, although an auction can result in a price at par. When a discounted bill reaches maturity, you receive its face value, with the difference between your purchase price and the amount received representing the interest earned.

    CDs in Simple Terms

    A certificate of deposit is a time deposit with a selected term. Traditional CDs commonly offer a fixed rate for that term, although the exact terms depend on the institution and CD type. Taking money out before maturity may trigger an early-withdrawal penalty, so the account’s disclosure matters before you open one.

    A SIMPLE WAY TO THINK ABOUT IT: A T-bill is a short-term Treasury security with a maturity date. A CD is a time deposit with a selected term. Once you understand that difference, compare the return, taxes, protection, and access rules.

    How Treasury Bills and CDs Work

    The practical difference becomes clearer when you follow the money from purchase to maturity. A T-bill is issued through a Treasury auction and has a defined maturity. A CD is opened with a bank or credit union for a selected term, with the institution’s terms controlling interest, maturity, and early access.

    How a Treasury Bill Works

    The Treasury sells bills through auctions. T-bills are issued at a discount and redeemed at their face value when they mature. For a discounted bill, the difference between the purchase price and the amount received at maturity is the interest earned. A marketable T-bill can generally be sold before maturity, but the sale price is determined by the market at that time.

    How a CD Works

    With a CD, you deposit money for a stated term and earn interest according to the CD’s terms. When the term ends, the deposit becomes available according to the institution’s maturity rules. If you need the money earlier, the CD agreement determines whether early withdrawal is permitted and what penalty or other restriction may apply.

    THE PRACTICAL DIFFERENCE: With a T-bill, getting out before maturity generally means selling a security at its current market price. With a CD, early access is governed by the deposit agreement and may involve a penalty.

    Treasury Bills vs CDs: Benefits and Drawbacks

    Neither product is automatically the right fit for every cash goal. The useful question is what you value most: a Treasury security with a defined maturity, or a time deposit with institution-specific terms.

    Treasury Bills: Pros and Cons

    PROS
    • Backed by the full faith and credit of the U.S. government.
    • Maturities of one year or less can fit short-term cash planning.
    • Interest is generally exempt from state and local income taxes.
    • Marketable T-bills can generally be sold before maturity.
    CONS
    • An early sale exposes you to the market price at that time.
    • Buying and managing Treasury securities may require more steps than opening a bank CD.
    • T-bills are securities, not FDIC-insured deposits.

    CDs: Pros and Cons

    PROS
    • Traditional CDs commonly provide a fixed rate for a defined term.
    • Different terms can accommodate different savings timelines.
    • Eligible bank CDs can receive FDIC insurance within applicable limits.
    • Eligible CDs at federally insured credit unions can receive NCUA share insurance.
    CONS
    • Early withdrawal may result in a penalty under the CD’s terms.
    • Your money may be less accessible during the selected term.
    • CD interest is generally subject to federal income tax and may also be subject to applicable state or local taxes.

    WHAT MATTERS MOST: A T-bill can be sold before maturity, but its market price can change. A traditional CD can keep its stated rate through the term, but early access may cost you through an early-withdrawal penalty. Your cash timeline should come first.

    Treasury Bills vs CDs: Detailed Comparison

    The headline return is only one piece of the puzzle. When comparing Treasury bills and CDs, look at how each product handles maturity, access, taxes, protection and what happens if your plans change.

    FeatureTreasury BillsCDs
    What you ownA short-term U.S. Treasury securityA time deposit with a bank or credit union
    MaturityOne year or lessThe term selected when the CD is opened
    ReturnFor a discounted bill held to maturity, the purchase price and maturity value determine the returnInterest is earned according to the CD’s stated terms
    ProtectionBacked by the U.S. government; not FDIC-insuredEligible bank CDs may receive FDIC insurance; eligible share certificates at federally insured credit unions may receive NCUA share insurance
    Early accessA marketable bill can generally be sold before maturity at the market price available thenEarly withdrawal depends on the CD agreement and may involve a penalty
    Federal taxInterest is generally subject to federal income taxInterest is generally taxable income
    State & local taxGenerally exempt from state and local income taxesMay be subject to applicable state and local income taxes
    Main trade-offDefined maturity with the ability to sell before maturity at the prevailing market priceDefined deposit term with early-access rules set by the CD

    HOW TO USE THIS TABLE: Start with your expected cash date. Then compare the current return, applicable protection, tax treatment and early-access rules. That gives you a more useful comparison than looking at the advertised rate alone.

    Costs, Risks and Expert Tips

    A good comparison goes beyond the advertised return. Before choosing a T-bill or CD, look at the cost of buying or exiting, the tax treatment, and what could happen if you need the money sooner than expected.

    Costs and Risks to Watch

    • T-bills: TreasuryDirect charges no purchase fee or commission. A broker may have its own charges or terms. Selling before maturity also means accepting the market price available at that time.
    • CDs: Check the specific CD agreement for early-withdrawal provisions, minimum deposit requirements, renewal terms, and any other conditions.
    • Taxes: Compare after-tax returns. T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally taxable income.
    • Protection: Confirm whether a CD is held at an FDIC-insured bank or through a federally insured credit union, and check the applicable insurance rules and limits.

    Expert Tips Before You Buy

    1. Start with the date you expect to need the money.
    2. Compare the current T-bill yield with the CD’s APY after considering taxes and applicable costs.
    3. Read the CD disclosure, especially the early-withdrawal and maturity sections.
    4. If buying a T-bill, decide whether you can hold it to maturity or accept the possibility of a different market price if you sell early.

    EXPERT TIP: Don’t compare the rate alone. A slightly higher return may not matter if the product’s maturity, taxes, fees, or early-access rules don’t fit your plans.

    Common Mistakes and a Real-Life Example

    The rate may grab your attention first, but the details can matter more. A few common mistakes can make a T-bill or CD less convenient than expected.

    Common Mistakes to Avoid

    • Looking only at the highest rate: Taxes, fees, maturity and access rules can change the practical value of a return.
    • Ignoring the maturity date: Make sure the T-bill maturity or CD term fits your expected cash date.
    • Confusing selling with withdrawing: A marketable T-bill can generally be sold before maturity at its market price, while a CD follows the withdrawal terms in its agreement.
    • Forgetting tax differences: T-bill interest is generally exempt from state and local income taxes, while CD interest may be subject to applicable state and local taxes.
    • Assuming every CD has identical protection: Check whether the deposit is at an FDIC-insured bank or whether the share certificate is at a federally insured credit union.

    Real-Life Example

    Suppose a couple has $25,000 set aside for a home improvement project they expect to fund in about six months. They could compare a T-bill with a maturity close to that date against a CD whose term fits their timeline.

    They would then compare the current return, taxes, applicable insurance, and early-access rules. If the project date moves, the consequences also matter: selling a T-bill before maturity means accepting its market price, while accessing a CD early depends on the CD’s terms and any applicable penalty.

    KEY LESSON: Choose the time frame first, then compare the return. Matching the product to your cash date can prevent an avoidable early-access problem.

    Who Should Choose Treasury Bills or CDs?

    Your plans for the money can help narrow the choice. Consider how long you can leave it untouched, whether you prefer a Treasury security or a deposit account, and how each product’s terms affect your return.

    Treasury Bills May Fit If:

    • Your spending date matches an available short-term T-bill maturity.
    • You want to hold a security backed by the U.S. government.
    • The state and local income tax treatment matters to you.
    • You can hold until maturity or accept market-price risk if you sell early.

    CDs May Fit If:

    • You want a deposit product with a term suited to your savings goal.
    • You prefer the predictable rate offered by a traditional fixed-rate CD.
    • You can meet the minimum deposit and early-withdrawal conditions.
    • You have confirmed applicable FDIC coverage for an eligible bank CD or NCUA coverage for an eligible credit-union share certificate.

    ONE MORE THING: If you might need this money without warning, neither product should be treated like an everyday spending account. Keep your immediate cash needs in mind before committing to a maturity date or deposit term.

    Frequently Asked Questions About Treasury Bills vs CDs

    1. How do Treasury bills and CDs differ?

    A T-bill is a short-term U.S. Treasury security, while a CD is a time deposit offered by a bank or credit union. Their maturity, access, tax treatment and protection work differently.

    2. Are Treasury bills FDIC-insured?

    No. Treasury bills are not FDIC-insured deposits. They are U.S. Treasury securities backed by the full faith and credit of the U.S. government.

    3. Are CDs FDIC-insured?

    An eligible CD at an FDIC-insured bank can receive FDIC coverage within applicable limits. A share certificate at a federally insured credit union may receive NCUA share insurance instead.

    4. Can you sell a Treasury bill before maturity?

    Yes. A marketable T-bill can generally be sold before maturity, but the amount received depends on its market price at the time of sale.

    5. Can you withdraw money from a CD early?

    That depends on the CD’s terms. A traditional CD may allow early withdrawal with a penalty, while certain CD types can have different access rules.

    6. Are Treasury bill earnings exempt from state taxes?

    Generally, yes. Interest from U.S. Treasury securities is generally exempt from state and local income taxes, while federal income tax generally applies.

    7. Do CDs and Treasury bills have the same tax treatment?

    No. T-bill interest generally receives state and local tax exemption. CD interest is generally taxable income and may also be subject to applicable state and local taxes.

    8. Which should you compare for short-term cash?

    Compare the specific T-bill and CD based on your cash date, current return, taxes, fees, access rules and applicable protection. There is no single comparison that fits every situation.

    REMEMBER: A T-bill is a Treasury security, while a CD is a deposit product. Their insurance, tax and early-access rules should be evaluated separately.


    Treasury Bills vs CDs: Final Comparison

    Treasury bills and CDs can both be used for short-term cash planning, but they work in different ways. A T-bill is a short-term U.S. Treasury security with a defined maturity. A CD is a time deposit with a term and conditions set by the financial institution.

    Before comparing them, look at when you need the money, the current return, applicable taxes, protection, and early-access rules. With a T-bill, consider the maturity date and the market price if you sell before maturity. With a CD, review the term, rate, maturity instructions, and early-withdrawal provisions.

    FINAL CHECK: A useful comparison goes beyond the headline rate. Review the cash timeline, access rules, tax treatment, applicable insurance or government backing, and any costs before making a decision.

    For a broader introduction to Treasury securities, read our Treasury Bills Explained guide. You can also compare another short-term cash option in our CD vs Money Market Account guide.

    Have a Money Question? Keep Exploring.

    Understanding the details can make short-term money decisions easier to compare. Keep exploring FinanceInvestment for practical guides on Treasury bills, CDs, and other personal finance topics.

    📩 Get in Touch With FinanceInvestment

    Have a money question or a topic you’d like us to cover?

    Email FinanceInvestment

    Continue Your Research