Treasury Bills vs High-Yield Savings Accounts
Treasury Bills vs High-Yield Savings Accounts: What Should You Know?
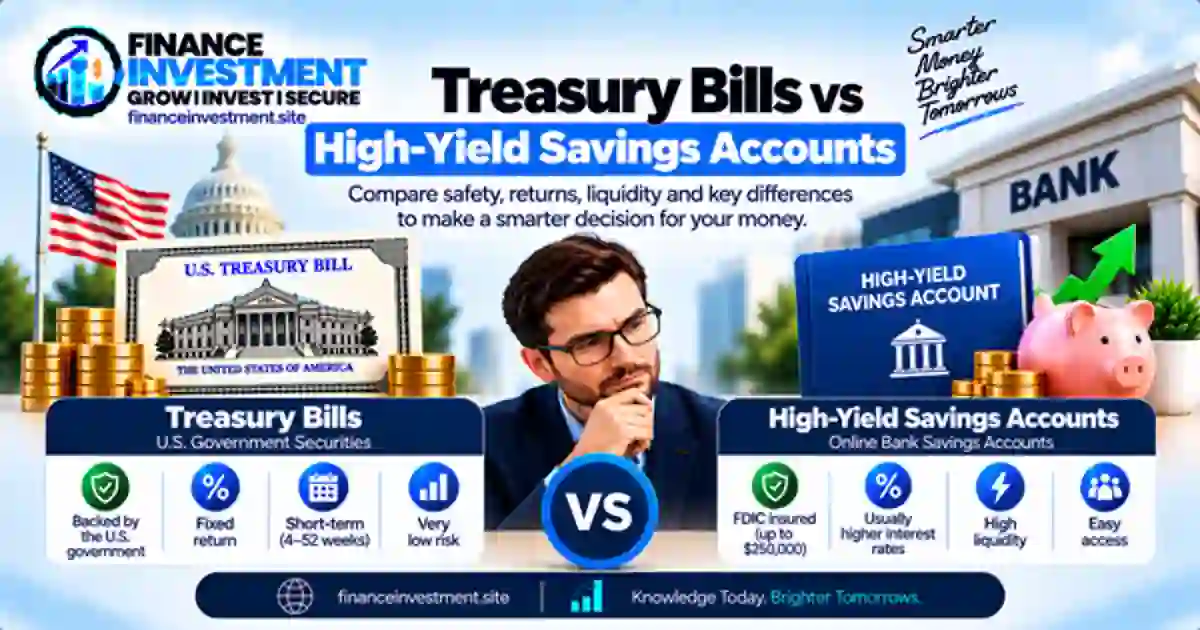 Treasury Bills vs High-Yield Savings Accounts is a useful comparison when you have cash that needs to earn interest without taking on the kind of market risk associated with stocks. The two options work differently. A Treasury bill is a short-term U.S. government security, while a high-yield savings account is a bank deposit account designed to pay a competitive interest rate.
The headline rate is only part of the story. An eligible savings deposit at an FDIC-insured bank can receive FDIC insurance within applicable limits and ownership rules. Treasury bills are not FDIC-insured, but they are backed by the full faith and credit of the U.S. government. Maturity, access, changing rates, taxes, fees, and your cash timeline can also change how the two compare.
What You’ll Learn
- How Treasury bills and high-yield savings accounts work.
- How FDIC insurance differs from Treasury government backing.
- How maturity, access, and changing rates affect your cash.
- How federal, state, and local taxes can affect your return.
- Which costs and risks deserve attention before you commit your money.
If you’re new to T-bills, start with our Treasury Bills Explained guide, then use this comparison to see how they differ from a high-yield savings account.
Quick Answer: Treasury Bills vs High-Yield Savings Accounts
Neither option is universally safer for every cash need. A high-yield savings account is a bank deposit, and eligible deposits at FDIC-insured banks can receive FDIC insurance within applicable limits. A Treasury bill is a U.S. government security, not an FDIC-insured deposit. Its protection comes from the full faith and credit of the U.S. government. The right comparison therefore depends on how you value deposit insurance, maturity, access, rate changes, taxes, and early-sale flexibility.
Key Takeaways
- Both are different products. A T-bill is a short-term Treasury security, while a high-yield savings account is a bank deposit account.
- FDIC insurance applies to eligible deposits. Coverage depends on the bank, ownership category, and applicable insurance limits.
- T-bills are not FDIC insured. They are backed by the full faith and credit of the U.S. government.
- Rates behave differently. A savings-account rate can change, while the return on a purchased T-bill is tied to its purchase price and maturity value.
- Access works differently. Savings accounts are designed for ongoing account access under their terms. Selling a T-bill before maturity means using the market price available at that time.
- Taxes can change the comparison. T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. Savings-account interest is generally taxable income and may also be subject to applicable state and local taxes.
BOTTOM LINE: Compare the actual product terms rather than the advertised rate alone. Your expected timeline, need for access, applicable protection, taxes, and willingness to hold a T-bill to maturity can all affect the practical result.
Table of Contents
Treasury Bills vs High-Yield Savings Accounts at a Glance
Both options can be used for short-term cash, but they are structured differently. A T-bill has a defined maturity, while a high-yield savings account is an ongoing bank deposit without a fixed maturity date.
| Feature | Treasury Bills | High-Yield Savings Account |
|---|---|---|
| Product | Short-term U.S. Treasury security | Bank deposit account |
| Protection | Backed by the full faith and credit of the U.S. government; not FDIC-insured | Eligible deposits at FDIC-insured banks can receive FDIC coverage within applicable limits |
| Maturity | One year or less | No fixed maturity |
| Rate behavior | Return is determined by the purchase price and maturity value | Interest rate can change over time |
| Early access | Generally requires selling the bill before maturity | Withdrawals follow the account agreement and bank terms |
| Tax treatment | Interest generally subject to federal income tax but exempt from state and local income taxes | Interest generally taxable as income and may also be subject to applicable state and local taxes |
A T-bill can fit money with a defined time frame. A HYSA can fit cash that may need ongoing account access.
The standard FDIC insurance amount is $250,000 per depositor, per insured bank, for each ownership category, subject to applicable rules.
QUICK TAKE: The central difference is structure: a T-bill is a Treasury security with a maturity date, while a HYSA is an ongoing bank deposit. Access, protection, rate behavior, taxes, and the timing of your cash needs all matter when comparing them.
Treasury Bills vs High-Yield Savings Accounts: A Beginner’s Guide
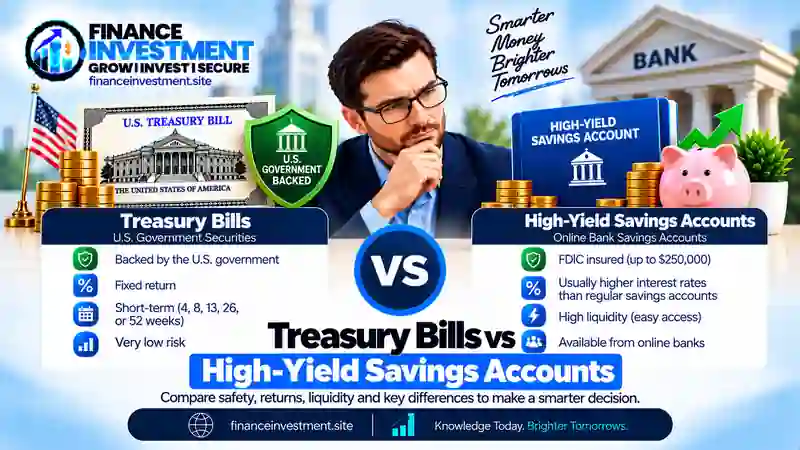 If you’re new to this comparison, begin with one practical question: when might you need this money? A high-yield savings account keeps your cash in a bank deposit, while a Treasury bill places it in a short-term U.S. government security. That basic difference explains much of the comparison.
What Is a High-Yield Savings Account?
A high-yield savings account is a deposit account that generally offers a higher interest rate than many traditional savings accounts. Its rate is typically variable, so the amount you earn can change when the bank changes its rate. At an FDIC-insured bank, eligible deposits can receive FDIC coverage within applicable limits and ownership rules.
What Is a Treasury Bill?
A Treasury bill is a short-term U.S. government security with a maturity of one year or less. T-bills are generally issued at a discount, so the purchase price is below the amount paid at maturity. The difference between those amounts represents the return.
You can purchase T-bills through TreasuryDirect or through a brokerage that offers Treasury securities. If you hold the bill until maturity, the Treasury pays its face value according to the security’s terms. If you sell before maturity, the market price at that time determines the amount you receive.
The Simple Difference
Think of it this way: a HYSA is an ongoing bank deposit with a rate that can change, while a T-bill has a defined maturity and a return based on its purchase price and maturity value. Your timeline, access needs, taxes, and the specific product terms determine how useful each structure may be.
How Treasury Bills and High-Yield Savings Accounts Work
The clearest way to compare them is to look at what happens after you put your money to work. A high-yield savings account remains a bank deposit, while a Treasury bill is a security with a defined maturity.
How a High-Yield Savings Account Works
You deposit money with the bank, and the account earns interest based on its current rate and terms. There is no fixed maturity date, so the account can remain open while you save or access funds according to the bank’s rules. Because the rate is generally variable, the APY you see today can change later.
How a Treasury Bill Works
When you buy a T-bill, you purchase a short-term Treasury security. T-bills are generally issued at a discount, meaning you pay less than the amount paid at maturity. The difference between the purchase price and maturity value represents the return. Treasury bills have maturities of one year or less. Learn how Treasury bills work for more detail.
What If You Need the Money Early?
A HYSA generally allows access to deposited funds under its account terms. A marketable T-bill can generally be sold before maturity, but its market price may change. As a result, the amount received from an early sale can be higher or lower than the original purchase price.
PRACTICAL POINT: A HYSA centers on an ongoing deposit relationship and a changing rate. A T-bill centers on a defined maturity and a return determined by its purchase price and maturity value.
Benefits and Drawbacks of Treasury Bills and High-Yield Savings Accounts
Both options can work for short-term cash, but their strengths come from different structures. A T-bill has a defined maturity and market price, while a HYSA is an ongoing bank deposit with a variable rate.
Treasury Bills: Benefits
- Backed by the full faith and credit of the U.S. government.
- Have a defined maturity that can align with a known future cash need.
- Interest is generally exempt from state and local income taxes.
- Marketable T-bills can generally be sold before maturity.
Treasury Bills: Drawbacks
- The bill has a set maturity date, so the planned holding period matters.
- Selling before maturity exposes you to changes in the market price.
- After maturity, you may need to reinvest if you want to continue holding T-bills.
High-Yield Savings Accounts: Benefits
- Eligible deposits at FDIC-insured banks can receive FDIC coverage within applicable limits.
- There is no fixed maturity date.
- Funds can generally be accessed according to the account’s terms.
- You do not need to sell a marketable security to access the deposit balance.
High-Yield Savings Accounts: Drawbacks
- The interest rate can change over time.
- Some accounts may have minimum-balance requirements or fees.
- Withdrawal, transfer, and access rules vary by account.
- Interest is generally taxable as income and may also be subject to applicable state and local taxes.
KEY POINT: The trade-offs are different. T-bills combine a defined maturity with market pricing before maturity, while HYSAs combine ongoing access with a rate that can change. Compare the features against the purpose and timing of your cash.
Treasury Bills vs High-Yield Savings Accounts: Detailed Comparison
The advertised yield is only one part of the comparison. The product type, protection, access, rate behavior, taxes, fees, and timing of your cash needs can all change the practical result.
| Factor | Treasury Bills | High-Yield Savings Account |
|---|---|---|
| Product type | Short-term U.S. Treasury security | Bank deposit account |
| Protection | Backed by the full faith and credit of the U.S. government; not FDIC-insured | Eligible deposits at FDIC-insured banks can receive coverage within applicable limits and ownership rules |
| Maturity | One year or less, with a specific maturity date | No fixed maturity date |
| Rate behavior | Return is based on the purchase price and amount received at maturity | Interest rate can change according to the account’s terms |
| Access before maturity | Generally requires selling the marketable bill | Withdrawals or transfers follow the account agreement |
| Early-access consideration | Market price may be higher or lower than the original purchase price | Fees, transaction limits, or other account restrictions may apply |
| Tax treatment | Interest generally subject to federal income tax but exempt from state and local income taxes | Interest generally taxable as income and may also be subject to applicable state and local taxes |
| Fees | TreasuryDirect does not charge a fee or commission to purchase Treasury securities directly; brokerage costs may vary | Fees and minimum-balance requirements depend on the account |
| At maturity | The Treasury pays the bill’s face value according to its terms | The account continues unless you close it or change the account arrangement |
WHAT TO NOTICE: These products can serve similar cash-management purposes while operating differently. A T-bill has a maturity date and market pricing if sold early. A HYSA has no fixed maturity, but its interest rate and account terms can change. Compare the specific terms instead of relying on the product name or headline yield alone.
Costs, Risks and Expert Tips
The highest advertised rate is not always the most useful number. Before moving your cash, look at the costs, access rules, tax treatment, and what could happen if you need the money sooner than expected.
Costs to Check
- Treasury bills: TreasuryDirect does not charge a fee or commission to purchase Treasury securities directly. Brokerage purchases may involve commissions, transaction charges, or other costs depending on the broker.
- High-yield savings accounts: Check for monthly maintenance fees, minimum-balance requirements, and other account charges. Some banks waive fees when specific conditions are met.
Risks Worth Understanding
A T-bill’s market price can change before maturity. If you sell it early, the amount you receive may be higher or lower than your original purchase price. A HYSA does not have that market-price exposure, but its interest rate can change and its account terms may affect how you access the money.
EXPERT TIP: Start with your cash timeline, then compare the maturity date, current APY, fees, taxes, and early-access rules. Looking at the complete terms can give you a clearer picture than comparing the headline rates alone.
Common Mistakes and a Real-Life Example
Many mistakes in the Treasury Bills vs High-Yield Savings Accounts comparison happen when investors focus on the advertised rate and overlook access, taxes, fees, or timing.
Common Mistakes to Avoid
- Comparing only the rate: A higher advertised yield does not automatically make an account or security a better fit. Check taxes, fees, access, and timing.
- Confusing FDIC insurance with Treasury backing: These are different forms of protection that apply to different types of financial products.
- Ignoring the cash timeline: A T-bill has a maturity date. Selling before maturity means accepting the market price available at that time.
- Forgetting that HYSA rates can change: A savings account’s current APY may be different later because the rate is generally variable.
Real-Life Example
Imagine Alex has $20,000 that may be needed in about six months for a planned expense. Alex compares a HYSA with a T-bill maturing around the same time. The HYSA offers ongoing account access, but its APY can change. The T-bill has a defined maturity, but selling it before maturity would expose Alex to the market price at that time.
LESSON: Alex can compare the current rates, taxes, fees, access rules, and expected cash date before deciding how to hold the money. The same framework can help evaluate planned expenses and other short-term cash needs.
Who Should Consider Treasury Bills or a High-Yield Savings Account?
The right fit depends on when you may need the money, how you want to access it, and which product features matter most to you.
A Treasury Bill May Fit When:
- You have a defined time frame for the cash.
- You are comfortable holding a Treasury security until maturity.
- The federal tax treatment and exemption from state and local income taxes are relevant to your situation.
- You want to hold a short-term U.S. government security rather than a bank deposit.
A High-Yield Savings Account May Fit When:
- You want an ongoing deposit account without a fixed maturity date.
- You may need access to the money according to the bank’s account terms.
- You want eligible deposits at an FDIC-insured bank to receive FDIC insurance within applicable limits.
- You prefer not to sell a marketable security when accessing your cash.
- You understand that the account’s interest rate can change over time.
KEEP IN MIND: These are product-fit considerations, not universal rules. Compare the actual rate, maturity, fees, taxes, protection, and access terms before deciding where to keep your cash.
Frequently Asked Questions
1. Are Treasury bills safer than high-yield savings accounts?
They have different forms of protection. T-bills are U.S. government securities backed by the full faith and credit of the government, while eligible deposits at FDIC-insured banks can receive FDIC insurance within applicable limits.
2. Are Treasury bills FDIC insured?
No. Treasury bills are not FDIC-insured deposits. They are Treasury securities backed by the full faith and credit of the U.S. government.
3. Is money in a high-yield savings account FDIC insured?
Eligible deposits at an FDIC-insured bank are generally insured up to applicable limits and ownership rules. The standard limit is $250,000 per depositor, per insured bank, for each ownership category.
4. Can I access a Treasury bill before maturity?
A T-bill generally cannot be redeemed directly before maturity. A marketable T-bill can generally be sold through a broker before maturity, and the market price at the time of sale determines the amount you receive.
5. Do Treasury bills pay more than high-yield savings accounts?
Not necessarily. T-bill yields and savings-account APYs can change over time and are calculated differently. Compare current rates, taxes, fees, and the period you expect to hold the money.
6. Are Treasury bills exempt from state income tax?
Generally, yes. Interest from U.S. Treasury securities is generally exempt from state and local income taxes, although federal income tax generally applies.
7. Can you lose money in a high-yield savings account?
Your balance can decrease because of withdrawals, fees, or other account activity. At an FDIC-insured bank, eligible deposits are protected against bank failure within applicable insurance limits. The account’s interest rate can also change over time.
8. Which is better for short-term cash?
There is no universal answer. Consider your cash timeline, access needs, taxes, protection preferences, and the specific rates and terms available. A T-bill has a defined maturity, while a HYSA is an ongoing deposit account.
QUICK FAQ TAKEAWAY: Treasury bills and high-yield savings accounts are different products. Compare government backing, FDIC insurance, maturity, access, rate changes, taxes, and fees rather than looking at the headline yield alone.
Final Comparison: Treasury Bills vs High-Yield Savings Accounts
Treasury Bills vs High-Yield Savings Accounts compares two different ways to manage short-term cash. T-bills are short-term U.S. government securities with defined maturity dates, while HYSAs are bank deposit accounts without a fixed maturity.
The main differences involve protection, access, rate behavior, taxes, fees, and timing. T-bills are not FDIC-insured, but they are backed by the full faith and credit of the U.S. government. Eligible deposits at FDIC-insured banks can receive FDIC insurance within applicable limits. T-bill interest is generally subject to federal income tax but exempt from state and local income taxes, while savings-account interest is generally taxable income.
If you want a broader introduction to T-bills before making this comparison, see our Treasury Bills Explained guide.
FINAL TAKEAWAY: Look beyond the headline rate. Compare the actual yield or APY, maturity, access rules, fees, taxes, and applicable protection against the purpose and timing of your cash.
Have a Money Question? Keep Exploring.
Understanding the differences between financial products can make cash-management decisions easier. Keep learning, compare the details, and consider your own goals, timeline, and access needs.
Have a finance question or topic you’d like us to explain? Send us your question or suggestion.
Leave a Reply