Tag: Investing for Beginners

  • Treasury Bills vs CDs: Safety, Taxes, Rates & Liquidity

    Treasury Bills vs CDs: Safety, Taxes, Rates & Liquidity

    Treasury Bills vs CDs

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 25, 2026
    Updated: Sep 25, 2026
    Reading Time: 10–12 min


    Treasury Bills vs CDs: What Should You Know?
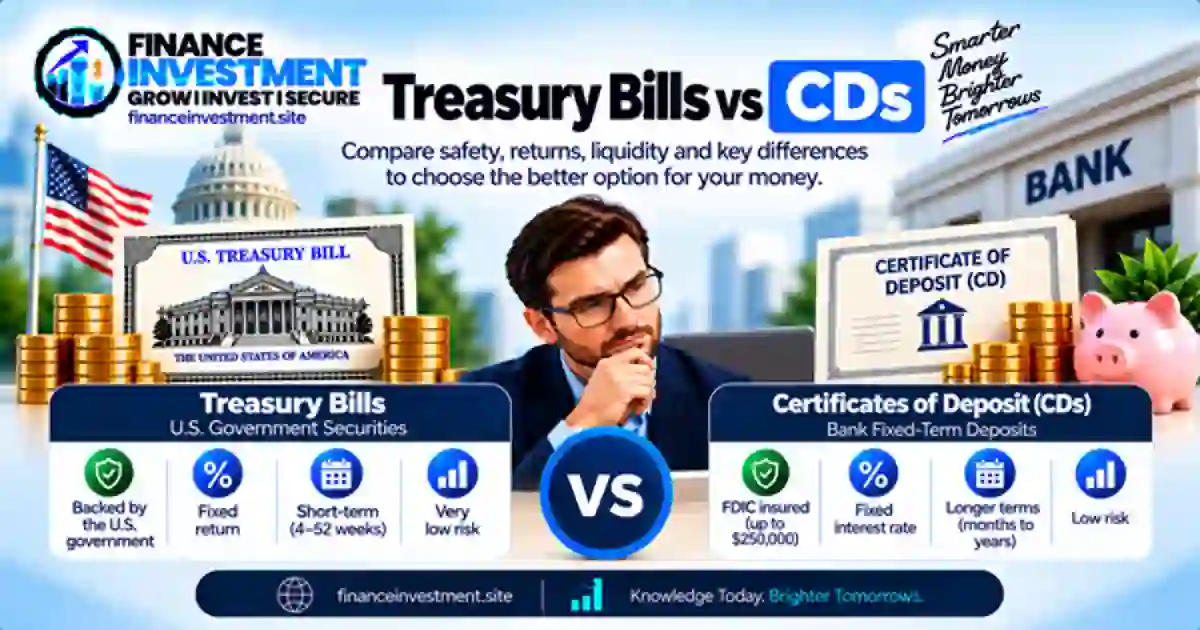
    Treasury Bills vs CDsTreasury Bills vs CDs is a useful comparison when you have cash to put aside and want to earn a return without taking on the volatility of stocks. Both can serve short-term savings goals, but they work differently. A T-bill is a short-term U.S. Treasury security, while a CD is a time deposit offered by a bank or credit union.

    The real difference shows up when you look past the advertised rate. The maturity date, access to your money, taxes, insurance, and what happens if your plans change can all affect the outcome. T-bills have maturities of one year or less, while CDs can come with a much wider range of terms.

    What You’ll Learn

    • How Treasury bills and CDs work from purchase to maturity.
    • How U.S. government backing differs from FDIC or NCUA insurance.
    • What can happen when you need your money before maturity.
    • How federal and state taxes can affect your actual return.
    • Which rates, fees, terms, and access rules deserve attention.
    • How to match each option with a short-term financial goal.

    If T-bills are new to you, start with our Treasury Bills Explained guide. It covers the basics before we get into the practical differences between T-bills and CDs.

    Quick Answer: Treasury Bills vs CDs

    Treasury bills and CDs can both fit short-term savings goals, but they are built differently. A T-bill is a short-term U.S. Treasury security with a maturity of one year or less. A CD is a time deposit from a bank or credit union with a specific term and account rules.

    Key Takeaways

    • Different products: T-bills are Treasury securities; CDs are deposit products.
    • Protection differs: T-bills are backed by the U.S. government, while eligible CDs at FDIC-insured banks can receive FDIC insurance within applicable limits.
    • Maturity differs: T-bills mature within one year, while CDs can have terms ranging from short periods to several years.
    • Early access differs: A CD may impose an early-withdrawal penalty. A marketable T-bill can generally be sold before maturity, but its market price may be higher or lower than the purchase price.
    • Taxes matter: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally taxable income.
    • Yield is only one factor: Compare the return with taxes, maturity, insurance, fees, access rules, and your cash timeline.

    BOTTOM LINE: Start with when you expect to need the money. Then compare the current T-bill yield or CD APY, applicable protection, tax treatment, fees, and the consequences of accessing the money early.

    Table of Contents

    Treasury Bills vs CDs at a Glance

    T-bills and CDs can both be used for money you expect to keep relatively stable, but they are structured differently. A T-bill is a marketable U.S. Treasury security with a maturity of one year or less. A CD is a time deposit with a specific term and institution-specific rules.

    BEST FOR

    T-bills may fit a defined cash timeline. CDs may fit savers who are comfortable committing money for a selected term.

    KEY NUMBERS

    T-bills mature in 1 year or less. Standard FDIC coverage is $250,000 per depositor, per insured bank, for each ownership category.

    FeatureTreasury BillsCDs
    ProductU.S. Treasury securityTime deposit at a bank or credit union
    MaturityOne year or lessSpecific term selected when opened
    ProtectionBacked by the U.S. government; not FDIC-insuredEligible bank CDs may receive FDIC insurance; eligible credit-union CDs may receive NCUA share insurance
    Early accessA marketable bill can generally be sold before maturity at the available market priceEarly withdrawal may involve a penalty or other product-specific restrictions
    ReturnFor a bill held to maturity, generally based on purchase price and maturity valueInterest is earned according to the CD’s stated terms

    QUICK TAKE: Don’t stop at the advertised return. Check the maturity, applicable insurance or government backing, taxes, access rules, and what happens if you need the money earlier than planned.

    Treasury Bills vs CDs: A Complete Beginner Guide
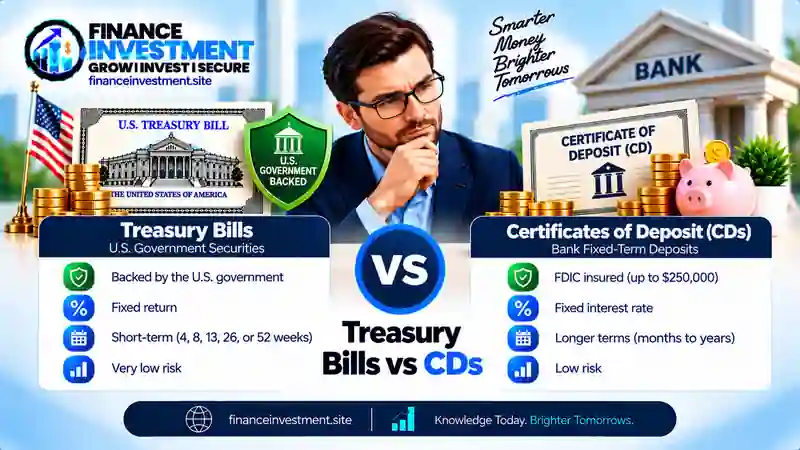
    Treasury Bills vs CDsIf you’re new to Treasury Bills vs CDs, start with the basic difference. A Treasury bill is a short-term U.S. government security. A CD is a time deposit offered by a bank or credit union. Both can be used for money you expect to keep relatively stable, but the way you earn and access that money is different.

    Treasury Bills in Simple Terms

    T-bills have maturities of one year or less. They are generally issued at a discount to face value, although an auction can result in a price at par. When a discounted bill reaches maturity, you receive its face value, with the difference between your purchase price and the amount received representing the interest earned.

    CDs in Simple Terms

    A certificate of deposit is a time deposit with a selected term. Traditional CDs commonly offer a fixed rate for that term, although the exact terms depend on the institution and CD type. Taking money out before maturity may trigger an early-withdrawal penalty, so the account’s disclosure matters before you open one.

    A SIMPLE WAY TO THINK ABOUT IT: A T-bill is a short-term Treasury security with a maturity date. A CD is a time deposit with a selected term. Once you understand that difference, compare the return, taxes, protection, and access rules.

    How Treasury Bills and CDs Work

    The practical difference becomes clearer when you follow the money from purchase to maturity. A T-bill is issued through a Treasury auction and has a defined maturity. A CD is opened with a bank or credit union for a selected term, with the institution’s terms controlling interest, maturity, and early access.

    How a Treasury Bill Works

    The Treasury sells bills through auctions. T-bills are issued at a discount and redeemed at their face value when they mature. For a discounted bill, the difference between the purchase price and the amount received at maturity is the interest earned. A marketable T-bill can generally be sold before maturity, but the sale price is determined by the market at that time.

    How a CD Works

    With a CD, you deposit money for a stated term and earn interest according to the CD’s terms. When the term ends, the deposit becomes available according to the institution’s maturity rules. If you need the money earlier, the CD agreement determines whether early withdrawal is permitted and what penalty or other restriction may apply.

    THE PRACTICAL DIFFERENCE: With a T-bill, getting out before maturity generally means selling a security at its current market price. With a CD, early access is governed by the deposit agreement and may involve a penalty.

    Treasury Bills vs CDs: Benefits and Drawbacks

    Neither product is automatically the right fit for every cash goal. The useful question is what you value most: a Treasury security with a defined maturity, or a time deposit with institution-specific terms.

    Treasury Bills: Pros and Cons

    PROS
    • Backed by the full faith and credit of the U.S. government.
    • Maturities of one year or less can fit short-term cash planning.
    • Interest is generally exempt from state and local income taxes.
    • Marketable T-bills can generally be sold before maturity.
    CONS
    • An early sale exposes you to the market price at that time.
    • Buying and managing Treasury securities may require more steps than opening a bank CD.
    • T-bills are securities, not FDIC-insured deposits.

    CDs: Pros and Cons

    PROS
    • Traditional CDs commonly provide a fixed rate for a defined term.
    • Different terms can accommodate different savings timelines.
    • Eligible bank CDs can receive FDIC insurance within applicable limits.
    • Eligible CDs at federally insured credit unions can receive NCUA share insurance.
    CONS
    • Early withdrawal may result in a penalty under the CD’s terms.
    • Your money may be less accessible during the selected term.
    • CD interest is generally subject to federal income tax and may also be subject to applicable state or local taxes.

    WHAT MATTERS MOST: A T-bill can be sold before maturity, but its market price can change. A traditional CD can keep its stated rate through the term, but early access may cost you through an early-withdrawal penalty. Your cash timeline should come first.

    Treasury Bills vs CDs: Detailed Comparison

    The headline return is only one piece of the puzzle. When comparing Treasury bills and CDs, look at how each product handles maturity, access, taxes, protection and what happens if your plans change.

    FeatureTreasury BillsCDs
    What you ownA short-term U.S. Treasury securityA time deposit with a bank or credit union
    MaturityOne year or lessThe term selected when the CD is opened
    ReturnFor a discounted bill held to maturity, the purchase price and maturity value determine the returnInterest is earned according to the CD’s stated terms
    ProtectionBacked by the U.S. government; not FDIC-insuredEligible bank CDs may receive FDIC insurance; eligible share certificates at federally insured credit unions may receive NCUA share insurance
    Early accessA marketable bill can generally be sold before maturity at the market price available thenEarly withdrawal depends on the CD agreement and may involve a penalty
    Federal taxInterest is generally subject to federal income taxInterest is generally taxable income
    State & local taxGenerally exempt from state and local income taxesMay be subject to applicable state and local income taxes
    Main trade-offDefined maturity with the ability to sell before maturity at the prevailing market priceDefined deposit term with early-access rules set by the CD

    HOW TO USE THIS TABLE: Start with your expected cash date. Then compare the current return, applicable protection, tax treatment and early-access rules. That gives you a more useful comparison than looking at the advertised rate alone.

    Costs, Risks and Expert Tips

    A good comparison goes beyond the advertised return. Before choosing a T-bill or CD, look at the cost of buying or exiting, the tax treatment, and what could happen if you need the money sooner than expected.

    Costs and Risks to Watch

    • T-bills: TreasuryDirect charges no purchase fee or commission. A broker may have its own charges or terms. Selling before maturity also means accepting the market price available at that time.
    • CDs: Check the specific CD agreement for early-withdrawal provisions, minimum deposit requirements, renewal terms, and any other conditions.
    • Taxes: Compare after-tax returns. T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. CD interest is generally taxable income.
    • Protection: Confirm whether a CD is held at an FDIC-insured bank or through a federally insured credit union, and check the applicable insurance rules and limits.

    Expert Tips Before You Buy

    1. Start with the date you expect to need the money.
    2. Compare the current T-bill yield with the CD’s APY after considering taxes and applicable costs.
    3. Read the CD disclosure, especially the early-withdrawal and maturity sections.
    4. If buying a T-bill, decide whether you can hold it to maturity or accept the possibility of a different market price if you sell early.

    EXPERT TIP: Don’t compare the rate alone. A slightly higher return may not matter if the product’s maturity, taxes, fees, or early-access rules don’t fit your plans.

    Common Mistakes and a Real-Life Example

    The rate may grab your attention first, but the details can matter more. A few common mistakes can make a T-bill or CD less convenient than expected.

    Common Mistakes to Avoid

    • Looking only at the highest rate: Taxes, fees, maturity and access rules can change the practical value of a return.
    • Ignoring the maturity date: Make sure the T-bill maturity or CD term fits your expected cash date.
    • Confusing selling with withdrawing: A marketable T-bill can generally be sold before maturity at its market price, while a CD follows the withdrawal terms in its agreement.
    • Forgetting tax differences: T-bill interest is generally exempt from state and local income taxes, while CD interest may be subject to applicable state and local taxes.
    • Assuming every CD has identical protection: Check whether the deposit is at an FDIC-insured bank or whether the share certificate is at a federally insured credit union.

    Real-Life Example

    Suppose a couple has $25,000 set aside for a home improvement project they expect to fund in about six months. They could compare a T-bill with a maturity close to that date against a CD whose term fits their timeline.

    They would then compare the current return, taxes, applicable insurance, and early-access rules. If the project date moves, the consequences also matter: selling a T-bill before maturity means accepting its market price, while accessing a CD early depends on the CD’s terms and any applicable penalty.

    KEY LESSON: Choose the time frame first, then compare the return. Matching the product to your cash date can prevent an avoidable early-access problem.

    Who Should Choose Treasury Bills or CDs?

    Your plans for the money can help narrow the choice. Consider how long you can leave it untouched, whether you prefer a Treasury security or a deposit account, and how each product’s terms affect your return.

    Treasury Bills May Fit If:

    • Your spending date matches an available short-term T-bill maturity.
    • You want to hold a security backed by the U.S. government.
    • The state and local income tax treatment matters to you.
    • You can hold until maturity or accept market-price risk if you sell early.

    CDs May Fit If:

    • You want a deposit product with a term suited to your savings goal.
    • You prefer the predictable rate offered by a traditional fixed-rate CD.
    • You can meet the minimum deposit and early-withdrawal conditions.
    • You have confirmed applicable FDIC coverage for an eligible bank CD or NCUA coverage for an eligible credit-union share certificate.

    ONE MORE THING: If you might need this money without warning, neither product should be treated like an everyday spending account. Keep your immediate cash needs in mind before committing to a maturity date or deposit term.

    Frequently Asked Questions About Treasury Bills vs CDs

    1. How do Treasury bills and CDs differ?

    A T-bill is a short-term U.S. Treasury security, while a CD is a time deposit offered by a bank or credit union. Their maturity, access, tax treatment and protection work differently.

    2. Are Treasury bills FDIC-insured?

    No. Treasury bills are not FDIC-insured deposits. They are U.S. Treasury securities backed by the full faith and credit of the U.S. government.

    3. Are CDs FDIC-insured?

    An eligible CD at an FDIC-insured bank can receive FDIC coverage within applicable limits. A share certificate at a federally insured credit union may receive NCUA share insurance instead.

    4. Can you sell a Treasury bill before maturity?

    Yes. A marketable T-bill can generally be sold before maturity, but the amount received depends on its market price at the time of sale.

    5. Can you withdraw money from a CD early?

    That depends on the CD’s terms. A traditional CD may allow early withdrawal with a penalty, while certain CD types can have different access rules.

    6. Are Treasury bill earnings exempt from state taxes?

    Generally, yes. Interest from U.S. Treasury securities is generally exempt from state and local income taxes, while federal income tax generally applies.

    7. Do CDs and Treasury bills have the same tax treatment?

    No. T-bill interest generally receives state and local tax exemption. CD interest is generally taxable income and may also be subject to applicable state and local taxes.

    8. Which should you compare for short-term cash?

    Compare the specific T-bill and CD based on your cash date, current return, taxes, fees, access rules and applicable protection. There is no single comparison that fits every situation.

    REMEMBER: A T-bill is a Treasury security, while a CD is a deposit product. Their insurance, tax and early-access rules should be evaluated separately.


    Treasury Bills vs CDs: Final Comparison

    Treasury bills and CDs can both be used for short-term cash planning, but they work in different ways. A T-bill is a short-term U.S. Treasury security with a defined maturity. A CD is a time deposit with a term and conditions set by the financial institution.

    Before comparing them, look at when you need the money, the current return, applicable taxes, protection, and early-access rules. With a T-bill, consider the maturity date and the market price if you sell before maturity. With a CD, review the term, rate, maturity instructions, and early-withdrawal provisions.

    FINAL CHECK: A useful comparison goes beyond the headline rate. Review the cash timeline, access rules, tax treatment, applicable insurance or government backing, and any costs before making a decision.

    For a broader introduction to Treasury securities, read our Treasury Bills Explained guide. You can also compare another short-term cash option in our CD vs Money Market Account guide.

    Have a Money Question? Keep Exploring.

    Understanding the details can make short-term money decisions easier to compare. Keep exploring FinanceInvestment for practical guides on Treasury bills, CDs, and other personal finance topics.

    📩 Get in Touch With FinanceInvestment

    Have a money question or a topic you’d like us to cover?
    Email FinanceInvestment

    Continue Your Research
  • Treasury Bill Price vs Face Value Explained: 2026 Guide

    Treasury Bill Price vs Face Value Explained: 2026 Guide

    Treasury Bill Price vs Face Value Explained

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    Published: September 21, 2026 • Updated: September 21, 2026 • Reading Time: 10–12 min


    Treasury Bill Price vs Face Value: Why the Difference Matters

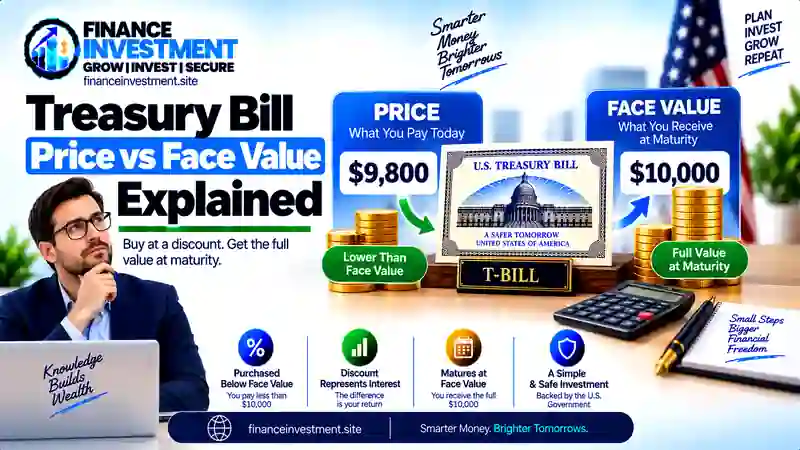
    Treasury Bill Price vs Face Value explained with T-bill pricing and maturity valueA Treasury bill can have a $1,000 face value but cost less than $1,000 when you buy it. That difference is a key part of how T-bills provide a return. Instead of receiving regular interest payments, you generally buy the bill at a discount and receive its face value when it matures.

    For example, suppose a $1,000 Treasury bill has a purchase price of $975. You pay $975 upfront. If you hold the bill until maturity, you receive $1,000. The $25 difference between your purchase price and the face value is the gross return built into that transaction, before considering taxes or any result from selling the bill before maturity.

    This is where beginners often get tripped up. Price, face value, discount rate and investment yield are connected, but they measure different things. Once you separate those numbers, a T-bill quote becomes much easier to read.

    In this guide, we’ll walk through the numbers step by step. We’ll also connect this topic with our complete Treasury Bills guide so you can see how pricing fits into the bigger picture.

    What You’ll Learn

    • What Treasury bill price and face value mean.
    • Why T-bills can be purchased below face value.
    • How the price difference becomes part of your return at maturity.
    • How price, discount rate and yield relate to each other.
    • How the purchase price affects your actual investment.
    • What can happen when you sell a T-bill before maturity.

    Quick Answer: How Is Treasury Bill Price Different From Face Value?

    A Treasury bill’s face value is the stated amount paid when the bill matures, while its purchase price is the amount you pay to acquire it. T-bills are generally issued at a price below their face value. The difference between those two amounts is the discount, which forms the basic return for an investor who holds the bill until maturity.

    Key Takeaways

    • The face value is the stated amount the Treasury bill is redeemed for at maturity.
    • The purchase price is the amount paid to acquire the bill.
    • For a T-bill issued at a discount, the purchase price is lower than its face value.
    • The difference between face value and purchase price is the discount amount.
    • T-bills do not make periodic coupon payments like Treasury notes and bonds.
    • The discount rate is a pricing measure and should not be treated as the same thing as the investor’s annualized return.

    BOTTOM LINE: Face value tells you the amount tied to the bill at maturity. Purchase price tells you what you pay upfront. When a T-bill is bought below face value and held to maturity, the difference between those amounts is the basic source of the return.

    Table of Contents

    Treasury Bill Price vs Face Value at a Glance

    The simplest way to read a Treasury bill is to separate its face value from its purchase price. For a newly issued T-bill sold at a discount, you pay less than the bill’s face value. If you hold it until maturity, the bill is redeemed for its stated face value. The difference between those amounts is the discount.

    Quick FactWhat It Means
    Face valueThe stated amount for which the T-bill is redeemed at maturity.
    Purchase priceThe amount an investor pays to acquire the T-bill.
    DiscountThe difference between the face value and the purchase price.
    MaturityThe date when the T-bill reaches the end of its stated term.

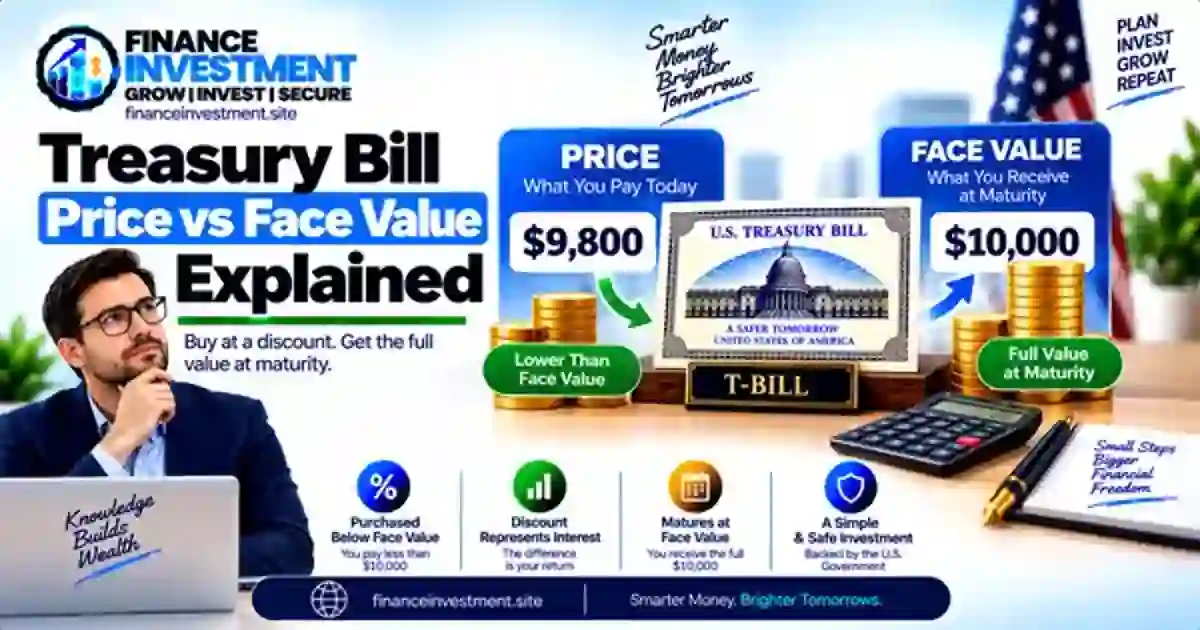
    QUICK TAKE: For example, if a hypothetical T-bill has a $10,000 face value and a $9,800 purchase price, the $200 difference is the discount. If the bill is held to maturity, the stated $10,000 face value is the maturity amount.

    Treasury Bill Price vs Face Value: A Complete Beginner Guide

    Treasury Bill Price vs Face ValueThe easiest way to understand a Treasury bill is to separate four numbers: face value, price per $100, purchase price, and discount amount. A newly issued T-bill is generally sold at a price below its face value. If you hold it until maturity, the bill is redeemed at its stated par amount. Treasury bills are short-term securities with maturities of one year or less and do not make periodic coupon payments.

    1. Start With Face Value

    Face value, also called par value, is the stated dollar amount of the T-bill. Suppose a bill has a $10,000 face value. If you hold that bill until maturity, the Treasury redeems it at its $10,000 par amount. You do not receive separate coupon payments during the bill’s term.

    2. Look at the Price Per $100

    Treasury bill pricing is expressed on a per-$100-of-face-value basis. For example, a price of $98.00 per $100 means an investor pays $98 for each $100 of face value. For a $10,000 bill, that works out to a $9,800 purchase price. Treasury’s rules use the price per $100 and the par amount to determine the total purchase price.

    3. Calculate the Discount Amount

    If the $10,000 bill costs $9,800, the discount amount is $200. That is simply the face value minus the purchase price. If you hold the bill until maturity, this difference represents the interest earned through the bill’s discounted purchase structure.

    4. Don’t Confuse Price With the Discount Rate

    The price tells you how much the bill costs. The discount rate expresses the price difference as an annualized rate using the bill’s face value and a 360-day convention. Treasury uses the discount rate to derive the price per $100. So a quoted discount rate and the resulting purchase price are connected, but they are not the same thing.

    BEGINNER TIP: When reading a T-bill quote, ask three questions first: What is the face value? What is the price per $100? How much will I actually pay? Once those numbers are clear, the discount and annualized rates become much easier to understand.

    How Treasury Bill Pricing Works

    Treasury bill pricing follows a simple chain: the discount rate helps determine the price per $100 of face value, and that price determines how much you actually pay. The face value does not change. What changes is the amount required upfront to buy the bill.

    Step 1: Convert the Discount Rate Into a Price

    Treasury’s formula for converting a T-bill discount rate into a price per $100 is:

    Price per $100 = 100 × [1 − (Discount Rate × Days to Maturity ÷ 360)]

    For example, using a hypothetical 5% discount rate and 91 days to maturity, the calculated price is approximately $98.736 per $100 of face value before applying the applicable auction-price rounding convention.

    Step 2: Calculate the Purchase Price

    Once the price per $100 is known, Treasury calculates the purchase price by dividing the bill’s face value by 100 and multiplying that amount by the price per $100. For a $10,000 face-value T-bill priced at $98.736 per $100, the approximate purchase price would be $9,873.60.

    Step 3: Find the Discount

    The discount is simply the difference between face value and purchase price. In this example, $10,000 minus $9,873.60 equals approximately $126.40. If the bill is held to maturity, that price-to-face-value difference is the basic return built into the T-bill’s discounted structure.

    Key point: The price tells you what you pay. Face value tells you the amount associated with maturity. The discount connects the two, while the quoted discount rate is the annualized rate calculated using Treasury’s 360-day convention.

    Treasury Bill Price vs Face Value: Benefits & Drawbacks

    The difference between a Treasury bill’s price and face value creates a straightforward way to understand how the bill’s return is built. Still, the price alone does not tell you everything about the investment. Maturity, taxes, market prices and your holding period can all affect the final result.

    Benefits of the T-Bill Pricing Structure

    • Simple purchase structure: Newly issued Treasury bills are generally bought below face value, with the discount built into the purchase price.
    • No periodic coupon payments: T-bills do not make regular interest payments during their term. The difference between the purchase amount and the amount received at maturity represents interest when held to maturity.
    • Easy price comparison: The price per $100 makes it easier to compare the upfront cost with the bill’s face value.
    • Predictable maturity amount: If you hold the bill until maturity, the Treasury pays the stated face amount, subject to applicable tax withholding or other account-specific considerations.

    Drawbacks to Consider

    • Price and yield are different: A lower purchase price increases the dollar discount, but it should not be confused with the annualized investment rate.
    • Early sale can change the result: If you sell a T-bill before maturity through a brokerage, its market price may be above or below your original purchase price.
    • Federal taxes apply: Treasury bill interest is subject to federal income tax, although it is generally exempt from state and local income taxes.
    • Inflation still matters: A positive T-bill return does not automatically mean your purchasing power increased after inflation.
    Quick Take: Face value shows the amount tied to maturity, while price shows your upfront cost. The difference can create interest when the bill is held to maturity, but investors should also consider annualized yield, taxes, inflation and the possibility of selling before maturity.

    Treasury Bill Price vs Face Value vs Yield

    Treasury bill price, face value, discount rate and investment rate are connected, but they are not interchangeable. Face value shows the bill’s stated amount at maturity. Price shows the amount paid upfront. The investment rate, also called the coupon-equivalent yield, expresses the annualized return based on the bill’s purchase price.

    TermWhat It MeansWhat It Tells You
    Face ValueThe bill’s stated par amountAmount associated with maturity
    Purchase PriceThe amount paid for the T-billYour upfront investment
    Discount RateAn annualized rate calculated using par valueThe discount quoted on a 360-day basis
    Investment RateAn annualized rate based on purchase priceA more useful measure for comparing the bill’s return with other investments

    Why the Discount Rate and Investment Rate Differ

    Consider a hypothetical T-bill with a $10,000 face value and a purchase price of $9,800. The $200 difference is the discount. However, that $200 is not automatically a 2% annual return because the bill has a specific time remaining until maturity. The investment rate accounts for the actual purchase price and the holding period. Treasury normally calculates this rate using a 365-day basis, or 366 days when applicable.

    Quick Take: Face value tells you the bill’s stated maturity amount. Price tells you what you pay. The discount rate describes the discount using par value, while the investment rate annualizes the return based on the price you actually paid.

    Treasury Bill Price vs Face Value: Costs, Risks & Expert Tips

    A Treasury bill does not work like a savings account that simply pays a stated interest rate. Your result depends on the price you pay, the amount tied to maturity, the time you hold the bill and the taxes that apply. Looking at these details before buying can prevent common misunderstandings.

    Costs to Check Before Buying

    • Purchase price: This is the actual amount committed upfront and should be compared with the bill’s face value.
    • Brokerage charges: If you buy through a broker, check the firm’s current pricing, spreads or other applicable charges. Costs can vary by provider.
    • Taxes: Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes under federal tax rules.

    Risks to Understand

    • Early-sale price risk: If you sell before maturity, the market price may be different from the amount you originally paid. The result can therefore differ from simply holding the bill to maturity.
    • Reinvestment risk: When the bill matures, a new Treasury bill may offer a different rate, so the same return may not be available when you reinvest.
    • Inflation risk: A positive nominal return does not guarantee an increase in purchasing power after inflation.
    Expert Tip: Before buying, write down the face value, purchase price, maturity date and investment rate. Then compare the return with your actual money invested—not just the face value shown on the T-bill quote.

    Common Treasury Bill Pricing Mistakes & Real-Life Example

    Treasury bill pricing becomes much easier when you keep the key numbers separate. Beginners often make mistakes by treating face value, purchase price, discount rate and investment rate as if they were interchangeable.

    Common Mistakes to Avoid

    • Confusing face value with purchase price: A $10,000 face-value T-bill can cost less than $10,000 when it is issued at a discount.
    • Treating the discount rate as the actual return: Treasury’s discount rate and investment rate use different calculations and day-count conventions.
    • Ignoring the holding period: The dollar discount alone does not show the annualized return because the time until maturity also matters.
    • Assuming early sale equals maturity: Selling before maturity can produce a different result because the T-bill’s market price may change.

    Real-Life Example

    Suppose an investor buys a hypothetical Treasury bill with a $10,000 face value for $9,800 and holds it until maturity. The investor pays $9,800 upfront and receives the $10,000 face amount at maturity. The $200 difference is the interest income created by the discounted purchase price. It should not, however, be described as a 2% annual return because the investment rate also depends on the time to maturity and the purchase price.

    Beginner Tip: When reviewing a T-bill quote, check the face value, price per $100, purchase price and maturity date first. Then look at the discount rate or investment rate. This order makes it easier to understand what you are paying and how the quoted return is calculated.

    Who May Consider Treasury Bills?

    Treasury bills may fit investors looking for short-term U.S. government debt and a defined maturity date. Because newly issued T-bills are generally sold at a discount, investors can compare the purchase price with the amount received at maturity when evaluating a potential investment.

    T-Bills May Fit These Situations

    • Short-term goals: You have money that can remain invested until a known maturity date.
    • Defined maturity: You prefer a Treasury security with a specific date when the bill matures.
    • Price-based investing: You want to evaluate an investment using its purchase price, face value and annualized rate.
    • Federal Treasury exposure: You want a direct U.S. government debt security rather than a corporate or municipal obligation.
    • Tax considerations: Treasury bill interest is subject to federal income tax but exempt from state and local income taxes under federal tax rules.

    When to Compare Other Options

    A T-bill may not match every cash need. If you need unrestricted access to your money, want periodic interest payments, or expect to sell before maturity, compare the relevant features, costs and risks of other short-term investments before making a decision.

    Quick Take: The right fit depends on your time horizon, liquidity needs, tax situation and how you plan to hold the T-bill. The price-versus-face-value relationship is only one part of that decision.

    Frequently Asked Questions About Treasury Bill Price vs Face Value

    1. What is the difference between Treasury bill price and face value?

    Face value is the stated par amount of a Treasury bill. The purchase price is the amount you pay upfront. Treasury bills are generally issued at a discount, so the purchase price can be lower than the face value paid at maturity.

    2. Why are Treasury bills sold below face value?

    Treasury bills generally do not make periodic coupon payments. Instead, they are issued at a discount, and the difference between the discounted purchase price and the face value received at maturity represents interest income when the bill is held to maturity.

    3. Is the Treasury bill discount rate the same as the investment rate?

    No. Treasury calculates the discount rate using the bill’s par value and a 360-day convention. The investment rate, also called the coupon-equivalent yield, is calculated from the purchase price and the applicable annual day count. These rates therefore can differ even for the same T-bill.

    4. How do I calculate the discount on a T-bill?

    Subtract the purchase price from the face value. For example, a hypothetical $10,000 face-value T-bill purchased for $9,800 has a $200 discount. If held to maturity, that difference represents the bill’s interest income before considering applicable taxes.

    5. Can a Treasury bill’s market price change after I buy it?

    Yes. If you sell a T-bill before maturity through a brokerage, its market price can change as market conditions change. The amount you receive from an early sale can therefore differ from the amount you would receive by holding the bill until maturity.

    6. Are Treasury bill earnings taxable?

    Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes under federal tax rules. Your individual tax situation may require additional considerations.

    Bottom Line: Face value, purchase price, discount rate and investment rate describe different parts of a Treasury bill. Keeping those figures separate makes T-bill quotes much easier to compare and understand.

    Final Verdict: Understanding Treasury Bill Price vs Face Value

    The difference between Treasury bill price and face value comes down to one simple idea: face value is the bill’s stated par amount, while the purchase price is what you pay upfront. When a T-bill is purchased at a discount and held to maturity, the difference between those amounts represents interest income.

    For a broader explanation of T-bill maturities, pricing, buying methods and how Treasury bills work, continue with our complete Treasury Bills guide. It provides a useful next step if you want to understand the bigger picture beyond price versus face value.

    For this specific topic, check the purchase price, face value, maturity date and applicable investment rate together. The discount rate is a separate measure and should not automatically be treated as the investment’s annualized return. If you sell before maturity, the market price can also affect the amount you receive.

    Bottom Line: Price tells you what you pay. Face value tells you the stated amount associated with maturity. Comparing both with the maturity period and investment rate gives you a clearer picture of a Treasury bill’s pricing and potential return.

    Have a Money Question? Keep Exploring.

    Understanding Treasury bills starts with knowing what you pay, what the bill is worth at maturity and how the stated rate is calculated. Keep exploring FinanceInvestment for practical guides that can help you understand different short-term investing topics.

    📩 Get in Touch With FinanceInvestment
    Have a finance question, topic suggestion or feedback?
    Email FinanceInvestment