Tag: Fixed Income Investing

  • Who Should Buy Treasury Bills? A 2026 Guide

    Who Should Buy Treasury Bills? A 2026 Guide

    Who Should Buy Treasury Bills?
    Subhash Rukade
    Founder, FinanceInvestment


    Published: Sep 28, 2026


    Updated: Sep 28, 2026


    Reading Time: 12–15 min


    Who Should Buy Treasury Bills?Choosing where to keep your money becomes easier when you first define the job that money needs to perform. Treasury bills can be useful for investors who want to keep funds relatively conservative while working toward a short-term goal, managing cash, or covering an upcoming expense.

    That does not mean T-bills belong in every portfolio. Someone saving for a home purchase within a year may have very different needs from a retiree managing living expenses or an investor building long-term wealth. The right decision can depend on your time horizon, liquidity needs, risk tolerance, tax situation, and what you plan to do with the money when the bill matures.

    If Treasury bills are new to you, begin with our Treasury Bills Explained guide. Then use this guide to determine which types of investors may find T-bills useful, who may want to consider other options, and what to check before placing an order.

    What You’ll Learn

    • Which investors may consider Treasury bills for short-term goals.
    • How T-bills can fit into cash-management and conservative strategies.
    • How beginners, retirees, and families may approach them differently.
    • When Treasury bills may not match an investor’s needs.
    • How T-bills compare with CDs, savings accounts, and money market options.
    • Which risks, taxes, liquidity considerations, and reinvestment decisions deserve attention.

    Quick Answer: Who Should Consider Treasury Bills?

    Treasury bills may be a reasonable option for investors who have cash to invest for a defined short-term period and want exposure to short-term U.S. government debt. They can also fit a portfolio when the priority is keeping money in a relatively conservative investment rather than taking stock-market risk for a near-term goal.

    A beginner might use T-bills to gain experience with fixed-income investing. A retiree could consider them for money needed for upcoming expenses, while a family might use them for a known financial goal with a clear timeline. In each case, the maturity should match when the money is likely to be needed.


    KEY TAKEAWAYS

    • T-bills are short-term U.S. Treasury securities.
    • They may suit investors with defined short-term cash needs.
    • The maturity should match the investor’s expected timeline.
    • They can play a role in conservative cash-management strategies.
    • Federal taxes, state-tax treatment, liquidity, reinvestment, and overall portfolio goals still matter.

    So the better question is not simply whether Treasury bills are a good investment. It is whether their maturity, risk profile, tax treatment, and expected use of the cash match your particular financial goal.

    Who Should Buy Treasury Bills? at a Glance

    The right investor depends on why the money is being invested, when it will be needed, and how much market risk the investor is willing to accept. This quick comparison shows where Treasury bills may fit before we examine each situation more closely.

    Investor TypePotential UseImportant Check
    BeginnersShort-term fixed-income investing and learning how Treasury securities work.Understand maturity, purchase price, taxes, and reinvestment.
    RetireesMoney reserved for expenses with a defined near-term timeline.Keep enough readily accessible cash for expenses and emergencies.
    FamiliesFunds set aside for a known goal with a relatively clear date.Choose a maturity that does not conflict with the planned expense.
    Conservative InvestorsShort-term exposure to U.S. Treasury securities within a broader portfolio.Consider reinvestment needs, liquidity, taxes, and opportunity cost.

    QUICK TAKE

    Treasury bills may fit when the investment’s maturity matches the purpose and timing of the money. They should not automatically replace an emergency fund, long-term growth investments, or cash that must remain immediately available.

    Treasury Bills for Beginners
    Who Should Buy Treasury Bills?For someone buying Treasury bills for the first time, the basic structure is worth understanding before placing an order. A T-bill is a short-term U.S. Treasury security with a stated maturity date. It is generally issued at a price below its face value, and the investor receives the face value when the bill matures.

    That structure makes the maturity date especially important. Before buying, a beginner should ask a simple question: When will I need this money? The answer can help determine which maturity fits the intended use of the cash. Money needed soon should not be committed to an investment whose timing does not match the expense.

    What Beginners Should Understand First

    • Purchase price: T-bills are generally purchased for less than their face value.
    • Maturity date: The Treasury pays the bill’s face value when it matures.
    • Tax treatment: Interest from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes.
    • Early sale: If you sell before maturity, the market price may be higher or lower than the amount you originally paid.
    • Reinvestment: When a bill matures, you must decide whether to use the money or invest it again.

    BEGINNER TIP

    Before buying your first T-bill, separate money that must remain immediately available from money that can stay invested until a planned maturity date. That small step can prevent a timing mismatch later.

    Treasury Bills for Retirees

    For retirees, Treasury bills may be considered for money connected to upcoming spending needs rather than as a replacement for an entire retirement portfolio. Their short maturities can make them useful when an investor wants to coordinate certain cash needs with a defined investment timeline.

    For example, a retiree expecting a significant expense several months from now could look at a T-bill whose maturity is reasonably close to that expected need. The important point is to work backward from the spending date instead of choosing a maturity first and figuring out the cash requirement later.

    What Retirees Should Consider

    • Cash-flow timing: Consider whether the maturity date fits an expected withdrawal or major expense.
    • Accessible cash: Keep a separate amount readily available for emergencies and expenses that cannot be predicted.
    • Reinvestment: Have a plan for the money when a T-bill matures, especially if another expense is approaching.
    • Tax treatment: Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • Portfolio role: T-bills can address certain short-term needs, while other investments may serve longer-term income or growth objectives.

    RETIREMENT TIP

    A practical approach is to start with the spending timeline. If money is needed before a T-bill matures, that investment may not match the purpose. Keep the maturity schedule aligned with the retirement cash-flow plan.

    Treasury Bills for Families and Short-Term Goals

    Family savings often have a specific purpose, such as upcoming tuition, a home project, a vehicle purchase, or another planned expense. Treasury bills may fit when the money has a reasonably clear timeline and can remain invested until the chosen maturity date.

    For example, imagine a family setting aside $8,000 for a home improvement project expected about six months from now. A 26-week Treasury bill could be one option to evaluate alongside a savings account or CD. The family would need to consider when the money will be needed, how accessible it must remain, applicable taxes, and whether the project date could change.

    Family Goals That May Fit a T-Bill Timeline

    • Planned purchases: Money reserved for a vehicle, appliance, or other expense with a reasonably defined date.
    • Upcoming education costs: Funds intended for tuition or other school expenses due within a shorter time frame.
    • Home projects: Savings that can remain invested until contractors, materials, or other costs are due.
    • Specific short-term goals: Money assigned to a known purpose rather than everyday household spending.

    FAMILY SAVINGS TIP

    Keep emergency savings separate from money committed to a Treasury bill. If the timing of a family expense is uncertain, access to cash may matter more than locking in a specific maturity. Families with several expenses at different dates can also explore a Treasury bill ladder to spread maturities across multiple dates.

    Treasury Bills for Conservative Investors

    Investors who prefer to keep some money in short-term government securities may consider Treasury bills as one part of their overall strategy. T-bills are short-term obligations of the U.S. Treasury with defined maturity dates, making the timing of the investment an important part of the decision.

    An investor might purchase an individual bill for a specific future cash need or use several maturities to create a ladder. The amount allocated and the maturity selected should reflect the investor’s cash requirements, existing portfolio, and willingness to accept the trade-offs associated with short-term fixed-income investing.

    Why Some Conservative Investors Consider T-Bills

    • Short maturities: Investors can select Treasury bill terms that align with different short-term timelines.
    • Defined maturity dates: Each bill has a scheduled maturity, which can help with planning for known future cash needs.
    • U.S. government obligation: Treasury bills are direct obligations of the U.S. government.
    • Flexible structuring: Multiple maturities can be combined when an investor wants money to become available at different dates.

    INVESTOR TIP

    A conservative approach still involves trade-offs. Before buying T-bills, consider liquidity, reinvestment risk, inflation, taxes, and whether your portfolio also needs assets intended for longer-term growth.

    T-Bills vs. Other Cash Options

    Treasury bills are one option for short-term money, but they work differently from bank deposit accounts and CDs. Before choosing where to keep cash, consider when you need the money, how easily you need to access it, and whether the funds are intended for spending, saving, or investing.

    OptionHow It May Be UsedImportant Consideration
    Treasury BillsShort-term money with a defined Treasury maturity.Maturity timing, early-sale price, taxes, and reinvestment.
    High-Yield Savings AccountCash that may need relatively easy access.Interest rates can change; FDIC coverage depends on the bank and account eligibility.
    Money Market AccountSavings with account features that may provide access to funds.Rates, fees, transaction rules, and FDIC coverage depend on the account.
    CDMoney committed for a stated deposit term.Maturity date, early-withdrawal rules, and applicable FDIC coverage.

    QUICK TAKE

    The choice depends on the job of the money. T-bills have defined maturities, while deposit accounts may provide easier access. CDs also use fixed terms, but they are bank deposits rather than Treasury securities. Compare liquidity, taxes, insurance coverage, and timing before committing the cash.

    Treasury Bill Risks and When They May Not Fit

    Treasury bills are direct obligations of the U.S. government, but their government backing does not make every T-bill strategy suitable for every investor. The main questions are when you need the money, whether you can hold the bill until maturity, and what role the investment plays in your broader financial plan.

    Key Risks to Understand

    • Market price risk: If you sell a T-bill before maturity, its market price may be higher or lower than your purchase price because market conditions can change.
    • Reinvestment risk: When a T-bill matures, a new bill may not offer the same return or terms as the one that matured.
    • Inflation risk: Inflation can reduce the purchasing power of the money you receive at maturity.
    • Timing risk: If your money is needed before the selected maturity date, you may have to sell the bill rather than simply waiting for maturity.
    • Opportunity cost: Money committed to short-term Treasury securities may not capture the potential long-term growth of investments with greater market risk.

    When T-Bills May Not Fit

    T-bills may not match money that needs to remain immediately accessible, a long-term goal where growth is a major priority, or an expense whose timing is uncertain. They may also create a mismatch if the selected maturity extends beyond the date when the money is expected to be needed.


    RISK CHECK

    Before buying, identify the amount you can leave invested, the date you may need the money, and whether you are prepared to hold the bill until maturity. If those details do not line up, reconsider the maturity or compare another cash option.

    How to Buy Treasury Bills

    U.S. investors can generally buy Treasury bills directly through TreasuryDirect or through a brokerage that offers Treasury securities. TreasuryDirect provides access to Treasury auctions, while a brokerage may provide access to new issues and, depending on the platform, Treasury securities available in the secondary market.

    A Simple Buying Process

    1. Choose where to buy: Compare TreasuryDirect and brokerage features based on how you plan to manage the investment.
    2. Choose a maturity: Select a T-bill term that fits the date when you expect to need the money.
    3. Review the offering: Check the security type, auction information, purchase amount, and transaction details.
    4. Submit the order: Follow the platform’s instructions and confirm the order before completing the purchase.
    5. Plan for maturity: Decide whether you will use the proceeds or reinvest them when the bill matures.

    BUYING TIP

    For a first purchase, start with the purpose and maturity date rather than the purchase platform. The account you use is only one part of the decision; the timing of the investment should match the job assigned to the money.

    Real-Life Example: Matching a T-Bill to a Financial Goal

    Consider a hypothetical family with $20,000 that is not needed for everyday spending. They expect to use $10,000 for a home renovation in about six months and anticipate another $10,000 expense later in the year. Rather than treating the full amount as one pool of cash, they could separate the money according to its purpose and expected timing.

    Step 1: Start With the Spending Date

    The family could first identify when the renovation payment is expected and then evaluate a Treasury bill whose maturity fits that timeline. The purpose is not to choose a maturity simply because it is available. The timing should work with the planned expense so the family does not have to sell the investment unexpectedly.

    Step 2: Separate Emergency Cash

    The family should keep emergency savings and money needed for unpredictable household bills outside the T-bill allocation. A planned expense can have a maturity date, but an emergency cannot. Keeping those two purposes separate can make the cash plan easier to manage.

    Step 3: Decide What Happens at Maturity

    When the T-bill matures, the family can use the proceeds for the planned expense or reassess the money if the goal has changed. If the funds are still needed later, they can evaluate another short-term investment based on the terms and circumstances available at that time.


    STRATEGY CHECK

    A thoughtful T-bill strategy starts with the financial goal rather than the security itself. Identify how much money can be invested, when it may be needed, how much access is required, and what maturity fits those conditions.

    The same planning process can be adapted to different situations. A retiree might organize cash around upcoming withdrawals, while a beginner could use it for a known purchase or a family goal. The amounts and dates will vary, but the basic sequence remains useful: purpose first, timing second, investment third.

    Treasury Bills FAQs

    Who should consider buying Treasury bills?

    Investors with defined short-term cash needs, a preference for short-term Treasury securities, or money tied to a known future date may consider T-bills as one option.

    Are Treasury bills suitable for beginners?

    They may be considered by beginners who understand the purchase price, maturity date, tax treatment, early-sale considerations, and reinvestment decisions before investing.

    Are Treasury bills suitable for retirees?

    They may fit certain short-term retirement cash needs, but their role should be considered alongside the investor’s broader retirement income and investment plan.

    Can Treasury bills lose money?

    If a T-bill is sold before maturity, its market price can be higher or lower than the purchase price. Holding the bill until maturity is a different situation because the Treasury pays its face value at maturity.

    Are Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    Related Resources and Authority Sources

    Before buying Treasury bills, it can help to review both practical investing guides and official government information. The resources below cover T-bill basics, purchasing, maturity structures, and federal tax treatment.

    FinanceInvestment Guides

    Official and Educational Sources

    Have a Money Question? Keep Exploring.

    Treasury bills can serve different purposes depending on your timeline and cash needs. Before buying, make sure the maturity, liquidity, taxes, and investment purpose fit your financial plan.
    📩 Get in Touch With FinanceInvestment


    subhashr325@gmail.com
  • Treasury Bills for Conservative Investors: Complete 2026 Guide

    Treasury Bills for Conservative Investors: Complete 2026 Guide

    Treasury Bills for Conservative Investors

    Subhash Rukade
    Founder, FinanceInvestment


    Published: Sep 27, 2026


    Updated: Sep 27, 2026


    Reading Time: 12–15 min


    Treasury Bills for Conservative Investors: A Practical Starting Point

    Treasury Bills for Conservative Investors can be worth considering when your priority is keeping short-term money in a U.S. Treasury security rather than taking on the larger price swings associated with stocks or longer-term investments. Treasury bills have short maturities, with regular terms ranging from a few weeks to one year.

    Still, conservative investing is not simply about avoiding volatility. A retiree may want part of a cash reserve to line up with upcoming expenses. A family may be setting money aside for a planned purchase. A beginner may want a straightforward way to understand short-term government securities without turning every savings decision into a complicated investment plan.

    This guide looks at T-bills from that practical perspective. If you want the foundation first, our Treasury Bills Explained guide covers the basics. Here, we will focus on the questions conservative investors usually care about: maturity, access, taxes, inflation, reinvestment and alternatives.

    What You’ll Learn

    • Why T-bills may appeal to investors who place a high value on capital preservation.
    • How maturity dates can shape a conservative short-term strategy.
    • What changes when you hold a T-bill to maturity versus selling it earlier.
    • How T-bills compare with CDs, savings accounts and money market accounts.
    • How taxes, inflation and reinvestment can affect the overall picture.
    • When a Treasury bill ladder may help organize several future cash needs.

    The goal is simple: understand what T-bills can offer, where their limitations are, and how they may fit alongside the other pieces of a conservative financial plan.

    How Treasury Bills Can Fit a Conservative Investment Strategy

    Treasury bills can be part of a conservative investment strategy when the goal is to keep short-term money in a U.S. Treasury security while accepting a defined maturity and a return that can change as market conditions change. Their short terms can make them useful for matching money with expenses that have a known or approximate time frame.

    That does not make T-bills identical to cash in a bank account. If you sell a bill before maturity, its market price may be higher or lower than the amount you paid. Reinvestment is another consideration because the rate available when one bill matures may differ from the rate available for the next bill.

    Quick Take: T-bills may fit investors who have short-term cash needs, value the credit quality of the U.S. Treasury, and want a defined maturity date. The decision should still account for liquidity, taxes, inflation, reinvestment needs and available alternatives.

    Key Points to Remember

    • T-bills are short-term U.S. Treasury securities with maturities of one year or less.
    • They are generally issued at a discount to face value and pay face value at maturity.
    • Treasury bill interest is subject to federal income tax but is generally exempt from state and local income taxes.
    • Holding a bill until maturity avoids the need to sell at an interim market price.
    • A Treasury bill ladder can spread maturity dates across different future cash needs.

    Treasury Bills for Conservative Investors at a Glance

    Before deciding where T-bills might fit, it helps to understand their basic structure. Treasury bills are short-term U.S. Treasury securities with maturities of one year or less. TreasuryDirect lists regular bill terms such as 4, 8, 13, 26 and 52 weeks. They are typically purchased at a discount to face value, with the difference representing the return when the bill matures.

    FeatureWhat It Means for Conservative Investors
    MaturityShort-term terms can help match an investment with a defined future cash need.
    Return StructureT-bills are generally bought below face value, with the difference paid at maturity representing the interest.
    Credit QualityThey are obligations of the U.S. Treasury, so federal government credit quality is an important consideration.
    TaxesT-bill interest is subject to federal income tax and is generally exempt from state and local income taxes.
    Early SaleSelling before maturity exposes the investor to the current market price, which can be different from the original purchase price.

    QUICK TAKE: T-bills offer short maturities and U.S. Treasury credit exposure, but they still require planning. Match the maturity with your expected cash needs, understand the tax treatment, and keep truly immediate emergency money separate when necessary.

    Treasury Bills for Conservative Investors: A Complete Beginner Guide

    Treasury Bills for Conservative InvestorsIf you are new to Treasury bills, think of a T-bill as a short-term U.S. government debt security. You generally buy it for less than its face value, hold it until maturity, and receive the face value when it matures. The difference between the purchase price and face value represents the interest earned.
    1. Start With Your Cash Timeline

    Before looking at yields, ask when you expect to need the money. A shorter bill may fit a near-term expense, while a longer maturity may work when the money can remain invested for several months. Your timeline should guide the maturity rather than choosing a bill simply because its quoted yield looks attractive.

    2. Choose Where You Will Buy

    Treasury bills can be purchased through TreasuryDirect or through a brokerage that offers Treasury securities. With a noncompetitive bid at auction, you specify how much you want to invest and accept the yield determined at the auction. This can be a straightforward approach for many beginners.

    3. Have a Maturity Plan

    When the bill matures, decide what the money needs to do next. You can use the proceeds for the planned expense, keep them in another cash option, or reinvest them into another Treasury bill. Thinking about that next step before maturity can make a conservative T-bill strategy easier to manage.

    How Treasury Bills Work for Conservative Investors

    Once you understand the basic idea, Treasury bills follow a fairly straightforward process. The key pieces are the auction, the purchase price, the maturity date and what happens if you decide to sell before maturity.

    Step 1: Place a Noncompetitive Bid

    Individual investors can generally purchase new T-bills through TreasuryDirect or an eligible brokerage. With a noncompetitive bid, you specify the amount you want to buy and agree to accept the yield determined at the auction, subject to the auction’s terms.

    Step 2: Buy Below Face Value

    Treasury bills generally use discount pricing rather than periodic interest payments. For example, a bill with a $10,000 face value could be purchased for less than $10,000. If held to maturity, the investor receives the $10,000 face value, and the difference between the purchase price and face value represents the interest.

    Step 3: Decide Whether to Hold or Sell

    Holding a T-bill until maturity avoids the need to sell it at an interim market price. If you need the money earlier, you may be able to sell the bill through your brokerage in the secondary market. The price at that time can be above or below your purchase price, depending on market conditions.

    Conservative Investor Tip: Match the maturity with your expected cash need whenever practical. A good time match can reduce the chance of selling early because the money is needed sooner than planned.

    Benefits and Drawbacks of Treasury Bills for Conservative Investors

    Treasury bills have features that may appeal to conservative investors, but they are not designed to solve every short-term cash need. The useful question is how their maturity, tax treatment and market behavior fit with your specific financial timeline.

    Potential Benefits

    • Short maturities: Terms of one year or less can help investors match T-bills with defined short-term goals.
    • U.S. Treasury obligation: T-bills are issued by the U.S. Treasury, so federal government credit quality is a central consideration.
    • Tax treatment: T-bill interest is generally exempt from state and local income taxes.
    • Multiple maturity choices: Different terms can help investors stagger when portions of their money mature.

    Potential Drawbacks

    • Early-sale risk: Selling before maturity means accepting the current market price, which may be higher or lower than your purchase price.
    • Reinvestment risk: Rates available when a bill matures may be lower than the rate on the bill you previously held.
    • Inflation risk: The return may not fully offset increases in the cost of goods and services.
    • Access planning: Money committed to a maturity date should be separated from cash needed immediately for unexpected expenses.

    Bottom Line: T-bills combine short maturities with U.S. Treasury credit exposure, but conservative investing still involves trade-offs. Before buying, consider when you need the money, how long you can leave it invested, and what you will do when the bill matures.

    T-Bills vs. Other Conservative Options

    For conservative investors, comparing the quoted rate is only one part of the decision. T-bills, high-yield savings accounts, money market deposit accounts and CDs have different rules for access, maturity, taxes and protection. The right comparison starts with what the money is supposed to do.

    OptionAccessTime StructureImportant Consideration
    T-BillsFunds are scheduled for maturity; early sale may be available through a brokerage.One year or lessU.S. Treasury security; interest is generally exempt from state and local income taxes.
    High-Yield SavingsGenerally designed for ongoing deposits and withdrawals, subject to account terms.No fixed maturityRate can change; eligible deposits at FDIC-insured banks can receive deposit insurance within applicable limits.
    Money Market AccountGenerally provides relatively easy access to deposited funds, subject to account rules.No fixed maturityA bank money market deposit account may be FDIC-insured within applicable limits; it is different from a money market mutual fund.
    CDFunds are generally committed for a fixed term; early withdrawal rules vary.Fixed termEligible bank CDs can receive FDIC insurance within applicable limits; interest is generally subject to federal and applicable state taxes.

    Key Point: T-bills are Treasury securities, while savings accounts, money market deposit accounts and bank CDs are deposit products. Compare liquidity, maturity, taxes and applicable insurance separately rather than treating these options as identical.

    Costs, Risks and Expert Tips for T-Bill Investors

    Treasury bills have a relatively simple structure, but conservative investors should look beyond the quoted yield. Taxes, early-sale pricing, reinvestment, inflation and the terms of the account used to buy the bill can all affect the result.

    Costs to Check Before Buying

    TreasuryDirect states that buying marketable Treasury securities directly through its platform has no purchase fee or commission. Brokerage accounts can have their own pricing, transaction or service terms, so check the broker’s current fee schedule before placing an order.

    Risks Worth Understanding

    • Early-sale risk: Selling before maturity means accepting the current market price, which can be above or below your purchase price.
    • Reinvestment risk: The rate available for a new T-bill may be lower when your current bill matures.
    • Inflation risk: Your return may not keep pace with increases in the cost of goods and services.
    • Tax impact: T-bill interest is subject to federal income tax but is generally exempt from state and local income taxes.

    Expert Tip: Do not evaluate a T-bill by yield alone. Start with your cash timeline, then consider taxes, inflation, reinvestment and how you would access the money if your plans change.

    Common T-Bill Mistakes and a Real-Life Example

    Treasury bills are relatively straightforward, but the wrong maturity can create a problem if the money is needed sooner than expected. Conservative investors can avoid many issues by thinking about the purpose and timing of the money before buying.

    Common Mistakes to Avoid

    • Choosing by yield alone: A higher quoted yield does not automatically match your cash timeline.
    • Committing emergency money: Cash needed for an unexpected expense should remain accessible according to your needs.
    • Ignoring maturity dates: When a bill matures, decide in advance whether to spend, save or reinvest the proceeds.
    • Overlooking taxes: Compare the applicable after-tax return rather than looking only at the headline yield.

    A Simple Illustrative Example

    Suppose a retiree has $30,000 that is not expected to be needed for several months. Instead of placing the entire amount into one maturity, the investor could consider different T-bill maturities so that portions of the money become available at different times. At each maturity, the proceeds could be used for an upcoming expense or evaluated for reinvestment.

    Why This Matters: This example is illustrative, not a recommendation. Staggering maturities can help organize cash-flow timing, but the appropriate structure depends on the investor’s goals, liquidity needs and other financial resources.

    Who Should Consider Treasury Bills?

    Treasury bills may be worth evaluating when money has a defined short-term purpose and the investor wants exposure to U.S. Treasury securities. Whether they fit depends on the timing of the goal, liquidity needs, taxes and the investor’s broader financial plan.

    Situations Where T-Bills May Be Relevant

    • Conservative investors: People who place a high priority on capital preservation and want short-term Treasury exposure.
    • Retirees: Those planning for known expenses may consider maturities that align with their expected cash needs.
    • Beginners: Investors learning about short-term government securities may find the defined maturity structure easier to understand.
    • Families: Households saving toward a known future expense can evaluate whether a maturity date fits their timeline.

    Important: T-bills are not automatically appropriate for every short-term goal. Money needed immediately may require a more accessible cash option, while longer-term goals may call for different investments. Consider the purpose, timing and liquidity requirement before buying.

    Treasury Bills FAQs for Conservative Investors

    Are Treasury bills considered low-risk investments?

    T-bills are short-term U.S. Treasury securities, so the credit risk associated with the U.S. government is an important consideration. They are not risk-free in every situation, however. Selling before maturity can expose an investor to market-price changes, while inflation and reinvestment can affect the overall outcome.

    Can retirees use Treasury bills?

    Retirees can evaluate T-bills when some money has a defined short-term purpose. Different maturities can be considered alongside expected expenses, while money needed immediately may require a more accessible cash arrangement.

    Do Treasury bills pay monthly interest?

    Generally, no. T-bills are typically issued at a discount rather than paying periodic coupon interest. When held to maturity, the investor generally receives the face value, with the difference between the purchase price and face value representing the interest.

    Are Treasury bills taxable?

    Yes. T-bill interest is subject to federal income tax. It is generally exempt from state and local income taxes, which can affect comparisons with other taxable short-term investments.

    Can you sell a Treasury bill before maturity?

    Yes. T-bills can generally be sold in the secondary market through a brokerage. The market price at the time of sale can be higher or lower than the original purchase price, depending on market conditions.

    Can beginners consider Treasury bills?

    Beginners can evaluate T-bills if they understand the maturity date, purchase price, tax treatment and liquidity considerations. A useful starting point is to connect the maturity with a specific financial goal instead of focusing only on the quoted yield.

    Final Verdict: Where T-Bills May Fit in a Conservative Strategy

    Treasury bills are short-term U.S. Treasury securities with defined maturity dates. For a conservative investor, their potential role depends on what the money is for, when it will be needed, and how much access to the funds is required before maturity.

    The decision involves more than comparing yields. Investors should consider early-sale market pricing, reinvestment when a bill matures, inflation, federal taxes and the treatment of interest under state and local tax rules. These factors can make the practical outcome different from the headline yield.

    The Bottom Line: T-bills are one option for managing short-term money. Their fit should be evaluated alongside liquidity needs, tax considerations, inflation and other available cash or investment choices.

    If you want to review the fundamentals before exploring specific strategies, continue with our Treasury Bills Explained guide.

    Related Resources for Treasury Bill Investors

    If you want to research Treasury bills further, start with official sources for current Treasury rules and tax information. Then use practical guides to compare different ways of organizing short-term money.

    Official Treasury and Tax Resources

    Continue Your Treasury Research

    Start with our Treasury Bills Explained guide for the fundamentals. Then explore What Is a Treasury Bill Ladder? to learn how different maturity dates can be organized around future cash needs.

    Note: Treasury procedures, tax rules and brokerage terms can change. Check the relevant official source for current details before making an important financial decision.

    Have a Money Question? Keep Exploring.

    Understanding the maturity date, liquidity, taxes and reinvestment plan can make Treasury bill decisions easier to evaluate. Keep exploring practical guides before deciding how short-term money fits into your financial plan.

    📩 Get in Touch With FinanceInvestment

    Have a question about Treasury bills, savings or conservative investing?


    Email FinanceInvestment

  • Are Treasury Bills Exempt From State Taxes? 2026 Guide

    Are Treasury Bills Exempt From State Taxes? 2026 Guide

    Are Treasury Bills Exempt From State Taxes?

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    Published: September 23, 2026
    •
    Updated: September 23, 2026
    •
    Reading Time: 10–12 min

    Are Treasury Bills Exempt From State Taxes?

    Are Treasury Bills Exempt From State Taxes?If you live in a state that charges individual income tax, the tax treatment of your investments can make a noticeable difference. So, are Treasury bills exempt from state taxes? Yes. Interest from U.S. Treasury bills is generally exempt from state and local income taxes. Federal income tax still applies, though, so T-bills should not be described as completely tax-free.

    That state-tax exemption becomes especially relevant when you compare Treasury bills with taxable alternatives such as bank savings accounts, certificates of deposit, or bank money market accounts. The advertised rate is only part of the comparison. The tax treatment can change the amount of income left after taxes.

    If you want the bigger picture first, our
    Treasury Bills Explained
    guide covers how these short-term U.S. government securities work. Here, the focus is narrower: the state and local income-tax exemption and how it affects Treasury bill investors.

    What You’ll Learn

    • Why Treasury bill interest is exempt from state and local income taxes.
    • How federal income tax applies to Treasury bill interest.
    • Why the exemption can matter when comparing after-tax returns.
    • How T-bills compare with CDs, savings accounts, and bank money market accounts.
    • How Form 1099-INT is used for Treasury interest reporting.
    • Common tax-reporting mistakes investors should watch for.

    Quick Answer: Are Treasury Bills Exempt From State Taxes?

    Yes. Interest from U.S. Treasury bills is subject to federal income tax but is exempt from state and local income taxes. Treasury bill interest is generally reported on Form 1099-INT, Box 3. That means the state-tax benefit is real, but Treasury bill income is not completely tax-free.

    Key Takeaways

    • Treasury bill interest is exempt from state and local income taxes.
    • Federal income tax still applies to Treasury bill interest.
    • The exemption can matter when comparing T-bills with taxable bank deposits.
    • Form 1099-INT generally reports Treasury bill interest in Box 3.
    • For a standard T-bill held to maturity, the difference between the discounted purchase price and the face value is generally treated as interest income.
    • State-tax exempt does not mean federal-tax exempt.
    BOTTOM LINE:
    The main tax advantage of Treasury bills is the exemption from state and local income taxes. When comparing a T-bill with another cash investment, look beyond the advertised rate and consider how each investment is taxed.

    Table of Contents

    Treasury Bills and State Taxes at a Glance

    The central tax rule is simple: interest income from U.S. Treasury bills is subject to federal income tax but exempt from all state and local income taxes. That can make the tax treatment different from interest earned on many bank deposits. Treasury interest is generally identified separately on Form 1099-INT.

    Tax DetailTreasury Bill Treatment
    Federal income taxApplies
    State income taxExempt
    Local income taxExempt
    Form 1099-INTTreasury interest generally appears in Box 3
    Key tax benefitExemption from state and local income taxes

    WHO MAY VALUE THIS TAX TREATMENT:
    Investors comparing Treasury bills with taxable cash investments may want to account for the state and local income-tax exemption when comparing after-tax income. The actual benefit depends on the investor’s tax situation and location.

    KEY NUMBERS:
    Treasury bills generally have 4-, 8-, 13-, 26-, or 52-week maturities. They are generally issued at a discount, and for a standard bill held to maturity, the difference between the discounted purchase price and face value is generally treated as interest income.

    Treasury Bill State Tax Exemption: A Complete Beginner Guide

    Are Treasury Bills Exempt From State Taxes?Treasury bills have a tax feature that can be easy to miss when you first compare them with other short-term investments. The IRS says interest from Treasury bills, notes, and bonds is subject to federal income tax but exempt from all state and local income taxes.
    1. What Does the State-Tax Exemption Mean?

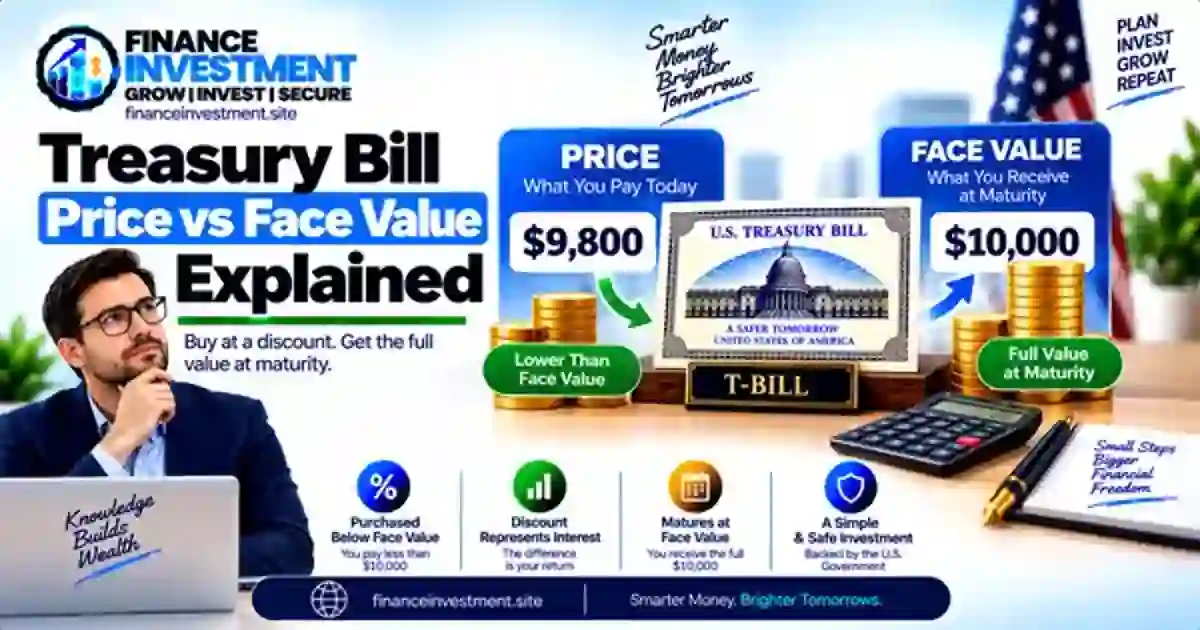
    Imagine buying a standard Treasury bill for $9,800 and receiving its $10,000 face value at maturity. The $200 difference is generally treated as interest income. That interest is taxable federally, but it is exempt from state and local income taxes.

    2. Why Doesn’t the Exemption Apply to Federal Tax?

    Treasury bills are obligations of the U.S. government, but their interest is not federally tax-exempt. For a standard Treasury bill held to maturity, the IRS generally treats the difference between the discounted purchase price and the face value received at maturity as interest income.

    3. Does the Exemption Include Local Income Taxes?

    Yes. The exemption covers both state and local income taxes. That means Treasury bill interest is generally not included in state or local income tax based on the interest itself. This treatment can differ from taxable interest earned through many bank deposit products.

    4. Where Does Treasury Interest Appear on Form 1099-INT?

    Treasury bill interest is generally reported on Form 1099-INT, Box 3. IRS instructions specifically say Box 3 is used for interest on U.S. savings bonds, Treasury bills, Treasury notes, and Treasury bonds. The amount is generally included with taxable interest for federal reporting.

    EASY WAY TO REMEMBER:
    Treasury bill interest gets a state and local income-tax exemption, not a complete tax exemption. Federal income tax still applies, and Treasury interest is generally identified in Box 3 of Form 1099-INT.

    That difference matters most when you compare the after-tax income from a Treasury bill with interest from a taxable bank account or another short-term investment.

    How the State-Tax Exemption Works

    The state-tax benefit follows the federal treatment of U.S. Treasury obligations. Treasury bill interest is taxable for federal income tax purposes, while that interest is exempt from state and local income taxes.

    Step 1: You Buy the Treasury Bill

    Treasury bills are generally issued at a discount. For example, a $10,000 face-value bill might be purchased for less than $10,000. The actual purchase price depends on the bill and the transaction terms.

    Step 2: The Bill Reaches Maturity

    For a standard Treasury bill held to maturity, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. Most individual taxpayers using the cash method generally report this interest when the bill is paid at maturity.

    Step 3: The State and Local Exemption Applies

    Once the Treasury interest is recognized for tax purposes, the key distinction is where it is taxed. Federal income tax applies, but the interest from Treasury bills is exempt from state and local income taxes. That is the tax advantage behind the phrase state-tax exempt.

    Step 4: Treasury Interest Is Reported Separately

    Form 1099-INT, when issued for Treasury obligations, reports Treasury bill interest in Box 3. IRS instructions specifically say Treasury bills, Treasury notes, Treasury bonds, and U.S. savings bonds belong in Box 3 rather than Box 1.

    THE SIMPLE VERSION:
    A Treasury bill can create federally taxable interest without creating state or local income tax on that same Treasury interest. The exemption is the tax advantage; it does not make the investment completely tax-free.

    Benefits & Drawbacks of the State-Tax Exemption

    The state-tax exemption can change the after-tax comparison between Treasury bills and taxable cash investments. Still, it is only one factor. Federal income tax continues to apply, while the value of the state and local exemption depends on the investor’s tax situation and where the investor lives.


    ✓ Benefits

    • Treasury bill interest is exempt from state and local income taxes.
    • The exemption can improve the after-tax comparison with taxable bank deposits for investors who would otherwise owe state or local income tax on comparable interest.
    • Treasury obligations are generally reported separately on Form 1099-INT, with applicable Treasury interest reported in Box 3.


    △ Drawbacks

    • Federal income tax still applies to Treasury bill interest.
    • The state-tax exemption does not by itself determine which investment produces the better after-tax result; yield, federal taxes, and the tax treatment of the alternative also matter.
    • Selling a Treasury bill before maturity or dealing with certain secondary-market transactions can introduce additional tax


    QUICK TAKE:

    The tax benefit is specific: state and local income taxes generally do not apply to Treasury bill interest. When comparing investments, look at the yield and federal tax treatment alongside your own state and local tax position.

    Treasury Bills vs. CDs vs. Savings vs. Money Market

    The tax difference becomes clearer when Treasury bills are placed beside familiar cash investments. Treasury interest receives a specific federal benefit: it remains subject to federal income tax but is exempt from state and local income taxes. Interest from ordinary bank deposit products is generally taxable, subject to the rules that apply to the account and the investor.

    InvestmentFederal TaxState & Local Income TaxCommon Federal Reporting
    Treasury BillsAppliesExemptForm 1099-INT, generally Box 3
    Bank CDGenerally appliesGenerally taxable under applicable rulesGenerally Form 1099-INT
    Bank Savings AccountGenerally appliesGenerally taxable under applicable rulesGenerally Form 1099-INT
    Bank Money Market AccountGenerally appliesGenerally taxable under applicable rulesGenerally Form 1099-INT

    Why the Tax Difference Matters

    Imagine two investments producing the same amount of interest. If one is a Treasury bill and the other is a taxable bank deposit, the Treasury interest can avoid state and local income tax while the bank interest generally remains subject to applicable state and local rules. The actual difference depends on the investor’s circumstances and jurisdiction.

    One detail is easy to overlook: a bank money market account is not the same thing as a money market fund. A bank money market account is a deposit account that generally pays interest. A money market fund is an investment product, and its distributions are generally reported as dividends rather than interest.

    QUICK TAKE:
    Treasury bills have a specific tax advantage: their interest is exempt from state and local income taxes. When comparing T-bills with CDs, savings accounts, or bank money market accounts, compare the tax treatment along with the yield.

    Costs, Tax Risks & Expert Tips

    Treasury bills are generally purchased at a discount and do not make regular interest payments during their short term. The main tax issue is straightforward: Treasury bill interest is subject to federal income tax but exempt from state and local income taxes. The purchase price, maturity date, and how the bill was held can also affect how the income is reported.

    Costs to Check Before Buying

    • If you buy through a brokerage account, check the broker’s current pricing and account terms rather than assuming every transaction is free.
    • Compare the Treasury bill’s yield with the yield available on other cash investments after considering the applicable tax treatment.
    • Keep purchase confirmations and maturity records, especially when buying or selling Treasury bills through different accounts.

    Tax Risks to Avoid

    • Do not describe Treasury bills as completely tax-free. Federal income tax still applies to the interest.
    • Do not ignore taxable interest simply because a tax form was not received. The IRS requires taxable interest to be reported even when a Form 1099-INT is not received.
    • Do not automatically enter Treasury bill interest in Form 1099-INT Box 1. Interest from Treasury bills, notes, and bonds is generally shown in Box 3.

    Expert Tips for Cleaner Tax Records

    For a standard Treasury bill held to maturity, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. For cash-method taxpayers, that income is generally reported when the bill is paid at maturity.

    EXPERT TIP:
    Keep your purchase confirmation, maturity statement, and tax forms together. TreasuryDirect reports Treasury bill interest for the year the bill matures or is sold, and a Treasury bill held through a broker can result in additional reporting records if the security moves between accounts.

    Common Mistakes + Real-Life Example

    Treasury bill taxes are usually straightforward, but a few common misunderstandings can create problems. The biggest one is confusing a state-tax exemption with a complete tax exemption. Treasury bill interest remains subject to federal income tax.

    Mistake 1: Assuming T-Bills Are Completely Tax-Free

    The exemption applies to state and local income taxes. It does not remove federal income tax from Treasury bill interest.

    Mistake 2: Ignoring the Tax Form

    For Treasury bills, Treasury notes, and Treasury bonds, Treasury interest is generally shown in Form 1099-INT, Box 3. Taxable interest must still be reported even when a 1099-INT is not received.

    Mistake 3: Overlooking the Sale or Maturity Year

    A Treasury bill does not normally pay periodic interest. For a standard bill held to maturity, the difference between the discounted purchase price and the amount received at maturity is generally interest income, normally reported when the bill matures. If the bill is sold before maturity, keep the transaction records because the reporting can involve additional details.

    Real-Life Example

    Consider this illustrative example: an investor buys a Treasury bill for $9,800 and receives $10,000 at maturity. The $200 difference represents interest income for this simplified example. Federal income tax applies to that interest, while the interest is exempt from state and local income taxes. The investor should use the actual tax documents and transaction records when preparing the tax return.

    KEY LESSON:
    Treasury bills are not completely tax-free. Their specific tax benefit is that Treasury interest is exempt from state and local income taxes while remaining subject to federal income tax.

    Who May Consider Treasury Bills?

    Treasury bills may be worth considering for investors looking for a short-term U.S. Treasury security with a defined maturity date. Their interest is subject to federal income tax but exempt from state and local income taxes, which can matter when comparing T-bills with taxable alternatives.

    T-Bills May Fit Investors Who:

    • Want a short-term U.S. Treasury security with a stated maturity of one year or less.
    • Live in a state or locality with an income tax and want to account for the Treasury interest exemption when comparing taxable investments.
    • Prefer a security that is generally purchased at a discount and redeemed at its face value at maturity.
    • Understand that the interest remains subject to federal income tax.
    KEEP IN MIND:
    The state-tax exemption is only one factor to consider. Maturity period, yield, liquidity needs, federal tax treatment, and the tax treatment of alternative investments can also affect the comparison.

    Frequently Asked Questions

    1. Are Treasury bills exempt from state taxes?

    Yes. Interest income from U.S. Treasury bills is subject to federal income tax but is exempt from state and local income taxes.

    2. Do you pay federal tax on Treasury bills?

    Yes. Treasury bill interest is subject to federal income tax. For a standard Treasury bill held to maturity, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income.

    3. Are Treasury bills exempt from local income taxes?

    Yes. The exemption covers state and local income taxes on Treasury bill interest. Federal income tax still applies, so Treasury bills should not be described as completely tax-free.

    4. Where is Treasury bill interest reported on Form 1099-INT?

    Interest from Treasury bills is generally reported in Box 3 of Form 1099-INT. IRS instructions specifically identify Box 3 for interest on Treasury bills, Treasury notes, Treasury bonds, and U.S. savings bonds.

    5. When do you report Treasury bill interest?

    For a standard Treasury bill held to maturity, the interest is generally reported when the bill is paid at maturity. TreasuryDirect also notes that T-bill interest is reportable in the year the bill matures or is sold.

    6. What if you do not receive a Form 1099-INT?

    Not receiving a Form 1099-INT does not automatically make taxable interest nonreportable. The IRS states that taxable interest must be reported even when the form is not received.

    7. Are Treasury bills tax-free if you live in a state with income tax?

    Treasury bill interest is exempt from state and local income taxes, even when the investor lives in a state that imposes an income tax. Federal income tax still applies to the interest.

    8. Does Treasury bill tax reporting change if you sell before maturity?

    It can. A standard Treasury bill held to maturity has a straightforward discount-to-face-value interest treatment, while a bill sold before maturity can involve different transaction details and reporting. TreasuryDirect states that the difference between the original purchase price and the amount received when a bill is sold or matures is interest.

    Final Verdict: Are Treasury Bills Exempt From State Taxes?

    Yes. Interest from U.S. Treasury bills is exempt from state and local income taxes, while federal income tax still applies. That makes the state and local tax exemption the key tax distinction to understand when evaluating Treasury bills. They are not completely tax-free investments. (IRS Publication 550)

    For a standard Treasury bill held to maturity, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. Treasury bill interest is generally reported in Box 3 of Form 1099-INT. (IRS Form 1099-INT Instructions)

    For a broader explanation of T-bill maturities, pricing, and basic investing concepts, continue with our Treasury Bills Explained guide.

    BOTTOM LINE:
    Treasury bill interest gets a state and local income-tax exemption, but federal income tax still applies. When comparing T-bills with other cash investments, consider the yield together with the applicable federal, state, and local tax treatment.

    Have a Money Question? Keep Exploring.

    Want to understand more about Treasury bills, taxes, or other ways to manage your cash? Keep exploring FinanceInvestment for practical, easy-to-follow personal finance guides.


    📩 Get in Touch With FinanceInvestment


    Have a finance question or a topic you’d like us to cover? Send us a message.


    Email FinanceInvestment

  • Treasury Bill Price vs Face Value Explained: 2026 Guide

    Treasury Bill Price vs Face Value Explained: 2026 Guide

    Treasury Bill Price vs Face Value Explained

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    Published: September 21, 2026 • Updated: September 21, 2026 • Reading Time: 10–12 min


    Treasury Bill Price vs Face Value: Why the Difference Matters

    Treasury Bill Price vs Face Value explained with T-bill pricing and maturity valueA Treasury bill can have a $1,000 face value but cost less than $1,000 when you buy it. That difference is a key part of how T-bills provide a return. Instead of receiving regular interest payments, you generally buy the bill at a discount and receive its face value when it matures.

    For example, suppose a $1,000 Treasury bill has a purchase price of $975. You pay $975 upfront. If you hold the bill until maturity, you receive $1,000. The $25 difference between your purchase price and the face value is the gross return built into that transaction, before considering taxes or any result from selling the bill before maturity.

    This is where beginners often get tripped up. Price, face value, discount rate and investment yield are connected, but they measure different things. Once you separate those numbers, a T-bill quote becomes much easier to read.

    In this guide, we’ll walk through the numbers step by step. We’ll also connect this topic with our complete Treasury Bills guide so you can see how pricing fits into the bigger picture.

    What You’ll Learn

    • What Treasury bill price and face value mean.
    • Why T-bills can be purchased below face value.
    • How the price difference becomes part of your return at maturity.
    • How price, discount rate and yield relate to each other.
    • How the purchase price affects your actual investment.
    • What can happen when you sell a T-bill before maturity.

    Quick Answer: How Is Treasury Bill Price Different From Face Value?

    A Treasury bill’s face value is the stated amount paid when the bill matures, while its purchase price is the amount you pay to acquire it. T-bills are generally issued at a price below their face value. The difference between those two amounts is the discount, which forms the basic return for an investor who holds the bill until maturity.

    Key Takeaways

    • The face value is the stated amount the Treasury bill is redeemed for at maturity.
    • The purchase price is the amount paid to acquire the bill.
    • For a T-bill issued at a discount, the purchase price is lower than its face value.
    • The difference between face value and purchase price is the discount amount.
    • T-bills do not make periodic coupon payments like Treasury notes and bonds.
    • The discount rate is a pricing measure and should not be treated as the same thing as the investor’s annualized return.

    BOTTOM LINE: Face value tells you the amount tied to the bill at maturity. Purchase price tells you what you pay upfront. When a T-bill is bought below face value and held to maturity, the difference between those amounts is the basic source of the return.

    Table of Contents

    Treasury Bill Price vs Face Value at a Glance

    The simplest way to read a Treasury bill is to separate its face value from its purchase price. For a newly issued T-bill sold at a discount, you pay less than the bill’s face value. If you hold it until maturity, the bill is redeemed for its stated face value. The difference between those amounts is the discount.

    Quick FactWhat It Means
    Face valueThe stated amount for which the T-bill is redeemed at maturity.
    Purchase priceThe amount an investor pays to acquire the T-bill.
    DiscountThe difference between the face value and the purchase price.
    MaturityThe date when the T-bill reaches the end of its stated term.

    QUICK TAKE: For example, if a hypothetical T-bill has a $10,000 face value and a $9,800 purchase price, the $200 difference is the discount. If the bill is held to maturity, the stated $10,000 face value is the maturity amount.

    Treasury Bill Price vs Face Value: A Complete Beginner Guide

    Treasury Bill Price vs Face ValueThe easiest way to understand a Treasury bill is to separate four numbers: face value, price per $100, purchase price, and discount amount. A newly issued T-bill is generally sold at a price below its face value. If you hold it until maturity, the bill is redeemed at its stated par amount. Treasury bills are short-term securities with maturities of one year or less and do not make periodic coupon payments.

    1. Start With Face Value

    Face value, also called par value, is the stated dollar amount of the T-bill. Suppose a bill has a $10,000 face value. If you hold that bill until maturity, the Treasury redeems it at its $10,000 par amount. You do not receive separate coupon payments during the bill’s term.

    2. Look at the Price Per $100

    Treasury bill pricing is expressed on a per-$100-of-face-value basis. For example, a price of $98.00 per $100 means an investor pays $98 for each $100 of face value. For a $10,000 bill, that works out to a $9,800 purchase price. Treasury’s rules use the price per $100 and the par amount to determine the total purchase price.

    3. Calculate the Discount Amount

    If the $10,000 bill costs $9,800, the discount amount is $200. That is simply the face value minus the purchase price. If you hold the bill until maturity, this difference represents the interest earned through the bill’s discounted purchase structure.

    4. Don’t Confuse Price With the Discount Rate

    The price tells you how much the bill costs. The discount rate expresses the price difference as an annualized rate using the bill’s face value and a 360-day convention. Treasury uses the discount rate to derive the price per $100. So a quoted discount rate and the resulting purchase price are connected, but they are not the same thing.

    BEGINNER TIP: When reading a T-bill quote, ask three questions first: What is the face value? What is the price per $100? How much will I actually pay? Once those numbers are clear, the discount and annualized rates become much easier to understand.

    How Treasury Bill Pricing Works

    Treasury bill pricing follows a simple chain: the discount rate helps determine the price per $100 of face value, and that price determines how much you actually pay. The face value does not change. What changes is the amount required upfront to buy the bill.

    Step 1: Convert the Discount Rate Into a Price

    Treasury’s formula for converting a T-bill discount rate into a price per $100 is:

    Price per $100 = 100 × [1 − (Discount Rate × Days to Maturity ÷ 360)]

    For example, using a hypothetical 5% discount rate and 91 days to maturity, the calculated price is approximately $98.736 per $100 of face value before applying the applicable auction-price rounding convention.

    Step 2: Calculate the Purchase Price

    Once the price per $100 is known, Treasury calculates the purchase price by dividing the bill’s face value by 100 and multiplying that amount by the price per $100. For a $10,000 face-value T-bill priced at $98.736 per $100, the approximate purchase price would be $9,873.60.

    Step 3: Find the Discount

    The discount is simply the difference between face value and purchase price. In this example, $10,000 minus $9,873.60 equals approximately $126.40. If the bill is held to maturity, that price-to-face-value difference is the basic return built into the T-bill’s discounted structure.

    Key point: The price tells you what you pay. Face value tells you the amount associated with maturity. The discount connects the two, while the quoted discount rate is the annualized rate calculated using Treasury’s 360-day convention.

    Treasury Bill Price vs Face Value: Benefits & Drawbacks

    The difference between a Treasury bill’s price and face value creates a straightforward way to understand how the bill’s return is built. Still, the price alone does not tell you everything about the investment. Maturity, taxes, market prices and your holding period can all affect the final result.

    Benefits of the T-Bill Pricing Structure

    • Simple purchase structure: Newly issued Treasury bills are generally bought below face value, with the discount built into the purchase price.
    • No periodic coupon payments: T-bills do not make regular interest payments during their term. The difference between the purchase amount and the amount received at maturity represents interest when held to maturity.
    • Easy price comparison: The price per $100 makes it easier to compare the upfront cost with the bill’s face value.
    • Predictable maturity amount: If you hold the bill until maturity, the Treasury pays the stated face amount, subject to applicable tax withholding or other account-specific considerations.

    Drawbacks to Consider

    • Price and yield are different: A lower purchase price increases the dollar discount, but it should not be confused with the annualized investment rate.
    • Early sale can change the result: If you sell a T-bill before maturity through a brokerage, its market price may be above or below your original purchase price.
    • Federal taxes apply: Treasury bill interest is subject to federal income tax, although it is generally exempt from state and local income taxes.
    • Inflation still matters: A positive T-bill return does not automatically mean your purchasing power increased after inflation.
    Quick Take: Face value shows the amount tied to maturity, while price shows your upfront cost. The difference can create interest when the bill is held to maturity, but investors should also consider annualized yield, taxes, inflation and the possibility of selling before maturity.

    Treasury Bill Price vs Face Value vs Yield

    Treasury bill price, face value, discount rate and investment rate are connected, but they are not interchangeable. Face value shows the bill’s stated amount at maturity. Price shows the amount paid upfront. The investment rate, also called the coupon-equivalent yield, expresses the annualized return based on the bill’s purchase price.

    TermWhat It MeansWhat It Tells You
    Face ValueThe bill’s stated par amountAmount associated with maturity
    Purchase PriceThe amount paid for the T-billYour upfront investment
    Discount RateAn annualized rate calculated using par valueThe discount quoted on a 360-day basis
    Investment RateAn annualized rate based on purchase priceA more useful measure for comparing the bill’s return with other investments

    Why the Discount Rate and Investment Rate Differ

    Consider a hypothetical T-bill with a $10,000 face value and a purchase price of $9,800. The $200 difference is the discount. However, that $200 is not automatically a 2% annual return because the bill has a specific time remaining until maturity. The investment rate accounts for the actual purchase price and the holding period. Treasury normally calculates this rate using a 365-day basis, or 366 days when applicable.

    Quick Take: Face value tells you the bill’s stated maturity amount. Price tells you what you pay. The discount rate describes the discount using par value, while the investment rate annualizes the return based on the price you actually paid.

    Treasury Bill Price vs Face Value: Costs, Risks & Expert Tips

    A Treasury bill does not work like a savings account that simply pays a stated interest rate. Your result depends on the price you pay, the amount tied to maturity, the time you hold the bill and the taxes that apply. Looking at these details before buying can prevent common misunderstandings.

    Costs to Check Before Buying

    • Purchase price: This is the actual amount committed upfront and should be compared with the bill’s face value.
    • Brokerage charges: If you buy through a broker, check the firm’s current pricing, spreads or other applicable charges. Costs can vary by provider.
    • Taxes: Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes under federal tax rules.

    Risks to Understand

    • Early-sale price risk: If you sell before maturity, the market price may be different from the amount you originally paid. The result can therefore differ from simply holding the bill to maturity.
    • Reinvestment risk: When the bill matures, a new Treasury bill may offer a different rate, so the same return may not be available when you reinvest.
    • Inflation risk: A positive nominal return does not guarantee an increase in purchasing power after inflation.
    Expert Tip: Before buying, write down the face value, purchase price, maturity date and investment rate. Then compare the return with your actual money invested—not just the face value shown on the T-bill quote.

    Common Treasury Bill Pricing Mistakes & Real-Life Example

    Treasury bill pricing becomes much easier when you keep the key numbers separate. Beginners often make mistakes by treating face value, purchase price, discount rate and investment rate as if they were interchangeable.

    Common Mistakes to Avoid

    • Confusing face value with purchase price: A $10,000 face-value T-bill can cost less than $10,000 when it is issued at a discount.
    • Treating the discount rate as the actual return: Treasury’s discount rate and investment rate use different calculations and day-count conventions.
    • Ignoring the holding period: The dollar discount alone does not show the annualized return because the time until maturity also matters.
    • Assuming early sale equals maturity: Selling before maturity can produce a different result because the T-bill’s market price may change.

    Real-Life Example

    Suppose an investor buys a hypothetical Treasury bill with a $10,000 face value for $9,800 and holds it until maturity. The investor pays $9,800 upfront and receives the $10,000 face amount at maturity. The $200 difference is the interest income created by the discounted purchase price. It should not, however, be described as a 2% annual return because the investment rate also depends on the time to maturity and the purchase price.

    Beginner Tip: When reviewing a T-bill quote, check the face value, price per $100, purchase price and maturity date first. Then look at the discount rate or investment rate. This order makes it easier to understand what you are paying and how the quoted return is calculated.

    Who May Consider Treasury Bills?

    Treasury bills may fit investors looking for short-term U.S. government debt and a defined maturity date. Because newly issued T-bills are generally sold at a discount, investors can compare the purchase price with the amount received at maturity when evaluating a potential investment.

    T-Bills May Fit These Situations

    • Short-term goals: You have money that can remain invested until a known maturity date.
    • Defined maturity: You prefer a Treasury security with a specific date when the bill matures.
    • Price-based investing: You want to evaluate an investment using its purchase price, face value and annualized rate.
    • Federal Treasury exposure: You want a direct U.S. government debt security rather than a corporate or municipal obligation.
    • Tax considerations: Treasury bill interest is subject to federal income tax but exempt from state and local income taxes under federal tax rules.

    When to Compare Other Options

    A T-bill may not match every cash need. If you need unrestricted access to your money, want periodic interest payments, or expect to sell before maturity, compare the relevant features, costs and risks of other short-term investments before making a decision.

    Quick Take: The right fit depends on your time horizon, liquidity needs, tax situation and how you plan to hold the T-bill. The price-versus-face-value relationship is only one part of that decision.

    Frequently Asked Questions About Treasury Bill Price vs Face Value

    1. What is the difference between Treasury bill price and face value?

    Face value is the stated par amount of a Treasury bill. The purchase price is the amount you pay upfront. Treasury bills are generally issued at a discount, so the purchase price can be lower than the face value paid at maturity.

    2. Why are Treasury bills sold below face value?

    Treasury bills generally do not make periodic coupon payments. Instead, they are issued at a discount, and the difference between the discounted purchase price and the face value received at maturity represents interest income when the bill is held to maturity.

    3. Is the Treasury bill discount rate the same as the investment rate?

    No. Treasury calculates the discount rate using the bill’s par value and a 360-day convention. The investment rate, also called the coupon-equivalent yield, is calculated from the purchase price and the applicable annual day count. These rates therefore can differ even for the same T-bill.

    4. How do I calculate the discount on a T-bill?

    Subtract the purchase price from the face value. For example, a hypothetical $10,000 face-value T-bill purchased for $9,800 has a $200 discount. If held to maturity, that difference represents the bill’s interest income before considering applicable taxes.

    5. Can a Treasury bill’s market price change after I buy it?

    Yes. If you sell a T-bill before maturity through a brokerage, its market price can change as market conditions change. The amount you receive from an early sale can therefore differ from the amount you would receive by holding the bill until maturity.

    6. Are Treasury bill earnings taxable?

    Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes under federal tax rules. Your individual tax situation may require additional considerations.

    Bottom Line: Face value, purchase price, discount rate and investment rate describe different parts of a Treasury bill. Keeping those figures separate makes T-bill quotes much easier to compare and understand.

    Final Verdict: Understanding Treasury Bill Price vs Face Value

    The difference between Treasury bill price and face value comes down to one simple idea: face value is the bill’s stated par amount, while the purchase price is what you pay upfront. When a T-bill is purchased at a discount and held to maturity, the difference between those amounts represents interest income.

    For a broader explanation of T-bill maturities, pricing, buying methods and how Treasury bills work, continue with our complete Treasury Bills guide. It provides a useful next step if you want to understand the bigger picture beyond price versus face value.

    For this specific topic, check the purchase price, face value, maturity date and applicable investment rate together. The discount rate is a separate measure and should not automatically be treated as the investment’s annualized return. If you sell before maturity, the market price can also affect the amount you receive.

    Bottom Line: Price tells you what you pay. Face value tells you the stated amount associated with maturity. Comparing both with the maturity period and investment rate gives you a clearer picture of a Treasury bill’s pricing and potential return.

    Have a Money Question? Keep Exploring.

    Understanding Treasury bills starts with knowing what you pay, what the bill is worth at maturity and how the stated rate is calculated. Keep exploring FinanceInvestment for practical guides that can help you understand different short-term investing topics.

    📩 Get in Touch With FinanceInvestment
    Have a finance question, topic suggestion or feedback?
    Email FinanceInvestment