Tag: Treasury Bill Returns

  • How Much Can $100,000 Earn in Treasury Bills? 2026 Guide
    How Much Can $100,000 Earn in Treasury Bills? 2026 Guide

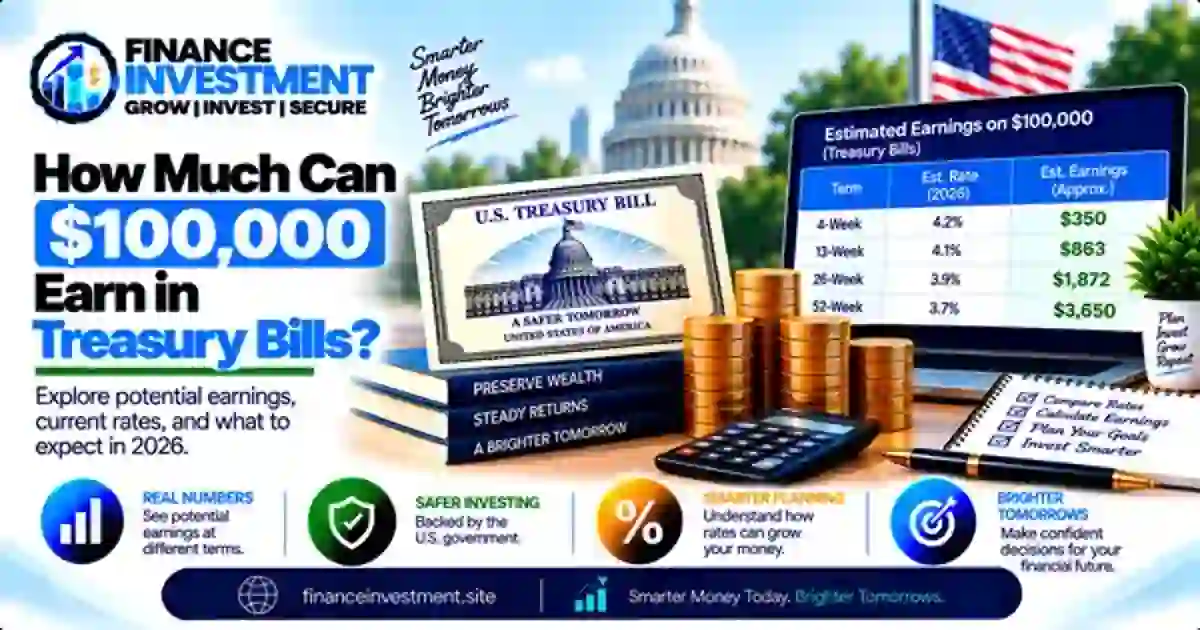
    How Much Can $100,000 Earn in Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 20, 2026


    Reading Time: ~14 minutes

    How Much Can $100,000 Earn in Treasury Bills?

    How Much Can $100,000 Earn in Treasury Bills?How Much Can $100,000 Earn in Treasury Bills? The answer depends on the purchase price, maturity and yield available when you invest. With $100,000 involved, even a relatively small change in the purchase price can affect the dollar amount of your gross return.

    Treasury bills also work differently from a savings account or a certificate of deposit. They generally do not make periodic coupon payments. Instead, a T-bill is typically purchased for less than its face value and pays its face value at maturity when held to maturity. That makes both the amount you pay and the date your money becomes available important parts of the decision.

    What You’ll Learn

    • How a $100,000 T-bill investment can generate a gross return.
    • How 4-, 8-, 13-, 26- and 52-week maturities affect your cash timeline.
    • Why the purchase price matters when estimating dollar earnings.
    • How federal taxes, early sales and reinvestment can affect the outcome.
    • What to consider before committing a large cash balance to Treasury bills.

    If Treasury bills are new to you, start with our

    complete Treasury Bills guide

    for the basic terminology and mechanics before moving into the $100,000 examples and maturity comparisons below.

    Quick Answer: What Could $100,000 Earn?

    A $100,000 Treasury bill investment can produce different gross returns depending on its purchase price, maturity and yield at the time you buy. If a bill has a $100,000 face value and you purchase it below that amount, the difference between your purchase price and the face value is the gross return when the bill reaches maturity.

    Key Takeaways

    • A $100,000 face-value T-bill may cost less than $100,000 when purchased at a discount.
    • The difference between the purchase price and face value represents the gross return at maturity.
    • T-bill yields are annualized, so a quoted annual rate is not the same as the exact dollar return for every maturity.
    • Shorter maturities return the money sooner, while longer maturities keep the funds committed for a longer period.
    • Treasury bill income is generally subject to federal income tax but exempt from state and local income taxes.
    • Reinvesting after maturity can produce a different return because future T-bill yields may change.
    BOTTOM LINE

    There is no single earnings figure for every $100,000 T-bill investment. The actual result starts with the purchase price and face value, then depends on the maturity, taxes and what you do with the money afterward.

    $100,000 Treasury Bill Earnings at a Glance

    A $100,000 Treasury bill position can generate a meaningful dollar return, but the exact amount depends on the price you pay and the bill’s maturity. The quoted yield is annualized, so it should not be treated as the exact cash earnings for every T-bill term.

    QUICK FACT
    $100,000 Face Value
    Example amount received at maturity
    RETURN SOURCE
    Face Value − Purchase Price
    Gross return when held to maturity
    BEST FOR
    Defined Cash Timelines
    Investors planning around a maturity date

    Key Numbers to Watch

    Number or TermWhat It Tells YouWhy It Matters
    $100,000Example face valueEstablishes the maturity value used in the example.
    Purchase priceAmount paid for the billDetermines the gross dollar difference at maturity.
    4–52 weeksAvailable maturity rangeDetermines when the money is scheduled to mature.
    Annualized yieldRate used for comparisonHelps compare different Treasury bill opportunities.
    QUICK TAKE

    With $100,000, the maturity date deserves close attention. First decide when the cash may be needed. Then compare the available purchase prices and annualized yields for maturities that fit that timeline.

    Complete Beginner Guide: How $100,000 in T-Bills Works

    How Much Can $100,000 Earn in Treasury Bills?If you have $100,000 available, Treasury bills can put that cash into short-term U.S. government securities for a defined period. T-bills have maturities of one year or less. They are issued at a discount and redeemed at their face, or par, amount at maturity.

    What Happens When You Buy

    Suppose you buy a hypothetical $100,000 face-value T-bill for less than $100,000. You pay the purchase price when the security is purchased. If you hold the bill until maturity, the Treasury pays the $100,000 face value. The difference between what you paid and what you receive at maturity is the gross interest earned on the bill.

    You can buy Treasury bills directly through TreasuryDirect or through a bank or brokerage. With TreasuryDirect, you select the bill’s term and par amount when scheduling a purchase. The maturity date then tells you when the bill is scheduled to be redeemed.

    BEGINNER TIP

    Before committing the full $100,000, mark the date when you may need the cash. Then compare that date with the T-bill’s maturity. For a larger balance, matching the maturity to your cash plan can help you avoid an unnecessary liquidity problem.

    For the basic mechanics behind Treasury bills, read our

    guide to how Treasury bills work
    .
    Next, we will look at how the purchase price turns into an actual dollar return.

    How T-Bill Earnings Are Calculated

    The basic calculation for a $100,000 Treasury bill starts with two numbers: the face value and the purchase price. Treasury bills are generally sold at a discount, and the Treasury pays the face value when the bill matures. The difference between those amounts is the interest earned when the bill is held to maturity.

    The Basic Dollar Calculation

    Gross Return = Face Value − Purchase Price

    For example, imagine a hypothetical $100,000 face-value T-bill with a purchase price of $98,500. If you hold it until maturity, the difference is $1,500. That $1,500 is the gross interest earned before applicable taxes. This example is for illustration only and is not a current Treasury auction quote.

    Why the Quoted Rate Can Look Different

    Treasury bill pricing uses an annualized discount-rate convention based on a 360-day year. TreasuryDirect also reports an investment rate or yield, which is an annualized simple-interest measure based on the purchase price and a 365-day year, or 366 days when applicable during a leap year. Because these measures use different bases, the quoted discount rate and investment rate are not interchangeable.

    CALCULATION TIP

    For a $100,000 investment, start with the actual purchase price, face value and maturity date. Do not simply multiply $100,000 by an annualized rate and treat that figure as the exact T-bill earnings.

    For a closer explanation of the terminology, read our

    Treasury Bill Yield vs. Interest Rate guide
    .

    Benefits and Drawbacks of Investing $100,000 in T-Bills

    A $100,000 Treasury bill position can offer a defined maturity date and a relatively straightforward return structure. However, putting a large amount into one short-term security also means paying attention to access to cash, taxes and what happens when the bill matures.

    Benefits

    • A known maturity date can make short-term cash planning easier.
    • Treasury bills are obligations of the U.S. government.
    • T-bill interest is generally exempt from state and local income taxes.
    • Different maturities can help spread a larger cash balance across several dates.

    Drawbacks

    • Holding the bill to maturity means waiting for its scheduled maturity date to receive the face value.
    • Future T-bill yields may be higher or lower when you reinvest the proceeds.
    • Selling before maturity exposes you to the current secondary-market price, which can differ from your purchase price.
    • T-bills are designed for short-term cash management rather than long-term growth from ownership of businesses or other assets.
    BEFORE YOU INVEST

    With $100,000, start with your cash timeline rather than the headline yield. Decide when the money may be needed, then compare T-bill maturities and pricing that fit that timeline.

    4-, 8-, 13-, 26- and 52-Week Treasury Bill Comparison

    If you are considering $100,000 in Treasury bills, the maturity date can be just as important as the quoted yield. This comparison focuses on five common T-bill terms: 4, 8, 13, 26 and 52 weeks. Treasury also offers other bill maturities, so these terms should be viewed as a practical comparison rather than a complete list of every available bill.

    MaturityApprox. TimelineCash-Planning RoleMain Consideration
    4 weeksAbout 1 monthVery near-term cashThe money reaches maturity relatively soon, creating an earlier reinvestment decision.
    8 weeksAbout 2 monthsNear-term cashGives you a little more time before the next maturity and reinvestment decision.
    13 weeksAbout 3 monthsShort-term cash planningCan fit a cash need that falls roughly three months ahead.
    26 weeksAbout 6 monthsMedium-term cash planningThe funds remain committed longer before the scheduled maturity.
    52 weeksAbout 1 yearLonger cash horizonThe money stays committed much longer before the next maturity decision.

    Does a Longer T-Bill Always Mean More Earnings?

    Not necessarily. Your actual dollar return depends on the purchase price, face value, maturity and yield available when you buy. A 52-week bill does not automatically produce a larger return simply because it has a longer term. Yields can differ across maturities and can change from one auction to another.

    Your cash needs matter too. If you expect to use part of the $100,000 within a few months, putting the entire amount into a longer-term bill could create a liquidity problem. A T-bill ladder can spread purchases across different maturity dates instead of concentrating the entire balance around one maturity.

    MATURITY TIP

    Start with the date when you may need the money. Then compare the available T-bill terms, purchase prices and current auction yields. That keeps the maturity decision connected to your cash plan rather than focusing only on the headline rate.

    Costs, Taxes, Risks and Expert Tips

    When $100,000 is involved, the quoted T-bill yield is only one part of the picture. Taxes, liquidity, reinvestment and the way you purchase or sell the bill can all affect the practical result.

    Taxes and Purchase Costs

    Interest from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes. For T-bills, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. TreasuryDirect does not charge a purchase fee or commission, although a bank or brokerage may have its own fees.

    Risks to Keep in Mind

    • Selling before maturity can expose you to a secondary-market price that differs from what you originally paid.
    • Reinvestment risk matters because the yield available when your bill matures may be different from today’s yield.
    • Inflation can reduce the purchasing power of your return even when the investment produces a positive nominal return.
    EXPERT TIP

    Before committing the full $100,000, check the maturity date against your expected cash needs. If you might need the money early, understand how your bank or broker handles secondary-market sales and review any applicable charges before buying.

    When comparing T-bills with other short-term choices, look beyond the headline yield. The tax treatment, maturity date and access to your money can change how useful the investment is for your particular cash plan.

    Common Mistakes and a $100,000 Treasury Bill Example

    A $100,000 Treasury bill purchase deserves more than a quick look at the quoted yield. The purchase price, maturity date and plan for the proceeds can all affect how the investment fits into your finances.

    Common Mistakes to Avoid

    • Treating an annualized T-bill yield as the exact dollar return for the entire maturity.
    • Assuming that having $100,000 in cash means the bill’s face value must also be exactly $100,000.
    • Choosing a maturity without checking when the money may actually be needed.
    • Assuming the same yield will be available when the bill matures and the proceeds are reinvested.
    • Selling before maturity without checking the current market price and any applicable transaction costs.

    A $100,000 Example

    Suppose an investor buys a hypothetical $100,000 face-value Treasury bill for $98,500.

    $100,000 − $98,500 = $1,500 gross return

    This is an illustrative example, not a current Treasury auction or market quote. The actual purchase price depends on the applicable Treasury pricing.

    If the investor holds the bill until maturity, the Treasury pays the $100,000 face value. The $1,500 difference is the gross return before applicable taxes. The example does not by itself establish an annualized yield because the maturity period is also needed for that calculation.

    CHECK BEFORE BUYING

    Before committing the full $100,000, confirm the face value, purchase price and maturity date. Then consider the federal tax treatment and when you expect to need the proceeds.

    Who Should Consider $100,000 in T-Bills?

    A $100,000 Treasury bill position may make sense for someone who has a substantial amount of cash available for a defined period and wants a scheduled maturity date. The key question is not simply how much the investment can earn. It is whether the maturity, liquidity and tax treatment fit the purpose of the money.

    Situations Where T-Bills May Fit

    • You have cash that is not expected to be needed before a selected maturity date.
    • You want to divide a large cash balance across several Treasury bill maturity dates.
    • You are comparing short-term Treasury securities with other cash-management choices.
    • You are comfortable with the possibility that reinvestment yields may be different when a bill matures.
    PLANNING CHECK

    Keep emergency reserves and money needed for near-term expenses separate from funds committed to a T-bill maturity. With $100,000, dividing the money across suitable maturities can also give you more than one point at which cash becomes available.

    Frequently Asked Questions About $100,000 in Treasury Bills

    1. How much can $100,000 earn in Treasury bills?

    The amount depends on the purchase price, maturity and yield available when you invest. When held to maturity, the gross return is generally the difference between the bill’s face value and purchase price.

    2. Can I invest exactly $100,000 in Treasury bills?

    Yes. You can use $100,000 of available cash to purchase Treasury bills, subject to the applicable purchase rules and available offerings. Because T-bills are generally purchased at a discount, the face value at maturity can be greater than the amount paid.

    3. Do Treasury bills pay monthly interest?

    No. Treasury bills generally do not make periodic coupon payments. They are typically purchased at a discount and pay their face value at maturity.

    4. Are Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Your individual tax situation can affect the amount you ultimately keep.

    5. Can I sell a Treasury bill before maturity?

    Yes. Treasury bills can generally be sold before maturity through a bank or broker in the secondary market. The market price at the time of sale can be higher or lower than your original purchase price.

    6. Which T-bill maturity should I choose for $100,000?

    There is no single maturity that fits every cash plan. Consider when you may need the money, then compare the available terms, purchase prices and annualized yields that fit that timeline.

    7. Can I reinvest $100,000 after a T-bill matures?

    You can use the maturity proceeds to purchase another Treasury bill. The next bill may have a different purchase price and yield, so its potential return may differ from the previous investment.

    8. Are Treasury bills completely risk-free?

    Treasury bills are U.S. government obligations, but investors can still face risks and limitations. Inflation can reduce purchasing power, future yields can change, and selling before maturity can expose you to changing market prices.

    Final Takeaway: How Much Can $100,000 Earn in Treasury Bills?

    The answer to How Much Can $100,000 Earn in Treasury Bills? depends on the purchase price, maturity and yield available when you invest. Because those factors can change, there is no single earnings figure that applies to every $100,000 T-bill purchase.

    When held to maturity, a Treasury bill generally pays its face value. The difference between the face value and purchase price represents the gross return before applicable taxes. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    THE BIG PICTURE

    For a $100,000 investment, pay attention to what you pay, when the bill matures and how you plan to use the proceeds. Taxes, liquidity needs and future reinvestment rates can also affect the overall result.

    Before You Invest

    Check the latest Treasury bill offerings and pricing before investing because yields and auction results can change. For the broader fundamentals, explore our

    Treasury Bills guide

    before making a purchase decision.
    Have a Money Question? Keep Exploring.

    Keep researching Treasury bills, cash management and investing with practical guides from FinanceInvestment.

    📧 Get in Touch With FinanceInvestment


    Email FinanceInvestment

    Continue Your Research
  • How Much Can $50,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $50,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $50,000 Earn in Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 20, 2026


    Reading Time: ~14 minutes

    How Much Can $50,000 Earn in Treasury Bills?

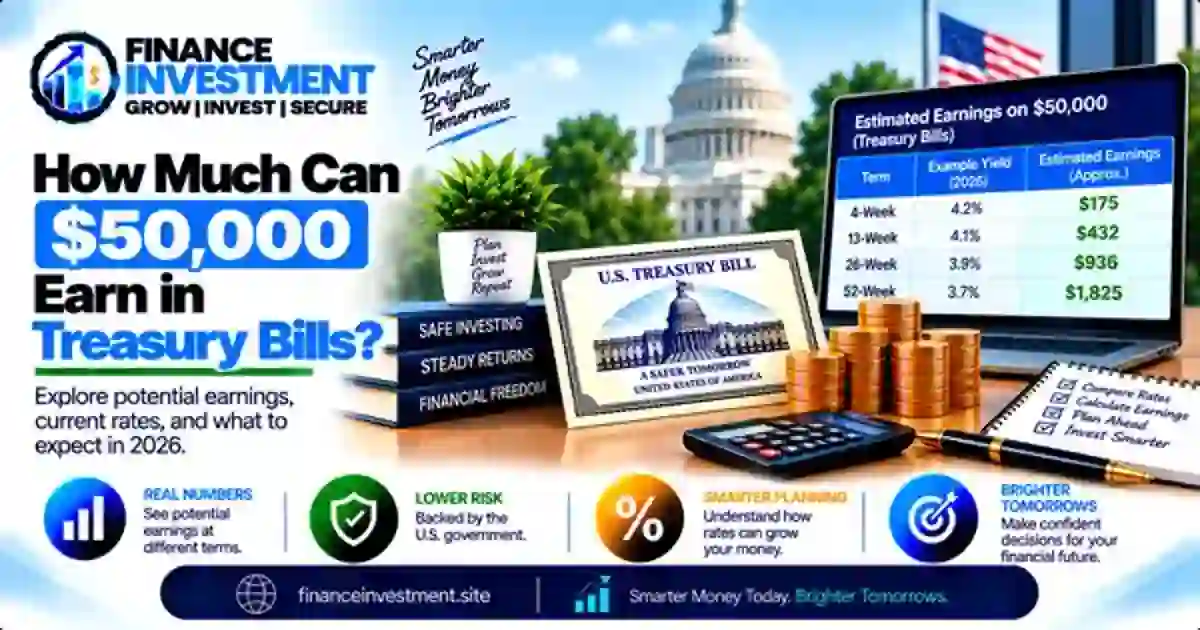
    How Much Can $50,000 Earn in Treasury Bills?How Much Can $50,000 Earn in Treasury Bills? There is no single answer because your potential return depends on the T-bill’s purchase price, maturity and yield available when you invest. With $50,000, the purchase price can make a noticeable difference in the gross amount you receive at maturity.

    Treasury bills also work differently from a savings account that may credit interest periodically. A T-bill is generally purchased at a discount to its face value and pays its face value at maturity when held to maturity. That makes both the price you pay and the date your money comes back important parts of the calculation.

    What You’ll Learn

    • How earnings on a $50,000 Treasury bill are calculated.
    • How 4-, 8-, 13-, 26- and 52-week maturities affect your cash timeline.
    • Why the purchase price matters when estimating your gross return.
    • How federal taxes and early-sale pricing can affect your results.
    • What to consider before placing the full $50,000 into one T-bill maturity.

    If Treasury bills are new to you, start with our

    complete Treasury Bills guide

    for the basic terminology and mechanics before moving into the $50,000 examples and maturity comparisons below.

    Quick Answer: What Could $50,000 Earn?

    The potential earnings on $50,000 in Treasury bills depend on the purchase price, maturity and yield available when you invest. If a $50,000 face-value bill is purchased for less than $50,000 and held to maturity, the difference between those amounts is the gross return before taxes.

    Key Takeaways

    • The face value of the bill and the amount you pay for it can be different.
    • Your gross return is the difference between the purchase price and the amount paid at maturity.
    • T-bill yields are annualized, so the quoted yield should not be treated as the exact dollar return for every term.
    • A shorter maturity returns the principal sooner, while a longer maturity keeps the money invested for more time.
    • Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • If you reinvest after maturity, the next T-bill may have a different yield.
    BOTTOM LINE

    There is no single earnings figure for every $50,000 T-bill purchase. The actual result starts with the price you pay and the face value you receive at maturity, then depends on taxes and what happens if you sell or reinvest.

    $50,000 Treasury Bill Earnings at a Glance

    A $50,000 T-bill investment can produce different gross returns depending on the purchase price, maturity and yield available when you buy. One important detail comes first: $50,000 can be the bill’s face value or the amount of cash you have available to invest. Those are not necessarily the same thing.

    EXAMPLE FACE VALUE
    $50,000
    GROSS RETURN SOURCE
    Face Value − Purchase Price
    MAIN VARIABLES
    Price, Yield & Maturity

    Maturity and Cash-Planning Snapshot

    MaturityApprox. TimelineExample Cash-Planning Role
    4 weeksAbout 1 monthVery short-term cash timeline
    8 weeksAbout 2 monthsNear-term cash planning
    13 weeksAbout 3 monthsRoughly quarterly timing
    26 weeksAbout 6 monthsMedium-term cash planning
    52 weeksAbout 1 yearLonger cash-planning horizon
    QUICK TAKE

    With $50,000, the maturity date can be an important part of the decision because more cash is involved. Start with when you expect to need the money, then compare the available T-bill terms and pricing for that timeline.

    Complete Beginner Guide: How $50,000 in T-Bills Works

    How Much Can $50,000 Earn in Treasury Bills?Treasury bills are short-term U.S. government securities with maturities of one year or less. If you have $50,000 available, you can use that cash to purchase T-bills, but the face value of the bills you receive does not have to equal exactly $50,000 because T-bills are generally purchased at a discount.
    What Happens After You Buy

    Suppose you purchase a hypothetical T-bill with a $50,000 face value for less than $50,000. If you hold that bill until maturity, you receive its $50,000 face value. The difference between the purchase price and the face value is the gross return before taxes.

    You can buy Treasury bills through TreasuryDirect or through a bank or brokerage. The maturity you choose determines when the bill is scheduled to mature, while the auction or market price determines what you pay. That makes the amount committed and the date you need the money important parts of the decision.

    BEGINNER TIP

    Before buying, write down two things: how much cash you want to commit and when you expect to need it again. Then compare that timeline with the T-bill’s maturity. This gives you a practical starting point before you look closely at the available yield.

    If you want to review the basic mechanics first, read our

    guide to how Treasury bills work
    .
    The next section moves from the buying process to the actual earnings calculation.

    How T-Bill Earnings Are Calculated

    The potential return on a $50,000 Treasury bill comes from the difference between what you pay and the bill’s face value at maturity. Treasury bills generally do not make periodic coupon payments. Instead, they are issued or purchased at a discount and pay the face value at maturity when held to maturity.

    Basic T-Bill Return Formula

    Gross Return = Face Value − Purchase Price

    For example, suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400. If you hold it until maturity, you would receive $50,000. The $600 difference represents the gross return before applicable federal income tax.

    Why the Quoted Yield Matters

    Treasury bill rates are annualized, so a quoted rate should not be treated as the exact dollar return for a shorter maturity. Treasury auction pricing commonly uses a discount-rate convention based on face value and a 360-day year, while the investment rate expresses an annualized return based on the purchase price and the applicable day-count convention. The maturity length therefore matters when translating a quoted rate into an actual dollar result.

    CALCULATION TIP

    When estimating earnings, use the actual purchase price, face value and maturity. Avoid simply multiplying $50,000 by an annualized rate and treating that number as the final return.

    For a closer look at Treasury bill pricing terminology, read our

    Treasury Bill Yield vs. Interest Rate guide
    .

    Benefits and Drawbacks of Investing $50,000 in T-Bills

    Investing $50,000 in Treasury bills can give you a defined maturity date and exposure to short-term U.S. government securities. However, the right maturity depends on when you may need the cash and what you plan to do with it afterward.

    Benefits

    • Short maturities can provide a defined timeline for returning the principal.
    • Treasury bills are obligations of the U.S. government.
    • T-bill interest income is generally exempt from state and local income taxes.
    • Different maturities allow you to match the investment with different cash needs.

    Drawbacks

    • Holding a bill to maturity means waiting until its scheduled maturity date for the face-value payment.
    • Reinvestment can produce a different return if future T-bill yields change.
    • Selling before maturity can result in a market price that is different from what you originally paid.
    • T-bills provide a defined short-term return structure rather than the ownership-based growth potential of stocks.
    BEFORE YOU INVEST

    With $50,000 involved, start with your cash timeline before focusing on the quoted yield. A maturity that fits your planned spending can be more useful than choosing a term based only on its annualized rate.

    4-, 8-, 13-, 26- and 52-Week Treasury Bill Comparison

    The maturity you choose determines how long the $50,000 remains invested before the bill reaches its scheduled maturity date. A shorter term can return the principal sooner, while a longer term extends the period before the next maturity or reinvestment decision.

    MaturityApprox. TimelineCash-Planning RoleMain Consideration
    4 weeksAbout 1 monthVery near-term cash timingShort investment period
    8 weeksAbout 2 monthsNear-term cash timingEarlier reinvestment decision
    13 weeksAbout 3 monthsQuarterly cash timingYield depends on purchase timing
    26 weeksAbout 6 monthsMedium-term cash timingCash stays invested longer
    52 weeksAbout 1 yearLonger cash-planning horizonMaturity is farther away

    Does a Longer Maturity Mean More Earnings?

    Not necessarily. Your actual dollar return depends on the purchase price, face value, maturity and yield available when you buy. A 52-week bill does not automatically produce a larger return simply because it has a longer maturity.

    The maturity you select should also fit your cash needs. If you expect to use part of the $50,000 within a few months, putting that entire amount into a longer-term bill may create a timing problem. A ladder can instead spread purchases across different maturity dates so that portions of the money become available at different times.

    MATURITY TIP

    Start with the date you may need the money. Then compare available T-bill maturities, purchase prices and annualized yields. This keeps both liquidity and potential return in view.

    Costs, Taxes, Risks and Expert Tips

    Before putting $50,000 into Treasury bills, look beyond the quoted yield. The purchase method, taxes, liquidity and the possibility of selling before maturity can all affect the practical outcome.

    Costs and Taxes

    TreasuryDirect does not charge a fee to purchase Treasury securities. Banks and brokerages can have their own account, transaction or trading charges, so review the institution’s current fee schedule before investing. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    Risks to Keep in Mind

    • Selling before maturity can produce a market price that is different from your original purchase price.
    • Reinvestment risk matters because future T-bill yields can change when your bill matures.
    • Inflation can reduce the purchasing power of the return over time.
    EXPERT TIP

    Compare the maturity date with your expected cash needs before focusing on the quoted yield. If early access could matter, understand how your bank or broker handles secondary-market sales and what charges may apply.

    The federal tax treatment can also make T-bills different from some other cash investments. Keep the tax effect in mind when comparing your expected after-tax results.

    Common Mistakes and a $50,000 Treasury Bill Example

    When you invest $50,000 in Treasury bills, the biggest mistakes often come from overlooking the details around price, maturity and reinvestment. A clear plan can help you understand what the investment is actually expected to return and when the money may become available again.

    Mistakes to Avoid

    • Treating an annualized yield as the exact dollar return for the entire maturity.
    • Confusing $50,000 of available cash with a $50,000 face-value T-bill.
    • Choosing a maturity without considering when the cash may be needed.
    • Assuming the same yield will be available when the bill matures and you reinvest.
    • Selling before maturity without checking the current market price and any applicable transaction costs.

    Illustrative $50,000 Example

    Suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400.

    $50,000 − $49,400 = $600 gross return

    This is an illustrative purchase-price example, not a current Treasury quote. The actual purchase price depends on the applicable auction or market conditions.

    If the bill is held to maturity, the investor receives its $50,000 face value. The $600 difference represents the gross return before applicable taxes. The actual annualized yield cannot be determined from these two dollar amounts alone because the maturity period also matters.

    CHECK BEFORE BUYING

    Confirm the face value, purchase price, maturity date and applicable tax treatment before committing the full $50,000.

    Who Should Consider $50,000 in T-Bills?

    A $50,000 Treasury bill allocation may be relevant for investors who have cash available for a defined period and want to use short-term U.S. government securities as part of their cash-management strategy. The appropriate maturity depends on when the money may be needed and whether the investor plans to reinvest the proceeds.

    Situations to Consider

    • You have cash that you do not expect to need before a selected maturity date.
    • You want to spread a larger cash balance across different T-bill maturity dates.
    • You are comparing Treasury bills with other short-term cash-management choices.
    • You understand that the yield available for a future reinvestment can change.
    PLANNING CHECK

    Before committing $50,000, separate money needed for near-term expenses or emergencies from money available for a chosen T-bill maturity. A Treasury bill can serve a specific cash-management purpose without being the only part of an overall financial plan.

    Frequently Asked Questions About $50,000 in Treasury Bills

    1. How much can $50,000 earn in Treasury bills?

    It depends on the purchase price, maturity and yield available when you invest. When held to maturity, the gross return is generally the difference between the bill’s face value and purchase price.

    2. Can I use exactly $50,000 to buy Treasury bills?

    Yes. You can commit $50,000 of available cash to a Treasury bill purchase, subject to the applicable purchase rules. Because T-bills are generally bought at a discount, the face value received at maturity can be higher than the amount you paid.

    3. Do Treasury bills pay monthly interest?

    No. Treasury bills generally do not make periodic coupon payments. They are typically purchased at a discount and pay their face value at maturity.

    4. Are Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    5. Can I sell a Treasury bill before maturity?

    Yes. Treasury bills can generally be sold before maturity through a bank or broker in the secondary market. The selling price can be higher or lower than your original purchase price.

    6. Which T-bill maturity should I choose for $50,000?

    There is no single maturity that fits every cash need. Consider when you expect to need the money, then compare the available maturities, purchase prices and annualized yields.

    7. Can I reinvest my $50,000 after a T-bill matures?

    Yes. After maturity, you can use the proceeds or purchase another Treasury bill. The yield available for the new bill may differ from the previous investment.

    8. Are Treasury bills completely risk-free?

    Treasury bills are U.S. government obligations, but “completely risk-free” can be misleading. Holding a bill to maturity avoids the need to sell at a changing market price, while inflation, reinvestment and early-sale considerations can still affect your overall result.

    Final Takeaway: How Much Can $50,000 Earn in Treasury Bills?

    The answer to How Much Can $50,000 Earn in Treasury Bills? depends on the purchase price, maturity and yield available when you invest. That means there is no single earnings figure that applies to every $50,000 T-bill purchase.

    When held to maturity, a Treasury bill generally pays its face value. The difference between the face value and purchase price represents the gross return before applicable taxes. Federal income tax can apply, while Treasury bill interest is generally exempt from state and local income taxes.

    THE BIG PICTURE

    For a $50,000 investment, pay attention to three core details: the purchase price, the face value at maturity and the date the money becomes available. Then account for taxes and your plans for the proceeds after maturity.

    Before You Invest

    Compare the available T-bill maturities, purchase prices and current auction information for the date you plan to invest. If you want to review the fundamentals again, explore our

    Treasury Bills guide

    before comparing specific opportunities.

    Have a Money Question? Keep Exploring.

    Get practical personal finance insights, investing guides and helpful money research from FinanceInvestment.

    📩 Get in Touch With FinanceInvestment


    Email FinanceInvestment

    Continue Your Research
  • How Much Can $25,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $25,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $25,000 Earn in Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 19, 2026


    Reading Time: ~14 minutes

    How Much Can $25,000 Earn in Treasury Bills?

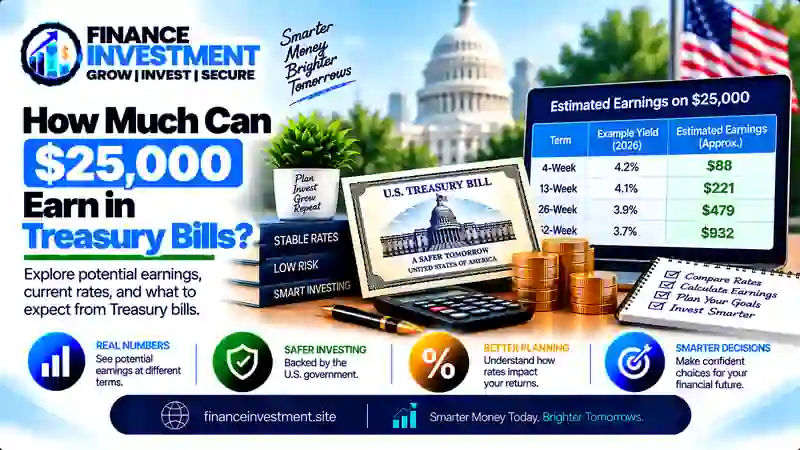
    How Much Can $25,000 Earn in Treasury Bills?How Much Can $25,000 Earn in Treasury Bills? There isn’t one fixed dollar amount. Your potential return depends on the T-bill yield, purchase price and maturity you choose. Unlike a savings account that may credit interest periodically, a Treasury bill is generally purchased below its face value and pays the full face value at maturity.

    With $25,000, even a small difference in the purchase price can change the dollar amount you earn. Your choice of maturity matters too. A bill that matures in a few months gives your money a different timeline than one held for close to a year. That makes the calendar just as important as the quoted yield when planning your cash.

    What You’ll Learn

    • How earnings on a $25,000 Treasury bill are calculated.
    • How 4-, 8-, 13-, 26- and 52-week maturities differ.
    • Why the purchase price matters when estimating your return.
    • How federal tax treatment can affect the amount you keep.
    • What to consider before putting the entire $25,000 into one bill.

    If Treasury bills are new to you, begin with our

    complete Treasury Bills guide

    before moving into the numbers and maturity comparisons in this article.

    Quick Answer: What Could $25,000 Earn?

    The potential earnings on $25,000 in Treasury bills depend on the bill you buy and the price set at purchase. T-bills are generally issued at a discount to face value, so an investor may pay less than $25,000 and receive $25,000 when the bill matures. The difference is the gross return before taxes.

    Key Takeaways

    • A $25,000 face-value bill can cost less than $25,000 at purchase.
    • Your gross earnings are tied to the purchase price and the amount received at maturity.
    • The quoted T-bill yield is annualized, so it should not be treated as the exact return for every maturity.
    • A 13-week bill and a 52-week bill give your money very different time horizons.
    • T-bill income is generally subject to federal income tax but exempt from state and local income taxes.
    • If you reinvest after maturity, the new bill may have a different yield.
    BOTTOM LINE

    There is no single earnings figure for every $25,000 T-bill investment. The maturity, auction result and purchase price all matter. The next sections show how to turn those details into a practical estimate.

    $25,000 Treasury Bill Earnings at a Glance

    A $25,000 Treasury bill investment starts with its face value, but the amount you pay can be lower. When the bill reaches maturity, you receive its face value if you hold it to maturity. The difference between the purchase price and the amount received is the gross return. Your actual purchase price depends on the yield and auction result available when you buy.

    FACE VALUE
    $25,000
    RETURN SOURCE
    Purchase Price Difference
    KEY VARIABLE
    Yield at Purchase

    Maturity Snapshot

    MaturityApprox. TimelineExample Cash-Planning Role
    4 weeksAbout 1 monthA very near-term cash timeline
    8 weeksAbout 2 monthsA short upcoming financial need
    13 weeksAbout 3 monthsA roughly quarterly timeline
    26 weeksAbout 6 monthsA medium-term cash horizon
    52 weeksAbout 1 yearMoney not expected to be needed soon
    QUICK TAKE

    The maturity tells you when the money is scheduled to come back. The purchase price tells you how much of the $25,000 face value you are giving up at the start. Looking at both numbers gives you a clearer picture of the potential gross return.

    Complete Beginner Guide: How $25,000 in Treasury Bills Works

    How Much Can $25,000 Earn in Treasury Bills? Treasury bills are short-term U.S. government securities with maturities of one year or less. When you put $25,000 into T-bills, you generally are not buying an investment that sends you monthly interest payments. Instead, a T-bill is typically sold at a discount and redeemed for its full face value at maturity.

    What Happens When You Buy

    Imagine you purchase a Treasury bill with a $25,000 face value. The purchase price can be below $25,000, depending on the auction result. If you hold the bill until maturity, the Treasury pays the $25,000 face value. The gap between your purchase price and that maturity value is the starting point for calculating your gross return.

    Treasury bills can be purchased directly through TreasuryDirect or through a bank or brokerage. Your maturity choice matters because it determines when the principal becomes available again. A bill with a longer term may not fit a cash need that arrives sooner, even if its quoted yield looks attractive.

    BEGINNER TIP

    Before buying, write down two numbers: the amount you will pay and the face value you expect at maturity. Then check the maturity date. Those details give you a clearer starting point than looking at the quoted yield by itself.

    If you want to understand the broader mechanics first, read our

    guide to how Treasury bills work
    .
    The next section moves into the actual earnings calculation.

    How Treasury Bill Earnings Are Calculated

    The basic math for a $25,000 Treasury bill starts with two numbers: the purchase price and the face value at maturity. If a hypothetical $25,000 bill costs $24,750 and you hold it until maturity, the difference would be $250 in gross interest before taxes.

    $25,000 − $24,750 = $250 gross interest
    Hypothetical example — not a current auction price

    Treasury calculates a bill’s discount rate using a 360-day basis. Its purchase-price formula is based on the discount rate and the number of days remaining until maturity. Treasury also publishes an investment rate, which is an annualized simple rate based on the purchase price and uses a 365-day year, or 366 days when applicable.

    Why the Quoted Yield Does Not Equal Your Dollar Gain

    A quoted T-bill rate is annualized. Your actual dollar return also depends on how long the bill remains outstanding. For that reason, multiplying $25,000 by an annualized rate can overstate the earnings on a bill that matures in only a few months.

    CALCULATION TIP

    For an actual purchase, check the auction result and the price you will pay. Then compare that amount with the $25,000 face value. The difference gives you the basic gross return before considering taxes or other factors.

    This same approach works across different T-bill maturities. What changes is the price, the number of days until maturity and the rate available when you purchase the bill.

    Benefits and Drawbacks of Investing $25,000 in T-Bills

    Treasury bills can be useful when you have money that can remain invested until a known maturity date. At the same time, a $25,000 investment has limits that are easy to overlook if you focus only on the quoted yield.

    POTENTIAL BENEFITS
    • Short maturities can fit specific near-term cash needs.
    • T-bills are obligations of the U.S. government.
    • Interest is generally exempt from state and local income taxes.
    • Multiple maturity periods give investors different cash timelines.

    POTENTIAL DRAWBACKS
    • Selling before maturity can expose you to changes in market price.
    • The yield available when you reinvest may differ from your original yield.
    • T-bill income is generally subject to federal income tax.
    • Inflation can reduce the purchasing power of the return.
    WHAT TO WATCH

    The biggest practical question is when you need the money. Holding the bill until maturity can keep the outcome tied to its stated maturity value, while selling earlier means accepting the market price available at that time.

    4-, 8-, 13-, 26- and 52-Week T-Bill Comparison

    If you have $25,000 to invest, the maturity date determines how long the money stays committed before the bill reaches its scheduled maturity. Treasury currently offers regular bills with several maturities, including 4, 8, 13, 26 and 52 weeks. The right comparison starts with your timeline, then moves to the yield and purchase price available at the time you invest.

    MaturityApprox. Timeline$25,000 Cash-Planning RoleWhat to Check
    4 weeksAbout 1 monthVery near-term cash planningMaturity date and purchase price
    8 weeksAbout 2 monthsA short upcoming cash needYield and time to maturity
    13 weeksAbout 3 monthsA roughly quarterly timelineAuction result and purchase price
    26 weeksAbout 6 monthsMedium-term cash planningYield, price and maturity date
    52 weeksAbout 1 yearMoney not expected to be needed soonLonger commitment and reinvestment plans

    Why the Maturity Matters

    A shorter maturity gives you access to the principal sooner, while a longer bill keeps the money invested for more time. However, the maturity length does not by itself tell you which bill will have the highest annualized yield. Treasury auction results and market conditions can change the rates available across maturities.

    Treasury bills are generally sold at a discount or at par and pay their face value at maturity. The difference between the purchase price and face value is the interest earned.

    COMPARISON TIP

    If your $25,000 has a specific job later this year, start with the date you expect to need it. Then compare the available T-bill yields and purchase prices for maturities that fit that timeline. This keeps the cash plan at the center of the comparison.

    Costs, Taxes, Risks & Expert Tips

    A $25,000 Treasury bill investment can have a relatively straightforward cost structure, but the headline yield is not the only number that matters. Taxes, early-sale pricing, reinvestment rates and your cash needs can all affect the outcome.

    Federal Taxes and State Tax Benefits

    Treasury bill interest is generally subject to federal income tax. However, interest from U.S. Treasury obligations is generally exempt from state and local income taxes. That difference can matter when comparing T-bills with other short-term investments, especially for investors who live in states with income taxes.

    Selling Before Maturity

    Holding a T-bill until maturity is different from selling it in the secondary market. If you sell before maturity through a bank or broker, the market price can be above or below your original purchase price. The result can therefore differ from the return you would have received by holding the bill to maturity.

    Reinvestment Risk

    A 13-week or 26-week T-bill eventually matures, and you may want to invest the proceeds again. The yield available at that future auction may be higher or lower than the rate on your original purchase. Your long-term earnings can therefore differ from a single T-bill’s return.

    EXPERT TIP

    Before investing the full $25,000, compare the maturity date with the date you may need the cash. A slightly different yield may matter less than having the money available when your financial plan calls for it.

    To understand another important part of T-bill pricing, read our

    Treasury Bill Yield vs. Interest Rate guide
    .

    Common Mistakes and a $25,000 T-Bill Example

    Investing $25,000 in Treasury bills is relatively straightforward, but estimating the return requires attention to a few details. Investors can misread an annualized yield, overlook the maturity date or confuse gross earnings with the amount they keep after taxes.

    Common Mistakes to Avoid

    • Using the annualized yield as though it were the exact dollar return for every maturity.
    • Forgetting that the purchase price determines the difference between what you pay and the face value received at maturity.
    • Choosing a maturity without checking when the $25,000 may be needed.
    • Assuming the same yield will be available when the proceeds are reinvested.
    • Estimating the final amount without accounting for federal income taxes.

    A Practical $25,000 Example

    Suppose an investor purchases a hypothetical T-bill with a $25,000 face value for $24,700. If the investor holds the bill until maturity, the maturity payment would be $25,000. The difference is $300 in gross earnings before taxes.

    EXAMPLE CHECK

    $25,000 face value − $24,700 purchase price = $300 gross earnings. This is a hypothetical illustration only. The actual purchase price depends on the Treasury auction or secondary-market price available when you invest.

    The example also shows why the amount invested and the face value are not always the same number. Your actual return depends on the price you pay, the maturity date and the terms available when you purchase the bill. For more background, see our

    guide to how Treasury bills make money
    .

    Who Should Consider $25,000 in T-Bills?

    A $25,000 Treasury bill investment may make sense for someone who has cash available for a defined period and wants a known maturity date. The important question is not simply how much the bill may earn, but whether its maturity fits the purpose of the money.

    Situations Where T-Bills May Fit

    • Investors holding cash for a known expense within several months or about a year.
    • Families looking to place a portion of short-term cash in U.S. Treasury securities.
    • Retirees who want to coordinate part of their cash holdings with specific maturity dates.
    • Investors who understand that T-bills are short-term securities rather than a substitute for a long-term diversified portfolio.

    When the Timeline Matters Most

    The maturity date should match the date you expect to need the money. If your plans change, selling before maturity can produce a different result because the market price may have moved since you bought the bill.

    BEFORE YOU INVEST

    Start with the purpose and timing of the $25,000. Once you know when the cash may be needed, you can compare T-bill maturities, purchase prices and available yields more meaningfully.

    Frequently Asked Questions About $25,000 in Treasury Bills

    1. How much can $25,000 earn in Treasury bills?

    It depends on the purchase price, maturity and yield available when you buy. If you hold a $25,000 face-value bill to maturity, the difference between what you pay and the $25,000 maturity value represents the gross earnings.

    2. Can I use exactly $25,000 to buy Treasury bills?

    Yes. However, $25,000 of available cash does not necessarily mean you will receive a $25,000 face-value bill. T-bills are purchased in increments of $100, and the purchase price depends on the bill’s auction or market price.

    3. Do Treasury bills pay monthly interest?

    No. T-bills generally do not make periodic coupon payments. They are typically sold at a discount and pay their face value at maturity.

    4. Are Treasury bill earnings taxable?

    Yes. T-bill interest is generally subject to federal income tax, while interest from U.S. Treasury obligations is generally exempt from state and local income taxes.

    5. Can I sell a Treasury bill before maturity?

    Yes. T-bills held through a bank or broker can generally be sold in the secondary market. The market price at that time may be higher or lower than your original purchase price.

    6. Does a longer T-bill always earn more?

    Not necessarily. Annualized yields can differ across maturities and auction dates. A longer maturity also means your money remains invested for a longer period.

    7. What happens when my $25,000 T-bill matures?

    If you hold the bill until maturity, you receive its face value. You can then use the proceeds or reinvest them in another Treasury security at the rates available at that time.

    8. Is $25,000 enough to invest in Treasury bills?

    Yes. Treasury bills can be purchased in relatively small increments, so $25,000 is more than enough to make a T-bill purchase. The amount you invest should still fit your cash needs and overall financial plan.

    QUICK FAQ NOTE

    Your actual earnings depend on the purchase price, maturity and rate available when you buy. Check the specific auction or transaction details before estimating the dollar return on $25,000.

    Final Takeaway: How Much Can $25,000 Earn in T-Bills?

    A $25,000 Treasury bill investment does not have one fixed earnings amount. Your gross return depends on the purchase price, maturity and yield available when you invest. The amount you ultimately keep can also be affected by federal income taxes.

    The maturity date deserves just as much attention as the potential return. A shorter bill gives you access to the money sooner, while a longer bill keeps the funds invested for a longer period. If your plans change, selling before maturity can produce a different result because market prices can move.

    FINAL TAKEAWAY

    Before investing $25,000, check the purchase price, maturity date, expected face-value payment and tax treatment. If you plan to reinvest after maturity, remember that the next T-bill may offer a different yield.

    For a broader look at T-bill maturities, pricing and purchase options, continue with our

    complete Treasury Bills guide
    .

    Have a Money Question? Keep Exploring.

    FinanceInvestment covers practical topics on saving, investing and building long-term financial knowledge. Keep exploring our guides for clear explanations you can use in your own research.

    📩 Get in Touch With FinanceInvestment

    Have a question or feedback about our finance content?


    Email FinanceInvestment

    Continue Your Research