Tag: Investing 2026

  • How Much Can $50,000 Earn in Treasury Bills? 2026 Guide
    How Much Can $50,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $50,000 Earn in Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 20, 2026


    Reading Time: ~14 minutes

    How Much Can $50,000 Earn in Treasury Bills?

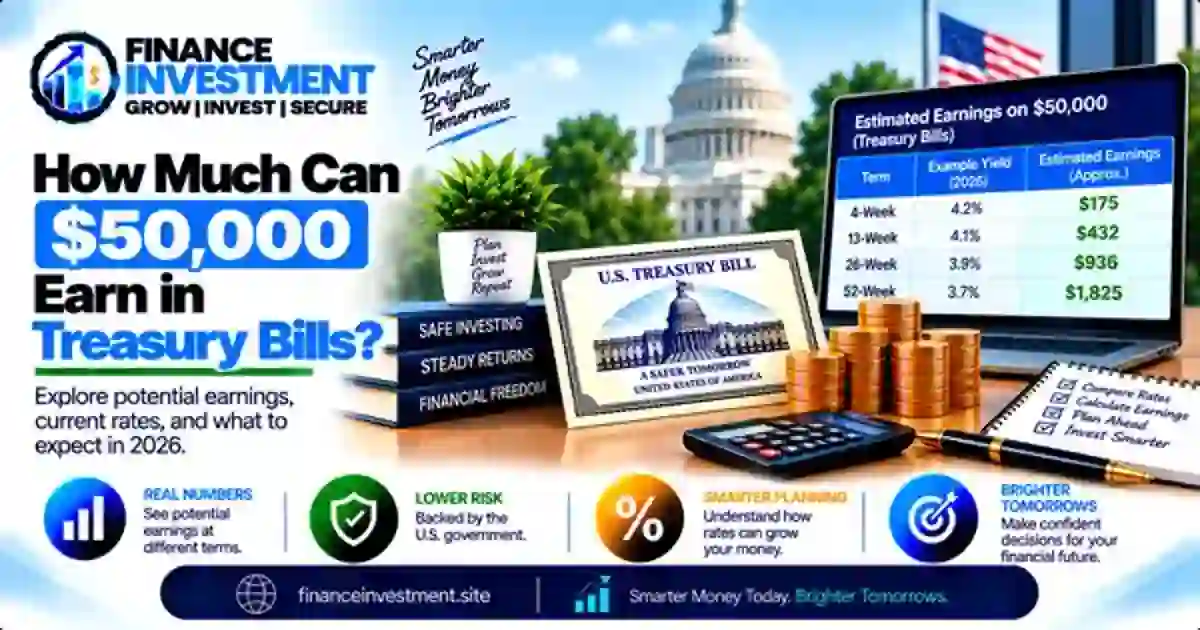
    How Much Can $50,000 Earn in Treasury Bills?How Much Can $50,000 Earn in Treasury Bills? There is no single answer because your potential return depends on the T-bill’s purchase price, maturity and yield available when you invest. With $50,000, the purchase price can make a noticeable difference in the gross amount you receive at maturity.

    Treasury bills also work differently from a savings account that may credit interest periodically. A T-bill is generally purchased at a discount to its face value and pays its face value at maturity when held to maturity. That makes both the price you pay and the date your money comes back important parts of the calculation.

    What You’ll Learn

    • How earnings on a $50,000 Treasury bill are calculated.
    • How 4-, 8-, 13-, 26- and 52-week maturities affect your cash timeline.
    • Why the purchase price matters when estimating your gross return.
    • How federal taxes and early-sale pricing can affect your results.
    • What to consider before placing the full $50,000 into one T-bill maturity.

    If Treasury bills are new to you, start with our

    complete Treasury Bills guide

    for the basic terminology and mechanics before moving into the $50,000 examples and maturity comparisons below.

    Quick Answer: What Could $50,000 Earn?

    The potential earnings on $50,000 in Treasury bills depend on the purchase price, maturity and yield available when you invest. If a $50,000 face-value bill is purchased for less than $50,000 and held to maturity, the difference between those amounts is the gross return before taxes.

    Key Takeaways

    • The face value of the bill and the amount you pay for it can be different.
    • Your gross return is the difference between the purchase price and the amount paid at maturity.
    • T-bill yields are annualized, so the quoted yield should not be treated as the exact dollar return for every term.
    • A shorter maturity returns the principal sooner, while a longer maturity keeps the money invested for more time.
    • Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • If you reinvest after maturity, the next T-bill may have a different yield.
    BOTTOM LINE

    There is no single earnings figure for every $50,000 T-bill purchase. The actual result starts with the price you pay and the face value you receive at maturity, then depends on taxes and what happens if you sell or reinvest.

    $50,000 Treasury Bill Earnings at a Glance

    A $50,000 T-bill investment can produce different gross returns depending on the purchase price, maturity and yield available when you buy. One important detail comes first: $50,000 can be the bill’s face value or the amount of cash you have available to invest. Those are not necessarily the same thing.

    EXAMPLE FACE VALUE
    $50,000
    GROSS RETURN SOURCE
    Face Value − Purchase Price
    MAIN VARIABLES
    Price, Yield & Maturity

    Maturity and Cash-Planning Snapshot

    MaturityApprox. TimelineExample Cash-Planning Role
    4 weeksAbout 1 monthVery short-term cash timeline
    8 weeksAbout 2 monthsNear-term cash planning
    13 weeksAbout 3 monthsRoughly quarterly timing
    26 weeksAbout 6 monthsMedium-term cash planning
    52 weeksAbout 1 yearLonger cash-planning horizon
    QUICK TAKE

    With $50,000, the maturity date can be an important part of the decision because more cash is involved. Start with when you expect to need the money, then compare the available T-bill terms and pricing for that timeline.

    Complete Beginner Guide: How $50,000 in T-Bills Works

    How Much Can $50,000 Earn in Treasury Bills?Treasury bills are short-term U.S. government securities with maturities of one year or less. If you have $50,000 available, you can use that cash to purchase T-bills, but the face value of the bills you receive does not have to equal exactly $50,000 because T-bills are generally purchased at a discount.

    What Happens After You Buy

    Suppose you purchase a hypothetical T-bill with a $50,000 face value for less than $50,000. If you hold that bill until maturity, you receive its $50,000 face value. The difference between the purchase price and the face value is the gross return before taxes.

    You can buy Treasury bills through TreasuryDirect or through a bank or brokerage. The maturity you choose determines when the bill is scheduled to mature, while the auction or market price determines what you pay. That makes the amount committed and the date you need the money important parts of the decision.

    BEGINNER TIP

    Before buying, write down two things: how much cash you want to commit and when you expect to need it again. Then compare that timeline with the T-bill’s maturity. This gives you a practical starting point before you look closely at the available yield.

    If you want to review the basic mechanics first, read our

    guide to how Treasury bills work
    .
    The next section moves from the buying process to the actual earnings calculation.

    How T-Bill Earnings Are Calculated

    The potential return on a $50,000 Treasury bill comes from the difference between what you pay and the bill’s face value at maturity. Treasury bills generally do not make periodic coupon payments. Instead, they are issued or purchased at a discount and pay the face value at maturity when held to maturity.

    Basic T-Bill Return Formula

    Gross Return = Face Value − Purchase Price

    For example, suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400. If you hold it until maturity, you would receive $50,000. The $600 difference represents the gross return before applicable federal income tax.

    Why the Quoted Yield Matters

    Treasury bill rates are annualized, so a quoted rate should not be treated as the exact dollar return for a shorter maturity. Treasury auction pricing commonly uses a discount-rate convention based on face value and a 360-day year, while the investment rate expresses an annualized return based on the purchase price and the applicable day-count convention. The maturity length therefore matters when translating a quoted rate into an actual dollar result.

    CALCULATION TIP

    When estimating earnings, use the actual purchase price, face value and maturity. Avoid simply multiplying $50,000 by an annualized rate and treating that number as the final return.

    For a closer look at Treasury bill pricing terminology, read our

    Treasury Bill Yield vs. Interest Rate guide
    .

    Benefits and Drawbacks of Investing $50,000 in T-Bills

    Investing $50,000 in Treasury bills can give you a defined maturity date and exposure to short-term U.S. government securities. However, the right maturity depends on when you may need the cash and what you plan to do with it afterward.

    Benefits

    • Short maturities can provide a defined timeline for returning the principal.
    • Treasury bills are obligations of the U.S. government.
    • T-bill interest income is generally exempt from state and local income taxes.
    • Different maturities allow you to match the investment with different cash needs.

    Drawbacks

    • Holding a bill to maturity means waiting until its scheduled maturity date for the face-value payment.
    • Reinvestment can produce a different return if future T-bill yields change.
    • Selling before maturity can result in a market price that is different from what you originally paid.
    • T-bills provide a defined short-term return structure rather than the ownership-based growth potential of stocks.
    BEFORE YOU INVEST

    With $50,000 involved, start with your cash timeline before focusing on the quoted yield. A maturity that fits your planned spending can be more useful than choosing a term based only on its annualized rate.

    4-, 8-, 13-, 26- and 52-Week Treasury Bill Comparison

    The maturity you choose determines how long the $50,000 remains invested before the bill reaches its scheduled maturity date. A shorter term can return the principal sooner, while a longer term extends the period before the next maturity or reinvestment decision.

    MaturityApprox. TimelineCash-Planning RoleMain Consideration
    4 weeksAbout 1 monthVery near-term cash timingShort investment period
    8 weeksAbout 2 monthsNear-term cash timingEarlier reinvestment decision
    13 weeksAbout 3 monthsQuarterly cash timingYield depends on purchase timing
    26 weeksAbout 6 monthsMedium-term cash timingCash stays invested longer
    52 weeksAbout 1 yearLonger cash-planning horizonMaturity is farther away

    Does a Longer Maturity Mean More Earnings?

    Not necessarily. Your actual dollar return depends on the purchase price, face value, maturity and yield available when you buy. A 52-week bill does not automatically produce a larger return simply because it has a longer maturity.

    The maturity you select should also fit your cash needs. If you expect to use part of the $50,000 within a few months, putting that entire amount into a longer-term bill may create a timing problem. A ladder can instead spread purchases across different maturity dates so that portions of the money become available at different times.

    MATURITY TIP

    Start with the date you may need the money. Then compare available T-bill maturities, purchase prices and annualized yields. This keeps both liquidity and potential return in view.

    Costs, Taxes, Risks and Expert Tips

    Before putting $50,000 into Treasury bills, look beyond the quoted yield. The purchase method, taxes, liquidity and the possibility of selling before maturity can all affect the practical outcome.

    Costs and Taxes

    TreasuryDirect does not charge a fee to purchase Treasury securities. Banks and brokerages can have their own account, transaction or trading charges, so review the institution’s current fee schedule before investing. Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    Risks to Keep in Mind

    • Selling before maturity can produce a market price that is different from your original purchase price.
    • Reinvestment risk matters because future T-bill yields can change when your bill matures.
    • Inflation can reduce the purchasing power of the return over time.
    EXPERT TIP

    Compare the maturity date with your expected cash needs before focusing on the quoted yield. If early access could matter, understand how your bank or broker handles secondary-market sales and what charges may apply.

    The federal tax treatment can also make T-bills different from some other cash investments. Keep the tax effect in mind when comparing your expected after-tax results.

    Common Mistakes and a $50,000 Treasury Bill Example

    When you invest $50,000 in Treasury bills, the biggest mistakes often come from overlooking the details around price, maturity and reinvestment. A clear plan can help you understand what the investment is actually expected to return and when the money may become available again.

    Mistakes to Avoid

    • Treating an annualized yield as the exact dollar return for the entire maturity.
    • Confusing $50,000 of available cash with a $50,000 face-value T-bill.
    • Choosing a maturity without considering when the cash may be needed.
    • Assuming the same yield will be available when the bill matures and you reinvest.
    • Selling before maturity without checking the current market price and any applicable transaction costs.

    Illustrative $50,000 Example

    Suppose a hypothetical $50,000 face-value T-bill has a purchase price of $49,400.

    $50,000 − $49,400 = $600 gross return

    This is an illustrative purchase-price example, not a current Treasury quote. The actual purchase price depends on the applicable auction or market conditions.

    If the bill is held to maturity, the investor receives its $50,000 face value. The $600 difference represents the gross return before applicable taxes. The actual annualized yield cannot be determined from these two dollar amounts alone because the maturity period also matters.

    CHECK BEFORE BUYING

    Confirm the face value, purchase price, maturity date and applicable tax treatment before committing the full $50,000.

    Who Should Consider $50,000 in T-Bills?

    A $50,000 Treasury bill allocation may be relevant for investors who have cash available for a defined period and want to use short-term U.S. government securities as part of their cash-management strategy. The appropriate maturity depends on when the money may be needed and whether the investor plans to reinvest the proceeds.

    Situations to Consider

    • You have cash that you do not expect to need before a selected maturity date.
    • You want to spread a larger cash balance across different T-bill maturity dates.
    • You are comparing Treasury bills with other short-term cash-management choices.
    • You understand that the yield available for a future reinvestment can change.
    PLANNING CHECK

    Before committing $50,000, separate money needed for near-term expenses or emergencies from money available for a chosen T-bill maturity. A Treasury bill can serve a specific cash-management purpose without being the only part of an overall financial plan.

    Frequently Asked Questions About $50,000 in Treasury Bills

    1. How much can $50,000 earn in Treasury bills?

    It depends on the purchase price, maturity and yield available when you invest. When held to maturity, the gross return is generally the difference between the bill’s face value and purchase price.

    2. Can I use exactly $50,000 to buy Treasury bills?

    Yes. You can commit $50,000 of available cash to a Treasury bill purchase, subject to the applicable purchase rules. Because T-bills are generally bought at a discount, the face value received at maturity can be higher than the amount you paid.

    3. Do Treasury bills pay monthly interest?

    No. Treasury bills generally do not make periodic coupon payments. They are typically purchased at a discount and pay their face value at maturity.

    4. Are Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    5. Can I sell a Treasury bill before maturity?

    Yes. Treasury bills can generally be sold before maturity through a bank or broker in the secondary market. The selling price can be higher or lower than your original purchase price.

    6. Which T-bill maturity should I choose for $50,000?

    There is no single maturity that fits every cash need. Consider when you expect to need the money, then compare the available maturities, purchase prices and annualized yields.

    7. Can I reinvest my $50,000 after a T-bill matures?

    Yes. After maturity, you can use the proceeds or purchase another Treasury bill. The yield available for the new bill may differ from the previous investment.

    8. Are Treasury bills completely risk-free?

    Treasury bills are U.S. government obligations, but “completely risk-free” can be misleading. Holding a bill to maturity avoids the need to sell at a changing market price, while inflation, reinvestment and early-sale considerations can still affect your overall result.

    Final Takeaway: How Much Can $50,000 Earn in Treasury Bills?

    The answer to How Much Can $50,000 Earn in Treasury Bills? depends on the purchase price, maturity and yield available when you invest. That means there is no single earnings figure that applies to every $50,000 T-bill purchase.

    When held to maturity, a Treasury bill generally pays its face value. The difference between the face value and purchase price represents the gross return before applicable taxes. Federal income tax can apply, while Treasury bill interest is generally exempt from state and local income taxes.

    THE BIG PICTURE

    For a $50,000 investment, pay attention to three core details: the purchase price, the face value at maturity and the date the money becomes available. Then account for taxes and your plans for the proceeds after maturity.

    Before You Invest

    Compare the available T-bill maturities, purchase prices and current auction information for the date you plan to invest. If you want to review the fundamentals again, explore our

    Treasury Bills guide

    before comparing specific opportunities.
    Have a Money Question? Keep Exploring.

    Get practical personal finance insights, investing guides and helpful money research from FinanceInvestment.

    📩 Get in Touch With FinanceInvestment


    Email FinanceInvestment

    Continue Your Research
  • How Much Can $10,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $10,000 Earn in Treasury Bills? 2026 Guide

    How Much Can $10,000 Earn in Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 19, 2026


    Reading Time: ~13 minutes

    How Much Can $10,000 Earn in Treasury Bills?How Much Can $10,000 Earn in Treasury Bills? It depends on the bill’s maturity, the yield available when you buy, and the price you pay. Treasury bills work differently from savings accounts because they generally do not make monthly interest payments. Instead, you buy a bill for less than its face value and receive the full face value when it matures.

    That difference between what you pay and what you receive is where your return comes from. A 4-week bill can produce a much smaller dollar gain than a 26-week or 52-week bill, even though all of them are Treasury securities. The actual result also changes as market yields move.

    What You’ll Learn

    • How Treasury bill earnings are calculated on a $10,000 investment.
    • How 4-week, 13-week, 26-week, and 52-week bills can differ.
    • Why the purchase price matters when estimating your return.
    • How federal taxes can affect your after-tax earnings.
    • What to consider before investing $10,000 in T-bills.

    If you want to understand the basics before looking at the numbers, start with our

    complete Treasury Bills guide
    .

    How Much Can $10,000 Earn in Treasury Bills?

    A $10,000 Treasury bill investment can earn different amounts depending on the bill’s maturity, auction yield, and purchase price. T-bills are generally bought below face value and mature at face value, so the difference between those two amounts represents the return before taxes. Because quoted T-bill yields are annualized, a shorter-term bill will not simply pay the full annualized rate over its shorter holding period.

    Key Takeaways

    • Your gross return is generally the difference between what you pay and the bill’s face value at maturity.
    • The maturity date helps determine how long your money remains invested.
    • The quoted yield is annualized, so the actual dollar return depends on the length of the investment.
    • T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • Reinvesting maturing T-bills can change your cumulative earnings over time.

    Now we can move from the quick answer to the numbers and see how a $10,000 investment can work across different Treasury bill maturities.

    $10,000 Treasury Bill Earnings at a Glance

    There is no single answer to how much $10,000 can earn in Treasury bills. Your potential return depends on the maturity you choose, the yield set at purchase, and the price of the bill. Because T-bills are generally purchased below face value and redeemed at face value, the difference between those amounts creates your gross return.

    T-Bill TermHolding PeriodWhat It Means for $10,000
    4 weeksShort termA shorter period for the discount to become part of your return
    13 weeksAbout 3 monthsA common short-term option for planned cash needs
    26 weeksAbout 6 monthsYour return is tied to the yield and price locked in at purchase
    52 weeksAbout 1 yearA longer commitment with the return determined when you buy
    QUICK TAKE

    The cleanest way to estimate your gross earnings is to compare the amount you pay with the $10,000 face value you receive at maturity. For example, a hypothetical 4% annualized yield can help illustrate the math, but it should not be treated as today’s T-bill rate or a guaranteed return. Your actual purchase price depends on the auction result.

    Once you understand that relationship between purchase price and face value, the calculation becomes much easier. The next section walks through how the $10,000 investment actually works from purchase to maturity.

    How $10,000 in Treasury Bills Works

    How Much Can $10,000 Earn in Treasury Bills?Treasury bills are short-term U.S. government securities with maturities of one year or less. If you plan to put $10,000 into a T-bill, the amount you pay at purchase is generally less than the bill’s face value. You then receive the full face value when the bill matures, assuming you hold it to maturity.
    Your Return Comes From the Discount

    Imagine a hypothetical $10,000 T-bill with a purchase price of $9,850. If you hold it until maturity, you receive $10,000. The $150 difference represents your gross return before taxes. This is only an illustration; your actual purchase price depends on the yield and auction results when you buy.

    Treasury bills can be purchased directly through TreasuryDirect or through a bank or brokerage. They do not make periodic coupon payments. Instead, the return is reflected in the difference between the purchase price and the amount paid at maturity. Selling before maturity is different: the market price can move, so you may receive more or less than your original purchase price.

    QUICK TIP

    Before buying, check the bill’s face value, purchase price, maturity date, and quoted yield. Those details give you a much clearer picture of what your $10,000 investment could produce.

    Once you understand the discount, the earnings calculation becomes much easier. The next section puts the math into a simple example you can reuse for different T-bill maturities.

    How T-Bill Earnings Are Calculated

    For a $10,000 Treasury bill, the face value is $10,000. The amount you actually pay can be lower because T-bills are generally sold at a discount. If you hold the bill until maturity, the difference between your purchase price and the $10,000 face value is your gross return.

    A Simple $10,000 Example

    Suppose a hypothetical $10,000 T-bill has a purchase price of $9,900. If you hold it to maturity, the basic return calculation would be:

    $10,000 face value − $9,900 purchase price = $100 gross return

    That $100 is the dollar gain in this illustration. It is not a statement about a current T-bill rate. In an actual Treasury auction, the purchase price is determined by the auction result and the terms of the bill.

    Treasury’s discount-rate calculation uses a 360-day basis. Its investment-rate calculation is based on the purchase price and uses a 365-day basis, or 366 days during a leap year. The investment rate is useful when comparing T-bill returns with other investments that use a more familiar annualized yield.

    IMPORTANT

    Do not treat an annualized T-bill yield as the exact dollar amount you will earn over a shorter maturity. The actual gain depends on the purchase price, face value, and time until maturity.

    Once you understand this relationship, comparing different T-bill maturities becomes much easier. The next section looks at the advantages and trade-offs of using Treasury bills for your $10,000.

    Benefits and Drawbacks of Putting $10,000 in T-Bills

    Treasury bills can be useful for money you expect to need within a relatively short period. Still, a $10,000 investment has trade-offs. The right maturity depends on when you may need the cash and what yield is available when you buy.

    Potential Benefits

    • Short maturities can work well for planned cash needs.
    • T-bills are obligations of the U.S. government.
    • Interest is generally exempt from state and local income taxes.
    • Several maturity options let you match the investment to your timeline.

    Potential Drawbacks

    • Your planned return assumes you hold the bill until maturity.
    • Reinvestment rates may be different when the bill matures.
    • Selling before maturity can expose you to market-price changes.
    • T-bill income is generally subject to federal income tax.

    One useful distinction is liquidity. You can sell a Treasury bill before maturity through the secondary market, but the price at that time may be above or below what you originally paid. Holding until maturity avoids that particular market-price uncertainty, assuming the bill is held to maturity.

    How $10,000 Can Work Across Different T-Bill Maturities

    Treasury bills are available in several short-term maturities, so the best comparison starts with your timeline rather than a single rate. The table below shows how the main terms differ for someone considering a $10,000 investment. Actual earnings depend on the yield and purchase price available when you buy.

    MaturityApprox. LengthWhat It Means for $10,000Possible Use
    4 weeksAbout 1 monthShortest commitment in this comparisonNear-term cash planning
    8 weeksAbout 2 monthsShort-term investment horizonPlanned expenses or cash reserves
    13 weeksAbout 3 monthsModerate short-term commitmentQuarterly cash planning
    26 weeksAbout 6 monthsLonger period before maturityMedium-term cash goals
    52 weeksAbout 1 yearLongest commitment in this comparisonMoney not expected to be needed soon

    A longer maturity does not automatically mean a higher annualized yield. Treasury yields can differ across maturities as market conditions change. That means the rate available when you buy matters just as much as the length of the bill when estimating what your $10,000 could earn.

    QUICK TAKE

    Choose the maturity around your cash timeline first. Then compare the available yield and purchase price. A higher quoted rate is only useful if the maturity also fits when you expect to need the money.

    Costs, Taxes, Risks and Tips for a $10,000 T-Bill Investment

    The headline yield is only one part of the picture when you invest $10,000 in Treasury bills. Taxes, account terms, liquidity and the possibility of changing rates after maturity can all affect your overall result.

    Taxes and Account Costs

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. If you purchase through a bank or brokerage, review its pricing and trading terms because fees or other charges can vary by provider.

    Risks Worth Knowing

    • Selling before maturity can expose you to changes in the market price.
    • The yield available when you reinvest may be different from your original yield.
    • Inflation can reduce the purchasing power of the money you earn.
    INVESTOR TIP

    Before putting the full $10,000 into one bill, think about when you may need the cash. If your timeline is uncertain, using different maturities can provide more flexibility than committing the entire amount to one maturity date.

    The goal is not simply to find a yield that looks attractive. Your maturity, tax situation, access to cash and reinvestment plans should all make sense for the role this $10,000 plays in your finances.

    Common Mistakes When Investing $10,000 in T-Bills

    Most T-bill mistakes are not complicated math errors. They happen when investors focus on the advertised annualized yield and overlook the purchase price, maturity date, taxes, or what they may need the money for later.

    Four Mistakes Worth Avoiding

    • Multiplying $10,000 by the annualized yield without adjusting for the bill’s maturity.
    • Looking at the yield but ignoring the actual purchase price.
    • Choosing a maturity date that arrives after you expect to need the cash.
    • Calculating gross earnings without considering federal income taxes.

    A Practical $10,000 Example

    Imagine someone has $10,000 available today but expects to use the money in about three months. Instead of choosing a maturity based only on the highest quoted yield, the investor could compare a short-term bill with a maturity that better matches that cash need. The actual earnings would then depend on the purchase price and auction yield available at the time.

    SMART CHECK

    Before buying, ask yourself: How much will I pay? When will I receive the face value? When might I need the cash? What will my after-tax return look like? Those four questions can make a $10,000 T-bill decision much clearer.

    Who Should Consider Investing $10,000 in T-Bills?

    A $10,000 Treasury bill investment may fit someone who has a defined time horizon and wants to know when the bill is scheduled to mature. It can also suit investors looking to keep part of their money in short-term U.S. government securities rather than putting that cash into assets with greater price swings.

    • Short-term planners: You have a known financial goal within the next few weeks or months.
    • Cash-focused investors: You want a short-term government security for money that is not needed immediately.
    • Maturity planners: You can choose a bill that lines up with your expected cash need.
    • Tax-aware investors: State and local tax treatment may be an advantage depending on your situation.

    A T-bill may be less convenient if you need the money at any moment or are primarily seeking long-term capital growth. In those cases, liquidity and investment horizon deserve attention before choosing a maturity or committing the full $10,000.

    Frequently Asked Questions About $10,000 in Treasury Bills

    1. How much can $10,000 earn in Treasury bills?

    There is no single fixed amount. Your gross earnings depend on the bill’s purchase price, face value, maturity and yield when you buy it. A shorter maturity also covers less time than a full-year investment, so the dollar return cannot be calculated by simply applying a full year’s yield.

    2. Do Treasury bills pay monthly interest?

    No. Treasury bills generally do not make periodic coupon payments. They are typically sold at a discount and redeemed at face value at maturity, with the difference representing the gross return.

    3. Can I buy $10,000 of T-bills directly from the Treasury?

    Yes. Treasury bills can be purchased directly through TreasuryDirect or through a bank or brokerage account. TreasuryDirect purchases are available in increments that meet the Treasury’s current minimum purchase requirements.

    4. Are Treasury bill earnings taxable?

    T-bill interest is generally subject to federal income tax but exempt from state and local income taxes. Your individual tax situation determines how much of the gross return you ultimately keep.

    5. What happens if I need the $10,000 before maturity?

    You can generally sell a Treasury bill through the secondary market using a bank or broker. The market price can change before maturity, so the amount you receive may be different from what you originally paid.

    6. Is a 52-week T-bill always the right choice instead of a 13-week T-bill?

    Not necessarily. The two maturities have different time commitments and may offer different yields. Your expected cash need and the yield available when you purchase should both be considered.

    7. Can I reinvest my $10,000 after a T-bill matures?

    Yes. You can use the maturity proceeds to purchase another Treasury bill if the new investment fits your plan. The yield on the new bill may be different from the rate available on your original purchase.

    8. Should I put all $10,000 into one T-bill?

    That depends on your cash needs and investment plan. Using different maturities can spread out maturity dates, while one bill may be simpler if you have a specific date when you expect to use the money.

    Final Takeaway: What Can $10,000 Earn in Treasury Bills?

    The earnings on $10,000 in Treasury bills depend on the price you pay, the bill’s face value, its maturity and the yield available when you purchase it. Since T-bills are generally sold at a discount and mature at face value, the difference between those amounts is the starting point for estimating your gross return.

    The maturity you choose also changes the role that $10,000 plays in your finances. A shorter bill may fit money you expect to use sooner, while a longer maturity may suit funds that can remain invested for longer. Taxes, liquidity and the rate available when you reinvest should also be considered.

    THE BIG PICTURE

    Start with your cash timeline, then look at the available T-bill yield and purchase price. This gives you a more useful estimate of what your $10,000 could earn than looking at an annualized rate by itself.

    If you want to go deeper into how Treasury bills work, explore our

    complete Treasury Bills guide
    .

    Have a Money Question? Keep Exploring.

    Building your financial knowledge takes time. Keep exploring FinanceInvestment for practical guides on saving, Treasury securities, investing, and everyday money decisions.

    📩 Get in Touch With FinanceInvestment


    Email FinanceInvestment

  • 13-Week Treasury Bills Explained: Complete 2026 Guide

    13-Week Treasury Bills Explained: Complete 2026 Guide

    13-Week Treasury Bills Explained: A Complete Beginner Guide for 2026


    SR

    Subhash Rukade
    Founder, FinanceInvestment


    TREASURY GUIDE


    BEGINNER GUIDE

    Last Updated
    September 17, 2026
    Reading Time
    About 15 minutes
    Guide Focus
    91-Day Treasury Bills


    13-Week Treasury Bills

    13-Week Treasury Bills give investors a simple way to put money to work for about three months while keeping a clear maturity date in sight. A 13-week Treasury bill is a short-term U.S. government security with a 91-day term. It is generally purchased at a discount and pays its face value when it matures.

    That pricing structure can feel confusing at first. You may see a Treasury bill quoted with a discount rate, investment rate, or yield rather than a traditional interest rate. Your actual return comes from the difference between what you pay and the amount you receive at maturity.

    This guide breaks the process into practical steps. You’ll see how the 13-week Treasury bill auction works, how much a purchase can potentially earn, what taxes apply, where you can buy T-bills, and what happens if you want to reinvest after 91 days.

    What You’ll Learn

    • How 13-week Treasury bills work from purchase to maturity.
    • How Treasury auctions, discount pricing, and yields fit together.
    • How to estimate your dollar return on a T-bill investment.
    • How federal, state, and local taxes affect Treasury bill income.
    • How TreasuryDirect and brokerage accounts can be used to buy T-bills.
    • What to consider before reinvesting or selling before maturity.

    Quick Answer

    What Is a 13-Week Treasury Bill?

    A 13-week Treasury bill is a short-term U.S. Treasury security that matures in 91 days. Instead of paying regular interest every month, it is generally sold at a discount and pays its full face value at maturity. Your return is the difference between the purchase price and the amount you receive when the bill matures.

    Key Takeaways

    • Term: The standard 13-week bill has a 91-day maturity.
    • Return: The discount between your purchase price and face value represents the bill’s interest income.
    • Purchase: Investors can buy Treasury bills through TreasuryDirect or eligible banks and brokers.
    • Taxes: Treasury bill interest is subject to federal income tax but is generally exempt from state and local income taxes.
    • Timing: Holding the bill until maturity gives you a defined 91-day investment timeline; selling earlier can expose you to market-price changes.

    13-Week T-Bills at a Glance

    A 13-week Treasury bill is a short-term U.S. Treasury security with a 91-day maturity. It does not make regular coupon payments. Instead, Treasury bills are generally issued at a discount to face value, with the face value paid when the bill matures. The difference between the purchase price and maturity value represents the interest earned.

    Feature13-Week T-Bill
    Maturity91 days
    Minimum purchaseGenerally $100, in $100 multiples
    PricingGenerally sold at a discount
    Periodic couponNone
    At maturityFace value is paid
    QUICK TAKE:
    Think of a 13-week T-bill as a defined 91-day cash cycle. You buy the bill below its face value, hold it through maturity, and receive the face value. The difference is your interest income before taxes.

    Complete Beginner Guide to 13-Week Treasury Bills

    If you have never bought a Treasury bill, the basic idea is easier than the terminology makes it sound. You are lending money to the U.S. government for a short period. With a 13-week bill, that period is 91 days.

    The bill has a face value, but you generally pay less than that amount when you buy it. At maturity, you receive the face value. That difference is your interest income before taxes. Treasury bills do not send you monthly or quarterly coupon payments along the way.

    How a Beginner Can Approach a 13-Week T-Bill

    1. Choose the amount: Treasury bills are generally available in $100 increments.
    2. Choose where to buy: You can use TreasuryDirect or a brokerage account that offers Treasury securities.
    3. Enter your order: Individual investors commonly use a noncompetitive bid at Treasury auctions, accepting the auction-determined terms.
    4. Hold until maturity: The 13-week bill reaches maturity after 91 days, when its face value is paid.
    5. Decide what happens next: You can use the proceeds for another goal or reinvest them in a new Treasury security.
    Beginner tip:
    Don’t judge a T-bill only by its advertised rate. Look at the purchase price, maturity value, holding period, and taxes to understand what the investment means in actual dollars.

    Treasury bill interest is taxable at the federal level but generally exempt from state and local income taxes.

    How 13-Week Treasury Bills Work

    A simple way to understand a 13-week Treasury bill is to follow it from auction to maturity. Treasury sells bills through public auctions using a single-price auction process. Individual investors can place a noncompetitive bid, which means they accept the rate or discount determined at the auction rather than choosing their own rate.

    The 91-Day Process

    1. Auction: Treasury accepts competitive and noncompetitive bids for the bill. The auction establishes the price used for successful purchases.
    2. Purchase: A Treasury bill is generally sold below its face value. Your purchase price depends on the auction result and the amount of face value you request.
    3. Settlement: Once the purchase is settled, you own the Treasury bill electronically. TreasuryDirect draws the required funds from your designated funding source.
    4. Holding period: The bill remains outstanding for its 13-week term. Unlike Treasury notes and bonds, it does not make periodic coupon payments.
    5. Maturity: At maturity, the Treasury pays the bill’s face value. The difference between the purchase price and face value is the bill’s interest income.

    For example, imagine a 13-week bill with a $10,000 face value is issued for $9,900. If you hold it until maturity, you receive $10,000. The $100 difference represents your gross interest income before taxes. This is only an illustration; the actual purchase price is set by the auction.

    Important:
    A Treasury bill’s quoted rate is annualized. It is not the same thing as the dollar amount you will earn over 91 days. To understand your actual return, look at the purchase price, face value, and holding period together.

    Benefits and Drawbacks of 13-Week Treasury Bills

    A 13-week T-bill can be useful when you want a defined short-term investment period, but it is not a perfect fit for every cash need. The biggest trade-off is between predictable maturity timing and the flexibility you may want from an ordinary savings account.

    Benefits

    • Short commitment: The 91-day maturity can work well for money you expect to need within a few months.
    • Defined maturity value: If held to maturity, the bill pays its face value.
    • Federal government security: T-bills are direct obligations of the U.S. government.
    • Tax advantage: Treasury interest is generally exempt from state and local income taxes.

    Drawbacks

    • No regular income payments: You do not receive monthly or quarterly coupon payments.
    • Cash is committed: Your money is tied to the security until maturity unless you sell it.
    • Early-sale risk: Selling before maturity means accepting the prevailing market price, which can be higher or lower than your purchase price.
    • Reinvestment risk: When the bill matures, a new 13-week bill may offer a different rate.
    QUICK TAKE:
    The appeal of a 13-week T-bill is its defined 91-day timeline and government backing. The main limitation is that your next investment rate is not locked in today, and selling before maturity exposes you to market pricing.

    13-Week T-Bills vs. Other Short-Term Options

    A 13-week Treasury bill is one of several ways to manage cash over a short period. Savings accounts, money market deposit accounts, and short-term CDs work differently. The useful comparison is not just the advertised rate. Liquidity, deposit insurance, taxes, maturity, and what happens if you need the money early all matter.

    OptionAccess to MoneyProtection / BackingTax Treatment
    13-Week T-Bill91-day maturity; may be sold before maturity through a bank, broker, or dealerDirect U.S. government obligation; not FDIC-insuredFederal tax; generally exempt from state and local income taxes
    High-Yield SavingsGenerally designed for easier access to deposited cashFDIC insurance may apply when held as an eligible deposit at an FDIC-insured bankInterest generally subject to federal income tax
    Money Market Deposit AccountGenerally provides account access, subject to the institution’s termsFDIC insurance may apply when eligibleInterest generally subject to federal income tax
    Short-Term CDFixed term; early withdrawal may involve a penaltyFDIC insurance may apply when eligibleInterest generally subject to federal income tax

    The biggest practical difference is how you access the money. A savings account or money market deposit account is built around account access, while a CD typically asks you to accept a defined term. A T-bill has a maturity date, but because it is a marketable security, you can sell it before maturity. That sale happens at the prevailing market price, so the amount you receive can differ from what you originally paid.

    QUICK TAKE:
    Compare the entire cash arrangement rather than the headline rate alone. A 13-week T-bill offers a defined maturity and U.S. government backing, while eligible bank deposits can offer FDIC insurance and easier account access. The right comparison depends on when you need the money and how much flexibility you want.

    Costs, Taxes, Risks, and Expert Tips

    13-Week Treasury BillsA 13-week Treasury bill has a fairly simple structure, but the quoted rate is only one part of the decision. Your purchase price, account costs, tax treatment, and plans for the money can all affect the result.
    Costs and Taxes

    • TreasuryDirect: TreasuryDirect does not charge a fee to purchase Treasury securities. A bank or broker may have its own pricing, commissions, or service terms.
    • Federal tax: Interest from Treasury bills is subject to federal income tax.
    • State and local tax: Treasury bill interest is exempt from state and local income taxes.

    Risks and Practical Tips

    • Early sale: Selling before maturity exposes you to the prevailing market price and can produce a gain or loss compared with your purchase price.
    • Reinvestment: When the 91-day term ends, a new T-bill may carry a different rate.
    • Check the actual numbers: Compare the purchase price, face value, holding period, and taxes instead of relying only on an annualized quoted rate.
    EXPERT TIP:
    Match the maturity date with the approximate date you expect to use the money. That can reduce the chance that you will need to sell the bill early simply because your cash need arrived sooner than expected.

    Tax note: Most individual investors use the cash method for federal tax reporting, but the tax treatment of a Treasury bill can differ when it is sold before maturity or held under special circumstances. Use your Form 1099-INT and current IRS guidance when preparing your return.

    Common Mistakes and a Real-Life Example

    Most beginner mistakes with 13-week Treasury bills come down to three things: misunderstanding the quoted rate, overlooking the maturity date, or failing to account for taxes. A quick check before placing an order can make the numbers much easier to understand.

    Common Mistakes to Avoid

    • Confusing yield with a 91-day return:
      The quoted Treasury rate is annualized. It should not be read as the exact percentage you will earn during the 13-week holding period.
    • Ignoring the maturity date:
      If you need the money sooner, you may have to sell the bill before maturity at the prevailing market price.
    • Forgetting federal taxes:
      Treasury bill interest is subject to federal income tax, although it is generally exempt from state and local income taxes.
    • Assuming the next bill will pay the same rate:
      A new Treasury bill can have a different auction rate when your current bill matures.

    Real-Life Example: A $10,000 Face-Value Bill

    Suppose an investor buys a 13-week Treasury bill with a $10,000 face value for an illustrative purchase price of $9,900. If the investor holds the bill until maturity, the Treasury pays the $10,000 face value.

    Illustrative purchase price
    $9,900
    Face value at maturity
    $10,000
    Gross difference
    $100

    For a typical cash-method individual investor who holds the bill to maturity, that $100 discount is generally reported as interest income when the bill matures. This example is illustrative only; $9,900 is not a current auction price.

    QUICK TAKE:
    Before buying, check three things together: the amount you pay, the face value you will receive at maturity, and the date you expect to need the money. That simple check can prevent many beginner mistakes.

    Who Should Choose 13-Week T-Bills?

    A 13-week Treasury bill may fit someone who has cash available for a short-term goal and does not expect to need it for about 91 days. The defined maturity can make it easier to coordinate the investment with a planned expense, a future purchase, or another financial decision.

    A 13-Week T-Bill May Fit If You:

    • Have cash you can leave invested for roughly three months.
    • Want a specific maturity date rather than an open-ended savings arrangement.
    • Prefer a short-term U.S. government security for money that is not needed immediately.
    • Value the federal tax treatment of Treasury interest, including its general exemption from state and local income taxes.
    Consider another option if:
    You may need the money before the 91-day maturity date or want everyday access similar to a savings account. A T-bill can be sold before maturity, but its market price may differ from the amount you originally paid.

    The key question is simple: does the 91-day timeline match the purpose and timing of your cash?

    Frequently Asked Questions About 13-Week Treasury Bills

    These common questions cover the basics of buying, holding, taxing, and using a 13-week Treasury bill.

    1. What is a 13-week Treasury bill?

    A 13-week Treasury bill is a short-term U.S. government security with a 91-day maturity. It is generally issued at a discount and pays its face value at maturity.

    2. How does a 13-week T-bill make money?

    You generally buy the bill for less than its face value. If you hold it to maturity, you receive the face value. The difference between your purchase price and the maturity value represents the gross interest income.

    3. What is the minimum amount needed to buy a 13-week T-bill?

    Treasury bills are generally offered in $100 increments. The amount actually paid depends on the bill’s auction price because T-bills are generally sold below face value.

    4. Where can I buy 13-week Treasury bills?

    Individual investors can buy Treasury bills through TreasuryDirect or through participating banks and brokerage firms. Brokers may also provide access to the secondary market.

    5. How are 13-week Treasury bills taxed?

    Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes. For a typical cash-method taxpayer who holds the bill to maturity, the discount is generally reported as interest income when the bill matures.

    6. Can I sell a 13-week T-bill before maturity?

    Yes. Treasury bills are marketable securities and can generally be sold before maturity through a bank, broker, or dealer. The market price at the time of sale can be different from your original purchase price.

    7. What happens when a 13-week T-bill matures?

    At maturity, the Treasury pays the bill’s face value. You can use the proceeds for your cash needs or reinvest them in another Treasury security.

    8. What should I consider before buying a 13-week T-bill?

    Consider whether the 91-day maturity matches your cash timeline, whether you may need the money earlier, how the federal and state tax treatment affects you, and what rate may be available if you reinvest after maturity.

    QUICK TAKE:
    The core numbers are simple: your purchase price, the bill’s face value, and the 91-day maturity. The details that deserve extra attention are taxes, liquidity, and what you plan to do when the bill matures.

    Final Verdict: What to Know Before Buying a 13-Week Treasury Bill

    A 13-week Treasury bill is a short-term U.S. government security with a defined 91-day maturity. It is generally issued at a discount, and the Treasury pays the bill’s face value when it matures. The difference between the purchase price and maturity value represents the gross return for a bill held to maturity.

    Before buying, look beyond the quoted annualized rate. Check the actual purchase price, the maturity date, federal tax treatment, your need for access to the money, and the rate that may be available if you reinvest after maturity.

    BOTTOM LINE:
    A 13-week T-bill follows a straightforward cycle:
    purchase → 91-day holding period → maturity → next cash decision.
    The important question is whether that timeline matches the purpose and timing of your money.

    If your plans change before maturity, a T-bill can generally be sold through a bank, broker, or dealer, but its market price at that time may differ from your original purchase price.

    Have a Money Question? Keep Exploring.

    A 13-week Treasury bill is one piece of a short-term cash plan. Keep exploring Treasury securities, savings options, and other personal finance topics with practical FinanceInvestment guides.

    📩 Get in Touch With FinanceInvestment

    Have a question or a topic you’d like us to cover?


    Email FinanceInvestment

  • 8-Week Treasury Bills Explained: Complete 2026 Guide

    8-Week Treasury Bills Explained: Complete 2026 Guide

    8-Week Treasury Bills Explained: A Complete Beginner Guide for 2026

    Subhash Rukade
    Founder, FinanceInvestment


    TREASURY GUIDE


    BEGINNER GUIDE


    Last Updated


    September 16, 2026


    Reading Time


    About 15 minutes


    8-WEEK TREASURY GUIDE

    8-Week Treasury Bills Explained: The 56-Day Cash Cycle

    8-Week Treasury Bills8-Week Treasury Bills are short-term U.S. Treasury securities with a 56-day maturity. They are generally sold below their face value, and the investor receives the face value when the bill matures. The difference between those amounts represents the bill’s interest.

    That 56-day window creates a useful middle ground between very short Treasury bills and longer cash commitments. But the number that gets attention first—the quoted annualized yield—is only part of the picture. The auction price, maturity date, taxes, access to the money and what happens after maturity all deserve attention.

    If Treasury bills are new to you, start with our

    complete Treasury bills guide
    .
    Then use this guide to focus specifically on the 8-week term, from buying the bill to deciding what to do with the proceeds after 56 days.

    What You’ll Learn


    How the 56 Days Work


    Follow the bill from auction and purchase through its maturity date.

    How You Earn


    See how discount pricing creates the dollar return at maturity.

    Taxes & Risks


    Understand federal taxes, early sales and changing reinvestment rates.

    Buying & Reinvesting


    Learn where to buy and what your choices are when the bill matures.
    QUICK ANSWER

    How Do 8-Week Treasury Bills Work?

    An 8-week Treasury bill is a 56-day U.S. Treasury security. It is generally issued at a discount to its face value. If you hold the bill until maturity, the Treasury pays the face value according to its terms, with the difference between your purchase price and that amount representing the gross interest.

    Key Takeaways


    56-Day Maturity


    An 8-week bill is identified by Treasury as a 56-day bill.

    Discount Pricing


    The purchase price is generally below the bill’s face value.

    No Coupon Payments


    T-bills do not make regular interest payments during the term.

    Federal Tax Applies


    Treasury bill interest is subject to federal income tax but generally exempt from state and local income taxes.

    Reinvestment Is Separate


    A new bill can have a different yield when you reinvest after maturity.

    Early Sale Has Market Risk


    Selling before maturity means the price you receive can differ from what you paid.

    Bottom line:
    An 8-week T-bill is built around a defined 56-day holding period. The quoted annualized yield helps with comparisons, but the purchase price, maturity date, taxes and your plan for the money after maturity matter just as much.

    Table of Contents

    Jump directly to the part of this 8-week Treasury bill guide you want to explore.

    8-Week Treasury Bills at a Glance

    An 8-week Treasury bill is a short-term U.S. Treasury security
    with a 56-day term. Instead of making regular interest payments,
    a Treasury bill is generally issued at a discount to its face value. At maturity,
    the investor receives the amount due under the bill’s terms, with the difference
    between the purchase price and maturity value representing the investment’s gross
    interest.

    Quick FactWhat It Means
    Term56 days, commonly described by the Treasury as an 8-week bill
    PricingGenerally sold at a discount to face value
    InterestComes from the difference between the purchase price and maturity value
    PaymentsNo periodic coupon payments
    Minimum bidCurrent 8-week Treasury bill offerings specify $100 and multiples of $100
    After maturityYou can use the proceeds or consider reinvesting in another Treasury security
    QUICK TAKE

    An 8-week T-bill is easiest to understand as a short cash cycle:
    buy → wait 56 days → receive the maturity amount → decide what to do next.
    The quoted yield helps compare investments, but your actual dollar return depends
    on the purchase price, amount invested and maturity value.

    8-Week Treasury Bills: A Complete Beginner Guide

    8-Week Treasury BillsIf you are new to Treasury bills, think of an 8-week Treasury bill
    as a short-term place for money you expect to need after roughly two months.
    The Treasury sells these securities through auctions. An 8-week bill is identified
    by the U.S. Treasury as a 56-Day Bill.

    Unlike a savings account or a Treasury note, an 8-week T-bill does not send you
    regular interest payments. It is generally purchased for less than its face value.
    If you hold it until maturity, the Treasury pays the amount due under the security’s
    terms. The difference between what you paid and the maturity value is the basic
    source of your gross return.

    1. Choose the Amount

    Decide how much cash you can leave invested for the 56-day term.

    2. Enter an Auction

    You can place a noncompetitive bid through TreasuryDirect or use a brokerage that offers Treasury auctions.

    3. Pay the Purchase Price

    The final auction price determines how much you pay for the bill.

    4. Reach Maturity

    After 56 days, the Treasury pays the maturity amount according to the bill’s terms.

    BEGINNER TIP

    Before buying, check the auction date, issue date and maturity date.
    The maturity date matters most because that is when you expect the money to become
    available again. Do not choose an 8-week bill simply because the quoted annualized
    yield looks attractive; first make sure the 56-day timeline matches your cash needs.

    How 8-Week Treasury Bills Work

    The easiest way to understand an 8-week Treasury bill is to follow the money
    from auction to maturity. The U.S. Treasury offers the bill at auction, and
    the final auction results determine the price investors pay. The Treasury
    identifies the 8-week security as a 56-Day Bill.

    STEP 1

    Auction

    Treasury bills are offered through scheduled auctions. A noncompetitive
    bidder accepts the auction’s resulting terms rather than specifying a rate.

    STEP 2

    Purchase

    The bill is generally purchased below its face value. Your purchase price
    depends on the auction result and the amount of the bill you buy.

    STEP 3

    56-Day Hold

    The bill remains outstanding until its stated maturity date. It does not
    make monthly or quarterly coupon payments during this period.

    STEP 4

    Maturity

    At maturity, the Treasury pays the face value according to the bill’s
    terms. The difference between your purchase price and that amount is
    the basic gross return.

    A Simple Example

    Suppose an investor buys a hypothetical $1,000 face-value 8-week T-bill for
    $992.50. If the investor holds it until maturity and receives $1,000, the
    gross difference is $7.50. This is only an illustration;
    the actual purchase price and return depend on the auction.

    THE KEY IDEA

    The quoted annualized yield helps investors compare short-term securities,
    but it is not the same as the actual dollar amount earned over 56 days.
    For your personal calculation, focus on the purchase price, face value,
    amount invested and maturity date.

    Benefits & Drawbacks of 8-Week Treasury Bills

    An 8-week Treasury bill can be useful when you want a defined
    short-term investment period. But the 56-day maturity also means you need to
    plan around the money being invested. Here are the main advantages and trade-offs
    to understand before buying.

    Benefits to Know

    • Short maturity: The 56-day term gives the investment a clearly defined end date.
    • U.S. government security: Treasury bills are obligations of the U.S. government.
    • No periodic coupon: You do not receive monthly or quarterly interest payments.
    • State and local tax advantage: Treasury bill interest is generally exempt from state and local income taxes.
    • Flexible access: Investors can buy bills through TreasuryDirect or participating financial institutions and brokers.

    Drawbacks to Consider

    • Limited day-to-day liquidity: Your money is committed to the security until maturity unless you sell it.
    • Early-sale price risk: If you sell before maturity, the market price can be higher or lower than your purchase price.
    • Federal taxes still apply: Treasury bill interest is generally subject to federal income tax.
    • Future rates can change: If you reinvest after maturity, the next 8-week bill may have a different auction yield.
    • No guaranteed future yield: Today’s auction result does not lock in the rate for your next Treasury bill.

    The practical takeaway:
    An 8-week T-bill works on a fixed 56-day timeline. Before investing, make sure
    the maturity date fits your cash needs and remember that selling early introduces
    market-price risk.

    8-Week Treasury Bills vs Other Short-Term Options

    An 8-week T-bill is only one way to manage money over a short period.
    Savings accounts, money market accounts and CDs work differently, so the
    comparison should go beyond the advertised rate. Your access needs, tax
    situation and intended holding period can change the practical result.

    OptionTime StructureAccess & Tax Notes
    8-Week T-BillFixed 56-day maturityCan be held to maturity or sold in the secondary market; Treasury interest is generally exempt from state and local income taxes.
    Savings AccountNo fixed maturityDesigned for easier access; interest rates can change over time and eligible deposits may receive federal deposit insurance.
    Money Market AccountNo fixed maturityBank or credit-union deposit account with access features that may include checks or a debit card; rates can change.
    CDFixed term selected at openingEarly withdrawal generally involves a penalty; CD interest is generally subject to applicable federal and state taxes.

    What Should You Compare?

    Start with the date you expect to need the money. A 56-day T-bill has a
    defined maturity, while a savings or money market account does not lock
    your funds into a specific maturity date. A CD also has a defined term,
    but its early-access rules are different.

    Taxes can also affect the comparison. Treasury bill interest is generally
    subject to federal income tax but exempt from state and local income taxes.
    Bank deposit interest generally does not receive that Treasury tax exemption.

    QUICK COMPARISON

    Think in terms of time, access, taxes and rate structure.
    The highest advertised rate is not necessarily the most useful comparison
    for money that has a specific job and a specific date.

    Costs, Risks & Expert Tips for 8-Week Treasury Bills

    The quoted yield is only one part of an 8-week Treasury bill
    decision. Before buying, look at the purchase price, tax treatment, access to
    your money and what could happen if you need to sell before the 56-day maturity.

    Purchase Costs

    TreasuryDirect does not charge a purchase fee or commission for Treasury
    securities. A bank or broker may have its own fees, pricing or transaction policies.

    Early-Sale Risk

    If you sell before maturity, the bill’s market price can be above or below
    your purchase price as market interest rates and other conditions change.

    Tax Treatment

    Treasury bill interest is subject to federal income tax but is exempt from
    state and local income taxes.

    Reinvestment Risk

    When your bill matures, a new 8-week bill may have a different auction yield.
    The next rate is not locked in by today’s purchase.

    Three Checks Before You Buy

    1. Check the dates: Know the auction date, issue date and
      maturity date before committing your cash.
    2. Check the price: Look at the actual purchase price rather
      than treating the annualized yield as your 56-day dollar return.
    3. Check your cash deadline: If you may need the money before
      maturity, understand the secondary-market price risk before buying.
    TAX RECORD TIP

    Keep your Treasury purchase records and tax documents. For most individual
    taxpayers using the cash method, Treasury bill interest is generally reported
    when the bill is paid at maturity. Tax rules can differ for other situations.

    Common Mistakes With 8-Week Treasury Bills

    Most mistakes with an 8-week Treasury bill happen when investors
    focus only on the quoted yield. The purchase price, maturity date and plan for
    the cash can matter just as much.

    Mistake 1: Treating Yield as 8-Week Return

    The quoted Treasury yield is annualized. It should not be treated as the
    actual percentage earned during the 56-day term.

    Mistake 2: Ignoring the Maturity Date

    Buying without checking when the bill matures can create a cash-flow problem
    if the money is needed sooner.

    Mistake 3: Forgetting the Next Step

    At maturity, the proceeds become available according to the security’s
    terms. Decide in advance whether the cash will be spent, saved or reinvested.

    A Simple 8-Week Treasury Bill Example

    Suppose an investor buys a hypothetical $1,000 face-value
    8-week Treasury bill for $992.50. If the investor holds the
    bill until maturity and receives $1,000, the gross difference is
    $7.50.

    WHAT THIS EXAMPLE SHOWS

    The investor does not receive $7.50 as a monthly payment. It represents the
    difference between the hypothetical purchase price and the maturity value.
    The actual auction price will determine the real return.

    This example also shows why comparing the purchase price with the maturity value
    is useful. Your actual result can differ because Treasury auction prices and
    yields change over time.

    Who Should Choose 8-Week T-Bills?

    An 8-week Treasury bill may fit investors who have money they
    expect to leave invested for about 56 days and who understand the bill’s
    maturity and pricing. The main consideration is whether the investment timeline
    matches when the cash may be needed.

    A Defined Cash Timeline

    It can be considered when funds have a known short-term purpose and the
    56-day maturity date fits that timeline.

    Short-Term Treasury Exposure

    It provides exposure to a short-term U.S. Treasury security rather than
    keeping the money in a deposit account.

    Investors Planning Ahead

    If the money is still available for investment after maturity, the proceeds
    can be used for another Treasury security or another financial goal.

    Investors Who May Need More Access

    If you may need the money before maturity, remember that selling the bill
    before maturity exposes you to its secondary-market price.

    The key check:
    Put the expected cash-need date next to the Treasury bill’s maturity date.
    If the dates do not work together, examine an option with different access
    or maturity terms before committing the money.

    8-Week Treasury Bills: Frequently Asked Questions

    1. What is an 8-week Treasury bill?

    An 8-week Treasury bill is a short-term U.S. Treasury security with a
    56-day term. Treasury auction documents identify the security as a
    “56-Day Bill” with an 8-week description.

    2. How do 8-week Treasury bills make money?

    Treasury bills are generally purchased below face value. If held to
    maturity, the difference between the purchase price and the amount
    received at maturity represents the gross interest.

    3. Do 8-week T-bills pay monthly interest?

    No. Treasury bills do not make periodic coupon payments. The return is
    generally reflected in the difference between the discounted purchase
    price and the maturity value.

    4. How much money do I need to buy an 8-week T-bill?

    Current Treasury auction offerings generally specify a minimum bid of
    $100 and multiples of $100. Always check the terms of the specific
    offering before placing an order.

    5. Can I sell an 8-week Treasury bill before maturity?

    Yes. Treasury bills can be sold in the secondary market before maturity,
    but the market price can be higher or lower than the price you paid.
    Selling early therefore creates market-price risk.

    6. Are 8-week Treasury bills taxable?

    Yes. Treasury bill interest is subject to federal income tax but is
    exempt from state and local income taxes. For most individual cash-method
    taxpayers, the IRS generally treats the bill’s interest as reportable
    when the bill is paid at maturity.

    7. What happens when an 8-week T-bill matures?

    At maturity, the Treasury pays the amount due under the security’s
    terms. You can then use the proceeds for your planned expense, keep
    the money elsewhere or consider another Treasury investment.

    8. Can I reinvest an 8-week Treasury bill?

    Yes. You can use the maturity proceeds to purchase another Treasury
    security. If you reinvest, remember that the next auction can have a
    different yield from the bill you just held.

    FAQ TAKEAWAY

    The basic cycle is simple: buy at the auction → hold for 56 days →
    receive the maturity amount → decide what to do with the proceeds.

    The details that deserve the most attention are the purchase price,
    maturity date, tax treatment and what happens if you need the money early.


    Final Verdict: Is an 8-Week Treasury Bill Right for Your Cash?

    An 8-week Treasury bill is a short-term U.S. Treasury security
    with a clearly defined 56-day maturity. It is generally purchased
    below face value, with the difference between the purchase price and maturity
    value representing the gross interest when held to maturity.

    The main question is whether that 56-day timeline matches your cash plans.
    If you expect to need the money around the maturity date, the fixed term gives
    you a specific point at which the investment ends. If you need unrestricted
    access before then, remember that selling a Treasury bill before maturity can
    expose you to changes in its market price.

    THE BOTTOM LINE

    Before buying, check the auction terms, purchase price, maturity date,
    tax treatment and your need for liquidity
    . If you plan to reinvest,
    remember that the next 8-week Treasury bill can have a different auction yield.

    For a broader look at Treasury securities and their different maturities,
    continue with our

    complete Treasury bills guide
    .

    Related Resources & Authority Sources

    If you want to go deeper after reading this guide, these resources cover
    Treasury bill mechanics, pricing, comparisons and tax rules. The internal
    guides help you explore related short-term investing topics, while the
    government sources provide primary information about Treasury securities
    and taxation.

    FinanceInvestment Guides

    Official Sources

    SOURCE CHECK

    Use TreasuryDirect for Treasury security terms and pricing information,
    and the IRS for federal tax rules. Auction results and Treasury rates can
    change, so check the latest official information before making an investment.

    FINANCEINVESTMENT

    Have a Money Question? Keep Exploring.

    Understanding an 8-week Treasury bill is easier when you look beyond the
    headline yield. Keep checking the maturity date, purchase price, tax impact
    and what you plan to do with the money after 56 days.

    📩 Get in Touch With FinanceInvestment

    Have a Treasury bill, savings or investing question you want us to cover?
    Send us a message.


    Email FinanceInvestment

  • 4-Week Treasury Bills Explained: Complete 2026 Guide

    4-Week Treasury Bills Explained: Complete 2026 Guide

    4-Week Treasury Bills Explained: A Complete Beginner Guide for 2026

    Subhash Rukade
    Founder, FinanceInvestment


    TREASURY GUIDE


    BEGINNER GUIDE

    Last Updated
    September 16, 2026
    Reading Time
    About 14 minutes

    START HERE

    4-Week Treasury Bills Explained: Why This Short Maturity Matters

    4-Week Treasury BillsA 4-week Treasury bill may look simple: you buy a short-term U.S. government security and receive its value at maturity. But the way you earn money is different from a savings account or a certificate of deposit. The bill is generally purchased at a price below its face value, and the difference represents the interest you earn.

    That short 28-day maturity is the part worth paying attention to. It can make a 4-week T-bill useful for money that has a known near-term purpose, while also giving investors a chance to reinvest after maturity. If you’re new to Treasury securities, start with our

    Treasury Bills Explained guide

    before going deeper.

    What You’ll Learn

    01 — How It Works
    See how the auction, purchase price and 28-day maturity fit together.
    02 — What You Earn
    Learn why a T-bill’s return is tied to its purchase price and face value.
    03 — Taxes & Risks
    Understand federal taxes, state and local tax treatment, and early-sale considerations.
    04 — Buying & Reinvesting
    See where you can buy a 4-week bill and what happens when it matures.
    QUICK ANSWER

    How Do 4-Week Treasury Bills Work?

    A 4-week Treasury bill is a short-term U.S. government security that matures in 28 days. Instead of paying a regular coupon, it is generally bought for less than its face value and redeemed at face value when it matures. The difference between the purchase price and the amount received at maturity represents the bill’s interest.

    Key Takeaways

    28-Day Maturity
    The standard 4-week bill matures after 28 days.
    No Regular Coupon
    Your return generally comes from the difference between the purchase price and face value.
    Short Holding Period
    The short maturity can suit money with a near-term purpose.
    Taxes Matter
    Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.
    Reinvestment Is a Choice
    After maturity, you can use the proceeds or consider buying another bill.
    Rates Can Change
    A future 4-week bill may have a different yield, so today’s return should not be assumed for every rollover.

    Bottom line:
    A 4-week Treasury bill is built around a short 28-day maturity. The key is to look beyond the quoted rate and understand the purchase price, maturity value, taxes and what you plan to do with the money afterward.

    4-Week Treasury Bills at a Glance

    Maturity
    28 days
    Minimum
    $100
    Interest Style
    Discount to face value
    Typical Use
    Short-term cash goals
    Quick FactWhat It Means
    4-week termThe bill is scheduled to mature 28 days after its issue date.
    No periodic couponYou do not receive monthly or quarterly interest payments.
    Maturity valueAt maturity, the Treasury pays the bill’s face value under its terms.
    ReinvestmentAfter maturity, you can use the proceeds or buy another Treasury security.

    QUICK TAKE:
    The defining feature of a 4-week Treasury bill is its short 28-day maturity. Its return comes from the relationship between the purchase price and face value, rather than from a regular coupon payment. That makes the timing of your cash need just as important as the quoted yield.

    4-Week Treasury Bills: A Complete Beginner Guide

    4-Week Treasury BillsIf you have never bought a Treasury bill, the first thing to understand is that a 4-week Treasury bill is a short-term U.S. government debt security. The Treasury issues it with a fixed maturity of 28 days. You are not opening a bank account or depositing money with the government. You are buying a marketable Treasury security.
    The way the return works is also different from a typical savings account. A 4-week T-bill is generally sold at a price below its face value. When it matures, the Treasury pays the face value. The gap between those amounts is the interest earned on the bill.

    What Does “4-Week” Actually Mean?

    The name refers to the bill’s term. A standard 4-week Treasury bill has a 28-day maturity. That short window can be useful when your goal is measured in weeks rather than years.

    For example, someone setting aside money for a known expense about a month away may care more about the maturity date than about receiving periodic income. The bill is designed around that short timeline.

    How the Money Moves

    STEP 1
    Buy the bill
    You purchase it through an available Treasury auction or brokerage platform.
    STEP 2
    Wait 28 days
    The security remains outstanding until its scheduled maturity date.
    STEP 3
    Receive face value
    At maturity, the Treasury pays the bill’s face value under its terms.

    One detail beginners often miss:
    the quoted T-bill discount rate is not the same thing as simply subtracting a percentage from the amount you invest. The purchase price, face value, term and quoted yield all work together to determine the actual return.

    How 4-Week Treasury Bills Work

    A 4-week Treasury bill starts with a U.S. Treasury auction. Investors can buy newly issued bills through TreasuryDirect or through a bank or brokerage that offers Treasury securities. The bill has a 28-day term, so the maturity date is known when the security is issued.

    Unlike a Treasury bond, a 4-week T-bill does not make scheduled interest payments during the holding period. Treasury bills are generally issued at a discount to face value. At maturity, the bill is redeemed at its face value under its terms. The difference between the purchase price and face value is the gross interest earned.

    The 4-Week T-Bill Process

    STEP 1


    Review the auction


    Check the available 4-week bill, auction schedule and purchase details.

    STEP 2


    Place your order


    Buy through TreasuryDirect or an eligible bank or brokerage account.

    STEP 3


    Hold for 28 days


    The bill remains outstanding until its scheduled maturity date.

    STEP 4


    Receive the maturity value


    At maturity, the Treasury pays the bill’s face value according to its terms.

    Simple Example: Where the Interest Comes From

    Imagine a 4-week Treasury bill with a $10,000 face value that you purchase for $9,950. If you hold the bill until maturity, you receive $10,000 according to its terms. The $50 difference represents the gross interest on that example.

    Keep this in mind:
    The $50 example is illustrative only. Actual purchase prices, discount rates and investment yields vary by auction and market conditions. The discount amount should not be confused with the quoted annualized yield.

    Benefits and Drawbacks of 4-Week Treasury Bills

    A 4-week Treasury bill can be useful for a specific type of cash: money you can leave untouched for a short period. But the short maturity also creates trade-offs. Here is what to consider before buying one.

    ✓ Benefits
    • Very short maturity:
      Your money is scheduled to reach maturity after 28 days.
    • U.S. government security:
      A Treasury bill is a direct obligation of the U.S. government, rather than a bank deposit.
    • No periodic coupon:
      You do not have to wait for monthly or quarterly interest payments.
    • Tax advantage at the state level:
      Treasury interest is generally exempt from state and local income taxes, although federal income tax generally applies.
    ✕ Drawbacks
    • No regular income stream:
      The return is built into the purchase price rather than paid as a recurring coupon.
    • Reinvestment risk:
      After 28 days, a new bill may offer a different yield.
    • Cash is committed until maturity:
      If you need the money sooner, selling before maturity may expose you to a different market price.
    • Inflation can reduce real value:
      Even when you earn interest, rising prices can reduce what that money can buy.

    The key trade-off:
    A 4-week T-bill gives you a short, defined maturity, but that also means you must decide what to do with the money again relatively soon. For a longer goal, repeatedly reinvesting may produce a different result as future Treasury yields change.

    4-Week T-Bills vs Other Short-Term Options

    A 4-week Treasury bill is only one way to hold money for a short period. A money market account, high-yield savings account, CD, or another Treasury bill can work differently. The right comparison depends on when you need the money, how much access you want, and how the return is structured.

    OptionTypical StructureAccess to MoneyInsurance / Guarantee
    4-Week T-Bill28-day Treasury security; generally bought below face valuePrimarily at maturity; can be sold earlier in the secondary marketNot FDIC-insured; direct U.S. government obligation
    8-Week T-BillShort-term Treasury security with an 8-week maturityPrimarily at maturity; earlier sale is possible through the marketNot FDIC-insured; direct U.S. government obligation
    Money Market AccountBank deposit account that generally earns interestGenerally easier access than a fixed-maturity securityFDIC insurance may apply at an eligible insured bank, subject to limits
    High-Yield Savings AccountBank deposit account with a variable interest rateGenerally designed for easier withdrawalsFDIC insurance may apply at an eligible insured bank, subject to limits
    CDBank deposit held for a specified term, usually at a stated rateEarly withdrawal may involve account-specific restrictions or penaltiesFDIC insurance may apply at an eligible insured bank, subject to limits

    When the Timeline Matters Most

    If you have a known date for a future expense, the 28-day maturity of a 4-week T-bill gives you a defined schedule. A deposit account may offer easier access, while a longer Treasury bill or CD may extend the holding period.

    One Detail to Watch

    Treasury bills and deposit accounts quote returns differently. A T-bill’s annualized yield does not mean you earn that full percentage in 28 days. Compare the actual purchase price, maturity value, holding period, and access rules.

    Research tip:
    If you are comparing a Treasury bill with a money market account or CD, look beyond the headline rate. Your decision can change based on liquidity, maturity date, taxes, deposit insurance, and what you plan to do with the money afterward.

    Costs, Taxes, Risks & Expert Tips for 4-Week T-Bills

    A 4-week Treasury bill has a simple structure, but the details can affect your actual return. Look at the purchase price, maturity value, taxes, and what could happen if your plans change before the 28-day term ends.

    Costs

    TreasuryDirect charges no purchase fee or commission for buying marketable Treasury securities. You still pay the purchase price of the security. A brokerage may have its own pricing or charges.

    Taxes

    Treasury bill interest is subject to federal income tax but exempt from state and local income taxes. For a bill held to maturity, the difference between the purchase price and face value is generally treated as interest income.

    Risks to Know

    Reinvestment risk is important because the next 4-week bill may offer a different yield. Inflation can also reduce purchasing power. Selling before maturity exposes you to the current market price.

    Expert Tips Before You Buy

    • Check the maturity date before focusing on the quoted annualized yield.
    • Compare the purchase price with the maturity value to see the dollar amount you could earn.
    • If you may need the money early, understand that a sale before maturity occurs at the market price.
    • Before reinvesting, compare the new yield rather than assuming it will match your previous bill.

    Official sources:

    TreasuryDirect

    and

    IRS Publication 550

    provide additional information on Treasury purchases and tax treatment.

    Common 4-Week T-Bill Mistakes and a Simple Real-Life Example

    Most mistakes with 4-week Treasury bills are not complicated. They usually come from misunderstanding the quoted yield, maturity date, or what happens after the bill matures.

    Mistake #1: Treating the Annualized Yield as 28-Day Interest

    A quoted T-bill investment rate is annualized. You do not simply earn that percentage on your money in 28 days.

    Mistake #2: Ignoring the Maturity Date

    If the cash is needed for a bill, tuition payment, or other expense, check the actual maturity date rather than assuming the money will be available exactly four calendar weeks after purchase.

    Mistake #3: Forgetting the Next Step

    A maturing bill returns your money. If you want to keep the strategy going, you must decide whether to spend, hold, or reinvest the proceeds.

    Real-Life Example: A $10,000 4-Week T-Bill

    Suppose an investor buys a 4-week T-bill with a $10,000 face value for an illustrative purchase price of $9,950. If the investor holds it until maturity, the bill pays $10,000 according to its terms.

    The $50 difference represents the gross interest in this simplified example. The investor should then consider federal taxes and decide what to do with the $10,000 proceeds.

    Important:
    The $9,950 purchase price and $50 return above are purely illustrative. Actual auction prices and investment rates change. The quoted annualized rate should not be confused with the dollar return over one 28-day holding period.

    Who Should Choose 4-Week T-Bills?

    A 4-week Treasury bill can make sense when you have money that does not need to be spent immediately but may be needed within a fairly short period. The key question is not simply how much risk you can tolerate. It is whether the 28-day maturity fits your cash-flow plans.

    A 4-Week T-Bill May Fit If You:

    • Have a known short-term cash timeline.
    • Can leave the money invested until maturity.
    • Want direct exposure to a short-term U.S. Treasury security.
    • Are comfortable deciding what to do with the proceeds after 28 days.

    Another Option May Fit Better If You:

    • Need unrestricted access to the cash.
    • Want a longer or more predictable investment period.
    • Prefer keeping emergency money in a readily accessible deposit account.
    • Do not want to manage repeated maturity and reinvestment decisions.

    Bottom line:
    A 4-week T-bill is primarily a short-term cash-management choice. Match the maturity date with your actual cash need, then compare the available yield, taxes, liquidity and reinvestment options.

    8 Frequently Asked Questions About 4-Week Treasury Bills

    1. What is a 4-week Treasury bill?

    A 4-week Treasury bill is a short-term U.S. government debt security with a 28-day maturity. It is generally purchased below its face value and pays the face value at maturity.

    2. How do 4-week T-bills make money?

    The return generally comes from the difference between the purchase price and the bill’s face value at maturity. There is no regular monthly or quarterly coupon payment.

    3. How much does a 4-week T-bill cost?

    The purchase price depends on the auction result. Treasury bills are generally issued at a discount, so the amount paid can be less than the face value received at maturity.

    4. Are 4-week Treasury bills taxable?

    Yes. Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes. For a typical bill held to maturity, the discount is generally reported as interest income.

    5. Can I sell a 4-week T-bill before maturity?

    Treasury bills are marketable securities, so they can generally be sold before maturity through a broker or other available secondary-market channel. The market price may be different from your purchase price.

    6. Can I reinvest a 4-week T-bill after it matures?

    Yes. You can use the maturity proceeds to purchase another Treasury security. The new bill will have its own auction price and yield, so the future return can differ from the previous bill.

    7. Are 4-week T-bills FDIC insured?

    No. A Treasury bill is not a bank deposit, so it is not covered by FDIC deposit insurance. It is a direct debt obligation of the U.S. government.

    8. Is a 4-week T-bill right for emergency savings?

    It depends on how quickly you may need the money. An emergency fund generally needs convenient access, while a 4-week T-bill has a defined maturity and can involve market-price risk if sold before maturity.

    Quick reminder:
    The quoted T-bill yield is annualized. It should not be interpreted as the amount you will earn over only 28 days.


    Final Verdict: Are 4-Week Treasury Bills Worth Considering?

    A 4-week Treasury bill is a simple short-term Treasury security with a defined 28-day maturity. It generally earns money through the difference between its purchase price and face value at maturity rather than through regular interest payments. Current Treasury offering documents identify the 4-week bill as a 28-day security.

    The main question is what you need the money to do. If your cash can remain invested for the full term, the short maturity may fit a defined near-term cash plan. If you need frequent access, a deposit account may offer a different level of convenience.

    The Bottom Line

    Before buying, check the auction price, maturity date, federal tax treatment, liquidity needs and your reinvestment plan. A 4-week T-bill can be evaluated alongside savings accounts, money market accounts and CDs based on those factors—not simply by looking at the headline annualized yield.

    Treasury bills are direct U.S. government obligations, while bank savings products are deposits with different access and insurance rules. Treasury interest is subject to federal income tax but exempt from state and local income taxes.

    Related Resources & Authority Sources

    If you want to keep researching short-term Treasury investments, these FinanceInvestment guides can help you compare Treasury bills with other options and understand how the pieces fit together.

    Official Sources


    TreasuryDirect — Marketable Securities

    — official information on Treasury bills, notes and bonds.


    TreasuryDirect — Understanding Pricing

    — explains how Treasury bill pricing relates to face value.


    IRS Publication 550 — Investment Income and Expenses

    — covers federal taxation of Treasury bill interest.

    Have a Money Question? Keep Exploring.

    A 4-week Treasury bill is one part of short-term cash planning. If you are comparing Treasury bills with savings accounts, CDs, or money market options, keep researching the details that matter to your own timeline, access needs, taxes, and investment goals.

    📩 Get in Touch With FinanceInvestment

    Have a question, topic suggestion, or feedback about this guide?


    Email FinanceInvestment

  • What Are Treasury Bills? Complete Beginner Guide 2026

    What Are Treasury Bills? Complete Beginner Guide 2026

    What Are Treasury Bills? Complete Beginner Guide


    Subhash Rukade


    FINANCEINVESTMENT

    Founder, FinanceInvestment


    Updated September 16, 2026


    Reading Time: About 15 minutes


    TREASURY BILLS


    BEGINNER GUIDE


    U.S. Government Securities


    What Are Treasury Bills? A Simple Starting Point for Beginners

    what are Treasury billsTreasury bills, commonly called T-bills, are short-term debt securities issued by the U.S. government. Unlike Treasury notes and bonds, newly issued T-bills generally do not pay periodic coupon interest. Instead, they are typically sold for less than their face value and pay the face value at maturity when held to maturity.

    For example, you might pay less than $1,000 for a T-bill with a $1,000 face value. The difference between the purchase price and the amount received at maturity is the bill’s return. The annualized yield is a separate calculation, which is why the purchase discount should not simply be treated as the T-bill’s annual interest rate.

    How this guide fits with our main T-bill guide

    This article focuses on the basic question of
    what Treasury bills are.
    For the broader picture—including T-bill rates, taxes, buying options, risks and comparisons—see our

    complete Treasury Bills explained guide
    .

    The goal is simple: by the end of this guide, you should understand what a T-bill represents, why its purchase price is usually below face value, how its maturity affects the investment and how it differs from other Treasury securities. That foundation makes the later discussion about rates, taxes and buying options much easier to follow.

    What You’ll Learn

    What Treasury bills are and where they fit within the U.S. Treasury family.

    How face value, purchase price and maturity work together.

    Why T-bills are generally issued below face value instead of paying a regular coupon.

    The common T-bill maturity periods and how they can affect your timeline.

    How Treasury bills compare with savings accounts, CDs and other short-term choices.

    Treasury Bills: Quick Answer & Key Takeaways

    Quick Answer

    Treasury bills, or T-bills, are short-term U.S. government debt securities with maturities of one year or less. Newly issued T-bills are generally sold for less than their face value instead of making regular coupon payments. When a bill reaches maturity, it is redeemed for its face value. The difference between the purchase price and the amount received at maturity is the investor’s return before taxes.

    Key Takeaways

    • T-bills have short maturities, generally ranging from a few weeks to one year or less.
    • A newly issued T-bill is generally purchased below its face value and redeemed for face value at maturity.
    • T-bills generally do not make periodic coupon payments during their term.
    • The amount of the purchase discount is not automatically the same as the bill’s annualized yield.
    • T-bills can generally be purchased through TreasuryDirect and through participating banks or brokerage firms.
    • Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.

    Bottom Line

    The basic idea is straightforward: you generally pay less than the bill’s face value, hold it until maturity, and receive the face value. The details that deserve closer attention are the purchase price, yield, maturity date and tax treatment.

    Table of Contents

    Treasury Bills at a Glance: Quick Facts, Best For & Key Numbers

    Before getting into auctions, pricing and yield calculations, it helps to see the basic T-bill structure in one place. These details give you a quick sense of how Treasury bills are structured and where they may fit into a short-term investment plan.

    Quick FactWhat It Means
    Investment typeShort-term U.S. government debt security
    MaturityCommon terms include 4, 8, 13, 17, 26 and 52 weeks
    Purchase structureGenerally issued below face value and redeemed at face value at maturity
    Face-value incrementsGenerally $100 and multiples of $100
    Coupon paymentsNo regular coupon payments during the bill’s term
    Tax treatmentGenerally subject to federal income tax and exempt from state and local income taxes

    Who Are Treasury Bills Best For?

    T-bills may suit investors who have money set aside for a defined short-term goal and do not need it for everyday spending. They can also be useful for people who want short-term exposure to U.S. government debt and may value the state and local income-tax treatment.

    Look beyond the headline number

    The number you see quoted for a T-bill may represent a particular rate or yield measure, so it should not be confused with the dollar amount of the purchase discount. When comparing bills, consider the purchase price, annualized yield, maturity date and tax treatment together.

    Complete Beginner Guide: What Are Treasury Bills?

    what are Treasury billsTreasury bills, commonly called T-bills, are short-term debt securities issued by the U.S. Department of the Treasury. They mature in one year or less and are designed to provide a relatively short-term way to invest in a direct obligation of the federal government. Unlike Treasury notes and bonds, T-bills do not make regular coupon payments during their term.

    Instead, a newly issued T-bill is generally purchased for less than its face value. When the bill reaches maturity, the Treasury pays its face value. That difference between the purchase price and the amount received at maturity is the basic source of the investor’s return.

    A simple example

    Imagine a T-bill with a $1,000 face value. If its purchase price is $990, you pay $990 and receive $1,000 when the bill matures, assuming you hold it to maturity. The $10 difference is the basic return before taxes. The actual purchase price and annualized yield vary with the bill and the auction or market conditions at the time.

    How T-Bills Fit Into the Treasury Family

    T-bills are the shortest-term marketable Treasury securities. Treasury notes generally mature in more than one year and up to 10 years, while Treasury bonds generally have maturities longer than 10 years. Notes and bonds generally pay interest every six months; T-bills instead provide their return through the difference between the purchase price and the amount paid at maturity.

    If you are comparing T-bills with bank deposits, our guide to

    Treasury bills vs. CDs

    looks at the major differences. You can also return to our

    complete Treasury Bills explained guide

    for the broader topic.

    The beginner takeaway

    The basic idea is simple: you buy a short-term Treasury security, generally at a price below its face value, and receive the face value when it matures. The next piece is understanding how Treasury auctions determine the price, how the discount rate differs from the investment yield, and what happens when the bill matures.

    How Treasury Bills Work: Purchase Price, Discount, Yield, Auctions & Maturity

    The easiest way to understand how Treasury bills work is to follow the transaction from auction to maturity. A T-bill is generally issued at a price below its face value. You pay the purchase price upfront, and if you hold the bill until maturity, the U.S. Treasury pays the full face value. The difference between those amounts is the bill’s discount and forms the basic return before taxes.

    Purchase Price and Discount

    Treasury bill prices are quoted per $100 of face value. For example, an illustrative price of $98.50 per $100 would mean a $1,000 face-value bill costs $985. If held to maturity, the Treasury would pay $1,000. The $15 difference is the discount amount and represents the investor’s return before taxes.

    Discount Rate vs. Investment Rate

    These two figures describe the same T-bill from different perspectives. The discount rate is calculated using the bill’s face value and a 360-day basis. The investment rate is based on the purchase price and uses a 365-day basis, or 366 days when applicable. Because the investment rate is based on the amount actually invested, TreasuryDirect says it can be used to compare a T-bill’s return with other investments.

    How the Treasury Auction Works

    Newly issued T-bills are generally sold through Treasury auctions. Individual investors using TreasuryDirect normally submit noncompetitive bids, which means they agree to accept the auction’s resulting rate. Competitive bidders specify the rate they are willing to accept. Treasury first accepts noncompetitive bids and then awards competitive bids starting with the lowest accepted rate until the announced offering amount is filled.

    What Happens at Maturity?

    At maturity, the bill becomes due and the Treasury pays its face value. There is no separate periodic coupon payment during the term. If you decide to sell a T-bill before maturity through the secondary market, the price may be higher or lower than your original purchase price because market conditions can change.

    The key idea to remember

    A T-bill’s purchase price, discount rate and investment rate are connected, but they are not the same thing. Start with the amount you pay, compare it with the face value you receive at maturity, and then use the investment rate when comparing annualized returns with other investments.

    Treasury Bill Benefits & Drawbacks: Pros, Cons & Key Trade-Offs

    Quick Answer

    Treasury bills can be attractive for investors who want short-term exposure to U.S. government securities without committing money for several years. Their main advantages are short maturities, a straightforward discount-to-face-value structure and federal government backing. The trade-offs include no regular coupon payments, the possibility of a different rate when you reinvest after maturity, and potential price changes if you sell before maturity.

    Key Benefits of Treasury Bills

    • Short-term flexibility: T-bills have maturities of one year or less, with regular terms ranging from 4 to 52 weeks.
    • U.S. government obligation: T-bills are direct obligations of the U.S. government and are backed by its full faith and credit.
    • Simple structure: You generally buy a bill below face value and receive its face value when it matures.
    • State and local tax advantage: Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes.

    Key Drawbacks to Consider

    • No regular coupon payments: T-bills do not provide periodic interest checks during the term; the interest is paid when the bill matures.
    • Reinvestment risk: When a T-bill matures, the rate available on a new bill may be higher or lower than the rate on your original investment.
    • Early-sale price risk: If you sell before maturity, the market price can be different from your original purchase price.
    • Not a bank deposit: T-bills are Treasury securities, not FDIC-insured bank deposits, so they should be compared with the right type of alternative.

    Bottom Line

    T-bills can work well for money you expect to need within a relatively short period and for investors who value U.S. government securities and state and local tax exemption. Their biggest trade-offs are the lack of periodic cash payments, changing reinvestment rates and possible price fluctuations if you sell before maturity.

    Treasury Bills Comparison Table: T-Bills vs. Savings Accounts, HYSA, Money Market Accounts & CDs

    Quick Answer

    Treasury bills are different from savings accounts, high-yield savings accounts, money market accounts and CDs because a T-bill is a U.S. Treasury security rather than a bank deposit. Savings and money market accounts are built for easier access to cash, while CDs and T-bills are generally better suited to money you can leave invested for a defined period.

    OptionAccess to MoneyHow You EarnProtection
    T-BillsReceive face value at maturity; can generally be sold before maturity through the secondary marketGenerally bought below face valueDirect U.S. government obligation; not FDIC-insured
    Savings AccountGenerally easy access, subject to account termsBank pays interestFDIC insurance may apply at an insured bank, subject to limits and rules
    High-Yield SavingsGenerally easy access, subject to account termsBank pays interestFDIC insurance may apply at an insured bank, subject to limits and rules
    Money Market AccountGenerally accessible, with features and restrictions varying by accountBank pays interestFDIC insurance may apply at an insured bank, subject to limits and rules
    CDUsually intended to remain invested until maturity; early withdrawal may involve a penaltyBank pays interest under the CD termsFDIC insurance may apply at an insured bank, subject to limits and rules

    Which Difference Matters Most?

    Start with the purpose of the money. A savings account or high-yield savings account can be more convenient when you need frequent access. A money market account may combine interest earnings with certain transaction features. A CD can lock in a rate for a chosen term, while a T-bill gives you a short-term Treasury security with a maturity date. T-bill interest also receives different state and local tax treatment from ordinary bank-deposit interest.

    For a closer look at one of these alternatives, compare

    Treasury bills vs. CDs

    or review our guides to

    money market accounts vs. Treasury bills
    .

    Bottom Line

    There is no single winner for every short-term cash need. T-bills offer Treasury exposure, while bank accounts emphasize accessibility and CDs emphasize a defined deposit term. Compare the expected return, access to your money, maturity, taxes and applicable insurance or government backing before choosing.

    Treasury Bill Costs, Taxes, Risks & Expert Tips

    Quick Answer

    Treasury bills generally have no TreasuryDirect purchase fee, although a broker or other financial institution may charge for its services. The bigger considerations are taxes, what happens if you sell before maturity, and the rate available when you reinvest after a bill matures. Those details can affect the return you actually keep and how well a T-bill fits your cash needs.

    Key Costs, Taxes & Risks to Know

    • Purchase costs: TreasuryDirect does not charge a fee to open an account or buy Treasury securities. Brokerage firms may charge fees or apply their own pricing.
    • Federal taxes: Interest from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes.
    • Early-sale risk: If you sell a T-bill before maturity, its market price may be higher or lower than your purchase price, which can change your actual gain or loss.
    • Reinvestment risk: When the bill matures, the rate available on a new T-bill may be different from the rate on your original investment.
    • Tax reporting: Treasury interest is generally reported on Form 1099-INT, with Treasury bills included in Box 3. Tax reporting can differ when a bill is sold before maturity.

    Expert Tip

    Match the T-bill’s maturity to the date you expect to need the money. Then compare the purchase price, investment rate, maturity date and tax treatment. If there is a reasonable chance you will need the money early, remember that selling before maturity exposes you to market-price changes.

    Bottom Line

    T-bill costs are not limited to the amount you pay at purchase. Taxes, possible selling costs, market prices before maturity and future reinvestment rates can all affect the outcome. For a short-term goal, choosing the right maturity and understanding the tax treatment may matter more than simply selecting the highest quoted rate.

    Common Treasury Bill Mistakes + Illustrative Example

    Quick Answer

    T-bill mistakes often happen when investors focus only on the quoted rate and overlook the purchase price, maturity date, tax treatment or what happens if they sell early. A T-bill is also not the same as a savings account or CD, so comparing the products requires more than looking at the headline yield.

    Key Takeaways

    • Don’t confuse rates: The discount rate and investment rate use different calculation methods and should not be treated as the same number.
    • Check the maturity date: A bill that matures later than your planned cash need may not fit your timeline.
    • Know the tax treatment: Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • Don’t assume early access is guaranteed at face value: Selling before maturity means accepting the market price available at that time.
    • Plan for reinvestment: The rate available when your T-bill matures may be different from the rate on your original bill.

    Illustrative Example

    Suppose an investor buys a T-bill with a $10,000 face value for an illustrative $9,850 and holds it until maturity. The investor would receive $10,000 at maturity, creating a $150 difference before taxes. This is only an example—the actual purchase price, discount and annualized investment rate depend on the specific bill and its auction or market conditions.

    Bottom Line

    The safest way to evaluate a T-bill is to look beyond the quoted rate. Check what you pay, when the bill matures, how the return is calculated and what happens if your plans change before maturity. Those details can prevent a simple short-term investment from becoming an unexpected cash-flow problem.

    Who Should Consider Treasury Bills? — Beginners, Retirees, Emergency Funds & Large Balances

    QUICK ANSWER

    Treasury bills may suit investors who have cash set aside for a specific short-term goal and know when they are likely to need it. They can be useful for beginners, retirees and people holding larger cash balances. The key is choosing a maturity that fits the timing of the goal.

    Key Takeaways

    • Beginners can use T-bills to learn how short-term U.S. government securities work.
    • Retirees may consider T-bills for cash that has a defined short-term purpose.
    • Investors with larger cash balances can spread maturities through a T-bill ladder.
    • Emergency funds should keep enough money readily accessible for unexpected expenses.
    • People seeking long-term growth generally need investments beyond short-term T-bills.
    • Before buying, check the maturity date and make sure the money can remain invested until then.

    BOTTOM LINE

    Treasury bills can be a practical choice for short-term cash when the maturity matches the investor’s timeline. They are not a substitute for money that must remain immediately accessible, and they are not designed to provide the long-term growth potential of stocks. Match the bill’s maturity to the job the cash needs to do.

    Treasury Bills FAQs: 8 Common Questions Beginners Ask

    QUICK ANSWER

    Treasury bills are short-term U.S. government securities with maturities of one year or less. They generally do not make periodic coupon payments. Instead, newly issued T-bills are typically sold at a discount or at par, and the investor receives the bill’s face value at maturity.

    Frequently Asked Questions

    1. What are Treasury bills?

    Treasury bills, or T-bills, are short-term debt securities issued by the U.S. Treasury. They have maturities of one year or less.

    2. Do Treasury bills pay monthly interest?

    No. T-bills generally do not pay periodic coupon interest. For a bill purchased below face value, the return generally comes from the difference between the purchase price and face value at maturity.

    3. What are the common Treasury bill maturities?

    Regular Treasury bill terms include 4, 6, 8, 13, 17, 26 and 52 weeks, although issuance can vary according to the Treasury’s schedule.

    4. Where can I buy Treasury bills?

    You can generally buy newly issued T-bills through TreasuryDirect or through participating banks and brokers. Brokerage fees and available services can vary.

    5. Are Treasury bills FDIC insured?

    No. T-bills are not bank deposits, so FDIC deposit insurance does not apply. They are obligations of the U.S. government.

    6. How are Treasury bills taxed?

    Interest from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes. Individual tax circumstances can affect the final after-tax result.

    7. Can I sell a Treasury bill before maturity?

    Yes. Marketable T-bills can generally be sold before maturity through a broker or applicable market channel. The market price at the time of sale may be above or below the purchase price.

    8. What happens when a Treasury bill matures?

    At maturity, the Treasury pays the bill’s face value. For a bill purchased at a discount, the difference between the purchase price and face value is generally the investor’s return before applicable taxes.

    BOTTOM LINE

    Treasury bill questions usually come down to the purchase price, maturity, return calculation, access before maturity and taxes. Once those pieces are clear, it becomes easier to judge whether a T-bill fits a particular short-term cash goal.

    Treasury Bills Final Verdict: Are T-Bills Right for You?

    QUICK ANSWER

    Treasury bills can be a useful choice for short-term money when you know roughly when you will need the cash. Their simple structure, short maturities and U.S. government backing make them worth considering, but they are not designed to replace an accessible emergency reserve or long-term growth investments.

    Key Takeaways

    • T-bills are short-term U.S. government debt securities with maturities of one year or less.
    • Newly issued T-bills are generally purchased at a discount or at par and redeemed at face value at maturity.
    • They can work well for defined short-term cash goals and investors who can match the maturity to their timeline.
    • T-bills are not FDIC-insured bank deposits, and selling before maturity exposes the investment to market-price changes.
    • Interest is generally subject to federal income tax but exempt from state and local income taxes.
    • For long-term wealth building, T-bills are usually better viewed as one part of a broader investment strategy rather than the entire portfolio.

    BOTTOM LINE

    Treasury bills make the most sense when safety of the U.S. government obligation, a short time horizon and a known maturity fit your goal. Before buying, compare the purchase price, investment rate, maturity date and tax treatment. If you need the money immediately or are investing for decades, another option may be a better fit.

    Treasury Bills Resources: Related Guides & Official Sources

    QUICK ANSWER

    The best next step is to use a mix of practical investing guides and official sources. FinanceInvestment can help you compare T-bills with other short-term choices, while TreasuryDirect, the IRS and Investor.gov provide primary information about Treasury securities, taxes and investing basics.

    Key Resources

    BOTTOM LINE

    Use the related FinanceInvestment guides for comparisons and practical explanations, then verify current Treasury and tax details with official government sources. That combination gives you both context and authoritative information before making a T-bill decision.

    Have a Money Question? Keep Exploring.

    Understanding Treasury bills is a good starting point. From here, compare T-bills with other short-term choices and consider how each option fits your cash needs, timeline and overall investment plan.

    📩 Get in Touch With FinanceInvestment

    Have a finance question or a topic you would like us to cover? Send us a message.


    Email FinanceInvestment