Author: subhashr325

  • Treasury Bill Rate Forecast 2026: What Investors Should Know

    Treasury Bill Rate Forecast 2026: What Investors Should Know

    Treasury Bill Rate Forecast 2026

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 19, 2026


    Reading Time: ~12 minutes

    Treasury Bill Rate Forecast 2026: What Could Happen Next?
    Treasury Bill Rate Forecast 2026The Treasury Bill Rate Forecast 2026 can help investors plan for short-term cash, but no single forecast can tell you the exact rate every T-bill will carry. Treasury bill rates can change as interest-rate expectations, inflation, economic conditions, Treasury borrowing needs, and investor demand shift.

    The Federal Reserve’s policy outlook is an important part of the picture, but the Fed does not set the auction rate for each Treasury bill. Treasury determines the applicable rate through its auction process, and different maturities can produce different results.

    This guide focuses on the signals that may shape short-term Treasury rates during 2026. We will also look at 13-week, 26-week, and 52-week bills so you can connect the rate outlook with your investment timeline instead of relying on one headline number.

    If you are new to Treasury securities, start with our

    Treasury Bills Explained

    guide. Then use this forecast to understand the factors behind future T-bill rates and auction results.

    What You’ll Learn

    • What could influence Treasury bill rates during 2026
    • How Federal Reserve policy and inflation can affect short-term yields
    • What to watch across 13-week, 26-week, and 52-week bills
    • Why Treasury auctions matter when checking actual T-bill rates
    • How to use rate scenarios when planning a short-term investment

    Quick Answer: Treasury Bill Rate Forecast 2026

    There is no single Treasury bill rate forecast for all of 2026 because T-bill rates can change with Federal Reserve policy, inflation, economic conditions, market expectations, and Treasury auction demand. The Federal Reserve’s September 2026 projections show a 4.1% median federal funds rate for year-end 2026. That is a monetary-policy projection, not a direct forecast for Treasury bills. The actual rate for a T-bill is established through its Treasury auction and can vary by maturity.

    Key Takeaways

    • T-bill rates can change as expectations for short-term interest rates shift.
    • Inflation and economic data can influence expectations for future Fed policy.
    • Treasury auctions determine the rate for a specific T-bill issue.
    • Different maturities can carry different auction rates.
    • Recent auction results are more useful for a purchase decision than an older forecast.
    • A forecast is a planning tool and should not be treated as a guaranteed future rate.

    BOTTOM LINE:


    The most useful approach is to watch the factors behind short-term rates and then check the latest Treasury auction results. Your maturity choice and cash timeline matter just as much as the rate outlook.

    2026 Treasury Bill Rate Forecast at a Glance

    The 2026 outlook for Treasury bill rates depends on several moving parts, including Federal Reserve policy, inflation, economic conditions, market expectations, and demand at Treasury auctions. The Federal Reserve’s September 2026 projections show a 4.1% median federal funds rate for year-end 2026. That figure is useful policy context, but it is not a forecast for a specific Treasury bill.

    Quick Facts

    • Fed policy signal: The September 2026 median projection is 4.1% for the federal funds rate at year-end.
    • Inflation signal: The Fed’s median 2026 PCE inflation projection is 3.7%.
    • Actual T-bill rate: Set through the Treasury auction for each individual issue.
    • Maturity matters: 13-week, 26-week, and 52-week bills can carry different auction rates.

    What These Numbers Mean

    The Fed’s projections help investors understand the broader interest-rate environment. They do not tell you what a future 13-week or 26-week bill will yield. For that, recent Treasury auction results are more directly relevant. Changes in inflation, economic data, rate expectations, and investor demand can all affect the rates offered on new bills.

    FactorCurrent 2026 ReferenceWhy It Matters
    Fed Policy4.1% median year-end projectionShapes expectations for short-term interest rates
    Inflation3.7% median 2026 PCE projectionCan influence expectations for future Fed policy
    Treasury AuctionsChanges by issue and maturityDetermines the actual rate and price of a bill

    QUICK TAKE:


    Treat the Fed’s projections as background information, not as a promised T-bill yield. When you are ready to invest, the latest Treasury auction result, bill maturity, purchase price, and investment rate are more directly useful.

    What Drives Treasury Bill Rates?
    Treasury Bill Rate Forecast 2026Treasury bill rates are influenced by several forces at the same time. Federal Reserve policy matters, but so do inflation, economic data, expectations for future short-term rates, Treasury’s borrowing needs, and demand for individual auctions. Because these factors can change, the rate available on a new bill can move even when the Fed has not changed its policy rate.

    Federal Reserve Policy

    The Fed does not set the auction rate for Treasury bills. However, its policy decisions influence the broader short-term interest-rate environment. When investors expect short-term rates to stay higher, T-bill pricing can reflect those expectations. When expectations change, bill rates can adjust as well. On September 16, 2026, the Fed’s federal funds target range was 3.75% to 4.00%.

    Inflation and Economic Data

    Inflation is another important signal because it can influence expectations about future monetary policy. The Fed’s September 2026 projections put median 2026 PCE inflation at 3.7%. Employment, economic growth, and other incoming data can also change how investors view the path of short-term rates.

    Treasury Auctions and Market Demand

    The actual rate for a specific T-bill is established through the Treasury auction. Competitive bidders submit a discount rate, while noncompetitive bidders accept the auction result under the applicable rules. Treasury ranks accepted competitive bids from lower to higher discount rates until the offering is filled. The resulting auction price and discount rate determine the bill’s terms.

    WHAT TO WATCH:


    Follow Fed decisions, inflation reports, economic data, short-term rate expectations, and recent Treasury auction results. Together, these signals give a clearer picture than any single forecast number.

    How T-Bill Rate Forecasts Work

    A Treasury bill rate forecast is an estimate of where short-term Treasury rates could move. It is not a guaranteed future rate. Forecasts generally combine expectations about monetary policy, inflation, economic conditions, and short-term market rates. Since these factors can change, a forecast is better viewed as a possible path rather than a fixed target.

    From Economic Outlook to Rate Scenario

    Analysts first assess the broader short-term rate environment. They may consider the expected path of the federal funds rate along with inflation, employment, economic growth, and market-based rate expectations. These signals can point toward higher, lower, or relatively stable short-term Treasury rates.

    Why the Forecast Is Not the Final Rate

    A forecast does not determine what you will receive when buying a T-bill. Treasury establishes the terms for each issue through its auction process. The final auction result can differ from an earlier forecast, and different maturities can produce different rates. Recent auction results therefore provide a more direct reference when evaluating a specific purchase.

    FORECAST TIP:


    Use a forecast to understand possible changes in the short-term rate environment, not to lock in an expected T-bill return. Before investing, compare the outlook with the latest auction result, bill maturity, purchase price, and investment rate.

    Potential Benefits & Drawbacks of Treasury Bills

    Treasury bills can be useful for short-term cash goals, but they also have trade-offs. The right fit depends on when you need the money, how you view changing rates, and whether you plan to hold the bill until maturity.

    Potential Benefits

    • Short-term flexibility: Treasury bills are issued with several short maturities, giving investors options for matching a bill with a planned cash need.
    • U.S. government security: Treasury bills are backed by the full faith and credit of the U.S. government.
    • State and local tax advantage: T-bill income is generally subject to federal income tax but exempt from state and local income taxes.

    Potential Drawbacks

    • Future-rate uncertainty: A new T-bill may offer a different rate when your current bill matures.
    • Early-sale price risk: If you sell a bill before maturity through the secondary market, its market price can be higher or lower than your purchase price.
    • Limited long-term growth potential: T-bills are designed for short-term investing, so they may not provide the long-term growth potential investors seek from assets such as stocks.

    13-Week vs. 26-Week vs. 52-Week T-Bills

    Treasury bills with different maturities can serve different cash-planning needs. A 13-week bill reaches maturity sooner, while 26-week and 52-week bills keep the money invested for longer. Comparing them is not only about finding the highest rate. The maturity should also fit your expected cash needs.

    MaturityTime Until MaturityPlanning Consideration
    13-WeekAbout 3 monthsReaches maturity sooner, but may require earlier reinvestment
    26-WeekAbout 6 monthsKeeps funds invested for a longer period before maturity
    52-WeekAbout 1 yearProvides a longer maturity period and less frequent reinvestment

    Why Maturity Matters

    A shorter bill gives you a sooner maturity date, which can be useful when your cash need is relatively close. A longer bill keeps the investment in place for more time and can reduce the need to reinvest as frequently. However, committing money for longer can matter if your plans change before maturity.

    The available auction rate can also differ between maturities. For that reason, compare the rate, maturity date, and your own cash timeline together rather than choosing a bill based on the quoted rate alone.

    QUICK TAKE:


    A 13-week, 26-week, or 52-week T-bill should be evaluated against your expected cash need. The maturity date tells you when the investment is scheduled to return its face value, while the auction result determines the terms of that particular bill.

    Risks & Investor Tips for Treasury Bills

    Treasury bills are short-term U.S. government securities, but investors still need to plan around changing market prices, future rates, taxes, and access to cash. Understanding these points can help you use T-bills without treating a rate forecast as a guaranteed outcome.

    Risks to Keep in Mind

    • Early-sale price risk: If you sell a T-bill before maturity, its market price may be higher or lower than the amount you paid.
    • Reinvestment risk: When a bill matures, a new T-bill may be available at a different rate.
    • Cash-access risk: If you need the money before maturity, you may have to sell through the secondary market rather than simply withdrawing the investment.

    Practical Investor Tips

    • Review the maturity date before placing an order.
    • Check recent Treasury auction results when comparing available bills.
    • Consider the investment rate and purchase price, not just the quoted discount rate.
    • Keep emergency or near-term spending money separate from funds committed to a T-bill.

    INVESTOR TIP:


    Before buying, identify the date you expect to need the money. Then compare that timeline with the bill’s maturity and the latest available auction terms. This keeps the investment decision tied to your cash needs rather than a forecast alone.

    Common Mistakes & Real-Life Example

    T-bill investing can look simple, but a few planning mistakes can lead to an unexpected result. The biggest issue is often treating a rate forecast as if it were the actual rate available when the investment is made.

    Common Mistakes to Avoid

    • Depending on one forecast: Economic conditions and rate expectations can change, making earlier forecasts less relevant.
    • Overlooking the maturity date: The investment should fit when you expect to need the cash.
    • Looking at only one rate figure: The discount rate, purchase price, and investment rate provide different pieces of information.
    • Ignoring the maturity decision: You should know whether you plan to spend the proceeds or evaluate a new investment when the bill matures.

    A Simple Example

    Imagine an investor has $20,000 available for a short-term goal and expects to need the money several months from now. Instead of choosing a T-bill solely because a forecast suggests rates may remain attractive, the investor first identifies the approximate date the funds will be needed.

    The investor then reviews available Treasury bills and their auction terms before placing an order. Because T-bills are generally sold at a discount and redeemed at face value at maturity, the purchase price and maturity terms help determine the investment’s return. When the bill matures, the investor can use the proceeds or review current rates before deciding whether to reinvest.

    SMART MOVE:


    Treat the Treasury Bill Rate Forecast 2026 as planning information, not a promised return. Check the actual auction terms and make sure the maturity fits your cash goal before investing.

    Who Should Consider T-Bills?

    Treasury bills may be relevant for investors who have money available for a defined short-term period and want exposure to U.S. Treasury securities. Whether they fit depends on the investor’s cash needs, timeline, liquidity requirements, and broader financial plan.

    • Investors with short-term goals: T-bills can be considered when the investment period can be matched with a bill’s maturity.
    • Retirees managing near-term cash: A short-maturity Treasury bill may be considered as one component of planned cash needs.
    • Families planning known expenses: A Treasury bill’s maturity date can be compared with the timing of a future financial obligation.
    • Investors learning about Treasuries: T-bills provide an opportunity to understand Treasury auctions, discount pricing, investment rates, and maturity.

    FIT CHECK:


    Before investing, consider when you need the money, how much liquidity you require, the available auction terms, and how the T-bill fits with your overall financial plan.

    Frequently Asked Questions About Treasury Bill Rate Forecast 2026

    1. What is the Treasury Bill Rate Forecast 2026?

    It is an estimate of how short-term Treasury bill rates could change during 2026. Forecasts may consider monetary policy expectations, inflation, economic conditions, and short-term market rates. They are not guaranteed future auction rates.

    2. Does the Federal Reserve set T-bill rates?

    No. The Federal Reserve sets the federal funds target range. Treasury bills are sold through Treasury auctions, where the terms and auction results determine the rate and price for each issue. Fed policy can influence the broader short-term rate environment.

    3. Can T-bill rates change during 2026?

    Yes. Rates on newly issued bills can change as economic conditions, inflation expectations, monetary policy expectations, and market conditions change. A previous auction result does not guarantee the rate of a future issue.

    4. Are 13-week, 26-week, and 52-week T-bills different?

    Yes. They have different maturity periods, and their auction rates can differ. The maturity determines how long the bill remains outstanding before it reaches its scheduled maturity date.

    5. Do Treasury bills pay monthly interest?

    No. T-bills do not make periodic coupon payments. They are generally issued at a discount and redeemed at their par value at maturity. The difference between the purchase price and amount received at maturity generally represents interest income.

    6. Are Treasury bill earnings taxable?

    Treasury bill interest income is generally subject to federal income tax but exempt from state and local income taxes. Individual tax situations can vary, so investors should consider their own tax circumstances.

    7. Can I sell a T-bill before maturity?

    TreasuryDirect does not provide an early-redemption option for Treasury bills. An investor who wants to sell before maturity generally uses the secondary market through a bank or broker, where the market price can be different from the original purchase price.

    8. Should I rely on a forecast when buying a T-bill?

    A forecast can provide useful context, but it should not be treated as a guaranteed rate. Before investing, review the latest auction results, maturity date, purchase price, and investment rate for the specific bill.

    Final Takeaway: Treasury Bill Rate Forecast 2026

    The Treasury Bill Rate Forecast 2026 can help investors think about possible changes in short-term rates, but it cannot tell you the exact rate a future T-bill will offer. Forecasts can change as new economic information and market expectations develop.

    For an actual investment, the specific Treasury bill matters more than a broad forecast. Its auction result, maturity date, purchase price, discount rate, and investment rate provide the information needed to understand the terms of that issue.

    Your cash timeline should also remain part of the decision. A 13-week bill, for example, reaches maturity sooner than a 26-week or 52-week bill. That difference can affect when the money becomes available and when you may need to make another investment decision.

    FINAL THOUGHT:


    Use the forecast to understand the broader rate outlook, then evaluate the actual Treasury auction terms for the bill you are considering. Keeping the forecast, maturity, and cash requirement separate can make the analysis much clearer.

    T-bill rates may change over the course of 2026, so investors should revisit the available auction information when they are ready to invest rather than relying on an older forecast alone.
    Have a Money Question? Keep Exploring.

    Questions about Treasury bills, interest rates, or your next financial research topic? Explore more FinanceInvestment guides or get in touch with us.

    📩 Get in Touch With FinanceInvestment


    Email FinanceInvestment

    Continue Your Research
  • Treasury Bill Yield vs Interest Rate: What’s the Difference?

    Treasury Bill Yield vs Interest Rate: What’s the Difference?

    Treasury Bill Yield vs Interest Rate

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 19, 2026


    Reading Time: ~12 minutes

    Treasury Bill Yield vs Interest Rate: What’s the Difference?

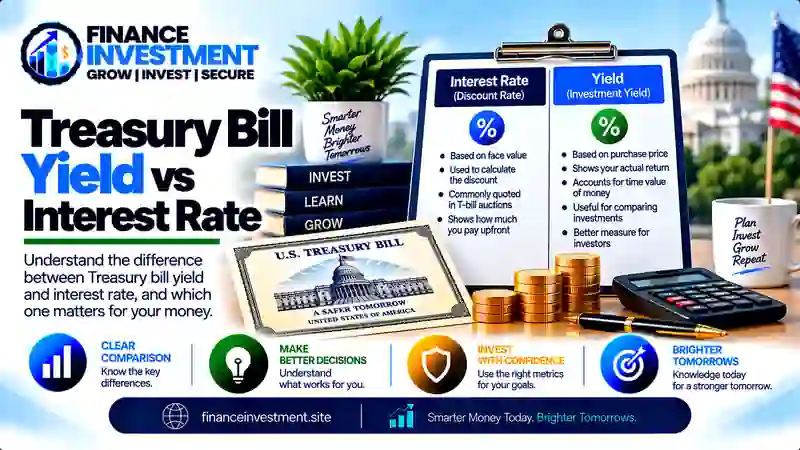
    Treasury Bill Yield vs Interest RateTreasury Bill Yield vs Interest Rate can be confusing because Treasury bills work differently from Treasury notes and bonds. A T-bill does not make periodic coupon payments. Instead, it is generally sold below its face value and pays its face value at maturity.

    That is why Treasury bill results can show several related numbers, including the discount rate, purchase price, and investment rate. They describe the same investment from different angles, but they are calculated differently.

    The difference matters when you compare T-bills with other short-term investments. A discount rate is based on the bill’s face value, while the investment rate is based on the price you actually pay. TreasuryDirect notes that the investment rate is the more useful measure for comparing a T-bill’s return with other investments.

    If you are new to Treasury securities, our

    Treasury Bills Explained

    guide covers the basics. Here, we will focus on the numbers behind a T-bill’s return and show why yield, rate, and price should not be treated as the same thing.

    What You’ll Learn

    • What Treasury bill yield means
    • How the discount rate differs from the investment rate
    • Why the purchase price changes the way a T-bill return is expressed
    • How yield and rate appear in Treasury auction results
    • Which numbers to compare when evaluating T-bills
    • Common mistakes investors make when comparing T-bill rates

    Quick Answer: Treasury Bill Yield vs Interest Rate

    For Treasury bills, the terms yield and interest rate need some context. Treasury’s current glossary uses “Interest Rate” for notes, bonds, and TIPS, while Treasury bills use a discount rate and an investment rate/yield. The discount rate is based on the bill’s face value and a 360-day convention. The investment rate is an annualized simple rate based on the purchase price and a 365-day year, or 366 days in a leap year.

    Key Takeaways

    • Treasury bills do not make periodic coupon payments like Treasury notes or bonds.
    • A T-bill is generally sold at a discount to its face value and pays the face value at maturity.
    • The discount rate is calculated using the bill’s face value and a 360-day basis.
    • The investment rate/yield uses the purchase price to express an annualized return.
    • These different calculation methods can produce different percentages for the same T-bill.
    • The purchase price, maturity date, and rate should be considered together when comparing T-bills.
    • The investment rate/yield can make a T-bill easier to compare with other short-term investments.

    BOTTOM LINE:


    A T-bill’s discount rate and investment rate/yield are not interchangeable numbers. Once you understand what each calculation measures, Treasury bill pricing and auction results become much easier to compare.

    Treasury Bill Yield vs Interest Rate: At a Glance

    Treasury bills are priced differently from coupon-paying Treasury securities. A T-bill is generally sold below its face value and pays its face value at maturity. Because of that structure, Treasury uses more than one rate measure to describe the bill’s return.

    Quick Facts

    • Security: Short-term U.S. Treasury security
    • Pricing: Generally purchased below face value
    • Return: The difference between the purchase price and face value at maturity
    • Discount rate: Based on the bill’s par value using a 360-day convention
    • Investment rate: Based on the purchase price using a 365-day basis, or 366 days when applicable

    Best For

    This distinction is especially useful when comparing a Treasury bill with another short-term investment. The discount rate describes the bill using its par value, while the investment rate uses the purchase price. TreasuryDirect identifies the investment rate as the measure that can be used to compare bill yields with other investments.

    MeasureWhat It UsesWhy It Matters
    Discount RatePar value and a 360-day basisHelps determine the T-bill’s purchase price
    Investment Rate / YieldPurchase price and a 365/366-day basisExpresses the bill’s annualized return for comparison
    Purchase PriceThe price paid for the billShows the actual amount invested relative to face value

    QUICK TAKE:


    The discount rate and investment rate are different ways of expressing a T-bill’s economics. When comparing its return with another short-term investment, pay attention to the purchase price and investment rate rather than relying on the discount rate alone.

    Complete Beginner Guide to Treasury Bill Yield vs Interest Rate

    Treasury Bill Yield vs Interest RateIf you are new to Treasury bills, the first thing to understand is that a T-bill does not work like a savings account or a coupon-paying Treasury note. It is generally purchased for less than its face value and pays its face value when it reaches maturity.
    Start With the Purchase Price

    Suppose a Treasury bill has a $10,000 face value and a purchase price of $9,800. You pay $9,800 when you buy the bill. If you hold it until maturity, the Treasury pays the $10,000 face value. The $200 difference is the gross return from the price difference, before applicable taxes or costs.

    This is the key to understanding T-bill returns. You do not receive separate monthly or quarterly coupon payments. Instead, the return is built into the difference between the amount you pay and the amount paid at maturity.

    Understand the Discount Rate

    The discount rate measures the discount using the bill’s par value and a 360-day convention. It is an important part of Treasury bill pricing, but it is not based on the actual amount you pay.

    Then Look at the Investment Rate

    The investment rate is based on the bill’s purchase price. Treasury calculates it using a 365-day basis, or 366 days when applicable. Because it uses the amount actually paid for the security, Treasury says the investment rate can be used to compare a T-bill’s return with other investments.

    For a broader introduction, see our

    guide to how Treasury bills work
    .
    Once the basic structure is clear, comparing a T-bill’s discount rate with its investment rate becomes much easier.

    BEGINNER TIP:


    When comparing T-bills, don’t rely on the discount rate alone. Check the purchase price and investment rate as well. Those numbers show how the quoted rate connects to the return on the money you actually invest.

    How Treasury Bill Yield and Interest Rate Work

    Understanding a Treasury bill yield becomes easier when you follow the process from the auction to the final maturity payment. Unlike coupon-paying Treasury securities, a T-bill generally earns its return through the difference between its purchase price and face value.

    Step 1: Investors Bid at the Auction

    Treasury bills are sold through auctions. Competitive bidders submit the discount rate they are willing to accept. Treasury evaluates those bids and accepts them from the lowest rate upward until there are enough bids to cover the offering amount.

    A noncompetitive bidder does not specify a discount rate. Instead, the bidder agrees to accept the rate determined by the auction, subject to the applicable auction rules.

    Step 2: The Discount Rate Connects to the Price

    Once the auction determines the applicable rate, Treasury calculates the bill’s purchase price. The discount rate is based on the bill’s par value and the actual number of days until maturity, using a 360-day basis.

    For the same face value and maturity:


    A higher discount rate generally means a lower purchase price and a larger discount from face value.

    Step 3: The Investment Rate Shows the Return Differently

    Treasury also reports an investment rate, sometimes described as an equivalent coupon yield. Unlike the discount rate, it is based on the bill’s purchase price. Treasury calculates it using a 365-day basis, or 366 days when applicable.

    This difference is important when comparing a T-bill with another short-term investment. TreasuryDirect specifically states that the discount rate should not be used for that comparison, while the investment rate can be used to compare bill yields with other investments.

    Why “Interest Rate” Can Be Confusing

    The phrase T-bill interest rate is common in everyday investing conversations, but Treasury uses more specific terminology. Its rules define an “interest rate” for notes and bonds, while Treasury bills are quoted using a discount rate and an investment rate.

    So, when you see a Treasury bill auction result, look at the discount rate, purchase price, and investment rate together. Each number answers a different question about the same security.

    Treasury Bill Yield vs Interest Rate: Benefits & Drawbacks

    Knowing how a T-bill’s yield and rate are calculated is only part of the picture. You also need to consider how the security fits your cash needs, taxes, and investment time frame.

    Benefits

    • U.S. government obligation: Treasury bills are direct obligations of the U.S. government.
    • Short-term structure: Regular Treasury bills have maturities of one year or less, making them suitable for investors managing short-term funds.
    • Return paid at maturity: Instead of receiving periodic coupon payments, the investor generally receives the bill’s face value at maturity. The difference between the purchase price and face value represents the bill’s interest.
    • State and local tax exemption: Treasury interest is subject to federal income tax but is exempt from state and local income taxes.

    Drawbacks

    • Inflation can reduce purchasing power: A positive T-bill return does not necessarily mean your money gained purchasing power after inflation.
    • Early-sale price can change: If you sell a T-bill before maturity, its market price may be higher or lower than the amount you originally paid.
    • No periodic income: Investors seeking regular monthly or quarterly interest payments will not receive them from a T-bill.

    QUICK TAKE:


    A Treasury bill can offer a straightforward short-term structure, but the quoted yield is not the only factor to consider. Look at taxes, inflation, your cash needs, and whether you plan to hold the bill until maturity.

    Treasury Bill Yield vs Interest Rate Comparison

    A Treasury bill’s discount rate and investment rate describe the same security from different calculation perspectives. The discount rate uses the bill’s par value, while the investment rate is based on the purchase price.

    MeasureCalculation BasisMain Use
    Discount RatePar value, actual days to maturity, and a 360-day basisUsed to quote the bill and calculate its purchase price
    Investment Rate / YieldPurchase price and a 365/366-day basisUsed to compare the bill’s return with other investments
    Purchase PriceAmount paid for the billShows the actual amount invested

    Which Number Should You Compare?

    If you are comparing a T-bill with a savings account, CD, money market investment, or another short-term investment, focus on the investment rate. TreasuryDirect specifically states that the discount rate should not be used to compare a bill’s rate of return with other instruments, while the investment rate can be used for that comparison.

    The investment rate is still an annualized measure. Your actual dollar return depends on factors such as the amount invested, purchase price, and time until maturity. Tax treatment can also affect how much of the return you ultimately keep.

    QUICK TAKE:


    Don’t treat the discount rate and investment rate as interchangeable. The discount rate helps describe T-bill pricing, while the investment rate is the more appropriate Treasury measure for comparing the bill’s return with other investments.

    Treasury Bill Costs, Risks & Expert Tips

    A Treasury bill can have a relatively simple return structure, but the quoted yield is not the only number that matters. Your purchase method, holding period, taxes, and plans for the money can all affect the result.

    Costs to Watch

    • Broker transaction costs: If you buy or sell a T-bill through a broker, check whether commissions, markups, or markdowns apply to the transaction.
    • Taxes: Bill interest is subject to federal income tax but is exempt from state and local income taxes.

    Risks to Understand

    • Early-sale risk: If you sell before maturity, the market price may be different from the amount you originally paid. A broker transaction can also affect your net proceeds.
    • Inflation risk: Inflation can reduce the purchasing power of your T-bill return.
    • Reinvestment risk: When a T-bill matures, the rate available on a new bill may be higher or lower than the rate on your original investment.

    EXPERT TIP:


    Before buying, check the investment rate, purchase price, maturity date, and tax treatment. If you might need the money early, understand how your bank or broker handles secondary-market sales and what transaction costs may apply.

    Common Treasury Bill Yield Mistakes & Real-Life Example

    T-bill comparisons can become confusing when investors treat the quoted discount rate as if it were the same as the investment return. The calculation basis matters.

    Common Mistakes

    • Comparing the discount rate directly with a CD or savings yield:
      The T-bill discount rate uses par value and a 360-day convention, so it is not the appropriate measure for comparing returns with other investments.
    • Ignoring the purchase price:
      The amount paid for the bill is an important part of calculating its investment rate and understanding the actual dollar return.
    • Expecting periodic interest payments:
      A T-bill does not make regular coupon payments during its term. Its interest is generally reflected in the difference between the purchase price and face value.
    • Forgetting the maturity period:
      An annualized investment rate helps with comparisons, but your actual dollar result depends on the amount invested and the time until maturity.

    Real-Life Example

    Suppose an investor buys a hypothetical $10,000 face-value T-bill for $9,800 and holds it until maturity. The investor pays $9,800 upfront and receives $10,000 at maturity. The gross difference between the purchase price and face value is $200.

    That $200 should not be confused with the T-bill’s quoted discount rate. The discount rate and investment rate use different calculation bases. The investment rate uses the purchase price and annualizes the bill’s return, making it the more appropriate Treasury measure when comparing the bill with another investment.

    REAL-WORLD LESSON:


    When evaluating a T-bill, look beyond the headline percentage. Check the purchase price, face value, maturity period, and investment rate before comparing it with another short-term investment.

    Who Should Consider Treasury Bills?

    Treasury bills may be worth considering for investors who have a short-term cash goal and want exposure to a U.S. government security. Treasury bills mature in a few days to 52 weeks, so the maturity date can be matched with a specific cash need.

    T-Bills May Fit Investors Who:

    • Have money they expect to use within a relatively short time frame.
    • Prefer a Treasury security backed by the U.S. government’s full faith and credit.
    • Are comfortable receiving the bill’s face value at maturity instead of periodic coupon payments.
    • Want to compare a T-bill’s return with other short-term investments using its investment rate.

    A T-bill may be less suitable for someone who needs regular income payments or may need to sell before maturity. An early sale can result in a market price that differs from the original purchase price.

    THINK ABOUT YOUR TIMELINE:


    Before comparing Treasury bill yields, consider when you need the money, whether you can hold the bill to maturity, and how its return compares with your other short-term options.

    Frequently Asked Questions About Treasury Bill Yield vs Interest Rate

    Is Treasury bill yield the same as the interest rate?

    Not exactly. For Treasury bills, Treasury reports a discount rate and an investment rate, also described as an equivalent coupon yield. The discount rate is based on par value, while the investment rate is based on the bill’s purchase price.

    Why is a T-bill sold at a discount?

    A T-bill is generally issued for less than its face value. At maturity, Treasury pays the face value. The difference between the purchase price and face value represents the bill’s interest.

    Which rate should I use to compare a T-bill with a CD?

    The investment rate is the appropriate Treasury measure for comparing a bill’s return with other investments. TreasuryDirect specifically states that the discount rate should not be used for that comparison.

    Does a Treasury bill pay monthly interest?

    No. T-bills do not make periodic coupon payments. Instead, the investor generally pays a discounted purchase price and receives the bill’s face value at maturity. The difference represents the interest.

    Is Treasury bill interest taxable?

    Yes. Treasury bill interest is subject to federal income tax. Treasury interest is generally exempt from state and local income taxes.

    Can I sell a T-bill before maturity?

    Yes. A Treasury bill can generally be sold before maturity through a bank, broker, or dealer in the secondary market. The market price at the time of sale may be different from your original purchase price, so the amount you receive can vary.

    Why can the Treasury bill yield and discount rate be different?

    They use different calculation bases. The discount rate uses par value and a 360-day convention. The investment rate uses the purchase price and an annualized 365-day basis, or 366 days when applicable. As a result, the two percentages can differ for the same bill.

    FAQ SUMMARY:


    When reading a Treasury bill quote, identify whether the percentage is the discount rate or investment rate. The distinction matters because each measure uses a different calculation basis and serves a different purpose.

    Final Takeaway: Treasury Bill Yield vs Interest Rate

    The key to understanding a Treasury Bill Yield vs Interest Rate is recognizing that Treasury bills use different rate measures for different purposes. The discount rate is based on the bill’s par value and uses a 360-day convention, while the investment rate is based on the purchase price and uses a 365-day basis, or 366 days when applicable.

    The discount rate helps determine the price of a T-bill. The investment rate, also called the equivalent coupon yield, expresses the bill’s annualized return using its purchase price. TreasuryDirect says this investment rate can be used when comparing a bill’s yield with other investments.

    When reviewing a T-bill, therefore, consider the purchase price, face value, maturity date, discount rate, and investment rate together. Looking at these figures as a group gives you a clearer understanding of how the quoted rate connects with the actual investment.

    FINAL TAKEAWAY:


    The discount rate and investment rate are not interchangeable. If you are comparing a T-bill’s return with another investment, use the investment rate for that comparison rather than treating the discount rate as an equivalent yield.

    Have a Money Question? Keep Exploring.

    Treasury bill rates can look confusing at first. Once you understand the difference between the discount rate, purchase price, and investment rate, auction results become easier to read and compare.

    📩 Get in Touch With FinanceInvestment
    Have a finance question or a topic you’d like us to cover?


    Email FinanceInvestment

  • How Treasury Bill Rates Are Determined: A 2026 Guide

    How Treasury Bill Rates Are Determined: A 2026 Guide

    How Treasury Bill Rates Are Determined

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 18, 2026


    Reading Time: ~11 minutes

    How Treasury Bill Rates Are Determined

    How Treasury Bill Rates Are DeterminedHow Treasury Bill Rates Are Determined starts with a simple question: who sets the rate you see on a T-bill? The answer lies in the U.S. Treasury auction process, where investors submit bids that help establish the price and rate for a particular Treasury bill.

    The process can seem complicated at first. A Treasury bill can involve a discount rate, purchase price, and investment rate, while different maturities can produce different auction results. The important part is understanding how bids are evaluated and how the accepted rate is used to determine the bill’s price.

    In this guide, we will follow that process from the first bid through the final auction result. We will also connect the auction mechanics to the numbers you see when researching T-bills, without relying on a current rate that could quickly change. Treasury bills are generally sold at a discount to face value and redeemed at face value at maturity.

    If you are new to Treasury securities, start with our

    Treasury Bills Explained

    guide for the broader basics. This article focuses specifically on how Treasury bill rates are determined.

    What You’ll Learn

    • How Treasury bill auctions work
    • The difference between competitive and noncompetitive bids
    • How Treasury determines the accepted auction rate
    • How the auction rate affects a T-bill’s purchase price
    • Why rates can differ between Treasury bill maturities
    • How to read a Treasury bill auction result

    Quick Answer: How Are Treasury Bill Rates Determined?

    Treasury bill rates are determined through U.S. Treasury auctions. For a Treasury bill, competitive bidders submit a discount rate they are willing to accept. Treasury accepts eligible bids according to the auction rules, starting with the lowest discount rates and moving upward until the offering is allocated. The highest accepted competitive discount rate becomes the auction’s high rate, which is used in determining the bill’s price.

    Key Takeaways

    • Treasury bills are issued through scheduled Treasury auctions.
    • Competitive bidders specify the discount rate they are willing to accept.
    • Noncompetitive bidders agree to accept the rate determined by the auction.
    • Competitive bids are evaluated from the lowest discount rate upward.
    • The highest accepted competitive discount rate becomes the auction’s high rate.
    • The auction result helps determine the price investors pay for the bill.
    • The investment rate uses the purchase price to express the bill’s annualized return.
    BOTTOM LINE:

    Treasury bill rates come from an auction process rather than a single rate chosen in isolation. Investor bids help establish the accepted rate, while the resulting pricing determines how much investors pay for the bill.

    Treasury Bill Rates: At a Glance

    Treasury bill rates are established through the U.S. Treasury auction process. Investors submit bids for a specific bill, Treasury determines the accepted discount rate, and that rate is used to calculate the bill’s purchase price. T-bills are short-term Treasury securities with maturities of one year or less and are generally issued below face value.

    Quick Facts

    • Security: Short-term U.S. Treasury security
    • Auction: Treasury bills are issued through Treasury auctions
    • Pricing: Bills are generally sold at a discount to face value
    • Common terms: 4, 8, 13, 26, and 52 weeks
    • Return: Generally reflects the difference between the purchase price and face value at maturity
    • Rate measures: Discount rate and investment rate use different calculation methods
    Key ItemWhat It Tells You
    Competitive BidThe discount rate a competitive bidder is willing to accept for the bill.
    Noncompetitive BidA bid in which the investor agrees to accept the rate determined by the auction.
    High RateThe highest accepted competitive discount rate for the Treasury bill auction.
    Purchase PriceThe amount paid for the bill, generally below its face value.
    Investment RateAn annualized return measure based on the purchase price that can help compare a T-bill with other investments.

    QUICK TAKE:


    The auction rate is only one piece of the picture. To understand what a T-bill costs and how its return is expressed, look at the accepted rate, purchase price, maturity, and investment rate together.

    Complete Beginner Guide to Treasury Bill Rates

    How Treasury Bill Rates Are DeterminedIf you are new to Treasury bills, the rate-setting process may look complicated at first. The easiest way to understand it is to follow the path from the Treasury’s offering to the investor’s purchase price. Each auction covers a specific Treasury bill, and investors submit bids under the rules for that offering.
    First, Know What You Are Buying

    A Treasury bill has a stated face or par value and a specific maturity date. T-bills are generally issued at a discount, meaning the purchase price is below the amount paid at maturity. For example, an investor might pay less than $10,000 for a bill with a $10,000 face value. The difference represents the discount when the bill is held to maturity.

    Then Understand the Bid

    Investors can submit either a noncompetitive or competitive bid. A noncompetitive bidder agrees to accept the yield or rate determined at the auction. A competitive bidder specifies the discount rate the investor is willing to accept. Treasury then evaluates eligible competitive bids under the auction rules.

    The Rate and Price Are Connected

    For Treasury bills, the accepted discount rate is used in the pricing calculation. Because the bill is generally sold below par value, the resulting price reflects the rate, face value, and time remaining until maturity. A change in the accepted rate therefore changes the price investors pay for that issue.

    Why the Investment Rate Looks Different

    Treasury auction results can also show an investment rate. Unlike the discount rate, which uses par value and a 360-day convention, the investment rate is calculated from the purchase price using a 365-day basis, or 366 days in a leap year. This difference in calculation explains why the two rates can show different percentages for the same bill.

    If you want to see how a particular maturity works, our

    8-week Treasury bill guide

    and

    26-week Treasury bill guide

    provide more detail on individual terms.

    BEGINNER TIP:

    When you read a Treasury auction result, separate the bid type, accepted rate, purchase price, and maturity date. Once those pieces are clear, the rest of the pricing process becomes much easier to follow.

    How Treasury Bill Rates Are Determined

    A Treasury bill rate is discovered through the U.S. Treasury auction process. Treasury announces a specific bill, investors submit bids, and the accepted competitive bids help establish the rate used to price that issue. The process is designed to allocate the securities based on the rates investors are willing to accept.

    1. Treasury Announces the Bill

    Before the auction, Treasury announces details such as the bill’s offering amount, auction date, issue date, maturity date, and bidding terms. Investors can review those details before deciding whether to participate.

    2. Investors Submit Bids

    Investors can submit a noncompetitive bid or a competitive bid. A noncompetitive bidder agrees to accept the rate determined by the auction. A competitive bidder specifies the discount rate the investor is willing to accept.

    3. Treasury Evaluates the Bids

    Treasury first accepts eligible noncompetitive bids according to the auction rules. It then evaluates competitive bids from the lowest discount rates upward until the amount needed to fill the offering has been allocated. When necessary, bids at the highest accepted rate can be prorated.

    4. The High Rate Is Established

    The highest accepted competitive discount rate becomes the auction’s high rate, also known as the stop-out rate. For a Treasury bill auction, this rate is used to determine the price awarded to successful bidders.

    5. Market Conditions Influence the Result

    Investors’ required rates can change with short-term interest rates, inflation expectations, economic conditions, and demand for Treasury securities. As a result, two Treasury bill auctions with similar maturities can produce different rates.

    THE AUCTION FLOW:

    Treasury announces the bill → investors submit bids → Treasury evaluates the bids → the highest accepted discount rate becomes the high rate → the auction price is established.

    Benefits and Drawbacks of Treasury Bill Rate Auctions

    The Treasury auction process gives investors a clear way to see how a particular T-bill is priced. Still, the rate established at one auction does not guarantee the rate available on the next bill.

    Pros

    • Transparent pricing: Treasury publishes auction announcements and results for individual issues.
    • Defined maturity: Each T-bill has a stated maturity date, making the investment period easier to identify.
    • U.S. government obligation: Treasury securities are backed by the full faith and credit of the U.S. government.
    • State and local tax exemption: Treasury bill interest is generally exempt from state and local income taxes.

    Cons

    • Future rates can differ: Changing market conditions can produce a different rate at a later auction.
    • Reinvestment risk: When a T-bill matures, a replacement bill may offer a higher or lower rate.
    • Early-sale risk: Selling before maturity can expose you to the secondary-market price available at that time.
    • Federal tax applies: Treasury bill interest is generally subject to federal income tax.

    KEEP IN MIND:


    An auction gives you the rate and pricing information for a specific Treasury bill issue. It does not lock future Treasury auctions to the same rate. Each new auction reflects the conditions at that time.

    Treasury Bill Rate Comparison by Maturity

    Treasury bill rates can differ across maturities because each auction reflects the market conditions at that time. The maturity alone does not determine the rate. When comparing T-bills, look at the auction rate, purchase price, investment rate, and time until maturity together.

    T-Bill TermWhat to ComparePlanning Consideration
    4 weeksAuction rate, purchase price, and investment rateShort maturity and earlier access to the funds at maturity
    8 weeksRate established at the auction and resulting purchase priceLonger holding period than a 4-week bill
    13 weeksAuction rate and annualized investment rateUseful term for comparing short-term Treasury pricing
    17 weeksRate, purchase price, and maturity date for the specific issueProvides a maturity between the 13-week and 26-week terms
    26 weeksAuction rate, purchase price, and investment rateRequires the money to remain invested for a longer period
    52 weeksAuction rate, purchase price, and annualized investment rateThe longer maturity makes the cash timeline especially important

    Keep in mind that a quoted T-bill rate is annualized. Your actual dollar return depends on the purchase price, face value, and time until maturity. A higher annualized rate on one maturity therefore should not be viewed separately from the length of time the money is invested.

    COMPARE THE FULL PICTURE:


    Put the maturity, auction rate, purchase price, and investment rate side by side. This makes the comparison more meaningful than simply choosing the bill with the largest headline percentage.

    Costs, Risks and Expert Tips

    The auction rate is only one part of the decision. Before buying a Treasury bill, consider the purchase method, potential transaction costs, your cash timeline, taxes, and what could happen if you need to sell before maturity.

    Costs to Check

    TreasuryDirect does not charge a fee to purchase a Treasury security at auction. If you buy or sell through a brokerage, review the firm’s current pricing and trading terms. Depending on the transaction, commissions, markups, markdowns, or bid-ask spreads can affect your effective return.

    Risks That Matter

    • Reinvestment risk: A new T-bill may offer a different rate when your current bill matures.
    • Early-sale risk: Selling before maturity can result in a price above or below what you originally paid.
    • Inflation risk: The return may not keep pace with rising prices over the investment period.
    • Tax considerations: Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    Expert Tips for Comparing T-Bills

    Start by checking the auction rate and investment rate, then look at the purchase price and maturity date. If you may need the money before maturity, understand how secondary-market pricing works before investing. You can also compare the expected cash return with your other short-term options after considering taxes and transaction costs.

    EXPERT TIP:


    Don’t judge a T-bill by its headline rate alone. Check the purchase price, maturity, investment rate, taxes, and any transaction costs that could affect your actual return.

    Common Mistakes and a Real-Life Example

    Understanding how Treasury bill rates are determined becomes much easier when you connect the auction rate to the price you actually pay. A few common mistakes can make T-bill results look more confusing than they really are.

    Common Mistakes to Avoid

    • Confusing discount rate with investment rate:
      These rates use different calculation methods, so they can show different percentages for the same bill.
    • Assuming every auction has the same rate:
      Each auction can produce a different result as market conditions and investor demand change.
    • Ignoring the purchase price:
      The purchase price determines how much you pay for a bill relative to its face value.
    • Forgetting the maturity date:
      The annualized rate should be considered alongside the length of time your money will remain invested.

    Real-Life Example

    Suppose an investor buys a Treasury bill with a $10,000 face value at an auction for less than $10,000. The investor pays the purchase price upfront. If the bill is held until maturity, the $10,000 face value is paid. The difference between the discounted purchase price and the amount received at maturity is generally treated as interest income.

    Now imagine a later auction produces a different accepted rate. Because the rate and price are connected, the purchase price for that new bill can also change. This is why a Treasury bill rate is not a permanent number; each auction reflects the conditions surrounding that particular offering.

    REAL-WORLD TAKEAWAY:


    When reviewing a T-bill auction, look at the accepted rate, purchase price, maturity date, and investment rate together. That gives you a clearer picture than looking at the headline rate alone.

    Who Should Consider Treasury Bills?

    Treasury bills may fit investors who want a short-term U.S. government security with a defined maturity date. They can also be useful for investors who have a specific cash timeline and want to compare auction rates and purchase prices before investing.

    T-Bills May Fit You If

    • You have cash that you expect to leave invested until a specific maturity date.
    • You want exposure to short-term U.S. Treasury securities.
    • You prefer a defined maturity rather than an open-ended investment period.
    • You are comfortable comparing auction rates, purchase prices, and maturity dates.

    T-bills may require more planning if you could need the money before maturity. Although Treasury bills are marketable securities, selling before maturity means accepting the secondary-market price available at that time, which can differ from your original purchase price.

    PLANNING TIP:


    Start with your cash timeline. Once you know when the money may be needed, compare T-bill maturities, auction rates, purchase prices, and potential early-sale considerations.

    Frequently Asked Questions About Treasury Bill Rates

    How are Treasury bill rates determined?

    Treasury bill rates are determined through Treasury auctions. Competitive bidders submit discount rates, and Treasury evaluates eligible competitive bids from the lowest discount rates upward until the securities being offered are allocated. The highest accepted competitive discount rate becomes the auction’s high rate.

    What is the difference between a competitive and noncompetitive bid?

    A competitive bidder specifies the discount rate they are willing to accept. A noncompetitive bidder does not specify a rate and agrees to accept the rate determined by the auction. TreasuryDirect does not allow investors to submit competitive bids through its system.

    Does a higher T-bill rate always mean a higher dollar return?

    Not necessarily. The quoted rate is annualized, while the actual dollar return depends on the purchase price, face value, and time until maturity. When comparing T-bills, consider the rate together with the maturity and amount invested.

    Why do Treasury bill rates change?

    Each auction reflects the conditions at that time. Changes in short-term interest rates, inflation expectations, economic conditions, and investor demand can affect the discount rates investors are willing to accept.

    Are Treasury bill earnings taxable?

    Yes. Interest income from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes. The IRS provides specific reporting rules for Treasury securities.

    Can I sell a Treasury bill before maturity?

    Yes. Treasury bills are marketable securities that can generally be sold through a bank or broker that supports secondary-market transactions. The price available when you sell may be different from your original purchase price.

    FAQ TAKEAWAY:


    The key numbers to understand are the auction rate, purchase price, investment rate, and maturity date. Looking at them together gives you a clearer picture of how a Treasury bill is priced and how its return is expressed.

    Final Thoughts on How Treasury Bill Rates Are Determined

    Understanding how Treasury bill rates are determined starts with the auction process. Treasury announces a specific bill, investors submit competitive or noncompetitive bids, and the accepted competitive bids help establish the auction’s high rate. For Treasury bills, the auction result is then used to determine the price of the security.

    The high rate is not the only number worth reviewing. The purchase price, face value, maturity date, and investment rate help explain how the bill is priced and how its annualized return is expressed. Because each auction reflects conditions at that time, rates and prices can change from one offering to another.

    Before investing, match the bill’s maturity with your cash needs and review the auction details carefully. If you may need the money before maturity, also consider how secondary-market pricing could affect the amount you receive when selling.

    FINAL TAKEAWAY:


    Treasury bill rates are discovered through the auction process. Once you understand the connection between bids, the high rate, purchase price, and investment rate, Treasury auction results become much easier to read and compare.

    Have a Money Question? Keep Exploring.

    Understanding Treasury bills starts with knowing how their rates, prices, and maturities work together. Keep exploring FinanceInvestment for practical guides that can help you make sense of everyday investing decisions.

    📩 Get in Touch With FinanceInvestment


    Email FinanceInvestment

    Continue Your Research
  • Treasury Bill Rates Explained: A Clear Guide for 2026

    Treasury Bill Rates Explained: A Clear Guide for 2026

    Treasury Bill Rates Explained

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 18, 2026


    Reading Time: ~11 minutes

    Why Treasury Bill Rates Matter

    Treasury Bill Rates ExplainedTreasury Bill Rates Explained is easier once you know what the numbers on a Treasury auction actually mean. You may see a discount rate, investment rate, purchase price, and maturity value. They are related, but each number tells you something different about the T-bill.

    Treasury bills are short-term U.S. government securities generally sold at a price below their face value. Instead of receiving regular coupon payments, the investor’s return generally comes from the difference between the purchase price and the amount paid at maturity. The quoted rate can vary as market conditions, investor demand, inflation expectations, and monetary policy change.

    If you are new to Treasury securities, our

    Treasury Bills Explained

    guide gives you the broader foundation. Here, we will focus specifically on how T-bill rates are presented, what they mean, and how to read them before making an investment decision.

    What You’ll Learn

    • What a Treasury bill rate represents
    • How the discount rate differs from the investment rate
    • Why T-bill rates change over time
    • How different maturity terms can have different rates
    • How to compare T-bill yields with other short-term investments
    • What to check before buying a Treasury bill

    Quick Answer: What Is a Treasury Bill Rate?

    A Treasury bill rate describes the annualized return associated with a short-term Treasury bill. Because T-bills are issued at a discount and redeemed at their face value at maturity, the rate is tied to the bill’s price, face value, and time to maturity. Treasury auction results can show both a discount rate and an investment rate, and those figures are calculated differently.

    Key Takeaways

    • T-bills are generally purchased for less than their face value.
    • The difference between the purchase price and face value represents the bill’s discount.
    • The discount rate is calculated using the bill’s par value and a 360-day basis.
    • The investment rate is based on the purchase price and is useful for comparing returns.
    • T-bill rates can change as market conditions and investor demand change.
    • Different Treasury bill maturities can carry different rates.
    BOTTOM LINE:

    Don’t look at a T-bill’s quoted rate in isolation. Check the purchase price, maturity date, and investment rate to get a clearer picture of the return you are comparing.

    Treasury Bill Rates at a Glance

    Treasury bill rates become easier to understand once you separate the bill’s price from the rate used to quote its return. T-bills are generally issued at a discount to face value and paid at face value at maturity. The quoted rate depends on the calculation method, purchase price, and time remaining until maturity.

    Quick Facts

    • Security: Short-term U.S. Treasury security
    • Pricing: Generally issued below face value
    • Maturity: The bill is redeemed at face value according to its terms
    • Return: Generally reflects the difference between the purchase price and the amount received at maturity
    • Rates: Can vary by maturity, auction conditions, and broader market conditions
    • Useful for: Investors comparing short-term Treasury investments
    Rate or TermWhat It Means
    Discount RateAn annualized rate calculated from the bill’s discount from face value using a 360-day basis.
    Investment RateAn annualized rate based on the purchase price and calculated on a 365- or 366-day basis. It is useful for comparing T-bill returns with other investments.
    Purchase PriceThe amount paid for the Treasury bill, generally below its face value.
    MaturityThe date when the T-bill reaches the end of its stated term and is redeemed according to its terms.
    QUICK TAKE:

    The discount rate and investment rate are not interchangeable. When you want to compare a T-bill’s annualized return with another short-term investment, the investment rate provides the more useful comparison.

    Complete Beginner Guide to Treasury Bill Rates

    Treasury Bill Rates ExplainedTreasury bill rates make more sense once you separate three things: what you pay, what the bill is worth at maturity, and how the return is expressed as an annualized rate. A T-bill generally does not send you regular interest payments. Instead, it is issued at a discount and redeemed at face value when it matures.
    Start With the Price

    Suppose a Treasury bill has a $10,000 face value and an investor pays $9,800. If the investor holds the bill until maturity, the Treasury pays the $10,000 face value according to the security’s terms. In this simplified example, the $200 difference is the discount and represents the investment’s return before applicable taxes.

    Understand the Two Rate Measures

    Treasury auction results can include both a discount rate and an investment rate. The discount rate is calculated from the bill’s par value using a 360-day convention. The investment rate is calculated using the purchase price and a 365- or 366-day basis. Because of these different calculations, the two percentages can be different even for the same T-bill.

    Compare the Maturity Terms

    The rate can also vary depending on how long the money is invested. A 4-week bill may have a different rate from a 13-week, 26-week, or 52-week bill. If you want to explore the shorter terms, see our

    4-week Treasury bill guide

    and

    13-week Treasury bill guide
    .

    For a longer holding period, our

    52-week Treasury bill guide

    explains what changes when you choose a one-year Treasury bill.

    BEGINNER TIP:

    When comparing T-bills, look at the maturity, purchase price, and investment rate together. A single percentage does not tell the whole story.

    How Treasury Bill Rates Work

    Treasury bill rates are established through the U.S. Treasury auction process. Investors can submit either competitive or noncompetitive bids. Competitive bidders specify the discount rate they are willing to accept, while noncompetitive bidders agree to receive the rate determined by the auction.

    1. Investors Submit Bids

    A competitive bid states both the amount the investor wants and the discount rate they are willing to accept. Noncompetitive bidders do not choose a discount rate. Instead, they agree to accept the rate established through the auction, subject to the auction’s terms.

    2. Treasury Determines the Accepted Rate

    After the auction closes, Treasury accepts noncompetitive bids and then evaluates competitive bids from the lowest discount rates upward until the required amount of securities has been allocated. The highest accepted competitive discount rate becomes the auction’s stop-out rate for Treasury bills.

    3. The Rate Determines the Purchase Price

    Because Treasury bills are generally sold below face value, the auction’s discount rate is used to calculate the price paid for the bill. A lower purchase price means a larger dollar difference between the amount paid and the face value received at maturity, all else being equal.

    4. Investment Rate Shows the Return Differently

    The discount rate and investment rate are not interchangeable. The discount rate is calculated using par value and a 360-day convention. The investment rate uses the purchase price and a 365- or 366-day basis. That difference is why the investment rate can be more useful when comparing a T-bill with other short-term investments.

    5. Future Auction Rates Can Change

    A rate from one Treasury auction does not lock in the rate for future bills. Market interest rates, investor demand, inflation expectations, economic conditions, and Federal Reserve policy can influence the rates available at later auctions.

    RATE CHECK:

    The simplest way to follow the process is: investors bid → Treasury accepts bids → the auction establishes the rate → the rate determines the bill’s price. The investment rate then expresses the return using the purchase price.

    Benefits and Drawbacks of Treasury Bill Rates

    Looking at the rate is only one part of evaluating a Treasury bill. The maturity date, purchase price, access to your money, and the rate available when you invest can all affect how the security fits into your short-term plans.

    Pros

    • Known maturity: Each T-bill has a stated maturity date, making the timing easier to plan around.
    • Simple pricing structure: T-bills are generally purchased below face value and redeemed at face value at maturity.
    • U.S. government obligation: Treasury securities are backed by the full faith and credit of the U.S. government.
    • Transparent auction information: Treasury publishes auction results, including relevant pricing and rate information.

    Cons

    • Rates can move: A new T-bill may offer a different rate when market conditions change.
    • Early access involves the market: Selling before maturity can expose you to a secondary-market price that differs from your purchase price.
    • Reinvestment risk: When a T-bill matures, the rate available on a replacement investment may be higher or lower than the original rate.
    • Taxes still matter: T-bill interest is generally subject to federal income tax, although it is generally exempt from state and local income taxes.
    KEEP IN MIND:

    A higher quoted rate does not tell the entire story. Look at the maturity, purchase price, investment rate, and your expected use for the money before comparing T-bills.

    Treasury Bill Rate Comparison by Maturity

    Treasury bill rates can vary from one maturity to another because each auction reflects market conditions at that time. Instead of comparing percentages alone, look at the rate together with the bill’s term, purchase price, and maturity date.

    T-Bill TermRate ConsiderationPlanning Consideration
    4 weeksThe applicable rate is established through the auction for that issue.The scheduled maturity arrives relatively soon, which can suit a shorter cash timeline.
    13 weeksThe auction determines the rate for that specific 13-week issue.Provides a longer maturity than a 4-week bill while remaining a short-term security.
    26 weeksThe rate reflects the pricing established at the auction for the 26-week issue.The scheduled maturity is farther away, so consider how long the money can remain invested.
    52 weeksThe auction determines the applicable rate for the 52-week issue.The longer maturity may require more planning around when the funds become available.

    One important detail: the rate on a T-bill is annualized. Your actual dollar return depends on the purchase price, face value, and length of the investment. Therefore, a higher quoted annualized rate does not automatically mean a larger dollar return for every investor or every maturity.

    COMPARE SMARTER:

    Compare the investment rate, maturity period, purchase price, and your cash timeline together. That gives you a more meaningful comparison than looking at the headline percentage alone.

    Costs, Risks and Expert Tips

    A Treasury bill’s quoted rate is useful, but it is not the only number worth checking. Your purchase price, maturity date, taxes, and the rate available when you reinvest can all affect the outcome.

    Costs to Check

    If you buy or sell T-bills through a brokerage, review that firm’s current pricing and trading terms. Depending on the institution and transaction, costs can include commissions, markups, markdowns, or bid-ask spreads. These expenses can reduce your effective return.

    Tax Considerations

    Interest income from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes. For T-bills, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income under federal tax rules.

    Risks Worth Understanding

    • Rate risk: A new T-bill may offer a different rate when market conditions change.
    • Early-sale risk: Selling before maturity means accepting the secondary-market price available at that time.
    • Reinvestment risk: A maturing T-bill may need to be replaced at a different rate.
    • Opportunity cost: Money committed to one maturity may not be available for another investment during that period.
    EXPERT TIP:

    Before comparing two T-bills, write down the purchase price, face value, maturity date, and investment rate. Looking at these details together gives you a much clearer comparison than the headline rate alone.

    Common Treasury Bill Rate Mistakes + Example

    Treasury bill pricing is straightforward once the numbers are separated. Still, a few common mistakes can make a T-bill rate look better or worse than it really is. The biggest issue is usually comparing figures that are calculated differently.

    Mistakes to Avoid

    • Mixing up the two rate measures: The discount rate and investment rate use different formulas and day-count conventions.
    • Ignoring the purchase price: The dollar return depends on what you actually pay for the bill.
    • Comparing different terms without context: A rate on a short maturity and a rate on a longer maturity may reflect different market conditions.
    • Treating an auction rate as permanent: A future Treasury auction can produce a different rate.
    • Overlooking taxes: Treasury bill interest generally has federal income-tax implications, although it is generally exempt from state and local income taxes.

    A Simple Example

    Suppose an investor purchases a Treasury bill with a $10,000 face value for $9,800. If the investor holds it until maturity and the security pays $10,000 according to its terms, the difference is $200.

    That $200 is the dollar difference in this simplified example, but it is not by itself the annualized Treasury bill rate. The investment period matters. For example, the same $200 difference over a shorter period represents a different annualized return than $200 earned over a longer period.

    SMART CHECK:

    When a T-bill rate catches your attention, look at the calculation behind it and the time period it covers. That small step can prevent a misleading comparison.

    Who Should Consider Treasury Bills?

    Treasury bills can be relevant for investors looking at short-term U.S. government securities with a stated maturity date. Whether they fit a particular financial plan depends on the investor’s time horizon, cash needs, available rates, and other investment choices.

    Common Situations

    • You have funds that may remain invested until a known short-term maturity date.
    • You are researching U.S. Treasury securities for short-term cash management.
    • You want to compare Treasury bill rates with savings accounts, money market accounts, or CDs.
    • You want to understand an investment whose return generally comes from buying below face value and receiving face value at maturity.

    Your timeline matters. If you could need the money before maturity, selling the T-bill may involve a secondary-market transaction, and the market price at that time can be different from your original purchase price.

    QUICK CHECK:

    Start by identifying when you may need the money. Then compare the available Treasury bill rate, maturity period, and alternatives that serve the same purpose.

    Frequently Asked Questions About Treasury Bill Rates

    1. What are Treasury bill rates?

    Treasury bill rates are annualized measures associated with short-term U.S. Treasury bills. T-bills are generally issued at a discount and redeemed at face value when they mature.

    2. How are Treasury bill rates determined?

    Treasury bills are sold through auctions. Competitive bidders specify the discount rate they are willing to accept, while noncompetitive bidders agree to accept the rate determined by the auction.

    3. What is the difference between the Treasury bill discount rate and investment rate?

    The discount rate is calculated using the bill’s par value and a 360-day basis. The investment rate is based on the purchase price and uses a 365-day basis, or 366 days during a leap year. TreasuryDirect says the investment rate can be used to compare bill yields with other investments.

    4. Why do Treasury bill rates change?

    T-bill rates can change because auction pricing responds to market conditions, investor demand, interest-rate expectations, inflation expectations, and broader economic conditions.

    5. Do longer Treasury bills always have higher rates?

    No. Rates can differ across maturities, and the relationship can change with market conditions. A longer maturity does not automatically mean a higher Treasury bill rate.

    6. Are Treasury bill rates the same as savings account rates?

    No. They are different types of rates. Treasury bills are generally issued below face value and pay the face value at maturity, while savings accounts generally credit interest based on the account’s terms.

    7. Can I sell a Treasury bill before maturity?

    Generally, yes. A marketable T-bill can be sold before maturity through a bank or broker that supports secondary-market Treasury transactions. The market price at that time can differ from the original purchase price.

    8. Is Treasury bill interest taxable?

    Yes, Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Individual tax circumstances can vary, so current IRS guidance should be reviewed for your situation.

    Final Thoughts on Treasury Bill Rates

    Treasury Bill Rates Explained comes down to understanding what sits behind the percentage you see. A T-bill’s purchase price, face value, maturity period, and rate calculation all affect how the investment is presented.

    One detail deserves special attention: the discount rate and investment rate are different measures. Because they use different calculation methods, the two percentages can vary for the same Treasury bill. Looking at the investment rate can make comparisons with other short-term investments more meaningful.

    If you want to build a stronger foundation before comparing individual bills, visit our

    Treasury Bills Explained

    guide. It covers the broader basics, while this article focuses on understanding the rates behind those securities.

    FINAL TAKE:

    A Treasury bill rate is more useful when you know what the number represents. Check the rate calculation, purchase price, and maturity together before comparing one T-bill with another.

    Have a Money Question? Keep Exploring.

    Understanding Treasury bill rates is a good starting point. Keep exploring related Treasury topics to build a clearer picture of short-term investing.

    📩 Get in Touch With FinanceInvestment


    Email Us

  • What Happens If You Hold a Treasury Bill Until Maturity? 2026

    What Happens If You Hold a Treasury Bill Until Maturity? 2026

    What Happens If You Hold a Treasury Bill Until Maturity?

    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 18, 2026


    Reading Time: ~12 minutes

    What Happens When a Treasury Bill Reaches Maturity?

    What Happens If You Hold a Treasury Bill Until Maturity?What happens if you hold a Treasury bill until maturity? When the T-bill reaches its maturity date, the U.S. Treasury pays the bill’s face value according to its terms. Treasury bills are generally purchased at a discount, so the difference between the purchase price and the amount paid at maturity represents the bill’s interest.

    Unlike Treasury notes and bonds, T-bills do not make periodic coupon payments. Your return is built into the discounted purchase price. Once the bill matures, the scheduled payment is made according to how and where you hold the security, and you can then decide what to do with the proceeds.

    If you’re new to T-bills, our

    Treasury Bills Explained

    guide covers the basics. This article focuses on what happens at maturity, how the payment works, what happens to your earnings, tax considerations, and the choices you have afterward.

    What You’ll Learn

    • What happens on a Treasury bill’s maturity date
    • How the maturity payment works
    • Why T-bills are sold at a discount
    • How your T-bill return is realized
    • What tax considerations may apply
    • What you can do with the proceeds after maturity

    Quick Answer: What Happens at T-Bill Maturity?

    When you hold a Treasury bill until maturity, the security reaches its scheduled maturity date and the U.S. Treasury pays its face value according to the bill’s terms. Because T-bills are generally purchased at a discount, the difference between your purchase price and the maturity payment represents the interest built into the investment.

    Key Takeaways

    • The T-bill reaches its stated maturity date.
    • The Treasury pays the bill’s face value according to its terms.
    • T-bills generally do not make periodic coupon payments.
    • Your return is generally the difference between the purchase price and the maturity payment.
    • How the maturity proceeds are credited or delivered depends on where you hold the T-bill.
    • Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.
    • After maturity, you can use or reinvest the proceeds according to your financial needs.
    BOTTOM LINE:

    If you keep a T-bill until maturity, you do not need to rely on a secondary-market sale. The Treasury makes the scheduled maturity payment, with the difference between your discounted purchase price and that payment representing the bill’s return.

    Treasury Bill Maturity at a Glance

    When you hold a Treasury bill through its full term, you keep the security until its stated maturity date. At maturity, the U.S. Treasury pays the bill’s face value according to its terms. Because T-bills are generally purchased for less than face value, the difference between your purchase price and the maturity payment represents the return built into the bill.

    Quick FactWhat It Means
    Investment typeShort-term U.S. Treasury security
    Purchase priceGenerally below the bill’s face value
    Interest structureNo periodic coupon payments; the return is generally the difference between the purchase price and maturity value
    At maturityThe Treasury pays the bill’s face value according to its terms
    Typical useA short-term investment with a defined maturity date
    After maturityThe proceeds can generally be used or reinvested according to your account setup and financial plans
    QUICK TAKE:

    The maturity payment is based on the T-bill’s face value. Since the bill is generally bought at a discount, the difference between what you paid and what the Treasury pays at maturity is the return built into the investment.

    Complete Beginner Guide to Holding a Treasury Bill Until Maturity

    What Happens If You Hold a Treasury Bill Until Maturity?A Treasury bill follows a straightforward investment cycle. You purchase the bill at a price that is generally below its face value, hold it in a TreasuryDirect or brokerage account, and wait for its stated maturity date. If you keep it through maturity, you do not need to sell the security in the secondary market.
    Start With the Maturity Date

    Every T-bill has a specific maturity date. That date marks the end of the bill’s term. Treasury bills are offered in several terms, including 4, 8, 13, 17, 26, and 52 weeks. The term you purchase determines when the scheduled maturity payment is due.

    If you are comparing different terms, our guides to

    4-week Treasury bills

    and

    13-week Treasury bills

    explain how shorter maturity periods work.

    Understand How the Return Is Earned

    T-bills generally do not make periodic coupon payments. Instead, you normally buy the bill at a discount to its face value. When the bill reaches maturity, the Treasury pays the face value according to its terms. The difference between your purchase price and the maturity payment represents the interest built into the investment.

    What to Check Before Maturity

    You usually do not need to take action simply because the T-bill is approaching maturity. Still, review your account and any maturity instructions beforehand. If you need the proceeds for a bill, purchase, or other financial goal, knowing the expected payment date can make cash planning easier.

    Beginner Tip:

    Treat the maturity date as an important cash-flow date. Once the T-bill reaches maturity, the scheduled payment is made according to its terms. From there, your next step is deciding how you want to use or reinvest the proceeds.

    How a Treasury Bill Maturity Works

    When your Treasury bill reaches its maturity date, its scheduled term ends and the Treasury makes the maturity payment according to the bill’s terms. If you have held the T-bill throughout the term, you do not need to find a buyer or arrange a secondary-market sale.

    1. The T-Bill Reaches Its Maturity Date

    Every T-bill has a stated maturity date. If you continue holding the security until that date, the bill completes its scheduled term. The maturity date is therefore an important cash-flow date to keep on your calendar.

    2. The Treasury Pays the Face Value

    Treasury bills are generally purchased at a discount to face value. For example, an investor might pay $9,700 for a T-bill with a $10,000 face value. If the investor holds it until maturity, the Treasury pays the $10,000 face value according to the security’s terms. The $300 difference represents the interest built into this simplified example.

    3. The Maturity Proceeds Are Credited or Paid

    The way you receive the maturity proceeds depends on where the T-bill is held and the applicable account procedures. TreasuryDirect and brokerage accounts can have different processes, so review your account information before the maturity date.

    4. Decide What to Do With the Proceeds

    Once the maturity proceeds are available, you can use them for a planned expense, keep the cash in an appropriate account, or consider another investment. If you are considering another T-bill, our

    guide to how Treasury bills make money

    explains how the discount-based return works.

    MATURITY CHECK:

    Before the T-bill matures, confirm the maturity date, review your account instructions, and have a clear plan for the proceeds. That small check can prevent surprises when the investment reaches its end date.

    Benefits and Drawbacks of Holding a Treasury Bill to Maturity

    Holding a T-bill through its maturity date can make the timing of your investment easier to plan because you are waiting for the scheduled maturity payment rather than relying on a secondary-market sale. However, this approach also comes with trade-offs.

    Pros

    • Defined maturity date: You know when the T-bill’s scheduled maturity payment is due.
    • No secondary-market sale needed: You can keep the bill through its stated term instead of arranging an early sale.
    • Simple return structure: The return generally comes from the difference between the discounted purchase price and the maturity value.
    • Easier cash planning: A known maturity date can help you plan around a future financial need.

    Cons

    • Early access may require a sale: If you need the money before maturity, you generally need to use a secondary-market transaction rather than wait for the scheduled payment.
    • Opportunity cost: Market yields can change during the T-bill’s term, so other investments may offer different rates later.
    • Reinvestment risk: When the T-bill matures, a new Treasury bill may have a different yield than the one you originally purchased.
    • Tax considerations: Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.
    KEY POINT:

    Holding a T-bill to maturity gives you a defined end date and avoids depending on a secondary-market sale for the scheduled payment. The main trade-offs involve access to the money before maturity and what market rates may look like when you reinvest.

    Treasury Bill Maturity Comparison

    Treasury bills can have different maturity periods, but the basic maturity process is similar. The main difference is how long you hold the security before the scheduled payment date arrives.

    T-Bill TermWhat Happens at Maturity?Planning Consideration
    4-week or 8-weekThe bill reaches its stated maturity date, and the Treasury pays its face value according to its terms.The shorter term means the scheduled maturity date arrives sooner.
    13-week or 26-weekThe scheduled maturity payment is made when the bill reaches its stated maturity date.Consider the maturity date when planning for future cash needs or possible reinvestment.
    52-weekThe bill reaches maturity after its stated 52-week term, and the Treasury pays the face value according to its terms.The longer term means waiting longer for the scheduled maturity payment.
    After maturityThe maturity proceeds are handled according to the procedures of the account where the T-bill is held.You can then decide whether to use the proceeds or consider another investment.
    QUICK COMPARISON:

    The basic maturity process does not change with the T-bill term: the security reaches its stated maturity date and the Treasury makes the scheduled payment. What changes is the length of time before that date arrives.

    Costs, Taxes, Risks and Expert Tips

    Holding a Treasury bill until maturity is generally straightforward, but a few details still deserve attention. Taxes, changing market yields, reinvestment decisions, and your plans for the maturity proceeds can all affect what happens next.

    What About Taxes?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. The IRS treats the discount on a Treasury bill as interest income under applicable tax rules. For the details that apply to your situation, review

    IRS Publication 550

    and keep your purchase records and tax documents.

    TAX TIP:

    Tax reporting can depend on the type of transaction and your individual circumstances. If you need personalized tax advice, consider speaking with a qualified tax professional.

    Understand Reinvestment Risk

    When your T-bill matures, the yield available on a new Treasury security may be different from the rate available when you made your original purchase. If you plan to reinvest, check the current rates and maturity options at that time rather than assuming the same return will be available.

    Expert Tips Before Maturity

    • Mark the T-bill’s maturity date on your calendar.
    • Check how your account handles the maturity proceeds.
    • Keep your purchase confirmation and tax records.
    • Decide whether the proceeds are needed for spending, saving, or another investment.
    • If you plan to reinvest, compare the Treasury rates available when the bill matures.

    Common Mistakes When Holding a Treasury Bill to Maturity

    A T-bill is simple to understand once you know the basic structure, but small oversights can still cause confusion around the maturity date, payment, taxes, or what happens afterward. A little preparation can make the end of the investment much easier to manage.

    Mistakes to Avoid

    • Forgetting the maturity date: Each T-bill has its own stated maturity date, so check the details of your specific security.
    • Expecting periodic interest payments: T-bills generally do not make coupon payments during their term.
    • Confusing purchase price with face value: A T-bill is generally purchased at a discount, so the amount paid can be lower than its face value.
    • Overlooking tax reporting: Treasury interest generally has federal tax implications, so keep the relevant records and tax documents.
    • Waiting until the last minute to plan: Know what you want to do with the maturity proceeds before the payment date arrives.

    A Simple Example

    Suppose an investor purchases a Treasury bill for $9,700 with a face value of $10,000. The investor keeps the bill until its stated maturity date. If the security’s terms provide for a $10,000 maturity payment, the $300 difference represents the interest in this simplified example, before considering applicable taxes.

    Because the investor held the T-bill through maturity, there is no need to arrange a secondary-market sale to receive the scheduled payment. Once the maturity proceeds are available according to the account’s procedures, the investor can use the money or consider another investment.

    SMART CHECK:

    Keep four details handy: your purchase price, face value, maturity date, and plan for the proceeds. Together, they show what you paid, what the bill is scheduled to pay, and what you want to do next.

    Who Should Consider Holding a Treasury Bill to Maturity?

    Holding a T-bill until maturity may make sense for an investor whose cash needs line up with the security’s scheduled maturity date. The fixed end date can also make it easier to plan when the investment is expected to reach maturity.

    Situations to Consider

    • You have a short-term financial goal with a reasonably clear timeline.
    • You expect to keep the T-bill through its scheduled maturity date.
    • You are comfortable waiting for the maturity payment rather than seeking access to the money sooner.
    • You want an investment with a stated maturity date for cash-flow planning.

    Your circumstances still matter. If you might need the money unexpectedly, remember that selling before maturity involves a secondary-market transaction and a market price that can differ from your purchase price. If you plan to reinvest after maturity, the yield available on a new T-bill may also be different.

    QUICK CHECK:

    Compare the T-bill’s maturity date with your expected cash needs. If those timelines do not match, consider how you would handle the money before making the investment.

    Frequently Asked Questions About Treasury Bill Maturity

    1. What happens if you hold a Treasury bill until maturity?

    The T-bill reaches its stated maturity date, and the U.S. Treasury pays the bill’s face value according to its terms. The difference between the discounted purchase price and the maturity payment generally represents the interest.

    2. Do Treasury bills pay interest at maturity?

    T-bills generally do not make periodic coupon payments. Instead, they are normally purchased at a discount, and the difference between the purchase price and the amount paid at maturity represents the interest.

    3. Do I get the face value of a Treasury bill at maturity?

    Generally, yes. If you hold the T-bill until maturity, the Treasury pays its face value according to the security’s terms. The original purchase price is generally lower because the bill is issued at a discount.

    4. What happens to a T-bill after it matures?

    The T-bill reaches the end of its term, and the maturity proceeds are handled according to the procedures of the account where the security is held. You can then decide what to do with the proceeds.

    5. Is Treasury bill interest taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Your individual tax situation may differ, so review current IRS guidance or consult a qualified tax professional.

    6. Can I reinvest a Treasury bill when it matures?

    Reinvestment may be available depending on where you hold the T-bill and the options provided by that account. A new Treasury security will have its own purchase price, maturity date, and yield.

    7. What if I need the money before the T-bill matures?

    You may generally be able to sell a marketable T-bill before maturity through a bank, broker, or brokerage that supports secondary-market Treasury transactions. The market price can differ from the amount you originally paid.

    8. What should I do when my Treasury bill matures?

    First, check that the maturity proceeds have been handled according to your account’s procedures. You can then consider whether to use the money, keep it as cash, or reinvest it based on your financial plans.

    Final Thoughts on Holding a Treasury Bill Until Maturity

    What happens if you hold a Treasury bill until maturity? The T-bill reaches its stated maturity date, and the U.S. Treasury makes the scheduled payment of the bill’s face value according to its terms. Because T-bills are generally purchased below face value, the difference between the purchase price and maturity payment represents the interest built into the investment.

    Keeping the bill through maturity also means you are not depending on a secondary-market sale to complete the investment. Once the maturity proceeds are handled according to your account’s procedures, you can decide whether the money is needed for a planned expense, kept as cash, or considered for another investment.

    For a broader explanation of Treasury securities, visit our

    Treasury Bills Explained

    guide. It covers the basics, while this article focuses on the final stage of a T-bill’s life cycle.

    BOTTOM LINE:

    When a T-bill reaches maturity, the Treasury makes the scheduled face-value payment according to the security’s terms. Your purchase price and maturity value determine the return built into the bill, while your account and financial plans determine what happens next.

    Have a Money Question? Keep Exploring.

    Keep learning with FinanceInvestment. Explore practical guides on Treasury bills, savings, CDs, and everyday money decisions.

    📩 Get in Touch With FinanceInvestment

    Have a question or feedback about this guide? Send us an email and get in touch with FinanceInvestment.


    Email FinanceInvestment

  • Can You Sell a Treasury Bill Before Maturity? 2026 Guide

    Can You Sell a Treasury Bill Before Maturity? 2026 Guide

    Can You Sell a Treasury Bill Before Maturity?

    SR
    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 18, 2026


    Reading Time: ~10 minutes

    Selling a Treasury Bill Before Maturity

    Can You Sell a Treasury Bill Before Maturity?Can you sell a Treasury bill before maturity? Yes. If you need access to the money sooner, you can generally sell the T-bill in the secondary market through a bank or brokerage that supports Treasury securities. The key detail is price: the amount you receive can be different from what you originally paid.

    That difference matters because Treasury bill prices can change before maturity as interest rates and market conditions move. Selling early is therefore different from holding the bill until its maturity date, when the Treasury makes the scheduled payment according to the security’s terms.

    If you are just getting started, our

    Treasury Bills Explained

    guide covers the basics. This article goes one step further by looking at the early-sale process, pricing, potential costs, risks, taxes, and the points worth checking before you sell.

    What You’ll Learn

    • Whether you can sell a Treasury bill before maturity
    • How the secondary market works
    • Why a T-bill’s market price can change
    • How selling early differs from holding to maturity
    • Potential costs, risks, and tax considerations
    • What to check before placing a sale

    Quick Answer: Can You Sell a Treasury Bill Before Maturity?

    Yes. You can generally sell a Treasury bill before maturity through a bank, broker, or brokerage that supports secondary-market Treasury transactions. The important detail is that you sell at the market price available at that time. Depending on market conditions, that price may be above or below what you originally paid.

    Key Takeaways

    • Treasury bills can generally be sold before their maturity date.
    • An early sale is normally completed through the secondary market.
    • TreasuryDirect does not provide a direct sell feature for marketable securities; selling generally involves transferring the security to a bank, broker, or appropriate brokerage account.
    • The T-bill’s market price can change before maturity as interest rates and market conditions change.
    • You may receive more or less than your original purchase price when selling early.
    • Holding the bill until maturity follows a different path because you are not relying on a secondary-market sale price.
    • Before selling, review the estimated proceeds, any applicable transaction costs, and your tax considerations.
    Bottom Line:

    You can generally sell a Treasury bill before maturity, but the amount you receive depends on its market price when you sell. If you need the cash early, understand that price difference before placing the order.

    Treasury Bill Early Sale at a Glance

    Can you sell a Treasury bill before maturity? Generally, yes. An investor can sell a T-bill before its maturity date through a bank, broker, or brokerage that supports secondary-market Treasury transactions. The key difference is that an early sale is based on the market price at the time of the sale.

    Quick FactWhat It Means
    Can you sell early?Generally yes, through a bank, broker, or brokerage that supports secondary-market Treasury transactions.
    Can TreasuryDirect sell it?TreasuryDirect does not provide a direct selling feature for marketable securities.
    How is the sale price set?The price depends on market conditions and the price available when you sell.
    What could you receive?The proceeds may be higher or lower than your original purchase price.
    What should you check?Review the estimated sale proceeds, applicable costs, and your need for the cash before selling.
    QUICK TAKE:

    Selling a T-bill early can provide access to your money before maturity, but you are selling at a market price rather than simply receiving the bill’s scheduled maturity payment.

    Complete Beginner Guide to Selling a Treasury Bill Early

    Can You Sell a Treasury Bill Before Maturity?Treasury bills are short-term U.S. government securities with a set maturity date. However, you do not necessarily have to keep one until that date. If you need the money sooner, you can generally sell the T-bill in the secondary market through a bank, broker, or brokerage that handles Treasury securities.

    What Happens When You Want to Sell?

    The first step depends on where you hold the security. TreasuryDirect lets investors buy and hold eligible marketable Treasury securities, but it does not provide a direct selling feature. If you want to sell a TreasuryDirect-held T-bill before maturity, you generally need to transfer it to a bank, broker, or brokerage account that can handle the secondary-market transaction.

    After the security is in an appropriate account, the financial institution can provide the available market price and transaction details. Your sale proceeds will depend on that price, the amount of the security being sold, and any applicable charges.

    Why Is the Sale Price Different?

    A T-bill’s market price can change before maturity. Interest rates, investor demand, and other market conditions can affect what buyers are willing to pay. For example, if newly issued Treasury securities begin offering higher yields, an existing T-bill may need to trade at a different price to remain competitive.

    This creates an important difference between selling early and holding the bill to maturity. An early sale exposes you to the price available in the secondary market at that moment. Before selling, review the quoted price, estimated proceeds, settlement details, and any applicable transaction costs.

    Beginner Tip:

    Do not compare only your original purchase price with today’s sale quote. Also consider how much time remains until maturity and whether receiving the cash now is worth giving up the remaining return.

    How Selling a Treasury Bill Before Maturity Works

    Selling a Treasury bill early is a secondary-market transaction. Instead of waiting for the bill to reach its maturity date, you sell the security through a financial institution that supports Treasury transactions. The amount you receive depends on the market price available when you sell.

    1. Check Where You Hold the T-Bill

    First, check whether your T-bill is held at TreasuryDirect or through a brokerage. TreasuryDirect does not provide a direct selling feature for marketable Treasury securities. If your bill is held there and you want to sell it early, you generally need to transfer it to a bank, broker, or brokerage account that can handle the secondary-market sale.

    2. Review the Available Sale Price

    Once the security is in an account that supports selling, the financial institution can provide the available market price and transaction details. Ask whether any commission, markup, spread, or other charge applies. These costs can reduce the amount you ultimately receive.

    3. Understand the Price Difference

    For example, suppose you purchased a T-bill for $9,700. If the current sale quote is $9,820, the quoted value is above your original purchase price before applicable costs and taxes. If the quote is $9,600, you would receive less than you originally paid.

    The result can differ because the secondary-market price changes as interest rates, demand, and other market conditions change. The closer the bill gets to maturity, the remaining time and prevailing market yields can also affect its price.

    4. Place the Sale and Wait for Settlement

    If you decide to proceed, the broker or dealer processes the sale. The cash may not be available immediately because the transaction has a settlement period. Check the expected settlement date and when the proceeds will become available in your account.

    Key Point:

    An early T-bill sale gives you access to the market before maturity, but the final proceeds depend on the quoted price, transaction costs, and settlement terms. Review all three before selling.

    Benefits and Drawbacks of Selling a Treasury Bill Early

    Selling a Treasury bill before maturity can give you more flexibility when your financial plans change. At the same time, an early sale exposes you to the current market price and possible transaction costs.

    Pros

    • Earlier access to cash: You may be able to access your money without waiting for the scheduled maturity date.
    • Greater flexibility: Selling can help if an unexpected expense changes your original plan.
    • Potential for a gain: If the market sale price is above what you paid, the sale can produce a gain before applicable costs and taxes.
    • Freedom to redirect funds: The proceeds can be used for another financial goal or investment.

    Cons

    • Market-price risk: The T-bill’s market value can be below your purchase price when you decide to sell.
    • Possible transaction costs: A broker or dealer may charge a commission, markup, spread, or other applicable fee.
    • Remaining return is no longer earned: After selling, you no longer hold the T-bill for the rest of its original term.
    • Settlement timing: The sale proceeds may not become available immediately.
    Key Point:

    The main trade-off is access versus market-price uncertainty. Before selling, consider the current sale price, time remaining until maturity, possible costs, and when you actually need the money.

    TreasuryDirect vs. Brokerage vs. Holding to Maturity

    TreasuryDirect and brokerage accounts are different ways to hold Treasury securities, while holding to maturity describes what you do with the investment. Understanding that distinction makes the early-sale process much easier to follow.

    SituationCan You Sell Early?How Is the Amount Determined?What to Know
    TreasuryDirectNot directly through TreasuryDirectA direct sale is not available on the platformA marketable security generally must be transferred to an appropriate financial institution for an early sale.
    Brokerage accountGenerally, if the firm supports secondary-market Treasury salesThe market price and transaction terms at the time of saleReview the quoted price, spread or other charges, and settlement timing.
    Hold to maturityNo sale is requiredPayment follows the Treasury bill’s terms at maturityYou keep the bill through its scheduled maturity date instead of selling it in the secondary market.
    QUICK COMPARISON:

    If you need cash before maturity, the key question is whether your financial institution can facilitate a secondary-market sale. If you keep the T-bill until maturity, you do not need to find a buyer or accept a secondary-market price.

    Costs, Risks and Expert Tips Before Selling a Treasury Bill

    Before selling a Treasury bill before maturity, do more than check the quoted price. The amount you actually receive can be affected by the market price, transaction costs, and settlement timing. A quick review of these details can help you make a more informed decision.

    Check the Total Selling Cost

    Depending on the financial institution, a Treasury transaction may involve a commission, markup, markdown, spread, or another charge. Pricing practices vary by firm. Before accepting a quote, ask how much you are expected to receive after applicable transaction costs.

    Understand Interest-Rate and Market Risk

    A T-bill’s market price can change before maturity. Interest rates are an important factor. When market yields rise, existing securities can become less attractive compared with newly issued securities, which can put downward pressure on their prices. Demand and other market conditions can also affect the price you are quoted.

    Warning:

    Do not assume that your original purchase price or the T-bill’s face value is the amount you will receive from an early sale. A secondary-market sale uses the price available when the transaction is made.

    Expert Tips Before You Sell

    • Check the remaining time until the T-bill matures.
    • Compare the current sale quote with what you originally paid.
    • Ask for the estimated net proceeds after applicable costs.
    • Confirm the settlement date if you need the money by a specific date.
    • Consider any federal tax implications that may apply to your transaction.

    Common Mistakes When Selling a Treasury Bill Early

    An early T-bill sale involves more than clicking a sell button. The market quote, transaction costs, settlement timing, and time remaining until maturity can all matter. Checking these details first can make the decision much clearer.

    Mistakes to Avoid

    • Ignoring the maturity date: If maturity is close, compare the timing of selling with your actual need for cash.
    • Looking only at the quoted price: Check whether commissions, spreads, markups, or other charges could reduce your proceeds.
    • Assuming face value is the sale price: A secondary-market sale uses the market price available at the time of the transaction.
    • Forgetting settlement timing: The day you place a sale order may not be the day the cash becomes available.
    • Overlooking tax considerations: Keep your transaction records and consider the federal tax treatment that may apply.

    A Simple Example

    For illustration, suppose Michael bought a Treasury bill for $9,700. Before maturity, he needs cash for an unexpected $9,000 expense. His brokerage shows an estimated sale value of $9,760 before any applicable transaction costs.

    Michael can review the quoted terms and decide whether to sell. If he proceeds, his final proceeds can be affected by applicable charges, and the money may not be available until settlement. If he does not need the cash immediately, he can also compare the early-sale option with keeping the T-bill until its scheduled maturity.

    SMART CHECK:

    Before selling, write down the current estimated proceeds, any applicable costs, the settlement date, and the time remaining until maturity.

    Who Should Consider Selling a Treasury Bill Early?

    An early sale may become relevant when your cash needs change before the T-bill reaches its maturity date. Instead of waiting for the scheduled payment, you can review the current market value and decide whether accessing the money now fits your plans.

    Common Situations

    • You have an unexpected expense and need access to cash before maturity.
    • A financial goal has changed since you purchased the T-bill.
    • You want to review the current market value of the security.
    • You need to redirect funds toward another financial goal or investment.

    If you do not need the money right away, look at how much time remains before maturity. Compare the current sale price, possible transaction costs, settlement timing, and the cash you expect to receive under your original maturity plan.

    SIMPLE CHECK:

    Before selling, ask: “Do I need this money before the T-bill matures?” Then compare the early-sale numbers with your original timeline.

    Frequently Asked Questions About Selling Treasury Bills Early

    1. Can you sell a Treasury bill before maturity?

    Yes. You can generally sell a Treasury bill before maturity through a bank, broker, or brokerage that supports secondary-market Treasury transactions. The price you receive depends on the market conditions when you sell.

    2. Can I sell a T-bill directly through TreasuryDirect?

    No. TreasuryDirect does not provide a direct selling feature for marketable Treasury securities. If you want to sell a TreasuryDirect-held T-bill before maturity, you generally need to transfer it to an appropriate bank, broker, or brokerage that can facilitate the transaction.

    3. Will I get the full face value if I sell a T-bill early?

    Not necessarily. An early sale takes place at the current secondary-market price. You may receive more or less than the bill’s face value or the amount you originally paid.

    4. Why can a Treasury bill’s price change before maturity?

    Market prices can change as interest rates, demand, and other market conditions change. For example, higher market yields can put downward pressure on prices of existing fixed-income securities.

    5. Are there fees when selling a Treasury bill?

    It depends on the financial institution and transaction. A broker or dealer may apply a commission, markup, markdown, spread, or another applicable charge. Review the estimated net proceeds before selling.

    6. Can I sell a Treasury bill at any time?

    You can generally sell a marketable T-bill before maturity when your financial institution can facilitate a secondary-market transaction. Available pricing, trading conditions, and settlement timing can vary.

    7. What happens to my T-bill’s return if I sell early?

    T-bills do not make periodic coupon payments. When you sell before maturity, your proceeds are based on the market sale price rather than a separate interest payment. The result can be different from the return you would have received by holding the bill to maturity.

    8. Is selling a Treasury bill before maturity taxable?

    An early sale can have federal tax consequences, including a potential gain or loss depending on the transaction and your circumstances. Keep your purchase and sale records, and consult a qualified tax professional for advice specific to your situation.

    Final Thoughts on Selling a Treasury Bill Before Maturity

    Can you sell a Treasury bill before maturity? Generally, yes. An early sale takes place through the secondary market, where the T-bill is sold at the market price available at that time. That price can be different from both your original purchase price and the bill’s face value.

    Before selling, review the current quote, any applicable transaction costs, and the expected settlement timing. It is also useful to check how much time remains until maturity and compare the cash you could receive from selling with your original investment plan.

    If you want to understand the bigger picture, our

    Treasury Bills Explained

    guide covers how T-bills work, while this article focuses on what changes when you decide to sell before maturity.

    BOTTOM LINE:

    An early T-bill sale can provide access to your money before maturity, but the proceeds depend on the market price and transaction terms when you sell.

    Have a Money Question? Keep Exploring.

    Keep learning with FinanceInvestment. Explore practical guides on Treasury bills, savings, CDs, and everyday cash decisions, and stay connected for more personal finance insights.

    📩 Get in Touch With FinanceInvestment

    Have a question or feedback about this guide? Send us an email.


    Email Us