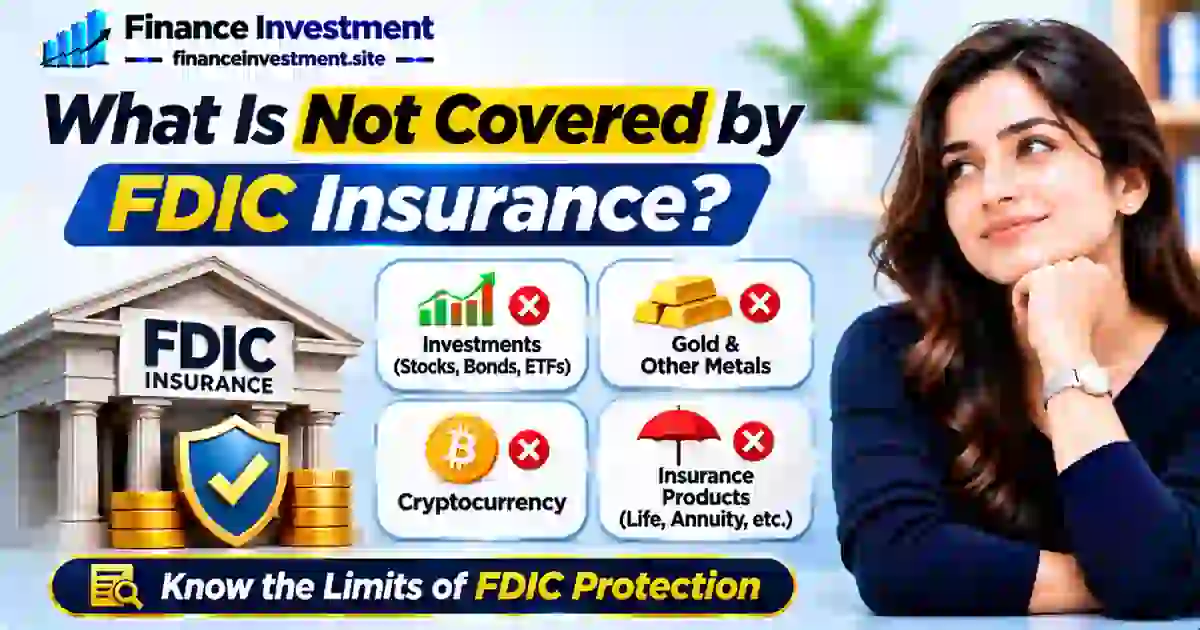
What Is Not Covered by FDIC Insurance?
 Your Bank Is FDIC-Insured. Is Everything in It Protected?
A bank can be FDIC-insured and still offer products that aren’t. That’s why the question “What Is Not Covered by FDIC Insurance?” matters before you move savings, purchase an investment or open an account through a financial app.
Suppose you keep $15,000 in a savings account and buy $5,000 in mutual funds through the same bank. Your eligible savings deposit may be insured against bank failure, while the mutual funds are not. The bank’s name doesn’t change how those products are treated.
FDIC insurance generally protects eligible deposits if an insured bank fails. It doesn’t reimburse investment losses or serve as insurance against ordinary theft and fraud. Below, we’ll explain the exclusions, coverage limits and practical checks worth making. Start with our FDIC and NCUA insurance guide if you want the full deposit-insurance basics.
What You’ll Learn
- Which investments and products fall outside FDIC coverage.
- Why bank fraud and account hacking require different protections.
- How the $250,000 limit and ownership categories work.
- How to verify deposit insurance before choosing a bank or financial app.
Quick Answer: What Doesn’t FDIC Insurance Cover?
FDIC insurance does not cover stocks, bonds, mutual funds, ETFs, annuities, crypto assets or safe-deposit-box contents. It also doesn’t insure against ordinary theft, fraud or investment losses. Deposits exceeding applicable insurance limits may be partly uninsured if a bank fails.
6 Key Takeaways
- Investments: Buying securities through an insured bank doesn’t make them FDIC-insured.
- Coverage limit: The standard limit is $250,000 per depositor, per insured bank, per ownership category.
- Fraud: Unauthorized transactions may qualify for separate consumer protections.
- Treasury securities: They aren’t FDIC-insured, but U.S. Treasury obligations have federal government backing.
- Financial apps: Coverage depends on where and how eligible deposits are actually held.
- Verification: Check the institution and account type before assuming your money is covered.
Bottom Line: FDIC insurance protects qualifying deposits against insured-bank failure—not every financial risk associated with a bank.
Table of Contents
At a Glance: What FDIC Insurance Leaves Out
A bank’s FDIC membership doesn’t extend insurance to every financial product it sells. This quick reference separates eligible deposits from investments and other risks.
Quick Facts: The standard limit is $250,000 per depositor, per insured bank, per ownership category.
Best For: Savers, investors and families checking whether a financial product qualifies for deposit insurance.
| Product or Situation | FDIC Treatment |
|---|---|
| Checking, savings, bank CDs | Eligible deposits insured within applicable limits |
| Stocks, ETFs, mutual funds | Not FDIC-insured |
| Deposits above coverage limits | Excess amount uninsured |
| Fraud or account hacking | Not an FDIC-insured event; other protections may apply |
| U.S. Treasury securities | Not FDIC-insured; backed by the U.S. government |
Quick Take: Check both the account type and the institution holding the funds. A familiar bank name alone isn’t proof that a product is insured.
What FDIC Insurance Doesn’t Cover: A Beginner’s Guide
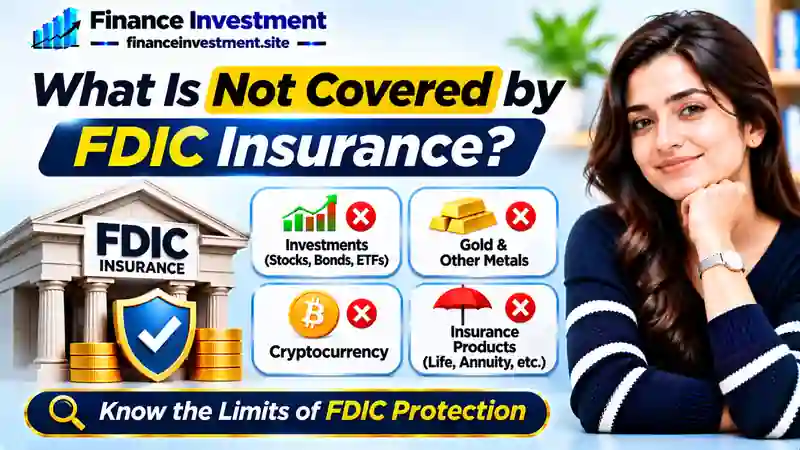
A bank can offer both insured deposits and uninsured financial products. The distinction matters because FDIC protection follows the type of account or product—not the logo on the building.
Investments and Insurance Products
Stocks, corporate bonds, mutual funds, ETFs, annuities and life insurance policies aren’t FDIC-insured. Neither are U.S. Treasury securities, although Treasury obligations carry federal government backing. Buying any of these through a bank doesn’t turn them into insured deposits.
Crypto Assets and Safe-Deposit Boxes
Cryptocurrency isn’t protected by FDIC deposit insurance. The contents of a safe-deposit box—including cash, jewelry or documents—also fall outside coverage. A box rental agreement isn’t the same as a bank deposit.
Balances Above Applicable Limits
Eligible deposits can still be partly uninsured when combined balances exceed the applicable limit. Opening several accounts in the same ownership category at one insured bank doesn’t automatically increase coverage.
For ways to manage larger balances, read how to protect more than $250,000.
How It Works: Bank Failure vs. Fraud vs. Investment Loss
Losing money in a bank failure isn’t the same as losing it to a scam or a falling investment. Each situation follows different rules.
When an Insured Bank Fails
When regulators close an FDIC-insured bank, the FDIC may transfer deposits to another institution or arrange payment of insured balances. The outcome depends on the resolution and applicable coverage limits. Read how FDIC bank account transfers work.
When Money Is Stolen or an Account Is Hacked
FDIC deposit insurance doesn’t reimburse fraud losses. Certain unauthorized electronic transfers may be covered by consumer protections under Regulation E, subject to its requirements and reporting rules. Payments you knowingly authorize during a scam may be treated differently. Our unauthorized transfer dispute guide explains the next steps.
When an Investment Falls in Value
FDIC insurance doesn’t reimburse market losses. SIPC protection at an eligible brokerage may address missing customer securities or cash when a brokerage fails, but it doesn’t protect against investments losing value.
FDIC Insurance: Benefits and Coverage Limitations
Deposit insurance can protect your savings when an insured bank closes. But its protections are specific, and some financial risks fall outside its scope.
✓ What FDIC Insurance Does Well
- Covers eligible deposits when an FDIC-insured bank fails.
- Applies automatically to qualifying deposits without an insurance application.
- Provides separate coverage for eligible ownership categories under FDIC rules.
✕ Where Coverage Stops
- Doesn’t insure securities or investment market losses.
- Doesn’t cover ordinary theft, scams or account hacking.
- Leaves deposits above applicable insurance limits uninsured.
Practical takeaway: Use FDIC coverage for deposit protection, account security measures for fraud risks and appropriate investment planning for market risks.
FDIC Coverage Comparison: Insured Deposits vs. Excluded Products
Some financial products look similar on a bank’s website but receive very different protections. Check the product type and the institution legally holding your funds.
| Product | FDIC Coverage | Important Condition |
|---|---|---|
| Checking and savings accounts | Eligible | Held at an FDIC-insured bank; subject to applicable limits |
| Bank CDs and money market deposit accounts | Eligible | Must qualify as deposits at an insured institution |
| Brokered CDs | May qualify | Issuing bank, ownership and recordkeeping requirements matter |
| Cashier’s checks and bank-issued money orders | Generally eligible | Qualifying bank obligations; ownership and limits apply |
| Stocks, ETFs and mutual funds | Not covered | Investments, even when sold through a bank |
| Money market mutual funds | Not covered | Investment funds, not bank deposit accounts |
| Crypto assets and annuities | Not covered | Not qualifying FDIC-insured deposits |
| U.S. Treasury securities | Not covered | U.S. government obligations, not FDIC-insured deposits |
Important distinction: A bank money market deposit account isn’t the same as a money market mutual fund. See our money market account vs. money market fund guide before comparing their protections.
Costs, Insurance Gaps & Practical Protection Tips
You don’t pay a separate FDIC insurance premium on an eligible bank deposit. Banks fund the insurance system, although their accounts may still charge service fees or impose CD early-withdrawal penalties.
Check Where Your Money Is Actually Held
Balances above applicable limits can leave money uninsured. Financial apps add another question: Is your money an eligible deposit at an FDIC-insured partner bank, and do the records support any claimed pass-through coverage? Read our fintech deposit insurance guide.
Expert Tip: Confirm the bank’s insurance status, identify the legal account owner and add together deposits held in the same ownership category. Our FDIC verification guide can help with the first step.
Important Warning: An FDIC-insured partner bank doesn’t automatically insure losses caused by a fintech company’s failure, operational problems or inaccessible app funds. FDIC protection generally responds to the failure of the insured bank itself.
Common FDIC Insurance Mistakes to Avoid
FDIC coverage mistakes often happen when people focus on account names rather than how their money is legally held.
- Assuming every account gets $250,000: Deposits in the same ownership category at one insured bank are generally combined.
- Confusing investments with deposits: Mutual funds remain uninsured even when purchased through a bank.
- Expecting FDIC reimbursement for fraud: Unauthorized transactions involve separate legal protections.
- Trusting a fintech insurance claim without checking: Partner-bank arrangements and records determine whether eligible deposit coverage applies.
Hypothetical Example: A $300,000 Portfolio
Imagine one person holds $200,000 in savings and $50,000 in checking at the same FDIC-insured bank, both under single ownership. They also own $50,000 in mutual funds.
FDIC-insured deposits: $250,000, assuming no other deposits in that ownership category at the bank and all eligibility requirements are met.
Not FDIC-insured: The $50,000 mutual fund investment. Its value remains subject to investment risks, regardless of where it was purchased.
Who Should Pay Extra Attention to FDIC Coverage?
Anyone with bank deposits benefits from understanding FDIC insurance. Some households, however, have more complicated balances or account arrangements worth reviewing.
- Families and couples: Joint and individual accounts may qualify for different ownership-category limits when FDIC requirements are satisfied.
- Retirees: Large cash reserves, matured CDs or proceeds from selling property can temporarily increase uninsured balances.
- Investors: Cash deposits and securities held through financial institutions may receive different forms of protection.
- Fintech users: App balances deserve closer examination when funds pass through intermediary companies or partner banks.
Helpful next step: Review account ownership and combined balances before assuming everything is insured. Our FDIC insurance for joint accounts guide explains an important distinction.
Frequently Asked Questions About FDIC Insurance Exclusions
1. Are stocks and mutual funds FDIC-insured?
No. Stocks, mutual funds and ETFs aren’t insured bank deposits, even when purchased through a bank.
2. Does FDIC insurance cover money stolen by hackers?
No. FDIC insurance doesn’t reimburse hacking losses. Separate consumer protections may apply to qualifying unauthorized electronic transfers, depending on the circumstances and reporting requirements.
3. Is cryptocurrency protected by FDIC insurance?
No. Cryptocurrency isn’t an FDIC-insured deposit. A crypto platform’s relationship with an insured bank doesn’t automatically protect crypto holdings.
4. Are U.S. Treasury bills FDIC-insured?
No. Treasury bills are obligations of the U.S. government, backed by its full faith and credit rather than FDIC deposit insurance.
5. Does FDIC insurance cover balances above $250,000?
Not automatically. The standard limit is $250,000 per depositor, per insured bank, per ownership category. Deposits above applicable limits may be uninsured.
6. Are money market accounts and funds treated the same?
No. Eligible money market deposit accounts at insured banks can receive FDIC coverage. Money market mutual funds cannot.
7. Does an FDIC-insured partner bank protect every fintech balance?
No. Coverage depends on eligible deposits, how funds are held and applicable recordkeeping requirements. The fintech company’s failure itself isn’t an FDIC-insured event.
8. Are items in a bank safe-deposit box insured by the FDIC?
No. FDIC insurance doesn’t cover cash, jewelry, documents or other property stored inside a safe-deposit box.
Final Verdict: Understand Where FDIC Protection Ends
FDIC insurance protects eligible deposits when an insured bank fails—not investments, cryptocurrency or property stored in safe-deposit boxes. It also doesn’t reimburse fraud losses, although separate consumer protections may apply to certain unauthorized transactions.
Before placing substantial funds in any account, verify the bank’s insurance status, review ownership categories and calculate combined deposits. Amounts above applicable limits may remain uninsured.
Continue learning: Our FDIC and NCUA insurance explained guide explores federal deposit protection at banks and credit unions.
Have a Money Question? Keep Exploring.
Understanding FDIC insurance exclusions is one step toward protecting your savings. Before opening an account or moving a large balance, explore these practical guides.
How to Verify FDIC Insurance
Protect Deposits Above $250,000
📩 Get in Touch With FinanceInvestment
Disclaimer: For educational purposes only; not personalized financial, legal or investment advice. Confirm applicable deposit insurance rules with the FDIC before making financial decisions.
Leave a Reply