How to Build a Treasury Bill Ladder
How to Build a Treasury Bill Ladder: A Simple Starting Point
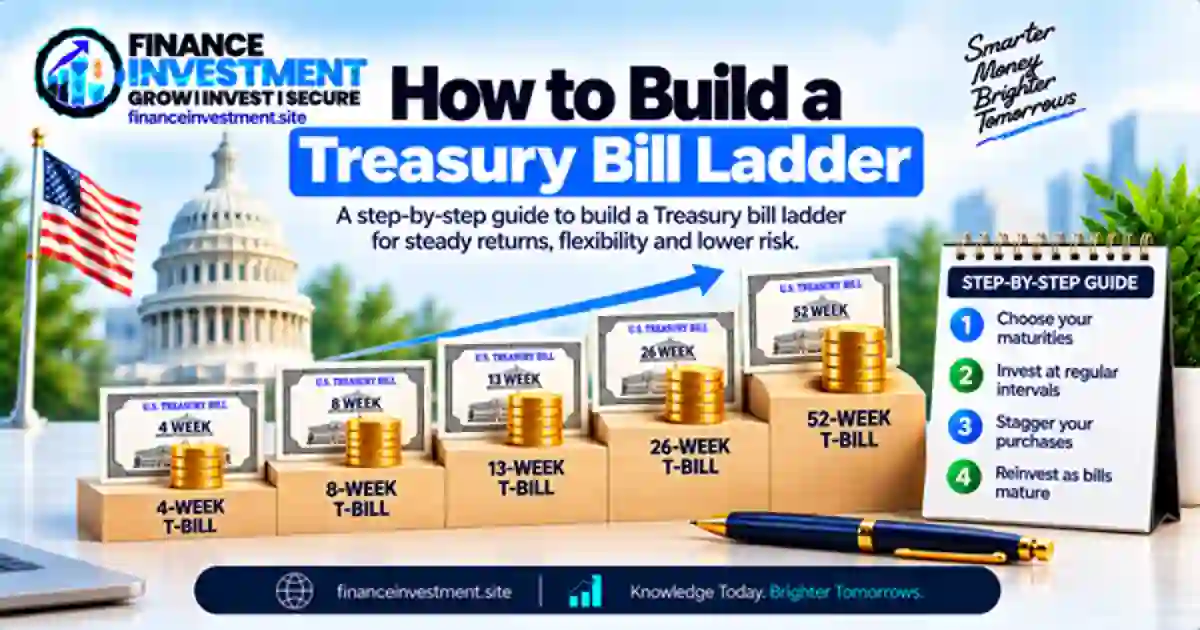 How to Build a Treasury Bill Ladder is easier to understand when you look at the timing of your cash. Instead of putting all your money into one Treasury bill with a single maturity date, a ladder spreads purchases across several maturity dates. As one bill matures, that cash becomes available while the other bills continue toward their own maturity dates.
This approach can give you a more organized way to manage short-term money. For instance, you may want part of your savings to become available every few months instead of having everything mature at once. The right setup depends on your starting amount, expected cash needs, and the Treasury bill maturities available when you invest.
If Treasury bills are still new to you, begin with our Treasury Bills Explained guide. It covers the basics of T-bills, including how they work and mature. Here, we’ll focus on turning individual Treasury bills into a simple ladder you can manage over time.
What You’ll Learn
- What a Treasury bill ladder is and how the strategy is structured.
- How to choose maturity dates around your expected cash needs.
- How to divide money among different T-bill maturities.
- What happens when one bill reaches maturity.
- How reinvesting can keep a ladder going over time.
- What to consider before selling a T-bill before maturity.
- Common mistakes that can make a ladder difficult to manage.
The idea is straightforward: give different portions of your cash different maturity dates. Once the schedule is set up, you can decide whether each maturity should be spent, held in cash, or reinvested.
Quick Answer: How to Build a Treasury Bill Ladder
A Treasury bill ladder uses multiple T-bills with different maturity dates. You start by identifying when you may need your money, choose maturities that fit that timeline, divide your cash among the purchases, and keep track of each maturity. When a bill matures, you can use the proceeds or reinvest them, depending on your next cash need.
Key Takeaways
- Spread maturity dates: Instead of having all your money mature at once, you create several maturity points.
- Plan around your cash needs: Your expected spending dates should guide the ladder more than a particular maturity schedule.
- Divide the investment: You can allocate different amounts to different T-bills rather than committing everything to one purchase.
- Decide what happens at maturity: Each maturity can provide cash for spending or become the starting point for another T-bill purchase.
- Understand early sales: A marketable T-bill can generally be sold before maturity, but its market price may be different from what you paid.
- Expect changing yields: Reinvesting later may produce a different return because Treasury market rates can change.
- Track the schedule: Recording purchase amounts and maturity dates can make the ladder much easier to manage.
BOTTOM LINE: A T-bill ladder is a way to organize short-term Treasury investments around future cash needs. The important part is not simply buying several bills. It is choosing maturity dates and amounts that make sense for your own timeline.
Table of Contents
Treasury Bill Ladder at a Glance
A Treasury bill ladder is a group of T-bills arranged with different maturity dates. Instead of having all your money tied to one maturity, you spread purchases across a schedule. When each bill matures, its proceeds become available for spending or another investment.
Investors who want to spread short-term cash availability across several planned maturity dates.
Treasury bills have maturities of one year or less. The number of rungs in your ladder depends on your cash needs and investment amount.
| Feature | What It Means |
|---|---|
| Structure | Multiple T-bills with maturity dates spread across a chosen schedule |
| Starting point | Identify your expected cash needs and decide how much money to allocate |
| Maturity | Each T-bill reaches maturity on its own scheduled date |
| When a bill matures | You can use the proceeds for a planned expense or consider reinvesting them |
| Early sale | A marketable T-bill can generally be sold before maturity, but its market price may differ from the purchase price |
| Tax treatment | T-bill interest is generally subject to federal income tax but exempt from state and local income taxes |
QUICK TAKE: Think about the dates first. A useful ladder starts with when you expect to need your cash, then works backward to the T-bill maturities and amounts that fit those needs.
Treasury Bill Ladder: A Complete Beginner Guide
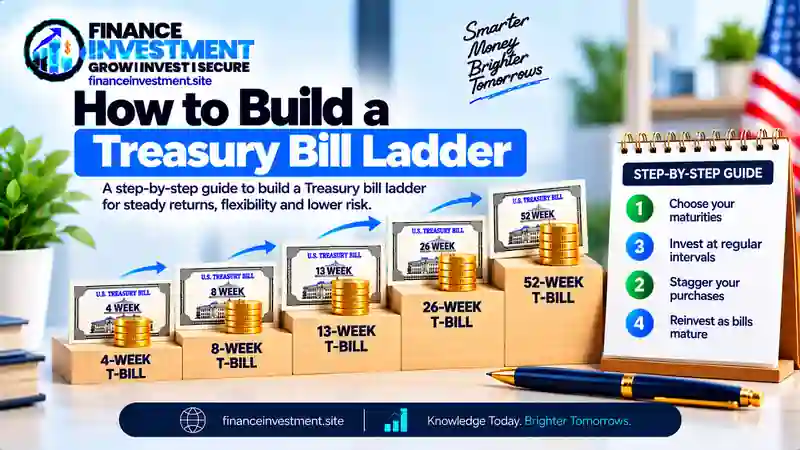 For a first-time investor, a Treasury bill ladder may sound more complicated than it really is. At its core, you are combining several T-bill purchases so that they reach maturity on different dates. That gives you a planned sequence of future cash availability.
What Is a Treasury Bill Ladder?
Suppose you have $20,000 that you do not expect to use immediately. You could put the entire amount into one T-bill. Another approach is to divide the money among several T-bills with different maturity dates. The result is a series of dates when portions of the investment can become available.
Start With Your Cash Timeline
The first question is not, “Which T-bill has the highest yield?” It is, “When might I need this money?” A planned tax payment, tuition bill, home repair, travel expense, or other short-term goal can help you decide when individual rungs should mature.
What Is a Ladder Rung?
Each T-bill in the arrangement can be thought of as one rung. The rungs do not have to contain equal amounts. You can allocate more money to a maturity that matches a larger upcoming expense and less to another. When a bill matures, you can use the proceeds or decide whether to replace that rung with a new T-bill.
BEGINNER TIP: Your first ladder does not need to be elaborate. A small number of clearly planned rungs can make it easier to track maturity dates, cash needs, and reinvestment decisions.
How to Build a Treasury Bill Ladder
A workable ladder starts with your cash calendar. Once you know how much money you can set aside and when you may need it, you can choose T-bill maturities and assign an amount to each one.
1. Set Aside the Right Amount
Use money intended for short-term investing rather than cash needed for everyday bills. Keep your immediate spending needs and emergency reserves separate. This helps prevent an unexpected expense from forcing you to sell a T-bill before maturity.
2. List Your Expected Cash Dates
Write down upcoming expenses and the approximate dates when you may need the money. A home project, tuition payment, tax bill, or planned purchase can give you a useful target for one or more maturities.
3. Match T-Bill Maturities to Your Timeline
Treasury bills come in several short-term maturities. Select the available maturities that fit your schedule rather than copying someone else’s ladder. If you need a refresher on the purchase process, see our guide to buying Treasury bills.
4. Assign an Amount to Each Rung
You can divide the money evenly or use different amounts. For example, a larger upcoming expense may justify a larger allocation to the T-bill maturing around that time. The important point is to make the amounts fit your actual cash plan.
5. Decide What Happens at Maturity
Each maturity creates a decision point. If you need the money, use the proceeds for the planned expense. If you do not, you can consider reinvesting them into another T-bill. Reinvestment can keep the ladder running, but the new T-bill’s yield may differ from the rate available when you made the original purchase.
SIMPLE EXAMPLE: Suppose you have $20,000 for short-term goals. You could split it across several T-bills with different maturity dates. When the first bill matures, you decide whether to spend that cash or buy a replacement T-bill. That decision can then be repeated as the next rungs mature.
Treasury Bill Ladder: Benefits and Drawbacks
A Treasury bill ladder can bring structure to short-term cash management, but it is not a set-it-and-forget-it strategy. Its usefulness depends on how well the maturity schedule fits your goals. Before building one, consider both the advantages and the trade-offs.
- Staggered access: Different maturity dates can provide several planned opportunities to access cash.
- Goal-based planning: You can align individual T-bills with known or expected short-term expenses.
- Reinvestment flexibility: At maturity, you can use the proceeds or evaluate another Treasury investment.
- Government obligation: T-bills are direct obligations of the U.S. government, subject to the government’s ability to meet its obligations.
- More recordkeeping: Multiple T-bills mean more purchase details and maturity dates to monitor.
- Changing reinvestment rates: The yield available when a bill matures may be higher or lower than your original yield.
- Market-price risk before maturity: If you sell a marketable T-bill before maturity, its price can be different from what you paid.
- Planning risk: A poorly timed ladder may not provide cash exactly when an expense is due.
KEY POINT: The goal of a ladder is not to create as many maturity dates as possible. A practical ladder uses a manageable number of rungs that fit your expected cash needs and your willingness to reinvest.
Treasury Bill Ladder Comparison
A Treasury bill ladder can be structured in different ways. The main difference is how you divide the money and what you plan to do when each bill matures. The table below compares four common approaches without assuming that one structure works for every investor.
| Structure | How It Works | Main Planning Focus |
|---|---|---|
| Single T-bill | Most or all of the money is placed into one T-bill maturity. | One primary maturity date. |
| Equal-rung ladder | Similar amounts are divided among T-bills with staggered maturity dates. | Keeping the schedule simple and consistent. |
| Goal-based ladder | Amounts and maturity dates are selected around specific expected cash needs. | Matching proceeds with planned expenses. |
| Rolling ladder | When a T-bill matures, its proceeds may be used to purchase another T-bill and extend the schedule. | Maintaining an ongoing short-term investment cycle. |
QUICK TAKE: The structure should follow your purpose. A simple equal-rung schedule may be easier to track, while a goal-based ladder gives you more flexibility when future expenses vary in size or timing.
Treasury Bill Ladder: Costs, Risks and Expert Tips
A Treasury bill ladder does not require complicated maintenance, but you still need to consider purchase costs, market prices, reinvestment rates, and the timing of your cash needs. Understanding these details can help you avoid building a ladder that looks organized but does not fit your actual financial schedule.
Potential Costs
- TreasuryDirect purchases: TreasuryDirect does not charge a fee or commission for purchasing Treasury securities directly through the platform.
- Brokerage costs: A broker may have its own commissions, spreads, markups, markdowns, or other transaction-related costs. Review the broker’s current pricing before placing an order.
- Management effort: A ladder with several rungs requires you to keep track of purchase amounts, maturity dates, and what you want to do with each maturity.
Key Risks
- Early-sale price risk: If you sell a marketable T-bill before maturity, its market price may be above or below the amount you paid.
- Reinvestment risk: When a T-bill matures, the yield available on a replacement bill may be different from the yield on your original investment.
- Cash-flow risk: If a maturity date does not line up with an upcoming expense, you may need another source of cash or may have to consider selling a bill early.
- Opportunity cost: Money committed to a ladder may not be available for another investment or financial goal during the selected maturity period.
EXPERT TIP: Build the ladder around your expected cash-flow dates first. Then compare available maturities, yields, and purchase costs. If you use a brokerage account, check its current fee schedule and understand how the broker handles Treasury purchases and secondary-market sales.
Common Treasury Bill Ladder Mistakes and an Illustrative Example
A Treasury bill ladder can be easy to understand but still easy to mismanage. The most common problems usually come from building the schedule without considering when the money will actually be needed.
Common Mistakes to Avoid
- Choosing maturities by yield alone: A higher yield may not be useful if the maturity date does not fit your cash needs.
- Investing money you may need soon: Keep money for immediate expenses and emergencies accessible rather than automatically adding it to the ladder.
- Making every rung the same size: Equal allocations are simple, but your future expenses may not be equal.
- Skipping the maturity plan: Decide in advance whether each maturity is likely to be spent, held as cash, or considered for reinvestment.
- Assuming the same yield will continue: Future T-bill yields can change, so a replacement bill may have a different return.
Illustrative Example: A $30,000 Ladder
Consider a hypothetical investor with $30,000 available for several short-term goals. Instead of placing the entire amount into one T-bill, the investor could divide the money among several T-bills with staggered maturity dates. The actual amounts and maturities would depend on the investor’s expected cash needs.
If one maturity is scheduled around a planned expense, those proceeds could be used for that expense. The remaining T-bills could continue until their own maturity dates. At each maturity, the investor can reassess the next step rather than automatically reinvesting every dollar.
KEY LESSON: A useful ladder connects three things: how much money you have available, when you expect to need it, and what you plan to do when each T-bill matures. The schedule should serve your cash needs rather than exist simply for the sake of having multiple rungs.
Who Should Consider a Treasury Bill Ladder?
A Treasury bill ladder is generally designed for short-term money that has a planned timeline. It can be useful when you want several T-bills to mature at different points instead of having one maturity date for the entire amount.
A Ladder May Fit Your Situation If You:
- Have money available for goals that are months away rather than immediate expenses.
- Expect to need portions of your savings at different times.
- Want to organize several T-bill maturities around a cash-flow schedule.
- Are comfortable keeping track of multiple purchase and maturity dates.
- Want to make a fresh decision whenever a T-bill matures.
A Ladder May Be Less Suitable If You:
Need the money available at any time, do not want to monitor multiple securities, or are investing for a goal that requires a longer time horizon. A ladder also should not replace an appropriate emergency cash reserve or money needed for near-term bills.
Frequently Asked Questions About Treasury Bill Ladders
1. What is a Treasury bill ladder?
A Treasury bill ladder is a strategy that uses multiple T-bills with different maturity dates. Instead of having the entire investment mature at one time, portions of the money become available according to a planned schedule.
2. How do I build a Treasury bill ladder?
Start by deciding how much money you can allocate and when you may need it. Then select available T-bill maturities, divide the money among the purchases, record the maturity dates, and decide whether to use or reinvest each maturity.
3. How many T-bills should be in a ladder?
There is no standard number of rungs. The appropriate number depends on your investment amount, expected cash needs, preferred maturity spacing, and how much activity you want to manage.
4. What happens when a T-bill in the ladder matures?
At maturity, the Treasury pays the bill according to its terms. For a typical discount T-bill, you receive its face value at maturity. You can then use the proceeds for a planned expense or consider reinvesting them.
5. Can I sell a T-bill before it matures?
Marketable T-bills can generally be sold before maturity through a brokerage or other appropriate secondary-market channel. The market price at the time of sale can be higher or lower than your purchase price, so the amount you receive may differ from the amount originally invested.
6. Are Treasury bills FDIC insured?
No. Treasury bills are not FDIC-insured bank deposits. They are direct debt obligations of the U.S. government, subject to the government’s ability to meet its obligations.
7. Are Treasury bill earnings exempt from state income tax?
Generally, interest income from U.S. Treasury bills is subject to federal income tax but exempt from state and local income taxes. Individual tax situations can vary, so review your circumstances with a qualified tax professional when appropriate.
8. Should I reinvest every maturing T-bill?
Not necessarily. You can use the proceeds for a planned expense, keep the money available for another goal, or consider buying another Treasury security. The decision depends on your cash needs, the available yields, and your overall financial plan.
Final Comparison: How to Build a Treasury Bill Ladder
A Treasury bill ladder is ultimately a way to organize short-term money around future dates. The structure you use should reflect how often you expect to need cash, how much you want to invest, and whether you plan to spend or reinvest the proceeds when each T-bill matures.
| Planning Question | What to Consider |
|---|---|
| When will I need the money? | Use expected cash-flow dates to help determine when individual T-bills should mature. |
| How much should each rung contain? | Equal amounts can simplify tracking, while different amounts may better match expenses of different sizes. |
| What happens at maturity? | Decide whether to use the proceeds, hold the cash for another goal, or consider reinvesting. |
| Could my plans change? | Leave enough flexibility so an unexpected cash need does not force an unnecessary early sale. |
FINAL TAKEAWAY: A well-planned T-bill ladder starts with your cash-flow needs, not with the number of rungs. Choose maturities and investment amounts that you can comfortably track, then reassess the plan whenever a bill matures or your financial needs change.
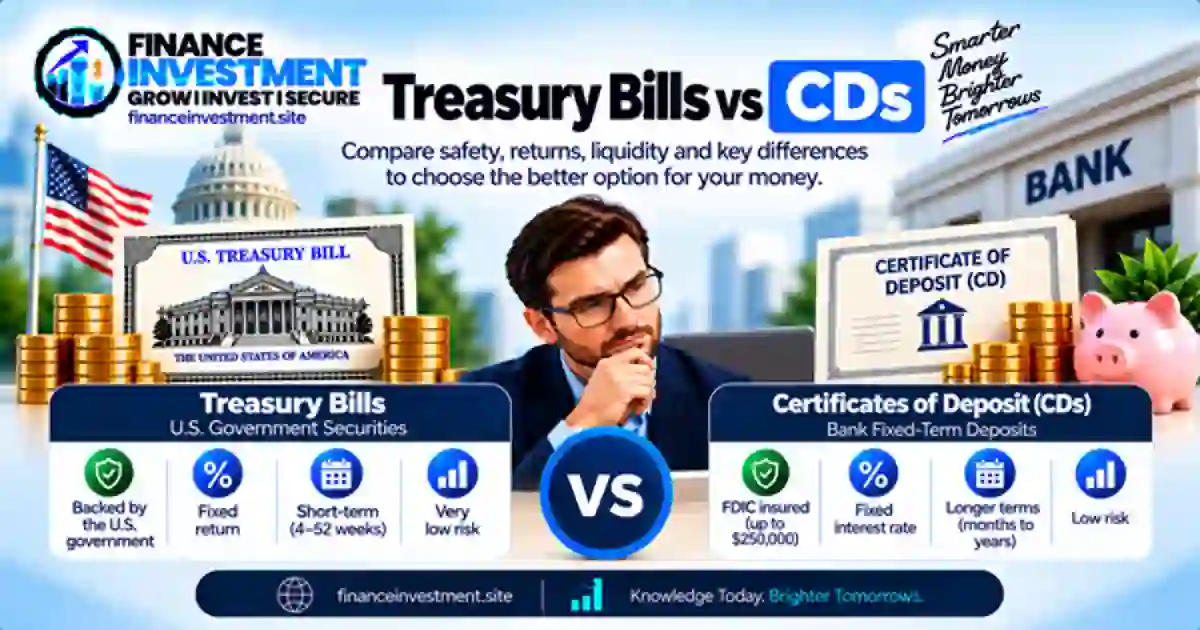
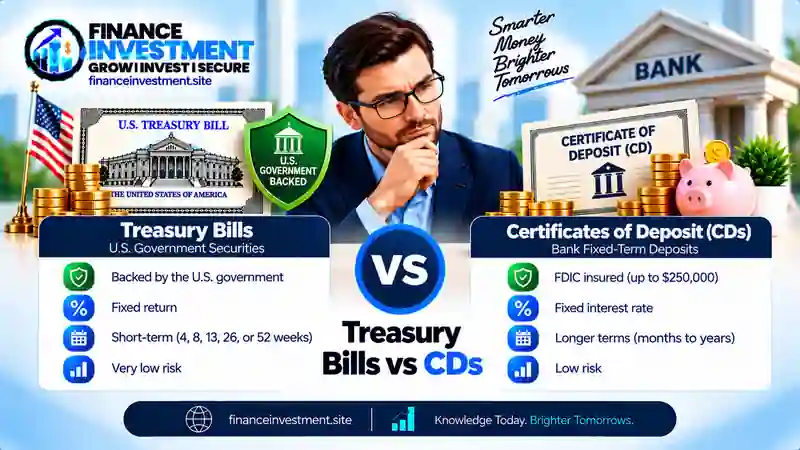 If you’re new to Treasury Bills vs CDs, start with the basic difference. A Treasury bill is a short-term U.S. government security. A CD is a time deposit offered by a bank or credit union. Both can be used for money you expect to keep relatively stable, but the way you earn and access that money is different.
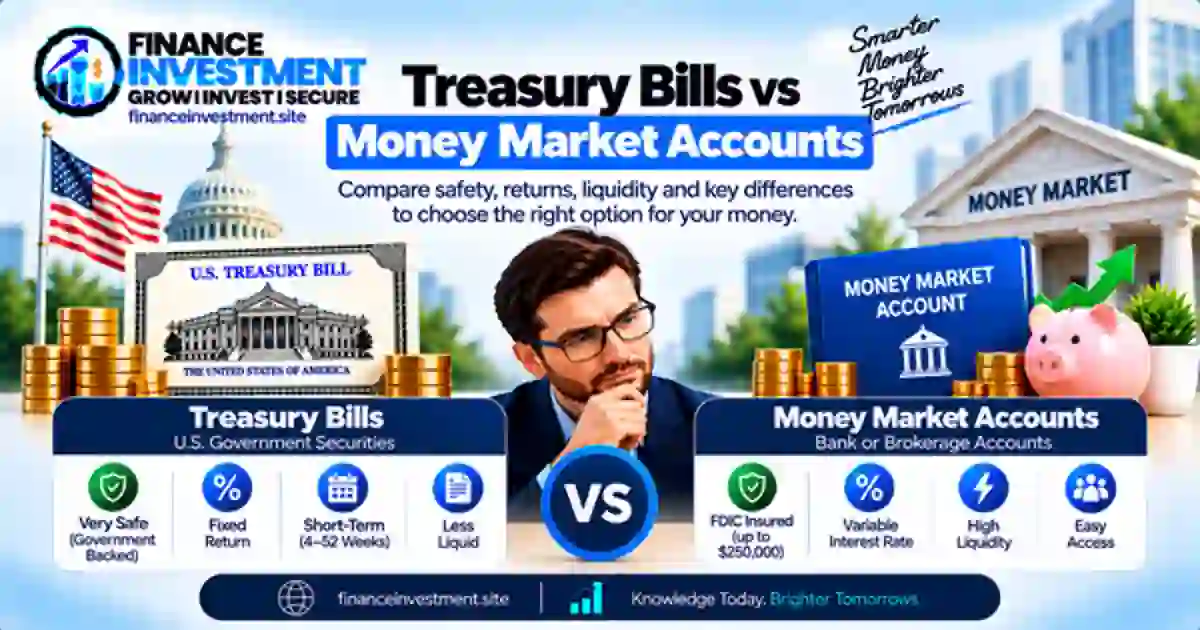
 If you’re new to this comparison, start with one simple question: what exactly is your money buying? A Treasury bill buys a short-term U.S. government security. A money market account keeps your money in a deposit account at a bank or a share account at a credit union.
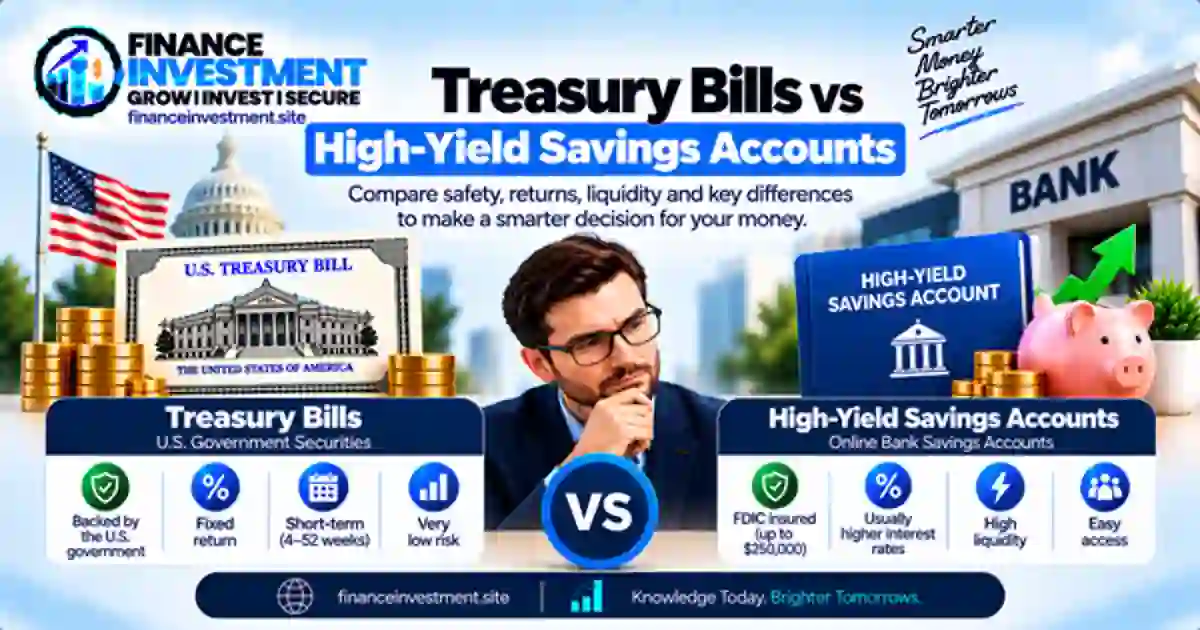
 If you’re new to this comparison, begin with one practical question: when might you need this money? A high-yield savings account keeps your cash in a bank deposit, while a Treasury bill places it in a short-term U.S. government security. That basic difference explains much of the comparison.
 If you’re new to this comparison, start with one simple question: Where is your money actually going? That answer makes the difference between a Treasury bill and a savings account much easier to understand.
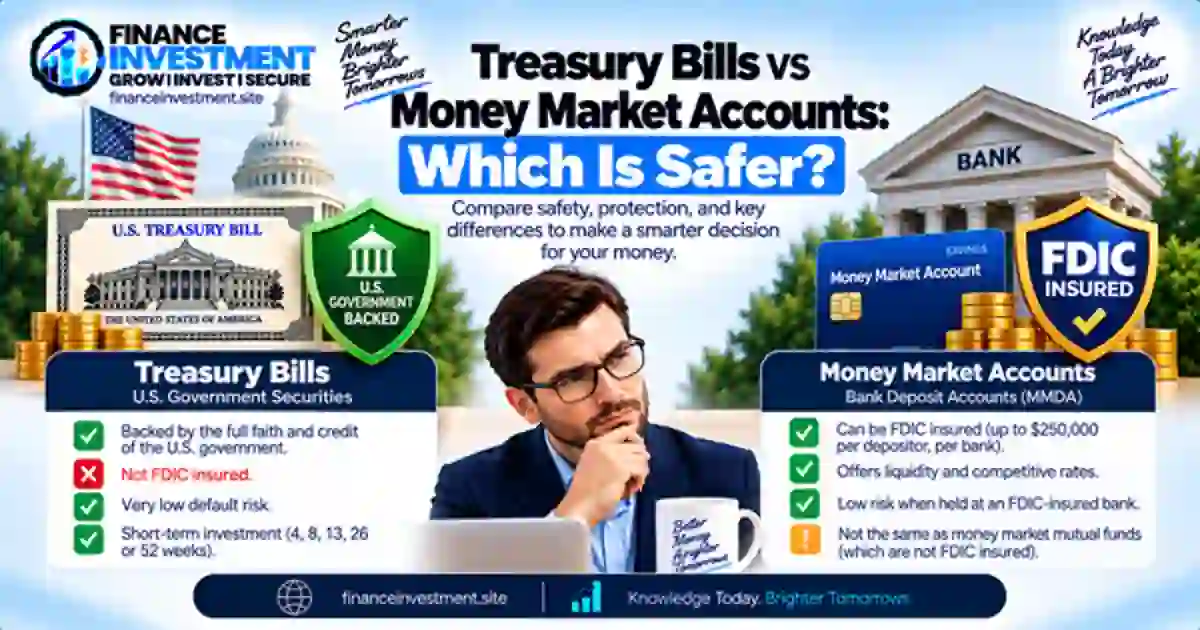
 Before comparing safety, it helps to understand what you actually own. Treasury bills and money market accounts can both be used for short-term cash, but they are different financial products. One is a U.S. government security, while the other is a deposit account.