Tag: Short-Term Investing

  • What Happens When a Treasury Bill Matures? A 2026 Guide

    What Happens When a Treasury Bill Matures? A 2026 Guide

    What Happens When a Treasury Bill Matures?

    SR
    Subhash Rukade
    Founder, FinanceInvestment


    Updated: September 17, 2026


    Reading Time: ~11 minutes

    When a Treasury Bill Reaches Maturity

    What Happens When a Treasury Bill Matures?What happens when a Treasury bill matures? For most investors, the process is straightforward. The bill reaches its maturity date, and the U.S. Treasury pays its face value according to the security’s terms. If you purchased the bill for less than its face value, the difference represents your return.

    The bigger question comes next. Once the money becomes available, you can use the proceeds, move the cash to another account, or reinvest in another Treasury bill. The right choice depends on when you need the money, what yields are available, and how long you want to keep your cash invested.

    So, the maturity date is not simply the finish line. It is also a natural point to review your next move. Our Treasury Bills Explained guide covers the broader topic, while this article focuses on the practical steps that follow maturity.

    What You’ll Learn

    • What happens on the Treasury bill maturity date
    • How the maturity payment works
    • What happens when you reinvest the proceeds
    • What to know about taxes and timing
    • How to think about your next use of the money

    Quick Answer: What Happens at T-Bill Maturity?

    When a Treasury bill reaches its maturity date, the bill’s term ends and the Treasury pays its face value according to the security’s terms. Because T-bills are generally bought at a discount, the difference between the purchase price and the face value represents the investor’s return. Once the proceeds are received, you can use the cash or consider another investment.

    Key Takeaways

    • The maturity date marks the end of the T-bill’s stated term.
    • The Treasury pays the bill’s face value at maturity.
    • The return generally comes from purchasing the bill below face value.
    • After maturity, you can use, transfer, or reinvest the proceeds.
    • TreasuryDirect offers reinvestment options for eligible Treasury bills.
    • Federal income tax generally applies to Treasury interest, while state and local income taxes generally do not.
    Bottom Line:

    Treasury bill maturity gives you a clear decision point. You can take the proceeds, put the money toward a goal, or reinvest it based on your current cash needs.

    Treasury Bill Maturity at a Glance

    When a Treasury bill matures, its scheduled term ends and the Treasury makes the maturity payment according to the bill’s terms. If you purchased the bill at a discount, the difference between your purchase price and its face value generally represents your return.

    Quick FactWhat It Means
    Maturity dateThe date when the Treasury bill reaches the end of its stated term
    Maturity paymentThe bill’s face value is paid according to its terms
    Investor returnGenerally the difference between the purchase price and face value
    After maturityUse the proceeds, move the cash, or consider another investment
    Best forInvestors planning for a future cash need or deciding what to do with the proceeds
    QUICK TAKE:

    Maturity is a natural checkpoint for your cash plan. Once the bill reaches its end date, the next decision is what you want to do with the proceeds.

    Complete Beginner Guide to Treasury Bill Maturity
    What Happens When a Treasury Bill Matures?If you are new to Treasury bills, maturity is simply the point when the bill’s stated term ends. You purchase the bill, hold it during the term, and receive its face value at maturity according to its terms. Because T-bills are generally issued at a discount, the amount you paid can be lower than the amount you receive.

    What Happens While You Hold the Bill?

    Treasury bills do not make regular coupon payments. Instead, the return is generally built into the purchase price. For example, if a bill has a $1,000 face value and you pay $970, the $30 difference represents the return before applicable taxes.

    You can hold the bill until its maturity date. If you need the money sooner, you may be able to sell the security through a bank or brokerage that supports Treasury securities. However, the market price can change before maturity, so the amount you receive from an early sale may be different from what you originally paid.

    What Happens When the Bill Matures?

    On the maturity date, the Treasury bill reaches the end of its term and the Treasury makes the scheduled payment. After the proceeds become available, you can use the money for a financial goal, move it to another cash account, or put it into another investment.

    Can You Reinvest the Proceeds?

    Yes. TreasuryDirect allows eligible Treasury bill investments to be scheduled for reinvestment. This can make it easier to continue a short-term Treasury strategy without manually starting from scratch each time.

    Beginner Tip:

    Check your maturity date before buying and decide in advance what you want the proceeds to do. That simple step can prevent a last-minute cash decision.

    What Happens When a Treasury Bill Matures?

    When a Treasury bill matures, its stated term ends. If you have held the bill until maturity, you generally do not need to sell it. Instead, the Treasury makes the scheduled maturity payment based on the bill’s face value and terms. Your original purchase price determines how much you invested, while the difference generally represents your return.

    1. The Bill Reaches Its Maturity Date

    Every Treasury bill has a specific maturity date established when it is issued. On that date, the bill reaches the end of its term. For example, if you purchased a $1,000 face-value T-bill for $970 and held it to maturity, the scheduled payment is based on the $1,000 face value. The $30 difference is the return before applicable taxes.

    2. The Maturity Proceeds Are Credited

    Where the money goes depends on how you purchased and hold the bill. With TreasuryDirect, maturity proceeds are handled through your TreasuryDirect account according to the applicable instructions. With a brokerage, the proceeds are generally reflected in the brokerage account under that firm’s procedures.

    3. You Choose What to Do Next

    Once the proceeds are available, you can use the money for a planned expense, move it to an appropriate cash account, or consider another investment. If your goal has changed since you bought the T-bill, maturity gives you a natural opportunity to reassess your cash needs.

    4. Reinvestment Starts a New Investment

    Eligible TreasuryDirect Treasury bills can be scheduled for reinvestment. A reinvestment means the proceeds are used to purchase another Treasury bill when the new bill is issued. The new bill has its own maturity date and auction-determined terms, so its yield may differ from the original investment.

    Key Point:

    Maturity does not automatically mean you must invest again. Your original T-bill ends, the maturity proceeds are handled through your account, and you then decide whether to spend, save, or reinvest the money.

    Benefits and Drawbacks of Treasury Bill Maturity

    A maturing Treasury bill gives you a defined point at which the investment ends and the proceeds can be redirected. That can make planning easier, but there are still a few trade-offs to consider before deciding what to do next.

    Pros

    • Defined maturity date: You know when the bill is scheduled to reach the end of its term.
    • Predictable maturity value: When held to maturity, the Treasury pays the bill’s face value according to its terms.
    • Useful for planning: The maturity date can be matched with a known future cash need.
    • Reinvestment available: Eligible TreasuryDirect bills can be scheduled for reinvestment.
    • State tax treatment: Treasury interest is generally exempt from state and local income taxes.

    Cons

    • Limited access before maturity: If you need the money early, you generally must sell the bill through the secondary market.
    • Early-sale price risk: The market value can be above or below your purchase price when you sell.
    • Changing reinvestment yields: A new T-bill may have a different yield from your original bill.
    • Federal taxation: Treasury interest is generally subject to federal income tax.
    Key Point:

    The maturity date gives you a clear point to reassess your money. Before reinvesting, consider your cash needs, the new available yield, and how long you are comfortable keeping the money invested.

    Maturity, Reinvestment and Cash Options

    Once a Treasury bill matures, the proceeds give you a new choice. You can reinvest the money in another Treasury bill, move it to a suitable cash account, or use it for a planned expense. The right path depends on when you expect to need the money and what you want your cash to accomplish next.

    ChoiceAccess to MoneyWhat Happens Next?May Make Sense When
    ReinvestMoney is placed into another Treasury billA new T-bill begins with its own purchase price, yield, and maturity dateYou want to keep the money invested
    Move to a cash accountGenerally more accessible than a maturing investmentThe proceeds can be transferred to an appropriate savings or money market accountYou may need the cash soon
    Use the proceedsDepends on how the funds are held and accessedThe money can be directed toward a planned expense or financial goalThe original purpose for the money has arrived
    QUICK COMPARISON:

    Reinvesting keeps the proceeds in another Treasury bill, while moving the money to a cash account can provide easier access. A new T-bill can have different terms and yield, so review the new opportunity before reinvesting.

    Taxes, Risks and Expert Tips for Treasury Bill Maturity

    Treasury bill maturity is straightforward, but taxes, early sales, and reinvestment decisions can affect how you use the money afterward. Understanding these points before maturity can make the next step easier to plan.

    How Are Treasury Bill Returns Taxed?

    Treasury bill interest is generally subject to federal income tax but is generally exempt from state and local income taxes. For a bill purchased at a discount and held to maturity, the difference between the purchase price and the amount received is generally treated as interest income for federal tax purposes.

    What Risks Should You Consider?

    Holding a T-bill until maturity is different from selling it early. If you sell before maturity, its market price can change as interest rates and market conditions move. Reinvestment also involves uncertainty because a new Treasury bill may have a different yield from the bill that just matured.

    Warning:

    Do not assume that reinvesting will preserve your previous yield. A new Treasury bill has its own auction price, yield, and maturity date.

    Expert Tips Before Maturity

    • Check the maturity date and review your plans before it arrives.
    • Decide whether you need the proceeds for an upcoming expense.
    • Compare the available yield before choosing to reinvest.
    • Keep your Treasury records for your federal tax reporting.

    Common Treasury Bill Maturity Mistakes

    A Treasury bill can be easy to hold, but the maturity date deserves some attention. The investment may be ending, yet you still need to decide what should happen to the money next.

    Mistakes to Avoid

    • Forgetting the maturity date: You may not have enough time to plan how the proceeds will be used.
    • Reinvesting automatically without reviewing the new yield: A new T-bill has its own auction price and yield.
    • Overlooking upcoming expenses: Money you expect to need soon may deserve a more accessible home.
    • Confusing early sale with maturity: Selling before maturity means accepting the market price available at that time.
    • Ignoring tax treatment: Federal taxes can affect the amount of your return that you ultimately keep.

    A Simple Real-Life Example

    Suppose Sarah buys a Treasury bill with a $10,000 face value for $9,700. She plans to hold it until maturity. If she holds the bill through maturity, the Treasury pays the $10,000 face value according to its terms. The $300 difference between her purchase price and the face value represents her return before applicable taxes.

    Sarah now needs to decide what happens next. If she has a planned home repair, she could use the proceeds for that expense. If she does not need the money, she could consider another Treasury bill, a money market account, or another suitable option. The new decision should reflect her current financial timeline.

    SMART MOVE:

    Treat the maturity date as a financial checkpoint. Review your upcoming needs first, then decide where the proceeds belong.

    Who Should Consider a Treasury Bill?

    A Treasury bill may be worth considering when you have cash that can remain invested for its full term and you have a clear idea of when you may need the money. A defined maturity date can make it easier to connect the investment with a future expense or savings goal.

    It May Fit If You

    • Have cash you do not expect to need before maturity.
    • Want to hold a U.S. Treasury security.
    • Can match the bill’s maturity date with a future cash need.
    • Value the generally favorable state and local tax treatment of Treasury interest.
    • Prefer a maturity-based return rather than periodic coupon payments.

    When Another Option May Be Worth Comparing

    If you expect to need the money before maturity, consider how easily you can access the funds. A savings or money market account may provide different access features, while a shorter-term Treasury bill may better match a nearer cash need.

    SIMPLE CHECK:

    Look at the date first. If the maturity timeline matches your financial goal, you can then compare the available yield, taxes, access, and other terms.

    Frequently Asked Questions About Treasury Bill Maturity

    1. What happens when a Treasury bill matures?

    When a Treasury bill reaches its maturity date, its term ends and the Treasury makes the scheduled payment according to the bill’s terms. The proceeds are then handled through the account where you hold the security.

    2. Do I receive a separate interest payment when a T-bill matures?

    Generally, no. T-bills do not make periodic coupon payments. They are typically purchased at a discount, and the difference between the purchase price and face value generally represents the return.

    3. What happens to my money after a Treasury bill matures?

    You can use the maturity proceeds for a planned expense, move the money to an appropriate cash account, or consider another investment. The exact process depends on where you hold the T-bill.

    4. Can I reinvest a matured Treasury bill?

    Yes. Eligible TreasuryDirect Treasury bills can be scheduled for reinvestment. The new purchase has its own price, yield, and maturity date.

    5. Is a Treasury bill automatically reinvested at maturity?

    Not necessarily. Reinvestment depends on your instructions and the platform or account you use. Check your settings before the maturity date if you want to continue investing the proceeds.

    6. Are Treasury bill returns taxable when the bill matures?

    Treasury bill interest is generally subject to federal income tax but is generally exempt from state and local income taxes. Keep your Treasury tax records for your federal tax reporting.

    7. Can I sell a Treasury bill before maturity?

    Generally, yes, if your bank or brokerage supports secondary-market Treasury transactions. The market price can change before maturity, so you may receive more or less than your original purchase price.

    8. What should I do before my T-bill matures?

    Check the maturity date, review upcoming expenses, compare current Treasury yields, and decide whether you want to use, move, or reinvest the proceeds.

    Final Thoughts on Treasury Bill Maturity

    When a Treasury bill matures, its stated term ends and the Treasury makes the scheduled maturity payment according to the bill’s terms. For a bill purchased at a discount, the difference between the purchase price and face value generally represents the investor’s return.

    What happens next depends on your financial plans. You may need the proceeds for an upcoming expense, want to keep the money accessible, or decide to reinvest in another Treasury bill. If you reinvest, remember that the new bill has its own purchase price, yield, and maturity date.

    For a broader look at how Treasury bills work, visit our Treasury Bills Explained guide. It can help you understand where T-bills fit alongside other Treasury securities and short-term cash options.

    BOTTOM LINE:

    Treat maturity as a planning checkpoint. Before deciding what to do with the proceeds, consider your cash needs, available yields, tax treatment, and how soon you may need the money.

    Have a Money Question? Keep Exploring.

    Your T-bill may have reached maturity, but your cash plan can keep moving. Explore FinanceInvestment for practical guides on Treasury bills, savings accounts, CDs, and money market accounts.
    📩 Get in Touch With FinanceInvestment


    Email Us

  • 52-Week Treasury Bills Explained: How They Work, Returns & Risks

    52-Week Treasury Bills Explained: How They Work, Returns & Risks

    52-Week Treasury Bills Explained

    SR
    Subhash Rukade
    Founder, FinanceInvestment

    Updated: September 17, 2026


    Reading Time: ~12 minutes


    52-Week Treasury Bills: A Simple Starting Point

    52-Week Treasury Bills ExplainedA 52-Week Treasury Bill is a U.S. government security that matures in 52 weeks. You generally buy it for less than its face value and receive the full face value at maturity. The difference between what you pay and what you receive represents your interest.

    The basic idea is simple, but the details matter. Your purchase price, auction result, yield, maturity date, taxes, and access to your money before maturity can all affect how a 52-week T-bill fits your plans.

    For investors with cash they do not need immediately, a 52-week bill can be considered alongside savings accounts, money market accounts, CDs, and other Treasury securities. The important question is how long you can leave the money invested and how much flexibility you need.

    What You’ll Learn

    • How 52-week Treasury bills work
    • How investors earn money from a T-bill
    • What happens when the bill matures
    • The main benefits and drawbacks
    • How 52-week bills compare with shorter-term T-bills
    • Common mistakes to avoid before buying

    Quick Answer: What Is a 52-Week Treasury Bill?

    A 52-week Treasury bill is a short-term U.S. government security with a 52-week maturity. It is generally purchased for less than its face value, and the full face value is paid at maturity. The difference between the purchase price and the amount received at maturity is the investor’s return.

    Key Takeaways

    • 52-week Treasury bills mature in about one year.
    • They are generally sold at a discount to their face value.
    • The return comes from the difference between the purchase price and maturity value.
    • Treasury interest is generally exempt from state and local income taxes.
    • A T-bill can be held until maturity or sold before maturity in the secondary market.
    • Selling before maturity exposes you to changes in the market price.
    Bottom Line:

    A 52-week T-bill may be worth considering when you want a U.S. Treasury investment with a defined one-year maturity and you do not need periodic interest payments.

    52-Week Treasury Bills at a Glance

    A 52-week Treasury bill is a U.S. Treasury security with a one-year maturity. It is generally sold at a discount, and investors receive the bill’s full face value when it matures.

    Quick FactDetails
    Maturity52 weeks
    Minimum purchase$100
    How you earnBuy below face value and receive face value at maturity
    Auction scheduleGenerally every four weeks
    Potential fitInvestors comfortable setting money aside for about one year
    QUICK TAKE:

    A 52-week T-bill offers a clearly defined maturity date. If you sell before maturity, however, the price you receive can be different from what you originally paid.

    Complete Beginner Guide to 52-Week Treasury Bills

    52-Week Treasury Bills ExplainedIf you have never bought a Treasury bill, the basic idea is easier than it may first appear. A 52-week Treasury bill is a U.S. Treasury security that matures in about one year. Unlike a Treasury note or bond, it does not make regular coupon payments. Instead, the return is generally built into the price you pay.
    What You Actually Buy

    Treasury bills are generally issued at a discount to their face value. For example, you could pay less than $1,000 for a bill with a $1,000 face value. If you hold it until maturity, the Treasury pays the $1,000 face value. The difference between your purchase price and the amount you receive is your return.

    The purchase price is determined through the Treasury auction. As a result, the yield can vary from one auction to another. It is better to look at the actual auction result rather than assume every 52-week bill offers the same return.

    How You Can Buy One

    Individual investors can buy Treasury bills through TreasuryDirect or through a bank or brokerage that offers Treasury securities. Treasury bills have a $100 minimum purchase amount and are generally purchased in $100 increments.

    Beginners using TreasuryDirect can place a noncompetitive bid. With this type of order, you accept the yield determined at the auction instead of specifying a particular yield. This can make the buying process more straightforward.

    What Happens After You Buy?

    Once the bill is issued, you can hold it until its maturity date and receive the face value. If you need the money earlier, Treasury bills can also be sold in the secondary market. However, the market price may be different from the amount you originally paid, so an early sale can produce a gain or a loss.

    Beginner Tip:

    Before buying, check the maturity date and match it with your financial goal. If you may need the cash sooner, keeping part of your money more accessible may give you greater flexibility.

    How 52-Week Treasury Bills Work

    A 52-week Treasury bill moves through a simple auction-and-maturity process. The Treasury sets the terms, investors submit bids, and the auction determines the price and discount rate. The bill then remains outstanding until its maturity date.

    1. Choose the Bill

    First, decide how much you want to invest and make sure a 52-week maturity fits your plans. Treasury bills have a $100 minimum purchase and are available in $100 increments.

    2. Place Your Order

    Through TreasuryDirect, individual investors can place noncompetitive bids. You accept the discount rate determined at the auction instead of choosing your own rate. Banks and brokers can also offer competitive and noncompetitive bidding.

    3. Pay the Auction Price

    Treasury bills are generally sold below face value. Your purchase price is determined by the auction, so the actual amount you pay depends on that auction’s result. The difference between the purchase price and face value is the bill’s interest.

    4. Reach Maturity

    When the bill matures, Treasury pays its face value. For example, if you bought a bill for less than $1,000 and held it to maturity, you would receive the $1,000 face value. Treasury bill interest is subject to federal income tax but is generally exempt from state and local income taxes.

    EXPERT TIP:

    Think about the maturity date before you buy. If the money has a specific purpose one year from now, matching that date with the T-bill’s maturity can make your cash planning much easier.

    Benefits and Drawbacks of 52-Week Treasury Bills

    A 52-week T-bill can work well for money with a one-year purpose, but it comes with trade-offs. Its defined maturity is useful for planning, while selling before maturity can introduce price risk.

    Benefits

    • U.S. government security: Treasury bills are backed by the full faith and credit of the U.S. government.
    • Known maturity: The bill has a scheduled maturity of 52 weeks.
    • Simple structure: You generally buy below face value and receive the face value at maturity.
    • State tax treatment: Treasury interest is generally exempt from state and local income taxes.
    • Accessible minimum: Treasury bills can be purchased with a $100 minimum.

    Drawbacks

    • Less flexibility: If you need the cash early, you may have to sell the bill before maturity.
    • Early-sale risk: The market price can be higher or lower than your purchase price.
    • No periodic coupon: Treasury bills do not make regular interest payments like Treasury notes and bonds.
    • Reinvestment risk: When the bill matures, available yields may have changed.
    KEY POINT:

    A 52-week T-bill is easier to evaluate when you start with your timeline. Match the maturity date with when you expect to need the money, rather than looking at yield alone.

    52-Week Treasury Bills vs. Other Cash Options

    A 52-week T-bill is one of several ways to hold short-term money. The key differences are the maturity period, access to your cash, and how the return is generated.

    OptionTypical TermAccess Before MaturityReturn StructureMain Point
    52-Week T-Bill52 weeksCan be sold before maturityDiscount to face valueDefined Treasury maturity
    Shorter T-Bill4–26 weeksCan be sold before maturityDiscount to face valueShorter time commitment
    Money Market AccountNo fixed maturityGenerally accessibleInterest/APYDeposit account; FDIC coverage may apply
    1-Year CDAbout 1 yearUsually subject to account terms and possible early-withdrawal penaltyInterestBank deposit; FDIC coverage may apply
    QUICK COMPARISON:

    A 52-week T-bill gives you a defined Treasury maturity. A money market account generally offers easier access to cash, while a CD typically has a fixed term and may charge a penalty for early withdrawal.

    Costs, Risks and Expert Tips for 52-Week Treasury Bills

    A 52-week Treasury bill does not have the same fee structure as a typical bank deposit. The main things to consider are the purchase price, any brokerage charges, taxes, market-price changes, and what happens if you need your money before maturity.

    Costs to Watch

    TreasuryDirect does not charge a fee for purchasing Treasury securities. A bank or brokerage, however, may have its own fees or trading charges. Before buying through an intermediary, check its current pricing so you know the actual cost of the transaction.

    Risks That Matter

    If you hold a 52-week T-bill until maturity, short-term market-price movements generally do not change the scheduled face-value payment. Selling before maturity is different. Market interest rates, demand, and remaining time to maturity can affect the price you receive. Inflation can also reduce the purchasing power of your return.

    WARNING:

    Avoid investing money that you may need unexpectedly before the bill matures. A T-bill can be sold early, but its market price may be different from your original purchase price.

    Expert Tips

    • Check the maturity date before placing your order.
    • Compare the yield with other suitable cash options.
    • Keep emergency money separate from your T-bill investment.
    • Plan ahead for what you will do when the bill matures.

    Common Mistakes With 52-Week Treasury Bills

    Buying a 52-week T-bill is straightforward, but the timing deserves attention. A common mistake is focusing on the yield while overlooking when the money may be needed.

    Mistakes to Avoid

    • Overlooking the maturity date: Make sure the 52-week term fits your financial goal.
    • Using emergency cash: Keep money for unexpected expenses readily accessible.
    • Focusing only on yield: Consider taxes, liquidity, purchase price, and your time horizon.
    • Forgetting reinvestment: The yield available when your bill matures may be different.
    • Selling too quickly: An early sale occurs at the prevailing market price, which may be above or below your purchase price.

    A Simple Real-Life Example

    Suppose Sarah has $10,000 that she expects to leave invested for about one year. For illustration, assume she purchases a $10,000 face-value Treasury bill for $9,600. If she holds it until maturity, she receives the $10,000 face value. The $400 difference is her return before applicable taxes.

    But six months later, Sarah unexpectedly needs the cash. She can potentially sell the bill in the secondary market. The amount she receives, however, depends on the market price at that time. It may not be exactly $9,600 or $10,000.

    SMART MOVE:

    Before buying, record the purchase price, face value, maturity date, and your planned use for the money. This makes the one-year commitment much easier to manage.

    Who Should Consider a 52-Week Treasury Bill?

    A 52-week T-bill can be considered when you have money that you expect to leave invested for about one year. Its scheduled maturity date can make it useful for planning around a future expense or financial goal.

    It May Fit Investors Who

    • Want to hold a U.S. Treasury security.
    • Have cash they do not expect to need for about 52 weeks.
    • Prefer a clearly defined maturity date.
    • Want Treasury interest that is generally exempt from state and local income taxes.
    • Are comfortable receiving the investment’s return at maturity rather than through regular coupon payments.

    When Another Option May Fit Better

    If you expect to need the money sooner, a shorter-term Treasury bill may provide a closer maturity date. A money market account can offer easier access to cash, while a CD may provide a fixed term and interest payments under its specific account terms. Your timeline and cash-access needs should guide the comparison.

    A SIMPLE CHECK:

    Before buying, check the maturity date and ask whether you can comfortably leave the money invested until then. If not, consider keeping that portion of your cash more accessible.

    Frequently Asked Questions About 52-Week Treasury Bills

    1. What is a 52-week Treasury bill?

    A 52-week Treasury bill is a U.S. Treasury security that matures in 52 weeks. It is generally issued at a discount, and the difference between the purchase price and the face value at maturity represents the return.

    2. How does a 52-week T-bill make money?

    You generally purchase the bill for less than its face value. When it matures, the Treasury pays the full face value. That difference is the investment return before applicable taxes.

    3. How much does a 52-week Treasury bill cost?

    There is no single fixed purchase price. The amount depends on the auction result and the face value purchased. Treasury bills have a $100 minimum purchase amount and are generally purchased in $100 increments.

    4. Can you sell a 52-week Treasury bill before maturity?

    Yes. Treasury bills are marketable securities and can generally be sold before maturity through a bank or brokerage that supports secondary-market trading. The price at the time of sale may be higher or lower than your purchase price.

    5. What happens when a 52-week T-bill matures?

    When the bill reaches maturity, the Treasury pays its face value. You can then use the proceeds or reinvest them in another eligible security.

    6. Are 52-week Treasury bill earnings taxable?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Your individual tax situation may be different, so consider your circumstances when estimating your after-tax return.

    7. Is a 52-week T-bill the same as a one-year CD?

    No. A T-bill is a U.S. government security, while a CD is a bank deposit. They can differ in liquidity, taxation, insurance, purchase process, and terms.

    8. Can beginners buy 52-week Treasury bills?

    Yes. Individuals can buy Treasury bills through TreasuryDirect or through eligible banks and brokerages. Before placing an order, check the auction terms, purchase amount, and maturity date.


    Final Thoughts on 52-Week Treasury Bills

    A 52-week Treasury bill can be a practical option when you have cash that can remain invested for roughly one year. Its structure is straightforward: you generally buy below face value and receive the face value when the bill matures.

    The one-year timeline is the part that deserves the most attention. If you know when you will need the money, the maturity date can make planning easier. On the other hand, money that may be needed unexpectedly should not be tied up without considering your access options.

    It is also worth comparing the T-bill with other places for short-term cash. A money market account may provide easier access, while a CD may have different withdrawal terms. Shorter Treasury bills can offer different maturity dates as well.

    BOTTOM LINE:

    The key is to match the 52-week maturity with your own cash timeline. Look at the yield, taxes, liquidity, and your future need for the money before making a decision.

    Have a Money Question? Keep Exploring.

    Understanding how Treasury bills work can help you make informed choices about short-term cash. Keep exploring FinanceInvestment for practical guides on Treasury bills, savings, CDs, money market accounts, and other personal finance topics.

    📩 Get in Touch With FinanceInvestment


    Email Us

  • How to Use CDs for Short-Term Financial Goals in 2026

    How to Use CDs for Short-Term Financial Goals in 2026

    FINANCEINVESTMENT • CD GUIDE 2026

    How to Use CDs for Short-Term Financial Goals

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August,24, 2026.
    About 10–12 min read

    A practical guide to using certificates of deposit for money you expect to need within a defined short-term time frame.

    How to Use CDs for Short-Term Financial Goals in 2026
    Learn how to use CDs for short-term financial goals, choose the right CD term, protect your cash needs, and avoid locking up money too early.
    how-to-use-cds-for-short-term-financial-goals
    How to Use CDs for Short-Term Financial Goals
    short-term CD strategy,
    CDs for short-term goals,
    short-term savings with CDs,
    CD for a financial goal,
    short-term savings goals,
    CD maturity planning,
    choosing a CD term,
    short-term certificate of deposit
    https://financeinvestment.site/how-to-use-cds-for-short-term-financial-goals/
    Subhash Rukade
    August 23, 2026
    About 10–12 minutes

    Use the Deadline to Choose the CD, Not Just the Rate

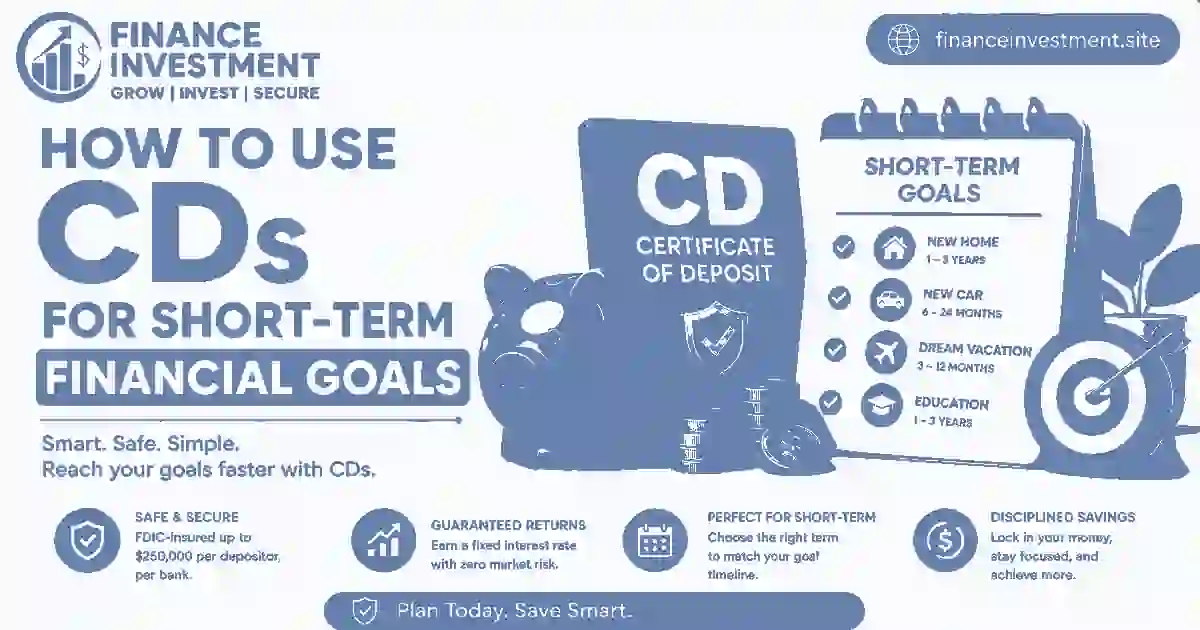
    How to Use CDs for Short-Term Financial GoalsHow to Use CDs for Short-Term Financial Goals starts with a simple question: When will I actually need this money? If you know the answer, choosing a CD term becomes much easier. A certificate that matures after your goal arrives may offer a good APY, but it may be a poor fit if your cash is needed sooner.

    Think about a planned expense such as a car purchase, tuition bill, home repair, annual insurance payment, or a family trip. These goals have something in common: the money has a job and a deadline. A CD can give that cash a defined timeline while potentially earning more than leaving it completely idle.

    The key is to work backward from the date. If you need the money in six months, a five-year CD is obviously out of step. Even a one-year certificate may create a problem if the expense cannot wait. Early withdrawal can also reduce the benefit of using a CD in the first place.

    Before choosing a term, it helps to understand how CDs fit into a broader savings plan. Our CD Guide 2026 provides that bigger picture.

    What You’ll Learn

    • How to match a CD term with a financial deadline
    • When a short-term CD can make sense
    • Why the highest APY may not be the best choice
    • How to plan around maturity dates
    • When a flexible savings account may be better

    Quick Answer: Are CDs Good for Short-Term Financial Goals?

    Yes, a CD can work well for a short-term financial goal when you know roughly when the money will be needed and choose a maturity date that fits. The goal is to earn interest without creating a cash-access problem.

    6 Key Takeaways

    1. Start with the deadline: Know when the money must be available before choosing a CD term.
    2. Match maturity to the goal: A CD that matures too late can be inconvenient, even with a strong APY.
    3. Compare flexibility: A high-yield savings account may be better when the spending date could change.
    4. Don’t chase APY alone: Consider the term, withdrawal rules, and actual dollar earnings together.
    5. Keep emergency cash separate: A CD should not replace money you may need immediately.
    6. Plan the next step: Know where the money will go when the CD matures instead of making the decision at the last minute.

    Bottom line: A short-term CD works best when the maturity date fits the purpose of the money. The best rate is useful only if the timing works, too.

    Short-Term CD Planning at a Glance

    A useful way to think about a short-term CD is to start with the calendar. The closer your financial goal is, the more important access and timing become. The table below gives a simple starting framework rather than a one-size-fits-all rule.

    Financial GoalPossible CD TermMain Consideration
    3–6 months
    Planned bill or near-term purchase
    3–6 month CD, where availableKeep the maturity date comfortably before the money is needed.
    6–12 months
    Tuition, insurance or planned purchase
    6-month or 1-year CDLeave enough time after maturity to move or spend the funds.
    12–18 months
    Longer planned expense
    1-year or 18-month CDConsider whether the goal date could move before locking in.

    Key number: Give yourself a timing cushion. If a goal requires $10,000 on June 1, a certificate maturing close to that date may leave little room for delays. A flexible account can be more appropriate when the spending date is uncertain.

    Complete Beginner Guide to Using CDs for Short-Term Goals

    A CD becomes useful for a short-term goal when three things line up: you know approximately how much the goal will cost, you have a reasonable spending date, and you can leave the deposited money alone until the certificate matures.

    Define the Amount Before Shopping for a CD

    Start with the expense rather than the bank’s advertised rate. If you expect a home project to cost $6,000 next spring, decide how much of that $6,000 is already saved and how much can safely be committed. This keeps the CD tied to a real purpose instead of turning rate shopping into the goal itself.

    Work Backward From the Spending Date

    Give the maturity date some breathing room. Money needed on a specific day generally should not be locked in a certificate that matures that same morning. Allow time to receive maturity instructions, move the funds, and handle any unexpected delay.

    Use Different Maturities for Different Goals

    If several expenses are coming at different times, you do not have to put everything into one CD. A simple ladder can split the cash among certificates with different maturity dates. For example, money needed in six months can sit separately from money earmarked for next year. Each portion then has its own timeline.

    Consider a No-Penalty CD When Timing Is Less Certain

    A no-penalty CD may provide more flexibility because qualifying withdrawals can be made without the traditional early-withdrawal penalty, subject to the institution’s rules. Compare its APY and withdrawal conditions with standard CDs and liquid savings options before choosing it.

    Keep Emergency Savings Outside the Plan

    Your short-term goal fund and emergency fund serve different purposes. A vacation, vehicle purchase, or planned renovation can often wait or change. An urgent medical bill or home repair may not. Keeping emergency cash readily accessible helps prevent an unexpected expense from forcing you to break a CD early.

    How a Short-Term CD Strategy Works

    A short-term CD strategy works best when the certificate is treated as part of a timeline, not as a permanent home for your cash. You decide what the money is for, when you need it, and then build the CD around those facts.

    Step 1: Set the Goal Amount

    Write down the amount you expect to need. If the target is $8,000, decide whether the full amount is ready now or whether you are still saving toward it. This also helps you avoid committing money that belongs to another priority.

    Step 2: Mark the Date on Your Calendar

    Choose the date when the money should be available. Then work backward to find a suitable CD term. A small cushion between maturity and the actual expense can make the plan easier to manage.

    Step 3: Fund the Certificate

    After comparing APY, term, withdrawal rules, and other conditions, open the CD and transfer the amount you have decided to commit. Save the account confirmation and maturity date so you can review the plan later.

    Step 4: Track Maturity

    Don’t wait until maturity morning to think about the next move. Check the institution’s maturity and renewal rules in advance. Some CDs automatically renew if you do nothing during the applicable grace period.

    Illustrative Example

    Maya expects to spend $5,000 on a home improvement project in about eight months. She keeps her emergency reserve separate and places the goal money into a suitable shorter-term CD. Rather than choosing a certificate that matures after the project date, she selects one that gives her time to access the funds before the contractor needs payment. When the CD matures, she reviews the proceeds and moves the money toward the project instead of automatically renewing it.

    The final step is simple but important: match the maturity decision to the goal. If the expense has arrived, use the money. If the date has changed, reassess. A CD strategy should adapt to the goal rather than lock you into a decision you no longer need.

    Benefits & Drawbacks of Using CDs for Short-Term Goals

    A CD can bring structure to money that already has a purpose. But that structure comes with trade-offs. The biggest question is whether the benefit of a defined return outweighs the loss of easy access.

    ✓ Pros

    • Predictable return: A fixed-rate CD can make the expected interest easier to estimate.
    • Defined timeline: The maturity date gives the savings a clear finish line.
    • Goal separation: Moving goal money into a separate certificate can reduce the temptation to spend it elsewhere.
    • Potentially stronger yield: Depending on current rates, a CD may offer more interest than leaving the same cash in a low-yield account.

    △ Cons

    • Early-withdrawal risk: Taking money out before maturity may trigger a penalty on a standard CD.
    • Timing mismatch: A goal can move, but the original maturity date does not necessarily move with it.
    • Inflation risk: Rising prices can reduce the purchasing power of the money while it is locked in.
    • Reinvestment risk: When the CD matures, comparable rates may be lower if you still need to save the money.

    The strongest case for a CD is money with a reasonably predictable purpose and timeline. If either one is uncertain, flexibility may deserve more weight than a slightly higher rate.

    Short-Term Savings Comparison: CD vs Other Options

    A CD is only one way to park money for a near-term goal. The better choice depends on how certain your spending date is and how quickly you might need access to the cash.

    OptionBest FitLiquidityReturn Characteristics
    CDKnown goal dateLimited before maturityOften fixed for the selected term
    High-yield savingsUncertain timingGenerally highVariable rate
    Treasury billsShort government-backed investment horizonDepends on whether held to maturity or soldYield set by market conditions
    Money market deposit accountSavings with easier accessGenerally highVariable rate

    If your goal date is firm, a CD can provide a useful fixed timeline. If the date could move, a high-yield savings account may give you more room to adjust. For short government securities, Treasury bills offer another route, but their market and tax characteristics differ from bank CDs.

    Before committing cash, also consider how FDIC insurance applies to CDs. Protection, access, maturity, and return should be considered together rather than comparing APYs alone.

    Costs, Risks & Expert Tips for Short-Term CD Planning

    The biggest risk with a short-term CD is not usually the rate itself. It is choosing a certificate that does not fit what happens around the goal. A little planning can prevent a good savings idea from becoming inconvenient later.

    Know the Cost of Changing Your Mind

    A standard CD may charge an early-withdrawal penalty if you need the money before maturity. That matters when the spending date is only an estimate. Review the penalty before opening the certificate, especially if the goal could move forward unexpectedly.

    Consider What the Cash Could Do Elsewhere

    Locking money into a CD has an opportunity cost. You may give up access to a savings account or another option that could become more attractive while your CD is running. Inflation also matters because a fixed return does not guarantee the same purchasing power when prices rise.

    Plan for the Rate After Maturity

    Rates may be different when your CD matures. If you still need the money for a later goal, the next available CD could offer a lower yield. A short CD ladder can spread maturity dates and reduce the chance that every dollar reaches maturity at the same time.

    Don’t Forget Taxes

    Interest from a taxable CD is generally subject to federal income tax, and state or local taxes may also apply. Factor the after-tax return into your planning rather than treating the advertised APY as the entire gain.

    Give the Money a Job After Maturity

    Before the CD matures, decide whether the money will be spent, transferred to savings, or placed into another investment. This prevents an automatic renewal from making the decision for you.

    Premium Expert Tip

    Build the exit plan when you open the CD. Put the maturity date on your calendar, note the renewal rules, and decide where the proceeds should go. A CD works best when the ending date is part of the strategy from day one.

    Common Mistakes When Using CDs for Short-Term Goals

    A short-term CD can be simple to manage, but small planning errors can make the money harder to use when the goal arrives. The most common problems happen when the certificate is chosen around the rate instead of the purpose.

    Mistakes Worth Avoiding

    • Ignoring the exact goal date: A CD that matures after the money is needed can create unnecessary pressure.
    • Locking up flexible cash: If an expense could happen earlier than expected, consider whether a standard CD gives you enough access.
    • Skipping the withdrawal rules: Understand the early-withdrawal penalty before committing the money.
    • Letting the CD renew automatically: Check maturity instructions before the certificate reaches its end date.
    • Ignoring taxes and inflation: The advertised APY does not tell the whole story about what the money will be worth after taxes and rising prices.
    • Putting every goal on one maturity date: Separate maturity dates can make several upcoming expenses easier to manage.

    Real-Life Example: Jordan’s Wedding Fund

    Jordan has $7,500 saved for a wedding planned about nine months from now. He finds a longer CD with a slightly higher rate and considers using it because the APY looks attractive.

    Illustrative calculation only: If the longer CD produced an extra $60 of interest compared with a suitable shorter certificate, that additional return would still need to be weighed against the risk of needing the money before maturity.

    Jordan chooses a maturity date that fits his planned spending window instead. The decision gives the goal a clearer path without making a small rate difference the main priority.

    Practical lesson: A CD should make a short-term goal easier to fund, not harder to access. Choose the certificate around the date and purpose of the money first, then use the APY to refine the choice.

    Who Should Use CDs for Short-Term Goals?

    CDs tend to fit best when the purpose of the money is clear and the spending date is reasonably predictable. They are less useful when you may need the cash at any moment.

    Good Candidates for a Short-Term CD

    Goal-based savers can use CDs for planned expenses such as tuition, a vehicle purchase, a home project, or an annual bill. Families may also find them useful when several known expenses are coming at different times.

    Conservative investors who value a defined return may appreciate having a specific maturity date. The strategy is especially comfortable for people who already have a separate emergency reserve and can leave the CD untouched until maturity.

    Who May Prefer Flexible Savings?

    If your income is unpredictable, your emergency fund is incomplete, or the spending date could change suddenly, a liquid savings account may be a better fit. Flexibility can be more valuable than squeezing out a little extra interest.

    Quick Decision Guide

    Firm date + separate emergency fund + money can stay untouched? A CD may fit. Uncertain date or frequent access needed? Keep the money flexible. Several future expenses? Consider different maturity dates.

    Frequently Asked Questions About CDs for Short-Term Goals

    Are CDs good for short-term goals?

    They can be useful when you know when the money will be needed and can leave it untouched until maturity. A CD is less suitable when the spending date is uncertain.

    What CD term is best for short-term savings?

    There is no single best term. Choose one that matures before you need the money, while leaving enough time to access the proceeds and complete the planned expense.

    Can I use a 6-month CD for a financial goal?

    Yes. A 6-month CD can fit a goal that is several months away, provided the maturity date works with your actual spending schedule.

    Is a 1-year CD considered short term?

    For many savers, a one-year CD can serve a short-term or near-term goal. The important point is whether the one-year maturity matches when you expect to need the funds.

    What if I need the money before maturity?

    A standard CD may impose an early-withdrawal penalty. Review the certificate’s rules before opening it. A liquid savings account or no-penalty CD may provide more flexibility.

    Are no-penalty CDs useful?

    They can be useful when your goal date is not completely certain. However, compare the APY, withdrawal conditions, and other account terms before choosing one.

    Should emergency funds go into CDs?

    Usually, emergency money is better kept readily accessible. A CD can restrict access, which may be inconvenient when an unexpected expense requires immediate cash.

    Can I create a CD ladder for short-term goals?

    Yes. You can divide money among CDs with different maturity dates. This can help coordinate several upcoming expenses without putting the entire balance behind one maturity date.

    What happens when a CD matures?

    The principal and applicable interest become available according to the institution’s maturity rules. Some CDs automatically renew if you do not provide different instructions during the applicable grace period.

    Illustrative: How much can a short-term CD earn?

    Illustrative calculation only: A $5,000 CD earning a hypothetical 4% APY for six months would produce roughly $99 of interest before taxes, assuming simple half-year proportional earnings. Actual results depend on the CD’s APY, compounding, and terms.

    Final Verdict: Use the CD to Serve the Goal

    Short-term CDs can be a useful choice when you have a defined financial goal, a reasonably firm spending date, and enough separate cash to handle unexpected expenses. The certificate should fit the timeline of the goal rather than forcing the goal to fit the certificate.

    Start with the date you expect to need the money. Then compare CD terms that mature early enough to give you a practical window for accessing the proceeds. After that, look at APY, minimum deposits, withdrawal rules, and other account terms.

    A higher APY is not automatically the better deal. If it comes with a maturity date that is too late or makes your money harder to access, the extra interest may not be worth the trade-off. When the spending date is uncertain, a flexible savings option can make more sense.

    For a broader look at CD terms, rates, safety, and strategy, explore our CD Guide 2026.

    Practical takeaway: Choose the CD that reaches the finish line when your financial goal does. Once the timing works, use the rate to make the final choice.

    FINANCEINVESTMENT

    Make Your Next Savings Goal Easier

    If you enjoy practical guidance on CDs, savings, and investing, you can join the FinanceInvestment newsletter for simple ideas you can use when planning your next financial goal.

    📧 subhashr325@gmail.com

    A good short-term savings plan gives every dollar a purpose while leaving enough room for real life to change.