Tag: Money Management

  • AI Tools That Automatically Find Hidden Savings: Complete 2026 Guide

    AI Tools That Automatically Find Hidden Savings: Complete 2026 Guide


    AI Tools That Automatically Find Hidden Savings: Complete 2026 Guide

    Author: Subhash Rukade

    Published: June 14, 2026
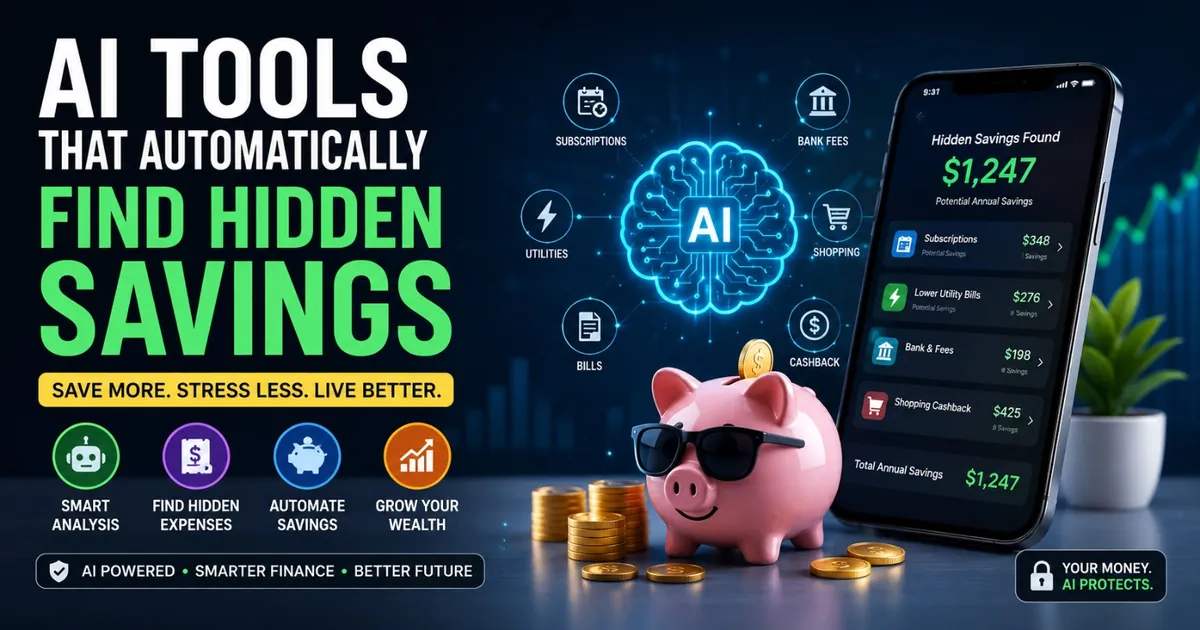
    AI Savings Tools

    Why AI Tools That Automatically Find Hidden Savings Are Becoming Essential

    Millions of Americans unknowingly lose money every month through forgotten subscriptions, unnecessary fees, higher-than-needed bills, and inefficient spending habits.

    The good news is that AI Tools That Automatically Find Hidden Savings are helping consumers uncover these hidden costs and keep more money in their pockets.

    Modern AI Savings Tools analyze spending patterns, monitor recurring expenses, identify wasteful transactions, and recommend personalized ways to save money.

    Instead of manually reviewing hundreds of transactions, artificial intelligence can scan financial activity within seconds and highlight opportunities that most people would never notice.

    For many households, these small savings add up quickly. Eliminating a few unused subscriptions, lowering utility bills, reducing bank fees, and optimizing spending habits can save hundreds or even thousands of dollars each year.

    As inflation and living costs continue affecting American families in 2026, finding hidden savings has become more important than ever.

    The same artificial intelligence technologies helping people save money are also transforming investing, budgeting, retirement planning, and wealth building.

    If you want to understand how AI is reshaping personal finance, explore our
    AI Investing Guide 2026.

    Unlike traditional budgeting methods that require significant manual effort, AI Savings Tools work continuously in the background.

    They can identify duplicate subscriptions, negotiate lower bills, track spending trends, recommend smarter financial products, and even automate savings transfers based on your financial behavior.

    This creates a more efficient approach to money management while helping consumers build stronger financial habits.

    In this guide, you’ll learn how AI Tools That Automatically Find Hidden Savings work, which strategies are most effective, common mistakes consumers make, real-world examples, future trends, and practical ways to use AI to improve your financial life.

    How AI Savings Tools Work

    Modern AI Savings Tools use artificial intelligence to analyze financial activity, identify wasteful spending, and uncover money-saving opportunities that many consumers miss.

    Instead of manually reviewing bank statements and credit card transactions, AI can evaluate thousands of data points within seconds.

    This makes AI Tools That Automatically Find Hidden Savings one of the most practical financial innovations available in 2026.

    Let’s look at how these systems work behind the scenes.

    Transaction Monitoring

    AI continuously monitors spending activity across connected financial accounts.

    It categorizes purchases, tracks recurring expenses, and identifies unusual spending patterns.

    For example, if a consumer’s dining expenses increase significantly from one month to the next, AI may highlight the change and recommend adjustments.

    This real-time visibility helps consumers understand exactly where their money is going.

    Subscription Detection

    One of the most popular features of AI Savings Tools is automatic subscription tracking.

    Many Americans pay for services they rarely use or completely forget about.

    AI can identify recurring charges from streaming services, software subscriptions, gym memberships, and other monthly expenses.

    By highlighting unused subscriptions, consumers can quickly eliminate unnecessary costs.

    Bill Negotiation and Optimization

    Some AI-powered financial platforms help users reduce monthly bills.

    These tools analyze utility costs, internet plans, insurance premiums, and mobile phone expenses.

    The system may recommend cheaper alternatives or identify opportunities to negotiate better rates.

    Over time, these small reductions can create significant annual savings.

    Spending Pattern Analysis

    AI Budgeting Tools do more than simply track transactions.

    They identify long-term spending habits and compare behavior against personal financial goals.

    For example, AI may notice excessive spending in certain categories and suggest realistic budget adjustments.

    This personalized approach often produces better results than generic budgeting advice.

    Automatic Savings Recommendations

    Many AI Savings Tools can recommend how much money consumers should save each month.

    Some platforms even automate transfers into savings accounts based on income patterns and spending behavior.

    This helps users build emergency funds and achieve financial goals with minimal effort.

    Traditional Budgeting vs AI Savings Tools

    FeatureTraditional BudgetingAI Savings Tools
    Expense TrackingManualAutomatic
    Subscription DetectionLimitedReal-Time Monitoring
    Savings SuggestionsUser DrivenAI Generated
    Bill OptimizationManual ResearchAI Recommendations
    Time RequiredHighLow

    Consumers who want to explore additional AI-powered financial tools should also review our
    AI Personal Finance 2026
    guide.

    As artificial intelligence becomes more advanced, AI Tools That Automatically Find Hidden Savings will continue helping Americans reduce wasteful spending, improve budgeting habits, and accelerate long-term wealth building.

    Best AI Strategies for Finding Hidden Savings

    Finding extra money in your budget does not always require earning more income.

    Many Americans can improve their financial situation simply by using AI Tools That Automatically Find Hidden Savings.

    Modern AI Savings Tools identify wasteful spending, uncover overlooked opportunities, and help consumers keep more of their hard-earned money.

    Here are some of the most effective AI-powered strategies available in 2026.

    1. Subscription Optimization

    Streaming services, software subscriptions, gaming memberships, and fitness apps can quietly drain your budget.

    AI Savings Tools automatically detect recurring charges and identify subscriptions you rarely use.

    Many consumers discover they are paying for multiple services they forgot existed.

    Canceling just a few unnecessary subscriptions can free up hundreds of dollars each year.

    2. Utility Bill Reduction

    Utility bills continue rising across many parts of the United States.

    AI can analyze historical utility costs and identify unusual increases in electricity, water, internet, and mobile phone bills.

    Some platforms even recommend lower-cost service providers or negotiation opportunities.

    Small monthly reductions often create substantial annual savings.

    3. Credit Card Rewards Optimization

    Many consumers use credit cards without maximizing available rewards.

    AI Savings Tools evaluate spending habits and recommend the most beneficial reward categories.

    For example, frequent travelers may benefit from travel-focused cards, while everyday spenders may earn more through cashback programs.

    Choosing the right rewards strategy can increase annual savings significantly.

    To compare leading options, visit our
    Best Credit Cards 2026
    guide.

    4. Shopping Price Tracking

    AI-powered shopping assistants monitor product prices across multiple retailers.

    Instead of purchasing immediately, consumers can receive alerts when prices drop.

    This strategy is especially useful for electronics, appliances, travel bookings, and large household purchases.

    Buying at the right time often saves more money than consumers expect.

    5. Cashback and Rewards Opportunities

    Many consumers overlook cashback programs and promotional offers.

    AI can automatically identify reward opportunities that align with normal spending behavior.

    Rather than searching manually, consumers receive personalized recommendations based on their transaction history.

    These rewards can accumulate into meaningful savings throughout the year.

    💰 Monthly Savings Calculator Example

    Suppose AI identifies the following opportunities:

    • Unused Streaming Services = $25/month
    • Lower Internet Bill = $20/month
    • Better Credit Card Rewards = $35/month
    • Reduced Shopping Costs = $40/month

    Total Monthly Savings: $120

    Annual Savings: $120 × 12 = $1,440

    This simple example shows how AI Tools That Automatically Find Hidden Savings can produce substantial financial benefits without requiring major lifestyle changes.

    Even small savings improvements become powerful when combined with long-term investing and disciplined financial planning.

    The most successful savers often use AI not only to reduce expenses but also to redirect those savings toward investments, emergency funds, and wealth-building opportunities.

    As AI Savings Tools continue evolving, consumers will gain even more personalized insights into spending habits and hidden opportunities to improve financial health.

    Real-World Case Study: How AI Found Hidden Savings for an American Family

    Understanding how AI Tools That Automatically Find Hidden Savings work becomes easier when we look at a real-world example.

    Meet Jason and Emily, a married couple from Texas with two children. Like many American families, they earned a decent income but often wondered why their savings account never seemed to grow.

    Despite careful budgeting, they felt as though money disappeared every month without a clear explanation.

    In early 2026, they decided to connect their bank accounts and credit cards to an AI-powered financial management platform.
    AI Tools That Automatically Find Hidden Savings Case Study

    Step 1: AI Reviews Spending Patterns

    Within minutes, the AI Savings Tools analyzed over 12 months of transaction history.

    The system categorized spending, identified recurring charges, and highlighted areas where money was being wasted.

    Several surprising discoveries appeared immediately.

    • Three unused streaming subscriptions
    • Duplicate cloud storage services
    • Higher-than-average internet bill
    • Unused gym membership
    • Low cashback credit card rewards

    The family had completely forgotten about some of these expenses.

    Step 2: AI Identifies Savings Opportunities

    The AI platform recommended specific actions.

    It suggested canceling unnecessary subscriptions, negotiating a lower internet plan, switching to a better rewards credit card, and automating monthly savings transfers.

    The software also identified recurring spending habits that could be reduced without affecting the family’s lifestyle.

    Step 3: Financial Results After Six Months

    After following the AI recommendations, Jason and Emily achieved significant savings.

    The improvements were surprisingly simple yet highly effective.

    📊 Case Study Summary

    • Cancelled Subscriptions: $45/month
    • Reduced Internet Costs: $25/month
    • Improved Credit Card Rewards: $40/month
    • Reduced Impulse Spending: $65/month
    • Total Monthly Savings: $175
    • Annual Savings Potential: $2,100

    Why This Example Matters

    Many Americans assume meaningful savings require major sacrifices.

    In reality, AI Tools That Automatically Find Hidden Savings often uncover small inefficiencies that quietly drain financial resources over time.

    The family did not dramatically change their lifestyle. They simply eliminated waste and optimized existing spending habits.

    This demonstrates one of the biggest advantages of AI Savings Tools. They make it easier to identify opportunities that are often overlooked during manual budgeting.

    Consumers who are preparing for economic uncertainty should also review our
    Recession-Proof Investing 2026
    guide for additional strategies to strengthen long-term financial security.

    As artificial intelligence continues improving, more households will be able to discover hidden savings opportunities, reduce unnecessary expenses, and redirect extra money toward investing, debt reduction, and wealth building.

    Common Money Mistakes That Waste Hidden Savings

    Even the best AI Savings Tools cannot help consumers who ignore obvious spending problems.

    Many Americans lose hundreds or even thousands of dollars each year because of avoidable financial mistakes.

    The good news is that AI Tools That Automatically Find Hidden Savings can identify many of these problems before they become serious financial drains.

    Understanding these common mistakes is the first step toward improving your financial health.

    1. Forgotten Subscriptions

    Subscription services have become one of the biggest hidden expenses in modern households.

    Streaming platforms, software tools, fitness apps, gaming memberships, and cloud storage services often continue charging long after consumers stop using them.

    Many people underestimate how much these recurring charges cost over an entire year.

    AI Savings Tools automatically detect these subscriptions and highlight opportunities to cancel unnecessary services.

    2. Unused Memberships

    Gym memberships, warehouse clubs, loyalty programs, and premium services often go unused for months.

    Yet the monthly fees continue.

    Artificial intelligence can identify recurring charges associated with memberships that show little or no activity.

    Eliminating these expenses is often one of the fastest ways to increase monthly savings.

    3. High-Interest Debt

    Credit card debt remains one of the most expensive financial mistakes Americans make.

    High interest rates can consume money that could otherwise be directed toward savings and investments.

    AI Budgeting Tools frequently recommend strategies for reducing debt faster and improving cash flow.

    Lower debt levels create more opportunities for long-term wealth building.

    4. Choosing the Wrong Credit Cards

    Many consumers use credit cards that provide limited rewards or poor benefits.

    As a result, they miss cashback opportunities, travel rewards, and other valuable incentives.

    AI Savings Tools can analyze spending patterns and recommend better reward structures based on individual behavior.

    Small reward improvements often generate meaningful annual savings.

    5. Impulse Spending

    Impulse purchases remain one of the largest obstacles to financial progress.

    Small unplanned purchases may seem harmless individually, but they often add up quickly over time.

    Artificial intelligence can identify spending categories where impulsive behavior is affecting savings goals.

    This awareness helps consumers make better purchasing decisions.

    📊 Savings Leak Chart

    Common sources of hidden financial waste:

    • Forgotten Subscriptions — 30%
    • Impulse Spending — 25%
    • High-Interest Debt — 20%
    • Unused Memberships — 15%
    • Poor Credit Card Rewards — 10%

    Example Scenario

    Consider a consumer paying for four unused subscriptions, carrying high-interest credit card debt, and frequently making impulse purchases online.

    Individually, each expense may appear manageable.

    Combined, however, these habits could easily cost more than $2,000 per year.

    This is exactly where AI Tools That Automatically Find Hidden Savings provide value by identifying spending leaks that are difficult to spot manually.

    Consumers interested in developing stronger long-term financial habits should also review our
    SIP Investing Guide 2026.

    Avoiding these common mistakes can dramatically improve savings rates and help consumers redirect more money toward investing, emergency funds, and long-term financial goals.

    How to Use AI Savings Tools Effectively

    Finding hidden savings is only the first step. To achieve meaningful financial progress, consumers must take action on the recommendations generated by AI Savings Tools.

    The most successful users treat artificial intelligence as a financial assistant rather than simply a budgeting app.

    When used consistently, AI Tools That Automatically Find Hidden Savings can help build stronger financial habits, increase savings rates, reduce debt, and support long-term wealth creation.

    1. Automate Your Savings

    One of the most powerful features of modern AI Savings Tools is automation.

    Instead of relying on willpower, consumers can automatically transfer money into savings accounts based on income patterns and spending behavior.

    Many financial experts recommend paying yourself first.

    By automating savings contributions, you ensure that financial goals receive priority before discretionary spending occurs.

    Even saving an additional $100 per month can result in $1,200 annually.

    2. Build Better Money Habits

    Artificial intelligence can identify spending patterns that may be preventing financial progress.

    For example, AI may highlight excessive dining expenses, impulse purchases, or recurring charges that have gradually increased over time.

    Small behavioral adjustments often create significant long-term financial improvements.

    The goal is not perfection but steady progress.

    3. Reduce High-Interest Debt

    Many consumers focus exclusively on saving money while ignoring expensive debt obligations.

    However, reducing high-interest debt is often one of the fastest ways to improve overall financial health.

    AI Savings Tools can help prioritize repayment strategies and identify opportunities to lower borrowing costs.

    Less money spent on interest means more money available for investing and saving.

    4. Redirect Savings Toward Investments

    Hidden savings become much more valuable when invested wisely.

    Instead of allowing extra cash to sit idle, consumers can use those funds to build long-term wealth.

    One effective strategy is creating an income-producing portfolio through dividend investing.

    To get started, explore our
    How to Build a Dividend Portfolio
    guide.

    You can also review our
    Top Dividend Stocks USA 2026
    article for additional investment ideas.

    5. Set Clear Financial Goals

    AI performs best when it has a target.

    Whether your goal is building an emergency fund, paying off debt, purchasing a home, or investing for retirement, clearly defined objectives help AI tools generate more useful recommendations.

    Tracking progress regularly increases motivation and improves long-term consistency.

    Recommended Financial Resources

    📘

    The Psychology of Money by Morgan Housel

    📘

    Atomic Habits by James Clear

    💰

    Rocket Money Budgeting Platform

    Consumers who consistently apply AI-generated recommendations often discover that small savings improvements compound over time.

    As AI Savings Tools continue evolving, they will play an increasingly important role in helping Americans improve financial discipline, eliminate wasteful spending, and accelerate wealth-building efforts.

    Future of AI Savings Tools (2026–2030)

    The future of AI Tools That Automatically Find Hidden Savings looks incredibly promising. As artificial intelligence becomes more advanced, consumers will gain access to smarter financial tools that can identify savings opportunities faster and with greater accuracy.

    Between 2026 and 2030, experts expect AI Savings Tools to evolve from simple budgeting assistants into full-service financial advisors capable of managing many aspects of personal finance automatically.

    For Americans looking to improve financial security, these innovations could become game changers.

    AI Financial Assistants

    Future AI systems will function like personal financial coaches.

    Instead of simply tracking spending, AI assistants will proactively recommend actions that improve financial health.

    For example, they may suggest refinancing debt, increasing retirement contributions, switching financial products, or adjusting spending habits before financial problems arise.

    This level of personalization could help consumers make smarter financial decisions every day.

    Hyper-Personalized Budgeting

    Traditional budgeting often relies on generic rules.

    Future AI Savings Tools will create highly customized financial plans based on individual income, goals, lifestyle, and spending behavior.

    As a result, recommendations will become more relevant and effective.

    Consumers may receive real-time alerts that help prevent overspending before it happens.

    Smart Banking Integration

    Banks are increasingly integrating artificial intelligence into everyday financial services.

    Future AI Savings Tools will likely connect directly with checking accounts, savings accounts, investment platforms, and credit products.

    This integration will allow AI to optimize money movement automatically while helping consumers maximize savings opportunities.

    The result could be a fully connected financial ecosystem that works continuously in the background.

    Greater Financial Awareness

    One of the biggest benefits of AI is increased financial awareness.

    Many consumers struggle because they do not clearly understand where their money goes each month.

    Advanced AI systems will provide deeper insights and more actionable recommendations than traditional budgeting tools.

    This could lead to higher savings rates and stronger long-term financial outcomes.

    Frequently Asked Questions

    1. What are AI Savings Tools?

    AI Savings Tools use artificial intelligence to analyze spending patterns, identify wasteful expenses, and recommend ways to save money.

    2. Can AI really find hidden savings?

    Yes. AI can identify forgotten subscriptions, excessive fees, inefficient spending habits, and other opportunities that consumers often overlook.

    3. Are AI Savings Tools safe to use?

    Most reputable platforms use strong encryption and security measures. Consumers should always choose trusted financial providers.

    4. How much money can AI Savings Tools help save?

    Results vary, but many users save hundreds or even thousands of dollars annually by eliminating unnecessary expenses and optimizing spending.

    5. Can AI Savings Tools help with investing?

    Many platforms now combine budgeting, saving, and investing features to help users build wealth more efficiently.

    6. Will AI replace human financial advisors?

    AI will likely complement human advisors rather than replace them entirely. Complex financial planning often benefits from professional guidance.

    Conclusion

    AI Tools That Automatically Find Hidden Savings are transforming personal finance in America.

    By identifying spending leaks, optimizing subscriptions, reducing unnecessary expenses, and automating savings, AI helps consumers keep more of their money and make smarter financial decisions.

    The same technology driving AI Savings Tools is also changing investing, retirement planning, budgeting, and wealth management.

    To explore how artificial intelligence is reshaping the financial world, visit our
    AI Investing Guide 2026.

    For additional consumer finance information, visit:

    📩 Join Our Free Finance Newsletter

    Get AI investing insights, saving strategies, budgeting tips, and wealth-building ideas delivered directly to your inbox.


    Subscribe today and discover smarter ways to grow your money.


    👨‍💼 About the Author

    Subhash Rukade writes about AI, investing, personal finance, budgeting, and wealth-building strategies. His mission is to help readers make informed financial decisions and achieve long-term financial success.


    🚀 Thank you for reading. Every dollar saved today can become an investment in your future tomorrow.
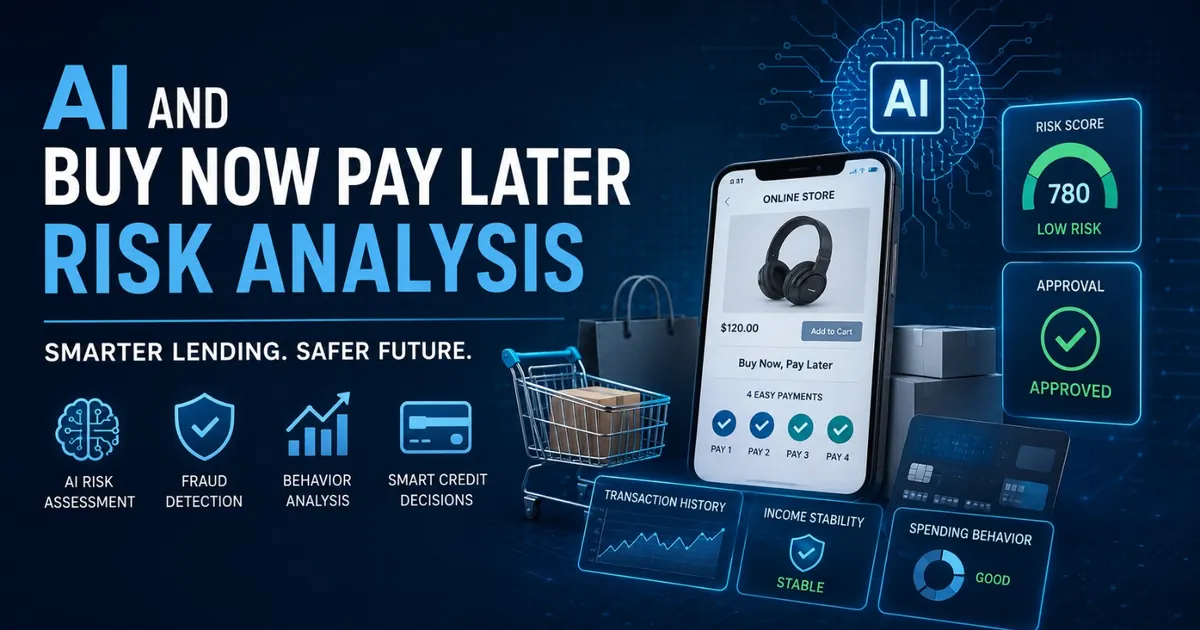
  • AI and Buy Now Pay Later Risk Analysis: Complete 2026 Guide

    AI and Buy Now Pay Later Risk Analysis: Complete 2026 Guide


    AI and Buy Now Pay Later Risk Analysis: Complete 2026 Guide

    Author: Subhash Rukade

    Published: June 14, 2026

    AI BNPL Risk

    Why AI and Buy Now Pay Later Risk Analysis Matters in 2026

    AI and Buy Now Pay Later Risk Analysis is becoming one of the most important developments in consumer finance. As millions of Americans use Buy Now Pay Later services for online shopping, travel, electronics, and everyday purchases, lenders need smarter ways to evaluate risk and protect both consumers and businesses.

    Traditional lending models often rely heavily on credit scores and historical borrowing records. However, modern BNPL providers now use artificial intelligence to analyze spending behavior, income patterns, repayment history, banking activity, and fraud indicators within seconds.

    This shift allows lenders to make faster and more accurate decisions while helping responsible consumers gain access to flexible payment options.

    The same technology transforming BNPL lending is also reshaping investing, retirement planning, and personal finance. To explore these innovations further, read our
    AI Investing Guide 2026.

    In this guide, you’ll learn how AI evaluates Buy Now Pay Later applications, the technologies behind AI risk analysis, real-world examples, common mistakes consumers make, and what the future of BNPL lending may look like in America.

    How AI Evaluates Buy Now Pay Later Applications

    Modern AI and Buy Now Pay Later Risk Analysis systems help lenders make faster and smarter decisions than traditional lending models.

    Instead of reviewing only a credit score, artificial intelligence evaluates multiple financial signals to determine whether an applicant can responsibly manage Buy Now Pay Later payments.

    This allows BNPL providers to reduce lending risk while improving approval accuracy.

    AI Risk Scoring

    One of the most important parts of AI BNPL Risk analysis is automated risk scoring.

    AI systems collect financial information and assign a risk level to each applicant. The lower the risk score, the higher the likelihood of approval.

    Unlike traditional underwriting, AI can analyze hundreds of variables simultaneously and identify patterns that human reviewers may overlook.

    Income and Cash Flow Analysis

    Many BNPL providers now use artificial intelligence to evaluate income stability and cash flow behavior.

    Instead of focusing only on reported income, AI examines whether consumers maintain consistent deposits, healthy account balances, and reliable spending habits.

    This helps lenders understand whether future installment payments are likely to be made on time.

    Spending Behavior Monitoring

    AI also evaluates spending patterns to determine overall financial responsibility.

    For example, a consumer who regularly pays bills on time and maintains reasonable spending habits may appear less risky than someone who frequently overspends.

    Behavioral analysis has become one of the most valuable components of AI and Buy Now Pay Later Risk Analysis.

    Fraud Detection Systems

    Fraud prevention is another major advantage of AI lending technology.

    Artificial intelligence can detect suspicious activity, unusual transactions, identity inconsistencies, and abnormal purchasing behavior within seconds.

    These systems help protect both consumers and BNPL providers from financial losses.

    Credit History Review

    Although AI uses advanced analytics, credit history still matters.

    Payment history, existing debt levels, credit utilization, and previous borrowing behavior remain important indicators during the approval process.

    However, AI combines these traditional factors with many additional data points to create a more complete financial profile.

    Traditional Lending vs AI BNPL Analysis

    FactorTraditional LendingAI BNPL Risk Analysis
    Decision SpeedHours or DaysSeconds or Minutes
    Data SourcesLimitedHundreds of Variables
    Fraud DetectionBasic ChecksAdvanced AI Monitoring
    PersonalizationLowHigh
    Risk AssessmentMostly Credit ScoreBehavior + Financial Data

    Consumers considering flexible payment options should also compare BNPL services with traditional rewards cards. Our
    Best Credit Cards 2026
    guide can help you choose the right option for your financial goals.

    As AI continues evolving, lenders are becoming more effective at balancing convenience with responsible lending practices. This is one reason AI and Buy Now Pay Later Risk Analysis is expected to remain a major part of consumer finance throughout 2026 and beyond.

    AI Technologies Behind Buy Now Pay Later Risk Analysis

    The rapid growth of Buy Now Pay Later services would not be possible without advanced artificial intelligence systems working behind the scenes.

    Modern AI and Buy Now Pay Later Risk Analysis platforms use multiple technologies to evaluate borrowers, predict repayment behavior, and reduce financial risk.

    These systems help lenders approve qualified applicants quickly while maintaining responsible lending standards.

    Machine Learning

    Machine learning serves as the foundation of most AI BNPL Risk systems.

    Banks and BNPL providers train machine learning models using millions of historical transactions and repayment records.

    The system learns which financial behaviors are associated with successful repayment and which patterns may indicate elevated risk.

    As more data becomes available, the model continuously improves its accuracy.

    This allows lenders to adapt to changing consumer behavior and economic conditions much faster than traditional lending systems.

    Predictive Analytics

    Predictive analytics helps AI estimate the probability that a borrower will successfully complete future installment payments.

    Rather than focusing only on past financial behavior, predictive models forecast future outcomes based on current financial patterns.

    For example, AI may identify a borrower with stable income and low debt as more likely to make payments on time compared to someone showing signs of financial stress.

    This capability improves lending decisions while reducing default rates.

    Behavioral Analysis

    Behavioral analysis has become one of the most valuable tools in AI and Buy Now Pay Later Risk Analysis.

    AI evaluates spending habits, purchase frequency, repayment patterns, account activity, and overall financial discipline.

    These insights help lenders understand how consumers manage money beyond traditional credit scores.

    A borrower who consistently demonstrates responsible financial behavior may receive a more favorable risk assessment.

    Open Banking Data

    With customer permission, many BNPL providers now use open banking technology to access additional financial information.

    This may include transaction history, account balances, income deposits, and spending trends.

    The result is a more complete picture of financial health and repayment capacity.

    Open banking is expected to play an increasingly important role in AI lending decisions over the coming years.

    Debt-to-Income Calculator Example

    One important metric used during AI BNPL Risk evaluations is the debt-to-income ratio.

    Formula:

    Debt-to-Income Ratio = Monthly Debt Payments ÷ Monthly Income × 100

    Example:

    • Monthly Income = $5,000
    • Monthly Debt Payments = $1,500

    Calculation:

    ($1,500 ÷ $5,000) × 100 = 30%

    A lower debt-to-income ratio generally improves lending decisions because it indicates stronger repayment capacity.

    To learn how artificial intelligence is transforming budgeting, saving, and investing, explore our
    AI Personal Finance 2026
    guide.

    By combining machine learning, predictive analytics, behavioral analysis, and open banking data, AI lending platforms can make more informed decisions while creating a safer and more efficient BNPL ecosystem.

    Real-World Case Study: How AI Evaluates BNPL Risk

    To understand how AI and Buy Now Pay Later Risk Analysis works in practice, let’s look at a realistic example involving a typical American consumer.

    Meet Sarah, a 31-year-old marketing manager from Florida. Like many consumers, she frequently shops online and occasionally uses Buy Now Pay Later services for larger purchases.

    In early 2026, Sarah wanted to purchase a new laptop worth $1,200 and selected a BNPL payment option that would allow her to spread the cost across several months.

    AI and Buy Now Pay Later Risk Analysis Example

    Step 1: AI Reviews the Application

    As soon as Sarah submitted her application, the BNPL provider’s AI system began analyzing hundreds of financial variables.

    Instead of reviewing only her credit score, the AI evaluated:

    • Monthly income stability
    • Bank account activity
    • Existing debt obligations
    • Previous repayment history
    • Spending behavior
    • Current BNPL commitments
    • Fraud risk indicators

    The entire review process took only a few seconds.

    Step 2: Risk Assessment

    The AI BNPL Risk model identified several positive indicators.

    Sarah maintained a stable income, had a strong repayment history, and carried relatively low debt compared to her earnings.

    The system also found no unusual transaction patterns or fraud concerns.

    Because the overall financial profile appeared healthy, the AI assigned a low-risk score.

    Step 3: Approval Decision

    Based on the risk assessment, the application received approval almost instantly.

    The lender offered a payment schedule that fit Sarah’s financial profile while maintaining responsible lending standards.

    This demonstrates one of the biggest advantages of AI and Buy Now Pay Later Risk Analysis. Qualified consumers can receive fast approvals while lenders reduce the likelihood of future payment problems.

    📊 BNPL Case Study Summary

    • Applicant: Sarah (Florida)
    • Purchase Amount: $1,200
    • Income Stability: Strong
    • Debt Level: Moderate
    • Fraud Indicators: None
    • AI Risk Score: Low Risk
    • Decision: Approved
    • Approval Time: Under 60 Seconds

    Why This Matters

    Traditional lending systems might focus primarily on credit history. AI lending models take a broader approach by analyzing real-time financial behavior and repayment capacity.

    This allows responsible borrowers to access financing more easily while helping lenders maintain healthy risk management practices.

    Consumers preparing for economic uncertainty should also explore our
    Recession-Proof Investing 2026
    guide for additional financial planning strategies.

    As AI continues improving, BNPL providers are becoming better at identifying qualified borrowers, reducing defaults, and creating safer lending environments for both consumers and businesses.

    Common Buy Now Pay Later Mistakes Consumers Make

    While Buy Now Pay Later services offer convenience and flexibility, they can also create financial challenges when used irresponsibly.

    Many consumers focus on the small installment payments and overlook the total amount they are committing to repay.

    This is why AI and Buy Now Pay Later Risk Analysis has become so important for lenders in 2026.

    Artificial intelligence helps identify potential repayment risks, but consumers still need to make smart financial decisions.

    Let’s look at the most common mistakes that increase BNPL risk.

    1. Taking Multiple BNPL Loans at the Same Time

    One of the biggest mistakes consumers make is opening several Buy Now Pay Later agreements simultaneously.

    Each individual payment may appear manageable, but the combined obligations can quickly become difficult to track.

    Many borrowers underestimate how much they owe because payments are spread across multiple platforms.

    AI BNPL Risk systems closely monitor this behavior because multiple active BNPL accounts often increase repayment risk.

    2. Missing Installment Payments

    Late payments remain one of the strongest warning signs in AI lending models.

    Missing installments can lead to fees, account restrictions, and potential credit reporting consequences depending on the lender.

    Consistent repayment behavior helps maintain a healthy financial profile and improves future approval opportunities.

    3. Overspending Because Approval Is Easy

    Fast approvals can sometimes encourage consumers to spend more than they normally would.

    The psychological effect of splitting payments into smaller amounts may make expensive purchases feel more affordable than they actually are.

    Responsible budgeting remains essential regardless of how easy financing becomes.

    4. Ignoring the Impact on Overall Debt

    Some borrowers treat BNPL purchases differently from traditional debt.

    However, installment obligations still affect overall financial health and repayment capacity.

    AI and Buy Now Pay Later Risk Analysis models evaluate total debt exposure when determining future lending decisions.

    5. Failing to Monitor Financial Accounts

    Consumers who do not regularly review bank accounts, repayment schedules, and spending patterns are more likely to encounter financial difficulties.

    Monitoring accounts helps identify potential issues before they become serious problems.

    📊 BNPL Risk Factors Chart

    Common factors that increase BNPL repayment risk:

    • Multiple Active BNPL Loans — 30%
    • Missed Payments — 25%
    • High Debt Levels — 20%
    • Overspending Behavior — 15%
    • Income Instability — 10%

    Example Scenario

    Consider a consumer who uses four different BNPL services for electronics, furniture, clothing, and travel expenses.

    Although each payment appears affordable individually, the combined monthly obligation may exceed their budget.

    AI lending systems identify this pattern as a potential risk indicator and may adjust future approval decisions accordingly.

    Consumers interested in strengthening their overall financial discipline should also review our
    SIP Investing Guide 2026,
    which discusses long-term wealth-building habits and financial planning strategies.

    Avoiding these common mistakes can help consumers use BNPL services responsibly while maintaining stronger financial health and better borrowing opportunities in the future.

    How to Use Buy Now Pay Later Responsibly in 2026

    Buy Now Pay Later services can be useful financial tools when used correctly. However, responsible usage is essential for maintaining financial stability and avoiding unnecessary debt.

    As AI and Buy Now Pay Later Risk Analysis becomes more advanced, lenders are increasingly evaluating consumer behavior, repayment habits, and financial discipline before approving future applications.

    Consumers who manage BNPL services responsibly are more likely to benefit from faster approvals and better lending opportunities.

    1. Create a Budget Before Using BNPL

    Before making any BNPL purchase, calculate whether the future installment payments fit comfortably within your monthly budget.

    A purchase may seem affordable when divided into smaller payments, but multiple BNPL commitments can quickly add up.

    The safest approach is to treat every BNPL purchase as real debt that must be repaid on schedule.

    2. Limit the Number of Active BNPL Accounts

    Many consumers make the mistake of using several BNPL providers simultaneously.

    Managing too many installment plans increases the risk of missed payments and financial stress.

    AI BNPL Risk systems often view excessive BNPL activity as a warning sign.

    Keeping the number of active repayment plans low makes financial management much easier.

    3. Make Payments on Time

    Payment history remains one of the strongest indicators of financial responsibility.

    Late payments can result in fees, account restrictions, and lower approval chances for future financing requests.

    Setting automatic payments or calendar reminders can help ensure installment obligations are never missed.

    4. Use AI Budgeting Tools

    Modern AI-powered budgeting applications can help consumers monitor spending patterns, track upcoming payments, and identify areas where expenses can be reduced.

    These tools provide valuable insights that support better financial decision-making.

    Many consumers are already using artificial intelligence to improve budgeting, saving, and debt management.

    5. Focus on Long-Term Financial Goals

    While BNPL services can provide short-term convenience, long-term wealth building should remain a priority.

    Consumers should balance spending with saving and investing.

    Learning how to build income-generating assets can strengthen financial security and reduce reliance on short-term financing options.

    For long-term wealth-building strategies, explore our
    How to Build a Dividend Portfolio
    guide.

    Investors can also review our
    Top Dividend Stocks USA 2026
    article for additional income-focused investment ideas.

    Recommended Financial Resources

    📘

    The Psychology of Money by Morgan Housel

    📘

    I Will Teach You To Be Rich by Ramit Sethi

    📊

    Experian Credit Monitoring Services

    Consumers who combine responsible borrowing habits with smart financial planning are in the best position to benefit from Buy Now Pay Later services while avoiding unnecessary financial risk.

    As AI and Buy Now Pay Later Risk Analysis continues evolving, disciplined financial behavior will remain one of the strongest factors influencing future lending decisions.

    Future of AI and Buy Now Pay Later Risk Analysis

    The future of AI and Buy Now Pay Later Risk Analysis looks increasingly sophisticated as artificial intelligence becomes a larger part of consumer finance.

    Over the next several years, BNPL providers are expected to use more advanced risk models, real-time financial data, and predictive analytics to make lending decisions faster and more accurately.

    The goal is simple: provide responsible consumers with flexible payment options while reducing financial risk for lenders.

    Open Banking Will Improve Risk Assessment

    One of the biggest trends shaping the future of AI BNPL Risk systems is open banking.

    With customer permission, lenders can access broader financial information, including spending habits, income patterns, savings behavior, and account activity.

    This creates a more complete financial profile and allows AI systems to make better-informed lending decisions.

    More Personalized Lending Decisions

    Future AI lending models will become increasingly personalized.

    Rather than relying heavily on generic approval criteria, lenders will tailor decisions based on individual financial behavior and repayment history.

    This may help qualified borrowers gain access to financing even when traditional credit histories are limited.

    Stronger Consumer Protection

    Regulators are paying closer attention to Buy Now Pay Later services as adoption continues growing.

    Organizations such as the
    Consumer Financial Protection Bureau (CFPB),
    the
    Federal Reserve,
    and the
    U.S. Securities and Exchange Commission (SEC)
    are monitoring developments in digital lending and consumer protection.

    Future regulations may require greater transparency, stronger disclosures, and improved risk management standards across the BNPL industry.

    Frequently Asked Questions

    1. What is AI and Buy Now Pay Later Risk Analysis?

    It is the use of artificial intelligence to evaluate borrower risk, analyze financial behavior, detect fraud, and improve lending decisions for BNPL services.

    2. Does AI approve BNPL applications instantly?

    In many cases, yes. Modern AI systems can analyze financial information and generate lending decisions within seconds.

    3. Can BNPL affect credit scores?

    Depending on the provider and repayment behavior, BNPL activity may influence credit reports and future lending decisions.

    4. What factors do AI BNPL Risk systems evaluate?

    Common factors include income stability, spending patterns, repayment history, existing debt levels, account activity, and fraud indicators.

    5. Is BNPL safer than credit cards?

    Both options have advantages and risks. Responsible use remains the most important factor regardless of the financing method chosen.

    6. How can consumers reduce BNPL risk?

    Maintaining a budget, limiting active installment plans, making payments on time, and monitoring spending habits can significantly reduce risk.

    Conclusion

    Artificial intelligence is transforming the Buy Now Pay Later industry. Modern AI and Buy Now Pay Later Risk Analysis systems help lenders make smarter decisions, reduce fraud, improve approval accuracy, and create safer lending environments.

    For consumers, understanding how these systems work can lead to better financial decisions and more responsible use of BNPL services.

    The same technologies driving AI-powered lending are also changing investing, retirement planning, wealth management, and personal finance.

    To learn more about these innovations, visit our
    AI Investing Guide 2026.

    📩 Join Our Free Finance Newsletter

    Get AI finance insights, investing strategies, BNPL updates, credit tips, and wealth-building ideas delivered directly to your inbox.


    Subscribe today and stay ahead of the future of finance.


    About the Author

    Subhash Rukade writes about AI, investing, personal finance, credit management, and wealth-building strategies to help readers make smarter money decisions in a rapidly changing financial world.


    🚀 Thank you for reading. Use AI wisely, manage debt responsibly, and build a stronger financial future.

  • AI Credit Score Tools: Best 2026 Guide to Credit Improvement

    AI Credit Score Tools: Best 2026 Guide to Credit Improvement


    AI-Powered Credit Score Improvement Tools: Best 2026 Guide

    Author. Subhash Rukade

    Published: June 13, 2026

    AI Credit Score Tools

    AI-Powered Credit Score Improvement Tools: Why They Matter in 2026

    Your credit score affects more than just loan approvals. It influences mortgage rates, car financing costs, credit card offers, insurance premiums, and sometimes even employment opportunities.

    AI Credit Score Tools are helping Americans improve credit health, track credit reports, and make smarter financial decisions in 2026.

    In 2026, maintaining a strong credit score has become more important than ever for Americans who want financial flexibility and long-term wealth-building opportunities.

    Traditionally, improving a credit score required manually tracking payments, reviewing credit reports, monitoring debt balances, and understanding complex credit-scoring rules.

    Today, artificial intelligence is making that process significantly easier.

    AI-Powered Credit Score Improvement Tools are transforming the way consumers manage their financial health. These intelligent platforms analyze spending habits, monitor credit activity, identify risks, and provide personalized recommendations designed to help users improve their scores faster.

    Instead of guessing what actions might increase a credit score, consumers can now receive data-driven insights tailored specifically to their financial situation.

    For example, AI tools can notify users when credit utilization becomes too high, recommend the best time to pay down balances, identify errors on credit reports, and even predict how certain financial decisions may affect future scores.

    These capabilities help consumers make smarter financial choices while avoiding costly mistakes.

    Many of the same technologies improving credit management are also transforming investing and wealth-building strategies. Readers interested in the broader impact of artificial intelligence on personal finance should explore our
    AI Investing & Personal Finance Guide 2026.

    One reason AI Credit Score Tools have gained popularity is their ability to simplify complex financial information. Instead of reviewing hundreds of data points manually, users receive clear recommendations that are easy to understand and act upon.

    As competition among lenders continues increasing, maintaining a strong credit profile can unlock lower borrowing costs and create more opportunities to build wealth.

    In this guide, you’ll discover how AI-Powered Credit Score Improvement Tools work, the technologies behind them, practical strategies for improving your score, common mistakes to avoid, and future trends shaping credit management in America.

    How AI Credit Score Tools Work

    Modern AI-Powered Credit Score Improvement Tools do much more than simply display a credit score. These platforms continuously analyze financial data and provide personalized recommendations that help consumers make smarter decisions.

    Instead of manually reviewing credit reports and financial statements, users can rely on artificial intelligence to identify opportunities for Credit Score Improvement.

    The goal is simple: help consumers build stronger credit profiles while reducing financial mistakes.

    Credit Monitoring in Real Time

    One of the most valuable features of AI Credit Score Tools is real-time credit monitoring.

    AI systems continuously track changes across credit reports. If a new account appears, a hard inquiry is added, or a balance changes significantly, users receive immediate alerts.

    This helps consumers identify potential issues before they negatively affect their credit scores.

    Early detection is especially important when dealing with identity theft or reporting errors.

    Spending Pattern Analysis

    Artificial intelligence can analyze spending behavior and identify patterns that may impact credit health.

    For example, AI tools can detect when credit card balances are increasing too quickly or when spending habits may cause credit utilization ratios to rise above recommended levels.

    Since credit utilization plays a major role in most scoring models, these insights can be extremely valuable.

    Debt Tracking and Optimization

    Many consumers struggle to decide which debts should be paid first.

    AI-powered systems evaluate balances, interest rates, payment histories, and credit utilization levels to suggest the most effective repayment strategies.

    Some tools even estimate how specific debt payments may influence future credit scores.

    Smart Payment Reminders

    Payment history remains one of the most important factors in credit scoring.

    Missing even a single payment can significantly impact a score.

    AI systems help reduce this risk by sending personalized reminders before due dates and identifying accounts that may require immediate attention.

    These automated alerts help consumers maintain positive payment histories and avoid costly penalties.

    Personalized Recommendations

    Unlike traditional financial apps, AI Credit Score Tools provide recommendations tailored to individual financial situations.

    The system may suggest reducing utilization on a specific card, disputing a reporting error, paying down a balance before a statement closing date, or avoiding unnecessary credit applications.

    Because these recommendations are based on personal financial data, they are often far more effective than generic advice.

    Consumers interested in broader AI-driven financial strategies should also explore our
    AI Personal Finance Guide 2026.

    By combining credit monitoring, spending analysis, debt management, and personalized coaching, AI-Powered Credit Score Improvement Tools are helping Americans take greater control of their financial future.

    AI Technologies Behind Credit Score Improvement

    The success of modern AI-Powered Credit Score Improvement Tools comes from advanced technologies that analyze financial behavior, identify risks, and provide highly personalized recommendations.

    Unlike traditional credit monitoring services that mainly report information, AI actively helps consumers make better financial decisions.

    These technologies work together to support faster and smarter Credit Score Improvement.

    Machine Learning Learns Your Financial Habits

    Machine learning is the foundation of most AI Credit Score Tools.

    The technology studies spending patterns, payment history, credit utilization, account balances, and borrowing behavior.

    Over time, the system learns how users manage credit and identifies behaviors that may positively or negatively affect future scores.

    Because machine learning continuously updates itself, recommendations become more accurate as additional financial data becomes available.

    Predictive Analytics Forecasts Future Scores

    One of the most powerful features of AI is predictive analytics.

    Instead of only showing current credit scores, AI systems estimate how future actions may influence credit performance.

    For example, an AI platform might predict how paying off a credit card balance, reducing utilization, or avoiding new credit inquiries could impact a score over the next several months.

    This forward-looking approach helps consumers make more informed financial decisions.

    Behavioral Analysis Identifies Hidden Risks

    AI also uses behavioral analysis to evaluate financial habits.

    The system can identify recurring behaviors that may hurt credit health, such as consistently carrying high balances or making payments close to due dates.

    By recognizing these patterns early, AI tools can recommend corrective actions before significant damage occurs.

    Personalized Financial Recommendations

    Every consumer has a unique financial situation.

    This is why AI-Powered Credit Score Improvement Tools generate personalized recommendations rather than offering generic advice.

    The system evaluates individual credit profiles and suggests actions based on each user’s specific goals and challenges.

    These tailored recommendations often produce better results than one-size-fits-all financial guidance.

    Credit Risk Assessment

    AI systems continuously assess credit risk by analyzing multiple factors simultaneously.

    This helps consumers understand which financial behaviors are helping their scores and which actions may increase risk.

    The result is a clearer path toward long-term financial stability.

    Traditional Credit Monitoring vs AI Credit Score Tools

    FeatureTraditional MonitoringAI Credit Score Tools
    Credit TrackingBasic UpdatesReal-Time Monitoring
    RecommendationsGeneric AdvicePersonalized Guidance
    Future Score ForecastsNoYes
    Risk DetectionLimitedAdvanced Analysis
    AutomationLowHigh

    Consumers seeking better borrowing opportunities should also review our
    Best Credit Cards 2026
    guide to find products that support responsible credit building.

    These advanced technologies explain why AI Credit Score Tools are becoming an essential part of modern personal finance management.

    Real-World Example of AI Improving a Credit Score

    To understand how AI-Powered Credit Score Improvement Tools work in practice, let’s look at a realistic example.

    Meet Sarah, a 32-year-old marketing professional from Texas. She had a credit score of 645 and wanted to improve it before applying for a mortgage.

    Like many Americans, Sarah paid her bills regularly but struggled with high credit card balances and inconsistent budgeting habits.

    Although she knew her credit score needed improvement, she wasn’t sure which actions would have the greatest impact.

    AI Credit Score Improvement Example

    Step 1: Connecting Financial Accounts

    Sarah connected her credit cards, bank accounts, and credit monitoring service to an AI-powered credit management platform.

    Within minutes, the system analyzed payment history, utilization ratios, account age, debt balances, and recent credit activity.

    The AI identified several opportunities for immediate Credit Score Improvement.

    Step 2: Reducing Credit Utilization

    The platform discovered that Sarah was using nearly 75% of her available credit limits.

    Because credit utilization is a major factor in most credit scoring models, the AI recommended paying down specific balances first.

    Instead of spreading payments across multiple cards, the system identified the accounts that would provide the greatest score improvement.

    Step 3: Optimizing Payment Timing

    Many consumers don’t realize that when they make payments can matter almost as much as how much they pay.

    The AI suggested making payments before statement closing dates rather than waiting until due dates.

    This helped lower reported balances and improved utilization ratios appearing on credit reports.

    Step 4: Ongoing Monitoring and Alerts

    One of the biggest benefits of AI Credit Score Tools is continuous monitoring.

    Whenever Sarah’s balances increased or unusual activity appeared on her accounts, the system sent alerts and updated recommendations.

    This allowed her to maintain progress and avoid setbacks.

    Many of the same technologies helping consumers improve credit scores are also transforming investing and financial planning. Readers interested in these broader innovations should revisit our
    AI Investing & Personal Finance Guide 2026.

    After approximately twelve months of following AI recommendations, Sarah’s credit score increased from 645 to over 740.

    This improvement helped her qualify for more favorable mortgage terms and potentially save thousands of dollars over the life of her loan.

    For additional insights on building better financial habits, consider reading
    The Psychology of Money by Morgan Housel.
    The book provides valuable lessons about behavior, decision-making, and long-term financial success.

    Sarah’s experience demonstrates how AI-Powered Credit Score Improvement Tools can help consumers make smarter financial decisions and achieve meaningful results over time.

    Common Mistakes When Using AI Credit Score Tools

    While AI-Powered Credit Score Improvement Tools can provide valuable guidance, success still depends on how consumers use the information. Artificial intelligence can identify opportunities for improvement, but it cannot make financial decisions on your behalf.

    Many people expect immediate results after installing an AI credit app. However, improving a credit score usually requires consistency, patience, and responsible financial behavior.

    Understanding common mistakes can help consumers get the most value from modern AI Credit Score Tools.

    Ignoring AI Recommendations

    One of the most common mistakes is simply ignoring the recommendations generated by the platform.

    AI systems analyze financial data and identify actions that may improve credit health. If users fail to act on these recommendations, the benefits of the technology become limited.

    The best results occur when consumers actively follow personalized guidance.

    Maintaining High Credit Utilization

    Credit utilization remains one of the most important factors affecting credit scores.

    Many consumers continue carrying high balances even after AI tools identify utilization problems.

    A credit utilization ratio above 30% may negatively impact scores, while lower utilization levels generally support stronger credit profiles.

    Reducing balances remains one of the fastest paths to meaningful Credit Score Improvement.

    Missing Payments

    Even with automated reminders and alerts, some consumers still miss payment deadlines.

    Payment history plays a major role in most credit scoring models.

    A single late payment can remain on a credit report for years and may significantly reduce a score.

    Using automatic payments and AI reminders can help avoid this costly mistake.

    Applying for Too Much Credit

    Some consumers mistakenly believe opening multiple credit accounts will improve their scores quickly.

    In reality, excessive credit applications can generate multiple hard inquiries and increase perceived borrowing risk.

    AI-powered platforms often warn users when new applications could negatively affect credit health.

    Expecting Instant Results

    Perhaps the biggest mistake is expecting overnight success.

    Even the best AI-Powered Credit Score Improvement Tools cannot instantly repair years of poor financial habits.

    Building strong credit requires time, discipline, and consistent positive behavior.

    Consumers focused on protecting their finances during uncertain economic conditions should also explore our
    Recession-Proof Investing 2026
    guide.

    For additional consumer education, trusted resources such as the
    Consumer Financial Protection Bureau (CFPB)
    and the
    Federal Trade Commission (FTC)
    offer valuable information about credit management and financial protection.

    The most successful users combine AI-powered insights with responsible financial habits, creating a stronger foundation for long-term credit health and financial stability.

    Practical Tips to Improve Your Credit Score Faster

    While AI-Powered Credit Score Improvement Tools can provide valuable insights, the best results come from combining technology with smart financial habits. Consumers who consistently follow proven credit-building strategies often see the greatest long-term improvements.

    The good news is that many of these actions are simple to implement and can have a meaningful impact on credit health over time.

    Keep Credit Utilization Low

    One of the fastest ways to improve a credit score is reducing credit utilization.

    Credit utilization measures how much available credit you are currently using.

    Most financial experts recommend keeping utilization below 30%, while lower levels may provide even stronger benefits.

    Modern AI Credit Score Tools continuously monitor utilization ratios and notify users when balances become too high.

    Make Every Payment on Time

    Payment history remains one of the most important factors in credit scoring.

    Even a single missed payment can negatively affect a score.

    AI-powered financial apps help users stay organized by providing payment reminders, due-date alerts, and automated notifications.

    Consistent on-time payments create a strong credit foundation.

    Monitor Your Credit Reports

    Errors on credit reports can sometimes reduce scores unnecessarily.

    Consumers should review credit reports regularly and dispute inaccurate information when necessary.

    Many AI-Powered Credit Score Improvement Tools automatically monitor reports and notify users when significant changes occur.

    Early detection can prevent small issues from becoming larger problems.

    Use AI Alerts and Automation

    One of the biggest advantages of AI technology is automation.

    AI systems can track balances, monitor spending patterns, detect unusual activity, and provide personalized recommendations.

    These automated insights help consumers stay proactive rather than reactive.

    Build Positive Credit History

    Credit improvement is not only about avoiding mistakes.

    Building a long history of responsible credit use is equally important.

    Maintaining older accounts, managing balances responsibly, and making consistent payments can strengthen credit profiles over time.

    Manual Credit Improvement vs AI Credit Improvement

    FeatureManual ApproachAI Credit Score Tools
    Credit MonitoringPeriodic ReviewsReal-Time Alerts
    Debt AnalysisManual CalculationsAutomated Insights
    Payment TrackingSelf-MonitoringSmart Reminders
    RecommendationsGeneric AdvicePersonalized Guidance
    EfficiencyTime-ConsumingHighly Efficient

    Investors interested in strengthening their overall financial future should also explore our
    Top Dividend Stocks USA 2026
    guide for long-term wealth-building ideas.

    Another excellent personal finance resource is
    The Simple Path to Wealth by JL Collins.
    The book offers practical lessons on investing, financial independence, and long-term money management.

    When combined with responsible financial habits, AI-Powered Credit Score Improvement Tools can help consumers make smarter decisions and achieve stronger credit profiles over time.

    Future of AI Credit Score Improvement

    The future of AI-Powered Credit Score Improvement Tools looks incredibly promising. As artificial intelligence continues evolving, consumers will gain access to smarter financial insights, faster recommendations, and more personalized credit-building strategies.

    Instead of simply monitoring credit reports, future AI platforms will act like digital financial coaches that help users make better decisions every day.

    Predictive Credit Coaching

    One of the biggest trends expected in the coming years is predictive credit coaching.

    AI systems will not only analyze current credit data but also forecast future score changes based on financial behavior.

    Consumers will receive personalized guidance before problems occur, helping them avoid actions that may negatively impact their credit profiles.

    AI Financial Assistants

    Many experts believe AI assistants will become a standard part of personal finance management.

    These assistants may automatically track spending, monitor debt levels, recommend payment strategies, and help consumers improve financial habits.

    This level of automation could make credit management easier than ever before.

    Open Banking and Personalized Credit Strategies

    As open banking expands across the financial industry, AI tools will gain access to richer financial data.

    This will allow platforms to generate highly personalized recommendations tailored to each consumer’s goals, income, debt profile, and spending patterns.

    The result will be more effective and accurate credit improvement strategies.

    Frequently Asked Questions

    1. Do AI Credit Score Tools really work?

    Yes. Many AI-powered platforms help consumers identify opportunities to improve payment history, lower utilization, and manage debt more effectively.

    2. Can AI increase my credit score instantly?

    No. Credit improvement takes time. AI provides guidance, but long-term results depend on consistent financial habits.

    3. Are AI Credit Score Tools safe?

    Most reputable platforms use strong encryption and security measures to protect financial data.

    4. What is the biggest benefit of AI-powered credit monitoring?

    The biggest advantage is personalized recommendations based on individual financial behavior.

    5. Can AI help detect errors on credit reports?

    Yes. Many tools monitor credit reports and alert users when unusual changes or potential errors appear.

    6. Who should use AI-Powered Credit Score Improvement Tools?

    Anyone looking to improve credit health, qualify for better loan terms, or strengthen their overall financial profile can benefit.

    Conclusion

    Strong credit remains one of the most valuable financial assets Americans can build. Better credit scores often lead to lower borrowing costs, improved financial opportunities, and greater long-term wealth-building potential.

    By combining technology, automation, and personalized insights, AI-Powered Credit Score Improvement Tools are helping consumers make smarter financial decisions and improve credit health more efficiently than ever before.

    To learn more about how artificial intelligence is transforming investing, wealth building, and personal finance, revisit our
    AI Investing & Personal Finance Guide 2026.

    Investors focused on long-term financial growth should also explore our
    How to Build a Dividend Portfolio
    guide.

    📩 Join Our Free Finance Newsletter

    Get AI finance insights, credit-building strategies, investing tips, and wealth-building ideas delivered directly to your inbox.

    Subscribe today and take control of your financial future!

    📘 Recommended Reading:

    I Will Teach You To Be Rich by Ramit Sethi


    About the Author

    Subhash Rukade writes about AI, investing, credit management, and personal finance to help readers make smarter money decisions and build long-term wealth.

    🚀 Thank you for reading. Build stronger credit, make smarter financial decisions, and create a brighter financial future!

  • AI Investing & Personal Finance Guide 2026: How Artificial Intelligence Is Reshaping Wealth Building

    AI Investing & Personal Finance Guide 2026: How Artificial Intelligence Is Reshaping Wealth Building


    AI Investing & Personal Finance Guide 2026: How Artificial Intelligence Is Reshaping Wealth Building

    Published: June 10, 2026

    Author: Subhash Rukade

    AI Investing

    Introduction: Why AI Investing Is Becoming Essential for American Investors in 2026

    AI Investing is no longer a futuristic idea discussed only by technology companies and Wall Street analysts. In 2026, it has become one of the fastest-growing trends in personal finance and wealth management. Millions of Americans are using artificial intelligence to analyze investments, improve portfolio performance, manage risk, and make smarter financial decisions.

    The financial world is changing rapidly. Every day, investors face an overwhelming amount of information. Stock market updates, earnings reports, economic data, inflation trends, interest-rate announcements, and geopolitical events all influence investment performance. For the average investor, keeping track of everything can feel impossible.

    This is where AI Investing is creating a major advantage. Instead of manually reviewing hundreds of reports and market updates, investors can now use artificial intelligence to process enormous amounts of information within seconds. These tools help identify trends, evaluate risks, and uncover opportunities that might otherwise be missed.

    One reason AI Investing has become so popular is accessibility. A few years ago, advanced financial analysis tools were available mainly to hedge funds and institutional investors. Today, many of the same technologies are available through mobile apps, brokerage platforms, and personal finance tools that everyday Americans can use.

    Artificial intelligence is helping investors make decisions based on data rather than emotion. Fear and greed have always been two of the biggest obstacles to successful investing. Many investors buy when markets are rising and panic when markets decline. AI Investing helps reduce these emotional mistakes by focusing on facts, probabilities, and long-term trends.

    Another reason for the growing popularity of AI Investing is its ability to work alongside proven investing strategies. For example, investors who follow systematic investing approaches can use artificial intelligence to monitor portfolio performance and identify opportunities without abandoning their long-term plans.

    If you’re building wealth through regular investing, be sure to explore our
    Complete SIP Investing Guide 2026,
    which explains how consistent investing habits can help investors grow wealth over time.

    Artificial intelligence is also transforming broader financial management. Budgeting tools, retirement calculators, spending analysis platforms, and financial planning apps now use AI to provide more personalized recommendations.

    For a deeper look at how artificial intelligence is reshaping everyday money management, visit our
    AI Personal Finance Guide 2026.

    Trusted financial organizations continue to encourage investors to combine technology with financial education. Resources from the SEC, FINRA, and Investor.gov remain valuable sources of information for understanding investment risks and making informed decisions.

    The goal of AI Investing is not to replace human judgment. Instead, it provides investors with better tools, faster analysis, and stronger insights. Investors still need patience, discipline, diversification, and a long-term mindset. However, artificial intelligence can help make those decisions more informed and more efficient.

    Over the next decade, AI Investing is expected to become a standard part of personal finance. Investors who understand how these tools work today may be better prepared to take advantage of the opportunities they create tomorrow.

    How AI Investing Works: The Technology Behind Smarter Financial Decisions

    To understand why AI Investing is becoming so popular in 2026, it’s important to understand the technology behind it. While artificial intelligence may sound complex, its purpose is simple: help investors make better decisions using data, automation, and advanced analysis.

    Traditional investing often requires hours of research. Investors must read company reports, analyze financial statements, monitor economic trends, and stay updated on market news. AI Investing simplifies this process by processing massive amounts of information in seconds.

    Instead of manually reviewing hundreds of data points, investors can use AI-powered tools that identify trends, evaluate risk, and provide actionable insights. This allows investors to focus more on strategy and less on time-consuming research.

    Machine Learning: The Core of AI Investing

    Machine learning is one of the most important technologies behind AI Investing. These systems learn from historical market data and continuously improve as new information becomes available.

    For example, machine learning models can study stock price movements, earnings reports, economic indicators, and market behavior from previous years. By recognizing patterns, these systems help identify opportunities and risks that may influence future investment decisions.

    Unlike traditional software, machine learning systems adapt over time. This makes AI Investing more flexible and responsive to changing market conditions.

    Predictive Analytics and Market Forecasting

    Another major component of AI Investing is predictive analytics. These systems analyze historical data and current market conditions to estimate potential future outcomes.

    While no technology can predict the future with complete accuracy, predictive analytics helps investors evaluate probabilities rather than relying solely on guesswork.

    Many AI Investing platforms use predictive models to estimate portfolio risk, identify market opportunities, and recommend investment strategies that align with long-term financial goals.

    Natural Language Processing and Financial News

    Financial markets react quickly to news. Earnings announcements, inflation reports, Federal Reserve decisions, and global events can all impact investments.

    AI Investing platforms often use Natural Language Processing (NLP) to read and analyze financial news, analyst reports, earnings calls, and market commentary. These systems can identify positive or negative sentiment and highlight important developments for investors.

    This allows investors to stay informed without spending hours reading financial publications every day.

    Portfolio Optimization and Risk Management

    One of the biggest advantages of AI Investing is portfolio optimization. Artificial intelligence can evaluate thousands of investment combinations and recommend allocations that match an investor’s goals and risk tolerance.

    AI systems also monitor portfolios continuously. If risks increase or market conditions change significantly, investors can receive alerts or recommendations that help protect long-term performance.

    As AI Investing technology continues to improve, investors are gaining access to tools that were once available only to large financial institutions. These innovations are making investing more efficient, more accessible, and more data-driven than ever before.

    How AI Investing Analyzes Stocks in Seconds and Identifies Opportunities

    One of the biggest reasons AI Investing has become so popular among American investors is speed. Traditional stock research can take hours or even days. Investors often need to review earnings reports, financial statements, analyst opinions, market news, and economic data before making a decision. AI Investing platforms can analyze much of this information within seconds.

    This speed allows investors to react faster to changing market conditions and focus on opportunities that match their financial goals. Instead of manually sorting through thousands of data points, AI systems organize information into clear and actionable insights.

    How AI Investing Analyzes Stocks

    Modern AI Investing platforms collect information from multiple sources. These include company earnings reports, stock price history, valuation metrics, industry trends, analyst forecasts, and broader economic indicators.

    Artificial intelligence processes this information using machine learning models. The system looks for patterns that have historically influenced stock performance and uses those patterns to support future investment decisions.

    This process helps investors identify strong companies, monitor risk levels, and discover opportunities that might otherwise go unnoticed.

    Investors who want a deeper understanding of this process can explore our upcoming guide,
    How AI Analyzes Stocks in Seconds
    which explains how artificial intelligence processes market data at scale.

    Market Sentiment Analysis

    Financial markets are influenced not only by numbers but also by investor sentiment. Positive news often encourages buying activity, while negative headlines can trigger selling pressure.

    AI Investing platforms use Natural Language Processing (NLP) technology to analyze news articles, earnings call transcripts, analyst reports, and public discussions. These systems evaluate sentiment and help investors understand how the market may react to important events.

    By combining sentiment analysis with traditional financial data, AI Investing tools provide a more complete view of potential opportunities and risks.

    Pattern Recognition and Big Data

    Artificial intelligence excels at identifying patterns. AI Investing systems can evaluate years of historical data and compare it with current market conditions.

    For example, AI may identify relationships between earnings growth, revenue trends, interest rates, and stock performance. These insights help investors understand which companies are gaining momentum and which may face challenges.

    Because AI systems analyze much larger datasets than humans can realistically process, they often uncover opportunities hidden within complex market information.

    Can AI Predict Market Crashes?

    A common question among investors is whether AI Investing can predict stock market crashes. The answer is that no technology can accurately forecast every market decline.

    However, AI systems can identify warning signs such as unusual volatility, weakening economic conditions, declining earnings growth, and shifting investor sentiment.

    Investors interested in this topic can learn more in our upcoming guide,
    Can AI Predict Stock Market Crashes?

    AI vs Human Investors

    Artificial intelligence offers speed and data-processing power, while human investors bring experience, judgment, and long-term perspective. The most successful investors often combine both approaches.

    Our future article,
    AI Stock Pickers vs Human Investors in 2026
    will explore this debate in greater detail.

    As AI Investing continues to evolve, investors are gaining access to faster research tools, deeper market insights, and more sophisticated analysis than ever before.

    Best AI Investing Strategies for Beginners in 2026

    Understanding how AI Investing analyzes stocks is important, but knowing how to apply that information is what truly helps investors build wealth. In 2026, artificial intelligence is helping investors create smarter portfolios, reduce emotional decisions, and stay focused on long-term financial goals.

    The biggest advantage of AI Investing is that it allows investors to make data-driven decisions instead of reacting to market headlines. Whether someone is just starting their investment journey or already has years of experience, AI-powered tools can help improve portfolio management and risk control.

    Start With Diversification

    Diversification remains one of the most effective investing principles. Instead of placing all your money into one stock or sector, diversification spreads risk across multiple investments.

    AI Investing platforms can analyze thousands of assets and recommend balanced portfolios based on an investor’s goals and risk tolerance. This helps reduce concentration risk while creating opportunities for long-term growth.

    Many beginners struggle with asset allocation. AI systems simplify this process by automatically suggesting diversified portfolios that match individual objectives.

    Use Automated Investing

    One of the biggest reasons investors underperform is emotional decision-making. Fear during market declines and excitement during market rallies often lead to poor investment choices.

    AI Investing platforms help solve this problem through automation. Investors can set contribution schedules, portfolio rules, and investment goals while allowing technology to handle routine tasks.

    This approach encourages consistency and helps investors remain focused on long-term wealth creation.

    AI Portfolio Management Explained

    Portfolio management is another area where AI Investing is creating significant value. Artificial intelligence can continuously monitor portfolio performance, evaluate risk exposure, and identify opportunities for improvement.

    Instead of reviewing investments only a few times each year, AI systems analyze portfolios every day and provide recommendations when adjustments may be beneficial.

    Readers interested in learning more can explore our upcoming guide,

    AI Portfolio Management Explained: Smart Investing With AI

    Best AI Investing Strategies Comparison

    StrategyRisk LevelBest For
    Automated ETF InvestingLowBeginners
    AI Portfolio ManagementMediumLong-Term Investors
    AI Stock ScreeningMedium-HighActive Investors
    Growth-Focused AI InvestingHighAggressive Investors

    Learn From Proven Investing Principles

    Technology can improve investing decisions, but timeless financial principles still matter. One highly recommended resource is
    The Psychology of Money by Morgan Housel.

    The book focuses on investor behavior, patience, and long-term thinking—qualities that remain essential even in the age of AI Investing.

    Common Mistakes Investors Should Avoid

    Many investors assume AI Investing can guarantee profits. This is one of the biggest misconceptions in modern finance.

    Artificial intelligence can provide valuable insights, but successful investing still requires discipline, diversification, and realistic expectations. Investors should avoid blindly following recommendations without understanding their overall strategy.

    Future readers can learn more in our upcoming article,

    Biggest AI Investing Mistakes to Avoid in 2026

    Investors who combine AI Investing with proven wealth-building principles often place themselves in a stronger position to achieve long-term financial success.

    For beginners, one of the best starting points is understanding the basics of asset allocation, diversification, and automation. AI tools can support these strategies, but consistent investing habits remain the foundation of wealth creation.

    Our upcoming guide,
    Best AI Investing Strategies for Beginners in 2026
    will provide a deeper look at beginner-friendly approaches that can help investors build confidence and long-term wealth.

    How AI Investing Is Helping Americans Build Wealth Faster in 2026

    Building wealth has never been easy. It requires discipline, patience, and smart financial decisions. In 2026, AI Investing is making that journey easier by helping investors analyze opportunities, manage risk, and stay focused on long-term goals.

    For years, sophisticated financial tools were available mainly to hedge funds and institutional investors. Today, AI Investing platforms are giving everyday Americans access to powerful technology that can improve decision-making and support wealth-building strategies.

    Whether someone is investing for retirement, financial independence, passive income, or long-term growth, artificial intelligence is becoming an important part of the modern investor’s toolkit.

    How Millionaires Are Using AI in 2026

    Many high-net-worth investors have embraced AI Investing because it helps them process information faster and make more informed decisions. Rather than relying only on traditional research methods, they use artificial intelligence to analyze market trends, evaluate opportunities, and monitor portfolio performance.

    AI systems can review earnings reports, economic data, analyst forecasts, and valuation metrics simultaneously. This allows investors to identify opportunities more efficiently while staying focused on long-term wealth creation.

    Readers interested in advanced investing techniques can explore our upcoming guide,
    How Millionaires Are Using AI in 2026

    AI Wealth Management for Middle-Class Americans

    One of the most exciting developments in AI Investing is accessibility. Wealth management is no longer limited to wealthy individuals with large investment accounts.

    Today, middle-class families can access AI-powered financial tools that help create investment plans, monitor portfolios, track progress, and improve financial decision-making.

    These platforms often provide personalized recommendations based on goals, risk tolerance, and investment timelines. This allows investors to receive guidance without paying the high fees traditionally associated with wealth management services.

    For a deeper look at this trend, check out our future article,
    AI Wealth Management for Middle-Class Americans

    Best AI Wealth Building Tools in 2026

    The rapid growth of AI Investing has led to the development of powerful financial tools designed to help investors build wealth more efficiently.

    • Portfolio monitoring systems
    • Risk management platforms
    • Retirement forecasting tools
    • Dividend analysis software
    • Investment screening platforms
    • Personal finance dashboards

    These tools help investors save time while improving the quality of their financial decisions.

    Our upcoming guide,
    Best AI Wealth Building Tools in 2026
    will review some of the most useful platforms available today.

    Real-World Example of AI Investing and Wealth Building

    Imagine a 35-year-old investor who contributes money to a diversified portfolio every month. Instead of trying to predict short-term market movements, he uses an AI Investing platform to monitor portfolio performance and identify opportunities for improvement.

    The system automatically evaluates risk levels, suggests diversification adjustments, and provides insights based on changing market conditions. Over time, the investor remains disciplined and avoids many emotional decisions that often hurt long-term performance.

    This combination of consistency and technology can significantly improve the wealth-building process.

    Combining AI Investing With Dividend Strategies

    Many investors use AI Investing alongside dividend-focused strategies. Artificial intelligence can screen thousands of companies and identify businesses with strong dividend growth, healthy cash flow, and sustainable payout ratios.

    If you’re interested in creating a reliable income stream, explore our
    How to Build a Dividend Portfolio
    guide.

    The combination of dividend investing and AI Investing is becoming increasingly popular among investors seeking both passive income and long-term growth.

    Ultimately, wealth building is still driven by consistency, patience, and smart financial habits. AI Investing simply provides investors with better tools to execute those principles more effectively.

    AI Investing, Passive Income, and the Path to a Million-Dollar Portfolio

    One of the biggest goals for many American investors is creating passive income while growing long-term wealth. In 2026, AI Investing is helping investors achieve both objectives more efficiently by identifying opportunities, monitoring portfolios, and supporting disciplined investment strategies.

    Passive income allows investors to generate earnings without actively trading or working additional hours. While building passive income still requires time and capital, artificial intelligence is making the process easier by helping investors find quality investments and avoid common mistakes.

    AI and Passive Income Opportunities

    AI Investing platforms can analyze thousands of investments and identify assets that may generate reliable income. These include dividend-paying stocks, exchange-traded funds (ETFs), real estate investment trusts (REITs), and other income-focused securities.

    Instead of manually researching hundreds of companies, investors can use artificial intelligence to screen investments based on dividend growth, earnings stability, payout ratios, cash flow strength, and valuation metrics.

    This saves time and helps investors focus on opportunities that align with their financial goals.

    Readers interested in income-generating strategies can explore our upcoming guide,
    AI and Passive Income Opportunities

    Can AI Help Build a Million-Dollar Portfolio?

    Many investors wonder whether AI Investing can help them reach major financial milestones such as building a million-dollar portfolio.

    The answer is that artificial intelligence can support the process, but it cannot replace discipline, patience, and consistent investing. Wealth is typically built through regular contributions, long-term compounding, diversification, and smart decision-making.

    AI Investing improves efficiency by identifying opportunities, monitoring risk, and helping investors stay focused on their plans during periods of market volatility.

    Over time, these advantages can contribute to stronger financial outcomes.

    For a deeper look at this topic, read our future article,

    Can AI Help Build a Million-Dollar Portfolio?

    Dividend Investing and Long-Term Growth

    Dividend investing remains one of the most popular passive income strategies in America. Many AI Investing tools can automatically evaluate dividend-paying companies and identify businesses with strong fundamentals.

    Investors seeking dividend opportunities can also explore our
    Top Dividend Stocks USA 2026
    guide for additional research and ideas.

    Combining dividend investing with AI-powered analysis allows investors to build portfolios that generate income while maintaining long-term growth potential.

    The Rise of AI Financial Assistants

    Another growing trend is the development of AI-powered financial assistants. These tools can track spending, monitor investments, provide reminders, analyze budgets, and answer financial questions in real time.

    As technology advances, these assistants may become a central part of everyday financial management for millions of Americans.

    Readers can learn more in our upcoming guide,

    AI Financial Assistants: The Next Big Money Trend

    AI Investing is not simply changing how people invest. It is creating an entire financial ecosystem designed to help investors save time, improve decision-making, generate passive income, and build wealth more effectively over the long term.

    How AI Investing Is Transforming Retirement Planning in 2026

    Retirement planning has always been one of the most important financial goals for American investors. However, predicting future expenses, inflation, healthcare costs, investment returns, and life expectancy is not easy. In 2026, AI Investing is helping investors make more informed retirement decisions by using advanced forecasting tools and personalized financial analysis.

    Instead of relying solely on basic retirement calculators, investors can now use artificial intelligence to create dynamic retirement plans that adjust as market conditions and personal circumstances change.

    This technology is helping Americans prepare for retirement with greater confidence and a clearer understanding of their long-term financial needs.


    How AI Is Transforming Retirement Planning

    Traditional retirement planning often relies on fixed assumptions. Investors enter estimated retirement ages, expected returns, and savings goals into a calculator and receive a projection.

    AI Investing platforms take a more advanced approach. These systems continuously evaluate market conditions, portfolio performance, inflation trends, and spending habits. As new information becomes available, retirement projections can be updated automatically.

    This creates a more realistic and personalized planning experience.

    Readers interested in learning more can explore our future guide,

    How AI Is Transforming Retirement Planning for Americans

    AI Retirement Calculators: Are They Accurate?

    Modern retirement calculators powered by artificial intelligence can analyze significantly more variables than traditional planning tools.

    These systems often consider:

    • Portfolio growth rates
    • Expected inflation
    • Healthcare expenses
    • Social Security benefits
    • Investment risk levels
    • Tax considerations
    • Life expectancy estimates

    While no calculator can predict the future perfectly, AI Investing tools often provide more flexible and realistic forecasts because they continuously adapt to changing conditions.

    Investors can learn more in our upcoming article,

    AI Retirement Calculators: Are They Accurate in 2026?

    Using AI to Estimate Retirement Income

    One of the biggest concerns for retirees is generating enough income throughout retirement. AI Investing platforms help address this challenge by estimating future income from multiple sources.

    These sources may include retirement accounts, dividend-paying investments, pensions, Social Security benefits, and taxable investment portfolios.

    Rather than focusing only on account balances, AI systems evaluate income sustainability and withdrawal strategies. This gives investors a better understanding of how long their money may last under different market conditions.

    For a deeper analysis, check out our future guide,

    Using AI to Estimate Retirement Income: Complete 2026 Guide

    Portfolio Longevity and Retirement Risk

    A major retirement risk is outliving your savings. AI Investing tools address this issue by running thousands of simulations based on different economic and market scenarios.

    These projections help investors understand how inflation, market downturns, healthcare costs, and withdrawal rates could affect retirement outcomes.

    By identifying risks early, investors can make adjustments before problems become serious.

    A Timeless Resource for Retirement Investors

    Technology is changing retirement planning, but proven investing principles still matter. One highly recommended book is
    The Simple Path to Wealth by JL Collins.

    The book focuses on long-term investing, financial independence, and building wealth through simple, disciplined strategies that work well alongside AI Investing tools.

    As retirement planning becomes more complex, AI Investing is giving investors better forecasting tools, more personalized recommendations, and greater confidence in their financial future.

    AI Strategies for Early Retirement and Financial Independence

    Retirement no longer means waiting until your late sixties. In 2026, more Americans are pursuing financial independence and exploring ways to retire earlier than previous generations. AI Investing is becoming an important tool in this movement by helping investors make smarter decisions, improve savings rates, and optimize long-term wealth-building strategies.

    The FIRE movement, which stands for Financial Independence, Retire Early, has gained significant popularity over the last decade. The goal is simple: build enough wealth so that work becomes optional rather than necessary. Achieving this goal requires disciplined saving, consistent investing, and careful financial planning.

    AI Strategies for Early Retirement

    AI Investing platforms can help investors create personalized financial roadmaps based on income, expenses, savings rates, and retirement goals.

    Instead of relying on generic assumptions, artificial intelligence analyzes individual financial situations and provides recommendations that may accelerate progress toward financial independence.

    These recommendations can include increasing investment contributions, improving portfolio diversification, reducing unnecessary expenses, and optimizing asset allocation.

    Investors interested in this topic can explore our upcoming guide,

    AI Strategies for Early Retirement: Financial Freedom Guide 2026

    Can AI Help Americans Retire Richer?

    While AI Investing cannot guarantee higher returns, it can improve decision-making and help investors avoid costly mistakes. Many investors lose money because they panic during market downturns, chase short-term trends, or abandon long-term plans.

    Artificial intelligence helps reduce emotional decision-making by focusing on data, probabilities, and long-term financial objectives.

    Over time, better decisions and stronger discipline can contribute to improved retirement outcomes.

    Readers can learn more in our future article,

    Can AI Help Americans Retire Richer? Smart AI Wealth Strategies for 2026

    Future of AI in Personal Finance (2026–2030)

    The future of AI Investing extends far beyond portfolio management. Experts expect artificial intelligence to play a larger role in budgeting, tax planning, retirement forecasting, estate planning, and overall wealth management.

    As technology becomes more advanced, investors may gain access to highly personalized financial assistants capable of providing real-time guidance across nearly every area of personal finance.

    For a closer look at upcoming trends, explore our future guide,

    Future of AI in Personal Finance (2026–2030)

    The combination of disciplined investing and intelligent technology is creating new opportunities for Americans seeking financial freedom. AI Investing is helping investors make smarter decisions today while preparing for a more technology-driven financial future.

    How AI Is Transforming Credit Card Security and Banking Decisions

    Artificial intelligence is not only changing how people invest. It is also transforming how banks, lenders, and credit card companies protect consumers and make financial decisions. In 2026, AI-powered systems are helping millions of Americans detect fraud, improve credit health, and gain access to financial products more efficiently.

    As AI Investing becomes more common, many of the same technologies used to analyze investment opportunities are also being applied to banking and consumer finance. These systems process large amounts of data, identify patterns, and help financial institutions make faster and more accurate decisions.

    How AI Detects Credit Card Fraud in Real Time

    Credit card fraud remains a major challenge for financial institutions. Traditional fraud detection systems relied heavily on fixed rules and manual reviews. Today, artificial intelligence can monitor transactions in real time and identify suspicious activity within seconds.

    AI systems analyze spending behavior, purchase locations, transaction amounts, and account history. If unusual activity is detected, the system can flag the transaction, request verification, or temporarily block suspicious purchases.

    Investors and consumers interested in this topic can learn more in our upcoming guide,

    How AI Detects Credit Card Fraud in Real Time: 2026 Guide

    AI-Powered Credit Score Improvement Tools

    Many financial apps now use artificial intelligence to help consumers understand and improve their credit profiles.

    These platforms analyze payment history, debt utilization, account balances, and borrowing habits. Based on this information, they provide personalized recommendations that may help users strengthen their credit scores over time.

    Artificial intelligence makes credit education more accessible and easier to understand for everyday consumers.

    Readers can explore this topic further in our future article,

    AI Credit Score Tools: Best 2026 Guide to Credit Improvement

    How Banks Use AI to Approve Credit Cards

    Banks increasingly rely on artificial intelligence when evaluating credit card applications. AI systems can assess multiple financial factors quickly, helping lenders make faster and more informed decisions.

    These systems evaluate income stability, debt obligations, repayment history, spending behavior, and overall financial health before making recommendations.

    For a deeper explanation, check out our upcoming guide,

    How Banks Use AI to Approve Credit Cards

    Strong personal finances support long-term investing success. Investors looking to strengthen their financial foundation during uncertain economic periods can also explore our
    Recession-Proof Investing 2026
    guide.

    As artificial intelligence continues to evolve, AI Investing and AI-powered banking will become increasingly connected, helping Americans make smarter financial decisions while protecting their money more effectively.

    AI, Consumer Finance, and the Future of Financial Decision-Making

    Artificial intelligence is rapidly transforming consumer finance. Beyond AI Investing and portfolio management, AI is helping lenders evaluate risk, monitor spending behavior, and improve financial decision-making across the banking industry. In 2026, these technologies are becoming increasingly important for consumers who want greater control over their finances.

    Financial institutions now use artificial intelligence to process applications faster, personalize financial products, and identify potential risks before they become serious problems. This shift is creating a more efficient and data-driven financial ecosystem.

    AI and Buy Now Pay Later Risk Analysis

    Buy Now Pay Later (BNPL) services have become popular because they allow consumers to spread purchases over multiple payments. While convenient, these services can create financial risks if users take on more obligations than they can comfortably manage.

    Artificial intelligence helps lenders assess these risks by analyzing spending patterns, repayment history, income stability, and borrowing behavior. This allows providers to make more informed lending decisions while helping consumers avoid excessive debt.

    Readers interested in this topic can learn more in our upcoming guide,

    AI and Buy Now Pay Later Risk Analysis

    Future of AI Credit Decisions in America

    Traditional credit decisions often relied heavily on a limited number of financial metrics. Today, artificial intelligence can evaluate a wider range of data points to create a more complete financial profile.

    As AI technology continues to improve, lenders may be able to make faster, more accurate, and more personalized credit decisions. This could help qualified borrowers gain access to financial products more efficiently.

    Explore this trend further in our future article,

    Future of AI Credit Decisions in America

    AI Spending Analysis: Where Your Money Really Goes

    Many consumers underestimate how much they spend each month. Artificial intelligence can automatically categorize expenses, identify spending patterns, and highlight opportunities for improvement.

    By understanding where money is going, investors can redirect more cash toward savings, retirement accounts, and AI Investing strategies that support long-term wealth creation.

    Learn more in our upcoming guide,
    AI Spending Analysis

    Traditional Finance vs AI-Powered Finance

    FeatureTraditional FinanceAI-Powered Finance
    Decision SpeedHours or DaysSeconds or Minutes
    Data AnalysisLimitedLarge-Scale Analysis
    PersonalizationBasic RecommendationsHighly Personalized Insights
    Risk MonitoringPeriodic ReviewsContinuous Monitoring

    Many investors also use trusted brokerage platforms such as
    Charles Schwab
    to complement their AI Investing strategies with research tools, portfolio management resources, and retirement planning features.

    As artificial intelligence continues to reshape consumer finance, investors will gain access to smarter tools that support better spending habits, improved credit decisions, and stronger long-term financial outcomes.

    How AI Is Helping Americans Save More Money and Improve Financial Habits

    Building wealth is not only about earning higher investment returns. Successful investors understand that saving money consistently is just as important as AI Investing, retirement planning, and long-term portfolio growth. In 2026, artificial intelligence is helping Americans identify wasteful spending, improve budgeting habits, and uncover savings opportunities that can strengthen their financial future.

    Many households lose hundreds or even thousands of dollars each year through forgotten subscriptions, unnecessary fees, inefficient spending habits, and overlooked financial opportunities. AI-powered financial tools are designed to find these leaks and help consumers keep more of their money.

    AI Tools That Automatically Find Hidden Savings

    One of the most practical uses of artificial intelligence is identifying hidden savings opportunities. Modern financial apps analyze bank transactions, recurring charges, monthly expenses, and spending behavior to uncover areas where consumers may be overspending.

    For example, AI systems can detect duplicate subscriptions, unused memberships, excessive service fees, and recurring expenses that often go unnoticed. Instead of manually reviewing months of financial statements, users receive personalized recommendations within minutes.

    Readers interested in this topic can explore our future guide,

    AI Savings Tools: Hidden Savings Guide 2026

    Can AI Reduce Monthly Household Expenses?

    Rising living costs continue to challenge many American families. Housing expenses, groceries, insurance premiums, and utility bills have increased significantly over recent years.

    Artificial intelligence helps consumers analyze spending habits and identify areas where money can be saved. Even small monthly savings can add up over time and provide additional funds for AI Investing, retirement accounts, or emergency savings.

    Learn more in our upcoming article,
    AI Household Expenses

    AI-Powered Subscription Cancellation Tools

    Subscription services have become a major part of modern life. Streaming platforms, software memberships, fitness programs, and digital services often renew automatically.

    AI-powered financial tools can identify recurring charges and help consumers determine which subscriptions are providing value and which may no longer be necessary.

    This creates an easy way to reduce monthly expenses without significantly affecting quality of life.

    Readers can learn more in our future guide,
    AI Subscription Tools

    AI Budget Coaches vs Human Financial Advisors

    Artificial intelligence is also creating a new generation of budgeting tools often called AI budget coaches. These platforms provide spending analysis, savings recommendations, financial reminders, and budgeting assistance in real time.

    While human financial advisors remain valuable for complex planning needs, AI tools offer affordable support for everyday financial decisions.

    Our future article,
    AI Budget Coaches
    will compare the strengths of both approaches.

    The combination of strong saving habits and AI Investing creates a powerful foundation for long-term financial success. By reducing wasteful spending and improving money management, investors can free up more capital to invest, build wealth, and achieve their financial goals faster.

    The Future of AI Investing: What Comes Next for American Investors?

    AI Investing has already transformed how millions of Americans manage money, build portfolios, plan retirement, and improve financial decisions. However, the technology is still evolving. As artificial intelligence becomes more advanced, investors will gain access to smarter tools, deeper insights, and more personalized financial guidance than ever before.

    Between 2026 and 2030, experts expect AI Investing to play an even larger role in wealth building, financial planning, and everyday money management. Investors who understand these trends today may be better positioned to benefit from tomorrow’s opportunities.

    AI Side Hustles That Actually Make Money in 2026

    Artificial intelligence is creating new opportunities for individuals looking to earn extra income. Content creation, online businesses, digital marketing, automation consulting, and AI-powered research services are becoming increasingly popular side hustles.

    Many investors are using these additional income streams to increase savings and invest more aggressively for long-term goals.

    Learn more in our upcoming guide,

    AI Side Hustles That Actually Make Money in 2026

    AI vs Traditional Financial Advisors

    Artificial intelligence is making financial guidance more accessible, but human advisors still provide valuable expertise. AI Investing platforms excel at data analysis, automation, and portfolio monitoring, while financial advisors offer personalized guidance during major life decisions.

    For many investors, the future may involve combining both approaches to create a stronger financial strategy.

    Readers can explore this topic further in our future article,

    AI vs Traditional Financial Advisors: Which Is Better in 2026?

    AI Financial Assistants: The Next Big Money Trend

    AI-powered financial assistants are expected to become one of the biggest personal finance trends of the decade. These systems can track spending, monitor investments, answer financial questions, and provide personalized recommendations in real time.

    As technology improves, AI financial assistants may become a standard feature in banking, investing, and retirement planning platforms.

    Learn more in our upcoming guide,
    AI Financial Assistants: The Next Big Money Trend.

    Frequently Asked Questions

    1. What is AI Investing?

    AI Investing uses artificial intelligence, machine learning, and data analytics to help investors research opportunities, manage portfolios, and improve financial decision-making.

    2. Is AI Investing safe for beginners?

    Yes. Many AI Investing platforms are designed specifically for beginners and offer automated portfolio management, educational resources, and risk-management features.

    3. Can AI predict stock market crashes?

    No technology can predict every market crash. However, AI systems can identify warning signs and potential risks that investors may want to monitor.

    4. Can AI help with retirement planning?

    Yes. AI Investing platforms can analyze retirement goals, estimate future income, evaluate portfolio risk, and provide retirement projections.

    5. Does AI replace financial advisors?

    Not completely. AI provides powerful analytical tools, while human advisors offer personalized guidance and experience.

    6. Can AI improve personal finance management?

    Yes. Artificial intelligence can help with budgeting, spending analysis, savings optimization, debt management, and financial planning.

    7. What are the biggest benefits of AI Investing?

    Faster research, improved portfolio monitoring, better risk management, personalized recommendations, and more efficient financial decision-making.

    8. What is the future of AI Investing?

    The future includes smarter financial assistants, improved forecasting tools, advanced portfolio management systems, and more personalized financial guidance.

    Conclusion: Why AI Investing Matters in 2026 and Beyond

    AI Investing is no longer a future concept. It is already reshaping how Americans invest, save, plan for retirement, manage risk, and build wealth.

    The most successful investors will not rely on technology alone. Instead, they will combine AI Investing tools with timeless principles such as diversification, consistency, patience, and long-term thinking.

    Artificial intelligence can help investors make smarter decisions, but lasting wealth is still built through disciplined financial habits and a commitment to long-term goals.

    As you continue building your financial future, don’t forget to explore our
    Best Credit Cards 2026
    guide for additional personal finance strategies.

    📩 Join Our Free Investor Newsletter

    Get exclusive investing insights, AI Investing trends, retirement strategies, dividend opportunities, and personal finance tips delivered directly to your inbox.

    Stay informed. Invest smarter. Build wealth with confidence.

    Subscribe today and stay ahead of the financial future.


    👨‍💼 About the Author

    Subhash Rukade is the founder of FinanceInvestment.site, a growing personal finance platform dedicated to helping Americans make smarter money decisions through practical, research-driven content.

    With a strong passion for investing, AI-powered finance, dividend income strategies, retirement planning, and wealth building, Subhash creates easy-to-understand financial guides designed for both beginners and experienced investors.

    His mission is simple:
    “Make investing easier, smarter, and more accessible for everyone.”

    Through FinanceInvestment.site, he regularly publishes in-depth content covering:

    • 📈 Stock Market Investing
    • 🤖 AI Investing & Financial Technology
    • 💰 Dividend Income Strategies
    • 🏦 Retirement Planning
    • 💳 Credit Cards & Banking
    • 🛡️ Recession-Proof Investing
    • 🚀 Wealth Building & Financial Independence

    Whether you’re starting your first investment account or building a long-term portfolio, Subhash’s goal is to provide actionable insights that help readers achieve greater financial confidence and long-term success.

    🌐 Website:

    FinanceInvestment.site

    Thank you for reading AI Investing & Personal Finance Guide 2026.
    Here’s to smarter investing, stronger finances, and a wealthier future. 🚀

  • Monthly Investing for Financial Freedom: Complete 2026 Guide for Americans

    Monthly Investing for Financial Freedom: Complete 2026 Guide for Americans

    Monthly Investing for Financial Freedom: Complete 2026 Guide for Americans


    monthly investing for financial freedomBy Subhash Rukade | Updated June 5, 2026

    Why Financial Freedom Matters More Than Ever in 2026

    For millions of Americans, financial freedom has become one of the most important life goals.

    Financial freedom means having enough investments, savings, and passive income to support your lifestyle without depending entirely on a paycheck.

    It creates flexibility, reduces financial stress, and gives people more control over their future.

    Rising living costs, economic uncertainty, and changing retirement expectations have encouraged more people to search for practical ways to build long-term wealth.

    One strategy continues to stand out above the rest:
    monthly investing for financial freedom.

    Unlike trying to get rich quickly, monthly investing focuses on consistency.

    By investing a fixed amount every month into diversified investments, Americans can gradually build wealth while taking advantage of compounding and long-term market growth.

    The beauty of this approach is its simplicity.

    You do not need a huge amount of money to start.

    What matters most is developing the habit of investing regularly and staying committed for many years.

    If you’re new to this strategy, start with our complete pillar guide:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    Financial freedom also requires smart money management outside investing.

    Reducing unnecessary expenses and maximizing rewards can free up additional cash for investments.

    For practical ideas, also review:


    Best Credit Cards 2026: Rewards, Cashback & Smart Usage Guide

    In this guide, you’ll learn how monthly investing for financial freedom works, which investments can accelerate wealth creation, common mistakes to avoid, and practical strategies that can help move you closer to financial independence in 2026 and beyond.

    How Monthly Investing Creates Financial Freedom

    The foundation of monthly investing for financial freedom is simple: invest consistently, stay patient, and allow time to work in your favor.

    Many people believe building wealth requires large amounts of money.

    In reality, financial freedom is often achieved through regular investing habits repeated over many years.

    Monthly investing helps investors develop discipline while reducing the stress of trying to predict market movements.

    Instead of waiting for the “perfect” time to invest, investors contribute regularly and allow long-term market growth to work on their behalf.

    What Is Monthly Investing?

    Monthly investing means contributing a fixed amount of money into investments every month.

    These investments may include:

    • Index Funds
    • ETFs
    • Dividend Funds
    • Mutual Funds
    • Retirement Accounts

    This approach helps investors remain consistent regardless of market conditions.

    Over time, small monthly investments can grow into substantial wealth through compounding.

    Dollar-Cost Averaging Reduces Risk

    One major advantage of monthly investing for financial freedom is dollar-cost averaging.

    When investors contribute regularly, they automatically purchase more shares when prices are low and fewer shares when prices are high.

    This process helps smooth out market volatility and reduces the pressure of trying to perfectly time investments.

    Many successful investors rely on this strategy because it removes emotion from investing decisions.

    Consistency Often Beats Market Timing

    A common mistake is waiting for the perfect investment opportunity.

    Unfortunately, many investors stay on the sidelines while markets continue moving higher.

    Consistent monthly investing often produces better long-term results because money remains invested and compounding continues uninterrupted.

    StrategyMonthly InvestingSaving Cash Only
    Potential GrowthHighLow
    Compounding BenefitsYesNo
    Inflation ProtectionBetterLimited
    Long-Term Wealth CreationStrongWeak
    Financial Freedom PotentialHighLow

    Why This Strategy Works

    Financial freedom is rarely built overnight.

    Instead, it is usually the result of consistent actions taken over many years.

    Monthly investing creates a structured system that keeps investors moving toward their goals regardless of short-term market conditions.

    The biggest lesson from this section is simple:
    monthly investing for financial freedom works because it combines consistency, dollar-cost averaging, and long-term compounding. These factors help investors steadily build wealth while reducing the emotional challenges that often derail financial plans.

    Building Wealth Through Compounding

    The real power behind monthly investing for financial freedom comes from compounding.

    Compounding is often called the eighth wonder of the world because it allows investments to grow faster over time without requiring investors to constantly add large amounts of money.

    When investment returns begin generating additional returns, wealth can accelerate at a surprising pace.

    This is one reason why investors who start early often accumulate significantly more wealth than those who begin later.

    How Compounding Works

    Imagine investing $500 every month into a diversified portfolio.

    In the beginning, growth may appear slow.

    However, as investment gains accumulate and remain invested, future gains begin earning returns on previous gains.

    Over many years, this creates a snowball effect.

    The longer the investment period, the more powerful compounding becomes.

    This is why monthly investing for financial freedom rewards patience and consistency.

    Small Contributions Can Produce Big Results

    Many people delay investing because they believe they need thousands of dollars to get started.

    In reality, small monthly investments can grow into substantial wealth when given enough time.

    The key is staying invested and allowing compounding to work uninterrupted.

    Investors who contribute regularly often outperform those who invest only occasionally.

    Dividend Reinvestment Accelerates Growth

    Another powerful strategy is reinvesting dividends.

    Instead of spending dividend income, many investors use it to purchase additional shares.

    Those new shares can generate future dividends and future growth.

    Over decades, dividend reinvestment can dramatically increase portfolio value.

    Investors interested in building passive income should also review:


    How to Build a Dividend Portfolio

    Wealth Building FactorImpact on Financial Freedom
    Monthly ContributionsConsistent Growth
    CompoundingAccelerates Wealth Creation
    Dividend ReinvestmentBoosts Portfolio Growth
    Long-Term InvestingMaximizes Returns
    Increasing ContributionsSpeeds Up Financial Freedom

    Increase Investments as Income Grows

    One common habit among financially successful investors is increasing monthly investments after receiving salary raises or additional income.

    Even a small increase each year can significantly improve long-term results.

    This strategy helps accelerate progress toward financial freedom without requiring major lifestyle changes.

    One of the most recommended books for understanding wealth creation is:


    The Psychology of Money by Morgan Housel

    The book explains why investor behavior, patience, and consistency often have a greater impact on wealth than chasing high-return investments.

    The biggest lesson from this section is simple:
    monthly investing for financial freedom works because compounding transforms small, consistent investments into significant long-term wealth. Combined with dividend reinvestment and increasing contributions over time, it becomes one of the most effective paths to financial independence.

    Best Investments for Financial Freedom

    Choosing the right investments is one of the most important parts of monthly investing for financial freedom.

    While consistent investing creates the foundation, investment selection determines how efficiently your money grows over time.

    The most successful investors focus on assets that offer long-term growth, diversification, and the ability to generate wealth through multiple market cycles.

    Instead of chasing short-term trends, they build portfolios designed to support financial independence for decades.

    Index Funds: The Foundation of Many Wealth-Building Portfolios

    Index funds remain one of the most recommended investments for long-term investors.

    These funds track major market indexes such as the S&P 500 and provide exposure to hundreds of companies through a single investment.

    Benefits include:

    • Low fees
    • Broad diversification
    • Strong historical performance
    • Simple portfolio management

    For many investors, index funds form the core of a monthly investing for financial freedom strategy.


    monthly investing for financial freedom strategy

    ETFs Offer Growth and Flexibility

    Exchange-Traded Funds (ETFs) provide another excellent option for investors pursuing financial freedom.

    Broad-market ETFs, technology ETFs, and dividend ETFs allow investors to diversify across different sectors and industries while maintaining low investment costs.

    Many investors combine ETFs and index funds to create balanced portfolios with long-term growth potential.

    Dividend Investments Create Passive Income

    Dividend-paying investments can support both wealth growth and future income generation.

    During the accumulation phase, dividends can be reinvested to increase portfolio value.

    Later, those dividends may help cover living expenses and reduce dependence on employment income.

    Investors seeking high-quality dividend opportunities should also review:


    Top Dividend Stocks USA 2026

    Investment TypeMain BenefitFinancial Freedom Potential
    Index FundsBroad DiversificationVery High
    Broad Market ETFsLong-Term GrowthVery High
    Dividend ETFsIncome + GrowthVery High
    Dividend StocksPassive IncomeHigh
    Balanced FundsRisk ManagementModerate

    A Must-Read Book for Financial Independence

    One of the most respected books among long-term investors is:


    The Simple Path to Wealth by JL Collins

    The book explains how low-cost investing, disciplined saving, and long-term thinking can help investors achieve financial freedom and build lasting wealth.

    The biggest lesson from this section is simple:
    monthly investing for financial freedom works best when combined with diversified investments such as index funds, ETFs, and dividend-focused assets. These investments provide the growth potential needed to support long-term financial independence.

    Real Investor Example and Common Mistakes That Delay Financial Freedom

    Understanding monthly investing for financial freedom becomes much easier when we look at how real investors build wealth over time.

    Many people assume financial freedom is reserved for high-income earners.

    However, countless Americans have achieved financial independence through consistent investing habits rather than extraordinary salaries.

    The key is creating a system that works year after year.

    Monthly investing provides that system.

    A Real Financial Freedom Example

    Consider two investors: Mark and Jennifer.

    Both begin their careers at age 27 and earn similar salaries.

    Mark commits to investing $500 every month into index funds and dividend ETFs.

    Jennifer plans to invest but often delays contributions because she wants to wait for better market conditions.

    Over time, Mark increases his monthly investments whenever he receives a raise.

    Jennifer invests occasionally but lacks consistency.

    After 20 years, Mark’s portfolio has benefited from uninterrupted compounding and regular contributions.

    Jennifer’s portfolio grows much slower because she missed many opportunities to invest during strong market periods.

    This example highlights why monthly investing for financial freedom often outperforms irregular investing strategies.

    Mistake #1: Waiting Too Long to Start

    One of the most common investing mistakes is delaying action.

    Many people believe they need a higher income before they can begin investing.

    Unfortunately, every year spent waiting reduces the benefits of compounding.

    Starting early with a smaller amount is often better than starting later with a larger amount.

    Mistake #2: Lifestyle Inflation

    As income increases, many people increase spending at the same pace.

    This habit is known as lifestyle inflation.

    Instead of directing raises toward investments, they upgrade cars, homes, and discretionary spending.

    Successful investors often invest a portion of every pay increase before increasing their lifestyle expenses.

    Financial HabitMarkJennifer
    Monthly InvestingConsistentIrregular
    Compounding BenefitsMaximizedReduced
    Lifestyle InflationControlledHigh
    Portfolio GrowthStrongerSlower
    Financial Freedom ProgressFasterDelayed

    Mistake #3: Trying to Time the Market

    Many investors spend years waiting for market crashes or perfect entry points.

    Unfortunately, nobody can consistently predict market movements.

    Monthly investing for financial freedom works because it removes the need for market timing and focuses on long-term consistency.

    Investors preparing for uncertain economic conditions should also review:


    Recession-Proof Investing 2026

    For a complete roadmap to building long-term wealth through disciplined investing, continue with:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    The biggest lesson from this section is simple:
    monthly investing for financial freedom works best when investors start early, remain consistent, avoid lifestyle inflation, and ignore the temptation to time the market. These habits create the foundation for long-term wealth and financial independence.

    Practical Tips, Diversification, and Future Trends for Financial Freedom Investors

    Building wealth through monthly investing for financial freedom becomes even more effective when investors combine consistent contributions with diversification and smart long-term planning.

    While investing regularly is important, protecting and growing wealth requires a broader strategy.

    This includes spreading investments across multiple asset classes, using modern investing tools, and adapting to future financial trends.

    The most successful investors rarely depend on a single investment to achieve financial freedom.

    Instead, they build diversified portfolios designed to perform across different market conditions.

    Diversification Reduces Risk

    Diversification is one of the most powerful tools available to investors.

    Rather than placing all money into a single stock or sector, diversified investors spread their capital across multiple investments.

    A diversified portfolio may include:

    • S&P 500 Index Funds
    • Broad Market ETFs
    • Dividend ETFs
    • Dividend Stocks
    • Bond Funds
    • Alternative Assets

    This approach helps reduce risk while maintaining long-term growth potential.

    Many experts consider diversification a core component of monthly investing for financial freedom.

    Consider a Small Allocation to Gold

    Many long-term investors allocate a portion of their portfolio to gold.

    Gold has historically served as a hedge against inflation and economic uncertainty.

    Although it should not replace growth-focused investments, it can provide additional stability during volatile market periods.

    Investors interested in portfolio diversification should also review:


    Gold Investment Strategies USA

    StrategyMain Benefit
    Monthly InvestingConsistent Wealth Creation
    DiversificationRisk Reduction
    Dividend ReinvestmentFaster Compounding
    Gold AllocationPortfolio Stability
    Long-Term InvestingFinancial Independence

    Technology Is Transforming Investing in 2026

    Modern investors have access to powerful technology that simplifies investing.

    • AI-powered portfolio analysis
    • Automated investing platforms
    • Robo-advisors
    • Retirement calculators
    • Portfolio tracking tools

    These tools help investors remain disciplined while reducing emotional investing decisions.

    Learn From Trusted Financial Organizations

    These organizations provide investor education, retirement planning guidance, and resources that help Americans make informed financial decisions.

    A Trusted Platform for Long-Term Investors

    Many investors use:


    Fidelity Investments

    Fidelity offers retirement accounts, investment research, portfolio planning tools, and educational resources that support long-term wealth building.

    The biggest lesson from this section is simple:
    monthly investing for financial freedom becomes more effective when combined with diversification, smart technology, and continuous financial education. These strategies help investors build resilient portfolios capable of supporting long-term financial independence.

    Frequently Asked Questions About Monthly Investing for Financial Freedom

    1. What Is Monthly Investing for Financial Freedom?

    Monthly investing for financial freedom is the process of investing a fixed amount of money every month into assets such as index funds, ETFs, mutual funds, or dividend investments. Over time, these investments can grow through compounding and help create long-term wealth.

    2. How Much Should I Invest Every Month?

    The ideal amount depends on your income, expenses, and financial goals. Many financial planners recommend investing at least 15% to 20% of income, but even smaller amounts can grow significantly when invested consistently over many years.

    3. Can Monthly Investing Really Lead to Financial Independence?

    Yes. Consistent investing combined with compounding can build substantial wealth over time. Many financially independent individuals achieved their goals by investing regularly rather than relying on large one-time investments.

    4. What Investments Are Best for Financial Freedom?

    Many investors use a combination of index funds, ETFs, dividend investments, and diversified portfolios. The best investments are often those that can be held consistently through different market conditions.

    5. Should I Stop Investing During Market Crashes?

    Historically, continuing to invest during market downturns has often benefited long-term investors because lower prices allow investors to accumulate more shares that may appreciate in future market recoveries.

    Final Thoughts on Monthly Investing for Financial Freedom

    After exploring compounding, diversification, investment strategies, real-world examples, and common mistakes, one fact becomes clear:

    Monthly investing for financial freedom remains one of the most effective wealth-building strategies available to American investors in 2026.

    Financial freedom is rarely achieved through luck.

    Instead, it is usually the result of consistent investing, disciplined decision-making, and a long-term mindset.

    Investors who focus on building strong financial habits often place themselves in a much better position than those who constantly chase short-term opportunities.

    • Invest consistently every month.
    • Allow compounding to work.
    • Stay diversified.
    • Reinvest dividends.
    • Avoid emotional investing decisions.
    • Think long term.

    These habits have helped millions of investors build wealth and move closer to financial independence.

    The goal is not to become rich overnight.

    The goal is to create a financial system that steadily grows wealth year after year.

    For a complete roadmap to monthly investing and long-term wealth creation, continue with our pillar guide:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    Whether your goal is early retirement, passive income, financial independence, or creating a stronger future for your family, monthly investing can help transform those goals into reality.

    The earlier you begin and the longer you stay invested, the greater the opportunity to benefit from market growth and compounding.

    That is why monthly investing for financial freedom continues to be one of the smartest financial habits Americans can develop in 2026 and beyond.

    📈 Join the Finance Investment Newsletter

    Get investing insights, financial freedom strategies, dividend income ideas, retirement planning tips, and market updates delivered directly to your inbox.

    Join thousands of readers building long-term wealth through smarter financial decisions.


    Subscribe Free →

    👨‍💼 About the Author

    Subhash Rukade

    Founder of Finance Investment and a passionate financial educator focused on helping Americans build wealth through investing, retirement planning, dividend income, and financial independence strategies.

    • 📈 Long-Term Investing Strategies
    • 💰 Financial Freedom Planning
    • 🏦 Retirement Wealth Building
    • 📊 Dividend Investing
    • 🪙 Gold & Alternative Investments
    • 💳 Personal Finance Education
    “Financial Freedom Is Built One Investment At A Time.”

    Through Finance Investment, Subhash shares practical investing strategies designed to help readers avoid common mistakes, build wealth consistently, and create long-term financial security.

    ✅ Beginner-Friendly Investing Guides
    ✅ USA-Focused Financial Content
    ✅ Financial Freedom Strategies
    ✅ Practical Wealth-Building Education

    🌐 Finance Investment
    Helping Investors Build Wealth One Smart Decision at a Time.

  • Common SIP Mistakes Beginners Make: Avoid These Costly Investing Errors in 2026

    Common SIP Mistakes Beginners Make: Avoid These Costly Investing Errors in 2026

    Common SIP Mistakes Beginners Make: A Complete 2026 Guide for Smart Investors

    <!-- FOCUS KEYWORD --> common sip mistakes beginners make


    By Subhash Rukade | Updated June 3, 2026

    Why Understanding Common SIP Mistakes Beginners Make Matters

    SIP investing has become one of the most effective ways for Americans to build wealth gradually through monthly investing. However, many new investors unknowingly make mistakes that reduce returns, delay retirement goals, and weaken long-term wealth creation.

    Understanding the common SIP mistakes beginners make can help investors avoid costly decisions and stay focused on long-term success.

    Most investing mistakes do not happen because people lack intelligence. Instead, they occur because investors allow emotions, fear, impatience, or misinformation to influence their decisions.

    Many beginners start investing with excitement but quickly become discouraged when markets fluctuate. Others wait years before starting because they believe they need large amounts of money to begin.

    If you’re serious about mastering monthly investing and avoiding beginner mistakes, start with our complete pillar guide:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    Some of the most common SIP mistakes beginners make include:

    • Waiting too long before investing.
    • Stopping SIPs during market declines.
    • Investing without clear goals.
    • Ignoring diversification.
    • Expecting unrealistic returns.

    Over time, these mistakes can significantly reduce portfolio growth and make it harder to achieve financial freedom.

    Good investing begins with strong financial habits. Investors who want to improve budgeting and spending efficiency should also explore:


    Best Credit Cards 2026: Rewards, Cashback & Smart Usage Guide

    In this guide, you’ll learn the common SIP mistakes beginners make, understand how these mistakes affect long-term wealth, and discover practical strategies that successful investors use to stay on track in 2026 and beyond.

    Top SIP Mistakes Beginners Make That Can Hurt Long-Term Wealth

    One of the biggest reasons investors fail to achieve their financial goals is that they repeat the same investing mistakes year after year.

    Understanding the common SIP mistakes beginners make can help investors avoid costly errors and improve their chances of building long-term wealth.

    The good news is that most of these mistakes are completely avoidable.

    Mistake #1: Waiting Too Long to Start Investing

    Many people believe they need a large amount of money before they can begin investing.

    As a result, they postpone investing for years.

    Unfortunately, every year spent waiting is a year lost to compounding.

    Even small monthly investments started early can often outperform larger investments started much later.

    Mistake #2: Investing Without Clear Financial Goals

    Another common SIP mistake beginners make is investing without knowing why they are investing.

    Successful investors usually invest for specific goals such as:

    • Retirement planning
    • Financial freedom
    • Buying a home
    • Building passive income
    • Long-term wealth creation

    Without clear goals, investors are more likely to lose motivation during periods of market volatility.

    Mistake #3: Chasing Quick Profits

    Many beginners enter the market expecting fast returns.

    They often chase trending stocks, social media recommendations, or speculative investments.

    However, SIP investing is designed to build wealth gradually over years and decades.

    Trying to get rich quickly often increases risk and leads to poor investment decisions.

    Common MistakeBetter Investing Habit
    Waiting to startStart investing immediately
    No clear goalsCreate financial objectives
    Chasing quick profitsFocus on long-term growth
    Market timingInvest consistently
    Emotional decisionsFollow a disciplined plan

    Mistake #4: Lack of Consistency

    Consistency is one of the biggest advantages of SIP investing.

    Unfortunately, many investors start enthusiastically and then stop contributing after a few months.

    This disrupts compounding and reduces long-term wealth potential.

    Among all the common SIP mistakes beginners make, inconsistency may be one of the most damaging because it prevents investors from benefiting fully from market growth and dollar-cost averaging.

    The biggest lesson from this section is simple:
    successful investing is not about being perfect. It is about starting early, staying consistent, and focusing on long-term goals instead of short-term market noise.

    How SIP Mistakes Can Hurt Long-Term Wealth Creation

    Many investors underestimate how expensive investing mistakes can become over time.

    The reality is that the common SIP mistakes beginners make often cost far more than temporary market declines.

    A market correction may last months, but a poor investing habit can affect portfolio growth for decades.

    This is why understanding the long-term impact of investing mistakes is essential for anyone serious about building wealth.

    The Cost of Waiting to Start Investing

    One of the most common SIP mistakes beginners make is delaying their investment journey.

    Many people spend years waiting for the perfect time to invest.

    Others believe they need more income before they can begin.

    Unfortunately, every year spent waiting reduces the amount of time available for compounding.

    Time is one of the most valuable assets an investor possesses.

    Once it is lost, it cannot be recovered.

    Missed Compounding Opportunities

    Compounding allows investment earnings to generate additional earnings.

    Over long periods, this process can significantly increase portfolio growth.

    However, investors who stop their SIP contributions, withdraw investments early, or frequently change strategies often interrupt compounding.

    As a result, their wealth-building potential may be reduced.

    This is one reason the common SIP mistakes beginners make can have a larger impact than many investors realize.

    MistakeLong-Term Impact
    Starting LateLess Compounding Time
    Stopping SIPsReduced Portfolio Growth
    Emotional InvestingPoor Investment Decisions
    No Clear GoalsWeak Long-Term Planning
    Lack of DiversificationHigher Investment Risk

    Retirement Goals Can Be Delayed

    Retirement planning depends heavily on consistency and long-term investing.

    Investors who repeatedly make the common SIP mistakes beginners make often find themselves contributing more money later just to catch up.

    This creates additional financial pressure and may delay retirement goals.

    Starting early and remaining disciplined can make retirement planning significantly easier.

    Dividend Investing Can Strengthen Wealth Creation

    Many successful investors eventually add dividend-producing investments to their portfolios.

    Dividend stocks and dividend ETFs can provide additional income while supporting long-term growth.

    Investors interested in building a dividend-focused portfolio should explore:


    How to Build a Dividend Portfolio

    Reinvesting dividends can increase compounding and further strengthen long-term wealth creation.

    A Highly Recommended Investing Book

    One of the most respected personal finance books available today is:


    The Psychology of Money by Morgan Housel

    The book explains why behavior and consistency often matter more than trying to predict stock market movements.

    The biggest lesson from this section is simple:
    avoiding the common SIP mistakes beginners make can be just as important as choosing the right investments. Investors who stay disciplined and allow compounding to work over decades often place themselves in a much stronger financial position.

    Choosing Better Investments and Avoiding Portfolio Mistakes

    Another reason many investors struggle is that they focus only on monthly contributions while ignoring investment quality.

    Among the common SIP mistakes beginners make, choosing unsuitable investments is one of the most damaging because it can reduce returns and increase risk over time.

    The good news is that investors do not need complicated strategies to build wealth. In many cases, simple and diversified investments perform extremely well over long periods.

    Why Diversification Matters

    Diversification means spreading investments across multiple assets rather than relying on a single stock or sector.

    A diversified portfolio can help reduce risk and create a smoother investing experience.

    Many beginners make the mistake of putting too much money into one company or one investment theme.

    If that investment performs poorly, the entire portfolio suffers.

    This is one of the most common SIP mistakes beginners make and can often be avoided through proper diversification.

    Index Funds and ETFs Remain Popular Choices

    Many successful long-term investors use index funds and ETFs as the foundation of their portfolios.

    These investments offer:

    • Broad diversification
    • Lower investment costs
    • Professional management
    • Long-term growth potential
    • Reduced stock-specific risk

    For beginners, index funds often provide a simple and effective way to participate in market growth.


    common sip mistakes beginners make investing strategy

    Dividend Investing Can Add Another Layer of Growth

    Dividend-paying investments can help investors generate passive income while continuing to build wealth.

    Investors looking for dividend opportunities should also review:


    Top Dividend Stocks USA 2026

    Reinvesting dividends can further strengthen the compounding process and improve long-term portfolio growth.

    Investment TypeMain AdvantageSuitable For
    Index FundsDiversificationMost Investors
    S&P 500 ETFsLong-Term GrowthGrowth Investors
    Dividend ETFsIncome + GrowthIncome Investors
    Dividend StocksPassive IncomeExperienced Investors
    Balanced FundsRisk ManagementConservative Investors

    A Valuable Resource for Investors

    Another highly recommended investing book is:


    The Simple Path to Wealth by JL Collins

    The book explains why simple investing strategies often outperform complicated approaches over the long run.

    The biggest lesson from this section is simple:
    avoiding the common SIP mistakes beginners make starts with choosing diversified, high-quality investments and staying committed to a long-term investing plan.

    Real Investor Example and Emotional Investing Mistakes Beginners Should Avoid

    Many investing mistakes are not caused by a lack of knowledge. Instead, they are caused by emotions.

    In fact, some of the common SIP mistakes beginners make happen when investors allow fear, greed, or panic to influence their decisions.

    Understanding these emotional traps can help investors stay disciplined and focused on long-term wealth creation.

    A Real-World Investor Example

    Consider two investors, Sarah and Michael.

    Both started SIP investing in diversified index funds at the same time.

    Sarah continued investing every month regardless of market conditions.

    Michael, however, became nervous whenever stock markets declined.

    During a major market correction, Michael stopped his SIP contributions and moved his money to cash.

    Sarah stayed invested.

    Several years later, Sarah’s portfolio benefited from market recovery and continued compounding.

    Michael missed a significant portion of that growth because he allowed short-term fear to dictate long-term decisions.

    This example perfectly demonstrates one of the most common SIP mistakes beginners make:
    trying to avoid temporary losses at the cost of future gains.

    Mistake #1: Panic Selling During Market Declines

    Market corrections are a normal part of investing.

    However, many beginners assume falling markets mean something is wrong.

    As a result, they stop investing or sell their holdings at lower prices.

    Historically, investors who remain disciplined during downturns often benefit when markets eventually recover.

    Mistake #2: Overconfidence During Bull Markets

    Just as fear can hurt investors, overconfidence can be equally dangerous.

    When markets rise rapidly, some investors believe every investment decision will succeed.

    They may take unnecessary risks or abandon diversification.

    This behavior is another example of the common SIP mistakes beginners make.

    EmotionCommon MistakeBetter Approach
    FearStop SIP InvestingStay Consistent
    PanicSell InvestmentsFollow Long-Term Plan
    GreedChase Hot StocksDiversify Portfolio
    OverconfidenceTake Excessive RiskMaintain Discipline

    Prepare for Market Uncertainty

    Successful investors understand that volatility is normal.

    Investors who want to build stronger portfolios during uncertain economic periods should also review:


    Recession-Proof Investing 2026

    For a complete roadmap to long-term SIP investing and wealth creation, continue reading:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    The biggest lesson from this section is simple:
    many of the common SIP mistakes beginners make are emotional, not technical. Investors who stay calm, remain consistent, and follow a long-term plan often give themselves the best chance of achieving financial freedom.

    Practical SIP Investing Tips, Risk Management, and Future Trends for 2026

    Avoiding the common SIP mistakes beginners make is only the first step toward becoming a successful investor.

    The next step is creating a strategy that can survive market volatility, economic uncertainty, and changing financial conditions.

    Investors who focus on risk management and long-term planning often place themselves in a stronger position to build wealth over time.

    Diversification Should Be a Priority

    One of the smartest ways to reduce investment risk is diversification.

    Instead of relying on a single stock, sector, or investment theme, diversified investors spread money across multiple assets.

    A diversified portfolio may include:

    • Index Funds
    • S&P 500 ETFs
    • Dividend Stocks
    • Bond Funds
    • International Investments
    • Alternative Assets

    Diversification helps investors avoid one of the common SIP mistakes beginners make—placing too much money into a single investment.

    Should Gold Be Part of Your Portfolio?

    Many investors allocate a small portion of their portfolios to gold as a hedge against inflation and economic uncertainty.

    Investors interested in this strategy should also review:


    Gold Investment Strategies USA

    While gold should not replace stock market investments, it can complement a diversified portfolio.

    StrategyMain Benefit
    DiversificationRisk Reduction
    Monthly SIP InvestingConsistency
    Dividend ReinvestmentCompounding Growth
    Long-Term InvestingWealth Creation
    Asset AllocationPortfolio Stability

    Technology Is Changing the Way People Invest

    The investing landscape continues evolving rapidly in 2026.

    Today’s investors have access to:

    • AI-powered investing tools
    • Portfolio tracking apps
    • Automated investing platforms
    • Robo-advisors
    • Fractional investing opportunities

    These tools make investing more accessible than ever before.

    However, technology cannot replace discipline, patience, and long-term thinking.

    Use Trusted Financial Resources

    Investors should always rely on credible financial information.

    These organizations provide educational resources that can help investors avoid the common SIP mistakes beginners make and make more informed financial decisions.

    A Useful Investing Platform

    Many long-term investors use:


    Fidelity Investments

    Fidelity offers retirement accounts, brokerage services, investment research, and educational tools for both beginners and experienced investors.

    The biggest lesson from this section is simple:
    successful investing is not about predicting markets. It is about building a diversified portfolio, managing risk, staying consistent, and avoiding the common SIP mistakes beginners make throughout your investing journey.

    Frequently Asked Questions About Common SIP Mistakes Beginners Make

    1. What Is the Biggest SIP Mistake Beginners Make?

    One of the biggest mistakes is waiting too long to start investing. Delaying investments reduces the time available for compounding and long-term wealth creation.

    2. Should I Stop My SIP During a Market Crash?

    No. Market corrections are a normal part of investing. Continuing SIP investments during downturns can help investors purchase assets at lower prices and potentially benefit when markets recover.

    3. Is Diversification Important for SIP Investors?

    Yes. Diversification helps reduce risk by spreading investments across multiple assets, sectors, and investment types.

    4. Can Emotional Investing Hurt Returns?

    Absolutely. Fear, panic, and greed often lead to poor decisions such as selling during market declines or chasing speculative investments.

    5. How Can Beginners Avoid SIP Investing Mistakes?

    By setting clear goals, investing consistently, staying diversified, and focusing on long-term growth instead of short-term market fluctuations.

    Final Thoughts on Common SIP Mistakes Beginners Make

    Understanding the common SIP mistakes beginners make is one of the most valuable lessons an investor can learn.

    While investing itself is relatively simple, many people struggle because they allow emotions, impatience, and misinformation to influence their decisions.

    Throughout this guide, we explored several mistakes that frequently hurt long-term wealth creation:

    • Waiting too long to start investing
    • Investing without clear financial goals
    • Stopping SIPs during market declines
    • Ignoring diversification
    • Chasing quick profits
    • Making emotional investment decisions

    Fortunately, every one of these mistakes can be avoided.

    Successful investors are not necessarily those who predict markets correctly. More often, they are the investors who remain disciplined, invest consistently, and allow compounding to work over many years.

    If you want a complete roadmap for building wealth through monthly investing, continue reading our pillar guide:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    Remember: avoiding mistakes is often just as important as choosing the right investments. Small improvements in investing behavior today can create a significant difference in financial results tomorrow.

    📈 Join the Finance Investment Community

    Get investing insights, retirement strategies, stock market updates, dividend ideas, and wealth-building tips delivered directly to your inbox.


    Subscribe Free →

    👨‍💼 About the Author

    Subhash Rukade

    Founder of Finance Investment and a passionate financial educator dedicated to helping investors build long-term wealth through smart investing, retirement planning, dividend strategies, and personal finance education.

    • 📈 Long-Term Investing
    • 💰 Dividend Investing
    • 🏦 Retirement Planning
    • 📊 Wealth Building Strategies
    • 🪙 Gold & Alternative Investments
    • 💳 Personal Finance Management
    “Successful Investing Is Not About Perfection. It’s About Consistency.”

    Through research-based financial content, Subhash helps readers make informed investing decisions and avoid costly financial mistakes.