Tag: Checking Accounts

  • Checking and Savings FDIC Insurance: 2026 Essential Guide

    Checking and Savings FDIC Insurance: 2026 Essential Guide


    Do Checking and Savings Accounts Share the Same FDIC Insurance Limit?

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    Published: November 6, 2026
    Updated: November 6, 2026
    Reading time: 10 minutes

    checking and savings accounts FDIC insurance

    Do Checking and Savings Accounts Share the Same FDIC Insurance Limit?

    Your checking account handles everyday expenses, while your savings account may hold money for emergencies or future plans. Keeping these accounts separate can make budgeting easier—but it does not automatically give you separate FDIC insurance limits.

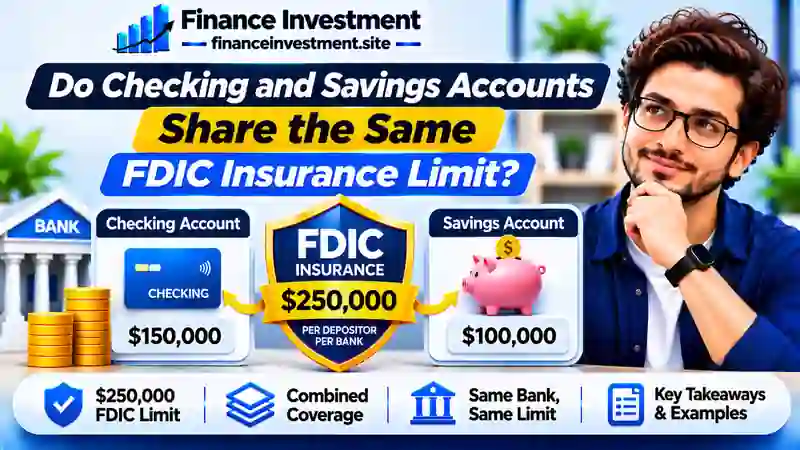
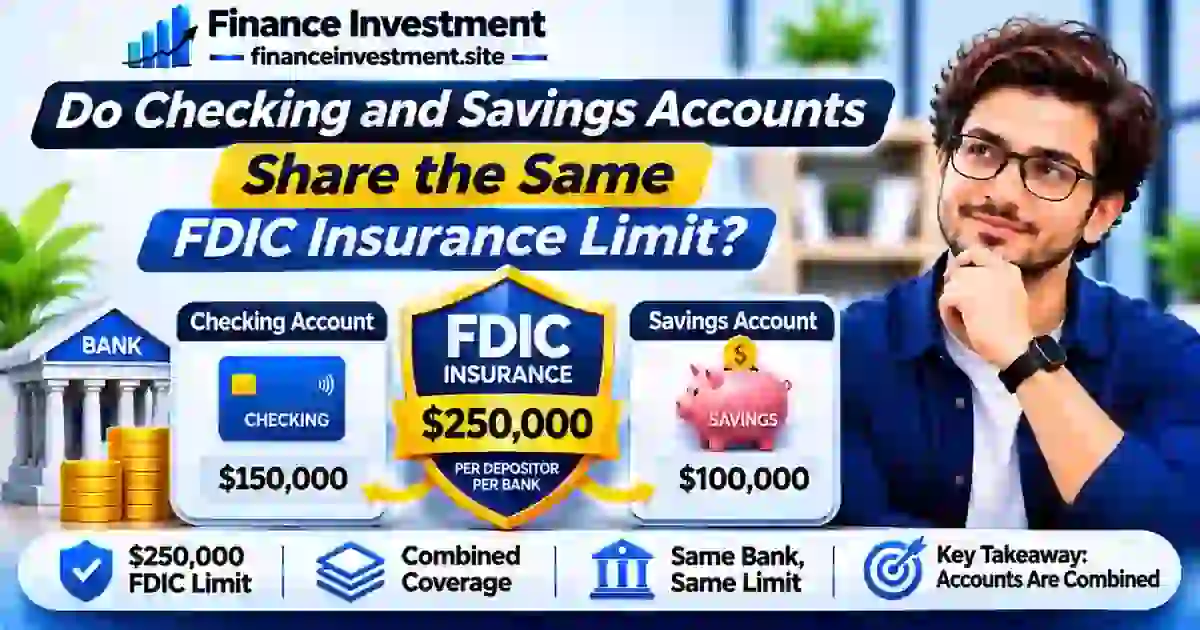
    At the same FDIC-insured bank, deposits you own in the same ownership category are generally combined when coverage is calculated. checking and savings accounts FDIC insurance That means your checking and savings balances may count toward one standard $250,000 insurance limit, rather than receiving $250,000 of protection each.

    The important details are where your money is held, who owns it, and how the accounts are legally categorized. Understanding those factors can help you avoid assuming that opening another account increases your protection.

    This guide explains the rule in practical terms, including how account ownership can affect coverage and what to review before moving money. For a broader explanation of bank and credit union protection, visit our FDIC and NCUA insurance guide.

    What You’ll Learn

    • Why checking and savings accounts generally share the same FDIC limit at one bank
    • How the standard $250,000 coverage rule applies to your deposits
    • How account ownership categories can affect total protection
    • What to check before deciding whether your deposits need a different arrangement

    Quick Answer: Do Checking and Savings Accounts Share FDIC Insurance?

    Yes, generally. If you own checking and savings deposits at the same FDIC-insured bank in the same ownership category, those balances are combined toward the standard $250,000 FDIC insurance limit. Having separate accounts does not automatically give you a separate $250,000 limit for each one.

    Key Takeaways

    • Same bank and ownership category: Your eligible checking and savings deposits generally count together.
    • Standard coverage: The limit is generally $250,000 per depositor, per insured bank, per ownership category.
    • More accounts do not automatically mean more coverage: Account count alone does not increase your insurance limit.
    • Ownership can make a difference: Qualifying ownership categories may receive separate coverage under FDIC rules.
    • Check your situation: Use the official FDIC EDIE calculator to estimate coverage based on your deposits and ownership details.

    FDIC Coverage at a Glance

    Checking and savings accounts may have different everyday uses, but FDIC insurance is based on how deposits are owned and where they are held—not simply how many accounts you open. This quick table highlights the standard coverage rules.

    Coverage DetailWhat It Means
    Standard limit$250,000 per depositor, per FDIC-insured bank, per ownership category
    Checking + savingsGenerally combined when owned by the same depositor in the same ownership category at one insured bank
    Different insured banksCoverage is generally calculated separately at each FDIC-insured bank
    Ownership categoriesQualifying categories may receive separate coverage under FDIC rules
    Coverage estimateUse the FDIC EDIE calculator to estimate coverage based on your account details

    This is a general overview. Actual coverage depends on deposit eligibility, bank status, account ownership, and applicable FDIC rules.

    FDIC Insurance Basics: What Every Bank Customer Should Knowchecking and savings accounts FDIC insurance

    The Federal Deposit Insurance Corporation (FDIC) is an independent U.S. government agency that protects depositors if an FDIC-insured bank fails. Its insurance helps protect eligible deposits from losses caused by a bank failure, subject to the applicable coverage limits and rules.

    What Does FDIC Insurance Cover?

    FDIC insurance covers eligible deposit products held at FDIC-insured banks. Common examples include checking accounts, savings accounts, money market deposit accounts, and certificates of deposit (CDs). Coverage is automatic when eligible deposits are held at an insured bank, so customers do not need to purchase a separate insurance policy.

    What Is Not FDIC-Insured?

    Some financial products offered through banks are investments rather than deposits. Stocks, bonds, mutual funds, annuities, and cryptocurrency are not protected by FDIC deposit insurance. A product does not become insured simply because a bank offers or sells it.

    Why Does Account Ownership Matter?

    The FDIC determines coverage based on who owns the deposits and the applicable ownership category. Eligible deposits in the same category at the same insured bank are generally combined. Certain qualifying categories, such as individual and joint accounts, may receive separate coverage when FDIC requirements are met.

    For a broader explanation of deposit protection at banks and credit unions, read our FDIC and NCUA insurance guide.

    How Checking and Savings Accounts Share FDIC Coverage

    FDIC insurance is calculated using three key factors: who owns the deposits, which FDIC-insured bank holds them, and the ownership category they belong to. Eligible deposits in the same category are combined, even when they are spread across checking, savings, and other deposit accounts.

    Checking and Savings at the Same Bank

    If you own an individual checking account and an individual savings account at the same FDIC-insured bank, their eligible balances generally count together under the single-account ownership category. Opening another account or moving money between those accounts does not create an additional insurance limit.

    Accounts at Different Banks

    Deposits at separately chartered FDIC-insured banks are generally calculated separately. However, different branches, websites, or brand names may belong to the same insured bank. Before relying on separate coverage, confirm that each institution is independently FDIC-insured.

    When Ownership Categories Can Differ

    FDIC rules recognize different legal ownership categories. For example, qualifying individual deposits and qualifying joint deposits may receive separate coverage. The accounts must meet the requirements for their respective categories; simply opening checking and savings accounts does not create separate ownership.

    Remember: The FDIC looks at eligible deposits and their legal ownership—not just the account names, number of accounts, or bank branding.

    To estimate your coverage, enter your account ownership and balances in the official FDIC EDIE calculator. You can also review our FDIC and NCUA insurance guide for a broader explanation of deposit protection.

    Benefits and Drawbacks of Shared FDIC Coverage

    Knowing how checking and savings deposits are insured can make it easier to organize your money and understand where your coverage may fall short. The main benefit is clarity; the limitation is that separate accounts do not automatically create separate insurance limits.

    Benefits

    • Clearer deposit planning: Reviewing checking and savings balances together helps you understand how eligible deposits are counted.
    • Flexible account organization: You can keep spending money in checking and reserves in savings without assuming that the account setup changes your insurance limit.
    • More coverage options: Qualifying ownership categories or deposits at separately insured banks may receive separate coverage when FDIC requirements are met.

    Drawbacks

    • Easy to miscalculate: Multiple accounts can make combined eligible balances harder to track.
    • Possible uninsured amounts: Deposits exceeding the applicable limit may not be fully insured.
    • Ownership rules can be complex: Joint, trust, and other account categories have specific eligibility requirements.

    Important: FDIC insurance protects eligible deposits if an insured bank fails. It does not protect against fraud, theft, or unauthorized transactions. For official coverage details, review the FDIC deposit insurance guidance.

    Checking vs. Savings Accounts: Do They Get Separate FDIC Coverage?

    Checking and savings accounts are both eligible deposit products, but their names do not create separate insurance limits. The FDIC generally combines eligible deposits owned by the same depositor in the same ownership category at the same insured bank. See the FDIC coverage overview.

    Account SituationHow FDIC Coverage Generally Works
    Individual checking + individual savings at one bankEligible balances are generally combined under the single-account ownership category.
    Two individual checking accounts at one bankBalances generally count together; opening another account does not create another limit.
    Checking and savings at separately chartered insured banksCoverage is generally calculated separately at each FDIC-insured bank.
    Individual account + qualifying joint accountThese may receive separate coverage because they fall under different ownership categories, if FDIC requirements are met.

    Bottom line: The account type alone does not create another FDIC limit. Coverage depends on the insured bank, depositor, and qualifying ownership category.

    FDIC Coverage Risks and Expert Tips

    The biggest FDIC coverage risk is assuming that every dollar across your checking and savings accounts is protected without reviewing the combined balance. Eligible deposits are insured within the applicable limit, including principal and accrued interest through the date an insured bank fails.

    Risks to Watch

    • Accrued interest: Interest earned before a bank failure counts toward your applicable insurance limit.
    • Uninsured deposits: Eligible balances above your available coverage may not be fully insured.
    • Bank identity confusion: Different branches or brand names may belong to the same FDIC-insured bank.
    • Deposit eligibility: Confirm that your institution is FDIC-insured and your financial product qualifies as an insured deposit.

    Practical Expert Tips

    • Verify your institution through the official FDIC BankFind Suite.
    • Review combined eligible balances across checking, savings, and other deposits in the same ownership category.
    • Include accrued interest when estimating your total deposits.
    • Use the official FDIC EDIE calculator to estimate coverage based on your account details.

    If you have complex trust, business, or joint-account arrangements, confirm the applicable requirements with the FDIC before relying on a coverage estimate.

    Common FDIC Insurance Mistakes and Real-Life Examples

    Checking and savings accounts may look like separate financial products, but FDIC insurance depends on more than the account name. These common mistakes can lead to an incorrect estimate of how much money is protected.

    Mistake 1: Assuming Every Account Gets Its Own Limit

    Jordan keeps $140,000 in checking and $125,000 in savings at the same FDIC-insured bank. If both accounts are owned individually and fall within the same ownership category, the $265,000 combined balance exceeds the standard $250,000 limit by $15,000, before considering accrued interest or other eligible deposits.

    Mistake 2: Confusing Bank Brands With Separate Banks

    A bank may operate under multiple brand names or offer online accounts through a separate website. If those accounts belong to the same insured bank, eligible deposits in the same ownership category generally count together. Different names alone do not establish separate insurance coverage.

    Mistake 3: Assuming Joint Accounts Automatically Add Coverage

    Adding a spouse or another person to an account does not automatically create separate coverage. Joint accounts must meet FDIC ownership and recordkeeping requirements, and each co-owner’s share is considered under the joint-account rules.

    Mistake 4: Forgetting Accrued Interest

    Riley checks only the original deposit amount. However, accrued interest through the date of an insured bank’s failure also counts toward the applicable coverage limit.

    Bottom line: Review the insured bank, account ownership, combined eligible balances, and accrued interest. Use the official FDIC EDIE calculator to estimate your coverage.

    Who Should Review Their FDIC Coverage?

    Reviewing FDIC insurance is especially important when your deposits, account ownership, or banking arrangements change. Checking and savings accounts at the same insured bank may share one coverage limit when they belong to the same ownership category.

    Consider Reviewing Your Coverage If You:

    • Hold substantial combined checking, savings, or CD balances at one insured bank.
    • Receive a large deposit from a home sale, inheritance, bonus, or maturing CD.
    • Have accounts under different bank brands and are unsure whether they belong to the same insured institution.
    • Maintain individual, joint, trust, or business accounts and need to understand their ownership categories.
    • Are uncertain whether your institution or financial product qualifies for FDIC insurance.

    Start by confirming your institution through FDIC BankFind. Then review eligible deposits, account ownership, and accrued interest. Use the official FDIC EDIE calculator to estimate coverage. Complex trust or business arrangements may require additional review.

    Frequently Asked Questions About Checking and Savings FDIC Insurance

    1. Do checking and savings accounts share the same FDIC limit?

    Yes. If both accounts belong to the same depositor, insured bank, and ownership category, eligible balances generally combine toward the $250,000 standard limit, along with other eligible deposits in that category.

    2. Is checking account money automatically FDIC-insured?

    Eligible checking deposits are automatically insured when held at an FDIC-insured bank, subject to the applicable coverage limit.

    3. Does opening two savings accounts increase FDIC coverage?

    No. Multiple accounts in the same ownership category at the same insured bank generally share the same limit.

    4. Are checking and savings accounts insured separately at different banks?

    Generally, deposits at separately chartered FDIC-insured banks are insured separately, subject to the applicable ownership category limit.

    5. Does FDIC insurance cover accrued interest?

    Yes. Principal and accrued interest through the date of an insured bank’s failure count toward applicable coverage.

    6. Are joint checking accounts covered separately?

    Joint accounts may qualify for separate coverage under the joint-account category, including up to $250,000 per co-owner, if FDIC ownership and recordkeeping requirements are met.

    7. Are money market accounts FDIC-insured?

    Money market deposit accounts at insured banks are eligible deposits. Money market mutual funds are investment products and are not FDIC-insured.

    8. Does FDIC insurance protect against bank fraud?

    No. FDIC insurance protects eligible deposits against an insured bank’s failure, not fraud, theft, or unauthorized transactions.

    9. How can I calculate my FDIC coverage?

    Use the official FDIC EDIE calculator and enter your bank, account balances, and ownership details.

    10. Can I have more than $250,000 insured at one bank?

    Yes. You may qualify for more than $250,000 in total coverage through different ownership categories at the same insured bank when all FDIC requirements are satisfied.


    Final Verdict: Checking and Savings Accounts Share One FDIC Limit

    Checking and savings accounts generally share the same $250,000 FDIC insurance limit when they belong to the same depositor, the same insured bank, and the same ownership category. Opening another account at that bank does not automatically increase your protection.

    Additional coverage may be available through separately chartered FDIC-insured banks or qualifying ownership categories, provided all applicable FDIC requirements are met. To understand your coverage, consider your combined eligible deposits, account ownership, and accrued interest.

    For a broader explanation of deposit insurance and ownership categories, read our FDIC and NCUA Insurance Explained guide.
    Bottom line: Your FDIC coverage depends on where your money is held and how the deposits are owned—not simply how many checking or savings accounts you have.

    Have Questions About Your FDIC Insurance?

    Checking and savings accounts can share an FDIC insurance limit, but your coverage depends on the insured bank, account ownership, and eligible deposits. Review your balances and use official FDIC resources if you need to estimate your protection.

    Need help understanding a banking topic?

    Send FinanceInvestment your question or suggestion for a future guide.

    Email FinanceInvestment

    Continue learning with our FDIC and NCUA Insurance Explained guide.
  • 7 Smart Ways to Calculate FDIC Insurance Coverage (2026)

    7 Smart Ways to Calculate FDIC Insurance Coverage (2026)


    FDIC Insurance Coverage for Multiple Accounts: How to Calculate It (2026)

    SR
    Subhash Rukade
    Founder, FinanceInvestment
    Published: November 6, 2026
    Updated: November 6, 2026
    READING TIME
    10 min


    FDIC insurance coverage for multiple accounts

    How to Calculate FDIC Insurance Coverage for Multiple Accounts

    Keeping money in different bank accounts can make everyday finances easier to manage. But if you have checking, savings, and CDs at the same bank, one question matters: How much of your money is protected by FDIC insurance? The answer may not be as simple as adding the insurance limit to every account.

    FDIC insurance generally depends on the insured bank, the depositor, the ownership category, and the amount of eligible deposits. Several accounts held in the same ownership category at one bank are usually combined when coverage is calculated. Accounts at different separately insured banks may qualify for separate coverage.

    Understanding these rules can help you identify whether your deposits fit within the applicable limits or whether some money may be uninsured. This guide explains the calculation step by step, using practical examples for individuals, couples, and families.

    For a broader introduction to deposit protection, read our FDIC and NCUA insurance guide.

    What You’ll Learn

    • How the standard FDIC insurance limit applies to eligible deposits
    • Why checking, savings, and CDs may share coverage at one bank
    • How account ownership categories affect your calculation
    • How joint accounts and deposits at separate banks are treated
    • How to identify balances that may exceed available coverage

    Quick Answer: How Much FDIC Coverage Do You Have?

    The standard FDIC insurance limit is $250,000 per depositor, per insured bank, per ownership category. To calculate coverage for multiple accounts, combine eligible deposits held by the same depositor in the same ownership category at that bank. Checking, savings, and CDs do not automatically receive separate limits just because they are different accounts. Deposits at another separately insured bank may qualify for separate coverage, while joint accounts and other ownership categories follow their own rules. Your total protection depends on how the deposits are owned and where they are held.

    Key Takeaways

    • The standard FDIC limit is $250,000 per depositor, per insured bank, per ownership category.
    • Eligible checking, savings, and CD deposits in the same ownership category at one bank are generally combined.
    • Having multiple accounts at the same bank does not automatically increase coverage.
    • Deposits at separate insured banks may qualify for separate coverage.
    • Joint accounts and certain other ownership categories have specific coverage rules.
    • Eligible principal and accrued interest count toward the applicable insurance limit.

    To estimate your actual coverage, verify your bank’s FDIC status, account ownership, and deposit balances using the FDIC’s official deposit insurance resources.

    FDIC Insurance Coverage at a Glance

    Before calculating your protection, understand the basic FDIC rules. Coverage depends on the insured bank, account ownership category, and eligible deposit balance—not simply the number of accounts you hold.

    Coverage DetailWhat It Means
    Standard limit$250,000 per depositor, per insured bank, per ownership category
    Multiple accountsEligible deposits in the same ownership category at one bank are added together
    Separate banksDeposits may receive separate coverage at each separately FDIC-insured bank
    Covered depositsChecking, savings, money market deposit accounts, and CDs
    Principal and interestBoth count toward the applicable insurance limit, including accrued interest

    Important: FDIC insurance protects eligible deposits, not every product sold by a bank. Stocks, bonds, mutual funds, crypto assets, and U.S. Treasury securities are not FDIC-insured deposits. Treasury securities have separate U.S. government backing.

    Check your bank’s insurance status and account ownership details before estimating your coverage. The FDIC’s Electronic Deposit Insurance Estimator (EDIE) can help calculate coverage for your accounts.

    FDIC Insurance: A Complete Beginner GuideFDIC insurance coverage for multiple accounts

    FDIC insurance protects eligible deposits if an FDIC-insured bank fails. You do not need to purchase this protection separately. The standard limit is $250,000 per depositor, per insured bank, per ownership category.

    What Does “Ownership Category” Mean?

    An ownership category describes how money is legally owned—not simply which account product you opened. Common categories include single accounts, joint accounts, certain retirement accounts, and qualifying trust accounts. Each category has its own rules, and separate coverage applies only when the FDIC requirements for that category are met.

    Why Multiple Accounts May Share One Limit

    Imagine you have a checking account with $100,000 and a savings account with $175,000. Both are in your name alone at the same FDIC-insured bank, with no beneficiaries. These are single accounts, so the FDIC generally combines them. Your total is $275,000: $250,000 is insured and $25,000 is above the standard limit.

    Opening another single account at that same bank would not automatically increase your coverage. Deposits at another separately insured bank may qualify for separate coverage, while eligible deposits in a different ownership category may receive separate protection when all applicable requirements are met.

    Which Accounts Qualify?

    Checking, savings, money market deposit accounts, and CDs are generally covered deposit products. Stocks, bonds, mutual funds, and other investment products are not FDIC-insured deposits, even when purchased through a bank.

    Before calculating your coverage, identify the insured bank, the legal owner, the ownership category, and the combined eligible balance. These details determine how much protection applies.

    How to Calculate FDIC Insurance Coverage

    To calculate FDIC insurance coverage, organize your eligible deposits by insured bank and ownership category. The standard limit is $250,000 per depositor, per insured bank, per ownership category. Include accrued interest and make sure each account is correctly identified by its legal owner.

    Step 1: List Your Accounts at Each Bank

    Write down your checking, savings, money market deposit accounts, and CDs. Record each balance, account title, and owner. Confirm that the institution is FDIC-insured and identify whether accounts are individually or jointly owned.

    Step 2: Group Accounts by Ownership Category

    Separate single accounts, joint accounts, eligible retirement accounts, and qualifying trust accounts. Combine eligible deposits within each ownership category at the same insured bank. Separate coverage applies only when the accounts meet the FDIC requirements for that category.

    Step 3: Apply the Coverage Limit

    Example: You have $90,000 in checking and $190,000 in savings, both single accounts at Bank A. Your combined balance is $280,000. Under the standard limit, $250,000 is insured and $30,000 is above the limit.

    If you also have $150,000 in a single account at Bank B, and Bank B is a separately FDIC-insured institution, that deposit generally receives its own single-account coverage calculation. A separate branch of Bank A would not qualify as another insured bank.

    Helpful tool: Use the FDIC’s EDIE calculator to enter accounts for one bank and review your report. Complete a separate report for each additional insured bank. EDIE’s result depends on accurate account and ownership information.

    Benefits and Drawbacks of FDIC Insurance

    FDIC insurance protects eligible bank deposits if an insured bank fails. It can help you manage savings with greater confidence, but the protection has limits. Understanding both sides is important when you hold money in multiple accounts.

    Benefits

    • Protects eligible deposits at FDIC-insured banks up to the applicable insurance limit.
    • Coverage is automatic for eligible deposits; you do not need to buy a separate policy.
    • Helps depositors understand and organize coverage across banks and ownership categories.
    • Can protect eligible checking, savings, money market deposit accounts, and CDs.

    Drawbacks and Limitations

    • The standard limit is $250,000 per depositor, per insured bank, per ownership category; deposits above applicable coverage may be uninsured.
    • Opening more accounts in the same ownership category at one bank does not automatically increase coverage.
    • Stocks, bonds, mutual funds, and crypto assets are not FDIC-insured deposits.
    • Coverage depends on accurate ownership records and meeting the requirements for each category.

    The bottom line: FDIC insurance protects eligible deposits, not every financial product. Review your account ownership and combined balances to understand how much protection applies.

    FDIC Insurance Coverage Comparison: Multiple Accounts

    FDIC insurance depends on how deposits are owned and where they are held. The standard limit is $250,000 per depositor, per insured bank, per ownership category. Compare the main categories below before calculating your coverage.

    Account CategoryGeneral Coverage RuleWhat to Verify
    Single accountsEligible single accounts are generally combined, with coverage up to $250,000 per depositor at each insured bankAccount ownership and combined single-account balance
    Joint accountsEach qualifying co-owner generally receives up to $250,000 in joint-account coverage at the same insured bankEligible co-owners, ownership shares, and FDIC joint-account requirements
    Retirement accountsCertain eligible retirement deposits receive coverage under the retirement-account categoryQualifying account type and applicable category rules
    Trust accountsCoverage depends on the trust arrangement, eligible owners or beneficiaries, and applicable FDIC rulesTrust documents, beneficiary eligibility, and current coverage requirements
    Separate insured banksDeposits may qualify for separate coverage at each independently FDIC-insured bankVerify each institution’s FDIC insurance status; branches of one bank are not separate banks

    Important: This table provides general guidance, not a personal coverage determination. Joint and trust account coverage depends on specific FDIC requirements. Use the FDIC EDIE calculator and verify your account ownership before relying on an estimate.

    FDIC Insurance Risks, Costs, and Expert Tips

    FDIC insurance generally protects eligible deposits without requiring depositors to purchase a separate policy or pay an insurance premium. The main risk is misunderstanding your coverage and leaving some deposits above the applicable limit uninsured if an insured bank fails.

    Risks to Watch

    • Excess balances: Eligible deposits above your applicable insurance limit may be uninsured.
    • Accrued interest: Interest added to your deposits can push the combined balance above the limit.
    • Bank confusion: Different branches or brand names may belong to the same FDIC-insured bank.
    • Ownership records: Incorrect account titles or incomplete records can affect how coverage is determined.
    • Product confusion: Investment products offered through a bank are not automatically FDIC-insured deposits.

    Expert Tips for Checking Coverage

    • Review account balances, ownership, and beneficiary details when applicable.
    • Confirm the institution’s FDIC insurance status using official resources.
    • Use the FDIC EDIE calculator to estimate coverage for each bank.
    • Keep records accurate, especially for joint and trust accounts.
    • Recheck your coverage after opening accounts, changing ownership, or moving money.

    Practical tip: If your balance is close to the applicable limit, account for accrued interest as well as principal. Review the combined eligible balance rather than relying only on the original deposit amount.

    For an estimate, use the FDIC EDIE calculator and verify your bank and ownership details before relying on the result.

    Common FDIC Insurance Mistakes and Real-Life Examples

    Calculating FDIC insurance coverage becomes easier when you understand how account ownership and bank identity affect the total. A few common mistakes, however, can cause depositors to overestimate their protection.

    Common Mistakes to Avoid

    • Counting each account separately: Eligible checking, savings, and CD deposits in the same ownership category at one insured bank are generally combined.
    • Confusing bank brands: Different branches or brand names may belong to the same FDIC-insured institution.
    • Ignoring accrued interest: Interest can increase your combined eligible balance and affect coverage.
    • Assuming joint coverage is automatic: Joint accounts must meet FDIC ownership and recordkeeping requirements.

    Real-Life Example 1: Multiple Accounts at One Bank

    Maria has $120,000 in checking and $160,000 in savings, both single accounts at Bank A. Her combined eligible balance is $280,000. Assuming no other single-category deposits or interest change the total, $250,000 is insured and $30,000 is above the standard limit.

    Real-Life Example 2: Deposits at Two Insured Banks

    James has $200,000 in single accounts at Bank A and $180,000 in single accounts at separately FDIC-insured Bank B. Assuming he has no other single-category deposits at either bank, both balances are within the standard $250,000 limit applied separately at each institution.

    Remember: These examples assume eligible deposits, accurate ownership records, and no other balances or accrued interest that change the coverage calculation. Use the FDIC EDIE calculator to review your own account details.

    Who Should Calculate FDIC Insurance Coverage?

    Checking FDIC insurance coverage is useful for anyone who keeps substantial savings in bank accounts or holds deposits across multiple institutions. A coverage review can help you understand whether your eligible deposits fit within the applicable insurance limits.

    You Should Review Your Coverage If You:

    • Keep checking, savings, or CD accounts at the same insured bank.
    • Have combined deposits approaching or exceeding $250,000 in one ownership category.
    • Hold deposits at different banks or banking brands and need to verify which institutions are separately insured.
    • Own joint accounts and want to confirm that the accounts meet FDIC requirements.
    • Maintain retirement or trust accounts with coverage rules that depend on account eligibility and ownership.
    • Recently received an inheritance, payout, or other large deposit that may change your total balance.

    Bottom line: Review your coverage when balances, ownership, or banking arrangements change. The FDIC EDIE calculator can help estimate coverage for eligible deposits, but accurate account and ownership details are essential.

    Frequently Asked Questions About FDIC Insurance Coverage

    1. What is the standard FDIC insurance limit?

    The standard limit is $250,000 per depositor, per FDIC-insured bank, per ownership category. Eligible deposits in different categories may receive separate coverage when applicable requirements are met.

    2. Are multiple accounts at the same bank insured separately?

    Not automatically. Eligible deposits owned by the same depositor in the same ownership category at one insured bank are generally combined.

    3. Do checking and savings accounts have separate FDIC coverage?

    Generally, no. Single-owner checking and savings deposits at the same insured bank are combined under the single-account category.

    4. Are CDs included in FDIC insurance?

    Yes. Eligible CDs at an FDIC-insured bank count toward coverage in their applicable ownership category.

    5. Can deposits at two banks receive $500,000 in FDIC coverage?

    They may receive up to $250,000 in standard coverage at each separately FDIC-insured bank for the same ownership category, provided the deposits are eligible and other balances do not change the calculation.

    6. Does accrued interest count toward FDIC insurance?

    Yes. Eligible principal and accrued interest are included when calculating the insured balance.

    7. Do joint accounts receive separate FDIC coverage?

    Qualifying joint accounts may receive coverage separate from other ownership categories. Coverage depends on FDIC ownership and recordkeeping requirements and each co-owner’s share.

    8. How can I calculate my FDIC insurance coverage?

    Use the FDIC EDIE calculator and enter accurate bank, account, balance, and ownership details to estimate coverage.


    Final Verdict: Calculate Your FDIC Coverage Before You Need It

    Calculating FDIC insurance coverage for multiple accounts comes down to identifying your eligible deposits, ownership category, and insured bank. The standard limit is $250,000 per depositor, per FDIC-insured bank, per ownership category. Eligible checking, savings, and CD deposits in the same category at one bank are generally combined, including accrued interest.

    If you keep money in several accounts or banking institutions, review the combined balances instead of assuming each account receives its own coverage limit. Confirm that each institution is separately FDIC-insured and check how your accounts are legally owned.

    Next step: Use the FDIC EDIE calculator to estimate coverage with accurate account and ownership details. For a broader explanation of deposit protection, read our FDIC and NCUA Insurance Explained guide.
    Check Your FDIC Coverage With Confidence

    Review your eligible deposits, account ownership, and insured bank details to understand how your coverage is calculated. Recheck your balances whenever you open an account, move money, or receive a large deposit.

    Read our FDIC and NCUA Insurance Guide

    Have a finance question or feedback? Contact FinanceInvestment.

  • How to Set Up Direct Deposit With Your Bank (2026 Guide)

    How to Set Up Direct Deposit With Your Bank (2026 Guide)

    How to Set Up Direct Deposit With Your Bank: A Step-by-Step Guide

    SR
    Subhash Rukade
    Founder, FinanceInvestment

    BANKING GUIDE

    Published: October 31, 2026
    Updated: October 31, 2026
    Reading time: 10 minutes

    how to set up direct deposit

    How to Set Up Direct Deposit With Your Bank

    Learning how to set up direct deposit can make getting paid easier, whether you have started a new job, want to stop handling paper checks, or receive regular government benefits. Instead of depositing a physical check yourself, your employer or benefit provider can send the money electronically to your eligible checking or savings account.

    The enrollment process is usually simple, but accuracy matters. Your payroll department may ask for your bank’s routing number, account number, account type, and a completed direct deposit form. Entering incorrect information or missing your employer’s payroll deadline could delay your first deposit.

    In this guide, you’ll learn how to gather your banking details, choose where your money should go, complete the enrollment process, and confirm that your first payment arrives. For a broader understanding of electronic payments, you can also explore our Bank Transfers and Payments Guide.

    What You’ll Learn

    • How to find your bank routing number and account number.
    • How to complete a direct deposit form or enroll through your employer’s payroll portal.
    • Whether to deposit your paycheck into checking, savings, or both.
    • How to verify your enrollment and prepare for your first deposit.
    • What to check if your expected direct deposit does not arrive.

    Quick Answer: How Do You Set Up Direct Deposit?

    To set up direct deposit, get your bank’s routing number and account number, then complete the enrollment process provided by your employer or benefit agency. Choose the eligible checking or savings account where you want the money deposited, enter the requested details, and review everything before submitting the form. Depending on the payer, you may need to provide a direct deposit form, a voided check, or other account verification. Ask when the change will take effect so you know whether your first payment will arrive by direct deposit or another method.

    Key Takeaways

    • Gather the correct bank details: You will generally need your routing number, account number, and account type.
    • Follow the payer’s enrollment process: Employers and government agencies may have different forms, portals, and verification requirements.
    • Choose your deposit account: You may be able to use checking, savings, or split your payment between eligible accounts.
    • Allow time for processing: If you miss a payroll cutoff, your first payment may still arrive through your previous payment method.
    • Confirm the effective date: Check with payroll or the benefit provider before assuming the new account is active.

    Security reminder: Never give your online banking password or one-time verification code to someone claiming to enroll you in direct deposit. Use your employer’s verified payroll system or your benefit provider’s official website.

    Direct Deposit at a Glance

    Direct deposit allows an employer, government agency, or another eligible payer to send money electronically to your bank account. Before enrolling, review these essential details to understand what you need and how the process generally works.

    What it meansAn electronic payment sent directly to an eligible bank account.
    Common usesEmployer paychecks, Social Security benefits, and other eligible government payments.
    Information neededBank routing number, account number, and account type.
    Where to enrollEmployer payroll portal, HR department, or the relevant benefit agency.
    Activation timeVaries by payer, account verification, submission date, and payroll or payment schedule.

    Best for: Employees, retirees, and benefit recipients who receive regular payments and prefer automatic deposits over paper checks. Enrollment requirements and eligible account types depend on the organization sending the money.

    Complete Beginner’s Guide to Setting Up Direct Deposithow to set up direct deposit

    Setting up direct deposit is generally straightforward once you have the correct bank information and know how your employer or payment provider handles enrollment. Follow these steps to prepare your details and avoid common setup problems.

    1. Choose the Bank Account for Your Deposit

    Decide whether you want your money deposited into a checking or savings account. Checking is useful for everyday purchases, bills, and automatic payments, while savings can help you set aside money for future goals. If your employer supports split deposits, you may be able to direct specific amounts or percentages into more than one eligible account.

    2. Find Your Routing and Account Numbers

    Locate your details through your bank’s official app, online banking account, statement, or direct deposit form. Confirm that you are using the correct routing number for ACH deposits. Some banks use different routing numbers for ACH and domestic wire transfers, so do not assume they are interchangeable.

    3. Complete Your Direct Deposit Enrollment

    Follow your employer’s verified payroll portal instructions or request an enrollment form from HR. Enter your legal name, account number, routing number, account type, and any requested deposit allocation. Provide a voided check or bank verification document only if your employer requires it.

    4. Submit and Verify the Setup

    Double-check every detail before submitting your information. Ask payroll when the change is expected to take effect and whether your next paycheck will use the new account. After that payment date, check your bank account and pay stub. Keep your existing payment arrangement in place until the first direct deposit is successfully confirmed.

    How Direct Deposit Works Behind the Scenes

    Most U.S. payroll direct deposits are processed through the Automated Clearing House (ACH) network, an electronic payment system used by banks and credit unions. After your enrollment is accepted, your employer or payroll provider uses your banking information to prepare and initiate the payment to your account.

    How the Direct Deposit Process Works

    Step 1 — Payroll calculation: Your employer calculates your gross pay, taxes, other deductions, and final take-home pay.
    Step 2 — Payment initiation: The employer or payroll provider submits the ACH payment instructions through its financial institution.
    Step 3 — ACH processing: The ACH network processes and routes the payment information to the receiving bank or credit union.
    Step 4 — Deposit to your account: Your financial institution processes the incoming credit and makes the funds available according to applicable rules and its processing schedule.

    Direct deposit does not always mean instant access to money. The payment’s effective date, payroll submission deadline, weekends, federal holidays, and bank processing schedules can affect when funds become available. Some banks offer early direct deposit by making eligible payroll payments available before the scheduled payday, but this is a bank-specific feature rather than a guaranteed ACH delivery time.

    To understand the payment network in more detail, read our guide on how ACH transfers work.

    Benefits and Drawbacks of Direct Deposit

    Direct deposit can simplify how you receive regular income, but it also comes with a few limitations. Understanding both sides can help you decide whether it suits your banking and payment needs.

    Benefits

    • Convenience: Eligible payments go directly into your account without requiring a branch visit or check deposit.
    • Payment planning: A regular deposit schedule can make budgeting and bill management easier.
    • Less paperwork: You do not need to handle, carry, or deposit a physical paycheck.
    • Flexible allocation: Some employers allow you to divide your paycheck between multiple eligible accounts.

    Drawbacks

    • Enrollment delays: Missing a payroll cutoff or completing verification late may delay activation.
    • Incorrect account details: A wrong routing or account number can cause a rejected or misdirected payment.
    • Account access issues: Bank outages, account restrictions, or account closures may affect access to deposited funds.
    • Payment schedule limitations: You depend on the payer’s processing schedule and your bank’s funds-availability policies.

    Practical takeaway: Direct deposit is useful for people who want regular payments handled electronically. Protect your banking information, review incoming deposits, and know whom to contact if a payment is delayed or sent to the wrong account.

    Direct Deposit Setup Methods Compared

    Your employer or payment provider determines which enrollment methods are available. Some organizations use online payroll systems, while others accept paper forms or bank-provided documents. Here is how the common options compare.

    Setup methodHow it worksBest suited for
    Employer payroll portalLog in to your employer’s verified payroll system, enter your bank details, and submit the enrollment request.Employees with access to online payroll services.
    Paper direct deposit formComplete the official form with your banking information and return it to the designated HR or payroll department.Employees whose workplace uses paper-based enrollment.
    Bank-provided form or assistanceObtain a prefilled direct deposit form or account details from your bank, then submit the required information through your payer’s approved process.People who need help locating or confirming their banking information.

    Which method should you choose? An employer’s secure payroll portal is often convenient when available. If your workplace accepts paper enrollment, request its official form. A bank-provided form can help supply accurate account details, but it does not necessarily complete enrollment on your behalf. Always follow the payer’s instructions and use a verified submission channel.

    Direct Deposit Costs, Risks, and Expert Tips

    Standard payroll direct deposits into eligible bank accounts generally do not carry a separate fee for receiving the payment. However, your bank account may have maintenance charges, balance requirements, or fees for optional services. Understanding these details and protecting your enrollment information can help prevent avoidable problems.

    Potential Banking Costs

    • Monthly maintenance fees: Some checking or savings accounts charge a fee unless you meet specific waiver conditions.
    • Minimum balance requirements: Certain accounts require a minimum balance to avoid charges.
    • Optional service fees: Other banking services may carry separate charges under your account agreement.

    Risks to Watch For

    • Incorrect bank details: A wrong routing or account number can cause a deposit to be rejected or potentially credited to an unintended account.
    • Payroll impersonation scams: Fraudulent emails or messages may try to trick you into changing direct deposit details.
    • Last-minute account changes: Updates submitted after payroll processing begins may not apply to the upcoming payment.

    Expert Tips for Safer Direct Deposit Setup

    • Verify your routing and account numbers through your bank’s official app, website, or account documents.
    • Submit enrollment changes only through your employer’s verified payroll portal or an authorized HR contact.
    • Confirm unexpected requests to change payroll details through a trusted contact method, not by replying to the suspicious message.
    • Never share your online banking password or one-time security code to complete enrollment.
    • Check your pay stub and bank activity after the expected deposit date.

    Common Direct Deposit Mistakes and How to Avoid Them

    Even a small mistake during enrollment can create problems with your first paycheck. Before submitting your direct deposit details, watch for these common errors:

    • Using the wrong routing number: Check that the number is intended for ACH deposits, not a different banking transaction.
    • Entering an incorrect account number: Compare every digit with your bank’s official account information.
    • Missing the payroll cutoff: Submit your enrollment early and ask when the change will become effective.
    • Selecting the wrong account type: Confirm whether your destination account is checking or savings.
    • Skipping confirmation: Do not assume enrollment is active until your payroll department confirms it.

    Real-Life Example: An Incorrect Account Number

    Imagine a new employee submits a direct deposit form but accidentally enters one incorrect digit in the account number. Depending on the details and receiving bank, the payment could be rejected, delayed, or credited to an unintended account. Once the employee notices the missing paycheck, the right step is to contact payroll immediately, confirm the payment status, and ask about the correction process. If the payment was sent to an unfamiliar account, the employee should also contact the bank promptly.

    What to remember: Verify your routing number, account number, and account type before submitting the form. After enrollment, confirm the effective date and monitor your first expected deposit.

    Who Should Set Up Direct Deposit?

    Direct deposit can suit different people depending on how they receive regular income and manage their bank accounts. It may be particularly useful for:

    • Employees: People who receive regular wages and want their paychecks sent directly to their bank accounts.
    • Retirees: Individuals receiving eligible Social Security or pension payments electronically.
    • Government benefit recipients: People who receive eligible federal payments and want an electronic payment option.
    • Families managing household finances: People who want to organize incoming income across checking and savings accounts, where split deposits are supported.
    • People starting a new job: Employees who want to arrange payroll deposits before their first payday.

    Who may need another option? People without an eligible bank account or those whose payment provider does not support direct deposit may need an alternative payment method. Check the payer’s requirements before enrolling.

    Frequently Asked Questions About Setting Up Direct Deposit

    1. What information do I need to set up direct deposit?

    You generally need your bank’s routing number, account number, account type, and the enrollment information requested by your employer or payment provider. Some organizations may also require a voided check or another form of account verification.

    2. Can I set up direct deposit online?

    Yes. Many employers allow employees to enroll through a secure payroll portal. Government agencies and other payment providers may also offer online enrollment through their official websites.

    3. How long does direct deposit take to start?

    It depends on the payer’s verification process and payment schedule. If you submit your information after the payroll cutoff, your next paycheck may still use your previous payment method. Ask payroll when the new instructions become effective.

    4. Can I use a savings account for direct deposit?

    Often, yes. However, your employer or payment provider must support the account type, and your bank must be able to receive the payment. Confirm your account details before submitting the enrollment form.

    5. Do I need a voided check to set up direct deposit?

    Not necessarily. Many employers accept online enrollment or a bank-provided direct deposit form. Provide a voided check only if your employer specifically requests one.

    6. Can I split my paycheck between two bank accounts?

    Some employers allow you to divide your paycheck between multiple eligible accounts using fixed dollar amounts or percentages. The available options depend on your employer’s payroll system.

    7. Is direct deposit free?

    Receiving a standard payroll direct deposit is generally free. However, your bank may charge separate monthly maintenance or optional service fees under your account agreement.

    8. What should I do if my direct deposit does not arrive?

    Check your pay stub and bank account first. Contact your payroll department or payment provider to confirm whether the payment was submitted, rejected, delayed, or sent to another account. If the money may have gone to an unintended account, contact your bank promptly as well.

    Final Verdict: Is Direct Deposit the Right Choice for You?

    For most people who receive regular eligible payments, direct deposit is a convenient alternative to paper checks. The key is not simply completing the enrollment form but making sure your banking details are accurate and your payment provider has accepted the change. Taking a few minutes to verify your information and confirm the effective date can help prevent avoidable payday problems.

    If you are comparing direct deposit with other electronic payment options, our Bank Transfers and Payments Guide explains how different bank payment methods fit into everyday financial transactions.

    Our final advice: Use an official enrollment channel, double-check your routing and account numbers, and verify your first deposit. A careful setup can make managing regular income simpler without relying on paper checks.

    Take the Next Step Toward Smarter Banking

    Setting up direct deposit can simplify how you receive regular payments. Keep your banking details accurate, follow your payer’s enrollment instructions, and explore more practical personal finance guides from FinanceInvestment.

    Clear information. Confident decisions. Smarter personal finance.

  • Can You Use Any ATM With a Credit Union Account?

    Can You Use Any ATM With a Credit Union Account?

    Can You Use Any ATM With a Credit Union Account?

    Subhash Rukade
    Founder, FinanceInvestment
    Published: October 6, 2026
    Updated: October 6, 2026
    Reading Time: 11–13 min

    Can You Use Any ATM With a Credit Union Account?Can You Use Any ATM With a Credit Union Account

    Can You Use Any ATM With a Credit Union Account? In many cases, your credit union debit card can be used at an ATM outside your credit union’s own locations. But “can use” and “can use without a fee” are not the same thing. The ATM’s network, your credit union’s policies, and the machine’s operator can all affect the transaction.

    That difference becomes important when you’re traveling, working in another city, or simply need cash away from home. An ATM may accept your card while still applying a surcharge. A participating network ATM may offer different terms, while an out-of-network machine may have additional costs or restrictions.

    If you’re still learning how credit unions work, our complete guide to credit unions covers the broader banking relationship. This guide narrows the focus to ATM access, helping you understand what to check before you insert your card and approve a transaction.

    What You’ll Learn

    • When a credit union debit card can be used at another financial institution’s ATM.
    • Why card acceptance does not automatically mean the transaction is fee-free.
    • How participating and out-of-network ATMs can differ.
    • Where to look for compatible ATM locations before withdrawing cash.
    • Which fees, limits, and transaction rules deserve attention.
    • How to make smarter ATM choices when you’re away from home.

    Quick Answer: Can You Use Any ATM With a Credit Union Account?

    In many cases, yes—you can use a credit union debit card at an ATM outside your credit union’s own locations. However, ATM access does not mean every machine has the same fees, services, or transaction rules. Your card network, credit union, and the ATM operator can each affect what happens.

    6 Key Takeaways

    • Your credit union card may work at ATMs beyond your credit union’s own locations.
    • An ATM accepting your card does not automatically mean there is no fee.
    • Participating network ATMs can expand where eligible members access their accounts.
    • Out-of-network machines may have different fees, limits, or transaction conditions.
    • Available services and withdrawal limits can vary by ATM and account.
    • Using your credit union’s current ATM locator can help you identify eligible locations.

    Bottom Line

    You do not need to limit yourself to an ATM carrying your credit union’s name. But before completing a withdrawal, consider the network, available services, and applicable charges. Knowing those details can help you avoid an unpleasant surprise at the machine.

    Table of Contents

    ATM Access at a Glance

    QuestionWhat to Know
    Can I use another ATM?Often yes, when the ATM supports your debit card’s network.
    Will it be free?Not necessarily. The ATM operator or your credit union may charge a fee.
    What determines access?Your card network, participating ATM networks, credit union policies, and transaction limits.
    What should I check first?Use your credit union’s ATM locator and review the fee shown before confirming a withdrawal.

    QUICK TAKE

    A credit union account usually does not mean you must use only your credit union’s own ATMs. Depending on your debit card and the available network, you may have access to many machines in different locations. Still, ATM availability and ATM cost are two separate questions. A machine may accept your card but charge a fee, while another participating ATM may have different terms. Before withdrawing cash, check the network information provided by your credit union and read the fee disclosure on the ATM screen.

    Complete Beginner Guide to Credit Union ATM AccessCan You Use Any ATM With a Credit Union Account

    If you have a credit union checking account, your debit card can give you access to cash at more places than your credit union’s own branches. The exact options depend on the ATM networks your card supports and the rules set by your credit union.

    1. Check Which ATM Networks Your Card Supports

    Start with your credit union’s website, mobile app, or card information. Look for the ATM networks available to members. These network details can help you find compatible machines when you’re away from your usual branch or hometown.

    2. Look at the ATM Fee Before Confirming

    An ATM can accept your debit card while still displaying a surcharge. Read the fee disclosure carefully before completing the withdrawal. If the displayed charge is not acceptable, follow the ATM’s prompts to cancel the transaction before proceeding.

    3. Learn Your Credit Union’s Out-of-Network Rules

    Your credit union may have specific rules for out-of-network ATM fees, reimbursements, daily withdrawal limits, and available services. Knowing these details ahead of time is especially useful when traveling or when you need a larger amount of cash.

    Beginner tip: Save your credit union’s ATM locator on your phone. It can be more useful than searching randomly for the nearest ATM because you can check participating locations and available services before you arrive.

    How ATM Access Works With a Credit Union Account

    When you use a credit union debit card at an ATM, the transaction is routed through the card and ATM networks involved in the transaction. The participating institutions and network arrangements help determine whether the requested service can be authorized.

    Your Credit Union’s Network Matters

    A credit union may participate in one or more ATM networks or other access arrangements. These can give eligible members access to machines beyond the credit union’s branches. Depending on the network and the ATM, available services may include cash withdrawals or balance inquiries. The exact access rules come from your credit union and the applicable network.

    What Happens During a Typical Withdrawal?

    1. You insert or tap your debit card at a compatible ATM and choose the requested transaction.
    2. You enter your PIN or provide other required verification.
    3. The ATM sends the transaction through the applicable network for authorization.
    4. The ATM may display a surcharge before you complete the transaction.
    5. If the transaction is approved, the ATM dispenses the cash and the transaction is recorded by the financial institutions involved.

    Key point: ATM access depends on the networks and arrangements connecting your card with the machine. That is why one ATM may accept your credit union card while another nearby machine may not—or may offer different services or fees.

    Benefits & Drawbacks of Credit Union ATM Access

    Broader ATM access can make a credit union account easier to use, especially when you are away from a branch. The trade-off is that convenience depends on the network, the ATM, and your credit union’s account terms.

    Benefits

    • Convenient cash access: You may have more places to withdraw cash than your credit union’s branch network alone provides.
    • Helpful when traveling: Participating ATM networks can give members access in cities where their credit union has no branch.
    • Possible fee savings: Eligible network ATMs or your credit union’s fee policy may help reduce out-of-network costs.
    • Less dependence on branches: Basic cash withdrawals and other supported ATM services can be handled outside normal branch hours.

    Drawbacks

    • Fees may apply: An ATM outside your credit union’s preferred network can involve a surcharge or other account fee.
    • Services can differ: Another ATM may offer fewer services than an ATM operated or designated by your credit union.
    • Cash limits still matter: Daily or per-transaction limits may restrict the amount you can withdraw.
    • Not every nearby ATM is equally useful: A machine can be accessible while still having less favorable fees or terms.

    The practical trade-off: Wider ATM access gives you flexibility, but the cheapest or most useful machine is not always the closest one. When the choice matters, compare the network, fee disclosure, and withdrawal limit before proceeding.

    Credit Union ATM Comparison: Which Machine Should You Use?

    The closest ATM is not always the best ATM for a credit union member. The right choice depends on whether the machine is supported by your credit union, whether your card can be used there, and what charges or limits apply.

    ATM OptionAccessPossible CostWhen It Makes Sense
    Credit Union ATMTypically intended for members of that credit union.Depends on the credit union’s account and ATM policies.A convenient first choice when one is nearby.
    Participating Network ATMAvailable when your card and the ATM qualify under the applicable network.May have favorable or reduced fees under the network arrangement.Useful when you’re away from your credit union’s branches.
    Out-of-Network ATMMay accept your card even though it is outside the preferred network.ATM surcharges or credit union fees may apply.A practical backup when a participating ATM is unavailable.
    Another Bank’s ATMDepends on card compatibility and the bank’s ATM network.The ATM operator may display a surcharge, and other fees may depend on your credit union.Useful when the machine supports your card and the cost is acceptable.

    Smart choice: If possible, start with an ATM listed by your credit union or its participating network. When you need to use another machine, look at the fee disclosure and consider your credit union’s out-of-network rules before approving the transaction.

    ATM Costs, Risks & Expert Tips

    Using an ATM outside your credit union’s preferred network can create extra costs, but the exact charge depends on the machine and your account terms. The safest approach is to understand the possible charges before you approve the withdrawal.

    Costs to Watch

    • ATM surcharge: The ATM operator may charge a fee for using its machine.
    • Credit union fee: Your credit union may charge a separate out-of-network ATM fee under your account’s fee schedule.
    • Fee reimbursement rules: Some accounts may reimburse certain ATM fees, subject to their specific terms and limits.

    Risks Worth Knowing

    An accepted card does not guarantee a low-cost transaction. You should also be cautious around unfamiliar machines, unexpected prompts, loose or damaged card readers, and unusual requests for information. Daily withdrawal limits can also affect how much cash you can access at one time.

    Expert Tips

    • Check your credit union’s ATM locator before choosing a machine.
    • Read the ATM’s fee disclosure before confirming the withdrawal.
    • Know your daily withdrawal limit if you expect to need substantial cash.
    • Protect your PIN and avoid using a machine that appears damaged or tampered with.

    Common ATM Mistakes Credit Union Members Make

    ATM mistakes often come from making a quick assumption. A machine may accept your card, for example, without offering the lowest-cost option or every service available through your credit union.

    4 Mistakes to Avoid

    1. Assuming every ATM is fee-free: A machine can accept your card and still display a surcharge.
    2. Checking only the ATM’s fee: Your credit union may have separate out-of-network fees or reimbursement rules.
    3. Choosing the closest machine automatically: A nearby ATM may not be part of your preferred network or may offer less favorable terms.
    4. Forgetting withdrawal limits: A daily or transaction limit can affect how much cash you can access at once.

    Real-Life Example

    Imagine Sarah is traveling and needs $100. She finds the nearest ATM and inserts her credit union debit card. Before approving the withdrawal, she notices a surcharge on the screen. She checks her credit union’s ATM information and finds another nearby machine that participates in an eligible network. She reviews the second machine’s fee disclosure before deciding which option makes more sense for her account.

    Lesson: The goal is not simply to find an ATM that works. It is to choose a compatible machine while understanding the applicable fee, network, and withdrawal terms.

    Who Benefits Most From Broad Credit Union ATM Access?

    Broad ATM access can be valuable when you need cash in places where your credit union does not have a branch. The benefit is less about having unlimited ATM choices and more about having convenient, compatible options when you need them.

    Frequent Travelers

    Useful for people who regularly need cash outside their credit union’s local service area.

    Regular Cash Users

    A broader eligible network can make routine withdrawals easier to manage.

    People Banking Outside Branch Hours

    ATM access can provide a practical way to handle supported cash needs when visiting a branch is inconvenient.

    Who should compare more carefully? If you rarely use cash, ATM availability may matter less than monthly fees, digital banking, branch access, or other account features. In that situation, evaluate the overall account instead of choosing one based mainly on ATM access.

    Frequently Asked Questions About Credit Union ATM Access

    1. Can you use any ATM with a credit union account?

    Not literally every ATM. Your credit union debit card may work at many machines, but acceptance depends on the card’s network and the ATM’s compatibility. Fees and available services can also vary.

    2. Can I use another bank’s ATM with a credit union debit card?

    Yes, if the bank’s ATM supports your debit card network. The transaction may still involve an ATM surcharge or a fee under your credit union’s account terms.

    3. Can a credit union charge an out-of-network ATM fee?

    It may. Check your credit union’s current fee schedule to see whether out-of-network ATM fees apply to your account and whether any reimbursement conditions are available.

    4. How do I find a credit union ATM near me?

    Start with your credit union’s website or mobile app. Its ATM locator may show eligible locations, while your card information can help identify participating ATM networks.

    5. Are credit union ATMs always free?

    No. Fees depend on the particular credit union, account terms, ATM location, and applicable network arrangement. Always check the terms that apply to your account.

    6. Can I withdraw cash from an out-of-network ATM?

    You may be able to if the machine supports your debit card. Review the surcharge displayed by the ATM and your credit union’s out-of-network rules before completing the withdrawal.

    7. Can I use my credit union debit card at an ATM while traveling?

    Often, compatible ATM networks can provide access outside your local area. Before traveling, review your credit union’s ATM options, withdrawal limits, and applicable fees so you know what to expect.

    8. What should I check before using another ATM?

    Confirm that the ATM supports your card, review any surcharge shown on screen, check your credit union’s fee policy, and make sure the withdrawal amount is within your applicable limit.

    Quick reminder: ATM access depends on the relationship between your debit card, the applicable network, the ATM, and your credit union’s account terms. Those details determine what you can do and what the transaction may cost.

    Final Verdict: Can You Use Any ATM With a Credit Union Account?

    In most cases, a credit union debit card gives you access to more than just your credit union’s branded ATMs. However, “many compatible ATMs” is a more accurate answer than “any ATM.” The card network, ATM operator, and your credit union’s account terms can all affect the transaction.

    For most members, the real advantage is flexibility. You can use participating ATM networks and, when necessary, other compatible machines instead of depending entirely on nearby branches. The key is knowing which access options your credit union actually provides.

    The Bottom Line

    A credit union account does not normally lock you into one ATM location. Still, ATM access is not unlimited or identical everywhere. If you regularly use cash, a credit union with convenient network access can make everyday banking easier.

    If you are comparing credit unions beyond ATM access, our complete guide to credit unions explains the broader features, benefits, and considerations to evaluate.

    Have a Money Question? Keep Exploring.

    ATM access is only one part of choosing and using a credit union account. Fees, account features, and everyday banking rules can matter just as much.

    Have a money topic you’d like FinanceInvestment to explain? Email us with your question or topic.

    Continue Your Research