Tag: Checking Accounts

  • How to Avoid Credit Union Fees: 2026 Guide to Saving More

    How to Avoid Credit Union Fees: 2026 Guide to Saving More

    How to Avoid Credit Union Fees: 2026 Guide to Saving More

    Subhash Rukade
    Founder, FinanceInvestment
    Published: October 5, 2026
    Updated: October 5, 2026
    Reading Time: 10–12 min

    How to Avoid Credit Union Fees Without Sacrificing ConvenienceHow to Avoid Credit Union Fees

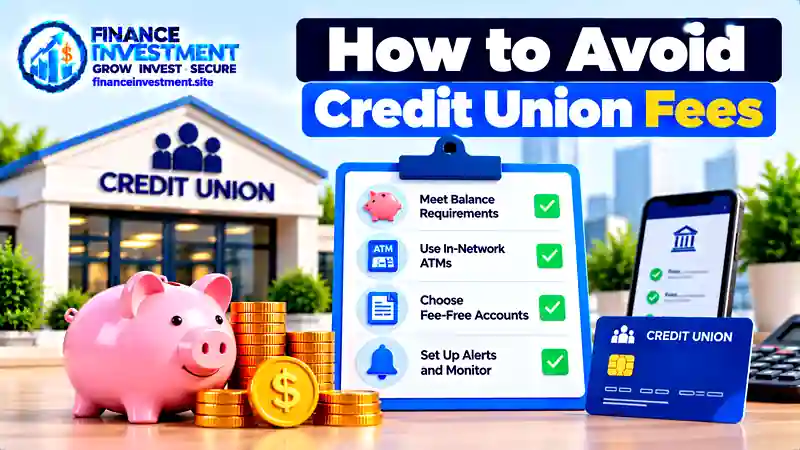
    Knowing how to avoid credit union fees can make a noticeable difference in your everyday finances. A credit union account may have low or no routine charges, but certain actions can still trigger costs. Using an out-of-network ATM, overdrawing your account, ordering paper statements, or missing an account requirement can turn a low-cost account into an expensive one.

    The key is knowing which charges you can prevent before they happen. Simple habits such as using your credit union’s ATM network, keeping a small account cushion, setting up direct deposit when it helps waive a fee, and checking account requirements regularly can reduce unnecessary costs.

    If you’re still learning how credit unions work, our complete guide to credit unions explains the basics. This guide takes the next step by showing you where fees commonly appear and what you can do to keep them under control.

    What You’ll Learn

    • The credit union fees that members are most likely to encounter.
    • Practical ways to avoid monthly, ATM, overdraft, and NSF charges.
    • How to compare account requirements and fee policies before choosing an account.
    • Simple money habits that can help beginners, families, investors, and retirees reduce unnecessary banking costs.

    Quick Answer: How to Avoid Credit Union Fees

    To avoid credit union fees, choose an account that matches how you actually bank, understand its requirements, and prevent the transactions that can trigger charges. Before opening an account, check monthly fees, minimum-balance rules, ATM costs, overdraft policies, and other common charges. Once the account is open, use fee-free options and keep enough money available for upcoming payments.

    6 Key Takeaways

    1. Choose the right account. A low-fee account is only useful if its balance, deposit, and transaction requirements fit your routine.
    2. Know how fees can be waived. Some accounts may remove certain charges when you meet specific conditions.
    3. Use fee-friendly ATM options. Your credit union’s network or available fee-reimbursement options may help reduce ATM costs.
    4. Keep overdrafts under control. Track your available funds and understand whether overdraft protection is enabled.
    5. Prevent returned payments. Keeping enough money available before checks and electronic payments can help avoid NSF-related charges.
    6. Check charges periodically. Reviewing recent transactions can help you spot an unexpected fee and address the cause quickly.

    Table of Contents

    At a Glance: Credit Union Fees in 2026

    Credit union fees are not identical across institutions. The charges you face depend on the account, services you use, and the rules attached to your membership. A smart starting point is to focus on the costs most likely to affect everyday checking and savings activity.

    4Common fee areas covered below
    ATMNetwork rules can affect costs
    2Key payment-balance risks: overdraft and NSF
    1Fee policy to review before opening
    Fee AreaPossible TriggerPractical Prevention
    Monthly maintenanceNot meeting account-specific requirementsChoose an account whose requirements fit your normal balance and activity
    ATM feesUsing an ATM outside an available networkUse participating ATMs or check whether reimbursement is available
    Overdraft feesA covered transaction is paid despite insufficient available fundsMonitor available funds and understand your overdraft options
    NSF feesA payment or transaction is returned because funds are insufficientKeep sufficient funds available before scheduled payments

    QUICK TAKE: The exact fees depend on the credit union and account. Before opening an account, review the current fee disclosures, balance requirements, ATM rules, and overdraft policies. The goal is not simply to find an account with the fewest fees—it is to choose one whose rules match the way you actually manage your money.

    Complete Beginner Guide: How to Avoid Credit Union FeesHow to Avoid Credit Union Fees

    For beginners, avoiding credit union fees starts with one simple idea: choose an account whose rules fit the way you already manage your money. You do not need to eliminate every possible charge. Instead, focus on the fees you are most likely to encounter and build a few habits around them.

    1. Compare the Account Requirements

    Before opening an account, check its monthly maintenance fee, minimum balance requirement, direct-deposit conditions, transaction rules, and other charges. If a fee can be waived, make sure the waiver requirement is realistic for you.

    2. Plan Your ATM Use

    Find out which ATMs you can use without a credit union fee and whether the institution participates in a broader ATM network. Some accounts may also reimburse qualifying out-of-network charges. Check the current account terms before relying on that benefit.

    3. Reduce Overdraft and NSF Risk

    Keep enough money available for upcoming bills, checks, and debit transactions. Review your overdraft settings and understand whether your credit union offers options such as a linked savings account or another form of overdraft protection.

    4. Read the Fee Disclosure Before You Need It

    Keep a copy of the current fee information for your account and review it when your banking needs change. If you see a charge you did not expect, ask the credit union what triggered it and whether another account option could reduce the cost.

    How Credit Union Fee Avoidance Works

    Credit union fee avoidance is not about trying to eliminate every possible charge. It is about understanding which account rules affect you and making small changes before those rules turn into unnecessary costs. The process becomes easier when you connect each fee to the action or account condition that caused it.

    Start With the Cause

    Look at the account terms and your recent transactions together. A monthly charge may be tied to a balance or activity requirement. An ATM charge may come from using an ATM outside the available network. An overdraft or NSF charge can be connected to insufficient funds and the way a payment or transaction is handled.

    Choose the Lowest-Cost Response

    Once you know why a fee occurred, look for the simplest solution. You might meet an account requirement, use an eligible ATM, change an overdraft setting, or keep more money available before scheduled payments. The right choice depends on your credit union’s current terms.

    Recheck When Your Banking Habits Change

    Fee avoidance is not a one-time task. A new job, different income pattern, lower account balance, or greater need for cash withdrawals can change whether your current account still fits. Recheck the terms when your financial routine changes.

    Bottom line: The smartest approach is to understand the rules first, identify the fees that could realistically affect you, and then choose habits or account features that reduce those costs.

    Benefits and Drawbacks of Avoiding Credit Union Fees

    Avoiding unnecessary credit union fees can help your money go further, but the cheapest option is not always the best option. A fee may sometimes pay for a service or convenience you genuinely use. The better goal is to eliminate avoidable costs while keeping the banking features that matter to you.

    Benefits

    • Lower everyday costs: Avoidable charges leave more money available for saving or spending.
    • Easier budgeting: Fewer unexpected fees can make monthly cash-flow planning more predictable.
    • Better account choices: Understanding fees helps you compare accounts based on how you actually bank.
    • Stronger money habits: Monitoring balances and account activity can reduce preventable mistakes.

    Drawbacks

    • Extra effort: Some fee waivers require you to monitor balances, deposits, or account activity.
    • Less convenience: Restricting ATM use may be inconvenient when you need cash away from your usual area.
    • Feature trade-offs: An account with fewer fees may not offer every service or benefit you want.
    • Switching costs: Changing accounts solely to avoid a minor fee may not justify the time and effort.

    Smart approach: Judge an account by its overall value, not by one fee alone. If avoiding a charge creates more inconvenience than the savings are worth, keeping the existing option may be the more sensible choice.

    Credit Union Fee Comparison Table

    Comparing credit union fees is easier when you look at the rules behind each charge, not just the advertised account name. One account may waive a fee under certain conditions, while another may avoid the charge without requiring a minimum balance. Use this table as a practical checklist, then verify the current terms before opening an account.

    Fee TypeWhat May VaryWhat to CheckWays to Reduce the Risk
    Monthly maintenanceFee amount and waiver conditionsBalance, direct deposit, or activity requirementsChoose requirements you can consistently meet
    ATMNetwork access, outside-ATM charges, and reimbursement rulesWhich ATMs are included and whether reimbursement has limitsUse participating ATMs when practical
    OverdraftAvailable coverage, fees, and account settingsWhich transactions are covered and what alternatives are offeredMonitor available funds and understand your settings
    NSFReturned-payment policy and applicable chargesWhat happens when available funds are insufficientKeep enough money available for scheduled payments
    Other servicesChecks, statements, transfers, and special servicesWhich services carry separate chargesUse included or lower-cost options when they meet your needs

    Comparison tip: Don’t choose an account simply because one fee is lower. Think about how often you use ATMs, whether you can meet balance requirements, how you handle recurring payments, and which services you actually use. A slightly different account structure may save more over time if it fits your routine better.

    Always check the credit union’s current disclosures before making a decision. Fees, waiver requirements, ATM arrangements, and available account features can change, so the terms that apply today matter more than an older comparison.

    Costs, Risks and Expert Tips for Avoiding Credit Union Fees

    Avoiding unnecessary fees can save money, but there is another cost to consider: your time, attention, and convenience. Switching accounts just to eliminate a small occasional charge may not be worthwhile. A better strategy is to focus first on fees that are recurring, preventable, or likely to affect your finances more often.

    Watch These Common Risks

    • Overdraft exposure: Understand how your credit union handles overdrafts and which services require your affirmative opt-in, particularly for ATM and one-time debit card transactions.
    • ATM costs: An out-of-network withdrawal may result in a fee from your credit union, the ATM operator, or both, depending on the applicable terms and disclosures.
    • Account requirements: A fee waiver may depend on a balance, deposit, or activity requirement that becomes harder to meet after your financial routine changes.
    • Outdated information: Fee schedules and account terms can change, so do not rely on information you reviewed years ago.

    Expert Tip: Prioritize the Fees You Can Control

    Start with the charges most closely connected to your normal banking habits. If you regularly withdraw cash, pay attention to ATM network access. If overdrafts are a concern, review the available settings and protection options. If you rarely use a particular service, check whether you can avoid paying for it.

    Practical rule: Before changing accounts, estimate how often a particular fee could affect you. Compare that potential cost with the time, effort, and loss of convenience involved in switching. This helps you focus on meaningful savings instead of chasing every small charge.

    Common Mistakes and Real-Life Examples

    Many avoidable credit union fees come from everyday oversights rather than major financial mistakes. A member may miss an account requirement, use an unfamiliar ATM, or forget about a payment that is scheduled to leave the account. These simple examples show why small checks can make a difference.

    Mistake 1: Assuming a Low-Fee Account Has No Conditions

    Example: Maria chooses a checking account because its monthly cost appears low. She later learns that the charge can be avoided only when certain account requirements are met. Reading the current fee schedule before opening the account could have helped her understand those conditions.

    Mistake 2: Using an Unfamiliar ATM Without Checking the Network

    Example: David needs cash while traveling and uses an ATM without checking whether it belongs to his credit union’s network. Depending on the applicable terms, the ATM operator and credit union may each impose a fee. Checking ATM access before withdrawing cash can reduce this risk.

    Mistake 3: Ignoring the Timing of Upcoming Transactions

    Example: James sees money in his account but forgets about a scheduled payment that is due soon. If available funds are not sufficient when the transaction is processed, the payment could lead to an overdraft or returned-payment situation, depending on the transaction and account terms.

    Lesson: Avoiding credit union fees often comes down to knowing your account rules and matching them with your daily habits. Check fee requirements, understand your ATM options, and review available funds before important transactions are processed.

    Who Should Focus on Avoiding Credit Union Fees?

    Almost any credit union member can benefit from avoiding unnecessary fees, but the impact can be greater for people who use their accounts frequently or have little room for unexpected expenses. The goal is not to eliminate every possible charge. It is to prevent costs that are avoidable and do not provide meaningful value.

    Beginners

    New members can benefit from learning account requirements, ATM rules, and common charges before they become a problem.

    Families

    Households with recurring bills and frequent transactions may have more opportunities to prevent avoidable account charges.

    Retirees

    Retirees who carefully manage regular account activity may value predictable banking costs and fewer unexpected charges.

    Frequent ATM Users

    Members who regularly withdraw cash should pay close attention to ATM networks, access rules, and reimbursement policies.

    Best approach: If your current account rarely generates fees and already fits your needs, you may not need to switch. Focus first on recurring or preventable costs, and compare alternatives only when the potential savings justify the effort.

    Frequently Asked Questions About Credit Union Fees

    1. How can I avoid credit union fees?

    You can avoid many credit union fees by choosing an account that fits your banking habits, meeting applicable waiver requirements, using participating ATMs, monitoring available funds, and reviewing the current fee schedule.

    2. Do credit unions charge monthly maintenance fees?

    Some credit union accounts may charge a monthly maintenance fee, while others may not. Some accounts may also waive a fee when specific balance, deposit, or activity requirements are met. Check the account’s current terms before opening it.

    3. How can I avoid credit union ATM fees?

    Use ATMs included in your credit union’s available network when practical. Also check whether your account offers ATM-fee reimbursement and whether any limits or conditions apply.

    4. How can I avoid credit union overdraft fees?

    Monitor your available balance, keep enough money available for upcoming transactions, and understand your credit union’s overdraft settings and available protection options. For covered ATM and one-time debit card overdraft services, understand whether you have affirmatively opted in.

    5. What is the difference between an overdraft fee and an NSF fee?

    An overdraft generally occurs when a credit union pays a transaction even though available funds are insufficient. An NSF situation generally involves a transaction being returned because available funds are insufficient. The exact fees, transaction treatment, and policies depend on the credit union and account.

    6. Can a credit union waive a fee?

    A credit union may waive or reverse a fee in some circumstances, but it is not guaranteed. If you see an unexpected charge, ask the credit union what caused it and whether a fee-waiver option is available.

    7. Should I switch credit unions to avoid fees?

    Not necessarily. If your current account works well and rarely charges you, switching may not be worthwhile. Compare the potential savings with the time, effort, and features you could give up by changing accounts.

    8. Where can I find my credit union’s fees?

    Start with the credit union’s current fee schedule, account disclosures, and applicable account agreement. You can also contact the credit union directly if a charge or requirement is unclear.

    FAQ takeaway: Credit union fees vary by institution and account. The safest approach is to review the current terms, understand the charges most relevant to your banking habits, and ask questions before a fee becomes a recurring expense.

    Final Verdict: How to Avoid Credit Union Fees

    The smartest way to avoid credit union fees is not simply to find an account with the fewest advertised charges. Choose an account whose requirements, access, and services fit the way you actually manage your money.

    Start by reviewing the current fee schedule and account disclosures. Pay close attention to monthly maintenance requirements, ATM access, overdraft policies, NSF charges, and services you use regularly. Then build simple habits around the costs you can control, such as checking available funds before important transactions and using eligible ATMs.

    For beginners, families, retirees, and frequent ATM users, understanding these rules can make banking costs easier to manage. But switching accounts is not automatically the answer. If your current credit union account already fits your needs and rarely creates avoidable charges, keeping it may be more practical.

    Bottom line: Understand the rules, prevent the charges you can control, and compare alternatives when the potential savings are meaningful. That is a practical way to reduce unnecessary credit union fees in 2026 without giving up useful banking features.
    Have a Money Question? Keep Exploring.

    The right account is one that fits your habits, keeps unnecessary costs under control, and gives you the services you actually need. Keep exploring FinanceInvestment for practical guides that can help you make more informed money decisions.

    Have a question about money? Email FinanceInvestment

    Continue Your Research

  • Credit Union Checking Accounts Explained: Guide 2026

    Credit Union Checking Accounts Explained: Guide 2026

    Credit Union Checking Accounts Explained: How They Work, Fees & Benefits in 2026

    Subhash Rukade
    Founder, FinanceInvestment
    Published: October 01, 2026Updated: October  01, 2026Reading Time: 10–12 min


    Credit Union Checking Accounts Explained: What You Need to Know

    Credit Union Checking Accounts Explained: How They Work, Fees and Benefits in 2026Credit union checking accounts are designed for the money you use regularly—such as receiving deposits, paying bills, making purchases and accessing cash. The basic idea is familiar, but the way a credit union structures its checking service can be different from a traditional bank.

    At many credit unions, a checking-style account is known as a share draft account. More importantly, you generally need to qualify for membership before you can open one. That makes eligibility the first step, followed by the account’s fees, minimums, access options and features.

    This guide keeps the process simple. We will look at how credit union checking works, what to compare, where costs can appear and which details matter for everyday banking. If you are new to credit unions, start with our complete Credit Unions Explained guide for the broader picture.

    What You’ll Learn

    • How credit union checking works for everyday spending and cash management.
    • What a share draft account means in practical terms.
    • Which fees, minimums and access features deserve attention.
    • How credit union checking compares with bank checking.
    • Potential advantages and limitations for different households.
    • What to check before opening an account.

    How Do Credit Union Checking Accounts Work?

    Quick answer: A credit union checking account gives members a convenient way to handle everyday money, including deposits, purchases, bill payments, withdrawals and electronic transfers. The account may be called a share draft account, while the exact features and fees depend on the credit union.

    Key Takeaways

    • Membership matters: You generally need to qualify for membership before opening a credit union account.
    • Built for everyday banking: The account can support routine spending, deposits and access to cash.
    • Share draft is a common term: Credit unions may use this name for their checking-style accounts.
    • Fees are institution-specific: Check monthly fees, overdraft charges, ATM costs and other account terms.
    • Access can differ: Review branch locations, ATM networks, shared branching and digital banking options.
    • Account terms matter: Look at minimums, transaction rules and other conditions before opening the account.

    Bottom line: A credit union checking account can be a practical everyday banking option, but the details matter. Check eligibility, fees, access and account features before applying.

    Credit Union Checking Accounts: At a Glance

    QUICK FACT

    A credit union checking account is designed for everyday money management. Many credit unions use the term share draft account for their checking-style accounts. Eligibility, fees, minimums and available features can vary by institution.

    What to CheckWhat It Means
    MembershipYou generally need to qualify for membership before opening the account.
    Everyday useDepending on the account, you may use it for deposits, purchases, withdrawals, bill payments and transfers.
    Fees & minimumsReview monthly fees, balance requirements, overdraft charges and ATM costs.
    AccessCompare branches, ATMs, shared branching and digital banking options.

    Best For

    A credit union checking account may be useful if you want a place for regular spending, deposits and bill payments while using a member-based financial institution. Families, retirees and other everyday banking customers can compare these accounts based on access, costs and the features they actually need.

    IMPORTANT CHECK

    There is no single fee, minimum balance or feature package for every credit union checking account. Read the specific account disclosure before opening one.

    Credit Union Checking Accounts: A Beginner Guide

    Credit Union Checking Accounts ExplainedThink of a credit union checking account as the account you use for money that moves regularly. A paycheck can be deposited into it, while groceries, utilities, subscriptions and other everyday expenses can be paid from the same account. The exact tools depend on the credit union.
    1. Membership Usually Comes First

    Unlike a typical bank account, credit union checking generally begins with membership. The credit union’s field of membership determines who can join. That connection may involve a community, employer, occupation, association or another qualifying relationship. If you are unsure about your eligibility, our guide on who can join a credit union provides a useful starting point.

    2. The Account May Be Called a Share Draft

    Credit unions commonly use the term share draft account for a checking-style account. NCUA lists share draft accounts among the types of share accounts that can receive federal share insurance at federally insured credit unions, subject to the applicable coverage rules.

    3. Everyday Banking Can Look Familiar

    Once the account is open, many everyday tasks may feel familiar. Depending on the institution, you may have a debit card, mobile banking, direct deposit, electronic transfers, bill payment and ATM access. Some credit unions also provide shared branching or participate in broader ATM networks.

    4. The Account Terms Still Matter

    The account name tells you only part of the story. Check the fee schedule, minimum balance, overdraft rules, ATM charges and digital banking features. If federal share insurance matters to you, verify that the credit union is federally insured and review the applicable NCUA coverage rules.

    BEGINNER TIP

    Do not choose an account simply because it is advertised as “free.” Check the conditions behind that offer, then compare them with how you use ATMs, make purchases and move money each month.

    How Credit Union Checking Accounts Work

    After the account is opened, the day-to-day process is fairly familiar. Money can come in through direct deposit or other supported deposit methods, while payments, purchases, transfers and cash withdrawals move money out. The exact options depend on the credit union and account.

    Adding Money to the Account

    A paycheck can be sent directly to the account, or you may be able to deposit money through a branch, mobile check deposit, transfer or another method supported by the credit union. Check the institution’s deposit rules before relying on a particular method.

    Making Everyday Payments

    Depending on the account, you may pay for purchases with a debit card, send electronic payments, use online bill pay or write checks. Transactions can appear as pending before they are fully posted, so the balance shown in your account may not always reflect every upcoming payment.

    Accessing Cash and Managing the Account

    You may access funds through ATMs, branches, online banking or a mobile app, depending on the credit union. Some institutions also participate in shared branching. If you frequently use cash or visit branches, check the available network before opening the account.

    SMART CHECK

    Look at your normal monthly routine: where your paycheck arrives, how you pay bills, how often you use ATMs and which digital tools you need. Then make sure the account supports those habits before you open it.

    Benefits & Drawbacks of Credit Union Checking Accounts

    A credit union checking account can be a practical choice for everyday banking, but the details vary from one institution to another. What works for one household may not work as well for another, so the account terms and your banking habits both deserve attention.

    Potential Benefits

    • Membership can give you access to checking, savings and other services offered by the credit union.
    • Some checking accounts may have competitive fees or useful features, depending on the institution.
    • Shared branching or participating ATM networks can provide additional access where available.
    • In-person support may be useful if you prefer dealing with a local financial institution.

    Potential Drawbacks

    • You may not qualify for every credit union because membership rules differ.
    • Branch and ATM access may not fit your location or regular travel pattern.
    • Mobile and online banking features can vary considerably between institutions.
    • Minimums, overdraft policies and other account fees can still apply.

    EXPERT TIP

    Start with your own routine. If you rely heavily on mobile banking, check the app and digital tools. If you use cash often, examine the ATM network and fees. The best comparison starts with how you actually use your account.

    Credit Union Checking vs Bank Checking

    Both account types can handle everyday spending, deposits, bill payments and cash access. The main difference is the institution behind the account. A credit union generally requires you to qualify for membership, while a bank does not use the same member-based eligibility structure.

    FeatureCredit Union CheckingBank Checking
    EligibilityGenerally requires you to qualify for membership.Does not require credit union membership, although the bank and account may have their own requirements.
    Account terminologyA checking-style account may be called a share draft account.The account is generally called a checking account.
    Fees & minimumsFees, balance requirements and waiver conditions vary by credit union and account.Fees, balance requirements and waiver conditions vary by bank and account.
    AccessBranch, ATM, shared-branching and digital access depend on the institution.Branch, ATM and digital access depend on the bank’s network and account.
    InsuranceFederally insured credit unions provide NCUA share insurance for qualifying shares, subject to applicable limits.FDIC-insured banks provide deposit insurance for qualifying deposits, subject to applicable limits.

    Which Details Matter Most?

    Compare the specific accounts rather than stopping at the institution type. Look at monthly fees, minimum balances, overdraft policies, ATM access, digital banking tools, deposit methods and the services you use most. For the broader differences, see our Credit Union vs Bank guide.

    QUICK COMPARISON

    There is no universal feature set for either type of institution. The useful comparison is between the actual accounts, their costs, access and terms.

    Costs, Risks & Expert Tips for Credit Union Checking

    A checking account can seem straightforward until a fee or account condition catches you by surprise. Before opening one, look beyond the advertised features and read the actual fee schedule and account disclosures.

    Costs Worth Checking

    • Monthly maintenance fees and the conditions for avoiding them.
    • Overdraft, returned-payment or insufficient-funds charges.
    • Out-of-network ATM fees and any related account conditions.
    • Minimum balance or transaction requirements that may affect fees.

    Risks to Watch

    The practical risk is choosing an account without checking whether its rules fit your habits. If you use ATMs frequently, network access matters. If most of your banking happens through an app, digital features deserve closer attention. You should also verify whether the credit union is federally insured if NCUA share insurance is important to you.

    EXPERT TIP

    Read the account disclosure before applying. Compare the fees, minimums, overdraft terms and access rules with your normal monthly routine. A few minutes of checking can help you avoid choosing an account that looks attractive but does not fit the way you bank.

    Common Mistakes When Opening a Credit Union Checking Account

    Most checking-account mistakes happen before the account is even opened. A quick review of the institution and its terms can help you avoid problems later.

    • Assuming you qualify: Check the credit union’s membership rules instead of starting with the application.
    • Choosing by the account label: Read the actual terms rather than relying on words such as “free” or “basic.”
    • Forgetting about access: Check whether the ATM, branch and digital options fit where and how you bank.
    • Moving payments too quickly: Make sure the new account is ready for deposits and recurring bills before changing your payment setup.
    • Ignoring account disclosures: Review the rules for overdrafts, transactions, deposits and other services you expect to use.

    Real-Life Example

    Suppose Daniel wants to move his everyday banking to a credit union. He first confirms that he qualifies for membership. Next, he checks the account’s fee conditions, ATM access and mobile banking tools. Before switching his paycheck and recurring bills, he opens the account, confirms that deposits and payments can be handled as expected, and reviews the overdraft terms.

    THE LESSON

    Take the process in order: confirm eligibility, read the account terms, check access, then move your regular banking over when you are comfortable with the setup.

    Who Should Consider a Credit Union Checking Account?

    A credit union checking account may make sense to research if you are eligible for membership and the account fits the way you handle money. There is no single type of customer it is designed for; the useful comparison depends on your banking needs and the specific account terms.

    It May Be Worth Comparing If You:

    • Need an everyday account: You want a place for regular deposits, purchases, bill payments and transfers.
    • Meet the membership rules: You have a qualifying connection accepted by the credit union.
    • Use branches or ATMs regularly: The institution’s available network works with your location and routine.
    • Want to compare member-based banking: You are interested in seeing how a credit union’s checking account compares with other banking options.

    BEFORE YOU DECIDE

    Check the specific account rather than judging the institution by its name. Review the fees, access, digital tools, minimums and other conditions, then decide whether they fit your normal banking routine.

    Frequently Asked Questions

    These questions cover the practical details worth knowing before opening a credit union checking account.

    1. What is a credit union checking account?

    It is an account designed for everyday banking, including deposits, purchases, bill payments, transfers and cash access. A credit union may call this type of account a share draft account.

    2. Do I need to be a member to open a credit union checking account?

    Generally, yes. You usually need to meet the credit union’s membership eligibility requirements before opening its member accounts.

    3. Is a share draft account the same as a checking account?

    A share draft account is the term commonly used by credit unions for a checking-style account. The exact features and conditions depend on the institution.

    4. Do credit union checking accounts charge monthly fees?

    Some accounts may charge monthly or service fees, while others may waive them when specific conditions are met. Always check the account’s current fee schedule.

    5. Can I get a debit card with a credit union checking account?

    Many credit unions offer debit cards with checking-style accounts, but availability, transaction limits and other features vary by institution.

    6. Are credit union checking accounts federally insured?

    Qualifying shares at federally insured credit unions are generally protected by NCUA share insurance, subject to applicable ownership rules and coverage limits.

    7. Can I use ATMs outside my credit union?

    Often, yes. However, available networks and fees vary, so check participating ATM networks and out-of-network charges before relying on them.

    8. What should I compare before opening a credit union checking account?

    Compare membership eligibility, monthly fees, minimums, overdraft terms, ATM access, digital banking, deposit options and the features you expect to use regularly.

    STRUCTURED DATA NOTE

    The FAQ schema below describes the questions and answers displayed on this page. Structured data does not guarantee a Google FAQ rich result, and Google currently limits FAQ rich-result eligibility.


    Final Verdict: Credit Union Checking Accounts Explained

    A credit union checking account is designed for everyday money management, but the experience depends on the specific institution and account. Membership eligibility, fees, ATM access, digital banking tools and account conditions can all vary.

    For someone considering a credit union, the process is straightforward: confirm that you qualify, review the account terms, and make sure the available services fit your regular banking habits. There is no need to judge the account by its name alone.

    If you want to understand the bigger picture—including membership, accounts, insurance and other services—continue with our complete Credit Unions Explained guide.

    BOTTOM LINE

    Before opening a credit union checking account, check four things: eligibility, account costs, access and the features you actually need. Those details give you a clearer basis for comparing your options.

    Have a Money Question? Keep Exploring.

    Keep exploring FinanceInvestment for practical guides on banking, saving, investing and everyday money decisions. New topics are written to make complicated financial subjects easier to understand.

    📬 Stay Connected With FinanceInvestment

    Have a question or topic suggestion? Send us an email.

    Email FinanceInvestment

    Continue Your Research

  • What Is a Credit Union? Complete Beginner Guide 2026

    What Is a Credit Union? Complete Beginner Guide 2026

    What Is a Credit Union? Complete Beginner Guide

    Subhash Rukade
    Founder, FinanceInvestment
    Published: Sep 29, 2026Updated: Sep 29, 2026Reading Time: 10–12 min


    What Is a Credit Union?

    What Is a Credit UnionIf you’ve ever wondered what is a credit union and how it differs from a bank, the basic idea is straightforward. A credit union is a member-owned, not-for-profit financial cooperative that provides services such as savings, checking, certificates and loans to people who qualify for membership. NCUA explains the credit union structure here.

    The difference becomes clearer when you look beyond the account itself. When you join a credit union, you become a member of the cooperative. That relationship can give you access to everyday banking, savings products and borrowing options offered by the institution.

    There is one important checkpoint before choosing an account: eligibility. Credit unions generally operate within a defined field of membership. Depending on the institution, qualification may be connected to your employer, association, geographic community or another permitted relationship. NCUA’s field-of-membership guide explains how these eligibility rules work.

    THE BIG IDEA

    A credit union can look much like a bank when you use it day to day. The meaningful differences are usually found in ownership, membership, account terms, fees, access and insurance. Understanding those details makes the comparison much easier.

    If you want the wider picture after this beginner guide, continue to our complete Credit Unions Explained guide, which brings together accounts, fees, NCUA insurance, membership and other important questions.

    What You’ll Learn

    • What a credit union is and what makes its ownership structure different.
    • Why membership eligibility matters before you open an account.
    • How common credit union accounts work.
    • How credit unions compare with banks.
    • What to check when reviewing fees, access and insurance.
    • The potential benefits and drawbacks of joining a credit union.

    Quick Answer: What Is a Credit Union?

    THE SHORT ANSWER

    A credit union is a member-owned, not-for-profit financial cooperative. People who meet its membership requirements can join and use services such as checking, savings, certificates and loans. The cooperative structure is one of the main differences between a credit union and a traditional bank.

    Key Takeaways

    • Eligibility matters: You need to qualify under the credit union’s membership rules.
    • Members own the cooperative: The institution is organized around its members rather than outside stockholders.
    • Everyday services are available: Many credit unions offer checking, savings, certificates and loans.
    • Account terms vary: Fees, rates, minimum balances and access can differ from one credit union to another.
    • Federal insurance may apply: Qualifying shares at federally insured credit unions can receive NCUSIF coverage, subject to applicable limits and ownership rules.
    • The institution still matters: Compare the actual account and services instead of relying only on the credit union label.

    BOTTOM LINE

    Think of a credit union as a financial cooperative with membership rules. Before joining, compare eligibility, costs, account features, access and applicable insurance.

    Credit Union at a Glance

    Before we get into the details, here is the quick picture. A credit union can provide many familiar financial services, but membership rules, account terms and insurance status are worth checking before you open an account.

    Quick Facts

    FactorWhat to Know
    OwnershipA credit union is a member-owned cooperative.
    MembershipYou generally need to meet the institution’s eligibility requirements.
    Common ServicesChecking, savings, certificates, payment services and loans may be available.
    AccessBranches, ATMs, shared branching and digital banking depend on the institution.
    Federal InsuranceQualifying shares at federally insured credit unions may receive NCUSIF coverage, subject to applicable rules.

    Key Numbers

    For federally insured credit unions, the standard maximum share-insurance amount is generally $250,000 per share owner, per federally insured credit union, for each ownership category. The actual coverage calculation can depend on ownership structure and other applicable rules.

    There is no single nationwide fee, minimum balance or savings rate for all credit unions. Those figures belong to individual institutions and accounts, so current terms should always be checked before opening an account.

    Who May Find a Credit Union Relevant?

    Credit unions can be relevant to people who qualify for membership and want access to everyday banking, savings or borrowing through a cooperative institution. Families, retirees, students and other consumers may all encounter credit unions, but the useful comparison depends on the products and services they actually need.

    QUICK TAKE

    The first checkpoint is eligibility. Once you qualify, compare the actual account’s fees, rates, minimum balance, access, services and applicable insurance rather than judging the institution by its name alone.

    What Is a Credit Union? A Beginner Guide

    What Is a Credit UnionA credit union is a member-owned, not-for-profit financial cooperative that provides financial services to people who qualify for membership. Like a bank, it may offer checking, savings, certificates, loans and other financial products. The important difference is the ownership structure behind those services. Members join the cooperative and have a membership relationship with the institution. NCUA explains the credit union structure and how it differs from other financial institutions.

    What Does “Member-Owned” Mean?

    When you qualify and join a credit union, you become a member of the cooperative. That is different from simply being a customer of a financial institution. In a federal credit union, members generally have voting rights in the governance of the cooperative, including the ability to participate in the election of the board of directors, subject to the credit union’s governing rules.

    The phrase not-for-profit can also be misunderstood. It does not mean a credit union operates without revenue or earnings. It still has employees, technology, branches, compliance costs and other expenses. Revenue helps cover those costs and supports the institution’s financial strength. NCUA’s guidance on credit-union earnings explains why earnings remain important to a cooperative financial institution.

    Why Do Credit Unions Have Membership Rules?

    A credit union generally serves a defined field of membership. In simple terms, that means there are rules describing who is eligible to join. Depending on the institution, eligibility may be connected to an employer, association, geographic community, family relationship or another qualifying connection. NCUA’s field-of-membership information provides more detail.

    This is why membership should be checked before comparing an account’s rate or fee. If you qualify, the same membership may give you access to several products offered by that credit union.

    Credit Union Terms You May See

    Credit Union TermOften Compared WithTypical Purpose
    Share AccountSavings accountHolding savings and, depending on the credit union, establishing the membership relationship.
    Share Draft AccountChecking accountEveryday spending, payments and other transactions.
    Share CertificateCertificate of deposit (CD)Holding money for a stated term under the certificate’s conditions.

    BEGINNER TIP

    The word “share” can make credit union accounts sound unfamiliar. In practice, many of these products serve purposes similar to accounts you may already know. Focus on the account’s actual fees, rates, access rules and other terms before opening it.

    How Do Credit Unions Work?

    A simple way to understand a credit union is to look at how members save, borrow and use financial services. Members place money into share accounts and other available products. The credit union manages those funds and other resources while making loans to eligible members and providing additional services. Interest from loans and other revenue help pay operating costs and support the institution’s financial strength.

    This creates a cooperative financial cycle. Member savings can help provide part of the funding used for lending, although individual deposits are not directly matched to individual loans. The credit union manages the overall pool of funds, assets and liabilities. NCUA’s explanation of credit union operations describes how federally chartered credit unions allow members to save, borrow and participate in the cooperative.

    Who Runs a Credit Union?

    For a federal credit union, members elect a board of directors from the membership. The board oversees the institution, while management and employees handle day-to-day operations. This gives members a formal role in the governance of the cooperative. NCUA’s operations guidance explains the role of the elected board and member ownership.

    What Happens to Credit Union Earnings?

    Not-for-profit does not mean a credit union can operate without earnings. NCUA explains that credit unions need revenue to cover the cost of serving members and maintain an appropriate level of net worth. Depending on the institution’s financial position, earnings may be retained to strengthen the credit union or may support member value through products, rates, fees or dividends. NCUA’s earnings guidance explains this balance.

    StepWhat Happens
    1. JoinAn eligible person becomes a member under the credit union’s membership rules.
    2. SaveMembers can place funds into available share accounts and other products.
    3. BorrowEligible members can apply for loans under the credit union’s lending requirements.
    4. ManageThe institution manages its funds, expenses, risks, capital and member services.

    HOW IT CONNECTS

    The cooperative model connects membership, saving, lending and shared financial services. The exact rates, fees, products and member benefits depend on the individual credit union and its financial condition.

    Credit Union Benefits & Drawbacks

    A credit union can fit well into one person’s banking setup and be less convenient for another. The important part is to compare the specific institution, because account features, fees, rates and access can vary.

    Potential Benefits

    • Member ownership: Joining creates an ownership relationship within the cooperative.
    • Several banking services: Many credit unions offer checking, savings, certificates and loans through the same membership.
    • Competitive terms may be available: Some institutions offer attractive rates or fees on particular products, although there is no guarantee across all credit unions.
    • Multiple access options: Depending on the institution, members may have access to branches, shared branches, ATMs and digital banking.
    • Federal share insurance: Qualifying shares at federally insured credit unions may receive NCUSIF coverage, subject to applicable limits and ownership rules.

    Potential Drawbacks

    • Membership eligibility: You generally need to meet the credit union’s field-of-membership requirements.
    • Branch availability can vary: Some credit unions have fewer physical locations than larger banking networks.
    • Digital features differ: Mobile apps, online banking tools and remote services are not identical across institutions.
    • Product selection varies: A particular credit union may not offer every financial service you want.
    • Rates and fees are not automatically better: The credit-union structure alone does not guarantee a lower fee or higher savings rate.

    EXPERT TIP

    Don’t compare a credit union with a bank using the name alone. Put the actual accounts side by side and check eligibility, APY or dividend terms, fees, minimum balances, ATM access, digital features and applicable insurance.

    Credit Union vs. Bank: What’s the Difference?

    Credit unions and banks can both provide checking, savings, payment services and loans. The differences become clearer when you look at how each institution is organized, who can use it and which insurance system applies to eligible accounts.

    FactorCredit UnionBank
    OwnershipMember-owned cooperativeBanks have their own ownership and corporate structures.
    EligibilityYou generally need to meet membership requirements.Banks generally do not use a credit-union field-of-membership system.
    InsuranceQualifying shares at federally insured credit unions may receive NCUSIF coverage.Qualifying deposits at FDIC-insured banks may receive FDIC coverage.
    Accounts & ServicesProducts and features vary by credit union.Products and features vary by bank.
    AccessBranches, ATMs, shared networks and digital tools depend on the institution.Branch, ATM and digital access also depend on the institution.

    What Should You Compare?

    For everyday banking, compare the actual account rather than the institution label. Look at monthly fees, minimum balances, savings APY, checking features, ATM access, branch locations and digital banking. If borrowing is important, compare loan APRs, fees, repayment periods and total costs using similar loan amounts and terms.

    Insurance is another important checkpoint. NCUA explains federal share insurance for qualifying shares at federally insured credit unions, while the FDIC explains deposit insurance for qualifying deposits at insured banks.

    COMPARISON TIP

    A useful comparison starts with your actual needs. Put the specific credit union account and bank account side by side and compare their current terms, access and applicable insurance.

    Credit Union Costs, Risks & Expert Tips

    A credit union is not automatically fee-free. Costs depend on the specific account, services you use and the institution’s current terms. Before joining, review the fee schedule and account disclosures instead of focusing only on the advertised rate.

    Costs Worth Checking

    CostWhat to Check
    Monthly FeeWhether a recurring fee applies and whether the credit union offers a waiver.
    Minimum BalanceAny required opening or ongoing balance and the consequences of falling below it.
    ATM ChargesWhich ATMs are available and whether out-of-network fees may apply.
    Other Service FeesReview overdraft, insufficient-funds, wire, transfer and other applicable charges.

    Risks and Important Checks

    The main risk is assuming that all credit unions offer the same rates, fees, technology or access. They do not. A credit union with attractive savings terms may have different ATM coverage or digital features, while another may offer a broader service network. Compare the details that matter to you.

    You should also confirm the institution’s insurance status. At a federally insured credit union, qualifying shares are generally insured through the National Credit Union Share Insurance Fund (NCUSIF), subject to applicable limits and ownership rules. Do not treat every financial product offered by a credit union as an insured share account.

    IMPORTANT CHECK

    Federal share insurance generally applies to qualifying share accounts, not investments such as stocks, bonds or mutual funds. Always confirm what you are purchasing and what protection applies before moving money.

    EXPERT TIP

    Before opening an account, save the fee schedule, rate information, account disclosures and insurance details. These documents give you a clear reference point when reviewing the account later.

    Common Credit Union Mistakes to Avoid

    Opening an account without checking the details can lead to avoidable fees or access problems. A few simple checks can make the process easier and help you understand what you are actually getting.

    Mistakes Beginners Often Make

    1. Skipping the eligibility check: Confirm that you qualify for membership and understand any required opening deposit or membership conditions.
    2. Ignoring the fee schedule: Review monthly, ATM, overdraft, transfer and other applicable service fees.
    3. Assuming every credit union works the same way: Branch locations, ATM access, digital tools and account features can vary significantly.
    4. Focusing only on the advertised rate: Check the APY or dividend rate along with minimum balances, fees and other account conditions.
    5. Overlooking insurance status: Confirm whether the institution is federally insured and understand which qualifying shares may receive NCUSIF coverage.

    Illustrative Example: Comparing a Credit Union Account

    Suppose Sarah is looking for a new checking account. She finds a credit union with a low monthly fee and is interested in joining. Instead of opening the account immediately, she first confirms that she qualifies for membership, checks the minimum balance requirement and reviews the fee schedule.

    Next, Sarah checks the credit union’s ATM network and digital banking features. She also verifies its federal insurance status and compares the account with a bank checking account that she could use instead. The comparison shows her the practical differences in fees, access and features.

    This example shows why the account details matter more than the label. A credit union may fit her needs, but she can make that decision only after reviewing the actual terms.

    LESSON FROM THE EXAMPLE

    Before moving your money, check eligibility, fees, rates, access, account conditions and applicable insurance. A few minutes of comparison can reveal details that an advertised offer may not show.

    Who Should Choose a Credit Union?

    A credit union may be worth considering if you qualify for membership and its accounts, services and costs match the way you manage your money. The right fit depends on your individual needs, so compare the actual terms rather than choosing based only on the institution’s name.

    A Credit Union May Fit If You:

    • Qualify for membership: You meet the credit union’s eligibility requirements.
    • Want several services: You can access the checking, savings, borrowing or other products you need through the institution.
    • Value cooperative membership: You prefer an institution organized around a member-owned structure.
    • Find suitable account terms: The fees, rates, minimum balances and features fit your financial needs.
    • Have convenient access: The available branches, ATMs, shared networks and digital tools work for your routine.

    When Should You Compare Other Options?

    Another financial institution may be worth comparing if you cannot qualify for membership or if the credit union’s fees, account features, ATM access, digital tools or product selection do not meet your needs. Comparing similar accounts can help you see the practical differences before opening an account.

    QUICK CHECK

    Before joining, ask three questions: Can I qualify? Does the account meet my needs? Do the costs, access and protections make sense for me?

    Frequently Asked Questions About Credit Unions

    Here are answers to common beginner questions about credit unions, membership, accounts, fees and federal share insurance.

    1. What Is a Credit Union?

    A credit union is a member-owned, not-for-profit financial cooperative. Eligible members can use services such as checking, savings, certificates and loans. The specific products and terms depend on the institution.

    2. Are Credit Unions Banks?

    No. Credit unions and banks are different types of financial institutions, although they can offer many similar financial products. Credit unions are member-owned cooperatives and generally have membership eligibility requirements.

    3. Can Anyone Join a Credit Union?

    Not necessarily. You generally need to meet the credit union’s field-of-membership requirements. Eligibility can depend on factors such as where you live, where you work, an association or another qualifying relationship.

    4. Are Credit Unions Safe?

    Federally insured credit unions provide federal share insurance for qualifying shares through the National Credit Union Share Insurance Fund (NCUSIF), subject to applicable limits and ownership rules. You should verify the credit union’s insurance status before depositing money.

    5. What Accounts Do Credit Unions Offer?

    Many credit unions offer share savings accounts, share draft accounts that work much like checking accounts, share certificates, money market products and loans. The exact product lineup varies by institution.

    6. Do Credit Unions Have Lower Fees Than Banks?

    Not necessarily. Fees vary by institution and account. Compare monthly maintenance fees, minimum balance requirements, ATM charges, overdraft policies and other service costs before opening an account.

    7. What Is NCUSIF Insurance?

    NCUSIF stands for the National Credit Union Share Insurance Fund. It provides federal share insurance for qualifying shares at federally insured credit unions, subject to applicable coverage limits and ownership categories. It does not insure investments such as stocks, bonds or mutual funds.

    8. How Should I Choose Between a Credit Union and a Bank?

    Start with your actual needs. Compare membership eligibility, account fees, rates, minimum balances, ATM and branch access, digital banking, product selection and applicable insurance. Looking at specific accounts side by side can give you a clearer picture than relying on the institution type alone.

    FAQ TAKEAWAY

    The key is to understand membership, account terms, fees, access and applicable insurance before opening a credit union account.


    Final Verdict: What Is a Credit Union?

    A credit union is a member-owned, not-for-profit financial cooperative that can offer checking, savings, certificates, loans and other financial services. Its membership structure and eligibility rules are what set it apart from a typical bank.

    If you are considering one, start with the basics: Can you qualify, and does the account fit your needs? Then review the actual fees, rates, minimum balances, ATM access, digital tools and available services. These details can vary significantly from one institution to another.

    For federally insured credit unions, also verify the applicable NCUSIF coverage for qualifying shares and understand the relevant ownership limits. This gives you a clearer picture of both the account and the protection attached to it.

    THE BOTTOM LINE

    A credit union is one financial option among several. The useful comparison comes down to eligibility, account terms, costs, access, services and applicable insurance.

    Related Resources & Authority Sources

    If you want to continue learning, our complete Credit Unions Explained guide covers accounts, membership, fees and NCUA insurance in greater detail. You can also explore digital banks vs. credit unions to understand how digital banking models compare with credit-union services.

    Trusted Authority Sources

    • NCUA Share Insurance Coverage — explains federal share insurance, coverage limits, ownership categories and products that are not covered.
    • NCUA Field of Membership — provides information about credit union membership eligibility and field-of-membership rules.
    • FDIC Deposit Insurance — provides information about federal deposit insurance for qualifying deposits at FDIC-insured banks.

    RESEARCH TIP

    Use regulator information to understand insurance and membership rules, then review the credit union’s current account disclosures for its specific rates, fees, minimums and conditions.

    Have a Money Question? Keep Exploring.

    Your banking needs can change over time. Keep learning about accounts, fees, insurance and other money topics so you can evaluate your options with greater confidence.

    📩 Get in Touch With FinanceInvestment

    Have a finance question, topic suggestion or feedback? Send us a message.

    Email FinanceInvestment

    Continue Your Research