Category: Investing

  • How Do Treasury Bills Work? Complete Beginner Guide 2026

    How Do Treasury Bills Work? Complete Beginner Guide 2026

    How Do Treasury Bills Work? A Complete Beginner Guide

    Subhash Rukade
    Founder, FinanceInvestment

    TREASURY BILLS

    BEGINNER GUIDE
    LAST UPDATED
    September 16, 2026
    READING TIME
    About 15 minutes

    How Do Treasury Bills Work? A Simple Starting Point for Beginners
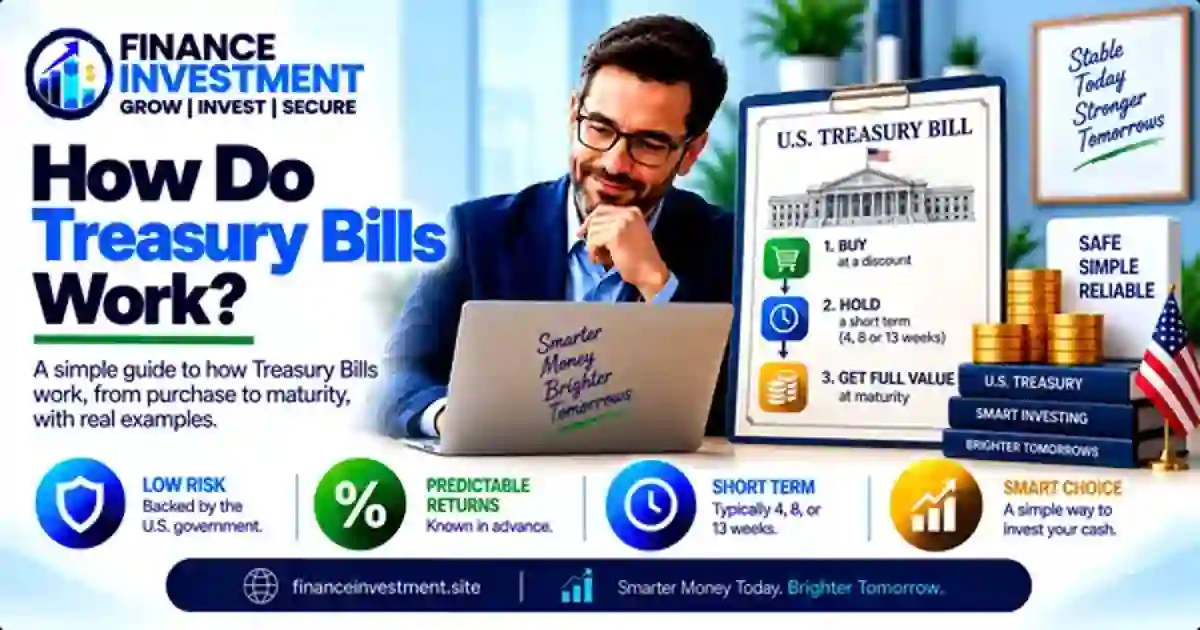
    How Do Treasury Bills WorkHow do Treasury bills work? Treasury bills, or T-bills, are short-term debt securities issued by the U.S. government. They generally do not pay periodic coupon interest. Instead, newly issued T-bills are typically sold below their face value and pay the full face value at maturity when held to maturity.

    For example, an investor might pay less than $1,000 for a T-bill with a $1,000 face value. At maturity, the investor receives $1,000. The difference between the purchase price and face value is the bill’s return before applicable taxes. The annualized investment yield is calculated separately, so the discount should not be treated as the T-bill’s annual interest rate.

    How this guide fits with our main T-bill guide

    This article focuses on the practical question of
    how Treasury bills work.
    For the broader picture—including rates, taxes, buying options, risks and comparisons—see our

    complete Treasury Bills explained guide
    .

    The process follows a simple sequence: the Treasury announces an auction, investors purchase bills, the bills are issued at the auction price, and the investor receives face value at maturity. The details become more useful when you understand how the auction price affects yield and what can happen if you sell before maturity.

    What You’ll Learn

    How Treasury bill auctions and purchases work.

    How face value, purchase price and the discount work together.

    The difference between the discount rate and investment yield.

    What happens when a T-bill reaches its maturity date.

    How early selling, taxes and reinvestment can affect your outcome.

    How Do Treasury Bills Work? Quick Answer

    Treasury bills work by allowing investors to buy short-term U.S. government debt and receive the bill’s face value at maturity. Newly issued T-bills are generally sold at a discount to face value. The difference between the purchase price and face value is the investor’s return before applicable taxes. T-bills generally do not make periodic coupon payments.

    Key Takeaways

    • T-bills have short maturities of one year or less.
    • Newly issued T-bills are generally sold at a discount or, in some offerings, at par.
    • Purchase price, face value, discount rate and investment yield are related but different measures.
    • When held to maturity, the Treasury pays the bill’s face value.
    • T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    The basic idea is simple: you put money into a short-term Treasury security, and its return comes from the difference between what you pay and what you receive at maturity. Understanding that relationship makes the auction process, treasury bill yield, maturity and early-sale decisions much easier to understand.

    Treasury Bills at a Glance

    Treasury bills are short-term U.S. government securities. Their structure is straightforward: you buy a bill at an auction or through a brokerage, hold it until maturity, and generally receive its face value at maturity. The return comes from the difference between your purchase price and that face value.

    IssuerU.S. Department of the Treasury
    MaturityOne year or less
    Minimum investment$100, generally in $100 increments
    How return worksGenerally purchased at a discount and paid at face value at maturity
    Coupon paymentsNone; interest is paid at maturity
    Federal taxInterest is generally subject to federal income tax but exempt from state and local income taxes

    QUICK TAKE: T-bills are not bank deposits, so they are not FDIC-insured. They are Treasury securities backed by the U.S. government’s obligations. TreasuryDirect offers direct purchases, while banks and brokers can provide other ways to buy them. If you hold a bill to maturity, the basic calculation is simple: purchase price compared with face value.

    Treasury Bills: A Complete Beginner Guide
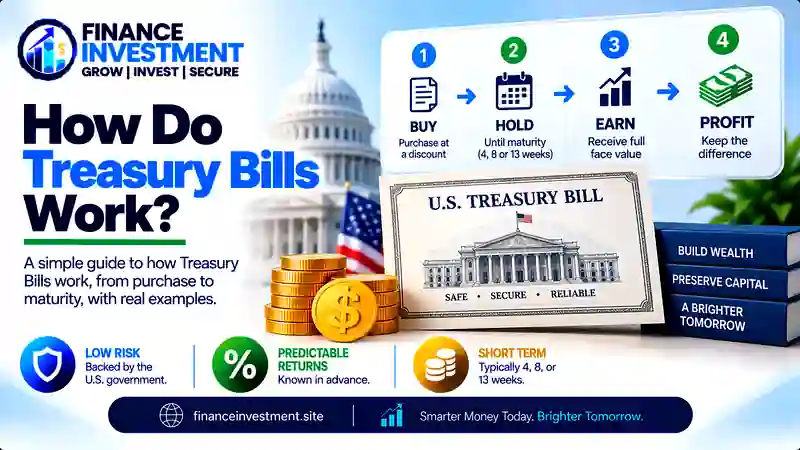
    How Do Treasury Bills WorkIf you are new to Treasury bills, think of a T-bill as a short-term U.S. government security that you can buy for your portfolio. The Treasury issues these securities to borrow money for a limited period. When the bill matures, the Treasury pays its face value. The return generally comes from the difference between the price you paid and the amount received at maturity.

    T-bills have maturities of one year or less. Regular Treasury bill terms include 4, 6, 8, 13, 17, 26 and 52 weeks. The Treasury may offer different terms depending on its borrowing schedule. The minimum purchase amount is generally $100, with additional amounts purchased in $100 increments.

    The key difference from many bonds: T-bills generally do not make periodic coupon payments. Instead, newly issued bills are typically sold at a discount to face value. The difference between the purchase price and face value represents the gross return if you hold the bill to maturity.

    What Happens to Your Money?

    Suppose a T-bill has a $5,000 face value and you pay $4,900 at issuance. If you hold it until maturity, you receive $5,000. The $100 difference is your gross return before applicable taxes. This is an illustration, not a quoted market rate. Your actual purchase price depends on the auction result and the security’s term.

    You can buy T-bills directly through TreasuryDirect or through a bank or brokerage. TreasuryDirect accepts noncompetitive bids for individual investors, while banks and brokers may provide both auction access and secondary-market trading. If you might sell before maturity, the market price can be different from what you originally paid.

    How Treasury Bills Work Step by Step

    The simplest way to understand how Treasury bills work is to follow a T-bill from its auction through maturity. The process is straightforward once you separate the auction, purchase price, yield and maturity.

    1. Treasury announces the bill

    The U.S. Treasury announces the bill’s term, auction date, issue date and other offering details. Investors can choose a maturity that matches their expected cash needs.

    2. You place an order

    When buying through TreasuryDirect, an individual investor generally uses a noncompetitive bid. You accept the yield determined at the auction instead of naming your own rate.

    3. The auction sets the terms

    Competitive bids submitted by eligible bidders help determine the auction result. Noncompetitive bidders receive the same rate as successful competitive bidders, subject to Treasury auction rules.

    4. The bill is issued

    For a newly issued discount T-bill, the amount paid is below the face value. The exact purchase price depends on the auction result and the bill’s term.

    5. The bill reaches maturity

    If you hold the T-bill until maturity, the Treasury pays its face value. The difference between your purchase price and that face value is the gross return before applicable taxes.

    How Treasury Bill Yield Fits In

    A treasury bill yield reflects the relationship between the purchase price, face value and time remaining to maturity. For example, if you pay $9,850 for a $10,000 face-value bill and hold it to maturity, your gross dollar return is $150. That $150 is not itself an annual yield. The quoted discount rate and investment yield use different calculations, so they should not be treated as interchangeable.

    Once the bill matures, you can use the proceeds or reinvest them in another Treasury security. Reinvesting at maturity can create a simple short-term strategy, but the new bill’s yield may be different from the previous one.

    Benefits and Drawbacks of Treasury Bills

    Treasury bills can be useful when you want to keep money in a short-term U.S. government security, but they are not a replacement for every savings or investment option. The right choice depends on when you need the money, how much liquidity you want and whether you need regular income.

    Benefits

    • Direct obligations of the U.S. government.
    • Short maturities can fit near-term financial goals.
    • Interest is generally exempt from state and local income taxes.
    • TreasuryDirect and brokerage accounts provide ways to purchase T-bills.

    Drawbacks

    • They generally do not provide periodic coupon payments.
    • Selling before maturity can result in a different price than your purchase price.
    • The yield available when you reinvest may be higher or lower.
    • Inflation can reduce the purchasing power of your return.

    QUICK TAKE: T-bills can be a strong fit for short-term money when preserving capital and knowing the maturity value matter more than long-term growth. They may be less suitable if you need instant access to cash or want regular interest payments.

    Treasury Bills vs. Other Short-Term Options

    Comparing T-bills with other places to keep short-term cash helps show where each option fits. The main differences are the type of account or security, access to your money, how the return is determined and how the investment is protected.

    OptionHow it worksGood fit for
    T-billsShort-term U.S. Treasury securityDefined maturity dates
    High-yield savingsBank deposit with a generally variable interest rateFrequent access to cash
    CDBank deposit with a stated term and rateMoney you can leave untouched for a set period
    Money market accountBank deposit that may offer checking-style accessCash access with interest

    The protection is also different. T-bills are direct obligations of the U.S. Treasury and are not FDIC-insured deposits. Eligible deposits at FDIC-insured banks are generally covered within applicable FDIC limits. A CD may charge an early-withdrawal penalty, while a savings or money market account generally provides easier access but may have a variable rate. T-bills can also be sold before maturity through a brokerage, but their market price can change.

    QUICK TAKE: T-bills can work well when you have a defined time horizon and want a Treasury security. Savings or money market accounts may be more convenient when immediate access matters, while CDs can suit money you are comfortable locking up for a stated term.

    Treasury Bill Costs, Taxes, Risks and Tips

    T-bills are relatively simple to buy and hold, but the headline yield is not the whole story. Your purchase method, taxes, liquidity needs and plans for the money can affect the overall result.

    Costs and Taxes

    • TreasuryDirect does not charge a fee to open an account or buy Treasury securities.
    • A bank or broker may have its own fees, pricing or transaction terms.
    • T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    Risks and Practical Tips

    A T-bill held to maturity does not require you to sell at a changing market price. However, inflation can reduce the purchasing power of your return, and the yield available when you reinvest may be different. If you sell before maturity, the market price may be higher or lower than the price you originally paid.

    Practical tip: Match the maturity date with your expected cash need. Then compare the investment yield, tax treatment, liquidity and any account costs before choosing a T-bill over a savings account, CD or another short-term option.

    Common Treasury Bill Mistakes and a Real-Life Example

    Understanding how Treasury bills work also means knowing the small details that can affect your decision. Beginners often focus only on the quoted rate and overlook the maturity date, purchase price or tax treatment.

    4 Mistakes to Avoid

    • Mixing up discount rate and investment yield: they use different calculations.
    • Choosing the wrong maturity: a T-bill may mature later than you actually need the cash.
    • Assuming the purchase price is guaranteed if you sell early: market prices can change before maturity.
    • Ignoring federal taxes: T-bill interest is generally federally taxable, although it is exempt from state and local income taxes.

    Real-Life Example

    Imagine Sarah has $20,000 that she expects to need in about six months. She buys an illustrative six-month T-bill with a $20,000 face value for $19,600. If she holds it to maturity, she receives $20,000. Her gross return is therefore $400 before applicable taxes. The $19,600 purchase price is only an example; actual auction prices and yields vary.

    Sarah’s key decision was matching the maturity with her expected cash need. If she sells before maturity instead, the market price could produce a different result. At maturity, she can use the proceeds or reinvest them in another T-bill at the yield available at that time.

    Who Should Consider Treasury Bills?

    Treasury bills may suit investors who have a defined short-term goal and want to hold a direct U.S. Treasury security. They can be useful when the maturity date matches a planned cash need, such as a future expense, or when an investor wants to spread money across several maturity dates.

    T-bills may fit investors who:

    • Want short-term exposure to U.S. government debt.
    • Can leave the money invested until the chosen maturity date.
    • Want to potentially benefit from the federal tax treatment of Treasury interest.
    • Want to create a T-bill ladder with multiple maturity dates.

    T-bills may be less convenient for someone who needs immediate access to cash or wants regular interest payments. The right choice depends on the purpose and timing of the money, rather than simply choosing the option with the highest quoted rate.

    Frequently Asked Questions About Treasury Bills

    1. How do Treasury bills work?

    T-bills are short-term U.S. government securities. Newly issued bills are generally sold at a discount, and investors receive the face value at maturity when held to maturity.

    2. What is the minimum amount to buy?

    The minimum purchase is generally $100, with additional purchases generally made in $100 increments.

    3. Do Treasury bills pay monthly interest?

    No. T-bills generally do not make periodic coupon payments. The return is built into the purchase price, with payment of face value at maturity.

    4. Can I sell a T-bill before maturity?

    Yes. Marketable T-bills can be sold before maturity through a broker or dealer, but the market price can be higher or lower than your purchase price.

    5. Are Treasury bills FDIC-insured?

    No. T-bills are Treasury securities, not bank deposits. Their protection comes from being direct obligations of the U.S. government rather than from FDIC deposit insurance.

    6. Are Treasury bill earnings taxable?

    Yes. Interest from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes.

    7. Can I reinvest a maturing T-bill?

    Yes. You can use the maturity proceeds for another investment or reinvest in another Treasury security. The new security’s yield may be different.

    8. Where can I buy Treasury bills?

    Individual investors can buy T-bills through TreasuryDirect or through a bank or brokerage account. Each route can have different features and terms.

    Final Verdict: How Do Treasury Bills Work?

    So, how do Treasury bills work? You buy a short-term U.S. Treasury security, generally at a price below its face value, and receive the face value when it matures. The difference between those amounts is the gross return when held to maturity. The investment yield is an annualized measure and should not be confused with the bill’s discount rate.

    T-bills can be useful for money with a defined time horizon. They may appeal to investors seeking short-term Treasury exposure and relatively low credit risk. Treasury interest also generally receives favorable state and local tax treatment. However, T-bills are not FDIC-insured deposits, and selling before maturity can result in a market price that differs from your purchase price.

    The key decision: Match the maturity with your expected cash need, compare the investment yield with suitable alternatives, and account for taxes and liquidity before buying. The goal is not simply to find the highest rate; it is to choose a maturity that fits the job your money needs to do.

    For a broader look at Treasury bills, including rates, taxes, buying options and risks, see our
    complete Treasury Bills guide.

    Have a Money Question? Keep Exploring.

    Treasury bills can be useful for short-term money, but the right choice depends on your timeline, liquidity needs, taxes and investment goals. Before you buy, make sure the maturity and expected return fit your plan.

    📩 Get in Touch With FinanceInvestment

    Have a finance question, topic suggestion or feedback? Send us a message.

    Email FinanceInvestment

    Continue Your Research

    Treasury Bills Explained
    •
    CD vs. Treasury Bills

  • What Are Treasury Bills? Complete Beginner Guide 2026

    What Are Treasury Bills? Complete Beginner Guide 2026

    What Are Treasury Bills? Complete Beginner Guide


    Subhash Rukade


    FINANCEINVESTMENT

    Founder, FinanceInvestment


    Updated September 16, 2026


    Reading Time: About 15 minutes


    TREASURY BILLS


    BEGINNER GUIDE


    U.S. Government Securities


    What Are Treasury Bills? A Simple Starting Point for Beginners

    what are Treasury billsTreasury bills, commonly called T-bills, are short-term debt securities issued by the U.S. government. Unlike Treasury notes and bonds, newly issued T-bills generally do not pay periodic coupon interest. Instead, they are typically sold for less than their face value and pay the face value at maturity when held to maturity.

    For example, you might pay less than $1,000 for a T-bill with a $1,000 face value. The difference between the purchase price and the amount received at maturity is the bill’s return. The annualized yield is a separate calculation, which is why the purchase discount should not simply be treated as the T-bill’s annual interest rate.

    How this guide fits with our main T-bill guide

    This article focuses on the basic question of
    what Treasury bills are.
    For the broader picture—including T-bill rates, taxes, buying options, risks and comparisons—see our

    complete Treasury Bills explained guide
    .

    The goal is simple: by the end of this guide, you should understand what a T-bill represents, why its purchase price is usually below face value, how its maturity affects the investment and how it differs from other Treasury securities. That foundation makes the later discussion about rates, taxes and buying options much easier to follow.

    What You’ll Learn

    What Treasury bills are and where they fit within the U.S. Treasury family.

    How face value, purchase price and maturity work together.

    Why T-bills are generally issued below face value instead of paying a regular coupon.

    The common T-bill maturity periods and how they can affect your timeline.

    How Treasury bills compare with savings accounts, CDs and other short-term choices.

    Treasury Bills: Quick Answer & Key Takeaways

    Quick Answer

    Treasury bills, or T-bills, are short-term U.S. government debt securities with maturities of one year or less. Newly issued T-bills are generally sold for less than their face value instead of making regular coupon payments. When a bill reaches maturity, it is redeemed for its face value. The difference between the purchase price and the amount received at maturity is the investor’s return before taxes.

    Key Takeaways

    • T-bills have short maturities, generally ranging from a few weeks to one year or less.
    • A newly issued T-bill is generally purchased below its face value and redeemed for face value at maturity.
    • T-bills generally do not make periodic coupon payments during their term.
    • The amount of the purchase discount is not automatically the same as the bill’s annualized yield.
    • T-bills can generally be purchased through TreasuryDirect and through participating banks or brokerage firms.
    • Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.

    Bottom Line

    The basic idea is straightforward: you generally pay less than the bill’s face value, hold it until maturity, and receive the face value. The details that deserve closer attention are the purchase price, yield, maturity date and tax treatment.

    Table of Contents

    Treasury Bills at a Glance: Quick Facts, Best For & Key Numbers

    Before getting into auctions, pricing and yield calculations, it helps to see the basic T-bill structure in one place. These details give you a quick sense of how Treasury bills are structured and where they may fit into a short-term investment plan.

    Quick FactWhat It Means
    Investment typeShort-term U.S. government debt security
    MaturityCommon terms include 4, 8, 13, 17, 26 and 52 weeks
    Purchase structureGenerally issued below face value and redeemed at face value at maturity
    Face-value incrementsGenerally $100 and multiples of $100
    Coupon paymentsNo regular coupon payments during the bill’s term
    Tax treatmentGenerally subject to federal income tax and exempt from state and local income taxes

    Who Are Treasury Bills Best For?

    T-bills may suit investors who have money set aside for a defined short-term goal and do not need it for everyday spending. They can also be useful for people who want short-term exposure to U.S. government debt and may value the state and local income-tax treatment.

    Look beyond the headline number

    The number you see quoted for a T-bill may represent a particular rate or yield measure, so it should not be confused with the dollar amount of the purchase discount. When comparing bills, consider the purchase price, annualized yield, maturity date and tax treatment together.

    Complete Beginner Guide: What Are Treasury Bills?

    what are Treasury billsTreasury bills, commonly called T-bills, are short-term debt securities issued by the U.S. Department of the Treasury. They mature in one year or less and are designed to provide a relatively short-term way to invest in a direct obligation of the federal government. Unlike Treasury notes and bonds, T-bills do not make regular coupon payments during their term.
    Instead, a newly issued T-bill is generally purchased for less than its face value. When the bill reaches maturity, the Treasury pays its face value. That difference between the purchase price and the amount received at maturity is the basic source of the investor’s return.

    A simple example

    Imagine a T-bill with a $1,000 face value. If its purchase price is $990, you pay $990 and receive $1,000 when the bill matures, assuming you hold it to maturity. The $10 difference is the basic return before taxes. The actual purchase price and annualized yield vary with the bill and the auction or market conditions at the time.

    How T-Bills Fit Into the Treasury Family

    T-bills are the shortest-term marketable Treasury securities. Treasury notes generally mature in more than one year and up to 10 years, while Treasury bonds generally have maturities longer than 10 years. Notes and bonds generally pay interest every six months; T-bills instead provide their return through the difference between the purchase price and the amount paid at maturity.

    If you are comparing T-bills with bank deposits, our guide to

    Treasury bills vs. CDs

    looks at the major differences. You can also return to our

    complete Treasury Bills explained guide

    for the broader topic.

    The beginner takeaway

    The basic idea is simple: you buy a short-term Treasury security, generally at a price below its face value, and receive the face value when it matures. The next piece is understanding how Treasury auctions determine the price, how the discount rate differs from the investment yield, and what happens when the bill matures.

    How Treasury Bills Work: Purchase Price, Discount, Yield, Auctions & Maturity

    The easiest way to understand how Treasury bills work is to follow the transaction from auction to maturity. A T-bill is generally issued at a price below its face value. You pay the purchase price upfront, and if you hold the bill until maturity, the U.S. Treasury pays the full face value. The difference between those amounts is the bill’s discount and forms the basic return before taxes.

    Purchase Price and Discount

    Treasury bill prices are quoted per $100 of face value. For example, an illustrative price of $98.50 per $100 would mean a $1,000 face-value bill costs $985. If held to maturity, the Treasury would pay $1,000. The $15 difference is the discount amount and represents the investor’s return before taxes.

    Discount Rate vs. Investment Rate

    These two figures describe the same T-bill from different perspectives. The discount rate is calculated using the bill’s face value and a 360-day basis. The investment rate is based on the purchase price and uses a 365-day basis, or 366 days when applicable. Because the investment rate is based on the amount actually invested, TreasuryDirect says it can be used to compare a T-bill’s return with other investments.

    How the Treasury Auction Works

    Newly issued T-bills are generally sold through Treasury auctions. Individual investors using TreasuryDirect normally submit noncompetitive bids, which means they agree to accept the auction’s resulting rate. Competitive bidders specify the rate they are willing to accept. Treasury first accepts noncompetitive bids and then awards competitive bids starting with the lowest accepted rate until the announced offering amount is filled.

    What Happens at Maturity?

    At maturity, the bill becomes due and the Treasury pays its face value. There is no separate periodic coupon payment during the term. If you decide to sell a T-bill before maturity through the secondary market, the price may be higher or lower than your original purchase price because market conditions can change.

    The key idea to remember

    A T-bill’s purchase price, discount rate and investment rate are connected, but they are not the same thing. Start with the amount you pay, compare it with the face value you receive at maturity, and then use the investment rate when comparing annualized returns with other investments.

    Treasury Bill Benefits & Drawbacks: Pros, Cons & Key Trade-Offs

    Quick Answer

    Treasury bills can be attractive for investors who want short-term exposure to U.S. government securities without committing money for several years. Their main advantages are short maturities, a straightforward discount-to-face-value structure and federal government backing. The trade-offs include no regular coupon payments, the possibility of a different rate when you reinvest after maturity, and potential price changes if you sell before maturity.

    Key Benefits of Treasury Bills

    • Short-term flexibility: T-bills have maturities of one year or less, with regular terms ranging from 4 to 52 weeks.
    • U.S. government obligation: T-bills are direct obligations of the U.S. government and are backed by its full faith and credit.
    • Simple structure: You generally buy a bill below face value and receive its face value when it matures.
    • State and local tax advantage: Treasury bill interest is subject to federal income tax but is exempt from state and local income taxes.

    Key Drawbacks to Consider

    • No regular coupon payments: T-bills do not provide periodic interest checks during the term; the interest is paid when the bill matures.
    • Reinvestment risk: When a T-bill matures, the rate available on a new bill may be higher or lower than the rate on your original investment.
    • Early-sale price risk: If you sell before maturity, the market price can be different from your original purchase price.
    • Not a bank deposit: T-bills are Treasury securities, not FDIC-insured bank deposits, so they should be compared with the right type of alternative.

    Bottom Line

    T-bills can work well for money you expect to need within a relatively short period and for investors who value U.S. government securities and state and local tax exemption. Their biggest trade-offs are the lack of periodic cash payments, changing reinvestment rates and possible price fluctuations if you sell before maturity.

    Treasury Bills Comparison Table: T-Bills vs. Savings Accounts, HYSA, Money Market Accounts & CDs

    Quick Answer

    Treasury bills are different from savings accounts, high-yield savings accounts, money market accounts and CDs because a T-bill is a U.S. Treasury security rather than a bank deposit. Savings and money market accounts are built for easier access to cash, while CDs and T-bills are generally better suited to money you can leave invested for a defined period.

    OptionAccess to MoneyHow You EarnProtection
    T-BillsReceive face value at maturity; can generally be sold before maturity through the secondary marketGenerally bought below face valueDirect U.S. government obligation; not FDIC-insured
    Savings AccountGenerally easy access, subject to account termsBank pays interestFDIC insurance may apply at an insured bank, subject to limits and rules
    High-Yield SavingsGenerally easy access, subject to account termsBank pays interestFDIC insurance may apply at an insured bank, subject to limits and rules
    Money Market AccountGenerally accessible, with features and restrictions varying by accountBank pays interestFDIC insurance may apply at an insured bank, subject to limits and rules
    CDUsually intended to remain invested until maturity; early withdrawal may involve a penaltyBank pays interest under the CD termsFDIC insurance may apply at an insured bank, subject to limits and rules

    Which Difference Matters Most?

    Start with the purpose of the money. A savings account or high-yield savings account can be more convenient when you need frequent access. A money market account may combine interest earnings with certain transaction features. A CD can lock in a rate for a chosen term, while a T-bill gives you a short-term Treasury security with a maturity date. T-bill interest also receives different state and local tax treatment from ordinary bank-deposit interest.

    For a closer look at one of these alternatives, compare

    Treasury bills vs. CDs

    or review our guides to

    money market accounts vs. Treasury bills
    .

    Bottom Line

    There is no single winner for every short-term cash need. T-bills offer Treasury exposure, while bank accounts emphasize accessibility and CDs emphasize a defined deposit term. Compare the expected return, access to your money, maturity, taxes and applicable insurance or government backing before choosing.

    Treasury Bill Costs, Taxes, Risks & Expert Tips

    Quick Answer

    Treasury bills generally have no TreasuryDirect purchase fee, although a broker or other financial institution may charge for its services. The bigger considerations are taxes, what happens if you sell before maturity, and the rate available when you reinvest after a bill matures. Those details can affect the return you actually keep and how well a T-bill fits your cash needs.

    Key Costs, Taxes & Risks to Know

    • Purchase costs: TreasuryDirect does not charge a fee to open an account or buy Treasury securities. Brokerage firms may charge fees or apply their own pricing.
    • Federal taxes: Interest from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes.
    • Early-sale risk: If you sell a T-bill before maturity, its market price may be higher or lower than your purchase price, which can change your actual gain or loss.
    • Reinvestment risk: When the bill matures, the rate available on a new T-bill may be different from the rate on your original investment.
    • Tax reporting: Treasury interest is generally reported on Form 1099-INT, with Treasury bills included in Box 3. Tax reporting can differ when a bill is sold before maturity.

    Expert Tip

    Match the T-bill’s maturity to the date you expect to need the money. Then compare the purchase price, investment rate, maturity date and tax treatment. If there is a reasonable chance you will need the money early, remember that selling before maturity exposes you to market-price changes.

    Bottom Line

    T-bill costs are not limited to the amount you pay at purchase. Taxes, possible selling costs, market prices before maturity and future reinvestment rates can all affect the outcome. For a short-term goal, choosing the right maturity and understanding the tax treatment may matter more than simply selecting the highest quoted rate.

    Common Treasury Bill Mistakes + Illustrative Example

    Quick Answer

    T-bill mistakes often happen when investors focus only on the quoted rate and overlook the purchase price, maturity date, tax treatment or what happens if they sell early. A T-bill is also not the same as a savings account or CD, so comparing the products requires more than looking at the headline yield.

    Key Takeaways

    • Don’t confuse rates: The discount rate and investment rate use different calculation methods and should not be treated as the same number.
    • Check the maturity date: A bill that matures later than your planned cash need may not fit your timeline.
    • Know the tax treatment: Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • Don’t assume early access is guaranteed at face value: Selling before maturity means accepting the market price available at that time.
    • Plan for reinvestment: The rate available when your T-bill matures may be different from the rate on your original bill.

    Illustrative Example

    Suppose an investor buys a T-bill with a $10,000 face value for an illustrative $9,850 and holds it until maturity. The investor would receive $10,000 at maturity, creating a $150 difference before taxes. This is only an example—the actual purchase price, discount and annualized investment rate depend on the specific bill and its auction or market conditions.

    Bottom Line

    The safest way to evaluate a T-bill is to look beyond the quoted rate. Check what you pay, when the bill matures, how the return is calculated and what happens if your plans change before maturity. Those details can prevent a simple short-term investment from becoming an unexpected cash-flow problem.

    Who Should Consider Treasury Bills? — Beginners, Retirees, Emergency Funds & Large Balances

    QUICK ANSWER

    Treasury bills may suit investors who have cash set aside for a specific short-term goal and know when they are likely to need it. They can be useful for beginners, retirees and people holding larger cash balances. The key is choosing a maturity that fits the timing of the goal.

    Key Takeaways

    • Beginners can use T-bills to learn how short-term U.S. government securities work.
    • Retirees may consider T-bills for cash that has a defined short-term purpose.
    • Investors with larger cash balances can spread maturities through a T-bill ladder.
    • Emergency funds should keep enough money readily accessible for unexpected expenses.
    • People seeking long-term growth generally need investments beyond short-term T-bills.
    • Before buying, check the maturity date and make sure the money can remain invested until then.

    BOTTOM LINE

    Treasury bills can be a practical choice for short-term cash when the maturity matches the investor’s timeline. They are not a substitute for money that must remain immediately accessible, and they are not designed to provide the long-term growth potential of stocks. Match the bill’s maturity to the job the cash needs to do.

    Treasury Bills FAQs: 8 Common Questions Beginners Ask

    QUICK ANSWER

    Treasury bills are short-term U.S. government securities with maturities of one year or less. They generally do not make periodic coupon payments. Instead, newly issued T-bills are typically sold at a discount or at par, and the investor receives the bill’s face value at maturity.

    Frequently Asked Questions

    1. What are Treasury bills?

    Treasury bills, or T-bills, are short-term debt securities issued by the U.S. Treasury. They have maturities of one year or less.

    2. Do Treasury bills pay monthly interest?

    No. T-bills generally do not pay periodic coupon interest. For a bill purchased below face value, the return generally comes from the difference between the purchase price and face value at maturity.

    3. What are the common Treasury bill maturities?

    Regular Treasury bill terms include 4, 6, 8, 13, 17, 26 and 52 weeks, although issuance can vary according to the Treasury’s schedule.

    4. Where can I buy Treasury bills?

    You can generally buy newly issued T-bills through TreasuryDirect or through participating banks and brokers. Brokerage fees and available services can vary.

    5. Are Treasury bills FDIC insured?

    No. T-bills are not bank deposits, so FDIC deposit insurance does not apply. They are obligations of the U.S. government.

    6. How are Treasury bills taxed?

    Interest from Treasury bills is generally subject to federal income tax but exempt from state and local income taxes. Individual tax circumstances can affect the final after-tax result.

    7. Can I sell a Treasury bill before maturity?

    Yes. Marketable T-bills can generally be sold before maturity through a broker or applicable market channel. The market price at the time of sale may be above or below the purchase price.

    8. What happens when a Treasury bill matures?

    At maturity, the Treasury pays the bill’s face value. For a bill purchased at a discount, the difference between the purchase price and face value is generally the investor’s return before applicable taxes.

    BOTTOM LINE

    Treasury bill questions usually come down to the purchase price, maturity, return calculation, access before maturity and taxes. Once those pieces are clear, it becomes easier to judge whether a T-bill fits a particular short-term cash goal.

    Treasury Bills Final Verdict: Are T-Bills Right for You?

    QUICK ANSWER

    Treasury bills can be a useful choice for short-term money when you know roughly when you will need the cash. Their simple structure, short maturities and U.S. government backing make them worth considering, but they are not designed to replace an accessible emergency reserve or long-term growth investments.

    Key Takeaways

    • T-bills are short-term U.S. government debt securities with maturities of one year or less.
    • Newly issued T-bills are generally purchased at a discount or at par and redeemed at face value at maturity.
    • They can work well for defined short-term cash goals and investors who can match the maturity to their timeline.
    • T-bills are not FDIC-insured bank deposits, and selling before maturity exposes the investment to market-price changes.
    • Interest is generally subject to federal income tax but exempt from state and local income taxes.
    • For long-term wealth building, T-bills are usually better viewed as one part of a broader investment strategy rather than the entire portfolio.

    BOTTOM LINE

    Treasury bills make the most sense when safety of the U.S. government obligation, a short time horizon and a known maturity fit your goal. Before buying, compare the purchase price, investment rate, maturity date and tax treatment. If you need the money immediately or are investing for decades, another option may be a better fit.

    Treasury Bills Resources: Related Guides & Official Sources

    QUICK ANSWER

    The best next step is to use a mix of practical investing guides and official sources. FinanceInvestment can help you compare T-bills with other short-term choices, while TreasuryDirect, the IRS and Investor.gov provide primary information about Treasury securities, taxes and investing basics.

    Key Resources

    BOTTOM LINE

    Use the related FinanceInvestment guides for comparisons and practical explanations, then verify current Treasury and tax details with official government sources. That combination gives you both context and authoritative information before making a T-bill decision.

    Have a Money Question? Keep Exploring.

    Understanding Treasury bills is a good starting point. From here, compare T-bills with other short-term choices and consider how each option fits your cash needs, timeline and overall investment plan.

    📩 Get in Touch With FinanceInvestment

    Have a finance question or a topic you would like us to cover? Send us a message.


    Email FinanceInvestment

  • Treasury Bills Explained: Rates, Taxes & Investing in 2026

    Treasury Bills Explained: Rates, Taxes & Investing in 2026

    Treasury Bills (T-Bills) Explained: Complete Beginner Guide to Rates, Taxes & Investing in 2026

    Subhash Rukade
    Founder, FinanceInvestment


    T-BILLS GUIDE


    BEGINNER FRIENDLY


    Updated


    September 15, 2026


    Reading Time


    About 38 minutes


    Topic


    U.S. Treasury Bills


    Treasury Bills Explained: A Simple Starting Point for Beginners

    Treasury billsTreasury bills can look confusing at first. A quote may show a discount rate, an investment yield, a purchase price and a maturity date, leaving you to figure out which number actually represents your return. The underlying idea is much easier to follow: Treasury bills are short-term U.S. government debt securities that are generally purchased for less than their face value and paid at face value when they mature.

    That setup can make T-bills useful for money with a known time horizon. You choose a maturity, purchase the bill, and receive its scheduled face value at maturity if you hold it until then. Your actual investment return comes from the difference between what you paid and what you receive, while taxes and the timing of your investment also affect the result. This is one reason T-bills should not be judged by a quoted rate alone.

    The key idea: a T-bill’s purchase price, face value and time to maturity work together to determine its return. Terms such as discount rate and yield describe that return in different ways, so they should not be treated as identical.

    There is also a practical side to the decision. Treasury bills are not savings accounts, money market accounts or CDs, even though investors sometimes use them for similar short-term goals. T-bills are U.S. government securities, while bank and credit union deposit products follow different rules for access, insurance, interest payments and withdrawals. Your choice can therefore change depending on how soon you may need the money and how much flexibility you want.

    This guide starts with the basics and gradually moves into the details that matter for an actual purchase. We will cover T-bill terms, auctions, pricing, yields, maturity, taxes, safety, buying options and early-sale considerations. You will also see how T-bills compare with CDs, high-yield savings accounts and money market accounts. If you are specifically weighing a CD against a Treasury bill, our CD vs. Treasury bills guide gives that comparison a closer look.

    What You’ll Learn

    • What Treasury bills are and how they differ from other Treasury securities and bank deposit products.
    • How T-bills work from purchase and auction through maturity and payment.
    • How Treasury bill rates and yields work and why the purchase price matters when measuring your return.
    • How to buy Treasury bills through TreasuryDirect or a brokerage account, including the practical differences between the two.
    • How Treasury bill taxes work, including federal income tax and the treatment of Treasury interest for state and local taxes.
    • What to consider before choosing a maturity, including cash needs, reinvestment and the possibility of selling before maturity.
    • How T-bills compare with other short-term options so you can see where they may fit alongside savings accounts, money market accounts and CDs.

    Treasury Bills: Quick Answer & Key Takeaways

    Quick answer: What are Treasury bills?

    Treasury bills, usually called T-bills, are short-term U.S. government securities with maturities of one year or less. They are generally issued at a price below their face value and pay the face value when they mature. Because there is normally no periodic interest payment, the difference between the purchase price and the amount paid at maturity represents the bill’s basic return before taxes. Investors can generally buy T-bills through TreasuryDirect or a brokerage account.

    T-bills can suit money that has a defined short-term purpose, such as cash you expect to use at a known point in the future. Their structure is different from a savings account, money market account or CD. T-bills are securities rather than bank deposits, so they are not covered by FDIC deposit insurance. If you hold one until maturity, you receive its scheduled face value; if you sell it before maturity, its market price may be higher or lower than what you originally paid.

    Key Takeaways

    • Short-term by design: Treasury bills have maturities of one year or less, with several standard terms available.
    • Usually bought below face value: Instead of making regular coupon payments, a T-bill generally provides its return through the difference between its purchase price and face value at maturity.
    • Rate and yield are not the same thing: A quoted discount rate and an investment yield use different calculations, so the two figures should not be treated as interchangeable.
    • Two common ways to buy: TreasuryDirect and brokerage accounts can both provide access to Treasury bills, although the purchasing experience and available features can differ.
    • Federal tax applies: Treasury bill interest is generally subject to federal income tax but is exempt from state and local income taxes.
    • Early selling is different from holding to maturity: A T-bill sold before maturity is traded at its current market price, which can be above or below the original purchase price.
    • Convenience still matters: T-bills can work well for planned short-term cash needs, while a savings account, money market account or CD may be a better fit when immediate access or a different account structure matters more.

    Bottom line: To understand a Treasury bill, start with four questions: How much do I pay? What will I receive at maturity? When will I receive it? And how will the return be taxed? Once those pieces are clear, comparing T-bills with other short-term options becomes much easier.

    Table of Contents

    T-Bills at a Glance: Quick Facts, Best For & Key Numbers

    Before getting into auctions, pricing and yield calculations, it helps to see the basic structure in one place. Treasury bills are built for short-term borrowing by the U.S. government, so the details that matter most are the bill’s maturity, purchase price, face value, yield and how you plan to use the money.

    Quick FactWhat It Means
    Investment typeShort-term U.S. government debt security
    MaturityOne year or less; common terms include 4, 8, 13, 17, 26 and 52 weeks
    Purchase priceGenerally below the bill’s face value
    How returns are paidT-bills generally do not make periodic coupon payments; the return is reflected in the price paid and the face value received at maturity
    DenominationGenerally available in $100 face-value increments
    Where to buyTreasuryDirect and many brokerage accounts
    Federal taxTreasury bill interest is generally subject to federal income tax
    State & local taxInterest is generally exempt from state and local income taxes
    FDIC insuranceNot FDIC-insured because T-bills are securities rather than bank deposits

    Who Are T-Bills Best For?

    T-bills may fit investors who have a defined short-term goal and can leave the money invested until a chosen maturity date. Examples include cash set aside for a planned purchase, an upcoming expense, or a temporary place to hold funds before making another investment. They can also be used as one part of a short-term Treasury strategy, including a ladder with several maturity dates.

    The tax treatment can make T-bills particularly interesting for investors who live in a state or locality that imposes income tax. Treasury interest is generally subject to federal income tax but exempt from state and local income taxes. The value of that exemption depends on your tax situation and should be considered alongside the yield available when you invest.

    Look beyond the headline rate

    A T-bill quote contains more than one useful number. Pay attention to the investment yield, purchase price, maturity date, tax treatment and what you expect to do with the money afterward. These details become especially useful when comparing T-bills with CDs or money market accounts.

    Complete Beginner Guide: What Are Treasury Bills?

    Treasury billsTreasury bills, commonly called T-bills, are short-term debt securities issued by the U.S. Department of the Treasury. In simple terms, you are lending money to the U.S. government for a defined period. The Treasury issues the bill with a stated face value and pays that face value when the bill matures, subject to the terms of the security.
    What makes T-bills different from many traditional bonds is the way the return is structured. Treasury bills generally do not make periodic coupon payments. Instead, newly issued bills are sold at a discount to their face value, so the amount you pay is generally less than the amount you receive at maturity. That difference is the basic return on the original investment before taxes.

    Think of a T-bill this way

    Buy a newly issued T-bill for less than its face value → hold it until maturity → receive the face value. The difference between those amounts is the basic return before taxes. The actual purchase price depends on the bill’s auction price.

    Treasury Bills Are One Part of the Treasury Family

    Treasury bills are one type of marketable Treasury security. The easiest way for a beginner to distinguish them from Treasury notes and bonds is to look at the maturity and payment structure. Bills are short-term securities with maturities of one year or less. Treasury notes generally have intermediate maturities and pay interest every six months. Treasury bonds are longer-term securities and also generally pay interest every six months.

    SecurityMaturityBasic Payment Structure
    Treasury billsOne year or lessGenerally issued below face value and paid at face value at maturity
    Treasury notesMore than one year to 10 yearsGenerally pays interest every six months
    Treasury bondsMore than 10 yearsGenerally pays interest every six months

    What Does a T-Bill Maturity Mean?

    The maturity date is the date on which the Treasury bill reaches the end of its stated term. Common Treasury bill terms include short periods such as 4, 8 and 13 weeks, along with longer bill terms such as 17, 26 and 52 weeks. The exact maturities available can vary with Treasury issuance schedules, so investors should check the current offering before placing an order.

    Maturity is more than a number on an investment screen. It tells you when the bill is scheduled to reach its end date and helps you decide whether the timing fits your cash needs. A shorter bill may suit money you expect to use relatively soon, while a longer bill may make sense when you can leave the funds invested for a longer period.  4-Week Treasury Bills Explained

    How Much Can You Invest?

    Treasury bills are generally issued in $100 and additional $100 multiples of face value. Your actual purchase amount for a newly issued bill can be lower than its face value because the bill is sold at a discount. The price you pay depends on the terms and pricing of the specific Treasury bill you purchase.

    A simple illustration

    Imagine a newly issued Treasury bill with a $1,000 face value and an illustrative purchase price of $980. If you hold that bill until maturity and receive $1,000, the $20 difference represents the basic return before taxes. This is only an example—the actual price and return depend on the specific Treasury bill and its market conditions.

    What Treasury Bills Are Not

    • Not a savings account: A T-bill is a marketable government security, not a bank deposit.
    • Not FDIC-insured: FDIC deposit insurance applies to eligible deposits at FDIC-insured banks, not Treasury securities.
    • Not a traditional coupon bond: T-bills generally do not send periodic interest payments during their term.
    • Not automatically the right choice for every cash goal: The maturity, access requirements, taxes and available yield all matter when deciding where short-term money belongs.

    The beginner takeaway: A Treasury bill is a short-term U.S. government security with a defined maturity. For a newly issued bill, you generally pay less than its face value and receive the face value when it matures. The next step is learning how the auction, purchase price, discount rate and investment yield fit together.

    How Treasury Bills Work: Purchase, Discount, Yield & Maturity

    The easiest way to understand a newly issued Treasury bill is to follow it from the auction to maturity. You select a bill with a particular term, place an order, and the auction determines the price and yield for the securities sold. Because T-bills generally do not make periodic coupon payments, the return is built into the difference between the price paid and the face value received at maturity.  What Are Treasury Bills? Complete Beginner Guide

    Step 1
    Choose a bill
    Select a maturity that matches the period you expect to leave the money invested.
    Step 2
    Place your order
    Use TreasuryDirect or a brokerage account to submit your purchase.
    Step 3
    Auction sets the price
    For a new issue, the auction establishes the applicable price and yield.
    Step 4
    Hold or sell
    Hold to maturity for the face value or sell earlier through the secondary market.

    1. Start With the Treasury Auction

    Newly issued Treasury bills are sold through auctions. An individual investor can generally place a noncompetitive bid, which means the investor agrees to accept the yield determined at the auction. You specify the amount of securities you want to buy rather than naming the yield you require. TreasuryDirect vs Brokerage: Which Is Better for T-Bills?

    A competitive bid works differently because the bidder specifies the discount rate they are willing to accept. The Treasury accepts bids according to the auction rules until the amount offered for sale is allocated. For a beginner using a noncompetitive order, the important point is simple: you are not trying to guess the winning auction yield yourself. How Do Treasury Bills Work?

    T-bill yield vs. interest rate

    2. Your T-Bill Is Priced Below Face Value

    Newly issued Treasury bills are generally sold at a discount to face value. Suppose, purely as an illustration, that you purchase a bill with a $10,000 face value for $9,800. If you hold that bill until maturity and receive $10,000, the $200 difference is the basic return before taxes. Treasury Bill Discount Rate Explained

    Why you should not call that simply “2% interest”

    The $200 difference is 2% of the $10,000 face value, but it is not automatically a 2% annual yield. The annualized investment yield depends on the purchase price and the length of time until maturity. This is why two T-bills with different maturities cannot be compared by looking only at the dollar discount.

    3. Discount Rate, Price and Investment Yield Tell Different Stories

    Treasury auction results can show a discount rate, a price and an investment rate. The discount rate measures the bill’s discount from face value using a 360-day basis. The investment rate, commonly described as the bond-equivalent yield, annualizes the return using a different convention. As a result, the discount rate and investment rate are related but are not interchangeable. Treasury Bills vs Treasury Bonds: What’s the Difference?

    The four numbers worth watching


    Face value


    The amount paid when the bill reaches maturity.

    Purchase price


    The amount paid for the newly issued bill.  How to Buy Treasury Bills Through a Brokerage

    Discount rate


    A Treasury auction measure based on the bill’s discount.

    Investment rate


    An annualized return measure useful for comparing investments.

    4. What Happens When the T-Bill Matures?

    If you hold a Treasury bill until maturity, the Treasury pays its face value. At that point, you can use the proceeds for the purpose you originally had in mind, move the money to another account or investment, or reinvest in another Treasury bill if an eligible reinvestment option is available.How Do Treasury Bills Make Money?

    Selling before maturity is different. T-bills can be traded in the secondary market, generally through a brokerage. Their market prices can move as interest rates, demand and other market conditions change. As a result, an early sale may produce more or less than your original purchase price, and you should not assume that you will receive the bill’s full face value before its maturity date. What Happens If You Hold a Treasury Bill Until Maturity?

    The practical rule: For a newly issued T-bill, look at the purchase price, face value, investment rate and maturity date. If there is a chance you will need the money early, also consider how the bill could be priced in the secondary market instead of relying on its maturity value.What Happens When a Treasury Bill Matures?

    Benefits & Drawbacks of T-Bills

    Treasury bills are often attractive because they combine a short maturity with the credit backing of the U.S. government. But a strong credit profile does not make every T-bill equally useful for every cash need. Your decision also depends on how long you can leave the money invested, how you plan to access it, what happens when the bill matures and how taxes affect the return. How Treasury Bill Auctions Work. Treasury Bill Auction Dates Explained

    Benefits of Treasury Bills

    • Low credit risk: T-bills are direct obligations of the U.S. government, so credit risk is generally considered very low compared with many other investments.
    • Short, defined maturities: Treasury bills have terms of one year or less, giving investors several ways to match an investment with a known cash timeline.
    • Known maturity value: If you hold a newly issued T-bill until maturity, the Treasury pays its stated face value.
    • State and local tax advantage: Interest from U.S. Treasury securities is generally exempt from state and local income taxes, although federal income tax generally applies.
    • Accessible through common investment platforms: Investors can generally purchase newly issued T-bills through TreasuryDirect or through many brokerage accounts.

    Drawbacks to Consider

    • Not designed for everyday spending: A T-bill is a security rather than a checking or savings account, so it does not provide ordinary deposit-account transaction features.
    • Early selling can change the result: If you sell before maturity, the bill’s market price may be higher or lower than the amount you originally paid.
    • Reinvestment risk: When a T-bill matures, a new bill may carry a different yield. You cannot assume that the rate on your current bill will still be available for the next investment.
    • Inflation can reduce real returns: Earning a positive nominal return does not guarantee that your money will gain purchasing power after inflation.
    • No FDIC deposit insurance: T-bills are Treasury securities, not deposits at an FDIC-insured bank.

    Where the Trade-Offs Matter Most

    The biggest advantage of a T-bill can be its defined timeline. If you know that a portion of your cash can remain invested for several weeks or months, you can choose a maturity that lines up with that goal. That is different from keeping the same money in an account designed for frequent deposits, withdrawals and everyday access.

    The trade-off becomes more noticeable if your plans change. You can potentially sell a T-bill before maturity through the secondary market, but the selling price is determined by market conditions at that time. A short-term security can therefore still have price risk if you need to exit before its maturity date.

    Taxes can also influence the comparison. For an investor who pays state or local income tax, the exemption for Treasury interest can make a T-bill’s after-tax return more attractive than the headline yield of a taxable alternative. The actual advantage varies by tax bracket, location and the competing investment’s yield.

    Bottom line: T-bills are most compelling when short maturity, low credit risk and favorable Treasury tax treatment fit the job your money needs to do. Their limitations become more relevant when you need everyday access, may have to sell early, or want to keep the money invested for a much longer period.

    Treasury Bills Comparison Table: T-Bills vs. Savings, MMAs & CDs

    A Treasury bill may look attractive because of its yield, but the yield is only one part of the decision. Savings accounts, high-yield savings accounts, money market accounts and CDs solve somewhat different problems. The comparison below focuses on the features that can change the real-world outcome: access to your money, term, rate structure, insurance and tax treatment.

    FeatureTreasury BillsHigh-Yield SavingsMoney Market AccountCD
    What it isU.S. government securityBank deposit accountBank deposit accountBank deposit account
    Time structureOne year or lessNo fixed maturityNo fixed maturityFixed term selected at opening
    How return is earnedGenerally bought below face value and paid at face value at maturityInterest credited according to the account termsInterest credited according to the account termsInterest paid or credited according to the CD terms
    Rate structureDetermined by auction for new issues; market pricing applies to secondary-market tradesUsually variableUsually variableGenerally fixed for the selected term
    Access to moneyNot designed for everyday spending; early access generally means selling before maturityGenerally accessible, subject to account termsAccess features vary by institutionGenerally limited before maturity; early-withdrawal rules may apply
    FDIC insuranceNoGenerally yes, at an FDIC-insured bank within applicable limitsGenerally yes, at an FDIC-insured bank within applicable limitsGenerally yes, at an FDIC-insured bank within applicable limits
    State & local income taxGenerally exemptGenerally subject to applicable state and local income taxesGenerally subject to applicable state and local income taxesGenerally subject to applicable state and local income taxes
    Often fitsDefined short-term goalsAccessible cash that can earn interestCash with certain deposit-account featuresMoney that can remain invested for a set term

    T-Bills vs. High-Yield Savings Accounts

    A high-yield savings account is built around access. You can generally keep adding money, withdraw funds according to the account terms and earn a variable interest rate. A T-bill works differently because it has a defined maturity and is a security rather than a deposit account. If the money may be needed unexpectedly, the flexibility of a savings account can be more valuable than a modest difference in yield.

    Treasury Bills vs High-Yield Savings Accounts

    T-Bills vs. Money Market Accounts

    A money market account is a bank deposit account, while a Treasury bill is a government security. An MMA may offer features such as checks or a debit card, but those features vary by institution and account. T-bills are not designed for everyday transactions. If your priority is keeping cash available while earning interest, an MMA may be more convenient; if you have a defined investment period, a T-bill may be worth comparing.Treasury Bills vs Money Market Accounts

    For a deeper look at this specific choice, see our .Treasury Bills vs Money Market Accounts: Which Is Safer?

    T-Bills vs. CDs

    CDs and T-bills can both work for money that does not need to remain fully accessible. A CD is a bank deposit with a fixed term and institution-specific early-withdrawal rules. A newly issued T-bill is priced at auction and generally pays its face value at maturity. T-bills and CDs also have different insurance and tax structures, so comparing their advertised yields without considering those differences can give you an incomplete picture.Treasury Bills vs CDs: Which Is Better in 2026?

    If a CD is your main alternative, our Treasury Bills vs CDs: Tax Differences provides a more focused comparison.

    How to compare them: Start with more than the advertised yield. Look at the after-tax return, access to your money, time commitment, insurance coverage and what happens if your plans change. A slightly lower yield can be worthwhile if it gives you the flexibility or protection your situation requires.

    Treasury Bills: Costs, Taxes, Risks & Expert Tips

    Treasury bills have a straightforward structure, but there are still a few details worth checking before you buy. The purchase method, federal tax treatment, state-tax advantage, maturity date and what happens if you need the money early can all affect your actual result. Looking at the yield alone can leave out some of the most useful information.

    What Does It Cost to Buy Treasury Bills?

    TreasuryDirect says it does not charge a purchase fee or commission when you buy Treasury securities directly through the platform. You still pay the purchase price of the security. If you use a brokerage instead, review that firm’s pricing and account terms because the overall cost structure can differ by provider.Who Should Buy Treasury Bills?

    Cost tip: With a newly issued T-bill held to maturity, the important comparison is not just whether there is a transaction fee. Think about the amount of cash committed, the maturity date and the return you could have earned elsewhere during the same period.

    How Are Treasury Bills Taxed?

    Interest income from Treasury bills is subject to federal income tax but is exempt from state and local income taxes. For Treasury bills issued at a discount, the difference between the discounted purchase price and the face value received at maturity is generally treated as interest income. The IRS says this income is generally reported when the bill is paid at maturity.

    Treasury interest is generally reported on Form 1099-INT, with U.S. Treasury obligations reported in Box 3. Keep your purchase and maturity records with your tax documents so you can reconcile the information reported to you.Are Treasury Bills Exempt From State Taxes?

    Illustrative tax example

    Suppose an illustrative T-bill has a $10,000 face value and you pay $9,800 for it. If you hold it until maturity and receive $10,000, the $200 difference represents the bill’s return before federal taxes. The Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.

    Four Risks to Keep in Mind

    1. Early-sale risk

    If you sell before maturity, the market price may be different from the price you originally paid. Your realized return can therefore be higher or lower than the result you expected from holding the bill to maturity.sell a T-bill before maturity

    2. Reinvestment risk

    When a T-bill matures, the yield available on a new bill may be higher or lower than the yield on your previous investment.

    3. Inflation risk

    A T-bill can produce a positive nominal return while your purchasing power grows more slowly after accounting for inflation.

    4. Timing risk

    Choosing a maturity that does not line up with your cash need can force you to reconsider your plans or potentially sell before maturity.

    Expert Tips for Buying T-Bills

    • Match the maturity to the goal.
      If you expect to need the money on a particular date, choose a maturity that fits that timeline instead of focusing only on the highest available yield.
    • Compare the right rate measure.
      Treasury auctions can quote discount rates and investment rates using different conventions. Do not assume two differently labeled percentages are directly interchangeable.
    • Account for taxes.
      Federal income tax still applies, but the exemption from state and local income taxes can make Treasury bills particularly interesting for investors who live in jurisdictions with income taxes.
    • Keep emergency cash separate.
      A T-bill can work well for a planned short-term goal, but money reserved for an unexpected expense may be better kept in an account designed for easier access.
    • Have a maturity plan.
      Decide in advance whether the proceeds will be spent, moved to another account or reinvested. This makes the maturity date part of the plan rather than an afterthought.

    Bottom line:
    Treasury bills are easy to understand once you separate the purchase price, maturity value, tax treatment and market risk. The strongest choice is not automatically the bill with the highest headline yield. Look at your timeline, after-tax return, access needs and reinvestment plan before committing the money.

    Common Treasury Bill Mistakes + an Illustrative Real-Life Example

    Treasury bills are easier to use when the investment is planned around the money’s purpose. Many mistakes happen because an investor sees an attractive yield, chooses a bill without checking the timeline, or forgets what happens after the bill matures. Here are the mistakes worth avoiding.

    6 Common T-Bill Mistakes to Avoid

    1. Confusing the discount with the yield

    A T-bill’s discount from face value is not automatically its annualized investment return. Discount rates and investment yields use different calculation methods.

    2. Chasing the highest headline rate

    A slightly higher yield may not be useful if the maturity does not match your cash needs. The best-looking rate on the screen is not automatically the best fit.

    3. Putting emergency cash into T-bills

    T-bills can be sold before maturity through the secondary market, but they are not everyday spending accounts. Keep money needed for immediate emergencies in a place designed for quick access.

    4. Forgetting the tax advantage

    Comparing a T-bill with a taxable cash investment using headline yields alone can miss the effect of state and local income taxes.

    5. Ignoring the maturity date

    The maturity date determines when the planned proceeds become available. A bill that ends at the wrong time can leave you needing to rearrange your cash plan.

    6. Having no plan for the proceeds

    A T-bill eventually matures. Decide ahead of time whether the money will be spent, moved to an account or reinvested rather than making that decision at the last minute.

    Illustrative Example: A $25,000 Short-Term Investment

    Imagine an investor has $25,000 that is not needed immediately but is earmarked for a known short-term goal. The investor considers a newly issued T-bill with a face value of $25,000. For illustration only, assume the purchase price is $24,600.

    The basic money flow

    Purchase

    $24,600

    Face Value

    $25,000

    Difference

    $400

    If the investor holds the bill until maturity and the terms in this illustration apply, the Treasury would pay the $25,000 face value. The $400 difference between the purchase price and face value represents the return before taxes in this simplified example.

    Important: The $400 difference is not the annualized T-bill yield. The actual annualized return depends on the purchase price and the bill’s term, using the applicable Treasury yield calculation.

    Now consider the planning side. If the investor knows the $25,000 will be needed around the bill’s maturity date, the investment has a clear purpose. If the money might be needed much earlier, the investor should consider a more accessible cash option or understand the consequences of selling the T-bill before maturity.

    How Much Can $25,000 Earn in Treasury Bills?

    The practical lesson:
    Start with the purpose and timing of the money, then compare available yields, taxes and access. The purchase price tells you what you pay today; the face value tells you what a newly issued bill pays at maturity. The time between those two points is what makes the return meaningful.

    If you are deciding between Treasury bills and other short-term cash options, compare them with money market accounts or review our CD vs. Treasury bills comparison.

    Who Should Choose Treasury Bills?

    Treasury bills can be a useful fit when money has a defined short-term purpose and you know roughly when you may need it. They are less about choosing an investment because of your age or account balance and more about matching a Treasury maturity with a specific cash need. Treasury Bills for Emergency Funds

    T-Bills May Fit You If…

    You have a defined short-term goal

    If you expect to use the money around a known date, a T-bill’s defined maturity can make the cash easier to plan around.

    You want short-term U.S. government securities

    T-bills are direct obligations of the U.S. government, which may appeal to investors who want short-term government securities rather than bank deposits.

    State or local taxes matter to you

    Treasury interest is generally subject to federal income tax but exempt from state and local income taxes. That treatment can matter when comparing after-tax returns with taxable alternatives.

    You want to spread out maturity dates

    Instead of putting all short-term money into one maturity, an investor can use different T-bill maturity dates to create a more staggered cash-flow plan. What Is a Treasury Bill Ladder?

    What About Retirees and Conservative Investors?

    Retirees and conservative investors may use T-bills for money earmarked for near-term expenses. A defined maturity can help with planning for a known cash need, while the credit quality of the U.S. government may appeal to investors who place a high priority on limiting credit risk.

    That does not mean T-bills need to replace every other part of a financial plan. A retiree might keep some money readily accessible for immediate expenses while using T-bills for a later spending need. A conservative investor might also combine different maturities rather than committing all short-term cash at once.

    T-Bills May Not Be the Best Fit If…

    • You need the money for everyday spending.
      A T-bill is a security, not a checking or savings account, so it is not designed for routine transactions.
    • Your timeline is highly uncertain.
      If you may need the money unexpectedly, an accessible deposit account may be easier to manage.
    • You are investing for long-term growth.
      T-bills have short maturities, so they may not by themselves address the growth needs of a long-term investment plan.who should buy Treasury bills

    A useful rule:
    Treasury bills often make the most sense when the money has a clear short-term job and a reasonably clear timeline. If you need day-to-day access or are focused mainly on long-term growth, another account or investment may serve that purpose better.

    Treasury Bills FAQ: 8 Common Questions Beginners Ask

    Once you understand the purchase price, face value, maturity and yield, Treasury bills are fairly straightforward. These eight questions cover the practical details investors commonly want to know before adding T-bills to a short-term savings or investment plan.

    1. What are Treasury bills?

    Treasury bills, commonly called T-bills, are short-term U.S. government securities with maturities of one year or less. Newly issued bills are generally sold for less than their face value. Unlike Treasury notes and bonds, T-bills generally do not make periodic coupon payments. Instead, an investor generally receives the bill’s face value at maturity. The difference between the purchase price and the amount received at maturity represents the return before taxes.

    2. How do Treasury bills make money?

    A newly issued T-bill generally generates its return through the difference between its purchase price and face value. For example, an illustrative $10,000 face-value bill might cost less than $10,000. If it is held until maturity, the investor receives the $10,000 face value, with the difference representing the return before taxes. The annualized yield depends on the purchase price and the bill’s term, so the dollar discount should not be mistaken for the annualized investment yield.

    3. Are Treasury bills safe?

    T-bills are generally considered to have very low credit risk because they are direct obligations of the U.S. government. They are not FDIC-insured bank deposits. If a newly issued T-bill is held until maturity, the investor’s expected payment is based on the Treasury’s obligation to pay the bill’s face value. Selling before maturity introduces market-price risk because the security’s value can change before the maturity date.Are Treasury Bills Safe? Risks, Safety & 2026 Guide

    4. How are Treasury bills taxed?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. For a bill issued at a discount, the difference between the purchase price and the amount received at maturity is generally treated as interest income. Treasury interest is generally reported on Form 1099-INT in Box 3. Tax treatment can be more involved when securities are sold before maturity or when other transactions are involved, so unusual situations may require guidance from a qualified tax professional.

    5. Where can I buy Treasury bills?

    Individuals can buy Treasury bills directly through TreasuryDirect or through many brokerage accounts. TreasuryDirect provides access to Treasury auctions. A brokerage may also provide access to new Treasury issues and, depending on the firm, the secondary market. Account requirements, available features and pricing policies can differ, so check the terms of the platform you plan to use.

    6. Can I sell a Treasury bill before it matures?

    Yes. Treasury bills can be sold before maturity in the secondary market through a brokerage that supports Treasury trading. The price you receive can be different from the price you originally paid because market conditions change over time. As a result, selling early can produce a different gain or loss than holding the bill until maturity.

    7. Are Treasury bills better than CDs or savings accounts?

    Not necessarily. Treasury bills may appeal to investors who want short-term U.S. government securities, defined maturities and the state and local tax exemption available for Treasury interest. Savings accounts and money market accounts generally provide easier access to cash, while CDs can offer a fixed rate for a selected term. Eligible deposits at FDIC-insured banks are covered within applicable insurance limits. The better option depends on the purpose of the money, access requirements, tax situation and available return.

    For a focused comparison, see our CD vs. Treasury bills guide.

    8. What happens when a Treasury bill matures?

    At maturity, a newly issued T-bill reaches its scheduled payment date and the investor receives the bill’s face value according to the applicable Treasury payment terms. The proceeds can then be used for the original financial goal or directed toward another investment. If you continue buying T-bills, each new purchase has its own maturity date, purchase price and yield. Using different maturities can also help create a staggered schedule for future cash needs.

    Quick takeaway:
    Treasury bills are short-term U.S. government securities with a discount-based return. Before buying, pay attention to the maturity date, the applicable yield measure, taxes, access to your money and your plan for the proceeds.


    Treasury Bills Final Verdict: Are T-Bills Worth Considering?

    Treasury bills can be a useful part of a short-term money strategy when the investment has a clear purpose and a defined time frame. A newly issued T-bill is generally purchased for less than its face value and, when held to maturity, pays its face value. That simple structure can make T-bills easier to plan around than investments whose value or maturity is less predictable.

    Their appeal goes beyond the purchase-price discount. T-bills are direct obligations of the U.S. government, can be purchased through TreasuryDirect and many brokerages, and receive favorable state and local tax treatment. Treasury interest is generally subject to federal income tax but exempt from state and local income taxes.

    Treasury bills may make sense when you:

    • Have money earmarked for a short-term goal
    • Know approximately when you will need the money
    • Prefer short-term U.S. government securities
    • Want to consider the state and local tax treatment of Treasury interest

    When T-Bills May Not Be the Right Tool

    A T-bill is not a substitute for every type of cash or investment account. Money needed for everyday purchases or unexpected expenses may be better kept in an accessible deposit account. A CD may be worth comparing when a bank deposit with a fixed term is the priority. For long-term goals, investors may need a broader strategy rather than relying primarily on short-term Treasury securities.

    There is also a practical consideration if your plans change. Holding a newly issued T-bill until maturity follows the original maturity schedule, while selling before maturity exposes you to the market price at the time of sale. That difference matters if the money could be needed sooner than expected.

    A simple way to make the decision

    1. Decide what the money is for.
    2. Identify when you expect to need it.
    3. Compare the relevant T-bill yield with suitable alternatives.
    4. Consider the effect of federal and state/local taxes.
    5. Decide what you will do when the T-bill matures.

    Final Takeaway

    Treasury bills are worth considering when they match the job your money needs to do. They can be a strong short-term option for planned cash, but the best decision comes from looking at the whole picture—not just the advertised yield. Match the maturity to your timeline, understand the tax treatment and keep enough accessible cash outside the T-bill for needs that cannot wait.

    Treasury Bills Resources: Related Guides & Official Sources

    This guide covers the main T-bill questions, but you may want to explore a specific part of the decision before investing. The resources below are grouped by purpose so you can quickly move from the basics to comparisons, cash planning, buying information and official government guidance.

    Related FinanceInvestment Guides

    Official Sources for T-Bill Information

    For information that can affect an actual purchase or tax return, use primary sources rather than relying only on secondary articles. TreasuryDirect is the official Treasury platform for Treasury securities and auction information. The IRS provides the applicable federal tax guidance. Investor.gov, the SEC’s investor-education website, provides a separate overview of Treasury securities and their characteristics.

    1. TreasuryDirect — Official Treasury Information

    Use TreasuryDirect to review Treasury securities, auction information, purchase procedures and current Treasury offerings. TreasuryDirect’s official materials explain that T-bills are issued at a discount and redeemed at face value at maturity.


    Visit TreasuryDirect.gov

    2. IRS Publication 550 — Treasury Tax Rules

    IRS Publication 550 explains the federal tax treatment of Treasury bills, notes and bonds. It also explains that Treasury interest is exempt from state and local income taxes and discusses the reporting of Treasury interest.


    Read IRS Publication 550

    3. Investor.gov — Treasury Securities Overview

    Investor.gov provides investor-education information about Treasury bills, notes and bonds, including their status as U.S. government debt securities and the general characteristics of Treasury investments.


    Explore Treasury Securities on Investor.gov

    Before You Invest

    Use FinanceInvestment’s related guides for comparisons and planning ideas, then verify time-sensitive purchase, auction and tax details with the official sources above. Treasury offerings, auction schedules and market yields can change, so check current information before placing an order.

    Your Next Step

    Ready to Decide If Treasury Bills Fit Your Plan?

    A good T-bill decision starts with your timeline, not simply the highest rate you see. Think about when you will need the money, how much access you want, and how the after-tax return compares with other short-term choices.

    If you are still comparing options, our

    CD vs. Treasury Bills guide

    and

    Money Market Account vs. Treasury Bills comparison

    can help you look at the differences side by side.

    Have a Treasury Bill Question?

    Have a question, correction or suggestion about this guide? You can contact FinanceInvestment directly by email.


    ✉ Email FinanceInvestment

    Quick reminder:
    Treasury rates, auction details and tax rules can change. Verify current information with official sources before making an investment decision.

  • Best Health Insurance for Young Adults (2026): Complete Guide to Affordable Coverage

    Best Health Insurance for Young Adults (2026): Complete Guide to Affordable Coverage


    Best Health Insurance for Young Adults (2026): Complete Guide to Affordable Coverage

    Published: July 3, 2026

    Author: Subhash Rukade

    best health insurance for young adultsBest Health Insurance for Young Adults (2026): Compare Affordable Health Plans and Choose the Right Coverage.

    Best health insurance for young adults is one of the most important financial decisions Americans can make in 2026. Whether you’re graduating from college, starting your first full-time job, working as a freelancer, or launching a business, having the right health insurance protects both your health and your finances. One unexpected medical emergency without insurance can easily cost thousands of dollars, making quality coverage a smart investment rather than an unnecessary expense.

    Today’s young adults have more health insurance options than ever before. You may qualify for employer-sponsored coverage, Affordable Care Act (ACA) Marketplace plans, Medicaid, or even remain on your parents’ health insurance policy until age 26. Understanding how each option works allows you to select a plan that matches your healthcare needs while staying within your monthly budget.

    If you’re completely new to health insurance, begin with our comprehensive

    Insurance for Beginners USA 2026: Complete Guide to Choosing the Right Coverage
    .
    It explains premiums, deductibles, copays, provider networks, and other essential insurance terms before you compare individual plans.

    Throughout this guide, you’ll learn how to compare health insurance plans, estimate your total healthcare costs, understand deductibles and out-of-pocket limits, avoid common buying mistakes, and discover practical strategies that help young adults save money without sacrificing quality medical coverage.

    We’ll also compare different plan types, review real-world examples, answer frequently asked questions, and highlight trusted government resources so you can confidently choose the best health insurance for young adults in 2026.

    Health Insurance Options Available for Young Adults in 2026

    Finding the best health insurance for young adults starts with understanding the different types of coverage available. Every young adult has unique healthcare needs, career goals, and financial responsibilities, so the right insurance plan depends on your situation. Fortunately, Americans have several reliable options that provide affordable coverage and financial protection.

    1. Employer-Sponsored Health Insurance

    If you work full-time, your employer may offer health insurance benefits. Employer-sponsored plans are often the most affordable because companies usually pay part of the monthly premium. These plans typically include preventive care, specialist visits, prescription drug coverage, and access to a broad provider network.

    Before enrolling, compare your employer’s deductible, copayments, coinsurance, and annual out-of-pocket maximum to ensure the plan fits your healthcare needs.

    2. ACA Marketplace Health Insurance

    The Affordable Care Act (ACA) Marketplace allows individuals to compare health insurance plans based on coverage, monthly premiums, deductibles, and provider networks. Many young adults qualify for premium tax credits that significantly reduce monthly insurance costs depending on household income.

    Marketplace plans are divided into Bronze, Silver, Gold, and Platinum levels, allowing you to balance monthly premiums with expected healthcare expenses.

    3. Staying on a Parent’s Health Insurance Plan

    One of the biggest advantages for young Americans is the ability to remain on a parent’s health insurance plan until age 26. This option often provides comprehensive coverage while helping recent graduates save money during the early stages of their careers.

    4. Medicaid

    Young adults with lower incomes may qualify for Medicaid, depending on their state’s eligibility rules. Medicaid generally offers comprehensive healthcare benefits with little or no monthly premium, making it an excellent option for eligible individuals.

    5. Individual Health Insurance Plans

    Self-employed professionals, freelancers, entrepreneurs, and gig workers often purchase individual health insurance policies directly through the Marketplace or licensed insurance providers. Comparing several plans helps you find the best health insurance for young adults while keeping long-term healthcare costs under control.

    As you begin building financial independence, healthcare should be only one part of your overall financial strategy. Our

    Retirement Planning Guide

    explains how starting early can help build long-term wealth, while our

    AI Investing Guide 2026

    shows how technology is helping Americans make smarter financial decisions.

    For official information about Marketplace enrollment and financial assistance, visit

    Healthcare.gov
    .
    You can also review federal consumer resources from the

    Centers for Medicare & Medicaid Services (CMS)
    .

    Understanding these coverage options is the first step toward selecting the best health insurance for young adults. In the next section, we’ll compare premiums, deductibles, provider networks, and other important factors that should influence your final decision.

    How to Compare Health Insurance Plans Before You Enroll

    Choosing the best health insurance for young adults isn’t simply about finding the lowest monthly premium. A smart comparison considers your expected healthcare needs, annual medical expenses, provider network, prescription coverage, and long-term financial goals. Spending a little extra time comparing plans today can save hundreds or even thousands of dollars over the next year.

    1. Compare Monthly Premiums

    Your monthly premium is the amount you pay every month to keep your health insurance active. Lower premiums often come with higher deductibles, while higher premiums usually provide lower out-of-pocket costs. If you expect frequent doctor visits or ongoing medical treatment, paying a slightly higher premium may reduce your total healthcare expenses.

    2. Understand Deductibles and Out-of-Pocket Maximums

    Before selecting any plan, compare the deductible, coinsurance, copayments, and annual out-of-pocket maximum. A high-deductible plan may work well for healthy young adults who rarely visit doctors, while lower deductibles are often better for individuals expecting regular healthcare services.

    3. Check the Provider Network

    Always verify that your preferred doctors, urgent care centers, hospitals, specialists, and pharmacies participate in the insurer’s network. Out-of-network treatment can significantly increase your healthcare expenses even if your monthly premium is affordable.

    4. Review Prescription Drug Coverage

    If you regularly take prescription medications, compare each insurance company’s formulary before enrolling. Different insurers classify medications into pricing tiers that directly affect your annual healthcare costs.

    5. Consider Additional Benefits

    • Telehealth services
    • Mental health counseling
    • Preventive care and annual wellness visits
    • Vision and dental coverage
    • Fitness and wellness rewards
    • Virtual primary care options

    Many insurers now include digital healthcare services that make routine medical care faster and more convenient for busy young professionals and students.

    Building strong financial habits early is just as important as choosing quality health insurance. Learn how consistent investing creates long-term wealth in our

    SIP Investing Guide 2026
    .
    You can also explore passive income opportunities with our

    Top Dividend Stocks USA 2026
    .

    For official plan comparison tools and Marketplace enrollment information, visit

    Healthcare.gov
    .
    Additional consumer guidance is available from the

    National Association of Insurance Commissioners (NAIC)
    .

    Taking the time to compare these important features helps you confidently choose the best health insurance for young adults based on your medical needs, budget, and future financial goals. In the next section, we’ll compare plan types using a simple table, calculate healthcare costs, and review a real-life case study.

    Compare Health Insurance Plans, Estimate Costs, and Learn from a Real-Life Example

    Selecting the best health insurance for young adults becomes much easier when you compare plans side by side instead of focusing only on monthly premiums. A plan with a slightly higher premium may actually save you money if it offers lower deductibles, better prescription coverage, and a lower annual out-of-pocket maximum.

    Health Insurance Plan Comparison

    FeatureBronzeSilverGold
    Monthly PremiumLowMediumHigh
    DeductibleHighModerateLow
    Out-of-Pocket CostsHigherModerateLower
    Best ForHealthy Young AdultsAverage Healthcare NeedsFrequent Medical Care

    Healthcare Cost Calculator

    Estimated Annual Healthcare Cost

    (Monthly Premium × 12)
    + Expected Deductible
    + Copays
    + Coinsurance

    Example

    Monthly Premium = $285

    Annual Premium = $3,420

    Deductible = $1,800

    Estimated Copays & Coinsurance = $950

    Total Estimated Annual Cost = $6,170

    Real-Life Case Study

    Emily, a 24-year-old software engineer from Texas, recently started her first full-time job. Initially, she selected the cheapest health insurance plan because it had the lowest monthly premium. After reviewing her expected doctor visits, allergy medications, and annual wellness care, she realized the Bronze plan would cost more throughout the year due to its high deductible.

    After comparing several Marketplace and employer-sponsored plans, Emily selected a Silver plan with a slightly higher premium but significantly lower deductible and better prescription drug coverage. By calculating her total healthcare costs instead of focusing only on monthly premiums, she saved approximately $1,900 during the year while receiving better healthcare benefits.

    If you’re still learning the basics of health insurance, continue with our complete

    Insurance for Beginners USA 2026 Guide
    .
    It explains premiums, deductibles, provider networks, and insurance terminology before you compare health plans.

    For official Marketplace plan comparisons and financial assistance information, visit

    Healthcare.gov
    .
    Consumer education and insurance guidance are also available from the

    Centers for Medicare & Medicaid Services (CMS)

    and the

    National Association of Insurance Commissioners (NAIC)
    .

    This comparison demonstrates why choosing the best health insurance for young adults requires evaluating total healthcare expenses—not just monthly premiums. A well-researched decision today can protect your health, reduce unexpected medical bills, and support your long-term financial goals throughout 2026.

    Best Health Insurance Plans for Different Types of Young Adults

    The best health insurance for young adults depends on your lifestyle, income, healthcare needs, and career stage. A recent college graduate has different insurance requirements than a freelancer, entrepreneur, or young family. Choosing a plan that fits your situation helps you avoid unnecessary healthcare expenses while maintaining quality medical coverage.

    College Students and Recent Graduates

    Students and recent graduates often have limited income, making affordability a top priority. Many can remain on a parent’s health insurance plan until age 26. Others may qualify for Affordable Care Act (ACA) Marketplace subsidies or Medicaid, depending on income and state eligibility rules.

    Young Professionals

    If your employer offers health insurance benefits, compare those plans before purchasing private insurance. Employer-sponsored plans usually provide lower premiums, larger provider networks, preventive care benefits, and employer contributions that reduce your monthly healthcare costs.

    Freelancers and Self-Employed Workers

    Freelancers, consultants, content creators, and gig workers should compare Marketplace plans carefully. A High-Deductible Health Plan (HDHP) paired with a Health Savings Account (HSA) can reduce monthly premiums while providing valuable tax advantages for future medical expenses.

    Young Families

    Young couples planning children or raising small families should prioritize comprehensive coverage, maternity care, pediatric services, prescription drug coverage, and lower annual out-of-pocket maximums. Although premiums may be slightly higher, these benefits often result in lower total healthcare expenses throughout the year.

    Financial Planning Beyond Health Insurance

    Health insurance protects your physical well-being, but building long-term wealth requires additional financial planning. Regular investing, retirement savings, and emergency funds help protect your finances from unexpected medical expenses while supporting future financial independence.

    Start investing consistently with our

    SIP Investing Guide 2026
    .
    If you’re preparing for retirement early, our

    Retirement Planning Guide

    explains how small investments today can grow into substantial long-term wealth.

    Recommended Financial Resources

    • Healthcare.gov Marketplace Plan Finder — Compare ACA Marketplace health insurance plans and estimate premium tax credits.
    • Fidelity Health Savings Account (HSA) — A tax-advantaged account for eligible individuals enrolled in qualified HDHPs.
    • The Bogleheads’ Guide to Investing — A highly recommended personal finance book covering investing, budgeting, and long-term wealth building.

    For official health insurance information and Marketplace enrollment, visit

    Healthcare.gov
    .
    Consumer protection and insurance education resources are also available through the

    National Association of Insurance Commissioners (NAIC)
    .

    Selecting the best health insurance for young adults isn’t simply about finding the lowest premium. Matching your health insurance plan to your career, healthcare needs, and long-term financial goals provides better protection and greater financial confidence throughout 2026.

    Young Professionals

    Common Health Insurance Mistakes, Money-Saving Tips, and Future Trends

    Even after researching the best health insurance for young adults, many people still make costly mistakes when enrolling in a health insurance plan. Choosing the wrong policy can lead to higher medical bills, limited access to healthcare providers, and unnecessary financial stress. Understanding these mistakes will help you make a smarter decision in 2026.

    Common Mistakes to Avoid

    • Choosing the cheapest premium without comparing total yearly costs.
    • Ignoring deductibles and annual out-of-pocket maximums.
    • Not checking if your doctors and hospitals are in-network.
    • Overlooking prescription drug coverage.
    • Skipping preventive care benefits that are included at no extra cost.
    • Automatically renewing last year’s policy without comparing new plans.

    Money-Saving Tips for Young Adults

    • Compare at least three health insurance plans before enrolling.
    • Use preventive care services such as annual wellness exams and vaccinations.
    • If eligible, contribute to a Health Savings Account (HSA) for tax advantages.
    • Stay within your insurance provider’s network whenever possible.
    • Review your health insurance during every Open Enrollment period.
    • Estimate your total healthcare costs instead of focusing only on monthly premiums.

    Future Trends in Health Insurance

    Health insurance is rapidly evolving. Artificial intelligence now helps insurers process claims faster, detect fraud, and personalize healthcare recommendations. Telehealth appointments, digital insurance cards, wearable health devices, and wellness reward programs are becoming standard features in many insurance plans. These innovations make healthcare more convenient while helping young adults reduce long-term medical expenses.

    Build Long-Term Financial Security

    Good health insurance is only one part of financial success. Emergency savings, retirement investing, and diversified investments help protect your finances against unexpected medical emergencies while building long-term wealth.

    Prepare for uncertain markets with our

    Recession-Proof Investing Guide 2026
    .
    You can also improve your everyday finances with our

    Best Credit Cards 2026
    ,
    which explains cashback, travel rewards, and smart credit management strategies.

    Trusted Government Resources

    For accurate information about Marketplace enrollment, subsidies, and consumer protections, visit

    Healthcare.gov
    ,
    the

    Centers for Medicare & Medicaid Services (CMS)
    ,
    the

    IRS Health Savings Account Guide
    ,
    and the

    National Association of Insurance Commissioners (NAIC)
    .
    These trusted resources provide the latest information on health insurance rules, tax benefits, and consumer rights.

    Recommended Financial Products

    • Fidelity Health Savings Account (HSA) — Tax-efficient healthcare savings for eligible individuals.
    • Blue Cross Blue Shield Individual Health Plans — Nationwide health insurance options for young adults.
    • Kaiser Permanente Health Plans — Comprehensive healthcare coverage with integrated medical services in participating regions.

    By avoiding these common mistakes and following proven money-saving strategies, you’ll be better prepared to choose the best health insurance for young adults that balances affordability, quality healthcare, and long-term financial security throughout 2026.

    Expert Tips, Trusted Resources, and Frequently Asked Questions

    Finding the best health insurance for young adults is much easier when you focus on long-term value instead of simply choosing the lowest monthly premium. The right plan should protect your finances, provide access to quality healthcare providers, and fit comfortably within your monthly budget. Spending time comparing plans today can prevent costly surprises later.

    Expert Tips Before Choosing a Health Insurance Plan

    • Compare at least three health insurance plans before enrolling.
    • Calculate your total annual healthcare costs instead of looking only at monthly premiums.
    • Verify that your preferred doctors, hospitals, and pharmacies are included in the provider network.
    • Review prescription drug coverage if you take regular medications.
    • Compare deductibles, copayments, coinsurance, and annual out-of-pocket maximums.
    • Review your coverage every Open Enrollment because premiums and benefits change each year.

    Trusted Government Resources

    Recommended Financial Resources

    • Healthcare.gov Plan Finder — Compare Marketplace health insurance plans based on your location and income.
    • Fidelity Health Savings Account (HSA) — A tax-advantaged healthcare savings solution for eligible individuals.
    • The Bogleheads’ Guide to Investing — A trusted personal finance book covering long-term investing and wealth building.

    Frequently Asked Questions

    1. What is the best health insurance for young adults?

    The best plan depends on your income, healthcare needs, employer benefits, and budget. Compare Marketplace plans, employer-sponsored insurance, and individual policies before making your decision.

    2. Can I stay on my parents’ health insurance?

    Yes. Under federal law, most young adults can remain on a parent’s health insurance plan until they turn 26 years old.

    3. Should healthy young adults choose high-deductible plans?

    Healthy individuals who rarely visit doctors often benefit from High-Deductible Health Plans (HDHPs), especially when paired with a Health Savings Account (HSA). However, always make sure you can afford the deductible if an unexpected medical emergency occurs.

    4. Is Marketplace health insurance worth it?

    Yes. Many young adults qualify for premium tax credits through the Affordable Care Act Marketplace, making comprehensive health insurance much more affordable.

    5. How often should I review my health insurance?

    Review your health insurance every Open Enrollment period because premiums, provider networks, deductibles, and benefits may change from year to year.

    Choosing the best health insurance for young adults isn’t only about protecting your health today—it’s also about protecting your financial future. In the final section, we’ll summarize the key points, revisit our complete insurance guide, include a professional email subscribe CTA, and finish with a premium colorful author box.

    Conclusion

    Choosing the best health insurance for young adults is one of the smartest investments you can make for your health and financial future. Instead of selecting a plan based only on the lowest monthly premium, compare deductibles, provider networks, prescription drug coverage, annual out-of-pocket costs, and preventive care benefits. The right policy protects you from unexpected medical bills while giving you access to quality healthcare when you need it most.

    If you’re still building your insurance knowledge, continue with our complete

    Insurance for Beginners USA 2026: Complete Guide to Choosing the Right Coverage
    .
    You can also strengthen your financial future with our

    Retirement Planning Guide

    and maximize everyday savings using our

    Best Credit Cards 2026
    .
    Building strong financial habits early will help you achieve greater security throughout every stage of life.

    📩 Stay Ahead with Weekly Money & Insurance Tips

    Join thousands of readers receiving practical health insurance advice, investing strategies, retirement planning guides, and personal finance tips every week.


    Subscribe Free

    ✔ Free Weekly Updates   |   ✔ No Spam   |   ✔ Unsubscribe Anytime

    SR

    Subhash Rukade

    Founder & Finance Content Creator • FinanceInvestment.site

    Subhash Rukade creates research-backed content on health insurance, retirement planning, investing, passive income, and personal finance. His mission is to simplify complex financial topics into practical, easy-to-understand guides that help Americans make confident money decisions.


    Health Insurance


    Retirement Planning


    Investing


    Personal Finance


    USA Finance Guides

  • ETF SIP Strategy for Beginners: Complete 2026 Guide for American Investors

    ETF SIP Strategy for Beginners: Complete 2026 Guide for American Investors

    ETF SIP Strategy for Beginners: Complete 2026 Guide for American Investors

    etf sip strategy for beginners


    By Subhash Rukade | Updated June 7, 2026

    What Is an ETF SIP Strategy and Why Is It So Popular in 2026?

    ETF SIP strategy for beginners has become one of the most searched investing topics among American investors in 2026.

    More people are looking for simple, low-cost, and effective ways to grow their money without spending hours researching individual stocks.

    That is where ETFs and SIP investing work extremely well together.

    An Exchange-Traded Fund (ETF) is an investment fund that holds a collection of assets such as stocks, bonds, or other securities.

    Instead of buying shares of one company, investors can gain exposure to dozens, hundreds, or even thousands of investments through a single ETF.

    This diversification helps reduce risk and makes investing easier for beginners.

    A SIP, or Systematic Investment Plan, involves investing a fixed amount of money at regular intervals.

    Rather than trying to predict the perfect time to invest, SIP investors contribute consistently every month.

    This strategy helps investors stay disciplined and benefit from dollar-cost averaging over time.

    When ETFs and SIP investing are combined, investors gain a simple strategy that can support long-term wealth creation while reducing emotional decision-making.

    Many beginners prefer ETF investing because it removes much of the complexity associated with stock picking.

    Instead of constantly monitoring individual companies, investors can focus on building a diversified portfolio and staying committed to their financial goals.

    If you’re new to monthly investing, start with our complete pillar guide:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    Strong financial habits also support successful investing. Investors should also review:


    Best Credit Cards 2026: Rewards, Cashback & Smart Usage Guide

    In this guide, you’ll learn how ETF SIP investing works, the best ETF categories for beginners, common mistakes to avoid, practical portfolio strategies, and future investing trends that can help American investors build wealth in 2026 and beyond.

    Why ETF SIP Investing Is Growing Rapidly in 2026

    The popularity of the ETF SIP strategy for beginners continues to grow across the United States in 2026.

    More investors are moving away from complicated investing approaches and choosing simple, diversified, and low-cost investment solutions.

    ETFs have become a major part of that trend.

    Combined with a systematic investment plan, ETFs offer a practical way for beginners to start building wealth without needing extensive investing experience.

    Diversification Makes Investing Easier

    One of the biggest reasons investors choose ETFs is diversification.

    Instead of putting all their money into a single stock, investors gain exposure to a large group of companies through one investment.

    For example, a broad-market ETF may hold hundreds of stocks from different industries.

    This helps reduce company-specific risk and creates a more balanced investment portfolio.

    Diversification is one of the strongest advantages of an ETF SIP strategy for beginners because it reduces the impact of any single investment performing poorly.

    Low Costs Help Investors Keep More Money

    Another reason ETFs continue gaining popularity is their low cost.

    Many ETFs have significantly lower fees compared to actively managed investment funds.

    Lower costs mean investors keep more of their returns.

    Over decades, even small fee differences can have a meaningful impact on long-term portfolio growth.

    This is particularly important for investors following a long-term SIP strategy.

    ETFs Simplify the Investing Process

    Many beginners feel overwhelmed by the idea of selecting individual stocks.

    ETFs simplify the process by providing instant diversification through a single investment.

    Instead of researching dozens of companies, investors can focus on selecting ETFs that match their goals and risk tolerance.

    This simplicity makes ETF investing attractive for busy professionals, new investors, and retirement savers.

    ETF Investing vs Individual Stock Investing

    FeatureETF InvestingIndividual Stocks
    DiversificationHighLow to Moderate
    Research RequiredLowerHigher
    Risk LevelGenerally LowerHigher
    Cost EfficiencyOften Low CostDepends on Strategy
    Beginner FriendlyExcellentModerate
    Portfolio ManagementSimplerMore Complex

    Popular ETF Categories in 2026

    Investors have access to a wide variety of ETFs today.

    • Broad Market ETFs
    • S&P 500 ETFs
    • Dividend ETFs
    • Growth ETFs
    • Technology ETFs
    • Bond ETFs
    • International ETFs

    These options allow investors to build diversified portfolios that align with their financial goals and risk preferences.

    The biggest lesson from this section is simple:
    ETF SIP strategy for beginners continues growing because it combines diversification, affordability, simplicity, and long-term investing discipline. These advantages make ETFs one of the most accessible investment tools available to American investors in 2026.

    How ETF SIP Investing Builds Long-Term Wealth

    One of the biggest reasons the ETF SIP strategy for beginners has become so popular is its ability to support long-term wealth creation through consistency and discipline.

    Many new investors believe they must constantly buy and sell investments to generate strong returns.

    However, history shows that investors who stay invested and contribute regularly often achieve better results than those who try to predict short-term market movements.

    This is where ETF SIP investing becomes a powerful strategy.

    Dollar-Cost Averaging Reduces Timing Risk

    Dollar-cost averaging is one of the biggest advantages of an ETF SIP strategy.

    Instead of investing a large amount at one time, investors contribute fixed amounts on a regular schedule.

    When ETF prices are lower, the same investment buys more shares.

    When prices rise, the same contribution buys fewer shares.

    Over time, this process helps smooth market fluctuations and reduces the pressure of finding the perfect entry point.

    For beginners, this approach can make investing less stressful and easier to maintain.

    The Power of Compounding

    Compounding is one of the most important concepts in investing.

    It occurs when investment gains begin generating additional gains.

    Over many years, even small monthly contributions can grow significantly because returns continue building upon previous returns.

    The earlier investors begin, the more time compounding has to work.

    This is why many financial experts encourage consistent investing rather than waiting for the “perfect” market conditions.

    Consistency Often Beats Market Timing

    Many investors attempt to predict market highs and lows.

    Unfortunately, successful market timing is extremely difficult.

    Even professional investors struggle to consistently predict short-term market movements.

    A disciplined ETF SIP strategy helps remove emotional decisions from the investing process.

    Instead of reacting to daily headlines, investors continue contributing according to their plan.

    This consistency often becomes a major advantage over long investment periods.

    Investors interested in creating additional passive income streams should also read:


    How to Build a Dividend Portfolio

    Consistent ETF Investing vs Market Timing

    StrategyMain FocusPotential Outcome
    ETF SIP InvestingConsistencySteady Wealth Building
    Dollar-Cost AveragingRegular ContributionsReduced Timing Risk
    Long-Term HoldingCompounding GrowthHigher Wealth Potential
    Market TimingPredicting Price MovesHigher Mistake Risk
    Emotional InvestingShort-Term ReactionsInconsistent Results

    A Recommended Investing Book

    One of the most respected books for long-term investors is:


    The Psychology of Money by Morgan Housel

    The book explains why patience, consistency, and strong financial habits often have a greater impact on wealth creation than trying to predict short-term market movements.

    The biggest lesson from this section is simple:
    ETF SIP strategy for beginners works because it combines dollar-cost averaging, compounding, diversification, and long-term discipline. Investors who remain consistent through different market cycles often place themselves in a stronger position to build lasting wealth.

    Best ETF Categories for Beginners in 2026

    One of the biggest advantages of an ETF SIP strategy for beginners is the wide range of investment options available.

    ETFs allow investors to build diversified portfolios based on their financial goals, risk tolerance, and investment timeline.

    Rather than selecting individual stocks, investors can choose ETF categories that match their long-term objectives.

    This approach simplifies investing and helps beginners stay focused on wealth creation.

    Broad Market ETFs

    Broad market ETFs are among the most popular choices for beginners.

    These ETFs provide exposure to a large number of companies across multiple industries.

    Because they spread investments across the market, they help reduce company-specific risk while providing long-term growth potential.

    Many investors use broad market ETFs as the foundation of their portfolio.


    etf sip strategy for beginners portfolio

    S&P 500 ETFs

    S&P 500 ETFs track some of the largest companies in the United States.

    These ETFs offer exposure to industry leaders across technology, healthcare, finance, consumer goods, and other sectors.

    Because of their diversification and historical performance, S&P 500 ETFs remain a popular choice among long-term investors.

    Dividend ETFs

    Dividend ETFs focus on companies that regularly distribute dividends to shareholders.

    These ETFs can provide both income and long-term growth potential.

    Investors interested in dividend investing should also review:


    Top Dividend Stocks USA 2026

    Growth ETFs

    Growth ETFs typically invest in companies expected to expand revenues and earnings at faster rates than the broader market.

    These funds often include technology, innovation, and artificial intelligence-related businesses.

    While growth ETFs may experience higher volatility, many investors include them to pursue long-term capital appreciation.

    Bond ETFs

    Bond ETFs invest in government bonds, corporate bonds, or a combination of fixed-income securities.

    These ETFs are commonly used to add stability and diversification to investment portfolios.

    Many retirement-focused investors allocate a portion of their portfolios to bond ETFs as they approach retirement age.

    ETF Categories Compared

    ETF CategoryMain ObjectiveSuitable For
    Broad Market ETFsMarket DiversificationMost Investors
    S&P 500 ETFsLarge-Cap ExposureLong-Term Growth
    Dividend ETFsIncome + GrowthPassive Income Investors
    Growth ETFsHigher Growth PotentialAggressive Investors
    Bond ETFsPortfolio StabilityConservative Investors

    A Recommended Wealth-Building Book

    One of the most respected books for ETF and index fund investors is:


    The Simple Path to Wealth by JL Collins

    The book explains how low-cost investing, diversification, and long-term discipline can help investors achieve financial independence.

    The biggest lesson from this section is simple:
    ETF SIP strategy for beginners becomes more effective when investors choose ETF categories that align with their goals. A diversified mix of broad market, dividend, growth, and bond ETFs can help create a balanced portfolio capable of supporting long-term wealth creation.

    Real Investor Example and Common ETF Investing Mistakes

    Understanding an ETF SIP strategy for beginners is important, but applying that strategy consistently is what creates long-term results.

    Many investors start investing with good intentions.

    However, emotional decisions, unrealistic expectations, and poor habits often prevent them from achieving their financial goals.

    Learning from real-world examples can help investors avoid costly mistakes and stay focused on long-term success.

    A Beginner ETF SIP Example

    Imagine a 30-year-old investor who contributes $500 every month into a diversified ETF portfolio.

    The portfolio includes a broad market ETF, a dividend ETF, and a small allocation to a bond ETF.

    Instead of trying to predict market movements, the investor continues investing every month regardless of market conditions.

    Some years deliver strong returns.

    Other years bring volatility and uncertainty.

    Despite market fluctuations, the investor remains disciplined and continues contributing.

    Over time, dollar-cost averaging and compounding work together to help build wealth.

    This simple approach reflects how many successful long-term investors manage their portfolios.

    Common Mistake #1: Chasing Recent Performance

    One of the most common mistakes investors make is buying investments solely because they recently performed well.

    Markets move in cycles.

    An ETF that performed strongly last year may not necessarily be the best performer next year.

    Successful investors focus on long-term strategy rather than short-term trends.

    Common Mistake #2: Over-Diversification

    Diversification is important, but too much diversification can create unnecessary complexity.

    Some investors own numerous ETFs with overlapping holdings.

    This can make portfolio management more difficult without providing meaningful additional diversification.

    Many beginners achieve excellent diversification with only a few carefully selected ETFs.

    Common Mistake #3: Emotional Investing

    Market declines often create fear.

    Market rallies often create excitement.

    Investors who make decisions based on emotions frequently buy high and sell low.

    A disciplined ETF SIP strategy helps reduce emotional decision-making because investments continue automatically according to a predetermined plan.

    Disciplined Investor vs Emotional Investor

    Investment HabitDisciplined InvestorEmotional Investor
    Monthly InvestingConsistent ContributionsIrregular Investing
    Market VolatilityRemains CalmReactively Changes Strategy
    ETF SelectionLong-Term FocusChases Trends
    Portfolio ManagementSimple and ConsistentFrequently Changes Holdings
    Investment HorizonYears or DecadesShort-Term Focus
    Wealth Building PotentialHigherOften Lower

    Investors preparing for uncertain markets should also review:


    Recession-Proof Investing 2026

    For a complete roadmap to monthly investing and long-term wealth creation, continue with:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    The biggest lesson from this section is simple:
    ETF SIP strategy for beginners works best when investors remain consistent, avoid emotional decisions, and focus on long-term goals. A disciplined investing process often delivers better results than constantly reacting to short-term market movements.

    Practical Tips and Future Trends for ETF SIP Investors in 2026

    Building wealth through an ETF SIP strategy for beginners is not only about choosing the right ETFs. It is also about creating habits and systems that help investors stay consistent for years.

    The investing world continues evolving rapidly. New technology, automation tools, and portfolio management platforms are making investing easier than ever before.

    Investors who combine quality ETFs with smart investing habits often put themselves in a stronger position to achieve long-term financial goals.

    Focus on Diversification

    Diversification remains one of the most effective ways to manage investment risk.

    Even though ETFs are already diversified, investors can improve portfolio balance by combining different ETF categories.

    A diversified ETF portfolio may include:

    • Broad Market ETFs
    • S&P 500 ETFs
    • Dividend ETFs
    • Bond ETFs
    • International ETFs
    • Gold Investments

    This approach can help reduce volatility while maintaining long-term growth potential.

    Investors interested in portfolio diversification should also review:


    Gold Investment Strategies USA

    Automated ETF SIP Investing Is Becoming More Popular

    One major trend in 2026 is the growth of automated investing.

    Many brokerage platforms now allow investors to automatically invest into ETFs on a monthly schedule.

    Automation removes emotional decision-making and helps investors stay consistent regardless of market conditions.

    For beginners, this can be one of the simplest ways to maintain long-term investing discipline.

    Traditional Investing vs Automated ETF SIP Investing

    FeatureTraditional InvestingAutomated ETF SIP
    Investment TimingManual DecisionsAutomatic Contributions
    Emotional ImpactHigherLower
    ConsistencyDepends on InvestorHighly Consistent
    Ease of UseModerateVery Simple
    Long-Term DisciplineVariesStrong Support

    AI-Powered Investing Tools Are Expanding

    Artificial intelligence is playing a growing role in personal finance.

    Many investment platforms now offer:

    • Portfolio analysis tools
    • Retirement planning projections
    • Risk assessment reports
    • Automatic portfolio rebalancing
    • Personalized investing insights

    These technologies help investors make more informed decisions while reducing behavioral mistakes.

    Learn From Trusted Financial Sources

    Investors should always verify information using reputable financial organizations.

    These organizations provide educational resources, investor alerts, and retirement planning guidance that can help investors make better financial decisions.

    A Trusted Resource for ETF Investors

    Many long-term investors use:


    Fidelity Investments

    Fidelity offers investment research, retirement calculators, educational resources, and portfolio planning tools that support long-term investing success.

    The biggest lesson from this section is simple:
    ETF SIP strategy for beginners becomes even more effective when combined with diversification, automation, financial education, and a long-term mindset. These habits can help investors stay focused and continue building wealth regardless of short-term market fluctuations.

    Frequently Asked Questions About ETF SIP Strategy for Beginners

    1. What Is an ETF SIP Strategy?

    An ETF SIP strategy involves investing a fixed amount of money into Exchange-Traded Funds on a regular schedule, usually monthly. This approach helps investors benefit from dollar-cost averaging and long-term market growth.

    2. Are ETFs Good for Beginner Investors?

    Yes. ETFs are often considered one of the best investment options for beginners because they provide diversification, low costs, and easy access to different market sectors through a single investment.

    3. How Much Money Do I Need to Start an ETF SIP?

    Many brokerage platforms allow investors to start with relatively small monthly contributions. The ideal amount depends on individual financial goals, income, and investment horizon.

    4. Can ETF SIP Investing Help With Retirement Planning?

    Many retirement investors use ETFs because they offer long-term market exposure, diversification, and the potential to benefit from compounding over several decades.

    5. Should Beginners Invest Monthly or Wait for Market Corrections?

    Most long-term investors prefer regular monthly investing because it reduces timing risk and helps maintain discipline regardless of market conditions.

    Final Thoughts on ETF SIP Strategy for Beginners

    After exploring diversification, compounding, ETF categories, investor behavior, automation, and long-term wealth-building strategies, one conclusion becomes clear:

    ETF SIP strategy for beginners is one of the simplest and most effective ways to build long-term wealth in 2026.

    Successful investing does not require predicting stock market movements every day.

    It does not require finding the next winning stock.

    Instead, successful investing often comes from following a disciplined plan, investing consistently, and staying focused on long-term goals.

    ETFs make diversification simple.

    SIP investing creates consistency.

    Together, they form a powerful combination that can help investors navigate market volatility while continuing to build wealth over time.

    • Invest consistently every month.
    • Focus on diversification.
    • Keep investment costs low.
    • Avoid emotional investing decisions.
    • Stay committed during market fluctuations.
    • Allow compounding to work over time.

    These principles have helped investors build wealth through bull markets, bear markets, recessions, and economic uncertainty.

    Rather than trying to predict every market move, focus on creating a process you can follow for years.

    For a complete roadmap to monthly investing and long-term wealth creation, continue with:


    SIP Investing Guide 2026: How Monthly Investing Builds Long-Term Wealth

    Whether your goal is retirement planning, financial independence, passive income, or building generational wealth, an ETF SIP strategy can provide a practical foundation for long-term success.

    The greatest advantage of ETF investing is not complexity.

    It is consistency.

    And consistency remains one of the most powerful financial habits any investor can develop.

    📈 Join the Finance Investment Newsletter

    Get ETF investing insights, retirement planning strategies, market updates, wealth-building tips, and personal finance guidance delivered directly to your inbox.

    Join thousands of investors building stronger financial futures through smarter investing decisions.


    Subscribe Free →

    👨‍💼 About the Author

    Subhash Rukade

    Founder of Finance Investment and a dedicated financial educator focused on helping investors build wealth through ETF investing, SIP strategies, retirement planning, dividend investing, and long-term financial independence.

    • 📈 ETF & Index Fund Investing
    • 💰 Long-Term Wealth Building
    • 🏦 Retirement Planning
    • 📊 SIP Investing Strategies
    • 🪙 Portfolio Diversification
    • 📚 Personal Finance Education
    “Consistent Investing Beats Occasional Perfection.”

    Through Finance Investment, Subhash helps readers understand investing concepts, avoid common financial mistakes, and build practical strategies designed for long-term success.

    ✅ Beginner-Friendly Investing Guides
    ✅ USA-Focused Financial Content
    ✅ ETF & SIP Strategies
    ✅ Practical Wealth-Building Education

    🌐 Finance Investment
    Helping Investors Build Wealth One Smart Decision at a Time.