Finance Investment • Banking Guide
CDs (Certificates of Deposit) USA 2026:
Best CD Rates, Types, Strategies & Safety
By Subhash Rukade
•
Updated August, 18, 2026
•
12–15 min read
 A certificate of deposit can be a simple way to earn interest on money you do not need right away.
But choosing a CD is not just about finding the highest advertised rate. The term length, APY, withdrawal rules, minimum deposit and insurance coverage all matter.
A certificate of deposit can be a simple way to earn interest on money you do not need immediately. In this 2026 guide, we’ll explain how CDs work, how to compare rates and terms, and when a CD may or may not fit your financial goals.
Certificate of Deposit Basics for 2026
That is especially important in 2026. Interest rates can change, and a rate that looks attractive today may come with a commitment that does not fit your plans. A six-month CD, one-year CD and five-year CD can serve very different purposes.
The good news is that CDs are relatively straightforward once you understand the basic rules. You deposit your money for a specific period, earn interest according to the account terms, and generally receive your money plus interest when the CD matures.
CDs at a Glance
A CD may be worth considering if you can leave your money untouched for a set period and want a predictable return.
- Best for: Money you do not expect to need before the CD matures.
- Main advantage: Predictable interest for the agreed term.
- Main drawback: Early withdrawals may trigger a penalty.
- Safety: CDs at FDIC-insured banks are generally covered by federal deposit insurance within applicable limits.
- Before opening: Compare APY, term, minimum deposit, withdrawal penalty and maturity rules.
Is a CD Right for You?
The answer depends mainly on when you will need the money.
If you may need your cash at any time, locking it into a CD could create an unnecessary restriction. A liquid savings account may be more appropriate for money that needs to stay accessible.
On the other hand, suppose you are saving for a known expense one or two years from now. If you are confident you will not need the money early, a CD could give that portion of your savings a predictable return.
It is also worth comparing a CD with a high-yield savings account before making a decision. Savings accounts generally provide easier access to your money, while CDs are designed around a fixed term.
You can compare the two approaches in our guide to
high-yield savings accounts
.
Quick tip:
Do not use money you may need for an emergency just to chase a slightly higher CD rate. A higher return is not helpful if accessing the money creates a penalty or financial problem.
What This 2026 CD Guide Covers
This guide goes beyond simply explaining what a certificate of deposit is. It walks through the decisions you are likely to face before opening one.
You will learn how CD rates work, how to compare different terms, how much various deposits could potentially earn, and how different types of CDs work. We will also cover CD laddering, early withdrawal penalties, taxes, FDIC insurance and what happens when a CD reaches maturity.
Later, we will compare CDs with high-yield savings accounts, money market accounts, Treasury bills and bonds. That comparison matters because the best place for your money depends on more than the interest rate alone.
You will also see practical examples for different savings amounts and financial situations, so you can judge whether a CD fits your own timeline rather than simply following a generic recommendation.
Why the Details Matter
Two CDs can have similar advertised rates but work very differently for the person opening them.
One may require a larger minimum deposit. Another may have a more restrictive early withdrawal penalty. One may mature in six months, while another locks the money away for five years.
That is why the right question is not simply,
“Which CD has the highest rate?”
A better question is:
“Which CD gives me a competitive return without creating a problem if my financial plans change?”
By the end of this guide, you should be able to answer that question with much more confidence.
Are CDs Worth It in 2026?
For some savers, yes. A CD can make sense in 2026 if you have money you will not need for a set period and want a predictable return. The key is choosing a term that matches your timeline instead of locking up money simply because the rate looks attractive.
CDs may work well for conservative savers, people preparing for a known expense, and retirees who want to keep part of their money in lower-risk deposits. They can also fit short- or medium-term goals where protecting the principal matters more than chasing higher long-term investment returns.
However, a CD is not a good fit for every dollar you have saved. Emergency money usually needs to remain accessible. If you expect to need the cash soon or want the flexibility to move your money when rates change, a savings account may be more practical. Our guide to high-yield savings accounts explains why liquidity can matter when building an emergency reserve.
CDs: Pros and Cons
| Potential Benefits | Potential Drawbacks |
|---|
| Predictable return for the CD term | Money may be locked up until maturity |
| Can offer competitive APYs | Early withdrawal may trigger a penalty |
| Generally lower risk than market investments | Rates may rise after you lock in |
| Can support short- and medium-term goals | Less flexible than a savings account |
A Simple $10,000 Example
Suppose you have $10,000 that you will not need for one year. A CD could give you a fixed return for that period, while a savings account would generally give you easier access to the money. The better choice depends on the APY difference and how valuable that flexibility is to you.
That is why the best CD decision in 2026 is not simply about finding the highest rate. Consider three things together: the rate, the term and your need for liquidity.
If you can comfortably leave the money untouched, a CD may be worth considering. If you need access to it, keeping the money liquid may be more important.
Now let’s start with the basics and look at exactly what a certificate of deposit is and how this type of account works.
What Is a Certificate of Deposit (CD)?
A certificate of deposit (CD) is a type of deposit account offered by banks and credit unions. You put money into the account for a set period, called the term, and the financial institution pays you interest based on the account’s terms.
The basic idea is simple:
How a CD Works at a Glance
Deposit → Choose a term → Earn interest → Reach maturity → Withdraw or renew
Unlike a regular savings account, a CD is designed around a fixed time commitment. A savings account generally lets you add or withdraw money when needed, while a CD usually expects you to leave the deposit in place until the maturity date. Taking money out early may result in an early withdrawal penalty.
For example, imagine you deposit $10,000 into a one-year CD. If the account offers a fixed APY, you generally know the rate when you open the CD. You leave the money deposited for the one-year term. When the CD matures, you can usually take your money and earned interest, or renew the CD according to the bank’s available terms.
CDs are available from both banks and credit unions. When comparing accounts, look beyond the advertised rate. Check the APY, minimum opening deposit, term, early withdrawal penalty and what happens when the CD matures.
If you are completely new to CDs, our supporting guide ⚓ What Is a Certificate of Deposit? Complete 2026 Guide provides a beginner-friendly explanation of the basics.
CDs Are Simple, but the Terms Matter
The basic concept does not change much, but individual CDs can have very different rules. One account may offer a higher APY but require a larger deposit. Another may offer more flexibility but a lower rate.
Understanding those details becomes especially important before you lock your money away. Once you know what a CD is, the next question is more practical: what actually happens after you open one?
That’s what we’ll cover next in how a CD works from the day you make your deposit through the maturity date.
How Does a CD Work?
Opening a CD is usually straightforward. You choose a bank or credit union, decide how much money you want to deposit, pick a term, and review the interest rate and account rules. Once you fund the CD, the money stays in the account for the agreed period unless you make an early withdrawal.
The two numbers that deserve the most attention are the term and the APY. The term tells you how long your money will be committed. The APY shows the annualized return, including the effect of compounding when applicable. A longer term is not automatically better, so choose one that matches when you expect to need the money.
What Happens During the CD Term?
Once the CD is open, your deposit earns interest according to the account’s terms. Depending on the CD, interest may compound during the term or be paid according to a different schedule. The account agreement will explain how interest is handled.
For example, suppose you put $10,000 into a 12-month CD. You open the account, fund it, and leave the money there for the full year. During that time, the CD earns interest based on its APY. When the 12-month term ends, the CD reaches its maturity date.
A Simple CD Timeline
Day 1: Deposit $10,000 and open the CD.
Months 1–12: The money remains in the CD and earns interest.
Month 12: The CD reaches maturity.
After maturity: You can generally withdraw the money, move it elsewhere, or renew it under the bank’s available terms.
What If You Need the Money Early?
This is where CDs differ from savings accounts. Many CDs charge an early withdrawal penalty if you take money out before maturity. The penalty varies by institution and account, so check the terms before opening the CD.
You should also pay attention to automatic renewal. Some banks automatically renew a CD if you do nothing after it matures. If you want to move the money, check the bank’s grace period and maturity instructions ahead of time.
For a more detailed beginner explanation, see our guide on ⚓ How Does a CD Work? Smart 2026 Guide
Once you understand the basic mechanics, the next question is usually the one that matters most: how much could your money actually earn?
In the next section, we’ll look at CD earnings with simple examples using different deposit amounts and rates.
How Much Can You Earn From a CD?
How much a CD earns depends mainly on three things: the amount you deposit, the APY and how long you leave the money in the account. A higher APY can produce more interest, but the term also matters because a longer CD gives your money more time to earn.
APY stands for annual percentage yield. It shows how much an account can earn over one year while taking compounding into account. That makes APY more useful for comparing deposit accounts than looking at the stated interest rate alone.
A Simple Example
Suppose a CD offers a hypothetical 4.00% APY. If you deposit $1,000 and leave it there for one year, you would earn roughly $40 in interest before taxes, assuming the account compounds in a way that produces the stated APY.
| Deposit | Illustrative APY | Approx. 1-Year Interest* |
|---|
| $1,000 | 4.00% | About $40 |
| $5,000 | 4.00% | About $200 |
| $10,000 | 4.00% | About $400 |
| $25,000 | 4.00% | About $1,000 |
*These are simple illustrations, not current rate quotes. Actual earnings depend on the CD’s APY, term, compounding method and account terms.
For a closer look at a larger deposit, see our guide to ⚓ How Much Can You Earn From a $10,000 CD? 2026 Guide. If you are considering a $25,000 deposit, our guide on How Much Interest Does a $25,000 CD Earn? goes deeper into the numbers. We also explain what a larger deposit could earn in ⚓ How Much Can You Earn From a CD? Smart 2026 Guide
Does a Longer CD Always Earn More?
Not necessarily. A five-year CD may give you more total interest simply because your money stays invested longer, but its APY may not always be higher than a shorter-term CD. You also give up access to your money for a longer period.
That is why comparing the APY alone is not enough. Look at the rate, the term and when you expect to need the money.
Once you understand how much a CD can earn, the next question is what determines those rates in the first place. Next, we’ll look at how CD rates work in 2026 and why they change.
How Do CD Interest Rates Work in 2026?
CD rates tell you how much a bank or credit union is willing to pay when you leave your money on deposit for a set period. When comparing accounts, pay close attention to the APY rather than looking only at the stated interest rate. APY accounts for compounding and gives you a better way to compare what different accounts may earn over a year.
Why Do Banks Offer Different CD Rates?
There is no single CD rate that every bank has to offer. Financial institutions set their rates based on factors such as funding needs, competition, loan demand and the broader interest-rate environment.
That is why two banks can offer noticeably different APYs on CDs with the same term. Online banks may sometimes offer competitive rates because their business models can have lower operating costs, while other institutions may focus more on branch access or a broader range of banking services.
How Do Federal Reserve Rates Affect CDs?
The Federal Reserve does not set the CD rate you receive from your bank. However, changes in the federal funds rate can influence the broader rate environment.
When market rates move higher, banks may raise deposit rates to attract or retain customers. When rates move lower, CD and savings rates can also decline. The timing is not always immediate, and banks do not necessarily change every product by the same amount.
What About Inflation?
Inflation matters because the interest you earn is only part of the picture. If prices are rising quickly, the purchasing power of your money can still decline even when a CD is earning interest.
For that reason, a CD can be useful for preserving and growing cash over a known period, but it should not automatically be treated as a complete long-term investing strategy.
Why the Highest CD Rate Isn’t Always the Best Choice
Imagine you have $10,000 to deposit. One bank offers a hypothetical 4.00% APY, while another offers 4.20%. The second account would earn more if all other terms were the same. But what if the higher-rate CD has a much longer term or a tougher early withdrawal penalty?
The extra interest may not be worth giving up that flexibility.
| APY | $10,000 for 1 Year* | Approx. Difference |
|---|
| 4.00% | About $400 | — |
| 4.20% | About $420 | About $20 more |
*Illustrative figures only. Actual earnings depend on the CD’s terms and compounding.
Before choosing an account, compare current offers in our guide to ⚓ Best CD Rates in 2026: Smart Guide to Finding Better Yields If you are thinking about locking in a rate, our guide ⚓ Should You Lock In a CD Rate Now? Smart 2026 Guide can help you think through the trade-offs. For the basics behind CD pricing, see ⚓ How Do CD Interest Rates Work? Smart 2026 Guide
The rate matters, but so does the amount of time your money will be tied up. Next, we’ll look at CD terms and how to choose one that fits your financial timeline.
Choosing the Right CD Term
A CD term is simply the amount of time you agree to keep your money in the account. Common choices include six months, one year, 18 months, two years, three years and five years.
The right term has less to do with choosing the longest option and more to do with knowing when you will need the money. A longer CD can give you a longer rate lock, but it also means less access to your cash.
Short-Term vs. Long-Term CDs
| CD Term | May Fit | Main Trade-Off |
|---|
| 6 months | Money needed relatively soon | Shorter commitment |
| 1 year | Near-term planned expenses | Limited access during the term |
| 18 months | Medium-term savings goals | Money stays committed longer |
| 2 years | Known expenses a few years away | Less flexibility |
| 3 years | Longer planned goals | More exposure to changing rates |
| 5 years | Money you can leave untouched | Longest commitment |
Match the Term to Your Goal
Suppose you are saving $10,000 for a car you expect to buy in about a year. A five-year CD would not match that goal very well, even if its APY looks attractive. A six-month or one-year CD may give you a better balance between earning interest and having the money available when you need it.
Now imagine you have money that you are confident you will not need for several years. A longer-term CD could make more sense, especially if you want to lock in a rate and avoid worrying about where rates may move next.
What About Future Interest Rates?
Rate-locking can work in your favor when rates fall because your CD keeps its agreed rate for the term. But it can work against you when rates rise because your money remains tied to the older rate unless you are willing to wait for maturity or accept the cost of an early withdrawal.
That is one reason the highest APY today should not be the only factor in your decision. Think about the rate, the term and your timeline together.
If you are comparing shorter terms, see ⚓ Best 6-Month CD Rates in 2026: Higher Yields for Short-Term Savings and ⚓ Best 1-Year CD Rates in 2026: Find Better Yields. For longer options, you can compare ⚓ Best 18-Month CD Rates in 2026: Find Better Yields, ⚓ Best 2-Year CD Rates in 2026: Lock In Competitive Yields ⚓ Best 3-Year CD Rates in 2026: Compare Competitive Yields and ⚓ Best 5-Year CD Rates in 2026: Lock In Long-Term Yields.
Once you know how long you want to keep your money in a CD, the next step is understanding the different types available. Not every CD has the same rules or features.
Types of CDs Explained: Which CD Is Right for You?
Not every certificate of deposit works the same way. A standard CD may be all you need if you want a fixed term and a predictable return. But other CDs offer different features that can make sense in specific situations.
The main differences usually come down to flexibility, how the interest rate can change, where the CD is held and whether the account is connected to a retirement account.
Standard CDs
A standard CD is the basic version most people think of when they hear “CD.” You deposit a set amount, choose a term and earn interest according to the account terms. The rate is typically fixed for the CD term.
This type may work well if you know you will not need the money before maturity and want a straightforward deposit account.
Standard CDs Explained: How They Work, Rates, Risks & Benefits in 2026
No-Penalty CDs
A no-penalty CD gives you more flexibility than a traditional CD. Depending on the account, you may be able to withdraw your money before maturity without paying the usual early withdrawal penalty.
The trade-off is that the APY may be lower than what you could find on a comparable standard CD. This type can appeal to savers who want some of the benefits of a CD without giving up as much access to their cash.
No-Penalty CDs Explained: How They Work in 2026.
Callable CDs
A callable CD gives the issuing bank the right to end the CD before its scheduled maturity date under the terms of the account. This can become more relevant when interest rates fall.
Callable CDs may offer attractive rates, but you should understand the call provisions before putting your money into one. The bank’s ability to end the CD early can affect how long you actually earn the advertised rate.
Callable CDs Explained: How They Work in 2026.
Jumbo CDs
Jumbo CDs generally require a large minimum deposit. The exact amount varies by financial institution, but the idea is simple: you commit a substantial amount of money in exchange for the CD’s stated terms.
They may be useful for people with large cash balances, but a larger deposit does not automatically make a jumbo CD the better choice. Compare the APY, term, insurance coverage and liquidity before opening one.
Jumbo CDs Explained: Rates, Risks, Insurance & How They Work in 2026
Brokered CDs
A brokered CD is purchased through a brokerage account rather than directly from a bank in the same way as a traditional bank CD. Brokerages may offer CDs from multiple banks, which can make it easier to compare different offerings.
Brokered CDs can have features and risks that differ from ordinary bank CDs, particularly around selling before maturity. Read the product details carefully before buying.
Brokered CDs Explained: How They Work, Rates, Risks & FDIC Insurance
IRA CDs
An IRA CD is a certificate of deposit held inside an individual retirement account. The CD itself works much like a regular CD, but the surrounding IRA has its own tax rules and contribution requirements.
This option may appeal to someone who wants part of their retirement savings in a deposit product rather than putting the entire account into market investments.
IRA CDs Explained
Bump-Up CDs
A bump-up CD can give you an opportunity to request a higher rate during the CD term if the bank increases the rate for eligible accounts. The number of times you can use the feature depends on the product.
This feature may be useful when you are concerned that rates could rise after you open the CD. The starting APY and other terms still deserve close attention.
Bump-Up CDs Explained
Step-Up CDs
A step-up CD has a rate structure that increases at predetermined points during the term. Instead of keeping the same rate from beginning to end, the account follows the schedule set by the financial institution.
These CDs can be interesting if you want a built-in rate increase, but compare the full schedule rather than focusing only on the final rate.
Step-Up CDs Explained
Add-On CDs
An add-on CD may allow you to make additional deposits after the account is opened. That can be useful if you expect to have more money to save during the CD term.
Not every bank offers this feature, and the account may have specific rules about additional deposits, rates and minimum amounts.
Add-On CDs Explained
Variable-Rate CDs
A variable-rate CD does not necessarily keep the same interest rate throughout the entire term. The rate can change according to the rules of the account.
This can give you a different experience from a traditional fixed-rate CD. If rates rise, the account may benefit from the change, but you should also understand how the rate is determined and whether there are limits on adjustments.
Variable-Rate CDs Explained
CD Types at a Glance
| CD Type | What Makes It Different? | May Fit | Main Trade-Off |
|---|
| Standard CD | Fixed term and predictable rate | Savers seeking simplicity | Limited access before maturity |
| No-Penalty CD | More flexible withdrawals | Savers who value access | May offer a lower APY |
| Callable CD | Bank may end the CD early | Rate-focused savers comfortable with call risk | CD may mature earlier than expected |
| Jumbo CD | Large minimum deposit | Savers with substantial cash | Large amount committed |
| Brokered CD | Purchased through a brokerage | Investors comparing multiple bank offerings | Different liquidity rules |
| IRA CD | Held inside an IRA | Retirement savers | IRA rules also apply |
| Bump-Up CD | May allow a rate increase | Savers expecting rates to rise | Feature may have restrictions |
| Step-Up CD | Rate rises on a preset schedule | Savers wanting scheduled increases | Starting rate may be less attractive |
| Add-On CD | Allows additional deposits | Savers adding money over time | Limited availability and rules |
| Variable-Rate CD | Rate can change | Savers comfortable with changing rates | Future return is less predictable |
The best CD type depends on what matters most to you. If simplicity is the priority, a standard CD may be enough. If flexibility matters, a no-penalty option may deserve a look. Retirement savers may consider an IRA CD, while someone comparing several banks through a brokerage may explore brokered CDs.
Once you have chosen the type of CD that fits your situation, there is another way to improve flexibility: using multiple CDs with different maturity dates instead of putting everything into one account.
Next, we’ll look at how to build a CD ladder in 2026 and how the strategy can help spread out your maturity dates.
How to Build a CD Ladder in 2026
A CD ladder spreads your money across several CDs with different maturity dates instead of putting the entire amount into one CD. The idea is simple: when one CD matures, you have an opportunity to use the money, move it elsewhere or reinvest it into another CD.
This can give you more flexibility than putting all your savings into a single long-term CD.
One CD vs. a CD Ladder
| Approach | How It Works | Main Advantage | Main Trade-Off |
|---|
| One CD | All money goes into one term | Simple to manage | All money may mature at the same time |
| CD ladder | Money is spread across different terms | More frequent maturity dates | Requires more planning |
A Simple $20,000 CD Ladder
Suppose you have $20,000 that you do not need immediately. Instead of putting all $20,000 into one five-year CD, you could divide it into five $4,000 CDs with different maturity dates.
| Deposit | CD Term | What Happens |
|---|
| $4,000 | 1 year | Matures after 1 year |
| $4,000 | 2 years | Matures after 2 years |
| $4,000 | 3 years | Matures after 3 years |
| $4,000 | 4 years | Matures after 4 years |
| $4,000 | 5 years | Matures after 5 years |
When the first CD matures, you could take the money for a planned expense or reinvest it into a new five-year CD. If you keep doing that, another CD can mature each year.
The exact structure does not have to follow five equal deposits. You can adjust the amounts and terms based on your goals and cash-flow needs.
Why Use a CD Ladder?
The biggest benefit is timing. Instead of having all your money locked away until one maturity date, you create several points when money becomes available.
A ladder can also spread your rate risk. If rates rise, a maturing CD gives you a chance to reinvest at a potentially higher rate. If rates fall, some of your money may already be locked into earlier CDs with higher rates.
There is a trade-off, though. A ladder takes more effort to manage than a single CD, and the rates available when each CD matures may be different from the rates you originally received.
For a detailed walkthrough, see How to Build a CD Ladder in 2026 If you are comparing laddering with another approach, read CD Ladder vs. CD Barbell StrategyYou can also learn ways to improve your overall returns in How to Maximize CD Interest Earnings in 2026.
CD Ladder Mistakes to Watch For
- Putting emergency savings into the ladder
- Choosing terms without considering when you need the money
- Ignoring early withdrawal penalties
- Forgetting CD maturity dates
- Automatically renewing every CD without checking current rates
- Putting too much money into one bank without reviewing deposit insurance limits
A CD ladder works best when the maturity dates match your financial plans. It is a tool for managing cash, not a reason to lock up every dollar you have.
Once the ladder is in place, there are other ways to manage CDs, from choosing when to reinvest to deciding how much flexibility you want. Next, we’ll look at CD strategies beyond laddering.
CD Strategies Beyond Laddering
A CD can be more useful when you choose the account around your financial goal instead of simply picking the highest rate you can find. Once you know how much money you can set aside and when you may need it, a few simple strategies can help you make better use of a CD.
Compare Rates Before You Open a CD
Rates can vary widely between banks and credit unions. Before opening an account, compare the APY, term, minimum deposit and early withdrawal penalty. A slightly higher rate may not be worth choosing if the account has terms that do not fit your plans.
Our guide on How to Compare CD Rates Before Opening a CD in 2026covers the details worth checking before you commit your money.
Think About When You Will Need the Money
A CD should match your timeline. If you are saving for a known expense within a year, a shorter CD may make more sense than locking the money away for several years. For money you will not need for a longer period, a longer term could provide more certainty.
If the money is for a specific short-term goal, our guide to How to Use CDs for Short-Term Financial Goals can help you think through the trade-offs.
Know What Happens When Your CD Matures
A CD does not always end automatically when the term is over. Many banks give you a short grace period during which you can withdraw the money or make changes. After that period, the bank may automatically renew the CD.
Check the maturity date and renewal instructions before the CD reaches the end of its term. Our guide on What to Do When Your CD Matures in 2026 explains the choices you may have.
Do Not Let Automatic Renewal Make the Decision for You
Automatic renewal can be convenient, but the new CD may have a different rate or term. Take a few minutes to check current offers before allowing the money to roll into another CD.
See How to Avoid Automatic CD Renewal in 2026 for practical ways to stay in control of your money.
Reinvest With a Purpose
When a CD matures, you can take the money, move it to another savings option or reinvest it into a new CD. The best choice depends on your current needs and the rates available at that time.
If you decide to keep using CDs, How to Reinvest a Matured CD in 2026 can help you evaluate your options before committing to another term.
Keep Some Money Accessible
Even if CDs are part of your savings plan, keeping enough cash outside CDs can give you room to handle unexpected expenses without breaking a CD early. The exact amount depends on your income, expenses and financial situation.
There is no need to put every available dollar into a CD. A mix of liquid savings and fixed-term deposits can give you both access and predictable returns.
Once you have looked at these strategies, the next question is how CDs compare with other places you could keep your money. In the next section, we will compare CDs with savings accounts, money market accounts, Treasury bills and bonds.
CD vs. Other Savings & Investment Options
A CD is only one way to keep money working while you wait to use it. Depending on your goal, a high-yield savings account, money market account, Treasury bill or bond may make more sense.
The biggest difference is usually the trade-off between return, access and risk. A CD can give you a predictable rate for a set term, but you generally give up some flexibility in exchange.
CD vs. High-Yield Savings Account
A high-yield savings account can be a better fit when you want competitive interest while keeping your money accessible. A CD may be more appealing when you are comfortable leaving the money untouched until maturity.
Before choosing between the two, compare the current APY and how much access you need. You can also read our guide to high-yield savings accounts to see how savings accounts can fit into a broader cash strategy.
CD vs. Money Market Account
Money market accounts generally offer easier access to your money than CDs and may provide features such as check-writing or debit-card access, depending on the bank. A CD, by comparison, is built around a fixed term.
If you expect to use the money during the next few months, that extra access may matter more than locking in a CD rate.
CD vs. Savings Account
A traditional savings account is usually designed for flexibility. You can generally add money and make withdrawals under the account’s rules without waiting for a maturity date.
A CD works differently. You agree to leave the deposit in place for a specific period, and withdrawing early may result in a penalty. That restriction can be worthwhile if you want a predictable return and know you will not need the money during the term.
CD vs. Treasury Bills
Treasury bills, or T-bills, are short-term U.S. government securities with maturities of one year or less. They are not bank deposits, so they are not covered by FDIC insurance. Instead, they are backed by the full faith and credit of the U.S. government.
T-bills can be attractive for investors who want short-term exposure to U.S. government debt. They also have a different tax treatment: interest from U.S. Treasury securities is generally exempt from state and local income taxes, although federal income tax still applies.
CD vs. Bonds
Bonds can offer income and may play a role in longer-term portfolios, but their prices can move before maturity. A CD held to maturity generally does not have the same market-price fluctuations as a traded bond.
That does not make CDs better in every situation. Bonds can provide broader investment opportunities and may be more appropriate for longer-term goals, while CDs are often used for money that has a known purpose and timeline.
CD Comparison at a Glance
| Option | Return Potential | Liquidity | Risk | Protection | May Fit |
|---|
| CD | Predictable rate for the term | Lower | Generally low for bank CDs | FDIC coverage may apply | Money you can leave untouched |
| High-Yield Savings | Variable rate | High | Generally low for insured deposits | FDIC coverage may apply | Emergency and accessible savings |
| Money Market Account | Variable rate | High | Generally low for insured deposits | FDIC coverage may apply | Accessible cash with interest |
| Savings Account | Usually variable | High | Generally low for insured deposits | FDIC coverage may apply | Everyday savings goals |
| Treasury Bills | Market-based | Moderate to high, depending on how held | Very low credit risk | Backed by U.S. government | Short-term government securities |
| Bonds | Varies | Varies | Varies | Depends on the issuer | Longer-term investing and income |
For a deeper comparison, see our guides on CD vs High-Yield Savings Account: Which Is Better in 2026?, CD vs Money Market Account: Which Is Better in 2026?, CD vs Savings Account: Which Is Better in 2026?. CD vs Treasury Bills: Which Is Better in 2026?. and CD vs Bonds: Which Is Better for Your Money in 2026?.
The right choice comes down to what you need the money to do. If access matters most, a savings option may be easier to live with. If you want a fixed term and predictable return, a CD may fit. If you are looking beyond bank deposits, Treasury bills and bonds offer a different set of risks and potential returns.
Before opening a CD, there is one cost you should understand clearly: what happens if you need your money before the maturity date?
Next, we’ll look at CD early withdrawal penalties and how they can affect your savings.
What Is a CD Early Withdrawal Penalty?
 A CD early withdrawal penalty is a fee or loss of interest that may apply when you take money out of a certificate of deposit before its maturity date. The exact rule depends on the bank or credit union and the specific CD you opened.
Unlike a savings account, a CD is built around a commitment to leave your money deposited for a set period. If you break that agreement early, the financial institution may take some of the interest you have earned.
How Can the Penalty Affect Your Money?
Suppose you put $10,000 into a one-year CD and the account has an early withdrawal penalty equal to several months of interest. If you need the money after only a few months, the bank may deduct the applicable penalty from the interest you earned.
In some situations, the penalty can reduce your earnings significantly. The exact amount depends on the CD’s terms, so never assume every bank calculates the charge the same way.
Why Do Penalties Differ?
Financial institutions set their own early withdrawal policies within applicable rules. One CD might charge a certain number of months of interest, while another could use a different formula. Some accounts may have minimum holding periods or other restrictions.
That is why the early withdrawal section of the account agreement deserves a close look before you deposit your money.
What If You Want More Flexibility?
A No-Penalty CD may be worth considering if you want a CD structure but do not want the usual early withdrawal charge. These accounts can provide more flexibility, although the APY may be different from comparable standard CDs.
It is also a good reason to keep emergency savings separate from money you put into CDs. If an unexpected bill comes up, you may need immediate access to cash rather than having to break a CD.
Before opening an account, make sure you know the penalty, maturity date and withdrawal rules. A competitive APY is useful, but it should not come at the cost of money you may need unexpectedly.
Once you understand the withdrawal risk, the next question is safety. How protected is your money if the bank holding your CD fails?
Next, we’ll look at CD safety, FDIC insurance and what happens to your money when an insured bank fails.
Are CDs Safe and FDIC Insured?
For many savers, one of the biggest reasons to consider a CD is the protection available on eligible bank deposits. But it is important to understand what that protection covers and where its limits are.
A CD issued by an FDIC-insured bank is generally covered by federal deposit insurance, subject to the applicable rules and coverage limits. The standard coverage limit is $250,000 per depositor, per insured bank, for each ownership category.
What Does FDIC Insurance Protect?
FDIC insurance is designed to protect covered deposits if an insured bank fails. Covered deposit accounts can include checking accounts, savings accounts and CDs.
For example, if you have a $50,000 CD at an FDIC-insured bank and the bank fails, that deposit would generally fall within the standard insurance limit, assuming you have no other deposits at that bank that affect your coverage.
That last point matters. The $250,000 limit is not simply $250,000 for every account you have at the same bank. Deposits are generally combined based on ownership category when determining coverage.
What About Amounts Above $250,000?
If your deposits exceed the applicable insurance limit at one bank and ownership category, the amount above the limit may not have the same federal protection. Savers with larger balances may consider how their deposits are spread across insured institutions and ownership categories.
You can learn more about the basics in our guides to Are CDs Safe for Your Money? Understanding CD Safety and Are CDs FDIC Insured? 2026 Guide to CD Coverage.
What Happens if a Bank Fails?
For an FDIC-insured bank, covered deposits are protected according to FDIC rules. If you want to understand what happens specifically to a CD after a bank failure, see What Happens to a CD if a Bank Fails?.
It is also worth checking that the institution is actually FDIC insured before opening a bank CD. Do not assume that every product described as a CD has the same protection.
Safety is only one part of the decision. Even an insured CD can generate taxable interest, which affects what you actually keep.
For official information about deposit insurance and coverage limits, see the
FDIC’s deposit insurance guide.
For current information about U.S. interest-rate policy, see the
Federal Reserve’s monetary policy information.
For general information about taxable interest income, see the
IRS guidance on interest income.
Next, we’ll look at how CD interest is taxed and what that can mean for your after-tax return.
How Are CD Earnings Taxed?
Interest earned from a regular CD is generally taxable income. That means the interest you earn can increase your taxable income for the year, even if you leave the money inside the CD instead of taking it out.
Federal, State and Local Taxes
For a typical bank CD held outside a retirement account, the interest is generally subject to federal income tax. Depending on where you live, state or local income taxes may apply as well.
For example, suppose you put $10,000 into a CD and earn $400 of interest during the year. The $400 is generally taxable interest income. You do not get to exclude it simply because the money stays in the CD until maturity.
Your actual after-tax return depends on your tax situation. Someone in a higher tax bracket may keep less of the interest than someone in a lower bracket.
What About an IRA CD?
An IRA CD works differently because the CD is held inside an individual retirement account. The tax rules come from the type of IRA and the applicable retirement-account rules, rather than simply treating the CD like an ordinary taxable bank account.
If you are considering this option, our guide to IRA CDs Explained covers how these accounts work and what makes them different from regular CDs.
Why Taxes Matter When Comparing CDs
A CD with a higher APY does not necessarily leave you with the highest amount after taxes. When comparing accounts, consider the rate, term and how much of the interest you may actually keep.
For a detailed explanation, see How Are CD Earnings Taxed? A 2026 Guide.
Tax rules can change and individual circumstances differ, so this section is for general educational purposes rather than personalized tax advice. If you have questions about how CD interest affects your taxes, a qualified tax professional can help with your specific situation.
Once taxes are accounted for, there is another practical question: how much of your savings should actually go into CDs?
Next, we’ll look at how to decide how much money to put in a CD without leaving yourself short on accessible cash.
How Much Money Should You Put in a CD?
There is no single amount that makes sense for everyone. The right CD deposit depends on how much cash you have, when you may need it and how much money you want to keep available.
A good starting point is to separate money you may need soon from money you can leave untouched. Your emergency savings should generally stay accessible. A CD can then be considered for money that is set aside for a known goal or a longer-term cash need.
Start With Your Timeline
If you have $1,000 that you will not need for several months, a short-term CD could be one option to consider. With $5,000 or $10,000, you may have more flexibility to divide the money between a CD and an accessible savings account.
For example, someone with $10,000 in excess cash might keep part of it liquid and put the rest into a CD that matches a known financial goal. The exact split depends on the person’s expenses, income and comfort with having money locked up.
What About Larger Deposits?
If you have $25,000 or more available, the same principle applies. You do not have to put the entire amount into one CD. Splitting the money between different terms can provide more flexibility and may also reduce the chance of having all your cash tied up at one maturity date.
For larger balances, remember that FDIC insurance limits matter. If your deposits at one insured bank exceed the applicable coverage limits, review how your accounts are structured before adding more money.
Keep Some Cash Accessible
A CD should not replace the cash you may need for an unexpected repair, medical bill, job loss or other urgent expense. Breaking a CD early can mean losing some of the interest you expected to earn.
Our guide on How Much Money Do You Need to Open a CD? explains minimum deposit requirements, while How to Use CDs for Short-Term Financial Goals looks at ways CDs can fit specific savings timelines.
The goal is not to put as much money as possible into CDs. It is to put the right amount into a term you can comfortably complete.
Once you know how much money you can set aside, the next question is whether a CD actually fits your situation. Next, we’ll look at who may benefit from CDs—and who may want to choose a more flexible option.
Who Should Consider a CD?
A CD can be a good fit when you have money set aside for a specific period and do not expect to need it before the account matures. It can give you a predictable return without exposing that portion of your savings to the daily ups and downs of the stock market.
Who May Benefit From CDs?
- Conservative savers: People who value predictable returns and want to keep some money in deposit accounts.
- Known future expenses: Someone saving for a purchase or bill that is several months or years away.
- Short- and medium-term goals: A CD can work when the timeline is clear and the money does not need to remain fully accessible.
- Retirees: CDs may be useful for part of a cash allocation when predictable income and principal protection are important.
The key is to match the CD term with the date you expect to need the money. Our guide on How Long Should You Keep Money in a CD?
explains how different terms can fit different timelines.
Who May Want to Skip a CD?
- People building an emergency fund: Emergency money usually needs to be available without waiting for maturity or paying a penalty.
- People who may need the cash soon: A fixed term can become a problem if your plans change.
- Long-term growth investors: If your goal is decades away, investments such as diversified stocks may offer greater growth potential, although they also carry more risk.
CDs do not have to be an all-or-nothing decision. You can keep some money liquid while using CDs for cash you are confident you will not need right away.
Before choosing one, also consider the basic safety rules explained in our guide to Are CDs Safe for Your Money?.
Once you know whether a CD fits your situation, the next step is choosing the right account. Rate matters, but it is only one part of the decision.
How to Choose the Right CD
Choosing a CD is about more than finding the highest APY. A good CD should fit your timeline, your cash needs and the amount of money you are comfortable leaving untouched.
1. Compare the APY
Start with the annual percentage yield. APY gives you a useful way to compare what different CDs may earn, including the effect of compounding. Make sure you are comparing CDs with similar terms and conditions.
2. Match the Term to Your Goal
Think about when you expect to need the money. If you will need it within a year, a five-year CD may create an unnecessary restriction. If the money is for a goal several years away, a longer term may be worth considering.
3. Check the Minimum Deposit
Some CDs can be opened with a relatively small amount, while others require a larger deposit. Do not move more money into a CD than you are comfortable keeping there for the full term.
4. Understand the Early Withdrawal Penalty
Read the penalty rules before opening the account. Find out how much interest you could lose if you need the money early. A slightly higher APY may not be worth it if the withdrawal terms are too restrictive for your situation.
5. Review Maturity, Renewal and Insurance Rules
Check what happens when the CD matures. Some banks automatically renew CDs if you do not give different instructions within the available grace period. Also verify that the bank is FDIC insured and understand how deposit insurance applies to your accounts.
A Simple CD Selection Checklist
- Compare the APY.
- Choose a term that matches your financial goal.
- Check the minimum opening deposit.
- Review the early withdrawal penalty.
- Confirm maturity, renewal and FDIC insurance details.
For a more detailed walkthrough, see How to Choose the Right CD for Your Money.
One final point matters: do not judge a CD by its rate alone. A competitive APY is useful, but the account still needs to work with your plans. If you might need the money early, flexibility can be worth more than a small difference in interest.
Once you know what to look for, it is easier to avoid the mistakes that can turn an otherwise reasonable CD into a poor fit. Next, we’ll look at the most common CD mistakes beginners should avoid.
Common CD Mistakes Beginners Should Avoid
CDs are simple to understand, but a few small oversights can make the account a poor fit. Most problems happen when savers focus on the advertised rate and overlook the rules attached to it.
1. Choosing the Highest APY Without Reading the Terms
A higher APY can be attractive, but check the term, minimum deposit, withdrawal penalty and renewal rules before opening the account. A better rate is not useful if the account does not fit your timeline.
2. Locking Up Emergency Savings
Emergency money needs to be available when an unexpected expense arrives. Putting your entire emergency reserve into a CD could leave you facing an early withdrawal penalty when you need the cash.
3. Ignoring the Early Withdrawal Penalty
Before opening a CD, find out exactly what happens if you take the money out early. The penalty can reduce your interest earnings and, depending on the account terms, may have a bigger impact than expected.
4. Forgetting the Maturity Date
Mark the maturity date on your calendar. Waiting until the last minute can make it easier to miss your options for moving or reinvesting the money.
5. Letting a CD Renew Automatically
Some banks automatically renew CDs after maturity. The new CD may have a different APY or term. Check the renewal instructions before the maturity date arrives.
6. Choosing a Longer Term Than You Need
A five-year CD is not automatically better than a one-year CD. If you may need the money sooner, a shorter term can give you more flexibility.
7. Ignoring FDIC Coverage Limits
If you have a large amount of money at one bank, review how FDIC insurance applies to your deposits. Do not assume every dollar is covered simply because the bank is insured.
8. Putting All Your Cash Into One CD
Dividing money between different accounts or maturity dates can give you more flexibility. A CD ladder is one way to spread out maturity dates.
9. Forgetting About Taxes
Interest from a regular CD is generally taxable. When comparing returns, remember that the amount you keep after taxes may be lower than the headline interest figure.
Before You Open a CD
- Check the APY and term.
- Review the early withdrawal penalty.
- Confirm the minimum deposit.
- Check the maturity and renewal rules.
- Verify FDIC insurance.
- Make sure you have enough liquid savings outside the CD.
- Consider the tax impact of the interest.
For a deeper beginner-focused checklist, see Common CD Mistakes Beginners Should Avoid
Avoiding these mistakes can make it much easier to use CDs for the right purpose. But rates are another piece of the decision, especially when the broader interest-rate environment is changing.
Next, we’ll look at the CD rate outlook for 2026 and what could influence rates in the months ahead.
CD Rate Outlook for 2026
CD rates can change as the broader interest-rate environment changes. In August 2026, the Federal Reserve’s target range for the federal funds rate is 3.50% to 3.75%, while inflation remains above the Fed’s 2% goal. That leaves some uncertainty around where deposit rates may go next.
That uncertainty matters when deciding whether to lock in a CD. Recent rate data also shows that some of the most competitive CD offers are coming from shorter terms, rather than following the usual pattern of longer CDs always paying more.
What Could Move CD Rates?
The Federal Reserve is one important factor, although it does not set the rate on your individual CD. Banks and credit unions also look at their need for deposits, competition and the rates they can earn elsewhere.
If market rates move higher, financial institutions may have more reason to raise CD rates to attract deposits. If rates move lower, banks may reduce the rates they offer on new CDs.
Inflation matters, too. If inflation stays elevated, interest rates could remain higher for longer. If price pressures continue to ease, the rate environment could move in a different direction. Recent U.S. inflation data has cooled somewhat, but inflation is still above the Fed’s target.
Should You Lock In a CD Rate Now?
There is no reliable way to know the highest rate you will see during 2026. Instead of trying to time the exact top, consider how long you can comfortably leave the money untouched.
If a current rate works for your goal and you value certainty, locking it in may make sense. If you expect to need the money soon or want to keep the opportunity to benefit from higher future rates, a shorter-term CD may give you more flexibility.
Before making a decision, compare current offers in Best CD Rates in 2026 and see our guide on Should You Lock in a CD Rate Now?. You can also learn more about how rates are determined in ⚓ CD Rate Forecast 2026: What Savers Should Watch.
What Is a CD Early Withdrawal Penalty? The key is not predicting the market perfectly. It is choosing a CD term and rate that you can live with even if rates move in an unexpected direction.
Once you have a rate and term in mind, the next step is seeing what the numbers could look like with different deposit amounts. Next, we’ll work through practical CD earnings examples.
CD Earnings Examples & Calculator-Style Scenarios
The amount you can earn from a CD depends on the deposit, APY and term. The examples below use illustrative rates to show how the numbers can work. They are not current rate quotes or guaranteed returns.
How Much Could Different Deposits Earn?
To keep the math simple, assume a hypothetical 4.00% APY for a one-year CD.
| Deposit | Term | Illustrative APY | Approx. Interest |
|---|
| $1,000 | 1 year | 4.00% | About $40 |
| $5,000 | 1 year | 4.00% | About $200 |
| $10,000 | 1 year | 4.00% | About $400 |
| $25,000 | 1 year | 4.00% | About $1,000 |
These figures assume the stated APY applies for the full term. Actual CD earnings can differ based on the account’s compounding method and terms.
What Happens When the APY Changes?
Consider a $10,000 deposit. At a hypothetical 3.50% APY, the one-year return would be roughly $350. At 4.50%, it would be roughly $450. That 1-percentage-point difference represents about $100 more in interest over a year before taxes.
Term length matters, too. A six-month CD may give you access to the money sooner, while a one-year CD gives you a longer rate commitment. A longer term does not automatically mean a better APY.
For larger deposits, see ⚓ How Much Can $100,000 Earn in a CD? Complete 2026 Guide ⚓ How Much Interest Does a $25,000 CD Earn? 2026 Guide and ⚓ How Much Can You Earn From a CD? Smart 2026 Guide. When Is the Best Time to Open a CD in 2026?
Remember Taxes
Interest from a regular CD is generally taxable. So the amount you actually keep can be lower than the interest shown in a simple calculation. Your after-tax result depends on your individual tax situation.
These examples are useful for comparing scenarios, but they should not be treated as promises of what a particular CD will earn.
Once you see how the numbers work, the next question is more personal: which type of CD makes sense for your particular goal? Next, we’ll match different CD options with common financial situations.
Best CD for Your Situation
The best CD is not necessarily the one with the highest APY. It is the one that fits your timeline, cash needs and comfort with leaving the money untouched.
| Your Situation | CD Option to Consider | Why It May Fit |
|---|
| Need the money within a year | Short-term CD | Shorter commitment |
| Saving for a known expense | CD matching the goal date | Term can line up with your timeline |
| Want more flexibility | No-penalty CD | May allow earlier access without the usual penalty |
| Want regular maturity dates | CD ladder | Spreads money across different terms |
| Saving inside retirement funds | IRA CD | Held within an IRA structure |
| Have a large cash balance | Compare jumbo and standard CDs | Different deposit requirements and rates |
If Flexibility Matters
A no-penalty CD may be worth looking at if you want a fixed-term deposit but are concerned about needing the money early. Read the account rules carefully because flexibility can come with a different APY.
See our guide to No-Penalty CDs Explained for more details.
If You Want Regular Access to Matured Money
A CD ladder can spread your maturity dates across several years. Instead of waiting for one large CD to mature, you may have smaller amounts becoming available at different times. Learn more in How to Build a CD Ladder in 2026.
For retirement savings, an IRA CD may be worth considering, but remember that the IRA has its own tax and withdrawal rules.
The right choice starts with your goal. Once that is clear, compare the rate, term, fees, access and insurance before opening the account.
Next, let’s bring the major CD options together in one comparison table so you can see the differences at a glance.
Complete CD Comparison Table
Each CD type has a different mix of rate structure, flexibility and account rules. This table gives you a quick way to compare the main options before you start looking at individual accounts.
| CD Type | Rate Structure | Flexibility | Risk / Consideration | May Fit |
|---|
| Standard CD | Usually fixed | Low | Early withdrawal penalty may apply | Savers who want simplicity |
| No-Penalty CD | Usually fixed | Higher | APY may be lower | Savers who want easier access |
| Callable CD | Usually fixed | Low | Bank may call the CD early | Savers comfortable with call features |
| Jumbo CD | Usually fixed | Low | Large amount may be committed | Savers with substantial deposits |
| Brokered CD | Usually fixed | Varies | Different liquidity and market considerations | Investors using brokerage accounts |
| IRA CD | Usually fixed | Lower | IRA rules apply | Retirement savers |
| Bump-Up CD | Can increase under account rules | Moderate | Rate increases may have restrictions | Savers expecting rates to rise |
| Step-Up CD | Rises on a preset schedule | Low | Starting rate may be lower | Savers wanting scheduled increases |
| Add-On CD | Varies by account | Moderate | Additional deposit rules apply | Savers who expect to add money |
| Variable-Rate CD | Can change | Low to moderate | Future return is less predictable | Savers comfortable with changing rates |
No single CD type wins for every saver. A standard CD may be enough if you want a straightforward fixed-term account. Someone who values flexibility may prefer a no-penalty CD, while a saver with retirement funds may look at an IRA CD. The important part is matching the account features with your own timeline and cash needs.
Now that we have covered the major CD options, rates, strategies, risks and tax considerations, it is time to bring everything together.
Next, we’ll answer the big question: Are CDs worth considering in 2026?
Are CDs Worth It in 2026?
CDs can still have a useful place in a savings plan when you know when you will need the money and are comfortable leaving it untouched for a set period. They offer a straightforward way to earn interest without exposing that cash to the daily price swings of the stock market.
But a CD is not automatically the best choice just because it offers a competitive APY. If you need quick access to your money, a savings account may be a better fit. If your goal is long-term growth, investments such as diversified stocks and funds may offer more growth potential, along with more risk.
Three Things to Remember
- Match the term to your timeline: Do not choose a five-year CD if you expect to need the money next year.
- Look beyond the APY: Check the withdrawal penalty, minimum deposit, maturity rules and insurance coverage.
- Keep some money liquid: A CD should not replace the cash you may need for emergencies.
For savers who want predictable returns and can leave their money alone, a CD may be a reasonable part of a broader cash strategy. A CD ladder can add flexibility by spreading maturity dates, while a no-penalty CD may make sense when access matters more.
If you are still comparing options, revisit our guide to high-yield savings accounts before making a decision. The better option depends on how much access you need and how long you can leave the money untouched.
Most importantly, do not feel pressured to lock up money simply because a rate looks attractive. The right CD is one that fits your financial timeline without creating a cash-flow problem later.
With the main CD decisions covered, let’s answer some of the most common questions readers have before opening an account.
Frequently Asked Questions About CDs
What Is a Certificate of Deposit?
A certificate of deposit is a deposit account that usually pays interest in exchange for keeping your money in the account for a set period. The CD has a maturity date, and withdrawing money before that date may result in a penalty.
How Does a CD Work?
You deposit money, choose a term and earn interest according to the account’s terms. When the CD matures, you can generally withdraw the money and interest or renew the account.
Are CDs Safe?
Bank CDs are generally considered low-risk deposit products when issued by an FDIC-insured bank and kept within applicable insurance limits. They do not have the same market-price fluctuations as stocks or many traded bonds.
Are CDs FDIC Insured?
Eligible CDs held at FDIC-insured banks are generally covered by federal deposit insurance, subject to applicable limits and ownership categories. The standard coverage limit is $250,000 per depositor, per insured bank, for each ownership category.
Can You Lose Money in a CD?
A properly structured bank CD within applicable FDIC coverage is designed to protect the insured deposit if the bank fails. However, you can lose some expected interest if you withdraw early and the account charges a penalty. Inflation can also reduce the purchasing power of your returns.
What Happens When a CD Matures?
When the term ends, the CD reaches its maturity date. Depending on the bank’s rules, you may be able to withdraw the money, move it to another account or renew it. Check the maturity instructions before the date arrives.
Can You Withdraw Money From a CD Early?
Usually, you can request an early withdrawal, but the bank may charge a penalty or reduce the interest you receive. The exact rule depends on the CD. A no-penalty CD may provide more flexibility.
What Is a CD Ladder?
A CD ladder spreads your money across CDs with different maturity dates. For example, you could divide $20,000 among five CDs with one- through five-year terms. As each CD matures, you can use the money or reinvest it.
How Long Should You Keep Money in a CD?
The term should match when you expect to need the money. Shorter terms can work for nearer goals, while longer terms may suit money you are confident you will not need for several years.
Are CD Earnings Taxable?
Interest from a regular CD is generally taxable income. Federal income tax usually applies, and state or local taxes may also apply depending on where you live. CD interest held within an IRA follows the applicable retirement-account tax rules.
Is a CD Better Than a Savings Account?
Neither is always better. A CD may offer a fixed return in exchange for a commitment, while a savings account generally provides easier access to your money. Your timeline and need for liquidity should guide the choice.
How Much Money Do You Need to Open a CD?
Minimum deposits vary by bank, credit union and CD. Some accounts accept relatively small deposits, while others require much more. Always check the minimum before opening an account.
Can You Have Multiple CDs?
Yes. You can have multiple CDs, including CDs with different terms and maturity dates. Using several accounts can help you spread out when your money becomes available.
Are Longer-Term CDs Always Better?
No. A longer CD may give you a longer rate lock, but it also keeps your money committed for more time. The APY may not be higher than shorter-term options either. Compare the rate with your timeline before choosing.
What Should You Check Before Opening a CD?
Review the APY, term, minimum deposit, early withdrawal penalty, maturity and renewal rules, and FDIC insurance status. Also make sure the money is not part of your emergency reserve.
A CD works best when its rules fit your financial plan. Once you understand the rate, term, access and safety considerations, you can make a much more informed choice.
Get More Practical Money Guides
Money decisions are easier when you understand the trade-offs before you commit.
If you found this CD guide useful, subscribe to Finance Investment for practical guides on saving, banking, investing and retirement planning.
Want more straightforward money tips for 2026? Subscribe and get our latest personal finance guides delivered to you.
 How Much Can You Earn From a CD depends mainly on the amount you deposit, the APY, and how long you leave the money in the account. Imagine David placing $15,000 into a 12-month CD at a 4.25% APY. If the rate and terms stay as stated, his account could earn roughly $637.50 over a year before taxes.
 How Much Can You Earn From a CD becomes easier to judge when you look at the actual dollars instead of the rate alone. Suppose Maria has $8,000 she will not need for 18 months. She finds a CD offering a 4.00% APY. If that APY applies for the full term, the account could earn roughly $480 over 18 months before taxes, using a simple annualized estimate.
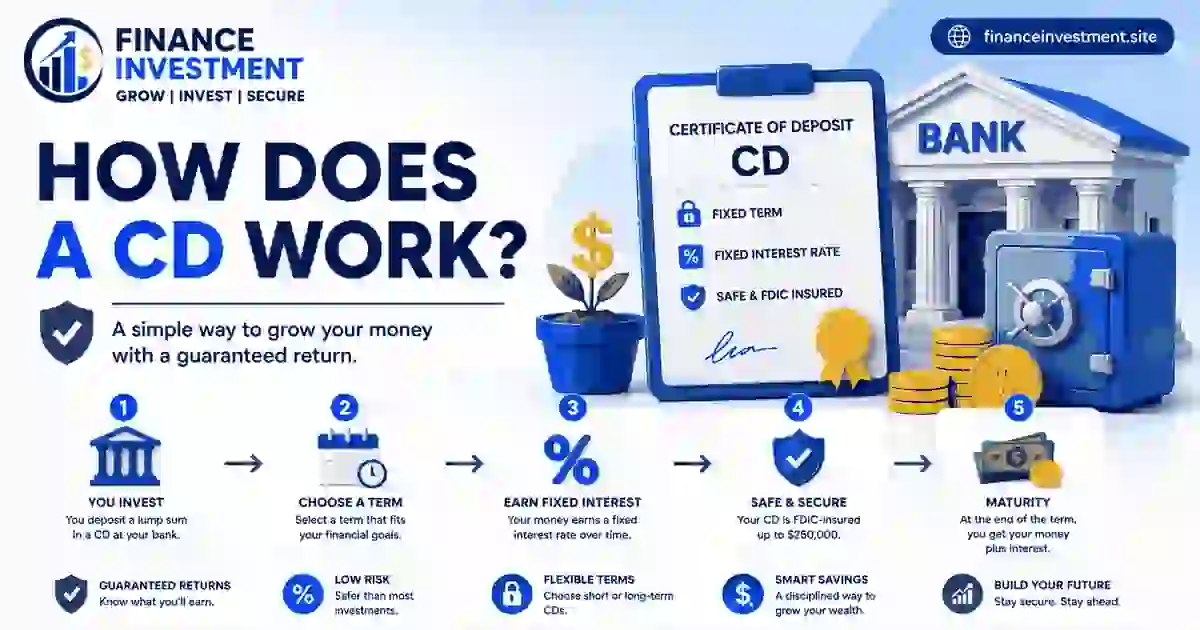
 How Does a CD Work when you open one for the first time? The basic idea is straightforward. You choose how much money to deposit, select a term, and agree to leave the funds in the account under the bank’s stated conditions. In return, the bank pays interest according to the CD agreement.
 What Is a Certificate of Deposit when you look beyond the basic definition? Think of it as a deal between you and a bank. You place a certain amount of money into the account, agree to leave it there for a specific term, and the bank pays interest according to the account’s terms.
 A CD early withdrawal penalty is a fee or loss of interest that may apply when you take money out of a certificate of deposit before its maturity date. The exact rule depends on the bank or credit union and the specific CD you opened.