A money market account can be an appealing middle ground when you want your cash to earn interest without putting it completely out of reach. You may have money set aside for an emergency, a home project, a vehicle, or another expense that is still months away. Leaving it in a basic checking account may earn little or no interest, while locking it into a longer-term product can make access less convenient.
That’s where the trade-off gets interesting. A money market account can offer interest earnings along with features such as transfers, ATM access, checks, or debit-card access, depending on the bank. But higher earnings or added convenience can come with minimum-balance rules, monthly fees, transaction restrictions, or rates that can change over time.
If you want the bigger picture first, our
Money Market Accounts guide
explains how these accounts fit into a broader cash-management plan. This article takes the next step by looking closely at the good and the less convenient parts.
What You’ll Learn
- Where money market accounts can fit in a savings strategy.
- The practical advantages that may make an account worthwhile.
- The fees, restrictions, and rate changes that can reduce its appeal.
- How an MMA compares with savings, checking, and CDs.
- Which types of savers may benefit most—and who may want another option.
Are Money Market Accounts Worth It?
A money market account can be worthwhile if you want your savings to earn interest while keeping relatively convenient access to the cash. The main advantages are interest earnings, flexible access, and useful banking features at some institutions. The trade-offs can include minimum-balance requirements, monthly fees, variable rates, and transaction restrictions. In other words, the account can work well for certain savings goals, but the advertised APY should never be the only thing you compare.
Key Takeaways
- Interest can be the biggest attraction. An MMA may help cash earn more than leaving it in a low-interest transaction account.
- Access varies by bank. Some accounts may include checks, debit cards, ATM access, or convenient transfers.
- Fees can change the calculation. A monthly charge may offset part of the interest you earn.
- Rates are often variable. Today’s APY is not necessarily the rate you’ll receive later.
- Balance rules matter. Some accounts use minimum balances for fee waivers or advertised rates.
- Safety depends on the product and institution. A federally insured deposit account is different from a money market mutual fund.
- Another account may fit better. Savings, checking, or a CD can make more sense depending on how you plan to use the money.
Bottom line:
The best money market account is not simply the one showing the highest rate. Look at what you earn, what you pay, and how easily you can use the money when you need it.
Table of Contents
Use the links below to jump directly to the part of the guide you want to explore.
Money Market Account Pros and Cons: At a Glance
Before getting into the details, here is a quick snapshot of what to expect from a money market account. The exact features can vary from one financial institution to another, so treat these points as a starting place rather than a promise that every account will work the same way.
Best For
A money market account may suit someone holding a meaningful cash balance who wants interest while retaining access to the funds. It can be useful for an emergency reserve, a planned purchase, or cash that is waiting for a future financial decision.
Key Numbers to Check
- Current APY
- Minimum opening deposit
- Minimum balance for fees or advertised rates
- Monthly maintenance fee
- Available withdrawal and transfer options
| Feature | What to Expect |
|---|---|
| Interest | Usually earned on the account balance. |
| Flexibility | Generally more accessible than a CD, subject to account rules. |
| Potential downside | Fees, balance conditions, restrictions, or falling rates can reduce the benefit. |
Money Market Accounts: A Complete Beginner Guide
 A money market account is a type of deposit account offered by banks and credit unions. It is designed for people who want to keep cash in a relatively accessible account while earning interest on the balance. Depending on the institution, the account may come with features such as check-writing, ATM access, a debit card, or electronic transfers.
The name can cause confusion because a money market deposit account is not the same thing as a money market mutual fund. A bank or credit-union deposit account is held as a deposit, while a mutual fund invests in short-term securities and follows different rules. Knowing the distinction matters when you are evaluating safety, access, and where your cash is actually held.
How It Compares With Other Cash Accounts
A savings account is often simpler and may be a better fit when you mainly want to set money aside. A checking account is built around frequent transactions and everyday payments. A CD, meanwhile, generally exchanges some flexibility for a specified term and rate. An MMA sits somewhere among these choices, offering a combination of interest and access that can be useful for certain cash reserves.
If you are still deciding which account belongs in your cash plan, our
money market accounts guide
provides a broader look at how these accounts work and where they can fit.
Deposit Insurance and Account Structure
Eligible deposits at an FDIC-insured bank are generally covered by FDIC insurance within applicable limits and ownership categories. At federally insured credit unions, qualifying shares are generally insured through the NCUA’s share insurance program. Coverage is subject to specific rules, so check the institution’s insurance status and account ownership structure rather than assuming every financial product has the same protection.
How Does a Money Market Account Work?
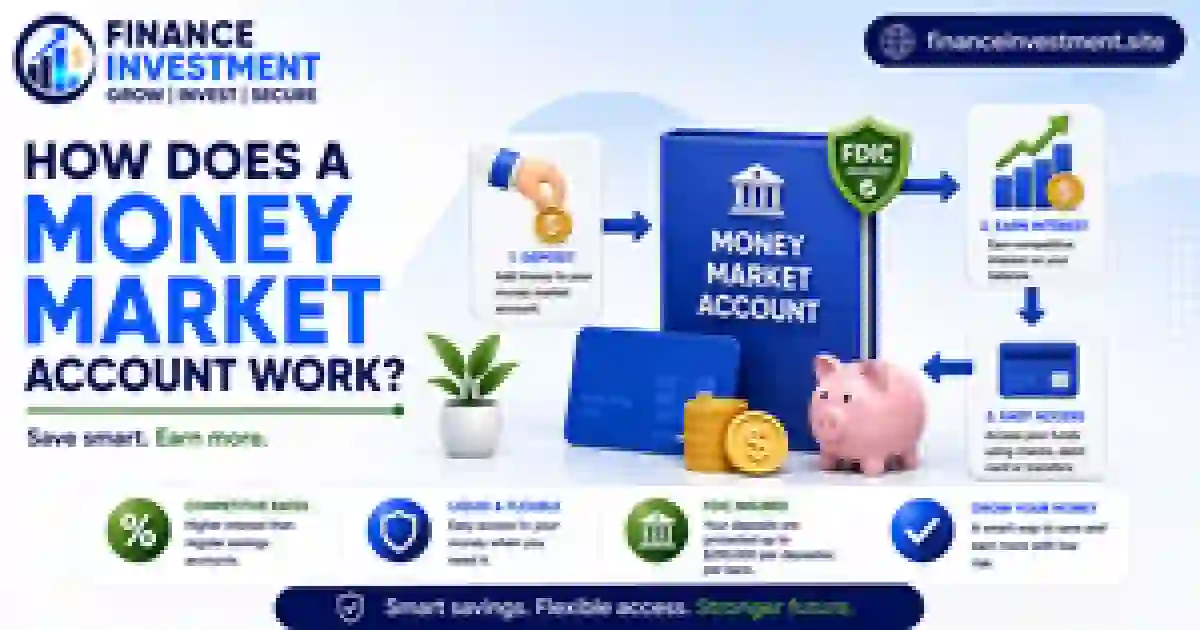
Once you open the account, you can deposit money much like you would with other bank deposit accounts. The institution then calculates interest according to its account terms. Your earnings are commonly expressed as an annual percentage yield, or APY, which reflects the rate of return over a year while taking compounding into account.
The rate is often variable, so the APY you receive when you open the account can rise or fall later. That means a strong rate today should not be treated as a permanent guarantee. Some institutions may also use balance tiers, offering different rates depending on how much money you keep in the account.
Deposits, Withdrawals and Transfers
You may be able to move money into or out of the account through electronic transfers, ATMs, checks, or a debit card, depending on the institution. However, access is not unlimited by default. Banks and credit unions can impose transaction limits, fees, minimum balances, or other account-specific conditions. Always check the current account agreement for the exact rules.
A Simple Example
Imagine you keep $15,000 in an MMA for an upcoming home project. The balance earns interest while it remains there. A few months later, you transfer part of the money to checking to pay a contractor. If the account’s APY changes during that period, your future interest earnings change too. If the balance falls below a required threshold, the account could also have different rate or fee consequences.
The practical idea:
keep the money there while the account’s rate and conditions make sense, then use the available access features when the cash is needed. The details in the account agreement determine how smoothly that process works.
Money Market Account Pros and Cons
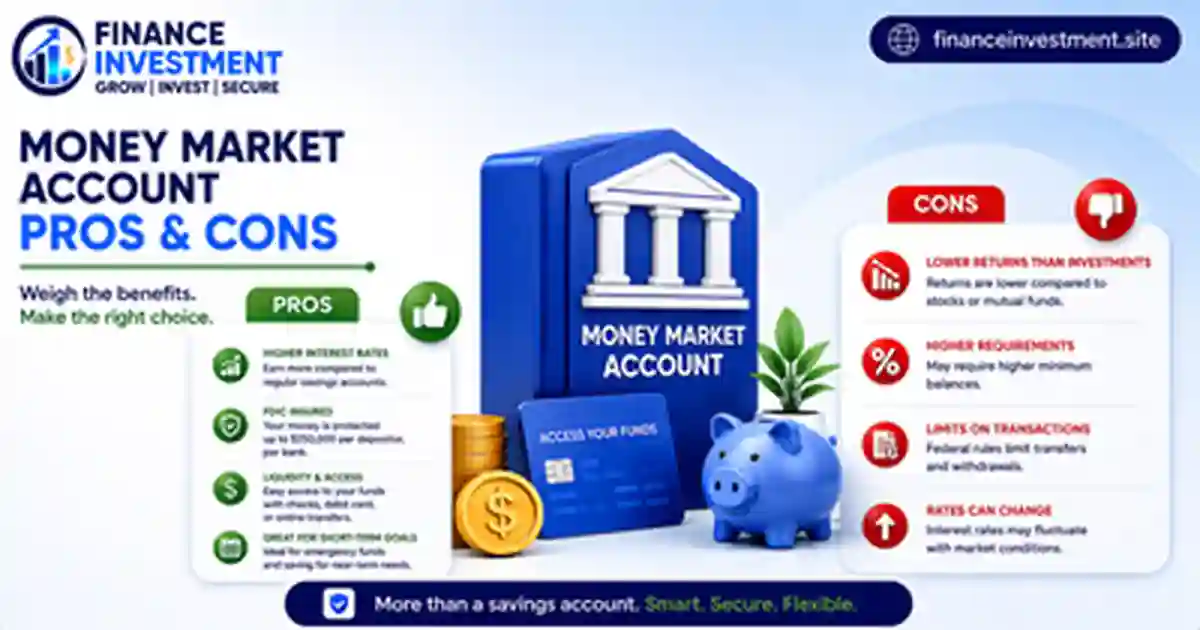
A money market account can be a useful middle ground, but it is not automatically the best home for every dollar. The biggest advantages tend to come from combining interest earnings with convenient access, while the trade-offs usually involve account rules, fees, and changing rates.
Where an MMA Can Work Well
- Interest on idle cash: Instead of leaving a larger cash balance earning little or no interest, you may be able to earn a competitive APY.
- Useful access: Depending on the institution, you may have checks, ATM access, debit-card access, or electronic transfers available when you need the money.
- Good for larger balances: Some accounts offer attractive rates or tiered benefits when you maintain a higher balance.
- Convenient cash management: An MMA can be practical for money you expect to use later but do not need for everyday purchases.
Where the Trade-Offs Appear
- Rates can change: A variable APY may fall after you open the account, reducing future interest income.
- Minimum-balance rules: Some accounts require you to maintain a certain balance to avoid a monthly fee or qualify for a stated rate.
- Access may have limits: Transaction restrictions or account-specific conditions can make an MMA less convenient than checking for frequent spending.
- Fees can reduce returns: A monthly maintenance fee, excess-transaction charge, or other cost can eat into the interest you earn.
A useful way to look at it:
the advertised APY is only one part of the deal. A slightly lower rate with no monthly fee and fewer restrictions could leave you better off than a higher headline rate with costly conditions.
Money Market Account vs. Other Cash Accounts
The easiest way to judge a money market account is to compare it with the other places you could keep the same cash. Each account type solves a slightly different problem. An MMA may appeal when you want interest earnings without giving up as much access as you would with a time deposit, while another account may be simpler for everyday spending or routine saving.
| Account | Access | Rate Potential | Liquidity | Typical Use |
|---|---|---|---|---|
| Money Market Account | Moderate to high | Often competitive | High | Larger cash reserves with occasional access |
| Savings Account | Moderate | Varies by institution | High | General-purpose saving |
| High-Yield Savings Account | Moderate | Often higher than basic savings | High | Saving while prioritizing interest |
| Checking Account | Very high | Usually lower | Very high | Bills, purchases and everyday transactions |
| Certificate of Deposit | Lower during the term | Usually fixed for the term | Lower | Money you can leave untouched for a set period |
Which Difference Matters Most?
If you expect frequent transactions, checking usually makes more sense. If your main goal is earning interest while keeping savings readily available, a high-yield savings account may be worth comparing with an MMA. And when you know you will not need the money for a specific period, a CD can offer a different rate-and-access trade-off.
For a closer look at the time-deposit option, see our
CD vs. money market account comparison
.
It can help you decide whether keeping your cash flexible or locking it away for a defined term better fits your plans.
Money Market Account Costs, Risks and Expert Tips
A competitive APY can look attractive, but the details around that rate can make a real difference to your results. Before moving a large cash balance, look beyond the headline number and check what the account actually costs to maintain.
Watch for Fees and Balance Requirements
Some accounts charge a monthly maintenance fee unless you meet a minimum balance. Others may have charges for certain transactions, outgoing transfers, paper statements, or additional services. A simple calculation can reveal whether the account is worthwhile: compare the interest you expect to earn with the fees you could realistically pay.
Watch the rate, too:
money market account rates can change. If your bank reduces the APY, leaving the account untouched for months could mean earning substantially less than you expected. Make a habit of reviewing the current rate and account terms periodically.
Keep the Account Secure
Account safety also depends on how you manage access. Use a unique, strong password, enable multi-factor authentication when available, and turn on transaction alerts. Avoid signing in through suspicious links or sharing one-time verification codes. If you notice an unfamiliar withdrawal or transfer, contact the financial institution promptly.
Expert Tips for Protecting Your Interest
- Compare APYs and fees together rather than chasing the highest advertised rate.
- Keep enough of a balance to satisfy any minimum-balance condition you actually need.
- Review the APY after major rate changes in the broader market.
- Confirm that your bank or credit union provides the applicable federal deposit or share insurance before depositing significant cash.
Smart cash management is about the net result.
The best account is not necessarily the one with the biggest advertised APY; it is the one whose rate, fees, access and safety features work well together for the money you plan to keep there.
Common Money Market Account Mistakes — Plus a Real-Life Example
Most problems with a money market account do not come from the basic idea of the account. They usually happen when someone overlooks a small detail in the account agreement or assumes the advertised rate and access rules will stay unchanged.
Mistakes Worth Avoiding
- Looking only at the APY: A high advertised rate can lose its appeal if the account has a monthly fee or a balance requirement you cannot consistently meet.
- Assuming the rate is fixed: Many MMAs have variable rates, so today’s APY may not be tomorrow’s APY.
- Using it like checking: Frequent payments or withdrawals may not fit the account’s transaction rules or could result in fees.
- Ignoring insurance details: Verify that the institution is federally insured and understand which account ownership category applies to your deposits.
- Leaving the account unchecked: A once-competitive account can become less attractive after its rate changes or another fee is introduced.
Real-Life Example: Two Ways to Handle $20,000
Imagine Alex has $20,000 set aside for a home renovation expected within the next year. Alex chooses an MMA because the money can remain available while earning interest.
At first, the account looks attractive. Later, the APY falls and Alex’s balance drops below the level required to avoid a monthly fee. The account still works, but the combination of lower interest and fees reduces the cash earnings.
A quick review could reveal a better option. Alex might find another MMA with fewer restrictions, move the money to a competitive savings account, or use a CD for the portion that will not be needed soon. The lesson is simple: review the whole account, not just the opening APY.
A good habit:
whenever your cash needs, balance or account rate changes, take a few minutes to check whether the account still earns its place in your financial plan.
Who Should Choose a Money Market Account?
A money market account can make sense when you have cash that matters to you, but you do not expect to spend it every day. The best fit often comes down to how quickly you may need the money and how much access you want.
An MMA can suit a sizable emergency reserve when you want interest earnings alongside relatively convenient access.
Money set aside for a vehicle, tuition, home project or another upcoming expense may fit well if you want to keep it separate from everyday spending.
An MMA may be useful for part of a cash reserve that needs to remain accessible rather than being committed for a fixed term.
When Another Account May Be Better
If you make frequent payments, a checking account is usually more practical. If your priority is earning a competitive rate on savings with straightforward access, compare a high-yield savings account. And if you know you will not need part of the cash for a defined period, a CD may be worth considering in exchange for less flexibility. The goal is to match the account with the job your money needs to perform.
Frequently Asked Questions About Money Market Accounts
1. What is a money market account?
A money market account is a bank or credit-union deposit account that can pay interest while offering access to your cash. Features and restrictions vary by institution.
2. Are money market accounts FDIC insured?
Eligible deposits at an FDIC-insured bank are generally covered within applicable limits and ownership categories. Credit-union shares may instead be covered by NCUA insurance.
3. Can a money market account lose money?
An eligible insured money market deposit account generally does not expose your
deposited funds to market-price fluctuations like a money market mutual fund.
However, fees can reduce your balance, and a changing APY can affect how much
interest you earn over time.
4. Do money market accounts have variable interest rates?
Many do. Because the rate can change, the APY you receive after opening the account may be different from the rate you originally saw.
5. Is a money market account better than a savings account?
Neither is automatically better. Compare the APY, fees, minimum balance, transaction rules and access features to see which account fits your needs.
6. Can you use a money market account for everyday spending?
Some MMAs provide checks or debit-card access, but account rules may make them less suitable for frequent everyday transactions than checking accounts.
7. Do money market accounts require a minimum balance?
Some do and some do not. A minimum balance may affect the APY you receive or whether a monthly maintenance fee applies.
8. Is a money market account good for an emergency fund?
It can be, particularly when you want your reserve accessible while earning interest. Make sure the account’s withdrawal rules and fees work with how you expect to use the fund.
9. What is the difference between an MMA and a money market mutual fund?
An MMA is a deposit account offered by a bank or credit union. A money market mutual fund is an investment product, so its structure, risks and protections are different.
Final Verdict: Are Money Market Accounts Worth It?
A money market account can be a useful middle ground for people who want their cash to earn interest without giving up convenient access. It can work especially well for larger cash reserves, an emergency fund, or money earmarked for an expense that is still a little way off.
The decision becomes easier when you focus on the job of the money. Need frequent transactions? A checking account may be more practical. Want to maximize savings interest and rarely need transaction features? A high-yield savings account could deserve a closer look. Have money you can leave untouched for a set period? A CD may offer a better fit.
Also look beyond the advertised APY. Check the minimum balance, monthly fees, withdrawal options, rate conditions, and deposit-insurance coverage. A slightly higher rate is not much help if fees or account restrictions eat into the benefit.
If you want to keep exploring, our
money market accounts guide
provides a broader look at how these accounts fit into a cash-management strategy. From there, you can compare related savings and CD options before deciding where your cash belongs.
Stay Ahead of Your Money
Make Your Cash Work Smarter
Want more practical money guidance without the jargon? Join our newsletter for useful ideas about savings, CDs, banking, investing and everyday money decisions.
You can also continue exploring our
money market account guides
and related savings and CD resources.
subhashr325@gmail.com
 A money market account is a type of deposit account offered by banks and credit unions. It is designed for people who want to keep cash in an interest-bearing account while retaining access to the balance. Unlike an investment account, the money is held as a deposit with the financial institution rather than being directly invested in stocks or bonds.
 A money market account is a deposit account offered by a bank or credit union that lets your cash earn interest while keeping it relatively accessible. It can be useful when you want more earning potential than a basic spending account without committing the money to a fixed-term CD.
 If you’ve used a regular certificate of deposit before, the main difference here is the interest rate. With a traditional fixed-rate CD, the rate is generally set when you open the account and remains unchanged through the term. A variable-rate CD can adjust during that period based on the terms of the account.
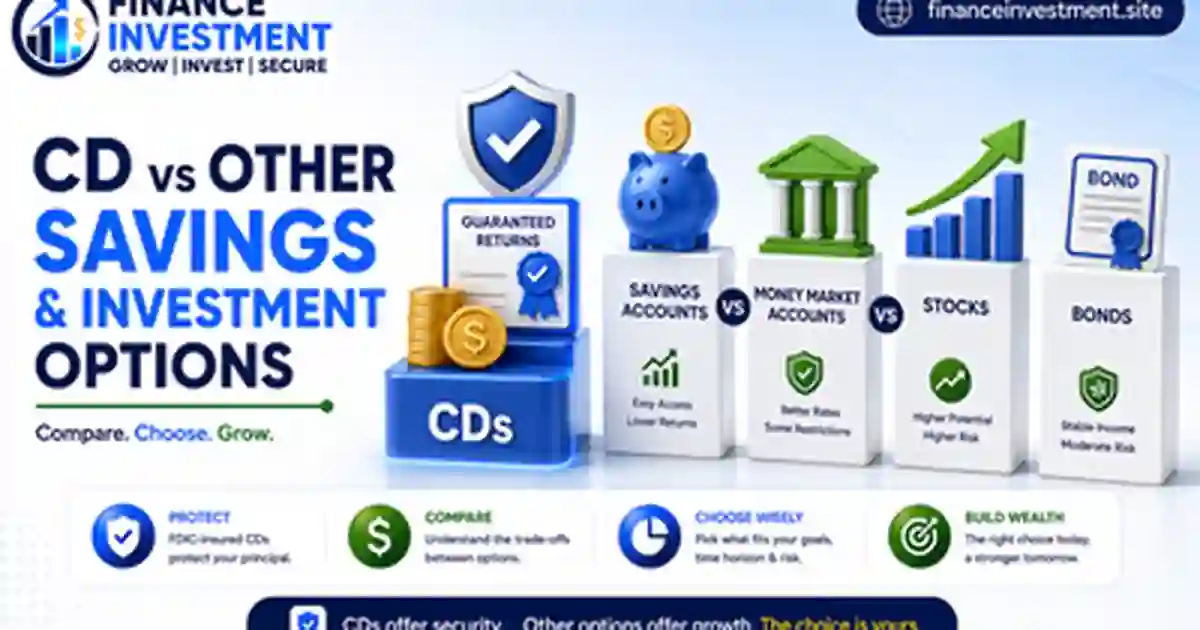 When you have cash to put to work, a certificate of deposit isn’t the only place it can go. A CD may offer a predictable return, but a high-yield savings account can keep your money easier to reach, while Treasury bills and bonds may play a different role in a broader investment plan. The real question isn’t simply which option pays more.
 Choosing where to keep your money starts with one simple question: When will you need it? A CD, savings account, money market account, Treasury bill and bond can all hold or grow money, but they do not work the same way.
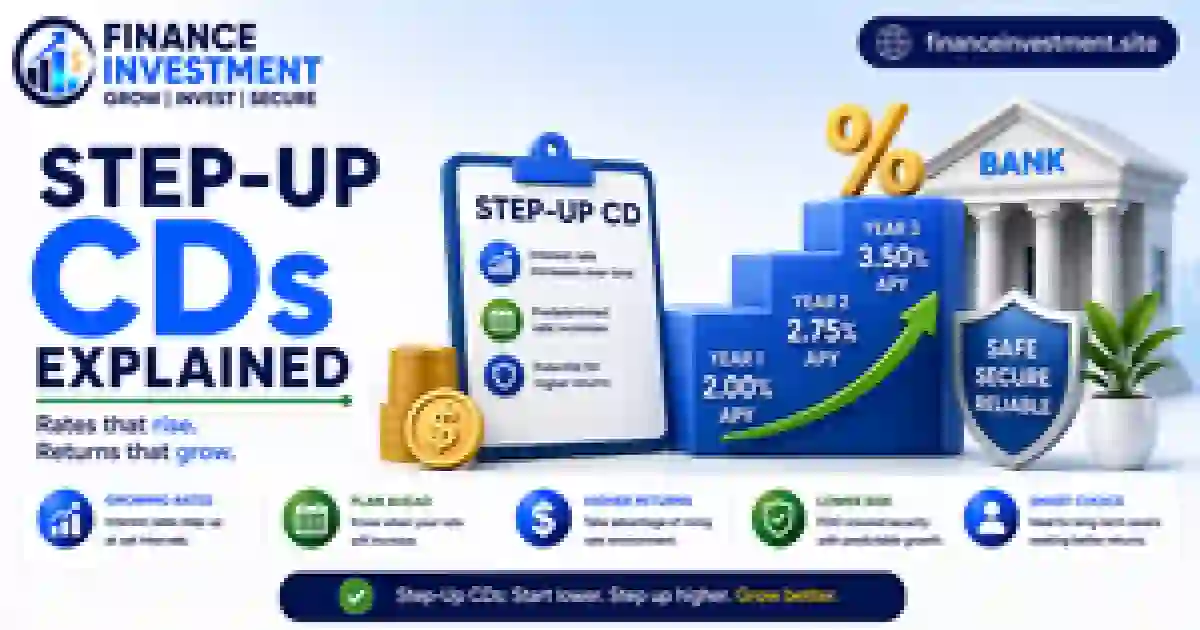
 A Step-Up CD works much like a traditional certificate of deposit: you place money with a bank or credit union for a set period and earn interest in return. The key difference is the rate structure. Instead of keeping one interest rate for the entire term, a Step-Up CD has predetermined rate increases that take effect at specific times.