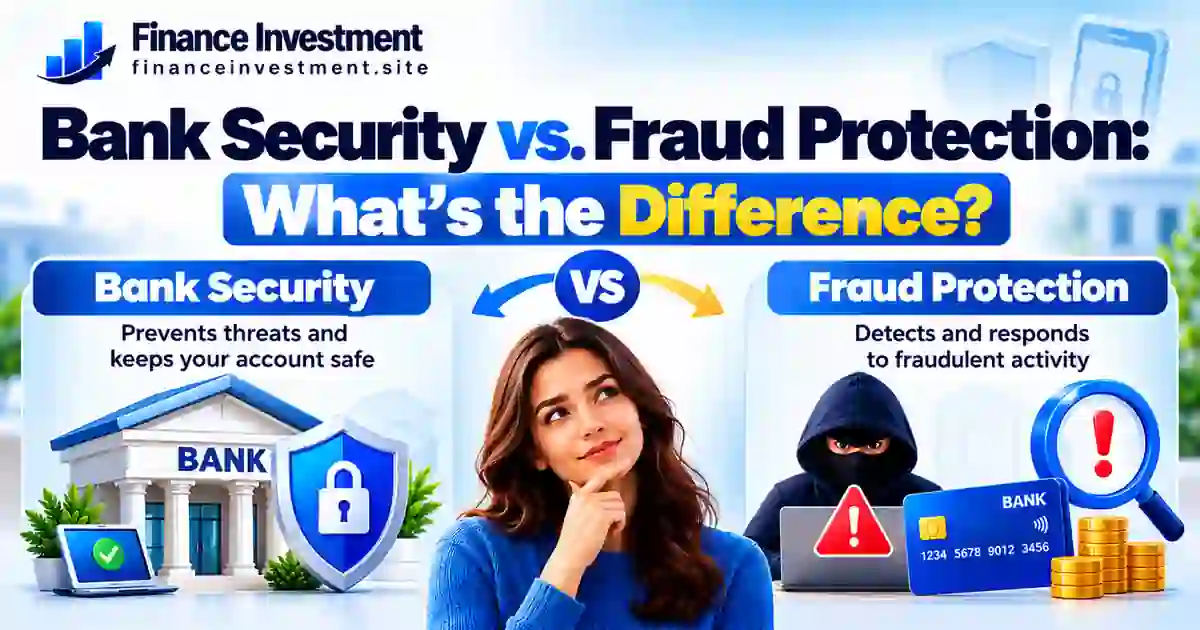
Bank Security vs. Fraud Protection: What’s the Difference?
*Confirm the reading time after the full article is complete.
Bank Security vs. Fraud Protection: Why the Difference Matters 
Understanding bank security vs. fraud protection starts with a simple distinction: bank security helps protect your account, information, and access to banking services, while fraud protection focuses on identifying suspicious activity, limiting potential losses, and responding to suspected fraud.
For example, a strong password and multifactor authentication can make unauthorized account access harder. Transaction monitoring and alerts may help flag unusual activity. These safeguards work together, but none can guarantee that every scam will be stopped or that every loss will be reimbursed.
That difference matters when you choose a bank or credit union, review account features, or decide what to do after receiving a suspicious message. Start with our Bank Security & Fraud Prevention Guide for a broader look at protecting your financial accounts.
What You’ll Learn
- How bank security differs from fraud protection.
- How authentication, account alerts, and transaction monitoring can help.
- What these safeguards can do—and what they cannot guarantee.
- Which protection features to compare when choosing a bank or credit union.
- What steps to take if you notice an unfamiliar transaction or suspect a scam.
Quick Answer: What’s the Difference?
Bank security refers to the safeguards that help protect banking systems, personal information, and account access. Fraud protection focuses on identifying suspicious activity, blocking or limiting potential fraud, and helping customers report and resolve incidents. The two overlap: a single tool, such as multifactor authentication or transaction monitoring, may support both. Neither guarantees that every scam will be stopped or every loss reimbursed.
Key Takeaways
- Use unique passwords and multifactor authentication when available to help secure account access.
- Enable transaction alerts and review account activity to spot unfamiliar payments sooner.
- Check both a bank’s security features and its process for reporting suspected fraud.
- Your rights and possible reimbursement depend on the transaction, applicable protections, and reporting deadlines.
- Banks and credit unions may offer different security tools, alert options, and support processes, so compare the specific features.
- Contact your financial institution promptly through a verified channel if you notice suspicious activity.
Bottom line: Don’t judge an account by a “fraud protection” label alone. Check how access is secured, how suspicious transactions are handled, and what steps you must take if a problem occurs.
In This Guide
Bank Security vs. Fraud Protection at a Glance
Bank security and fraud protection work together, so their features can overlap. The main difference is their purpose: security safeguards banking systems, information, and account access, while fraud protection focuses on recognizing suspicious activity, limiting potential losses, and responding to suspected fraud.
Bank Security
Safeguard accounts and information
Common measures include secure sign-in, encryption, multifactor authentication, access controls, and device verification.
Fraud Protection
Identify and respond to fraud
Measures may include suspicious-transaction monitoring, alerts, card controls, transaction reviews, and dispute procedures.
Quick Comparison
| Comparison | Bank Security | Fraud Protection |
|---|---|---|
| Primary focus | Secure systems, information, and access | Detect, limit, and respond to suspected fraud |
| Typical measures | Authentication, encryption, access controls | Monitoring, alerts, card controls, dispute handling |
| Your role | Protect credentials and devices | Review activity and report suspicious transactions promptly |
| Important limit | Cannot eliminate every security threat | Cannot guarantee that every loss will be recovered |
What to look for: When comparing banks or credit unions, check available sign-in protections, account alerts, card-locking options, and the procedure for reporting and disputing suspicious transactions. Features and policies vary by institution.
Bank Security vs. Fraud Protection: A Beginner’s Guide
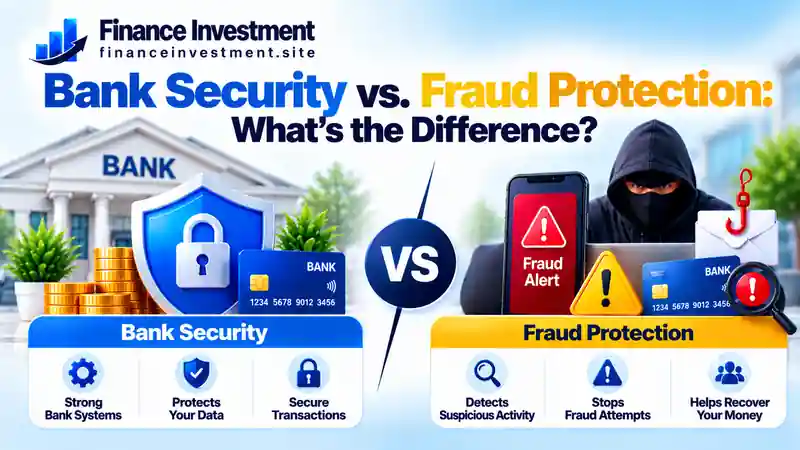
Bank security and fraud protection work toward the same goal: safer banking. The difference lies in their primary focus. Security safeguards help protect systems, information, and account access. Fraud protection focuses on identifying suspicious activity, limiting potential losses, and handling suspected fraud. In practice, many tools support both.
1. What Does Bank Security Include?
Bank security includes the technology and procedures financial institutions use to protect banking systems and customer information. Some safeguards operate behind the scenes, while others are features customers use directly.
- Authentication: Passwords and multifactor authentication help verify who is attempting to sign in.
- Data protection: Encryption and access controls help prevent unauthorized access to sensitive information.
- Device and sign-in checks: Some banks assess unfamiliar devices or unusual login patterns.
- Internal controls: Procedures help restrict access to banking systems and customer records.
Example: If someone steals your password, multifactor authentication may add another barrier to account access. However, the level of protection depends on the verification method and whether the attacker can compromise it.
2. What Does Fraud Protection Include?
Fraud protection covers measures designed to prevent, detect, limit, or respond to fraudulent activity. The tools and procedures available vary by financial institution, account, and transaction type.
- Transaction monitoring: Systems may flag payments or account activity that appear unusual.
- Alerts and card controls: Notifications and card-locking features may help customers respond to suspicious activity.
- Reporting and investigation: Banks provide procedures for reporting suspected fraud and disputing transactions.
- Account recovery: Depending on the incident, customers may need to secure access, replace a card, or change compromised credentials.
3. How Do the Two Overlap?
The categories are connected. Multifactor authentication may help prevent unauthorized access, while transaction monitoring may identify activity that suggests an account has been compromised. Both can contribute to a financial institution’s broader security and fraud-control program.
For example, a criminal might obtain login details through a fake banking message. Account security measures may make access harder, while monitoring systems may flag an unusual transaction. Neither response is guaranteed, so customers should also verify unexpected requests and report suspicious activity promptly.
Before choosing an account: Check available sign-in protections, customizable alerts, card controls, and the procedure for reporting suspected fraud. Banks and credit unions can differ in their features and service policies. Our guide to whether credit unions are safe can help you explore that decision.
How Bank Security and Fraud Protection Work
Bank security and fraud protection can work together to reduce banking risks. Their exact operation varies by institution, account type, and transaction method. Some controls operate when you sign in, while others monitor activity or help the bank respond to a reported problem.
Protect Account Access
Passwords, multifactor authentication, and other verification checks may help prevent unauthorized people from accessing an account.
Monitor Transactions
Available monitoring systems may flag unusual payments or other activity for review. Not every suspicious transaction will be detected or blocked.
Report and Respond
If fraud is suspected, the bank may investigate, restrict certain activity, or explain how to dispute a transaction and secure the account.
Example: You Notice an Unauthorized Transfer
Imagine you check your checking account and discover a transfer you did not authorize. Your bank may already have flagged the activity, but it is also possible that its systems did not detect it. Contact the bank promptly through its official app, website, or the phone number on your card. Report the transfer, ask how to secure your account, and follow the bank’s instructions for submitting a dispute.
Keep records of the transaction, your report, and any confirmation number. Reporting deadlines and legal protections can depend on the type of transfer and the circumstances, so do not delay while waiting for an alert or further investigation.
Know your rights: The CFPB’s electronic fund transfer FAQs explain key rules related to electronic transfers. Review the guidance relevant to your situation, and contact your financial institution promptly if you suspect an unauthorized transaction.
Benefits and Drawbacks of Bank Security vs. Fraud Protection
Bank security and fraud protection work together, but each addresses different risks. Knowing their benefits and limitations helps you make informed decisions about your checking, savings, and online banking accounts.
Key Benefits
- Safer account access: Authentication and access controls can make unauthorized logins harder.
- Suspicious activity alerts: Monitoring tools may help identify unusual transactions sooner.
- Support after suspected fraud: Reporting channels may help you secure your account and begin an investigation.
Key Drawbacks
- Not foolproof: Some scams and unauthorized transactions may escape detection.
- Possible inconvenience: Extra verification or false alerts can interrupt legitimate banking activity.
- Action is still required: You must protect your credentials, review account activity, and report suspected fraud promptly.
Bottom line: Neither protection approach eliminates every risk or guarantees reimbursement. Look for a financial institution with clear security practices, useful account alerts, and accessible fraud-reporting support. For more practical steps, read our complete bank security and fraud prevention guide.
Bank Security vs. Fraud Protection: Detailed Comparison
Bank security helps protect account access, information, and banking systems. Fraud protection focuses on identifying suspicious activity and responding to potential financial fraud. These functions overlap, so a bank may use the same technology to support both.
| Comparison | Bank Security | Fraud Protection |
|---|---|---|
| Primary goal | Protect systems, sensitive data, and account access. | Help detect, prevent, or respond to suspected fraud. |
| Common measures | Authentication, encryption, access controls, and system monitoring. | Transaction monitoring, alerts, card controls, and fraud investigations. |
| Main risks addressed | Unauthorized access, compromised credentials, and data exposure. | Suspicious transactions, unauthorized transfers, and certain deceptive schemes. |
| Your responsibility | Use strong, unique passwords and enable available security features. | Review transactions and promptly report suspected unauthorized activity. |
| Important limitation | Cannot eliminate every cyberattack or account compromise. | May not catch every scam, stop every payment, or guarantee reimbursement. |
What should you compare? Look at both account-security features and the institution’s process for reporting and investigating suspected fraud. Also review available alerts, account controls, customer support, and applicable consumer protections. Neither category alone tells you how well every possible risk will be handled.
Costs, Risks, and Expert Tips for Better Bank Protection
Many banks include basic account-security features and certain fraud-monitoring services at no extra charge. However, fees, features, and eligibility vary. Optional identity-monitoring products, premium account services, or other add-ons may cost extra. Check your bank’s current fee schedule before paying for additional protection.
Risks Every Account Holder Should Know
- Phishing scams: Fake emails, texts, or calls may pressure you to reveal passwords, verification codes, or financial details.
- Missed alerts: Monitoring systems may not identify every suspicious transaction, so check your account even when no alert arrives.
- Limited recovery options: Disputes and reimbursement depend on the transaction type, applicable law, and specific circumstances.
Four Practical Ways to Improve Protection
- Create a unique password and enable multifactor authentication when available.
- Set up transaction alerts and review recent activity regularly.
- Never share passwords or one-time verification codes with unexpected callers or message senders.
- Report suspected unauthorized transactions promptly through your bank’s official app, website, or verified phone number.
Expert tip: Do not assume that every payment has the same legal protections. Regulation E covers certain electronic fund transfers, subject to its scope and requirements. Reporting deadlines can affect your rights. Read the CFPB’s electronic fund transfer FAQs and contact your financial institution promptly if you notice a transaction you did not authorize.
Common Bank Security Mistakes and a Realistic Example
Even with bank security controls and fraud-monitoring tools, everyday mistakes can expose your account to avoidable risks. Watch out for these common problems:
- Reusing passwords: If another website exposes a reused password, criminals may try it on your banking account.
- Ignoring alerts: An unfamiliar transaction deserves attention, even if the amount is small.
- Trusting unexpected messages: Scammers may impersonate bank employees and request passwords, verification codes, or urgent payments.
- Delaying a report: Waiting to report a suspected unauthorized transfer may affect your available options and, in some cases, your legal protections.
Realistic Example: A Suspicious Bank Text
Imagine receiving a text claiming your checking account will be locked unless you verify your details immediately. The message links to a fake website that looks like your bank’s login page. You enter your username and password, unknowingly sharing them with a scammer.
Your bank may detect unusual activity, but you should not wait for an alert. Contact the bank through its official app or the verified number on your card. Tell the bank what happened, change your compromised password using the legitimate website or app, and secure any other account that used the same password. Review recent transactions and promptly report anything you did not authorize.
Remember: Never use a suspicious message’s link to verify your banking details. If you suspect fraud, act promptly. For more warning signs, read our guide to spotting checking account fraud.
Who Needs Bank Security and Fraud Protection?
Both bank security and fraud protection matter to anyone who holds a checking, savings, or other bank account. The most useful features depend on how you manage money and the risks you want to address.
- Banking beginners: Learn to recognize suspicious messages, use unique passwords, and review transactions regularly.
- Families: Review joint-account access, protect shared login details, and enable suitable transaction alerts.
- Retirees: Consider convenient alerts, secure account access, and clear procedures for reporting unfamiliar transactions.
- Frequent online banking users: Enable multifactor authentication when available and check account activity after important transactions.
- Small-business owners: Use separate business accounts where appropriate, limit employee permissions, and establish clear payment-approval procedures.
How to choose: Compare available security features, transaction alerts, customer-support access, and procedures for reporting suspected fraud. If you’re deciding where to bank, read our guide to online banks vs. traditional banks to understand the differences.
Bank Security vs. Fraud Protection: Frequently Asked Questions
1. What is the difference between bank security and fraud protection?
Bank security protects banking systems, sensitive information, and account access. Fraud protection focuses on detecting suspicious activity and responding to potential fraud. The two often use overlapping tools.
2. Does bank security prevent all fraud?
No. Security controls can reduce certain risks, but scammers may still exploit stolen credentials, deceptive messages, or other weaknesses. Regular account reviews remain important.
3. Can banks automatically detect suspicious transactions?
Many financial institutions use automated systems to flag unusual activity. However, detection methods vary, and some suspicious transactions may not trigger an alert or immediate block.
4. Is fraud protection included with a bank account?
Basic security and monitoring features may be included, depending on the institution and account. Optional identity-monitoring services or premium features may cost extra. Check the account terms and fee schedule.
5. What should I do if I notice an unauthorized transaction?
Contact your bank promptly through an official channel. Report the transaction, ask how to secure your account, and follow the bank’s dispute process. Keep records of your report and any confirmation number.
6. Will my bank reimburse every fraudulent transaction?
No, reimbursement is not guaranteed in every situation. Legal protections depend on the payment type, circumstances, and reporting requirements. Regulation E covers certain electronic fund transfers, including qualifying unauthorized transfers, subject to applicable rules.
7. Are online banks safe to use?
Online banks can offer safeguards such as multifactor authentication, account alerts, and transaction monitoring. Check the institution’s legitimacy, security features, customer support, and applicable deposit insurance. FDIC insurance protects eligible deposits if an insured bank fails; it does not cover losses from theft or fraud.
8. What is the easiest way to improve bank security?
Use a unique password, enable multifactor authentication when available, turn on transaction alerts, avoid suspicious links, and review account activity regularly. Report suspected unauthorized transactions promptly.
Official resources: Read the CFPB’s electronic fund transfer FAQs for information about certain transfer protections, and the FDIC’s deposit insurance guide to understand what deposit insurance covers.
Final Verdict: Bank Security vs. Fraud Protection
Bank security and fraud protection work best together. One helps safeguard account access and sensitive information, while the other helps identify and address suspicious activity. Neither can eliminate every risk, so your own banking habits matter too.
When comparing banks or credit unions, look beyond advertised features. Check available account alerts, authentication options, customer-support access, and the process for reporting unauthorized transactions.
Our recommendation: Choose an institution with clear security practices and accessible fraud-reporting support. Use unique passwords, enable multifactor authentication when available, review transactions regularly, and report suspicious activity promptly.
The bottom line: Do not rely on a single security feature. Combining your bank’s safeguards with consistent personal precautions is a more practical way to manage everyday banking risks.
Have a Money Question? Keep Exploring.
Understanding bank security and fraud protection is an important step toward safer everyday banking. Keep learning, review your account regularly, and use the security features available through your financial institution.
Contact FinanceInvestment
Have a finance-related question or feedback about our content? Send us an email.
Continue Your Research
Explore practical steps for protecting your bank account and personal information.
Learn to recognize suspicious transactions and warning signs that deserve attention.