ACH Transfer vs. Wire Transfer: Which Is Right for You? 
When you need to move money between bank accounts, choosing an ACH transfer vs. wire transfer can affect how much you pay, when the money arrives, and how easily a mistake can be corrected. The best option depends on your deadline, payment amount, and the type of transaction.
ACH transfers are commonly used for direct deposits, recurring bills, and routine bank-to-bank payments. Wire transfers are often chosen for time-sensitive or high-value payments, including some home closings and international transactions. However, a wire is not automatically instant, and it usually costs more. Bank cutoff times, processing schedules, verification checks, and intermediary banks can all affect delivery.
Before sending money, it helps to understand how each method works and what happens if you enter the wrong details. Our complete guide to bank transfers and payments covers the broader picture; this article focuses on choosing between ACH and wire transfers.
What You’ll Learn
- How ACH and wire transfers work.
- Typical processing times, fees, and transfer limits.
- How domestic transfers differ from international wires.
- Ways to reduce delays and avoid costly transfer scams.
- When ACH is practical—and when a wire transfer may be worth the extra cost.
Quick Answer: ACH Transfer vs. Wire Transfer
An ACH transfer is usually a cost-effective choice for direct deposits, recurring bills, and routine bank-to-bank payments. A wire transfer may be better when a payment is time-sensitive, high-value, or specifically requires a wire. Standard ACH transfers commonly take one to three business days, although timing varies by bank and payment schedule. Eligible same-day ACH payments may arrive sooner if deadlines are met. Domestic wires may be completed the same business day when submitted before the bank’s cutoff, while international wires can take several business days or longer.
Key Takeaways
- Fees: ACH transfers are often free or inexpensive, while wire transfers commonly have sending, receiving, or intermediary fees.
- Processing time: Wires can be faster for domestic payments, but cutoff times, verification checks, and receiving-bank procedures can affect delivery.
- Best use: ACH works well for routine payments; wires may suit urgent transactions such as certain real estate closings.
- Risk: Check the recipient’s details carefully. A bank may attempt to recall a mistaken or fraudulent wire, but recovery is not guaranteed once it has been processed.
The Bottom Line
Choose ACH when lower cost and convenience are priorities and the payment can follow the ACH processing schedule. Consider a wire when the deadline or recipient’s instructions justify the fee. Before authorizing either transfer, confirm the total cost, expected arrival time, and payment details directly with your bank or a trusted recipient contact.
Table of Contents
Jump to the section you need to compare ACH and wire transfer costs, speed, safety, and use cases.
ACH vs. Wire Transfer at a Glance
QUICK TAKE: ACH is generally a cost-effective choice for routine U.S. payments. A wire transfer may be more suitable when a payment is time-sensitive, high-value, or the recipient specifically requires a wire.
| Feature | ACH Transfer | Wire Transfer |
|---|---|---|
| Typical speed | Often 1–3 business days; eligible payments may qualify for same-day ACH | Domestic wires may be processed the same business day if deadlines are met |
| Typical cost | Often free or low-cost, depending on the bank and transfer type | Sending, receiving, or intermediary fees may apply |
| Common uses | Payroll, recurring bills, and routine account transfers | Urgent payments, some real estate closings, and high-value transactions |
| International payments | Primarily used within the U.S. ACH network | Commonly used for cross-border bank payments |
| Mistakes and recovery | Returns or reversals may be available only under applicable rules | A recall may be requested, but recovery is not guaranteed |
These are general comparisons, not guarantees. Actual timing, fees, limits, and eligibility depend on the bank, transfer type, cutoff time, and receiving institution. Confirm the details with your financial institution before sending money.
ACH Transfers and Wire Transfers Explained 
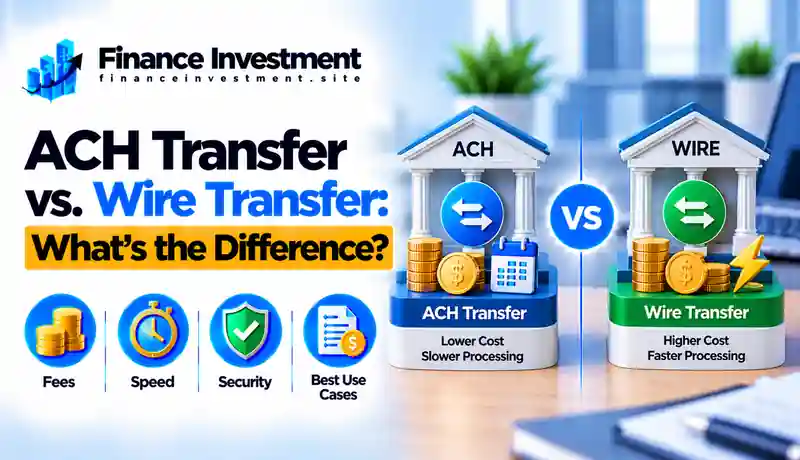
ACH transfers and wire transfers both move money electronically, but they use different payment networks and processing methods. Understanding that difference helps you choose a transfer based on its cost, urgency, and purpose.
What Is an ACH Transfer?
An Automated Clearing House (ACH) transfer moves money through the U.S. ACH network, which processes payments in batches. ACH is widely used for employee direct deposits, mortgage payments, utility bills, and transfers between eligible U.S. bank accounts.
ACH payments can be credits, which deposit money into an account, or debits, which collect money after the required authorization. Standard ACH transfers commonly take one to three business days, although eligible payments may qualify for same-day processing. Actual timing depends on the payment schedule, bank cutoff times, and the institutions involved.
What Is a Wire Transfer?
A wire transfer moves funds electronically between financial institutions through a wire payment system. In the United States, Fedwire Funds Service is one system used for domestic wire payments; other arrangements may also be used. Domestic wires can often be processed the same business day when submitted before the bank’s cutoff, but processing is not guaranteed to be immediate.
International wires may involve intermediary banks, additional fees, and currency conversion, so delivery can take several business days or longer. Wire transfers also tend to be more expensive than routine ACH payments, and recovering funds sent to the wrong recipient may be difficult.
Remember: ACH is often a practical choice for routine payments. A wire may make sense when timing, transaction requirements, or the recipient’s instructions justify the cost. Before sending either type, verify the recipient and transfer details using a trusted method.
ACH vs. Wire Transfer: Detailed Comparison
ACH and wire transfers both move money electronically, but they differ in processing, cost, and typical use. Compare these features before choosing a payment method.
| Feature | ACH Transfer | Wire Transfer |
|---|---|---|
| Typical speed | Often 1–3 business days; eligible payments may qualify for same-day ACH | Domestic wires may be processed the same business day if bank deadlines are met |
| Cost | Often free or low-cost, depending on the bank and transfer type | Sending, receiving, intermediary, or currency-conversion fees may apply |
| Transfer limits | Depend on the bank, account, transfer channel, and payment type | Depend on the institution, account, and verification requirements |
| Common uses | Payroll, recurring bills, and routine account transfers | Urgent payments, certain home closings, and high-value transactions |
| International payments | The U.S. ACH network primarily serves U.S. bank accounts; international options depend on the provider and arrangement | Commonly used for cross-border bank payments, subject to destination and bank requirements |
| Recurring payments | Well suited to scheduled deposits and payments | Often less economical for routine payments because fees may apply |
| Payment errors | Returns or reversals depend on the reason, timing, and applicable rules | A recall can be requested, but recovery is not guaranteed |
These are general comparisons, not guarantees. Actual fees, limits, and arrival times vary by institution, transfer channel, cutoff time, and transaction details.
Decision tip: If ACH is accepted and the payment is not urgent, it is often the lower-cost choice. If a wire is required or timing is critical, confirm the total fee, cutoff time, recipient details, and expected delivery with your bank before authorizing it.
ACH Transfer vs. Wire Transfer: Costs, Risks & Expert Tips
Check the Total Transfer Cost
ACH transfers are often free or inexpensive for routine consumer payments. Wire transfers may involve an outgoing fee, a receiving fee, intermediary-bank charges, or currency-conversion costs for international payments. Before submitting a transfer, review your bank’s current fee schedule, exchange rate, transfer limits, and expected delivery time. For international payments, compare the amount the recipient is expected to receive—not just the advertised fee.
Understand the Risks
Both payment methods can be affected by incorrect details, unauthorized transactions, or scams. A completed wire can be difficult to recover, particularly if the money reaches a scammer. ACH returns and reversals are available only in certain circumstances under applicable rules; they are not a general cancellation option.
Expert Tips Before Sending Money
- Confirm the recipient’s name, account number, and required routing or banking details.
- For a wire, verify instructions through a trusted phone number you already know. Be especially cautious with home-closing payments and last-minute changes sent by email.
- Check bank cutoff times, fees, delivery estimates, and transaction limits before authorizing payment.
- Save your confirmation. If you notice an error or suspect fraud, contact your bank immediately and ask whether the payment can be stopped, recalled, or investigated.
Smart rule: Choose ACH when it meets your deadline at a lower cost. Use a wire when the transaction or recipient requires it, and independently verify the payment details before sending.
Common ACH and Wire Transfer Mistakes to Avoid
- Assuming a wire is always faster: Domestic wires may arrive the same business day, but bank cutoff times, verification, and receiving-bank procedures can affect delivery.
- Overlooking the total cost: Check applicable sending, receiving, intermediary, and currency-conversion fees before authorizing the transfer.
- Entering incorrect details: Carefully verify the recipient’s name, account information, and required routing or banking codes.
- Trusting changed payment instructions: If emailed instructions change unexpectedly, contact the recipient using a trusted phone number you already have—not a number supplied in the suspicious message.
- Expecting guaranteed recovery: ACH returns and wire recalls have different rules and limitations. Neither guarantees that funds can be recovered.
Real-Life Example: Sending a Home-Closing Deposit
Imagine a homebuyer needs to send a $15,000 deposit to a closing company by a specified deadline. The closing company requires a wire, so the buyer checks the bank’s cutoff time, confirms the fee, and independently verifies the recipient’s payment instructions using a previously trusted phone number. These steps help reduce the risk of sending the money to a fraudulent account.
For a routine monthly utility bill, the same buyer might choose ACH if the provider accepts it and the payment schedule allows enough processing time. The buyer can compare the available options without paying for a wire when one is unnecessary.
Key lesson: Choose the transfer method that fits the deadline and recipient’s requirements. Verify payment details independently, and if a transfer appears mistaken or fraudulent, contact your bank immediately to ask what action is still possible.
Who Should Choose an ACH Transfer vs. a Wire Transfer?
ACH May Be Better for Everyday Payments
Consider ACH if you receive direct deposits, pay recurring bills, or transfer money between eligible U.S. bank accounts. It is often a cost-effective choice when the recipient accepts ACH and the processing schedule, transfer limits, and payment date fit your needs. Eligible same-day ACH may be an option when supported by your bank and payment type.
A Wire May Be Better for Time-Sensitive or Required Payments
Consider a wire when the recipient specifically requires one, a transaction has a tight deadline, or you need to send funds through an international banking arrangement. Before proceeding, confirm the bank’s cutoff time, total fees, transfer limits, and expected delivery. A wire may still be delayed by verification checks or receiving and intermediary banks.
Simple decision rule: First check which payment methods the recipient accepts. If ACH meets the deadline and requirements, compare its cost. If a wire is required or better fits the transaction, independently verify the instructions and confirm the fee before authorizing it.
Frequently Asked Questions About ACH and Wire Transfers
1. Is an ACH transfer faster than a wire transfer?
Usually not for urgent domestic payments. Standard ACH transfers often take one to three business days, while domestic wires may be processed the same business day. Cutoff times, bank reviews, and receiving-bank procedures affect delivery.
2. Is ACH cheaper than a wire transfer?
Often, yes. ACH payments are frequently free or low-cost for consumers, while wires may carry sending, receiving, or intermediary fees. Check your bank’s current fees before choosing.
3. Can an ACH transfer arrive the same day?
Yes. Eligible payments may qualify for same-day ACH when the payment type, bank, and submission timing meet the applicable requirements. Same-day processing is not available for every transaction.
4. Can a wire transfer be canceled or reversed?
A bank may be able to request a wire recall, but a completed transfer may be difficult to recover. Contact your bank immediately if you suspect an error or fraud; recovery is not guaranteed.
5. Are ACH transfers safe?
ACH is widely used for legitimate bank payments, but unauthorized transactions and scams can still occur. Use trusted payment channels, protect your banking credentials, and review account activity regularly.
6. Can ACH be used for international transfers?
The U.S. ACH network primarily handles payments involving U.S. bank accounts. Some providers offer separate international payment services, so availability depends on the provider, destination, and transfer arrangement.
7. Should I use ACH or a wire for a home closing?
Follow the closing professional’s verified payment instructions. If a wire is required, confirm the recipient and instructions using a trusted phone number you already have before sending funds.
8. Do ACH transfers and wire transfers have limits?
Yes. Limits vary by bank, account type, transfer channel, and transaction. Ask your financial institution about applicable limits and any additional verification needed for a large payment.
Final Verdict: ACH Transfer vs. Wire Transfer
The best choice in an ACH transfer vs. wire transfer comparison depends on your deadline, total cost, and the recipient’s requirements. ACH is often a practical option for direct deposits, recurring bills, and routine transfers between eligible U.S. bank accounts. If the payment can follow the ACH processing schedule, you may avoid paying a wire transfer fee.
A wire transfer may be more suitable when the recipient requires one or a transaction has a firm deadline, such as certain real estate closings. However, fees may be higher, bank cutoff times and verification can affect delivery, and recovering a completed wire sent to the wrong account may be difficult.
Our recommendation: Check which payment methods the recipient accepts first. If ACH meets the deadline, compare its cost and processing time. If a wire is necessary, confirm the total fees, expected delivery, and recipient details independently before authorizing payment.
For a broader overview of payment methods, read our complete guide to bank transfers and payments to explore the options available for different banking needs.
Make Your Next Bank Transfer With Confidence
Before sending money, compare the total fees, confirm the expected arrival time, and independently verify the recipient’s payment instructions. A few checks can help you avoid unnecessary costs and reduce preventable transfer mistakes.
Written by Subhash Rukade, Founder of FinanceInvestment.
Disclaimer
This article is for general educational purposes only and does not constitute financial, legal, or tax advice. Transfer fees, processing times, eligibility, and bank policies vary and may change. Verify current terms directly with your financial institution before authorizing a payment.
Leave a Reply