✓ Editorial Reviewed , Subhash Rukade.
FinanceInvestment Editorial Team
Independent personal finance researchers creating practical, beginner-friendly money guides for Americans using trusted sources and real-world financial best practices.
FinanceInvestment Team
July 29, 2026
14–16 Min
Savings Buckets Explained: A Simple Way to Organize Your Money in 2026
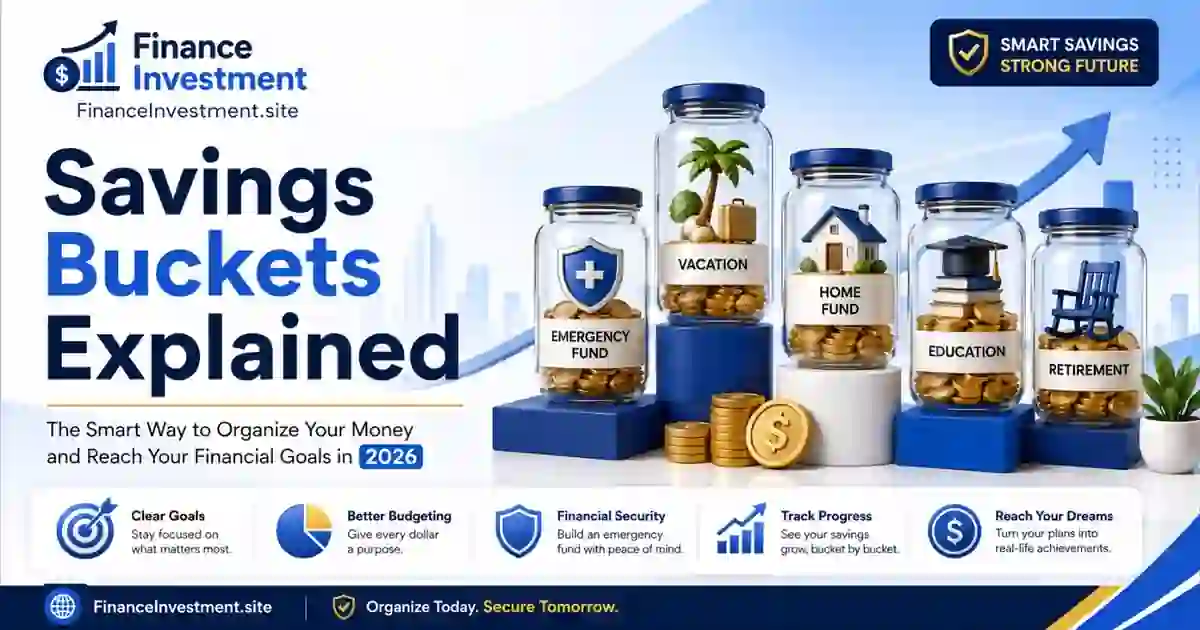 Saving money is easier when every dollar has a purpose. Instead of keeping all your cash in one account and hoping it lasts, many Americans now divide their savings into separate “buckets” for specific goals. This simple system makes budgeting clearer, reduces unnecessary spending, and helps you stay on track for both short-term and long-term financial plans. In this guide, you’ll learn Savings Buckets Explained in plain English, so you can start using the strategy with confidence.
Whether you’re building an emergency fund, planning a vacation, saving for a new car, or preparing for retirement, savings buckets help you see exactly where your money is going. The best part is that you don’t need a complicated budgeting app or multiple bank accounts to get started.
What You’ll Learn
- What savings buckets are and why they work.
- How to organize money for multiple financial goals.
- Common mistakes to avoid.
- Tips for choosing the right savings account.
- How this strategy can help you build financial confidence.
If you’re also looking for the best place to keep your savings, don’t miss our complete guide on High-Yield Savings Accounts USA, where you’ll learn how to earn more interest while keeping your money safe.
Quick Answer
Savings Buckets Explained is a money management method that divides your savings into separate categories based on your financial goals. Instead of keeping every dollar in one general savings account, you assign money to specific purposes such as an emergency fund, vacation, home repairs, holiday shopping, or retirement. This simple approach helps you stay organized, spend with confidence, and avoid dipping into money meant for other goals.
Many online banks make this process even easier by allowing you to create multiple savings buckets inside a single account. Combined with a high-yield savings account, this strategy can also help your money earn more interest while remaining accessible when you need it.
Key Takeaways
- Create separate buckets for different financial goals instead of mixing all your savings together.
- Knowing exactly what each dollar is meant for can reduce impulse spending.
- Even small monthly deposits become easier to track and manage.
- High-yield savings accounts can help your buckets grow faster through higher interest.
- This strategy works well for beginners, families, and retirees alike.
- Review your buckets regularly and adjust them as your priorities change.
Bottom Line: Savings buckets don’t require complicated budgeting tools or financial expertise. They simply give every dollar a clear job, making it easier to reach your goals while building healthier money habits over time.
Table of Contents
At a Glance
If you’ve ever wondered where your money disappeared at the end of the month, a savings bucket system can help. Instead of treating all your savings as one big balance, you divide it into smaller buckets, with each one assigned to a specific goal. This simple habit makes saving feel more organized and helps you avoid using money meant for future plans.
One bucket might cover unexpected expenses, another could be for vacations, while a third helps you save for holiday shopping or a home down payment. As your priorities change, you can adjust or add new buckets without changing your overall savings strategy.
Quick Tip: Start with three buckets—an emergency fund, short-term goals, and long-term savings. Once this becomes a habit, you can create additional buckets for travel, holidays, home repairs, or other personal goals without making your finances feel complicated.
Complete Beginner Guide to Savings Buckets
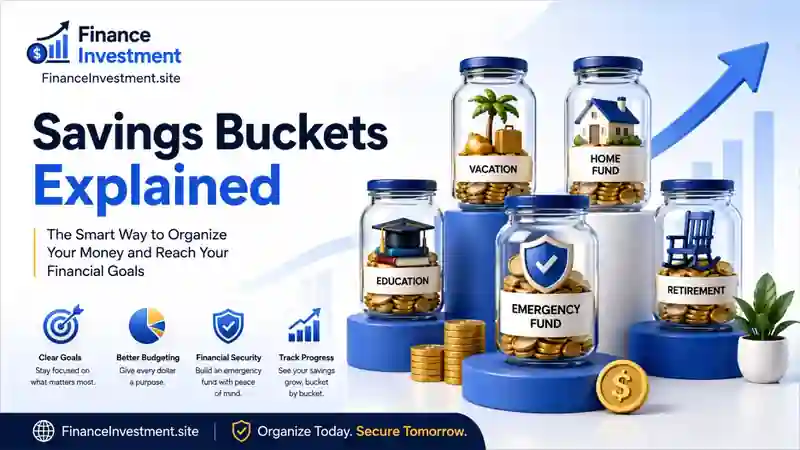 When people first hear about savings buckets, they often assume they need several bank accounts or a complicated budgeting system. In reality, it’s much simpler. A savings bucket is just a way to give every dollar a specific purpose before you spend it.Savings Buckets Explained Instead of looking at one large savings balance, you divide your money into smaller categories that match your financial goals.
Think about how most people save. They deposit money into one account and hope there’s enough left when a vacation, car repair, or holiday shopping season arrives. The problem is that all those goals compete for the same money.Savings Buckets Explained Without realizing it, you may spend funds that were meant for something more important.
Savings buckets solve this problem by creating clear boundaries. For example, you could have one bucket for emergencies, another for annual bills, one for travel, and another for future investments. Every deposit has a destination, making it easier to stay organized and avoid financial surprises.
Start with Your Most Important Goals
You don’t need ten buckets on day one. Most beginners do well with three to five categories. Start by identifying the goals that matter most over the next year. Your first bucket should usually be an emergency fund because unexpected expenses can happen at any time.Savings Buckets Explained After that, create buckets for goals like vacations, home maintenance, holiday gifts, education, or a future down payment.
Many online banks now let you create virtual savings buckets within a single account, making it easy to track progress without opening multiple accounts. If you’re comparing banking options, our guide on Online Banks vs. Traditional Banks explains which choice may fit your needs best.
Automate Your Savings
One of the easiest ways to stay consistent is to automate your deposits. As soon as your paycheck arrives, schedule automatic transfers into each bucket. Even modest contributions can build meaningful savings over time because consistency often matters more than the amount you save each month.
Choosing the right account also makes a difference. A high-yield savings account can help your money earn more interest while remaining easily accessible. If you’re unsure how these accounts work, read our guide on APY vs. Interest Rate Explained to understand how your savings can grow faster.
Review and Adjust Regularly
Your financial goals won’t stay the same forever, and your savings buckets shouldn’t either. Set aside a few minutes every month to review your progress. If one goal has been reached, simply redirect those contributions to your next priority. This flexibility is one of the biggest reasons the savings bucket method continues to work for students, growing families, and retirees alike.
Expert Tip: Name each bucket after a real goal instead of using generic labels like “Savings.” Seeing names such as “Emergency Fund,” “New Car,” or “Summer Vacation” creates a stronger connection to your goals and can make it easier to stay motivated every time you save.
How Savings Buckets Work
The idea behind savings buckets is simple: every dollar you save should have a purpose before you need it.Savings Buckets Explained Instead of keeping one large balance and trying to remember what it’s for, you divide your savings into separate categories. Each bucket represents a specific financial goal, making it much easier to stay organized and make confident spending decisions.
You can create savings buckets using multiple savings accounts, virtual buckets offered by many online banks, or even a budgeting app. The method you choose matters less than building the habit of saving consistently.
Step 1: List Your Financial Goals
Start by writing down the reasons you’re saving money. Include both short-term and long-term goals.Savings Buckets Explained Your list might include an emergency fund, annual insurance premiums, holiday shopping, a family vacation, a home down payment, or retirement savings. Once your goals are clear, it’s easier to decide where each dollar belongs.
Step 2: Create a Bucket for Each Goal
Give every goal its own bucket. For example, you could have one bucket for unexpected expenses, another for travel, one for home maintenance, and another for future investments. Separating your savings this way helps prevent you from accidentally spending money that was meant for something else.
Step 3: Add Money Automatically
After each paycheck, transfer a fixed amount into every bucket. Automatic deposits remove the need to remember each month and help turn saving into a routine instead of a decision.Savings Buckets Explained Even small, regular contributions can make a noticeable difference over time.
If you’re opening a new account for this strategy, our guide on How to Open a High-Yield Savings Account walks you through the process step by step.
Step 4: Track Your Progress
Check your buckets once a month to see how close you are to each goal. If you’ve fully funded one bucket, redirect those monthly deposits to your next priority. This keeps your savings working toward the goals that matter most without increasing your monthly budget.
Example: Imagine your monthly savings budget is $500. You might place $250 into your emergency fund, $100 toward a vacation, $75 for home repairs, and $75 for holiday shopping. Every dollar has a clear purpose, so you’re less likely to borrow from one goal to pay for another.
Remember: Savings buckets aren’t about opening as many accounts as possible. They’re about creating a simple system that helps you stay focused, reduce financial stress, and make steady progress toward the goals that matter most.
Benefits & Drawbacks of Using Savings Buckets
A savings bucket system isn’t about making your finances more complicated—it’s about making them easier to understand. By giving each savings goal its own place, you always know what your money is meant to do.Savings Buckets Explained Like any financial strategy, though, it has a few limitations. Understanding both the advantages and the potential challenges will help you decide whether this approach fits your lifestyle.
✅ Benefits
- Every savings goal has a clear purpose, making your finances easier to organize.
- Reduces the temptation to spend money that was set aside for another goal.
- Makes it easier to track progress and celebrate small milestones.
- Works well with automatic transfers, helping you build consistent saving habits.
- Pairs perfectly with high-yield savings accounts, allowing your money to earn more while staying accessible.
- Easy to adjust as your financial priorities change throughout the year.
❌ Drawbacks
- Managing too many buckets can become confusing if you create more than you actually need.
- Some banks may not offer virtual buckets, requiring separate accounts or manual tracking.
- The system only works if you review your savings regularly and stay consistent with deposits.
- Irregular income can make it harder to contribute the same amount every month, although even small deposits still move you forward.
For most people, the benefits outweigh the drawbacks.Savings Buckets Explained Starting with just a few well-defined buckets keeps the system simple, while regular check-ins help you stay focused on your financial goals without feeling overwhelmed.
Savings Buckets vs. Other Saving Methods
There isn’t one perfect way to save money. The best approach depends on how you manage your finances and what motivates you to stay consistent. Some people prefer keeping everything in one savings account, while others use budgeting apps or spreadsheets. A savings bucket system stands out because it combines simplicity with clear organization, making it easy to see where every dollar is going.
The table below compares savings buckets with other common saving methods to help you decide which option fits your financial goals.
Bottom Line: If you’re saving for more than one goal, a savings bucket system offers the clearest way to stay organized. It gives every dollar a purpose without adding unnecessary complexity, making it a practical choice for beginners as well as experienced savers.
Costs, Risks & Expert Tips
One of the biggest advantages of a savings bucket system is that it doesn’t have to cost anything. Many banks and credit unions let you open a savings account with no monthly maintenance fee, and several online banks even include virtual buckets at no extra charge.Savings Buckets Explained Before choosing an account, it’s worth checking for fees, minimum balance requirements, and withdrawal limits so your savings can keep growing without unnecessary costs.
Possible Risks to Watch For
The biggest risk isn’t the bucket system itself—it’s losing track of it. Creating too many buckets can make your finances feel harder to manage instead of easier. Another common mistake is forgetting to review your goals. If your priorities change but your automatic transfers stay the same, you may end up putting money into the wrong place.
It’s also important to choose the right account. If you’re comparing options, our guide on How Many Savings Accounts Should You Have? can help you decide whether multiple accounts or virtual buckets make more sense for your situation.
💡 Expert Tips
- Start with three to five buckets instead of creating one for every small expense.
- Rename your buckets whenever your financial goals change to keep them relevant.
- Schedule automatic transfers on payday so saving happens before you have a chance to spend.
- Review your progress once a month and celebrate milestones to stay motivated.
- Keep your emergency fund separate from lifestyle goals like vacations or holiday shopping.
Pro Tip: The best savings system is the one you’ll actually use. A simple plan that you follow every month will usually produce better results than a complicated strategy you abandon after a few weeks.
Common Mistakes to Avoid + A Real-Life Example
A savings bucket system is easy to start, but a few small mistakes can make it less effective.Savings Buckets Explained The good news is that most of these problems are easy to fix once you recognize them. The goal isn’t to create a perfect system—it’s to build one that fits your everyday life and keeps you moving toward your financial goals.
Common Mistakes
- Creating too many buckets. Managing ten or more categories can quickly become overwhelming. Start with only the goals that matter most.
- Skipping monthly reviews. Your priorities change over time. A quick monthly check helps you adjust contributions and stay on track.
- Using one bucket for every expense. Taking money from your emergency fund to pay for a vacation defeats the purpose of separating your savings.
- Ignoring interest earnings. Keeping your money in a low-interest account could slow your progress. Choosing a competitive savings account helps every bucket grow a little faster.
Real-Life Example
Sarah wanted to save for several goals at the same time, but everything was sitting in one savings account. Whenever an unexpected expense came up, she wasn’t sure how much money was actually available for her vacation or holiday shopping.
She created four savings buckets: an emergency fund, travel, home maintenance, and holiday gifts. Then she set up automatic transfers on payday.Savings Buckets Explained Six months later, she could clearly see the progress toward each goal and no longer needed to guess whether she could afford an upcoming expense. Instead of feeling stressed about her savings, she felt confident because every dollar already had a job.
Key Lesson: A savings bucket system works best when it’s simple, reviewed regularly, and matched to your current financial priorities. Small, consistent habits usually produce better results than trying to save large amounts only once in a while.
Who Should Choose a Savings Bucket System?
The savings bucket method works for almost anyone, but it’s especially helpful if you’re trying to save for more than one goal at the same time.Savings Buckets Explained Instead of wondering whether you can afford an upcoming expense, you’ll always know exactly what each portion of your savings is meant for.
People Who Benefit the Most
- Beginners: If you’re just starting your savings journey, buckets provide a simple way to build good money habits without feeling overwhelmed.
- Families: Parents can create separate buckets for school expenses, vacations, home repairs, holidays, and emergency savings.
- Students and Young Professionals: Saving for tuition, moving costs, a first car, or future travel becomes much easier when every goal has its own place.
- Retirees: Buckets can help organize healthcare expenses, travel plans, home maintenance, and cash reserves while keeping long-term savings untouched.
- Anyone with Multiple Financial Goals: If you’re balancing several priorities at once, this system brings clarity and helps you stay focused on what matters most.
Is it right for you? If you often lose track of your savings or struggle to balance several financial goals, a savings bucket system is worth trying. It’s easy to set up, simple to maintain, and can make managing your money feel far less stressful.
Frequently Asked Questions
1. What are savings buckets?
Savings buckets are separate categories that organize your money based on specific financial goals. Instead of keeping all your savings in one place, you assign funds to goals such as an emergency fund, a vacation, home repairs, or retirement. This makes it easier to track your progress and avoid spending money that was meant for something else.
2. Do I need multiple bank accounts to use savings buckets?
No. Many online banks let you create virtual buckets inside a single savings account. If your bank doesn’t offer this feature, you can use multiple savings accounts or even track your buckets with a budgeting app or spreadsheet.
3. How many savings buckets should I have?
For most people, three to five buckets are enough. A good starting point is an emergency fund, short-term savings, long-term goals, and one or two buckets for upcoming expenses like travel or holidays. As your financial priorities change, you can always add or remove buckets.
4. Can I earn interest on my savings buckets?
Yes. If your buckets are part of a high-yield savings account, every bucket benefits from the interest earned on the account balance. Choosing a competitive APY can help your savings grow faster without changing your saving habits.
5. Are savings buckets better than one regular savings account?
If you’re saving for several goals at the same time, the bucket method is usually more organized. It gives every dollar a purpose, making it easier to avoid overspending and stay focused on your financial plans.
6. How often should I review my savings buckets?
A monthly review works well for most people. Check your progress, update your goals if needed, and redirect contributions once a bucket has reached its target. These quick check-ins help keep your savings plan aligned with your current priorities.
7. Are savings buckets only for people with a high income?
Not at all. The strategy works regardless of how much you earn. Even small, regular deposits can build meaningful savings over time. The key is consistency, not the size of each contribution.
8. What should my first savings bucket be?
For most beginners, an emergency fund should come first. Having money set aside for unexpected expenses can help you avoid relying on credit cards or loans when life doesn’t go as planned.
9. Can I change my savings buckets later?
Absolutely. Your financial goals will change over time, and your bucket system should change with them. You can rename, merge, remove, or create new buckets whenever your priorities shift, making the system flexible enough for every stage of life.
Final Verdict
If managing your savings feels confusing or you often find yourself borrowing from one goal to pay for another, a savings bucket system can make a real difference.Savings Buckets Explained It’s a simple approach that gives every dollar a purpose, helping you stay organized without adding unnecessary complexity to your finances.
Whether you’re building an emergency fund, planning a family vacation, saving for a home, or preparing for retirement, separating your money into dedicated buckets makes it easier to track progress and stay motivated. You don’t need a large income to make this strategy work.Savings Buckets Explained Consistent deposits and regular reviews are usually enough to build healthy saving habits over time.
To get the best results, combine your bucket strategy with a competitive high-yield savings account so your money can continue growing while remaining accessible when you need it. If you’re still comparing your options, be sure to read our complete guide to High-Yield Savings Accounts USA, where you’ll learn how to choose the right account and maximize the value of every dollar you save.
Final Thought: Saving money isn’t just about putting cash aside—it’s about giving your future plans the attention they deserve. When every dollar has a clear purpose, reaching your financial goals becomes more organized, less stressful, and far more achievable.
Take the Next Step Toward Smarter Saving
You’ve learned how a savings bucket system can make your money easier to manage and help you stay focused on the goals that matter most. Now it’s time to put the idea into action. Choose one financial goal, create your first bucket, and make your first deposit today. Small steps taken consistently can lead to meaningful progress over time.
📩 Join the FinanceInvestment Newsletter
Get practical money tips, savings strategies, banking guides, and beginner-friendly investing insights delivered straight to your inbox. Our goal is to help you make smarter financial decisions with clear, easy-to-understand advice.
Continue Your Learning
- Explore our complete guide to High-Yield Savings Accounts USA.
- Learn how compound interest helps your savings grow faster.
- Compare today’s savings options and build a plan that fits your financial goals.
Your future self will thank you for every dollar you choose to save today.

 If you’re asking How Much Interest Can $10,000 Earn in a High-Yield Savings Account, you’re already thinking about making your savings work harder. Unlike a standard savings account that may pay very little interest, a high-yield savings account offers a higher Annual Percentage Yield (APY). That means your money earns interest every day while remaining available when you need it.
 If you’re wondering How Much Interest Can $5,000 Earn in a High-Yield Savings Account, the first step is understanding how these accounts work. A high-yield savings account is similar to a traditional savings account, but it typically offers a much higher Annual Percentage Yield (APY). That means your money can grow faster while remaining easy to access whenever you need it.
 Building the right savings balance is simpler than many people think. Instead of choosing a random dollar amount, start by looking at your monthly essential expenses. These include housing, groceries, utilities, transportation, insurance, healthcare, and other bills you must pay even during a financial emergency.
 The best savings accounts for kids are usually affordable and easy to manage, but parents should still review the account terms before opening one. Many children’s savings accounts have no monthly maintenance fee, yet some banks may charge for optional services such as paper statements, wire transfers, or other special banking requests.