Tag: Saving Money

  • CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?

    CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?

    FINANCEINVESTMENT • CD STRATEGIES 2026

    CD Ladder vs CD Barbell Strategy: Which One Fits Your Goals?

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August 25, 2026
    About 10–12 min read

    Compare two practical ways to spread CD maturities, balance liquidity, and manage rate risk without making your cash strategy unnecessarily complicated.

    CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?
    CD Ladder vs CD Barbell Strategy explained for 2026. Compare maturity schedules, liquidity, rate risk, flexibility, and which strategy may fit your goals.
    cd-ladder-vs-cd-barbell-strategy
    CD Ladder vs CD Barbell Strategy
    CD ladder strategy,
    CD barbell strategy,
    CD ladder vs barbell,
    ladder vs barbell CDs,
    CD laddering,
    barbell CD strategy,
    CD investment strategy,
    CD maturity strategy,
    CD liquidity strategy,
    CD rate risk
    https://financeinvestment.site/cd-ladder-vs-cd-barbell-strategy/
    Subhash Rukade
    August 24, 2026
    About 10–12 minutes

    CD Ladder vs CD Barbell Strategy: Start With Your Cash Timeline
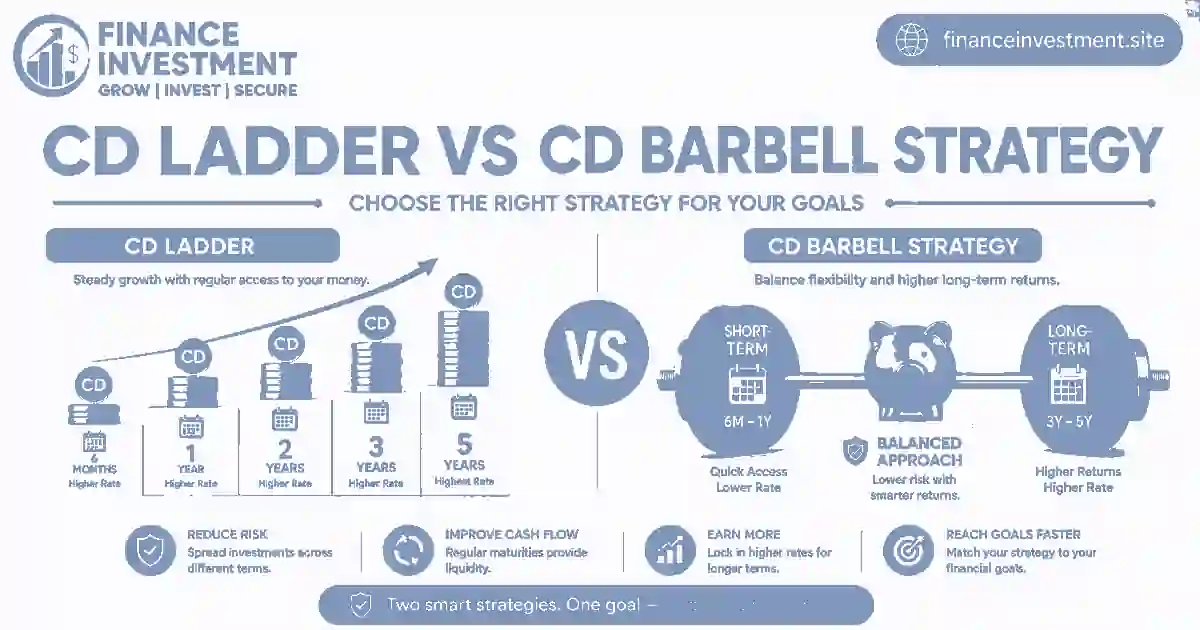
    CD Ladder vs CD Barbell StrategyWhen people compare a CD Ladder vs CD Barbell Strategy, they often start by asking which one earns more. That can miss the bigger issue. The more useful question is when you expect to need the money again. A strategy that works beautifully for someone with several upcoming expenses may feel restrictive to someone who mainly wants access to cash at the short and long ends of the timeline.

    A CD ladder spreads money across several maturity dates. That creates a steady stream of opportunities to reassess or use funds. A barbell takes a different route. It typically places money toward shorter and longer maturities while leaving less in the middle.

    Neither structure automatically wins. Your expected cash needs, comfort with locking money away, views on future rates, and desire for regular access can point you toward one design over the other. The goal is to build a schedule that makes sense for your money instead of forcing your money into a preset formula.

    If you want to refresh the basics before comparing these strategies, our

    CD Guide 2026

    explains CD basics, terms, rates, and the details worth checking before you choose an account.

    What You’ll Learn

    • How CD ladders and barbells are structured
    • Where each strategy can fit different cash needs
    • How maturity timing affects liquidity
    • The trade-offs involving rates and reinvestment
    • How to choose a structure without overcomplicating your savings plan

    Quick Answer: CD Ladder or CD Barbell?

    A CD ladder generally spreads money across multiple maturity dates, while a CD barbell concentrates more of the money in shorter and longer terms, with less in the middle. A ladder can offer more regular access points; a barbell can keep some cash relatively near-term while committing another portion for longer.

    6 Key Takeaways

    1. Ladder: Several CDs mature at different points.
    2. Barbell: Money is concentrated toward short and long maturities.
    3. Liquidity: A ladder can create more frequent maturity dates.
    4. Rate exposure: A barbell can give you both shorter-term flexibility and longer-term rate certainty.
    5. Cash needs matter: Upcoming expenses can influence which structure makes more sense.
    6. There is no universal winner: The better setup is the one that matches your timeline and comfort with locked-up money.

    Bottom line: A ladder is useful when you want several planned maturity dates. A barbell may fit better when you want a short-term pool alongside a longer commitment.

    CD Ladder vs CD Barbell: At a Glance

    The two structures differ mainly in where your maturity dates sit. A ladder usually creates a sequence of scheduled maturities, while a barbell places more weight at the short and long ends. That difference can affect how often you can access cash and how much of the portfolio is committed for longer periods.

    FeatureCD LadderCD Barbell
    Typical structureSeveral staggered maturitiesShort and long maturities
    Liquidity patternMore frequent maturity pointsMore concentrated access
    Rate exposureSpread across maturitiesShort and long rate exposure
    May suitSavers wanting scheduled access pointsSavers comfortable pairing near-term access with longer commitments

    Quick read: A ladder emphasizes a sequence of maturity dates. A barbell emphasizes separation between the short and long ends. The real difference is how each structure distributes your maturity dates and future decisions.

    How to Build a CD Ladder or Barbell From Scratch

    Building either strategy starts with the same basic question: how much money can you commit without needing it unexpectedly? Once that amount is clear, the structure becomes easier to design. Keep your emergency reserve and near-term spending money outside the CDs first. The remaining cash can then be divided according to your timeline.

    Building a CD Ladder

    A simple ladder divides your deposit among certificates with different maturity dates. For example, someone with $20,000 might place $5,000 into four CDs with staggered terms. As each certificate matures, the owner can use the money or reinvest it into a new longer-term CD.

    The exact terms do not have to follow one fixed formula. You might use six-month, one-year, 18-month, and two-year certificates, depending on available rates and when you expect to need the cash. Pick maturity dates that match real expenses or review points instead of filling every available term.

    Building a CD Barbell

    A barbell uses two ends of the maturity spectrum. One portion can sit in shorter CDs for relatively earlier access, while another portion can use longer certificates for a longer rate commitment. There is no universal percentage split. Your spending needs and tolerance for locking money away should guide the allocation.

    Plan the Reinvestment Before Maturity

    Decide in advance what you might do when a certificate matures. If you need the cash, move it to the account where you will spend it. If you still have a long-term need, consider reinvesting after checking current rates. Avoid automatic renewal simply because it is convenient.

    Practical Tip

    Keep a simple maturity calendar. Knowing which CD matures next can be more useful than trying to remember every account detail.

    How a CD Ladder and Barbell Work Over Time
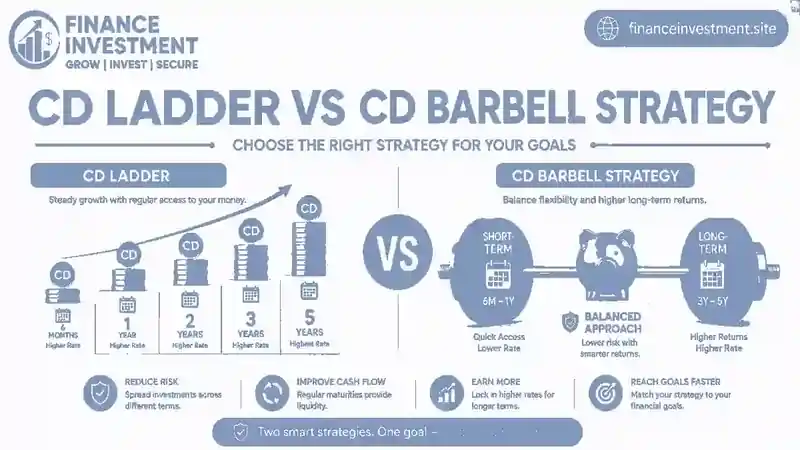
    CD Ladder vs CD Barbell StrategyThe main difference becomes clearer once the certificates are actually in place. You are not simply choosing several CDs; you are creating a schedule for when portions of your money become available and when you will decide what to do next.

    How a CD Ladder Moves

    Imagine you divide $24,000 into four $6,000 CDs. You could choose terms that mature at different points, such as six months, one year, 18 months, and two years. When the first CD matures, you can take the money for a planned expense or reinvest it into a new certificate. The other CDs continue following their original schedules.

    You can compare the current CD market, check whether your original goal has changed, and decide whether that slice of money still belongs in another CD. That gives the strategy a built-in review point instead of requiring you to commit the entire balance at one time.

    How a CD Barbell Moves

    Now consider a $24,000 barbell. You might place $8,000 in shorter-term CDs and $16,000 in a longer-term certificate. The short side can provide an earlier opportunity to access or reposition part of the money, while the longer side remains committed for a longer period.

    The two sides do not have to be equal. A saver expecting a major expense soon might give more weight to the short end. Someone comfortable leaving most of the money untouched could place more toward the longer end.

    Illustrative example: Mark expects to need some cash within a year but wants another portion working for several years. A barbell may give him two distinct time horizons, while a ladder would spread those maturities more evenly.

    In both structures, the important work happens when a CD matures. That is when you reassess the rate, timing, and purpose of that portion of the money rather than automatically repeating the old decision.

    Benefits and Drawbacks of CD Ladders and Barbells

    The appeal of these strategies comes from giving each portion of your cash a different place on the calendar. That can make a large balance easier to organize, but the structure also creates trade-offs you should understand before committing the money.

    ✓ Pros

    • Planned access: A ladder can create regular maturity dates, giving you more opportunities to use or reposition cash.
    • Rate diversification: Different maturity dates can reduce the need to commit the entire balance at one rate.
    • Reinvestment choices: Each maturity gives you a chance to compare current rates before putting the money back to work.
    • Flexible structure: A barbell can pair shorter commitments with longer ones instead of spreading money evenly.

    ⚠ Cons

    • Timing risk: A maturity date may not arrive when you actually need the money.
    • Concentration: A barbell can leave a larger share committed at one end of the maturity range.
    • Inflation risk: Fixed CD returns may lose purchasing power when prices rise faster than the account’s return.
    • Reinvestment risk: A maturing CD may need to be renewed when available rates are lower.

    That timing control is useful only if your cash outside the CDs is large enough to handle unexpected expenses.

    CD Ladder vs CD Barbell: Side-by-Side Comparison

    Once you move beyond the basic definitions, the choice comes down to how much control you want over maturity dates and where you want your rate exposure. A ladder spreads decisions across time, while a barbell creates a sharper split between shorter and longer commitments.

    FactorCD LadderCD Barbell
    StructureMoney is divided across several maturity dates.Money is concentrated around shorter and longer terms.
    LiquidityCan create more frequent maturityAccess is generally concentrated in the shorter-term portion.
    Maturity spreadBroad and staggered.Focused at two ends.
    ReinvestmentDecisions occur more regularly.Fewer, more concentrated decisions.
    ComplexityCan require tracking several CDs.Can be simpler to maintain.
    May suitSavers who value recurring maturity dates.Savers who want a short-term pool alongside longer commitments.

    The strategy can also be adjusted around the available products. For example, you could review
    6-month CD rates
    for the shorter side and compare them with
    5-year CD rates
    for a longer commitment. If you are unsure which term fits your cash needs, our guide on
    choosing the right CD
    can help frame the decision.

    Neither structure guarantees a better return. The useful comparison is how well each one fits your expected cash flow, tolerance for locked-up funds, and willingness to revisit rates over time.

    Costs, Risks and Expert Tips for CD Ladders and Barbells

    A well-planned CD structure can make your cash easier to manage, but it cannot remove the normal risks of certificates. The biggest issues usually appear when your circumstances change, rates move, or a maturity date arrives at an inconvenient time.

    Risks to Check Before Funding

    Early withdrawal penalties can reduce your interest if you need money before a CD matures. That matters in both strategies, especially if the amount at a particular maturity is smaller than the expense you eventually face.

    Opportunity cost matters when rates change. A long-term CD can keep earning its agreed rate while newer certificates become more attractive. On the other hand, short-term CDs may mature when available rates are lower. Inflation can also reduce the purchasing power of a fixed return.

    Insurance and taxes deserve a separate check. Check that eligible deposits are within applicable FDIC or NCUA coverage limits, including the relevant ownership category and institution. particularly when several CDs are held at the same institution. Interest from taxable CDs can also affect your tax bill and after-tax return.

    Expert Checks Before You Build or Renew

    Premium Expert Tip

    Write down every CD’s balance, APY, maturity date, penalty, ownership category, and renewal instructions. Then review the schedule as a whole. Several CDs can end up maturing close together, while a barbell can leave a large share of the balance tied to the long end.

    Before renewing, compare the new rate with current offers and ask whether the original cash plan still applies. Also check whether you still need the same balance at each maturity. A strategy should be adjusted when your financial timeline changes.

    Finally, keep emergency cash outside the certificates. A ladder or barbell works best when you are not forced to break a CD simply because an unexpected bill arrives.

    Common CD Ladder and Barbell Mistakes

    The trouble usually starts with the details: too many CDs, poorly spaced maturities, or money that should never have been locked up. The most common errors are usually not about picking a particular bank. They come from building a schedule that does not match the way the money will actually be used.

    Mistakes to Watch For

    • Making the structure too complicated: A ladder with too many small certificates can become difficult to track. If the added complexity does not create useful maturity dates, simplify it.
    • Clustering maturities: Several CDs that mature within the same narrow period may leave you with less flexibility than expected.
    • Using emergency cash: Money that may be needed immediately should not depend on a CD reaching maturity.
    • Ignoring renewal dates: A certificate can automatically renew according to its terms if you do not act during the applicable window.
    • Chasing rates: Moving money repeatedly for a slightly higher APY can add unnecessary work and may leave the maturity schedule disconnected from your goals.

    Illustrative Example: David Simplifies His Ladder

    David initially creates six small CDs because he wants frequent maturity dates. After reviewing the accounts, he realizes two mature within the same month and several balances are too small to make the extra tracking worthwhile. He consolidates his plan around fewer, more useful maturity points while keeping his emergency savings separate.

    Illustrative lesson: A useful CD strategy does not need to be complicated. The schedule should make your cash easier to manage, not create another chore.

    Before adding another certificate, look at the entire schedule rather than evaluating the new CD by itself. That simple habit can reveal gaps, clusters, and unnecessary commitments.

    Who Should Choose a CD Ladder or Barbell?

    A CD ladder may appeal to savers who want several planned points when money becomes available. It can work well for families with expenses spread across the year, retirees who want periodic access to part of their cash, or investors who prefer making smaller reinvestment decisions over time.

    A ladder tends to make sense for savers who want several planned maturity dates. keeping part of the money relatively accessible while committing another portion for a longer period. It can be useful when near-term liquidity and longer-term rate certainty both matter.

    Neither structure is necessary for every saver. If the balance is modest or the goal has one clear date, a single CD may be easier to manage. And if you may need the money without warning, a flexible savings account can be a better home for that cash.

    Quick Decision Guide

    • Want recurring maturity dates? Consider a ladder.
    • Need short and long commitments? Consider a barbell.
    • Have one clear cash date? A single CD may be enough.
    • Need immediate access? Keep the money flexible.

    Frequently Asked Questions About CD Ladders and Barbells

    What is the main difference between a CD ladder and a CD barbell?

    A ladder distributes money across a series of maturity dates, while a barbell puts greater weight on shorter and longer terms. The choice mainly changes how your cash becomes available over time.

    How many CDs do I need to build a CD ladder?

    There is no fixed number. A few certificates can create useful maturity dates, while a larger balance may support more steps. Keep the structure simple enough to track.

    Does a CD ladder provide more liquidity than a barbell?

    A ladder can create more maturity points, but that does not mean the money is available on demand. A CD generally remains subject to its terms until maturity.

    Which strategy has more rate risk?

    Both have rate exposure in different ways. A ladder spreads renewal decisions across time, while a barbell can leave more money committed at the long end.

    What happens when a CD in a ladder matures?

    You can generally use the money, move it elsewhere, or reinvest it after reviewing current rates and your financial needs.

    Can I change a CD ladder after I build it?

    Yes. As certificates mature, you can change the next term or amount rather than rebuilding the entire structure from scratch.

    Do CD ladders and barbells require a minimum deposit?

    Each bank or credit union sets its own CD minimums. Building a strategy with several certificates may require enough money to meet those minimums comfortably.

    Are CDs in a ladder or barbell federally insured?

    Eligible bank CDs may receive FDIC insurance, while qualifying credit-union share certificates may receive NCUA federal share insurance. Coverage limits and ownership categories apply.

    Are CD ladder and barbell earnings taxable?

    Interest from CDs held in a regular taxable account is generally taxable interest income. Your actual tax treatment depends on your circumstances and account type.

    Illustrative: Which strategy could fit a $30,000 balance?

    Illustrative comparison only: A saver could divide $30,000 among several maturity dates for a ladder or place more toward short and long terms for a barbell. The better structure depends on when the saver expects to need the money, not simply the balance size.

    Final Verdict: Which CD Strategy Makes More Sense?

    Choose a ladder if your main priority is having several planned maturity dates. Choose a barbell if your money has two different time horizons and you want a shorter-term portion alongside longer-term CDs. A ladder makes more sense when you want several maturity dates and prefer to spread your cash decisions across time. A barbell can be useful when you have two clear priorities: keeping one portion relatively near-term while giving another portion a longer runway.

    The key is to build around your expected cash needs rather than choosing a structure simply because it looks attractive on a rate table. A higher APY can lose its appeal if the money becomes unavailable when you need it, or if a maturity schedule creates more management work than you want.

    If you want to review CD basics, terms, safety considerations, and rate factors before choosing a structure, see our

    CD Guide 2026
    .

    Practical takeaway: Map out when you may need the money first. Then choose the CD structure that gives those dollars the right maturity dates.

    Build a CD Strategy That Fits Your Timeline

    A useful CD strategy starts with your cash needs, not with a complicated formula. Start with when you may need the money, then choose a structure that makes those dates easier to manage. For practical finance guides and new money insights, join our newsletter.

    📧 subhashr325@gmail.com
  • Common CD Mistakes Beginners Should Avoid: 2026 Guide

    Common CD Mistakes Beginners Should Avoid: 2026 Guide

    FINANCEINVESTMENT • CD GUIDE 2026

    Common CD Mistakes Beginners Should Avoid

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August 25, 2026
    About 10–12 min read

    A practical look at the small CD decisions that can become expensive surprises later.

    Common CD Mistakes Beginners Should Avoid: Smart 2026 Guide
    Learn the common CD mistakes beginners should avoid, from choosing the wrong term to ignoring penalties, insurance, taxes, and automatic renewal.
    common-cd-mistakes-beginners-should-avoid
    Common CD Mistakes Beginners Should Avoid
    common CD mistakes,
    CD mistakes for beginners,
    CD investing mistakes,
    mistakes to avoid with CDs,
    certificate of deposit mistakes,
    CD early withdrawal penalty,
    CD maturity mistakes,
    CD renewal mistakes,
    CD ladder mistakes,
    CD safety mistakes
    https://financeinvestment.site/common-cd-mistakes-beginners-should-avoid/
    Subhash Rukade
    August 24, 2026
    About 10–12 minutes

    Common CD Mistakes Beginners Should Avoid Before Opening an Account

    Common CD Mistakes Beginners Should AvoidMany first-time CD buyers start with one question: What is the highest APY I can get? A good rate matters, but it should come after you know what the money is for and when you may need it. Some of the costliest CD mistakes happen before the account is opened—when you choose money that may be needed soon, pick a term that does not match your plans, or overlook an important account rule.

    A CD works best when the money has a clear job. Cash reserved for an emergency, an upcoming bill, or an uncertain expense may need more flexibility. On the other hand, money you can comfortably leave untouched may be a better candidate for a fixed-term certificate.

    The account’s fine print can change the picture. Minimum deposits, early-withdrawal penalties, renewal rules, insurance coverage, interest payments, and tax treatment can all affect the real value of the account. A higher advertised rate does not automatically make one CD better than another.

    If you want to understand how CDs fit together before comparing individual accounts, start with ourour CD Guide 2026 explains the basics before you compare specific certificates.

    What You’ll Learn

    • The mistakes beginners most often make with CDs
    • How to match the CD with your money and timeline
    • Which fees, penalties, and account rules deserve attention
    • Why APY should not be your only comparison point
    • How to make a cleaner decision before depositing your money

    Quick Answer: Which CD Mistakes Matter Most?

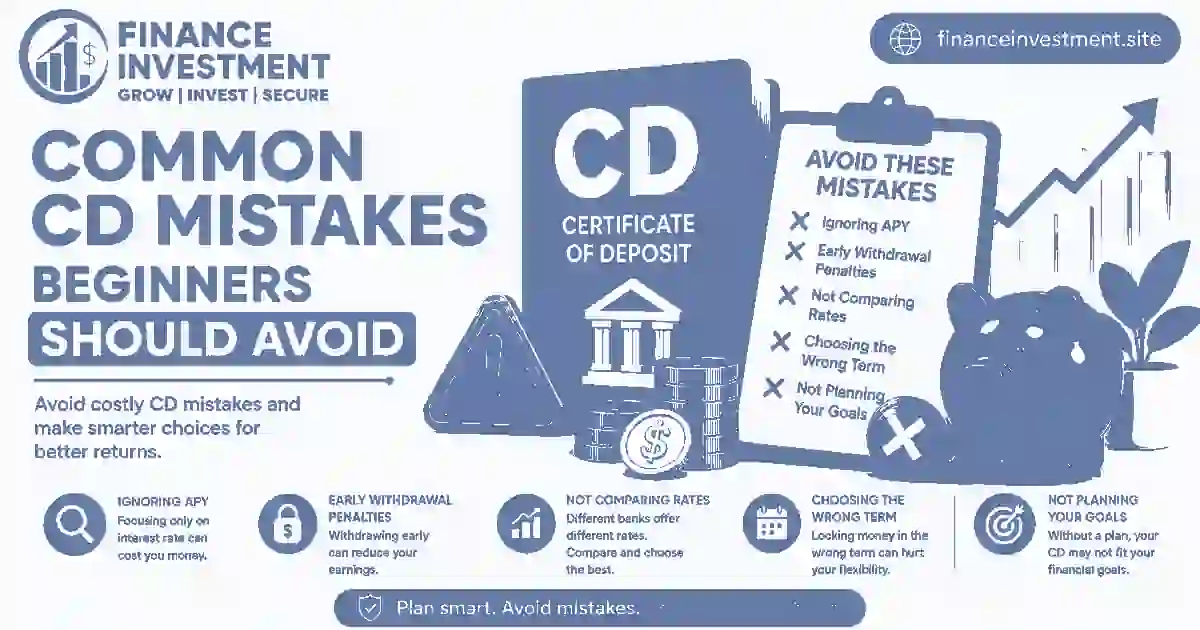
    The biggest beginner mistakes are usually simple: choosing a CD only for its APY, locking up money that may be needed soon, overlooking early-withdrawal penalties, skipping insurance checks, and failing to review what happens at maturity.

    6 Key Takeaways

    1. Look beyond APY: Compare the term, access rules, minimum deposit, and overall fit.
    2. Protect liquidity: Keep emergency money readily accessible instead of committing it to a standard CD.
    3. Read the penalty rules: Know what could happen if you withdraw before maturity.
    4. Check insurance: Confirm that the bank or credit union has the appropriate federal deposit or share insurance.
    5. Watch automatic renewal: A certificate may renew if you do not give instructions during the applicable grace period.
    6. Review taxes and interest: The advertised APY is not necessarily the amount you keep after taxes.

    Bottom line: A good CD decision is about more than chasing the highest rate. Look for a CD that fits your timeline, keeps your needed cash accessible, and has rules you understand before you fund it.

    At a Glance: CD Mistakes to Watch For

    Common CD Mistakes Beginners Should AvoidMost beginner mistakes can be caught with a quick review before you deposit the money. Before funding a certificate, check the term, withdrawal rules, insurance status, renewal instructions, and tax treatment. These details can matter more than a small difference in APY.
    Potential MistakeWhat to CheckWhy It Matters
    Chasing APYTerm and accessA higher rate may come with less flexibility
    Ignoring penaltiesEarly-withdrawal policyEarly access may reduce your return
    Skipping insurance checksFDIC or NCUA coverageConfirms applicable federal protection
    Forgetting renewalMaturity and grace periodYou may miss the chance to reassess your money

    A few minutes of checking the terms can save you from an unpleasant surprise later.

    Complete Beginner Guide to Choosing a CD

    Before opening a CD, think of it as a fixed agreement with rules you will need to follow until maturity. Before moving money, take a few minutes to understand what you are agreeing to. This simple review can help you avoid several common CD mistakes before they become expensive.

    1. Start With the Money You Are Using

    First, identify the purpose of the cash. Money needed for rent, an upcoming bill, or emergencies may not belong in a standard CD. Use funds that you can reasonably leave untouched for the selected term. If you are saving for a known near-term goal, a shorter certificate may be more appropriate.

    2. Check the Term and Minimum Deposit

    Look at the exact term, not just the advertised APY. A longer commitment may limit access for a longer period. Also check the minimum opening deposit. Some certificates accept small amounts, while others require substantially more. Our guide to how much money you need to open a CD can help with this part.

    3. Compare the APY With the Rules

    APY matters, but it should be viewed alongside the term, interest-payment schedule, and withdrawal conditions. A slightly lower rate may be more useful if the account gives you terms that better match your plans.

    4. Read the Early-Withdrawal Terms

    Find out how the penalty works before depositing the money. Some institutions calculate the charge using a set number of months of interest. The exact formula varies, so read the certificate disclosure rather than assuming every CD follows the same rule.

    5. Verify Insurance, Taxes, and Renewal Rules

    Confirm applicable FDIC insurance for a bank CD or NCUA share insurance for an eligible credit-union certificate. Also understand how interest may be reported for tax purposes. Finally, check whether the CD automatically renews and how long the grace period lasts.

    If all of these details fit your plan, you are in a much stronger position to choose a certificate without letting one attractive number make the decision for you.

    How a CD Works From Opening to Maturity

    Once you decide to open a certificate, the process is fairly straightforward. The important part is understanding what happens after the money leaves your regular account. A CD follows a defined timeline, so each stage has a specific purpose.

    Opening and Funding

    You apply through the bank or credit union, select the available certificate, and provide the required information. After approval, you fund the account with the amount you choose, subject to the institution’s minimum. The opening confirmation should show the principal, APY, term, maturity date, and other applicable conditions.

    During the CD Term

    The deposited money remains in the certificate while interest accrues according to its terms. Depending on the product, interest may compound inside the account or be paid according to a stated schedule. You normally do not need to manage the CD day to day, but keep the account documents available for reference.

    Approaching Maturity

    The maturity date is when the original term ends. The institution may send a notice explaining your options. You may be able to withdraw the funds, move them elsewhere, or renew the certificate. If automatic renewal applies, check the new rate and term before the grace period expires.

    Illustrative Example

    Elena opens a 12-month CD with $7,500. Her confirmation shows the agreed APY and maturity date. Several weeks before maturity, she reviews the renewal notice. Because she expects to use part of the money for a planned expense, she chooses not to let the entire balance automatically move into another CD.

    This simple timeline shows why reading the maturity notice matters just as much as opening the account correctly.

    Benefits and Drawbacks of Avoiding CD Mistakes

    Choosing the CD carefully can make the account easier to live with once the money is locked in. Still, even a well-chosen certificate has trade-offs. Knowing both sides helps you decide whether a CD belongs in your cash plan.

    ✓ Pros

    • Fewer surprises: Understanding the rules before opening the account makes the term easier to manage.
    • Better planning: A suitable maturity date can keep goal-specific money organized.
    • Rate certainty: A fixed-rate certificate can keep its stated rate during the agreed term.
    • More disciplined saving: Limited access can discourage unnecessary spending.

    ⚠ Cons

    • Reduced liquidity: Accessing money early can be less convenient than using a savings account.
    • Potential penalties: Early withdrawal may reduce the return under the certificate’s terms.
    • Inflation and taxes: The purchasing power and after-tax value of interest can be lower than the headline APY suggests.
    • Renewal risk: A new CD may offer a different rate when the original one matures.

    CD Mistake Comparison: The Shortcut vs. the Smarter Move

    A few choices made before funding can make a big difference later.. This comparison shows what a common shortcut looks like and what a more careful approach can look like instead.

    Common ShortcutPossible ProblemSmarter Move
    Chasing the highest APYThe term may not fit your plans.Compare APY with term, access, and account rules.
    Choosing the wrong termYou may need the money before maturity.Match the maturity date to your expected cash need.
    Ignoring early withdrawalA penalty can reduce your return.Read the withdrawal terms before depositing.
    Skipping insurance checksYou may misunderstand available federal protection.Verify applicable FDIC or NCUA coverage.
    Forgetting automatic renewalYour money may roll into a new term.Review maturity instructions and the grace period.
    Ignoring tax treatmentYour after-tax return may be lower than expected.Consider taxes when comparing the actual value of the CD.

    The goal is not to eliminate every trade-off. It is to make sure the certificate you choose matches the purpose of your money and the rules you are comfortable accepting.

    Costs, Risks and Expert Tips for Avoiding CD Mistakes

    A CD mistake does not always show up as an obvious fee. Sometimes the cost is lost flexibility, a missed opportunity, or a lower return than you expected. Looking at these risks before opening or renewing a certificate can make the decision much cleaner.

    Where the Financial Costs Can Appear

    Early withdrawal is one of the clearest risks. If you need the money before maturity, the institution may impose a penalty under the CD’s terms. That can reduce the interest you keep and may make the original APY less meaningful.

    There is also an opportunity cost. If market rates rise after you lock in a certificate, your money may continue earning the older rate until maturity. Inflation creates another concern because a fixed return may not keep pace with rising prices.

    Taxes can further reduce the amount you keep from interest earned in a taxable account. Also check insurance limits when placing a large balance with one institution. Federal deposit or share insurance has coverage rules, so do not assume every dollar is automatically protected.

    Expert Checks Before You Commit

    Premium Expert Tip

    Before funding a CD, write down five things: the APY, maturity date, early-withdrawal penalty, insurance coverage, and renewal terms. Before renewal, run the same check again. Your circumstances and available rates may have changed.

    Renewal deserves particular attention. A CD that made sense a year ago may not be the best place for the money today. Compare the new rate with current alternatives and ask whether you still need the same level of commitment.

    The simplest way to avoid these costs is to read the terms before funding the CD and review the account again before renewal.

    Common CD Mistakes and a Real-Life Example

    Not every CD mistake involves the interest rate. Beginners can also run into trouble by putting too much money into one certificate, misunderstanding how ownership affects insurance coverage, or simply missing an important maturity notice.

    Mistakes That Deserve Extra Attention

    • Overfunding one CD: Putting a large share of your cash into one certificate can leave too little money available for unexpected needs.
    • Ignoring account ownership: Deposit-insurance coverage can depend on how accounts are owned and how much is held within the applicable coverage categories. Do not assume separate account numbers automatically mean separate coverage.
    • Missing the maturity notice: A renewal window can be limited. If you do not review the notice, the CD may renew under the institution’s stated terms.
    • Misunderstanding interest payments: Interest may compound in the certificate or be paid according to a specific schedule. Read the account disclosure so you know when and where interest is credited.

    Illustrative Example: Sarah Spreads Her Cash

    Sarah has $80,000 available for several future goals. Instead of placing the entire amount into one CD, she keeps part of the money accessible and divides the remainder between certificates with different maturity dates. She also reviews the institution’s insurance information and sets a calendar reminder before each maturity date.

    Illustrative lesson: Sarah’s approach is hypothetical. The point is not that one structure is always best, but that spreading cash and reviewing account rules can reduce the consequences of a single decision.

    A CD should support your cash plan, not become the plan itself. Keeping track of ownership, coverage, interest, and maturity dates can prevent small oversights from turning into larger problems.

    Who Should Pay Special Attention to CD Mistakes?

    First-time buyers have more reason to slow down because CD terms can be unfamiliar at first. Large-balance savers should pay particular attention to deposit-insurance limits and account ownership. Retirees may need to think carefully about access to cash, especially when a CD is part of their regular income plan.

    Families can face similar issues when money is earmarked for tuition, a home purchase, or another known expense. People using several certificates should also keep track of different maturity dates, rates, and renewal instructions. A CD may be less suitable when the money could be needed without warning.

    Quick Decision Guide

    • New to CDs? Start with a manageable amount and understand the terms.
    • Holding a large balance? Review insurance and ownership carefully.
    • Need regular access? Keep enough cash outside the CD.
    • Using several CDs? Track every maturity and renewal date.

    Frequently Asked Questions About CD Mistakes

    What is the biggest mistake beginners make with CDs?

    A frequent mistake is looking at the APY without checking the term and account rules. The term, withdrawal rules, insurance, maturity instructions, and tax treatment also affect whether the CD fits your needs.

    Can you lose money by withdrawing from a CD early?

    You may receive less than the return you expected because the institution can generally charge an early-withdrawal penalty under the CD’s terms. Review the penalty before opening the account.

    Should I choose a CD with the highest APY

    Not necessarily. The highest APY may come with a term or conditions that do not fit your plans.

    How do I know if my CD is federally insured?

    For a bank CD, verify that the institution is FDIC-insured. For an eligible credit-union certificate, check for NCUA federal share insurance. Also consider applicable coverage limits.

    What happens if I forget my CD maturity date?

    The certificate may automatically renew according to its terms. Check the maturity notice and grace period so you have time to decide what to do with the money.

    Is automatic CD renewal a mistake?

    Automatic renewal itself is not necessarily a problem. The issue is letting the CD renew without checking the new rate, term, and your current plans.

    Are CD earnings taxable?

    Interest from a CD held in a regular taxable account is generally taxable as interest income. Your tax situation can affect the return you actually keep.

    Illustrative: What happens if a $10,000 CD earns 4%?

    Illustrative calculation only: At a hypothetical 4% APY for one year, $10,000 could earn approximately $400 under the stated assumptions. Actual earnings depend on the CD’s APY, compounding, and account terms.

    Final Verdict: Avoid the Mistakes That Can Cost You Later

    Avoiding CD mistakes starts with one simple habit: check the terms before moving your money. Do not let an attractive APY make the entire decision for you. The better certificate is the one whose term, access rules, minimum deposit, and maturity date fit your actual plans.

    Before funding a CD, verify the early-withdrawal penalty, applicable FDIC or NCUA insurance, interest-payment details, tax considerations, and automatic-renewal rules. These details may seem small when you open the account, but they can matter considerably if your plans change.

    It is also worth checking the account again when it approaches maturity. A CD that made sense when you opened it may not be the best choice when the term ends.

    For a broader look at certificates, rates, terms, and important account features, explore our

    CD Guide 2026
    .

    Practical takeaway: Read the fine print, protect the cash you may need, and compare the whole CD—not just the rate printed at the top.

    Make Your Next CD Decision With Fewer Surprises

    A good CD decision starts with understanding the rules before your money is committed. If you enjoy practical guides on CDs, saving, and everyday investing, join our newsletter for useful money insights and new guides.

    📧 subhashr325@gmail.com

  • How Are CD Earnings Taxed? 2026 Guide to CD Interest Taxes

    How Are CD Earnings Taxed? 2026 Guide to CD Interest Taxes

    FINANCEINVESTMENT • CD TAX GUIDE 2026

    How Are CD Earnings Taxed?

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August , 24,2026.
    About 10–12 min read

    Learn how CD interest is generally taxed, what Form 1099-INT means, and how taxes can affect the money you actually keep from a certificate of deposit.

    How Are CD Earnings Taxed? 2026 Guide to CD Interest Taxes
    How are CD earnings taxed? Learn how CD interest is reported, when it becomes taxable, how 1099-INT works, and how taxes affect your CD returns.
    how-are-cd-earnings-taxed
    How Are CD Earnings Taxed
    CD interest tax, how CD interest is taxed, are CD earnings taxable, CD tax rate, CD interest income, taxes on certificate of deposit, 1099-INT CD, CD interest and federal taxes, CD early withdrawal penalty tax, CD taxes USA
    https://financeinvestment.site/how-are-cd-earnings-taxed/
    Subhash Rukade
    August 23, 2026
    About 10–12 minutes

    How Are CD Earnings Taxed?

    How Are CD Earnings TaxedA CD may advertise an attractive APY, but the amount you actually keep can be lower after taxes. How are CD earnings taxed? For a CD held in a regular taxable account, the interest is generally taxable as interest income for federal tax purposes. That means your after-tax return can be lower than the APY shown when you open the certificate.
    IRS guidance on taxable interest

    The timing matters, too. For many CDs, interest is generally included in income when you actually receive it or when you are entitled to receive it without paying a substantial penalty. A CD that pays interest at maturity can therefore have different timing from a certificate that credits interest during the term. Certain CDs with interest deferred for more than one year can also fall under original issue discount rules.
    IRS Publication 550

    The basic reporting process is usually straightforward. Financial institutions generally report qualifying interest on Form 1099-INT, while certain OID situations may involve Form 1099-OID. Even if you do not receive an information form, taxable interest generally still has to be reported on your federal tax return.
    IRS Form 1099-INT information

    If you are still getting familiar with certificates of deposit, our

    CD Guide 2026

    provides the broader picture before you compare CD rates, terms, and tax considerations.

    What You’ll Learn

    • How CD interest is generally taxed at the federal level
    • When CD interest generally becomes taxable
    • How Form 1099-INT fits into CD tax reporting
    • Why the advertised APY and your after-tax return can differ
    • How early-withdrawal penalties can affect the tax calculation
    • When OID rules may apply to certain CDs

    Quick Answer: Are CD Earnings Taxable?

    Yes. Interest from a CD held in a regular taxable account is generally taxable as interest income for federal tax purposes. It is generally included in your ordinary taxable income rather than receiving the preferential federal rates that may apply to qualified dividends or certain long-term capital gains.
    IRS guidance on taxable interest

    6 Key Takeaways

    1. CD interest is generally taxable:
      Earning interest from a regular taxable CD does not make that interest tax-free.
    2. Your tax situation matters:
      The amount of federal tax you owe depends on your taxable income, filing situation, and applicable tax rates.
    3. Tax can arise before maturity:
      For many CDs, interest may be taxable when you receive it or when you become entitled to receive it without a substantial penalty. Reaching maturity is not automatically the taxable event.
    4. Form 1099-INT can help with reporting:
      Banks and other payers generally use Form 1099-INT to report qualifying interest income when the applicable reporting requirements are met.
      IRS Form 1099-INT information
    5. APY is not the same as your after-tax return:
      The advertised APY shows the CD’s stated annual percentage yield. Your amount left after taxes can be lower.
    6. Some CDs require special attention:
      Certain deferred-interest CDs, including some longer-term CDs subject to original issue discount rules, can have different reporting requirements.
      IRS Publication 550

    Bottom line: When comparing CDs, look beyond the advertised APY. Consider the interest you expect to earn, your likely tax treatment, and how much money you may actually keep after taxes.

    CD Taxes at a Glance

    CD tax treatment is easier to understand when you separate the interest the certificate earns from the amount you ultimately keep. The table below highlights the main points to check when reviewing a taxable CD.

    Tax PointWhat to Know
    CD interestGenerally taxable as interest income when applicable tax rules require it to be reported.
    Federal treatmentGenerally included in ordinary taxable income rather than receiving the special rates used for qualified dividends or long-term capital gains.
    Form 1099-INTFinancial institutions generally use this form to report taxable interest when required.
    APY vs. money keptThe advertised APY is a pre-tax figure; your after-tax return can be lower.
    Shorter CDsOften produce less total interest, so the dollar amount subject to tax may also be smaller.
    Longer CDsCan create more interest over time and may involve additional tax considerations for certain CD structures.

    One useful habit is to compare CDs using both the advertised APY and an estimated after-tax result. Your actual tax depends on your circumstances, so an after-tax estimate should be treated as a planning tool, not a tax bill.

    Complete Beginner Guide to CD Taxes

    How Are CD Earnings TaxedThink of CD interest as income, not as a discount on the amount you originally deposited. If you put $10,000 into a taxable CD and it earns interest, the interest can become part of your taxable income even though your original $10,000 is still sitting in the certificate.
    When Does CD Interest Enter Your Taxable Income?

    The timing depends on how the CD pays or credits interest. The IRS generally says interest is taxable in the year you receive it or when it is credited to an account and available for withdrawal without substantial restriction. For many ordinary CDs, this means you do not necessarily have to wait until the certificate reaches maturity to report the interest.

    For example, if your CD credits interest annually and you can access that interest under the account terms, the taxable amount may be reported for that year even if you leave the money inside the CD.

    What Is Form 1099-INT?

    Your bank will generally report taxable CD interest on Form 1099-INT when the reporting requirements apply. The form helps you identify the interest that belongs on your federal tax return. However, there is an important rule for beginners: you still have to report taxable interest even if you never receive a 1099-INT.

    Federal, State, and Local Taxes

    Federal income tax is only part of the picture. Depending on where you live, your CD interest may also be subject to state or local income tax. The exact treatment varies by jurisdiction, so don’t assume the federal result tells you the entire tax cost.

    Long-Term CDs and OID

    Longer-term CDs can require extra attention. Under IRS rules, certain CDs with terms of more than one year can fall under original issue discount (OID) rules. In those situations, taxable interest may need to be recognized as it accrues rather than waiting until the cash is paid at maturity. A Form 1099-OID may be used for reportable OID.

    Finally, a CD held inside a tax-advantaged account such as an IRA is a different situation from a CD held in an ordinary taxable account. The account’s tax rules can change when and how income is taxed. Don’t automatically apply the rules for a regular bank CD to every CD you own.

    How CD Taxation Actually Works

    The tax side of a CD follows the interest, not simply the date printed on the certificate. Once you open a taxable CD, the key question becomes when the interest is considered received or available to you under federal tax rules.

    From Opening the CD to Reporting Interest

    Suppose you open a one-year CD in June and the bank credits interest during the year. If that interest becomes available to you without a substantial restriction, it can generally be taxable for that tax year even if you leave it inside the CD. You do not necessarily wait until maturity to deal with the tax.

    For many ordinary CDs, the bank reports taxable interest on Form 1099-INT. You use that information when preparing your federal return. Taxable interest still has to be reported even if you do not receive the form.

    Where 1099-OID Can Enter the Picture

    Some longer-term CDs can involve original issue discount (OID). In those cases, taxable OID may be included in income as it accrues rather than waiting for the final payment. Form 1099-OID is used for reportable OID.

    What If You Withdraw Early?

    If you cash out a CD early and forfeit part of the interest, you generally report the interest shown before subtracting the penalty. The qualifying early-withdrawal penalty is reported separately and may be deductible under federal rules.

    Illustrative Example

    Imagine a taxable CD earns $600 during a calendar year. If the interest is taxable in that year, the $600—not simply the amount you withdraw at maturity—can be part of your taxable interest income. Your actual tax depends on your circumstances. This is an illustrative example, not a tax calculation for a specific taxpayer.

    Benefits & Drawbacks of CD Tax Treatment

    CD taxes are not necessarily difficult to track, especially when you receive a standard Form 1099-INT from your bank. The bigger issue is the effect taxes can have on the return you actually keep.

    ✓ Pros

    • Predictable reporting: A regular bank CD generally produces straightforward interest records for your tax return.
    • 1099-INT simplifies recordkeeping: Your financial institution generally reports taxable interest when the applicable reporting rules are met.
    • Early-withdrawal penalties can receive separate treatment: A qualifying penalty is reported separately rather than simply reducing the interest shown on the tax form.

    △ Cons

    • Taxes reduce your effective return: A CD’s advertised APY is not necessarily the amount you keep after federal and potentially state or local taxes.
    • Reinvested interest can still create tax: Interest that is credited and available to you can be taxable even when you leave it inside the CD.
    • Some CDs require extra attention: Certain long-term CDs can fall under OID rules, creating taxable income as OID accrues.

    Taxable CD vs. Tax-Advantaged Account

    A CD held in an ordinary taxable account generally follows the interest-reporting rules discussed in this article. A CD held inside a tax-advantaged account can follow a different set of rules because the account itself affects when income is taxed. That distinction matters when comparing where to hold a CD, not just which CD offers the highest APY.

    The practical takeaway is simple: taxes are part of the return calculation. For a standard CD, reporting is often manageable, but the tax cost can become more noticeable as the balance and interest earnings grow.

    CD Tax Comparison: How Other Investments Stack Up

    A CD can look attractive next to other income-producing investments, but the tax treatment can change the comparison. The advertised yield is only one part of the calculation.

    InvestmentTypical Federal Tax TreatmentKey Tax Difference
    Bank CDInterest is generally taxable income.Taxes can reduce the CD’s effective return even when the rate is fixed.
    High-yield savingsInterest is generally taxable.Similar federal tax treatment, although the rate can change.
    U.S. Treasury securitiesInterest is federally taxable.Treasury interest is generally exempt from state and local income taxes.
    Municipal bondsQualifying municipal bond interest is generally exempt from federal income tax.Tax treatment can make the after-tax yield more competitive for some investors.
    Stocks / dividendsDividends and investment gains can receive different tax treatment.Qualified dividends and long-term capital gains may receive preferential federal rates when requirements are met.

    The IRS generally treats CD interest as taxable interest income, while qualified dividends and certain long-term capital gains follow different rules. Municipal bond interest can be federally tax-exempt when the applicable requirements are satisfied. Treasury interest is federally taxable but generally exempt from state and local income taxes.

    Compare the After-Tax Return, Not Just the Yield

    For example, a 4.50% CD may not leave you with the same usable return as a 4.50% investment receiving different tax treatment. Your actual result depends on your tax situation, so a simple after-tax estimate can be more useful than comparing headline yields alone.

    If you’re also comparing the amount a CD can generate, our guide to how much you can earn from a CD can help you connect the advertised rate with the potential dollar return.

    Tax Costs, Risks & Expert Tips

    The tax bite on a CD can be easy to overlook because banks usually advertise the return before taxes. For a taxable account, your federal tax bracket—and potentially your state or local tax situation—can reduce what the interest is worth to you. The IRS generally treats CD interest as taxable interest income.

    Higher Tax Brackets Can Change the Picture

    Two people can earn the same CD interest and face different federal tax costs because their taxable incomes are different. That is why a CD’s APY should not be viewed as the final return in a taxable account.

    Reinvested Interest Is Not Automatically Tax-Free

    If interest is credited to your account and available under the applicable rules, leaving it inside the CD does not necessarily postpone the tax. You can owe tax on interest you chose to reinvest rather than spend.

    Early Withdrawal Creates Two Separate Numbers

    If you cash out early and forfeit interest, the bank generally reports the interest separately from the early-withdrawal penalty. The IRS says the interest is reported without subtracting the penalty, while a qualifying penalty may be deductible under the applicable rules.

    Long-Term CDs May Need Extra Attention

    Some CDs with maturities longer than one year can fall under original issue discount rules. In those cases, part of the interest may be included in income as OID accrues, even before the CD reaches maturity.

    A Simple After-Tax Comparison

    For a quick planning estimate, start with the CD’s annual interest and subtract an estimated federal and applicable state/local tax cost. For example, if a CD earns $500 and your assumed combined tax rate is 24%, an illustrative after-tax amount would be $380. Your actual liability can differ.

    Expert Tip

    Compare CDs using the return you expect to keep, not just the number in the rate box. For a straightforward taxable CD, estimate the tax effect first. For a long-term CD, OID situation, early withdrawal, or tax-advantaged account, check the specific rules instead of relying on a simple APY calculation.

    Common CD Tax Mistakes + A Real-Life Example

    Most CD tax mistakes are not caused by complicated math. They happen when the timing of interest, the tax forms, or the difference between the advertised APY and the taxable amount gets overlooked.

    Common Mistakes to Watch

    • Waiting until maturity to think about taxes: Maturity is not automatically the tax date. Depending on the CD and its terms, interest may be taxable earlier when it is received or available to you.
    • Ignoring interest left inside the CD: Reinvesting or leaving credited interest untouched does not necessarily make it tax-free.
    • Forgetting Form 1099-INT: Check the form against your own records. Even if you do not receive one, taxable interest generally still must be reported.
    • Using APY as the final return: A quoted APY is a pre-tax figure. Your actual after-tax result can be lower.
    • Missing OID reporting: Certain CDs with interest deferred for more than one year can fall under OID rules, which may require income to be recognized as it accrues.
    • Subtracting an early-withdrawal penalty from interest: The IRS says interest is generally reported before the penalty is deducted; a qualifying penalty is handled separately.

    Real-Life Example: Lisa Reviews Her CD Return

    Lisa opens a one-year CD with $20,000 at a 4.50% APY. For planning purposes, assume it generates about $900 of interest over the year. She initially thinks the $900 is her final gain because that is what the CD statement shows.

    Illustrative calculation only: If Lisa uses a hypothetical 24% federal tax rate and ignores state or local taxes, $900 × 24% = $216 of estimated federal tax. Her simplified after-tax amount would be about $684. This is not Lisa’s actual tax bill; her real liability depends on her complete tax situation.

    Lisa also checks her Form 1099-INT and compares it with her CD records rather than assuming the maturity date tells the whole tax story.

    Practical tax lesson: Keep the CD statement, review the tax form, and judge the investment by its potential after-tax return—not just the APY printed in the account advertisement.

    Who Should Pay Special Attention to CD Taxes?

    CD taxes matter more as the amount of interest grows. A small CD may produce a modest tax bill, while several large certificates can add a meaningful amount to your taxable income each year.

    Savers Who May Need a Closer Look

    • Higher-income savers: A larger taxable-interest amount can have a bigger effect when your marginal federal tax rate is higher.
    • People with large CD balances: Even a modest APY can generate substantial interest when applied to a large principal balance.
    • People holding several taxable CDs: Add the interest from your certificates together rather than judging each CD separately.
    • Investors comparing account types: A taxable CD and a CD held inside a tax-advantaged account can have very different tax consequences. Don’t compare their headline yields without considering the account structure.
    • Long-term CD holders: CDs with maturities over one year can involve OID rules, meaning part of the interest may be included in income as it accrues.
    • Retirees: Taxable CD interest can become an important part of annual income planning, particularly when several deposits generate interest at the same time.
    • Savers in states with income taxes: Federal tax is not necessarily the entire tax cost. State and local rules can add another layer.

    Quick Decision Guide

    If your CD balance is modest and your tax situation is straightforward, basic 1099-INT reporting may be all you need to track. If you have large balances, several CDs, long-term certificates, or a more complex tax picture, calculate the potential after-tax return and review the specific reporting rules before choosing where to keep your money.

    Frequently Asked Questions About CD Taxes

    Are CD earnings taxable?

    Yes. Interest earned on a CD held in a regular taxable account is generally taxable as interest income for federal income-tax purposes. The IRS specifically includes certificates of deposit among common sources of taxable interest.
    IRS guidance on interest income

    When is CD interest taxable?

    For many CDs, interest is generally taxable when you receive it or when it is credited to your account and available for withdrawal without a substantial penalty. A CD does not automatically become taxable only because it reaches maturity. Certain deferred-interest CDs can follow different rules.
    IRS Publication 550

    Is CD interest ordinary income?

    Generally, yes. Taxable CD interest is treated as interest income for federal tax purposes. It generally does not receive the preferential tax rates that may apply to qualified dividends or certain long-term capital gains. Your actual tax liability depends on your overall tax situation.
    IRS Publication 550

    What is Form 1099-INT?

    Form 1099-INT is an information return used to report certain interest income. For many interest payments of $10 or more, the payer generally reports the amount on Form 1099-INT when the applicable reporting rules are met. You should use the information on the form when preparing your tax return.
    IRS Form 1099-INT information

    What if I don’t receive a 1099-INT?

    You generally still must report taxable interest even if you do not receive Form 1099-INT. The IRS requires taxpayers to report taxable interest income whether or not an information form is received.
    IRS Topic 403

    Are long-term CDs subject to OID?

    Certain CDs with a maturity of more than one year can be subject to original issue discount, or OID, rules. In that situation, part of the interest may generally need to be included in taxable income each year as OID accrues, even if the cash has not yet been paid to you. A financial institution may report the taxable amount on Form 1099-OID.
    IRS Publication 550

    Is CD interest taxable if I reinvest it?

    It can be. Reinvesting interest does not automatically make it tax-deferred. If interest is credited to your account and you are entitled to withdraw it without a substantial penalty, it can generally be taxable even if you leave the money in the CD rather than taking it as cash.
    IRS rules on constructive receipt

    How is an early-withdrawal penalty handled?

    If you withdraw money from a CD before maturity and the bank charges an early-withdrawal penalty, the interest and penalty are generally handled separately for federal tax purposes. You generally report the interest shown by the financial institution without subtracting the penalty. A qualifying penalty may be deductible under the applicable federal rules, and the financial institution generally reports the penalty separately.
    IRS Publication 550

    Are CDs inside IRAs taxed the same way?

    No. A CD held inside an IRA is subject to the tax rules that apply to the IRA rather than being treated exactly like a CD held in a regular taxable account. The tax consequences generally arise under the IRA’s distribution rules when money is taken from the account.
    IRS retirement distribution guidance

    Illustrative: How much tax could you owe on $1,000 of CD interest?

    Illustrative calculation only:
    If a taxpayer assumes a 24% federal marginal tax rate, $1,000 × 24% = $240 of estimated federal tax. That leaves $760 before considering any applicable state or local taxes. This is only an example and is not a prediction of an individual’s actual tax bill.

    Final Verdict: What Your CD Really Earns After Taxes

    For most people, the basic rule is straightforward: interest from a CD held in a regular taxable account is generally taxable income. The APY tells you what the certificate earns before taxes, not what you ultimately keep.

    For a standard CD, reviewing your Form 1099-INT and matching it with your bank records is usually a manageable way to handle the interest-reporting side. The picture deserves more attention when you own a longer-term CD that may involve OID, or when you close a certificate early and pay a withdrawal penalty.

    The account itself matters, too. A CD inside a tax-advantaged account such as an IRA does not follow exactly the same tax rules as a CD held in an ordinary taxable account. The tax treatment of the broader account can determine when income is recognized and when distributions are taxed.

    Practical takeaway: When comparing CDs, look beyond the advertised APY. Estimate the potential tax impact, keep your 1099 records organized, and pay closer attention to OID or early-withdrawal situations. For the broader picture, explore our CD Guide 2026.

    Get Smarter About Your CD Returns

    Want practical ideas about CDs, savings, rates, and personal finance? Join the FinanceInvestment newsletter for clear, useful money insights you can put to work.

    📧 subhashr325@gmail.com

    A good CD decision is about more than the headline rate. Keep taxes, timing, and your real cash needs in the same picture.

  • What Happens to a CD if a Bank Fails? 2026 Guide

    What Happens to a CD if a Bank Fails? 2026 Guide

    FINANCEINVESTMENT • CD GUIDE 2026

    What Happens to a CD if a Bank Fails?

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August,24, 2026.
    About 10–15 min read

    What happens to your CD when a bank fails? Learn how FDIC protection, CD maturity, accrued interest, and bank resolution can affect your money.

    What Happens to a CD if a Bank Fails? 2026 Guide
    What happens to a CD if a bank fails? Learn how FDIC protection works, what happens to your principal and interest, and what CD holders should expect.
    what-happens-to-a-cd-if-a-bank-fails
    What Happens to a CD if a Bank Fails
    CD if bank fails, what happens to CD when bank fails, bank failure CD, FDIC insured CD bank failure, CD deposit insurance, FDIC CD protection, what happens to CD interest, CD maturity after bank failure, failed bank CD, FDIC bank failure
    https://financeinvestment.site/what-happens-to-a-cd-if-a-bank-fails/
    Subhash Rukade
    August 23, 2026
    About 10–15 minutes

    What Happens to a CD if a Bank Fails?

    What Happens to a CD if a Bank FailsA bank failure can make a CD owner wonder whether the money is suddenly frozen, lost, or stuck until the original maturity date. For an eligible deposit at an FDIC-insured bank, however, a bank closing does not simply make the CD disappear. The FDIC steps into the process and works to protect insured deposits under the applicable rules.

    What happens next depends on how the failed bank is resolved. In many cases, another bank assumes the failed institution’s deposits. If that happens, your CD may continue under the acquiring bank’s arrangements. If no acquiring institution takes over the deposits, the FDIC can pay insured depositors directly, subject to the applicable coverage limits.

    For CD holders, the important details are the issuing bank, insurance coverage, account ownership, principal, accrued interest, and the CD’s terms. A bank failure does not automatically mean you lose the interest you have earned or the entire deposit. At the same time, a failed-bank resolution can affect how and when you access the money, particularly when a CD is transferred to another institution.

    If you want the broader picture before diving into bank-failure scenarios, our CD Guide 2026 covers CD terms, rates, and strategies in one place.

    What You’ll Learn

    • What happens when an insured bank closes
    • How the FDIC handles failed-bank deposits
    • What can happen to your CD principal and accrued interest
    • How CD maturity and access may be affected
    • Why insurance limits and ownership still matter
    • What CD holders should check after a bank failure

    Quick Answer: What Happens to a CD if a Bank Fails?

    An eligible, FDIC-insured CD does not simply disappear when the issuing bank fails. The FDIC generally resolves the failure by arranging for another bank to assume the insured deposits or, when there is no acquiring bank, by paying depositors directly up to the applicable insurance limit.

    6 Key Takeaways

    1. Your insured balance remains protected: FDIC coverage includes principal and accrued interest through the bank’s failure date, subject to the applicable limit.
    2. Another bank may take over: In the most common resolution, a healthy bank assumes the failed bank’s insured deposits and customers become depositors of the acquiring institution.
    3. Your original CD terms may change: The acquiring bank is not required to keep the failed bank’s rates or account terms. Depositors may generally withdraw funds without an early-withdrawal penalty following the failure, subject to the applicable resolution terms.
    4. The FDIC may pay you directly: If no bank assumes the deposits, the FDIC can pay the insured balance directly.
    5. Amounts above insurance limits are different: Any uninsured portion is handled through the receivership process and is not guaranteed in the same way as insured deposits.
    6. Keep your records: Your CD statements, ownership information, and deposit records can help establish exactly what you own and how it should be treated.

    Bottom line: A bank failure can change who services your CD and may affect its original terms, but an eligible insured deposit is protected within the applicable FDIC limits. The key is knowing how much of your CD is insured and understanding what happens under the bank’s specific resolution.

    CD Bank Failure: At a Glance

    A bank failure does not automatically mean a CD holder has to start over. The outcome depends mainly on the FDIC resolution process and the amount of the depositor’s eligible funds that falls within applicable insurance coverage.

    What to CheckWhat It Means for Your CD
    FDIC-insured depositEligible funds are protected up to the applicable insurance limit.
    Principal + accrued interestBoth are considered when determining the insured balance, subject to coverage limits.
    Acquiring bankA healthy bank may assume the deposits and provide access to insured funds.
    No acquiring bankThe FDIC may pay depositors directly up to the insured balance.
    CD maturityThe treatment can depend on the resolution and the acquiring institution’s arrangements.
    Amount above coverageThe uninsured portion is handled through the failed bank’s receivership and is not protected like an insured deposit.

    One detail is easy to miss: an acquiring bank is not required to preserve the failed bank’s original rates or account terms. The FDIC notes that depositors can generally withdraw funds without an early-withdrawal penalty following the failure, subject to the resolution arrangements.

    For complicated deposit structures, the FDIC’s Electronic Deposit Insurance Estimator can help you review coverage across CDs and other eligible deposits at the same bank.

    Complete Beginner Guide: What a Bank Failure Means for Your CD

    A bank failure is the official closing of a bank because it can no longer meet its obligations. For a CD holder, that event changes who is responsible for the deposit, but it does not automatically turn an eligible insured CD into a loss.

    The FDIC Has Two Different Jobs

    It helps to separate two FDIC roles. As the insurer, the FDIC protects eligible deposits up to the applicable insurance limit. As the receiver, it takes control of the failed bank, handles its assets and settles claims, including claims involving deposits above the insured limit.

    That distinction matters because insured and uninsured money do not receive the same treatment. FDIC insurance covers an eligible CD’s principal and interest accrued or due through the bank’s failure date, subject to the applicable coverage limit.

    Where Your CD Fits Into the Process

    If another bank takes over the failed institution’s deposits, your insured deposit can move to the acquiring bank. You become a customer of that institution, but the original deposit agreement does not simply carry over unchanged. The acquiring bank is not required to keep the failed bank’s rate or account terms. FDIC guidance also says depositors can generally withdraw insured funds without an early-withdrawal penalty after the failure, subject to the resolution arrangements.

    If there is no acquiring bank for the deposits, the FDIC can pay depositors directly for their insured balance. Interest stops accruing on the failed bank’s accounts at the time of closing; if an acquiring bank takes over the deposits, that bank becomes responsible for establishing the post-failure interest treatment.

    Why Your Other Deposits Still Matter

    Insurance is calculated by depositor, insured bank, and ownership category. Your CD therefore cannot always be viewed separately from other deposits you hold at the same institution. Funds above the applicable insurance limit become part of the receivership claim rather than receiving the same guaranteed treatment as insured deposits.

    Brokered CDs Need an Extra Check

    A brokered CD can qualify for pass-through FDIC insurance when the underlying requirements are satisfied. The actual owner must own the funds, and the relevant ownership and agency information must be properly recorded. A brokerage platform itself is not the insurer.

    Beginner tip: If you ever receive a bank-failure notice, keep your CD statements and ownership records handy. Check the FDIC’s instructions for that specific failure rather than assuming your original CD rate, maturity date, or access rules will remain unchanged.

    How It Actually Works After a Bank Failure

    The process usually moves quickly, but the exact steps depend on how the failed bank is resolved. Here is what a CD holder can generally expect.

    1. The Bank Closes

    When regulators close an insured bank, the FDIC immediately begins working on the deposit side of the failure. Its goal is to provide prompt access to insured deposits.

    2. Another Bank May Take Over

    The preferred and most common resolution is a purchase-and-assumption transaction. A healthy bank assumes the failed bank’s insured deposits. Your insured CD can then become a deposit at the acquiring institution, giving you access to the covered funds.

    That does not guarantee the old CD rate will continue. The acquiring bank can establish different interest rates and terms. Depositors generally have the option to withdraw insured funds without an early-withdrawal penalty following the failure, subject to the specific resolution arrangements.

    3. The FDIC May Pay You Directly

    If no acquiring bank takes the deposits, the FDIC can pay the insured balance directly. Such payments generally begin within a few days of the bank closing, although accounts requiring additional documentation can take longer.

    What Happens to Interest?

    Interest is covered through the bank’s failure date, within the applicable insurance limit. Interest stops accruing at the failed bank when it closes. If another bank assumes the deposits, that bank becomes responsible for setting the post-failure interest treatment. If the FDIC pays the insured balance directly, interest does not continue beyond the failure date.

    Illustrative example: Suppose Maria has an eligible $40,000 CD when her bank fails. If another bank assumes the deposit, Maria may receive access through the new institution, but the new bank could establish a different rate. If the FDIC instead pays her directly, the insured amount would be paid based on the applicable coverage rules, and interest would not continue after the failure date.

    Benefits & Drawbacks of FDIC Protection

    What Happens to a CD if a Bank FailsFDIC protection gives CD owners an important safety net, but it does not mean every part of the original CD agreement survives a bank failure unchanged. The biggest benefit is protection of eligible deposits; the main tradeoff is that the resolution can alter how the CD is serviced.
    ✓ Benefits

    • Eligible deposits are protected: Covered principal and accrued interest receive FDIC protection within the applicable limits.
    • Access may return quickly: When another bank assumes the deposits, customers may regain access without waiting for the entire receivership to finish.
    • No separate insurance purchase: Eligible deposits receive FDIC insurance automatically; you do not buy a separate policy for the CD.
    • Less uncertainty about principal: Within the coverage limit, a qualifying deposit is treated differently from a market investment during a bank failure.

    △ Drawbacks

    • The rate may change: An acquiring bank does not necessarily have to preserve the failed bank’s original CD rate.
    • Terms may be different: Servicing arrangements and account conditions can change after the transfer.
    • Coverage has limits: Money above the applicable insurance limit is not protected in the same way as an insured deposit.
    • Access can feel unfamiliar: Even when funds are protected, customers may need to follow new instructions or work with a different institution.

    The important distinction is that deposit protection and contract continuity are not the same thing. FDIC insurance can protect an eligible balance, while the bank-failure resolution determines how that deposit is transferred or paid.

    CD Bank-Failure Comparison: How Does Your Money Differ?

    A CD is only one way to hold cash. The useful comparison here is how each option behaves when the institution behind it runs into trouble, not simply which one offers the highest yield.

    OptionProtectionAccessReturn / Market Exposure
    FDIC-insured CDFDIC protection for eligible deposits within applicable limitsUsually restricted until maturity, although a bank failure can change access arrangementsFixed CD rate; no daily market pricing
    High-yield savings accountFDIC or NCUA protection when eligibleGenerally more flexibleRate can change; no stock-market exposure
    Treasury securitiesBacked by the U.S. government, not FDIC insuranceCan generally be sold before maturity, subject to market conditionsKnown terms, but market prices can move before maturity
    Money market deposit accountFDIC or NCUA protection when eligibleTypically more accessible than a CDRate can change; no stock-market exposure
    Stocks and bondsNot FDIC-insuredGenerally tradableMarket prices can rise or fall

    For someone building a CD portfolio, the term can matter as much as the institution. You can compare 6-month CD rates or 1-year CD rates when shorter commitments are more useful. Longer timelines can be explored through the 3-year CD guide or 5-year CD guide.

    The key difference is the type of protection involved. An eligible CD and savings account rely on federal deposit insurance when held at an insured institution. Treasury securities rely on the U.S. government’s backing, while stocks and bonds are market investments whose values can fluctuate.

    Costs, Risks & Expert Tips After a Bank Failure

    FDIC protection removes one major fear from an eligible CD, but it does not make every part of the experience predictable. A bank failure can create practical issues around rates, access, uninsured balances, and what you do with the money afterward.

    Your CD Rate May Not Survive the Transfer

    If another bank assumes the failed bank’s deposits, the acquiring institution does not necessarily have to keep the original CD rate. That can create a reinvestment risk: you may suddenly have money available at a time when comparable CD rates are lower than the rate you originally locked in. The FDIC explains that acquiring institutions may establish their own interest rates and terms.

    Watch the Uninsured Portion

    The biggest financial concern is usually the amount that falls outside applicable FDIC coverage. Deposits above the insurance limit become part of the failed bank’s receivership process rather than receiving the same protection as insured deposits. Recovery of an uninsured amount can depend on the value of the bank’s assets and the receivership process.

    That is why a large CD balance deserves more attention than simply comparing APYs. Review your other deposits at the same bank and consider how ownership categories affect your total coverage.

    Brokered CDs Need Extra Attention

    If you purchased a CD through a brokerage or another platform, identify the actual issuing bank. Pass-through insurance can apply when the required ownership and recordkeeping conditions are satisfied, but the platform itself is not the FDIC insurer.

    Practical Ways to Reduce Surprises

    • Verify the issuing bank’s FDIC status before depositing.
    • Keep your CD confirmation, statements, and ownership records.
    • Review all deposits held at the same institution.
    • Don’t assume a familiar financial platform means every CD is insured.
    • Read bank-failure notices carefully if your institution closes.
    • Keep some cash outside CDs so a resolution does not disrupt your entire cash reserve.

    Expert Tip

    Don’t build your CD strategy around the assumption that a bank failure will preserve your original rate. Treat FDIC insurance as protection for eligible deposits—not a promise that every original CD feature will remain unchanged. For larger balances, map your deposits by bank and ownership category before opening another certificate.

    Common Mistakes + A Real-Life Example

    A bank failure is stressful enough without discovering that a few assumptions about your CD were wrong. The most avoidable problems usually come from overlooking the details attached to the deposit.

    Common Mistakes to Avoid

    • Assuming FDIC insurance preserves every CD term: Insurance protects eligible deposits within applicable limits. It does not guarantee that an acquiring bank will keep the failed bank’s original rate or terms.
    • Ignoring uninsured balances: If your deposits exceed the applicable coverage limit, the excess is handled through the receivership process and does not receive the same protection as the insured portion.
    • Keeping too much cash at one institution: Several CDs and other deposits can count toward the same coverage calculation when they share the same ownership category.
    • Not identifying the issuing bank: When a CD is purchased through a financial platform, check which bank actually issued it. The platform itself may not be the insured institution.
    • Assuming your original rate will continue: A new bank that assumes deposits may establish different rates or terms.
    • Skipping official notices: The FDIC or acquiring bank may provide important instructions about access, account servicing, and what happens next. Don’t treat those messages as routine paperwork.

    Real-Life Example: David’s CD Strategy

    David has $180,000 in a CD and $90,000 in an individual savings account at the same bank. He assumes both accounts are separately protected because they are different products. When the bank fails, he discovers that the ownership category matters more than the account names.

    Illustrative calculation: $180,000 + $90,000 = $270,000. This example does not determine David’s actual insurance payout because the applicable ownership rules and accrued interest must also be reviewed. It simply shows why looking at each account separately can produce the wrong impression.

    David also reads the acquiring bank’s notice instead of assuming his original CD rate will remain unchanged. That gives him a clearer picture of what happens next and what choices are available under the resolution.

    Practical lesson: Don’t judge your protection by the CD’s APY or account name alone. Know the issuing bank, review your combined deposits, keep your records, and read the official resolution instructions if the institution ever fails.

    Who Should Be Most Concerned About Bank Failure?

    Bank failure is not something most CD savers need to worry about every day. The bigger issue is whether your deposit setup could leave you exposed if your institution runs into trouble.

    Savers Who Should Pay Closer Attention

    • People with large balances: If your eligible deposits may exceed applicable FDIC coverage limits, review the amount that could fall outside insurance.
    • Savers using one institution for everything: Keeping CDs, savings, and other deposits at one bank can make the total coverage calculation more important.
    • Brokered-CD holders: If you bought CDs through a brokerage or platform, identify the underlying issuing bank and understand how your ownership is recorded.
    • People without liquid reserves: A bank resolution can create uncertainty around account access. Keeping separate emergency cash at an accessible institution can provide breathing room.
    • Savers with complicated ownership: Trusts, joint accounts, business deposits, and other ownership arrangements can have different insurance rules. These situations deserve a closer review rather than a quick $250,000 calculation.

    Who May Be Comfortable With a Straightforward Insured CD?

    A saver with a manageable balance, a clearly identified FDIC-insured bank, a simple ownership structure, and separate liquid cash may have a much simpler setup to monitor.

    Quick decision guide: Review your bank exposure more carefully when your balances are large, your ownership structure is complex, or your CD came through a broker. If your deposit structure is simple and your emergency money remains liquid elsewhere, an insured CD can be easier to manage.

    Frequently Asked Questions About CDs and Bank Failures

    What happens to a CD when a bank fails?

    The FDIC generally arranges for another bank to assume insured deposits or pays depositors directly up to the applicable insured amount. Your CD does not simply disappear because the issuing bank closes.

    Does FDIC insurance protect CD principal?

    Yes, eligible CD principal is protected up to the applicable FDIC insurance limit. Coverage also includes qualifying accrued interest through the bank’s failure date.

    What happens to accrued CD interest?

    Interest accrued through the failure date is included when determining the insured balance, subject to the applicable coverage limit. Interest does not continue accruing at the failed bank after closure.

    Does the original CD rate continue after a bank failure?

    Not necessarily. An acquiring bank is not required to maintain the failed bank’s original rates or account terms.

    Can I withdraw a CD after a bank failure?

    If another bank assumes the deposit, depositors generally have the option to withdraw some or all insured funds without an early-withdrawal penalty, subject to the specific resolution arrangements.

    What happens if my CD exceeds FDIC coverage?

    The insured portion receives FDIC protection. Any uninsured amount becomes a claim against the failed bank’s receivership and is not guaranteed in the same way as an insured deposit. Recovery can depend on the assets available to the receivership.

    What happens to a brokered CD when the issuing bank fails?

    The treatment depends on the underlying issuing bank, ownership records, and whether the CD qualifies for applicable pass-through insurance. The brokerage platform itself is not the FDIC insurer.

    What happens to a CD’s maturity date after a bank failure?

    The original maturity date should not be assumed to remain unchanged. An acquiring institution can establish different terms, so CD holders should follow the official instructions provided during the bank-failure resolution.

    Is a CD at a credit union protected by FDIC or NCUA insurance?

    Eligible time deposits such as share certificates at federally insured credit unions are generally covered by NCUA share insurance rather than FDIC insurance. NCUA says eligible share accounts are insured up to applicable limits, including principal and posted dividends through the credit union’s closing date.

    Illustrative: What if I have a $300,000 CD when my bank fails?

    Illustrative example only: A $300,000 CD does not automatically receive $300,000 of standard FDIC coverage. The depositor’s ownership category, other deposits at the same bank, accrued interest, and applicable insurance rules would need to be reviewed to determine the protected amount.

    Final Verdict: What Should CD Holders Expect?

    If an FDIC-insured bank fails, an eligible CD does not simply vanish. The insured deposit is handled through the FDIC’s resolution process, which may involve transferring deposits to another bank or paying the insured amount directly. For most CD owners, the more important question is not whether the money exists, but how the failed bank’s resolution changes the way that money is handled.

    Your total deposits, ownership category, and accrued interest matter when determining how much receives FDIC protection. That makes it important to look at your entire relationship with the bank rather than viewing one CD in isolation.

    Also, don’t assume the original CD rate or maturity arrangement will remain untouched. An acquiring institution may establish different rates or terms. If that happens, your next decision may involve keeping the funds with the new bank or moving them elsewhere.

    Practical takeaway: FDIC insurance can provide meaningful confidence for eligible CD deposits, but good CD planning starts before a failure occurs. Verify the issuing bank, understand your coverage, keep important records, and maintain enough liquid cash outside CDs for everyday needs.

    For the bigger picture on choosing terms, rates, and CD strategies, explore our CD Guide 2026.

    Stay Informed About Smarter CD Decisions

    Want practical insights on CDs, savings, rates, and everyday money decisions? Join the FinanceInvestment newsletter for useful ideas without the financial jargon.

    📧 subhashr325@gmail.com

    Keep your CD strategy simple: understand the protection, know your limits, and choose terms that fit your cash needs.

    “

  • How to Maximize Savings Interest in 2026: A Complete Beginner’s Guide

    How to Maximize Savings Interest in 2026: A Complete Beginner’s Guide


    ✓ Editorially Reviewed

    FinanceInvestment Editorial Team

    Our editorial team researches trusted financial sources and converts complex banking topics into practical, easy-to-follow guidance for American readers. Every article is reviewed for accuracy, readability, and real-world usefulness before publication.

    Written By
    FinanceInvestment, Subhash Rukade. 
    Updated
    July 30, 2026
    Reading Time
    12–14 Min


    How to Maximize Savings Interest: Smart Ways to Make Every Dollar Work Harder in 2026

    How to Maximize Savings InterestSaving money is a great habit, but where you keep that money can make a bigger difference than many people realize. If your savings account pays a low interest rate, your balance may grow much more slowly than it could. Learning how to maximize savings interest helps you earn more without taking on the risks that come with investing in the stock market.

    A few simple decisions—such as choosing a competitive APY, keeping your money in the right account, and letting compound interest do its job—can add hundreds or even thousands of extra dollars over time. The best part is that these strategies are easy to follow, even if you’re just getting started.

    In this guide, you’ll discover practical ways to increase your savings earnings, avoid common mistakes, and choose habits that can help your money grow steadily throughout 2026. If you’re new to high-yield savings accounts, our complete guide to

    High-Yield Savings Accounts USA

    is the perfect place to begin.

    What You’ll Learn

    • Why some savings accounts earn much more interest than others.
    • Simple strategies that can increase your annual savings earnings.
    • How APY and compound interest work together.
    • Common habits that reduce your interest income.
    • When switching to a better savings account makes financial sense.
    • Practical tips that beginners, families, and retirees can use right away.


    Quick Answer

    The easiest way to maximize savings interest is to keep your money in a high-yield savings account that offers a competitive APY, add money consistently, and avoid unnecessary withdrawals. Even a small difference in APY can lead to noticeably higher earnings over time, especially when interest compounds month after month.

    You don’t need a large balance to benefit. Building the habit of saving regularly and reviewing your account once or twice a year can make a meaningful difference without changing your daily routine.

    Key Takeaways

    • Choose a savings account with a competitive APY instead of settling for a low rate.
    • Deposit money regularly so your balance has more time to earn interest.
    • Leave your savings untouched whenever possible to benefit from compound growth.
    • Compare rates every few months because banks may change their offers.
    • Online banks often provide higher savings rates than many traditional banks.
    • Keep separate savings goals so you’re less likely to spend your emergency fund.

    Bottom Line

    Growing your savings isn’t only about putting away more money. It’s also about making sure every dollar earns as much interest as possible. A few smart choices today can help your savings grow faster throughout 2026 without taking on extra investment risk.


    At a Glance

    If your savings account isn’t earning much interest, a few small changes can make a noticeable difference. Moving your money to a competitive high-yield savings account, saving consistently, and allowing interest to compound can help your balance grow faster without adding extra risk. The goal isn’t simply to save more—it’s to make every dollar earn as much as it can.

    Quick FactDetails
    Best ForAnyone who wants to earn more from their savings with minimal risk.
    Main GoalIncrease interest earnings while keeping your money safe and accessible.
    Works Best WithHigh-yield savings accounts, automatic deposits, and compound interest.
    Risk LevelLow when using FDIC-insured banks or NCUA-insured credit unions.
    Time CommitmentOnly a few minutes each month to review rates and keep savings on track.


    Complete Beginner Guide

    How to Maximize Savings InterestLearning how to maximize savings interest isn’t about finding a secret trick. It’s about making smarter choices with the money you’re already saving.How to Maximize Savings Interest A higher interest rate may look like a small change on paper, but over months and years, it can leave you with a much larger balance.

    The first step is choosing the right savings account. Many traditional banks still offer very low interest rates, while many online banks pay several times more through high-yield savings accounts. Before opening a new account, compare the Annual Percentage Yield (APY) rather than looking only at the basic interest rate. If you’re unsure about the difference, read our guide on

    APY vs. Interest Rate Explained
    .

    Next, make saving automatic. Scheduling a transfer every payday removes the temptation to spend first and save later. Even small deposits made consistently can build momentum because every new dollar starts earning interest immediately.

    Another habit that often goes unnoticed is leaving your savings alone.How to Maximize Savings Interest Withdrawing money frequently reduces the balance that earns interest. If your emergency fund is separate from your everyday spending account, you’ll be less likely to dip into it for purchases that can wait. Organizing your money into different savings goals also helps. Our guide on

    Savings Buckets Explained

    shows one simple way to do that.

    It’s also worth checking your savings account once or twice a year. Banks regularly adjust their APYs, and a bank that offered one of the best rates last year may no longer be as competitive. Switching to a better account is often easier than people expect. If you’re considering a move, this guide on

    How to Switch Savings Accounts

    walks through the process.

    Finally, give your savings time. Interest grows gradually, and compound interest rewards patience. The longer your money stays in the account, the more opportunities it has to earn interest on both your deposits and the interest you’ve already earned. That’s how steady saving turns into meaningful financial progress.


    How It Works

    Understanding how to maximize savings interest becomes much easier once you know what happens behind the scenes. Every dollar in your savings account has the chance to earn interest. As your balance grows, the amount of interest you receive can grow as well.”How to Maximize Savings Interest” Over time, this creates a cycle where your money begins working for you instead of simply sitting in the bank.

    1. Start with a Competitive APY

    The interest your bank pays has the biggest impact on your earnings. Two accounts may look similar, but a higher APY can produce noticeably better results over several years. That’s why comparing APYs before opening an account is worth a few extra minutes. If you’re still deciding where to save, our guide on

    How to Open a High-Yield Savings Account

    can help you get started.

    2. Add Money Consistently

    Interest is calculated using the money already in your account. Every deposit increases the balance that can earn interest.”How to Maximize Savings Interest” Whether you save $25 or $500 each payday, building the habit matters more than waiting until you can save a large amount.

    3. Let Compound Interest Do the Heavy Lifting

    When interest is added to your account, future interest is calculated on that larger balance. This is known as compound interest. At first the growth feels slow, but as months and years pass, the effect becomes much more noticeable. If you’d like a deeper explanation, read our guide on

    Compound Interest Explained
    .

    4. Avoid Unnecessary Withdrawals

    Every time you take money out, the balance earning interest becomes smaller.How to Maximize Savings Interest It’s perfectly fine to use your savings for real emergencies, but using it for everyday spending can slow your progress. Keeping a separate checking account for monthly expenses makes this much easier.

    5. Review Your Account Every Year

    Banks regularly change their savings rates to match market conditions. A quick annual review can tell you whether your current account is still competitive. If another bank offers a better APY with similar features and no hidden fees, switching may help your savings grow faster without changing your saving habits.

    Expert Insight

    Many people focus only on saving more money, but they rarely check whether that money is earning its full potential. A yearly APY review takes only a few minutes and could increase your interest income without requiring larger monthly deposits.


    Benefits & Drawbacks

    ✅ Benefits

    • Your savings earn more without taking on stock market risk.
    • Higher APYs can add meaningful extra income over time.
    • Compound interest rewards patience by helping your balance grow faster.
    • Automatic deposits make saving feel effortless and build consistency.
    • Money usually stays easy to access for emergencies or planned expenses.
    • FDIC-insured banks and NCUA-insured credit unions provide strong protection within coverage limits.

    ❌ Drawbacks

    • Savings rates can rise or fall as market conditions change.
    • Interest earnings may not always keep pace with high inflation.
    • Some banks require minimum balances to unlock their best APY.
    • Moving money too often just to chase small rate changes may not be worth the effort.
    • Savings accounts are designed for stability, not for the higher long-term returns that investments may provide.

    Finding the Right Balance

    For most people, a high-yield savings account works best as a place to keep an emergency fund, short-term goals, or money you’ll need within the next few years.How to Maximize Savings Interest It offers a combination of safety, flexibility, and steady growth. Once your short-term savings are in good shape, you can explore other options for long-term wealth building while allowing your cash savings to continue earning interest in the background.


    Comparison Table

    Not every saving habit produces the same results. Some approaches help your money grow steadily, while others leave you earning very little interest. The table below compares common saving choices so you can see where the biggest opportunities are.

    StrategyInterest PotentialBest For
    Traditional Savings AccountLowEveryday banking and basic savings
    High-Yield Savings AccountHighEmergency funds and short-term financial goals
    Automatic Monthly DepositsHighAnyone building consistent saving habits
    Leaving Money UntouchedHighLonger-term savings with compound growth
    Frequent WithdrawalsLowNot recommended unless truly necessary


    Costs, Risks & Expert Tips

    One of the biggest advantages of learning how to maximize savings interest is that it usually doesn’t cost anything. Most high-yield savings accounts have no monthly maintenance fee, and opening an account often takes only a few minutes.How to Maximize Savings Interest Even so, it’s worth reading the account details before moving your money.

    Costs & Risks

    • Some banks charge fees if your balance falls below a required minimum.
    • Promotional APYs can change after a limited period, so check the ongoing rate.
    • Interest rates may decrease when overall market rates decline.
    • Keeping all of your long-term money in savings may limit your growth compared with investing for retirement.

    Expert Tip

    Instead of chasing every tiny APY increase, focus on banks with a strong reputation, no monthly fees, and competitive long-term rates.”How to Maximize Savings Interest A consistent saving habit usually has a much bigger impact than switching accounts every few weeks for a slightly higher return.

    Keep in Mind

    Review your savings account once or twice a year. If your rate has fallen well below other competitive options, it may be a good time to compare accounts. A quick review can help your savings continue earning more without changing your financial goals.


    Common Mistakes + Real-Life Example

    Many people work hard to save money but still miss out on extra interest because of a few avoidable habits.”How to Maximize Savings Interest The good news is that these mistakes are easy to fix once you know what to watch for.

    Common Mistakes

    • Leaving savings in an account that pays a very low APY for years without comparing better options.
    • Skipping automatic transfers and saving only when money is left at the end of the month.
    • Making frequent withdrawals for non-essential purchases, which reduces the balance earning interest.
    • Ignoring APY changes and assuming the bank will always offer a competitive rate.
    • Keeping emergency savings and daily spending money in the same account, making it easier to spend savings unintentionally.

    Real-Life Example

    Emily, a first-time saver from Texas, kept nearly all of her emergency fund in a traditional savings account because it was linked to her checking account. The money was safe, but the interest she earned each month was barely noticeable.

    After comparing different banks, she opened a high-yield savings account, set up an automatic transfer every payday, and stopped using her emergency fund for everyday shopping. She also checked her account once a year to make sure the APY remained competitive.

    Within the next year, Emily had not only saved more money through regular deposits, but she also earned significantly more interest than before. The biggest change wasn’t how much she earned at work—it was making better use of the money she had already saved.


    Who Should Choose This?

    The strategies in this guide aren’t just for experienced savers. They can help almost anyone who wants their money to grow a little faster while keeping it safe and easy to access.

    • Beginners who are building their first emergency fund and want to earn more interest from the start.
    • Families saving for vacations, home repairs, education costs, or other short-term financial goals.
    • Retirees looking for a secure place to keep cash while earning a competitive return.
    • Young professionals who receive regular paychecks and want automatic savings to become part of their monthly routine.
    • Anyone with money sitting in a low-interest savings account who wants better growth without taking on stock market risk.

    If your goal is to keep your savings safe while earning as much interest as reasonably possible, these habits are a practical place to start.How to Maximize Savings Interest Small improvements made today can continue benefiting your savings for years to come.


    Frequently Asked Questions

    1. What is the easiest way to maximize savings interest?

    The simplest approach is to move your money into a high-yield savings account, make regular deposits, and leave your savings untouched whenever possible.”How to Maximize Savings Interest” These three habits work together to help your balance grow steadily over time.

    2. Does a higher APY really make a difference?

    Yes. Even a small increase in APY can add up over several years, especially if you continue adding money to your account. The larger your balance and the longer you save, the more noticeable the difference becomes.

    3. How often should I compare savings account rates?

    Checking once or twice a year is usually enough for most people. If your bank’s rate falls well behind other competitive accounts, it may be worth considering a switch.

    4. Is my money safe in a high-yield savings account?

    If your account is held at an FDIC-insured bank or an NCUA-insured credit union and your balance stays within the applicable insurance limits, your deposits are protected even if the financial institution fails.

    5. Should I keep all of my money in a savings account?

    Not necessarily. A savings account is a great place for emergency funds and short-term goals.How to Maximize Savings Interest Money you won’t need for many years may be better suited to long-term investments, depending on your financial goals and comfort with risk.

    6. Can I earn interest if I only save a small amount each month?

    Absolutely. Every deposit starts earning interest. Saving consistently is often more important than the size of each individual deposit because the habit builds your balance over time.

    7. Do online banks usually pay higher interest?

    Many online banks offer more competitive APYs because they generally have lower operating costs than traditional branch-based banks. That’s one reason they’re popular with savers looking to increase interest earnings.

    8. Will savings interest rates stay the same throughout the year?

    No. Banks can adjust their rates as economic conditions and market interest rates change. Reviewing your account periodically helps ensure you’re still earning a competitive return.

    9. Can I withdraw money whenever I need it?

    In most cases, yes. High-yield savings accounts are designed to keep your money accessible, although some banks may place limits on certain types of withdrawals. Reading your account terms before opening an account is always a good idea.


    Final Verdict

    Learning how to maximize savings interest doesn’t require a large income or years of financial experience. In many cases, a few thoughtful changes—choosing a competitive high-yield savings account, saving consistently, and allowing compound interest to work over time—can make a noticeable difference.

    There’s no need to chase every small rate change or constantly move your money from one bank to another.”How to Maximize Savings Interest A reliable account with a strong APY and healthy saving habits will usually deliver better long-term results than making frequent switches.

    If you’re building an emergency fund or looking for the best place to keep short-term savings, start with a solid foundation. Our complete guide to

    High-Yield Savings Accounts USA

    explains how to compare accounts, understand APYs, and choose the right option for your financial goals.

    The earlier you start, the more time your savings has to grow. Even small steps taken today can lead to a stronger financial future tomorrow.


    Keep Building Your Financial Future

    Every smart financial habit starts with one simple step. Keep learning, compare your options, and make decisions that help your money grow over time. Small improvements today can create more financial freedom in the years ahead.