Tag: financial planning

  • Best Savings Accounts for Families in 2026: Compare Top Family Savings Options

    Best Savings Accounts for Families in 2026: Compare Top Family Savings Options


    FI

    FinanceInvestment Editorial Team

    Independent personal finance researchers dedicated to helping American families make smarter banking, saving, and investing decisions through accurate, practical, and easy-to-understand financial guides.


    ✍ Written by FinanceInvestment Editorial Team   Subhash                Rukade.


    ✔ Reviewed by Financial Research Team


    ✓ Fact Checked


    📅 Updated: July 23, 2026


    ⏱ Reading Time: 12 Minutes


    🛡 Editorial Integrity Reviewed

    This guide was researched using publicly available information from reputable financial institutions and government resources. Our editorial team evaluates savings account features, interest rates, fees, accessibility, and consumer protections to provide unbiased recommendations for families in the United States.


    Best Savings Accounts for Families in 2026

    Best Savings Accounts for FamiliesFinding the best savings accounts for families isn’t just about earning a higher interest rate. It’s about choosing an account that helps your household save for both everyday needs and long-term goals. Whether you’re building an emergency fund, planning a family vacation, saving for your child’s education, or preparing for retirement, the right savings account can make managing money much easier.

    With so many banks offering different APYs, fees, mobile apps, and family-friendly features, deciding where to keep your savings can feel overwhelming. Some accounts reward larger balances, while others focus on flexibility, digital banking, or automatic savings tools. Knowing what matters most can help you avoid unnecessary fees and earn more from your money.

    This guide is designed to simplify the process. You’ll learn how best savings accounts for families work, which features deserve your attention, how to compare banks confidently, and the common mistakes families should avoid before opening an account. We’ll also explain how high-yield savings accounts compare with traditional bank accounts and what to consider before making a final decision.

    By the end of this guide, you’ll have the knowledge to choose a savings account that fits your family’s financial goals, keeps your money secure, and helps every dollar work harder for your future.


    💡 Quick Answer

    If you’re looking for the best savings accounts for families, focus on more than just the highest APY. A great family savings account should offer competitive interest rates, no monthly maintenance fees, FDIC insurance, easy online access, and tools that make saving for multiple goals simple. The right account can help your family grow an emergency fund, prepare for future expenses, and keep your savings secure while earning interest.

    📌 Key Takeaways

    • Choose accounts with competitive APYs and no monthly maintenance fees.
    • Make sure the bank offers FDIC insurance for eligible deposits.
    • Compare mobile banking features, automatic savings tools, and account accessibility.
    • Look for flexible options that support both short-term and long-term family goals.
    • Review balance requirements and withdrawal rules before opening an account.
    • Compare several banks instead of selecting the first account you find.

    Bottom Line: The best savings accounts for families combine strong returns, low costs, and convenient banking features, making it easier to build financial security for every stage of family life.


    Table of Contents

    1. What Are Family Savings Accounts?
    2. How Family Savings Accounts Work
    3. Benefits and Drawbacks
    4. Comparison of Popular Savings Account Options
    5. Costs, Risks, and Expert Tips
    6. Common Mistakes to Avoid
    7. Who Should Open a Family Savings Account?
    8. Frequently Asked Questions
    9. Final Verdict


    Best Savings Accounts for Families at a Glance

    The best savings accounts for families help households save for both planned and unexpected expenses while earning interest on their money. Whether you’re building an emergency fund, saving for your children’s education, planning a vacation, or preparing for retirement, choosing the right account can make reaching those goals much easier.

    Not every savings account offers the same value. Some banks focus on higher Annual Percentage Yields (APYs), while others provide better digital banking tools, lower fees, or features designed for busy families. Comparing these details before opening an account can help you maximize your savings and avoid unnecessary costs.

    FeatureQuick Overview
    Best ForFamilies building emergency funds and long-term savings.
    Interest EarningsCompetitive APYs help savings grow faster than many traditional accounts.
    Monthly FeesMany top accounts charge no monthly maintenance fee.
    SafetyLook for FDIC-insured banks to protect eligible deposits.
    Digital FeaturesMobile apps, automatic transfers, and savings goal trackers.
    Ideal Savings GoalsEmergency funds, education, home improvements, vacations, and future family expenses.

    Quick Summary: The best savings accounts for families offer a balance of competitive interest rates, low fees, convenient online banking, and secure FDIC protection. Choosing an account that matches your family’s financial goals can make saving easier and more rewarding over time.


    Complete Beginner’s Guide to Family Savings Accounts

    Best Savings Accounts for FamiliesIf you’ve never opened a family savings account before, don’t worry. The process is simpler than many people expect. The best savings accounts for families are designed to help households save money safely while earning interest. They also make it easier to prepare for both planned expenses and unexpected emergencies.
    A family savings account can be used for many financial goals. Some families save for a home down payment, while others build an emergency fund, set aside money for their children’s education, plan vacations, or prepare for major life events. Keeping these savings separate from everyday spending can make budgeting much easier.

    When comparing accounts, don’t focus only on the advertised APY. A higher interest rate is valuable, but you should also look at monthly maintenance fees, minimum balance requirements, withdrawal policies, customer service, and mobile banking features. Many online banks offer competitive rates along with helpful tools such as automatic transfers, savings goals, and spending alerts.

    Security is another important factor. Choose a bank that offers FDIC insurance for eligible deposits so your family’s savings remain protected. It’s also helpful to select an account with a simple mobile app that allows you to monitor balances, schedule transfers, and track your progress toward financial goals.

    The best savings accounts for families are those that fit your household’s needs, encourage consistent saving, and provide easy access when you need your money. Starting with regular monthly deposits—even small ones—can create healthy financial habits and help your savings grow steadily over time.


    How Family Savings Accounts Work

    The best savings accounts for families work much like a standard savings account, but they’re used to help households save for shared financial goals. After opening an account, you can deposit money whenever it fits your budget. As your balance grows, the bank pays interest based on the account’s Annual Percentage Yield (APY), allowing your savings to increase over time.

    Many families set up automatic transfers from their checking account every payday. This simple habit makes saving consistent and removes the need to remember monthly deposits. Even modest contributions can add up over time, especially when interest is earned on the growing balance.

    Most banks also provide online and mobile banking, making it easy to check your balance, schedule transfers, track savings goals, and monitor account activity from anywhere. Some accounts even include budgeting tools and savings trackers that help families stay focused on their financial plans.

    While the best savings accounts for families make it easy to access your money when needed, they’re designed for saving rather than everyday spending. Keeping these funds separate from your regular checking account can reduce unnecessary spending and help you stay on track toward important goals such as building an emergency fund, paying for education, or planning future family expenses.


    Benefits and Drawbacks of Family Savings Accounts

    The best savings accounts for families can help households build financial security while keeping money easily accessible for future needs. However, like any financial product, they have both advantages and limitations. Understanding both sides can help you choose an account that matches your family’s goals.

    ✅ Pros

    • Earn interest while keeping your money available when needed.
    • Many accounts have no monthly maintenance fees.
    • FDIC insurance protects eligible deposits.
    • Automatic transfers make regular saving easier.
    • Mobile banking apps help families track balances and savings goals.
    • Suitable for emergency funds, education savings, vacations, and other long-term family goals.

    ❌ Cons

    • Interest rates may change over time.
    • Some banks require a minimum balance to earn the highest APY.
    • Certain accounts may limit specific types of withdrawals or transfers.
    • Returns are generally lower than long-term investment options.
    • Account features and digital tools vary between banks.

    Overall, the best savings accounts for families provide a safe and flexible way to build savings. Comparing fees, interest rates, and account features before opening an account can help your family receive the greatest long-term value.


    Compare Different Family Savings Account Options

    Choosing the best savings accounts for families becomes easier when you compare the features that matter most. While every family has different financial goals, factors such as interest rates, monthly fees, digital banking tools, account accessibility, and FDIC protection can make a significant difference over time.

    The table below highlights the key differences you should evaluate before opening a family savings account.

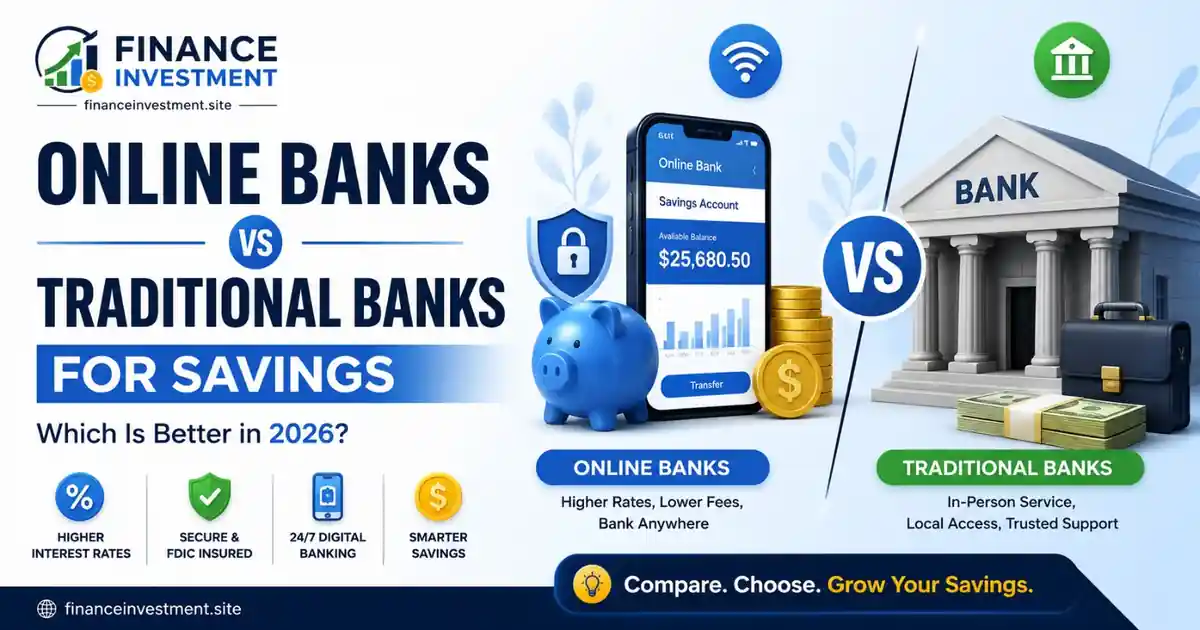
    FeatureTraditional BankOnline BankBest Choice
    Interest Rate (APY)Usually lowerOften more competitiveOnline Bank
    Monthly FeesMay applyOften no monthly feeOnline Bank
    Branch AccessExcellentLimited or noneTraditional Bank
    Mobile BankingGoodExcellentOnline Bank
    Automatic Savings ToolsAvailable at some banksCommon featureOnline Bank
    FDIC InsuranceYes (eligible deposits)Yes (eligible deposits)Both

    For many households, the best savings accounts for families are those that balance competitive interest rates, low fees, reliable customer service, and convenient digital banking. Comparing these features before opening an account can help your family choose a solution that supports both short-term needs and long-term financial goals.


    Costs, Risks, and Expert Tips

    The best savings accounts for families are often affordable, but it’s still important to understand the costs before opening an account. Many banks offer family savings accounts with no monthly maintenance fee, while others may charge fees if your balance falls below a required minimum. Reviewing the fee schedule can help you avoid unnecessary expenses.

    Interest rates are another factor to watch. A bank may advertise an attractive APY today, but savings rates can increase or decrease as market conditions change. It’s also worth checking whether the account has withdrawal limits, balance requirements, or conditions for earning the highest interest rate.

    💡 Expert Tip: Don’t choose the best savings accounts for families based only on the highest APY. Look for a combination of competitive interest rates, low fees, FDIC insurance, strong mobile banking, automatic savings tools, and reliable customer support. These features can provide greater value over the long term than a slightly higher interest rate alone.

    Comparing several banks before making a decision can help your family find an account that supports both your everyday needs and your future financial goals.


    Common Mistakes Families Make When Choosing a Savings Account

    Opening a savings account is an important step toward financial security, but choosing the wrong account can reduce the benefits over time. The best savings accounts for families should support your household’s goals, not create unnecessary costs or limitations. Avoiding a few common mistakes can help your savings grow more efficiently.

    Common Mistakes to Avoid

    • Focusing only on the highest APY: A high interest rate is attractive, but monthly fees, minimum balance requirements, and account features are just as important.
    • Ignoring fees: Even small maintenance fees can slowly reduce your family’s savings if you’re not paying attention.
    • Not comparing different banks: Checking several online and traditional banks often leads to better rates and more useful features.
    • Skipping automatic savings: Setting up recurring transfers makes it easier to save consistently without relying on memory.
    • Using savings for everyday spending: Keeping emergency savings separate from daily expenses helps protect your long-term financial goals.

    Real-Life Example

    The Johnson family wanted to build a stronger emergency fund after unexpected home repairs affected their budget. Instead of choosing the first bank they found, they compared several options and selected one of the best savings accounts for families with no monthly fees, a competitive APY, and automatic monthly transfers. By saving a fixed amount every payday, they steadily grew their emergency fund and felt more prepared for future expenses without making major changes to their lifestyle.


    Who Should Choose a Family Savings Account?

    The best savings accounts for families are a smart choice for households that want to build financial stability while keeping their money safe and accessible. Whether you’re saving for short-term expenses or planning years ahead, the right account can help you stay organized and reach your financial goals with confidence.

    • Parents with young children: Ideal for building emergency savings, education funds, or future family expenses.
    • Couples managing shared finances: A great way to save together for a home, vacations, or other major life goals.
    • Families creating an emergency fund: Keeping dedicated savings separate from everyday spending provides extra financial security.
    • New homeowners: Perfect for setting aside money for home maintenance, repairs, and unexpected costs.
    • Retirees supporting family members: Helpful for managing savings while remaining prepared for future financial needs.

    The best savings accounts for families offer competitive interest rates, low fees, FDIC protection, and convenient online banking. If your goal is to grow savings steadily while maintaining easy access to your money, opening a family savings account can be a practical step toward stronger long-term financial health.


    Frequently Asked Questions

    1. What is a family savings account?

    A family savings account is a bank account designed to help households save money for shared financial goals. Families often use these accounts to build emergency funds, save for vacations, children’s education, home improvements, or other future expenses while earning interest on their balance.

    2. What should I look for in the best savings accounts for families?

    When comparing the best savings accounts for families, look beyond the advertised APY. Consider monthly fees, minimum balance requirements, FDIC insurance, mobile banking features, customer service, and automatic savings tools. Choosing an account that fits your family’s lifestyle is just as important as earning a competitive interest rate.

    3. Are family savings accounts safe?

    Yes. If the account is held at an FDIC-insured bank, eligible deposits are protected up to the applicable federal insurance limits. This helps provide peace of mind while your family works toward its financial goals.

    4. Can I access my money whenever I need it?

    In most cases, yes. Savings accounts are designed to give you access to your funds when needed, although some banks may have policies regarding certain types of withdrawals or transfers. Always review the account terms before opening one.

    5. Do online banks offer better savings accounts?

    Many online banks offer higher APYs and lower fees because they have lower operating costs than traditional banks. However, the best choice depends on your family’s preferences for branch access, customer support, and digital banking features.

    6. Can I open more than one savings account?

    Absolutely. Many families use multiple savings accounts to organize different goals, such as emergency savings, vacations, holiday spending, or future education costs. Separating your savings can make budgeting easier.

    7. How much should a family keep in savings?

    The ideal amount depends on your income, monthly expenses, and financial goals. Many financial professionals recommend building an emergency fund that can cover several months of essential living expenses while continuing to save for future needs.

    8. Are family savings accounts better than keeping money in a checking account?

    For long-term savings, yes. The best savings accounts for families usually earn more interest than standard checking accounts while encouraging better saving habits and helping your money grow over time.


    Final Verdict

    The best savings accounts for families can play an important role in building long-term financial security. Whether you’re creating an emergency fund, saving for your children’s future, planning a family vacation, or preparing for unexpected expenses, the right savings account gives your money a safe place to grow while remaining accessible when you need it.

    Before opening an account, compare more than just the advertised APY. Review monthly fees, minimum balance requirements, FDIC insurance, mobile banking features, customer service, and automatic savings tools. A slightly lower interest rate may still offer greater overall value if the account provides better flexibility and fewer fees.

    The best savings accounts for families are those that match your household’s financial goals and encourage consistent saving over time. By choosing wisely and making regular deposits, your family can build stronger financial habits, stay prepared for life’s unexpected costs, and move confidently toward future milestones with greater peace of mind.


    📩 Stay One Step Ahead with Smarter Family Finance Tips

    If this guide on the Best Savings Accounts for Families helped you, join the FinanceInvestment newsletter for practical advice on saving, banking, retirement planning, investing, and building long-term wealth. Every guide is written to help you make confident financial decisions with simple, reliable information.


    📧 Subscribe Free

    ✔ Weekly Money Tips   •   ✔ Free Guides   •   ✔ Unsubscribe Anytime

    Continue Reading

  • Umbrella Insurance Explained: Complete USA Guide (2026)

    Umbrella Insurance Explained: Complete USA Guide (2026)


    Umbrella Insurance Explained: Complete USA Guide (2026)

    Author: Subhash Rukade

    Published: July 17, 2026

    Umbrella Insurance ExplainedWhy Umbrella Insurance Matters More Than Ever

    Umbrella Insurance Explained Umbrella Insurance Explained is one of the most important topics for Americans who want to protect their savings, home, investments, and future income from large liability claims. A single lawsuit caused by a serious auto accident, an injury on your property, or a personal liability claim can easily exceed the limits of your existing insurance policy. That’s where umbrella insurance becomes valuable.

    Many people believe umbrella insurance is only for millionaires, but that’s no longer true. Today, homeowners, families, landlords, business owners, and even individuals with growing assets can benefit from this affordable extra layer of liability protection. For a relatively low annual premium, an umbrella policy can provide an additional $1 million or more in liability coverage beyond your home or auto insurance.Umbrella Insurance Explained

    If you’re new to insurance, start with our Insurance for Beginners USA Guide (2026). It explains essential insurance terms, policy types, and coverage options before you explore umbrella insurance.

    In this guide, you’ll learn how umbrella insurance works, what it covers, what it doesn’t cover, typical costs, who should buy it, and practical tips to choose the right policy in 2026. By the end, you’ll know whether umbrella insurance is the right choice to strengthen your family’s financial protection.

    💡 Quick Tip

    If your total assets or future income are worth more than your current liability limits, an umbrella insurance policy can help protect your financial future from expensive lawsuits and major liability claims.


    Quick Answer: What Is Umbrella Insurance?

    Umbrella Insurance is an extra layer of personal liability Umbrella Insurance Explained protection that starts after the liability limits of your existing auto, homeowners, renters, or boat insurance have been exhausted. It helps protect your savings, investments, future income, and other assets from expensive lawsuits and large claims. Because it offers high liability limits for a relatively low annual premium, umbrella insurance is an affordable way to strengthen your financial security.

    📌 Quick Facts

    CategoryDetails
    ✅ Best ForHomeowners, families, landlords, high-income professionals, business owners, and anyone with significant assets.
    💲Average CostApproximately $150–$300 per year for the first $1 million of coverage (varies by insurer and risk profile).
    🛡️ CoverageProvides additional liability protection beyond your home, auto, renters, or boat insurance policy limits.
    👍 ProsHigh liability protection, affordable premiums, protects assets and future earnings, extra peace of mind.
    👎 ConsDoes not cover your own injuries, personal property damage, or intentional acts. Requires underlying insurance policies.


    Table of Contents

    1. What Is Umbrella Insurance?
    2. Why Umbrella Insurance Matters
    3. How It Differs from Standard Liability Insurance
    4. Who Should Buy Umbrella Insurance?
    5. Beginner-Friendly Explanation
    6. Key Takeaways


    What Is Umbrella Insurance?

    Umbrella Insurance Explained is a personal liability policy that provides additional financial protection when the liability limits on your existing auto, homeowners, renters, or boat insurance are no longer enough. Instead of replacing your current insurance, it works alongside those policies by extending your liability coverage after their limits have been reached.

    For example, if you’re responsible for a serious accident that results in a $1.5 million lawsuit but your auto insurance covers only Umbrella Insurance Explained $500,000, an umbrella policy may help pay the remaining eligible amount, helping protect your savings and future income.


    Why Umbrella Insurance Matters

    Large lawsuits are more common than many people realize. Medical expenses, legal fees, property damage, and liability claims can quickly exceed the limits of a standard insurance policy. Umbrella insurance helps reduce the financial impact of these unexpected events.

    • ✔ Protects personal savings and investments.
    • ✔ Helps safeguard future income from lawsuits.
    • ✔ Provides additional liability protection at a relatively low cost.
    • ✔ Offers extra peace of mind for families and homeowners.


    How Is It Different from Standard Liability Insurance?

    Your home or auto insurance includes liability coverage, but every policy has a maximum limit. Umbrella insurance begins only after those limits have been exhausted, giving you an additional layer of financial protection.


    Who Should Consider Umbrella Insurance?

    • ✔ Homeowners
    • ✔ Families with teenage drivers
    • ✔ Landlords and rental property owners
    • ✔ High-income professionals
    • ✔ Individuals with significant savings or investments
    • ✔ Anyone who wants additional liability protection


    Beginner-Friendly Explanation

    Think of your regular insurance policy as your first line of defense. If a lawsuit or liability claim exceeds that policy’s limit, umbrella insurance acts like a second safety net, providing extra financial protection before you have to pay from your own assets.


    Key Takeaways

    • ✔ Umbrella insurance provides extra liability coverage.
    • ✔ It works with your existing insurance policies.
    • ✔ It helps protect savings, investments, and future earnings.
    • ✔ Coverage usually starts at $1 million.
    • ✔ It’s affordable compared to the protection it provides.
    • ✔ Best suited for people with valuable assets or higher liability risks.


    How Umbrella Insurance Works

    Umbrella Insurance Explained is easier to understand when you think of it as a backup layer of liability protection. Your auto, homeowners, renters, or boat insurance pays first when you’re responsible for an accident or lawsuit. If the damages exceed your policy’s liability limit, your umbrella insurance can help cover the remaining eligible costs up to your umbrella policy limit.Umbrella Insurance Explained

    Without umbrella insurance, you may have to pay the remaining expenses from your own savings, investments, or future income. Umbrella Insurance Explained That’s why many financial experts recommend umbrella coverage for people who have valuable assets or face higher liability risks.

    Step 1: Maintain Required Base Insurance

    Most insurance companies require you to carry minimum liability limits on your home and auto insurance before you can purchase an umbrella policy. This ensures your primary insurance pays first.

    Step 2: Choose an Umbrella Coverage Limit

    Most policies start with $1 million in liability coverage. Higher limits such as $2 million, $3 million, or more are available depending on your assets and financial needs.

    Step 3: Umbrella Coverage Activates

    If a covered liability claim exceeds the limits of your primary insurance policy, your umbrella insurance begins paying eligible expenses after those limits have been exhausted.

    Step 4: Protect Your Personal Assets

    An umbrella policy helps protect your savings, investments, retirement funds (where applicable), and future earnings from large liability judgments that could otherwise create serious financial hardship.

    Who Should Buy Umbrella Insurance?

    • ✔ Homeowners with significant equity
    • ✔ Families with teenage drivers
    • ✔ Landlords and rental property owners
    • ✔ Individuals with high net worth
    • ✔ Business owners with personal assets
    • ✔ Anyone who wants extra liability protection

    Why It Is Important

    Serious accidents and lawsuits are unpredictable. Medical bills, legal expenses, and court judgments can easily exceed standard liability limits. Umbrella insurance offers an affordable way to strengthen your financial protection and reduce the risk of losing personal assets.

    Protecting your future also means planning for retirement. Read our Retirement Planning Guide (2026) for additional long-term financial strategies.

    📋 Expert Tip

    If your total assets and future income exceed your current liability coverage, consider adding an umbrella policy. The annual premium is relatively low compared to the financial protection it can provide during a major lawsuit.


    What Does Umbrella Insurance Cover?

    Umbrella Insurance Explained becomes valuable when a liability claim is larger than the limits of your home, auto, renters, or boat insurance. Instead of paying the remaining expenses from your own savings, an umbrella policy can provide additional liability protection, helping preserve your assets and future income.

    Umbrella Insurance Explained Although every insurer has different policy terms, most umbrella insurance policies cover a wide range of personal liability situations.

    What’s Covered?

    • ✅ Bodily injury liability
    • ✅ Property damage liability
    • ✅ Legal defense costs
    • ✅ Personal injury claims (libel, slander, defamation)
    • ✅ Landlord liability (eligible situations)
    • ✅ Certain lawsuits covered by the policy
    • ✅ Worldwide liability protection (subject to policy terms)

    What’s Not Covered?

    Umbrella insurance does not replace your existing insurance policies and doesn’t cover every type of loss.

    • ❌ Damage to your own home or vehicle
    • ❌ Your personal medical expenses
    • ❌ Business liability (unless specifically endorsed)
    • ❌ Intentional or criminal acts
    • ❌ Contractual liabilities
    • ❌ Flood or earthquake damage
    • ❌ Professional liability claims

    Key Features of Umbrella Insurance

    • ✔ Starts where your primary liability insurance ends.
    • ✔ Coverage typically begins at $1 million.
    • ✔ Higher limits are available in $1 million increments.
    • ✔ Covers legal defense costs for many covered claims.
    • ✔ Helps protect savings, investments, and future earnings.
    • ✔ Affordable annual premium compared to the protection provided.

    Umbrella Insurance Coverage Comparison

    SituationPrimary InsuranceUmbrella Insurance
    Major Auto AccidentUp to policy limitAdditional liability coverage
    Serious Home Injury ClaimCovered up to liability limitExtends eligible liability protection
    Personal LawsuitLimited coverageMay provide additional protection
    Legal Defense CostsCovered as definedAdditional coverage for eligible claims
    Protection of Personal AssetsLimitedMuch stronger financial protection


    Umbrella Insurance ExplainedReal-Life Example

    Umbrella Insurance Explained Suppose Sarah causes a serious auto accident and is found legally responsible for $1.4 million in damages. Her auto insurance provides $500,000 in liability coverage. Without umbrella insurance, Sarah could be responsible for the remaining amount herself. If she has a $1 million umbrella policy, it may cover eligible costs above her auto policy limit, helping protect her savings and future earnings.

    📌 Expert Insight

    Umbrella insurance isn’t designed for everyday claims. It’s designed for rare but financially devastating liability situations. For many families, paying a small annual premium is an affordable way to protect assets that took years to build.


    Umbrella Insurance Cost & Coverage Comparison

    One of the biggest advantages of Umbrella Insurance Explained is that it provides a large amount of liability protection for a relatively small annual premium. The exact cost depends on factors such as your assets, driving history, insurance company, location, number of properties, and desired coverage limit.

    Most Americans find umbrella insurance surprisingly affordable, especially when compared with the financial risk of a major lawsuit.Umbrella Insurance Explained

    Average Umbrella Insurance Cost (2026)

    Coverage AmountEstimated Annual Cost
    $1 Million$150–$300
    $2 Million$225–$450
    $3 Million$300–$600
    $5 Million$500–$900+

    Factors That Affect Umbrella Insurance Premiums

    • ✔ Number of homes and vehicles you own
    • ✔ Driving record
    • ✔ Previous liability claims
    • ✔ Swimming pools, trampolines, or pets
    • ✔ Rental properties
    • ✔ Coverage amount selected
    • ✔ Existing auto and homeowners insurance limits

    Umbrella Insurance Comparison

    FeatureStandard Liability InsuranceUmbrella Insurance
    Coverage LimitLimited to policy maximumAdds $1M or more
    Legal DefenseLimitedExtended protection for eligible claims
    Asset ProtectionBasicExcellent
    Annual CostIncluded with primary policyRelatively low premium
    Best ForEveryday liability protectionHigh-value asset protection

    Best Strategies Before Buying

    • ✅ Maintain adequate home and auto liability limits.
    • ✅ Compare quotes from multiple insurance companies.
    • ✅ Bundle policies with the same insurer when possible.
    • ✅ Choose a coverage limit that matches your assets.
    • ✅ Review your umbrella policy every year.

    Building wealth also means protecting it during difficult economic periods. Read our Recession-Proof Investing Guide (2026) for additional long-term financial strategies.

    For consumer information about liability insurance, visit the
    National Association of Insurance Commissioners (NAIC).

    Compare umbrella insurance quotes through a trusted online insurance marketplace to find competitive pricing and coverage options from multiple insurers.Umbrella Insurance Explained

    Use a personal finance and net worth tracking app to monitor your assets and determine whether your liability protection remains adequate as your wealth grows.

    ⭐ Expert Recommendation

    If your assets are worth more than your current liability limits, umbrella insurance is often one of the most affordable ways to strengthen your financial protection. Spending a few hundred dollars per year today could help protect millions of dollars in future financial exposure.


    How to Buy the Right Umbrella Insurance Policy

    Buying umbrella insurance is simple if you understand your liability risks and compare policies carefully.Umbrella Insurance Explained Instead of choosing the first policy you find, review your existing insurance coverage, estimate your total assets, and select an umbrella policy that provides enough financial protection for your lifestyle.

    Step 1: Review Your Existing Liability Coverage

    Check the liability limits on your auto, homeowners, renters, or boat insurance. Most insurers require minimum liability limits before issuing an umbrella policy.

    Step 2: Calculate Your Net Worth

    Add the value of your home, vehicles, savings, investments, retirement accounts (where applicable), and other valuable assets. Many financial professionals recommend choosing umbrella coverage that equals or exceeds your total net worth.

    Step 3: Compare Multiple Insurance Companies

    Request quotes from several insurers and compare coverage limits, exclusions, legal defense benefits, deductibles (if applicable), customer service, and premium costs before making a decision.

    Step 4: Choose the Right Coverage Limit

    Most policies start at $1 million, but homeowners, landlords, business owners, and higher-income families often choose $2 million or more for additional protection.

    Money-Saving Tips

    • 💰 Bundle umbrella insurance with your auto and homeowners insurance.
    • 💰 Maintain a clean driving record.
    • 💰 Review your policy every year.
    • 💰 Increase coverage only as your assets grow.
    • 💰 Compare quotes before every renewal.

    Available Discounts

    DiscountPotential Savings
    Multi-Policy Bundle5%–20%
    Loyalty Discount5%–10%
    Claim-Free HistoryVaries by insurer
    Multiple VehiclesAdditional savings may apply

    For official consumer insurance resources, visit
    USA.gov.

    Use a trusted online insurance comparison marketplace to compare umbrella insurance quotes from multiple providers and identify the best value for your coverage needs.

    A reliable personal finance and net worth tracking app can help you monitor your assets and determine when it’s time to increase your umbrella liability coverage.

    📌 Expert Buying Tip

    Choose an umbrella insurance policy based on the value of the assets you want to protect—not simply the lowest premium. A slightly higher coverage limit today can provide significantly better financial protection if a major liability claim occurs in the future.


    Common Umbrella Insurance Mistakes to Avoid

    Buying umbrella insurance is a smart financial decision, but many Americans make simple mistakes that reduce the value of their coverage.Umbrella Insurance Explained Understanding these common errors can help you avoid denied claims, unnecessary expenses, and gaps in liability protection.

    1. Assuming Umbrella Insurance Covers Everything

    An umbrella policy only provides additional liability protection. It does not cover damage to your own home, vehicle, personal belongings, or intentional acts.

    2. Buying Too Little Coverage

    Many people purchase the minimum $1 million policy even though their total assets are worth much more. Your coverage should reflect the value of the assets you want to protect.

    3. Not Maintaining Required Underlying Insurance

    Umbrella insurance requires adequate liability limits on your home, auto, or renters insurance. Reducing those limits could leave you responsible for part of a claim.

    4. Never Reviewing the Policy

    Your liability risks change over time. Buying a new home, rental property, boat, or adding a teenage driver may require additional umbrella coverage.

    5. Ignoring Policy Exclusions

    Read your policy carefully so you understand what situations are covered and which exclusions apply before you need to file a claim.

    6. Choosing Price Over Protection

    The lowest premium isn’t always the best value. Compare coverage limits, exclusions, customer service, and financial strength before selecting an insurer.

    7. Forgetting to Bundle Policies

    Many insurance companies offer lower premiums when umbrella insurance is bundled with home and auto insurance.

    8. Waiting Until After a Lawsuit

    Umbrella insurance must be purchased before a covered liability event occurs. It cannot protect you against claims that have already happened.

    Real-Life USA Example

    John owned a home, two vehicles, and investment accounts worth more than $1.8 million. He carried only the minimum umbrella coverage without reviewing it for years.Umbrella Insurance Explained After a serious auto accident resulted in a large liability claim, he discovered his protection wasn’t enough to fully cover the lawsuit. Increasing his umbrella coverage earlier would have cost only a small additional premium each year while providing significantly better financial protection.

    Expert Tips

    • ✔ Review umbrella insurance every year.
    • ✔ Match coverage to your total assets.
    • ✔ Compare multiple insurance companies before renewal.
    • ✔ Maintain required home and auto liability limits.
    • ✔ Read exclusions carefully.
    • ✔ Bundle policies whenever possible.
    • ✔ Update coverage after major life changes.
    • ✔ Keep digital copies of all insurance documents.

    Building wealth is only half the journey—protecting it is equally important. Read our Best Credit Cards USA Guide (2026) to discover additional ways to improve your financial health.

    Learn more about liability insurance and consumer protections from the
    National Association of Insurance Commissioners (NAIC).

    Use a trusted insurance comparison marketplace to review umbrella insurance options, compare liability limits, and find competitive pricing from leading insurers.

    A personal finance and asset tracking app can help you monitor your net worth and determine when increasing your umbrella insurance coverage makes financial sense.

    ⭐ Expert Reminder

    Umbrella insurance is designed to protect the wealth you’ve spent years building. Review your policy regularly, keep your primary insurance updated, and increase coverage as your assets grow to stay protected against large liability claims.


    Pros & Cons of Umbrella Insurance

    Umbrella insurance offers valuable extra liability protection at a relatively affordable cost. However, like any insurance product, it has both advantages and limitations. Understanding these can help you decide whether an umbrella policy fits your financial situation.

    ✅ Pros❌ Cons
    Provides $1 million or more in additional liability coverage.Doesn’t cover damage to your own property or personal injuries.
    Protects savings, investments, and future earnings.Requires minimum liability limits on primary insurance policies.
    Covers many large lawsuits and legal defense costs.Not every type of liability claim is covered.
    Affordable annual premiums compared to coverage provided.Coverage and exclusions vary by insurance company.
    Offers extra peace of mind for families and homeowners.Policy should be reviewed regularly as assets increase.

    ⭐ Final Verdict

    If you have a home, savings, investments, rental property, or other valuable assets, umbrella insurance can be one of the most cost-effective ways to protect your financial future. A relatively small annual premium can provide substantial additional liability coverage and greater peace of mind.


    Frequently Asked Questions (FAQs)

    1. What is umbrella insurance?

    Umbrella insurance is an additional liability insurance policy that provides extra protection after the liability limits of your home, auto, renters, or boat insurance have been exhausted. It helps protect your assets and future income from large lawsuits and liability claims.

    2. Who should buy umbrella insurance?

    Umbrella insurance is a good option for homeowners, landlords, families with teenage drivers, business owners, high-income professionals, and anyone with significant savings, investments, or valuable assets that could be at risk in a lawsuit.

    3. How much umbrella insurance do I need?

    Many financial professionals recommend carrying umbrella insurance equal to or greater than your total net worth. Policies typically start at $1 million, with higher limits available in $1 million increments.

    4. How much does umbrella insurance cost?

    Most Americans pay approximately $150 to $300 per year for the first $1 million of umbrella liability coverage. Premiums vary based on your assets, insurance history, location, and coverage amount.

    5. What doesn’t umbrella insurance cover?

    Umbrella insurance generally does not cover damage to your own property, your personal medical expenses, business liabilities (unless endorsed), intentional acts, or professional liability claims. Always review your policy exclusions carefully.

    6. Is umbrella insurance worth it?

    For many Americans, yes. If you own a home, have investments, future earning potential, or other valuable assets, umbrella insurance offers affordable protection against large liability claims that could otherwise threaten your financial security.

    💡 Quick Takeaway

    Umbrella insurance provides an affordable extra layer of liability protection. Choosing the right coverage limit, maintaining adequate primary insurance, and reviewing your policy regularly can help safeguard your assets from unexpected lawsuits and major financial losses.


    Conclusion: Is Umbrella Insurance Worth It?

    Umbrella Insurance Explained shows that a relatively small annual premium can provide significant financial protection when a major liability claim exceeds the limits of your existing insurance policies. Whether you own a home, drive regularly, have rental property, or simply want to protect your savings and future income, an umbrella policy can serve as an important financial safety net.

    Before purchasing a policy, review your current liability limits, calculate the value of your assets, compare quotes from multiple insurers, and choose a coverage amount that matches your financial situation. Reviewing your policy every year ensures your protection continues to grow along with your wealth.

    If you’re still learning about insurance, don’t miss our comprehensive Insurance for Beginners USA Guide (2026). It covers essential insurance concepts, policy types, and practical tips to help you make confident insurance decisions.

    For official consumer resources and insurance education, visit the
    National Association of Insurance Commissioners (NAIC).

    Use a trusted online insurance comparison marketplace to compare umbrella insurance quotes from leading providers and choose the policy that offers the best balance of price and protection.

    A personal finance and net worth tracking app can help you monitor your assets, insurance needs, and financial goals as your wealth grows.


    📩 Stay Updated with Insurance & Personal Finance Tips

    Subscribe to FinanceInvestment.site for expert insurance guides, investing strategies, retirement planning tips, and practical money-saving advice created specifically for U.S. readers.


    📧 Subscribe Free


    ✅ Insurance Guides   |
    ✅ Investing Tips   |
    ✅ Retirement Planning   |
    ✅ 100% Free

    SR

    Subhash Rukade

    Subhash Rukade is the founder of FinanceInvestment.site, where he publishes research-based content about insurance, investing, retirement planning, credit cards, and personal finance. His goal is to help U.S. readers make smarter financial decisions through practical, trustworthy, and easy-to-understand guides.