Tag: financial planning

  • Top Insurance Mistakes That Cost Americans Thousands: Complete USA Guide (2026)

    Top Insurance Mistakes That Cost Americans Thousands: Complete USA Guide (2026)


    Top Insurance Mistakes That Cost Americans Thousands: Complete USA Guide (2026)

    Author: Subhash Rukade

    Published: July 17, 2026

    Top Insurance Mistakes That Cost Americans ThousandsWhy Insurance Mistakes Can Become Extremely Expensive

    Top Insurance Mistakes That Cost Americans Thousands are more common than most people realize. Every year, thousands of U.S. families lose money because they buy the wrong policy, choose inadequate coverage, ignore policy exclusions, or fail to review their insurance before renewal. These mistakes often remain hidden until it’s time to file a claim, when fixing them is usually too late.

    Insurance is designed to protect your financial future, but even a small error can lead to denied claims, higher out-of-pocket expenses, or years of paying unnecessary premiums. Whether you have auto, home, renters, life, health, or pet insurance,Top Insurance Mistakes understanding these common mistakes can help you avoid expensive surprises.

    If you’re new to insurance, start with our Insurance for Beginners USA: Complete Guide (2026). It explains the fundamentals of insurance, policy types, and important coverage terms before you choose or renew any policy.

    In this guide, you’ll discover the most expensive insurance mistakes Americans make, learn why they happen, understand how to avoid them, and get practical tips to choose better coverage while keeping your insurance costs under control in 2026.

    💡 Quick Tip

    The cheapest insurance policy isn’t always the best value. Compare coverage limits, deductibles, exclusions, and claims service before making your final decision.


    Quick Answer: Top Insurance Mistakes That Cost Americans Thousands

    Top Insurance Mistakes That Cost Americans Thousands include buying too little coverage, choosing policies based only on price, ignoring deductibles and exclusions, failing to compare quotes, and never reviewing insurance after major life changes. These mistakes can result in denied claims, higher out-of-pocket expenses, and unnecessary premiums.Top Insurance Mistakes Understanding your policy before purchasing is the best way to protect both your family and your finances.

    📌 Quick Facts

    CategoryDetails
    ✅ Best ForHomeowners, renters, drivers, families, first-time insurance buyers, and anyone reviewing an insurance policy.
    💲Average CostA single insurance mistake can cost anywhere from hundreds to several thousand dollars, depending on the claim and coverage gap.
    🛡️ Main BenefitHelps you avoid denied claims, reduce unnecessary premiums, and choose the right insurance coverage.
    👍 ProsBetter financial protection, smarter insurance decisions, lower long-term costs, and improved peace of mind.
    👎 ConsRequires time to review policies, compare insurers, and understand insurance terminology.


    Table of Contents

    1. What Are Insurance Mistakes?
    2. Why Insurance Mistakes Matter
    3. Why People Make Insurance Mistakes
    4. How These Mistakes Affect Your Finances
    5. Beginner-Friendly Explanation
    6. Key Takeaways


    What Are the Top Insurance Mistakes That Cost Americans Thousands?

    Top Insurance Mistakes That Cost Americans Thousands are common errors people make when buying, renewing, or using insurance policies. These mistakes include purchasing insufficient coverage, selecting policies based only on the lowest premium, ignoring deductibles, failing to read exclusions, and forgetting to update coverage after major life events.

    Although these decisions may seem minor, they often become extremely expensive when an accident, natural disaster, theft, illness, or lawsuit occurs. At that point, many policyholders discover that their insurance doesn’t provide the protection they expected.


    Why Avoiding Insurance Mistakes Is Important

    Insurance exists to protect your finances during unexpected events. One mistake can result in denied claims, higher out-of-pocket costs, unnecessary premiums, or significant financial losses that could have been avoided with proper planning.

    Understanding common insurance mistakes helps you choose better coverage while keeping your long-term insurance costs under control.


    Why Do People Make These Mistakes?

    • ✅ Choosing the cheapest policy without comparing coverage.
    • ✅ Not understanding insurance terminology.
    • ✅ Ignoring policy exclusions.
    • ✅ Failing to compare multiple insurance companies.
    • ✅ Never reviewing policies after major life changes.
    • ✅ Assuming every insurance policy offers the same protection.


    How Insurance Mistakes Affect Your Finances

    • ✔ Higher claim expenses.
    • ✔ Denied insurance claims.
    • ✔ Increased annual premiums.
    • ✔ Unexpected out-of-pocket costs.
    • ✔ Reduced financial security.
    • ✔ Difficulty recovering after major losses.


    Beginner-Friendly Explanation

    Think of insurance like a safety net. If the net has holes because you purchased the wrong coverage or ignored important policy details, it may not protect you when you need it most. Spending a little extra time reviewing your policy today can prevent thousands of dollars in unexpected expenses later.Top Insurance Mistakes


    Key Takeaways

    • ✔ Compare more than just insurance premiums.
    • ✔ Review deductibles and policy exclusions carefully.
    • ✔ Update coverage after major life events.
    • ✔ Compare quotes from multiple insurers.
    • ✔ Read your policy before filing a claim.
    • ✔ Review your insurance every year.


    How Insurance Mistakes Happen and How to Avoid Them

    Top Insurance Mistakes That Cost Americans Thousands usually don’t happen because people ignore insurance completely. Instead, they occur when buyers rush through the purchasing process, focus only on low premiums, or fail to understand what their policy actually covers. Taking a few extra minutes to review policy details can prevent expensive financial surprises later.

    Whether you’re buying auto, home, renters, life, or pet insurance, following a simple process helps you choose the right protection while avoiding unnecessary costs.

    Step 1: Understand Your Insurance Needs

    Start by identifying the risks you want to protect against. Consider your home, vehicle, income, savings, family responsibilities, and valuable assets before selecting coverage.

    Step 2: Compare Multiple Insurance Companies

    Never purchase the first policy you receive. Compare several insurers using identical coverage limits and deductibles so you can make an accurate comparison.

    Step 3: Read the Entire Policy

    Many expensive mistakes happen because policyholders never review exclusions, waiting periods, deductibles, or claim requirements before purchasing coverage.

    Step 4: Review Coverage Every Year

    Your insurance should change as your life changes. Buying a new home, getting married, adding a vehicle, welcoming a child, or starting a business are all good reasons to update your policies.

    Step 5: Keep Important Records

    Store copies of your insurance policies, receipts, photos of valuable belongings, and claim documents in a secure location. Good documentation makes the claims process much easier.

    Who Should Pay Extra Attention?

    • ✔ First-time insurance buyers
    • ✔ Homeowners and renters
    • ✔ Families with children
    • ✔ Drivers renewing auto insurance
    • ✔ Small business owners
    • ✔ Retirees protecting their assets

    Why This Process Matters

    Most costly insurance mistakes can be prevented through careful planning and regular policy reviews. Understanding your coverage before you need it reduces financial stress and increases the likelihood that your claim will be handled smoothly.

    Building long-term financial security also means preparing for retirement. Read our Retirement Planning Guide (2026) to learn additional strategies for protecting your future.

    📋 Expert Tip

    Review your insurance policies at least once a year—even if nothing has changed. Premiums, coverage options, and discounts change frequently, and a quick annual review could save you hundreds of dollars while improving your protection.


    The Biggest top  Insurance Mistakes That Cost Americans Thousands

    Top Insurance Mistakes That Cost Americans Thousands often begin with small decisions that seem harmless at the time. Choosing the cheapest policy, skipping policy reviews, or misunderstanding deductibles can create major financial problems when it’s time to file a claim. Understanding these common mistakes helps you choose better coverage while protecting your savings.

    Regardless of whether you have auto, home, renters, life, or pet insurance, avoiding these mistakes can save you significant money over the long term.Top Insurance Mistakes

    What’s Covered in This Guide?

    This guide explains the most expensive insurance mistakes Americans make and shows how to avoid them before they become costly.

    • ✅ Buying too little insurance coverage
    • ✅ Choosing policies based only on the lowest premium
    • ✅ Ignoring deductibles
    • ✅ Overlooking policy exclusions
    • ✅ Missing available discounts
    • ✅ Failing to compare insurance companies
    • ✅ Not updating policies after major life changes
    • ✅ Forgetting to review policies before renewal

    What’s Not Covered?

    Although this guide covers general insurance mistakes, it doesn’t replace professional advice for specialized insurance products or state-specific regulations.

    • ❌ Legal advice
    • ❌ State-specific insurance laws
    • ❌ Business insurance planning
    • ❌ Tax planning
    • ❌ Investment recommendations

    Warning Signs That Your Insurance Needs Attention

    • ✔ Your policy hasn’t been reviewed in years.
    • ✔ You don’t know your deductible amount.
    • ✔ Your home or vehicle value has changed.
    • ✔ Your family situation has changed.
    • ✔ You purchased the cheapest policy without comparing coverage.
    • ✔ You haven’t compared quotes recently.

    Insurance Mistakes & Their Financial Impact

    Insurance MistakePossible Financial ImpactHow to Avoid It
    Buying minimum coverageLarge out-of-pocket expensesChoose adequate coverage limits
    Ignoring deductiblesUnexpected claim costsReview deductible before buying
    Not reading exclusionsDenied insurance claimsRead policy documents carefully
    Never comparing quotesHigher annual premiumsCompare multiple insurers yearly
    Skipping annual policy reviewOutdated protectionReview insurance every renewal
    Missing discountsOverpaying for insuranceAsk about every available discount

    Top Insurance Mistakes That Cost Americans Thousands

    Real-World Example

    Imagine a homeowner who purchased the least expensive home insurance policy five years ago and never updated it. After renovating the property, its replacement value increased substantially. When severe storm damage occurred, the insurance payout covered only part of the repair costs because the policy limits were too low. A simple annual policy review could have prevented thousands of dollars in unexpected expenses.Top Insurance Mistakes

    This example shows why reviewing coverage regularly is just as important as finding affordable premiums.

    📌 Expert Insight

    The most expensive insurance mistake isn’t paying slightly higher premiums—it’s discovering after a loss that your policy doesn’t provide the protection you expected. Review your coverage, compare quotes regularly, and understand every major policy term before you need to file a claim.


    Financial Cost of Common Insurance Mistakes

    The Top Insurance Mistakes That Cost Americans Thousands don’t always happen because insurance is expensive. In many cases, people lose money because they buy the wrong policy, choose insufficient coverage, or fail to review their insurance before renewing it. Spending a little more time comparing policies today can prevent major financial losses later.Top Insurance Mistakes

    Most insurance mistakes can be avoided by comparing multiple insurers, understanding policy details, and reviewing your coverage every year.

    Average Financial Impact of Insurance Mistakes

    Insurance MistakePotential Cost
    Buying insufficient coverage$5,000–$100,000+ depending on the loss
    High deductible you can’t afford$1,000–$5,000 out-of-pocket
    Ignoring policy exclusionsEntire claim may be denied
    Never comparing insurance quotes10%–30% higher annual premiums
    Missing available discounts$100–$1,000+ per year
    Not updating insurance after life changesThousands in uncovered losses

    Factors That Increase Insurance Costs

    • ✔ Low credit-based insurance score (where allowed)
    • ✔ Multiple insurance claims
    • ✔ High-risk location
    • ✔ Driving violations or accidents
    • ✔ Older property or vehicle
    • ✔ Low policy limits requiring future upgrades
    • ✔ Failure to bundle multiple insurance policies

    Comparison: Smart Insurance Buyer vs. Common Buyer

    ComparisonSmart BuyerCommon Mistake
    Insurance QuotesCompares 3–5 companiesBuys first quote
    Coverage ReviewReviews yearlyNever reviews policy
    DeductibleChooses affordable amountSelects highest deductible
    DiscountsRequests all discountsMisses available savings
    Policy UnderstandingReads exclusions carefullyAssumes everything is covered

    Best Strategies to Avoid Expensive Insurance Mistakes

    • ✅ Compare quotes from at least three insurance companies.
    • ✅ Review your coverage before every renewal.
    • ✅ Increase coverage after major life events.
    • ✅ Ask about bundle, loyalty, safe driver, and paperless discounts.
    • ✅ Read exclusions before purchasing any policy.
    • ✅ Keep copies of all insurance documents.

    Reducing insurance costs is only one part of protecting your finances. Learn how to build a stronger financial future with our Recession-Proof Investing Guide (2026).

    Consumer insurance information and educational resources are available from the
    National Association of Insurance Commissioners (NAIC).

    Use a trusted online insurance comparison marketplace to compare quotes from multiple insurers and identify better coverage at competitive prices.

    A reliable personal finance and budgeting app can help you monitor insurance premiums, renewal dates, deductibles, and annual savings.

    ⭐ Expert Recommendation

    The biggest insurance savings come from making informed decisions—not simply buying the cheapest policy. Compare coverage, deductibles, exclusions, discounts, and customer service before choosing any insurance provider.


    How to Avoid Top Insurance Mistakes Before Buying a Policy

    A few extra minutes of research before purchasing insurance can save you thousands of dollars later. The best way to avoid costly mistakes is to compare policies carefully, understand your coverage, and choose insurance based on value—not just the lowest premium.

    Step 1: Identify Your Coverage Needs

    Consider your home, vehicle, family, income, and financial responsibilities before selecting a policy. Buy enough coverage to protect your assets without paying for unnecessary extras.

    Step 2: Compare Multiple Insurance Companies

    Always request quotes from at least three reputable insurers. Compare identical coverage limits, deductibles, exclusions, and discounts so you’re making a fair comparison.

    Step 3: Read the Policy Before Purchasing

    Review deductibles, claim procedures, waiting periods, exclusions, and optional coverages. Never assume every insurance policy offers the same protection.

    Step 4: Ask About Every Available Discount

    Many insurers offer discounts that customers never request.

    • 💰 Multi-policy bundle discounts
    • 💰 Safe driver discounts
    • 💰 Loyalty rewards
    • 💰 Paperless billing discounts
    • 💰 Automatic payment discounts
    • 💰 Home security or safety device discounts

    Money-Saving Tips

    • ✔ Review insurance before every renewal.
    • ✔ Increase deductibles only if you can comfortably afford them.
    • ✔ Keep your policy information updated after major life events.
    • ✔ Compare insurance annually to find better pricing.
    • ✔ Store digital copies of important insurance documents.

    Popular Insurance Discounts

    Discount TypeTypical Savings
    Multi-Policy Bundle10%–25%
    Safe Driver5%–30%
    Loyalty Discount5%–15%
    Paperless Billing2%–5%
    Automatic Payments2%–8%

    For official insurance information and consumer resources, visit
    USA.gov.

    Use a trusted insurance comparison marketplace to compare quotes, discounts, and policy features from leading insurance providers before making your final decision.

    A reliable personal finance or budgeting app can help you track premiums, renewal dates, deductibles, and insurance expenses throughout the year.

    📌 Expert Buying Tip

    Buying the right insurance isn’t about finding the cheapest premium. It’s about choosing the policy that provides the best balance of affordable pricing, comprehensive coverage, reasonable deductibles, and dependable claims support.


    Top Insurance Mistakes That Cost Americans Thousands

    Many Americans lose money every year because of avoidable insurance mistakes. Most of these errors happen long before a claim is filed. Understanding these common mistakes can help you choose better coverage, Top Insurance Mistakes reduce unnecessary expenses, and avoid costly financial surprises.

    1. Buying Insurance Based Only on Price

    The cheapest policy often provides the least protection. Always compare coverage limits, deductibles, exclusions, and claim service instead of focusing only on monthly premiums.

    2. Choosing Too Little Coverage

    Minimum coverage may reduce premiums today, but it can leave you paying thousands of dollars out of pocket after a serious accident or disaster.

    3. Ignoring Policy Exclusions

    Many policyholders never read what isn’t covered. Flood damage, earthquakes, business property, or valuable personal items may require additional coverage.

    4. Selecting a Deductible You Can’t Afford

    A high deductible lowers premiums but increases your out-of-pocket costs when filing a claim. Choose a deductible that fits your emergency savings.

    5. Never Comparing Insurance Quotes

    Insurance companies use different pricing models. Comparing several quotes could save hundreds of dollars every year.

    6. Forgetting to Update Policies

    Marriage, buying a home, renovating property, adding a driver, or purchasing expensive belongings should trigger a policy review.

    7. Missing Available Discounts

    Many customers never ask about multi-policy bundles, safe driver discounts, loyalty rewards, or paperless billing savings.

    8. Waiting Until Renewal to Read the Policy

    Review your insurance immediately after purchasing it. Understanding your policy before an emergency helps prevent denied claims and unexpected expenses.

    Real-Life USA Example

    David from Florida purchased the least expensive homeowners insurance policy without reviewing its exclusions. After severe water damage, he discovered that the policy didn’t cover the specific cause of the loss. The repairs cost him more than $18,000 out of pocket. Spending a little more time reviewing the policy beforehand could have prevented this expensive mistake.

    Expert Tips to Avoid Costly Insurance Errors

    • ✔ Compare quotes from at least three insurance companies.
    • ✔ Review your insurance coverage every year.
    • ✔ Read every policy exclusion carefully.
    • ✔ Choose deductibles that fit your budget.
    • ✔ Ask about every available insurance discount.
    • ✔ Keep digital copies of all policy documents.
    • ✔ Update insurance after major life changes.
    • ✔ Work with financially strong insurance companies that have good customer service.

    Strong financial planning goes beyond insurance. Explore our Best Credit Cards USA (2026) to discover additional ways to reduce expenses and improve your financial health.

    Learn more about insurance consumer protections through the
    National Association of Insurance Commissioners (NAIC).

    Use a trusted online insurance comparison marketplace to compare policies, customer reviews, and available discounts before purchasing your next insurance plan.Top Insurance Mistakes

    A reliable digital document organizer or password manager can securely store insurance policies, claim records, and renewal reminders in one place.

    ⭐ Expert Reminder

    The most expensive insurance mistake is discovering after a loss that your policy doesn’t provide the protection you expected. Review your coverage every year, compare quotes regularly, and understand your policy before you ever need to file a claim.


    Pros & Cons of Avoiding Common Insurance Mistakes

    Understanding the Top Insurance Mistakes That Cost Americans Thousands helps you make smarter financial decisions. While reviewing and comparing insurance policies requires some time, the long-term savings and financial protection usually outweigh the effort.

    ✅ Pros❌ Cons
    Avoid expensive coverage gaps and denied claims.Comparing multiple insurance policies takes extra time.
    Reduce unnecessary insurance premiums.Insurance terminology may be confusing for beginners.
    Choose better coverage for your family’s needs.Some policies require careful review before purchasing.
    Qualify for valuable discounts and bundle savings.Higher-quality coverage may cost slightly more upfront.
    Improve long-term financial security and peace of mind.Annual policy reviews require ongoing attention.

    ⭐ Final Verdict

    Avoiding common insurance mistakes is one of the easiest ways to protect your finances. By comparing coverage, understanding deductibles, reviewing exclusions, and updating your policy regularly, you can prevent costly surprises and keep more of your money over the long term.


    Frequently Asked Questions (FAQs)

    1. What is the biggest insurance mistake people make?

    The biggest mistake is choosing an insurance policy based only on the lowest premium. A cheaper policy may have lower coverage limits, higher deductibles, or important exclusions that could leave you paying thousands of dollars out of pocket after a claim.

    2. How often should I review my insurance policy?

    You should review your insurance coverage at least once a year and after major life events such as buying a home, getting married, adding a driver, starting a business, or purchasing valuable property.

    3. Can comparing insurance quotes really save money?

    Yes. Comparing quotes from multiple insurance companies often helps drivers, homeowners, and families find better coverage at a lower price. Many Americans save hundreds of dollars annually by shopping around before renewal.

    4. Why do insurance claims get denied?

    Claims may be denied because of policy exclusions, missed premium payments, insufficient coverage, inaccurate application information, or failure to follow the insurer’s claim procedures. Reading your policy carefully helps reduce these risks.

    5. What discounts should I ask my insurance company about?

    Common discounts include multi-policy bundles, safe driver rewards, loyalty discounts, paperless billing, automatic payments, home security systems, and claim-free discounts. Always ask your insurer which discounts you qualify for.

    6. Is buying more insurance always better?

    Not necessarily. The goal is to purchase enough coverage to protect your assets without paying for unnecessary features. Compare your risks, budget, and financial goals before selecting coverage limits.

    📌 Quick Takeaway

    Review your insurance every year, compare multiple quotes, understand deductibles and exclusions, and update your coverage after major life changes. These simple habits can help you avoid costly insurance mistakes and protect your financial future.


    Conclusion: Avoid Insurance Mistakes and Protect Your Financial Future

    The Top Insurance Mistakes That Cost Americans Thousands are almost always preventable. Choosing the right coverage, reviewing your policy every year, comparing multiple insurance companies, and understanding deductibles and exclusions can save you significant money while giving you better financial protection.

    Don’t make the mistake of buying insurance based only on the lowest premium. Instead, focus on finding the right balance between affordable pricing, comprehensive coverage, reliable claims service, and strong customer support. A few extra minutes spent reviewing your policy today can prevent thousands of dollars in unexpected expenses tomorrow.

    If you’re still learning about insurance, be sure to read our comprehensive Insurance for Beginners USA Guide (2026). It explains essential insurance concepts, coverage options, and practical strategies to help you make smarter financial decisions.

    For additional insurance education and consumer protection resources, visit the
    National Association of Insurance Commissioners (NAIC).

    Use a trusted online insurance comparison marketplace to compare policies from leading insurers and find the best combination of coverage, price, and customer service.

    A quality personal finance and budgeting app can help you track insurance premiums, renewal dates, deductibles, and yearly savings while keeping your financial goals organized.


    📩 Stay Updated with Smarter Insurance & Personal Finance Tips

    Subscribe to FinanceInvestment.site for expert insurance guides, investing strategies, retirement planning tips, and practical money-saving advice created specifically for U.S. readers.


    📧 Subscribe Free


    ✅ Insurance Guides   |
    ✅ Investing Tips   |
    ✅ Retirement Planning   |
    ✅ 100% Free

    SR

    Subhash Rukade

    Subhash Rukade is the founder of FinanceInvestment.site, where he publishes research-based articles on insurance, investing, retirement planning, credit cards, and personal finance. His mission is to help American readers make smarter financial decisions through simple, trustworthy, and practical guidance.


    🌐 Visit Website


    📚 Read More Guides
     

  • Term Life vs Whole Life Insurance (2026): Complete Guide to Choosing the Right Policy

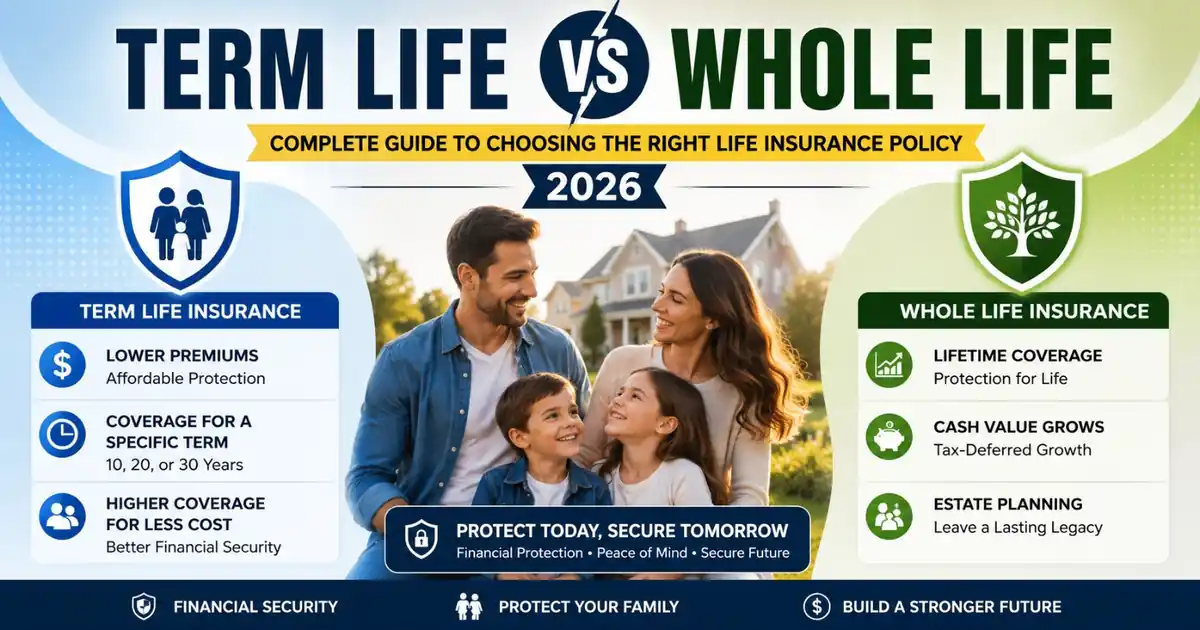
    Term Life vs Whole Life Insurance (2026): Complete Guide to Choosing the Right Policy


    Term Life vs Whole Life Insurance (2026): Complete Guide to Choosing the Right Policy

    Published: July 4, 2026 |
    Author: Subhash Rukade


    Term Life vs Whole Life InsuranceCompare Term Life and Whole Life Insurance to choose the best protection for your family’s future in 2026.

    Term Life vs Whole Life Insurance is one of the biggest decisions Americans face when purchasing life insurance in 2026. While both policies provide financial protection for your loved ones, they work very differently. Choosing the wrong policy may cost thousands of dollars over time, while selecting the right one can provide long-term financial security and peace of mind.

    Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years. Whole life insurance, on the other hand, offers lifelong protection while building cash value that grows over time. Understanding the differences in premiums, benefits, flexibility, and long-term value is essential before purchasing a policy.

    If you’re new to insurance, start with our comprehensive

    Insurance for Beginners USA 2026: Complete Guide to Choosing the Right Coverage
    .
    This pillar guide explains insurance terminology, policy types, premiums, claims, deductibles, and coverage options in simple language, helping beginners confidently compare different insurance products.

    Throughout this guide, you’ll learn how term life and whole life insurance work, compare their costs and benefits, understand cash value, review real-life examples, avoid common mistakes, and discover which policy is best for young families, parents, retirees, and high-income earners. You’ll also find a comparison table, premium calculator, expert recommendations, and answers to frequently asked questions.

    By the end of this article, you’ll clearly understand the strengths and weaknesses of each policy type and confidently choose the life insurance coverage that best protects your family’s financial future in 2026.

    What Is Term Life Insurance and How Does It Work?

    Understanding Term Life vs Whole Life Insurance begins with learning how term life insurance works. Term life insurance is the simplest and most affordable type of life insurance available. It provides financial protection for a fixed period—commonly 10, 20, or 30 years. If the insured person passes away during the policy term, the beneficiaries receive a tax-free death benefit that can help cover living expenses, debts, education costs, or mortgage payments.

    How Does Term Life Insurance Work?

    When you purchase a term life policy, you choose the coverage amount and policy length. As long as you continue paying premiums, your beneficiaries remain protected throughout the selected term. Once the policy expires, coverage generally ends unless you renew it, convert it to permanent coverage, or purchase a new policy, depending on the insurer’s rules.

    Advantages of Term Life Insurance

    • Lower monthly premiums than whole life insurance.
    • Simple and easy-to-understand coverage.
    • High coverage amounts at affordable prices.
    • Ideal for protecting mortgages, children, and family income.
    • Excellent choice for young families and first-time buyers.

    Potential Disadvantages

    • Coverage expires after the selected term.
    • No cash value or investment component.
    • Premiums may increase significantly if renewed later in life.
    • No payout if the policy expires before death.

    Who Should Consider Term Life Insurance?

    Term life insurance is often recommended for young parents, homeowners, newly married couples, and anyone who wants affordable financial protection during their highest earning years. It allows families to secure substantial coverage without placing a heavy burden on their monthly budget.

    Life insurance should be part of a broader financial strategy. Strengthen your future with our

    Retirement Planning Guide

    and discover how technology is changing wealth management in our

    AI Investing Guide 2026
    .

    For reliable consumer guidance on purchasing life insurance, visit the
    National Association of Insurance Commissioners (NAIC).
    You can also find general financial education and consumer protection resources at
    USA.gov.

    Understanding how term coverage works is the first step in comparing Term Life vs Whole Life Insurance. In the next section, we’ll explore whole life insurance, explain how cash value grows, and compare its long-term benefits with term life coverage.

    What Is Whole Life Insurance? Benefits, Cash Value, and Long-Term Protection

    After learning how term life insurance works, the next step in comparing Term Life vs Whole Life Insurance is understanding whole life insurance. Unlike term life insurance, whole life insurance provides lifelong coverage as long as premiums are paid. In addition to a guaranteed death benefit, it also builds a cash value that grows over time, making it both an insurance policy and a long-term financial asset.

    How Does Whole Life Insurance Work?

    A portion of every premium pays for life insurance coverage, while another portion is added to the policy’s cash value. This cash value grows on a tax-deferred basis and may be accessed through policy loans or withdrawals, depending on the insurer’s rules. Because of these additional benefits, whole life insurance premiums are generally much higher than term life insurance premiums.

    Advantages of Whole Life Insurance

    • Lifetime coverage with no expiration date.
    • Guaranteed death benefit for beneficiaries.
    • Cash value grows over time.
    • Potential to borrow against accumulated cash value.
    • Predictable premiums that generally remain level throughout life.

    Potential Disadvantages

    • Higher monthly premiums than term life insurance.
    • Cash value grows slowly during the early years.
    • Less affordable for young families with limited budgets.
    • More complex policy structure compared to term

    Building financial security involves more than purchasing life insurance. Learn long-term investing strategies in our

    SIP Investing Guide 2026

    and discover reliable income opportunities through our

    Top Dividend Stocks USA 2026
    .

    For trusted consumer guidance on life insurance policies, visit the
    National Association of Insurance Commissioners (NAIC).
    Additional financial education is available from the
    Consumer Financial Protection Bureau (CFPB).

    Understanding the differences between whole life and term coverage makes comparing Term Life vs Whole Life Insurance much easier. In the next section, we’ll compare both policies side by side using a detailed comparison table, a premium calculator, and a real-life case study to help you choose the right life insurance policy for 2026.

    Term Life vs Whole Life Insurance Comparison: Which Policy Offers Better Value?

    Now that you understand how both policies work, it’s time to compare Term Life vs Whole Life Insurance side by side. Although both provide financial protection for your loved ones, they differ significantly in cost, policy duration, cash value, flexibility, and long-term financial benefits. Choosing the right policy depends on your age, financial goals, family responsibilities, and budget.

    Term Life vs Whole Life Insurance Comparison Table

    FeatureTerm Life InsuranceWhole Life Insurance
    Coverage Period10, 20, or 30 YearsLifetime Coverage
    Monthly PremiumLowerHigher
    Cash ValueNoYes
    Investment GrowthNoneTax-Deferred
    Death BenefitGuaranteed During Policy TermGuaranteed for Life
    Policy LoansNoAvailable
    Best ForAffordable Family ProtectionLong-Term Wealth & Estate Planning

    Simple Premium Comparison Calculator

    Estimated Lifetime Premium Cost

    Monthly Premium × 12 × Policy Years

    Example

    Term Life Premium = $35/month

    20-Year Policy = $35 × 12 × 20 = $8,400

    Whole Life Premium = $250/month

    20 Years = $250 × 12 × 20 = $60,000

    Although whole life insurance costs considerably more, it builds cash value and provides permanent lifetime protection.

    Real-Life Case Study

    Michael and Sarah, a married couple in their early thirties with two young children, wanted life insurance to protect their family’s future. After comparing Term Life vs Whole Life Insurance, they selected a 30-year term life policy because it provided $1 million of coverage at an affordable monthly premium. The money they saved on premiums was invested toward retirement and their children’s education. As their financial situation improves, they plan to evaluate permanent life insurance later in life.

    Families with higher incomes, estate planning goals, or lifelong financial protection needs may find whole life insurance more appropriate despite the higher premiums.

    If you’re new to life insurance, continue with our

    Insurance for Beginners USA 2026: Complete Guide to Choosing the Right Coverage
    .
    It explains insurance basics, premiums, beneficiaries, claims, and policy selection in simple language before comparing advanced insurance products.

    For trusted consumer information, visit the
    National Association of Insurance Commissioners (NAIC)
    and the
    Consumer Financial Protection Bureau (CFPB).

    Comparing Term Life vs Whole Life Insurance side by side helps you focus on long-term value instead of price alone. The right policy should fit your family’s financial goals, income, and future responsibilities while providing lasting peace of mind.

    Which Is Better? Choosing Between Term Life and Whole Life Insurance

    The answer to Term Life vs Whole Life Insurance depends on your financial goals, age, family responsibilities, and long-term plans. Neither policy is universally better. Instead, the right choice depends on how much coverage you need, how long you need it, and how much you’re comfortable paying each month.

    Best for Young Adults

    Young professionals beginning their careers usually benefit from term life insurance because it provides high coverage at affordable premiums. It protects future income while leaving more money available for investing, paying student loans, or purchasing a first home.

    Best for Families with Children

    Parents often need enough coverage to replace lost income, pay off a mortgage, cover childcare expenses, and fund college education. For most families, term life insurance provides excellent protection at a lower monthly cost. However, families with significant assets may also consider adding a whole life policy for long-term financial planning.

    Best for High-Income Earners

    Individuals with substantial wealth, business ownership, or estate planning goals often choose whole life insurance because of its permanent coverage, tax-deferred cash value growth, and estate planning benefits. Although premiums are higher, the policy can become an important part of a long-term financial strategy.

    Best for Retirees and Estate Planning

    Retirees looking to leave a financial legacy or help cover estate taxes may find whole life insurance more suitable. Lifetime coverage ensures beneficiaries receive a guaranteed death benefit regardless of when the policyholder passes away.

    Recommended Financial Resources

    • NAIC Life Insurance Buyer’s Guide — Independent consumer guidance for comparing life insurance policies.
    • Fidelity Financial Planning — Retirement and long-term financial planning resources.
    • The Bogleheads’ Guide to Investing — A trusted personal finance book focused on long-term wealth building.

    Recommended Life Insurance Companies

    • State Farm — Competitive term life insurance with flexible coverage options.
    • Northwestern Mutual — Well-known for permanent life insurance and financial planning services.
    • New York Life — Offers both term and whole life insurance with customizable policy options.

    Life insurance works best as part of a complete financial plan. Strengthen your long-term wealth with our

    Retirement Planning Guide
    ,
    learn how technology is transforming personal finance through our

    AI Investing Guide 2026
    ,
    and build consistent wealth using our

    SIP Investing Guide 2026
    .

    For official consumer guidance about life insurance, visit the
    National Association of Insurance Commissioners (NAIC).
    Additional financial education is available from the
    Consumer Financial Protection Bureau (CFPB).

    Understanding Term Life vs Whole Life Insurance allows you to choose a policy that matches your family’s financial needs, protects your loved ones, and supports your long-term wealth-building strategy. Taking time to compare both options today can provide financial security and peace of mind for decades to come.

    Common Life Insurance Mistakes and Future Trends in 2026

    Understanding Term Life vs Whole Life Insurance is only the first step toward protecting your family’s financial future. Many Americans purchase the wrong policy because they focus only on monthly premiums or fail to review their long-term financial goals. Avoiding these common mistakes can help you choose the right life insurance coverage while maximizing the value of your policy.

    1. Buying Too Little Coverage

    One of the biggest mistakes is purchasing a policy with an insufficient death benefit. Your life insurance should cover outstanding debts, mortgage payments, children’s education expenses, daily living costs, and future financial obligations. Underestimating these expenses may leave your family financially vulnerable.

    2. Choosing a Policy Based Only on Price

    Although affordable premiums are important, the cheapest policy isn’t always the best choice. Compare coverage length, financial strength of the insurer, policy features, cash value benefits, and long-term flexibility before making your decision.

    3. Waiting Too Long to Buy Life Insurance

    Life insurance generally becomes more expensive as you get older. Purchasing coverage while you’re young and healthy usually results in lower premiums and a wider range of policy options.

    4. Not Reviewing Beneficiaries

    Marriage, divorce, the birth of children, or other major life events should prompt you to review and update your policy beneficiaries. Keeping beneficiary information current helps ensure your death benefit reaches the intended recipients.

    Future Trends in Life Insurance

    Life insurance is becoming more digital than ever before. Many insurers now offer online applications, accelerated underwriting, electronic policy management, AI-powered risk assessments, wearable health data integration, and faster claims processing. These innovations are making life insurance easier to purchase while improving the customer experience.

    Protecting your family should go hand in hand with building long-term wealth. Learn how to prepare your portfolio for uncertain markets in our

    Recession-Proof Investing Guide 2026

    and compare money-saving financial tools in our

    Best Credit Cards 2026
    .

    Trusted Consumer Resources

    Before purchasing life insurance, compare policies using trusted resources like the
    National Association of Insurance Commissioners (NAIC),
    review consumer protection information from the
    Consumer Financial Protection Bureau (CFPB),
    and explore financial education through
    USA.gov.
    These organizations provide reliable information to help consumers make informed insurance decisions.

    By carefully comparing Term Life vs Whole Life Insurance, avoiding common buying mistakes, and reviewing your financial goals regularly, you’ll be better prepared to select a policy that protects your loved ones, supports long-term financial security, and provides peace of mind for years to come.

    Expert Checklist, Trusted Resources, and Frequently Asked Questions

    Choosing between Term Life vs Whole Life Insurance becomes much easier when you understand your financial goals, family responsibilities, and long-term protection needs. Instead of focusing only on monthly premiums, compare policy duration, death benefits, cash value growth, financial flexibility, and your future income requirements. Taking time to evaluate these factors today can help protect your loved ones while avoiding expensive insurance mistakes in the future.

    Expert Checklist Before Buying Life Insurance

    • ✔ Calculate how much life insurance your family actually needs.
    • ✔ Compare at least three life insurance companies before purchasing.
    • ✔ Review policy premiums and long-term affordability.
    • ✔ Compare Term Life and Whole Life benefits carefully.
    • ✔ Check the insurer’s financial strength and customer reviews.
    • ✔ Review policy riders such as disability, critical illness, and accidental death benefits.
    • ✔ Update your beneficiaries after major life events.
    • ✔ Review your life insurance coverage every few years.

    Recommended Resources

    • NAIC Life Insurance Buyer’s Guide — Independent guidance for comparing life insurance policies.
    • Fidelity Financial Planning — Retirement planning and long-term wealth management resources.
    • The Bogleheads’ Guide to Investing — One of the most trusted personal finance books for long-term investors.

    Frequently Asked Questions (FAQs)

    1. What is the biggest difference between Term Life and Whole Life Insurance?

    Term life insurance provides coverage for a specific number of years and does not build cash value. Whole life insurance offers permanent lifetime coverage while building tax-deferred cash value that can be accessed during your lifetime.

    2. Which type of life insurance is more affordable?

    Term life insurance is usually much more affordable because it provides temporary coverage without a savings or investment component. Whole life insurance costs more due to its lifetime protection and cash value feature.

    3. Who should choose Whole Life Insurance?

    Whole life insurance may be a good option for high-income earners, business owners, individuals interested in estate planning, or anyone seeking lifelong protection and guaranteed cash value growth.

    4. Can I convert a Term Life policy into Whole Life Insurance?

    Many insurance companies offer conversion options that allow eligible policyholders to convert a term policy into permanent life insurance without completing another medical examination. Conversion rules vary by insurer and policy.

    5. Where can I compare life insurance companies safely?

    Compare policies using trusted consumer resources such as the
    National Association of Insurance Commissioners (NAIC),
    the
    Consumer Financial Protection Bureau (CFPB),
    and
    USA.gov
    for reliable financial education and consumer protection information.

    By understanding Term Life vs Whole Life Insurance, comparing policy features carefully, and using trusted financial resources, you’ll be able to select the life insurance policy that best protects your family and supports your long-term financial goals. In the final section, we’ll summarize the key takeaways, revisit our complete insurance guide, include a professional email subscribe box, and finish with a premium colorful author box.

    Conclusion

    Choosing between Term Life vs Whole Life Insurance is one of the most important financial decisions you’ll make for your family’s future. While both policies provide valuable financial protection, the best choice depends on your age, income, financial responsibilities, long-term goals, and budget. Term life insurance offers affordable, high-value coverage for a specific period, making it ideal for young families, homeowners, and individuals with temporary financial obligations. Whole life insurance, on the other hand, provides lifelong protection, guaranteed cash value growth, and long-term estate planning benefits.

    Before purchasing any policy, compare premiums, coverage amounts, policy duration, cash value benefits, riders, and the financial strength of the insurance company. Reviewing your life insurance needs every few years—and after major life events such as marriage, buying a home, or having children—helps ensure your family remains financially protected as your circumstances change.

    If you’re still learning the basics of insurance, continue with our complete

    Insurance for Beginners USA 2026: Complete Guide to Choosing the Right Coverage
    .
    You can also strengthen your financial future by exploring our

    Retirement Planning Guide

    and discover smart money-saving strategies with our

    Best Credit Cards 2026
    .
    Combining the right life insurance policy with a solid financial plan gives your loved ones greater security and peace of mind for years to come.

    📩 Stay Updated with Insurance & Personal Finance Tips

    Subscribe for free weekly insights on life insurance, retirement planning, investing, passive income, and smart money management. Get practical financial tips delivered straight to your inbox.


    Subscribe Free

    ✔ Weekly Financial Tips   |   ✔ No Spam   |   ✔ Unsubscribe Anytime

    SR

    Subhash Rukade

    Founder • FinanceInvestment.site

    Subhash Rukade writes practical, research-backed articles on life insurance, health insurance, retirement planning, investing, passive income, and personal finance. His goal is to simplify complex financial topics into easy-to-understand guides that help Americans make confident financial decisions and build long-term wealth.


    Life Insurance


    Retirement


    Investing


    USA Finance

  • AI Financial Assistants: The Next Big Money Trend in 2026

    AI Financial Assistants: The Next Big Money Trend in 2026


    AI Financial Assistants: The Next Big Money Trend in 2026

    Author: Subhash Rukade

    Published: June 18, 2026

    AI Financial Assistants

    Why AI Financial Assistants Are Becoming So Popular

    AI Financial Assistants are quickly becoming one of the biggest trends in personal finance. Across the United States, investors, savers, and families are using artificial intelligence to simplify money management and make smarter financial decisions.

    Just a few years ago, managing finances often meant tracking expenses manually, reviewing spreadsheets, and spending hours researching investment opportunities. In 2026, AI-powered financial tools can perform many of these tasks automatically.

    Modern AI Financial Assistants can analyze spending patterns, monitor savings goals, track investments, identify unusual transactions, and provide personalized recommendations. As a result, users can spend less time managing money and more time focusing on their financial goals.

    One of the biggest reasons for the rapid growth of AI Financial Assistants is accessibility. Professional financial advice is often expensive. Many Americans cannot justify paying large advisory fees, especially when starting their wealth-building journey.

    Artificial intelligence is changing that situation.

    AI-powered platforms now provide financial insights that were once available only to wealthy investors. Whether someone wants to build an emergency fund, improve budgeting habits, invest for retirement, or generate passive income, AI tools can offer guidance based on individual financial situations.

    The rise of AI Financial Assistants is closely connected to the broader transformation happening across the investing industry. Investors who want a complete understanding of this shift should explore our
    AI Investing Guide 2026.

    Another major advantage is personalization. Traditional financial advice often follows general rules. AI systems can analyze user behavior and generate recommendations based on specific goals, income levels, spending habits, and investment preferences.

    As artificial intelligence continues improving, these tools are becoming more accurate, more useful, and more capable of helping Americans make informed financial decisions.

    For many investors, AI Financial Assistants are no longer futuristic technology. They are becoming practical everyday tools that support budgeting, investing, saving, and long-term wealth building.

    How AI Financial Assistants Work

    Understanding how AI Financial Assistants work can help investors take full advantage of this growing financial technology trend.

    At their core, AI Financial Assistants use artificial intelligence, machine learning, and data analysis to review financial information and generate personalized recommendations. These systems continuously learn from user behavior, helping them deliver more accurate insights over time.

    Unlike traditional budgeting apps that simply track transactions, AI Financial Assistants actively analyze financial habits and suggest actions that may improve financial outcomes.

    AI Budgeting and Expense Tracking

    One of the most popular features is automated budgeting.

    AI Financial Assistants can connect to bank accounts, categorize transactions, and identify spending patterns automatically. Users no longer need to manually sort expenses or build complex spreadsheets.

    The system can detect areas where spending is increasing and provide recommendations to reduce unnecessary expenses.

    Investors interested in AI-powered budgeting tools can also read our
    AI Personal Finance 2026
    guide.

    Smart Savings Recommendations

    Saving money consistently is often difficult.

    AI Financial Assistants help solve this problem by analyzing cash flow and recommending realistic savings targets. Some platforms can even automate transfers into savings accounts based on spending habits and income patterns.

    This creates a more disciplined approach to wealth building.

    Credit Monitoring and Alerts

    Many AI systems also monitor credit health.

    Users receive notifications about credit score changes, unusual account activity, and opportunities to improve their financial profiles.

    Choosing the right financial products can also support long-term financial success. Readers can compare options in our
    Best Credit Cards 2026
    guide.

    Goal-Based Financial Planning

    Modern AI Financial Assistants are increasingly focused on financial goals.

    Whether someone wants to retire early, pay off debt, purchase a home, or build passive income, AI systems can track progress and suggest adjustments when needed.

    📊 Comparison Table: AI Financial Assistants vs Traditional Financial Planning

    FeatureAI Financial AssistantsTraditional Planning
    Budget TrackingAutomatedManual
    Spending AnalysisReal-TimePeriodic Reviews
    Savings RecommendationsPersonalizedGeneral Advice
    Credit MonitoringContinuous AlertsLimited Monitoring
    Financial Planning24/7 SupportScheduled Meetings

    As technology continues advancing, AI Financial Assistants are expected to become even more intelligent and personalized. For many Americans, they are quickly becoming an essential tool for managing money more effectively.

    AI Financial Assistants and Investing: A New Era of Wealth Building

    One of the most exciting benefits of AI Financial Assistants is their growing role in investing and wealth building. While many people initially use AI tools for budgeting and savings, investors are increasingly relying on artificial intelligence to help manage portfolios, monitor risk, and identify opportunities for long-term growth.

    The investing world generates enormous amounts of data every day. Market movements, earnings reports, interest rates, economic indicators, and company news can be difficult for individual investors to track consistently.

    AI Financial Assistants help solve this problem by processing large amounts of information quickly and providing insights that may help investors make better decisions.

    AI Portfolio Monitoring

    Modern AI systems can monitor investment portfolios around the clock.

    Instead of manually reviewing holdings every day, investors can receive alerts when portfolios become unbalanced, risk levels increase, or significant market changes occur.

    This helps investors stay informed without constantly watching financial markets.

    Risk Analysis and Diversification

    Managing risk is one of the most important parts of successful investing.

    AI Financial Assistants can evaluate portfolio diversification, identify concentration risks, and recommend adjustments that align with an investor’s goals and risk tolerance.

    By helping investors avoid emotional decisions, AI can support a more disciplined investment strategy.

    AI and Dividend Investing

    Dividend investing remains one of the most popular wealth-building strategies in America.

    AI-powered tools can help investors identify quality dividend stocks, monitor payout growth, and track income performance over time.

    Readers interested in creating long-term passive income can explore our
    How to Build a Dividend Portfolio
    guide.

    Investors looking for potential opportunities can also review our
    Top Dividend Stocks USA 2026
    resource.

    Building Wealth Through Automation

    One of the biggest advantages of AI Financial Assistants is consistency.

    Many investors struggle because they invest emotionally or abandon long-term plans during market volatility. AI systems can automate investing decisions, portfolio reviews, and contribution schedules based on predefined goals.

    This helps investors remain focused on long-term wealth building rather than short-term market noise.

    📘 Recommended Finance Book


    The Psychology of Money by Morgan Housel

    This bestselling finance book explains how behavior and decision-making influence investment success. Even with advanced AI tools, understanding human psychology remains one of the most important parts of building wealth.

    As AI technology continues evolving, AI Financial Assistants may become powerful partners for investors seeking smarter portfolio management, stronger risk control, and more efficient wealth-building strategies.

    Real-World Example: How AI Financial Assistants Help Americans Build Wealth

    The growing popularity of AI Financial Assistants is not just about technology. It is about helping real people make better financial decisions every day.

    Many Americans struggle to balance budgeting, saving, investing, debt repayment, and retirement planning. Managing all these responsibilities simultaneously can feel overwhelming.

    This is where AI-powered financial tools can provide meaningful support.

    📊 Real-World Case Study

    Consider Sarah, a 35-year-old marketing professional living in Texas.

    Sarah earns $75,000 annually and wants to achieve three goals:

    • Build a larger emergency fund
    • Increase retirement savings
    • Create passive income through investing

    Before using AI Financial Assistants, Sarah managed her finances manually. She often missed savings targets and struggled to track spending patterns.

    After connecting her accounts to an AI-powered financial platform, the system began analyzing her spending habits.

    Within a few weeks, the AI identified recurring expenses, unnecessary subscriptions, and spending categories where savings opportunities existed.

    The assistant recommended automatic transfers to savings accounts and increased retirement contributions without significantly impacting monthly cash flow.

    Over time, Sarah became more consistent with her financial plan.

    AI Financial Assistants Example

    💰 Investment Growth Calculator Example

    Suppose Sarah invests $300 per month into a diversified portfolio earning an average annual return of 8%.

    Years InvestedEstimated Portfolio Value
    10 Years~$55,000
    20 Years~$177,000
    30 Years~$447,000

    This example demonstrates how consistent investing combined with smart financial management can create meaningful wealth over time.

    AI Financial Assistants and Retirement Planning

    Many modern AI Financial Assistants can also help users prepare for retirement.

    These systems can estimate future savings needs, monitor retirement accounts, and recommend adjustments based on changing financial goals.

    Rather than replacing financial advisors, AI tools often act as intelligent assistants that help users stay organized and focused.

    For investors, the greatest value may come from improved consistency. Small improvements in budgeting, saving, and investing can compound into significant financial results over decades.

    Common Mistakes and Risks of Using AI Financial Assistants

    While AI Financial Assistants offer many benefits, investors should also understand their limitations. Like any financial tool, artificial intelligence works best when used responsibly.

    Many people assume AI can solve every financial problem automatically. In reality, successful money management still requires human judgment, financial education, and long-term planning.

    Understanding the risks can help investors use AI Financial Assistants more effectively.

    Mistake #1: Blindly Trusting AI Recommendations

    One of the biggest mistakes users make is assuming every AI recommendation is correct.

    Artificial intelligence analyzes available data and generates suggestions based on patterns. However, it cannot predict the future with complete accuracy.

    Investors should always review recommendations carefully and ensure they align with personal financial goals.

    Mistake #2: Ignoring Data Privacy

    Most AI Financial Assistants require access to financial information such as bank accounts, spending data, investment portfolios, and credit reports.

    Users should carefully review privacy policies and security measures before connecting sensitive financial accounts.

    Choosing reputable platforms with strong security practices is essential.

    Mistake #3: Depending Entirely on Automation

    Automation can improve consistency, but relying completely on AI can create problems.

    Financial goals, family situations, and market conditions change over time. Investors should regularly review their financial plans rather than assuming automation will handle every situation perfectly.

    Market Risks Still Exist

    Even the best AI Financial Assistants cannot eliminate investment risk.

    Markets remain unpredictable. Economic recessions, geopolitical events, and unexpected market downturns can impact investment performance.

    Investors who want to strengthen their portfolios during uncertain times should also read our
    Recession-Proof Investing 2026
    guide.

    Trusted Financial Resources

    📘 Recommended Finance Book


    The Simple Path to Wealth by JL Collins

    This popular investing book emphasizes diversification, long-term investing, and financial discipline. These principles remain important regardless of how advanced AI Financial Assistants become.

    The smartest investors view AI as a powerful tool rather than a replacement for financial knowledge. Combining technology with sound decision-making often produces the best long-term results.

    Practical Strategies for Using AI Financial Assistants Successfully

    The most successful users of AI Financial Assistants understand an important principle: artificial intelligence works best when combined with human judgment.

    AI can analyze data, identify patterns, and automate financial tasks. However, investors still need to define goals, manage risk, and make final decisions.

    Instead of replacing financial planning, AI Financial Assistants should be viewed as powerful tools that support smarter money management.

    Use the AI + Human Strategy

    One of the best approaches is combining AI recommendations with personal financial knowledge.

    For example, an AI assistant may recommend increasing investment contributions or adjusting spending habits. Investors should review these recommendations and ensure they align with personal goals before taking action.

    This balanced approach helps maximize the benefits of AI while maintaining control over financial decisions.

    Build a Strong Emergency Fund

    Many AI Financial Assistants can help users identify opportunities to save more money.

    Building an emergency fund should remain a priority before taking significant investment risks.

    A strong emergency fund provides financial stability during unexpected situations such as job loss, medical expenses, or economic downturns.

    Stay Consistent With Long-Term Investing

    Consistency is often more important than trying to predict short-term market movements.

    AI Financial Assistants can automate recurring investments and help investors stay committed to long-term wealth-building plans.

    Readers interested in disciplined investing strategies should also explore our
    SIP Investing Guide 2026.

    📊 Comparison Table: Smart AI User vs Poor AI User

    Smart AI UserPoor AI User
    Uses AI as a guideFollows AI blindly
    Reviews recommendationsNever verifies suggestions
    Diversifies investmentsConcentrates risk
    Focuses on long-term goalsChases short-term trends
    Maintains emergency savingsIgnores financial safety nets

    📘 Recommended Finance Book


    Rich Dad Poor Dad by Robert Kiyosaki

    This classic personal finance book teaches important lessons about assets, cash flow, investing, and wealth creation. These concepts remain valuable even in an AI-driven financial world.

    The future belongs to investors who combine technology, discipline, diversification, and long-term thinking. AI Financial Assistants can make financial management easier, but consistent action remains the foundation of lasting wealth.

    The Future of AI Financial Assistants: What Investors Can Expect by 2030

    The future of AI Financial Assistants looks incredibly promising. As artificial intelligence continues evolving, these tools are expected to become more intelligent, more personalized, and more integrated into everyday financial life.

    Today, AI Financial Assistants help users budget, save, and monitor investments. By 2030, many experts believe these systems could function as complete financial management platforms capable of supporting nearly every aspect of personal finance.

    AI Wealth Management Will Become More Personalized

    Future AI Financial Assistants may analyze income, spending habits, investment performance, retirement goals, and risk tolerance simultaneously.

    Instead of providing generic recommendations, they may create highly customized financial plans tailored to each individual’s unique circumstances.

    AI Retirement Planning Will Improve

    Retirement planning remains one of the biggest financial challenges facing Americans.

    Future AI systems may automatically adjust retirement contributions, estimate future healthcare costs, optimize withdrawal strategies, and monitor retirement readiness in real time.

    This could make retirement planning more accessible and effective for millions of households.

    Smarter Banking and Money Management

    Banks are investing heavily in artificial intelligence.

    Future AI Financial Assistants may provide predictive cash-flow management, advanced fraud protection, automated bill optimization, and personalized savings strategies directly within banking platforms.

    As a result, managing money could become significantly easier and more efficient.

    Frequently Asked Questions

    1. What are AI Financial Assistants?

    AI Financial Assistants are software tools that use artificial intelligence to help users manage budgeting, saving, investing, debt repayment, and financial planning.

    2. Are AI Financial Assistants safe?

    Most reputable platforms use strong security measures. However, users should always review privacy policies and security practices before connecting financial accounts.

    3. Can AI Financial Assistants help with investing?

    Yes. Many platforms offer portfolio monitoring, investment analysis, diversification recommendations, and risk management insights.

    4. Can AI replace financial advisors?

    AI can automate many financial tasks, but human advisors still provide emotional support, complex planning, and personalized guidance for unique situations.

    5. Do AI Financial Assistants help with retirement planning?

    Yes. Many tools already support retirement savings tracking, goal monitoring, and investment planning.

    6. Are AI Financial Assistants worth using in 2026?

    For many investors, they provide valuable insights, automation, and convenience that can improve financial decision-making.

    Conclusion

    AI Financial Assistants are becoming one of the most important trends in modern personal finance. They help users automate budgeting, improve saving habits, monitor investments, and make smarter financial decisions.

    As artificial intelligence becomes more advanced, these tools are expected to play an even larger role in wealth building, retirement planning, and everyday money management.

    Investors who want to stay ahead of these trends should also read our
    AI Investing Guide 2026.

    Additional trusted resources:

    📩 Join Our Free Financial Newsletter

    Get AI investing insights, personal finance tips, retirement strategies, passive income ideas, and wealth-building guides delivered directly to your inbox.


    Subscribe today and stay ahead of the future of money management.


    👨‍💼 About the Author

    Subhash Rukade writes about AI investing, personal finance, retirement planning, passive income, and wealth-building strategies. His mission is to help readers make smarter financial decisions through practical and easy-to-understand financial education.

  • AI vs Traditional Financial Advisors: Which Is Better for Investors in 2026?

    AI vs Traditional Financial Advisors: Which Is Better for Investors in 2026?


    AI vs Traditional Financial Advisors: Which Is Better for Investors in 2026?

    Author: Subhash Rukade

    Published: June 17, 2026

    AI vs Traditional Financial Advisors

    Why Investors Are Comparing AI and Human Financial Advisors in 2026

    AI vs Traditional Financial Advisors has become one of the biggest discussions in personal finance and investing. As artificial intelligence continues transforming the financial industry, investors are increasingly asking whether technology can deliver the same value as an experienced human advisor.

    For decades, traditional financial advisors helped individuals create retirement plans, build investment portfolios, manage risk, and navigate major financial decisions.

    However, the rise of AI-powered investing platforms has changed the landscape.

    Today’s AI systems can analyze massive amounts of financial data, monitor portfolios in real time, automate investment decisions, and provide personalized recommendations based on investor goals.

    As a result, many Americans now have access to sophisticated financial tools that were once available primarily to wealthy clients.

    Cost is another reason this comparison is gaining attention.

    Traditional financial advisors often charge annual management fees, consultation fees, or asset-based fees. AI-powered platforms typically offer lower-cost solutions that appeal to younger investors and middle-class families seeking affordable financial guidance.

    At the same time, many investors still value the experience, emotional support, and personalized advice that human advisors provide during uncertain market conditions.

    This creates an important question:

    Can artificial intelligence truly replace human financial expertise, or is the future of investing a combination of both?

    Readers who want a broader understanding of how artificial intelligence is transforming investing should also explore our
    AI Investing Guide 2026.

    In this comprehensive guide, we’ll compare AI financial advisors and traditional financial advisors, examine their strengths and weaknesses, explore real-world investing scenarios, and help you determine which approach may be best suited to your financial goals in 2026.

    How AI Financial Advisors Work in 2026

    Understanding how AI-powered investing platforms operate is essential when comparing AI vs Traditional Financial Advisors.

    While traditional advisors rely on personal meetings, experience, and human judgment, AI financial advisors use advanced algorithms, data analysis, and automation to help investors manage their money.

    The goal is similar: help clients build wealth and achieve financial goals.

    However, the process is very different.

    What Are AI Financial Advisors?

    AI financial advisors, often called robo-advisors, use artificial intelligence and machine learning to create and manage investment portfolios.

    After answering questions about age, income, risk tolerance, investment goals, and time horizon, investors receive portfolio recommendations tailored to their financial situation.

    Many platforms automatically invest funds, rebalance portfolios, and monitor risk without requiring constant human involvement.

    How AI Improves Portfolio Management

    One of the biggest advantages of AI is its ability to process large amounts of data quickly.

    AI systems can monitor market trends, evaluate asset performance, identify portfolio imbalances, and suggest adjustments almost instantly.

    Instead of waiting for scheduled advisor meetings, investors receive continuous portfolio oversight.

    Goal-Based Investing

    Many AI investing platforms focus on goal-based investing.

    Whether the objective is retirement planning, buying a home, creating passive income, or building long-term wealth, AI systems can create strategies designed around specific financial targets.

    Investors interested in improving budgeting and long-term financial planning should also review our
    AI Personal Finance 2026
    guide.

    Managing personal finances effectively often begins with choosing the right financial products. Our
    Best Credit Cards 2026
    resource can help readers explore useful financial tools.

    📊 Comparison Table: AI Advisors vs Traditional Advisors

    FeatureAI Financial AdvisorsTraditional Financial Advisors
    CostGenerally LowerUsually Higher
    Availability24/7 AccessAppointment Based
    Portfolio MonitoringContinuousPeriodic Reviews
    Human InteractionLimitedPersonalized Guidance
    Emotional SupportNoYes
    Complex PlanningBasic to ModerateAdvanced

    AI financial advisors have made investing more accessible and affordable for millions of Americans.

    However, understanding their strengths and limitations is important before deciding whether they can fully replace traditional financial advisors.

    In the next section, we’ll examine the major advantages that AI financial advisors offer investors in 2026.

    Advantages of AI Financial Advisors in 2026

    One reason the debate around AI vs Traditional Financial Advisors continues to grow is that artificial intelligence offers several advantages that appeal to modern investors.

    For many Americans, AI-powered financial platforms provide affordable access to investment management tools that were once reserved for high-net-worth individuals.

    Let’s examine the biggest benefits of AI financial advisors in 2026.

    1. Lower Costs and Fees

    Cost is often the first advantage investors notice.

    Traditional financial advisors commonly charge management fees based on assets under management, hourly consultation rates, or annual planning fees.

    Many AI-driven platforms operate at significantly lower costs.

    For investors with smaller portfolios, these savings can make a meaningful difference over time.

    Lower fees also allow more investment capital to remain invested and compound over the long term.

    2. 24/7 Portfolio Monitoring

    Unlike human advisors who work during business hours, AI systems monitor portfolios continuously.

    These platforms can track market movements, identify portfolio imbalances, and suggest adjustments in real time.

    This constant oversight helps investors stay informed without manually monitoring markets every day.

    3. Faster Data Analysis

    Artificial intelligence excels at processing large amounts of information quickly.

    AI systems can evaluate economic trends, market performance, portfolio risk, and investment opportunities much faster than traditional manual analysis.

    This speed allows investors to access insights almost instantly.

    4. Accessibility for Everyday Investors

    Many traditional advisors require minimum account balances that can be difficult for beginner investors to meet.

    AI investing platforms often allow users to start with relatively small amounts of money.

    This makes professional-quality investment tools accessible to a wider audience.

    5. Automated Wealth Building

    AI advisors can automate portfolio rebalancing, recurring investments, dividend reinvestment, and risk management.

    Investors focused on creating long-term income may also benefit from learning how to build diversified income portfolios.

    Our
    How to Build a Dividend Portfolio
    guide provides practical strategies for dividend investing.

    Readers looking for income-producing investments can also explore our
    Top Dividend Stocks USA 2026
    resource.

    📘 Recommended Finance Book


    The Little Book of Common Sense Investing by John C. Bogle

    This investing classic emphasizes low-cost investing, diversification, and long-term wealth building—principles that align closely with many AI-powered investing platforms.

    While AI financial advisors offer impressive efficiency, affordability, and convenience, they are not perfect solutions for every investor.

    In the next section, we’ll examine the strengths that traditional financial advisors continue to bring to the table in 2026.

    Advantages of Traditional Financial Advisors in 2026

    Although AI-powered investing platforms continue to grow, the debate surrounding AI vs Traditional Financial Advisors remains active because human advisors still offer advantages that technology cannot fully replicate.

    Financial decisions are often emotional, personal, and complex.

    While artificial intelligence can analyze data and automate investing tasks, experienced financial advisors provide human judgment, personalized guidance, and emotional support during important life events.

    1. Personalized Financial Planning

    Traditional financial advisors take a comprehensive approach to wealth management.

    They consider retirement goals, family circumstances, tax planning, insurance needs, estate planning, education funding, and long-term financial objectives.

    Unlike AI systems that rely primarily on data inputs, human advisors can adapt recommendations based on changing personal situations.

    2. Emotional Support During Market Volatility

    One of the biggest challenges investors face is managing emotions.

    Fear and greed often lead to poor financial decisions.

    During market downturns, many investors panic and sell investments at the wrong time.

    Experienced advisors help clients stay focused on long-term goals and avoid emotionally driven mistakes.

    3. Complex Financial Situations

    AI tools perform well with straightforward investing strategies.

    However, high-net-worth individuals, business owners, retirees, and families with complicated financial situations often require customized planning.

    Traditional advisors can provide tailored solutions that go beyond automated portfolio management.

    4. Retirement and Estate Planning

    Retirement planning involves more than selecting investments.

    Social Security strategies, tax-efficient withdrawals, healthcare planning, estate transfers, and legacy planning often require professional guidance.

    Human advisors can coordinate these decisions within a broader financial plan.

    AI vs Traditional Financial Advisors Comparison

    📊 Real-World Example

    Consider Sarah, a 58-year-old investor preparing for retirement.

    Her investment portfolio was already diversified and performing well through an AI-powered platform.

    However, she needed help determining when to claim Social Security benefits, how to manage retirement withdrawals, and how to reduce future tax liabilities.

    In this situation, a traditional financial advisor provided valuable guidance that extended beyond portfolio management.

    The advisor helped Sarah create a retirement income strategy, evaluate healthcare costs, and update her estate plan.

    This example highlights an important reality.

    AI excels at automation, efficiency, and portfolio management. Traditional advisors excel at personal relationships, emotional coaching, and complex financial planning.

    For many investors, the choice isn’t necessarily AI or human advice. Increasingly, the best solution may involve combining both approaches to create a more complete financial strategy.

    Common Mistakes Investors Make When Choosing Between AI and Traditional Financial Advisors

    The discussion around AI vs Traditional Financial Advisors often focuses on benefits, but investors can still make costly mistakes regardless of which option they choose.

    Artificial intelligence and human advisors can both be valuable tools. However, poor financial habits and unrealistic expectations frequently create problems that technology alone cannot solve.

    Understanding these mistakes can help investors make smarter decisions and build stronger long-term financial plans.

    1. Blindly Trusting AI Recommendations

    One of the most common mistakes is assuming that AI is always correct.

    AI systems analyze historical data, market trends, and portfolio information. However, markets are influenced by unexpected events, investor behavior, and economic changes that algorithms cannot predict perfectly.

    Successful investors use AI as a decision-support tool rather than relying on it blindly.

    2. Making Emotional Investment Decisions

    Even investors who use AI platforms often allow emotions to influence decisions.

    Fear during market declines and excitement during bull markets can lead to poor timing decisions.

    Traditional financial advisors often help clients remain disciplined during volatile periods.

    Whether using AI or a human advisor, maintaining a long-term perspective is essential.

    3. Ignoring Fees and Costs

    Many investors focus only on returns while ignoring fees.

    Traditional advisors may charge advisory fees, while some AI platforms include management costs and account fees.

    Over time, excessive fees can reduce portfolio growth significantly.

    Investors should always understand the total cost of any financial service they use.

    4. Lack of Diversification

    Concentrating investments in a small number of assets increases risk.

    Whether recommendations come from AI or human advisors, diversification remains one of the most important principles of successful investing.

    5. Investing Without a Financial Plan

    Many people focus on individual investments without defining clear financial goals.

    A strong financial plan should include savings targets, investment objectives, retirement goals, and risk management strategies.

    Readers looking to improve long-term investing discipline should review our
    SIP Investing Guide 2026.

    Preparing portfolios for uncertain economic conditions is equally important. Our
    Recession-Proof Investing 2026
    guide provides additional strategies.

    📘 Recommended Finance Book


    The Psychology of Money by Morgan Housel

    This bestselling book highlights the importance of behavior, patience, and financial decision-making—factors that often have a greater impact on wealth creation than investment selection alone.

    Avoiding these common mistakes can help investors get the most value from both AI financial tools and traditional advisory services while staying focused on long-term financial success.

    Which Option Is Better for Different Types of Investors?

    After comparing the strengths and weaknesses of both approaches, the biggest question remains:

    Who wins the AI vs Traditional Financial Advisors debate?

    The answer depends on an investor’s goals, financial situation, experience level, and the complexity of their finances.

    There is no one-size-fits-all solution.

    Instead, different investors may benefit from different approaches.

    1. Beginner Investors

    Many beginner investors prefer AI-powered platforms because they are affordable, easy to use, and highly automated.

    AI advisors can help new investors start building portfolios without requiring extensive financial knowledge.

    Features such as automatic rebalancing, recurring investments, and goal-based planning make investing more accessible.

    2. Middle-Class Investors

    Middle-class investors often seek a balance between affordability and professional guidance.

    For many households, AI financial advisors provide sufficient support for retirement investing, wealth building, and long-term portfolio management.

    Lower fees can also help investors keep more money invested and compounding over time.

    3. High-Net-Worth Investors

    Investors with significant assets often have more complex financial needs.

    Tax planning, estate planning, charitable giving strategies, business ownership, and retirement income planning frequently require personalized advice.

    In these situations, traditional financial advisors often provide additional value.

    4. The Hybrid Approach

    Many experts believe the future of financial advice will combine both AI and human expertise.

    AI handles portfolio monitoring, automation, and data analysis, while human advisors provide strategic guidance and emotional support.

    This hybrid model allows investors to benefit from technology without losing access to personalized advice.

    💰 Cost Comparison Example

    Portfolio SizeAI Advisor (0.25%)Traditional Advisor (1%)
    $100,000$250/year$1,000/year
    $250,000$625/year$2,500/year
    $500,000$1,250/year$5,000/year

    Over decades, lower fees can have a meaningful impact on long-term investment growth.

    📘 Recommended Finance Book


    The Simple Path to Wealth by JL Collins

    This highly respected investing book focuses on low-cost investing, long-term wealth creation, and financial independence.

    Ultimately, the best choice depends on your needs.

    Investors seeking simplicity and lower costs may prefer AI advisors. Those facing complex financial decisions may benefit from human expertise. For many Americans in 2026, combining both approaches may offer the strongest overall solution.

    The Future of Financial Advice (2026–2030)

    The future of AI vs Traditional Financial Advisors is unlikely to be a winner-takes-all scenario.

    Instead, the financial industry is moving toward a model where artificial intelligence and human expertise work together to deliver better outcomes for investors.

    As technology advances, AI systems will continue improving portfolio management, risk analysis, tax optimization, and financial planning capabilities.

    At the same time, investors will still value the personal relationships, trust, and guidance that experienced financial advisors provide.

    AI Will Become More Personalized

    Future AI platforms are expected to deliver highly customized financial recommendations.

    Rather than offering generic portfolios, AI systems may create investment plans based on income, spending habits, financial goals, life events, and risk tolerance.

    This could make professional-quality financial planning available to millions of Americans at lower costs.

    The Hybrid Advisor Model Will Expand

    Many financial firms are already combining artificial intelligence with human advisors.

    AI handles portfolio monitoring, data analysis, and automation, while human advisors focus on strategic planning and client relationships.

    This approach provides investors with the best of both worlds.

    Investors Will Demand More Transparency

    As AI becomes more influential in financial decision-making, investors will likely demand greater transparency regarding how recommendations are generated.

    Trust, security, and regulatory oversight will remain important priorities.

    Frequently Asked Questions

    1. Are AI financial advisors safe to use?

    Most regulated AI investing platforms use advanced security measures. However, investors should always research providers before investing.

    2. Can AI completely replace financial advisors?

    AI can automate many investing tasks, but complex planning and emotional guidance still benefit from human expertise.

    3. Which option is cheaper?

    AI financial advisors generally charge lower fees than traditional advisors.

    4. Are AI advisors good for beginners?

    Yes. Many beginner investors appreciate the simplicity, automation, and affordability of AI-powered investing platforms.

    5. When should I hire a traditional financial advisor?

    Investors facing complex financial situations, retirement planning challenges, or estate planning needs may benefit from personalized professional advice.

    6. Is a hybrid approach the future?

    Many industry experts believe combining AI technology with human expertise will become the preferred model for financial advice.

    Conclusion

    The debate surrounding AI vs Traditional Financial Advisors is not about choosing technology over people.

    Instead, it’s about understanding which tools and services best fit your financial goals.

    AI offers affordability, automation, and powerful data analysis. Traditional advisors provide experience, emotional support, and personalized planning.

    For many investors in 2026, the most effective solution may be a combination of both approaches.

    If you want a deeper understanding of how artificial intelligence is transforming investing and wealth management, explore our
    AI Investing Guide 2026.

    Trusted Financial Resources

    📩 Join Our Free Investing Newsletter

    Get AI investing insights, portfolio-building strategies, retirement planning tips, and wealth-building ideas delivered directly to your inbox.


    Subscribe today and stay informed about the future of investing.


    👨‍💼 About the Author

    Subhash Rukade writes about AI investing, personal finance, retirement planning, dividend investing, and wealth-building strategies. His mission is to help readers make smarter financial decisions through practical and easy-to-understand financial education.


    🚀 The best financial strategy is not choosing between AI and human advice. It’s using the right tools to reach your goals with confidence.

  • AI Budget Coaches vs Human Financial Advisors: Complete 2026 Guide

    AI Budget Coaches vs Human Financial Advisors: Complete 2026 Guide


    AI Budget Coaches vs Human Financial Advisors: Complete 2026 Guide

    Author: Subhash Rukade

    Published: June 15, 2026

    AI Budget Coaches

    Why Americans Are Comparing AI Budget Coaches and Human Financial Advisors

    Managing money has never been more complicated.

    Americans are dealing with rising living costs, inflation concerns, growing debt levels, and increasingly complex investment choices.

    As a result, many people are searching for better ways to manage their finances without spending thousands of dollars on professional financial services.

    This is where AI Budget Coaches are gaining attention.

    Modern artificial intelligence platforms can analyze spending habits, create budgets, track savings goals, monitor subscriptions, and provide personalized financial recommendations within seconds.

    At the same time, traditional Human Financial Advisors continue helping clients with retirement planning, investment strategies, tax planning, and long-term wealth management.

    The big question facing investors in 2026 is simple:

    Should you trust an AI Budget Coach or work with a Human Financial Advisor?

    The answer depends on your financial goals, budget, and level of complexity.

    For many Americans, AI tools provide an affordable and convenient solution for everyday budgeting and money management.

    Meanwhile, Human Financial Advisors often offer deeper expertise for retirement planning, estate planning, tax strategies, and major life decisions.

    Interestingly, the future may not be about choosing one over the other.

    Instead, many experts believe AI and human advisors will work together to create better financial outcomes.

    This trend is already visible across investing and wealth management.

    Readers interested in understanding how artificial intelligence is reshaping the entire financial industry should also explore our
    AI Investing Guide 2026.

    Throughout this guide, we’ll compare AI Budget Coaches and Human Financial Advisors across budgeting, investing, cost, convenience, accuracy, and long-term financial planning.

    You’ll also discover real-world examples, common mistakes, future trends, and practical strategies to help determine which option best fits your financial needs.

    Understanding AI Budget Coaches in 2026

    The popularity of AI Budget Coaches has exploded across the United States in recent years.

    Millions of Americans now use artificial intelligence to manage daily finances, track spending, build budgets, and improve saving habits.

    Unlike traditional financial planning services, AI Budget Coaches provide instant recommendations based on real-time financial data.

    They are available 24 hours a day, cost significantly less than many professional advisors, and can help consumers make smarter financial decisions consistently.

    But what exactly are AI Budget Coaches, and how do they work?

    What Are AI Budget Coaches?

    AI Budget Coaches are software platforms that use artificial intelligence and machine learning to analyze financial behavior.

    These tools connect to bank accounts, credit cards, savings accounts, and investment accounts to provide personalized financial guidance.

    Instead of manually reviewing transactions, users receive automatic insights about spending patterns, budgeting opportunities, and savings goals.

    Many modern AI Budget Coaches function like digital money managers.

    They continuously monitor financial activity and provide recommendations designed to improve financial health.

    How AI Budget Coaches Analyze Spending

    One of the most powerful features of AI Budget Coaches is spending analysis.

    Artificial intelligence reviews transaction history and automatically categorizes purchases into groups such as:

    • Housing
    • Transportation
    • Food and Dining
    • Entertainment
    • Subscriptions
    • Healthcare
    • Shopping

    This allows consumers to quickly identify areas where money may be leaking unnecessarily.

    Many people are surprised when AI reveals how much they spend on dining out, subscriptions, or impulse purchases.

    Personalized Savings Recommendations

    Beyond tracking expenses, AI Budget Coaches actively suggest ways to save money.

    For example, the system may recommend:

    • Reducing unnecessary subscriptions
    • Creating automated savings plans
    • Paying down high-interest debt
    • Improving emergency fund contributions
    • Adjusting spending habits

    Because recommendations are based on individual financial behavior, they often feel more relevant than generic budgeting advice.

    Debt Tracking and Financial Monitoring

    Debt management is another area where AI Budget Coaches excel.

    Many platforms monitor outstanding balances, payment due dates, and interest rates.

    Users receive alerts that help prevent late payments and reduce financial stress.

    Some AI systems also recommend debt repayment strategies designed to lower interest costs over time.

    Benefits of AI Budget Coaches

    There are several reasons Americans are increasingly choosing AI Budget Coaches:

    • Lower cost compared to many financial advisors
    • 24/7 availability
    • Instant financial insights
    • Automated budgeting
    • Real-time spending analysis
    • Personalized recommendations
    • Convenient mobile access

    For individuals focused on improving everyday money management, AI Budget Coaches can be extremely effective.

    Consumers looking for additional AI-driven financial strategies should also explore our
    AI Personal Finance 2026
    guide.

    Limitations of AI Budget Coaches

    While AI Budget Coaches offer many advantages, they are not perfect.

    Artificial intelligence can analyze data and identify patterns, but it may struggle with complex personal situations.

    Major life decisions involving retirement, inheritance planning, tax optimization, or business ownership often require human expertise.

    This is one reason Human Financial Advisors continue to play an important role in the financial industry.

    In the next section, we’ll examine the strengths and weaknesses of Human Financial Advisors and compare them directly with AI Budget Coaches.

    Human Financial Advisors: Strengths and Weaknesses

    While AI Budget Coaches continue gaining popularity, Human Financial Advisors remain a critical part of the financial industry.

    Many Americans still prefer working with experienced professionals when making important financial decisions.

    Unlike artificial intelligence, human advisors can understand emotions, personal circumstances, family goals, and complex life situations that may not fit neatly into a data model.

    This human element remains one of the biggest advantages of traditional financial planning.

    Personalized Financial Planning

    One of the greatest strengths of Human Financial Advisors is personalization.

    Every investor has unique goals, risk tolerance, income levels, and family responsibilities.

    A professional advisor can create a customized financial strategy based on those factors.

    This often includes retirement planning, investment management, debt reduction strategies, education funding, insurance planning, and long-term wealth building.

    Retirement Planning Expertise

    Retirement planning remains one of the most important financial decisions Americans face.

    Human advisors help clients evaluate retirement accounts, contribution strategies, withdrawal plans, Social Security considerations, and income needs.

    Because retirement planning involves many moving parts, professional guidance can provide valuable clarity.

    Tax Planning Opportunities

    Taxes can significantly affect investment returns.

    Human Financial Advisors often work alongside tax professionals to help clients improve tax efficiency.

    This may include:

    • Tax-loss harvesting
    • Retirement account optimization
    • Capital gains planning
    • Income management strategies
    • Tax-efficient investment allocation

    Most AI Budget Coaches currently provide limited support in these advanced areas.

    Estate Planning and Legacy Goals

    Estate planning is another area where human expertise remains extremely valuable.

    Families often need guidance regarding wills, trusts, inheritance planning, charitable giving, and wealth transfer strategies.

    These topics involve legal, emotional, and financial considerations that typically require professional advice.

    AI Budget Coaches vs Human Financial Advisors

    FeatureAI Budget CoachesHuman Financial Advisors
    CostLowHigher
    Availability24/7Appointment Based
    Budget TrackingExcellentLimited
    Spending AnalysisExcellentModerate
    Retirement PlanningBasicExcellent
    Tax PlanningLimitedExcellent
    Estate PlanningLimitedExcellent
    Emotional GuidanceNoneStrong

    Which Option Is Better?

    The answer depends on individual financial needs.

    For budgeting, spending control, and day-to-day money management, AI Budget Coaches often provide excellent value at a low cost.

    For retirement planning, tax strategies, estate planning, and major financial decisions, Human Financial Advisors still offer advantages that technology cannot fully replace.

    Many investors choose a hybrid approach that combines both options.

    AI handles budgeting and financial monitoring, while human advisors provide strategic guidance for long-term wealth building.

    Consumers interested in optimizing rewards and spending should also review our
    Best Credit Cards 2026
    guide.

    📘 Recommended Reading:

    The Psychology of Money by Morgan Housel

    As technology evolves, the line between AI Budget Coaches and Human Financial Advisors will likely become increasingly blurred.

    In the next section, we’ll compare both approaches using a real-world case study involving two investors pursuing similar financial goals.

    Real-World Case Study: AI Budget Coach vs Human Financial Advisor

    The debate between AI Budget Coaches and Human Financial Advisors becomes much easier to understand when we examine a real-world example.

    Both options can improve financial outcomes, but they often achieve results in different ways.

    Let’s compare two investors with similar incomes, financial goals, and starting conditions.

    Their objective was straightforward:

    • Reduce unnecessary spending
    • Increase monthly savings
    • Build a stronger investment portfolio
    • Improve long-term financial security

    Both investors earned approximately $85,000 annually and wanted to improve their overall financial situation.

    AI Budget Coaches Case Study 2026

    Investor A: Using an AI Budget Coach

    Investor A used an AI Budget Coach connected to checking accounts, credit cards, and savings accounts.

    The platform analyzed spending behavior and quickly identified several financial leaks.

    • Unused subscriptions
    • Excessive dining expenses
    • Frequent impulse purchases
    • High-interest credit card balances

    The AI generated recommendations and automated monthly savings transfers.

    Within six months, Investor A significantly improved spending discipline and increased monthly savings.

    Investor B: Working With a Human Financial Advisor

    Investor B hired a Human Financial Advisor.

    Instead of focusing primarily on spending behavior, the advisor developed a comprehensive financial plan.

    This included:

    • Retirement planning
    • Tax optimization strategies
    • Investment allocation guidance
    • Emergency fund planning
    • Long-term wealth-building goals

    The advisor provided ongoing accountability and personalized recommendations tailored to Investor B’s circumstances.

    📊 Six-Month Financial Improvement Comparison

    • AI Budget Coach Monthly Savings Increase: $320
    • Human Advisor Monthly Savings Increase: $280
    • AI Budget Coach Cost: Low
    • Human Advisor Cost: Higher
    • Investment Discipline Improvement: Strong for Both
    • Long-Term Planning Support: Stronger with Human Advisor

    What We Learned

    The results were surprisingly similar.

    The AI Budget Coach excelled at identifying spending leaks, automating savings, and improving daily money management.

    The Human Financial Advisor provided deeper strategic planning and helped address more complex financial issues.

    Neither approach was clearly superior in every category.

    Instead, each delivered different strengths.

    📈 Case Study Summary

    • Investor A: AI Budget Coach
    • Investor B: Human Financial Advisor
    • Analysis Period: 6 Months
    • Monthly Savings Improvement: Both Positive
    • Best for Budgeting: AI Budget Coach
    • Best for Complex Planning: Human Advisor
    • Best Overall Solution: Combining Both

    The Hybrid Approach Is Growing

    Many Americans are no longer choosing between AI Budget Coaches and Human Financial Advisors.

    Instead, they are combining both.

    AI handles budgeting, spending analysis, savings automation, and financial monitoring.

    Meanwhile, Human Financial Advisors provide guidance on retirement planning, taxes, estate planning, and long-term investment strategies.

    This hybrid model often delivers the best of both worlds.

    As artificial intelligence continues advancing, more investors are expected to adopt this combined approach to achieve stronger financial outcomes.

    Common Mistakes People Make When Using AI Budget Coaches and Human Financial Advisors

    Both AI Budget Coaches and Human Financial Advisors can improve financial outcomes.

    However, many investors fail to achieve their goals because they make avoidable mistakes.

    Technology and professional advice are valuable tools, but neither can replace good financial habits and consistent decision-making.

    Understanding these common mistakes can help investors get more value from both AI and human guidance.

    1. Blindly Trusting AI Recommendations

    One of the biggest mistakes people make is assuming artificial intelligence is always correct.

    AI Budget Coaches analyze historical data and spending patterns, but they do not fully understand personal circumstances.

    For example, an AI system may recommend reducing certain expenses without recognizing a temporary life event or unique family situation.

    Consumers should treat AI recommendations as guidance rather than automatic instructions.

    Human judgment remains important.

    2. Ignoring Professional Advice Completely

    Some investors assume AI can replace every aspect of financial planning.

    While AI Budget Coaches excel at budgeting, spending analysis, and savings automation, they may not provide the same level of expertise for complex financial decisions.

    Retirement planning, tax strategies, estate planning, and business finances often benefit from professional guidance.

    Ignoring expert advice can create costly mistakes later.

    3. Having Unrealistic Expectations

    Many consumers expect immediate financial transformation.

    Unfortunately, neither AI Budget Coaches nor Human Financial Advisors can create wealth overnight.

    Financial success requires consistent effort, disciplined spending, and long-term planning.

    The best results usually come from small improvements repeated over time.

    4. Poor Budgeting Habits

    Even the most advanced financial tools cannot help someone who ignores their budget completely.

    Many households continue overspending despite receiving alerts and recommendations.

    Successful budgeting requires regular monitoring and a willingness to adjust spending behavior.

    AI Budget Coaches can provide insights, but users must take action.

    5. Emotional Investing Decisions

    Fear and greed remain two of the biggest threats to long-term investing success.

    Many investors make emotional decisions during market volatility.

    They buy when prices are high and sell when prices fall.

    Human Financial Advisors often help clients stay disciplined during uncertain periods.

    AI systems can also reduce emotional decision-making by focusing on objective financial data.

    6. Failing to Review Financial Progress

    Some people set financial goals and then rarely review them.

    Regular reviews are essential for measuring progress and identifying opportunities for improvement.

    Both AI Budget Coaches and Human Financial Advisors perform best when financial plans are updated periodically.

    Example of a Costly Mistake

    Imagine an investor who saves an additional $250 per month after using an AI Budget Coach.

    Instead of investing those savings, the investor gradually increases discretionary spending.

    After one year:

    • Potential Savings = $3,000
    • Potential Investment Growth = Lost
    • Financial Progress = Limited

    This example highlights why behavior matters just as much as financial tools.

    Investors who want to build stronger long-term habits should review our
    SIP Investing Guide 2026.

    Additionally, households preparing for uncertain economic conditions may benefit from our
    Recession-Proof Investing 2026
    guide.

    The most successful investors understand that AI Budget Coaches and Human Financial Advisors are tools.

    Ultimately, long-term success depends on consistent action, disciplined financial habits, and a commitment to ongoing improvement.

    Practical Strategies for Investors: Using AI Budget Coaches and Human Advisors Together

    The most successful investors in 2026 are not choosing between AI Budget Coaches and Human Financial Advisors.

    Instead, they are combining both approaches to create a more complete financial strategy.

    Artificial intelligence handles daily money management, while human advisors provide guidance for major financial decisions.

    This combination often delivers stronger results than relying on either option alone.

    1. Automate Your Budget with AI

    One of the biggest advantages of AI Budget Coaches is automation.

    AI systems can categorize transactions, monitor spending, track subscriptions, and identify savings opportunities automatically.

    Instead of manually updating spreadsheets, investors receive real-time financial insights.

    This saves time while improving financial awareness.

    2. Use Human Advisors for Major Decisions

    While AI excels at budgeting, Human Financial Advisors provide valuable expertise for complex financial situations.

    Major decisions involving retirement planning, tax optimization, estate planning, insurance coverage, and investment allocation often benefit from professional guidance.

    This is especially important as wealth grows and financial situations become more complicated.

    3. Build Consistent Saving Habits

    Financial success begins with saving consistently.

    Many AI Budget Coaches automatically identify opportunities to increase savings without significantly affecting lifestyle choices.

    For example, AI may recommend reducing unnecessary subscriptions, limiting impulse purchases, or optimizing recurring expenses.

    Small monthly improvements often create substantial long-term results.

    4. Turn Savings Into Investments

    Saving money is important, but investing helps those savings grow.

    Many investors use the extra cash generated by AI Budget Coaches to build dividend portfolios and long-term investment accounts.

    If you’re interested in creating passive income, explore our
    How to Build a Dividend Portfolio
    guide.

    You can also review our
    Top Dividend Stocks USA 2026
    article for investment ideas.

    5. Review Financial Goals Regularly

    Financial goals change over time.

    Income increases, expenses shift, and life events create new priorities.

    Regular reviews help ensure that both AI recommendations and advisor strategies remain aligned with long-term objectives.

    Investors who review their finances quarterly often make better decisions than those who rarely evaluate progress.

    💰 Annual Savings Calculator Example

    Assume an AI Budget Coach identifies:

    • Subscription Savings = $50/month
    • Dining Savings = $75/month
    • Shopping Savings = $50/month
    • Fee Reduction = $25/month

    Total Monthly Savings = $200

    Annual Savings = $200 × 12 = $2,400

    If invested instead of spent, that money can become a meaningful contributor to long-term wealth creation.

    Recommended Financial Resources

    📘

    Atomic Habits by James Clear

    📘

    The Psychology of Money by Morgan Housel

    💰

    Rocket Money Budgeting Platform

    The strongest financial strategy is often a balanced one.

    By combining AI Budget Coaches with professional financial guidance, investors can improve budgeting, strengthen saving habits, and build wealth more efficiently over time.

    Future of AI Financial Guidance (2026–2030)

    The future of AI Budget Coaches is evolving rapidly.

    What started as simple budgeting software is becoming a sophisticated financial guidance system capable of helping consumers save, invest, and manage money more effectively.

    Between 2026 and 2030, experts expect artificial intelligence to play an even larger role in personal finance.

    For many Americans, AI may become a daily financial assistant that helps optimize spending, improve savings, and support long-term wealth building.

    AI Financial Assistants Will Become More Powerful

    Today’s AI Budget Coaches primarily focus on budgeting and spending analysis.

    Future AI systems will likely manage a much wider range of financial activities.

    These may include:

    • Budget planning
    • Investment monitoring
    • Retirement forecasting
    • Debt management
    • Tax planning assistance
    • Subscription optimization
    • Savings automation

    As artificial intelligence becomes more advanced, consumers will receive increasingly personalized recommendations.

    Hybrid Advisory Models Will Dominate

    Rather than replacing Human Financial Advisors, AI Budget Coaches are expected to work alongside them.

    This hybrid model combines the strengths of technology and human expertise.

    AI handles data analysis, budgeting, and financial monitoring.

    Human advisors provide emotional guidance, strategic planning, and support for complex financial decisions.

    Many industry experts believe this combination will become the standard approach for wealth management.

    Hyper-Personalized Financial Planning

    One of the biggest advantages of future AI systems will be personalization.

    Instead of generic financial advice, AI Budget Coaches will analyze spending habits, investment goals, risk tolerance, and lifestyle preferences to create highly customized recommendations.

    This level of personalization could dramatically improve financial outcomes.

    Consumers may receive real-time suggestions that help prevent financial mistakes before they occur.

    Greater Accessibility for Everyday Investors

    Traditional financial planning services can be expensive.

    AI Budget Coaches make financial guidance available to a much larger audience.

    As technology improves, more Americans will gain access to sophisticated financial tools that were previously available only to high-net-worth investors.

    This trend may help reduce financial inequality and improve overall financial literacy.

    Frequently Asked Questions

    1. What are AI Budget Coaches?

    AI Budget Coaches are financial software platforms that use artificial intelligence to analyze spending, create budgets, track savings goals, and provide personalized money-management recommendations.

    2. Are AI Budget Coaches better than Human Financial Advisors?

    Not necessarily. AI Budget Coaches excel at budgeting and spending analysis, while Human Financial Advisors provide deeper expertise for retirement planning, taxes, and complex financial situations.

    3. Can AI Budget Coaches help investors?

    Yes. Many investors use AI Budget Coaches to improve cash flow, increase savings, reduce expenses, and identify money that can be redirected toward investments.

    4. Are AI Budget Coaches expensive?

    Most AI budgeting platforms are significantly less expensive than traditional advisory services, making them accessible to a wider audience.

    5. Should I choose AI or a Human Financial Advisor?

    The best choice depends on your needs. Many investors benefit from combining AI Budget Coaches with professional financial advice.

    6. What is the future of AI financial planning?

    Future AI systems are expected to become more personalized, proactive, and integrated with banking, investing, and retirement planning services.

    Conclusion

    The debate between AI Budget Coaches and Human Financial Advisors is not about choosing a winner.

    Both options offer valuable benefits, and each serves different financial needs.

    AI Budget Coaches provide affordable budgeting assistance, spending analysis, and savings optimization.

    Human Financial Advisors deliver personalized guidance, retirement planning, tax strategies, and support for complex financial decisions.

    For many Americans, the most effective solution is a combination of both.

    Technology handles everyday money management, while human expertise supports long-term financial planning.

    To learn more about how artificial intelligence is transforming investing and personal finance, explore our
    AI Investing Guide 2026.

    For additional financial education and consumer resources, visit:

    📩 Join Our Free Finance Newsletter

    Get AI investing insights, budgeting strategies, money-saving tips, and wealth-building ideas delivered directly to your inbox.


    Subscribe today and stay ahead of the future of personal finance.


    👨‍💼 About the Author

    Subhash Rukade writes about AI, investing, personal finance, budgeting, and wealth-building strategies. His goal is to help readers make smarter financial decisions and build lasting financial security through practical, easy-to-understand financial education.


    🚀 Better budgeting today can create a stronger financial future tomorrow.

  • AI Credit Score Tools: Best 2026 Guide to Credit Improvement

    AI Credit Score Tools: Best 2026 Guide to Credit Improvement


    AI-Powered Credit Score Improvement Tools: Best 2026 Guide

    Author. Subhash Rukade

    Published: June 13, 2026

    AI Credit Score Tools

    AI-Powered Credit Score Improvement Tools: Why They Matter in 2026

    Your credit score affects more than just loan approvals. It influences mortgage rates, car financing costs, credit card offers, insurance premiums, and sometimes even employment opportunities.

    AI Credit Score Tools are helping Americans improve credit health, track credit reports, and make smarter financial decisions in 2026.

    In 2026, maintaining a strong credit score has become more important than ever for Americans who want financial flexibility and long-term wealth-building opportunities.

    Traditionally, improving a credit score required manually tracking payments, reviewing credit reports, monitoring debt balances, and understanding complex credit-scoring rules.

    Today, artificial intelligence is making that process significantly easier.

    AI-Powered Credit Score Improvement Tools are transforming the way consumers manage their financial health. These intelligent platforms analyze spending habits, monitor credit activity, identify risks, and provide personalized recommendations designed to help users improve their scores faster.

    Instead of guessing what actions might increase a credit score, consumers can now receive data-driven insights tailored specifically to their financial situation.

    For example, AI tools can notify users when credit utilization becomes too high, recommend the best time to pay down balances, identify errors on credit reports, and even predict how certain financial decisions may affect future scores.

    These capabilities help consumers make smarter financial choices while avoiding costly mistakes.

    Many of the same technologies improving credit management are also transforming investing and wealth-building strategies. Readers interested in the broader impact of artificial intelligence on personal finance should explore our
    AI Investing & Personal Finance Guide 2026.

    One reason AI Credit Score Tools have gained popularity is their ability to simplify complex financial information. Instead of reviewing hundreds of data points manually, users receive clear recommendations that are easy to understand and act upon.

    As competition among lenders continues increasing, maintaining a strong credit profile can unlock lower borrowing costs and create more opportunities to build wealth.

    In this guide, you’ll discover how AI-Powered Credit Score Improvement Tools work, the technologies behind them, practical strategies for improving your score, common mistakes to avoid, and future trends shaping credit management in America.

    How AI Credit Score Tools Work

    Modern AI-Powered Credit Score Improvement Tools do much more than simply display a credit score. These platforms continuously analyze financial data and provide personalized recommendations that help consumers make smarter decisions.

    Instead of manually reviewing credit reports and financial statements, users can rely on artificial intelligence to identify opportunities for Credit Score Improvement.

    The goal is simple: help consumers build stronger credit profiles while reducing financial mistakes.

    Credit Monitoring in Real Time

    One of the most valuable features of AI Credit Score Tools is real-time credit monitoring.

    AI systems continuously track changes across credit reports. If a new account appears, a hard inquiry is added, or a balance changes significantly, users receive immediate alerts.

    This helps consumers identify potential issues before they negatively affect their credit scores.

    Early detection is especially important when dealing with identity theft or reporting errors.

    Spending Pattern Analysis

    Artificial intelligence can analyze spending behavior and identify patterns that may impact credit health.

    For example, AI tools can detect when credit card balances are increasing too quickly or when spending habits may cause credit utilization ratios to rise above recommended levels.

    Since credit utilization plays a major role in most scoring models, these insights can be extremely valuable.

    Debt Tracking and Optimization

    Many consumers struggle to decide which debts should be paid first.

    AI-powered systems evaluate balances, interest rates, payment histories, and credit utilization levels to suggest the most effective repayment strategies.

    Some tools even estimate how specific debt payments may influence future credit scores.

    Smart Payment Reminders

    Payment history remains one of the most important factors in credit scoring.

    Missing even a single payment can significantly impact a score.

    AI systems help reduce this risk by sending personalized reminders before due dates and identifying accounts that may require immediate attention.

    These automated alerts help consumers maintain positive payment histories and avoid costly penalties.

    Personalized Recommendations

    Unlike traditional financial apps, AI Credit Score Tools provide recommendations tailored to individual financial situations.

    The system may suggest reducing utilization on a specific card, disputing a reporting error, paying down a balance before a statement closing date, or avoiding unnecessary credit applications.

    Because these recommendations are based on personal financial data, they are often far more effective than generic advice.

    Consumers interested in broader AI-driven financial strategies should also explore our
    AI Personal Finance Guide 2026.

    By combining credit monitoring, spending analysis, debt management, and personalized coaching, AI-Powered Credit Score Improvement Tools are helping Americans take greater control of their financial future.

    AI Technologies Behind Credit Score Improvement

    The success of modern AI-Powered Credit Score Improvement Tools comes from advanced technologies that analyze financial behavior, identify risks, and provide highly personalized recommendations.

    Unlike traditional credit monitoring services that mainly report information, AI actively helps consumers make better financial decisions.

    These technologies work together to support faster and smarter Credit Score Improvement.

    Machine Learning Learns Your Financial Habits

    Machine learning is the foundation of most AI Credit Score Tools.

    The technology studies spending patterns, payment history, credit utilization, account balances, and borrowing behavior.

    Over time, the system learns how users manage credit and identifies behaviors that may positively or negatively affect future scores.

    Because machine learning continuously updates itself, recommendations become more accurate as additional financial data becomes available.

    Predictive Analytics Forecasts Future Scores

    One of the most powerful features of AI is predictive analytics.

    Instead of only showing current credit scores, AI systems estimate how future actions may influence credit performance.

    For example, an AI platform might predict how paying off a credit card balance, reducing utilization, or avoiding new credit inquiries could impact a score over the next several months.

    This forward-looking approach helps consumers make more informed financial decisions.

    Behavioral Analysis Identifies Hidden Risks

    AI also uses behavioral analysis to evaluate financial habits.

    The system can identify recurring behaviors that may hurt credit health, such as consistently carrying high balances or making payments close to due dates.

    By recognizing these patterns early, AI tools can recommend corrective actions before significant damage occurs.

    Personalized Financial Recommendations

    Every consumer has a unique financial situation.

    This is why AI-Powered Credit Score Improvement Tools generate personalized recommendations rather than offering generic advice.

    The system evaluates individual credit profiles and suggests actions based on each user’s specific goals and challenges.

    These tailored recommendations often produce better results than one-size-fits-all financial guidance.

    Credit Risk Assessment

    AI systems continuously assess credit risk by analyzing multiple factors simultaneously.

    This helps consumers understand which financial behaviors are helping their scores and which actions may increase risk.

    The result is a clearer path toward long-term financial stability.

    Traditional Credit Monitoring vs AI Credit Score Tools

    FeatureTraditional MonitoringAI Credit Score Tools
    Credit TrackingBasic UpdatesReal-Time Monitoring
    RecommendationsGeneric AdvicePersonalized Guidance
    Future Score ForecastsNoYes
    Risk DetectionLimitedAdvanced Analysis
    AutomationLowHigh

    Consumers seeking better borrowing opportunities should also review our
    Best Credit Cards 2026
    guide to find products that support responsible credit building.

    These advanced technologies explain why AI Credit Score Tools are becoming an essential part of modern personal finance management.

    Real-World Example of AI Improving a Credit Score

    To understand how AI-Powered Credit Score Improvement Tools work in practice, let’s look at a realistic example.

    Meet Sarah, a 32-year-old marketing professional from Texas. She had a credit score of 645 and wanted to improve it before applying for a mortgage.

    Like many Americans, Sarah paid her bills regularly but struggled with high credit card balances and inconsistent budgeting habits.

    Although she knew her credit score needed improvement, she wasn’t sure which actions would have the greatest impact.

    AI Credit Score Improvement Example

    Step 1: Connecting Financial Accounts

    Sarah connected her credit cards, bank accounts, and credit monitoring service to an AI-powered credit management platform.

    Within minutes, the system analyzed payment history, utilization ratios, account age, debt balances, and recent credit activity.

    The AI identified several opportunities for immediate Credit Score Improvement.

    Step 2: Reducing Credit Utilization

    The platform discovered that Sarah was using nearly 75% of her available credit limits.

    Because credit utilization is a major factor in most credit scoring models, the AI recommended paying down specific balances first.

    Instead of spreading payments across multiple cards, the system identified the accounts that would provide the greatest score improvement.

    Step 3: Optimizing Payment Timing

    Many consumers don’t realize that when they make payments can matter almost as much as how much they pay.

    The AI suggested making payments before statement closing dates rather than waiting until due dates.

    This helped lower reported balances and improved utilization ratios appearing on credit reports.

    Step 4: Ongoing Monitoring and Alerts

    One of the biggest benefits of AI Credit Score Tools is continuous monitoring.

    Whenever Sarah’s balances increased or unusual activity appeared on her accounts, the system sent alerts and updated recommendations.

    This allowed her to maintain progress and avoid setbacks.

    Many of the same technologies helping consumers improve credit scores are also transforming investing and financial planning. Readers interested in these broader innovations should revisit our
    AI Investing & Personal Finance Guide 2026.

    After approximately twelve months of following AI recommendations, Sarah’s credit score increased from 645 to over 740.

    This improvement helped her qualify for more favorable mortgage terms and potentially save thousands of dollars over the life of her loan.

    For additional insights on building better financial habits, consider reading
    The Psychology of Money by Morgan Housel.
    The book provides valuable lessons about behavior, decision-making, and long-term financial success.

    Sarah’s experience demonstrates how AI-Powered Credit Score Improvement Tools can help consumers make smarter financial decisions and achieve meaningful results over time.

    Common Mistakes When Using AI Credit Score Tools

    While AI-Powered Credit Score Improvement Tools can provide valuable guidance, success still depends on how consumers use the information. Artificial intelligence can identify opportunities for improvement, but it cannot make financial decisions on your behalf.

    Many people expect immediate results after installing an AI credit app. However, improving a credit score usually requires consistency, patience, and responsible financial behavior.

    Understanding common mistakes can help consumers get the most value from modern AI Credit Score Tools.

    Ignoring AI Recommendations

    One of the most common mistakes is simply ignoring the recommendations generated by the platform.

    AI systems analyze financial data and identify actions that may improve credit health. If users fail to act on these recommendations, the benefits of the technology become limited.

    The best results occur when consumers actively follow personalized guidance.

    Maintaining High Credit Utilization

    Credit utilization remains one of the most important factors affecting credit scores.

    Many consumers continue carrying high balances even after AI tools identify utilization problems.

    A credit utilization ratio above 30% may negatively impact scores, while lower utilization levels generally support stronger credit profiles.

    Reducing balances remains one of the fastest paths to meaningful Credit Score Improvement.

    Missing Payments

    Even with automated reminders and alerts, some consumers still miss payment deadlines.

    Payment history plays a major role in most credit scoring models.

    A single late payment can remain on a credit report for years and may significantly reduce a score.

    Using automatic payments and AI reminders can help avoid this costly mistake.

    Applying for Too Much Credit

    Some consumers mistakenly believe opening multiple credit accounts will improve their scores quickly.

    In reality, excessive credit applications can generate multiple hard inquiries and increase perceived borrowing risk.

    AI-powered platforms often warn users when new applications could negatively affect credit health.

    Expecting Instant Results

    Perhaps the biggest mistake is expecting overnight success.

    Even the best AI-Powered Credit Score Improvement Tools cannot instantly repair years of poor financial habits.

    Building strong credit requires time, discipline, and consistent positive behavior.

    Consumers focused on protecting their finances during uncertain economic conditions should also explore our
    Recession-Proof Investing 2026
    guide.

    For additional consumer education, trusted resources such as the
    Consumer Financial Protection Bureau (CFPB)
    and the
    Federal Trade Commission (FTC)
    offer valuable information about credit management and financial protection.

    The most successful users combine AI-powered insights with responsible financial habits, creating a stronger foundation for long-term credit health and financial stability.

    Practical Tips to Improve Your Credit Score Faster

    While AI-Powered Credit Score Improvement Tools can provide valuable insights, the best results come from combining technology with smart financial habits. Consumers who consistently follow proven credit-building strategies often see the greatest long-term improvements.

    The good news is that many of these actions are simple to implement and can have a meaningful impact on credit health over time.

    Keep Credit Utilization Low

    One of the fastest ways to improve a credit score is reducing credit utilization.

    Credit utilization measures how much available credit you are currently using.

    Most financial experts recommend keeping utilization below 30%, while lower levels may provide even stronger benefits.

    Modern AI Credit Score Tools continuously monitor utilization ratios and notify users when balances become too high.

    Make Every Payment on Time

    Payment history remains one of the most important factors in credit scoring.

    Even a single missed payment can negatively affect a score.

    AI-powered financial apps help users stay organized by providing payment reminders, due-date alerts, and automated notifications.

    Consistent on-time payments create a strong credit foundation.

    Monitor Your Credit Reports

    Errors on credit reports can sometimes reduce scores unnecessarily.

    Consumers should review credit reports regularly and dispute inaccurate information when necessary.

    Many AI-Powered Credit Score Improvement Tools automatically monitor reports and notify users when significant changes occur.

    Early detection can prevent small issues from becoming larger problems.

    Use AI Alerts and Automation

    One of the biggest advantages of AI technology is automation.

    AI systems can track balances, monitor spending patterns, detect unusual activity, and provide personalized recommendations.

    These automated insights help consumers stay proactive rather than reactive.

    Build Positive Credit History

    Credit improvement is not only about avoiding mistakes.

    Building a long history of responsible credit use is equally important.

    Maintaining older accounts, managing balances responsibly, and making consistent payments can strengthen credit profiles over time.

    Manual Credit Improvement vs AI Credit Improvement

    FeatureManual ApproachAI Credit Score Tools
    Credit MonitoringPeriodic ReviewsReal-Time Alerts
    Debt AnalysisManual CalculationsAutomated Insights
    Payment TrackingSelf-MonitoringSmart Reminders
    RecommendationsGeneric AdvicePersonalized Guidance
    EfficiencyTime-ConsumingHighly Efficient

    Investors interested in strengthening their overall financial future should also explore our
    Top Dividend Stocks USA 2026
    guide for long-term wealth-building ideas.

    Another excellent personal finance resource is
    The Simple Path to Wealth by JL Collins.
    The book offers practical lessons on investing, financial independence, and long-term money management.

    When combined with responsible financial habits, AI-Powered Credit Score Improvement Tools can help consumers make smarter decisions and achieve stronger credit profiles over time.

    Future of AI Credit Score Improvement

    The future of AI-Powered Credit Score Improvement Tools looks incredibly promising. As artificial intelligence continues evolving, consumers will gain access to smarter financial insights, faster recommendations, and more personalized credit-building strategies.

    Instead of simply monitoring credit reports, future AI platforms will act like digital financial coaches that help users make better decisions every day.

    Predictive Credit Coaching

    One of the biggest trends expected in the coming years is predictive credit coaching.

    AI systems will not only analyze current credit data but also forecast future score changes based on financial behavior.

    Consumers will receive personalized guidance before problems occur, helping them avoid actions that may negatively impact their credit profiles.

    AI Financial Assistants

    Many experts believe AI assistants will become a standard part of personal finance management.

    These assistants may automatically track spending, monitor debt levels, recommend payment strategies, and help consumers improve financial habits.

    This level of automation could make credit management easier than ever before.

    Open Banking and Personalized Credit Strategies

    As open banking expands across the financial industry, AI tools will gain access to richer financial data.

    This will allow platforms to generate highly personalized recommendations tailored to each consumer’s goals, income, debt profile, and spending patterns.

    The result will be more effective and accurate credit improvement strategies.

    Frequently Asked Questions

    1. Do AI Credit Score Tools really work?

    Yes. Many AI-powered platforms help consumers identify opportunities to improve payment history, lower utilization, and manage debt more effectively.

    2. Can AI increase my credit score instantly?

    No. Credit improvement takes time. AI provides guidance, but long-term results depend on consistent financial habits.

    3. Are AI Credit Score Tools safe?

    Most reputable platforms use strong encryption and security measures to protect financial data.

    4. What is the biggest benefit of AI-powered credit monitoring?

    The biggest advantage is personalized recommendations based on individual financial behavior.

    5. Can AI help detect errors on credit reports?

    Yes. Many tools monitor credit reports and alert users when unusual changes or potential errors appear.

    6. Who should use AI-Powered Credit Score Improvement Tools?

    Anyone looking to improve credit health, qualify for better loan terms, or strengthen their overall financial profile can benefit.

    Conclusion

    Strong credit remains one of the most valuable financial assets Americans can build. Better credit scores often lead to lower borrowing costs, improved financial opportunities, and greater long-term wealth-building potential.

    By combining technology, automation, and personalized insights, AI-Powered Credit Score Improvement Tools are helping consumers make smarter financial decisions and improve credit health more efficiently than ever before.

    To learn more about how artificial intelligence is transforming investing, wealth building, and personal finance, revisit our
    AI Investing & Personal Finance Guide 2026.

    Investors focused on long-term financial growth should also explore our
    How to Build a Dividend Portfolio
    guide.

    📩 Join Our Free Finance Newsletter

    Get AI finance insights, credit-building strategies, investing tips, and wealth-building ideas delivered directly to your inbox.

    Subscribe today and take control of your financial future!

    📘 Recommended Reading:

    I Will Teach You To Be Rich by Ramit Sethi


    About the Author

    Subhash Rukade writes about AI, investing, credit management, and personal finance to help readers make smarter money decisions and build long-term wealth.

    🚀 Thank you for reading. Build stronger credit, make smarter financial decisions, and create a brighter financial future!