Tag: Emergency Fund

  • Who Should Not Buy Treasury Bills? A 2026 Guide

    Who Should Not Buy Treasury Bills? A 2026 Guide

    Who Should Not Buy Treasury Bills?

    Subhash Rukade
    Founder, FinanceInvestment


    Published: Sep 28, 2026


    Updated: Sep 28, 2026


    Reading Time: 10–12 min


    Who Should Not Buy Treasury Bills?

    Who Should Not Buy Treasury Bills?Who should not buy Treasury bills? In many cases, it is the person who needs immediate access to cash, cannot match the investment to a fixed timeline, or is using short-term money for a long-term goal. T-bills can be useful, but the maturity date matters.

    A family building an emergency fund may need more flexibility. A retiree may need cash available for an unexpected bill. A long-term investor may also have little reason to put growth-focused money into a short-term Treasury security. The issue is not simply whether T-bills are safe. It is whether they fit the job your money needs to perform.

    If you are new to Treasury securities, our Treasury Bills Explained guide covers the basics. This article takes the next step by showing when buying T-bills may create an unnecessary limitation or mismatch.

    What You’ll Learn

    • When a Treasury bill maturity may not match your cash needs.
    • Why emergency savings and everyday spending money need flexibility.
    • How early selling, reinvestment, inflation, and tax considerations can affect T-bill decisions.
    • When savings accounts, money market accounts, or CDs may be worth comparing.
    • Common mistakes people make when choosing short-term Treasury investments.

    Quick Answer: When Should You Avoid Treasury Bills?

    Treasury bills may not fit investors who need their money on demand, cannot comfortably wait until a chosen maturity date, or are using the funds for a long-term objective. They can also be a poor match when an upcoming expense has an uncertain date.

    KEY TAKEAWAYS

    • Money needed for emergencies may require easier access than a T-bill provides.
    • A maturity date can become inconvenient when your spending timeline changes.
    • Selling before maturity can result in a market price different from your purchase price.
    • Short-term Treasury securities are not a substitute for a diversified long-term portfolio.
    • After maturity, reinvestment may involve different rates and terms.
    • Taxes, liquidity, and opportunity cost should be considered before buying.

    Bottom line: A T-bill can be useful for the right purpose, but the wrong maturity can make even a conservative investment inconvenient. Start with the job of the money, then decide whether a Treasury bill fits.

    Who Should Not Buy Treasury Bills? at a Glance

    Treasury bills can be useful for certain short-term goals, but they may not suit every cash need. The clearest warning sign is a mismatch between your financial timeline and the fixed maturity of the bill.

    Investor SituationWhy a T-Bill May Not FitWhat to Check
    Needs immediate accessThe money may be needed before the bill reaches maturity.Keep emergency and everyday cash readily accessible.
    Has an uncertain expense dateA fixed maturity may not line up with when the expense actually occurs.Consider whether a flexible account would work better.
    Needs long-term growthA short-term Treasury security may not serve a long investment horizon.Review whether the portfolio needs growth-oriented assets.
    May need to sell earlyThe market price before maturity can differ from the original purchase price.Consider whether you can reasonably hold until maturity.
    QUICK TAKE

    A Treasury bill may be the wrong tool when flexibility matters more than a defined maturity. Start with the purpose of the money, then decide whether a T-bill fits that timeline.

    Complete Beginner Guide: When Treasury Bills May Not Fit
    Who Should Not Buy Treasury Bills?For a beginner, the first step is not choosing a Treasury bill. It is deciding whether the money can reasonably stay invested for a set period. Start with the purpose of the cash, the date you may need it, and how much flexibility you want.

    Treasury bills have specific maturity dates. That can be helpful for planned expenses, but it can also become inconvenient if your plans change. If you need the money earlier, selling before maturity may involve a different market price than the amount you originally paid.

    Three Questions to Ask Before Buying

    1. When might I need the money? Choose a maturity only after considering the likely spending date.
    2. Can I leave the money invested? Cash that may be needed unexpectedly may require a more accessible option.
    3. What will I do at maturity? Decide whether you will spend the proceeds, keep them available, or evaluate another investment.
    BEGINNER CHECK

    Do not select a T-bill based only on its quoted return. Make sure the maturity, access to the money, and purpose of the investment fit your situation first.

    How Treasury Bills Work — And Where the Mismatch Happens

    Treasury bills are short-term U.S. Treasury securities. They are generally sold at a discount, so the purchase price is below the bill’s face value. At maturity, the investor receives the face value. The difference between the purchase price and face value generally represents the investment’s interest.

    The potential problem appears when your plans change. If you need the money before maturity, you may choose to sell the bill in the secondary market. The price at that time can be above or below what you paid, depending on market conditions. That makes an early sale different from simply holding the bill until maturity.

    Where the Fit Can Break Down

    • Cash-flow mismatch: You need the proceeds before the scheduled maturity date.
    • Access mismatch: Your money needs to remain available for unpredictable expenses.
    • Goal mismatch: The funds are intended for a much longer investment objective.
    • Reinvestment mismatch: You plan to reinvest after maturity, but future rates may be different.
    KEY IDEA

    The mechanics of a T-bill are simple. The real question is whether the investment timeline still works if your financial plans change.

    Benefits & Drawbacks of Treasury Bills

    Treasury bills can have useful features, but those features do not make them suitable for every investor. The same fixed maturity that helps with planning can become inconvenient when the timing or purpose of your money changes.

    ✓ Potential Benefits

    • Short maturities can work for certain defined cash goals.
    • T-bills are direct obligations of the U.S. Treasury.
    • Interest is generally exempt from state and local income taxes.
    • Different maturities can help investors organize future cash needs.
    ✕ Potential Drawbacks

    • The money is linked to a defined maturity date.
    • An early sale can expose you to changes in market price.
    • Future reinvestment rates can be different from today’s rates.
    • T-bills may not match a portfolio’s long-term growth objectives.
    EXPERT TIP

    Look beyond the purchase yield. Before choosing a T-bill, consider when the money is needed, how much access you require, the tax treatment, and whether the investment matches the purpose of the cash.

    T-Bills vs. Other Cash Options

    If Treasury bills do not match your cash needs, compare them with options built for different purposes. A high-yield savings account, money market account, or CD may offer a different balance of access, timing, and account features.

    OptionMay Fit WhenMain Point to Check
    Treasury BillsYou have a defined short-term timeline and can plan around maturity.Maturity date, early-sale price, taxes, and reinvestment.
    High-Yield Savings AccountYou want savings with relatively easy access to your money.Rate changes, fees, withdrawal terms, and FDIC coverage.
    Money Market AccountYou want a bank deposit account with savings features and potential transaction access.Rate, fees, transaction rules, minimum balance, and FDIC coverage.
    CDYou can leave the money deposited for a stated term.Early-withdrawal penalty, maturity date, rate, and FDIC coverage.

    For a closer look at the differences, see our guides on Treasury bills vs. CDs and Treasury bills vs. money market accounts.

    QUICK COMPARISON

    Treasury bills are U.S. government securities, while savings accounts, money market accounts, and CDs are bank deposits. Compare access, maturity, taxes, fees, and applicable FDIC coverage before choosing where to keep the money.

    Costs, Risks & Expert Tips

    Buying a Treasury bill does not automatically mean paying a traditional account fee. However, your overall result can still be affected by the purchase method, an early sale, taxes, inflation, and what happens when the bill matures.

    Costs and Risks to Watch

    • Transaction costs: Check whether your brokerage charges any applicable fee or markup for buying or selling Treasury securities.
    • Early-sale risk: A T-bill sold before maturity can have a market price above or below your original purchase price.
    • Reinvestment risk: When the bill matures, a new T-bill may carry a different rate.
    • Inflation risk: Inflation can reduce the purchasing power of the money you receive at maturity.
    • Tax consideration: Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    EXPERT TIP

    Before buying, write down the amount you can invest, the earliest date you may need the money, and your plan if that date changes. If the timeline is uncertain, compare a more flexible cash option first.

    Common Mistakes + Real-Life Example

    The biggest T-bill mistakes often happen before the order is placed. Investors may focus on the advertised return while overlooking how soon the money could be needed or what happens if their plans change.

    Common Mistakes to Avoid

    • Putting emergency cash into a T-bill: Emergency money may need to remain readily accessible.
    • Choosing a maturity without a purpose: The term should connect to an actual financial timeline.
    • Looking only at the yield: A competitive return does not solve a liquidity or timing problem.
    • Ignoring the maturity plan: Decide in advance whether the proceeds will be spent, held, or considered for reinvestment.

    A Simple Family Example

    Suppose a family has $12,000 reserved for a home repair, but the contractor has not confirmed the project date. They choose a T-bill without leaving enough flexible cash. Two months later, the repair needs to start sooner than expected. The family now has to consider selling the T-bill instead of simply using available savings.

    LESSON

    When the spending date is uncertain, flexibility can matter more than locking money into a defined maturity. Match the investment to the certainty of the goal.

    Who Should Choose Something Else?

    Treasury bills are only one way to handle short-term money. If your priority is immediate access, a bank deposit with specific account features, or a much longer investment horizon, it may make sense to compare other choices before committing the cash.

    Situations Worth Comparing

    • Emergency savings: Money that may be needed without warning generally calls for easy access. Compare the differences in our Treasury bills vs. savings accounts guide.
    • Flexible cash needs: A money market account may be worth reviewing when deposit-account access and transaction features are important.
    • Fixed bank deposit: A CD uses a stated deposit term and may be considered when you can leave the money deposited for that period. See our Treasury bills vs. CDs guide.
    • Long-term goals: Money intended for a longer horizon may need to be evaluated within a broader investment strategy rather than treated as short-term cash.
    CHOICE CHECK

    Before choosing an alternative, identify how quickly you may need the money, how long you can leave it untouched, and what account or investment features matter to you.

    Frequently Asked Questions About Who Should Not Buy Treasury Bills

    Who should not buy Treasury bills?

    Treasury bills may not fit people who need immediate access to their money, cannot comfortably wait until maturity, or are using the funds for a long-term investment objective.

    Should beginners avoid Treasury bills?

    Beginners do not automatically need to avoid them. They should first understand the maturity date, purchase price, early-sale considerations, tax treatment, and reinvestment before investing.

    Should I use Treasury bills for my emergency fund?

    Emergency savings may need quick access. Consider whether a T-bill’s maturity structure fits that need or whether a more accessible savings option is appropriate for your emergency cash.

    Can you lose money by selling a Treasury bill early?

    Yes. If you sell before maturity, the market price may be above or below your original purchase price. The result depends on market conditions when you sell.

    Are Treasury bills bad for long-term investors?

    Not necessarily. T-bills can have a role in short-term cash management, but money intended primarily for long-term growth may need to be evaluated within a broader investment strategy.

    Are Treasury bills less flexible than savings accounts?

    They work differently. A T-bill has a maturity date, while a savings account is a bank deposit account designed to provide access to deposited funds according to its account terms.

    Do Treasury bills have tax advantages?

    Treasury bill interest is generally subject to federal income tax but exempt from state and local income taxes. Individual tax circumstances can vary.

    What should I consider before buying a Treasury bill?

    Consider when you need the money, whether you can hold until maturity, the possibility of an early-sale price change, applicable taxes, your reinvestment plan, and whether another cash option fits your needs.

    Final Verdict: When Treasury Bills May Not Fit

    Treasury bills can serve a useful role in short-term financial planning, but the same maturity structure that works for one goal may be inconvenient for another. The key question is whether you can leave the money invested for the period you selected.

    If your cash is needed for emergencies, an expense date may change, or the money is intended primarily for long-term growth, compare other options before buying. Savings accounts, money market accounts, CDs, and other investments each have different features to evaluate.

    If you want to understand the broader role and mechanics of T-bills, continue with our Treasury Bills Explained guide before making a decision.

    THE BOTTOM LINE

    Start with the purpose of the money, then consider the timeline and access you need. A Treasury bill should fit those conditions rather than forcing your financial plan to fit the investment.

    Related Resources

    If you want to explore the topic further, these resources cover emergency savings, T-bill comparisons, buying, maturity planning, pricing, and official tax information.

    FinanceInvestment Guides

    Official & Educational Sources

    • TreasuryDirect — Official U.S. Treasury information about Treasury securities, auctions, purchases, and account management.
    • IRS Publication 550 — Federal tax information covering Treasury securities and investment income.
    • NerdWallet Treasury Bills Guide — Additional educational information about T-bills, purchasing, and common considerations.

    Have a Money Question? Keep Exploring.

    Money decisions become easier when you understand how each option fits your timeline and goals. Keep exploring FinanceInvestment for practical guides on saving, investing, Treasury bills, CDs, and other personal finance topics.

    📬 Stay Connected With FinanceInvestment
    Follow new money guides and practical investing topics as they are published.
    📧 Email FinanceInvestment
  • Treasury Bills for Emergency Funds in 2026: What to Know

    Treasury Bills for Emergency Funds in 2026: What to Know

    Treasury Bills for Emergency Funds

    Subhash Rukade
    Founder, FinanceInvestment

    Published: Sep 26, 2026

    Updated: Sep 26,   2026

    Reading Time: 12–14 min


    Treasury Bills for Emergency Funds: A Practical Starting Point

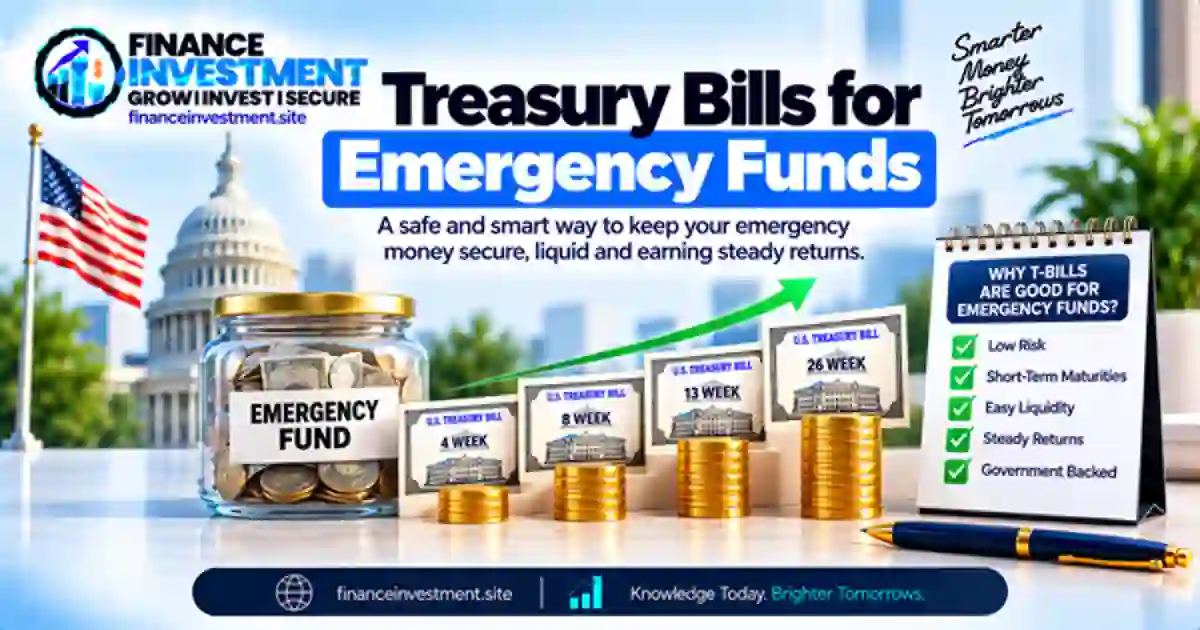
    Treasury Bills for Emergency FundsTreasury Bills for Emergency Funds can be worth considering if you want part of your short-term reserves invested in U.S. government securities. But an emergency fund has a different priority from a regular investment account: you need to be able to reach the money when an unexpected bill arrives.

    That is why liquidity matters before yield. A T-bill has a stated maturity date, while cash in a checking or savings account can generally be accessed without waiting for a security to mature. Some people may therefore keep their most immediate emergency cash in an accessible account and use shorter-term T-bills for money they may not need right away.

    If Treasury bills are new to you, our Treasury Bills Explained guide is a useful starting point. It covers what T-bills are and how they work before you decide whether they fit your emergency-fund plan.

    What You’ll Learn

    • Where T-bills can fit within an emergency-fund strategy.
    • Why immediate access can matter more than yield for emergency cash.
    • How T-bill maturities affect when invested money becomes available.
    • The potential benefits and drawbacks of using T-bills.
    • How T-bills compare with savings and money market accounts.
    • What to consider before using T-bills for unexpected expenses.

    The central question is not simply whether T-bills are safe or offer a competitive return. It is whether the maturity, access, and structure of the investment match the kind of emergency you are preparing for.

    Quick Answer: Can Treasury Bills Be Used for Emergency Funds?

    Yes, Treasury bills can be part of an emergency-fund strategy, but they may not be suitable for every portion of your reserve. Emergency money needs dependable access. Because a T-bill has a maturity date, it can require more planning than cash held in an accessible bank account. Keeping some emergency savings readily available can reduce the chance of needing to sell a T-bill at an inconvenient time.

    Key Takeaways

    • Liquidity matters: The money you may need immediately should be easy to access without relying on a security sale.
    • Maturity dates matter: A T-bill follows a defined maturity schedule, so the timing should fit your expected cash needs.
    • Shorter maturities offer more frequent planning points: They can give you more opportunities to reassess the money as bills mature.
    • You can split your emergency reserves: Some money can remain in an accessible account while another portion is allocated to short-term T-bills.
    • Early sales carry market-price risk: If you sell a marketable T-bill before maturity, the amount you receive may be different from your purchase price.
    • Future yields can change: Reinvesting after maturity does not guarantee the same yield as the original T-bill.
    • Tax treatment is different from bank interest: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.

    BOTTOM LINE: T-bills can be one component of an emergency-fund plan. The key is to match the amount and maturity of the T-bills with how quickly you may need the money, while keeping sufficient cash accessible for immediate surprises.

    Table of Contents

    Treasury Bills for Emergency Funds at a Glance

    Treasury bills can be useful for part of an emergency-fund plan, but they should be viewed differently from cash in a checking or savings account. The main issue is timing: a T-bill has a defined maturity, while an unexpected expense may arrive at any time.

    FeatureWhat It Means for an Emergency Fund
    MaturityT-bills have short-term maturities, so the maturity date should fit when you expect the money could be needed.
    AccessAccess is different from withdrawing cash from an ordinary bank account, particularly if the T-bill has not yet matured.
    FDIC insuranceT-bills are not FDIC-insured deposits. They are marketable securities issued by the U.S. Department of the Treasury.
    Before maturityA marketable T-bill can generally be sold before maturity through a broker, but its market price can change.
    Tax treatmentT-bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    Potential roleT-bills may fit a portion of emergency reserves that does not need to remain immediately accessible.

    QUICK TAKE: An emergency fund is about more than earning a return. If you use T-bills, match their maturity and access requirements with your expected cash needs. Money needed for an immediate emergency can remain in an easily accessible account, while a separate portion may be considered for short-term T-bills.

    Complete Beginner Guide to Using Treasury Bills for an Emergency Fund

    Treasury Bills for Emergency FundsA simple way to think about Treasury Bills for Emergency Funds is to divide your reserves according to when you might need the money. Cash needed for an expense tomorrow should be handled differently from money that may remain untouched for several months.
    1. Build an Accessible Cash Reserve First

    Start with money that can be accessed easily through a checking or savings account. This portion can help cover an urgent car repair, insurance deductible, unexpected household expense, or temporary gap in income without requiring you to sell an investment.

    2. Identify Money You May Not Need Immediately

    After setting aside readily accessible cash, look at the remaining emergency reserve. If some of that money is unlikely to be needed immediately, short-term Treasury bills may be one option to consider. The important point is to avoid treating the entire reserve as though it has the same access requirements.

    3. Choose a Maturity That Fits Your Timeline

    Each T-bill has a stated maturity. Before buying one, consider when the money may be needed and whether you are comfortable waiting until maturity. A shorter maturity can bring the maturity date closer, while a longer one may require a longer planning horizon.

    4. Decide What Happens When the Bill Matures

    At maturity, you can reassess the money based on your current circumstances. You might keep it available as cash, use it for an upcoming need, or consider another short-term investment. This review point can help keep your emergency reserves aligned with your changing financial situation.

    BEGINNER TIP: Build the emergency-fund structure around access rather than chasing the highest available yield. The right setup is one where you know which money is immediately available and which portion follows a T-bill maturity schedule.

    How Treasury Bills Work for Emergency Funds

    Using Treasury bills for an emergency fund involves more than buying a government security. You need to plan around the purchase amount, maturity date, account you use, and what you would do if an unexpected expense occurs before the bill matures.

    1. Decide How Much to Put Into T-Bills

    First, identify the portion of your emergency reserve that can follow a maturity schedule. Money needed for an immediate expense may be better kept in an easily accessible account. The T-bill portion should be money you are comfortable keeping invested for its selected term.

    2. Select the Maturity

    Treasury bills are short-term Treasury securities with maturities of one year or less. Different bill terms are offered through Treasury auctions. When choosing a term, consider how long you can leave that portion of your emergency reserve invested without needing it.

    3. Choose Where to Buy

    Individuals can buy Treasury bills through TreasuryDirect or through a brokerage that offers Treasury securities. The two routes differ in how securities are purchased, held, transferred, and sold, so the account you choose matters when planning for emergency access.

    For the purchase process, see our How to Buy Treasury Bills guide. You can also compare the two account options in TreasuryDirect vs. Brokerage T-Bills.

    4. Hold Until Maturity or Plan for an Early Sale

    Holding the T-bill until maturity follows the scheduled maturity process. If you need the money earlier, a marketable T-bill may be sold before maturity, but the process depends on where the security is held. With TreasuryDirect, a marketable security generally needs to be transferred to the commercial book-entry system for sale, and the amount received can be affected by market conditions.

    5. Review the Money at Maturity

    When the T-bill matures, reassess your emergency-fund needs. You may keep the proceeds accessible, use them for an upcoming expense, or consider another short-term investment. If you choose to reinvest, remember that the yield available on a new T-bill may be different from the original one.

    PRACTICAL POINT: For emergency savings, the purchase decision and the access plan should be considered together. A T-bill can provide a scheduled source of funds, but it should not be treated as identical to cash that is immediately available in a bank account.

    Benefits and Drawbacks of Using Treasury Bills for Emergency Funds

    Treasury bills can serve a purpose within a broader emergency-fund plan, particularly for reserves that do not need to remain immediately accessible. However, their advantages come with trade-offs that are important to understand before using them for unexpected expenses.

    Potential Benefits

    • U.S. government obligation: T-bills are securities issued by the U.S. Treasury and backed by the federal government’s obligation to pay according to their terms.
    • Short-term maturities: Their relatively short terms can suit money that has a defined short-term purpose.
    • State and local tax treatment: Interest from Treasury securities is generally exempt from state and local income taxes.
    • Known maturity date: The maturity date is established when the bill is issued, which can make future cash planning easier.

    Potential Drawbacks

    • Not immediate cash: A T-bill follows a security and maturity process rather than functioning like a bank-account balance.
    • Early-sale risk: If you sell before maturity, the market price may be different from the price you paid.
    • Changing future yields: If you reinvest after maturity, the new T-bill may have a different yield.
    • More administration: You need to keep track of maturities, account access, and how the proceeds will be handled.

    KEY POINT: T-bills can add a short-term government-security layer to an emergency-fund plan, but they do not eliminate the need for accessible cash. The important question is whether the maturity and access arrangements fit the type of emergency you are preparing for.

    Treasury Bills vs. Other Emergency-Fund Options

    Different emergency-fund options solve different cash-management needs. The key differences are how quickly you can access the money, whether there is a maturity date, whether the product is a bank deposit, and what happens if you need the funds earlier than planned.

    OptionAccessMaturity / WithdrawalFDIC InsurancePotential Role
    Treasury BillsDepends on maturity or an early-sale processFixed maturity; marketable bills may generally be sold before maturityNoA portion of reserves that can follow a Treasury maturity schedule
    High-Yield Savings AccountGenerally convenient accessNo fixed maturityGenerally yes, if it is a deposit at an FDIC-insured bank and within applicable limitsReadily accessible emergency cash
    Money Market Deposit AccountGenerally convenient accessNo fixed maturityGenerally yes, if it is an FDIC-insured bank deposit and within applicable limitsAccessible cash with bank-account features
    Certificate of Deposit (CD)Usually less flexible before maturityFixed term; early withdrawal may involve a penaltyGenerally yes, if it is an FDIC-insured bank CD and within applicable limitsMoney that can remain committed for a defined period

    QUICK COMPARISON: Bank savings and money market deposit accounts generally provide simpler access to emergency cash. T-bills and CDs add a defined investment term, so they require more planning when the money may be needed unexpectedly. FDIC insurance applies to eligible bank deposits, not Treasury bills.

    Costs, Risks and Expert Tips for Using T-Bills in an Emergency Fund

    Treasury bills generally have a straightforward cost structure when purchased directly through TreasuryDirect. The bigger issue for an emergency fund is often the trade-off between earning a return and keeping money readily available. Your purchase method and the timing of a potential withdrawal both matter.

    Potential Costs and Trade-Offs

    • TreasuryDirect purchase cost: The U.S. Treasury states that it does not charge a purchase fee or commission when you buy Treasury securities through TreasuryDirect.
    • Brokerage pricing: If you use a brokerage, review that firm’s current pricing and trading terms because costs and transaction policies can vary.
    • Liquidity trade-off: Money invested in a T-bill follows a maturity schedule, so it may not be as convenient for an emergency as cash held in an accessible bank account.

    Key Risks

    • Timing risk: An emergency may occur before your T-bill reaches maturity.
    • Market-price risk: If you sell a marketable T-bill before maturity, the price you receive can differ from the amount you originally paid.
    • Reinvestment risk: When a T-bill matures, a new bill may have a different yield.
    • Access considerations: The steps for accessing funds before maturity depend partly on where the T-bill is held and how it is sold or transferred.

    EXPERT TIP: For emergency savings, think about liquidity before yield. Keep an accessible cash layer for expenses that cannot wait, and consider T-bills only for the portion of your reserve that fits comfortably within a maturity schedule.

    Common Mistakes and an Illustrative Real-Life Example

    Treasury bills can be useful for part of an emergency-fund plan, but mistakes often happen when investors focus on the investment itself and overlook how quickly the money may be needed.

    Common Mistakes to Avoid

    • Putting the entire emergency fund into T-bills: This can create an access problem if an urgent expense occurs before a bill matures.
    • Choosing a maturity without considering cash needs: The maturity date should fit how long you can reasonably leave that portion of your reserve invested.
    • Assuming early access works like a bank withdrawal: Selling or transferring a marketable T-bill before maturity involves a different process.
    • Assuming future yields will remain unchanged: A new T-bill may have a different yield when the original bill matures.
    • Overlooking tax treatment: T-bill interest is generally subject to federal income tax but exempt from state and local income taxes.
    • Never reviewing the emergency-fund structure: Changes in income, expenses, family circumstances, or other liquid assets can affect how much accessible cash you need.

    Illustrative Example: A $24,000 Emergency Reserve

    Consider a hypothetical household with a $24,000 emergency reserve. The household decides to keep $8,000 in an accessible savings account and considers using the remaining $16,000 for short-term Treasury bills. The purpose is to separate money needed for immediate expenses from money that can follow a maturity schedule.

    Suppose an unexpected $3,000 expense occurs. The household could use part of its accessible cash instead of immediately trying to sell a T-bill. Later, when a T-bill matures, the household can reassess its cash needs and decide whether to keep the proceeds available or consider another short-term option.

    IMPORTANT: The $8,000 and $16,000 amounts are only illustrative. They are not a recommended emergency-fund allocation. The appropriate structure depends on factors such as monthly expenses, income stability, household obligations, other liquid assets, and how quickly the money may be needed.

    Who Should Consider Using Treasury Bills for an Emergency Fund?

    Treasury bills may be considered by people who want to keep part of their short-term reserves in U.S. government securities while maintaining separate funds that are readily accessible. Whether this approach fits depends on how quickly the money may be needed and how comfortable you are with a security that has a defined maturity.

    This Approach May Fit People Who:

    • Already keep some emergency money in an easily accessible account.
    • Can identify a portion of their reserves that is unlikely to be needed immediately.
    • Are comfortable tracking T-bill maturity dates and managing Treasury securities.
    • Understand that selling a marketable T-bill before maturity can involve changes in its market price.
    • Want to consider Treasury interest and its federal, state, and local tax treatment when comparing short-term options.

    It May Be Less Suitable When:

    You have very little readily accessible cash, expect frequent or unpredictable withdrawals, or do not want to manage maturity dates and potential early-sale considerations. In those circumstances, an emergency-fund structure with greater immediate access may better match your cash-flow needs.

    KEY QUESTION: Before using a T-bill for emergency savings, ask: “If I needed this money unexpectedly, would the maturity timing and access process work for me?”

    Frequently Asked Questions About Treasury Bills for Emergency Funds

    1. Can Treasury bills be used for an emergency fund?

    Yes. Treasury bills can be used for a portion of an emergency fund, particularly money that does not need to remain immediately accessible. Keeping some cash readily available can help cover expenses that cannot wait for a T-bill to mature.

    2. Are T-bills good for emergency savings?

    They can be useful for part of an emergency reserve, but they are not the same as immediately accessible cash. The appropriate choice depends on when you may need the money and whether the T-bill’s maturity and access arrangements fit your circumstances.

    3. How much of an emergency fund should be in T-bills?

    There is no universal percentage. The amount depends on your expenses, income, other liquid assets, and how quickly you might need the money. A useful framework is to separate immediately accessible cash from reserves that can follow a T-bill maturity schedule.

    4. Can you access T-bill money before maturity?

    Marketable T-bills can generally be sold before maturity, but the process depends on where the security is held. A TreasuryDirect-held marketable security may need to be transferred or sold through the applicable TreasuryDirect process, and an early sale can produce a price different from the amount originally paid.

    5. Are Treasury bills FDIC insured?

    No. Treasury bills are securities issued by the U.S. Treasury, not FDIC-insured bank deposits. FDIC insurance applies to eligible deposits held at FDIC-insured banks, subject to applicable coverage limits.

    6. Do T-bills have state and local tax benefits?

    Generally, yes. Interest from U.S. Treasury securities is generally exempt from state and local income taxes, while federal income tax generally applies.

    7. What T-bill maturity is best for an emergency fund?

    There is no single maturity that is best for everyone. The appropriate term depends on how long you can leave the money invested, how much accessible cash you already have, and how soon you may need the reserve.

    8. Should you keep some emergency money in a savings account?

    Keeping some emergency money in an accessible savings account can make sense when immediate access is important. The appropriate amount depends on your expected expenses, cash-flow needs, and overall financial situation.

    FAQ NOTE: These answers explain the general framework. Your emergency-fund structure should reflect your own cash needs, access requirements, and financial circumstances.


    Final Verdict: Where Treasury Bills Can Fit in an Emergency Fund

    Treasury Bills for Emergency Funds can be considered for a portion of short-term reserves when that money does not need to remain immediately accessible. Their defined maturities can help with planned cash management, while their status as U.S. Treasury securities gives them a different role from ordinary bank deposits.

    The main consideration is liquidity. An unexpected expense can arise before a T-bill reaches maturity. If you need to access the money earlier, the process depends on where the security is held, and selling before maturity can expose you to changes in market price. This is why emergency-fund planning should account for readily accessible cash as well as investments with defined terms.

    THE BIG IDEA: Think of an emergency fund as a liquidity structure rather than a single investment. Accessible cash can cover immediate needs, while T-bills may be considered for reserves that can comfortably follow a maturity schedule.

    There is no universal T-bill allocation or maturity for every household. The appropriate structure depends on expenses, income, other liquid assets, expected cash needs, and your comfort with managing Treasury securities.

    Have a Money Question? Keep Exploring.

    Emergency savings work best when the access plan matches your real-life needs. If you are considering Treasury bills, explore the guides below to understand the basics and compare them with other short-term options.

    📩 Get in Touch With FinanceInvestment

    Email FinanceInvestment

    Continue Your Research
  • High-Yield Savings Accounts During a Recession (2026 Guide)

    High-Yield Savings Accounts During a Recession (2026 Guide)


    ✓ Expert Reviewed •
    USA Banking Guide
    Finance Investment Editorial Team
    Author: Subhash Rukade.
    Research-backed financial content designed to help Americans protect their savings, compare banking products, and make confident money decisions in every stage of the economy.
    Updated
    August 4, 2026
    Reading Time
    12 Minutes
    Fact Checked ✓


    High-Yield Savings Accounts During a Recession (2026 Guide)

    High-Yield Savings Accounts During a RecessionNews about slowing economic growth, layoffs, and market swings often makes people ask the same question: Is my savings still in the right place? During uncertain times, protecting your cash becomes just as important as growing it. That’s why more Americans start comparing savings options whenever recession concerns return.

    If you’re wondering whether High-Yield Savings Accounts During a Recession are still worth using,”It’s a question many savers are asking.” Interest rates can change, inflation affects buying power, and financial headlines can make it difficult to know what to do next. Making a rushed decision, however, isn’t the answer.

    This guide explains what usually happens to high-yield savings accounts during an economic slowdown, why APYs move up and down, and how you can protect your emergency fund without taking unnecessary risks. You’ll also learn when these accounts make sense and when another option may deserve a closer look.

    What You’ll Learn

    • How recessions can influence high-yield savings account interest rates.
    • Whether your deposits remain protected during difficult economic periods.
    • Simple ways to keep your emergency fund working for you.
    • Mistakes that can quietly reduce the value of your savings.
    • How to compare savings accounts when the economy becomes uncertain.
    • More practical savings strategies in our Complete High-Yield Savings Accounts USA Guide.

    By the end of this guide, you’ll have a clear understanding of how High-Yield Savings Accounts During a Recession fit into a smart savings strategy and what steps can help you feel more confident regardless of where the economy goes next.


    Quick Answer & Key Takeaways

    💙 Quick Answer

    A recession doesn’t automatically make a high-yield savings account a bad place for your money. Interest rates may move lower as economic conditions change, but your savings can still remain protected when they’re held in an eligible FDIC-insured bank. For many households, High-Yield Savings Accounts During a Recession continue to provide a practical place for emergency funds and short-term savings because they balance safety, liquidity, and interest earnings.

    ⭐ Key Takeaways

    • Economic slowdowns can affect APYs, but your money doesn’t disappear because rates change.
    • Emergency savings should stay easy to access when unexpected expenses appear.
    • Compare account features, fees, and insurance instead of chasing the highest advertised rate.
    • Keeping cash available can reduce financial stress during uncertain times.
    • Review your savings strategy every few months instead of reacting to daily headlines.
    • High-Yield Savings Accounts During a Recession remain a sensible option for people who want stability without locking away their money.

    “Here’s what matters most:” A recession is a good time to become more intentional with your savings—not more fearful. Choosing a well-managed savings account and maintaining a healthy emergency fund can help you handle uncertainty with greater confidence.


    Table of Contents


    At a Glance

    Economic slowdowns can make even experienced savers feel uncertain. Stock prices may swing, borrowing costs can change, and headlines often create more questions than answers. Even so, a well-chosen High-Yield Savings Accounts During a Recession strategy can give your cash a safe place to earn interest while remaining available for unexpected expenses.

    Rather than trying to predict every market move, many households focus on building a strong emergency fund and keeping enough cash within easy reach. That approach provides flexibility without exposing short-term savings to unnecessary market risk.

    Quick FactsOverview
    Best ForEmergency funds and short-term savings.
    SafetyEligible deposits are generally protected by FDIC insurance.
    Interest RatesAPYs may rise or fall as the economy changes.
    Access to CashMoney remains available whenever you need it.
    Ideal UsersFamilies, retirees, beginners, and anyone preparing for uncertain times.

    Keeping cash safe doesn’t mean giving up growth entirely.”Most people simply want three things: safety, access to cash, and a reasonable return.”


    Complete Beginner Guide

    High-Yield Savings Accounts During a RecessionWhen the economy slows down, many people stop thinking about growing money and start thinking about protecting it. That’s a natural reaction. Job security may feel uncertain, prices can remain high, and the stock market often becomes more unpredictable. During times like these, knowing where your savings are parked matters just as much as how much you’ve saved.
    A High-Yield Savings Accounts During a Recession strategy gives your cash a place that’s designed for stability instead of speculation. While investment values may rise and fall every day, money in an eligible high-yield savings account isn’t tied to stock market performance. That difference helps many families sleep a little better during uncertain periods.

    Why Interest Rates Change

    High-yield savings accounts don’t keep the same APY forever. Banks adjust rates as economic conditions change. When the Federal Reserve raises or lowers interest rates, banks often respond by changing the APYs offered on savings accounts. Seeing your rate move doesn’t mean something is wrong with your account. It’s simply part of how the banking system works.

    How Your Money Stays Protected

    “Many people choose these accounts because. If your account is held at an eligible FDIC-insured bank, your deposits are generally protected up to the applicable federal insurance limits. That protection remains in place whether the economy is strong or struggling.

    If you’d like a better understanding of how these accounts work, read our guide explaining high-yield savings accounts. You can also learn how rates are calculated in our APY vs. Interest Rate comparison.

    Emergency Funds Matter Even More

    A recession can bring unexpected expenses or temporary income changes. Having several months of living expenses in an easily accessible savings account gives you more options if life takes an unexpected turn. Instead of relying on credit cards or selling investments at the wrong time, you already have cash available when you need it.

    Inflation Doesn’t Disappear

    Even during a recession, inflation may continue affecting everyday costs. A high-yield savings account won’t eliminate inflation, but earning interest helps reduce the impact compared with leaving money in a low-interest account that barely grows.

    💡 Premium Expert Tip

    Don’t wait until recession headlines become louder before reviewing your savings. Building an emergency fund while your finances are stable is usually easier than trying to catch up after unexpected expenses arrive.

    For many households, High-Yield Savings Accounts During a Recession aren’t about chasing the highest return. They’re about keeping cash available, protected, and steadily growing while staying prepared for whatever comes next. That’s why they continue to “continue to be useful” in many financial plans, regardless of the economic outlook.


    How It Works During a Recession

    Money in a high-yield savings account keeps working even when the economy slows down. The bank pays interest on your balance, and that interest is added to your account based on the bank’s payment schedule. As long as the money stays in the account, it continues earning interest on both your original deposit and the interest already credited.

    That’s one reason High-Yield Savings Accounts During a Recession remain popular with people who want stability. While investment markets can move sharply from one week to the next, the value of your savings doesn’t rise and fall with stock prices.

    What Changes When the Economy Slows?

    “What you’ll notice first is.”the interest rate, not the safety of your money. Banks may adjust APYs as borrowing costs and market conditions change. Some months rates move higher, while at other times they move lower. Those adjustments are normal and happen across much of the banking industry.

    Accessing Your Savings

    Your money doesn’t become locked away during a recession. You can still transfer funds, pay unexpected bills, or cover emergency expenses whenever they’re needed. That easy access is one of the biggest reasons people choose a savings account instead of placing every dollar into long-term investments.

    A Simple Example

    Imagine Sarah keeps six months of living expenses in a high-yield savings account. During an economic slowdown, her bank lowers the APY slightly. Even so, her emergency fund remains protected, continues earning interest, and is available immediately if she needs to repair her car or cover household bills after a temporary loss of income.

    If you’re planning to build your emergency fund gradually, our How to Automate Your Savings guide explains how automatic transfers can make saving easier throughout the year.

    💡 Good to Know

    Many savers focus too much on short-term APY changes. Keeping enough cash for emergencies is usually far more important than trying to move money every time another bank advertises a slightly higher rate.

    For many households, High-Yield Savings Accounts During a Recession provide something that’s difficult to measure with numbers alone: confidence that emergency savings will still be there whenever life takes an unexpected turn.


    Benefits & Drawbacks

    “When money feels tighter, saving habits often change.” Instead of chasing bigger returns, the focus often shifts toward protecting savings while keeping cash available for unexpected expenses. That’s where High-Yield Savings Accounts During a Recession can be especially useful, although they aren’t perfect for every situation.

    ✅ Benefits

    • Your savings stay available whenever an emergency comes up.
    • Eligible deposits are generally protected through FDIC insurance.
    • You continue earning interest instead of leaving cash in a low-paying account.
    • No need to worry about daily stock market swings affecting your balance.
    • Online access makes it easy to monitor and manage your savings from anywhere.

    ❌ Drawbacks

    • Interest rates can decline if banks lower their APYs.
    • Returns may not keep pace with inflation during some periods.
    • These accounts are built for saving, not long-term wealth creation through investing.
    • Moving money frequently to chase slightly higher rates rarely delivers a meaningful advantage.

    💡 Expert Insight

    A recession isn’t the time to abandon your savings plan. It’s a good time to review your emergency fund, compare account features, and make sure your cash is earning a competitive rate while remaining easy to access whenever life throws you an unexpected expense.


    Comparison Table

    “Each account was built for a different job.” During a recession, the right choice depends on whether you need immediate access to your money, higher interest, or a guaranteed return for a fixed period. Here’s a simple side-by-side comparison to help you decide.

    FeatureHigh-Yield Savings AccountTraditional SavingsMoney Market AccountShort-Term CD
    SafetyVery HighVery HighVery HighVery High
    Interest PotentialUsually HigherUsually LowerModerate to HighFixed for the term
    LiquidityExcellentExcellentGoodLimited until maturity
    FDIC InsuranceYes (eligible banks)YesYesYes
    Inflation ProtectionBetter than standard savingsLimitedModerateDepends on the fixed rate
    Best Use CaseEmergency fund and short-term savingsBasic banking needsHigher balances with flexible accessMoney you won’t need for several months

    Planning Tip: During uncertain economic periods, High-Yield Savings Accounts During a Recession often provide the best mix of safety, liquidity, and competitive interest. If you expect to need your money quickly, keeping it accessible is usually more valuable than locking it away for a slightly higher return.


    Costs, Risks & Expert Tips

    A recession doesn’t automatically make a savings account less useful, but it can change how much your money earns. Banks regularly adjust APYs as interest rates move. If rates fall, your account may earn less than it did a few months earlier. That doesn’t mean your savings are unsafe—it simply reflects changing economic conditions.

    Inflation is another factor to watch. Even when your balance grows through interest, rising prices can reduce what that money buys in the future.”Taking a fresh look at your savings once or twice a year is usually enough.”

    Before opening a new account, look beyond the advertised APY. Check for monthly maintenance fees, minimum balance requirements, and transfer policies. Many online banks avoid these charges, but it’s always worth reading the account details.

    FDIC insurance is straightforward. If your money is held at an eligible FDIC-insured bank, deposits are generally protected up to the federal insurance limit for each ownership category. That protection stays in place regardless of economic conditions.

    Switching banks may be worthwhile if your current account pays very little interest or charges unnecessary fees. If the difference is only a small fraction of a percent, staying where you are may be the simpler choice.

    ⚠️ Watch Out For

    Don’t let recession headlines push you into making rushed financial decisions. Compare facts, not emotions, before moving your savings.

    5 Practical Tips

    • Keep three to six months of essential expenses in an emergency fund.
    • Compare fees before opening or switching accounts.
    • Review your APY occasionally instead of checking it every week.
    • Choose FDIC-insured institutions whenever possible.
    • High-Yield Savings Accounts During a Recession work best when they’re part of a long-term savings plan rather than a reaction to short-term news.


    Common Mistakes + Real-Life Example

    “When recession news dominates the headlines, it’s easy to make quick decisions.”Sometimes those decisions help, but in many cases they create new problems. A little patience and a clear savings plan usually produce better results than reacting to every financial headline. That’s especially true when managing High-Yield Savings Accounts During a Recession.

    5 Common Mistakes

    • Moving money after every rate change. A slightly higher APY isn’t always worth changing banks.
    • Leaving too little in an emergency fund. Unexpected expenses rarely wait for the economy to recover.
    • Keeping all savings in a checking account. Low interest means your money grows much more slowly.
    • Ignoring fees and account requirements. Small monthly charges can quietly reduce your earnings.
    • Making decisions out of fear. Selling investments or emptying savings without a plan can create bigger financial challenges later.

    Real-Life Example

    David, a teacher from Ohio, became worried after hearing constant recession news. He transferred nearly all of his savings into a regular checking account because he wanted immediate access to every dollar. Months later, he realized his money had earned very little interest while prices continued to rise.

    After reviewing his finances, David rebuilt his emergency fund in a high-yield savings account and kept only his monthly spending money in checking. The change gave him easier access to cash when needed while allowing the rest of his savings to keep earning interest.

    ✅ Lesson Learned

    Financial headlines change every day, but good saving habits don’t. Keeping an emergency fund, avoiding emotional decisions, and reviewing your account from time to time can help you stay prepared through both strong and weak economic periods.


    Who Should Choose This?

    “The right choice depends on your own situation.” Some people want quick access to cash, while others simply want a safe place to keep money until conditions improve. For many households, High-Yield Savings Accounts During a Recession offer a practical balance between safety, flexibility, and steady interest.

    Who Benefits Most?

    • Beginners building their first emergency fund without taking unnecessary investment risk.
    • Families preparing for unexpected expenses such as medical bills, home repairs, or temporary income changes.
    • Retirees who want part of their savings to remain stable and easy to access.
    • Freelancers and self-employed workers whose monthly income may not always be predictable.
    • Investors looking for a secure place to hold cash while waiting for future investment opportunities.

    ✔️ Best Choice If…

    You want your savings to stay available without exposing them to daily market swings. A strong emergency fund, combined with a competitive savings account, can provide valuable peace of mind while the economy works through uncertain periods.


    Frequently Asked Questions

    1. Are high-yield savings accounts safe during a recession?

    Yes. If your account is with an eligible FDIC-insured bank, your deposits are generally protected up to the applicable federal insurance limits. Market ups and downs don’t directly reduce the balance in your savings account.

    2. Why do APYs sometimes fall during a recession?

    Banks adjust savings rates as overall interest rates change. If borrowing costs decline, savings account APYs often follow. A lower APY doesn’t mean your money is less secure—it simply means future interest earnings may be smaller.

    3. Should I keep my emergency fund in a high-yield savings account?

    For many households, yes. Emergency savings should stay easy to reach while still earning interest. That’s one reason High-Yield Savings Accounts During a Recession remain a popular choice for short-term financial security.

    4. Can inflation reduce the value of my savings?

    Yes. Rising prices reduce purchasing power over time. Although a high-yield savings account won’t completely eliminate inflation’s impact, earning interest helps your money grow more than it would in a low-interest account.

    5. Are online banks reliable during a recession?

    Many online banks are well-established financial institutions. As long as the bank offers eligible FDIC insurance, your deposits receive the same federal protection as they would at many traditional banks.

    6. Should I switch banks every time another account offers a higher APY?

    Usually not. A slightly higher rate doesn’t always justify changing accounts. Compare customer service, fees, account features, and convenience before deciding to move your money.

    7. Is a high-yield savings account better than investing during a recession?

    “Each one solves a different problem.” while savings accounts are designed for stability and quick access to cash. Many people choose to use both instead of relying on only one option.

    8. How do I choose the right savings account?

    Look at more than the advertised APY. Check fees, minimum balance requirements, online banking tools, transfer options, and customer support. Choosing an account that matches your financial habits is usually more valuable than chasing the highest rate.

    9. Can I lose money in a high-yield savings account during a recession?

    Your balance doesn’t fluctuate with the stock market, so market declines won’t directly reduce your deposits. The main change you’ll notice is that interest rates may move up or down over time.

    10. Are High-Yield Savings Accounts During a Recession still worth opening in 2026?

    For many Americans, the answer is yes. They provide a practical place to keep emergency savings while earning interest and maintaining easy access to cash. If your goal is protecting money rather than taking additional investment risk, they continue to be a sensible option.


    Final Verdict

    “When the economy slows down, many people start paying closer attention to where their savings are kept.”High-Yield Savings Accounts During a Recession continue to offer an effective combination of safety, flexibility, and interest for money you’ll likely need within the next few months or years.

    Although APYs may change as the economy changes, keeping emergency savings in an account that remains accessible can provide valuable financial stability. Rather than reacting to every headline, focus on building healthy savings habits and reviewing your account occasionally to be sure it still meets your needs.

    If you’re comparing more savings options, explore our Complete High-Yield Savings Accounts USA Guide for additional comparisons, practical tips, and account recommendations.

    For trusted consumer information, visit the FDIC, the Consumer Financial Protection Bureau (CFPB), and Consumer.gov.

    ✔️ Final Takeaway

    A recession is a reminder to protect your savings, not to panic. Keeping an emergency fund in a competitive, FDIC-insured high-yield savings account gives you quick access to cash while allowing your money to continue earning interest as you prepare for whatever comes next.


    Stay Ready for Whatever the Economy Brings

    “If you found this guide useful” Join our free newsletter for practical savings ideas, banking tips, and easy-to-follow money guides delivered throughout the year. If you have a strategy that has helped you protect your savings during uncertain times, share it in the comments. Your experience could help another reader make a smarter financial decision. If you found this article useful, consider sharing it with friends and family.


    Explore the Complete Savings Guide →