Tag: Digital Banking

  • How Credit Union Mobile Banking Works: 2026 Guide

    How Credit Union Mobile Banking Works: 2026 Guide

    How Credit Union Mobile Banking Works
    Subhash Rukade
    Founder, FinanceInvestment
    Published: October 7, 2026
    Updated: October 7, 2026
    Reading Time: 12–14 minutes

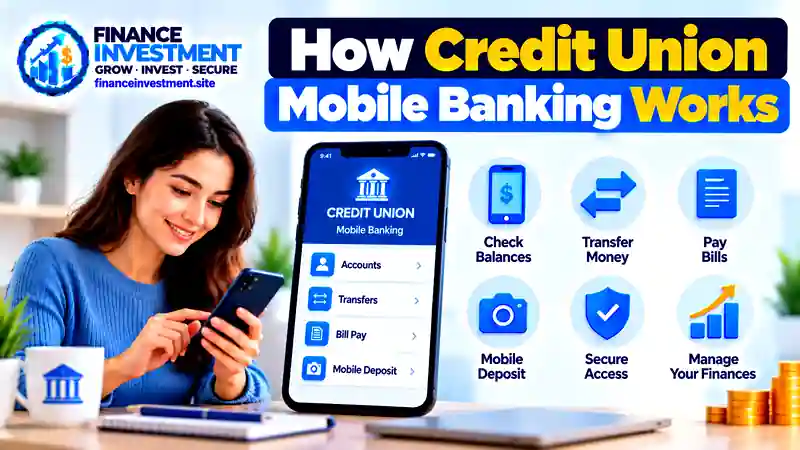
    How Credit Union Mobile Banking WorksFor many credit union members, banking no longer means waiting for a branch to open. How Credit Union Mobile Banking Works comes down to using a secure smartphone app to handle everyday account tasks when it is convenient for you. Depending on the credit union, you may be able to view balances, check recent activity, move money, pay bills, deposit checks, and receive account alerts without making a branch visit.

    The important part is knowing what your particular credit union actually offers. Mobile features can differ by institution, and some services may have transaction limits, eligibility rules, fees, or processing times. Your app also does not replace everything a credit union provides. Branches, ATMs, shared networks, and member support can still play an important role in how you manage your money. If you are new to the credit union model, our credit union guide explains the bigger picture.

    What You’ll Learn

    • How a credit union mobile app connects you with your accounts.
    • What you can typically do from a smartphone.
    • How mobile deposits, transfers, payments, and alerts fit into everyday banking.
    • What fees, limits, and processing delays you should watch for.
    • How mobile access works alongside ATMs, branches, and other services.
    • Which security habits can help protect your account.

    Quick Answer: How Does Credit Union Mobile Banking Work?

    Credit union mobile banking connects your eligible credit union accounts to a smartphone app. Once you sign in, the app can give you access to everyday banking tasks such as checking account activity, moving money, paying bills, depositing eligible checks, and managing certain card settings. The exact tools, limits, and fees depend on the credit union.

    6 Key Takeaways

    1. It extends branch access: Many routine banking tasks can be completed from your phone instead of requiring a branch visit.
    2. The app connects to your existing accounts: Mobile banking normally works as a digital access point for eligible checking, savings, and other accounts.
    3. Not every feature is universal: Two credit unions can offer noticeably different apps, services, limits, and payment options.
    4. Some transactions take time: Transfers, deposits, and bill payments may have processing windows or cutoff times.
    5. Security remains your responsibility: Account credentials, device settings, authentication methods, and scam awareness all matter.
    6. The app should be judged with the whole account: Fees, ATM access, deposit options, customer support, and account terms can matter just as much as app quality.

    Bottom line: A credit union mobile app can make everyday banking considerably more convenient, but a polished app does not automatically make an account a good fit. Look at the complete banking experience—including access, costs, transaction rules, security, and support—before choosing a credit union.

    Table of Contents

    At a Glance: Credit Union Mobile Banking

    FactorQuick Summary
    What it isA smartphone-based way to access eligible credit union accounts and services.
    Typical accessA credit union mobile app, usually protected by account credentials and additional security controls.
    Best forMembers who prefer handling routine banking tasks from a smartphone.
    Key considerationCompare the app’s features with account fees, limits, deposit options, ATM access, and support.

    QUICK TAKE: Mobile banking is the digital access layer of your credit union account. It can make everyday banking more convenient, but the app should not be judged by features alone. A good fit also depends on how easily you can access cash, make deposits, get help, and manage the account within its rules and costs.

    Credit Union Mobile Banking: A Beginner GuideHow Credit Union Mobile Banking Works

    If you are new to credit union mobile banking, the easiest way to think about it is as a digital way to reach the accounts you already have. You typically do not create a separate account just for the app. Instead, your credit union connects eligible checking, savings, or other accounts to its mobile banking service.

    Getting Started

    1. Join the credit union and open an eligible account. Membership requirements vary between credit unions.
    2. Download the official app. Use the mobile application recommended by your credit union rather than an unfamiliar third-party app.
    3. Register or sign in. The setup may require your existing online-banking information and identity verification.
    4. Connect your preferred device settings. Depending on the service, you may be able to use biometric login, alerts, or other account-access options.
    5. Explore the app first. Locate your balances, transaction history, payments, transfers, deposits, statements, and help options before you need them.

    Beginner tip: Do not assume every credit union app works the same way. Before using a new feature, check the instructions, eligibility requirements, limits, and processing details shown by your credit union.

    How Credit Union Mobile Banking Works

    A credit union mobile app works as a digital connection to your eligible accounts. After you sign in, the app securely displays information provided by the credit union and lets you submit certain banking requests. The credit union’s systems then process those requests based on the account rules, transaction limits, and service schedules that apply to you.

    The Basic Mobile Banking Flow

    1. Sign in: You authenticate your identity through the credit union’s approved mobile service.
    2. Choose a service: You select an available function, such as viewing an account, transferring money, paying a bill, or depositing an eligible check.
    3. Review the request: The app may show the amount, destination, date, or other details before you submit it.
    4. Submit: The request is sent through the credit union’s digital banking system for processing.
    5. Check the status: The transaction may appear as completed, pending, or otherwise subject to processing before it is fully available.
    Common TaskTypical Mobile Action
    Account reviewCheck eligible balances, transactions, and account details.
    Money transferEnter the permitted accounts or destination and submit the transfer.
    Mobile depositFollow the app’s instructions to submit an eligible check deposit.
    Bill paymentSet up or schedule an eligible payment through the available bill-pay service.

    Key point: Mobile banking gives you a convenient way to send instructions to your credit union, but it does not guarantee that every transaction settles immediately. Cutoff times, account eligibility, transaction limits, verification, and funds-availability rules can affect the final result.

    Benefits & Drawbacks of Credit Union Mobile Banking

    A well-designed credit union app can remove friction from everyday banking. You can handle many routine tasks from wherever you are, which is especially useful when a branch is not nearby. However, mobile access has limits. The quality of the experience depends on the credit union’s app, account rules, service availability, and the other ways you can access your money.

    Benefits

    • Convenient access: Complete many routine banking tasks without traveling to a branch.
    • Quick account visibility: Review balances, transactions, and available alerts from your phone.
    • Remote check deposits: Eligible members may be able to submit checks without visiting a branch.
    • Digital self-service: Payments, transfers, statements, and other available tools can reduce routine calls or visits.

    Drawbacks

    • Different app experiences: Features and usability can vary significantly between credit unions.
    • Internet dependence: A poor connection, outage, or app problem can temporarily limit access.
    • Service restrictions: Certain transactions may have eligibility requirements, limits, cutoff times, or delays.
    • Not every problem is digital: Account disputes, complex requests, or some service needs may still require human assistance.

    Best perspective: Do not judge a credit union only by its mobile app. Consider how the digital service works alongside ATM access, branches, deposits, customer support, account rules, and the features you actually use. The strongest choice is the one that remains convenient when the app cannot handle what you need.

    Credit Union Mobile Banking Comparison

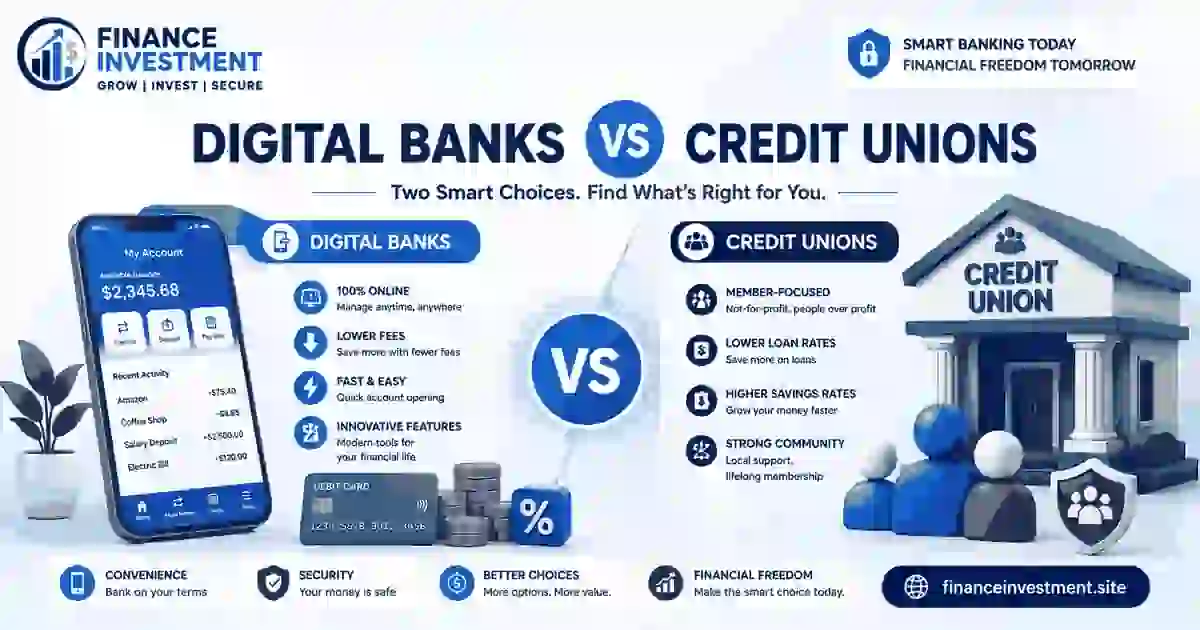
    Mobile banking is convenient, but it is not the only way to access a credit union account. Each channel has a different job. Comparing them helps you decide where a particular banking task makes the most sense.

    Access MethodBest ForMain AdvantageMain Limitation
    Mobile appRoutine banking on a smartphoneConvenient access while away from a branchFeatures depend on the credit union and app
    Online bankingAccount management from a computerLarger screen for detailed account tasksLess convenient when you are away from a computer
    ATMCash withdrawals and selected self-service tasksPhysical cash accessLimited compared with full digital banking
    BranchComplex needs and personal assistanceDirect help from credit union staffLocation and operating hours can limit access

    QUICK COMPARISON: For everyday tasks, the mobile app is often the most convenient option. However, ATM access remains useful for cash, online banking can be easier for detailed work, and branches matter when a request needs personal assistance. A strong credit union experience gives you more than one practical way to access your money.

    Costs, Risks & Expert Tips

    A credit union may provide its mobile app at no separate monthly cost, but other banking charges can still apply. Depending on the account and service, costs may involve certain transfers, ATM use, overdrafts, expedited services, or other transactions. The safest approach is to check the credit union’s current fee schedule and account disclosures before using a service.

    Mobile Banking Risks

    • Impersonation scams: Fake messages, websites, or apps can be designed to capture banking credentials.
    • Device exposure: A lost, stolen, or poorly protected phone can create additional account-security concerns.
    • Unsafe connections: Public or untrusted networks can create privacy and security risks.
    • Service interruptions: An outage, maintenance period, or technical problem can temporarily prevent digital access.

    Expert Tips for Safer Mobile Banking

    • Download the app through the official channel recommended by your credit union.
    • Use a strong, unique password and enable available multifactor authentication.
    • Keep your phone’s operating system and banking app updated.
    • Turn on useful transaction and account alerts so unusual activity is easier to spot.
    • Contact the credit union through a trusted phone number or website if something looks suspicious.

    If you want to understand the broader charges that may affect your account, see our guide to credit union fees.

    Common Credit Union Mobile Banking Mistakes

    Mobile banking is simple once you get familiar with it, but small oversights can cause unnecessary problems. The most common mistakes involve assuming every credit union app works the same way, overlooking account rules, or treating a digital confirmation as proof that everything is finished.

    Mistakes to Avoid

    • Assuming features are universal: Check whether your credit union actually supports the service you want to use.
    • Skipping the details: Review amounts, recipients, dates, and available instructions before confirming an important request.
    • Ignoring account rules: Check applicable limits, eligibility requirements, and processing information.
    • Relying only on the app: Know how to contact your credit union if a digital request needs additional help.

    Real-Life Example

    Imagine Maria opens her credit union app to deposit a check. She assumes the money will be available immediately because the app accepts the deposit. Before spending the funds, she checks the credit union’s instructions and availability information. She learns that submitting the check and having the funds available are separate steps. That quick check helps her avoid planning a payment around money she cannot yet use.

    The lesson: Convenience is the biggest strength of mobile banking, but a few seconds of review can help prevent avoidable mistakes.

    Who Should Choose Credit Union Mobile Banking?

    Credit union mobile banking makes the most sense when your everyday banking needs are simple enough to handle digitally and you value access from your smartphone. It can be especially useful if you regularly check transactions, manage eligible transfers, make payments, or use other services available through your credit union’s app.

    A Good Fit If You:

    • Prefer banking from your phone: You are comfortable handling routine account tasks without visiting a branch.
    • Want flexible account access: You often need to review or manage your accounts when you are away from a branch.
    • Use routine digital services: Your banking needs include features supported by the credit union’s mobile app.
    • Want backup support: You are comfortable using the app for routine needs but can contact the credit union when a request requires additional assistance.

    When it may not be ideal: If you strongly prefer face-to-face service, rarely use a smartphone, or regularly need services unavailable through the app, a branch or another access method may suit you better. The goal is not to choose the most digital option—it is to choose the access method that fits your banking habits.

    Frequently Asked Questions About Credit Union Mobile Banking

    1. How do I start using credit union mobile banking?

    You generally need an eligible credit union account and access to the institution’s mobile banking service. Registration may require your existing online-banking details or identity verification.

    2. Do I need a separate account for mobile banking?

    No separate bank account is normally created just for the app. Mobile banking generally provides digital access to eligible accounts you already have with the credit union.

    3. Can I deposit a check through a credit union mobile app?

    Many credit unions offer mobile check deposit for eligible members. Availability, deposit limits, endorsement requirements, and funds-availability rules can vary.

    4. Can I transfer money using credit union mobile banking?

    Yes, when the credit union supports the type of transfer you need. Available destinations, limits, verification requirements, and processing times depend on the service.

    5. Does credit union mobile banking cost money?

    Some credit unions do not charge a separate fee for mobile banking, but account, transaction, ATM, or other service fees may still apply. Check the current fee schedule for your account.

    6. How can I make credit union mobile banking safer?

    Use the official credit union app, protect your login credentials, keep your device and app updated, and enable available authentication and account-alert features.

    7. Can I use mobile banking when I cannot visit a branch?

    Yes. Supported mobile features can let you handle routine banking without a branch visit. However, some services may still require staff assistance or another access method.

    8. What should I do if my credit union mobile app stops working?

    Check your internet connection, confirm that the app and device software are updated, and try again later if the service is temporarily unavailable. If the issue continues, contact the credit union through an official support channel.

    Quick answer: Credit union mobile banking can handle many routine tasks, but the exact features, limits, fees, and availability depend on the credit union and the account.

    Final Verdict: Is Credit Union Mobile Banking Worth It?

    Credit union mobile banking is worth considering if the app supports the tasks you regularly handle and you are comfortable managing routine banking from your phone. It can reduce the need for branch visits while giving you a convenient way to review and manage eligible accounts.

    Still, the app should be only one part of your decision. Before choosing or relying on a credit union, compare the features you actually need with its account fees, transaction limits, deposit rules, ATM and branch access, and customer support. Those details can matter more than how polished the app looks.

    Bottom line: The best credit union mobile banking setup is not the one with the most features. It is the one that makes your routine banking easier while giving you reliable alternatives when a task cannot be completed through the app.
    Have a Money Question? Keep Exploring.

    Credit union mobile banking can make routine tasks easier, but the right setup depends on the features, costs, access, and support that fit your needs. Keep comparing the details before making an important banking decision.

    Have a question? Contact FinanceInvestment

    Continue Your Research

    Credit Union Fees Explained ·
    Credit Union ATM Networks Explained

  • AI Credit Card Approval: How Banks Use AI to Approve Credit Cards in 2026

    AI Credit Card Approval: How Banks Use AI to Approve Credit Cards in 2026


    AI Credit Card Approval: How Banks Use AI to Approve Credit Cards in 2026

    Author: Subhash Rukade

    Published: June 14, 2026

    AI Credit Card Approval

    How Banks Use AI to Approve Credit Cards in 2026

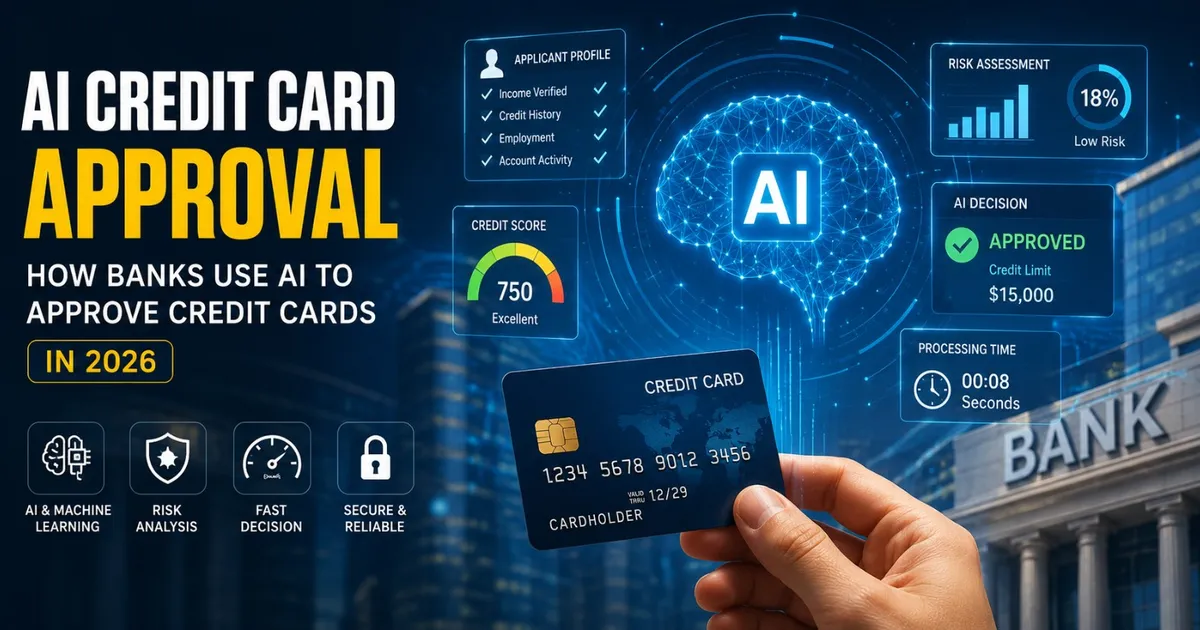
    AI Credit Card Approval systems are transforming the way banks evaluate applications in 2026. Instead of relying only on traditional credit scores and manual reviews, financial institutions now use artificial intelligence to analyze risk, verify information, and make approval decisions within minutes.

    Modern AI models evaluate multiple factors, including credit history, income stability, spending behavior, payment patterns, debt levels, and banking activity. This allows banks to make faster and more accurate lending decisions while reducing fraud and financial risk.

    As artificial intelligence becomes a larger part of personal finance, many consumers are curious about what happens behind the scenes when they apply for a new credit card.

    To understand how AI is changing investing, banking, and financial planning, explore our
    AI Investing Guide 2026.

    In this guide, you’ll learn how banks use AI to approve credit cards, what data is analyzed, why approvals are becoming faster, and how consumers can improve their chances of getting approved in 2026.

    Traditional vs AI Credit Card Approval

    For decades, banks relied on traditional underwriting systems to approve or reject credit card applications. These systems primarily focused on credit scores, income verification, debt levels, and manual reviews performed by loan officers.

    While traditional methods worked reasonably well, they often required more time and sometimes failed to capture a complete picture of an applicant’s financial behavior.

    Today, AI Credit Card Approval systems are changing the process dramatically.

    Artificial intelligence allows banks to analyze large amounts of financial information within seconds. Instead of reviewing only a few data points, AI evaluates hundreds of variables simultaneously to determine risk levels and approval eligibility.

    How Traditional Credit Card Approval Worked

    In the traditional process, banks generally reviewed:

    • Credit score
    • Credit history length
    • Income information
    • Existing debt obligations
    • Past payment history
    • Manual verification documents

    This process could take several days and sometimes required additional paperwork before a final decision was made.

    Although effective, traditional underwriting often depended heavily on historical credit data.

    How AI Credit Card Approval Works

    Modern AI systems go far beyond traditional scoring models.

    Banks use machine learning algorithms to evaluate spending patterns, banking activity, debt management behavior, account stability, fraud indicators, and financial trends.

    The system then calculates a risk score and recommends an approval decision within minutes.

    Because AI can process significantly more information than a human reviewer, the approval process becomes faster and often more accurate.

    Benefits for Banks

    • Faster application processing
    • Improved fraud detection
    • Lower operational costs
    • More accurate risk assessment
    • Better customer experience

    Benefits for Consumers

    • Quicker approval decisions
    • Less paperwork
    • More personalized credit offers
    • Improved access to credit
    • Fairer evaluation methods

    Traditional vs AI Credit Card Approval Comparison

    FactorTraditional ApprovalAI Credit Card Approval
    Decision SpeedHours to DaysMinutes or Seconds
    Data AnalysisLimited VariablesHundreds of Variables
    Fraud DetectionBasic ChecksAdvanced AI Monitoring
    PersonalizationLowHigh
    Operational EfficiencyManual ReviewAutomated Processing

    Consumers looking for the best cards available today should also review our
    Best Credit Cards 2026
    guide before applying.

    As AI continues evolving, banks are increasingly replacing slow manual reviews with intelligent systems that deliver faster, smarter, and more reliable credit decisions.

    AI Technologies Used by Banks to Approve Credit Cards

    Modern AI Credit Card Approval systems rely on several advanced technologies that help banks evaluate applications faster and more accurately than traditional underwriting methods.

    Instead of looking at only a credit score, artificial intelligence analyzes hundreds of financial signals simultaneously. This allows banks to make smarter lending decisions while reducing fraud and financial risk.

    Let’s examine the key technologies driving today’s AI lending systems.

    Machine Learning

    Machine learning is the foundation of most AI credit decisions.

    Banks train machine learning models using millions of historical lending records. These systems learn which financial behaviors are associated with responsible borrowers and which patterns may indicate higher risk.

    As new data becomes available, the models continuously improve their accuracy.

    This means AI can adapt to changing economic conditions and consumer behavior much faster than traditional underwriting systems.

    Predictive Analytics

    Predictive analytics helps banks estimate the likelihood that an applicant will successfully manage future credit obligations.

    Rather than focusing only on past financial behavior, AI evaluates trends and forecasts future risk.

    This approach helps financial institutions make more informed lending decisions while expanding access to qualified applicants.

    Behavioral Analysis

    Modern AI systems analyze spending habits, payment behavior, banking activity, and account stability.

    For example, consistent bill payments and responsible account management may strengthen an application, even when traditional credit history is limited.

    Behavioral analysis provides a more complete picture of financial responsibility.

    Alternative Data Sources

    One reason AI Credit Card Approval systems are becoming more popular is their ability to evaluate alternative financial data.

    Some AI models may consider factors such as banking activity, income consistency, savings behavior, and cash flow patterns.

    This can help applicants with shorter credit histories demonstrate financial reliability.

    Credit Risk Models

    Banks use AI-powered risk models to assign a credit risk score to every application.

    The lower the predicted risk, the greater the likelihood of approval.

    These models evaluate hundreds of variables simultaneously, helping lenders make decisions with greater confidence.

    Credit Utilization Calculator Example

    Credit utilization is one of the most important factors in many approval decisions.

    Simple Formula:

    Credit Utilization = (Current Balance ÷ Total Credit Limit) × 100

    Example:

    • Total Credit Limit = $10,000
    • Current Balance = $2,500

    Calculation:

    ($2,500 ÷ $10,000) × 100 = 25%

    A utilization rate below 30% is generally viewed more favorably by lenders and AI underwriting systems.

    To learn how artificial intelligence is improving budgeting, investing, and financial planning, explore our
    AI Personal Finance Guide 2026.

    By combining machine learning, predictive analytics, behavioral analysis, and advanced risk models, AI lending platforms help banks approve qualified applicants faster while maintaining strong risk controls.

    Real-World Case Study: How AI Approved a Credit Card Application

    To better understand how AI Credit Card Approval works, let’s look at a realistic example that reflects how many modern banks evaluate applications in 2026.

    Meet Michael, a 27-year-old software engineer from Texas. Although he had a stable income and strong savings habits, he had only recently started building his credit history.

    Because of his limited credit profile, Michael worried that traditional lenders might reject his application.

    How Banks Use AI to Approve Credit Cards

    The Application Process

    Michael applied online for a rewards credit card offered by a major U.S. bank.

    Within seconds, the bank’s AI lending system began analyzing his application.

    Instead of relying only on a traditional credit score, the AI reviewed multiple financial indicators:

    • Monthly income consistency
    • Bank account activity
    • Savings patterns
    • Existing debt obligations
    • Payment history
    • Credit utilization levels
    • Employment stability

    How the AI Evaluated Risk

    The applicant’s credit history was relatively short, which might have created challenges under older underwriting models.

    However, the AI Credit Card Approval system identified several positive signals.

    Michael maintained regular direct deposits, consistently paid bills on time, carried very little debt, and demonstrated responsible financial behavior.

    The machine learning model recognized these patterns as indicators of a lower-risk borrower.

    As a result, the system generated a favorable risk score.

    The Approval Decision

    After analyzing hundreds of variables, the AI recommended approval.

    The bank automatically approved the application and provided a competitive credit limit based on the applicant’s overall financial profile.

    The entire process took less than three minutes.

    📊 Case Study Summary

    • Applicant: Michael (Texas)
    • Credit History: Limited
    • Income Stability: Strong
    • Debt Level: Low
    • Credit Utilization: 18%
    • AI Risk Assessment: Low Risk
    • Decision: Approved
    • Approval Time: Under 3 Minutes

    This example demonstrates one of the biggest advantages of modern AI lending systems. Instead of focusing exclusively on credit scores, banks can evaluate a broader financial picture.

    That approach may help qualified consumers gain access to credit even when their traditional credit history is relatively limited.

    Investors and consumers preparing for uncertain economic conditions should also review our
    Recession-Proof Investing 2026
    guide.

    As AI Credit Card Approval systems continue evolving, banks are becoming better at identifying responsible borrowers while reducing unnecessary rejections and improving customer experiences.

    Common Mistakes That Reduce Credit Card Approval Chances

    Even though modern AI Credit Card Approval systems are more advanced than traditional underwriting models, applicants can still make mistakes that reduce their chances of getting approved.

    Artificial intelligence helps banks make smarter decisions, but the quality of those decisions still depends on the financial information available.

    Understanding these common mistakes can help consumers improve approval odds and strengthen their overall financial profile.

    1. High Credit Utilization

    Credit utilization remains one of the most important factors evaluated during the approval process.

    Many applicants carry balances that use a large percentage of their available credit limits.

    High utilization may signal financial stress and increase perceived lending risk.

    Most experts recommend keeping utilization below 30%, while levels under 10% are often viewed even more favorably.

    2. Applying for Multiple Credit Cards at Once

    Submitting several credit card applications within a short period can trigger multiple hard inquiries.

    AI lending systems may interpret excessive applications as a sign that an applicant urgently needs credit.

    This behavior can negatively affect approval decisions.

    Instead, consumers should apply strategically and only when necessary.

    3. Income Reporting Errors

    Providing inaccurate income information is another common mistake.

    Banks use income data to evaluate repayment capacity and overall financial stability.

    Applicants should always provide accurate and verifiable information.

    Even small reporting mistakes can delay or complicate the approval process.

    4. Ignoring Credit Monitoring

    Many consumers fail to monitor their credit reports regularly.

    Errors, fraudulent activity, or outdated information may reduce approval chances without the applicant realizing it.

    Regular monitoring helps identify potential issues before applying for new credit.

    5. Carrying Excessive Debt

    AI Credit Card Approval systems evaluate existing debt obligations carefully.

    High debt levels may increase risk scores and reduce approval odds, even when credit scores appear strong.

    Reducing debt before applying can improve the overall application profile.

    📊 Factors That Influence AI Credit Card Approval

    The chart below illustrates common factors considered by many AI lending systems.

    Approval Influence Ranking:

    • Payment History — 35%
    • Credit Utilization — 30%
    • Income Stability — 15%
    • Credit History Length — 10%
    • Existing Debt Levels — 10%

    Consumers looking to strengthen their financial profiles should also review our
    AI Credit Score Tools Guide,
    which explains how artificial intelligence can help improve credit health and borrowing opportunities.

    Avoiding these common mistakes can significantly improve approval odds and help applicants present a stronger financial profile to AI-powered lending systems.

    How to Increase Your Credit Card Approval Chances in 2026

    While banks continue improving AI Credit Card Approval systems, consumers can take several practical steps to improve their chances of getting approved.

    The good news is that many of the factors evaluated by AI lending models are within your control.

    By strengthening your financial profile before applying, you can significantly improve approval odds and potentially qualify for better credit card offers.

    1. Improve Your Credit Score

    Although AI evaluates more than just credit scores, your score still plays an important role in most lending decisions.

    Paying bills on time, reducing outstanding balances, and avoiding unnecessary credit applications can help strengthen your credit profile.

    Consistent positive behavior often produces the best long-term results.

    2. Reduce Existing Debt

    AI lending systems carefully evaluate current debt obligations.

    Applicants carrying high levels of debt may appear riskier to lenders.

    Reducing balances before applying can improve debt-to-income ratios and lower overall risk scores.

    Even modest debt reduction can make a positive difference.

    3. Monitor Credit Reports Regularly

    Errors on credit reports can negatively impact approval decisions.

    Reviewing reports regularly allows consumers to identify inaccurate information and dispute mistakes before submitting applications.

    Many AI-powered financial tools now provide automated credit monitoring and alerts.

    4. Use AI Financial Tools

    Modern AI tools can help consumers track spending, manage debt, monitor credit utilization, and improve overall financial health.

    These platforms often provide personalized recommendations that support stronger approval outcomes.

    The same technologies driving AI Credit Card Approval are also helping consumers build healthier financial habits.

    5. Practice Smart Borrowing Habits

    Responsible borrowing remains one of the strongest signals evaluated by AI underwriting systems.

    Making payments on time, maintaining low utilization, and avoiding excessive debt can demonstrate financial responsibility over time.

    Banks reward applicants who consistently manage credit wisely.

    Investors interested in strengthening their long-term financial future should also explore our
    How to Build a Dividend Portfolio
    guide.

    For additional investing ideas, review our
    Top Dividend Stocks USA 2026
    and
    SIP Investing Guide 2026.

    Recommended Resources

    📘

    The Psychology of Money by Morgan Housel

    📘

    I Will Teach You To Be Rich by Ramit Sethi

    📊

    Experian Credit Monitoring Services

    As AI lending technology continues evolving, consumers who maintain strong financial habits will remain in the best position to benefit from faster approvals, better offers, and improved access to credit.

    Future of AI Credit Decisions in America

    The future of AI Credit Card Approval is expected to be faster, smarter, and more personalized than ever before.

    As artificial intelligence continues evolving, banks will gain access to more advanced tools that improve lending accuracy while helping consumers receive fairer and more customized credit decisions.

    Many experts believe AI lending technology will play a major role in shaping the future of consumer finance throughout the next decade.

    Open Banking and Better Financial Insights

    One of the biggest trends influencing AI credit decisions is open banking.

    With consumer permission, financial institutions can securely analyze broader financial information, including banking activity, savings habits, income patterns, and cash flow behavior.

    This creates a more complete picture of financial health and may help qualified consumers gain access to credit even when traditional credit histories are limited.

    Personalized Lending Decisions

    Future AI systems will become increasingly personalized.

    Instead of applying identical approval standards to every applicant, banks may tailor lending decisions based on individual financial behavior and risk profiles.

    This approach can improve both customer experience and lending accuracy.

    Responsible AI and Regulation

    As AI lending expands, regulators are paying closer attention to transparency and fairness.

    Financial institutions must ensure AI systems avoid bias and comply with consumer protection laws.

    Organizations such as the
    Consumer Financial Protection Bureau (CFPB),
    the
    Federal Reserve,
    and the
    U.S. Securities and Exchange Commission (SEC)
    continue monitoring developments across the financial industry.

    Frequently Asked Questions

    1. How do banks use AI to approve credit cards?

    Banks use AI to analyze credit history, income patterns, debt levels, spending behavior, fraud indicators, and other financial data to assess risk and make approval decisions.

    2. Is AI Credit Card Approval faster than traditional underwriting?

    Yes. AI systems can review hundreds of variables within seconds, allowing many applications to receive decisions almost instantly.

    3. Can AI approve applicants with limited credit history?

    In some cases, yes. AI may evaluate alternative financial signals such as income stability, banking activity, and savings behavior.

    4. What factors matter most during AI credit decisions?

    Payment history, credit utilization, debt levels, income stability, and overall financial behavior remain important factors.

    5. Does AI replace human underwriters completely?

    No. Many lenders still use human oversight for complex cases, compliance reviews, and final approval decisions.

    6. How can consumers improve approval chances?

    Maintaining strong credit habits, reducing debt, monitoring credit reports, and using AI financial tools can improve approval odds.

    Conclusion

    Artificial intelligence is transforming the credit card industry. Modern AI Credit Card Approval systems help banks evaluate risk more accurately, reduce fraud, improve efficiency, and provide faster lending decisions.

    For consumers, these advancements can create better access to credit, more personalized offers, and a smoother application experience.

    The same technologies shaping AI lending are also transforming investing, wealth management, retirement planning, and personal finance.

    To explore these broader innovations, visit our
    AI Investing Guide 2026.

    📩 Join Our Free Finance Newsletter

    Get investing insights, AI finance trends, credit card strategies, and wealth-building ideas delivered directly to your inbox.


    Subscribe today and stay ahead of the future of finance.


    About the Author

    Subhash Rukade writes about investing, AI finance, credit management, and wealth-building strategies to help readers make smarter financial decisions in a rapidly changing economy.


    🚀 Thank you for reading. Use technology wisely, build strong financial habits, and create a better financial future.