Tag: CD Investing

  • How to Build a CD Ladder in 2026: Step-by-Step Guide

    How to Build a CD Ladder in 2026: Step-by-Step Guide

    FINANCEINVESTMENT • CD GUIDE 2026

    How to Build a CD Ladder in 2026

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August 25, 2026
    About 10–12 min read

    A practical guide to organizing CDs around different maturity dates, cash needs, and future reinvestment decisions.

    How to Build a CD Ladder in 2026: Beginner’s Guide
    Learn how to build a CD ladder in 2026, including how to choose CD terms, divide your money, plan maturity dates, manage liquidity, and reinvest.
    how-to-build-a-cd-ladder-in-2026
    How to Build a CD Ladder in 2026
    how to build a CD ladder,
    CD ladder strategy,
    CD ladder for beginners,
    CD ladder example,
    CD laddering,
    CD maturity schedule,
    CD maturity dates,
    CD ladder terms,
    CD reinvestment strategy,
    how CD ladders work
    https://financeinvestment.site/how-to-build-a-cd-ladder-in-2026/
    Subhash Rukade
    August 25, 2026
    About 10–12 minutes

    Start With Your Cash Calendar

    How to Build a CD Ladder in 2026How to Build a CD Ladder in 2026 is easier when you start with your cash calendar instead of a rate table. A CD ladder spreads one pool of money across certificates with different maturity dates, giving portions of the balance a chance to become available at different times.

    Think about what your money may need to do over the next few years. You might have a home project, tuition payment, planned purchase, or another expense on the horizon. Those dates can help determine which CD terms make sense. The goal is to create a schedule that works with your plans rather than forcing your plans around the certificates.

    Before opening anything, decide how much cash can genuinely stay untouched. Emergency savings and money needed for regular expenses belong somewhere more accessible. The amount left for the ladder can then be divided into practical pieces, with each piece assigned a term that creates a useful maturity date.

    You do not need a complicated formula to get started. A simple ladder can give you several opportunities to review your cash, compare available rates, and decide what to do when each certificate matures. If you want to refresh the basics first, our

    CD Guide 2026

    explains CD terms, rates, features, and other details worth understanding before you choose a certificate.

    What You’ll Learn

    • How to decide how much money belongs in a CD ladder
    • How to select terms that create useful maturity dates
    • How to divide a larger deposit into manageable amounts
    • How to handle each CD when it matures
    • How to keep emergency and near-term cash outside the ladder

    Quick Answer: How Do You Build a CD Ladder?

    Build a CD ladder by choosing the amount you want to commit, dividing it among several CDs, and selecting different terms so the certificates mature at separate points. When a CD matures, review your plans and current rates before deciding whether to use, move, or reinvest the money.

    6 Key Takeaways

    1. Set a workable amount: Commit only money that does not need to remain immediately available.
    2. Pick a manageable number of CDs: More rungs can create more maturity dates, but they also require more tracking.
    3. Space maturity dates: Choose terms that create useful opportunities to access or reposition portions of the balance.
    4. Keep liquid savings separate: Emergency reserves should not depend on a CD reaching maturity.
    5. Review each maturity: A maturing certificate gives you a chance to reassess the money’s next job.
    6. Check renewal instructions: Review the bank’s terms before an automatic renewal locks the money into another period.

    Bottom line: A useful ladder is built around practical maturity dates, not a target number of CDs. Keep the structure simple enough to manage and flexible enough to review as each certificate matures.

    CD Ladder at a Glance

    A ladder can be built with a few certificates or a larger set of rungs. The useful size depends on your balance, expected cash needs, and how much account tracking you want to handle. Terms can range from several months to several years, depending on how far into the future you want to spread your maturities.

    Planning AreaPractical RangeWhat to Watch
    Ladder sizeA few to several CDsKeep tracking manageable
    TermsAbout 6 months to 5 yearsMatch terms to future cash needs
    Maturity spacingMonthly, quarterly, annual, or goal-basedChoose dates that are actually useful
    LiquidityKeep emergency cash outsideAvoid relying on early withdrawals
    ReinvestmentReview each maturityCompare current rates and goals

    Quick view: A smaller ladder may be easier to maintain, while additional rungs can create more frequent maturity points. Neither is automatically better; the schedule should earn its place in your plan.

    How to Build a CD Ladder Step by Step
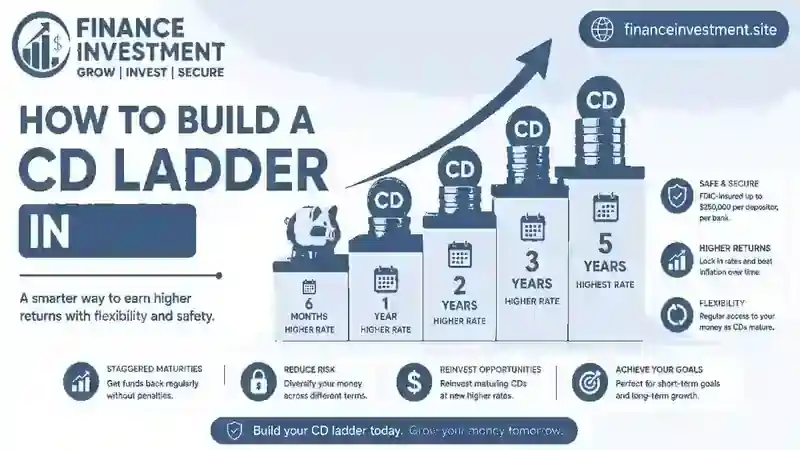
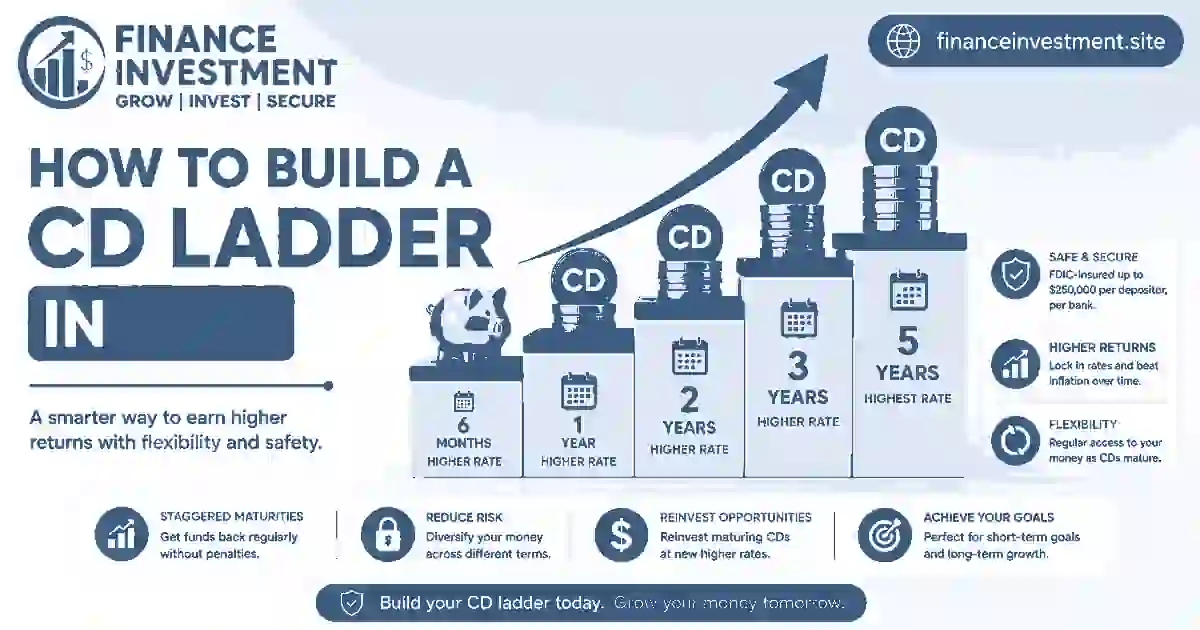
    how to build a CD ladder in 2026Once you know which money is available for longer-term saving, the next job is turning that balance into actual certificates. The process is straightforward: decide how much to commit, choose the number of CDs, select terms, divide the money, and set reminders for every maturity.

    1. Decide How Much You Can Commit

    Start with money that is not earmarked for rent, regular bills, or unexpected expenses. Keep your emergency reserve in an account that you can access without waiting for a certificate to mature. The amount left over becomes the pool for your ladder.

    2. Choose the Number of Rungs

    Think about how often you would realistically want a portion of the balance to become available. A few certificates may be enough for a simple plan. If you use more, make sure each additional maturity date serves a clear purpose rather than adding complexity for its own sake.

    3. Select Terms Around Your Goals

    Now work backward from your expected cash needs. If you expect to need money next year, a shorter certificate may fit that portion. Money intended for a later goal can potentially use a longer term. You can compare different options with our guide on
    how to choose the right CD.

    4. Divide the Money

    Suppose you have $20,000 available. You could place $5,000 into each of four CDs with different terms. Equal amounts keep the structure simple, but unequal amounts can make sense when one future expense is larger than another.

    5. Set Your Maturity Targets

    Record every maturity date, APY, balance, early-withdrawal terms, and renewal instruction. Set reminders before each certificate reaches maturity so you have time to decide whether the money should be used, moved, or reinvested.

    Beginner Tip

    Do not force every dollar into the ladder. A separate cash reserve gives you breathing room when an unexpected expense arrives.

    How a CD Ladder Works After Funding

    Once the certificates are funded, the main job shifts from building the ladder to watching how the maturity dates move through time. Each CD follows its own account agreement, while the staggered schedule gives you separate points to review your cash.

    During Each CD Term

    A certificate generally earns interest according to the APY and terms agreed to when you open it. The account may compound interest or pay it according to the institution’s rules. Keep the original disclosures because they show the interest schedule, maturity date, early-withdrawal terms, and other conditions that apply to that specific CD.

    As one certificate approaches maturity, check the bank’s renewal window. You may decide to take the money for a planned expense, move it to another account, or place it into a new CD. The next term does not have to match the previous one. Your choice can reflect current rates and what you expect to need the money for next.

    Illustrative Example: A $30,000 Ladder

    Imagine Jordan has $30,000 set aside for medium- and longer-term goals. The money is divided among several CDs that mature at different times. When the first certificate matures, Jordan needs $6,000 for a planned home expense, so that portion is withdrawn. The remaining funds can stay invested through the other certificates.

    At the next maturity, suppose Jordan no longer needs the cash. After checking the available rates, that amount can be placed into a new CD with a term that extends the ladder. This creates a rolling process: one certificate reaches maturity, a decision is made, and the rest of the ladder continues unchanged.

    Practical check: Review each maturity before the renewal deadline. That small habit gives you time to compare the new rate, term, and your current cash needs.

    Benefits and Drawbacks of a CD Ladder

    A ladder can make a large cash balance easier to organize by giving different portions of the money their own maturity dates. That structure can be useful, but it does not remove the trade-offs that come with putting money into CDs.

    Pros

    • Planned access: Staggered maturities can create regular opportunities to use or reposition part of your savings.
    • Rate diversification: Your entire balance does not have to be committed at one rate or on one opening date.
    • Reinvestment flexibility: Each maturity gives you a chance to review available rates and your plans.
    • Saving discipline: Fixed terms can make it easier to leave money untouched for longer-term goals.

    Cons

    • Reduced liquidity: Money in a CD generally is not as accessible as cash held in a checking or savings account.
    • Early-withdrawal penalties: Taking funds out before maturity may reduce your return under the CD’s terms.
    • Changing rates: New CD rates may rise or fall while your existing certificates remain locked at their agreed rates.
    • Inflation: A fixed return may not fully preserve purchasing power if prices rise faster than the CD’s return.
    • More tracking: Multiple certificates mean more maturity dates, renewal decisions, and account details to monitor.

    Worth remembering: A ladder works best when its structure solves a real planning problem. If managing several maturity dates adds more work than value, a simpler CD or flexible savings account may be a better fit.

    CD Ladder Designs Compared

    The number of rungs changes how often money becomes available and how much information you need to track. A smaller structure can be easier to manage, while additional certificates can create more maturity points. The goal is to give each rung a useful job rather than adding CDs simply to make the ladder larger.

    DesignMaturity SpreadFlexibilityTrackingMay Suit
    3-rungThree planned datesBasicLowSimple goals and smaller balances
    4-rungFour staggered datesModerateModerateBalanced planning
    5-rungFive maturity pointsHigherHigherLarger balances or several goals
    Longer-term ladderMay extend several yearsGoal-dependentModerate to highLonger-term savings goals

    Your terms do not have to follow a rigid formula. For example, someone expecting a need within a year could include a
    6-month CD
    alongside a
    1-year CD.
    A longer goal might justify reviewing
    2-year CD options
    or
    3-year CD options.
    Compare the maturity dates alongside the rates rather than treating the highest APY as the automatic winner.

    CD Ladder Costs, Risks and Expert Tips

    The biggest risks in a CD ladder often appear after the accounts are opened. A certificate can look attractive at the time of purchase, yet its rules may become inconvenient if your cash needs change or market conditions move in another direction.

    Watch the Cost of Early Access

    Most traditional CDs can charge an early-withdrawal penalty when money is taken out before maturity. The amount and calculation depend on the account agreement. If you expect a possible near-term expense, compare the cost of keeping that money liquid with the return you expect from the CD.
    Learn how CD early withdrawals work
    before committing funds.

    Consider What You Give Up

    A fixed rate can become less attractive if newly available CD rates rise. That is an opportunity cost rather than a direct fee. Inflation can create another concern because the purchasing power of a fixed return may decline over time.

    Check Taxes and Deposit Insurance

    Interest earned by CDs in a regular taxable account is generally taxable interest income. Also verify that your deposits remain within applicable insurance limits. Bank deposits may qualify for FDIC coverage, while qualifying federally insured credit-union share accounts may receive NCUA coverage. Coverage depends on factors such as the institution, ownership category, and total eligible deposits or shares.

    Review Before Every Renewal

    Do not treat automatic renewal as a final decision. Before maturity, check the new APY, term, penalty, and your current plans. A CD that made sense last year may not deserve another term today.

    Expert Tip

    Keep a one-page CD record with each balance, APY, maturity date, withdrawal penalty, insurance status, and renewal instruction. Review it before opening a new CD and again before every maturity.

    Common CD Ladder Mistakes to Avoid

    A ladder can be perfectly sound on paper and still become frustrating if the setup does not match how you actually use your money. Most avoidable problems come from making the structure more complicated than necessary or ignoring what happens after the first CD matures.

    Mistakes That Can Create Problems

    • Opening too many CDs: Extra rungs can create more maturity dates without adding meaningful value.
    • Chasing the highest APY: A higher rate is not necessarily better if its maturity date clashes with a known cash need.
    • Creating awkward maturity dates: A schedule that looks neat on paper may be inconvenient if several certificates mature around the wrong time.
    • Unequal allocations without a purpose: Different deposit amounts can make sense for different goals, but random amounts can make future planning harder.
    • Forgetting renewal dates: Missing a maturity window can lead to an automatic renewal you did not intend.
    • Putting emergency cash into CDs: Money needed for an unexpected expense should remain readily accessible rather than depending on a maturity date.

    Illustrative Example: Marcus Simplifies His Ladder

    Marcus has $24,000 available for longer-term savings. He initially opens six CDs because he wants frequent maturity dates. After a few months, he realizes that tracking six accounts is unnecessary and that most of his expected expenses occur only twice a year. He simplifies the structure and keeps his emergency reserve separate.

    The lesson: A ladder should reduce friction around your savings. If the number of certificates makes the plan harder to follow without providing useful access, fewer rungs may be the smarter choice.

    Who Should Build a CD Ladder?

    A ladder can be a good fit when your savings have several future uses and you are comfortable leaving each portion untouched until its maturity. It is less about having a large balance and more about having a reason to spread your money across different time periods.

    It May Make Sense If You:

    • Are buying CDs for the first time: Staggering maturities can make a large commitment feel more manageable.
    • Have planned family expenses: Maturity dates can be matched with tuition, home projects, or other known costs.
    • Are retired: A staggered schedule can create planned opportunities to review or use portions of savings.
    • Hold a larger cash balance: Multiple certificates can help organize money across different time horizons.
    • Prefer predictable returns: Fixed CD terms may appeal to conservative savers who value knowing the agreed rate.
    • Can leave the money untouched: The strategy works best when early access is unlikely.

    Keep it simple when appropriate: If you have one clear maturity goal, a single CD may be enough. If you need frequent access or your plans are still changing, a flexible savings account may be more practical.

    Frequently Asked Questions About CD Ladders

    What is a CD ladder?

    A CD ladder spreads money across multiple certificates with different maturity dates. As each certificate matures, you can use the funds, move them, or consider reinvesting them.

    How many CDs should I use in a ladder?

    There is no fixed number. Use enough certificates to create useful maturity dates without making the account structure difficult to track.

    Do CD ladders have minimum deposit requirements?

    Each bank or credit union sets its own minimum. Check the requirements for every certificate before dividing your money so the planned amounts qualify.

    How should I choose CD maturity dates?

    Look at when you may need portions of the money and choose terms that create practical dates. A maturity schedule should fit your plans rather than simply follow a standard formula.

    What happens when a CD in the ladder matures?

    You can generally take the money, transfer it, or reinvest it after reviewing your current needs and available rates. Check the renewal instructions before maturity.

    Can a CD ladder provide immediate access to my money?

    No. A ladder creates planned access points, but it does not provide the same on-demand access as a checking or savings account. Keep emergency cash separate.

    Can CD rates change while my ladder is running?

    Yes. Rates offered on new CDs can change while existing certificates continue under their agreed terms. Each maturity gives you an opportunity to review the current choices.

    Are CD ladders covered by FDIC or NCUA insurance?

    Eligible bank deposits may qualify for FDIC insurance, while qualifying federally insured credit-union share accounts may receive NCUA coverage. Applicable limits and ownership categories matter.

    Are CD ladder earnings taxable?

    Interest from CDs held in a regular taxable account is generally taxable interest income. Tax treatment may differ when CDs are held through certain tax-advantaged accounts.

    Illustrative: How could a $50,000 balance be divided into a CD ladder?

    Illustrative example only: A saver might divide $50,000 among four or five CDs, using different amounts and maturity dates to match expected cash needs. The actual allocation should reflect available rates, account minimums, liquidity needs, and applicable insurance limits.

    Final Verdict: Is a CD Ladder Right for You?

    A CD ladder can be a smart way to organize money when you have several future cash needs and do not want the entire balance tied to one maturity date. It gives you planned opportunities to review portions of your savings instead of making one large commitment.

    The key is to build around your expected cash needs rather than chasing the highest APY. A certificate with a slightly better rate may not be useful if its maturity date arrives at the wrong time. Look at the timing first, then compare rates and account terms.

    Keep emergency savings, upcoming bills, and money that may be needed unexpectedly outside the ladder. If you want a broader refresher on CD terms, rates, safety, and account features, read our

    CD Guide 2026
    .

    Practical takeaway: Choose the maturity schedule first, then choose the CDs that fit it.

    Build Your Next CD Ladder With Confidence

    Your CD ladder does not need to be complicated. Keep the maturity dates useful, leave emergency cash accessible, and review each certificate before it renews. For more practical guides on CDs, saving, and investing, join the FinanceInvestment newsletter.

    📧 subhashr325@gmail.com
  • CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?

    CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?

    FINANCEINVESTMENT • CD STRATEGIES 2026

    CD Ladder vs CD Barbell Strategy: Which One Fits Your Goals?

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August 25, 2026
    About 10–12 min read

    Compare two practical ways to spread CD maturities, balance liquidity, and manage rate risk without making your cash strategy unnecessarily complicated.

    CD Ladder vs CD Barbell Strategy: Which Is Better in 2026?
    CD Ladder vs CD Barbell Strategy explained for 2026. Compare maturity schedules, liquidity, rate risk, flexibility, and which strategy may fit your goals.
    cd-ladder-vs-cd-barbell-strategy
    CD Ladder vs CD Barbell Strategy
    CD ladder strategy,
    CD barbell strategy,
    CD ladder vs barbell,
    ladder vs barbell CDs,
    CD laddering,
    barbell CD strategy,
    CD investment strategy,
    CD maturity strategy,
    CD liquidity strategy,
    CD rate risk
    https://financeinvestment.site/cd-ladder-vs-cd-barbell-strategy/
    Subhash Rukade
    August 24, 2026
    About 10–12 minutes

    CD Ladder vs CD Barbell Strategy: Start With Your Cash Timeline

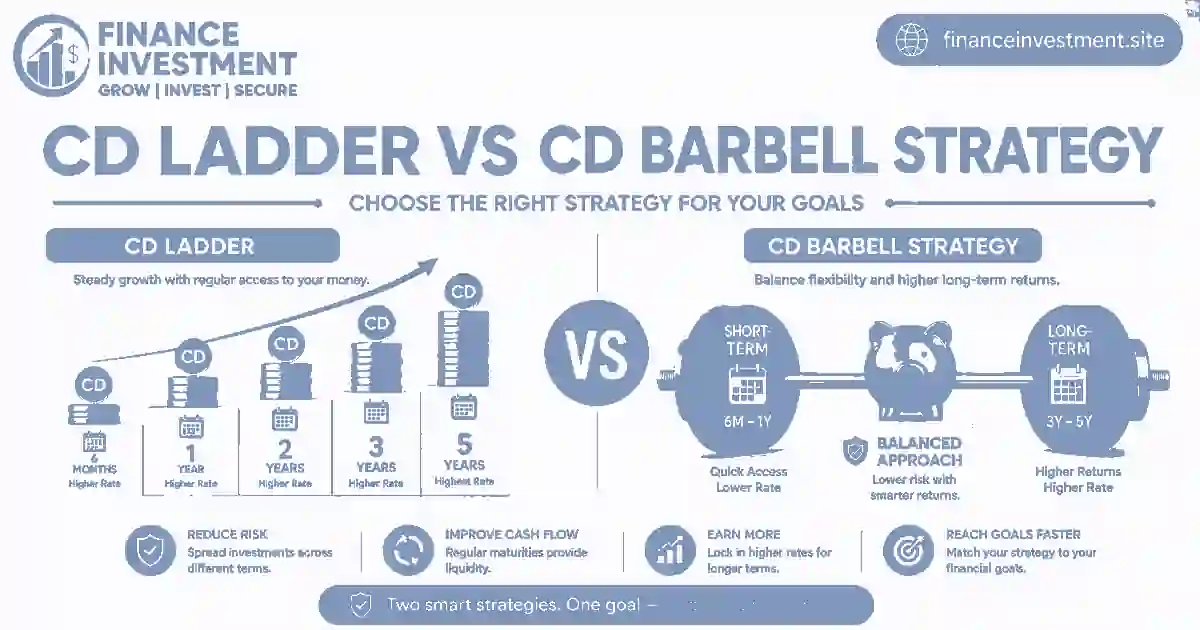
    CD Ladder vs CD Barbell StrategyWhen people compare a CD Ladder vs CD Barbell Strategy, they often start by asking which one earns more. That can miss the bigger issue. The more useful question is when you expect to need the money again. A strategy that works beautifully for someone with several upcoming expenses may feel restrictive to someone who mainly wants access to cash at the short and long ends of the timeline.

    A CD ladder spreads money across several maturity dates. That creates a steady stream of opportunities to reassess or use funds. A barbell takes a different route. It typically places money toward shorter and longer maturities while leaving less in the middle.

    Neither structure automatically wins. Your expected cash needs, comfort with locking money away, views on future rates, and desire for regular access can point you toward one design over the other. The goal is to build a schedule that makes sense for your money instead of forcing your money into a preset formula.

    If you want to refresh the basics before comparing these strategies, our

    CD Guide 2026

    explains CD basics, terms, rates, and the details worth checking before you choose an account.

    What You’ll Learn

    • How CD ladders and barbells are structured
    • Where each strategy can fit different cash needs
    • How maturity timing affects liquidity
    • The trade-offs involving rates and reinvestment
    • How to choose a structure without overcomplicating your savings plan

    Quick Answer: CD Ladder or CD Barbell?

    A CD ladder generally spreads money across multiple maturity dates, while a CD barbell concentrates more of the money in shorter and longer terms, with less in the middle. A ladder can offer more regular access points; a barbell can keep some cash relatively near-term while committing another portion for longer.

    6 Key Takeaways

    1. Ladder: Several CDs mature at different points.
    2. Barbell: Money is concentrated toward short and long maturities.
    3. Liquidity: A ladder can create more frequent maturity dates.
    4. Rate exposure: A barbell can give you both shorter-term flexibility and longer-term rate certainty.
    5. Cash needs matter: Upcoming expenses can influence which structure makes more sense.
    6. There is no universal winner: The better setup is the one that matches your timeline and comfort with locked-up money.

    Bottom line: A ladder is useful when you want several planned maturity dates. A barbell may fit better when you want a short-term pool alongside a longer commitment.

    CD Ladder vs CD Barbell: At a Glance

    The two structures differ mainly in where your maturity dates sit. A ladder usually creates a sequence of scheduled maturities, while a barbell places more weight at the short and long ends. That difference can affect how often you can access cash and how much of the portfolio is committed for longer periods.

    FeatureCD LadderCD Barbell
    Typical structureSeveral staggered maturitiesShort and long maturities
    Liquidity patternMore frequent maturity pointsMore concentrated access
    Rate exposureSpread across maturitiesShort and long rate exposure
    May suitSavers wanting scheduled access pointsSavers comfortable pairing near-term access with longer commitments

    Quick read: A ladder emphasizes a sequence of maturity dates. A barbell emphasizes separation between the short and long ends. The real difference is how each structure distributes your maturity dates and future decisions.

    How to Build a CD Ladder or Barbell From Scratch

    Building either strategy starts with the same basic question: how much money can you commit without needing it unexpectedly? Once that amount is clear, the structure becomes easier to design. Keep your emergency reserve and near-term spending money outside the CDs first. The remaining cash can then be divided according to your timeline.

    Building a CD Ladder

    A simple ladder divides your deposit among certificates with different maturity dates. For example, someone with $20,000 might place $5,000 into four CDs with staggered terms. As each certificate matures, the owner can use the money or reinvest it into a new longer-term CD.

    The exact terms do not have to follow one fixed formula. You might use six-month, one-year, 18-month, and two-year certificates, depending on available rates and when you expect to need the cash. Pick maturity dates that match real expenses or review points instead of filling every available term.

    Building a CD Barbell

    A barbell uses two ends of the maturity spectrum. One portion can sit in shorter CDs for relatively earlier access, while another portion can use longer certificates for a longer rate commitment. There is no universal percentage split. Your spending needs and tolerance for locking money away should guide the allocation.

    Plan the Reinvestment Before Maturity

    Decide in advance what you might do when a certificate matures. If you need the cash, move it to the account where you will spend it. If you still have a long-term need, consider reinvesting after checking current rates. Avoid automatic renewal simply because it is convenient.

    Practical Tip

    Keep a simple maturity calendar. Knowing which CD matures next can be more useful than trying to remember every account detail.

    How a CD Ladder and Barbell Work Over Time

    CD Ladder vs CD Barbell StrategyThe main difference becomes clearer once the certificates are actually in place. You are not simply choosing several CDs; you are creating a schedule for when portions of your money become available and when you will decide what to do next.
    How a CD Ladder Moves

    Imagine you divide $24,000 into four $6,000 CDs. You could choose terms that mature at different points, such as six months, one year, 18 months, and two years. When the first CD matures, you can take the money for a planned expense or reinvest it into a new certificate. The other CDs continue following their original schedules.

    You can compare the current CD market, check whether your original goal has changed, and decide whether that slice of money still belongs in another CD. That gives the strategy a built-in review point instead of requiring you to commit the entire balance at one time.

    How a CD Barbell Moves

    Now consider a $24,000 barbell. You might place $8,000 in shorter-term CDs and $16,000 in a longer-term certificate. The short side can provide an earlier opportunity to access or reposition part of the money, while the longer side remains committed for a longer period.

    The two sides do not have to be equal. A saver expecting a major expense soon might give more weight to the short end. Someone comfortable leaving most of the money untouched could place more toward the longer end.

    Illustrative example: Mark expects to need some cash within a year but wants another portion working for several years. A barbell may give him two distinct time horizons, while a ladder would spread those maturities more evenly.

    In both structures, the important work happens when a CD matures. That is when you reassess the rate, timing, and purpose of that portion of the money rather than automatically repeating the old decision.

    Benefits and Drawbacks of CD Ladders and Barbells

    The appeal of these strategies comes from giving each portion of your cash a different place on the calendar. That can make a large balance easier to organize, but the structure also creates trade-offs you should understand before committing the money.

    ✓ Pros

    • Planned access: A ladder can create regular maturity dates, giving you more opportunities to use or reposition cash.
    • Rate diversification: Different maturity dates can reduce the need to commit the entire balance at one rate.
    • Reinvestment choices: Each maturity gives you a chance to compare current rates before putting the money back to work.
    • Flexible structure: A barbell can pair shorter commitments with longer ones instead of spreading money evenly.

    ⚠ Cons

    • Timing risk: A maturity date may not arrive when you actually need the money.
    • Concentration: A barbell can leave a larger share committed at one end of the maturity range.
    • Inflation risk: Fixed CD returns may lose purchasing power when prices rise faster than the account’s return.
    • Reinvestment risk: A maturing CD may need to be renewed when available rates are lower.

    That timing control is useful only if your cash outside the CDs is large enough to handle unexpected expenses.

    CD Ladder vs CD Barbell: Side-by-Side Comparison

    Once you move beyond the basic definitions, the choice comes down to how much control you want over maturity dates and where you want your rate exposure. A ladder spreads decisions across time, while a barbell creates a sharper split between shorter and longer commitments.

    FactorCD LadderCD Barbell
    StructureMoney is divided across several maturity dates.Money is concentrated around shorter and longer terms.
    LiquidityCan create more frequent maturityAccess is generally concentrated in the shorter-term portion.
    Maturity spreadBroad and staggered.Focused at two ends.
    ReinvestmentDecisions occur more regularly.Fewer, more concentrated decisions.
    ComplexityCan require tracking several CDs.Can be simpler to maintain.
    May suitSavers who value recurring maturity dates.Savers who want a short-term pool alongside longer commitments.

    The strategy can also be adjusted around the available products. For example, you could review
    6-month CD rates
    for the shorter side and compare them with
    5-year CD rates
    for a longer commitment. If you are unsure which term fits your cash needs, our guide on
    choosing the right CD
    can help frame the decision.

    Neither structure guarantees a better return. The useful comparison is how well each one fits your expected cash flow, tolerance for locked-up funds, and willingness to revisit rates over time.

    Costs, Risks and Expert Tips for CD Ladders and Barbells

    A well-planned CD structure can make your cash easier to manage, but it cannot remove the normal risks of certificates. The biggest issues usually appear when your circumstances change, rates move, or a maturity date arrives at an inconvenient time.

    Risks to Check Before Funding

    Early withdrawal penalties can reduce your interest if you need money before a CD matures. That matters in both strategies, especially if the amount at a particular maturity is smaller than the expense you eventually face.

    Opportunity cost matters when rates change. A long-term CD can keep earning its agreed rate while newer certificates become more attractive. On the other hand, short-term CDs may mature when available rates are lower. Inflation can also reduce the purchasing power of a fixed return.

    Insurance and taxes deserve a separate check. Check that eligible deposits are within applicable FDIC or NCUA coverage limits, including the relevant ownership category and institution. particularly when several CDs are held at the same institution. Interest from taxable CDs can also affect your tax bill and after-tax return.

    Expert Checks Before You Build or Renew

    Premium Expert Tip

    Write down every CD’s balance, APY, maturity date, penalty, ownership category, and renewal instructions. Then review the schedule as a whole. Several CDs can end up maturing close together, while a barbell can leave a large share of the balance tied to the long end.

    Before renewing, compare the new rate with current offers and ask whether the original cash plan still applies. Also check whether you still need the same balance at each maturity. A strategy should be adjusted when your financial timeline changes.

    Finally, keep emergency cash outside the certificates. A ladder or barbell works best when you are not forced to break a CD simply because an unexpected bill arrives.

    Common CD Ladder and Barbell Mistakes

    The trouble usually starts with the details: too many CDs, poorly spaced maturities, or money that should never have been locked up. The most common errors are usually not about picking a particular bank. They come from building a schedule that does not match the way the money will actually be used.

    Mistakes to Watch For

    • Making the structure too complicated: A ladder with too many small certificates can become difficult to track. If the added complexity does not create useful maturity dates, simplify it.
    • Clustering maturities: Several CDs that mature within the same narrow period may leave you with less flexibility than expected.
    • Using emergency cash: Money that may be needed immediately should not depend on a CD reaching maturity.
    • Ignoring renewal dates: A certificate can automatically renew according to its terms if you do not act during the applicable window.
    • Chasing rates: Moving money repeatedly for a slightly higher APY can add unnecessary work and may leave the maturity schedule disconnected from your goals.

    Illustrative Example: David Simplifies His Ladder

    David initially creates six small CDs because he wants frequent maturity dates. After reviewing the accounts, he realizes two mature within the same month and several balances are too small to make the extra tracking worthwhile. He consolidates his plan around fewer, more useful maturity points while keeping his emergency savings separate.

    Illustrative lesson: A useful CD strategy does not need to be complicated. The schedule should make your cash easier to manage, not create another chore.

    Before adding another certificate, look at the entire schedule rather than evaluating the new CD by itself. That simple habit can reveal gaps, clusters, and unnecessary commitments.

    Who Should Choose a CD Ladder or Barbell?

    A CD ladder may appeal to savers who want several planned points when money becomes available. It can work well for families with expenses spread across the year, retirees who want periodic access to part of their cash, or investors who prefer making smaller reinvestment decisions over time.

    A ladder tends to make sense for savers who want several planned maturity dates. keeping part of the money relatively accessible while committing another portion for a longer period. It can be useful when near-term liquidity and longer-term rate certainty both matter.

    Neither structure is necessary for every saver. If the balance is modest or the goal has one clear date, a single CD may be easier to manage. And if you may need the money without warning, a flexible savings account can be a better home for that cash.

    Quick Decision Guide

    • Want recurring maturity dates? Consider a ladder.
    • Need short and long commitments? Consider a barbell.
    • Have one clear cash date? A single CD may be enough.
    • Need immediate access? Keep the money flexible.

    Frequently Asked Questions About CD Ladders and Barbells

    What is the main difference between a CD ladder and a CD barbell?

    A ladder distributes money across a series of maturity dates, while a barbell puts greater weight on shorter and longer terms. The choice mainly changes how your cash becomes available over time.

    How many CDs do I need to build a CD ladder?

    There is no fixed number. A few certificates can create useful maturity dates, while a larger balance may support more steps. Keep the structure simple enough to track.

    Does a CD ladder provide more liquidity than a barbell?

    A ladder can create more maturity points, but that does not mean the money is available on demand. A CD generally remains subject to its terms until maturity.

    Which strategy has more rate risk?

    Both have rate exposure in different ways. A ladder spreads renewal decisions across time, while a barbell can leave more money committed at the long end.

    What happens when a CD in a ladder matures?

    You can generally use the money, move it elsewhere, or reinvest it after reviewing current rates and your financial needs.

    Can I change a CD ladder after I build it?

    Yes. As certificates mature, you can change the next term or amount rather than rebuilding the entire structure from scratch.

    Do CD ladders and barbells require a minimum deposit?

    Each bank or credit union sets its own CD minimums. Building a strategy with several certificates may require enough money to meet those minimums comfortably.

    Are CDs in a ladder or barbell federally insured?

    Eligible bank CDs may receive FDIC insurance, while qualifying credit-union share certificates may receive NCUA federal share insurance. Coverage limits and ownership categories apply.

    Are CD ladder and barbell earnings taxable?

    Interest from CDs held in a regular taxable account is generally taxable interest income. Your actual tax treatment depends on your circumstances and account type.

    Illustrative: Which strategy could fit a $30,000 balance?

    Illustrative comparison only: A saver could divide $30,000 among several maturity dates for a ladder or place more toward short and long terms for a barbell. The better structure depends on when the saver expects to need the money, not simply the balance size.

    Final Verdict: Which CD Strategy Makes More Sense?

    Choose a ladder if your main priority is having several planned maturity dates. Choose a barbell if your money has two different time horizons and you want a shorter-term portion alongside longer-term CDs. A ladder makes more sense when you want several maturity dates and prefer to spread your cash decisions across time. A barbell can be useful when you have two clear priorities: keeping one portion relatively near-term while giving another portion a longer runway.

    The key is to build around your expected cash needs rather than choosing a structure simply because it looks attractive on a rate table. A higher APY can lose its appeal if the money becomes unavailable when you need it, or if a maturity schedule creates more management work than you want.

    If you want to review CD basics, terms, safety considerations, and rate factors before choosing a structure, see our

    CD Guide 2026
    .

    Practical takeaway: Map out when you may need the money first. Then choose the CD structure that gives those dollars the right maturity dates.

    Build a CD Strategy That Fits Your Timeline

    A useful CD strategy starts with your cash needs, not with a complicated formula. Start with when you may need the money, then choose a structure that makes those dates easier to manage. For practical finance guides and new money insights, join our newsletter.

    📧 subhashr325@gmail.com

  • Common CD Mistakes Beginners Should Avoid: 2026 Guide

    Common CD Mistakes Beginners Should Avoid: 2026 Guide

    FINANCEINVESTMENT • CD GUIDE 2026

    Common CD Mistakes Beginners Should Avoid

    SR
    Written by Subhash Rukade
    FinanceInvestment
    Updated August 25, 2026
    About 10–12 min read

    A practical look at the small CD decisions that can become expensive surprises later.

    Common CD Mistakes Beginners Should Avoid: Smart 2026 Guide
    Learn the common CD mistakes beginners should avoid, from choosing the wrong term to ignoring penalties, insurance, taxes, and automatic renewal.
    common-cd-mistakes-beginners-should-avoid
    Common CD Mistakes Beginners Should Avoid
    common CD mistakes,
    CD mistakes for beginners,
    CD investing mistakes,
    mistakes to avoid with CDs,
    certificate of deposit mistakes,
    CD early withdrawal penalty,
    CD maturity mistakes,
    CD renewal mistakes,
    CD ladder mistakes,
    CD safety mistakes
    https://financeinvestment.site/common-cd-mistakes-beginners-should-avoid/
    Subhash Rukade
    August 24, 2026
    About 10–12 minutes

    Common CD Mistakes Beginners Should Avoid Before Opening an Account

    Common CD Mistakes Beginners Should AvoidMany first-time CD buyers start with one question: What is the highest APY I can get? A good rate matters, but it should come after you know what the money is for and when you may need it. Some of the costliest CD mistakes happen before the account is opened—when you choose money that may be needed soon, pick a term that does not match your plans, or overlook an important account rule.

    A CD works best when the money has a clear job. Cash reserved for an emergency, an upcoming bill, or an uncertain expense may need more flexibility. On the other hand, money you can comfortably leave untouched may be a better candidate for a fixed-term certificate.

    The account’s fine print can change the picture. Minimum deposits, early-withdrawal penalties, renewal rules, insurance coverage, interest payments, and tax treatment can all affect the real value of the account. A higher advertised rate does not automatically make one CD better than another.

    If you want to understand how CDs fit together before comparing individual accounts, start with ourour CD Guide 2026 explains the basics before you compare specific certificates.

    What You’ll Learn

    • The mistakes beginners most often make with CDs
    • How to match the CD with your money and timeline
    • Which fees, penalties, and account rules deserve attention
    • Why APY should not be your only comparison point
    • How to make a cleaner decision before depositing your money

    Quick Answer: Which CD Mistakes Matter Most?

    The biggest beginner mistakes are usually simple: choosing a CD only for its APY, locking up money that may be needed soon, overlooking early-withdrawal penalties, skipping insurance checks, and failing to review what happens at maturity.

    6 Key Takeaways

    1. Look beyond APY: Compare the term, access rules, minimum deposit, and overall fit.
    2. Protect liquidity: Keep emergency money readily accessible instead of committing it to a standard CD.
    3. Read the penalty rules: Know what could happen if you withdraw before maturity.
    4. Check insurance: Confirm that the bank or credit union has the appropriate federal deposit or share insurance.
    5. Watch automatic renewal: A certificate may renew if you do not give instructions during the applicable grace period.
    6. Review taxes and interest: The advertised APY is not necessarily the amount you keep after taxes.

    Bottom line: A good CD decision is about more than chasing the highest rate. Look for a CD that fits your timeline, keeps your needed cash accessible, and has rules you understand before you fund it.

    At a Glance: CD Mistakes to Watch For

    Common CD Mistakes Beginners Should AvoidMost beginner mistakes can be caught with a quick review before you deposit the money. Before funding a certificate, check the term, withdrawal rules, insurance status, renewal instructions, and tax treatment. These details can matter more than a small difference in APY.
    Potential MistakeWhat to CheckWhy It Matters
    Chasing APYTerm and accessA higher rate may come with less flexibility
    Ignoring penaltiesEarly-withdrawal policyEarly access may reduce your return
    Skipping insurance checksFDIC or NCUA coverageConfirms applicable federal protection
    Forgetting renewalMaturity and grace periodYou may miss the chance to reassess your money

    A few minutes of checking the terms can save you from an unpleasant surprise later.

    Complete Beginner Guide to Choosing a CD

    Before opening a CD, think of it as a fixed agreement with rules you will need to follow until maturity. Before moving money, take a few minutes to understand what you are agreeing to. This simple review can help you avoid several common CD mistakes before they become expensive.

    1. Start With the Money You Are Using

    First, identify the purpose of the cash. Money needed for rent, an upcoming bill, or emergencies may not belong in a standard CD. Use funds that you can reasonably leave untouched for the selected term. If you are saving for a known near-term goal, a shorter certificate may be more appropriate.

    2. Check the Term and Minimum Deposit

    Look at the exact term, not just the advertised APY. A longer commitment may limit access for a longer period. Also check the minimum opening deposit. Some certificates accept small amounts, while others require substantially more. Our guide to how much money you need to open a CD can help with this part.

    3. Compare the APY With the Rules

    APY matters, but it should be viewed alongside the term, interest-payment schedule, and withdrawal conditions. A slightly lower rate may be more useful if the account gives you terms that better match your plans.

    4. Read the Early-Withdrawal Terms

    Find out how the penalty works before depositing the money. Some institutions calculate the charge using a set number of months of interest. The exact formula varies, so read the certificate disclosure rather than assuming every CD follows the same rule.

    5. Verify Insurance, Taxes, and Renewal Rules

    Confirm applicable FDIC insurance for a bank CD or NCUA share insurance for an eligible credit-union certificate. Also understand how interest may be reported for tax purposes. Finally, check whether the CD automatically renews and how long the grace period lasts.

    If all of these details fit your plan, you are in a much stronger position to choose a certificate without letting one attractive number make the decision for you.

    How a CD Works From Opening to Maturity

    Once you decide to open a certificate, the process is fairly straightforward. The important part is understanding what happens after the money leaves your regular account. A CD follows a defined timeline, so each stage has a specific purpose.

    Opening and Funding

    You apply through the bank or credit union, select the available certificate, and provide the required information. After approval, you fund the account with the amount you choose, subject to the institution’s minimum. The opening confirmation should show the principal, APY, term, maturity date, and other applicable conditions.

    During the CD Term

    The deposited money remains in the certificate while interest accrues according to its terms. Depending on the product, interest may compound inside the account or be paid according to a stated schedule. You normally do not need to manage the CD day to day, but keep the account documents available for reference.

    Approaching Maturity

    The maturity date is when the original term ends. The institution may send a notice explaining your options. You may be able to withdraw the funds, move them elsewhere, or renew the certificate. If automatic renewal applies, check the new rate and term before the grace period expires.

    Illustrative Example

    Elena opens a 12-month CD with $7,500. Her confirmation shows the agreed APY and maturity date. Several weeks before maturity, she reviews the renewal notice. Because she expects to use part of the money for a planned expense, she chooses not to let the entire balance automatically move into another CD.

    This simple timeline shows why reading the maturity notice matters just as much as opening the account correctly.

    Benefits and Drawbacks of Avoiding CD Mistakes

    Choosing the CD carefully can make the account easier to live with once the money is locked in. Still, even a well-chosen certificate has trade-offs. Knowing both sides helps you decide whether a CD belongs in your cash plan.

    ✓ Pros

    • Fewer surprises: Understanding the rules before opening the account makes the term easier to manage.
    • Better planning: A suitable maturity date can keep goal-specific money organized.
    • Rate certainty: A fixed-rate certificate can keep its stated rate during the agreed term.
    • More disciplined saving: Limited access can discourage unnecessary spending.

    ⚠ Cons

    • Reduced liquidity: Accessing money early can be less convenient than using a savings account.
    • Potential penalties: Early withdrawal may reduce the return under the certificate’s terms.
    • Inflation and taxes: The purchasing power and after-tax value of interest can be lower than the headline APY suggests.
    • Renewal risk: A new CD may offer a different rate when the original one matures.

    CD Mistake Comparison: The Shortcut vs. the Smarter Move

    A few choices made before funding can make a big difference later.. This comparison shows what a common shortcut looks like and what a more careful approach can look like instead.

    Common ShortcutPossible ProblemSmarter Move
    Chasing the highest APYThe term may not fit your plans.Compare APY with term, access, and account rules.
    Choosing the wrong termYou may need the money before maturity.Match the maturity date to your expected cash need.
    Ignoring early withdrawalA penalty can reduce your return.Read the withdrawal terms before depositing.
    Skipping insurance checksYou may misunderstand available federal protection.Verify applicable FDIC or NCUA coverage.
    Forgetting automatic renewalYour money may roll into a new term.Review maturity instructions and the grace period.
    Ignoring tax treatmentYour after-tax return may be lower than expected.Consider taxes when comparing the actual value of the CD.

    The goal is not to eliminate every trade-off. It is to make sure the certificate you choose matches the purpose of your money and the rules you are comfortable accepting.

    Costs, Risks and Expert Tips for Avoiding CD Mistakes

    A CD mistake does not always show up as an obvious fee. Sometimes the cost is lost flexibility, a missed opportunity, or a lower return than you expected. Looking at these risks before opening or renewing a certificate can make the decision much cleaner.

    Where the Financial Costs Can Appear

    Early withdrawal is one of the clearest risks. If you need the money before maturity, the institution may impose a penalty under the CD’s terms. That can reduce the interest you keep and may make the original APY less meaningful.

    There is also an opportunity cost. If market rates rise after you lock in a certificate, your money may continue earning the older rate until maturity. Inflation creates another concern because a fixed return may not keep pace with rising prices.

    Taxes can further reduce the amount you keep from interest earned in a taxable account. Also check insurance limits when placing a large balance with one institution. Federal deposit or share insurance has coverage rules, so do not assume every dollar is automatically protected.

    Expert Checks Before You Commit

    Premium Expert Tip

    Before funding a CD, write down five things: the APY, maturity date, early-withdrawal penalty, insurance coverage, and renewal terms. Before renewal, run the same check again. Your circumstances and available rates may have changed.

    Renewal deserves particular attention. A CD that made sense a year ago may not be the best place for the money today. Compare the new rate with current alternatives and ask whether you still need the same level of commitment.

    The simplest way to avoid these costs is to read the terms before funding the CD and review the account again before renewal.

    Common CD Mistakes and a Real-Life Example

    Not every CD mistake involves the interest rate. Beginners can also run into trouble by putting too much money into one certificate, misunderstanding how ownership affects insurance coverage, or simply missing an important maturity notice.

    Mistakes That Deserve Extra Attention

    • Overfunding one CD: Putting a large share of your cash into one certificate can leave too little money available for unexpected needs.
    • Ignoring account ownership: Deposit-insurance coverage can depend on how accounts are owned and how much is held within the applicable coverage categories. Do not assume separate account numbers automatically mean separate coverage.
    • Missing the maturity notice: A renewal window can be limited. If you do not review the notice, the CD may renew under the institution’s stated terms.
    • Misunderstanding interest payments: Interest may compound in the certificate or be paid according to a specific schedule. Read the account disclosure so you know when and where interest is credited.

    Illustrative Example: Sarah Spreads Her Cash

    Sarah has $80,000 available for several future goals. Instead of placing the entire amount into one CD, she keeps part of the money accessible and divides the remainder between certificates with different maturity dates. She also reviews the institution’s insurance information and sets a calendar reminder before each maturity date.

    Illustrative lesson: Sarah’s approach is hypothetical. The point is not that one structure is always best, but that spreading cash and reviewing account rules can reduce the consequences of a single decision.

    A CD should support your cash plan, not become the plan itself. Keeping track of ownership, coverage, interest, and maturity dates can prevent small oversights from turning into larger problems.

    Who Should Pay Special Attention to CD Mistakes?

    First-time buyers have more reason to slow down because CD terms can be unfamiliar at first. Large-balance savers should pay particular attention to deposit-insurance limits and account ownership. Retirees may need to think carefully about access to cash, especially when a CD is part of their regular income plan.

    Families can face similar issues when money is earmarked for tuition, a home purchase, or another known expense. People using several certificates should also keep track of different maturity dates, rates, and renewal instructions. A CD may be less suitable when the money could be needed without warning.

    Quick Decision Guide

    • New to CDs? Start with a manageable amount and understand the terms.
    • Holding a large balance? Review insurance and ownership carefully.
    • Need regular access? Keep enough cash outside the CD.
    • Using several CDs? Track every maturity and renewal date.

    Frequently Asked Questions About CD Mistakes

    What is the biggest mistake beginners make with CDs?

    A frequent mistake is looking at the APY without checking the term and account rules. The term, withdrawal rules, insurance, maturity instructions, and tax treatment also affect whether the CD fits your needs.

    Can you lose money by withdrawing from a CD early?

    You may receive less than the return you expected because the institution can generally charge an early-withdrawal penalty under the CD’s terms. Review the penalty before opening the account.

    Should I choose a CD with the highest APY

    Not necessarily. The highest APY may come with a term or conditions that do not fit your plans.

    How do I know if my CD is federally insured?

    For a bank CD, verify that the institution is FDIC-insured. For an eligible credit-union certificate, check for NCUA federal share insurance. Also consider applicable coverage limits.

    What happens if I forget my CD maturity date?

    The certificate may automatically renew according to its terms. Check the maturity notice and grace period so you have time to decide what to do with the money.

    Is automatic CD renewal a mistake?

    Automatic renewal itself is not necessarily a problem. The issue is letting the CD renew without checking the new rate, term, and your current plans.

    Are CD earnings taxable?

    Interest from a CD held in a regular taxable account is generally taxable as interest income. Your tax situation can affect the return you actually keep.

    Illustrative: What happens if a $10,000 CD earns 4%?

    Illustrative calculation only: At a hypothetical 4% APY for one year, $10,000 could earn approximately $400 under the stated assumptions. Actual earnings depend on the CD’s APY, compounding, and account terms.

    Final Verdict: Avoid the Mistakes That Can Cost You Later

    Avoiding CD mistakes starts with one simple habit: check the terms before moving your money. Do not let an attractive APY make the entire decision for you. The better certificate is the one whose term, access rules, minimum deposit, and maturity date fit your actual plans.

    Before funding a CD, verify the early-withdrawal penalty, applicable FDIC or NCUA insurance, interest-payment details, tax considerations, and automatic-renewal rules. These details may seem small when you open the account, but they can matter considerably if your plans change.

    It is also worth checking the account again when it approaches maturity. A CD that made sense when you opened it may not be the best choice when the term ends.

    For a broader look at certificates, rates, terms, and important account features, explore our

    CD Guide 2026
    .

    Practical takeaway: Read the fine print, protect the cash you may need, and compare the whole CD—not just the rate printed at the top.

    Make Your Next CD Decision With Fewer Surprises

    A good CD decision starts with understanding the rules before your money is committed. If you enjoy practical guides on CDs, saving, and everyday investing, join our newsletter for useful money insights and new guides.

    📧 subhashr325@gmail.com

  • Best 5-Year CD Rates in 2026: Compare 60-Month CDs

    Best 5-Year CD Rates in 2026: Compare 60-Month CDs

    Best 5-Year CD Rates in 2026

    FINANCEINVESTMENT
    Best 5-Year CD Rates in 2026
    Written by Subhash Rukade

    SEO Title: Best 5-Year CD Rates in 2026: Compare 60-Month CDs

    Meta Description: Compare the best 5-year CD rates in 2026, understand 60-month CD terms, APY, penalties, insurance, risks, and long-term savings trade-offs.

    URL Slug: best-5-year-cd-rates-in-2026

    Focus Keyword: Best 5-Year CD Rates in 2026

    Secondary Keywords: 5-year CD rates, best 60-month CD rates, 5-year certificate of deposit rates, 60-month CD, 5-year CD APY, best 5-year CDs

    Canonical URL: https://financeinvestment.site/best-5-year-cd-rates-in-2026/

    Author Name: Subhash Rukade

    Last Updated: August 21, 2026

    Reading Time: About 15 minutes

    Featured Image ALT Text: Best 5-Year CD Rates in 2026

    Why a 5-Year CD Is a Bigger Decision

    Best 5-Year CD Rates in 2026Best 5-Year CD Rates in 2026 can look appealing when you want to lock in a return and leave the money alone. But a 60-month CD asks for something that shorter certificates do not: patience. Five years is long enough for your plans, expenses, and the interest-rate environment to change several times.

    That longer lock can work in your favor if deposit rates fall after you open the account. Your fixed rate may continue through maturity while newer CDs offer less. The other side of the deal is just as important. If rates climb substantially, your money may remain tied to the original rate unless the CD’s terms give you another option.

    That is why choosing a five-year certificate should start with your timeline, not just the headline APY. If the money has a specific long-term purpose and you are comfortable leaving it untouched, the longer term may fit. If you expect to need flexibility, a shorter CD or liquid savings option deserves a closer look.

    For a broader explanation of certificates, terms, strategies, and alternatives, you can explore our Complete CD Guide 2026.

    What You’ll Learn

    • How 60-month CDs work from opening to maturity
    • What to compare beyond the advertised APY
    • How rate changes can affect a five-year decision
    • Early-withdrawal costs, inflation, and other risks
    • When a 5-year CD may fit your financial plan

    Quick Answer: Are 5-Year CDs Worth Considering in 2026?

    Short answer: A 5-year CD can be attractive when you value a long fixed-rate period and are confident you will not need the money for 60 months. Bankrate’s survey showed a 1.75% national average APY for five-year CDs as of August 20, 2026, while its tracked top CD offers reached 4.50%. Individual five-year offers vary, so the headline average is only a starting point.

    6 Key Takeaways

    • Five years is a serious commitment: Only use money that does not have a likely near-term job.
    • The rate can work in your favor: A fixed rate stays in place even if newly offered CD rates fall.
    • Rising rates create opportunity cost: A higher-rate environment could make an older five-year CD less competitive.
    • Early access can be expensive: Check the exact early-withdrawal penalty before opening the account.
    • Insurance matters: Eligible deposits at FDIC-insured banks and eligible shares at federally insured credit unions receive coverage within applicable limits.
    • The right saver needs patience: A five-year CD can fit long-range goals, but someone expecting to need the cash sooner may prefer a shorter term or more liquid account.

    Bottom line: The best 5-year CD is not simply the one with the biggest APY. Look at the rate, penalty, minimum deposit, insurance, and what you expect interest rates and your own cash needs to look like over the next five years.

    At a Glance: 60-Month CDs in 2026

    A five-year CD is built for money you can leave untouched for a long stretch. The term is 60 months, so the details deserve more attention than the headline APY alone. Bankrate’s latest national survey lists the five-year CD average at 1.75% APY as of August 20, 2026. Some individual offers are considerably higher, which makes shopping around especially important.

    Term
    60 months
    National Average
    1.75% APY as of Aug. 20, 2026
    Liquidity
    Generally limited before maturity
    Insurance
    FDIC or NCUA when eligible

    Who Might Consider One?

    A 5-year CD may fit someone saving for a distant goal, building a conservative portion of a larger portfolio, or seeking a fixed rate without having to reinvest every year. It is less suitable for cash that may be needed on short notice.

    Numbers Worth Comparing

    FactorWhat to Check
    APYCompare the actual 60-month offer with other institutions.
    Minimum depositCheck the amount required to open the certificate.
    Early-withdrawal penaltyFind out what accessing the money early could cost.
    Maturity rulesReview the maturity date, grace period, and renewal instructions.
    InsuranceConfirm applicable FDIC or NCUA coverage and limits.

    Rate note: The 1.75% figure is a national average, not a recommendation or a guaranteed offer. Bankrate’s current listings show individual five-year CDs with APYs well above that average, so compare actual products before choosing one.

    Complete Beginner Guide to 60-Month CDs

    Best 5-Year CD Rates in 2026A 60-month CD is a time deposit that keeps your money in the account for five years. You deposit money at a bank or credit union, accept the account’s stated terms, and generally leave the funds there until the certificate reaches maturity. In exchange, a fixed-rate CD can give you a defined return over a much longer period than shorter certificates.
    How the Five-Year Term Works

    The clock starts when the certificate is opened and funded. From that point, the account follows the rate, interest-crediting schedule, withdrawal rules, and other terms in its agreement. The five-year period can be useful for a distant financial goal, but it also means you have fewer opportunities to move the money into a new certificate if market conditions change.

    That makes the maturity date especially important. A 60-month CD is not simply a place to park cash; it is a commitment with a specific finish line.

    APY and Compounding

    APY, or annual percentage yield, helps you compare the earning potential of different deposit accounts because it reflects the effect of compounding. The actual way interest is credited can vary by institution, so check whether earnings are paid monthly, quarterly, annually, or according to another schedule.

    For a basic explanation of the mechanics behind CD rates, see our guide to how CD interest rates work.

    Minimum Deposits Can Vary

    There is no single minimum deposit requirement for every 5-year CD. One institution may accept a relatively small opening deposit, while another may require a larger amount. Don’t stretch your budget just to qualify for a particular offer. The deposit should fit comfortably within the amount you have available for long-term savings.

    FDIC and NCUA Protection

    Eligible CDs at FDIC-insured banks are covered by FDIC deposit insurance. The standard coverage limit is $250,000 per depositor, per insured bank, for each ownership category. CDs are among the deposit products covered by FDIC insurance.

    At a federally insured credit union, a CD may be called a share certificate. The NCUA’s Share Insurance Fund covers eligible share deposits, including share certificates, generally up to $250,000 within the applicable coverage rules.

    What Beginners Should Check First

    • Verify the APY and how long it remains fixed.
    • Check the minimum opening deposit.
    • Read the early-withdrawal penalty carefully.
    • Confirm the institution’s FDIC or NCUA insurance status.
    • Record the maturity date and grace-period rules.
    • Find out whether the CD automatically renews after maturity.

    That last step can save you from an unwanted rollover. When a five-year CD matures, the next rate may be very different from the rate you originally accepted. Give yourself enough time to review the maturity notice and decide whether to withdraw, move, or reinvest the money.

    How a 5-Year CD Works From Day 1 to Maturity

    Once the certificate is funded, the process is mostly hands-off. What matters is knowing what happens during each stage and keeping track of the date when your five-year commitment ends.

    Opening and Funding

    You choose the institution, review the certificate agreement, and transfer the amount you want to deposit. Before confirming the transaction, save the APY, maturity date, early-withdrawal terms, and renewal instructions.

    Years 1 Through 5

    During the 60-month period, interest is credited according to the account’s terms. With a fixed-rate certificate, the agreed rate generally remains unchanged for the original term. You do not need to make monthly contributions to keep the CD active.

    The important difference is what happens outside the account. Deposit rates can move higher or lower while your certificate continues following its original agreement. That makes the five-year timeline useful for planning, but it can also limit your ability to react to new opportunities.

    At Maturity

    After 60 months, the certificate reaches maturity. Depending on the institution, you may withdraw the money, transfer it elsewhere, or renew it into another CD. A grace period may give you a short window to make that choice before automatic renewal takes effect.

    A Simple Five-Year Timeline

    TimeWhat Happens
    Day 1Deposit the money and confirm the rate and maturity date.
    Year 1The CD continues under its original terms while interest is credited.
    Years 2–4The certificate continues toward maturity; changing market rates do not normally change its fixed rate.
    Year 5Review the maturity notice and decide whether to withdraw or reinvest.
    Grace periodIf provided, use the window to give instructions before automatic renewal.

    A good habit is to set a reminder several weeks before maturity. That gives you time to compare current CD options rather than allowing the certificate to renew automatically without reviewing the new terms.

    Benefits and Drawbacks of a 5-Year CD

    A five-year certificate changes the balance between certainty and freedom. The longer term gives a fixed-rate CD more time to deliver the return you agreed to, but it also leaves less room to change direction if your finances or the rate environment shifts.

    Pros

    • Long rate protection: A competitive fixed rate can remain in place for the entire 60-month term, even if new deposit rates decline.
    • Predictable interest: The defined rate and maturity date can make long-range cash planning easier.
    • Potentially attractive yield: Some institutions offer competitive long-term CD rates, although the highest rate is not always attached to the longest term.
    • Less reinvestment work: You do not have to decide every year whether to renew another certificate.

    Cons

    • Five-year opportunity cost: If rates rise substantially, newer CDs could become more attractive while your money remains locked at the original rate.
    • Limited liquidity: Accessing the funds before maturity may come with restrictions or a penalty.
    • Early-withdrawal cost: The penalty can reduce your interest earnings and may make an early exit less appealing.
    • Inflation risk: Your account balance can grow while inflation reduces the purchasing power of that future money.

    The Five-Year Difference

    The biggest advantage of a 60-month CD is also its biggest limitation: time. A rate that looks attractive today has five years to prove whether it was a good choice. If rates decline, the longer lock can look valuable. If rates climb, the same decision can leave you wishing you had more flexibility.

    5-Year CD vs. Other Savings Options

    A 60-month CD sits at the long end of the usual CD range. Comparing it with shorter certificates and a high-yield savings account can show whether the extra years actually fit your plans.

    OptionTermLiquidityUseful For
    6-Month CD6 monthsGenerally higherNear-term goals and frequent rate reviews
    1-Year CD12 monthsModerateGoals roughly a year away
    2-Year CD24 monthsLowerMedium-term savings goals
    3-Year CD36 monthsGenerally lowerLonger planned expenses
    5-Year CD60 monthsGenerally lowestLong-range goals and extended rate protection
    High-Yield SavingsNo fixed termGenerally highestAccessible savings and changing needs

    Choosing the Term That Matches Your Timeline

    If five years feels too long, compare the best 6-month CD rates in 2026 or the best 1-year CD rates in 2026. You can also review the best CD rates in 2026 to compare terms side by side.

    For readers considering a middle ground, the 2026 CD rate forecast can provide useful context when thinking about how much rate flexibility you want to keep.

    Costs, Risks and Expert Tips for a 5-Year CD

    A five-year CD deserves a closer look at the fine print because a small disadvantage can matter for a long time. The rate may be fixed, but your financial circumstances and the broader rate environment can change during those 60 months.

    Early-Withdrawal Costs

    Most traditional CDs charge a penalty when you take money out before maturity. The amount varies by institution and product, so don’t assume every five-year CD uses the same formula. Some penalties can consume a substantial amount of interest, making an early exit costly. 0

    When comparing offers, look for the exact penalty period, whether the penalty can reach your principal, and whether any special withdrawal provisions apply.

    Inflation and Purchasing Power

    A fixed balance can still lose purchasing power. If inflation runs above your CD’s effective return for an extended period, the dollars you receive at maturity may buy less than they do today. Bankrate has also noted that inflation has been putting pressure on the real value of CD returns in 2026.

    The Five-Year Opportunity Cost

    The longer term creates another risk: rates could rise after you lock in. New CDs might become more attractive, but your existing certificate would generally continue under its original terms. That’s the price of having rate certainty for five years.

    Automatic Renewal

    Don’t let maturity sneak up on you. A CD may renew automatically if you don’t give instructions during the applicable grace period. Set a calendar reminder well before maturity so you can compare the new rate with other options.

    Consider a CD Ladder

    A ladder can spread money across different maturity dates rather than placing the entire amount into one five-year certificate. For example, you could divide savings among one-, two-, three-, four-, and five-year CDs. As each certificate matures, you regain access to a portion of the money while maintaining exposure to longer-term rates.

    Expert Tip

    Don’t compare five-year CDs by APY alone. Write down the APY, minimum deposit, early-withdrawal penalty, maturity date, renewal terms, and insurance coverage side by side. A slightly lower rate with better terms can be more useful than a headline rate that comes with restrictions you don’t want.

    Common 5-Year CD Mistakes + A Real-Life Example

    A five-year CD can look simple on the surface, but the longest terms leave more room for a small decision to become a costly one. Here are the mistakes worth catching before you deposit your money.

    Chasing the APY Without Reading the Terms

    A slightly higher rate can grab your attention, but check the minimum deposit, withdrawal penalty, compounding details, and renewal policy before choosing the account. A higher APY is not automatically the better deal.

    Putting Emergency Money Into a 5-Year CD

    Money you may need for an unexpected expense should not normally depend on a five-year maturity date. Keep short-term cash accessible instead of relying on an early CD withdrawal that could reduce your earnings.

    Ignoring What Could Happen to Rates

    Locking in a rate means accepting today’s terms for a long period. If market rates rise substantially later, you may have limited options without paying the applicable early-withdrawal cost.

    Forgetting Maturity and Taxes

    Mark the maturity date on your calendar. Also remember that CD interest can create taxable income even when you leave the earnings inside the account. Your individual tax treatment can vary.

    A Simple 5-Year Example

    Suppose Maria deposits $25,000 into a five-year CD earning an illustrative 4.00% APY. If the APY remained unchanged and the earnings compounded as assumed, the balance would be approximately $30,416 after five years.

    This is an illustrative calculation, not a current CD offer. Actual earnings depend on the institution’s APY, compounding method, account terms, and taxes.

    The practical lesson: A five-year CD works best when the money can stay committed for the full term and the account’s terms still look attractive after you read the fine print.

    Who Should Choose a 5-Year CD?

    A 5-year CD is most useful when the timing of your goal matches the length of the certificate. The decision becomes easier when you know roughly when the money will be needed and have other cash available for unexpected expenses.

    Who May Find It Useful?

    • Savers with a five-year goal: If the money has a known purpose several years away, a fixed-rate CD can give that portion of your savings a defined timeline.
    • Families planning ahead: Money earmarked for a distant education expense, major purchase, or other planned cost may have enough time to remain committed.
    • Retirees seeking predictable returns: A CD can provide a known rate for a defined period, although it should be considered alongside the rest of a retirement cash and income strategy.
    • Conservative savers: Someone who values deposit protection and a fixed return may prefer a CD over taking additional market risk with money reserved for a specific goal.
    • People with liquid reserves: Having accessible savings elsewhere makes it easier to leave the certificate untouched until maturity.

    Who Should Think Twice?

    A five-year term may be a poor fit if you expect to need the money soon, want to take advantage of potentially higher rates later, or would struggle to cover an unexpected expense without touching the CD.

    Quick Decision Guide

    Choose a 5-year CD: Your goal is five years away, the rate is competitive, and you have separate liquid savings.

    Look at shorter terms: Your plans may change, you need flexibility, or you expect to need the money before maturity.

    Frequently Asked Questions About 5-Year CDs

    What is the five-year CD rate environment in 2026?

    Bankrate reported a 1.75% national average APY for five-year CDs as of August 20, 2026. Individual offers can be much higher, so compare actual 60-month certificates rather than using the national average as an expected return.

    What happens if CD rates rise after I open a 5-year CD?

    With a typical fixed-rate CD, your original rate stays in effect through the term. If new five-year certificates start paying more, you generally cannot switch without following the account’s withdrawal rules.

    What if CD rates fall after I lock in my rate?

    A fixed rate can become more valuable if newly available CDs begin paying less. Your certificate generally continues earning the agreed rate until maturity, subject to its original terms.

    How does inflation affect a 5-year CD?

    Inflation can reduce the purchasing power of your future balance. A CD can increase your dollar balance while still producing a smaller gain in real purchasing power if inflation remains elevated.

    Can I withdraw money from a 5-year CD early?

    Many traditional CDs allow early withdrawal subject to a penalty, although the exact rules vary by institution. Read the penalty terms before opening the certificate so you know the potential cost of accessing the money early.

    What happens when a 5-year CD reaches maturity?

    At maturity, you can generally withdraw the funds, move them elsewhere, or renew the certificate, depending on the institution’s rules. A grace period may provide a limited window to give instructions before automatic renewal.

    Can a 5-year CD be part of a CD ladder?

    Yes. A ladder can spread money across certificates with different maturity dates, giving you periodic access to part of your savings while still using longer-term CDs for another portion.

    Are 5-year CDs insured?

    Eligible CDs at FDIC-insured banks receive FDIC deposit insurance within applicable limits. At federally insured credit unions, eligible share certificates receive NCUA share insurance, generally up to $250,000 per member-owner within the applicable ownership category.

    Is interest from a 5-year CD taxable?

    CD interest can generally create taxable income. Your actual tax treatment depends on the account and your circumstances, so consider the tax impact when estimating your after-tax return.

    How much could a 5-year CD earn on $20,000?

    Illustrative example: At a hypothetical 4.00% APY compounded annually, $20,000 would grow to about $24,333 after five years. This is only an illustration, not a current rate or guaranteed result; actual earnings depend on the CD’s APY, compounding method, terms, and taxes.

    Final Verdict: Is a 5-Year CD Right for You?

    A 5-year CD can be a sensible choice when the rate is competitive and you have a clear reason to keep the money invested for 60 months. The appeal is not simply the APY. You are also buying a fixed rate that can remain unchanged while the broader deposit market moves around you.

    But five years is long enough for the financial landscape to look very different. If rates rise substantially, you may miss better opportunities elsewhere. If your circumstances change, accessing the money early could also reduce the benefit of the original deal.

    For that reason, look beyond the advertised rate. Compare the APY, withdrawal penalty, minimum deposit, renewal policy, insurance coverage, and the role the money plays in your overall savings plan.

    A 5-year CD may suit a long-range saver who values certainty more than frequent access. Someone who expects changing cash needs or wants to react quickly to future rates may prefer shorter CDs or a savings account.

    If you want to compare terms, strategies, and alternatives before making that choice, visit our Complete CD Guide 2026.

    The useful question is not “Is this the highest APY?” It is “Would I still be comfortable with this decision if rates, prices, or my plans changed during the next five years?”

    FINANCEINVESTMENT

    Keep Your CD Research Moving

    Want more practical guides on CDs, savings, and smarter ways to manage your cash? Send a note to subhashr325@gmail.com to stay connected with FinanceInvestment.

    A five-year CD is a long decision. Take your time, compare the terms, and choose an option that still feels comfortable after the headline rate fades from view.

  • Best 3-Year CD Rates in 2026: Compare 36-Month CDs

    Best 3-Year CD Rates in 2026: Compare 36-Month CDs

    CD RATES • 2026 GUIDE

    Best 3-Year CD Rates in 2026

    Compare 36-month CDs, understand the trade-offs of a longer rate lock, and see what to check before committing your savings for three years.


    Written by


    Subhash Rukade

    Updated


    August 22, 2026

    Reading time


    About 14 min

    Introduction: Why a 3-Year CD Is a Bigger Rate Decision

    Best 3-Year CD Rates in 2026Choosing the Best 3-Year CD Rates in 2026 is different from picking a short-term certificate. With a 36-month CD, you are not simply choosing where to park your savings. You are deciding how much flexibility you are willing to give up for a fixed return over a longer stretch of time.

    That longer commitment can work in your favor when rates fall after you open the account. Your agreed rate generally stays in place through the term. But there is another side to that deal. If rates rise substantially later, your money remains tied to the original rate until the CD matures, unless the account has special withdrawal or upgrade features.

    That makes the timing of your financial goal especially important. Money needed for a house purchase, tuition bill, business expense, or emergency should not automatically be pushed into a three-year certificate just because the APY looks attractive.

    If you are still getting familiar with certificates of deposit, our CD Guide 2026 covers the broader basics. This guide takes the next step by looking closely at what changes when you commit your savings for 36 months.

    What You’ll Learn

    You will see how 3-year CDs work, what numbers deserve attention, where the longer term can help or hurt, how it compares with shorter CDs and savings accounts, and which savers may have a good reason to choose a 36-month maturity.

    Quick Answer: What Makes a 3-Year CD Different?

    Short answer: A 3-year CD can work well when you want a fixed return and already know you can leave the money alone for 36 months. Bankrate reported a 1.69% national average APY for 3-year CDs on August 12, 2026, while some top nationwide offers were around 4.50%. That gap shows why comparing individual offers matters more than relying on an average.

    6 Key Takeaways

    • The rate stays central to the decision: A competitive APY can make a long-term CD more attractive, but the account terms matter too.
    • Three years is a real commitment: Make sure the money has a purpose that extends beyond the maturity date.
    • Check the penalty before depositing: Early access can reduce your earnings, depending on the institution’s rules.
    • Compare more than APY: Look at minimum deposits, interest-crediting terms, renewal rules, and withdrawal penalties.
    • Protect your deposits: Eligible deposits at FDIC-insured banks and eligible shares at federally insured credit unions receive coverage within applicable limits.
    • Shop around: The difference between a national average and a competitive individual offer can be meaningful over a 36-month term.

    Bottom line: A 3-year CD deserves consideration when the rate is competitive, the terms are clear, and you are comfortable giving up access to the money until maturity.

    At a Glance: 3-Year CDs in 2026

    Before choosing a 36-month certificate, focus on the numbers that affect the actual decision. APY gets attention first, but the deposit requirement, penalty, insurance, and maturity rules can matter just as much.

    Term
    36 months
    Market Reference
    1.69% national average APY reported Aug. 12, 2026
    Access
    Generally limited before maturity
    Deposit Protection
    FDIC or NCUA when eligible

    Who Might Look at a 3-Year CD?

    This term can appeal to savers who have a longer time horizon and want to reduce the need to make frequent reinvestment decisions. It may also fit someone building a conservative part of a broader financial plan.

    Numbers Worth Comparing

    FactorWhat to Check
    APYCompare the actual 36-month offer with competing institutions.
    Minimum depositCheck whether the opening requirement fits your available cash.
    Early-withdrawal penaltyFind out how much an early exit could cost.
    Maturity rulesCheck the grace period and automatic-renewal instructions.
    InsuranceConfirm applicable FDIC or NCUA coverage.

    Rate reference: Bankrate reported a 1.69% national average APY for 3-year CDs on August 12, 2026. Individual offers can be much higher or lower than an average, so compare actual account offers before making a decision.

    Complete Beginner Guide to 36-Month CDs

    Best 3-Year CD Rates in 2026A 36-month CD is a time deposit designed for money you can leave untouched for three years. You deposit a set amount with a bank or credit union, agree to the account’s terms, and generally receive the stated rate through the certificate’s maturity date. In return for making that longer commitment, you get a clearer picture of how your savings can grow.
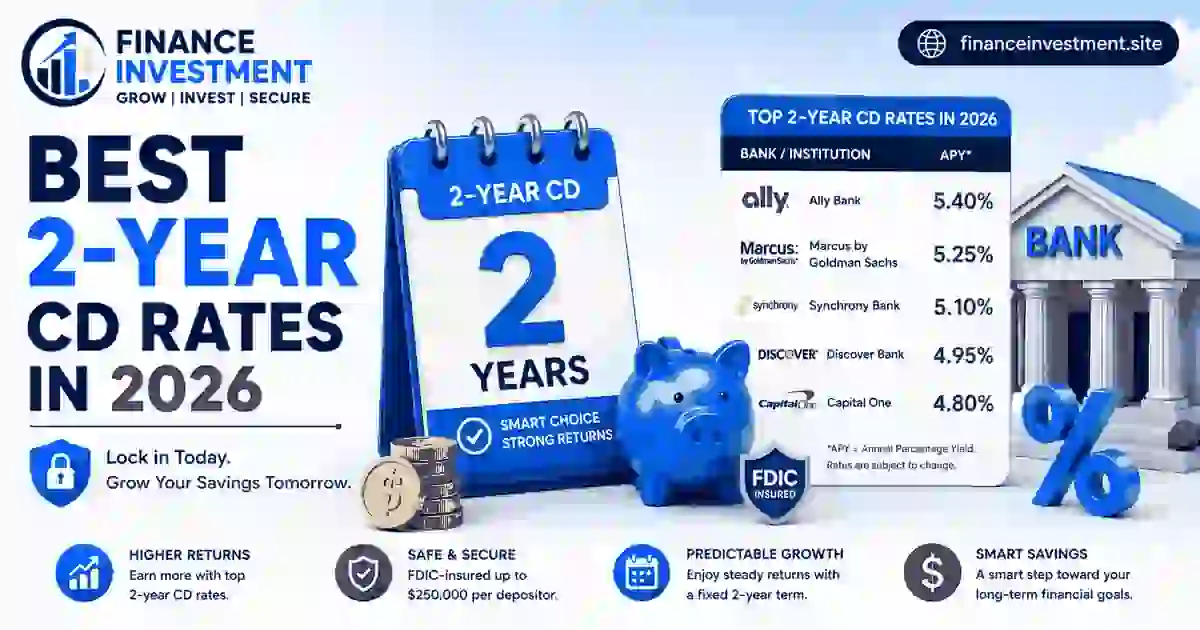
    What Makes a 3-Year CD Different?

    The biggest difference is the length of the commitment. A 6-month or 1-year CD gives you an earlier maturity date. A 3-year CD pushes that decision further into the future. That can be useful if your goal is several years away, but it also means you have more time to live with the rate you chose.

    For that reason, the best 36-month CD is not automatically the one with the highest advertised APY. Think about the entire term, including the rate, withdrawal rules, minimum deposit, and maturity options.

    How APY and Compounding Affect Your Return

    APY, or annual percentage yield, is the standard figure used to compare deposit-account returns because it reflects the effect of compounding. The way interest is credited can vary between products, so read the account disclosures rather than assuming every CD handles earnings in exactly the same way.

    If you want to understand the mechanics in more detail, our guide to how CD interest rates work goes deeper into rates and earnings.

    Minimum Deposits Matter

    Some CDs can be opened with a modest amount, while others require a larger deposit. A higher minimum does not automatically mean a better deal. Choose an amount that leaves enough cash available for emergencies and other financial needs.

    FDIC and NCUA Insurance

    Eligible deposits at an FDIC-insured bank are generally protected by FDIC deposit insurance within applicable coverage limits. The FDIC says deposits are automatically insured to at least $250,000 at each FDIC-insured bank.

    At a federally insured credit union, a CD may be called a share certificate. NCUA share insurance covers eligible time deposits such as share certificates within applicable limits.

    What Happens at Maturity?

    When the three-year term ends, the CD reaches maturity. Depending on the account, you may be able to withdraw the funds, transfer them, or place them into another CD. Some certificates automatically renew if you do not act during the institution’s stated grace period. The FDIC recommends checking renewal terms and the rate that would apply after maturity.

    That final detail is easy to overlook. Put the maturity date on your calendar so you have time to decide what the money should do next.

    How a 3-Year CD Works From Opening to Maturity

    Once you choose a 36-month certificate, the process becomes a timeline. Your main job is to understand what happens at each stage and keep an eye on the date when the commitment ends.

    Opening and Funding

    You select the institution, review the CD agreement, and deposit the amount required to open the account. The rate, APY, maturity date, early-withdrawal rules, and renewal terms should be clear before you confirm the deposit.

    The 36-Month Rate Lock

    For a typical fixed-rate CD, the agreed rate stays in place during the term. Your balance earns interest according to the account’s stated schedule. The money does not need daily attention, but you should keep the account documents available in case you need to check a term or maturity instruction.

    What Happens During the Three Years?

    Think of the CD as a savings bucket with a destination date. Interest is credited according to the product’s terms, while your original deposit remains committed. If you withdraw early, the institution may apply the penalty described in the account agreement.

    At Maturity: Withdraw or Renew?

    When the 36 months end, you reach the decision point. Depending on the account, you may withdraw the funds, transfer them, or renew into another CD. An automatic renewal can use the rate available for the new certificate rather than your original rate. Federal consumer rules require applicable maturity disclosures for renewing time accounts, and institutions must disclose renewal and grace-period terms.

    A Simple 36-Month Timeline

    StageWhat to Do
    Month 0Fund the CD and save the agreement, rate, and maturity date.
    Months 1–35Let the certificate run while interest is credited under its stated terms.
    Month 36Review the maturity notice and decide what you want to do with the money.
    Grace periodIf offered, use this window to withdraw or change the CD before automatic renewal takes effect.

    The renewal decision deserves attention because the new rate can be different from the one you originally locked in. The CFPB recommends comparing available rates before allowing an existing CD to roll over.

    Benefits and Drawbacks of a 3-Year CD

    A three-year certificate can be appealing when stability matters more than having every dollar available on demand. The extra time can make a fixed rate more valuable if deposit rates decline, but that same commitment can become a disadvantage if your plans or the rate environment change.

    Pros

    • Longer rate protection: A competitive fixed rate can remain in place for the full three-year term even if new deposit rates fall.
    • Predictable return: You have a defined rate and maturity date, which can make longer-term savings easier to plan.
    • Potentially attractive yield: Some institutions may offer competitive rates on longer certificates, although term structures vary across the market.
    • Useful for planned goals: A 36-month maturity can line up with a future expense that is several years away.

    Cons

    • Three-year opportunity cost: If rates rise significantly, your locked rate may look less attractive while your CD remains open.
    • Limited liquidity: The money is intended to stay in the certificate until maturity.
    • Early-withdrawal penalty: Accessing funds ahead of schedule may reduce your interest earnings or otherwise make the withdrawal costly.
    • Less room to change course: A three-year commitment can be uncomfortable if your financial plans are still uncertain.

    The Extra Year Can Change the Equation

    Suppose rates move sharply higher one year after you open a CD. A 1-year certificate would already be approaching maturity, while a 3-year certificate would still have roughly two years remaining. That is the trade-off: the longer term gives your original rate more time to work, but it also gives you more time to be stuck with it.

    For a saver with a firm long-term goal, that may be an acceptable trade. For someone who wants to react quickly to changing rates, it may not be.

    3-Year CD vs. Other Savings Options

    A 36-month certificate is the longest commitment in this comparison. That does not make it automatically better. The useful question is what you gain for accepting the extra time: a potentially attractive fixed return, a defined maturity date, and less need to revisit the account during the term.

    OptionCommitmentFlexibilityBest Use
    6-Month CDShortHigherNear-term goals and rate flexibility
    1-Year CDModerateModerateGoals about a year away
    2-Year CDLongLowerA defined two-year savings goal
    3-Year CDLongestLowestMoney you can leave untouched for three years
    High-Yield SavingsNoneHighestFlexible savings and accessible cash

    Which Term Fits Your Timeline?

    If three years feels too restrictive, compare the best 6-month CD rates in 2026 or the best 1-year CD rates in 2026. For a middle ground, our guide to the best 2-year CD rates in 2026 focuses on the 24-month option.

    Before choosing any term, it is also worth reviewing the broader list of best CD rates in 2026 so you can see how different maturities compare.

    Costs, Risks, and Expert Tips for a 3-Year CD

    A three-year CD deserves a closer look before you commit. The biggest issue is not simply whether the rate is attractive today. You also need to consider what could happen to your money over the next 36 months.

    Early-Withdrawal Costs

    If you take money out before maturity, a traditional CD may charge an early-withdrawal penalty. The formula differs between institutions. Some penalties are based on several months of interest, while others use a different calculation. Check the exact rule before opening the account.

    This matters more with a three-year term because there is a longer period during which an unexpected expense could arise. Keep emergency savings separate so you are less likely to break the CD at the wrong time.

    Inflation Can Reduce Your Real Return

    A fixed APY tells you how much your balance can grow in dollar terms. It does not guarantee that your purchasing power will grow at the same pace. If inflation stays elevated, the real value of your earnings may be less impressive than the account statement suggests.

    The Bigger Rate-Rise Risk

    Imagine deposit rates move considerably higher after you open a three-year CD. Your original rate generally remains fixed, which means you cannot simply move the money into a newer, higher-paying certificate without dealing with the existing account’s rules. That opportunity cost is more important here than with a six-month or one-year CD because the commitment lasts longer.

    Watch Automatic Renewal

    Do not assume maturity means the money automatically returns to your checking account. Some CDs renew unless you provide instructions during the grace period. Mark the maturity date well in advance and review the new rate before allowing a renewal.

    Could a CD Ladder Help?

    A ladder can reduce the pressure of putting every dollar into one maturity date. Instead of committing your entire savings balance to a single three-year certificate, you can divide the money among CDs with different maturity dates. When one matures, you can use the cash or reinvest it based on the rates and goals at that time.

    Expert Tip

    Compare the early-withdrawal penalty in actual dollars, not just the APY. A rate that looks slightly better may not be worth choosing if accessing the money later would cost you substantially more interest.

    Common 3-Year CD Mistakes and a Real-Life Example

    A three-year CD can be useful, but the wrong setup can make a good rate feel restrictive. Most problems come from treating the APY as the whole story.

    Choosing the Highest APY Without Reading the Terms

    A higher rate deserves attention, but check the minimum deposit, early-withdrawal penalty, insurance coverage, interest-crediting rules, and maturity instructions before opening the account.

    Using Emergency Cash

    Emergency money needs quick access. Putting that cash into a 36-month certificate can create a difficult choice if an unexpected expense arrives and withdrawing early triggers a penalty.

    Underestimating Rate-Lock Risk

    A rate that looks attractive today may look different if market rates climb later. With three years still remaining, you have more time exposed to that opportunity cost than you would with a shorter CD.

    Forgetting the Maturity Date

    Automatic renewal can happen if you do not provide instructions during the institution’s grace period. Add the maturity date to your calendar and review the renewal notice before the deadline.

    Overlooking Taxes

    Interest from a typical taxable CD is generally taxable income. Your actual after-tax return can therefore be lower than the advertised APY. Your individual tax treatment may vary.

    Real-Life Example: A $30,000 Three-Year CD

    Imagine Daniel has $30,000 that he will not need for three years. He already maintains a separate emergency fund, so this money has a longer-term purpose.

    Illustrative calculation: If a hypothetical CD earned 4.00% APY for the full 36 months, $30,000 would grow to approximately $33,745 before taxes, assuming the stated APY remained unchanged and earnings stayed in the account. This is an example, not a current bank offer or guaranteed result.

    The Practical Lesson

    Daniel’s decision works because the money has a clear three-year job and his emergency savings are separate. The same CD could be a poor choice for someone who expects to need the money next year. Match the term to the goal before comparing the rate.

    Who Should Choose a 3-Year CD?

    A three-year CD tends to work best when the money already has a destination. You are not trying to guess the perfect moment to move your cash. Instead, you are accepting a longer commitment because the timing fits your financial plan.

    People Who May Benefit

    • Beginners with a clear three-year goal: A fixed maturity can create a simple target for money you expect to use several years from now.
    • Families planning ahead: Savings for a future education expense, planned move, or major purchase may fit a 36-month timeline if the money is not needed sooner.
    • Retirees seeking predictable returns: A CD can provide a defined return on an eligible deposit without exposing that particular savings bucket to daily stock-market fluctuations.
    • Conservative savers: If stability matters more than reacting to every change in deposit rates, a longer fixed term may be appealing.
    • Investors with a separate emergency fund: Keeping accessible cash elsewhere can make it easier to leave the CD untouched until maturity.

    Who Should Think Twice?

    A three-year term may not suit someone who expects to need the money soon, is still building an emergency reserve, or wants to move savings quickly when market rates change. A shorter CD or liquid savings account may provide a better fit.

    Quick Decision Guide

    Have a three-year goal, separate emergency cash, and no need for this money before maturity? A 3-year CD may deserve a place on your shortlist. If any of those pieces are missing, compare a shorter term or a more accessible savings option first.

    Frequently Asked Questions About 3-Year CDs

    Is a 3-year CD better than a 2-year CD when the APYs are similar?

    Not necessarily. If the rates are close, the shorter term gives you an earlier maturity date and more flexibility. The 3-year option becomes more interesting when its rate or your timeline clearly justifies the extra year.

    What if CD rates rise during my 3-year term?

    A typical fixed-rate CD keeps its original rate. If new certificates begin paying more, your existing CD generally stays at the rate you accepted until maturity.

    What if CD rates fall after I lock in my rate?

    A falling-rate environment can make a previously locked fixed rate more attractive. Your certificate can continue earning its stated rate while newer offers become less competitive.

    How can a 3-year CD fit into a CD ladder?

    You can divide your savings among certificates with different maturity dates instead of putting everything into one term. As shorter CDs mature, you can use the cash or reinvest it based on your needs at that time.

    What happens if rates are lower when my 3-year CD matures?

    You can generally choose whether to withdraw the money or reinvest it, subject to the account’s maturity rules. If rates have fallen, having the original principal available gives you the chance to reassess rather than being tied to the old certificate.

    How should I compare a 3-year CD with a high-yield savings account?

    Compare the expected return with access to your money. A CD may provide a fixed rate for the term, while a high-yield savings account generally offers easier access but a variable rate that can change.

    How does inflation affect a 3-year CD?

    Inflation can reduce what your interest earnings can buy. Even when your account balance rises, the purchasing power of that money may grow more slowly if inflation remains elevated.

    Can retirees use 3-year CDs for income planning?

    They can use them as one part of a broader cash or fixed-income strategy. The maturity date can help with planning, but retirees should consider liquidity needs and avoid putting money needed for near-term expenses into a long lock-up.

    When is a shorter CD better than a 3-year CD?

    A shorter term may be preferable when you expect to need the money sooner or want more opportunities to reinvest at future rates. It can also make sense when the extra APY from the longer certificate is small.

    Should I put all my savings into one 3-year CD?

    Usually, there is little reason to make every savings dollar follow the same schedule. Keeping different buckets for short-term needs, upcoming goals, and longer-term savings can give you more room to adjust.

    Final Verdict: Is a 3-Year CD Right for You?

    A 3-year CD makes the most sense when you can give the money a clear three-year job. The appeal is not simply a higher APY. It is the ability to secure a fixed rate today and know what kind of return the certificate is designed to provide through its maturity date.

    There is a trade-off, though. Once your money is committed, you have less freedom to take advantage of higher rates that may appear later. That matters more with a 36-month term than with a shorter certificate. A competitive rate can work in your favor if rates fall, but it can feel restrictive if the market moves sharply upward.

    This option may suit savers who have accessible cash elsewhere and a financial goal that comfortably sits beyond the maturity date. If you might need the money sooner, keeping more of it liquid may be the smarter move.

    For a broader look at CD terms, strategies, and alternatives, visit our complete CD Guide 2026.

    The key takeaway: A 3-year CD is a commitment, not just a rate. Choose it when the maturity date fits your plan as well as the APY fits your expectations.

    Keep Your CD Research Moving

    Want practical money guides without the noise?

    Send us an email to stay connected with straightforward guides covering CDs, savings, investing, retirement, and everyday money decisions.

    Take your time, compare the terms, and choose a CD that fits the job your money needs to do.

    A three-year decision does not have to be complicated. Know your timeline, understand the trade-offs, and let the maturity date—not just the headline rate—guide your choice.

  • Best 2-Year CD Rates in 2026: Compare 24-Month CDs

    Best 2-Year CD Rates in 2026: Compare 24-Month CDs

    CD RATES • 2026 GUIDE

    Best 2-Year CD Rates in 2026

    A practical guide to comparing 24-month CD rates, understanding APY, and deciding whether locking your money away for two years makes sense.


    Written by


    Subhash Rukade

    Updated


    August 22, 2026

    Reading time


    About 14 min

    Is a 2-Year CD a Smart Move in 2026?

    Best 2-Year CD Rates in 2026If you have cash that you probably will not need for the next two years, a certificate of deposit can turn that waiting period into a chance to earn interest. The challenge is finding the Best 2-Year CD Rates in 2026 without focusing on APY alone.

    A 24-month CD gives you a fixed rate for a defined period. That can be appealing when you want predictable returns. But there is a trade-off. Your money is less flexible, and taking it out before maturity may trigger an early withdrawal penalty.

    There is another factor to consider. Interest rates can change while your money is locked in. If rates rise later, you may be stuck with the rate you originally accepted until the CD matures. If rates fall, however, that same fixed rate could become more valuable.

    That is why a good comparison goes beyond the headline APY. You also need to look at the minimum deposit, early withdrawal rules, deposit insurance, maturity options, and how the CD compares with shorter terms and savings accounts.

    If you want to understand the bigger picture first, read our CD Guide 2026. Then use this guide to decide whether a two-year term fits the money you have available.

    What You’ll Learn

    This guide will show you how 2-year CDs work, what features deserve the most attention, how to think about the trade-off between return and access to your money, and which savers may benefit most from a 24-month term.

     Are 2-Year CDs Worth Considering in 2026?

    Short answer: A 2-year CD can be a solid choice when you want a fixed return and know you can leave the money untouched for 24 months. As of August 2026, competitive 2-year CD offers are reaching roughly the low-4% APY range, although rates vary by institution and can change quickly. One recent market snapshot listed a top 24-month offer at 4.25% APY, so compare the actual offer, minimum deposit, and withdrawal rules rather than relying on a headline rate.

    6 Key Takeaways

    • APY is only one part of the deal. A higher yield can lose its appeal if the CD has a large minimum deposit or harsh early-withdrawal penalty.
    • Two years means less flexibility. Keep emergency savings and money needed for near-term expenses outside the CD.
    • A fixed rate cuts both ways. You get predictable earnings, but you may miss a better rate if market yields rise after you open the account.
    • Early withdrawals can be expensive. Penalties vary by institution and may reduce some of the interest you expected to earn.
    • Insurance matters. Eligible deposits at FDIC-insured banks are protected within applicable limits. At federally insured credit unions, share certificates receive NCUA share insurance within applicable limits.
    • The best fit is money with a clear two-year timeline. Families saving for a known future expense, conservative savers, and retirees seeking predictable income may find the structure useful.

    Bottom line: A competitive 2-year CD can work well when certainty matters more than instant access. The strongest choice is not simply the account with the biggest APY; it is the one whose rate, rules, insurance, and maturity date fit the job your money needs to do.

    At a Glance: 2-Year CD Rates in 2026

    A two-year CD is built for money that has a job later, not money you may need tomorrow. Here are the main points to check before opening one.

    Term
    24 months
    Rate Type
    Usually fixed until maturity
    Access
    Limited before maturity
    Insurance
    FDIC or NCUA, when eligible

    Who Is a 2-Year CD Best For?

    It can suit savers who have a known two-year time horizon, want predictable interest, and already keep separate cash for emergencies. It may also work for retirees or families who prefer a defined maturity date instead of taking market risk with money earmarked for a near-term goal.

    Key Numbers to Watch

    FactorWhy It Matters
    APYShows the annualized return, including compounding.
    Minimum depositDetermines how much you need to open the CD.
    Early withdrawal penaltyShows the potential cost of accessing money early.
    Maturity dateTells you when the original term ends and your options open up.

    Complete Beginner Guide to 2-Year CDs

    Best 2-Year CD Rates in 2026A 2-year certificate of deposit is a savings product with a simple trade-off: you agree to leave your money with a bank or credit union for a set period, and in return, you receive a stated interest rate. For a 24-month CD, that period is two years.

    Unlike a regular savings account, a CD is designed around a fixed maturity date. Once you open the account and fund it, the rate generally stays fixed through the term. That makes the return easier to estimate, but it also means you have less flexibility if your plans change.

    What Does a 24-Month CD Actually Mean?

    A 24-month CD simply means the certificate is scheduled to mature two years after it is opened. For example, if you open one in August 2026, the maturity date will generally fall around August 2028, subject to the institution’s specific terms.

    At maturity, you typically receive your original deposit plus the interest earned. The institution may give you a limited grace period to withdraw the money, change the CD, or choose another term. If you do nothing, some CDs automatically renew, so checking the maturity instructions matters.

    APY: The Number Beginners Should Compare

    APY, or annual percentage yield, is the standard figure used to compare deposit-account returns because it reflects the effect of compounding. A higher APY can produce more interest, but the difference should always be considered alongside the CD’s other rules.

    For a broader explanation of CD pricing and interest, see our guide on how CD interest rates work.

    Minimum Deposit and Insurance

    Minimum opening deposits vary widely. Some institutions allow relatively small deposits, while others reserve their most attractive offers for larger balances. Do not move money you may need for an emergency just to meet a higher minimum.

    Insurance is another basic check. Eligible deposits at an FDIC-insured bank are covered within applicable limits. At a federally insured credit union, eligible share deposits are generally protected by NCUA share insurance within applicable limits. Insurance protects against the failure of the covered institution; it does not protect you from every investment or rate risk.

    What Beginners Should Check First

    • APY and how long the rate is guaranteed.
    • Minimum opening deposit.
    • Early withdrawal penalty.
    • FDIC or NCUA insurance status.
    • Interest payment and compounding schedule.
    • Maturity and automatic-renewal rules.

    The goal is not simply to find a high number. It is to find a 24-month CD whose terms match the reason you are setting the money aside.

    How a 2-Year CD Works From Opening to Maturity

    A 2-year CD follows a fairly predictable path. You choose the account, deposit your money, lock in the stated rate, and leave the funds in place until the certificate reaches maturity. The details can vary by institution, but the basic process is similar.

    1. Open and Fund the CD

    You start by choosing a bank or credit union and reviewing its 24-month CD terms. After checking the APY, minimum deposit, insurance coverage, and withdrawal rules, you fund the certificate with the amount you want to save.

    2. Your Rate Is Locked In

    With a typical fixed-rate CD, the agreed rate remains in place during the two-year term. If market rates move down, your rate generally does not fall with them. If rates move up, however, you usually cannot switch to the new rate without dealing with the existing CD’s terms.

    3. Interest Builds

    The CD earns interest according to the institution’s stated schedule. Interest may compound within the account or be paid elsewhere, depending on the product. Your actual return therefore depends on the APY, starting balance, compounding rules, and account terms.

    4. The CD Reaches Maturity

    After 24 months, the certificate matures. You can generally take the money out, move it elsewhere, or choose another CD term. Many institutions provide a short grace period for making that decision.

    A Simple 24-Month Timeline

    TimeWhat Happens
    Day 1You deposit your chosen amount and accept the 24-month terms.
    Months 1–23The CD earns interest at its stated rate, subject to the account’s terms.
    Month 24The CD reaches maturity and your next-step window begins.
    Grace periodYou may be able to withdraw, transfer, or select a new term before automatic renewal.

    That final step deserves attention. If the CD automatically renews and you miss the grace period, your money could move into a new certificate with a different rate and term.

    Benefits and Drawbacks of a 2-Year CD

    A two-year CD works best when certainty has real value to you. You know the term, know the rate when you open the account, and can plan around a specific maturity date. That structure can be useful, but it also puts limits on what you can do with the money during those 24 months.

    Pros

    • Rate certainty: A fixed-rate CD can protect your agreed APY if market rates decline.
    • Predictable earnings: You can estimate the return more easily than with accounts whose rates change frequently.
    • Potentially stronger yield: A competitive CD may offer more than a basic savings account, depending on current market conditions.
    • Clear time frame: The maturity date gives your savings a defined destination.

    Cons

    • Limited access: Your money is committed for the agreed term unless the institution allows an early withdrawal.
    • Early withdrawal penalty: Taking money out before maturity can reduce your interest earnings and, depending on the terms, may affect principal.
    • Rate opportunity cost: If new CD rates climb after you lock in, your existing certificate generally stays at its original rate.
    • Less flexibility: Money tied up in a CD cannot respond as easily to an unexpected expense or a better opportunity elsewhere.

    Where the Trade-Off Matters Most

    Consider two savers with the same $20,000. One has a separate emergency fund and knows the money is not needed for two years. The other expects a major expense within the next year. The first saver may value the fixed return more; the second may value access more than a slightly higher yield.

    That difference is the heart of the decision. A CD can be attractive without being the right home for every dollar you have.

    2-Year CD vs. Other Savings Options

    A two-year term sits in an interesting spot. It gives you more time to earn at a locked rate than a short CD, but it does not commit your cash for as long as a three-year certificate. The better choice depends on when you expect to need the money and how much flexibility you want.

    Rates can also vary sharply by term and institution. For example, Bankrate’s August 2026 data shows some institutions offering similar or even higher yields on longer terms, while other offers favor shorter maturities. That makes comparing the actual APY available to you more useful than assuming a longer CD will always pay more.

    OptionTypical Trade-OffBest Use
    6-Month CDShort commitment and earlier access to maturity.Money you may need within a year.
    1-Year CDMiddle ground between yield and flexibility.Goals roughly one year away.
    2-Year CDLonger rate commitment with less liquidity.Cash with a clear two-year timeline.
    3-Year CDLonger lock-in and greater exposure to future rate changes.Money you can leave untouched longer.
    High-Yield SavingsRate can change, but access is generally much easier.Emergency funds and flexible savings.

    Which Term Deserves Your Attention?

    If you are leaning toward a shorter commitment, compare the best 6-month CD rates in 2026 and best 1-year CD rates in 2026. If your money has a firm two-year purpose, the 24-month option may offer a better balance between time and return.

    For a broader market comparison, our guide to the best CD rates in 2026 can help you see how different terms stack up before you commit.

    Costs, Risks, and Expert Tips for a 2-Year CD

    A two-year CD can look straightforward on paper, but the fine print can change the value of the deal. The biggest issues are not usually complicated. They come down to what happens if you need the money, rates move, or you forget about the account when it matures.

    Early-Withdrawal Costs

    Most traditional CDs are designed to stay open until maturity. If you take money out early, the institution may charge an early-withdrawal penalty. The formula varies, so check whether the penalty is based on a number of months’ interest, a percentage of the amount withdrawn, or another method.

    Do not compare CDs by APY alone. A slightly lower rate with a much more manageable penalty can be more practical if there is a reasonable chance you will need the funds.

    Inflation and Purchasing Power

    A fixed APY gives you a predictable nominal return, but your purchasing power can still change. If inflation runs higher than the return you earn after taxes, the real value of the money may grow slowly or even decline.

    What If Rates Rise?

    A locked rate protects you from falling deposit rates, but it also limits your ability to benefit from higher rates later. This is the main opportunity cost of committing money for two years. You are trading flexibility for certainty.

    Watch Automatic Renewal

    Many CDs can automatically renew when the term ends. That can be convenient, but it can also catch you off guard if the new rate or term is less attractive. Mark the maturity date on your calendar and review the renewal notice before the grace period ends.

    Consider a CD Ladder

    A CD ladder spreads money across different maturity dates instead of putting the entire balance into one certificate. For example, someone with $20,000 could divide it among several CDs with staggered terms. As each certificate matures, the money can be reinvested or used for the next financial goal.

    Expert Tip

    Before opening a CD, write down three numbers: the APY, the early-withdrawal penalty, and the maturity date. Those three details give you a quick picture of the return, the cost of changing plans, and when your money becomes flexible again.

    Common Mistakes With 2-Year CDs

    A good CD can still become a poor choice when the account is opened for the wrong reason. Most mistakes happen before the money ever starts earning interest.

    Chasing the Highest APY

    A top rate can grab attention, but it should not end the comparison. Check the minimum deposit, early-withdrawal penalty, insurance status, interest-payment rules, and maturity instructions. A slightly lower APY may be easier to live with if the terms are more flexible.

    Putting Emergency Money Into a CD

    Your emergency fund has a different job. It needs to be available when an unexpected bill arrives. Using a two-year CD for that cash can create a penalty at exactly the moment you need quick access.

    Forgetting the Maturity Date

    Automatic renewal can turn an overlooked CD into a new commitment. Put the maturity date on your calendar and review the renewal notice before the grace period closes.

    Ignoring Taxes

    Interest from a taxable CD is generally taxable income even if you leave the earnings inside the account. Your after-tax return can therefore be lower than the advertised APY. Your actual tax treatment depends on your circumstances, so consider the effect when comparing options.

    Real-Life Example: A $25,000 Decision

    Imagine Sarah has $25,000 that she expects to use for a home-related expense in about two years. She already has a separate emergency fund, so she does not need this particular cash for unexpected bills.

    She finds a hypothetical 2-year CD offering 4.00% APY. If the rate stayed fixed for the full term and the APY were applied as stated, $25,000 would grow to roughly $27,040 after two years, before taxes. That is an illustrative calculation, not a promise of what any specific bank will pay.

    Sarah’s decision becomes easier because the money already has a two-year purpose. Someone who might need the same $25,000 next month would face a very different trade-off.

    The Lesson

    The value of a CD is not measured by APY alone. The timing of your goal matters just as much. Match the term to the date you expect to need the money, then compare the rate and account rules.

    Who Should Choose a 2-Year CD?

    A 24-month CD makes the most sense when the timing of your goal lines up with the maturity date. You do not need to predict where rates will go. You simply need to know that the money can stay put for the agreed period.

    Good Fits for a 2-Year CD

    • Beginners with a defined goal: If you have money earmarked for a purchase or expense about two years away, a fixed-rate CD can provide a clear target date.
    • Families planning ahead: Money set aside for tuition, a planned move, or another known expense may benefit from a defined savings timeline.
    • Retirees seeking predictability: A CD can provide a known rate on eligible deposits without exposing that specific savings bucket to stock-market price swings.
    • Conservative savers: If preserving principal and knowing the return matters more than having immediate access, a two-year term may fit.

    Who May Want Something Else?

    A 2-year CD may be a poor fit if you are still building an emergency fund, expect to need the money soon, or want the freedom to move your cash whenever rates change. A high-yield savings account or shorter CD may offer a better balance for those situations.

    Quick Decision Guide

    Can you leave the money untouched for about two years? If yes, compare 2-year CD offers. If no, keep more flexibility and consider a shorter-term or liquid savings option.

    Frequently Asked Questions About 2-Year CDs

    Are 2-year CDs worth it in 2026?

    They can be useful if you want a fixed return and can leave the money untouched for 24 months. Compare the current APY with shorter CDs and savings accounts before opening one.

    What is a good 2-year CD rate?

    There is no single rate that stays “good” for the entire year. CD offers change by institution and market conditions. Compare the APY, minimum deposit, withdrawal penalty, and insurance together.

    How much can $10,000 earn in a 2-year CD?

    The amount depends on the APY and compounding method. For example, at a hypothetical 4% APY, $10,000 would grow to about $10,816 after two years before taxes. This is an illustration, not a current bank offer.

    Can I withdraw money from a 2-year CD early?

    Many traditional CDs allow early withdrawal subject to a penalty. The exact cost depends on the institution and account agreement, so check the penalty before depositing your money.

    Are 2-year CDs FDIC insured?

    An eligible CD at an FDIC-insured bank is generally covered by FDIC deposit insurance within applicable limits. FDIC coverage protects insured deposits if the covered bank fails.

    Are credit union CDs insured?

    Credit unions generally call CDs “share certificates.” At a federally insured credit union, eligible shares are protected by NCUA share insurance within applicable limits.

    What happens when a 2-year CD matures?

    At maturity, you generally can withdraw the money, transfer it, or choose another certificate. Some CDs automatically renew, so check the maturity notice and grace-period rules.

    Can CD rates rise after I open a 2-year CD?

    Yes. Market rates can rise after you lock in your CD. A fixed-rate certificate normally keeps its original rate, which means you may miss higher offers until your term ends.

    Is CD interest taxable?

    For a typical taxable CD, interest is generally taxable income. Your after-tax return can therefore be lower than the advertised APY. Your individual tax situation may differ.

    Who should consider a 2-year CD?

    It may suit someone with a clear two-year savings goal, separate emergency cash, and a preference for predictable returns. It may be less suitable if you expect to need the money soon.


    Final Verdict: When a 2-Year CD Makes Sense

    A 2-year CD can be a strong fit when you have money with a clear two-year purpose and value a predictable return more than immediate access. Current August 2026 rate listings show that competitive CD yields remain available, but the strongest rates are not necessarily attached to every term. That makes the exact 24-month offer worth comparing rather than assuming longer is always better.

    The bigger question is APY versus flexibility. If you can leave the money alone, a competitive fixed rate can provide useful certainty. If you may need the cash early, a savings account or shorter CD could be more practical.

    Beginners with a defined goal, families planning for a known expense, retirees seeking predictable returns, and conservative savers may find a two-year term appealing. Someone still building an emergency fund or expecting a near-term expense should probably keep that money accessible.

    For the broader picture on CD terms, strategies, and alternatives, continue with our complete CD Guide 2026.

    The takeaway: Choose a 2-year CD because its timing fits your goal—not simply because its APY looks attractive.

    Keep Your CD Research Simple

    Want more practical money guides?

    Join our email updates for straightforward guides on CDs, savings, investing, retirement, and other ways to make smarter decisions with your money.

    No complicated jargon. Just useful ideas you can come back to when you need them.

    A good savings decision does not have to be complicated. Start with your timeline, compare the terms carefully, and choose an account that gives your money a clear purpose.