Tag: ACH Transfers

  • Bank Transfer vs. Payment: Key Differences Explained

    Bank Transfer vs. Payment: Key Differences Explained

    FinanceInvestment
    Straightforward guidance for everyday money decisions

    Bank Transfer vs. Payment: What’s the Difference?

    Written by
    Subhash Rukade
    Publish date: October,  25,  10.
    FinanceInvestment

    Learn how bank transfers differ from payments, how common methods work, and what to consider before sending money.

    Bank Transfer vs. Payment: Understanding the Differencebank transfer vs payment

    When comparing bank transfer vs. payment, remember that a transfer describes moving money between accounts, while a payment means giving money to settle a purchase, bill, or obligation. The terms can overlap: paying a bill from your checking account may involve a bank transfer behind the scenes.

    For example, moving savings to another bank is a transfer. Paying for groceries with a debit card is a payment. Sending rent to a landlord is a payment that may use an electronic transfer. Knowing the difference helps you compare fees, understand processing times, and choose a method that fits the situation.

    For a wider overview, start with our
    guide to bank transfers and payment methods.
    This article takes a closer look at how the terms differ and when they overlap.

    What You’ll Learn

    • How transfers and payments differ—and where they overlap.
    • Where ACH, wire transfers, debit cards, and payment apps fit in.
    • How to compare fees, timing, and recipient details.
    • How to recognize common payment risks and make informed choices.

    QUICK ANSWER

    Bank Transfer vs. Payment: The Short Answer

    A bank transfer moves money between accounts; a payment settles a purchase, bill, or obligation. One transaction can do both—for example, paying a bill through your bank using ACH. Choose a method based on the recipient, urgency, fees, and available options.

    Key Takeaways

    • ACH is commonly used for routine electronic bank transactions.
    • Wire transfers may suit urgent or wire-required payments, but fees can apply.
    • Debit cards are mainly used to pay merchants, not transfer funds between your own accounts.
    • Payment apps can simplify eligible person-to-person payments.
    • Fees, limits, and delivery times depend on the bank or service.
    • Check the recipient details before authorizing a transaction.

    Bottom Line

    Match the method to the purpose, cost, timing, and recipient requirements.

    Bank Transfer vs. Payment at a Glance

    A transfer describes how money moves; a payment describes what the money is for. One transaction can be both, such as paying a bill through your bank.

    Bank Transfer
    Moves funds

    Example: moving savings between your bank accounts.

    Payment
    Pays for something

    Example: paying rent, a utility bill, or a store.

    On a small screen, swipe horizontally to see every column.

    FeatureBank TransferPayment
    PurposeMove money between accountsSettle a purchase or obligation
    ExamplesACH or wire transferDebit card, bill, or app payment
    FeesDepend on the bank and methodDepend on the provider and method
    TimingVaries by transfer typeVaries by payment method

    Quick Take

    Start with the purpose of the transaction, then compare the available methods, fees, delivery estimates, and recipient requirements.

    A Beginner’s Guide to Bank Transfers and Paymentsbank transfer vs payment

    In U.S. banking, a transfer describes how money moves, while a payment describes what the money is for. The same transaction can be both. Your bank statement may label activity as a transfer, bill payment, card purchase, or electronic withdrawal, depending on how it was processed.

    Three Everyday Examples

    Moving Savings

    Moving $500 from checking at one bank to savings at another is a bank transfer.

    Paying Rent

    Paying your landlord is a payment. Your bank may send the money electronically or mail a check.

    Buying Groceries

    A debit-card purchase is a payment, usually processed through a card network.

    Where ACH and Wire Transfers Fit In

    ACH is a U.S. electronic network used for transactions such as direct deposits, bill payments, and bank transfers. Wire transfers use wire networks and may suit urgent or high-value transactions. Fees, availability, and processing times depend on the provider and transfer details.

    Beginner Tip

    Check the recipient’s details, fees, and expected delivery time before authorizing a transaction. A confirmation screen does not necessarily mean the money has arrived.

    How Bank Transfers and Payments Work

    A typical electronic transaction has three stages: authorization, processing, and completion. The exact steps depend on whether you use an ACH transfer, wire transfer, debit card, or payment service.

    STEP 1

    Authorize

    Enter the amount and recipient details, review any fee, and approve the transaction through your bank or payment provider.

    STEP 2

    Process

    The relevant bank or payment network handles the transaction according to its rules, checks, and processing schedule.

    STEP 3

    Complete

    The payment or transfer reaches the applicable completion stage. When funds become available depends on the method and provider.

    Why Processing Times Differ

    ACH transfers may take longer than some faster electronic payment options. Wire transfers have their own deadlines and processing rules, while a debit-card authorization can appear before final settlement. Cutoff times, weekends, holidays, and provider policies can also affect timing.

    Before You Send Money

    Double-check the recipient, account details, and amount. For an unexpected request, verify it using a trusted contact method before authorizing the transaction.

    How Bank Transfers and Payments Work

    An electronic transaction generally involves authorizing the transaction, processing it through the relevant bank or payment network, and completing the transfer or payment. The exact process depends on the method you choose.

    STEP 1

    Authorize

    Enter the amount and recipient details, review any fee, and approve the transaction through your bank or payment provider.

    STEP 2

    Process

    The transaction is routed and handled under the relevant network’s rules. Processing may include verification and other required checks.

    STEP 3

    Complete

    The transaction progresses to completion, and the recipient’s access to the funds depends on the payment method and provider.

    Why Processing Times Differ

    ACH transfers follow ACH network processing schedules, while wire transfers have separate deadlines and procedures. Debit-card transactions may show a pending authorization before final settlement. Bank cutoff times, weekends, holidays, and provider policies can affect when a transaction is completed or funds become available.

    Before You Send Money

    Verify the recipient’s details and the amount before approving a transaction. If a payment request is unexpected, contact the person or organization through a trusted, independently verified channel.

    Benefits and Drawbacks of Bank Transfers and Payments

    Bank transfers and payment methods offer convenience, but the right choice depends on your purpose, timing, fees, and risk tolerance.

    Benefits

    • Move money electronically without handling cash.
    • Use ACH for many direct deposits, bills, and recurring transfers.
    • Use cards or payment apps for convenient purchases and eligible person-to-person payments.
    • Choose wire transfers when their features and timing fit the transaction.

    Drawbacks

    • Fees and transfer limits vary by provider and method.
    • Processing and fund availability may take longer than expected.
    • Incorrect recipient details can cause delays or misdirected funds.
    • Scam payments may be difficult to recover, even when you contact your provider quickly.

    Before You Choose

    Compare fees, delivery estimates, limits, and applicable protections. Verify the recipient independently, and contact your bank or payment provider immediately if you suspect fraud.

    Bank Transfer vs. Payment: A Side-by-Side Comparison

    ACH and wire transfers are ways to move money between accounts. Debit cards and payment apps are commonly used to make payments, although an app may rely on a bank transfer or another payment network behind the scenes. Compare the options by purpose, timing, and cost—not by speed alone.

    Common U.S. transfer and payment options
    OptionTypical UseTimingCost
    ACH transferDirect deposits, bills, recurring transfersDepends on processing schedules and serviceBank or service fees may apply
    Wire transferCertain urgent or high-value transfersMay arrive the same business day; deadlines and checks matterSending or receiving fees may apply
    Debit cardIn-store and online purchasesAuthorization is often quick; settlement occurs laterCosts depend on account and transaction terms
    Payment appEligible person-to-person payments or purchasesApp payments and withdrawals to a bank may have different timelinesFees depend on the app, funding source, and transaction

    Timing, fees, limits, and dispute options vary by provider and transaction type. Review the applicable terms before authorizing a transaction.

    Which Option Fits Your Needs?

    ACH is commonly used for recurring bills and direct deposits. Debit cards suit many everyday purchases. A wire transfer may fit a transaction requiring that network’s capabilities. Before using a payment app, verify the recipient and understand the provider’s cancellation and dispute policies.

    Costs, Risks, and Tips for Safer Transactions

    The cost and risk of sending money depend on the payment method, provider, and transaction details. Compare fees, delivery estimates, and available protections before choosing an option.

    Understand the Possible Fees

    • ACH transfers: Many common transactions have no customer fee, but charges depend on the bank, account, and service.
    • Wire transfers: Domestic or international wires may involve sending, receiving, or intermediary-bank fees.
    • Cards and payment apps: Fees can vary by funding source, transaction type, and whether you choose an instant transfer.

    Recognize the Risks

    Incorrect recipient details can delay a transaction or send money to the wrong account. Scammers may impersonate banks, landlords, relatives, or businesses and pressure you to pay urgently. Some authorized transactions are difficult to reverse, so verify unexpected requests before sending money.

    Review these guides to learn about payment app scams and strengthen your account with this bank account security checklist.

    Before You Send Money

    • Confirm the recipient, account details, and amount.
    • Check fees, limits, and estimated delivery time.
    • Verify unexpected requests using a trusted contact method you find independently.
    • Enable transaction alerts and contact your bank immediately if you suspect fraud.

    Common Mistakes When Sending Money

    Rushing a transaction can lead to avoidable costs, delays, or financial loss. Before sending money, check these common mistakes.

    1. Selecting the Wrong Recipient

    A wrong account detail, phone number, or saved contact can direct a payment to the wrong person. Confirm the recipient and transaction details before authorizing it.

    2. Overlooking Fees and Timing

    Ignoring service fees, transfer limits, cutoff times, or estimated delivery can lead to unexpected costs or late payments.

    3. Trusting Urgent Payment Requests

    Scammers may impersonate a bank, landlord, relative, or business and pressure you to act quickly. Verify unexpected requests using contact details you already trust or independently obtain.

    Illustrative Example: A Rent Payment

    Fictional scenario: Jordan needs to pay $1,200 in monthly rent. An email claims the landlord has changed bank accounts and demands immediate payment to the new account.

    Rather than sending the money, Jordan contacts the landlord using the phone number listed on the signed lease. The landlord confirms that the payment instructions have not changed.

    Lesson: Never rely solely on an email or message announcing new payment details. Verify the change independently before transferring money.

    If you send money to the wrong recipient or suspect fraud, contact your bank or payment provider immediately. Ask what options are available to stop, recall, or dispute the transaction. Recovery is not guaranteed, and the available options depend on the payment method and circumstances.

    Who Should Choose a Bank Transfer or Another Payment Method?

    The right option depends on the purpose of the transaction, how quickly funds are needed, the cost, and the recipient’s payment options.

    Regular Bills

    ACH payments or bank bill pay can work well for recurring bills. Check the payment deadline and allow enough processing time.

    Everyday Purchases

    Debit cards are convenient for many in-store and online purchases. Review your account terms and check transactions for unfamiliar charges.

    Large or Urgent Transfers

    A wire transfer may fit certain high-value or time-sensitive transactions. Verify the recipient, fees, cutoff time, and receiving instructions first.

    Friends and Family

    A supported payment app can simplify person-to-person payments. Confirm the recipient because mistaken or scam payments may be difficult to recover.

    Before You Decide

    Compare the total cost, expected arrival time, recipient details, and applicable protections. The fastest-looking option may not be the best fit for every transaction.

    Frequently Asked Questions

    1. What is the difference between a bank transfer and a payment?

    A bank transfer describes moving money between accounts. A payment is money given to settle a purchase, bill, or other obligation. A payment may use a bank transfer as its underlying method.

    2. Is an ACH transfer the same as a wire transfer?

    No. ACH transactions use the U.S. Automated Clearing House network for activities such as direct deposits and bill payments. Wire transfers use wire networks and have different processing procedures, fees, and rules.

    3. Which is faster: a bank transfer or a payment?

    It depends on the method and provider. Some card or app transactions are authorized quickly, while ACH and wire transfers follow their own processing schedules. Authorization does not necessarily mean the funds have fully settled or are available to the recipient.

    4. Do bank transfers usually have fees?

    Some transfers are free, while others carry fees. The cost depends on the bank, account, transfer type, destination, and service. Review the applicable fee schedule before confirming the transaction.

    5. Can I cancel a bank transfer after sending it?

    Not always. Cancellation or recall options depend on the transfer method, transaction status, and provider rules. Contact your bank promptly if you entered incorrect details or suspect fraud.

    6. Are payment apps considered bank transfers?

    Not necessarily. A payment app is a service for sending or receiving money. Depending on the app and transaction, funds may move through an app balance, linked bank account, card, or another supported method.

    7. Which option is safer for sending money?

    No method is risk-free, and protections differ by transaction type. Use a trusted provider, verify the recipient, secure your account, and understand the applicable dispute process. Treat unexpected urgent payment requests with caution.

    8. What should I do if I send money to the wrong person?

    Contact your bank or payment provider immediately. Explain the mistake and ask whether a cancellation, recall, or dispute is available. Recovery is not guaranteed; provide accurate transaction details and follow the provider’s instructions.

    Final Verdict: Bank Transfer vs. Payment

    The key difference in bank transfer vs. payment is what each term describes. A bank transfer explains how money moves between accounts, while a payment is made to settle a purchase, bill, or other obligation. A payment may be completed through a bank transfer, debit card, or payment app.

    Choose based on the transaction, not just convenience. ACH may suit eligible recurring bills, debit cards work well for many everyday purchases, and wire transfers may fit certain high-value or time-sensitive transactions. Compare fees, expected timing, recipient details, and applicable protections before authorizing payment.

    Continue Learning

    For a broader explanation of how money moves through the U.S. banking system, explore our complete guide to bank transfers and payments.

    FinanceInvestment

    Make More Confident Banking Decisions

    Understanding bank transfers and payment methods can help you compare costs, check processing times, and make informed financial decisions. Always verify transaction details and choose a method that fits your needs.

    Have a question or feedback about this guide? You can contact FinanceInvestment by email.


    Email FinanceInvestment

    This link opens your device’s default email application, if configured.

    Explore More Banking Guides

    Continue learning with these related FinanceInvestment resources.

    How ACH Transfers Work

    Understand how ACH is used for direct deposits, bills, and electronic transfers.

    Bank Account Security Checklist

    Find practical ways to protect your account and monitor transactions.

    How to Use Online Banking Safely

    Learn safer habits for accessing accounts and managing digital transactions.

  • How to Transfer Money From One Bank to Another (2026)

    How to Transfer Money From One Bank to Another (2026)

    BANKING & MONEY TRANSFERS

    How to Transfer Money From One Bank to Another

    Written by Subhash Rukade
    Founder, FinanceInvestment
    Publish date: October,  25, – 10.


    how to transfer money from one bank to another

    Knowing how to transfer money from one bank to another can make it easier to manage savings, pay bills, move money between your own accounts, or send funds to someone else. In the United States, the right method depends on how quickly the money needs to arrive, the amount you’re sending, and the fees or transfer limits that apply.

    Most people can start a transfer through their bank’s website or mobile app. Depending on the banks and services involved, options may include an external bank transfer using ACH, a domestic wire transfer, or a supported person-to-person payment service. Processing times, costs, and protections vary, so the fastest option isn’t always the most practical one.

    This guide walks you through the process, explains the differences between common transfer methods, and shows you how to reduce avoidable mistakes. For more background, visit our guide to bank transfers and payment methods.

    What You’ll Learn

    • How to initiate a transfer between two different banks.
    • When to use ACH transfers, wire transfers, or payment apps.
    • How transfer fees, limits, and delivery times can differ.
    • Which account details you may need before getting started.
    • How to avoid common errors and reduce transfer-related risks.

    Quick Answer

    What Is the Best Way to Transfer Money Between Banks?

    For routine transfers between your own U.S. bank accounts, an external bank transfer using ACH is often a cost-effective choice, and many banks offer it without a fee. Transfers commonly take one to three business days, but timing varies. A domestic wire transfer may suit urgent or large payments when the receiving bank can process it promptly and the fees are acceptable. For sending money to another person, an eligible payment app may be convenient. Before choosing, compare fees, transfer limits, delivery estimates, and available protections.

    Key Takeaways

    • Compare fees: Check whether the sending or receiving bank charges for the transfer.
    • Plan around timing: Weekends, holidays, bank cutoff times, and verification checks can delay delivery.
    • Verify account details: Double-check the recipient’s routing number and account number before submitting the transfer.
    • Check limits: Confirm your bank’s daily or per-transfer limits, especially for large amounts.
    • Stay alert: Use official banking channels and independently verify unexpected requests to send money.

    Table of Contents

    Use the links below to explore bank transfer methods, compare costs and timing, and learn how to move money between accounts safely.

    1. Article Title and Author
    2. Introduction: How to Transfer Money From One Bank to Another
    3. Quick Answer
    4. Table of Contents
    5. Bank Transfer Methods at a Glance
    6. A Beginner’s Guide to Bank Transfers
    7. How to Transfer Money Step by Step
    8. Benefits and Drawbacks
    9. ACH vs. Wire Transfers vs. Payment Apps
    10. Transfer Fees, Risks, and Expert Tips
    11. Common Mistakes and How to Avoid Them
    12. Who Should Choose Each Transfer Method?
    13. Frequently Asked Questions
    14. Final Verdict
    15. Related Resources and Further Reading
    16. Contact FinanceInvestment

    Bank Transfer Methods at a Glance

    If you’re deciding how to transfer money from one bank to another, compare the available methods before you send it. The right choice depends on how quickly the money must arrive, the amount you’re transferring, and the fees and limits set by your bank or payment service.

    Transfer MethodTypical TimingTypical CostBest Use
    External bank transfer (usually ACH)Often 1–3 business days; bank policies varyOften free, but check both banks’ termsMoving money between your own accounts
    Domestic wire transferMay arrive the same business day if submitted before the cutoff and processed in timeSending or receiving fees may applyUrgent payments or transactions requiring a wire
    Real-time bank paymentCan be completed within seconds when both banks and accounts are eligibleDepends on the payment network and bankEligible payments where speed is important
    Person-to-person payment appMay be quick within the service; moving funds to a bank can take longerVaries by app, payment source, and withdrawal speedSending money to another person through a supported service

    Important: Timing and fees are general estimates, not guarantees. Weekends, federal holidays, bank cutoff times, transfer limits, account verification, and fraud checks can affect processing. Real-time payment availability depends on the specific network and participating institutions.

    Quick Take

    For routine transfers between your own accounts, check whether an ACH transfer is available and free. If you need the money to arrive sooner, ask your bank about wire or real-time payment options, confirm eligibility and limits, and compare the total cost before proceeding.

    A Beginner’s Guide to Bank Transfershow to transfer money from one bank to another

    An external bank transfer moves money between accounts held at different financial institutions. In the United States, many banks process these transfers through the Automated Clearing House (ACH) network. To get started, sign in to your bank’s official website or mobile app, choose the external transfer option, and follow the instructions to link the receiving account. Available options and processing times vary by bank.

    Understanding Routing and Account Numbers

    A routing number identifies a financial institution for a particular transaction type, while an account number identifies the specific bank account. You may need both to set up a transfer. Do not assume the routing number printed on a check is suitable for every transaction; confirm the correct details with your bank. Read our guide on how to find your checking account routing number.

    Verifying the External Bank Account

    Before allowing transfers, your bank may require you to verify ownership of the external account. Depending on the institution, verification may use a secure connection, login-based verification, small test deposits called micro-deposits, or another approved process. Complete the steps through your bank’s official channel and allow extra time if verification is required.

    Beginner tip: Before confirming a transfer, check the receiving account details, amount, fees, and estimated delivery date. Never share your banking password or one-time verification code with someone who contacts you unexpectedly. If anything looks unfamiliar, contact your bank using its verified phone number or official app.

    How to Transfer Money From One Bank to Another: Step by Step

    Most transfers between U.S. bank accounts can be started online or through a mobile banking app. The exact process depends on your bank and the transfer method, but these steps can help you prepare and avoid common errors.

    1. Sign in to your bank.
      Use the bank’s official website or mobile app and look for “Transfers,” “External Transfers,” or a similar option.
    2. Add the receiving account.
      Enter the requested details, which may include the bank routing number and account number. Follow the bank’s instructions to verify account ownership, if required.
    3. Choose the accounts and amount.
      Select the sending and receiving accounts, enter the amount, and choose a transfer date or frequency if scheduling is available.
    4. Review the transfer carefully.
      Confirm the account details, amount, fees, transfer limits, and estimated delivery date. Correct any errors before authorizing the transaction.
    5. Authorize and save confirmation.
      Complete any required security checks and submit the transfer. Save the confirmation number or receipt for future reference.
    6. Track the status and verify delivery.
      Check your bank’s transfer history for updates. Once the transfer is expected to arrive, confirm that the receiving account shows the funds. If the transfer is delayed or the status is unclear, contact your bank through an official channel.

    Important: A confirmation screen only shows that the request was submitted or accepted for processing; it does not always mean the money has arrived. Keep your receipt until the transfer is complete, and never share your banking password or one-time security code with someone who contacts you unexpectedly.

    Benefits and Drawbacks of Bank Transfers

    Bank transfers can make everyday money management easier, especially when you need to move funds between accounts at different banks. However, costs, delivery times, and payment protections vary depending on the method and the institutions involved.

    Benefits

    • Transfer money online without visiting a bank branch.
    • Use ACH transfers that may be free or inexpensive, depending on your bank.
    • Move funds between personal accounts and manage bills or savings more conveniently.
    • Review transaction records to help track deposits and payments.

    Drawbacks

    • Standard transfers may take several business days.
    • Wire transfers and expedited services may carry fees.
    • Banks can impose transfer limits, verification steps, or processing holds.
    • Incorrect account details and fraudulent payment requests can lead to financial loss.

    How to Choose the Right Method

    For routine transfers between your own accounts, compare ACH options and their fees. If the payment is urgent, ask your bank about wire transfers or eligible real-time payment services. Check the delivery estimate, transfer limits, and total cost before sending money, and verify the receiving account details carefully.

    ACH vs. Wire Transfers vs. Payment Apps

    In the United States, ACH transfers, wire transfers, and payment apps serve different needs. ACH is commonly used for routine bank payments, wires can suit urgent or high-value transactions, and payment apps are often convenient for eligible person-to-person payments. Compare their typical timing, costs, and requirements before deciding.

    FeatureACH TransferWire TransferPayment Apps
    Typical speedOften 1–3 business days; timing variesMay arrive the same business day if processed before the cutoffMay be quick within the service; bank withdrawals can take longer
    Typical costOften free, but fees may applySending or receiving fees may applyDepends on the app, payment source, and withdrawal speed
    Best useRoutine transfers and eligible bill paymentsUrgent or wire-required paymentsEligible payments between individuals
    Before sendingCheck transfer limits, processing time, and account detailsConfirm recipient details, cutoff time, and total feesVerify the recipient, payment limits, and withdrawal terms

    These are general estimates, not guarantees. Actual delivery times and fees depend on your bank, payment service, transaction details, processing schedule, and any required verification.

    Which Option Should You Choose?

    For routine transfers between your own bank accounts, compare the bank’s ACH options first. If timing is critical, ask about wire transfers or eligible real-time bank payments. Use a payment app when it suits the recipient and payment type. Before confirming any transaction, check the total cost, delivery estimate, limits, and recipient details.

    Transfer Fees, Risks, and Expert Tips

    Before moving money between banks, check more than the advertised transfer fee. Processing delays, account restrictions, and incorrect payment details can cause complications or unexpected costs. Reviewing the terms and recipient information before authorizing a transfer can help you avoid preventable problems.

    Fees and Costs to Check

    • Wire transfer fees: The sending bank may charge a fee, and the receiving bank may charge one too.
    • Faster delivery: Expedited services may cost more than standard transfers.
    • Returned payments or overdrafts: A rejected transaction or insufficient balance may lead to additional charges, depending on your account terms.
    • Payment app fees: Fees may apply based on the funding source, payment type, or withdrawal speed.

    How to Reduce Transfer Risks

    • Verify account details: Confirm the recipient’s name and the correct routing and account numbers before sending.
    • Watch for payment scams: Independently confirm unexpected requests to change bank details or send money, especially requests that create urgency.
    • Secure your account: Use your bank’s official website or app. Never share your password or one-time security code with someone who contacts you unexpectedly.
    • Keep transaction records: Save the confirmation number and monitor the transfer until its status is clear.

    Expert Tip: Act Quickly if Something Goes Wrong

    If you notice an unfamiliar transaction, enter incorrect transfer details, or suspect a scam, contact your bank or payment provider immediately through an official channel. Ask whether the payment can be stopped, recalled, or investigated. Recovery is not guaranteed, particularly after certain payments have been completed, so do not delay reporting the problem.

    Common Mistakes and How to Avoid Them

    A small mistake can delay a bank transfer or create extra work. Before sending money, check these common problems and how to prevent them.

    1. Entering Incorrect Account Details

    An incorrect routing or account number may cause a transfer to be rejected, delayed, or sent to an unintended account. Verify the details with the receiving bank or account holder before authorizing the payment.

    2. Underestimating Transfer Time

    An ACH transfer started on Friday may not arrive immediately. Weekends, federal holidays, cutoff times, and bank processing schedules can affect delivery. Check the estimated arrival date and allow extra time for bills or other deadlines.

    3. Submitting a Duplicate Transfer

    If a payment remains pending, sending it again could result in two transfers. Check your transaction history and confirmation number first. If the status is unclear, contact your bank before retrying.

    4. Trusting Unexpected Payment Instructions

    A scammer may impersonate a vendor, family member, or bank employee and request an urgent payment or new account details. Independently verify the request using a trusted phone number or previously confirmed contact method.

    If something goes wrong: Contact your bank or payment provider promptly if you notice an incorrect transfer, duplicate payment, or suspected scam. Ask whether the transaction can be stopped, recalled, or investigated. Recovery is not guaranteed, so report the problem as soon as possible.

    Who Should Choose Each Transfer Method?

    Choose your transfer method based on the recipient, urgency, cost, and your bank’s requirements.

    Routine Transfers Between Your Own Accounts

    Consider ACH: Often a practical, low-cost option when you can wait for processing. Check fees, limits, and the estimated arrival date.

    Urgent or Wire-Required Payments

    Consider a wire: It may suit time-sensitive transactions, but confirm the recipient’s requirements, cutoff time, fees, and expected delivery before sending.

    Payments to Friends or Family

    Consider a supported payment app: It can be convenient for eligible person-to-person payments. Verify the recipient and review the app’s limits, fees, and protections.

    Practical rule: Compare total cost, delivery time, eligibility, and available protections. Never choose a method based on speed alone.

    Frequently Asked Questions

    1. How long does it take to transfer money between banks?

    Many ACH transfers take one to three business days, although timing varies by bank. Domestic wires may arrive the same business day if processed before the cutoff. Verification, weekends, and holidays can affect delivery.

    2. Is transferring money between banks free?

    Some banks offer standard ACH transfers at no charge. Wire transfers and expedited services may cost extra. Check the fees charged by both banks and any applicable service before confirming.

    3. What information do I need for a bank transfer?

    Depending on the method, you may need the recipient’s name, routing number, account number, and transfer amount. Follow your bank’s instructions and confirm the details before authorizing the payment.

    4. Can I transfer money between banks online?

    Yes. Many U.S. banks support transfers through online banking or mobile apps. You may need to add the receiving account and complete verification before sending money.

    5. Are there limits on bank transfers?

    Yes, banks may set per-transfer, daily, or other limits. The amount you can send depends on your account, transfer method, and bank policies. Ask your bank about limits before making a large payment.

    6. Why is my bank transfer delayed?

    Common reasons include weekends, holidays, cutoff times, account verification, security reviews, or incorrect details. Check the transaction status and contact your bank if the delay exceeds its estimate.

    7. Can I cancel a bank transfer after submitting it?

    Sometimes. A scheduled transfer may be cancellable before processing, but a transfer already sent may be difficult or impossible to reverse. Contact your bank immediately to ask about available options.

    8. How can I transfer money safely?

    Use your bank’s official website or app, verify recipient details, and review fees before sending. Independently confirm unexpected payment requests, never share security codes, and report suspected fraud to your bank promptly.

    Final Verdict: Choose the Right Way to Transfer Money

    For routine transfers between your own U.S. bank accounts, an ACH transfer is often a practical, low-cost starting point. If a payment is urgent or the recipient requires a wire, compare the available options, fees, cutoff times, and delivery estimates before sending. Payment apps can be convenient for eligible transfers to friends and family, but check their limits and protections.

    Before confirming any transfer, verify the recipient’s details and use your bank’s official website or app. Keep the confirmation and check that the money arrives. The best method is the one that fits your timing, budget, and security needs.

    Need more guidance? Read our
    complete guide to bank transfers and payment methods
    to explore your options.

    Have Questions About Bank Transfers?

    Have feedback or a suggestion for this guide? Email FinanceInvestment at

    For pending, delayed, or incorrect transfers, contact your bank directly.

    Explore More Banking Guides

    Learn more in our guide to
    bank transfers and payment methods
    or review our
    bank account security checklist
    for practical account-protection tips.

  • How to Transfer Money Between Bank Accounts (2026)

    How to Transfer Money Between Bank Accounts (2026)

    PERSONAL BANKING GUIDE

    How to Transfer Money Between Bank Accounts

    Written by Subhash Rukade
    Founder, FinanceInvestment
    Publish date: October,  25, 10.
    Reading Time: 10, Menits.

    how to transfer money between bank accounts

    How to Transfer Money Between Bank Accounts

    Your paycheck may arrive in one bank account while your savings sit in another. You might need to move money to cover rent, add funds to a joint household account, or put extra cash into an account that earns a better interest rate. Knowing how to transfer money between bank accounts helps you handle these everyday tasks without unnecessary hassle.

    The best method depends on where your accounts are held, how quickly the money needs to arrive, and what your bank charges. Transfers between accounts at the same bank may be quick, while transfers between different banks can take one or more business days. Wire transfers may suit certain time-sensitive payments, but they can cost more. Bank cutoff times, weekends, holidays, security checks, and transfer limits can also affect the process.

    Not sure how ACH transfers and wire payments differ? Start with our
    complete guide to bank transfers and payments
    for a broader look at common U.S. payment methods. Here, we’ll focus on the steps, costs, and precautions involved in moving money between bank accounts.

    What You’ll Learn

    • How to move money between accounts at the same bank or different banks.
    • When to consider ACH transfers, wire transfers, and other options.
    • How to check transfer fees, limits, and estimated arrival times.
    • How to avoid common mistakes and protect your money.

    QUICK ANSWER

    What Is the Best Way to Transfer Money Between Bank Accounts?

    For routine transfers, start by checking your bank’s online or mobile banking options. Transfers between accounts at the same bank may be straightforward, while transfers between different banks often use ACH. A wire transfer may be appropriate when a payment is time-sensitive or involves a large amount, but fees can apply. The right choice depends on your bank’s available services, delivery estimates, transfer limits, and the recipient’s details.

    Key Takeaways

    • Transfers at the same bank:
      You can often move money between eligible accounts through online or mobile banking. Availability and posting times vary.
    • Transfers between different banks:
      You may need to link the external account and complete the bank’s verification process before sending money.
    • ACH transfers:
      Standard ACH payments commonly take one to three business days, although the actual timing depends on the payment and the institutions involved.
    • Wire transfers:
      Eligible domestic wires may arrive the same business day when sent before the applicable cutoff time. Arrival is not guaranteed, and fees may apply.
    • Fees and limits:
      Review your bank’s current fee schedule, daily limits, and per-transfer restrictions before moving a large amount.
    • Security matters:
      Verify the recipient and account details independently. If you notice an error or suspect fraud, contact your bank immediately.

    The Bottom Line

    For everyday banking, an internal transfer or ACH transfer may be all you need. For a time-sensitive payment, compare wire options and costs before proceeding. Whichever method you choose, confirm the recipient, understand the expected delivery time, and keep the confirmation for your records.

    Table of Contents

    Find the transfer method, practical steps, fees, safety tips, or answers you need.

    Bank Transfer Methods at a Glance

    Moving money between bank accounts can be simple, but the best option depends on how quickly you need the funds, where the accounts are held, and what the transfer costs. Here is a quick comparison of common methods in the United States.

    Quick Facts

    • Transfers between eligible accounts at the same bank may be available quickly, depending on the bank’s systems and account rules.
    • ACH transfers are commonly used for routine payments between U.S. bank accounts.
    • Eligible domestic wire transfers may arrive the same business day if submitted before the applicable cutoff time.
    • Fees, transfer limits, and delivery times depend on the bank, payment method, and transaction details.

    Compare Bank Transfer Options

    MethodTypical timingBest suited forTypical cost
    Same-bank transferMay be quick; timing variesMoving funds between eligible accounts at one bankOften free
    ACH transferStandard transfers commonly take 1–3 business daysRoutine transfers between bank accountsOften low-cost; fees vary
    Wire transferSame-business-day delivery may be possibleEligible large or time-sensitive paymentsFees often apply
    P2P payment serviceDepends on the service and withdrawal methodSending money to another personDepends on the service and transaction type

    Before you transfer:
    Check the current fees, transfer limits, estimated delivery date, and recipient details in your bank’s official app or website. Processing estimates can change, and a submitted transfer is not always immediately available to the recipient.

    A Beginner’s Guide to Bank-to-Bank Transfershow to transfer money between bank accounts

    Before moving money, check whether both accounts are held at the same bank or at different financial institutions. This affects which transfer options are available, what information you need, and how the transfer is processed.

    Internal vs. External Transfers

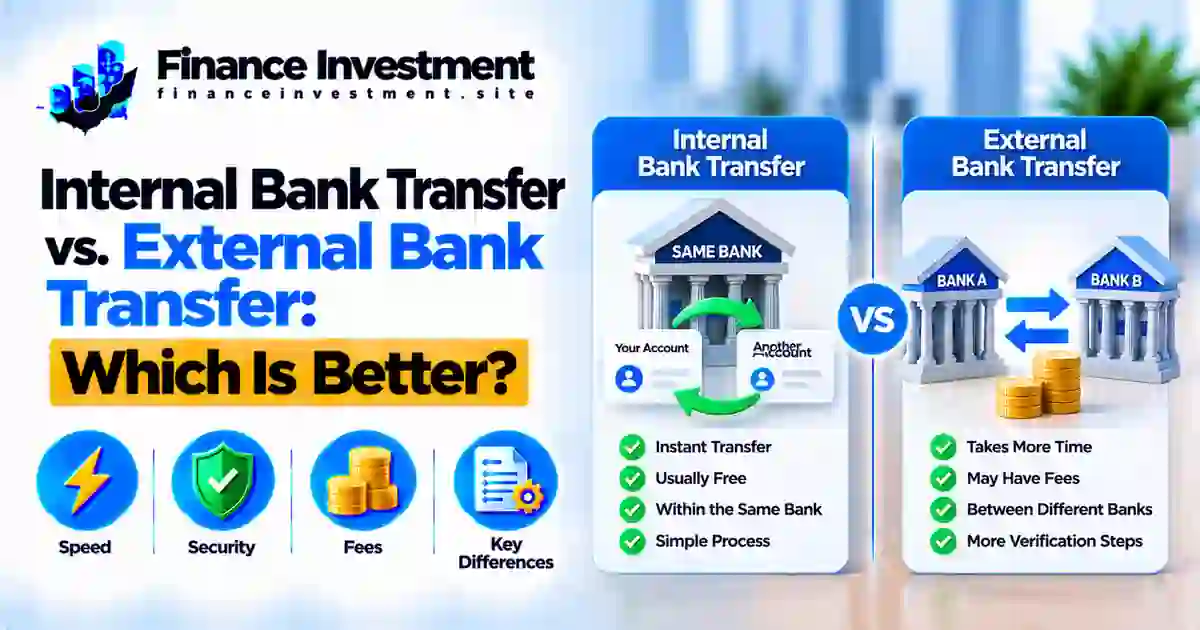
    An internal transfer moves money between eligible accounts at the same bank, such as your checking and savings accounts. You can often start one through online banking or the bank’s mobile app. An external transfer moves money between accounts at different banks or credit unions. Depending on the institution, you may need to add and verify the external account before sending funds.

    Linking Accounts and Finding the Right Details

    For many U.S. bank transfers, you may need the receiving account’s routing number and account number. A routing number identifies a financial institution for a particular type of transaction, while an account number identifies the individual account. The exact details required depend on the transfer method.

    Banks may verify an external account through a secure connection or small trial deposits that you confirm later. Follow the instructions provided by your own bank and double-check the details before submitting a transfer. For help locating this information, read our guide to checking account routing numbers.

    Safety tip:
    Open your bank’s official website or app yourself when linking accounts. Never disclose your password or one-time security code to an unexpected caller or message claiming to be from your bank.

    How to Transfer Money Between Bank Accounts Step by Step

    Most U.S. banks allow customers to initiate transfers through online banking or a mobile app. Although menu names and requirements vary, these steps can help you move money more carefully.

    Step 1: Open Your Bank’s Transfer Menu

    Sign in through your bank’s official website or app. Look for an option such as “Transfers,” “Move Money,” or “External Accounts.” Choose the transfer method available for your accounts.

    Step 2: Select the Sending and Receiving Accounts

    Choose the account the money will come from and the account that will receive it. If you are adding an external account, complete your bank’s required linking and verification process before proceeding.

    Step 3: Verify the Banking Details

    For an account you own, confirm the linked account details. When sending money to someone else, independently verify the recipient’s name and payment instructions. Check routing and account numbers whenever the chosen method requires them.

    Step 4: Enter the Amount and Check the Delivery Date

    Enter the amount and choose an available transfer date. Review fees, transfer limits, and the estimated arrival time. Bank cutoff times, weekends, holidays, and security reviews may affect processing. Make sure sufficient funds are available.

    Step 5: Review, Submit, and Save the Confirmation

    Check the amount, accounts, fees, and scheduled date before confirming. Save the confirmation number or receipt, then monitor your account activity until the transfer is completed.

    Important:
    Cancellation options depend on the transfer method and its status. If you spot an error or suspect fraud, contact your bank immediately. Do not assume a submitted payment can be stopped or reversed.

    Benefits and Drawbacks of Bank Transfers

    Bank transfers can simplify everyday money management, from moving savings into a checking account to funding an account at another bank. Before choosing a method, consider its convenience, cost, processing time, and potential risks.

    Benefits of Bank Transfers

    • Convenient access: Many banks let you initiate eligible transfers through online banking or a mobile app without visiting a branch.
    • Potentially lower costs: Transfers between your own accounts and standard ACH transfers may be free or inexpensive, depending on the bank and transaction.
    • Flexible money management: You can organize household spending, move money into savings, or keep funds in separate accounts for different goals.
    • Useful transaction records: Confirmations and account statements can help you track payments and reconcile your finances.

    Drawbacks to Consider

    • Possible delays: External transfers may take several business days. Cutoff times, weekends, holidays, and bank processing rules can affect arrival.
    • Fees and restrictions: Some transfer methods have service charges, daily limits, or account eligibility requirements.
    • Errors and fraud exposure: Incorrect payment details can delay or misdirect a transfer. Money voluntarily sent to a scammer may be difficult to recover.

    Before you transfer:
    Check your bank’s current fees, limits, and estimated delivery date. Verify the recipient and payment instructions independently, especially when transferring a large amount or sending money to someone new.

    Compare ACH vs. Wire vs. Zelle vs. Other Transfer Methods

    Not every payment method works the same way. An ACH transfer or wire can move funds between eligible bank accounts, while Zelle is designed primarily for eligible payments between people. Compare the purpose, delivery estimate, and cost before choosing.

    MethodBest suited forTiming and cost
    ACH transferRoutine transfers between eligible U.S. bank accountsStandard transfers commonly take 1–3 business days; fees and timing vary.
    Wire transferPayments that require a wire or have a tight deadlineEligible domestic wires may arrive the same business day; fees often apply.
    ZelleEligible payments to people you know and trustPayments to enrolled recipients are typically fast; availability and limits apply.
    Same-bank transferMoving money between eligible accounts at one bankOften quick and free, depending on account terms and bank processing.
    Other P2P appsPersonal payments through supported payment servicesDelivery speed and fees depend on the service and withdrawal option.

    Which Transfer Method Should You Choose?

    For routine transfers between your own accounts at different banks, an external ACH transfer is often a practical starting point. Consider a wire if the receiving institution requires one or the payment deadline makes it appropriate; check the fee and cutoff time first. Zelle is intended for eligible person-to-person payments, so do not assume it can replace an external bank transfer for every purpose. Other payment apps have their own eligibility rules, fees, and withdrawal options.

    Safety reminder:
    Before sending money through Zelle or another payment service, verify the recipient and payment purpose. Payments to enrolled recipients can be difficult to reverse if you send money to the wrong person or voluntarily pay a scammer. Read our guide to recognizing and avoiding Zelle scams.

    Bank Transfer Costs, Risks & Expert Tips

    Before moving money, check more than the delivery estimate. Transfer fees, account limits, processing rules, and security risks can all affect your transaction. A few checks before submitting a payment can help prevent avoidable problems.

    Check Fees and Transfer Limits

    Internal transfers and standard ACH transfers may be free, while wire transfers often carry fees. Your bank may also impose per-transfer or daily limits, account eligibility rules, or additional verification requirements. Check the current fee schedule and transfer terms before sending money, particularly for a large payment.

    Protect Your Banking Information

    • Use your bank’s official website or mobile app, and enable multifactor authentication and transaction alerts when available.
    • Verify the recipient and payment instructions independently. If someone unexpectedly changes bank details, confirm the change through a previously trusted phone number.
    • Never disclose your password or one-time security code to an unexpected caller, text sender, or email contact claiming to represent your bank.

    What to Do If a Transfer Goes Wrong

    If you enter incorrect details, send money to the wrong recipient, or suspect fraud, contact your bank immediately using its official contact information. Provide the transaction amount, date, recipient details, and confirmation number. Ask whether the transfer can be stopped, recalled, or investigated; the available options depend on the payment method and transaction status. Keep receipts and relevant messages, and follow the bank’s reporting instructions. A reversal or recovery is not guaranteed.

    Expert tip:
    Save your transfer confirmation and check your account activity until the transaction is complete. For more ways to protect your money, use our bank account security checklist.

    Common Bank Transfer Mistakes and How to Avoid Them

    A routine bank transfer can become stressful when details are incorrect or the money takes longer than expected to arrive. These simple checks can help you avoid common problems.

    • Entering incorrect account details:
      Double-check the routing number, account number, and recipient information before confirming. If you discover an error after submitting the transfer, contact your bank immediately.
    • Sending a duplicate payment:
      Check your transaction history and transfer status before submitting another payment. A pending transaction may still be processing.
    • Ignoring processing times:
      Bank cutoff times, weekends, holidays, and verification checks can affect when funds arrive.
    • Overlooking fees and limits:
      Review the bank’s current transfer limits, fees, and account requirements before sending money.

    Real-Life Example: A Delayed Rent Transfer

    Imagine Sarah schedules a $1,200 ACH transfer from her savings account to her checking account to cover rent. The money does not appear immediately, so she assumes the transfer failed and submits another one. Later, both transfers process, leaving her checking account with an unexpected extra $1,200 deposit and her savings balance reduced by the same amount twice.

    Sarah could have avoided the duplicate by checking the transfer status and estimated arrival date before acting. If a transfer appears delayed, review your bank activity and contact the bank when needed. Do not assume a payment has failed simply because the funds have not appeared yet.

    Remember:
    Save the confirmation number, verify recipient details before submitting, and allow the stated processing time. If you suspect an incorrect or fraudulent transfer, contact your bank promptly.

    Who Should Choose Each Bank Transfer Method?

    The most suitable transfer method depends on who is receiving the money, how quickly it is needed, and which services your bank supports. Use these guidelines to narrow down your options.

    • Beginners:
      Start with an internal transfer if both eligible accounts are at the same bank. For accounts at different banks, consider a standard ACH transfer and review the setup instructions, fees, and estimated delivery date.
    • Families and joint-account users:
      Internal or external bank transfers can help organize household bills, savings, and shared expenses. Confirm which account is sending the money and keep a record of recurring transfers.
    • Retirees:
      Online transfers may simplify managing checking and savings accounts. Choose a method you can use confidently, verify account details carefully, and enable transaction alerts when available.
    • Urgent payments:
      A domestic wire may be appropriate when the recipient requires it or a deadline is close. Check the bank’s cutoff time, fees, and receiving instructions. Same-day arrival is not guaranteed.

    Choosing tip:
    Zelle may be convenient for eligible payments to people you know and trust, but it is not a universal substitute for moving money between your own bank accounts. Compare the available methods and verify the recipient before sending funds.

    Frequently Asked Questions About Bank Transfers

    1. How long does it take to transfer money between bank accounts?

    Transfers between eligible accounts at the same bank may be available quickly. Standard ACH transfers commonly take one to three business days, while eligible domestic wire transfers may arrive the same business day. Actual timing depends on the banks, cutoff times, and transaction details.

    2. Is it free to transfer money between bank accounts?

    Some internal and ACH transfers are free, but fees depend on your bank, account terms, and transfer method. Wire transfers often carry fees. Check your bank’s current fee schedule before sending money.

    3. What information do I need for an external bank transfer?

    Depending on the method, you may need the receiving bank’s routing number, account number, and account-holder details. Some banks offer secure account-linking services or other verification methods. Follow your bank’s instructions and confirm the details before submitting the transfer.

    4. Can I transfer money between banks on weekends?

    You may be able to schedule a transfer online during the weekend, but standard ACH processing generally follows business-day schedules. Processing may begin on the next business day, depending on the bank and transfer type. Check the estimated delivery date shown by your bank.

    5. Are there limits on how much money I can transfer?

    Banks and payment services may set per-transfer, daily, or other limits. Restrictions can depend on your account, transfer method, verification status, and the institution’s policies. Contact your bank before arranging a large transfer.

    6. What should I do if I enter the wrong account details?

    Contact your bank immediately and provide the transaction details and confirmation number. Ask whether the transfer can be stopped, recalled, or investigated. The available options depend on the payment method and transaction status, and recovery is not guaranteed.

    7. Can I cancel a bank transfer after submitting it?

    Cancellation depends on the transfer method, timing, and status. Some scheduled transfers may be cancellable before processing, while completed payments may be difficult or impossible to reverse. Contact your bank promptly if you need to stop a transfer.

    8. Can I use Zelle to transfer money between my own bank accounts?

    Zelle is designed primarily for eligible person-to-person payments, not as a universal method for moving money between your own bank accounts. For accounts at different banks, check whether an external ACH transfer is available. Use payment services only in accordance with their terms.


    Final Verdict: Choose the Right Bank Transfer Method

    Knowing how to transfer money between bank accounts starts with identifying your needs. For routine transfers between your own accounts at different banks, a standard ACH transfer is often a practical option. Moving money between eligible accounts at the same bank may be simpler, while a wire transfer can suit certain time-sensitive payments when the recipient accepts or requires it.

    Before sending money, compare fees, transfer limits, and estimated delivery times. Verify the receiving account details, use your bank’s official website or app, and save the confirmation for your records. If a transfer appears delayed, check its status with your bank before submitting another one.

    Explore More Bank Transfer Guides

    Want to understand other payment options? Read our complete guide to bank transfers and payments for an overview of common methods, how they work, and what to consider before moving your money.

    FINANCEINVESTMENT

    Make Your Next Bank Transfer with Confidence

    Before moving money, compare the available transfer methods, review the fees and estimated delivery time, and verify the recipient details. A few simple checks can help you avoid unnecessary delays and prevent common transfer mistakes.

    Continue Exploring Our Banking Guides

    Questions or Suggestions?

    Have feedback about this guide or an idea for a future banking article? You can contact FinanceInvestment by email.


    Email FinanceInvestment

    FinanceInvestment provides educational information, not individualized financial advice. For account-specific questions, contact your bank directly. Never email passwords, account numbers, one-time security codes, or other sensitive banking information.

  • Bank Transfers & Payments Guide: ACH, Wires & More (2026)

    Bank Transfers & Payments Guide: ACH, Wires & More (2026)

    Bank Transfers And Payments Explained: Complete Guide to ACH, Wire Transfers, Direct Deposit & Digital Payments (USA 2026)

    Written by Subhash Rukade

    Founder, FinanceInvestment


    Reading time: Approximately 18–20 minutes


    Published: October 24, 2026


    Last updated: October 24, 2026


    bank transfers and paymentsBank transfers and digital payments help people across the United States manage everyday finances, from receiving a paycheck and paying bills to moving savings between accounts or sending money to family. However, payment methods differ in processing time, fees, limits, and available protections. Knowing these differences can help you choose an option that fits your transaction.This guide explains the main U.S. payment methods, including Automated Clearing House (ACH) transfers, domestic and international wire transfers, direct deposit, online bill pay, and person-to-person payment apps. You’ll learn how they work, what they may cost, how long transfers can take, and what steps to consider when a payment is delayed, rejected, or sent to the wrong account.There is no single best method for every situation. ACH transfers are commonly used for recurring payments, while wire transfers may suit transactions that require funds to be sent through a bank wire. Payment apps offer another convenient option, but their fees, transaction limits, and dispute procedures vary.
    understanding bank security and fraud prevention
    Security is equally important. Fraudsters may impersonate bank employees, send fake payment instructions, or pressure people to transfer money quickly. For additional precautions, read our bank security and fraud prevention guide.

    What You’ll Learn

    • How ACH, wire transfers, direct deposit, and digital payments differ.
    • How transfer times, fees, limits, and processing cut-off times affect payments.
    • What to do when a transfer is delayed, rejected, or sent to the wrong account.
    • How to verify payment details and respond to suspected fraud.
    • How to compare payment methods for your needs.

    Quick Answer: Which Bank Transfer Method Should You Use?

    The right payment method depends on the transaction, delivery timing, fees, and provider rules. ACH transfers are widely used for payroll, recurring payments, and moving money between eligible bank accounts. Wire transfers are often used for large or time-sensitive payments, although fees and processing times vary. Direct deposit commonly delivers paychecks and eligible benefits electronically. Online bill pay and person-to-person payment apps serve other everyday needs. Before choosing, check the provider’s terms, confirm the recipient, and review the payment details carefully.

    Key Takeaways

    • Compare fees, transfer limits, expected arrival times, and convenience.
    • Check processing cut-off times, weekends, and holidays before relying on an estimated delivery date.
    • Verify recipient and account details before authorizing a transfer.
    • If a payment appears fraudulent, contact your bank or payment provider immediately.

    Bank Transfers & Payments at a Glance

    U.S. bank transfers and payment services use different processes to move money. Some are designed for recurring payments, others for sending funds directly to another person or institution. Compare the main options below, keeping in mind that processing times, fees, and limits depend on the bank, payment provider, and transaction.

    MethodCommon usesTiming and costWhat to check
    ACH transferAccount-to-account transfers, payroll, recurring paymentsOften low-cost; standard and Same-Day ACH have different processing windowsAvailability, cut-off times, limits
    Wire transferProperty closings, large payments, some international transfersMay be processed quickly during banking hours; sending or receiving fees may applyRecipient details, fees, cut-off time
    Direct depositPaychecks and eligible benefit paymentsUsually arranged through the payer and commonly processed through ACHCorrect account details and payer’s schedule
    Online bill payUtilities, loans, credit cards, other billsMay be sent electronically or by paper check, depending on the biller and bankDelivery date, biller processing time, any fees
    P2P payment appsSending money to friends or familyDelivery speed and fees vary by service, funding source, and transfer optionRecipient identity, account security, dispute rules

    How to Choose the Right Method

    ACH may be suitable for routine account transfers and recurring payments. A wire transfer may fit a transaction that specifically requires a bank wire. Direct deposit is generally set up through an employer or benefit payer, while online bill pay is designed for paying bills. P2P apps can be convenient for sending money to people you know, but their terms and protections differ.

    Before confirming a payment, check the provider’s current fees, delivery estimate, transfer limits, and cancellation options.

    Bank Transfer Basics: How Money Movesbank transfers and payments

    A bank transfer moves money electronically between accounts. The route, processing time, and cost depend on whether the accounts are held at the same bank, at different financial institutions, or accessed through a payment service. Understanding the basics helps you select an appropriate method and avoid timing surprises.

    Internal vs. External Bank Transfers

    An internal transfer moves money between accounts at the same financial institution, such as transferring funds from your checking account to your savings account at that bank. These transfers may be completed quickly, although timing depends on the bank and transaction type. An external transfer moves money between accounts at different financial institutions. It may require account verification and additional processing time.

    Bank Transfer vs. Payment

    A bank transfer describes moving funds between accounts, while a payment uses funds to pay a person, business, or organization. Moving money from checking to savings is a transfer; paying your electricity bill is a payment. Many electronic payments still rely on transfer networks behind the scenes, so the terms can overlap in everyday banking.checking account routing numbers explained

    ACH Push vs. ACH Pull

    An ACH push occurs when you instruct your bank to send money to another account through the ACH network. An ACH pull occurs when an authorized business or service requests money from your account—for example, to collect an automatic utility payment. Before authorizing a pull, review the payment amount, timing, and terms, and make sure the requester is legitimate. ACH Transfer vs. Paper Check

    Scheduled vs. Immediate Transfers

    A scheduled transfer is arranged for a future date or recurring interval. An immediate transfer is submitted for processing as soon as the service allows. Neither label guarantees instant arrival: cut-off times, weekends, holidays, verification checks, and the transfer method can affect when funds become available. Check the bank’s estimated delivery date before relying on the money.

    Before confirming any transfer, verify the recipient’s details, amount, source account, and expected arrival time. The next section explains ACH transfers in greater detail, including how they work and when they may be useful.
    ACH Transfer vs. Paper Check: Key Differences

    ACH Transfers Explained

    The Automated Clearing House (ACH) network processes electronic payments between U.S. bank and credit union accounts. It supports everyday transactions such as payroll deposits, recurring bills, government benefit payments, and transfers between accounts at different financial institutions. ACH is often a cost-effective choice for routine payments, although fees, processing times, and fund availability depend on the banks and transaction involved.

    How the ACH Network Works

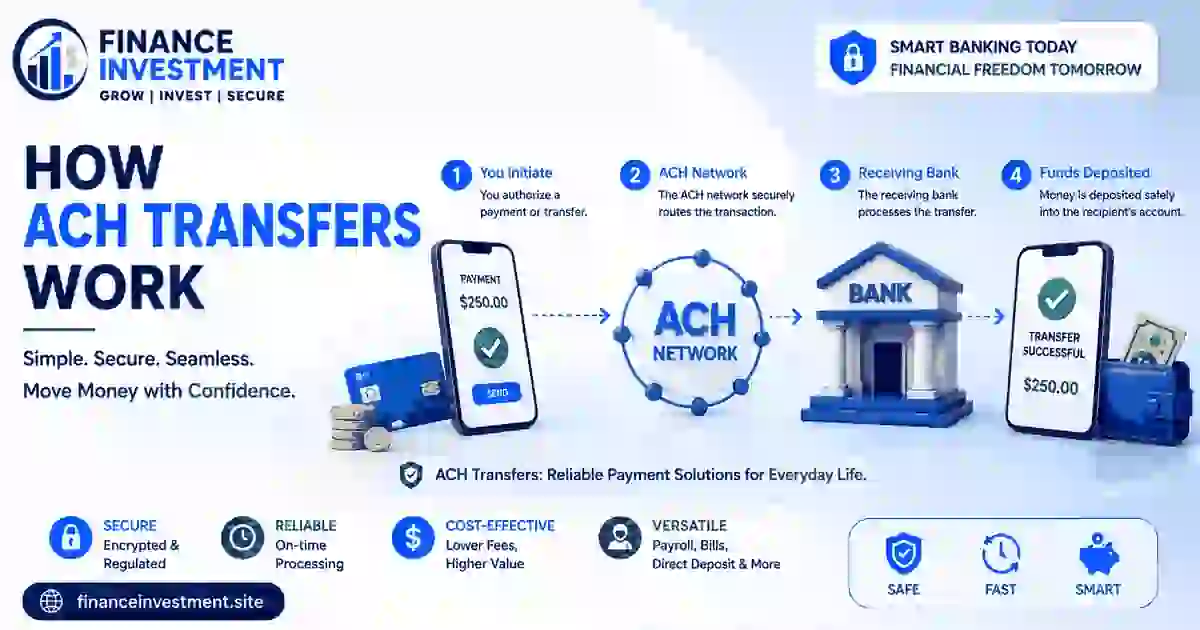
    An ACH transaction begins when a person or organization initiates or authorizes a payment. The originating financial institution submits the transaction through the ACH network, which sorts and delivers payment instructions to the receiving institution. The receiving bank processes the entry and posts it to the recipient’s account according to its procedures. ACH credits include direct deposits, while ACH debits include authorized bill payments and other collections.

    Standard ACH vs. Same-Day ACH

    Standard ACH commonly takes one to three business days, but the actual timing depends on when the payment is submitted, the institutions involved, and the transaction type. Same-Day ACH can process eligible payments on the same business day when they meet network requirements and applicable submission deadlines. It is not available for every transaction, and same-day processing does not guarantee immediate access to funds. Weekends, federal holidays, bank cut-off times, and account-specific reviews can affect when a payment is completed.

    When Should You Use ACH?

    ACH works well for payroll, recurring utility bills, loan payments, and many bank-to-bank transfers. Compared with domestic wire transfers, ACH is often cheaper but may take longer. Wires may suit time-sensitive or high-value payments when the recipient requires them and the fees are acceptable. Services such as Zelle are separate payment services with their own eligibility, timing, and dispute rules; they should not be treated as equivalent to ACH. Paper checks can also take longer because they must be delivered and processed.

    Before initiating an ACH transfer, confirm the recipient’s name, routing number, account number, amount, and expected delivery date. If speed matters, ask your bank whether Same-Day ACH is available for your transaction. Keep in mind that ACH payments may be subject to return or reversal procedures under applicable rules, but recovery is not guaranteed if an error occurs.

    Wire Transfers Explained

    A wire transfer electronically sends money between financial institutions. In the United States, wires are commonly used for real estate closings, business transactions, and other payments where the recipient requires this method or timely delivery is important. Wires can move quickly, but processing times, fees, and requirements depend on the sending bank, receiving institution, and destination.
    What Is a Wire Transfer? Complete Beginner Guide

    Domestic vs. International Wire Transfers

    A domestic wire transfer sends funds between financial institutions within the United States. An eligible wire may arrive the same business day if it is submitted before the bank’s cut-off time and processed successfully. An international wire transfer sends funds across borders and may involve intermediary banks. Delivery can take several business days, depending on the destination country, currency, receiving bank, compliance reviews, and intermediary processing. Neither method has a universal delivery guarantee.
    How Do Wire Transfers Work?

    Wire Transfer Timing and Fees

    Banks generally process wires according to their operating hours and cut-off schedules. Requests submitted after a deadline, on a weekend, or on a bank holiday may be handled on the next business day. Sending and receiving fees may apply, and intermediary banks may deduct additional charges from international payments. Currency conversion can also affect the final amount received. Before authorizing a wire, ask about the total fees, exchange rate, estimated delivery time, and any charges the recipient may pay.

    Verify Recipient Details Before Sending

    Confirm the recipient’s name, account number, bank routing details, and any required SWIFT/BIC or international payment instructions. If you receive new or changed wire instructions by email, call the intended recipient using a phone number you already trust—not a number supplied in the message. This independent check can help prevent costly business email compromise and payment-redirection scams.

    Can a Wire Transfer Be Reversed?

    Once a wire has been processed, recovering the money can be difficult, especially if the receiving account has already been credited or the funds withdrawn. Contact your bank’s wire department immediately if you enter incorrect details or suspect fraud. Ask whether the bank can initiate a cancellation or recall and request a fraud investigation when appropriate. A recall is a request, not a guarantee that the funds will be returned.

    Transfer Times, Processing Windows & Delays

    Bank transfer timing depends on the payment method, submission time, and financial institutions involved. Sending a transfer does not always mean the recipient can use the money immediately. Before initiating a payment, check the estimated delivery date and whether the funds will be available upon arrival.

    Business Days and Bank Cut-Off Times

    Banks use processing schedules and cut-off times for many transactions. A payment submitted after the applicable deadline may not be processed until the next business day. Standard ACH transfers commonly take one to three business days, while eligible domestic wire transfers may arrive the same business day if submitted before the bank’s cut-off. These are general estimates, not guarantees; individual banks and transaction types can differ.

    Weekends, Holidays, and Pending Transfers

    Standard ACH processing generally follows business-day schedules, so weekends and federal holidays can extend delivery times. Wire transfers also depend on the operating schedules of the relevant banks and payment systems. A pending status means the transaction has not been shown as fully completed, but its precise meaning varies by bank or payment service. Do not treat a pending payment as proof that the recipient has received usable funds.

    Common Reasons for Transfer Delays

    Delays can result from incorrect account details, insufficient funds, incomplete verification, security reviews, processing backlogs, or additional checks on large and international payments. The receiving bank may also need time to post incoming funds. If a transfer exceeds the provider’s estimated delivery window, contact the sending institution using its official contact details. Provide the transaction reference and ask whether the payment is processing, completed, rejected, or returned.

    If you suspect fraud or discover that you sent money to the wrong recipient, contact your bank immediately. Ask whether the transfer can be stopped, recalled, or investigated. Acting quickly may help, but recovery is not guaranteed.

    Transfer Fees, Limits & Large Payments

    The cost of sending money depends on the transfer method, your financial institution, account terms, and destination. Before confirming a payment, compare the total expected cost and check whether transaction limits or processing requirements could affect delivery.

    Common Bank Transfer Fees

    ACH transfers are often inexpensive, and some banks include them at no additional charge. However, fees can apply to certain services or account types. Domestic and international wires commonly carry sending fees, while receiving or intermediary banks may impose additional charges. International transfers can also involve currency-conversion costs and exchange rates that affect how much the recipient receives. Check your provider’s current fee schedule and ask about the estimated total before authorizing the transaction.

    Transfer Limits and Daily Caps

    Financial institutions and payment services may impose per-transaction, daily, or monthly limits. These can vary by account type, transfer method, recipient, verification status, and security controls. Online bank transfers, wire transfers, and person-to-person payment services may each have different limits. A transaction that exceeds an applicable limit may be declined, delayed, or require another approved method. Confirm your current limit directly with the provider because limits can change and may be specific to your account.

    Planning a Large Payment

    For a home purchase, tuition bill, or major business payment, verify the recipient’s instructions through a trusted, independent contact method. Ask your bank about applicable limits, fees, documentation, cut-off times, and any additional verification well before the deadline. Allow enough time for processing and confirm when the recipient should expect the funds. Never split transactions to evade legal reporting requirements or bank controls; ask your institution about legitimate alternatives if a payment exceeds a limit.

    To reduce unexpected costs, double-check the destination details, review exchange rates and possible intermediary charges, and save the transaction confirmation. If a fee or restriction is unclear, obtain an explanation from your provider before sending the money.

    Transfer Problems, Cancellations & Reversals

    A bank transfer may be delayed, rejected, returned, or sent to the wrong recipient. Your options depend on the payment method, transaction status, and reason for the problem. Contacting your financial institution promptly can help you understand the next steps, but recovering money is not always possible.

    Failed or Delayed Transfers

    Transfers may fail because of incorrect account information, insufficient funds, verification issues, or security reviews. Check your transaction history and any bank notification to see whether the payment is pending, rejected, completed, or returned. If it exceeds the estimated delivery window, contact the sending institution with your transaction reference and ask for the current status and any action required.checking account fraud warning signs

    Cancellations, Reversals, and ACH Returns

    A transfer that has not yet been processed may sometimes be canceled, depending on the provider and payment type. Once completed, stopping it may be difficult. An ACH return sends an entry back through the ACH system for a permitted reason under applicable rules; it is not the same as a general cancellation. A bank may also be able to request a wire recall, but the request does not guarantee that the funds will be recovered. Contact your provider immediately to learn which options apply.

    If You Sent Money to the Wrong Recipient

    Contact your bank or payment service immediately and explain the error. Ask whether the payment can be stopped, traced, or recalled. Do not send another payment to correct the mistake until you know what happened to the original transaction. Save confirmations, reference numbers, and relevant messages. If the recipient’s account details were incorrect, the institution can explain whether the payment was rejected, returned, or delivered.

    If You Suspect Fraud or an Unauthorized Transfer

    Contact your bank through its official app, website, or the number on your card. Report the transaction as soon as possible, request a fraud investigation, and ask whether the payment can be stopped or recalled. Secure compromised credentials and keep records of your report. For more guidance, read our guide to disputing an unauthorized bank transaction. Reporting deadlines and protections can vary by transaction type, so do not delay.

    Direct Deposit, Online Bill Pay & Recurring Transfers

    Automated banking services help you receive income, pay bills, and move money on a schedule. Each service follows different processing and authorization rules. Understanding how it works, when funds may move, and how to manage scheduled payments can help prevent missed bills and unexpected withdrawals.

    Direct Deposit for Paychecks and Benefits

    Direct deposit electronically sends money to your bank account, commonly through the ACH network. Employers use it for wages, and eligible government agencies may use it for benefits. Submit your account details through the payer’s approved process and confirm when the arrangement becomes effective. Early access to a paycheck is not guaranteed; availability depends on when the payer submits the deposit and how your bank processes it.

    Online Bill Pay vs. Automatic Payments

    With online bill pay, you instruct your bank to pay a company or individual. Depending on the recipient and service, the bank may send an electronic payment or mail a paper check, so allow enough delivery time. With a biller-authorized automatic payment, you authorize a company to collect money from your account, often through ACH. Before enrolling, review the amount or calculation method, due date, authorization terms, and cancellation instructions.

    Managing Recurring Transfers Safely

    Recurring transfers move money automatically between accounts at a chosen frequency, such as weekly or monthly. Confirm the source and destination accounts, amount, schedule, and first transfer date. Keep sufficient funds available, including a buffer for other pending transactions.

    To avoid missed or duplicate payments, track due dates, enable transaction alerts, and review your account regularly. Before paying a bill manually, check whether an automatic payment has already been scheduled or processed. When switching banks or canceling a service, confirm the new arrangement is active and follow the relevant cancellation procedure. Save confirmations and check subsequent statements to ensure payments occur—or stop—when expected.

    Digital Wallets, P2P & International Payments

    Digital payment services make it convenient to shop, pay in stores, and send money to other people. However, digital wallets, person-to-person (P2P) services, and international money transfers work differently. Their funding methods, fees, processing times, and options for resolving problems depend on the provider and transaction type.

    Digital Wallets and Contactless Payments

    Digital wallets, such as Apple Pay and Google Wallet, can store payment credentials for eligible purchases. When you pay with a wallet, the transaction generally follows the rules of the linked card or payment method; it is not necessarily a direct bank-to-bank transfer. Check which card or account will be charged, review transaction alerts, and secure your device with a passcode and available authentication features.

    P2P Payments: Convenient but Not Risk-Free

    P2P services let users send money to eligible recipients, such as friends and family. Depending on the service and funding method, a payment may reach the recipient quickly, while withdrawing or transferring the balance to a bank account can take longer. Fees may apply to certain funding methods or expedited transfers. Before sending money, independently verify the recipient and the reason for payment. Our guide to avoiding Zelle scams explains why payments to impostors can be difficult to recover. Availability of refunds or other remedies depends on the circumstances and applicable rules.

    International Transfers, Fees, and Exchange Rates

    International transfer providers can send money across borders using eligible payout methods, including bank deposits. Delivery may take minutes or several business days, depending on the provider, destination, funding method, compliance checks, and receiving institution. Compare the transfer fee, exchange rate, any exchange-rate markup, possible intermediary charges, and the final amount the recipient is expected to receive. Check the destination and currency carefully before confirming the payment.how to protect yourself from Zelle scams

    Reduce Digital Payment Risks

    Scammers may impersonate friends, businesses, or bank employees to pressure people into sending money. Verify urgent requests through a separate, trusted contact method, avoid unfamiliar payment links, and never share one-time verification codes. If you notice a transaction you did not authorize or suspect a scam, contact your bank or payment provider immediately through its official app or website. Explain what happened and ask about available reporting, cancellation, or recovery options; a refund is not guaranteed.how to avoid QR code payment scams

    Payment Security, Verification & Disputes

    Electronic payments are convenient, but incorrect recipient details, compromised accounts, and payment scams can put your money at risk. Verify payment instructions before sending funds, protect your banking access, and report suspicious activity promptly. Quick action may help limit further losses and preserve available recovery options.how to recognize bank email phishing scams

    Verify Recipients Before Sending Money

    Check the recipient’s name, account number, routing details, amount, and destination before confirming a transfer. For large or unfamiliar payments, independently verify instructions using a trusted phone number or contact method you already have. Do not rely solely on an email, text, or unexpected call requesting changed payment details. Scammers may impersonate vendors, relatives, or bank employees to redirect money into accounts they control.how to protect your bank account

    Protect Your Banking Access

    Use a unique password, enable multifactor authentication where available, and keep your device and banking apps updated. Never share one-time passcodes or approve sign-in requests you did not initiate. Enable transaction alerts and review account activity regularly. Our guides on protecting your bank account and setting up bank transaction alerts provide additional security steps.how to spot fake bank phone calls

    What to Do About a Suspicious or Unauthorized Transaction

    Contact your bank immediately through its official app, website, or the number on your card. Explain whether you did not authorize the transaction or authorized a payment because someone deceived you. Ask the bank to secure your account, investigate the activity, and determine whether the payment can be stopped or recalled. Change compromised credentials from a trusted device, preserve transaction records, and save your case number. Do not wait for your next statement if you already suspect fraud.how to recognize bank impersonation scams,  remote access banking scams

    Report and Dispute Payment Problems

    Ask your bank how to submit a formal dispute and what deadlines apply. In the United States, legal protections and procedures depend on the account, payment method, and circumstances. Prompt reporting is especially important for potentially unauthorized electronic transfers. Read our guide to disputing unauthorized bank transactions for additional steps. Keep copies of communications and follow up using your case reference.fake bank text message scams An investigation may lead to a refund or other remedy, but recovery is not guaranteed in every case.how to monitor your bank account ,  SIM swap scams and bank account security

    Frequently Asked Questions About Bank Transfers

    1. What is the best way to transfer money between bank accounts?

    ACH is often a cost-effective option for routine transfers between U.S. bank accounts. A wire may be more appropriate when the recipient requires it or timing is important. Compare fees, delivery estimates, limits, and cancellation options before choosing.

    2. Is ACH cheaper than a wire transfer?

    ACH is often less expensive, and some banks include it at no additional charge. Wire transfers commonly have sending fees, while international wires may involve intermediary charges and currency-conversion costs. Check your provider’s fee schedule.

    3. How long does a typical bank transfer take?

    Standard ACH transfers commonly take one to three business days. Eligible domestic wires may arrive the same business day. Actual timing depends on the payment method, submission time, bank schedules, and any required reviews.

    4. Can you cancel a bank transfer after sending it?

    Cancellation may be possible before processing is complete, depending on the provider and transfer type. After processing, recovery can be difficult. Contact your bank immediately to ask about cancellation or recall options; success is not guaranteed.

    5. Why is my bank transfer still pending?

    A pending status may reflect normal processing, a weekend or holiday, verification checks, or a bank review. Check the provider’s estimated delivery window and contact it if the transaction remains pending beyond that estimate or shows an unexpected warning.

    6. What should you do if you send money to the wrong account?

    Contact your bank or payment provider immediately. Explain the mistake and ask whether the payment can be stopped, traced, or recalled. Keep the confirmation and transaction reference. Recovery depends on the payment status and circumstances.

    7. Are bank transfers safer than payment apps?

    Neither method is automatically safer in every situation. Use trusted services, verify recipients, and understand the applicable dispute process. Payments you authorize after being deceived may be difficult to recover, even when fraud is involved.

    8. Are there limits on how much money you can transfer?

    Many banks and payment services set per-transaction or daily limits. The amount may depend on your account, payment method, recipient, and verification status. Confirm your current limit and any additional requirements with the provider before arranging a large payment.