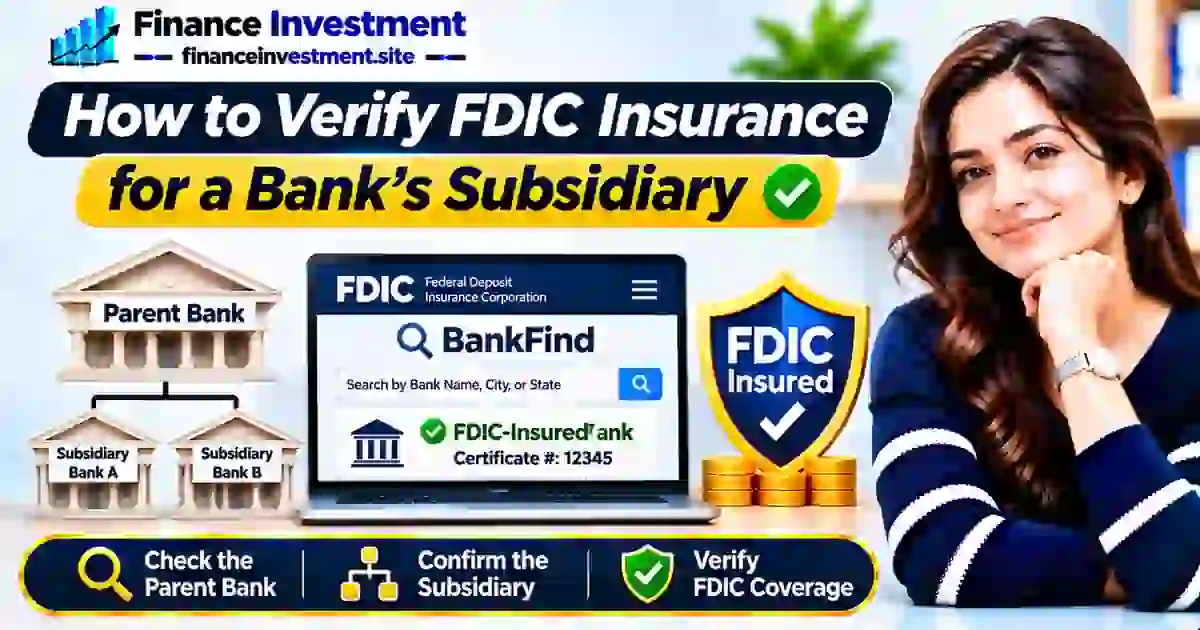
How to Verify FDIC Insurance for a Bank’s Subsidiary: 2026 Guide
 Does Your Bank’s Subsidiary Have Separate FDIC Insurance?
Imagine finding a savings account with a better interest rate, only to discover that the bank belongs to the same company as your current bank. Learning how to verify FDIC insurance for a bank’s subsidiary can help you determine whether moving your money provides additional deposit protection.
The distinction matters because two banking brands may operate under one insured bank or belong to separately chartered institutions. Common ownership alone doesn’t determine your insurance coverage.
This guide walks you through the verification process. If you’re new to deposit protection, start with our FDIC and NCUA insurance guide for the basics.
What You’ll Learn
- How parent banks and subsidiaries differ.
- Where to find FDIC certificate numbers.
- When affiliated banks provide separate coverage.
- How banking divisions affect insurance limits.
- What to check before transferring your savings.
Quick Answer: How to Verify FDIC Insurance for a Bank’s Subsidiary
Search both banks using the official FDIC BankFind Suite. Compare their legal names, active insurance status and FDIC certificate numbers. Separately chartered, FDIC-insured banks generally provide separate deposit insurance coverage, even when they share a parent company.
6 Key Takeaways
- Common ownership does not automatically combine FDIC coverage.
- Separate insured bank charters generally provide separate coverage.
- Different banking brands may share one FDIC certificate number.
- The standard limit is $250,000 per depositor, per insured bank, per ownership category.
- Nonbank subsidiaries do not automatically receive FDIC insurance.
- Bank mergers can change how your deposits are insured.
Bottom line: Verify the actual insured bank behind each account before assuming your deposits qualify for separate protection.
At a Glance: FDIC Insurance for Bank Subsidiaries
How Coverage Differs by Banking Arrangement
| Banking Arrangement | FDIC Coverage |
|---|---|
| Separately insured subsidiary bank | Separate coverage for eligible deposits. |
| Bank division or brand | Same-bank deposits combine by ownership category. |
| Nonbank subsidiary | No direct coverage; qualifying pass-through insurance may apply. |
| Recently merged banks | Temporary separate coverage may apply under FDIC merger rules. |
Quick take: A different banking brand does not necessarily give you another $250,000 insurance limit.
Understanding Parent Banks and Subsidiaries: A Beginner’s Guide
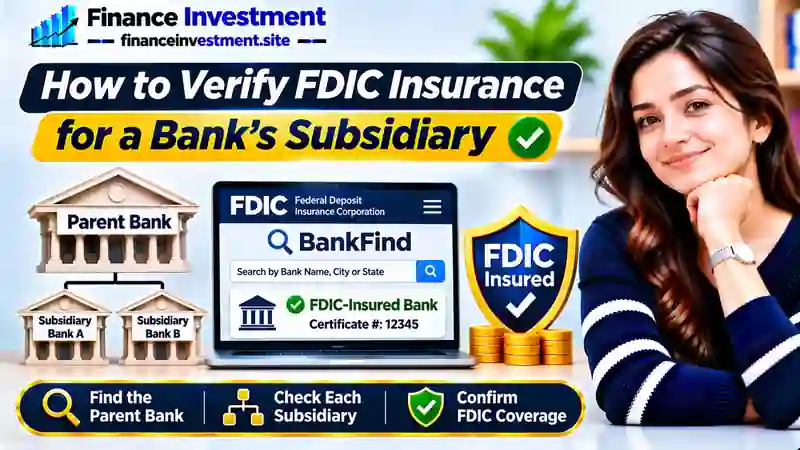
Banking groups often operate several businesses under different names. Some accept deposits independently, while others simply market products offered by an existing bank. Knowing which arrangement you’re dealing with matters when calculating insurance coverage.
What Is a Bank Holding Company?
A bank holding company owns or controls one or more banks. The holding company itself does not receive FDIC deposit insurance merely because it owns insured banks. Each banking subsidiary may have its own charter and insurance status.
What Is a Separately Chartered Bank Subsidiary?
A subsidiary bank operates under the control of another company. When it holds its own bank charter and active FDIC insurance, eligible deposits receive coverage separately from deposits at other insured banks in the same corporate group.
How Is a Banking Division Different?
A banking division can offer different interest rates, account names and websites without being a separate legal bank. Deposits across divisions of the same insured bank generally combine within each ownership category.
Keep this in mind when spreading deposits across multiple banks for additional protection.
What About Nonbank Subsidiaries?
Brokerage firms and payment companies do not receive direct FDIC insurance. Customer funds deposited at insured banks may qualify for pass-through FDIC insurance when applicable requirements are met. However, that insurance protects against the insured bank’s failure, not the nonbank company’s failure.
Remember: Corporate ownership explains who controls a business. The identity of the insured bank determines how your eligible deposits are grouped for insurance purposes.
How to Verify a Bank Subsidiary’s FDIC Insurance: 7 Simple Steps
Before moving your savings to an affiliated bank, follow these steps to determine whether your new account qualifies for separate deposit insurance.
Step 1: Identify the Actual Bank
Review the deposit agreement, account statement or banking disclosures. Find the legal name of the institution holding your money rather than relying on its advertised brand.
Step 2: Search the FDIC BankFind Database
Visit the official FDIC BankFind Suite. Search for the legal bank name and confirm that the matching institution is currently FDIC-insured.
Step 3: Compare FDIC Certificate Numbers
Find the certificate numbers for both banks. Different active certificates identify separate insured institutions. A shared certificate indicates the same insured bank, regardless of branding.
Step 4: Confirm the Account Type
Make sure you’re opening an eligible deposit account, such as savings, checking or a CD. Investment products are not FDIC-insured, even when offered by insured banks.
Step 5: Review Recent Bank Mergers
Check the institution’s history in BankFind. Deposits transferred through a bank merger generally retain separate coverage for at least six months. Special rules may extend coverage for certain CDs.
Step 6: Calculate Your Total Coverage
Use the FDIC Electronic Deposit Insurance Estimator (EDIE) for each insured bank separately. Include existing deposits, accrued interest and applicable ownership categories.
Step 7: Confirm Any Unclear Details
Save the verification results and ask the bank for clarification if necessary. For unresolved insurance questions, contact the FDIC at 1-877-275-3342.
Practical tip: Recheck your coverage before making large transfers or renewing CDs. Banking relationships can change over time. For additional guidance, read our FDIC insurance verification guide.
Benefits and Drawbacks of Using Bank Subsidiaries
Bank subsidiaries can offer attractive savings opportunities, but their corporate relationships may complicate deposit insurance planning. Consider these advantages and limitations before opening an account.
Benefits
- Additional deposit protection when using separately insured banks.
- Potentially competitive savings and CD rates.
- More account choices within a familiar banking group.
- Greater flexibility when distributing large cash balances.
Drawbacks
- Different brands may share one insured bank.
- Corporate structures can be difficult to understand.
- Bank mergers may eventually reduce separate coverage.
- Nonbank subsidiaries introduce additional verification requirements.
Quick take: Competitive rates are worth exploring, but verify the underlying insured institution before moving substantial savings.
Parent Bank vs. Subsidiary vs. Banking Division: Key Differences
Two financial institutions can belong to the same corporate group without sharing the same deposit insurance limit. This comparison shows how different banking structures affect your coverage.
Swipe or scroll horizontally on smaller screens to view the complete table.
| Banking Structure | Legal Status | FDIC Certificate | Deposit Coverage |
|---|---|---|---|
| Insured parent bank | Chartered bank | Own active certificate | Coverage within applicable limits |
| Separately insured subsidiary bank | Independent bank charter | Separate active certificate | Separate insurance coverage |
| Banking division or brand | Part of an existing bank | Shares the bank’s certificate | Combined within each ownership category |
| Nonbank subsidiary | Nonbank business | No own FDIC certificate | No direct insurance; qualifying pass-through coverage may apply |
Key difference: A bank holding company does not receive deposit insurance simply because it owns insured banks. Separate coverage depends on the identity of the insured institution, not the corporate relationship.
Costs, Risks and Expert Tips for Verifying Bank Subsidiaries
What Does FDIC Verification Cost?
Checking insurance through FDIC BankFind and EDIE is free. However, transferring or maintaining deposits may involve wire transfer fees, account maintenance charges or CD early withdrawal penalties, depending on the bank’s terms.
Financial Risks Worth Understanding
- Combined deposits and accrued interest exceeding applicable insurance limits.
- Temporary separate coverage expiring after a bank merger.
- Nonbank deposit arrangements failing to satisfy pass-through insurance requirements.
Expert Tips for Protecting Your Savings
- Maintain a reasonable cushion below applicable insurance limits to accommodate interest growth.
- Recalculate coverage before large transfers and after merger announcements.
- Consider additional strategies for protecting more than $250,000 in bank deposits.
Important Warning
A Member FDIC logo or an outdated certificate screenshot is not sufficient proof of current coverage. Independently verify the insured bank’s identity and confirm that your funds will be held in eligible deposit accounts.
Common Mistakes When Checking a Bank Subsidiary’s FDIC Insurance
- Trusting brand names: Different banking websites may represent the same insured institution.
- Ignoring existing balances: Deposits in the same ownership category at one insured bank generally combine.
- Assuming automatic coverage: Corporate affiliation does not establish separate FDIC insurance.
- Using outdated records: Historical certificate numbers may not reflect current insurance arrangements.
Hypothetical Example: One Saver, Two Banking Brands
Sarah holds $180,000 at insured Bank A and deposits $120,000 through its affiliated Brand B. Both accounts qualify under the single ownership category.
Scenario 1: Both Brands Use the Same Insured Bank
Combined deposits: $300,000
FDIC-insured amount: $250,000
Uninsured amount: $50,000
Scenario 2: Brand B Is a Separately Insured Bank
Bank A insured deposits: $180,000
Bank B insured deposits: $120,000
Total insured deposits: $300,000
Uninsured amount: $0
Assumptions: Fictional banking institutions, eligible deposits, no other balances or additional accrued interest, and no applicable merger-related exceptions.
Lesson: Checking both banks’ active FDIC certificate numbers before transferring money could help Sarah avoid leaving $50,000 uninsured.
Who Should Verify a Bank Subsidiary’s FDIC Insurance?
Every depositor benefits from checking a bank’s insurance status, but verification is particularly important for these groups:
- High-balance savers: Those approaching applicable FDIC insurance limits.
- Retirees: Individuals holding substantial retirement cash reserves.
- Families: Households managing deposits across affiliated banks.
- Online banking customers: Anyone opening accounts through unfamiliar banking brands.
- Business owners: Companies maintaining substantial operating cash balances.
If you maintain substantial savings, explore our guide to FDIC insurance for high-balance savings accounts before distributing funds across related institutions.
Frequently Asked Questions About FDIC Insurance for Bank Subsidiaries
Are bank subsidiaries separately FDIC-insured?
Yes, if they are separately chartered banks with active FDIC insurance. Corporate affiliation alone does not establish separate coverage.
How do I verify FDIC insurance for a bank’s subsidiary?
Search its legal bank name in FDIC BankFind. Confirm active insurance and compare its certificate number with your existing bank’s certificate.
Can two banks owned by the same company have separate FDIC coverage?
Yes. Separately insured banks provide independent coverage for eligible deposits, even when they share a parent company.
What if two banking brands share the same FDIC certificate number?
If both use the same active FDIC certificate, deposits generally combine within each ownership category at that insured bank.
Is a bank holding company FDIC-insured?
Owning insured banks does not make a holding company FDIC-insured. Deposit insurance applies to eligible deposits at insured institutions.
What happens to FDIC coverage after affiliated banks merge?
Deposits from the acquired bank generally remain separately insured for six months. Special rules may extend coverage for certain CDs.
Are nonbank subsidiaries covered by FDIC insurance?
Not directly. Eligible funds at insured banks may qualify for pass-through coverage against bank failure, not the nonbank subsidiary’s failure.
Is it free to verify a subsidiary bank’s FDIC insurance?
Yes. FDIC BankFind verifies bank insurance status, while EDIE estimates deposit coverage. Both official tools are free.
Final Verdict: Verify the Bank Before Moving Your Money
Knowing how to verify FDIC insurance for a bank’s subsidiary helps you make informed decisions about where to keep your savings. Separately insured banks can provide independent coverage for eligible deposits, even under common ownership.
Before transferring money, confirm the legal bank name, active FDIC certificate and applicable insurance limits. For a broader understanding of deposit protection, explore our complete FDIC and NCUA insurance guide.
Final takeaway: Choose verified deposit protection over assumptions about familiar banking brands.
Have a Money Question? Keep Exploring.
Protecting your savings starts with understanding where your money is held. Explore more FinanceInvestment guides to build confidence in your everyday banking decisions.
Have questions or suggestions about our banking guides? We’d love to hear from you.
Disclaimer: This article is for educational and informational purposes only and does not constitute personalized financial or legal advice. Deposit insurance depends on applicable FDIC rules and individual account arrangements. Verify your coverage directly with the FDIC before making financial decisions.
Leave a Reply